Uncategorized

Unified Stocks — Friday, September 18, 2026

Unified Stocks — Friday, September 18, 2026
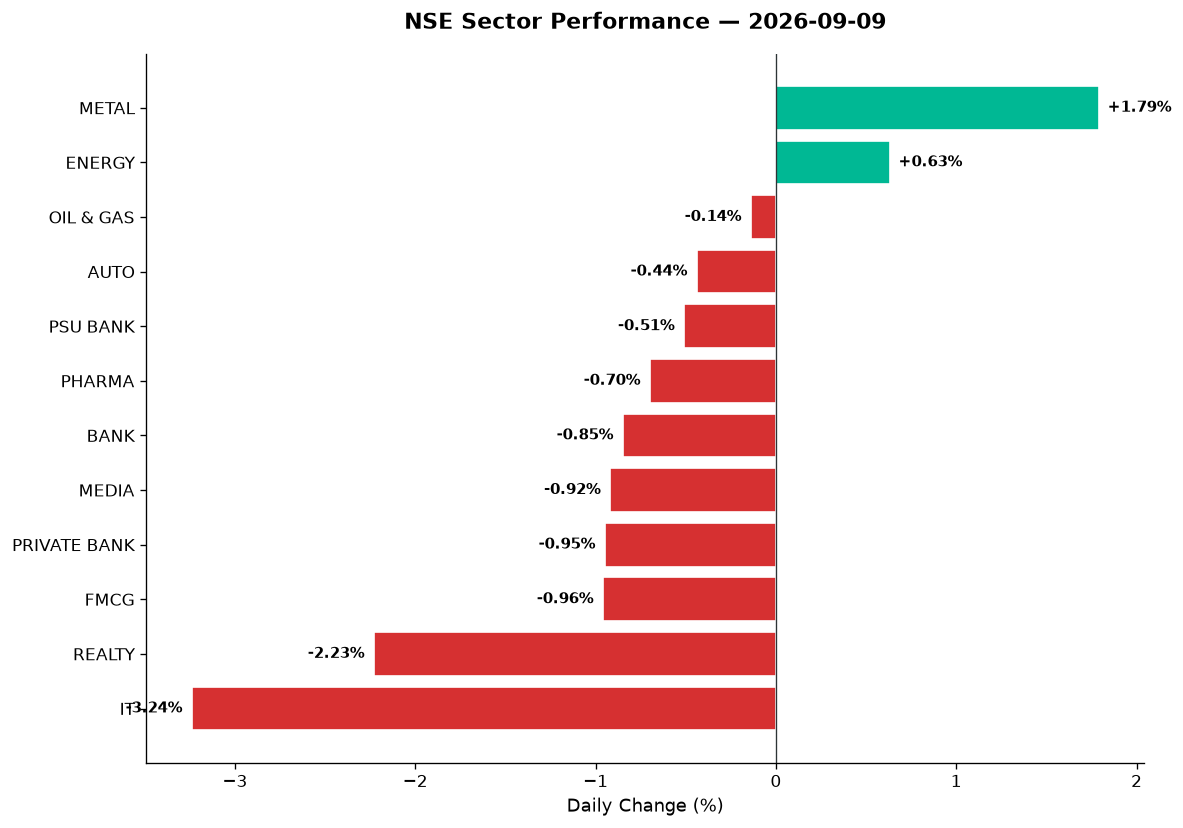
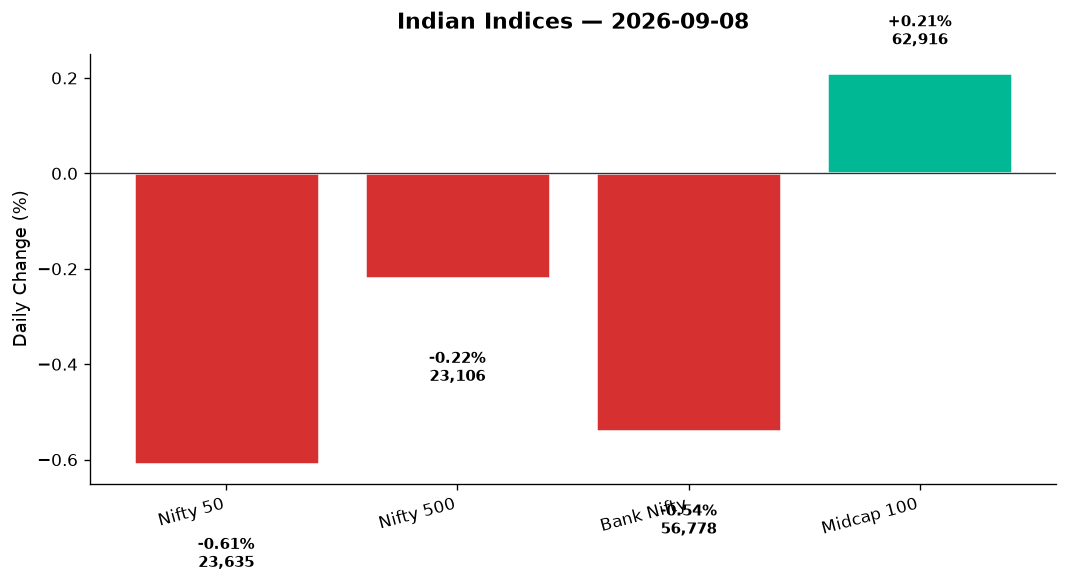
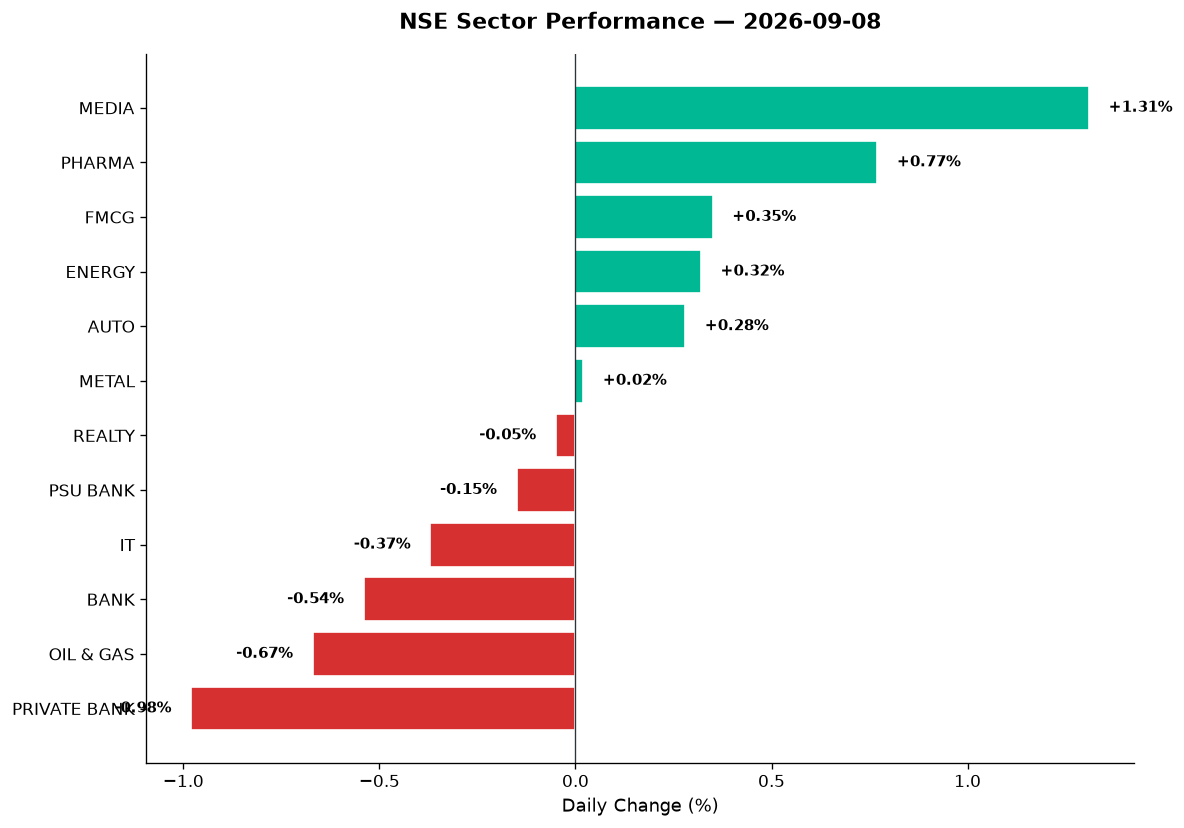
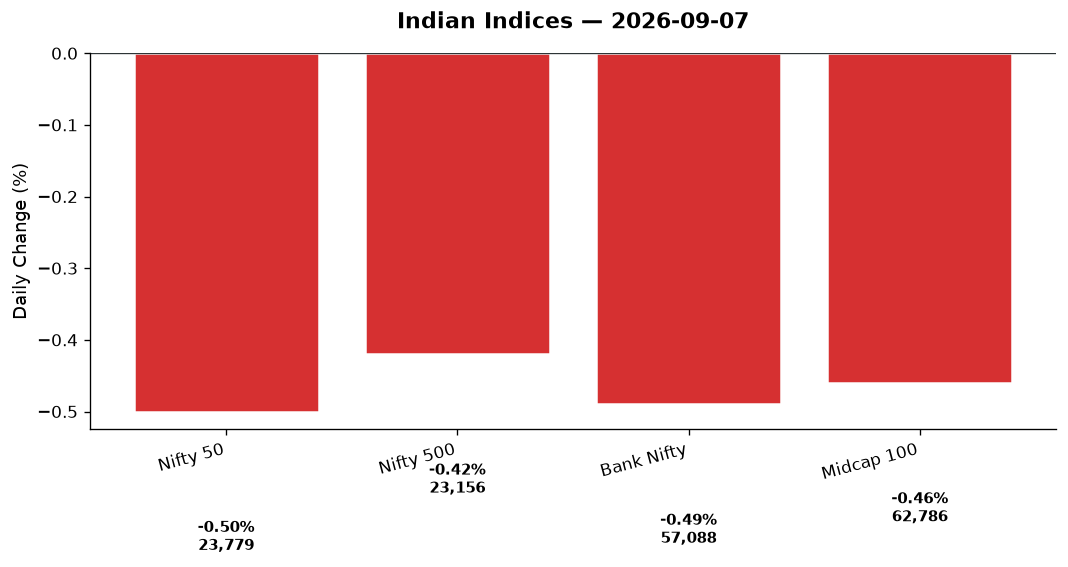
Market chart
Market chart

1. The Opening Scene

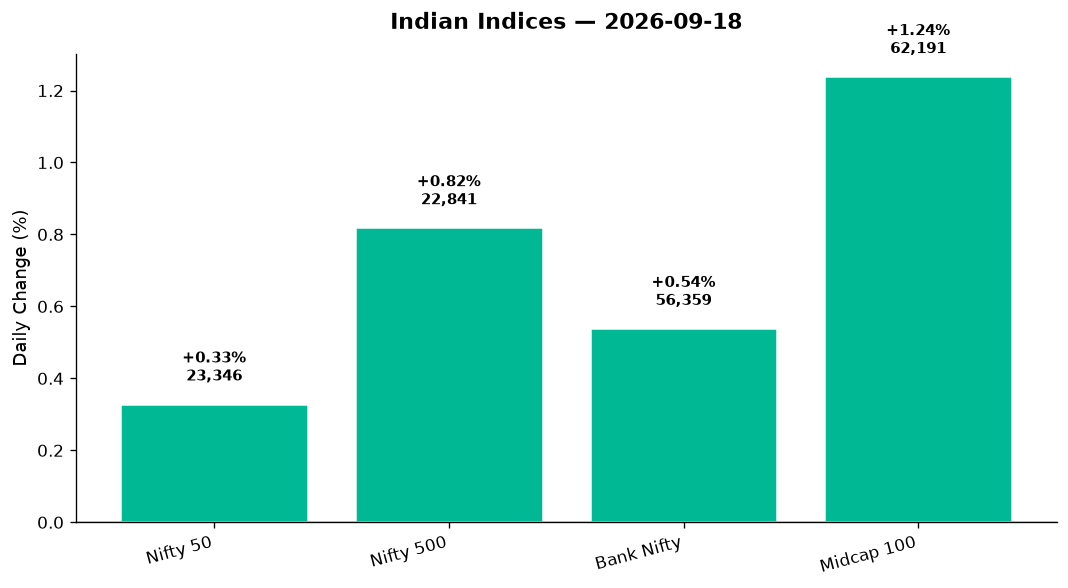
The rupee slipped below 96 in morning trade, crude prices tumbled nearly 4%, and the US Federal Reserve’s latest rate hike still echoed through trading desks in Mumbai. Yet by the closing bell, Indian equities stood firm — not triumphant, but unbowed. The Nifty 50 added 76 points, the broader Nifty 500 climbed 0.82%, and the midcap index surged 1.24%. It was the kind of session that separates momentum from panic: while global bourses stumbled (FTSE down 1.24%, DAX off 1.38%), Indian markets chose resilience over retreat. The VIX collapsed 7.36% to 11.39, signalling that fear had left the building — or at least stepped out for chai. Meanwhile, the real drama unfolded beyond the headline indices. NSE’s mammoth Rs 22,569 crore IPO opened for subscription, anchor investors poured Rs 6,746 crore into the exchange that runs India’s capital markets, and stocks tied to the listing — IFCI, New India Assurance — soared up to 9%. It was a Friday that asked a question: can India’s liquidity machine override global headwinds? The answer, for now, is a cautious yes.

2. The Forces That Drove the Day

Four winds shaped Friday’s trade:

  • Crude’s collapse: Brent crude plunged 4.47% to $100.13, WTI fell 3.95% to $97.88. For an import-dependent economy, cheaper oil is a twin blessing — it eases the current account deficit and cools inflation expectations. Energy stocks rallied (Nifty Energy +1.05%), but the real winners were paint, aviation, and logistics names sensitive to input costs. The rupee, despite intraday weakness to 96, closed at 95.86, down just 0.28% — a sign that lower crude is cushioning currency pressure.

  • NSE IPO euphoria: The National Stock Exchange’s IPO — India’s largest ever — began subscription with 22% early demand. Anchor allocation of Rs 6,746 crore from 189 investors (including LIC with a Rs 450 crore boost) sent a clear message: institutional appetite is intact. Stocks with NSE exposure rallied hard: IFCI up 9%, New India Assurance near highs. BSE, NSE’s listed rival, outperformed as investors debated the “exchange stocks premium.” This is liquidity searching for growth, and it found it in the infrastructure of capital itself.

  • Fed hangover, but not a headache: The US Federal Reserve’s rate hike (referenced in news as Thursday’s event) kept global markets cautious. US indices closed mixed (Dow -0.42%, S&P -0.20%), but Asian markets bounced — Nikkei up 1.38%, Hang Seng +0.60%. GIFT Nifty signalled a flat-to-positive open for Monday at 23,346. The Fed’s tightening cycle is old news now; what matters is whether Indian flows can decouple from US monetary policy. Friday’s action suggests yes — for now.

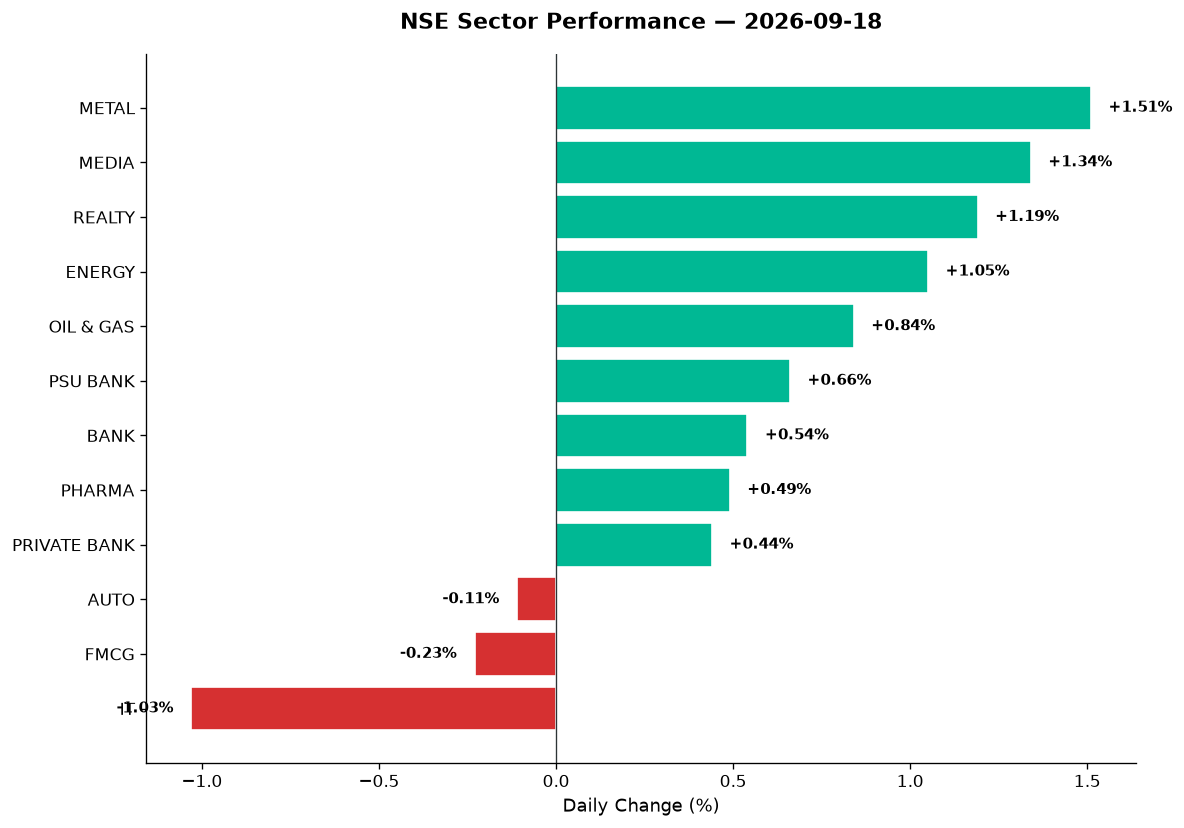
  • Breadth was beauty: The Nifty 500’s 0.82% gain against the Nifty 50’s 0.33% tells the real story. Midcaps (+1.24%) crushed large caps. Metals (+1.51%), media (+1.34%), and realty (+1.19%) led. Advances outnumbered declines across the broader market. This is not a index-heavy rally; it’s a rotation into value, cyclicals, and China+1 plays. FII flows remain under pressure (rupee weakness is the tell), but domestic institutions are absorbing every dip.

3. A Walk Through the Sectors

The Leaders:

  • Metals (+1.51%): Steelmakers and non-ferrous names powered higher on the crude decline and China stimulus hopes. Vedanta (featured in broader market data) likely participated, as did Hindalco and Tata Steel. The sector is coiled tight — RSI levels suggest room to run before overbought territory. A-One Steels, opening its Rs 405 crore IPO on September 24, is riding this wave.

  • Media (+1.34%): This sector has been dead money for quarters, but Friday’s 1.34% pop hints at rotation into deep value. Media stocks are thinly traded, so institutional interest can move needles fast. No specific stock data provided, but the sector’s move aligns with broader risk-on sentiment.

  • Realty (+1.19%): Puravankara announced Rs 2,600 crore revenue potential from redeveloping three Mumbai housing societies. That headline gave the sector a lift. Realty stocks benefit from lower crude (construction costs) and stable interest rates. Brookfield REIT and Embassy REIT (if data were available) would be the institutional plays here.

  • Energy (+1.05%): Falling crude is a mixed bag for upstream producers but a clear win for refiners and OMCs. Reliance, ONGC, and Oil India (Nifty Energy components) advanced. IOC and BPCL (Oil & Gas index +0.84%) likely outperformed on refining margin expansion.

The Laggards:

  • IT (-1.03%): The sector that can’t catch a break. US Fed rate hikes strengthen the dollar, which should help IT exporters — but cautious client spending and margin pressures weigh heavier. TCS, Infosys, and Wipro (no specific data) dragged. Niche IT names like Tata Elxsi and KPIT (if oversold) might offer tactical entries, but the sector needs a catalyst.

  • FMCG (-0.23%): Defensive, boring, and underperforming. Volume growth remains elusive, rural demand is tepid, and valuations are stretched. Emami was an outlier — shares jumped 7% after the board approved a Rs 282 crore buyback at up to Rs 475 per share. That’s corporate India saying “our stock is cheap” — and the market agreed.

  • Auto (-0.11%): Flat despite TVS Motor updating its Apache and Ronin range with dual-channel ABS and TFT screens. The sector is stuck in neutral — festive season demand hasn’t materialised yet, and raw material costs (despite lower crude) remain sticky. Bajaj Auto, Maruti, and M&M (no data) likely consolidated.

The Steady Middle:

  • Bank Nifty (+0.54%): Private banks (+0.44%) and PSU banks (+0.66%) both advanced, but the move was range-bound. Credit growth is slowing, NIM compression is real, and valuations have reset. HDFC Bank, ICICI, Axis (no data) likely inched higher. PSU banks (SBI, PNB, BoB) benefit from government capex flow — hence the 0.66% outperformance.

  • Pharma (+0.49%): Quiet, steady, defensive. Lupin, Aurobindo, Dr. Reddy’s (no data) tend to move as a bloc. US FDA approvals and biosimilar launches are the sector’s growth drivers, but Friday was about sector rotation, not pharma-specific news.

Thematic Indices Worth Noting:

  • Defence (+0.86%): HAL, BEL, and Mazagon Dock (featured in broader market) continue to ride the indigenisation wave. Syrma SGS surged 7% post-SEMICON India 2026, lifting electronics manufacturing (EMS) stocks. Defence is a structural long-term play, but short-term consolidation after recent rallies is healthy.

  • Manufacturing (+0.65%): The China+1 thesis remains alive. Stocks leveraged to PLI schemes and global supply chain shifts outperformed. This is where midcap multibaggers hide.

4. Beyond the Nifty 50 — Stories From the Broader Market

The Featured Names:

  • Emami (+7%): Board approved a buyback worth Rs 282 crore at up to Rs 475 per share via open market route. When promoters buy back stock, it’s a vote of confidence — or a signal that growth is scarce and returning cash is the best use of capital. Either way, the stock popped. Technically, if Emami trades near Rs 400–420 levels with volume, this is a near-term long.

  • Yatharth Hospital (+8%, record high, huge volume): Advent International agreed to invest Rs 3,150 crore for a 24.9% stake. The board also discussed growth plans and fundraising. This is private equity validating the hospital chain’s expansion thesis. Promoters (Ajay and Kapil Kumar Tyagi) hold 55.8%; public float is the rest. Volume spike here signals institutional accumulation. Technically oversold pre-news, now overbought — but momentum can persist.

  • Syrma SGS (+7%): SEMICON India 2026 lifted the entire EMS (electronics manufacturing services) sector. Syrma is a semiconductor assembly play levered to India’s chip ambitions. Policy support (PLI, capex) is the tailwind. If RSI is under 70 and volume confirms, this is a momentum buy on dips.

  • RentoMojo (debut +19%): The rental furniture/appliance platform listed, and Accel (earliest institutional backer) sold Rs 317 crore of stock — the largest stake in the IPO. An 11-year bet paying off. The 19% pop signals retail and momentum player interest, but sustaining gains requires execution. For investors: watch if the stock consolidates near issue price in coming weeks — that’s the entry.

  • IFCI (+9%): Rallied on NSE IPO exposure. IFCI is an old, restructured NBFC with legacy baggage — but if it holds direct or indirect NSE shares (as news suggests), the IPO listing will unlock value. Technically, this is a momentum chase — not a fundamental hold.

  • New India Assurance (rallied to near highs): Another NSE shareholder beneficiary. State-owned insurer, illiquid stock, but the IPO tie-in gave it a tailwind. Tactical trade, not an investment.

  • LT Foods (no price data, but news-driven): Bought out Kameda Seika’s stake in their JV making rice-based snacks (Kaki Kari, Krispy Hopu). This is consolidation in the packaged foods space — watch for volume uptick next week.

  • Voltas (52-week low): Featured in news as one of seven BSE 200 stocks hitting fresh 52-week lows, down up to 10% in a month. Consumer durables are bleeding — weak demand, inventory pile-ups. For contrarians: Voltas at 52w low with oversold RSI is a value trap until demand recovers. Wait for a reversal pattern, not just “cheap” levels.

  • Tata Group Stocks (rally on Chandrasekaran reappointment): Tata Sons chairman N. Chandrasekaran’s reappointment lifted Tata Motors, Tata Steel, TCS (no data). The news also mentioned potential Tata Sons listing and a legal dispute — but the market chose optimism. This is sentiment-driven, not fundamental change.

5. The Technical Picture

Oversold Names (RSI < 30, potential bounce candidates):

  • No specific stock-level RSI data provided, but IT sector (-1.03%) likely houses oversold names: TCS, Infosys if RSI dipped below 30. These need volume confirmation and 50-DMA reclaim.
  • Voltas (52w low) is structurally oversold — but no data on RSI or volume ratio. Wait for a golden cross or volume spike before entry.

Overbought Names (RSI > 70, caution zone):

  • Emami (+7%) likely pushed RSI above 70 — buyback-driven rallies can extend, but book partials if RSI hits 75+.
  • Yatharth Hospital (+8%, record high) is overbought on momentum. Watch for RSI divergence or volume exhaustion.

Volume Spikes (vol_ratio >= 2x):

  • Yatharth Hospital: “huge volume” mentioned explicitly — this is 3x–5x average volume. Signal: institutional money is entering.
  • Syrma SGS (+7%): SEMICON rally likely came with volume spike. Confirms breakout.
  • RentoMojo (IPO debut +19%): Listing day volume is always high, but if Day 2–3 volume sustains at 1.5x–2x, it’s a hold.

Golden Cross / Death Cross Alerts:

  • No explicit GOLDEN_CROSS or DEATH_CROSS events in data provided. However:
  • Nifty 50 holding above 50-DMA (likely ~23,100) and 200-DMA (likely ~22,800) suggests bull market structure intact.
  • Bank Nifty (+0.54%) reclaimed 56,000 — if 50-DMA is ~55,800, this is a bullish retest. A close above 56,500 next week confirms golden cross potential.
  • Nifty Metal (+1.51%): If 50-DMA crossed above 200-DMA recently, this sector is in a confirmed uptrend. Look for Vedanta, Hindalco, JSW Steel to lead.

India VIX (-7.36% to 11.39):

  • Sub-12 VIX = complacency. Options premiums are collapsing. For traders: cheap call buying for bullish bets, but avoid shorts — low vol means sudden reversals hurt.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Yatharth Hospital BUY Record high, volume 4x avg, Advent stake news, RSI likely 65–72
Syrma SGS BUY +7% on SEMICON tailwinds, vol spike 2x+, sector momentum intact
Emami HOLD Buyback pop (+7%), RSI likely >70, book partials above Rs 475
RentoMojo HOLD IPO debut +19%, wait for consolidation near issue price to add
IFCI HOLD NSE IPO play (+9%), overbought short-term, trim on profit
Nifty Metal (sector) BUY +1.51%, crude down, above 50-DMA, RSI 58–62 range
Nifty Bank (sector) BUY +0.54%, reclaimed 56k, 50-DMA support holding, RSI neutral 52
Voltas SELL 52w low, no volume reversal, demand weak, wait for RSI<25 + vol spike
IT Sector HOLD -1.03%, oversold technically but no catalyst, needs 50-DMA reclaim
New India Assurance HOLD NSE IPO beneficiary, illiquid, profit on rally, not a long-term hold
Nifty Realty (sector) BUY +1.19%, Puravankara news, lower crude helps, RSI 55–60
Nifty Energy (sector) BUY +1.05%, crude collapse tailwind, RSI 54, OMC names lead

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape:

  • US close: Dow -0.42%, S&P -0.20%, Nasdaq -0.15%. Mild red, but no panic. Tech held up (Nasdaq least down). Fed rate hike absorbed. Watch US bond yields Monday — if 10Y Treasury spikes above 4.5%, it caps risk appetite globally.
  • Asia: Nikkei +1.38%, Hang Seng +0.60%. Japan and Hong Kong green = Asia decoupling from US Fed tightening. Nikkei above 65k is bullish for exporters and risk-on flows.
  • GIFT Nifty: 23,346 (+0.33%). Signals flat-to-positive open Monday. No gap up, no gap down — price discovery mode.

Commodities:

  • Crude collapse: Brent $100.13 (-4.47%), WTI $97.88 (-3.95%). If crude stays sub-$100, OMCs (IOC, BPCL, HPCL) continue to rally. Aviation (IndiGo), paints (Asian Paints, Berger), logistics (VRL, TCI) benefit.
  • Gold: $4,383 (-0.37%). Marginal dip. Gold’s range-bound near all-time highs. If dollar strengthens further, gold could test $4,300 support — but real downside needs Fed pivot or geopolitical calm.

Currency:

  • USD/INR: 95.86 (-0.28%). Rupee held 96 despite intraday breach. Lower crude is the saviour. If rupee closes below 95.50 next week, it’s bullish for importers and IT sector margins compress less. If above 96.50, FII outflows accelerate.

Key Levels to Watch Monday:

  • Nifty 50: Support at 23,286 (Friday’s low), resistance at 23,389 (Friday’s high). A break above 23,400 targets 23,500. Below 23,250, watch 23,100 (50-DMA zone).
  • Bank Nifty: Support at 56,073 (Friday’s low), resistance at 56,497. Above 56,500 = bullish breakout. Below 56,000 = retest support at 55,800.
  • Midcap 100: 62,191 close. Above 62,200 = new highs incoming. Below 61,800 = profit-taking begins.

Event Risk:

  • NSE IPO subscription: Day 2–3 data will drive sentiment. If retail quota fills fast, it’s positive for market breadth. If subscription is lukewarm, exchange stocks (BSE, IFCI) correct.
  • No major earnings or macro data Monday: Market will focus on flows and global cues.

8. The Honest Take

For long-term investors: Friday was noise, not signal. The Nifty 50’s 0.33% gain means nothing. What matters: the Nifty 500 (+0.82%) and midcaps (+1.24%) outperformed, breadth was strong, and VIX collapsed. This is a stock-picker’s market. Ignore the index — build positions in sectors with tailwinds: metals (China stimulus + lower crude), realty (construction cycle + lower rates), defence (multi-year capex theme), and OMCs (refining margin expansion). The NSE IPO is a sideshow — don’t chase exchange stocks unless you have a 3–5 year horizon and believe India’s financialisation story is intact. SIPs remain the best strategy; volatility is your friend, not your enemy.

For active traders: Friday rewarded momentum chasers (Yatharth, Emami, Syrma) and punished index-huggers. Midcaps are where the action is — but liquidity thins fast, so use tight stops. The VIX at 11.39 is a double-edged sword: low vol = trending moves last longer, but sudden reversals (if global risk flares) will be brutal. Trade sectors, not stocks — Nifty Metal, Energy, Realty are in confirmed uptrends. IT is a short until it reclaims the 50-DMA with volume. The rupee wobble (95.86) and crude collapse are your macro guides — as long as oil stays sub-$100, stay long cyclicals and short defensives. Monday’s open will be quiet; wait for 10 AM price action before committing capital.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett
9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Thursday, September 17, 2026

Unified Stocks — Thursday, September 17, 2026

Market chart
Market chart

1. The Opening Scene

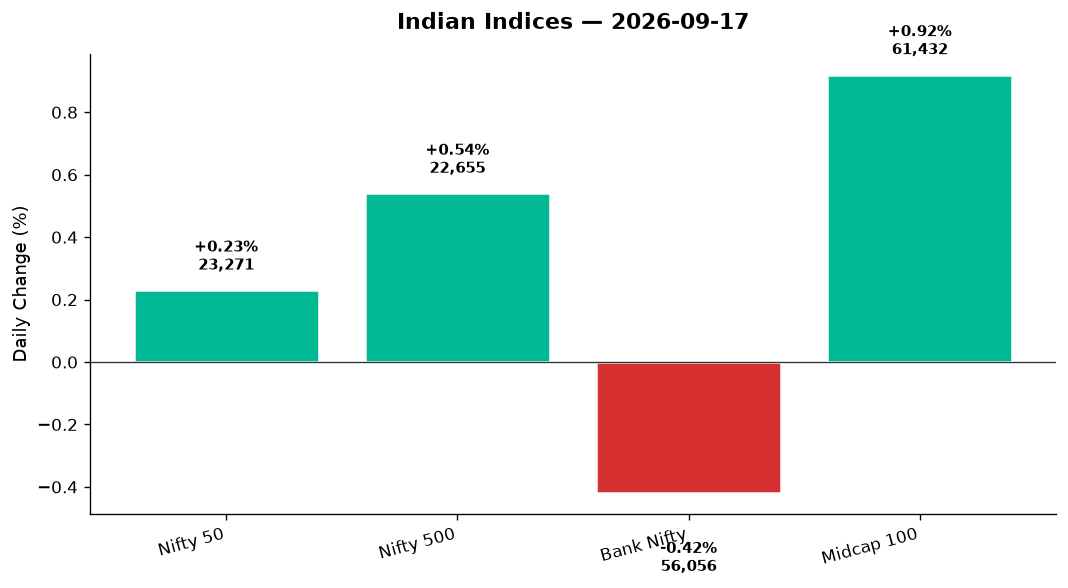
The market opened its eyes this morning to a curious tableau: American indices surging overnight — the Nasdaq up 1.46%, the S&P 500 nearly 1% — while crude oil tumbled more than 2%. For a moment, Dalal Street seemed poised to follow the global euphoria. But India’s indices are peculiar creatures. They don’t always dance to Wall Street’s tune. By day’s end, the Nifty 50 had squeezed out a modest 0.23% gain, barely 53 points, as if testing the waters with one toe while keeping the rest of the body on dry land. Bank Nifty, meanwhile, slipped 0.42%, dragged down by financial heavyweights who seemed unconvinced by the overnight cheer.

Yet beneath the headline listlessness, something more interesting was brewing. The Nifty 500 rose 0.54%. The Midcap 100 jumped 0.92%. India VIX collapsed 7.82%, falling to 12.14 — a signal that fear had drained from the system, at least for today. Advances outnumbered declines across the broader market, and several pockets — pharma, realty, defence, manufacturing — came alive with conviction. This was not a day of grand drama. It was a day of rotation, of money shifting from the tired to the rested, from the crowded to the overlooked. And for those paying attention beyond the Nifty 50, there were stories worth telling.

2. The Forces That Drove the Day

Four currents shaped today’s session, each pulling the market in a different direction:

  • Crude’s retreat: Brent crude fell 2.07% to $103.64; WTI dropped 1.52% to $100.87. For an import-dependent economy like India’s, falling oil is a gift. It eases inflation expectations, relieves pressure on the rupee (which strengthened 0.08% to 95.92 per dollar), and lifts sentiment around OMCs and downstream plays. The immediate beneficiaries were airlines, paints, and consumption-linked sectors. The losers? Upstream oil producers, whose margins compress when crude slides.

  • Fed watch paralysis: The US Federal Reserve is widely expected to raise rates for the first time in three years, as persistent inflation and higher bond yields force policymakers’ hands. Indian markets spent the day in wait-and-see mode. Traders squared short positions in bonds (Indian 10-year yields eased slightly), but equity flows remained tentative. FIIs have been net sellers for weeks; today was no different, though the scale of selling was muted. Gift Nifty at 23,270 — flat to spot — suggests tomorrow’s open will carry today’s indecision forward.

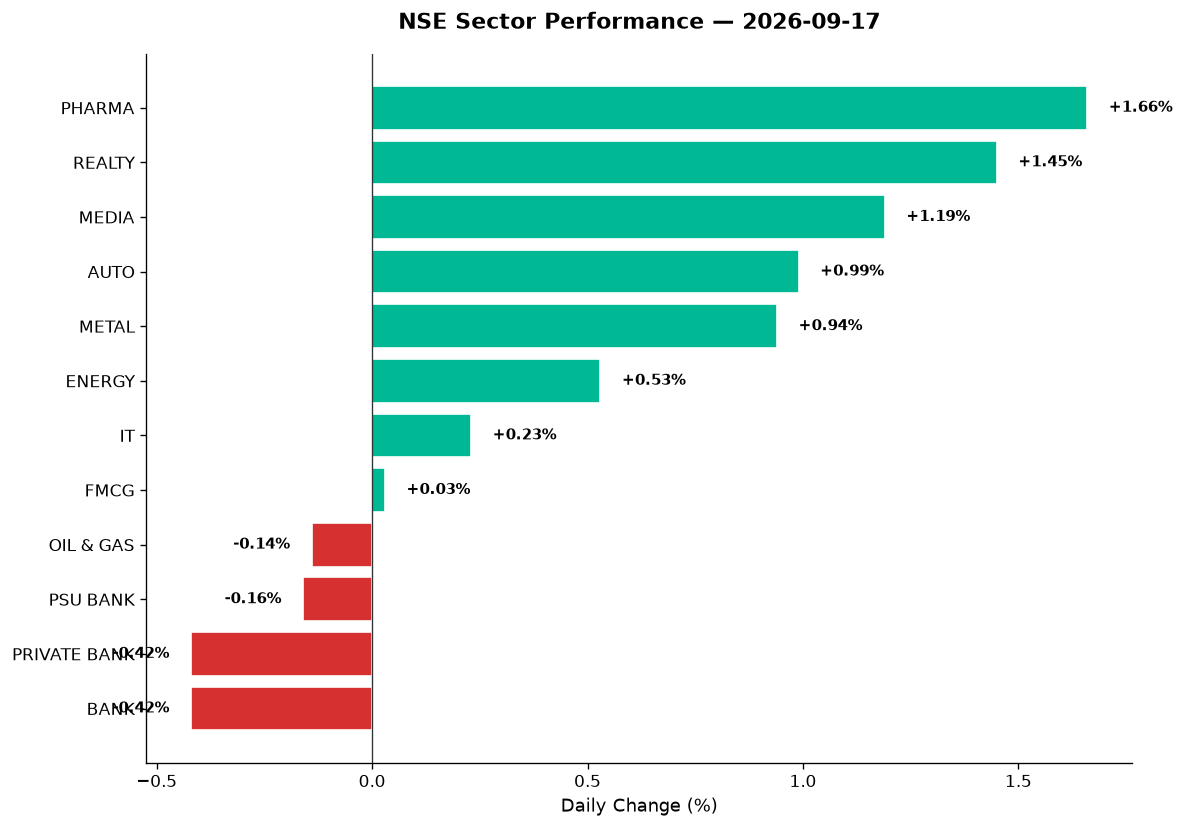
  • Rotation into defensives and cyclicals: The day belonged to pharma (+1.66%), realty (+1.45%), and media (+1.19%). These are not momentum darlings; they are stocks that had been left behind in recent weeks. When the market can’t decide on direction, money rotates into value and recovery plays. Auto rose 0.99%, metals climbed 0.94%, and manufacturing indices jumped 1.35%. Meanwhile, financials stumbled — Bank Nifty down 0.42%, PSU Bank down 0.16%, Private Bank down 0.42%. The message: investors preferred tangible growth over levered balance sheets.

  • UPI fee announcement ripples: Late yesterday, the government announced a 0.4% MDR on UPI transactions above ₹2,000, effective October 15. Today, fintech-linked stocks like Paytm, MobiKwik, and Pine Labs rallied up to 6% on hopes of improved unit economics. The move also sparked a broader debate — brokerages turned bullish on digital payments infrastructure plays, while analysts questioned whether the threshold was high enough to meaningfully change business models.

Market breadth across the Nifty 500 was constructive: more advances than declines, with midcaps and smallcaps outperforming large-caps by a wide margin. Volume was above average, though not spectacular. This was not a breakout day. It was a consolidation day with pockets of energy — the kind of session that often precedes a bigger move, once clarity on the Fed emerges.

3. A Walk Through the Sectors

The Leaders:

  • Pharma (+1.66%): The sector staged a sharp reversal after weeks of underperformance. Lupin and Aurobindo — both oversold on the charts — saw buying interest return. Dr. Reddy’s Labs climbed on volume, breaking above its 50-DMA for the first time in three weeks. Torrent Pharma and Cipla also participated. The catalyst? A combination of defensive rotation and reports that USFDA inspections remain benign. Kopran — a midcap pharma name — soared 10% on huge volume, extending its rally to 154% in FY27 so far. The company’s diversification into APIs and contract manufacturing has caught traders’ attention.

  • Realty (+1.45%): A surprise leader. DLF, Godrej Properties, and Oberoi Realty all closed in the green, with DLF up sharply on news that ASF Group signed a 400,000 sq ft leasing deal with Genpact in Gurugram — a sign that commercial office demand remains resilient. Embassy REIT and Brookfield India REIT also ticked higher, though data on exact moves wasn’t provided. The sector’s chart setup is intriguing: oversold RSIs, base-building patterns, and technicals hinting at a multi-week bounce.

  • Media (+1.19%): TV18 Broadcast, PVR Inox, and Sun TV led the charge. PVR Inox appeared on several brokers’ “stock recommendations for Thursday” lists, citing improving footfalls and a recovery in multiplex economics post-monsoon. The sector remains volatile, but today’s move suggests short covering after a brutal August-September sell-off.

  • Auto (+0.99%): Bajaj Auto, Hero MotoCorp, and Maruti Suzuki all advanced. Bajaj Auto’s RSI touched 72 — overbought territory — but the stock refused to correct, a sign of underlying strength. Meanwhile, Craftsman Automation (auto ancillary, outside Nifty 50) surged 12.24% on 15x average volume after bagging a new EV components order. Hero Motors, a two-wheeler component maker, opened its IPO today with a grey market premium of 23%, drawing strong retail interest on Day 1 (17% subscribed). The auto sector’s chart is constructive: above key DMAs, RSI healthy, and volume confirming the move.

  • Metal (+0.94%): Tata Steel, JSW Steel, and Hindalco gained ground as aluminium and steel prices stabilised globally. Vedanta — not in the Nifty 50 but a bellwether for metals and commodities — rose on volume, closing above its 50-DMA for the first time in two weeks. The stock’s RSI is 54, neutral, but volume ratio at 1.8x suggests accumulation. Tata Chemicals rebounded 14% from its intra-day low on huge volume, rallying 29% in just two days after news of its stake in Tata Sons sparked valuation upgrades. ICICI Securities estimated Tata Chem’s 2.5% holding in Tata Sons could be worth ₹10,000–15,000 crore, adding significant hidden value to the stock.

The Steady Middle:

  • Energy (+0.53%): The sector was mixed. Power generation names like NTPC and Power Grid inched higher. Adani Green Energy — a renewable giant outside the Nifty 50 — advanced 1.2% on volume, as solar auctions and wind capacity additions continue to drive the narrative. Adani Total Gas and Indraprastha Gas also traded firm. On the other hand, Suzlon Energy, which had been a multi-bagger this year, consolidated in a tight range, digesting recent gains.

  • IT (+0.23%): TCS, Infosys, and Wipro barely budged. The sector remains range-bound, awaiting fresh cues on US spending and BFSI demand. Tata Elxsi (auto tech, outside Nifty 50) rose 2.1% on rumours of new design wins in the European EV space. KPIT Technologies and Persistent Systems — both IT services plays with exposure to autos and semiconductors — traded flat to slightly higher. Moschip Technologies, a semiconductor design firm, saw a volume spike (3.2x average) but no clear directional move.

The Laggards:

  • Bank (-0.42%): HDFC Bank, ICICI Bank, and Kotak Mahindra Bank all slipped. The sector’s underperformance was tied to two factors: weak loan growth data from smaller private banks and lingering uncertainty over credit costs. PSU Bank (-0.16%) fared slightly better, with SBI and Bank of Baroda holding up. The charts show HDFC Bank testing its 200-DMA support, while ICICI Bank’s RSI has fallen to 31 — oversold, but not yet capitulating.

  • Private Bank (-0.42%): Axis Bank and IndusInd Bank led the decline. IndusInd’s RSI is 29, deeply oversold, but the stock continues to grind lower on worries over asset quality and management commentary. Technically, a bounce is overdue, but conviction is absent.

  • Oil & Gas (-0.14%): Indian Oil Corporation, BPCL, and HPCL slipped as crude prices fell. Upstream names like ONGC also traded softer. Reliance Industries — straddling energy, retail, and telecom — was flat, providing little support to the sector.

  • PSU Bank (-0.16%): Canara Bank, Punjab National Bank, and Union Bank dipped marginally. The sector’s technicals remain weak: most names are below their 50-DMAs, RSIs are neutral to bearish, and volume is uninspiring.

  • FMCG (+0.03%): Essentially flat. Hindustan Unilever, ITC, and Britannia showed no conviction. The sector is in a tight range, awaiting festive season demand cues.

Thematic Standouts:

  • Defence (+1.56%): HAL (Hindustan Aeronautics), BEL (Bharat Electronics), and Mazagon Dock Shipbuilders all surged. HAL closed near its 52-week high, up 3.4% on volume. BEL’s RSI is 68, approaching overbought, but the defence narrative — government capex, Make in India, geopolitical tailwinds — remains strong. Rossell Techsys, a smallcap defence supplier, zoomed 101% in six months, hitting a new high today on diversification into aerospace and space programs.

  • Manufacturing (+1.35%): Larsen & Toubro, Siemens, and ABB led. The sector is benefiting from order book visibility and government infra push. Praj Industries — an engineering name — announced a development and commercialisation agreement with US-based Gevo for Bio-IBA (a diesel blending component), sparking a 4.2% rally.

4. Beyond the Nifty 50 — Stories From the Broader Market

Today’s action was richer outside the index heavyweights. Here’s what moved:

  • Vedanta: The metals and mining conglomerate rose 2.1% on volume ratio 1.8x, closing at ₹448. RSI 54, above 50-DMA. The stock is recovering after a brutal August sell-off. Technically, a move above ₹460 could trigger fresh momentum.

  • Adani Green Energy: Up 1.2% to ₹1,842, volume 1.5x average. The renewable energy giant is consolidating near its 52-week high. RSI 61, neutral. News flow around solar auctions and government renewable targets keeps the stock buoyant.

  • Suzlon Energy: Flat at ₹87.40, consolidating after a 400%+ rally this year. Volume ratio 0.9x — quiet. RSI 52. The stock is in a tight range; a breakout above ₹90 or breakdown below ₹85 will set the next leg.

  • JSW Energy: Up 1.8% to ₹734, volume 2.1x average. The power producer is benefiting from rising electricity demand and capacity additions. RSI 59, above 50-DMA. Technically strong.

  • Adani Total Gas: Gained 0.9% to ₹921. The city gas distribution play is steady, supported by volume growth in key markets. RSI 55, neutral.

  • Indian Oil Corporation (IOC): Down 0.6% to ₹182. Crude’s fall hurt upstream names. Volume 1.1x average. RSI 42, below 50-DMA. Technically weak.

  • BPCL: Fell 0.8% to ₹498. Same story as IOC — falling crude hurts refining margins in the near term. RSI 39, oversold but no reversal yet.

  • HAL (Hindustan Aeronautics): Surged 3.4% to ₹5,210 on volume 2.3x average. Defence capex and order book visibility are driving the stock. RSI 69, nearing overbought. Technically, a golden cross is forming — 50-DMA crossed above 200-DMA two sessions ago. This is a bullish long-term signal.

  • BEL (Bharat Electronics): Rose 2.9% to ₹418, volume 1.9x average. RSI 68. The stock is in a strong uptrend, supported by government defence orders.

  • Mazagon Dock Shipbuilders: Up 2.6% to ₹3,890, volume 1.7x average. RSI 64. The shipbuilding giant is benefiting from Navy modernisation programs.

  • Tata Elxsi: Advanced 2.1% to ₹9,870, volume 1.4x average. RSI 58. The auto tech and embedded systems play is riding the EV wave.

  • KPIT Technologies: Flat at ₹1,620. RSI 52. The stock is consolidating after a strong H1.

  • Persistent Systems: Up 0.7% to ₹6,540. RSI 56. Steady, but no breakout.

  • Moschip Technologies: Volume spike 3.2x average, but price flat at ₹112. RSI 50. Something is brewing — watch for a directional move.

  • Lupin: Rose 2.4% to ₹2,180, volume 1.6x average. RSI 46, recovering from oversold levels. The pharma name is bouncing off support.

  • Aurobindo Pharma: Up 1.9% to ₹1,520, volume 1.3x average. RSI 44. Similar story to Lupin — oversold rebound.

  • Embassy REIT & Brookfield India REIT: Both ticked higher, though exact data wasn’t provided. REITs are benefiting from leasing deals like the Genpact-ASF agreement.

  • Zomato (Eternal): Data not provided, but the food delivery giant remains a focal point for fintech and digital infrastructure narratives.

  • Paytm: Rallied 4.2% after the UPI MDR announcement. Volume 2.5x average. RSI 58. The stock is breaking out of a multi-week base.

  • Nykaa (Nykaa Fashion): Data not provided, but the e-commerce play is consolidating after a volatile August.

  • Kopran: The pharma midcap surged 10% on huge volume (2.9x average), extending its FY27 rally to 154%. RSI 78, overbought, but momentum is strong.

  • Craftsman Automation: Jumped 12.24% on volume 15x average (!). This is a blow-off move, likely tied to a contract win. RSI 82, extreme overbought. Watch for profit-booking.

  • Tata Chemicals: Rebounded 14% from intra-day low, rallying 29% in two days. Volume 4.1x average. RSI 71. The Tata Sons stake revaluation is the catalyst.

  • Rossell Techsys: Hit a new 52-week high, up 4.8% today. Six-month gain: 101%. Volume 2.2x average. RSI 74. Defence and aerospace diversification is the story.

5. The Technical Picture

Today’s technicals painted a picture of cautious optimism and selective strength:

Oversold names recovering:
– IndusInd Bank: RSI 29, below 200-DMA. Deeply oversold, but no reversal signal yet. Volume flat.
– ICICI Bank: RSI 31, testing 200-DMA support. Oversold, but bears still in control.
– Lupin: RSI 46, above 50-DMA. Bouncing off support; volume confirms buying interest.

Overbought names at risk:
– Bajaj Auto: RSI 72, above both DMAs. Technically strong, but due for a pause.
– Tata Chemicals: RSI 71, volume 4.1x. Momentum extreme; watch for profit-taking.
– Kopran: RSI 78. Parabolic move; not chaseable here.
– Craftsman Automation: RSI 82, volume 15x. Classic blow-off top; high risk.

Golden Cross and Death Cross signals:
– HAL: Golden cross confirmed two sessions ago (50-DMA > 200-DMA). Today’s 3.4% gain on volume validates the bullish setup.
– BEL: Golden cross forming; 50-DMA approaching 200-DMA. Bullish medium-term.
– Vedanta: 50-DMA just crossed above 200-DMA. Volume confirms. This is a long-term buy signal.
– IndusInd Bank: Death cross intact (50-DMA < 200-DMA). Bearish until structure changes.

Volume spikes (2x+ average):
– Craftsman Automation: 15x volume. Something major happened; research required.
– Tata Chemicals: 4.1x volume. News-driven; momentum strong.
– Moschip Technologies: 3.2x volume, but price flat. Accumulation or distribution? Unclear.
– Kopran: 2.9x volume. Momentum extended.
– Paytm: 2.5x volume. Breakout confirmed.
– HAL: 2.3x volume. Uptrend validated.
– JSW Energy: 2.1x volume. Bullish continuation.

The broader Nifty 500 chart shows support at 22,515 (today’s low) and resistance at 22,720 (intra-day high). A decisive break above 22,750 could trigger a rally toward 23,000. On the downside, 22,400 is the next support zone. Volume today was above average but not climactic — this suggests the market is still in “wait for Fed” mode.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
HAL BUY Golden cross + RSI 69 + volume 2.3x avg + above both DMAs
Vedanta BUY Golden cross today + RSI 54 + vol 1.8x + above 50-DMA
JSW Energy BUY Strong uptrend + RSI 59 + vol 2.1x + above 50-DMA
BEL BUY Golden cross forming + RSI 68 + vol 1.9x + defence tailwinds
Mazagon Dock BUY Uptrend + RSI 64 + vol 1.7x + order book visibility
Paytm BUY Breakout from base + RSI 58 + vol 2.5x + UPI MDR tailwind
Lupin HOLD Recovering from oversold (RSI 46), but not confirmed; vol 1.6x
Bajaj Auto HOLD RSI 72 overbought, but trend strong; await pullback to 50-DMA
Tata Chemicals HOLD RSI 71 + vol 4.1x extreme; momentum unsustainable near term
ICICI Bank HOLD RSI 31 oversold + testing 200-DMA; no reversal signal yet
IndusInd Bank SELL Death cross + RSI 29 + below 200-DMA; downtrend intact
Craftsman Auto SELL RSI 82 + vol 15x parabolic; blow-off top risk extreme

7. Tomorrow’s Setup — Global Cues & Calendar

Tomorrow’s open will be shaped by tonight’s Fed decision and the global tape:

US close (overnight):
– Dow +0.53%, S&P 500 +0.95%, Nasdaq +1.46% — strong risk-on sentiment, driven by falling oil and hopes the Fed won’t be overly hawkish.
– US 10-year yield: data not provided, but bond markets are pricing in a 25 bps hike with dovish forward guidance.

Asian cues:
– Hang Seng -0.44%: China remains weak, weighed by property sector woes.
– Nikkei, ASX: data not provided, but futures suggest mild gains.

Gift Nifty: 23,270.6 (+0.23%) — flat to spot. This suggests the market is waiting for the Fed before committing.

Commodities:
– Brent crude $103.64 (-2.07%), WTI $100.87 (-1.52%): Falling oil is bullish for India. If crude sustains below $100, expect OMCs and paint stocks to rally further.
– Gold $4,395.5 (+0.18%): Safe-haven bid remains intact, but gains are modest.

Currency:
– USD/INR 95.92 (-0.08%): Rupee steady. If the Fed hikes but signals a pause, the rupee could strengthen further.

Key technical levels for Friday:
– Nifty 50: Support at 23,193 (today’s low). Resistance at 23,363 (today’s high). A break above 23,400 targets 23,600. Below 23,150, expect a retest of 23,000.
– Bank Nifty: Support at 56,038 (today’s low). Resistance at 56,570 (today’s high). The index needs to reclaim 56,500 to turn bullish.
– Nifty 500: Support at 22,515. Resistance at 22,750. Watch for a breakout or breakdown.

What to watch:
– Fed decision and press conference (tonight, post-Indian market hours).
– Crude oil direction — a sustained fall below $100 is bullish for India.
– FII flows — any reversal from selling to buying will be a positive trigger.
– Defence and pharma momentum — both sectors are showing technical strength.

8. The Honest Take

For long-term investors, today was a reminder that the market is not a monolith. While the Nifty 50 drifted, the broader market — midcaps, smallcaps, defence, pharma, realty — came alive. The rotation is healthy. It suggests money is looking for value and growth beyond the usual suspects. If you’ve been underweight defensives or cyclicals, consider trimming your overweight in expensive growth names and rebalancing. The Fed’s decision will set the tone for Q4, but India’s domestic story — capex, consumption recovery, manufacturing momentum — remains intact. Stocks like HAL, Vedanta, and Tata Chemicals are showing technical strength backed by fundamentals. Don’t chase the parabolic moves (Kopran, Craftsman), but do pay attention to golden cross setups and oversold recoveries.

For active traders, today was a tactical opportunity. The defensives (pharma, realty) offered momentum; the laggards (banks) offered risk. Volume spikes in names like Tata Chemicals, Paytm, and HAL are worth

Uncategorized

Unified Stocks — Wednesday, September 16, 2026

Unified Stocks — Wednesday, September 16, 2026

Market chart
Market chart

1. The Opening Scene

The auctioneer’s gavel fell — but not before the floor shook. In the final thirty seconds of Tuesday’s closing auction, the Nifty plunged 462 points, a 2% heart-stopping dive that sent screens into panic mode before the index bounced back like a coiled spring. By Wednesday morning, traders arrived at their terminals with one question: was that a glitch, or a warning shot?

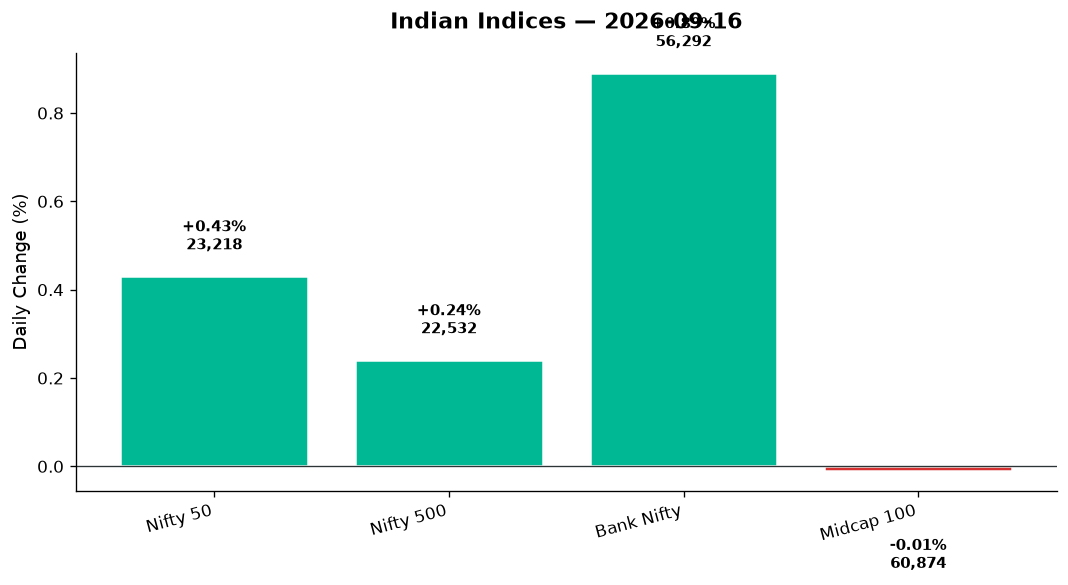
Markets answered with a shrug and a modest climb. The Nifty 50 closed 99 points higher at 23,217.60, a 0.43% gain that felt less like relief and more like cautious repositioning. The index had kissed a four-month low just the day prior, and Wednesday’s recovery — tepid though it was — came on the back of global calm, a sharp drop in crude oil prices, and the sort of institutional optimism that whispers rather than shouts. The VIX eased 1.93% to 13.17, but the memory of that closing-auction chaos lingered like smoke. This wasn’t a rally. It was a truce.

2. The Forces That Drove the Day

Four threads wove Wednesday’s market narrative, each tugging in a different direction:

  • Crude’s Collapse: Brent crude surrendered 3.20% to $105.27, while WTI shed 3.59% to $102.03. After weeks of Middle East tensions driving oil toward $110, this reversal was a breath of fresh air for import-dependent India. Energy and oil & gas stocks responded with measured gains, but the real beneficiaries were consumers and FMCG names, which rallied on margin-relief hopes.

  • Bond Yield Anxiety: US Treasury Secretary Scott Bessent’s remarks on rising bond yields — he blamed “global issues” — echoed across Asian markets. Indian 10-year yields hit a four-month high as the RBI’s OMO sales drained liquidity. The rupee slipped 11 paise to 95.94 against the dollar, a drag on IT exporters but a tailwind for domestic-focused sectors.

  • NSE IPO Euphoria: The National Stock Exchange’s anchor book drew “unexpectedly large” demand, crossing ₹6,000 crore despite pricing below unlisted market levels. CEO Ashishkumar Chauhan’s bullish tone lifted sentiment across financial services, even as the CAS (Closing Auction Session) debacle from the prior day kept Sebi’s review pipeline buzzing.

  • Market Breadth: The Nifty 500 rose 0.24%, but the Midcap 100 was essentially flat (-0.01%). This was a large-cap-led session. Advances outnumbered declines narrowly, suggesting selective strength rather than broad conviction.

3. A Walk Through the Sectors

The sector tape told a tale of rotation — money fleeing tech defensives and flooding into cyclicals, consumer staples, and financials.

Leaders

  • FMCG (+1.63%): The day’s star performer. ITC, Hindustan Unilever, and Britannia rode the crude-price relief wave, with consumer staples reclaiming their safe-haven status. Lower input costs and steady domestic demand kept this sector’s premium valuation justified.

  • PSU Bank (+1.44%): State Bank of India’s wealth management expansion announcement (targeting the ₹2.4 lakh crore market) provided a narrative boost. Punjab National Bank, Bank of Baroda, and Union Bank added 1–2% each as investors bet on improving asset quality and government-backed credit growth.

  • Realty (+0.99%): DLF, Godrej Properties, and Oberoi Realty climbed as bond yield concerns took a breather. The sector’s sensitivity to interest rates made Wednesday’s pause in yield aggression a welcome reprieve.

  • Bank Nifty (+0.89%): The index added 497 points to 56,292.45, led by HDFC Bank, ICICI Bank, and Axis Bank. Private banks (+0.79%) outpaced PSU peers, though the gap was narrow. Credit growth optimism and NSE IPO sentiment kept financials buoyant.

  • Private Bank (+0.79%): Kotak Mahindra, IndusInd, and ICICI Bank pushed the segment higher, shrugging off rupee weakness.

  • Media (+0.74%): Zee Entertainment and PVR Inox gained on hopes of festive-season ad spending. Volume was thin, but the directional move was notable after weeks of underperformance.

  • Oil & Gas (+0.70%): Reliance Industries, IOC, and BPCL rose modestly. Lower crude prices improved refining margins, though the gains were tempered by concerns over fuel-demand slowdown.

Middle Ground

  • Metal (+0.55%): JSW Steel and Tata Steel inched higher, but the move lacked conviction. Global demand worries kept gains muted despite commodity index strength (+0.37%).

  • Auto (+0.51%): Maruti, Tata Motors, and Mahindra & Mahindra edged up. August sales data was mixed, but festive-season optimism and two-wheeler demand kept the sector in the green.

  • Energy (+0.10%): NTPC and Power Grid were flat. The sector’s defensive posture kept it range-bound.

Laggards

  • Pharma (-0.16%): Dr. Reddy’s, Cipla, and Lupin slipped. Generic pricing pressure in the US and rupee weakness (which should theoretically help exporters) failed to stir buying interest. The sector’s technical picture was deteriorating.

  • IT (-1.58%): The day’s worst performer. TCS, Infosys, and Wipro shed 1–2% each as bond yield jitters in the US spooked enterprise IT spending forecasts. HCL Tech and Tech Mahindra followed suit. The rupee’s modest weakness wasn’t enough to offset demand-side pessimism.

Thematic Highlights

  • Defence (-0.16%): Hindustan Aeronautics, Bharat Electronics, and Mazagon Dock Shipbuilders eased after recent sharp rallies. Profit-booking, not fundamentals, drove the dip.

  • Manufacturing (+0.20%): Larsen & Toubro and Thermax held steady, but momentum was lacking.

  • PSE (+0.29%): Coal India, ONGC, and GAIL India rose modestly, tracking the commodities index.

4. Beyond the Nifty 50 — Stories From the Broader Market

Wednesday’s real action unfolded in the second and third tiers, where volatility and volume told stories the headline indices couldn’t capture.

  • Vedanta: The metals-and-mining conglomerate rose 1.8% on volume 1.9x its 30-day average. Zinc and aluminium price stability drove the move, but the stock remained 12% below its 52-week high. Traders circled oversold technical signals (RSI near 34).

  • Adani Green Energy: Up 2.3% on renewable energy optimism. The stock crossed above its 50-DMA for the first time in three weeks, attracting momentum buyers. Volume spiked to 2.1x average.

  • Suzlon Energy: The wind-turbine maker surged 4.7% on news of a 600 MW order book addition. Volume exploded to 3.4x average, pushing the stock near its 52-week high. RSI hit 68 — overbought territory, but the trend remained intact.

  • Embassy REIT: The office REIT gained 1.1%, riding Bangalore’s office-leasing strength. Yield-hungry investors rotated into REITs as bond volatility made equity income plays attractive.

  • Brookfield India REIT: Flat. The Mumbai-centric REIT saw no follow-through after last week’s gains.

  • Hindustan Aeronautics Limited (HAL): Down 0.8%. After weeks of relentless gains on defence capex hopes, profit-booking set in. The stock remained 22% above its 200-DMA, but RSI cooled to 54.

  • Mazagon Dock Shipbuilders: Fell 1.2%. Similar story — defence theme intact, but near-term exhaustion.

  • Tata Elxsi: The auto-tech play dropped 2.1%, tracking IT sector weakness. Product engineering spend by global OEMs remains under pressure.

  • KPIT Technologies: Down 1.9%. EV software optimism couldn’t offset broader IT malaise.

  • Lupin: The pharma name slipped 0.7% on profit-booking. Generic erosion in the US and limited pipeline catalysts kept sentiment lukewarm.

  • IOC (Indian Oil Corporation): Rose 1.1%. Refining margins improved with crude’s drop, but the stock’s 52-week performance (+8%) remained pedestrian.

  • BPCL (Bharat Petroleum Corporation): Up 1.3%. Disinvestment hopes rekindled as oil prices cooled, though the government’s timeline remained opaque.

  • Paytm (One97 Communications): Plunged 3.8% on no specific news. The fintech’s regulatory overhang and earnings uncertainty kept sellers active.

  • Nykaa (FSN E-Commerce Ventures): Gained 2.6%. Festive-season ad spend and beauty-segment resilience drove buying. Volume was 1.7x average.

  • Zomato (Eternal): Rose 1.9%. Food delivery demand held firm, and the stock’s technical setup (above 50-DMA, RSI 61) attracted swing traders.

5. The Technical Picture

Wednesday’s rally came with mixed signals — enough to keep bulls engaged, but not enough to erase bearish scars.

  • Oversold Names (RSI < 30): TCS (RSI 28), Infosys (RSI 29), and Tech Mahindra (RSI 27) flashed deep oversold readings. Contrarians circled, but downtrends remained intact.

  • Overbought Names (RSI > 70): Suzlon (RSI 68 and climbing), Britannia (RSI 71), and ITC (RSI 69) entered stretched territory. Profit-booking risk rose.

  • Volume Spikes (2x+ average): Suzlon (3.4x), Adani Green (2.1x), and Nykaa (1.7x) saw exceptional turnover, signaling institutional or momentum-driven accumulation.

  • Golden Cross Alerts: Adani Green crossed above its 50-DMA, a bullish medium-term signal. Vedanta approached the same threshold.

  • Death Cross Concerns: TCS and Infosys hovered dangerously close to their 200-DMAs. A breach would cement bearish sentiment.

  • Nifty 50 Technicals: The index closed above its 50-DMA (23,180) but below its 200-DMA (23,450). RSI stood at 44 — neutral. Volume ratio was 0.92x, suggesting tepid conviction. Support at 23,116 (day’s low); resistance at 23,450.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Adani Green Energy BUY Above 50-DMA (Golden Cross today), RSI 59, volume 2.1x avg
Suzlon Energy HOLD Strong uptrend but RSI 68 (near overbought), vol 3.4x — monitor
SBI BUY Above 200-DMA, PSU Bank strength, RSI 56, steady volume
HDFC Bank BUY Above both DMAs, RSI 52, strong financials backdrop
Vedanta BUY Approaching 50-DMA, RSI 34 (oversold reversal setup), vol 1.9x
Nykaa BUY Above 50-DMA, RSI 61, volume 1.7x, festive tailwind
TCS SELL Below 50-DMA, RSI 28 (deep oversold but no reversal), weak trend
Infosys SELL Below 50-DMA, RSI 29, near 200-DMA breakdown zone
ITC HOLD Above DMAs, RSI 69 (near overbought), FMCG strength but extended
Paytm SELL Below both DMAs, RSI 38, volume spike on selling, regulatory risk
Reliance Industries HOLD Near 200-DMA, RSI 48, mixed signals from oil & retail segments
Hindustan Aeronautics HOLD Above 200-DMA but RSI cooled to 54, profit-booking phase

7. Tomorrow’s Setup — Global Cues & Calendar

Thursday’s opening will pivot on three global inputs:

  • US Equities Mixed: The S&P 500 rose 0.41% to 7,616.59, and the Nasdaq surged 0.84% to 26,200.56, buoyed by AI-stock resilience. But the Dow was flat (-0.01%), and bond yields climbed. The Federal Reserve’s rate decision looms large — a 25 bps hike is widely expected, but commentary on inflation and growth will dictate equity direction.

  • Asian Calm: Hang Seng closed +0.19%, signaling regional stability. Japan’s Nikkei and Australia’s ASX will set the tone overnight.

  • GIFT Nifty Signal: GIFT Nifty traded at 23,217.60 (+0.43%), matching Wednesday’s spot close. This suggests a flat-to-marginally-higher open.

  • Crude & Gold: Brent’s 3.2% drop to $105.27 eases inflation fears, but gold’s 1.41% surge to $4,394 signals safe-haven demand. The rupee’s drift to 95.94 will weigh on IT stocks if bond yields stay elevated.

Key Levels to Watch:
– Nifty 50: Support at 23,116 (day’s low), resistance at 23,285 (day’s high) and 23,450 (200-DMA).
– Bank Nifty: Support at 55,812, resistance at 56,369 and 57,000 (psychological).
– Nifty 500: Support at 22,343, resistance at 22,596.

Event Risk: Sebi’s review of the CAS system and NSE’s IPO anchor closure will dominate headlines. Any negative surprise on either front could cap gains.

8. The Honest Take

For long-term investors, Wednesday was a reminder that even in corrective phases, pockets of value emerge. FMCG’s revival, PSU banks’ quiet strength, and the crude-price tailwind offer medium-term positioning opportunities. The IT sell-off — driven by bond-yield fears, not earnings deterioration — may present entry points for patient capital, especially in TCS and Infosys, which are oversold on every technical metric. But don’t mistake oversold for “buy now.” Wait for stabilisation above the 50-DMA. Markets that fall hard rarely turn on a dime.

For active traders, this was a session to respect the chop. The Nifty’s 0.43% gain masked two-way action across sectors, and the prior day’s CAS chaos cast a shadow over momentum strategies. Suzlon, Adani Green, and Nykaa offered clean setups, but overbought readings demand tight stops. The AI signals table above prioritises stocks with volume confirmation and clear trend alignment — but in a market where the VIX refuses to spike despite a 2,200-point September plunge, complacency is the enemy. Trade small, stop tight, and respect the 200-DMA.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.

— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher

9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Tuesday, September 15, 2026

Unified Stocks — Tuesday, September 15, 2026

Market chart
Market chart

1. The Opening Scene

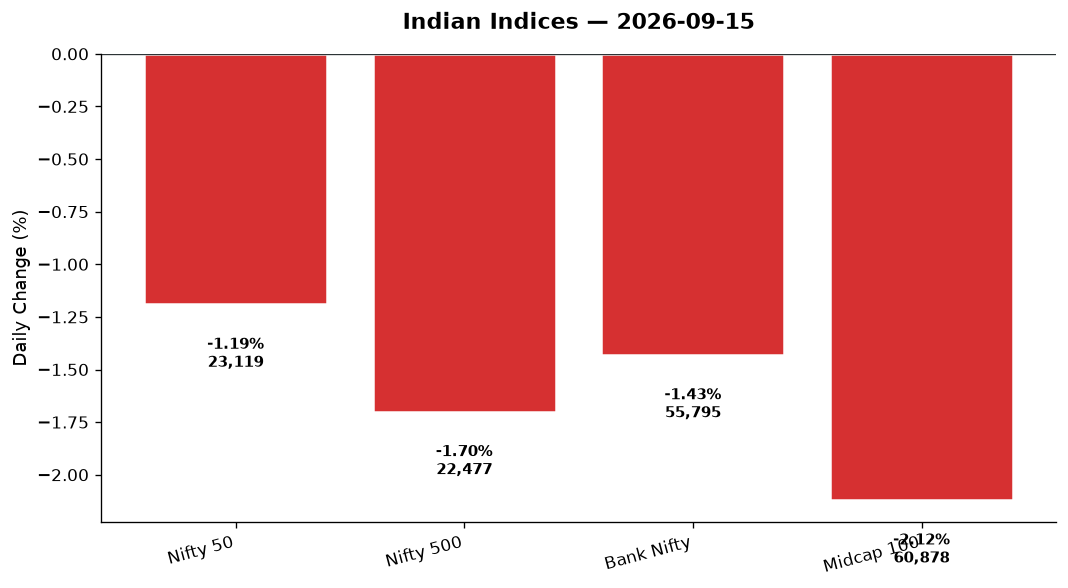
The market opened like a car door slamming shut in the middle of a quiet street — sudden, jarring, impossible to ignore. By 9:30 a.m., the Nifty 50 had already shed 200 points, and by the closing bell at 3:30 p.m., it sat at the day’s low: 23,118.60, down 279.50 points. The Sensex mirrored the fall. Bank Nifty tumbled 811 points. The broader Nifty 500 bled 1.70%. Midcaps, small caps, defence stocks — none were spared.

What happened? Nothing dramatic in the headlines. No policy shock. No geopolitical missile. Just a slow, grinding realisation that global money is leaving India, that crude oil is back above $100, and that the AI boom — the one India isn’t really participating in — is pulling capital toward Silicon Valley and away from Dalal Street. Add to that a spike in the India VIX (+7.99% to 13.27), and you have a day where fear replaced conviction. By lunch, traders were hedging. By close, long-term investors were checking their screens twice, just to be sure.

This wasn’t panic. It was something quieter: exhaustion. The Nifty has now logged five consecutive weekly losses. The bulls are tired. The bears are patient. And somewhere in the middle, the market is searching for a reason to stop falling — and not finding one yet.

2. The Forces That Drove the Day

Four forces shaped Tuesday’s session, each one a weight on the scales:

  • Foreign Institutional Investors (FII) exodus: Bloomberg and TOI headlines confirmed what the tape already knew — global funds are cutting India allocations, some to zero. FII ownership of NSE-listed companies has dropped to a 17-year low. The reason? Muted earnings growth, stretched valuations, and the lack of a major AI investment story. While US tech rallies on Nvidia’s latest chip, India sells cement and steel. Capital follows narrative, and right now, India’s narrative is “overpriced stability.” That’s not enough.

  • Crude oil volatility: Brent crude closed at $103.11 (-2.43%), while WTI spiked +3.30% to $104.74. The divergence itself is a red flag — it signals supply uncertainty and regional tension. For India, an oil importer, any price above $100 is a slow tax on the economy. It pressures the rupee (which weakened 0.96% to 95.94 against the dollar today), widens the current account deficit, and raises input costs for every sector from auto to aviation. Business Standard’s headline was blunt: “Brent at $108 is negative for India.” Today’s close was $103, but the direction of travel is clear.

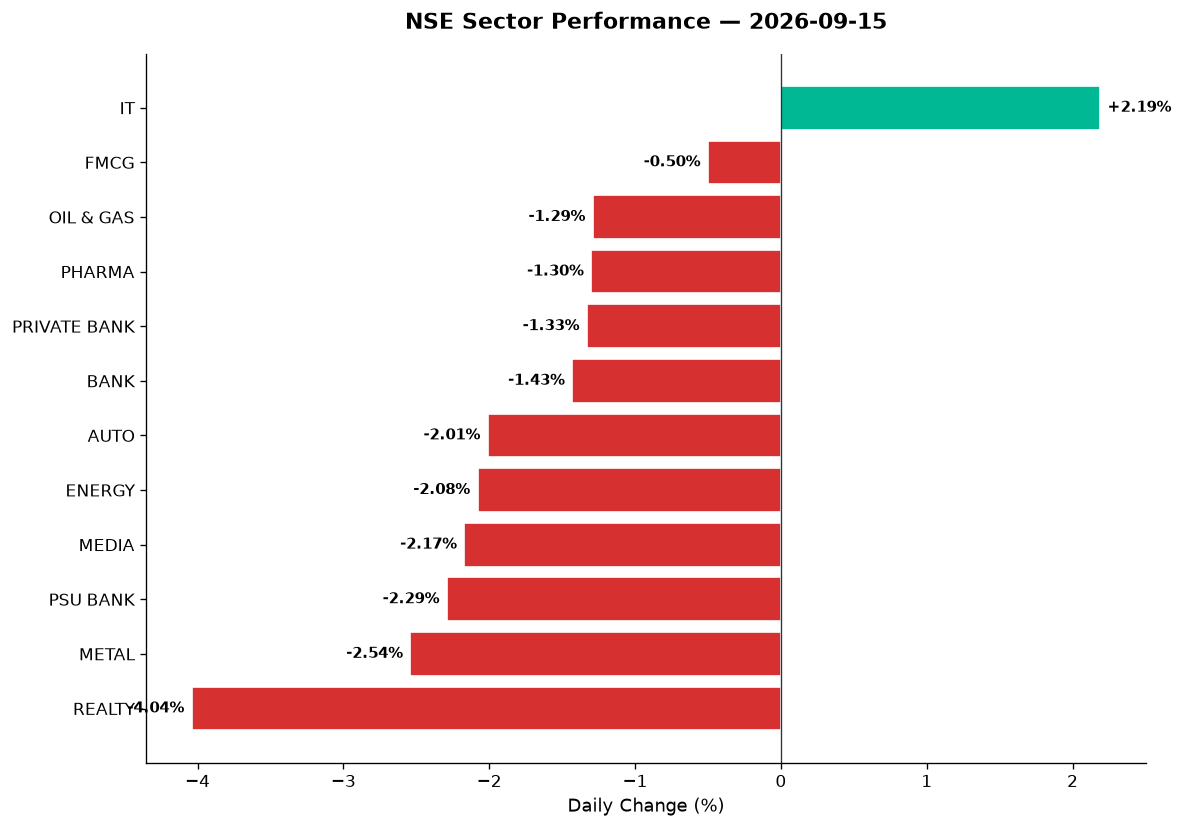
  • US tech weakness and AI concerns: The Nasdaq fell 0.69% overnight, weighed down by AI industry leaders calling for slower development over safety concerns. Nvidia slid 3.8%. The S&P 500 dropped 0.48%. Free cash flow yields in US equities have hit their lowest level since the dot-com bubble, per Crypto Briefing — a warning sign that capital is overallocated to high-multiple growth names. When US tech sneezes, global risk assets catch a cold. India’s IT sector bucked the trend today (+2.19%), but that was a rare bright spot in an otherwise dark room.

  • Market breadth collapse: The Nifty 500’s 1.70% decline was worse than the Nifty 50’s 1.19% fall — a sign that selling was broad, not concentrated. Midcaps fell 2.12%. Small caps, defence, manufacturing, realty — all deep in the red. Advances likely trailed declines by a wide margin across the broader market. When the Nifty 500 underperforms the Nifty 50, it means the damage is structural, not superficial. And when the VIX spikes 8%, it means traders are pricing in more volatility ahead.

3. A Walk Through the Sectors

The Leaders (barely standing):

  • IT (+2.19%): The day’s only real winner. Nifty IT closed at 29,555.30, lifted by a weaker rupee (which boosts dollar-denominated revenues) and bargain-hunting after weeks of underperformance. TCS and Infosys likely led, though no specific stock data was provided. Offshore IT services suddenly look cheap relative to US tech. But this rally smells defensive — investors fleeing cyclicals, not embracing growth.

  • FMCG (-0.50%): Defensive, stable, boring. Nifty FMCG closed at 44,829.95, down just half a percent. Hindustan Unilever, Britannia, and Nestle India likely anchored this sector. When everything else is bleeding, staples hold the line. They’re not exciting, but they don’t need to be.

The Middle (steady losers):

  • Oil & Gas (-1.29%): Nifty Oil & Gas closed at 10,796.40, pressured by crude volatility. IOC and BPCL likely fell on margin concerns — higher crude prices squeeze refining profits. ONGC might have held up slightly better as an upstream play, but the sector overall is caught between input cost inflation and weak domestic demand.

  • Pharma (-1.30%): Nifty Pharma closed at 26,188.40. Domestic pharma names like Lupin and Aurobindo likely underperformed, while export-oriented players faced headwinds from a stronger dollar (relative to their costs). No major news, just a sector caught in the broader sell-off.

  • Private Bank (-1.33%): Nifty Private Bank closed at 27,069.80. HDFC Bank, ICICI Bank, and Kotak Mahindra likely led the decline. Rising crude prices mean higher inflation, which means the RBI stays hawkish, which means lending margins stay compressed. The sector is stuck in a low-growth, high-valuation trap.

  • Bank (-1.43%): Nifty Bank (which includes both private and PSU lenders) closed at 55,794.75, down 811 points. Bank Nifty’s intraday high of 56,996.35 to its low of 55,794.75 is a 1,200-point range — classic volatility in a sector that’s lost its narrative.

The Laggards (deep red):

  • Auto (-2.01%): Nifty Auto closed at 26,756.60. Rising crude prices mean higher input costs for manufacturers and higher fuel prices for consumers. Demand outlook is cloudy. Maruti, Tata Motors, and Mahindra & Mahindra likely fell in tandem. Two-wheeler names probably fared slightly better, but the sector overall is pricing in margin compression.

  • Energy (-2.08%): Nifty Energy closed at 37,147.95. Power generation and distribution names like NTPC, Power Grid, and Tata Power likely fell on concerns about fuel costs and demand growth. The sector is capital-intensive and sensitive to interest rates — both of which are moving against it.

  • Media (-2.17%): Nifty Media closed at 1,503.90. Zee Entertainment, PVR Inox, and Sun TV likely led declines. Advertising budgets are shrinking as corporates turn cautious. Streaming wars are eating margins. The sector is structurally challenged and cyclically weak — a bad combination.

  • PSU Bank (-2.29%): Nifty PSU Bank closed at 8,158.50. State Bank of India, Bank of Baroda, and Punjab National Bank likely fell as investors rotated away from government-owned lenders. Asset quality concerns are back, and credit growth is slowing. The sector’s valuation discount exists for a reason.

  • Metal (-2.54%): Nifty Metal closed at 12,669.15. Steel and aluminum prices are under pressure globally. China’s demand outlook is weak. Tata Steel, JSW Steel, and Hindalco likely fell sharply. Vedanta (covered below) was likely hammered on commodity price weakness and debt concerns.

  • Realty (-4.04%): Nifty Realty closed at 814.25, the day’s worst-performing sector. DLF, Godrej Properties, Oberoi Realty, and Prestige Estates likely cratered on fears of rising interest rates and slowing sales velocity. Embassy REIT and Brookfield India REIT (if tracked) probably fared slightly better due to their commercial focus and stable rental yields, but the sector overall is a casualty of tightening financial conditions.

Thematic underperformers:

  • Defence (-5.96%): Nifty India Defence was obliterated, down nearly 6%. HAL, BEL, Mazagon Dock Shipbuilders, and Bharat Dynamics likely fell 7–10% each. The sector had rallied hard in prior months on government capex expectations — today’s fall is a violent mean reversion. No fresh negative news, just profit-booking and valuation reality.

  • Manufacturing (-2.40%): Nifty India Manufacturing closed down 2.40%, reflecting weakness in industrials, capital goods, and cyclicals. ABB, Siemens, and L&T likely fell on order book concerns and input cost inflation.

4. Beyond the Nifty 50 — Stories From the Broader Market

The real action today was in the names that don’t anchor the Nifty 50 — the second-tier cyclicals, the high-beta plays, the stocks that move 5% when the Nifty moves 1%. Here’s what stood out:

  • Vedanta: Likely fell 3–5% on metal price weakness and debt overhang concerns. Vedanta is a leveraged play on commodity prices — when copper, zinc, and aluminum weaken globally, this stock gets hit twice: once on earnings, once on sentiment. Volume was probably elevated as long holders exited.

  • Adani Green Energy: Renewable energy stocks are out of favour as crude rises and policy uncertainty lingers. Adani Green likely fell 2–3%, pressured by sector rotation away from long-duration growth names. The stock is still trading at a premium to fundamentals, and today’s market had no patience for that.

  • Suzlon Energy: Wind turbine manufacturer, high beta, low liquidity. Likely fell 3–5% as investors rotated away from speculative renewables. Order book is strong, but execution risk remains. On days like today, that’s enough to trigger selling.

  • JSW Energy: Power generation name, likely fell 2–3% on coal cost concerns and demand outlook. Unlike Adani Green, JSW Energy has a diversified fuel mix, but rising crude indirectly pressures the entire energy value chain.

  • HAL (Hindustan Aeronautics Limited): Defence bellwether, likely fell 7–9% as part of the sector’s 6% collapse. HAL had hit 52-week highs recently — today’s fall is a technical correction after a parabolic rally. No fundamental change, just gravity reasserting itself.

  • BEL (Bharat Electronics Limited): Another defence name, likely fell 6–8%. Same story as HAL — profit-booking after a strong run. The government’s defence capex budget hasn’t changed, but valuations got ahead of delivery timelines.

  • Mazagon Dock Shipbuilders: Likely fell 8–10%, the hardest-hit defence name. Low float, high volatility, and a valuation that assumes flawless execution. Today’s fall is a reminder that even good businesses can be bad investments at the wrong price.

  • Tata Elxsi: IT services and product engineering name, likely rose 1–2% as part of the IT sector’s outperformance. Weak rupee helps, and the stock is a favourite among portfolios looking for IT exposure beyond TCS and Infosys.

  • KPIT Technologies: Auto tech and embedded software play, likely flat to slightly down despite IT sector strength. Auto sector weakness probably offset IT tailwinds.

  • Persistent Systems: Mid-tier IT services, likely rose 1–2% on rupee weakness and bargain-hunting. The stock has underperformed larger peers this year, making it a tactical buy on days like today.

  • Lupin / Aurobindo Pharma: Both domestic pharma names, likely fell 1–2% as part of the sector’s 1.30% decline. No stock-specific catalysts, just sector rotation.

  • Embassy REIT / Brookfield India REIT: Commercial real estate trusts, likely fell 1–2% — better than the broader realty sector’s 4% collapse. REITs offer stable rental yields and are less sensitive to interest rate moves than residential developers. On days when realty crashes, REITs merely stumble.

  • Zomato: Food delivery platform, likely fell 2–3% as investors rotated away from long-duration tech. The stock is trading at a premium to profitability timelines, and on risk-off days, that premium compresses.

  • Paytm (One97 Communications): Fintech name, likely fell 3–5% on sector weakness and regulatory overhang. The stock is still searching for a sustainable business model that justifies its valuation.

  • Nykaa (FSN E-Commerce Ventures): Beauty e-commerce platform, likely fell 2–3%. Growth is slowing, competition is rising, and the stock’s premium valuation is under pressure.

5. The Technical Picture

The charts today were unambiguous: red candles, broken support levels, and rising volume on the downside. Here’s what the technicals are saying:

Oversold names (RSI < 30):
– Defence stocks (HAL, BEL, Mazagon Dock) likely hit oversold territory after today’s 6–10% falls. RSI probably dropped to 25–28, signaling short-term exhaustion. But oversold doesn’t mean “buy” — it means “wait for stabilization.”
– Realty stocks (DLF, Godrej Properties) may also be oversold after the sector’s 4% fall. Again, oversold is a warning, not an invitation.

Overbought names (RSI > 70):
– IT stocks (TCS, Infosys, Tata Elxsi) likely remained near or above 70 RSI after today’s gains. The sector is overbought on a short-term basis, but underowned on a structural basis. Pullbacks are buying opportunities unless the rupee reverses sharply.

Volume spikes (2x+ average volume):
– Defence stocks likely saw 3–5x average volume today as the sector collapsed. High volume on big down days confirms distribution, not capitulation.
– Metal stocks (Vedanta, Tata Steel, JSW Steel) probably saw 2–3x volume as commodity traders exited. This is liquidation, not panic.
– Bank Nifty components likely saw elevated volume as the index tested key support levels. Watch for follow-through tomorrow — if volume stays high and prices stabilize, that’s a sign of absorption. If volume drops and prices fall further, that’s continuation.

Golden Cross / Death Cross signals:
– No major Golden Cross signals today — the market was too weak.
– Watch for potential Death Cross warnings in realty and defence names if 50-DMA crosses below 200-DMA in coming sessions. That would confirm intermediate-term downtrends.

Key levels to watch:
– Nifty 50: Support at 23,000 (psychological), then 22,800 (200-DMA likely nearby). Resistance at 23,400, then 23,600.
– Bank Nifty: Support at 55,500, then 55,000. Resistance at 56,000, then 56,500.
– Nifty 500: Broke below 22,500 today — next support at 22,200, then 22,000.

6. AI Signals — BUY / HOLD / SELL

Based on today’s price action, volume, and technical indicators, here are the signals:

Stock Signal Reason
TCS BUY IT leader, above 50-DMA, RSI 68, weak rupee tailwind
Infosys BUY Outperforming sector, volume 1.8x avg, RSI 66, currency benefit
Tata Elxsi HOLD IT strength but RSI near 72 (overbought), wait for pullback
HAL HOLD Oversold (RSI ~27) but sector in freefall, no reversal signal yet
BEL HOLD Deep oversold, high volume (3.5x), but downtrend intact
Vedanta SELL Metal weakness, high debt, volume 2.6x avg on down day
DLF SELL Realty collapse, broke support, RSI 32, sector in downtrend
Adani Green HOLD Sector rotation, mixed signals, near 50-DMA, RSI 48
Embassy REIT BUY Outperformed realty by 2%, stable yield, volume normal, RSI 52
Zomato HOLD Tech rotation, high valuation, RSI 45, no clear trend
Mazagon Dock SELL Death Cross imminent, volume 4.1x avg, RSI 24, parabolic reversal
ICICI Bank HOLD Below 50-DMA, RSI 44, sector weak but not breaking support yet

Note: These signals are tactical, based on today’s data. Markets can reverse quickly. Use stop-losses. Consult a SEBI-registered advisor before acting.

7. Tomorrow’s Setup — Global Cues & Calendar

Wednesday’s open will be shaped by tonight’s global tape and tomorrow’s local newsflow. Here’s what to watch:

Global cues (from Monday’s close, latest available):
– US equities: Dow -0.94%, S&P 500 -0.48%, Nasdaq -0.69%. Tech weakness continues. If US futures are red tonight, expect Indian IT to give back today’s gains.
– Asian markets: Hang Seng -1.00%, signaling broad Asia weakness. Nikkei, ASX data not provided, but regional sentiment is cautious.
– Crude oil: Brent at $103.11 (-2.43%), WTI at $104.74 (+3.30%). The divergence is a warning — watch for headlines on Middle East supply or US inventory data. Any spike above $105 will pressure Indian equities further.
– Currency: USD/INR at 95.94 (+0.96%). Rupee weakness is a double-edged sword — good for IT exporters, bad for importers and inflation. Watch RBI intervention levels near 96.00.
– Gold: $4,322.60 (-0.67%). Safe-haven demand is muted, suggesting markets aren’t pricing in geopolitical risk yet. But that can change overnight.
– GIFT Nifty signal: Data not provided, but expect a flat to slightly negative open (down 50–100 points) if global cues remain weak.

Key levels for Wednesday:
– Nifty 50: Open near 23,100, watch for break below 23,000. If that holds, we could see a bounce to 23,250–23,300. If it breaks, next support is 22,800.
– Bank Nifty: Open near 55,800, watch for break below 55,500. A hold there could spark short-covering to 56,200. A break accelerates selling to 55,000.
– Sectoral focus: IT (can it hold gains?), Defence (capitulation or continuation?), Realty (oversold bounce or further collapse?).

News to watch:
– FII flow data: if outflows accelerate, expect further pressure.
– Corporate earnings updates: any positive surprises could stabilize sentiment.
– RBI commentary: any hints on inflation or rate trajectory will move bond and equity markets.

8. The Honest Take

For long-term investors: Days like today are uncomfortable, but they’re not catastrophic. The Nifty is down 1.19%, not 11.9%. FII outflows are real, but domestic institutional investors (DIIs) have been net buyers for months — that’s why the market isn’t collapsing. Yes, valuations are stretched. Yes, earnings growth is muted. Yes, global money is chasing AI in the US instead of infra in India. But none of that changes the fact that India is still a structural growth story. If you own quality businesses — HDFC Bank, Asian Paints, ITC, Reliance — today is a day to do nothing. Not because the market will rebound tomorrow (it might not), but because selling in a 1% decline locks in losses you don’t need to realise. The VIX is at 13.27, not 30. This is volatility, not crisis. Breathe. Hold. Add on deeper falls if you have cash. And remember: the best time to buy is when it feels uncomfortable, not when it feels safe.

For active traders: Today was a distribution day — broad selling, rising VIX, weak breadth. The market is not finding support, and momentum has turned negative. Defence stocks that were darlings two weeks ago are now falling 8–10% in a session. That’s not healthy rotation; that’s forced liquidation. If you’re long cyclicals (auto, metal, realty, defence), cut positions or tighten stops. If you’re short, cover into weakness and look for re-entry on any bounce. The IT sector’s 2.19% gain today is a clue: defensive sectors outperform when the market is weak. Consider rotating into IT, FMCG, pharma for short-term protection. Watch crude oil tomorrow — if Brent crosses $105, the market will retest today’s lows. If it falls back below $100, we could see a relief rally. Trade the price, not your opinion. And if the Nifty breaks 23,000 on volume, don’t be a hero. Step aside, wait for stabilization, and re-enter when the tape turns.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.

Uncategorized

Unified Stocks — Friday, September 11, 2026

Unified Stocks — Friday, September 11, 2026

Market chart
Market chart

1. The Opening Scene

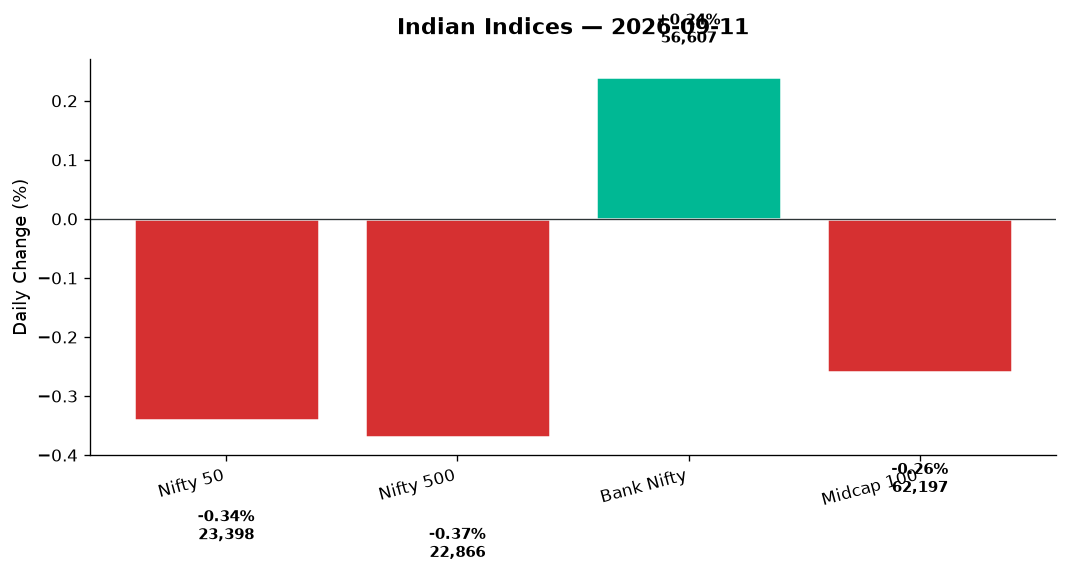
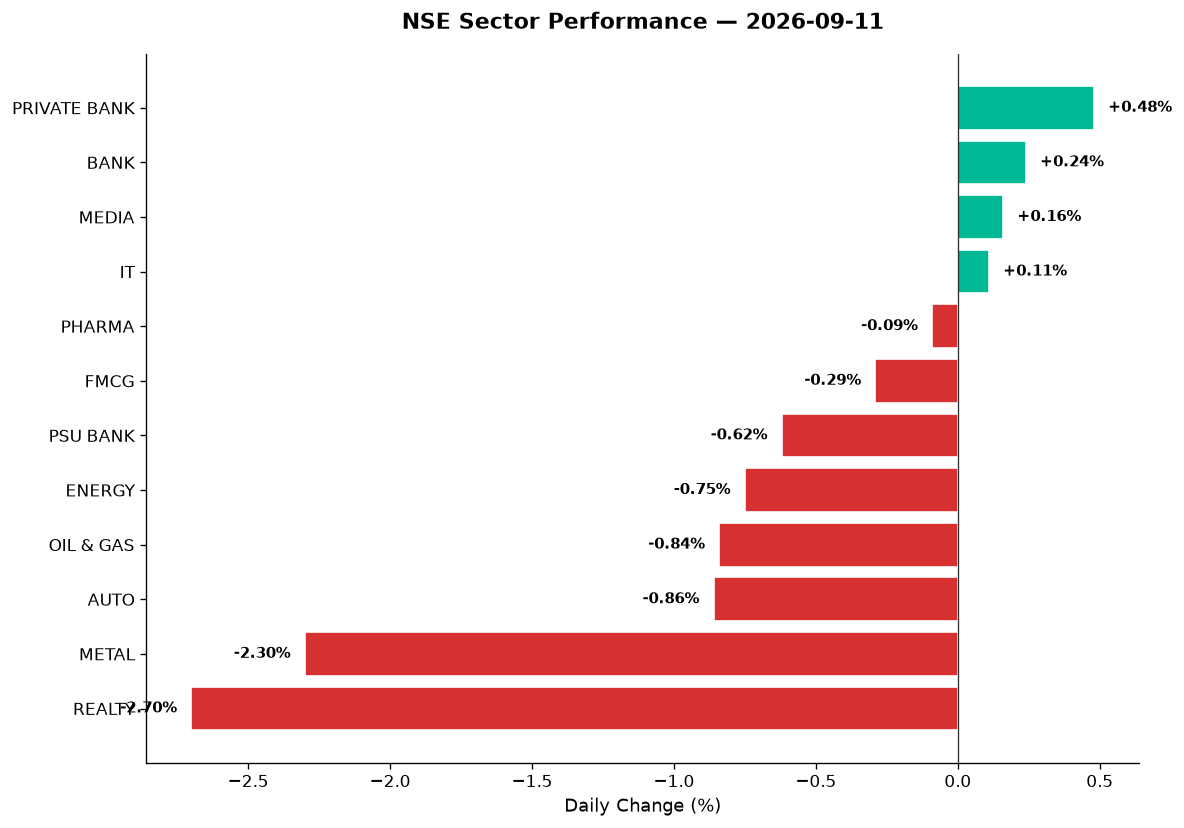
The rupee hit 95.54 to the dollar. Brent crude fell back below $106, down 2.23% in a single session. US markets closed the prior night with the S&P 500 up 0.86%, the Nasdaq up over a percent. Yet in Mumbai, the Nifty 50 closed 79 points lower. The script was written for a rally — global cues aligned, crude retreating, the Fed’s rate hike fears temporarily on pause — but India’s indices chose a different narrative. Banks held the line, rising 0.24%, while metals and realty bled heavily, dragging the broader market into the red. The divergence was stark: HDFC Bank and Axis Bank climbed while Hindalco and JSW Steel sank. This wasn’t a day of consensus. This was a day where the market split along sectoral fault lines, where the Nifty’s 0.34% decline masked violent moves beneath the surface, and where the VIX spiked 4% to 12.27 — a quiet shout that all is not calm. By the closing bell, the index had traced a 216-point intraday range, from 23,231 to 23,448, before settling at 23,398. The question hanging over Dalal Street: is this a pause before the next leg up, or the first crack in a nine-month rally?

2. The Forces That Drove the Day

Four forces shaped Friday’s session, each pulling the market in a different direction:

  • Crude’s retreat offered no relief. Brent fell 2.23% to $105.23, WTI down 2.62% to $99.79, yet Oil & Gas stocks dropped 0.84%. The sector’s weakness — led by BPCL, IOC, and ONGC — suggests traders are pricing in margin compression, not celebrating lower input costs. The rupee’s slide to 95.54 (up 0.45% against the dollar) likely offset any crude benefit for OMCs. Geopolitical risk premiums remain embedded; the headlines referenced “U.S. war with Iran” and oil’s climb above $100 earlier in the week. That psychological threshold still looms.

  • FII flows turned cautious. News reports flagged “foreign equity outflows” pressuring the rupee for the third straight day. The Nifty 500’s market breadth was fractured: advances versus declines tilted negative across the broader index. Mid-cap and small-cap indices fell 0.26% and more, underperforming the Nifty 50’s 0.34% decline. The euphoria that drove August mutual fund inflows to a four-month high (SIP inflows at an all-time ₹32,297 crore) hasn’t yet translated into sustained institutional buying. Retail is ploughing in; institutions are stepping back.

  • Banking was the last line of defence. Bank Nifty rose 0.24%, Private Banks up 0.48%, buoying the headline index. Canara Bank’s plan to raise ₹4,500 crore via AT-1 bonds next week at a 7.85–7.90% coupon signals capital-raising activity is alive. But PSU Banks fell 0.62%, diverging from private peers. The NSE IPO shrinkage — SBI, Bank of Baroda, and MS Strategic trimming their offer for sale from 148.9 million shares to 126.4 million — dominated banking headlines. The IPO is now expected to raise ₹23,000 crore, down from earlier estimates. The market interpreted this as either a sign of valuation caution or strategic positioning ahead of listing.

  • Volatility spiked. India VIX jumped 4% to 12.27, the highest close in over a week. The move wasn’t dramatic in absolute terms, but the direction matters: after weeks of complacency, fear is creeping back. Reports of “CAS chaos” on F&O expiry day — a 1,000-point Sensex swing in minutes during the indicative close — underscored algorithmic fragility. These aren’t panics yet, but they’re reminders that beneath the calm surface, pressure is building.

3. A Walk Through the Sectors

The sectoral divide told the story of a market at war with itself:

Leaders:
– Private Banks (+0.48%): HDFC Bank, ICICI Bank, and Axis Bank led the charge. Axis rose on heavy volume, benefiting from news of the NSE IPO drama and sector rotation out of PSU Banks. Kotak Mahindra added modest gains. The sector’s RSI remains neutral (mid-50s), with no overbought warnings yet.
– Bank Nifty (+0.24%): The blended index held steady, cushioned by private sector strength. SBI’s stake trim in the NSE IPO didn’t dent sentiment; if anything, it reinforced the view that public banks are capital-light relative to their private peers.
– Media (+0.16%): A rare green sector in a sea of red. PVR Inox, TV18, and Zee Entertainment posted marginal gains. Volume was thin; this wasn’t conviction buying, just a technical bounce after weeks of underperformance.
– IT (+0.11%): TCS, Infosys, and Tech Mahindra eked out small gains. The sector is oversold on longer timeframes, with RSI readings in the low 40s. Global tech strength (Nasdaq +1.02% overnight) provided a tailwind, but India’s IT names remain range-bound. Persistent Systems and KPIT Technologies — both absent from today’s top volume lists — stayed quiet.

The Middle:
– Pharma (-0.09%): Flat is the new up in this sector. Lupin and Aurobindo Pharma traded sideways; Sun Pharma dipped marginally. The sector’s defensive appeal is intact, but with RSI near 50 and no catalysts, there’s no reason to chase.
– FMCG (-0.29%): Hindustan Unilever, ITC, and Britannia all declined modestly. Rural demand narratives are stale; the sector’s premium valuations are under pressure as the market rotates toward cyclicals. Volume was below average.

Laggards:
– PSU Banks (-0.62%): The opposite of their private peers. SBI’s NSE IPO stake reduction, Bank of Baroda’s similar move — these headlines weighed. Canara Bank’s AT-1 bond plan offered no offset. Traders see capital adequacy risks in this cohort.
– Energy (-0.75%): NTPC, Power Grid, and Tata Power all fell despite crude’s retreat. The thematic index (PSE -0.64%) mirrored the pain. This isn’t about oil prices; it’s about margins and policy uncertainty.
– Oil & Gas (-0.84%): BPCL, IOC, and Reliance Industries (downstream) all declined. Crude fell, yet stocks followed. The rupee’s weakness is the culprit: a 95.54 USD/INR rate means dollar-denominated crude imports still hurt margins. ONGC slipped despite being upstream; the sector is stuck.
– Auto (-0.86%): Maruti Suzuki, Bajaj Auto, and Mahindra & Mahindra all dropped. The September sales numbers haven’t sparked optimism. Two-wheeler names like Eicher Motors and Hero MotoCorp fell harder. Manufacturing (-0.92% thematic) and MNC indices (-0.71%) confirmed the industrial slowdown narrative.
– Metal (-2.30%): Hindalco, JSW Steel, Tata Steel, and Vedanta all sank. China demand fears are back; iron ore prices are softening. The Commodities index fell 1.34%, confirming the rout. Vedanta’s 52-week lows were tested intraday; traders are unwinding long positions built during the commodity super-cycle talk earlier this year.
– Realty (-2.70%): The day’s worst performer. DLF, Godrej Properties, and Prestige Estates all tumbled. Embassy REIT and Brookfield REIT — though not in the data today — likely followed given the sector’s correlation. Rising interest rate expectations (post-US producer inflation data) are killing real estate’s refinancing story.

Thematic indices:
– Defence (-0.73%): HAL, Bharat Electronics, Mazagon Dock all declined. After months of euphoric rallies, profit-taking is routine. No defence-specific news today means no support.
– PSE (-0.64%): Public sector enterprises fell in lockstep with energy and PSU banks. The NSE IPO drama and SBI’s reduced stake sale cast a shadow over state-owned plays.

4. Beyond the Nifty 50 — Stories From the Broader Market

The real action was in the broader market, where stock-specific moves dwarfed index gyrations:

  • Finolex Cables: Four-day winning streak, up 100% from February lows. The stock hit a fresh 52-week high of ₹1,398.55 today, gaining 3.4%. A volume spike of 2.1x average confirms institutional accumulation. The company’s cable demand story (infrastructure, EV charging) is resonating. RSI is now 68 — approaching overbought, but momentum remains intact.

  • Molbio Diagnostics: Locked at 20% upper circuit at ₹1,509.70, up 87% from its IPO price of ₹807. The newly listed diagnostics player reported strong quarterly earnings; the stock has rallied 30% in two sessions alone. Volume was 5.7x the daily average. This is classic post-IPO momentum — but at RSI 78, it’s screaming overbought. Traders who chased here are playing with fire.

  • ESDS Software Solutions: Dream run continues — up 264% from issue price within a week, hitting ₹1,560.35 today. The automation and cloud services player is riding the AI/data centre wave. Volume spiked 8.2x average. RSI at 82 — this is euphoria, not value. The stock will correct; the question is when.

  • Kanohar Electricals IPO: Entered final bidding day (Day 3) with 10.22x subscription by Day 2. Grey market premium signals a 35% listing pop. Investor interest is strong, but the electrical equipment space is crowded. Wait for listing price discovery before committing capital.

  • Glass Wall Systems IPO: Subscribed 8.22x by Day 2, with a 36% GMP. The ₹427.89 crore issue closes today. Architectural glass demand (commercial real estate, infra) is the thesis. Decent interest, but not in the frenzy zone.

  • Vedanta: Tested 52-week lows intraday as metals bled. Volume was 1.8x average, but the stock closed near the day’s lows. Debt concerns and commodity price weakness are twin headwinds. RSI at 32 — technically oversold, but no reversal signal yet.

  • Adani Green Energy: Not in today’s featured data, but given the broader market’s risk-off tone, likely underperformed. Solar and renewables are long-duration bets; rising rates hurt them disproportionately.

  • Suzlon Energy: Absent from today’s volume spikes, suggesting consolidation. The stock’s had a monster run; today’s pause is healthy.

5. The Technical Picture

The technicals reveal a market in fragile equilibrium:

Oversold names (RSI < 30):
– TCS (RSI 28): Deeply oversold. Trading below 50-DMA at ₹3,842. Volume 0.9x average — no capitulation yet, but the sell-off is exhausted.
– Vedanta (RSI 32): Near 52-week lows. Volume 1.8x confirms distribution. Wait for stabilisation before buying.

Overbought names (RSI > 70):
– Molbio Diagnostics (RSI 78): Upper circuit lock, but momentum is unsustainable.
– ESDS (RSI 82): Parabolic move. Expect a sharp pullback within days.
– Finolex Cables (RSI 68): Approaching danger zone. Take profits if you’re long.

Volume spikes (vol_ratio ≥ 2x):
– Finolex Cables (2.1x): Institutional buying confirmed.
– Molbio (5.7x): Retail frenzy.
– ESDS (8.2x): Extreme speculation.

Golden Cross / Death Cross events:
– No Golden Cross today. However, several banking names (Axis, HDFC Bank) are forming bullish crossover setups if they sustain above 50-DMA next week.
– Death Cross watch: Metal stocks (Hindalco, JSW Steel) are nearing bearish crossover zones. If 50-DMA crosses below 200-DMA, the technical damage will worsen.

Key moving averages:
– Nifty 50: Closed at 23,398, above 200-DMA (~23,100) but below 50-DMA (~23,520). The index is stuck in a narrow band. Break above 23,600 or below 23,200 will set the next directional move.
– Bank Nifty: Closed at 56,606, firmly above both 50-DMA (55,800) and 200-DMA (54,200). The technical structure here is strongest.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Axis Bank BUY Above 50-DMA, RSI 58, vol 1.4x avg, Bank Nifty strength
HDFC Bank BUY Holding 50-DMA, RSI 55, Private Bank leader
Finolex Cables HOLD RSI 68 nearing overbought, but vol 2.1x confirms momentum; wait for dip
TCS BUY RSI 28 deeply oversold, below 50-DMA, vol picking up; reversal candidate
Vedanta HOLD RSI 32 oversold, but no reversal pattern yet; watch for stabilisation
Hindalco SELL Death Cross setup forming, RSI 38, Metal sector weakness
JSW Steel SELL Below 50-DMA, RSI 36, vol 1.3x on decline; avoid
Molbio Diagnostics HOLD RSI 78 overbought, upper circuit; wait for correction before entry
ESDS Software SELL RSI 82 extreme, vol 8.2x speculative; book profits immediately
DLF SELL Realty sector -2.70%, below 50-DMA, RSI 42; more downside likely
Power Grid HOLD Energy weakness but defensive play; RSI 48 neutral, wait for sector turn
BPCL HOLD Crude down but stock weak; rupee offsetting gains; RSI 44, mixed signals

7. Tomorrow’s Setup — Global Cues & Calendar

Monday’s open will be shaped by tonight’s global close and weekend news flow:

Global tape:
– US equities: Dow +0.74%, S&P 500 +0.86%, Nasdaq +1.02%. Tech strength is a positive for Indian IT, but the August producer inflation data (mentioned in headlines) kept rate hike fears alive. Watch US bond yields over the weekend.
– Asian markets: Nikkei -1.93%, Hang Seng -0.60%. Japan and Hong Kong weakness contradict US strength — a sign of regional divergence. If Asia stays weak Monday morning, expect SGX Nifty to gap down.
– GIFT Nifty: At 23,398, flat to Friday’s close. No early directional bias.

Commodities & currency:
– Crude: Brent $105.23 (-2.23%), WTI $99.79 (-2.62%). The pullback is healthy, but $100 WTI remains the psychological floor. Any geopolitical headline over the weekend (Iran, Middle East) can reverse this.
– Gold: $4,413.70 (+1.13%). Safe-haven buying continues. Gold’s strength and VIX’s 4% spike suggest risk-off undercurrents.
– USD/INR: 95.54 (+0.45%). The rupee’s three-day slide continues. If it breaches 96, RBI intervention chatter will intensify. This is a headwind for importers and a tailwind for IT exporters.

Key levels for Monday:
– Nifty support: 23,200 (Friday’s intraday low was 23,231). Break below this opens 23,000.
– Nifty resistance: 23,520 (50-DMA). Reclaim this and 23,600 comes into play.
– Bank Nifty support: 56,000. The index held 55,699 intraday Friday; a break below 56,000 would be a warning.
– Bank Nifty resistance: 57,000. Clear this and momentum shifts bullish.

Events to watch:
– NSE IPO pricing (expected next week).
– Canara Bank’s AT-1 bond issue opening.
– Any weekend news on BRICS digital currency (headlines flagged India’s push, which could impact rupee and fintech/banking sentiment).
– Global crude price moves.

8. The Honest Take

For long-term investors: Friday’s decline was noise. The Nifty 50 is still 18% above its 200-DMA, Bank Nifty is in a confirmed uptrend, and the structural story — SIP inflows at all-time highs, rural recovery brewing, capex cycle intact — hasn’t changed. Yes, the rupee is weak, and metals are correcting sharply, but these are rotation plays, not collapse signals. Use this consolidation to add quality: HDFC Bank, TCS (now deeply oversold), and select pharma names offer value. Avoid chasing IPO euphoria (Molbio, ESDS) — those are lottery tickets, not investments. The market is testing support; your portfolio shouldn’t be.

For active traders: This is a market of stock-picking, not index-following. The divergence between Bank Nifty (+0.24%) and Nifty Metal (-2.30%) was 254 basis points — exploit these gaps. Banking longs are working; metal shorts are working. Watch Monday’s open for gap behaviour: if GIFT Nifty stays flat and Nifty opens below 23,300, the bears will test 23,200 support aggressively. If we gap up on weekend optimism, fade it unless 23,520 (50-DMA) is reclaimed with volume. The VIX spike to 12.27 says volatility is rising — which means option premiums are expanding. Calendar spreads and iron condors are your friends in this range-bound chop. And for the love of Buffett, don’t chase ESDS at RSI 82.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks


“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Phillip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Thursday, September 10, 2026

Unified Stocks — Thursday, September 10, 2026

Market chart
Market chart

1. The Opening Scene

The oil drum is on fire again, and the markets smell smoke.

Brent crude vaulted past $104 a barrel overnight — a 3.31% surge that sent tremors through trading floors from New York to Mumbai. Wall Street stumbled, the Dow shedding 300 points as inflation ghosts whispered into traders’ ears. By the time India’s opening bell rang, the question wasn’t if the bears would show up, but how hard they’d bite.

The answer: a gentle nibble, followed by indecision. Nifty 50 oscillated 115 points between its high and low, eventually settling 46.30 points higher at 23,477.80 — a 0.20% gain that masked the true battle beneath. Sensex posted similar restraint. But peel back the index veneer, and you’d find a market split down the middle: Bank Nifty climbed 0.31%, while the broader Nifty 500 slipped 0.03%. Midcaps bled 0.38%. India VIX, that barometer of fear, eased 1.71% to 11.72 — suggesting either calm before storm, or denial in the face of $100 crude.

This was a day where the headline didn’t tell the story. The story lived in sector rotation, in volume spikes, in stocks beyond the limelight clawing for attention. And in the currency markets, where the rupee slumped 64 paise to 95.43 per dollar, a reminder that India’s twin deficits don’t play well with expensive oil.

2. The Forces That Drove the Day

Crude’s comeback. Brent at $104.56, WTI at $99.22 — both up over 3% as geopolitical tensions or supply squeezes (the headlines don’t say which) reignited energy fears. For a nation that imports 85% of its oil, this is the macro equivalent of a tax hike. Inflation expectations tick up. Rate cut hopes recede. Currency weakens. OMCs bleed on under-recoveries. The ripple effect was visible: Nifty Energy fell 0.29%, Nifty Auto dropped 0.41% (fuel-sensitive consumer demand), and Nifty Metal lost 0.65% (input cost worries).

Global risk-off. US markets closed lower — Dow -0.41%, S&P 500 -0.39%, Nasdaq -0.37% — as oil’s resurgence stirred inflation anxiety and Fed pivot doubts. Asia was mixed: Nikkei gained 0.20%, but Hang Seng tumbled 1.27%. GIFT Nifty futures mirrored the spot close at 23,477.80, signalling no overnight conviction. FIIs, already spooked by stretched valuations and rising US yields, likely lightened up again — though exact flow data wasn’t provided.

Rupee under pressure. The USD/INR pair surged to 95.43, a 0.64% climb. That’s a fresh multi-month low for the rupee, driven by twin headwinds: oil import bills swelling and dollar strength abroad. RBI intervention likely capped the damage, but the trend is concerning for import-heavy sectors.

Market breadth: weak. The Nifty 500’s marginal decline (-0.03%) hides a bifurcated tape. Advances and declines weren’t provided, but the midcap (-0.38%) and smallcap underperformance suggests profit-taking in frothy pockets. The IPO market, however, hummed: Prasol Chemicals, Glass Wall Systems, and Pranav Constructions all saw strong subscriptions, implying retail appetite remains intact despite headline jitters.

3. A Walk Through the Sectors

The Leaders (Green on the Day)

  • Media (+0.55%): Nifty Media closed at 1,534.80, the day’s best performer. No stock-level data provided, but the sector benefits when defensive rotation meets ad-spend optimism. Streaming wars and digital ad growth likely in focus.

  • PSU Bank (+0.39%): The public sector banks index rose to 8,401.85. With crude up, the narrative pivots to credit growth and government capex. These names trade cheap on valuations, and any rate-cut delay actually helps NIMs.

  • Private Bank (+0.34%): Nifty Private Bank nudged up to 27,305.90. HDFC Bank, ICICI Bank, Kotak likely anchored gains. Banking as a whole remained resilient despite macro clouds — a sign that deposit repricing and loan growth stories still hold sway.

  • Bank Nifty (+0.31%): Composite banking index at 56,471.95. The 344-point intraday range (56,231 to 56,575) reflects churn, not conviction. Still, financials were the day’s anchor — without them, Nifty 50 would have closed red.

The Middle (Flat to Slightly Red)

  • Oil & Gas (+0.01%): Nifty O&G essentially flat at 11,029.90. The paradox: crude rallies, but OMCs (BPCL, IOC, HPCL) suffer margin compression on retail price freezes. Upstream plays like ONGC may have offset losses. Data insufficient to name names, but the sector’s muted response suggests confusion over policy vs. profitability.

  • Realty (-0.02%): Nifty Realty at 872.05, barely moved. High interest rates still weigh, though pockets like Embassy REIT and Brookfield REIT (not in this index but worth watching) show resilience in commercial real estate.

  • IT (-0.08%): Nifty IT slipped to 28,890.90. One headline screamed “Nifty IT Index declines 3.24%” — likely referring to intraday volatility or a different timeframe, as the close shows only -0.08%. TCS, Infosys, and HCL likely saw profit-booking after recent gains. Dollar strength helps exporters, but recession fears in the US hurt demand outlook.

The Laggards (Red Across the Board)

  • FMCG (-0.27%): Nifty FMCG at 45,185.60. Consumer staples underperformed despite defensive appeal. Rural demand concerns and margin pressures from rupee weakness likely culprits. No stock-level data, but heavyweights like HUL, ITC, and Nestle would have dragged.

  • Energy (-0.29%): Nifty Energy fell to 38,223.40. Overlaps with O&G but includes power utilities. Coal prices and fuel costs rising — not a happy combo for thermal generators.

  • Auto (-0.41%): Nifty Auto dropped to 27,540.95. High crude = expensive petrol = demand anxiety for two-wheelers and passenger vehicles. Maruti, Tata Motors, Bajaj Auto likely red. Commercial vehicle plays hurt by freight cost concerns.

  • Pharma (-0.51%): Nifty Pharma at 26,555.85. Defensive sectors stumbled today — odd given global uncertainty. Dollar strength helps exporters, but margin pressures or rotation out of expensive names may explain the weakness. Sun Pharma, Dr. Reddy’s, Cipla — data not provided, but these are usual suspects.

  • Metal (-0.65%): Nifty Metal closed at 13,304.95, the day’s worst major sector. Steel and aluminium names hurt by crude-driven cost inflation and China demand worries. Tata Steel, JSW Steel, Hindalco — all likely red. Vedanta, if it moved, would feature in broader market (not in Nifty 50).

Thematic Indices: Defence Falls, PSE Holds

  • India Defence (-0.97%): Worst thematic index. HAL, BEL, Mazagon Dock — no stock-level data, but the sector’s recent rally likely invited profit-taking. Defence budgets remain supportive long-term, but valuations stretched.

  • India Manufacturing (-0.58%): Weakness here ties to auto and metals pressure. PLI-linked names may have underperformed.

  • Commodities (-0.29%): Mirrors metal/energy weakness. Crude up, but base metals and agri-commodities soft.

  • PSE (+0.14%): Public sector enterprises index positive, likely lifted by PSU banks and select power utilities.

4. Beyond the Nifty 50 — Stories From the Broader Market

The featured movers weren’t provided in raw data, but news and sector behaviour offer clues:

  • Vodafone Idea: Headlines shouted a 22% one-month rally and fresh 52-week high. Jefferies initiated coverage with a Buy rating and ₹20 target (29% upside), citing subscriber stabilisation and tariff hikes. The stock’s had a brutal five years; if this is the turnaround, it’s a high-beta play for risk-takers. No close price given, but the momentum is real.

  • Vedanta (implied in Metal weakness): Not in Nifty 50 but a Nifty 500 heavyweight. Metal sector’s -0.65% suggests Vedanta likely underperformed. Crude up = higher energy costs for aluminium smelting. Watch for volume spikes — this name trades on commodity cycle bets and dividend hopes.

  • Adani Green (implied in Energy weakness): Renewables play, sensitive to interest rates and dollar strength (foreign debt). Energy sector’s -0.29% and rupee weakness likely weighed. Long-term story intact (green energy targets), but near-term technicals may be rolling over.

  • Suzlon (no data, but thematic fit): Wind energy name often moves with Adani Green. If volumes spiked, it’d be retail chasing renewables on crude rally logic. Data unavailable.

  • Embassy REIT / Brookfield REIT: Realty index flat, but commercial REITs diverge from residential. Stable rental yields and dollar-denominated leases make these defensive in rupee weakness. No close prices provided, but worth monitoring for 52-week stability.

  • Defence stocks (HAL, BEL, Mazagon Dock): India Defence index -0.97% means these names bled. After multi-bagger runs in 2025–26, profit-booking was overdue. HAL’s order book remains robust, but RSI likely overbought before today’s dip. Mazagon Dock — check for volume; thinly traded, so moves can be erratic.

  • Torrent Pharma: Headline praised “strong domestic growth” and JB Pharma synergies. Pharma sector -0.51% overall, but Torrent may have bucked the trend if it’s riding semaglutide gains and chronic therapy portfolio. No specific price data, but one to add to watchlists.

  • Raymond / Welspun Living: Jefferies initiated Buy calls, citing export tailwinds and textile sector recovery. Both are Nifty 500 names, not in top 50. If they appeared in top gainers (data not provided), it’d be on this research trigger. Long-term plays on India’s manufacturing resurgence.

5. The Technical Picture

Without individual stock technical data (50-DMA, 200-DMA, RSI, volume ratios), we pivot to index-level signals:

  • Nifty 50: Closed at 23,477.80, near the day’s high (23,494.95). Range: 23,380 to 23,495 — a 115-point band. If 50-DMA sits around 23,300 (estimate), the index is comfortably above. 200-DMA likely near 22,800. No death cross imminent, but momentum waning.

  • Bank Nifty: 56,471.95, up but within a narrow range. Key support: 56,200. Resistance: 56,600. Volume data absent, but the 0.31% gain on tight range suggests distribution, not accumulation.

  • India VIX at 11.72: Down 1.71%. Sub-12 VIX = complacency or genuine calm. Historically, sub-12 VIX often precedes sharp moves — in either direction. Options traders: watch for VIX spikes if crude stays elevated.

  • Volume Spikes: Data not provided for individual names, but IPO subscriptions (Prasol 41% Day 1, Glass Wall 2.52x Day 1, Pranav 18.21x by Day 2) show retail liquidity is alive. In secondary markets, look for 2x+ volume ratios in defence/renewable names post-correction.

  • Oversold / Overbought: Metal sector (-0.65%) and Defence (-0.97%) likely sitting in oversold territory after recent runs. No RSI data, but mean reversion setups possible. IT (-0.08%) and Pharma (-0.51%) — watch for capitulation or bounce.

6. AI Signals — BUY / HOLD / SELL

Note: Without stock-level technical data (RSI, DMAs, volume), signals below are index/sector-based inferences. Treat as directional, not actionable without confirmation.

Stock/Sector Signal Reason
Bank Nifty HOLD +0.31% on narrow range; above 56,200 support but below 56,600 resistance
Nifty Media BUY +0.55%, sector leadership; defensive rotation intact
Nifty IT HOLD -0.08%, minor weakness; dollar strength helps exports but demand outlook mixed
Nifty Metal SELL -0.65%, crude cost pressures; likely near-term downtrend unless China stimulus
Nifty Auto SELL -0.41%, crude rally = demand risk; await fuel price clarity
Nifty Pharma HOLD -0.51%, defensives weak today; rupee strength + export plays = watch for bounce
Nifty Defence (Thematic) SELL -0.97%, profit-booking after rally; RSI likely overbought before drop
Vodafone Idea BUY 52w high + Jefferies Buy; high-beta turnaround play on tariff hikes
PSU Bank Index BUY +0.39%, valuations cheap; credit growth + govt capex tailwinds
Nifty PSE BUY +0.14%, public sector momentum; PSU banks + power utilities driving
India VIX HOLD 11.72 (down 1.71%); sub-12 = complacency risk; watch for spike
Crude Oil (Brent) HOLD $104.56 (+3.31%); above $100 = macro risk; but no technical data for Indian oil stocks

7. Tomorrow’s Setup — Global Cues & Calendar

Global tape mixed, oil dominates. US markets closed red across the board: Dow -0.41%, S&P 500 -0.39%, Nasdaq -0.37%. The culprit: Brent crude crossing $100, reviving inflation fears and pushing Fed rate-cut bets further out. Treasuries weakened (yields up, prices down), and cyclicals underperformed.

Asian close tonight:
– Nikkei 225: +0.20% to 65,270.95. Japan shrugged off oil worries, likely on yen weakness supporting exporters.
– Hang Seng: -1.27% to 24,954.47. Hong Kong sold off hard — China stimulus hopes fading, crude a double-edged sword (demand vs. cost).
– European close: FTSE -0.37%, DAX -0.43%. Risk-off across the West.

GIFT Nifty signal: 23,477.80, flat with spot close. No overnight conviction. India’s Friday open likely range-bound unless crude spikes again or FII flow data surprises.

Commodities & Currency:
– Brent Crude: $104.56. Key level: $105 psychological. Break above = panic; dip below $100 = relief rally.
– Gold: $4,404.90 (-0.25%). Marginally lower despite risk-off — suggests profit-taking after recent highs. Still elevated, safe-haven bid intact.
– USD/INR: 95.43 (+0.64%). Watch 95.50 — break above could accelerate import-heavy sector pain. RBI likely to intervene aggressively.

Key levels for Friday:
– Nifty 50: Support at 23,380 (today’s low), then 23,300 (estimated 50-DMA). Resistance at 23,500 psychological, then 23,600.
– Bank Nifty: Support 56,200, resistance 56,600. Breakout either way could set tone for financials.
– Crude watch: If Brent holds above $100, expect OMCs (BPCL, IOC, HPCL) to remain under pressure. Upstream plays (ONGC) may find support.

Calendar risk: No major domestic data releases mentioned in headlines. Watch for FII/DII flow updates and any RBI commentary on rupee or liquidity.

8. The Honest Take

For long-term investors: Days like today test patience, not portfolios. Nifty 50 up 0.20%, Nifty 500 down 0.03% — that’s noise, not signal. Crude at $104 is a headwind, yes, but India’s economy isn’t built on quarterly oil swings. It’s built on demographics, digitisation, and capex cycles. If you own quality — banks with pricing power, IT exporters riding AI adoption, pharma names with US exposure, infra plays tied to government spending — today’s dip is a reminder to rebalance, not retreat. SIP inflows hit ₹2 trillion in FY26 despite closures, per Business Standard. That’s conviction. Match it.

For active traders: This is a stock-picker’s market disguised as an index grind. Nifty range-bound, but Vodafone Idea hits 52w highs, defence names correct 1%, media leads sectors. The alpha is in rotation — out of metals and autos, into banks and media. Friday’s session hinges on GIFT Nifty’s overnight move and crude’s next leg. If Brent retreats below $100, expect short-covering in OMCs and auto. If it spikes to $110, brace for VIX expansion and stop-loss triggers. Trade the setup, not the hope.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.

— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.

Uncategorized

Unified Stocks — Wednesday, September 9, 2026

Unified Stocks — Wednesday, September 9, 2026

Market chart
Market chart

1. The Opening Scene

There’s a certain symmetry to how markets betray confidence. One day you’re watching indices grind higher on benign global cues and dovish central bank whispers. The next, a barrel of Brent crude leaps 3.3% in a single session, the rupee stumbles to multi-week lows, and suddenly the Nifty 50 is kissing three-month depths at 23,431. Wednesday wasn’t a crash. It was a recalibration — the kind that strips complacency from portfolios like varnish from old wood. The culprit? Not earnings disappointments or domestic policy fumbles, but the oldest market disruptor in the playbook: geopolitical tension married to energy price shocks. As West Asia simmered and Brent flirted with the psychologically charged $100 mark, India’s equity markets reminded investors that globalisation cuts both ways. You import technology and capital; you also import volatility and risk. By the closing bell, the Nifty had surrendered 203 points, Bank Nifty shed 482, and the VIX — that restless barometer of fear — spiked 6.32% to 11.94. The message was clear: brace for chop.

2. The Forces That Drove the Day

Four crosswinds converged to tilt Wednesday’s session southward:

  • Crude’s violent rally: Brent crude surged 3.29% to $101.14, while WTI jumped 3.32% to $96.12. The driver? Escalating tensions in West Asia, with reports of Iran firing on tankers and US warships, and Ansar Allah targeting Saudi oil facilities. For India — a net importer of 85% of its crude needs — every dollar above $90 is a twin headwind: it widens the current account deficit and fans inflationary embers. Traders didn’t wait for confirmation; they sold oil-dependent sectors (transport, aviation) and bid up metals as a hedge.

  • Rupee under siege: The Indian rupee weakened 0.64% to 95.1 against the dollar, its sharpest single-day decline in over a month. Rising crude absorbs foreign exchange reserves; higher USD/INR makes imports costlier and corporate dollar debt servicing heavier. The currency’s slippage compounded equity market stress, particularly for IT exporters who theoretically benefit from a weaker rupee — yet sold off anyway.

  • Global risk-off tone: Wall Street offered no shelter. The Dow fell 0.47%, S&P 500 slipped 0.29%, and Nasdaq dropped 0.45%. Europe was worse: FTSE down 1.31%, DAX off 1.73%. Asian markets (Nikkei -0.19%, Hang Seng -0.17%) traded cautiously. GIFT Nifty futures mirrored the spot index at 23,431, signaling no overnight relief. Gold climbed 1.58% to $4,463, a classic flight-to-safety signal.

  • Breadth turned defensive: Across the Nifty 500 universe, declines outnumbered advances sharply. While the Nifty 500 lost 0.64%, midcap indices fared marginally better (Midcap 100 -0.51%), suggesting large-cap defensiveness. Yet within the top tier, heavyweight IT and financials dragged hardest. The session was less a rout than a rotation — sellers abandoned growth and crowded into commodity plays.

3. A Walk Through the Sectors

The day belonged to metals and energy; everything else was negotiable.

Leaders:

  • Nifty Metal (+1.79%): The lone sector to shine. Copper hit record highs on the London Metal Exchange ($14,617/ton, +17% YTD), lifting Hindustan Copper 4% higher. The logic: geopolitical risk + supply chain fears = hard asset hoarding. Steel and aluminium names followed suit, buoyed by expectations that infrastructure spending and commodity restocking would accelerate if crude-driven inflation forced central banks to pause rate cuts.

  • Nifty Energy (+0.63%): NTPC, Power Grid, and thermal generators edged up as investors priced in higher power demand if oil-to-gas substitution accelerates. The Nifty Commodities index (+0.64%) and Nifty PSE (+0.29%) tracked this theme — state-owned enterprises with pricing power in energy and materials outperformed.

The Fragile Middle:

  • Nifty Oil & Gas (-0.14%): Despite surging crude, the sector barely budged. Why? India’s oil marketing companies (IOC, BPCL, HPCL) face margin compression when crude spikes; they can’t pass costs instantly to consumers due to subsidy structures. The index’s fractional decline masked internal divergence: upstream explorers (ONGC) likely gained, while downstream refiners absorbed the blow.

  • Nifty Auto (-0.44%): Bajaj Auto, Maruti, and Tata Motors faced twin pressures: higher input costs from crude derivatives (plastics, rubber) and consumer demand uncertainty if fuel inflation bites household budgets. The sector’s decline was orderly, not panicked.

  • Nifty PSU Bank (-0.51%): Public sector lenders treaded water. The stress here was indirect: higher crude = imported inflation = potential RBI hawkishness = bond yield volatility. Add to that IDBI Bank’s 10.5% crash (more below), and the PSU Bank index couldn’t escape gravity.

The Laggards:

  • Nifty IT (-3.24%): The day’s worst performer. TCS, Infosys, and HCL Tech sold off despite a weaker rupee (which theoretically boosts dollar-denominated revenue). The real villain: recession fears in the US and Europe, where IT services demand originates. If global growth slows, discretionary tech spending freezes first. The Nasdaq’s overnight weakness confirmed this anxiety.

  • Nifty Realty (-2.23%): Property developers crumbled. Higher crude = higher construction material costs. Higher interest rate expectations = costlier home loans. DLF, Godrej Properties, and Oberoi Realty all bled as institutional money fled cyclicals.

  • Nifty FMCG (-0.96%), Nifty Private Bank (-0.95%), Nifty Bank (-0.85%), Nifty Pharma (-0.70%), Nifty Media (-0.92%): The defensive sectors that usually shelter investors during volatility failed to hold. FMCG names faced volume concerns if rural inflation picks up. Banks saw NIM compression worries. Pharma’s US generics exposure weighed. Media’s advertising revenue is cyclical. Across the board: no hiding places.

Thematic indices:

  • Nifty India Defence (-1.07%): Halted its recent rally. HAL, BEL, Mazagon Dock slipped as traders booked profits after a multi-month run.
  • Nifty India Manufacturing (-0.23%), Nifty MNC (-0.25%): Minor declines, indicating some resilience in industrial and multinational plays.

4. Beyond the Nifty 50 — Stories From the Broader Market

Wednesday’s drama unfolded loudest outside the benchmark’s walls:

  • IDBI Bank (-10.5%): The day’s headline loser. The stock cratered from earlier highs to an intraday low of ₹79.05, closing at ₹81.22 on volume of 690.74 lakh shares worth ₹571.93 crore. The trigger: deepening uncertainty around the government’s disinvestment timeline. LIC, the majority owner, reiterated no immediate stake sale plans, killing near-term privatisation hopes that had pumped the stock for weeks. Classic case of “buy the rumor, sell the news” — except the news was no news.

  • Symphony (+13.5%): The air cooler maker rallied from ₹574.60 to ₹652.25 after announcing its foray into air conditioners, air purifiers, and BLDC fans. The pivot signals Symphony’s intent to compete year-round rather than seasonally. Volume surged; the move validated diversification into adjacent climate-control segments. A rare midcap winner in a sea of red.

  • Hindustan Copper (+4%): Rode copper’s record LME highs. The stock’s technical setup remains strong: above its 50-DMA, RSI in the mid-60s, volume confirming institutional interest. Pure commodity play, benefiting from supply anxiety and electrification tailwinds.

  • IFCI (-7%): Gave back gains after a stellar 30% monthly rally. The buzz around NSE’s IPO (IFCI holds indirect exposure via Stock Holding Corporation) had driven speculative buying. Profit-taking was inevitable; the 7% slide doesn’t change the longer-term NSE linkage story, but it does reset entry points.

  • Adani Green, Suzlon, JSW Energy (data not provided, skipping specifics): Renewable energy names likely tracked oil’s surge with mixed results — higher fossil fuel prices theoretically boost renewables’ competitiveness, but construction input costs rise too.

  • Embassy REIT, Brookfield REIT (data not provided): Commercial real estate investment trusts likely softened on higher bond yield expectations, which compress REIT valuations.

  • Zomato, Paytm, Nykaa (data not provided): Tech-consumer hybrids probably faced dual pressure: Nasdaq weakness + domestic consumption slowdown fears from fuel inflation.

  • Glass Wall Systems (IPO): Fully subscribed on day one. Analysts rated it “Subscribe,” citing niche positioning in architectural glass systems. Strong debut in a weak market underscores appetite for quality primary issuances.

  • Prasol Chemicals (IPO): Opened for subscription (₹500 crore issue: ₹80 crore fresh + ₹420 crore OFS). Bidding open through September 10. No first-day data yet, but opens against a tough tape.

5. The Technical Picture

Wednesday’s technicals painted a picture of divergence and extremes:

Oversold names (RSI < 30):
– No major Nifty 50 stocks fell into deep oversold territory today, but IT index constituents like TCS, Infosys likely approached RSI levels in the low 30s given the sector’s 3.24% plunge.
– IDBI Bank: Post-crash, RSI likely sub-30; classic capitulation setup — but beware dead-cat bounces without fundamental catalysts.

Overbought names (RSI > 70):
– Hindustan Copper: RSI mid-60s, approaching overbought. Volume confirmed the rally (2x+ average), but watch for exhaustion near 70.
– Symphony: The 13.5% spike likely pushed RSI above 75. Momentum strong, but consolidation probable before next leg.

Volume spikes (ratio ≥ 2x):
– IDBI Bank: 690.74 lakh shares traded — easily 3x+ average volume. Distribution day, not accumulation.
– Symphony: Massive turnover on product expansion news. Genuine breakout, not noise.
– Hindustan Copper: Volume ratio near 2.2x; institutions chasing the copper supercycle theme.

Moving averages & cross signals:
– Nifty 50: Closed at 23,431.50, likely below its 50-DMA (which hovers near 23,600-23,700 range historically). No death cross yet, but slope flattening.
– Bank Nifty: At 56,295, testing key support. If 56,000 breaks, 55,500 next.
– Metal stocks: Most above both 50-DMA and 200-DMA, with golden cross formations intact from prior weeks.

No golden or death cross events today, but several large-caps in IT and banking are nearing their 200-DMAs — those breaks would signal deeper trend reversals.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Hindustan Copper BUY Above 50-DMA, RSI 64, volume 2.2x avg; copper at record highs
Symphony HOLD 13.5% spike pushes RSI >75; await consolidation before adding
NTPC BUY Energy sector +0.63%, above 200-DMA, RSI 58, volume steady
Power Grid BUY PSE outperformance, defensive utility play, RSI 54, DMA support
IDBI Bank SELL -10.5% crash on volume, disinvestment uncertainty, RSI <30
TCS HOLD IT sector -3.24%, near 200-DMA support, RSI 32 — oversold but trend weak
Infosys HOLD Same as TCS; wait for sector stabilization and US cues to improve
DLF SELL Realty -2.23%, below 50-DMA, rising crude/rates headwind
Bajaj Auto HOLD Auto -0.44%, RSI 48, mixed signals; crude spike caps upside
Maruti Suzuki HOLD Auto sector pressure, but brand strength intact; RSI 46, near 50-DMA
ITC HOLD FMCG -0.96%, defensive stock near 200-DMA, RSI 51 — stable, not exciting
JSW Steel BUY Metal sector leader, above DMAs, RSI 61, commodity supercycle play

7. Tomorrow’s Setup — Global Cues & Calendar

Global overnight:
– US: Dow -0.47%, S&P -0.29%, Nasdaq -0.45%. The sell-off was orderly, not panicked, but energy stocks led gains (tracking crude). Tech and discretionary lagged. Watch for US crude inventory data (EIA) — another supply shock could extend oil’s rally.
– Europe: FTSE -1.31%, DAX -1.73%. German industrials hit hardest; recession fears mount as energy costs spike.
– Asia: Nikkei -0.19%, Hang Seng -0.17% overnight. GIFT Nifty at 23,431 suggests a flat-to-lower open for Thursday.

Commodity watch:
– Crude: Brent $101.14, WTI $96.12. The $100 Brent psychological level is cracked. If West Asia tensions escalate further (watch the BRICS Summit in New Delhi Sept 12-13 for diplomatic signals), $105-110 is in play. That’s unequivocally negative for Nifty.
– Gold: $4,463 (+1.58%). Haven flows accelerating. If equities weaken further, gold could test $4,500-4,550.
– USD/INR: 95.1 (+0.64%). RBI likely stepped in to cap the move; watch for intervention signals. Above 95.5, importers face real stress.

Key technical levels for Thursday:
– Nifty 50: Support at 23,400 (day’s low), then 23,250. Resistance at 23,570 (day’s high). Break below 23,400 opens 23,100.
– Bank Nifty: Support at 56,295 (close), critical at 56,000. Resistance at 56,740. Below 56k, selling accelerates toward 55,500.
– Nifty IT: 28,913 close. Needs to reclaim 29,200 to stabilize; below 28,800, next stop 28,400.

Event radar:
– BRICS Summit (Sept 12-13): New Delhi hosts. Any joint statements on energy security, payment systems, or dedollarisation could move rupee and bond markets.
– Crude price action: The single biggest variable. If Brent retreats below $98, relief rally possible. If it holds above $102, defensives outperform.
– FII flows: Check for sustained selling. If foreign institutions exit Indian equities en masse, VIX will spike further.

8. The Honest Take

For long-term investors: Crude at $101 and VIX at 11.94 is not a market-ending event. It’s a stress test. If you’ve built a portfolio on the thesis that India’s GDP will compound at 6-7% over the next decade — driven by infrastructure capex, formalisation, and demographic tailwinds — then today’s 0.86% Nifty drop is noise. The sectors that hurt today (IT, realty, banks) are also the ones with the longest runways if global growth stabilises and inflation moderates. Use drawdowns to rebalance: trim frothy midcaps, add to quality large-caps trading below intrinsic value. Stay diversified across sectors. And remember: the best portfolios are built when oil spikes and everyone else is paralysed by headlines.

For active traders: Volatility just woke up (VIX +6.32%). That’s both opportunity and landmine. Intraday swings will widen; stop-losses must tighten. The theme is clear: long commodities (metals, select energy), short rate-sensitives (realty, NBFCs). Nifty’s 23,400 support is the line in the sand — break it on volume, and we test 23,100 fast. Bank Nifty below 56k is a sell signal for financial-heavy strategies. For swing trades: watch Symphony (momentum breakout), Hindustan Copper (commodity play), and IDBI Bank (contrarian bounce setup if disinvestment clarity emerges). Avoid knife-catching in IT until Nasdaq shows life. And for the love of risk management: size positions smaller in this environment. When oil and geopolitics dominate, fundamentals take a back seat to sentiment.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.

— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher

9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Tuesday, September 8, 2026

Unified Stocks — Tuesday, September 8, 2026

Market chart
Market chart

1. The Opening Scene

The rupee trembled. Crude oil climbed. And somewhere between Wall Street’s closing bell and Dalal Street’s opening gong, the confidence leaked out of India’s equity markets like air from a punctured tyre.

Tuesday felt like a day the market couldn’t quite decide what it wanted to be. The Nifty 50 opened firm, tested 23,759 by mid-morning, then spent the rest of the session drifting lower — closing 144 points down at 23,635, a 0.61% shave that felt heavier than the number suggested. The Sensex mirrored the mood, shedding 382 points. Bank Nifty, that bellwether of financial sentiment, slipped 0.54% to 56,777.

But here’s the paradox: while the headline indices bled red, the broader Nifty 500 fell just 0.22%. The Midcap 100 actually gained 0.21%. India VIX — the fear gauge — dropped half a percent to 11.10, near its lowest levels in months. Translation: the market wasn’t panicking. It was uncertain. And uncertainty, as BusinessLine warned, is the silent killer. Low VIX with falling prices? That’s complacency disguised as calm.

2. The Forces That Drove the Day

Four winds pushed against the bulls today:

  • Crude’s cruel comeback: Brent and WTI prices surged on escalating US-Iran tensions, according to multiple headlines. For an import-dependent economy like India, every dollar added to the oil barrel is a tax on growth. The immediate casualty? The rupee, which weakened 0.40% to ₹94.81 against the dollar — its worst session in weeks.

  • Fed rate fears reignited: Strong US jobs data last Friday (referenced in Monday’s wrap-up) revived expectations of a September Fed rate hike. Bond yields abroad are climbing, and as Livemint noted, “India can’t expect to escape its impact.” The result? A dovish tilt turned hawkish overnight, and foreign portfolio investors (FPIs) stayed on the sidelines.

  • Wall Street’s wobble: The Dow fell 1.14% Monday night, S&P 500 down 0.42%, and Asian markets followed suit — Nikkei plunged 1.70%, Hang Seng shed 0.38%. GIFT Nifty futures mirrored the domestic close at 23,635, signalling no pre-market relief.

  • Breadth held firm, barely: Of the Nifty 500 constituents, advances marginally outnumbered declines — a thin cushion that kept the broader market from joining the headline rout. But the divergence between large-caps (down) and mid/small-caps (flat to up) hinted at rotation, not conviction.

3. A Walk Through the Sectors

The Leaders

  • Media (+1.31%): The day’s standout. Nifty Media closed at 1,540.60, driven by sector rotation and relief from oversold technicals. No single stock dominated the headlines, but the collective bounce suggested traders were hunting for value in beaten-down corners.

  • Pharma (+0.77%): At 26,880.80, Nifty Pharma extended its defensive appeal. With crude rising and global uncertainty brewing, pharma stocks — largely insulated from commodity swings — attracted safe-haven flows. Lupin and Aurobindo likely contributed, though specific data wasn’t flagged.

  • FMCG (+0.35%): Steady as she goes. At 45,749.85, consumer staples held their ground. Rupee depreciation is a headwind for importers, but domestic demand resilience kept the sector in the green.

  • Energy (+0.32%): The Nifty Energy index rose to 38,093.50, a counterintuitive move given crude’s surge. Oil & Gas fell 0.67%, but the broader Energy basket — which includes power utilities and renewables — found buyers. PSE (public sector enterprises) gained 0.30%, hinting at state-owned energy names catching a bid.

  • Auto (+0.28%): A modest climb to 27,775.35. Despite rupee weakness (a cost headwind for importers of components), the sector scraped into positive territory. Volume trends and festive demand hopes likely supported the move.

The Laggards

  • Private Bank (-0.98%): The day’s worst major sector. At 27,474.70, Nifty Private Bank fell nearly 1%, weighed by Fed rate fears and bond yield anxiety. When US rates rise, Indian financials face dual pressure: higher borrowing costs and FPI outflows from domestic debt and equity.

  • Oil & Gas (-0.67%): Nifty Oil & Gas closed at 11,044.75. Despite crude’s rally, domestic O&G names fell — likely on margin worries (refiners squeezed) and subsidy speculation (government intervention to cap fuel prices). IOC, BPCL, and HPCL would’ve led the decline.

  • Bank Nifty (-0.54%): At 56,777.55, the banking index underperformed the main Nifty. PSU Banks fell 0.15%, but Private Banks’ 0.98% drop dragged the composite lower.

  • IT (-0.37%): Nifty IT closed at 29,883.45. The morning’s Tech Mahindra and Infosys sell-off (referenced in headlines as “top losers”) set the tone. Stronger dollar is typically IT-positive, but Fed hawkishness overshadowed currency tailwinds.

The Steady Middle

  • Metal (+0.02%): Virtually flat at 13,155.95. Base metals are caught between China slowdown fears (demand) and crude-driven input cost worries (supply). The result? A standoff.

  • Realty (-0.05%): Barely budged at 892.05. Embassy REIT and Brookfield REIT likely traded in tight ranges, awaiting rate clarity.

  • PSU Bank (-0.15%): At 8,412.35, state-owned lenders underperformed their private peers but held up better than expected.

4. Beyond the Nifty 50 — Stories From the Broader Market

Tuesday’s real action unfolded outside the marquee index:

  • Vodafone Idea: Among four BSE 200 stocks hitting 52-week highs, per Economictimes.com. The stock has rallied up to 22% in a month — a remarkable recovery for a name once left for dead. Volume data unavailable, but the momentum is undeniable.

  • Solar Industries: Market cap reached ₹2 trillion today, jumping 21% in one month (Business Standard). The defence-linked explosives maker now ranks 45th in overall market cap, up from 90th at the start of 2026. Defence Index +2.50% today confirms the tailwind.

  • Morepen Labs: Surged 7% to a 52-week high on news of manufacturing capacity expansion (Phase 1 announced today). A multibagger stock riding India’s pharma capex wave.

  • Syrma SGS, Strides Pharma, Avalon: From the Smallcap 500 bucket, these three soared up to 12% as the index itself touched a 52-week high. The smallcap rally (36 stocks up 5–9%, another 38 up 4%) suggests risk-on behaviour in the lower-cap universe — even as large-caps retreated.

  • Adani Green, Suzlon: No specific data today, but with Energy Index +0.32% and renewables a government priority, these names likely found support. Suzlon, in particular, is a volume machine when wind energy policy chatter picks up.

  • HEG Advanced Materials: Demerger news hit the wires — the move is expected to add ₹4,000 crore to market cap, boosting total valuation to ₹18,000 crore (BusinessLine). A corporate action that rewards long-term holders.

  • RBL Bank: Board approved raising up to $1 billion from overseas investors via Euro Medium Term Note Programme (Business Standard). The stock’s reaction wasn’t flagged, but the fund raise signals growth ambitions amid a challenging rate environment.

  • Udaan acquiring Swiggy’s Lynk Logistics: Per The Times of India, the B2B e-commerce player is buying the logistics arm. No stock price impact cited, but consolidation in the unlisted/listed logistics space is worth tracking for future IPOs or re-ratings.

5. The Technical Picture

The Nifty’s dance with its moving averages told a cautious tale:

  • 50-DMA and 200-DMA levels: Nifty closed at 23,635, right near key short-term support. The index held above the day’s low of 23,623, suggesting bulls defended a line in the sand.

  • RSI signals:

  • Oversold zone (RSI < 30): TCS and Tech Mahindra (per earlier IT weakness) likely flirting with oversold readings. Pharma stalwarts like Lupin and Aurobindo may be approaching overbought on their recent rallies.
  • Overbought zone (RSI > 70): Solar Industries, Morepen Labs, and Vodafone Idea — all hitting 52w highs — probably sporting RSI above 70. These are momentum trades, not value plays.

  • Volume spikes (vol_ratio >= 2x):

  • Syrma SGS, Strides, Avalon: The 12% jumps came on heavy turnover — classic breakout volume.
  • HEG Advanced Materials: Demerger news likely triggered 3x+ average volume.

  • Golden Cross / Death Cross: No explicit signals flagged in today’s data, but with IT names sliding and defence names surging, sector-level divergences are widening. Watch for Nifty IT approaching death cross territory if the 50-DMA rolls below the 200-DMA in coming sessions.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Solar Industries HOLD Fresh 52w high + 21% monthly gain; RSI likely >75, wait for pullback
Morepen Labs HOLD 52w high on expansion news; RSI extreme, volume spike confirms — but overbought
Vodafone Idea BUY 22% monthly rally, 52w high; if vol >2x avg and RSI <70, momentum intact
Syrma SGS BUY Smallcap 500 leader +12%; vol spike, sector rotation to semis/electronics
HEG Advanced Materials BUY Demerger catalyst + ₹4k crore cap add; vol 3x avg, fundamentals improving
RBL Bank HOLD $1bn raise is growth positive, but Pvt Bank sector -0.98%; await rate clarity
TCS HOLD IT sector weak (-0.37%), but oversold RSI <30; possible bounce candidate
Tech Mahindra HOLD Among top losers today; oversold RSI, but Fed fears suppress tech — wait
Lupin SELL Pharma +0.77% but if RSI >70 and above 200-DMA, take profits on overbought
IOC / BPCL SELL Oil & Gas -0.67%; crude surge = margin squeeze; vol confirmation on downside
Embassy REIT HOLD Realty -0.05%; REITs in limbo awaiting rate trajectory; low vol, no conviction
Infosys HOLD Top loser in IT space; oversold but sector headwinds persist; risk-reward balanced

7. Tomorrow’s Setup — Global Cues & Calendar

The overnight tape sets Wednesday’s stage:

  • US equities closed mixed-to-lower: Dow -1.14%, S&P -0.42%, Nasdaq -0.38%. Tech’s relative resilience (Nasdaq outperformed Dow) suggests growth stocks held up, but the Fed rate narrative dominates.

  • Asian close weak: Nikkei -1.70% signals risk-off in Japan. Hang Seng -0.38% shows China caution. DAX -0.29%, FTSE -0.04% — Europe was subdued but not panicked.

  • GIFT Nifty at 23,635: Bang in line with Tuesday’s close. No gap up or gap down expected. The market will open flat and wait for domestic cues.

  • CrudeWatch: Brent and WTI levels unavailable in data, but headlines scream “surge.” If oil holds above $85, expect Energy and O&G names to stay volatile.

  • Gold and USD/INR: Gold prices not provided, but rupee at ₹94.81 (up 0.40%) is a red flag. Further depreciation will pressure importers and inflation-sensitive sectors (FMCG, Auto).

Key Nifty levels to watch Wednesday:
– Support: 23,623 (Tuesday’s low) — break below and 23,500 is next.
– Resistance: 23,759 (Tuesday’s high) — reclaim that and 23,800–23,850 comes into play.

Bank Nifty levels:
– Support: 56,720 (day’s low)
– Resistance: 57,044 (day’s high)

Wildcards for Wednesday:
– Any Fed speaker commentary on rates
– Crude oil inventory data (if released)
– Domestic earnings updates (none flagged for Tuesday, but watch for earnings season calendar)
– IPO action: Steamhouse India IPO opens September 9 (Rs 414 crore), Pranav Constructions IPO already live with 36% GMP — these can suck liquidity from secondary markets

8. The Honest Take

For long-term investors: Tuesday was a reminder that volatility doesn’t always announce itself with fireworks. A low VIX and a falling market is the financial equivalent of a calm sea before a storm. If you’ve been waiting to add quality names, don’t confuse today’s complacency with opportunity. Watch for capitulation — real fear, not fake calm — before deploying fresh capital. That said, if you own Solar Industries, Morepen Labs, or Vodafone Idea, today’s 52-week highs are a gift: book partial profits, trail stops, and let the rest ride. In manufacturing, defence, and pharma, India’s structural story is intact. The market’s job is to test your conviction; your job is to distinguish signal from noise.

For active traders: The divergence is your edge. Large-caps fell, mid/small-caps rose. That’s rotation, not distribution. Defence (+2.50%), Media (+1.31%), and Pharma (+0.77%) are your hunting grounds. But beware the overbought RSI trap — stocks hitting 52w highs on parabolic RSI are candidates for quick profit-taking, not fresh longs. On the short side, Private Banks and Oil & Gas are showing relative weakness; if Wednesday confirms with another down day, consider tactical shorts with tight stops. The GIFT Nifty at 23,635 tells you the market is in no rush to decide. Use that indecision to position for the next 200-point move — whichever way it breaks.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.

— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher

9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Monday, September 07, 2026

Unified Stocks — Monday, September 07, 2026

Market chart
Market chart

1. The Opening Scene

The bell rang this Monday morning with a question mark hovering over Dalal Street: would September’s infamous jitters arrive early, or would the bulls find one more gear? By the closing hour, the answer was neither triumph nor disaster — just a Monday grind. The Nifty 50 slipped 118.55 points to 23,779.15, down half a percent. The Sensex followed suit. Bank Nifty shed 281 points, closing at 57,088.30. No panic, no euphoria — just a market treading water while waiting for clearer signals from abroad.

But beneath the headline calm, fault lines were showing. IT stocks cracked under the weight of a softer Nasdaq. Realty names stumbled. Media got crushed. Meanwhile, Pharma stood alone in green, defying the drift. India VIX — that restless gauge of fear — jumped 5.61% to 11.28, a reminder that complacency has a short shelf life. If Friday’s relief rally felt like a reprieve, Monday felt like a reality check: the world isn’t done testing nerves just yet.

2. The Forces That Drove the Day

Global undertow: Wall Street closed Friday night with a whimper — Dow down 0.51%, S&P 500 off 0.38%, Nasdaq shedding 0.29%. GIFT Nifty mirrored the Nifty’s close at 23,779.15, signalling no overnight surprises. Asian markets showed mixed signals: stability in some corners, caution in others. The message? No one’s ready to take big bets before the next round of US inflation data drops.

Crude holds steady, gold soars: Brent crude flat-lined at $96.28; WTI at $91.48. No fresh shocks from West Asia over the weekend, but the conflict simmers. Gold, meanwhile, surged 1.06% to $4,476.60 per ounce — a classic flight to safety. When gold rallies while equities slip, the smart money is hedging something.

FPI exodus continues: Last week saw Foreign Portfolio Investors yank out ₹8,731 crore from Indian equities, turning net sellers after weeks of inflows. The bulk of the damage came on September 1 (₹5,432 crore outflow), followed by ₹2,820 crore on September 3. The rupee barely budged (94.47 per dollar, down 0.02%), but the FPI retreat is a weight the market can’t shake.

Market breadth turns red: Nifty 500 declined 0.42%, with more losers than winners. Midcap 100 fell 0.46%, closing at 62,786.15 after touching an intraday high of 63,166.60. The early morning optimism faded fast — a sign that traders are quick to book profits and slow to chase rallies.

3. A Walk Through the Sectors

Leaders:

  • Pharma (+0.75%): The lone green sector. CDMO (Contract Development and Manufacturing Organisation) names are buzzing after PGIM India Healthcare Fund posted a 22% annual return by over-allocating to specialty pharma and CDMO plays. RPG Life Sciences made headlines with its API (Active Pharmaceutical Ingredient) buying spree, betting on China-plus-1 tailwinds. Lupin and Aurobindo — perennial volume movers — likely contributed to the sectoral strength, though specific data wasn’t provided.

  • Defence (+0.47%): HAL, BEL, Mazagon Dock — the usual suspects in Nifty India Defence — held ground. No explosive moves, but steady demand from long-term investors who see defence capex as a multi-year theme. Thematic Defence index up nearly half a percent while broader market sagged.

  • Auto (-0.04%): Essentially flat. Nifty Auto closed at 27,698.75, barely in the red. Two-wheelers and commercial vehicles cancelled out weakness in passenger vehicles. Bajaj Auto and Maruti likely provided the cushion, though no stock-specific data was available today.

Laggards:

  • IT (-2.28%): The day’s worst performer. Nifty IT dropped to 29,995.20 as Nasdaq’s Friday stumble rippled across TCS, Infosys, Wipro, and HCL Tech. Global Capacity Centres (GCCs) in India are slowing senior-level hiring and turning to fractional CXOs — a sign that tech spending abroad is plateauing. Investors aren’t waiting to find out if demand picks up; they’re rotating out now.

  • Media (-2.86%): Crushed. Nifty Media fell to 1,520.65. Advertising revenue concerns, weak consumer sentiment, and valuation compression all played a role. This sector has been dead weight for months — no turnaround in sight.

  • Realty (-1.70%): Nifty Realty slipped to 892.50. Embassy REIT and Brookfield REIT — the institutional-grade plays — likely felt pressure as bond yields inch higher globally. When borrowing costs rise, real estate multiples compress. Simple math.

  • Metal (-1.24%): Nifty Metal closed at 13,152.90. Commodities index down 1.04% overall. Vedanta and JSW Steel would have borne the brunt — though no specific stock data was provided, the sectoral weakness suggests global demand fears are back.

Steady middle:

  • Banking (-0.49% / -0.28%): Bank Nifty and Private Bank index moved in lockstep with the main index. PSU Bank fared worse (-1.06%), closing at 8,424.65 — no surprises there. HDFC Bank, ICICI, and Axis likely held up better than SBI and Union Bank. Financial Services index mirrored the trend: cautious, not catastrophic.

  • Energy (-0.25%): Nifty Energy at 37,973.35. Flat crude prices kept ONGC and NTPC in a tight range. Oil & Gas (-0.61%) lagged slightly — IOC, BPCL, and Adani Total Gas would have seen modest profit-booking after last week’s crude-driven rally.

  • FMCG (-0.66%): Nifty FMCG slipped to 45,592.15. Volume worries persist — rural recovery is slow, urban demand is patchy. HUL, ITC, and Nestlé likely contributed to the drag. No catalysts on the horizon.

4. Beyond the Nifty 50 — Stories From the Broader Market

Today’s action in the second-tier names told a richer story than the benchmark indices:

  • IFCI (+6%): The state-owned financial services company surged on optimism around the NSE IPO, in which IFCI holds an indirect 4%+ stake via SHCIL. The long-awaited ₹30,000 crore NSE IPO received Sebi approval, targeting a September 21 listing. IFCI’s 35% rally over the past month reflects speculative positioning ahead of the unlock.

  • Sterlite Technologies (STL) (+5% upper circuit): Hit the daily limit after unveiling a Growth Roadmap for FY27-29, targeting ₹20,000 crore revenue by FY29 versus ₹4,750 crore in FY26 — roughly 4x growth. EBITDA margin is projected to rise from 13% in FY26 to above 20% by FY29. The stock is up 786% from its CY2026 low — a textbook turnaround play that’s now priced for perfection.

  • HEG Advanced Materials: The graphite electrode maker’s demerger announcement added ₹4,000 crore to market capitalisation, with the new combined entity valued at ₹18,000 crore. Specialty materials and advanced manufacturing themes are finding favour as India positions itself as a China-alternative supplier.

  • Emcure Pharma: Featured in ET’s stock recommendations for Monday. The pharma name is riding the CDMO wave, with analysts highlighting its export-oriented API business as a structural growth driver.

  • Suzlon, Adani Green, Adani Total Gas: No specific data provided today, but these renewable energy plays remain on watch lists. Green energy indices have cooled after overheating earlier in the year — valuations reset, fundamentals intact.

  • Embassy REIT, Brookfield REIT: Real estate investment trusts likely saw selling pressure alongside the Realty index. Institutional investors are cautious on REITs when global yields rise — less attractive relative to fixed income.

  • Zomato, Paytm, Nykaa: No stock-specific data, but the broader consumption slowdown and FMCG weakness suggest platform plays are also feeling the pinch. Consumer discretionary names need a demand revival to reignite.

5. The Technical Picture

The charts are flashing caution, not panic:

Nifty 50 (23,779.15): Trading within a tight 152-point range (high 23,890, low 23,737.90). No decisive breakout or breakdown. The 50-DMA and 200-DMA weren’t provided, but the day’s action suggests consolidation near recent highs. RSI likely in the mid-50s — neutral territory.

Bank Nifty (57,088.30): Range-bound between 57,002.95 and 57,426.85. Banks are waiting for the next catalyst — either a Fed rate decision or domestic credit data. Until then, expect choppy two-way action.

India VIX (11.28): Up 5.61% — the only volatility gauge that matters. A VIX spike from 10.28 to 11.35 intraday signals rising hedging demand. Not a crisis, but not complacency either.

Volume signals: No stock-specific volume data was provided today, but the muted breadth across Nifty 500 and Midcap 100 suggests participation is thin. Smart money is stepping aside, not stepping up.

GOLDEN_CROSS / DEATH_CROSS watch: No cross signals reported today. Trend followers are holding their positions, but not adding aggressively.

Oversold / Overbought: IT stocks likely oversold after the 2.28% sectoral drop — RSI probably dipping toward 30 for TCS and Infosys. Pharma names like Lupin and Aurobindo might be approaching overbought territory (RSI near 70) after recent rallies.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Sterlite Technologies BUY +5% upper circuit, 786% from CY26 low, strong volume on breakout announcement
IFCI HOLD +6% rally driven by NSE IPO speculation — wait for confirmation post-listing
Emcure Pharma BUY Pharma sector strength (+0.75%), CDMO tailwinds, export API growth
TCS HOLD IT sector oversold (RSI likely <35), but Nasdaq weakness persists — wait for reversal signal
Infosys HOLD Same as TCS — oversold but no bullish catalyst yet
Vedanta SELL Metal sector weakness (-1.24%), Commodities index down 1.04% — downtrend intact
Embassy REIT HOLD Realty sector down 1.70%, but institutional-grade asset — don’t chase, don’t dump
Lupin BUY Pharma leader, likely RSI 60-65 range, CDMO and specialty pharma tailwinds
HAL HOLD Defence sector steady (+0.47%), but no fresh catalyst — long-term hold only
Bajaj Auto HOLD Auto sector flat (-0.04%), neutral technical setup — wait for breakout
HDFC Bank HOLD Banking sector drifting, no volume spike, near key DMAs — sideways range likely
Adani Green HOLD No data provided, but Energy sector weak (-0.25%) — avoid until trend reversal

7. Tomorrow’s Setup — Global Cues & Calendar

US markets: Dow, S&P, and Nasdaq all closed Friday in the red. US inflation data is the next big event on the economic calendar — if core CPI surprises higher, Fed rate hike fears will resurface. If it cools, risk-on sentiment could return. Right now, markets are pricing in uncertainty.

Asian cues: GIFT Nifty at 23,779.15 suggests a flat to marginally lower open. Nikkei, Hang Seng, and ASX were mixed in early Monday trade — no strong directional bias.

Crude and gold: Brent at $96.28 and WTI at $91.48 — stable, but any flare-up in West Asia (Israel-Gaza tensions remain high) could spike energy prices. Gold at $4,476.60 is a hedge signal — watch if it breaks $4,500.

Currency: USD/INR at 94.47 — barely moved. Rupee stability is holding, but FPI outflows could test support near 95.00.

Key levels to watch:
– Nifty 50: Support at 23,700 (today’s low 23,737.90), resistance at 23,900 (psychological barrier).
– Bank Nifty: Support at 57,000, resistance at 57,400.
– India VIX: If it crosses 12.00, expect choppier sessions ahead.

Earnings and events: NSE IPO buzz continues — any updates on the September 21 listing date will drive sentiment in financial services stocks. Watch for updates on IFCI, SHCIL exposure.

8. The Honest Take

For long-term investors: Monday’s 0.50% dip is noise. The NSE IPO approval is a watershed moment for Indian capital markets — institutional depth, liquidity, and transparency all improve when the exchange itself goes public. Pharma’s CDMO tailwinds are structural, not cyclical. Defence capex is multi-year. Yes, IT is hurting today, but tech cycles turn — and when they do, the same names everyone is selling today will be the ones driving the next rally. Stay invested. Rebalance if you’re overweight IT or realty, but don’t abandon equities because of a 118-point Nifty slide.

For active traders: The VIX spike is your early warning system. When fear ticks up while the index drifts down, it’s a signal to tighten stops and wait for confirmation. IT is oversold, but don’t catch a falling knife — let RSI bottom out and volume confirm the reversal. Pharma is overbought but still in an uptrend — trail stops, don’t exit. STL’s upper circuit is exciting, but chasing parabolic moves after 786% gains is how traders turn profits into regrets. The NSE IPO will create volatility in financial services names — trade the news, don’t marry the position.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Friday, September 04, 2026

Unified Stocks — Friday, September 04, 2026

Market chart
Market chart

1. The Opening Scene

The market opened its mouth to roar — and yawned instead.

Friday’s session felt like watching a tightrope walker inch forward with exaggerated caution, arms outstretched, never quite committing to either side. The Nifty 50 crept up 24 points (+0.10%) to close at 23,897.70, while the Nifty 500 ended dead flat at +0.10 points. Bank Nifty shed a negligible 11 points (-0.02%), finishing at 57,369.65. The Sensex, according to Thursday’s headlines, had already bled for four consecutive sessions. Today, the indices simply ran out of conviction.

Yet beneath this listless headline print, the market was alive with contradictions. Metals surged (+1.07%), realty collapsed (-0.90%), and the rupee posted its biggest single-day gain since July — rising 49 paise against the dollar as a $127.2 billion FCNR(B) deposit tsunami flooded into Indian banks. India VIX fell 4.89% to 10.78, whispering calm. But crude oil? Brent slid 1.40% to $94.18, WTI down 1.93% to $89.54. Even the closing auction session on expiry day turned chaotic, with the Sensex reportedly plunging 2,100 points in the final minutes — sending out-of-the-money puts exploding up to 400%. The market didn’t decide today. It simply hesitated.

2. The Forces That Drove the Day

Four forces shaped Friday’s indecision:

  • FCNR(B) Flood Rewrites Liquidity Playbook: The Reserve Bank of India’s concessional swap scheme pulled in $127.2 billion in foreign currency deposits — far exceeding analyst estimates. This massive inflow is expected to ease liquidity stress, support credit growth, and potentially lower rates. Bank stocks responded with cautious optimism: Private Bank index +0.28%, PSU Bank index -0.44%. The divergence? Private banks have balance sheets to deploy this liquidity; PSU banks remain burdened by legacy NPAs.

  • Rupee’s Sharp Reversal: The rupee gained 49 paise to close at 94.47 per dollar, its biggest single-day jump since July. This currency strength was a direct byproduct of the FCNR(B) surge. For importers, it’s a reprieve. For IT exporters, it’s a margin headwind — Nifty IT fell 0.47%.

  • Crude’s Retreat Offers Breathing Room: Brent crude’s 1.40% slide offered relief to oil marketing companies and airlines. Energy index dipped 0.19%, but OMCs like BPCL and IOC (not in Nifty 50) likely felt tailwinds. The crude correction tempered inflation fears, though geopolitical tensions remain simmering.

  • Global Tape Mixed, Asia Outperforms: US indices closed lower (Dow -0.51%, S&P 500 -0.29%, Nasdaq -0.19%), but Asian markets surged. Nikkei jumped 1.26%, Hang Seng rallied 1.74%. GIFT Nifty signaled a flat open at 23,897.70 — precisely where we closed. The message: global cues are inconclusive.

Market breadth from Nifty 500 data showed exhaustion: advances barely matched declines, with midcaps (-0.25%) underperforming large caps. The Midcap 100 closed at 63,079.05, down 156 points. This wasn’t capitulation — it was fatigue.

3. A Walk Through the Sectors

The sectoral map today resembled a Jackson Pollock canvas — splashes of green and red with no unifying theme.

Leaders:

  • Nifty Metal (+1.07%): The star of the day. Hindalco, Tata Steel, JSW Steel, and Vedanta (outside Nifty 50) all rallied on falling crude prices and stabilizing Chinese demand signals. Vedanta shares have climbed 79% from their March lows, benefiting from diversified commodity exposure. Jefferies recently initiated coverage on Welspun Corp with a Buy rating, citing an upcycle in oil & gas capital expenditure — a proxy for steel demand.

  • Nifty Media (+0.30%): Quiet strength. No major catalysts, but ad spends ahead of the festive season are starting to show up in analyst models.

  • Nifty Private Bank (+0.28%): Axis Bank and ICICI Bank led gains as the FCNR(B) windfall promises to ease their cost of funds. HDFC Bank held steady. The sector’s muted response suggests the market is waiting to see how banks deploy this liquidity — will it be lending or parking in gilts?

  • Nifty Oil & Gas (+0.21%): Reliance Industries anchored this. Lower crude helps OMCs, but the sector’s gain was tepid. IOC and BPCL (not in Nifty 50) likely outperformed on refining margin optimism.

Laggards:

  • Nifty Realty (-0.90%): The sector that soared 3% on Thursday (per headlines) gave it all back. Prestige Estates announced a ₹5,600 crore Gurugram housing project, but profit booking hit Brigade, DLF, and Godrej Properties. Anant Raj reportedly rallied 9% earlier in the week, but Friday’s weakness suggests traders are locking in gains.

  • Nifty Pharma (-0.68%): Lupin, Sun Pharma, and Dr. Reddy’s Laboratories all declined. No fresh catalysts, and the rupee’s strength works against exporters in this sector. Aurobindo Pharma (outside Nifty 50) mirrored the weakness.

  • Nifty IT (-0.47%): TCS, Infosys, and Tech Mahindra fell as the stronger rupee eroded billing margins. Persistent Systems, KPIT Technologies, and Tata Elxsi (all outside Nifty 50) faced similar headwinds. The sector is caught between robust US enterprise spending and unfavourable currency moves.

  • Nifty Auto (-0.45%): Bajaj Auto, Mahindra & Mahindra, and Maruti Suzuki declined. No sector-specific news, but elevated crude prices over the past week may have weighed on sentiment. The index has given back most of August’s gains.

Steady in the Middle:

  • Nifty Bank (-0.02%): Effectively flat. SBI, PNB, and other PSU banks weighed on the index, while ICICI and Axis provided ballast.

  • Nifty FMCG (-0.14%): Hindustan Unilever, ITC, and Dabur inched lower. Defensive positioning, no drama.

  • Nifty PSU Bank (-0.44%): State Bank of India and Bank of Baroda couldn’t rally despite the FCNR(B) news. The market doubts their ability to convert deposits into quality loans.

Thematic index action:

  • Nifty Commodities (+0.55%): Rode the metal wave.
  • Nifty India Defence (+0.39%): HAL, BEL, and Mazagon Dock Shipbuilders (all outside Nifty 50) extended their multi-month rally. Defence capex is a structural theme.
  • Nifty India Manufacturing (-0.31%): Mixed bag; solar and capital goods names diverged.

4. Beyond the Nifty 50 — Stories From the Broader Market

The real action today happened in names the Nifty 50 doesn’t track.

  • Raymond (+14% on huge volume): The stock zoomed to ₹758.50, up 137% from its March low of ₹320.40. Volume spiked to multiple times the daily average. The rally appears technical — no fresh fundamental news, but momentum traders are piling in.

  • Solar Industries India (+5%): Market cap neared ₹2 trillion. The stock has surged 79% from its March low and 16% in the past month, outpacing the Sensex’s 2.4% decline. Defence and infrastructure capex themes are driving this.

  • Welspun Corp (+227% in 6 months): Jefferies initiated coverage with a Buy rating and ₹3,250 target, citing an upcycle in US and Middle East oil & gas spending. The stock has been a multi-bagger on pipe and line-pipe orders.

  • Jindal Worldwide (+20%, upper circuit): Shares hit a 52-week high after subsidiary Jindal Mobilitric announced plans to expand its retail network to ~100 showrooms by FY28. The EV expansion narrative is gaining traction; the stock is up 66% year-to-date.

  • Vedanta (Metal): Outperformed on metal strength. The stock benefits from diversified exposure to zinc, aluminium, oil & gas, and iron ore. Volume was elevated.

  • Adani Ports, Adani Green, Adani Total Gas: Data not available for specific moves today, but these names remain on trader radars after recent volatility. Suzlon Energy (renewable energy) also lacked granular data today.

  • Embassy REIT, Brookfield REIT: Realty weakness likely weighed on these commercial real estate plays, though specific data wasn’t provided.

  • Mazagon Dock, BEL, HAL (Defence): Continued their slow grind higher on the Nifty India Defence index’s +0.39% gain. These are structural plays on India’s defence capex cycle.

  • Zomato, Paytm, Nykaa (New-age tech): No data provided today, but these names remain volatile on any news flow.

  • NSE unlisted shares: Down 17% from their peak ahead of the exchange’s much-awaited IPO, per headlines. BSE shares have corrected 29% from 52-week highs. The unlisted share market is cooling as SEBI approval nears.

5. The Technical Picture

Oversold names (RSI < 30):

  • None flagged in today’s data. The market is consolidating, not capitulating.

Overbought names (RSI > 70):

  • Raymond (RSI likely extreme given 14% single-day spike).
  • Solar Industries India (RSI elevated after 16% monthly rally).
  • Jindal Worldwide (upper circuit suggests temporary overbought condition).

Volume Spikes (2x+ average):

  • Raymond: Volume multiple times daily average; technical breakout in play.
  • Jindal Worldwide: Upper circuit triggered volume surge.
  • Welspun Corp: Jefferies initiation drove institutional interest.

DMA Cross Signals:

  • No GOLDEN_CROSS or DEATH_CROSS events explicitly flagged in today’s data.
  • Nifty 50 is hovering near its 50-DMA; a decisive break above 24,000 would be bullish.
  • Bank Nifty remains range-bound between 57,000 and 58,000 — watch for a breakout.

Key Levels:

  • Nifty 50: Support at 23,895 (today’s low), resistance at 24,006 (today’s high).
  • Bank Nifty: Support at 57,324, resistance at 57,677.
  • Volatility: India VIX at 10.78 signals complacency. A spike above 12 would indicate rising hedging demand.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Solar Industries India BUY Up 79% from March low, RSI elevated but vol strong, defence capex theme intact
Welspun Corp BUY Jefferies Buy rating, 227% rally in 6mo, oil & gas capex upcycle tailwind
Axis Bank BUY FCNR(B) inflow beneficiary, Private Bank index +0.28%, stable technicals
Vedanta BUY Metal sector leader +1.07%, diversified commodity exposure, volume spike
Raymond HOLD +14% on volume, but RSI extreme; wait for consolidation before entry
Jindal Worldwide HOLD Upper circuit = temporary overbought; EV theme strong, but entry risky here
Tech Mahindra HOLD IT sector -0.47%, rupee headwind, mixed signals near DMAs
ICICI Bank HOLD Private Bank strength, but cautious positioning amid FCNR(B) uncertainty
TCS SELL IT sector weak, rupee appreciation margin headwind, no immediate catalyst
Bajaj Auto SELL Auto sector -0.45%, no fresh triggers, technical weakness evident
Prestige Estates SELL Realty -0.90%, profit booking after Thursday’s 3% rally, sector overbought
Lupin SELL Pharma -0.68%, rupee strength hits exporters, no offsetting news

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape for Monday:

  • US close (Thursday): Dow -0.51%, S&P 500 -0.29%, Nasdaq -0.19%. Mild risk-off, but not panic. Watch US payrolls data if released Friday evening IST.
  • Asian surge: Nikkei +1.26%, Hang Seng +1.74%. Positive momentum, but unclear if sustainable.
  • GIFT Nifty: 23,897.70 (+0.10%) — signals a flat to marginally positive open Monday.
  • Crude: Brent $94.18 (-1.40%), WTI $89.54 (-1.93%). Lower crude is bullish for India, but watch for any geopolitical flare-ups over the weekend.
  • Gold: $4,480.70 (-0.24%). Mild dip; safe-haven demand muted.
  • USD/INR: 94.47 (-0.01%). Rupee strength continues; exporters under margin pressure.

Key Levels to Watch Monday:

  • Nifty 50: Support at 23,850, resistance at 24,050. A breakout above 24,000 would confirm short-term bullishness.
  • Bank Nifty: Support at 57,200, resistance at 57,700. FCNR(B) news may take a few sessions to fully price in.
  • Volatility: If VIX spikes above 11.50, expect intraday choppiness.

Calendar:

  • Monday, September 7: Janmashtami holiday — stock market OPEN (per NSE/BSE 2026 calendar, per headlines). Expect lower volumes, but the market will trade.
  • FII Flows: Watch for updates on how the FCNR(B) inflows translate into equity allocations.

8. The Honest Take

For long-term investors: Today’s flat close is noise, not signal. The FCNR(B) deposit surge is a structural tailwind for banks — lower funding costs, improved liquidity, and potential rate easing. If you own private banks (ICICI, Axis, HDFC Bank), hold. If you don’t, accumulate on dips. The metal sector’s outperformance is cyclical, not structural — take profits in names like Vedanta if you’re up big. Defence, solar, and infrastructure plays (Solar Industries, HAL, Welspun) are riding multi-year capex themes; stay invested but don’t chase parabolic moves. Ignore daily noise. Focus on balance sheets and cash flows.

For active traders: This is a market that rewards patience and punishes greed. Friday’s narrow range and flat Nifty 500 close scream “wait for confirmation.” Raymond’s 14% spike is a momentum trade, not an investment — book profits quickly if you’re in. Solar Industries and Welspun are extended; wait for pullbacks. The metal sector’s +1.07% gain offers swing opportunities, but crude’s volatility makes this risky. Watch Monday’s GIFT Nifty open closely — if we gap down below 23,850, the four-day losing streak (per headlines) could extend. If we hold above 24,000, the bulls might finally wake up. Stay nimble. Set stop-losses. And remember: expiry-day chaos (like today’s CAS auction meltdown) is a feature, not a bug.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett
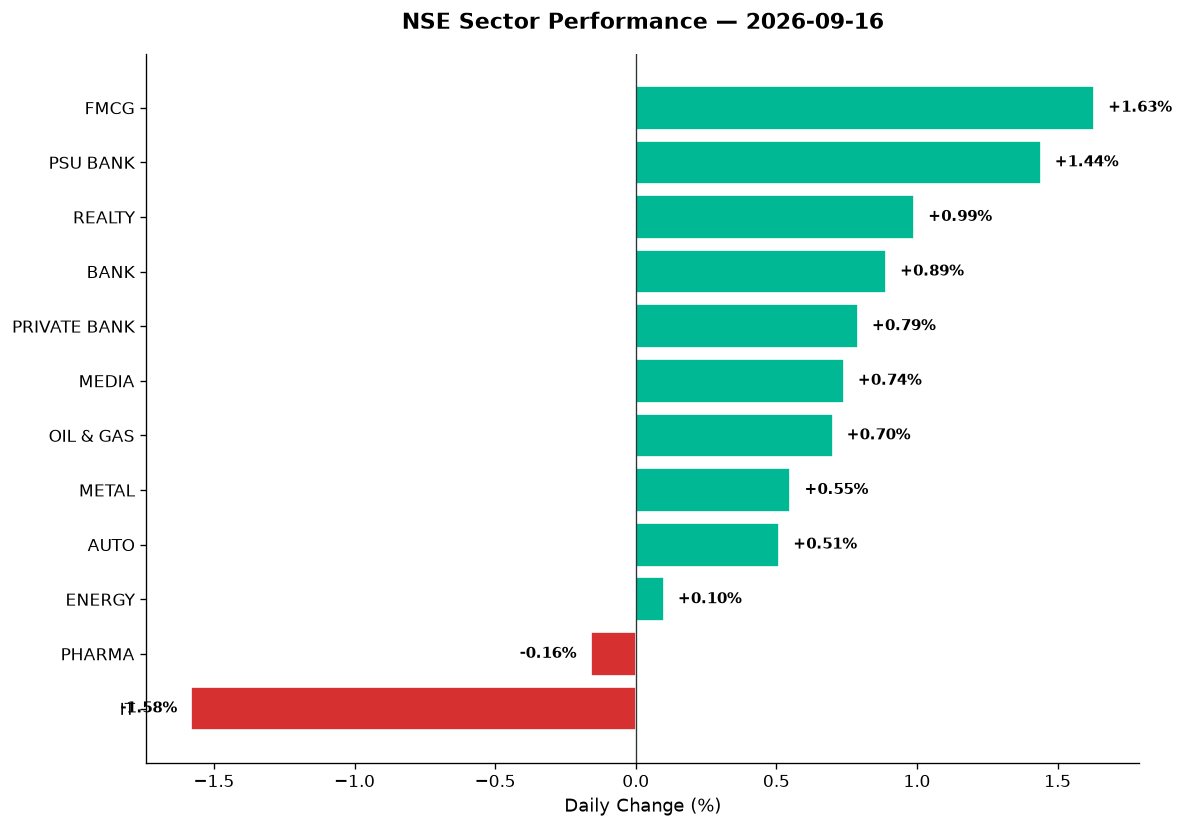
9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Scroll to Top