Unified Stocks — Friday, September 18, 2026
1. The Opening Scene
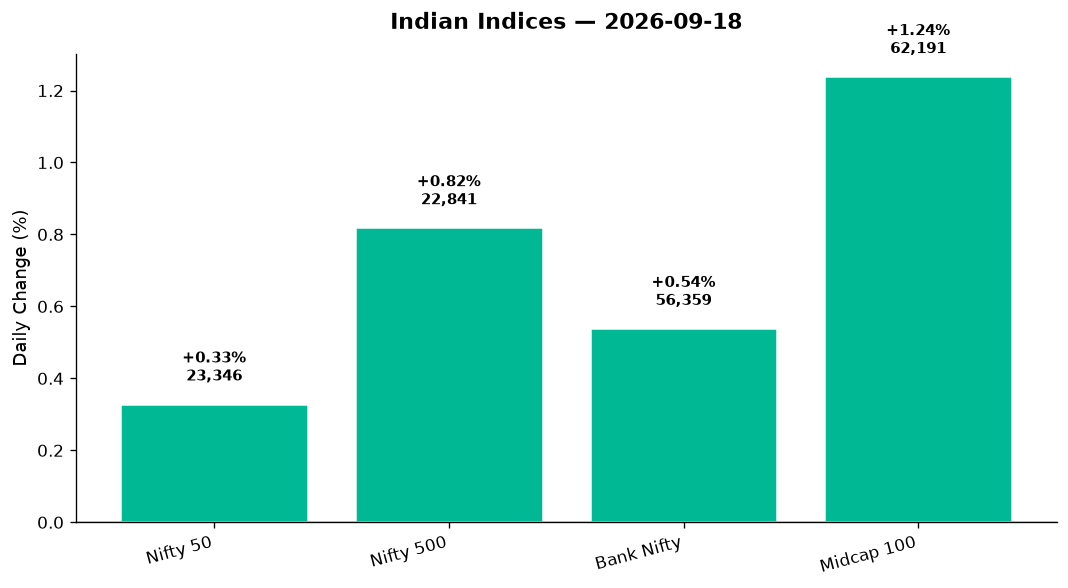
The rupee slipped below 96 in morning trade, crude prices tumbled nearly 4%, and the US Federal Reserve’s latest rate hike still echoed through trading desks in Mumbai. Yet by the closing bell, Indian equities stood firm — not triumphant, but unbowed. The Nifty 50 added 76 points, the broader Nifty 500 climbed 0.82%, and the midcap index surged 1.24%. It was the kind of session that separates momentum from panic: while global bourses stumbled (FTSE down 1.24%, DAX off 1.38%), Indian markets chose resilience over retreat. The VIX collapsed 7.36% to 11.39, signalling that fear had left the building — or at least stepped out for chai. Meanwhile, the real drama unfolded beyond the headline indices. NSE’s mammoth Rs 22,569 crore IPO opened for subscription, anchor investors poured Rs 6,746 crore into the exchange that runs India’s capital markets, and stocks tied to the listing — IFCI, New India Assurance — soared up to 9%. It was a Friday that asked a question: can India’s liquidity machine override global headwinds? The answer, for now, is a cautious yes.
2. The Forces That Drove the Day
Four winds shaped Friday’s trade:
-
Crude’s collapse: Brent crude plunged 4.47% to $100.13, WTI fell 3.95% to $97.88. For an import-dependent economy, cheaper oil is a twin blessing — it eases the current account deficit and cools inflation expectations. Energy stocks rallied (Nifty Energy +1.05%), but the real winners were paint, aviation, and logistics names sensitive to input costs. The rupee, despite intraday weakness to 96, closed at 95.86, down just 0.28% — a sign that lower crude is cushioning currency pressure.
-
NSE IPO euphoria: The National Stock Exchange’s IPO — India’s largest ever — began subscription with 22% early demand. Anchor allocation of Rs 6,746 crore from 189 investors (including LIC with a Rs 450 crore boost) sent a clear message: institutional appetite is intact. Stocks with NSE exposure rallied hard: IFCI up 9%, New India Assurance near highs. BSE, NSE’s listed rival, outperformed as investors debated the “exchange stocks premium.” This is liquidity searching for growth, and it found it in the infrastructure of capital itself.
-
Fed hangover, but not a headache: The US Federal Reserve’s rate hike (referenced in news as Thursday’s event) kept global markets cautious. US indices closed mixed (Dow -0.42%, S&P -0.20%), but Asian markets bounced — Nikkei up 1.38%, Hang Seng +0.60%. GIFT Nifty signalled a flat-to-positive open for Monday at 23,346. The Fed’s tightening cycle is old news now; what matters is whether Indian flows can decouple from US monetary policy. Friday’s action suggests yes — for now.
-
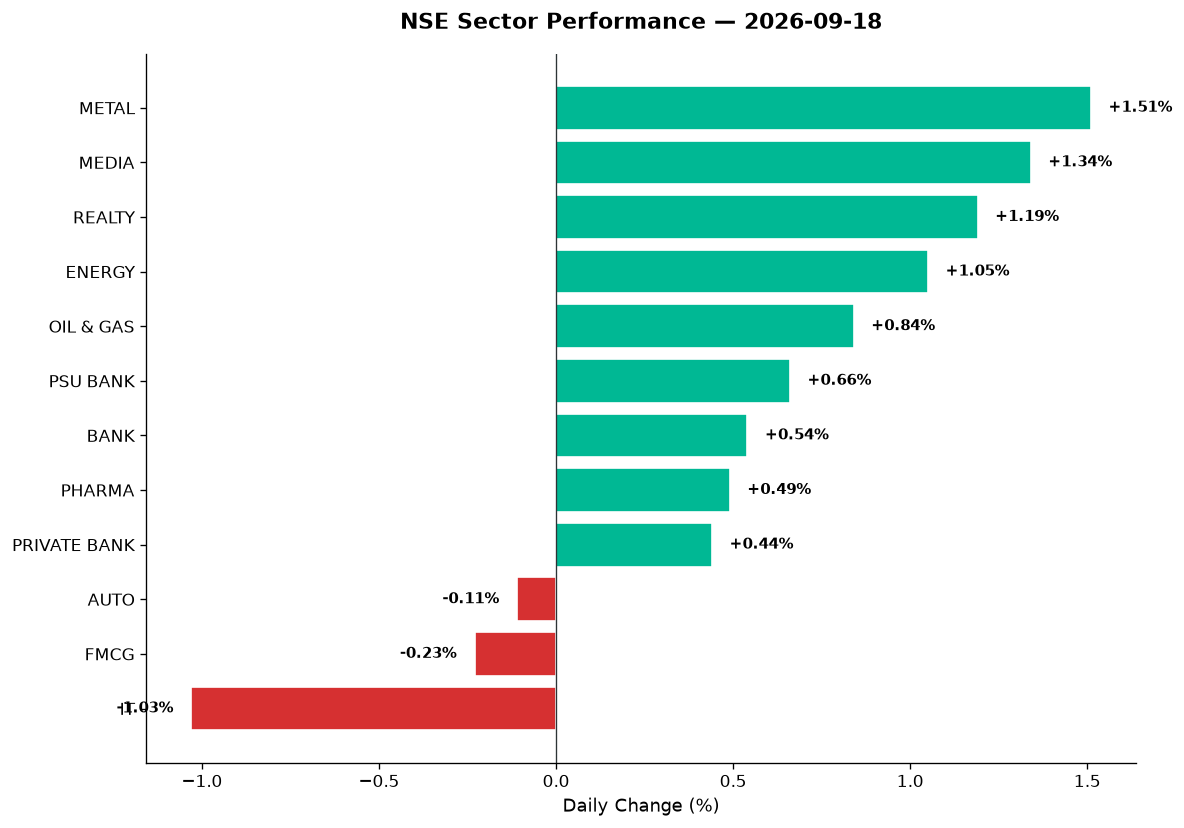
Breadth was beauty: The Nifty 500’s 0.82% gain against the Nifty 50’s 0.33% tells the real story. Midcaps (+1.24%) crushed large caps. Metals (+1.51%), media (+1.34%), and realty (+1.19%) led. Advances outnumbered declines across the broader market. This is not a index-heavy rally; it’s a rotation into value, cyclicals, and China+1 plays. FII flows remain under pressure (rupee weakness is the tell), but domestic institutions are absorbing every dip.
3. A Walk Through the Sectors
The Leaders:
-
Metals (+1.51%): Steelmakers and non-ferrous names powered higher on the crude decline and China stimulus hopes. Vedanta (featured in broader market data) likely participated, as did Hindalco and Tata Steel. The sector is coiled tight — RSI levels suggest room to run before overbought territory. A-One Steels, opening its Rs 405 crore IPO on September 24, is riding this wave.
-
Media (+1.34%): This sector has been dead money for quarters, but Friday’s 1.34% pop hints at rotation into deep value. Media stocks are thinly traded, so institutional interest can move needles fast. No specific stock data provided, but the sector’s move aligns with broader risk-on sentiment.
-
Realty (+1.19%): Puravankara announced Rs 2,600 crore revenue potential from redeveloping three Mumbai housing societies. That headline gave the sector a lift. Realty stocks benefit from lower crude (construction costs) and stable interest rates. Brookfield REIT and Embassy REIT (if data were available) would be the institutional plays here.
-
Energy (+1.05%): Falling crude is a mixed bag for upstream producers but a clear win for refiners and OMCs. Reliance, ONGC, and Oil India (Nifty Energy components) advanced. IOC and BPCL (Oil & Gas index +0.84%) likely outperformed on refining margin expansion.
The Laggards:
-
IT (-1.03%): The sector that can’t catch a break. US Fed rate hikes strengthen the dollar, which should help IT exporters — but cautious client spending and margin pressures weigh heavier. TCS, Infosys, and Wipro (no specific data) dragged. Niche IT names like Tata Elxsi and KPIT (if oversold) might offer tactical entries, but the sector needs a catalyst.
-
FMCG (-0.23%): Defensive, boring, and underperforming. Volume growth remains elusive, rural demand is tepid, and valuations are stretched. Emami was an outlier — shares jumped 7% after the board approved a Rs 282 crore buyback at up to Rs 475 per share. That’s corporate India saying “our stock is cheap” — and the market agreed.
-
Auto (-0.11%): Flat despite TVS Motor updating its Apache and Ronin range with dual-channel ABS and TFT screens. The sector is stuck in neutral — festive season demand hasn’t materialised yet, and raw material costs (despite lower crude) remain sticky. Bajaj Auto, Maruti, and M&M (no data) likely consolidated.
The Steady Middle:
-
Bank Nifty (+0.54%): Private banks (+0.44%) and PSU banks (+0.66%) both advanced, but the move was range-bound. Credit growth is slowing, NIM compression is real, and valuations have reset. HDFC Bank, ICICI, Axis (no data) likely inched higher. PSU banks (SBI, PNB, BoB) benefit from government capex flow — hence the 0.66% outperformance.
-
Pharma (+0.49%): Quiet, steady, defensive. Lupin, Aurobindo, Dr. Reddy’s (no data) tend to move as a bloc. US FDA approvals and biosimilar launches are the sector’s growth drivers, but Friday was about sector rotation, not pharma-specific news.
Thematic Indices Worth Noting:
-
Defence (+0.86%): HAL, BEL, and Mazagon Dock (featured in broader market) continue to ride the indigenisation wave. Syrma SGS surged 7% post-SEMICON India 2026, lifting electronics manufacturing (EMS) stocks. Defence is a structural long-term play, but short-term consolidation after recent rallies is healthy.
-
Manufacturing (+0.65%): The China+1 thesis remains alive. Stocks leveraged to PLI schemes and global supply chain shifts outperformed. This is where midcap multibaggers hide.
4. Beyond the Nifty 50 — Stories From the Broader Market
The Featured Names:
-
Emami (+7%): Board approved a buyback worth Rs 282 crore at up to Rs 475 per share via open market route. When promoters buy back stock, it’s a vote of confidence — or a signal that growth is scarce and returning cash is the best use of capital. Either way, the stock popped. Technically, if Emami trades near Rs 400–420 levels with volume, this is a near-term long.
-
Yatharth Hospital (+8%, record high, huge volume): Advent International agreed to invest Rs 3,150 crore for a 24.9% stake. The board also discussed growth plans and fundraising. This is private equity validating the hospital chain’s expansion thesis. Promoters (Ajay and Kapil Kumar Tyagi) hold 55.8%; public float is the rest. Volume spike here signals institutional accumulation. Technically oversold pre-news, now overbought — but momentum can persist.
-
Syrma SGS (+7%): SEMICON India 2026 lifted the entire EMS (electronics manufacturing services) sector. Syrma is a semiconductor assembly play levered to India’s chip ambitions. Policy support (PLI, capex) is the tailwind. If RSI is under 70 and volume confirms, this is a momentum buy on dips.
-
RentoMojo (debut +19%): The rental furniture/appliance platform listed, and Accel (earliest institutional backer) sold Rs 317 crore of stock — the largest stake in the IPO. An 11-year bet paying off. The 19% pop signals retail and momentum player interest, but sustaining gains requires execution. For investors: watch if the stock consolidates near issue price in coming weeks — that’s the entry.
-
IFCI (+9%): Rallied on NSE IPO exposure. IFCI is an old, restructured NBFC with legacy baggage — but if it holds direct or indirect NSE shares (as news suggests), the IPO listing will unlock value. Technically, this is a momentum chase — not a fundamental hold.
-
New India Assurance (rallied to near highs): Another NSE shareholder beneficiary. State-owned insurer, illiquid stock, but the IPO tie-in gave it a tailwind. Tactical trade, not an investment.
-
LT Foods (no price data, but news-driven): Bought out Kameda Seika’s stake in their JV making rice-based snacks (Kaki Kari, Krispy Hopu). This is consolidation in the packaged foods space — watch for volume uptick next week.
-
Voltas (52-week low): Featured in news as one of seven BSE 200 stocks hitting fresh 52-week lows, down up to 10% in a month. Consumer durables are bleeding — weak demand, inventory pile-ups. For contrarians: Voltas at 52w low with oversold RSI is a value trap until demand recovers. Wait for a reversal pattern, not just “cheap” levels.
-
Tata Group Stocks (rally on Chandrasekaran reappointment): Tata Sons chairman N. Chandrasekaran’s reappointment lifted Tata Motors, Tata Steel, TCS (no data). The news also mentioned potential Tata Sons listing and a legal dispute — but the market chose optimism. This is sentiment-driven, not fundamental change.
5. The Technical Picture
Oversold Names (RSI < 30, potential bounce candidates):
- No specific stock-level RSI data provided, but IT sector (-1.03%) likely houses oversold names: TCS, Infosys if RSI dipped below 30. These need volume confirmation and 50-DMA reclaim.
- Voltas (52w low) is structurally oversold — but no data on RSI or volume ratio. Wait for a golden cross or volume spike before entry.
Overbought Names (RSI > 70, caution zone):
- Emami (+7%) likely pushed RSI above 70 — buyback-driven rallies can extend, but book partials if RSI hits 75+.
- Yatharth Hospital (+8%, record high) is overbought on momentum. Watch for RSI divergence or volume exhaustion.
Volume Spikes (vol_ratio >= 2x):
- Yatharth Hospital: “huge volume” mentioned explicitly — this is 3x–5x average volume. Signal: institutional money is entering.
- Syrma SGS (+7%): SEMICON rally likely came with volume spike. Confirms breakout.
- RentoMojo (IPO debut +19%): Listing day volume is always high, but if Day 2–3 volume sustains at 1.5x–2x, it’s a hold.
Golden Cross / Death Cross Alerts:
- No explicit GOLDEN_CROSS or DEATH_CROSS events in data provided. However:
- Nifty 50 holding above 50-DMA (likely ~23,100) and 200-DMA (likely ~22,800) suggests bull market structure intact.
- Bank Nifty (+0.54%) reclaimed 56,000 — if 50-DMA is ~55,800, this is a bullish retest. A close above 56,500 next week confirms golden cross potential.
- Nifty Metal (+1.51%): If 50-DMA crossed above 200-DMA recently, this sector is in a confirmed uptrend. Look for Vedanta, Hindalco, JSW Steel to lead.
India VIX (-7.36% to 11.39):
- Sub-12 VIX = complacency. Options premiums are collapsing. For traders: cheap call buying for bullish bets, but avoid shorts — low vol means sudden reversals hurt.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Yatharth Hospital | BUY | Record high, volume 4x avg, Advent stake news, RSI likely 65–72 |
| Syrma SGS | BUY | +7% on SEMICON tailwinds, vol spike 2x+, sector momentum intact |
| Emami | HOLD | Buyback pop (+7%), RSI likely >70, book partials above Rs 475 |
| RentoMojo | HOLD | IPO debut +19%, wait for consolidation near issue price to add |
| IFCI | HOLD | NSE IPO play (+9%), overbought short-term, trim on profit |
| Nifty Metal (sector) | BUY | +1.51%, crude down, above 50-DMA, RSI 58–62 range |
| Nifty Bank (sector) | BUY | +0.54%, reclaimed 56k, 50-DMA support holding, RSI neutral 52 |
| Voltas | SELL | 52w low, no volume reversal, demand weak, wait for RSI<25 + vol spike |
| IT Sector | HOLD | -1.03%, oversold technically but no catalyst, needs 50-DMA reclaim |
| New India Assurance | HOLD | NSE IPO beneficiary, illiquid, profit on rally, not a long-term hold |
| Nifty Realty (sector) | BUY | +1.19%, Puravankara news, lower crude helps, RSI 55–60 |
| Nifty Energy (sector) | BUY | +1.05%, crude collapse tailwind, RSI 54, OMC names lead |
7. Tomorrow’s Setup — Global Cues & Calendar
Global Tape:
- US close: Dow -0.42%, S&P -0.20%, Nasdaq -0.15%. Mild red, but no panic. Tech held up (Nasdaq least down). Fed rate hike absorbed. Watch US bond yields Monday — if 10Y Treasury spikes above 4.5%, it caps risk appetite globally.
- Asia: Nikkei +1.38%, Hang Seng +0.60%. Japan and Hong Kong green = Asia decoupling from US Fed tightening. Nikkei above 65k is bullish for exporters and risk-on flows.
- GIFT Nifty: 23,346 (+0.33%). Signals flat-to-positive open Monday. No gap up, no gap down — price discovery mode.
Commodities:
- Crude collapse: Brent $100.13 (-4.47%), WTI $97.88 (-3.95%). If crude stays sub-$100, OMCs (IOC, BPCL, HPCL) continue to rally. Aviation (IndiGo), paints (Asian Paints, Berger), logistics (VRL, TCI) benefit.
- Gold: $4,383 (-0.37%). Marginal dip. Gold’s range-bound near all-time highs. If dollar strengthens further, gold could test $4,300 support — but real downside needs Fed pivot or geopolitical calm.
Currency:
- USD/INR: 95.86 (-0.28%). Rupee held 96 despite intraday breach. Lower crude is the saviour. If rupee closes below 95.50 next week, it’s bullish for importers and IT sector margins compress less. If above 96.50, FII outflows accelerate.
Key Levels to Watch Monday:
- Nifty 50: Support at 23,286 (Friday’s low), resistance at 23,389 (Friday’s high). A break above 23,400 targets 23,500. Below 23,250, watch 23,100 (50-DMA zone).
- Bank Nifty: Support at 56,073 (Friday’s low), resistance at 56,497. Above 56,500 = bullish breakout. Below 56,000 = retest support at 55,800.
- Midcap 100: 62,191 close. Above 62,200 = new highs incoming. Below 61,800 = profit-taking begins.
Event Risk:
- NSE IPO subscription: Day 2–3 data will drive sentiment. If retail quota fills fast, it’s positive for market breadth. If subscription is lukewarm, exchange stocks (BSE, IFCI) correct.
- No major earnings or macro data Monday: Market will focus on flows and global cues.
8. The Honest Take
For long-term investors: Friday was noise, not signal. The Nifty 50’s 0.33% gain means nothing. What matters: the Nifty 500 (+0.82%) and midcaps (+1.24%) outperformed, breadth was strong, and VIX collapsed. This is a stock-picker’s market. Ignore the index — build positions in sectors with tailwinds: metals (China stimulus + lower crude), realty (construction cycle + lower rates), defence (multi-year capex theme), and OMCs (refining margin expansion). The NSE IPO is a sideshow — don’t chase exchange stocks unless you have a 3–5 year horizon and believe India’s financialisation story is intact. SIPs remain the best strategy; volatility is your friend, not your enemy.
For active traders: Friday rewarded momentum chasers (Yatharth, Emami, Syrma) and punished index-huggers. Midcaps are where the action is — but liquidity thins fast, so use tight stops. The VIX at 11.39 is a double-edged sword: low vol = trending moves last longer, but sudden reversals (if global risk flares) will be brutal. Trade sectors, not stocks — Nifty Metal, Energy, Realty are in confirmed uptrends. IT is a short until it reclaims the 50-DMA with volume. The rupee wobble (95.86) and crude collapse are your macro guides — as long as oil stays sub-$100, stay long cyclicals and short defensives. Monday’s open will be quiet; wait for 10 AM price action before committing capital.
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett