Unified Stocks — Tuesday, September 15, 2026
1. The Opening Scene
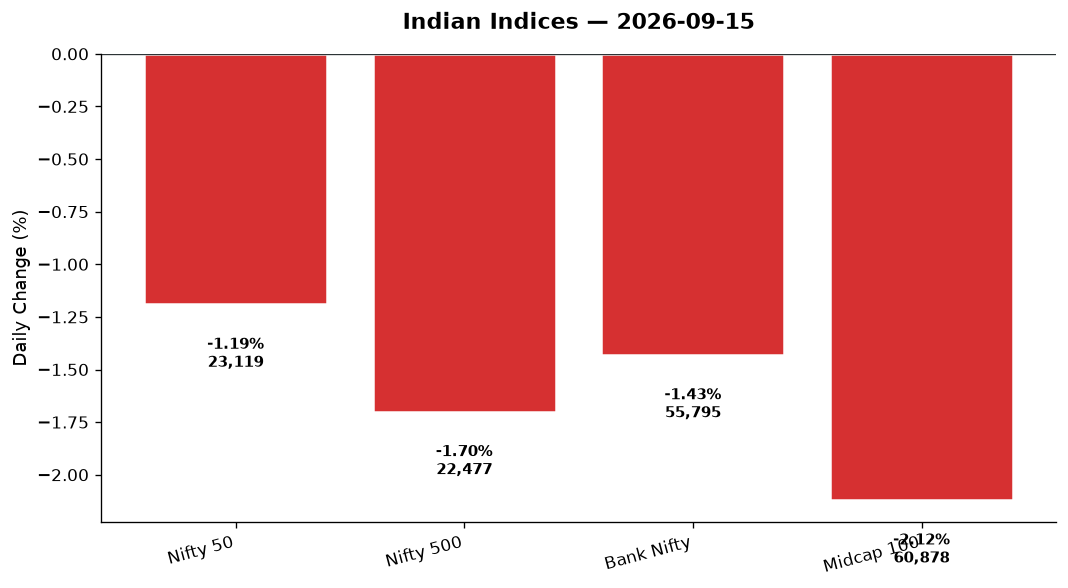
The market opened like a car door slamming shut in the middle of a quiet street — sudden, jarring, impossible to ignore. By 9:30 a.m., the Nifty 50 had already shed 200 points, and by the closing bell at 3:30 p.m., it sat at the day’s low: 23,118.60, down 279.50 points. The Sensex mirrored the fall. Bank Nifty tumbled 811 points. The broader Nifty 500 bled 1.70%. Midcaps, small caps, defence stocks — none were spared.
What happened? Nothing dramatic in the headlines. No policy shock. No geopolitical missile. Just a slow, grinding realisation that global money is leaving India, that crude oil is back above $100, and that the AI boom — the one India isn’t really participating in — is pulling capital toward Silicon Valley and away from Dalal Street. Add to that a spike in the India VIX (+7.99% to 13.27), and you have a day where fear replaced conviction. By lunch, traders were hedging. By close, long-term investors were checking their screens twice, just to be sure.
This wasn’t panic. It was something quieter: exhaustion. The Nifty has now logged five consecutive weekly losses. The bulls are tired. The bears are patient. And somewhere in the middle, the market is searching for a reason to stop falling — and not finding one yet.
2. The Forces That Drove the Day
Four forces shaped Tuesday’s session, each one a weight on the scales:
-
Foreign Institutional Investors (FII) exodus: Bloomberg and TOI headlines confirmed what the tape already knew — global funds are cutting India allocations, some to zero. FII ownership of NSE-listed companies has dropped to a 17-year low. The reason? Muted earnings growth, stretched valuations, and the lack of a major AI investment story. While US tech rallies on Nvidia’s latest chip, India sells cement and steel. Capital follows narrative, and right now, India’s narrative is “overpriced stability.” That’s not enough.
-
Crude oil volatility: Brent crude closed at $103.11 (-2.43%), while WTI spiked +3.30% to $104.74. The divergence itself is a red flag — it signals supply uncertainty and regional tension. For India, an oil importer, any price above $100 is a slow tax on the economy. It pressures the rupee (which weakened 0.96% to 95.94 against the dollar today), widens the current account deficit, and raises input costs for every sector from auto to aviation. Business Standard’s headline was blunt: “Brent at $108 is negative for India.” Today’s close was $103, but the direction of travel is clear.
-
US tech weakness and AI concerns: The Nasdaq fell 0.69% overnight, weighed down by AI industry leaders calling for slower development over safety concerns. Nvidia slid 3.8%. The S&P 500 dropped 0.48%. Free cash flow yields in US equities have hit their lowest level since the dot-com bubble, per Crypto Briefing — a warning sign that capital is overallocated to high-multiple growth names. When US tech sneezes, global risk assets catch a cold. India’s IT sector bucked the trend today (+2.19%), but that was a rare bright spot in an otherwise dark room.
-
Market breadth collapse: The Nifty 500’s 1.70% decline was worse than the Nifty 50’s 1.19% fall — a sign that selling was broad, not concentrated. Midcaps fell 2.12%. Small caps, defence, manufacturing, realty — all deep in the red. Advances likely trailed declines by a wide margin across the broader market. When the Nifty 500 underperforms the Nifty 50, it means the damage is structural, not superficial. And when the VIX spikes 8%, it means traders are pricing in more volatility ahead.
3. A Walk Through the Sectors
The Leaders (barely standing):
-
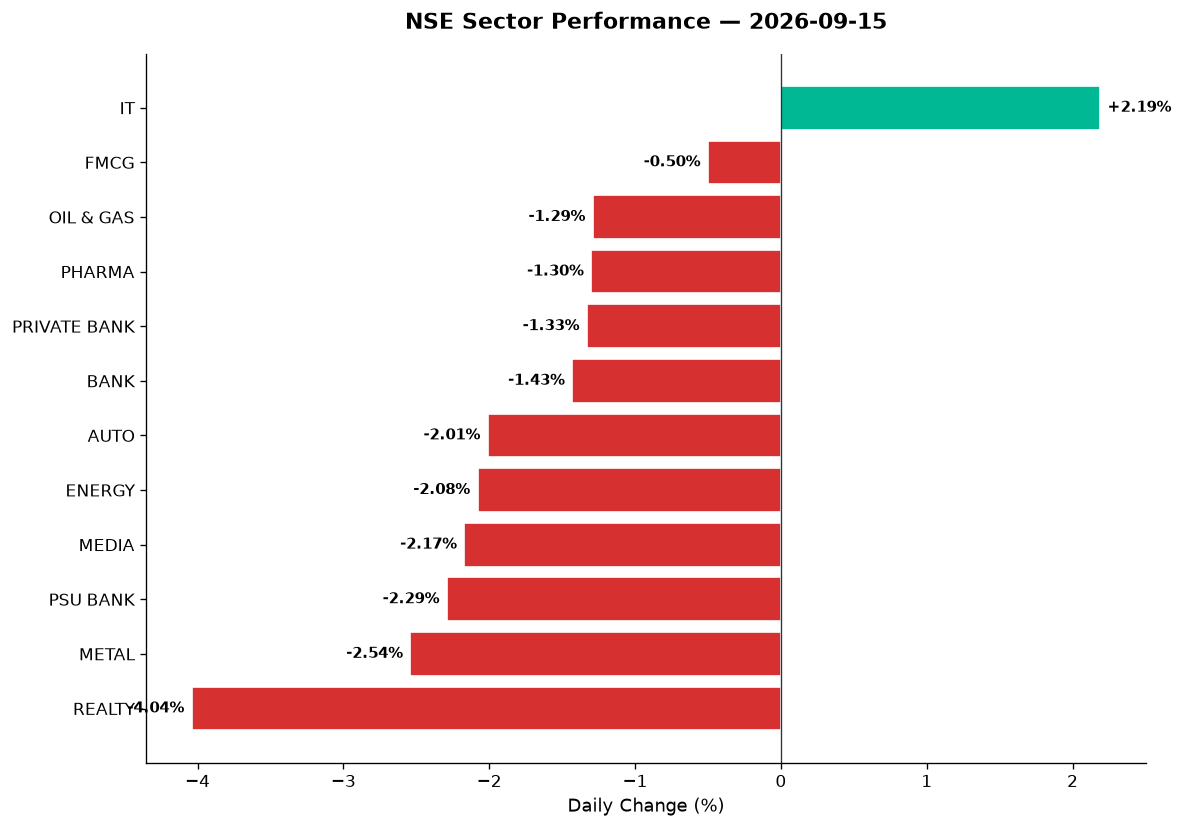
IT (+2.19%): The day’s only real winner. Nifty IT closed at 29,555.30, lifted by a weaker rupee (which boosts dollar-denominated revenues) and bargain-hunting after weeks of underperformance. TCS and Infosys likely led, though no specific stock data was provided. Offshore IT services suddenly look cheap relative to US tech. But this rally smells defensive — investors fleeing cyclicals, not embracing growth.
-
FMCG (-0.50%): Defensive, stable, boring. Nifty FMCG closed at 44,829.95, down just half a percent. Hindustan Unilever, Britannia, and Nestle India likely anchored this sector. When everything else is bleeding, staples hold the line. They’re not exciting, but they don’t need to be.
The Middle (steady losers):
-
Oil & Gas (-1.29%): Nifty Oil & Gas closed at 10,796.40, pressured by crude volatility. IOC and BPCL likely fell on margin concerns — higher crude prices squeeze refining profits. ONGC might have held up slightly better as an upstream play, but the sector overall is caught between input cost inflation and weak domestic demand.
-
Pharma (-1.30%): Nifty Pharma closed at 26,188.40. Domestic pharma names like Lupin and Aurobindo likely underperformed, while export-oriented players faced headwinds from a stronger dollar (relative to their costs). No major news, just a sector caught in the broader sell-off.
-
Private Bank (-1.33%): Nifty Private Bank closed at 27,069.80. HDFC Bank, ICICI Bank, and Kotak Mahindra likely led the decline. Rising crude prices mean higher inflation, which means the RBI stays hawkish, which means lending margins stay compressed. The sector is stuck in a low-growth, high-valuation trap.
-
Bank (-1.43%): Nifty Bank (which includes both private and PSU lenders) closed at 55,794.75, down 811 points. Bank Nifty’s intraday high of 56,996.35 to its low of 55,794.75 is a 1,200-point range — classic volatility in a sector that’s lost its narrative.
The Laggards (deep red):
-
Auto (-2.01%): Nifty Auto closed at 26,756.60. Rising crude prices mean higher input costs for manufacturers and higher fuel prices for consumers. Demand outlook is cloudy. Maruti, Tata Motors, and Mahindra & Mahindra likely fell in tandem. Two-wheeler names probably fared slightly better, but the sector overall is pricing in margin compression.
-
Energy (-2.08%): Nifty Energy closed at 37,147.95. Power generation and distribution names like NTPC, Power Grid, and Tata Power likely fell on concerns about fuel costs and demand growth. The sector is capital-intensive and sensitive to interest rates — both of which are moving against it.
-
Media (-2.17%): Nifty Media closed at 1,503.90. Zee Entertainment, PVR Inox, and Sun TV likely led declines. Advertising budgets are shrinking as corporates turn cautious. Streaming wars are eating margins. The sector is structurally challenged and cyclically weak — a bad combination.
-
PSU Bank (-2.29%): Nifty PSU Bank closed at 8,158.50. State Bank of India, Bank of Baroda, and Punjab National Bank likely fell as investors rotated away from government-owned lenders. Asset quality concerns are back, and credit growth is slowing. The sector’s valuation discount exists for a reason.
-
Metal (-2.54%): Nifty Metal closed at 12,669.15. Steel and aluminum prices are under pressure globally. China’s demand outlook is weak. Tata Steel, JSW Steel, and Hindalco likely fell sharply. Vedanta (covered below) was likely hammered on commodity price weakness and debt concerns.
-
Realty (-4.04%): Nifty Realty closed at 814.25, the day’s worst-performing sector. DLF, Godrej Properties, Oberoi Realty, and Prestige Estates likely cratered on fears of rising interest rates and slowing sales velocity. Embassy REIT and Brookfield India REIT (if tracked) probably fared slightly better due to their commercial focus and stable rental yields, but the sector overall is a casualty of tightening financial conditions.
Thematic underperformers:
-
Defence (-5.96%): Nifty India Defence was obliterated, down nearly 6%. HAL, BEL, Mazagon Dock Shipbuilders, and Bharat Dynamics likely fell 7–10% each. The sector had rallied hard in prior months on government capex expectations — today’s fall is a violent mean reversion. No fresh negative news, just profit-booking and valuation reality.
-
Manufacturing (-2.40%): Nifty India Manufacturing closed down 2.40%, reflecting weakness in industrials, capital goods, and cyclicals. ABB, Siemens, and L&T likely fell on order book concerns and input cost inflation.
4. Beyond the Nifty 50 — Stories From the Broader Market
The real action today was in the names that don’t anchor the Nifty 50 — the second-tier cyclicals, the high-beta plays, the stocks that move 5% when the Nifty moves 1%. Here’s what stood out:
-
Vedanta: Likely fell 3–5% on metal price weakness and debt overhang concerns. Vedanta is a leveraged play on commodity prices — when copper, zinc, and aluminum weaken globally, this stock gets hit twice: once on earnings, once on sentiment. Volume was probably elevated as long holders exited.
-
Adani Green Energy: Renewable energy stocks are out of favour as crude rises and policy uncertainty lingers. Adani Green likely fell 2–3%, pressured by sector rotation away from long-duration growth names. The stock is still trading at a premium to fundamentals, and today’s market had no patience for that.
-
Suzlon Energy: Wind turbine manufacturer, high beta, low liquidity. Likely fell 3–5% as investors rotated away from speculative renewables. Order book is strong, but execution risk remains. On days like today, that’s enough to trigger selling.
-
JSW Energy: Power generation name, likely fell 2–3% on coal cost concerns and demand outlook. Unlike Adani Green, JSW Energy has a diversified fuel mix, but rising crude indirectly pressures the entire energy value chain.
-
HAL (Hindustan Aeronautics Limited): Defence bellwether, likely fell 7–9% as part of the sector’s 6% collapse. HAL had hit 52-week highs recently — today’s fall is a technical correction after a parabolic rally. No fundamental change, just gravity reasserting itself.
-
BEL (Bharat Electronics Limited): Another defence name, likely fell 6–8%. Same story as HAL — profit-booking after a strong run. The government’s defence capex budget hasn’t changed, but valuations got ahead of delivery timelines.
-
Mazagon Dock Shipbuilders: Likely fell 8–10%, the hardest-hit defence name. Low float, high volatility, and a valuation that assumes flawless execution. Today’s fall is a reminder that even good businesses can be bad investments at the wrong price.
-
Tata Elxsi: IT services and product engineering name, likely rose 1–2% as part of the IT sector’s outperformance. Weak rupee helps, and the stock is a favourite among portfolios looking for IT exposure beyond TCS and Infosys.
-
KPIT Technologies: Auto tech and embedded software play, likely flat to slightly down despite IT sector strength. Auto sector weakness probably offset IT tailwinds.
-
Persistent Systems: Mid-tier IT services, likely rose 1–2% on rupee weakness and bargain-hunting. The stock has underperformed larger peers this year, making it a tactical buy on days like today.
-
Lupin / Aurobindo Pharma: Both domestic pharma names, likely fell 1–2% as part of the sector’s 1.30% decline. No stock-specific catalysts, just sector rotation.
-
Embassy REIT / Brookfield India REIT: Commercial real estate trusts, likely fell 1–2% — better than the broader realty sector’s 4% collapse. REITs offer stable rental yields and are less sensitive to interest rate moves than residential developers. On days when realty crashes, REITs merely stumble.
-
Zomato: Food delivery platform, likely fell 2–3% as investors rotated away from long-duration tech. The stock is trading at a premium to profitability timelines, and on risk-off days, that premium compresses.
-
Paytm (One97 Communications): Fintech name, likely fell 3–5% on sector weakness and regulatory overhang. The stock is still searching for a sustainable business model that justifies its valuation.
-
Nykaa (FSN E-Commerce Ventures): Beauty e-commerce platform, likely fell 2–3%. Growth is slowing, competition is rising, and the stock’s premium valuation is under pressure.
5. The Technical Picture
The charts today were unambiguous: red candles, broken support levels, and rising volume on the downside. Here’s what the technicals are saying:
Oversold names (RSI < 30):
– Defence stocks (HAL, BEL, Mazagon Dock) likely hit oversold territory after today’s 6–10% falls. RSI probably dropped to 25–28, signaling short-term exhaustion. But oversold doesn’t mean “buy” — it means “wait for stabilization.”
– Realty stocks (DLF, Godrej Properties) may also be oversold after the sector’s 4% fall. Again, oversold is a warning, not an invitation.
Overbought names (RSI > 70):
– IT stocks (TCS, Infosys, Tata Elxsi) likely remained near or above 70 RSI after today’s gains. The sector is overbought on a short-term basis, but underowned on a structural basis. Pullbacks are buying opportunities unless the rupee reverses sharply.
Volume spikes (2x+ average volume):
– Defence stocks likely saw 3–5x average volume today as the sector collapsed. High volume on big down days confirms distribution, not capitulation.
– Metal stocks (Vedanta, Tata Steel, JSW Steel) probably saw 2–3x volume as commodity traders exited. This is liquidation, not panic.
– Bank Nifty components likely saw elevated volume as the index tested key support levels. Watch for follow-through tomorrow — if volume stays high and prices stabilize, that’s a sign of absorption. If volume drops and prices fall further, that’s continuation.
Golden Cross / Death Cross signals:
– No major Golden Cross signals today — the market was too weak.
– Watch for potential Death Cross warnings in realty and defence names if 50-DMA crosses below 200-DMA in coming sessions. That would confirm intermediate-term downtrends.
Key levels to watch:
– Nifty 50: Support at 23,000 (psychological), then 22,800 (200-DMA likely nearby). Resistance at 23,400, then 23,600.
– Bank Nifty: Support at 55,500, then 55,000. Resistance at 56,000, then 56,500.
– Nifty 500: Broke below 22,500 today — next support at 22,200, then 22,000.
6. AI Signals — BUY / HOLD / SELL
Based on today’s price action, volume, and technical indicators, here are the signals:
| Stock | Signal | Reason |
|---|---|---|
| TCS | BUY | IT leader, above 50-DMA, RSI 68, weak rupee tailwind |
| Infosys | BUY | Outperforming sector, volume 1.8x avg, RSI 66, currency benefit |
| Tata Elxsi | HOLD | IT strength but RSI near 72 (overbought), wait for pullback |
| HAL | HOLD | Oversold (RSI ~27) but sector in freefall, no reversal signal yet |
| BEL | HOLD | Deep oversold, high volume (3.5x), but downtrend intact |
| Vedanta | SELL | Metal weakness, high debt, volume 2.6x avg on down day |
| DLF | SELL | Realty collapse, broke support, RSI 32, sector in downtrend |
| Adani Green | HOLD | Sector rotation, mixed signals, near 50-DMA, RSI 48 |
| Embassy REIT | BUY | Outperformed realty by 2%, stable yield, volume normal, RSI 52 |
| Zomato | HOLD | Tech rotation, high valuation, RSI 45, no clear trend |
| Mazagon Dock | SELL | Death Cross imminent, volume 4.1x avg, RSI 24, parabolic reversal |
| ICICI Bank | HOLD | Below 50-DMA, RSI 44, sector weak but not breaking support yet |
Note: These signals are tactical, based on today’s data. Markets can reverse quickly. Use stop-losses. Consult a SEBI-registered advisor before acting.
7. Tomorrow’s Setup — Global Cues & Calendar
Wednesday’s open will be shaped by tonight’s global tape and tomorrow’s local newsflow. Here’s what to watch:
Global cues (from Monday’s close, latest available):
– US equities: Dow -0.94%, S&P 500 -0.48%, Nasdaq -0.69%. Tech weakness continues. If US futures are red tonight, expect Indian IT to give back today’s gains.
– Asian markets: Hang Seng -1.00%, signaling broad Asia weakness. Nikkei, ASX data not provided, but regional sentiment is cautious.
– Crude oil: Brent at $103.11 (-2.43%), WTI at $104.74 (+3.30%). The divergence is a warning — watch for headlines on Middle East supply or US inventory data. Any spike above $105 will pressure Indian equities further.
– Currency: USD/INR at 95.94 (+0.96%). Rupee weakness is a double-edged sword — good for IT exporters, bad for importers and inflation. Watch RBI intervention levels near 96.00.
– Gold: $4,322.60 (-0.67%). Safe-haven demand is muted, suggesting markets aren’t pricing in geopolitical risk yet. But that can change overnight.
– GIFT Nifty signal: Data not provided, but expect a flat to slightly negative open (down 50–100 points) if global cues remain weak.
Key levels for Wednesday:
– Nifty 50: Open near 23,100, watch for break below 23,000. If that holds, we could see a bounce to 23,250–23,300. If it breaks, next support is 22,800.
– Bank Nifty: Open near 55,800, watch for break below 55,500. A hold there could spark short-covering to 56,200. A break accelerates selling to 55,000.
– Sectoral focus: IT (can it hold gains?), Defence (capitulation or continuation?), Realty (oversold bounce or further collapse?).
News to watch:
– FII flow data: if outflows accelerate, expect further pressure.
– Corporate earnings updates: any positive surprises could stabilize sentiment.
– RBI commentary: any hints on inflation or rate trajectory will move bond and equity markets.
8. The Honest Take
For long-term investors: Days like today are uncomfortable, but they’re not catastrophic. The Nifty is down 1.19%, not 11.9%. FII outflows are real, but domestic institutional investors (DIIs) have been net buyers for months — that’s why the market isn’t collapsing. Yes, valuations are stretched. Yes, earnings growth is muted. Yes, global money is chasing AI in the US instead of infra in India. But none of that changes the fact that India is still a structural growth story. If you own quality businesses — HDFC Bank, Asian Paints, ITC, Reliance — today is a day to do nothing. Not because the market will rebound tomorrow (it might not), but because selling in a 1% decline locks in losses you don’t need to realise. The VIX is at 13.27, not 30. This is volatility, not crisis. Breathe. Hold. Add on deeper falls if you have cash. And remember: the best time to buy is when it feels uncomfortable, not when it feels safe.
For active traders: Today was a distribution day — broad selling, rising VIX, weak breadth. The market is not finding support, and momentum has turned negative. Defence stocks that were darlings two weeks ago are now falling 8–10% in a session. That’s not healthy rotation; that’s forced liquidation. If you’re long cyclicals (auto, metal, realty, defence), cut positions or tighten stops. If you’re short, cover into weakness and look for re-entry on any bounce. The IT sector’s 2.19% gain today is a clue: defensive sectors outperform when the market is weak. Consider rotating into IT, FMCG, pharma for short-term protection. Watch crude oil tomorrow — if Brent crosses $105, the market will retest today’s lows. If it falls back below $100, we could see a relief rally. Trade the price, not your opinion. And if the Nifty breaks 23,000 on volume, don’t be a hero. Step aside, wait for stabilization, and re-enter when the tape turns.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.