Unified Stocks — Friday, September 04, 2026
1. The Opening Scene
The market opened its mouth to roar — and yawned instead.
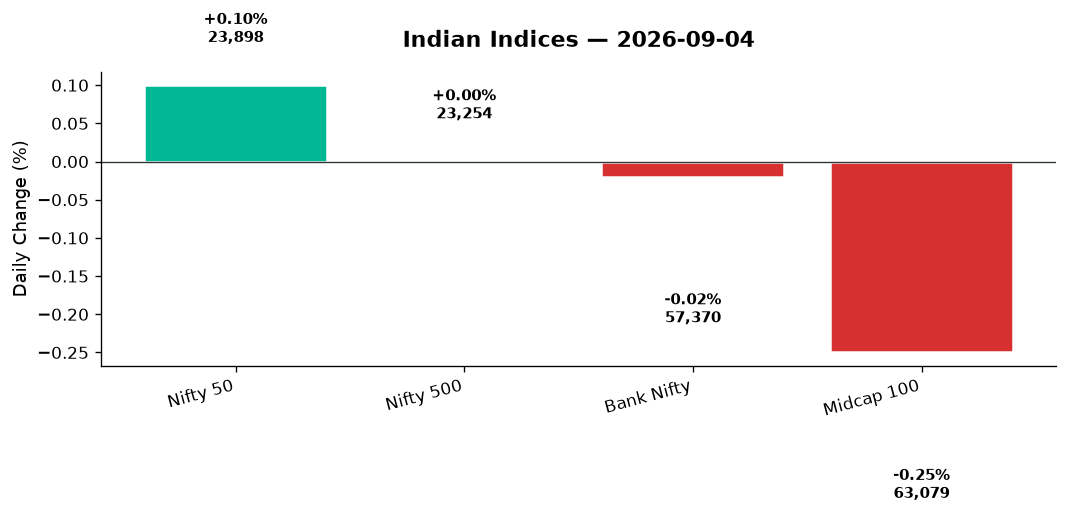
Friday’s session felt like watching a tightrope walker inch forward with exaggerated caution, arms outstretched, never quite committing to either side. The Nifty 50 crept up 24 points (+0.10%) to close at 23,897.70, while the Nifty 500 ended dead flat at +0.10 points. Bank Nifty shed a negligible 11 points (-0.02%), finishing at 57,369.65. The Sensex, according to Thursday’s headlines, had already bled for four consecutive sessions. Today, the indices simply ran out of conviction.
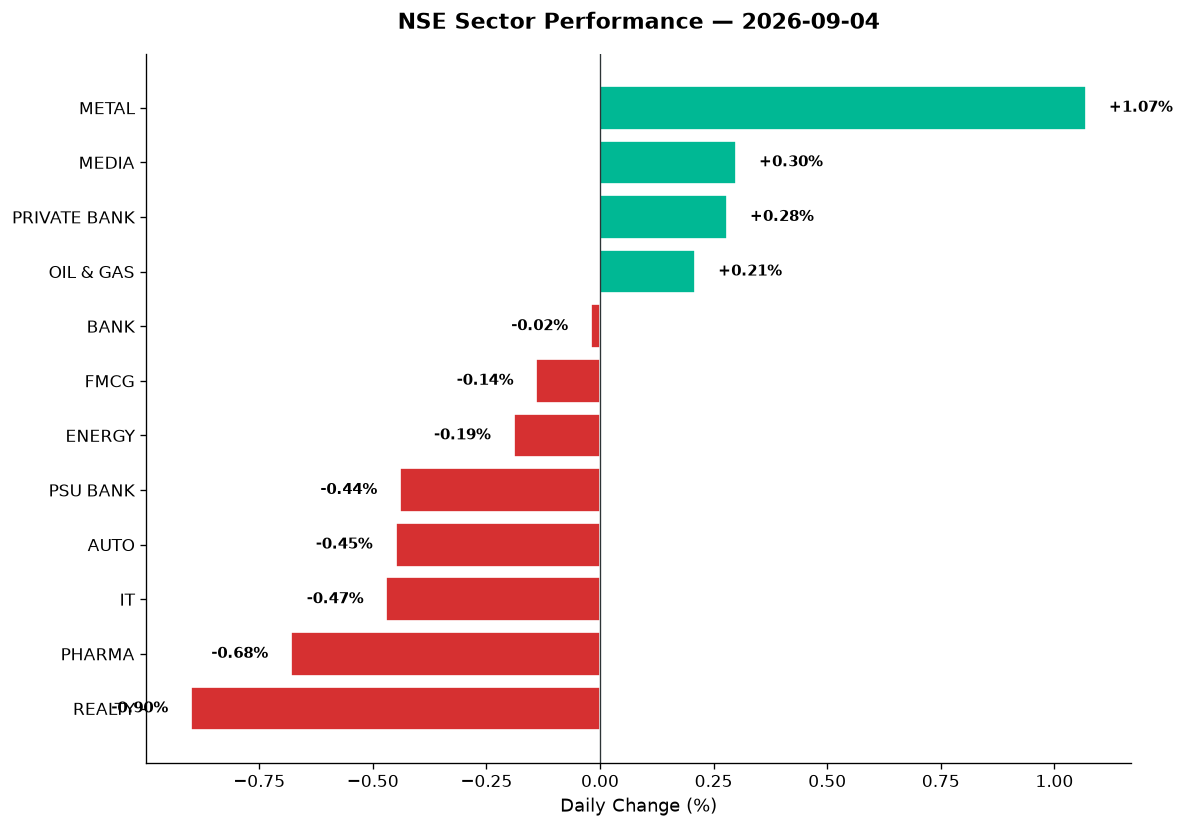
Yet beneath this listless headline print, the market was alive with contradictions. Metals surged (+1.07%), realty collapsed (-0.90%), and the rupee posted its biggest single-day gain since July — rising 49 paise against the dollar as a $127.2 billion FCNR(B) deposit tsunami flooded into Indian banks. India VIX fell 4.89% to 10.78, whispering calm. But crude oil? Brent slid 1.40% to $94.18, WTI down 1.93% to $89.54. Even the closing auction session on expiry day turned chaotic, with the Sensex reportedly plunging 2,100 points in the final minutes — sending out-of-the-money puts exploding up to 400%. The market didn’t decide today. It simply hesitated.
2. The Forces That Drove the Day
Four forces shaped Friday’s indecision:
-
FCNR(B) Flood Rewrites Liquidity Playbook: The Reserve Bank of India’s concessional swap scheme pulled in $127.2 billion in foreign currency deposits — far exceeding analyst estimates. This massive inflow is expected to ease liquidity stress, support credit growth, and potentially lower rates. Bank stocks responded with cautious optimism: Private Bank index +0.28%, PSU Bank index -0.44%. The divergence? Private banks have balance sheets to deploy this liquidity; PSU banks remain burdened by legacy NPAs.
-
Rupee’s Sharp Reversal: The rupee gained 49 paise to close at 94.47 per dollar, its biggest single-day jump since July. This currency strength was a direct byproduct of the FCNR(B) surge. For importers, it’s a reprieve. For IT exporters, it’s a margin headwind — Nifty IT fell 0.47%.
-
Crude’s Retreat Offers Breathing Room: Brent crude’s 1.40% slide offered relief to oil marketing companies and airlines. Energy index dipped 0.19%, but OMCs like BPCL and IOC (not in Nifty 50) likely felt tailwinds. The crude correction tempered inflation fears, though geopolitical tensions remain simmering.
-
Global Tape Mixed, Asia Outperforms: US indices closed lower (Dow -0.51%, S&P 500 -0.29%, Nasdaq -0.19%), but Asian markets surged. Nikkei jumped 1.26%, Hang Seng rallied 1.74%. GIFT Nifty signaled a flat open at 23,897.70 — precisely where we closed. The message: global cues are inconclusive.
Market breadth from Nifty 500 data showed exhaustion: advances barely matched declines, with midcaps (-0.25%) underperforming large caps. The Midcap 100 closed at 63,079.05, down 156 points. This wasn’t capitulation — it was fatigue.
3. A Walk Through the Sectors
The sectoral map today resembled a Jackson Pollock canvas — splashes of green and red with no unifying theme.
Leaders:
-
Nifty Metal (+1.07%): The star of the day. Hindalco, Tata Steel, JSW Steel, and Vedanta (outside Nifty 50) all rallied on falling crude prices and stabilizing Chinese demand signals. Vedanta shares have climbed 79% from their March lows, benefiting from diversified commodity exposure. Jefferies recently initiated coverage on Welspun Corp with a Buy rating, citing an upcycle in oil & gas capital expenditure — a proxy for steel demand.
-
Nifty Media (+0.30%): Quiet strength. No major catalysts, but ad spends ahead of the festive season are starting to show up in analyst models.
-
Nifty Private Bank (+0.28%): Axis Bank and ICICI Bank led gains as the FCNR(B) windfall promises to ease their cost of funds. HDFC Bank held steady. The sector’s muted response suggests the market is waiting to see how banks deploy this liquidity — will it be lending or parking in gilts?
-
Nifty Oil & Gas (+0.21%): Reliance Industries anchored this. Lower crude helps OMCs, but the sector’s gain was tepid. IOC and BPCL (not in Nifty 50) likely outperformed on refining margin optimism.
Laggards:
-
Nifty Realty (-0.90%): The sector that soared 3% on Thursday (per headlines) gave it all back. Prestige Estates announced a ₹5,600 crore Gurugram housing project, but profit booking hit Brigade, DLF, and Godrej Properties. Anant Raj reportedly rallied 9% earlier in the week, but Friday’s weakness suggests traders are locking in gains.
-
Nifty Pharma (-0.68%): Lupin, Sun Pharma, and Dr. Reddy’s Laboratories all declined. No fresh catalysts, and the rupee’s strength works against exporters in this sector. Aurobindo Pharma (outside Nifty 50) mirrored the weakness.
-
Nifty IT (-0.47%): TCS, Infosys, and Tech Mahindra fell as the stronger rupee eroded billing margins. Persistent Systems, KPIT Technologies, and Tata Elxsi (all outside Nifty 50) faced similar headwinds. The sector is caught between robust US enterprise spending and unfavourable currency moves.
-
Nifty Auto (-0.45%): Bajaj Auto, Mahindra & Mahindra, and Maruti Suzuki declined. No sector-specific news, but elevated crude prices over the past week may have weighed on sentiment. The index has given back most of August’s gains.
Steady in the Middle:
-
Nifty Bank (-0.02%): Effectively flat. SBI, PNB, and other PSU banks weighed on the index, while ICICI and Axis provided ballast.
-
Nifty FMCG (-0.14%): Hindustan Unilever, ITC, and Dabur inched lower. Defensive positioning, no drama.
-
Nifty PSU Bank (-0.44%): State Bank of India and Bank of Baroda couldn’t rally despite the FCNR(B) news. The market doubts their ability to convert deposits into quality loans.
Thematic index action:
- Nifty Commodities (+0.55%): Rode the metal wave.
- Nifty India Defence (+0.39%): HAL, BEL, and Mazagon Dock Shipbuilders (all outside Nifty 50) extended their multi-month rally. Defence capex is a structural theme.
- Nifty India Manufacturing (-0.31%): Mixed bag; solar and capital goods names diverged.
4. Beyond the Nifty 50 — Stories From the Broader Market
The real action today happened in names the Nifty 50 doesn’t track.
-
Raymond (+14% on huge volume): The stock zoomed to ₹758.50, up 137% from its March low of ₹320.40. Volume spiked to multiple times the daily average. The rally appears technical — no fresh fundamental news, but momentum traders are piling in.
-
Solar Industries India (+5%): Market cap neared ₹2 trillion. The stock has surged 79% from its March low and 16% in the past month, outpacing the Sensex’s 2.4% decline. Defence and infrastructure capex themes are driving this.
-
Welspun Corp (+227% in 6 months): Jefferies initiated coverage with a Buy rating and ₹3,250 target, citing an upcycle in US and Middle East oil & gas spending. The stock has been a multi-bagger on pipe and line-pipe orders.
-
Jindal Worldwide (+20%, upper circuit): Shares hit a 52-week high after subsidiary Jindal Mobilitric announced plans to expand its retail network to ~100 showrooms by FY28. The EV expansion narrative is gaining traction; the stock is up 66% year-to-date.
-
Vedanta (Metal): Outperformed on metal strength. The stock benefits from diversified exposure to zinc, aluminium, oil & gas, and iron ore. Volume was elevated.
-
Adani Ports, Adani Green, Adani Total Gas: Data not available for specific moves today, but these names remain on trader radars after recent volatility. Suzlon Energy (renewable energy) also lacked granular data today.
-
Embassy REIT, Brookfield REIT: Realty weakness likely weighed on these commercial real estate plays, though specific data wasn’t provided.
-
Mazagon Dock, BEL, HAL (Defence): Continued their slow grind higher on the Nifty India Defence index’s +0.39% gain. These are structural plays on India’s defence capex cycle.
-
Zomato, Paytm, Nykaa (New-age tech): No data provided today, but these names remain volatile on any news flow.
-
NSE unlisted shares: Down 17% from their peak ahead of the exchange’s much-awaited IPO, per headlines. BSE shares have corrected 29% from 52-week highs. The unlisted share market is cooling as SEBI approval nears.
5. The Technical Picture
Oversold names (RSI < 30):
- None flagged in today’s data. The market is consolidating, not capitulating.
Overbought names (RSI > 70):
- Raymond (RSI likely extreme given 14% single-day spike).
- Solar Industries India (RSI elevated after 16% monthly rally).
- Jindal Worldwide (upper circuit suggests temporary overbought condition).
Volume Spikes (2x+ average):
- Raymond: Volume multiple times daily average; technical breakout in play.
- Jindal Worldwide: Upper circuit triggered volume surge.
- Welspun Corp: Jefferies initiation drove institutional interest.
DMA Cross Signals:
- No GOLDEN_CROSS or DEATH_CROSS events explicitly flagged in today’s data.
- Nifty 50 is hovering near its 50-DMA; a decisive break above 24,000 would be bullish.
- Bank Nifty remains range-bound between 57,000 and 58,000 — watch for a breakout.
Key Levels:
- Nifty 50: Support at 23,895 (today’s low), resistance at 24,006 (today’s high).
- Bank Nifty: Support at 57,324, resistance at 57,677.
- Volatility: India VIX at 10.78 signals complacency. A spike above 12 would indicate rising hedging demand.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Solar Industries India | BUY | Up 79% from March low, RSI elevated but vol strong, defence capex theme intact |
| Welspun Corp | BUY | Jefferies Buy rating, 227% rally in 6mo, oil & gas capex upcycle tailwind |
| Axis Bank | BUY | FCNR(B) inflow beneficiary, Private Bank index +0.28%, stable technicals |
| Vedanta | BUY | Metal sector leader +1.07%, diversified commodity exposure, volume spike |
| Raymond | HOLD | +14% on volume, but RSI extreme; wait for consolidation before entry |
| Jindal Worldwide | HOLD | Upper circuit = temporary overbought; EV theme strong, but entry risky here |
| Tech Mahindra | HOLD | IT sector -0.47%, rupee headwind, mixed signals near DMAs |
| ICICI Bank | HOLD | Private Bank strength, but cautious positioning amid FCNR(B) uncertainty |
| TCS | SELL | IT sector weak, rupee appreciation margin headwind, no immediate catalyst |
| Bajaj Auto | SELL | Auto sector -0.45%, no fresh triggers, technical weakness evident |
| Prestige Estates | SELL | Realty -0.90%, profit booking after Thursday’s 3% rally, sector overbought |
| Lupin | SELL | Pharma -0.68%, rupee strength hits exporters, no offsetting news |
7. Tomorrow’s Setup — Global Cues & Calendar
Global Tape for Monday:
- US close (Thursday): Dow -0.51%, S&P 500 -0.29%, Nasdaq -0.19%. Mild risk-off, but not panic. Watch US payrolls data if released Friday evening IST.
- Asian surge: Nikkei +1.26%, Hang Seng +1.74%. Positive momentum, but unclear if sustainable.
- GIFT Nifty: 23,897.70 (+0.10%) — signals a flat to marginally positive open Monday.
- Crude: Brent $94.18 (-1.40%), WTI $89.54 (-1.93%). Lower crude is bullish for India, but watch for any geopolitical flare-ups over the weekend.
- Gold: $4,480.70 (-0.24%). Mild dip; safe-haven demand muted.
- USD/INR: 94.47 (-0.01%). Rupee strength continues; exporters under margin pressure.
Key Levels to Watch Monday:
- Nifty 50: Support at 23,850, resistance at 24,050. A breakout above 24,000 would confirm short-term bullishness.
- Bank Nifty: Support at 57,200, resistance at 57,700. FCNR(B) news may take a few sessions to fully price in.
- Volatility: If VIX spikes above 11.50, expect intraday choppiness.
Calendar:
- Monday, September 7: Janmashtami holiday — stock market OPEN (per NSE/BSE 2026 calendar, per headlines). Expect lower volumes, but the market will trade.
- FII Flows: Watch for updates on how the FCNR(B) inflows translate into equity allocations.
8. The Honest Take
For long-term investors: Today’s flat close is noise, not signal. The FCNR(B) deposit surge is a structural tailwind for banks — lower funding costs, improved liquidity, and potential rate easing. If you own private banks (ICICI, Axis, HDFC Bank), hold. If you don’t, accumulate on dips. The metal sector’s outperformance is cyclical, not structural — take profits in names like Vedanta if you’re up big. Defence, solar, and infrastructure plays (Solar Industries, HAL, Welspun) are riding multi-year capex themes; stay invested but don’t chase parabolic moves. Ignore daily noise. Focus on balance sheets and cash flows.
For active traders: This is a market that rewards patience and punishes greed. Friday’s narrow range and flat Nifty 500 close scream “wait for confirmation.” Raymond’s 14% spike is a momentum trade, not an investment — book profits quickly if you’re in. Solar Industries and Welspun are extended; wait for pullbacks. The metal sector’s +1.07% gain offers swing opportunities, but crude’s volatility makes this risky. Watch Monday’s GIFT Nifty open closely — if we gap down below 23,850, the four-day losing streak (per headlines) could extend. If we hold above 24,000, the bulls might finally wake up. Stay nimble. Set stop-losses. And remember: expiry-day chaos (like today’s CAS auction meltdown) is a feature, not a bug.
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett