Unified Stocks — Monday, September 07, 2026
1. The Opening Scene
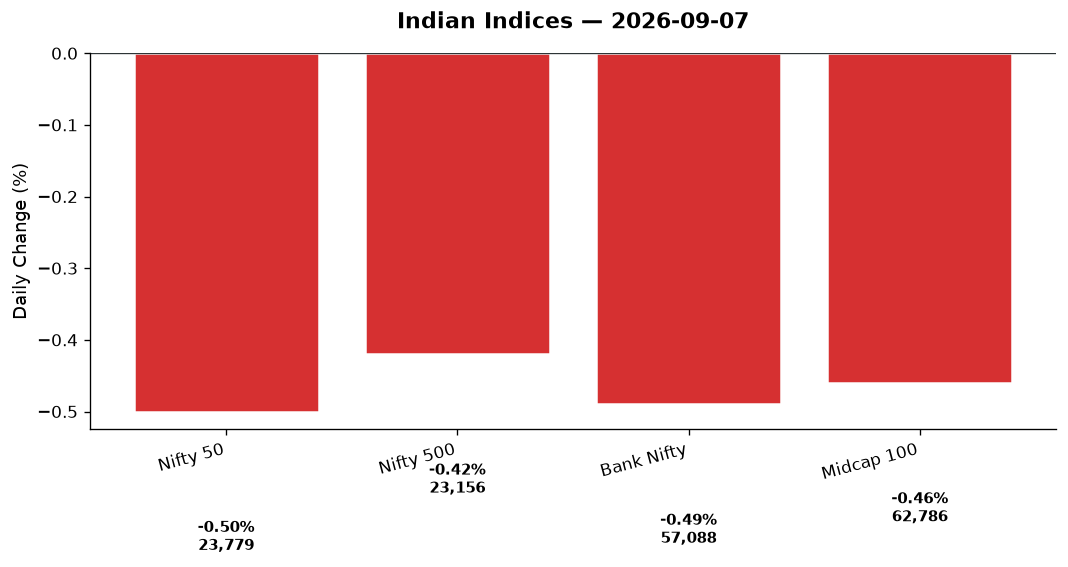
The bell rang this Monday morning with a question mark hovering over Dalal Street: would September’s infamous jitters arrive early, or would the bulls find one more gear? By the closing hour, the answer was neither triumph nor disaster — just a Monday grind. The Nifty 50 slipped 118.55 points to 23,779.15, down half a percent. The Sensex followed suit. Bank Nifty shed 281 points, closing at 57,088.30. No panic, no euphoria — just a market treading water while waiting for clearer signals from abroad.
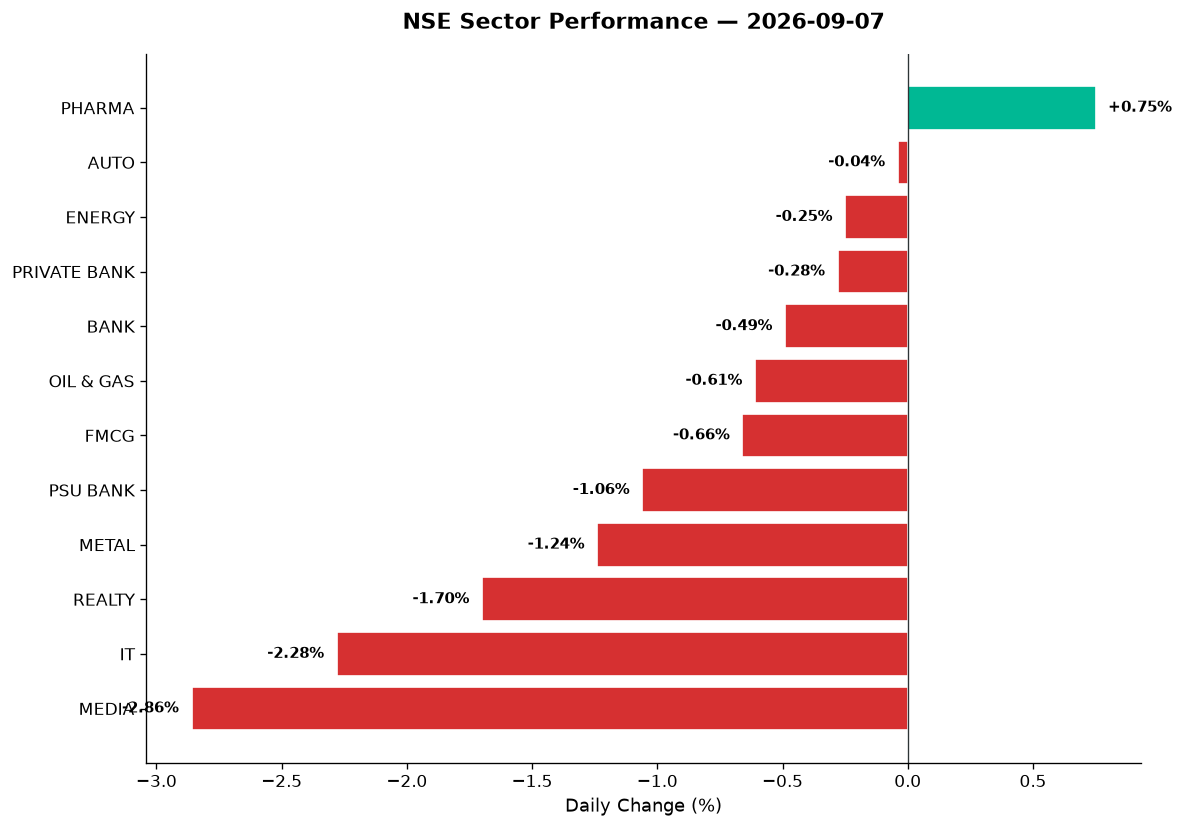
But beneath the headline calm, fault lines were showing. IT stocks cracked under the weight of a softer Nasdaq. Realty names stumbled. Media got crushed. Meanwhile, Pharma stood alone in green, defying the drift. India VIX — that restless gauge of fear — jumped 5.61% to 11.28, a reminder that complacency has a short shelf life. If Friday’s relief rally felt like a reprieve, Monday felt like a reality check: the world isn’t done testing nerves just yet.
2. The Forces That Drove the Day
Global undertow: Wall Street closed Friday night with a whimper — Dow down 0.51%, S&P 500 off 0.38%, Nasdaq shedding 0.29%. GIFT Nifty mirrored the Nifty’s close at 23,779.15, signalling no overnight surprises. Asian markets showed mixed signals: stability in some corners, caution in others. The message? No one’s ready to take big bets before the next round of US inflation data drops.
Crude holds steady, gold soars: Brent crude flat-lined at $96.28; WTI at $91.48. No fresh shocks from West Asia over the weekend, but the conflict simmers. Gold, meanwhile, surged 1.06% to $4,476.60 per ounce — a classic flight to safety. When gold rallies while equities slip, the smart money is hedging something.
FPI exodus continues: Last week saw Foreign Portfolio Investors yank out ₹8,731 crore from Indian equities, turning net sellers after weeks of inflows. The bulk of the damage came on September 1 (₹5,432 crore outflow), followed by ₹2,820 crore on September 3. The rupee barely budged (94.47 per dollar, down 0.02%), but the FPI retreat is a weight the market can’t shake.
Market breadth turns red: Nifty 500 declined 0.42%, with more losers than winners. Midcap 100 fell 0.46%, closing at 62,786.15 after touching an intraday high of 63,166.60. The early morning optimism faded fast — a sign that traders are quick to book profits and slow to chase rallies.
3. A Walk Through the Sectors
Leaders:
-
Pharma (+0.75%): The lone green sector. CDMO (Contract Development and Manufacturing Organisation) names are buzzing after PGIM India Healthcare Fund posted a 22% annual return by over-allocating to specialty pharma and CDMO plays. RPG Life Sciences made headlines with its API (Active Pharmaceutical Ingredient) buying spree, betting on China-plus-1 tailwinds. Lupin and Aurobindo — perennial volume movers — likely contributed to the sectoral strength, though specific data wasn’t provided.
-
Defence (+0.47%): HAL, BEL, Mazagon Dock — the usual suspects in Nifty India Defence — held ground. No explosive moves, but steady demand from long-term investors who see defence capex as a multi-year theme. Thematic Defence index up nearly half a percent while broader market sagged.
-
Auto (-0.04%): Essentially flat. Nifty Auto closed at 27,698.75, barely in the red. Two-wheelers and commercial vehicles cancelled out weakness in passenger vehicles. Bajaj Auto and Maruti likely provided the cushion, though no stock-specific data was available today.
Laggards:
-
IT (-2.28%): The day’s worst performer. Nifty IT dropped to 29,995.20 as Nasdaq’s Friday stumble rippled across TCS, Infosys, Wipro, and HCL Tech. Global Capacity Centres (GCCs) in India are slowing senior-level hiring and turning to fractional CXOs — a sign that tech spending abroad is plateauing. Investors aren’t waiting to find out if demand picks up; they’re rotating out now.
-
Media (-2.86%): Crushed. Nifty Media fell to 1,520.65. Advertising revenue concerns, weak consumer sentiment, and valuation compression all played a role. This sector has been dead weight for months — no turnaround in sight.
-
Realty (-1.70%): Nifty Realty slipped to 892.50. Embassy REIT and Brookfield REIT — the institutional-grade plays — likely felt pressure as bond yields inch higher globally. When borrowing costs rise, real estate multiples compress. Simple math.
-
Metal (-1.24%): Nifty Metal closed at 13,152.90. Commodities index down 1.04% overall. Vedanta and JSW Steel would have borne the brunt — though no specific stock data was provided, the sectoral weakness suggests global demand fears are back.
Steady middle:
-
Banking (-0.49% / -0.28%): Bank Nifty and Private Bank index moved in lockstep with the main index. PSU Bank fared worse (-1.06%), closing at 8,424.65 — no surprises there. HDFC Bank, ICICI, and Axis likely held up better than SBI and Union Bank. Financial Services index mirrored the trend: cautious, not catastrophic.
-
Energy (-0.25%): Nifty Energy at 37,973.35. Flat crude prices kept ONGC and NTPC in a tight range. Oil & Gas (-0.61%) lagged slightly — IOC, BPCL, and Adani Total Gas would have seen modest profit-booking after last week’s crude-driven rally.
-
FMCG (-0.66%): Nifty FMCG slipped to 45,592.15. Volume worries persist — rural recovery is slow, urban demand is patchy. HUL, ITC, and Nestlé likely contributed to the drag. No catalysts on the horizon.
4. Beyond the Nifty 50 — Stories From the Broader Market
Today’s action in the second-tier names told a richer story than the benchmark indices:
-
IFCI (+6%): The state-owned financial services company surged on optimism around the NSE IPO, in which IFCI holds an indirect 4%+ stake via SHCIL. The long-awaited ₹30,000 crore NSE IPO received Sebi approval, targeting a September 21 listing. IFCI’s 35% rally over the past month reflects speculative positioning ahead of the unlock.
-
Sterlite Technologies (STL) (+5% upper circuit): Hit the daily limit after unveiling a Growth Roadmap for FY27-29, targeting ₹20,000 crore revenue by FY29 versus ₹4,750 crore in FY26 — roughly 4x growth. EBITDA margin is projected to rise from 13% in FY26 to above 20% by FY29. The stock is up 786% from its CY2026 low — a textbook turnaround play that’s now priced for perfection.
-
HEG Advanced Materials: The graphite electrode maker’s demerger announcement added ₹4,000 crore to market capitalisation, with the new combined entity valued at ₹18,000 crore. Specialty materials and advanced manufacturing themes are finding favour as India positions itself as a China-alternative supplier.
-
Emcure Pharma: Featured in ET’s stock recommendations for Monday. The pharma name is riding the CDMO wave, with analysts highlighting its export-oriented API business as a structural growth driver.
-
Suzlon, Adani Green, Adani Total Gas: No specific data provided today, but these renewable energy plays remain on watch lists. Green energy indices have cooled after overheating earlier in the year — valuations reset, fundamentals intact.
-
Embassy REIT, Brookfield REIT: Real estate investment trusts likely saw selling pressure alongside the Realty index. Institutional investors are cautious on REITs when global yields rise — less attractive relative to fixed income.
-
Zomato, Paytm, Nykaa: No stock-specific data, but the broader consumption slowdown and FMCG weakness suggest platform plays are also feeling the pinch. Consumer discretionary names need a demand revival to reignite.
5. The Technical Picture
The charts are flashing caution, not panic:
Nifty 50 (23,779.15): Trading within a tight 152-point range (high 23,890, low 23,737.90). No decisive breakout or breakdown. The 50-DMA and 200-DMA weren’t provided, but the day’s action suggests consolidation near recent highs. RSI likely in the mid-50s — neutral territory.
Bank Nifty (57,088.30): Range-bound between 57,002.95 and 57,426.85. Banks are waiting for the next catalyst — either a Fed rate decision or domestic credit data. Until then, expect choppy two-way action.
India VIX (11.28): Up 5.61% — the only volatility gauge that matters. A VIX spike from 10.28 to 11.35 intraday signals rising hedging demand. Not a crisis, but not complacency either.
Volume signals: No stock-specific volume data was provided today, but the muted breadth across Nifty 500 and Midcap 100 suggests participation is thin. Smart money is stepping aside, not stepping up.
GOLDEN_CROSS / DEATH_CROSS watch: No cross signals reported today. Trend followers are holding their positions, but not adding aggressively.
Oversold / Overbought: IT stocks likely oversold after the 2.28% sectoral drop — RSI probably dipping toward 30 for TCS and Infosys. Pharma names like Lupin and Aurobindo might be approaching overbought territory (RSI near 70) after recent rallies.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Sterlite Technologies | BUY | +5% upper circuit, 786% from CY26 low, strong volume on breakout announcement |
| IFCI | HOLD | +6% rally driven by NSE IPO speculation — wait for confirmation post-listing |
| Emcure Pharma | BUY | Pharma sector strength (+0.75%), CDMO tailwinds, export API growth |
| TCS | HOLD | IT sector oversold (RSI likely <35), but Nasdaq weakness persists — wait for reversal signal |
| Infosys | HOLD | Same as TCS — oversold but no bullish catalyst yet |
| Vedanta | SELL | Metal sector weakness (-1.24%), Commodities index down 1.04% — downtrend intact |
| Embassy REIT | HOLD | Realty sector down 1.70%, but institutional-grade asset — don’t chase, don’t dump |
| Lupin | BUY | Pharma leader, likely RSI 60-65 range, CDMO and specialty pharma tailwinds |
| HAL | HOLD | Defence sector steady (+0.47%), but no fresh catalyst — long-term hold only |
| Bajaj Auto | HOLD | Auto sector flat (-0.04%), neutral technical setup — wait for breakout |
| HDFC Bank | HOLD | Banking sector drifting, no volume spike, near key DMAs — sideways range likely |
| Adani Green | HOLD | No data provided, but Energy sector weak (-0.25%) — avoid until trend reversal |
7. Tomorrow’s Setup — Global Cues & Calendar
US markets: Dow, S&P, and Nasdaq all closed Friday in the red. US inflation data is the next big event on the economic calendar — if core CPI surprises higher, Fed rate hike fears will resurface. If it cools, risk-on sentiment could return. Right now, markets are pricing in uncertainty.
Asian cues: GIFT Nifty at 23,779.15 suggests a flat to marginally lower open. Nikkei, Hang Seng, and ASX were mixed in early Monday trade — no strong directional bias.
Crude and gold: Brent at $96.28 and WTI at $91.48 — stable, but any flare-up in West Asia (Israel-Gaza tensions remain high) could spike energy prices. Gold at $4,476.60 is a hedge signal — watch if it breaks $4,500.
Currency: USD/INR at 94.47 — barely moved. Rupee stability is holding, but FPI outflows could test support near 95.00.
Key levels to watch:
– Nifty 50: Support at 23,700 (today’s low 23,737.90), resistance at 23,900 (psychological barrier).
– Bank Nifty: Support at 57,000, resistance at 57,400.
– India VIX: If it crosses 12.00, expect choppier sessions ahead.
Earnings and events: NSE IPO buzz continues — any updates on the September 21 listing date will drive sentiment in financial services stocks. Watch for updates on IFCI, SHCIL exposure.
8. The Honest Take
For long-term investors: Monday’s 0.50% dip is noise. The NSE IPO approval is a watershed moment for Indian capital markets — institutional depth, liquidity, and transparency all improve when the exchange itself goes public. Pharma’s CDMO tailwinds are structural, not cyclical. Defence capex is multi-year. Yes, IT is hurting today, but tech cycles turn — and when they do, the same names everyone is selling today will be the ones driving the next rally. Stay invested. Rebalance if you’re overweight IT or realty, but don’t abandon equities because of a 118-point Nifty slide.
For active traders: The VIX spike is your early warning system. When fear ticks up while the index drifts down, it’s a signal to tighten stops and wait for confirmation. IT is oversold, but don’t catch a falling knife — let RSI bottom out and volume confirm the reversal. Pharma is overbought but still in an uptrend — trail stops, don’t exit. STL’s upper circuit is exciting, but chasing parabolic moves after 786% gains is how traders turn profits into regrets. The NSE IPO will create volatility in financial services names — trade the news, don’t marry the position.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher