Unified Stocks — Wednesday, September 9, 2026
1. The Opening Scene
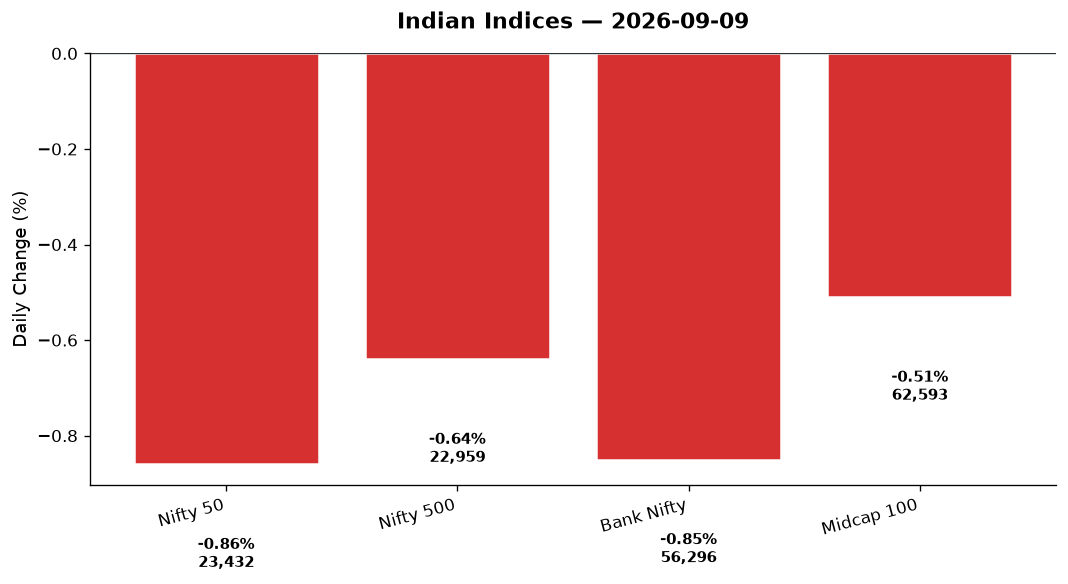
There’s a certain symmetry to how markets betray confidence. One day you’re watching indices grind higher on benign global cues and dovish central bank whispers. The next, a barrel of Brent crude leaps 3.3% in a single session, the rupee stumbles to multi-week lows, and suddenly the Nifty 50 is kissing three-month depths at 23,431. Wednesday wasn’t a crash. It was a recalibration — the kind that strips complacency from portfolios like varnish from old wood. The culprit? Not earnings disappointments or domestic policy fumbles, but the oldest market disruptor in the playbook: geopolitical tension married to energy price shocks. As West Asia simmered and Brent flirted with the psychologically charged $100 mark, India’s equity markets reminded investors that globalisation cuts both ways. You import technology and capital; you also import volatility and risk. By the closing bell, the Nifty had surrendered 203 points, Bank Nifty shed 482, and the VIX — that restless barometer of fear — spiked 6.32% to 11.94. The message was clear: brace for chop.
2. The Forces That Drove the Day
Four crosswinds converged to tilt Wednesday’s session southward:
-
Crude’s violent rally: Brent crude surged 3.29% to $101.14, while WTI jumped 3.32% to $96.12. The driver? Escalating tensions in West Asia, with reports of Iran firing on tankers and US warships, and Ansar Allah targeting Saudi oil facilities. For India — a net importer of 85% of its crude needs — every dollar above $90 is a twin headwind: it widens the current account deficit and fans inflationary embers. Traders didn’t wait for confirmation; they sold oil-dependent sectors (transport, aviation) and bid up metals as a hedge.
-
Rupee under siege: The Indian rupee weakened 0.64% to 95.1 against the dollar, its sharpest single-day decline in over a month. Rising crude absorbs foreign exchange reserves; higher USD/INR makes imports costlier and corporate dollar debt servicing heavier. The currency’s slippage compounded equity market stress, particularly for IT exporters who theoretically benefit from a weaker rupee — yet sold off anyway.
-
Global risk-off tone: Wall Street offered no shelter. The Dow fell 0.47%, S&P 500 slipped 0.29%, and Nasdaq dropped 0.45%. Europe was worse: FTSE down 1.31%, DAX off 1.73%. Asian markets (Nikkei -0.19%, Hang Seng -0.17%) traded cautiously. GIFT Nifty futures mirrored the spot index at 23,431, signaling no overnight relief. Gold climbed 1.58% to $4,463, a classic flight-to-safety signal.
-
Breadth turned defensive: Across the Nifty 500 universe, declines outnumbered advances sharply. While the Nifty 500 lost 0.64%, midcap indices fared marginally better (Midcap 100 -0.51%), suggesting large-cap defensiveness. Yet within the top tier, heavyweight IT and financials dragged hardest. The session was less a rout than a rotation — sellers abandoned growth and crowded into commodity plays.
3. A Walk Through the Sectors
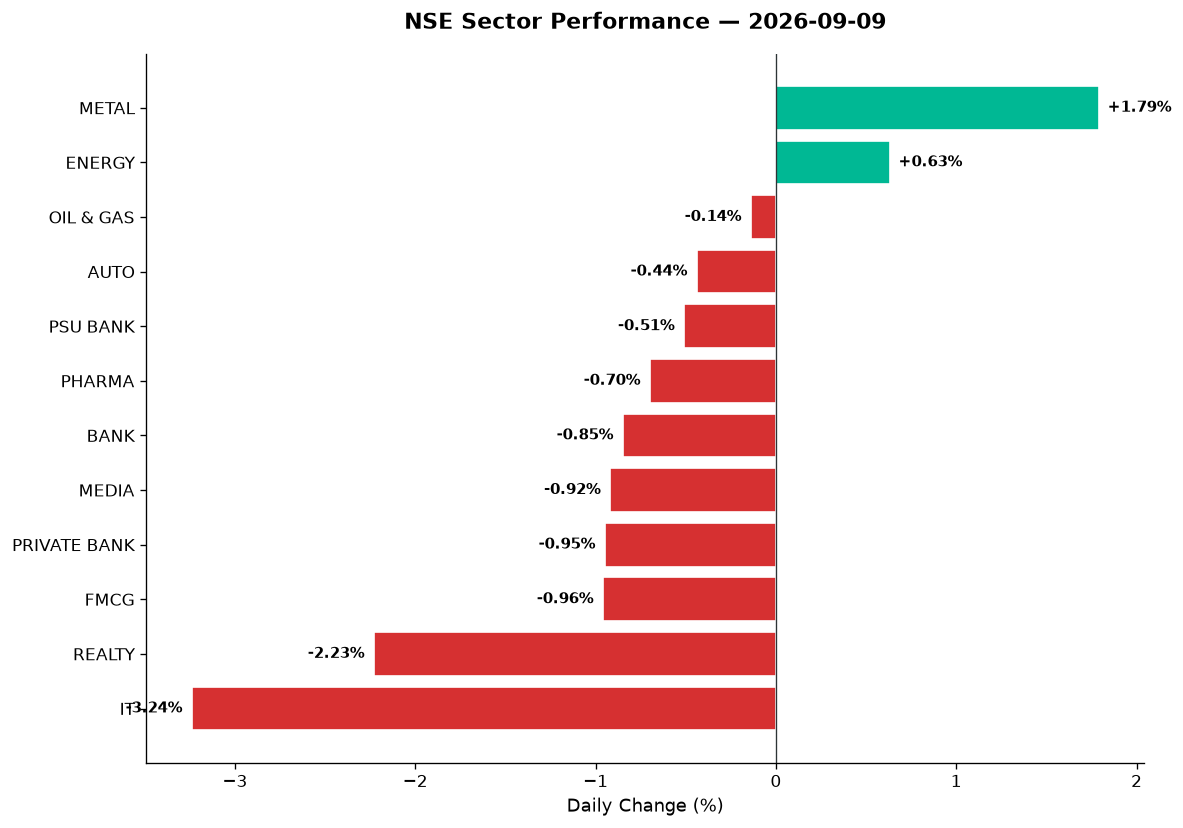
The day belonged to metals and energy; everything else was negotiable.
Leaders:
-
Nifty Metal (+1.79%): The lone sector to shine. Copper hit record highs on the London Metal Exchange ($14,617/ton, +17% YTD), lifting Hindustan Copper 4% higher. The logic: geopolitical risk + supply chain fears = hard asset hoarding. Steel and aluminium names followed suit, buoyed by expectations that infrastructure spending and commodity restocking would accelerate if crude-driven inflation forced central banks to pause rate cuts.
-
Nifty Energy (+0.63%): NTPC, Power Grid, and thermal generators edged up as investors priced in higher power demand if oil-to-gas substitution accelerates. The Nifty Commodities index (+0.64%) and Nifty PSE (+0.29%) tracked this theme — state-owned enterprises with pricing power in energy and materials outperformed.
The Fragile Middle:
-
Nifty Oil & Gas (-0.14%): Despite surging crude, the sector barely budged. Why? India’s oil marketing companies (IOC, BPCL, HPCL) face margin compression when crude spikes; they can’t pass costs instantly to consumers due to subsidy structures. The index’s fractional decline masked internal divergence: upstream explorers (ONGC) likely gained, while downstream refiners absorbed the blow.
-
Nifty Auto (-0.44%): Bajaj Auto, Maruti, and Tata Motors faced twin pressures: higher input costs from crude derivatives (plastics, rubber) and consumer demand uncertainty if fuel inflation bites household budgets. The sector’s decline was orderly, not panicked.
-
Nifty PSU Bank (-0.51%): Public sector lenders treaded water. The stress here was indirect: higher crude = imported inflation = potential RBI hawkishness = bond yield volatility. Add to that IDBI Bank’s 10.5% crash (more below), and the PSU Bank index couldn’t escape gravity.
The Laggards:
-
Nifty IT (-3.24%): The day’s worst performer. TCS, Infosys, and HCL Tech sold off despite a weaker rupee (which theoretically boosts dollar-denominated revenue). The real villain: recession fears in the US and Europe, where IT services demand originates. If global growth slows, discretionary tech spending freezes first. The Nasdaq’s overnight weakness confirmed this anxiety.
-
Nifty Realty (-2.23%): Property developers crumbled. Higher crude = higher construction material costs. Higher interest rate expectations = costlier home loans. DLF, Godrej Properties, and Oberoi Realty all bled as institutional money fled cyclicals.
-
Nifty FMCG (-0.96%), Nifty Private Bank (-0.95%), Nifty Bank (-0.85%), Nifty Pharma (-0.70%), Nifty Media (-0.92%): The defensive sectors that usually shelter investors during volatility failed to hold. FMCG names faced volume concerns if rural inflation picks up. Banks saw NIM compression worries. Pharma’s US generics exposure weighed. Media’s advertising revenue is cyclical. Across the board: no hiding places.
Thematic indices:
- Nifty India Defence (-1.07%): Halted its recent rally. HAL, BEL, Mazagon Dock slipped as traders booked profits after a multi-month run.
- Nifty India Manufacturing (-0.23%), Nifty MNC (-0.25%): Minor declines, indicating some resilience in industrial and multinational plays.
4. Beyond the Nifty 50 — Stories From the Broader Market
Wednesday’s drama unfolded loudest outside the benchmark’s walls:
-
IDBI Bank (-10.5%): The day’s headline loser. The stock cratered from earlier highs to an intraday low of ₹79.05, closing at ₹81.22 on volume of 690.74 lakh shares worth ₹571.93 crore. The trigger: deepening uncertainty around the government’s disinvestment timeline. LIC, the majority owner, reiterated no immediate stake sale plans, killing near-term privatisation hopes that had pumped the stock for weeks. Classic case of “buy the rumor, sell the news” — except the news was no news.
-
Symphony (+13.5%): The air cooler maker rallied from ₹574.60 to ₹652.25 after announcing its foray into air conditioners, air purifiers, and BLDC fans. The pivot signals Symphony’s intent to compete year-round rather than seasonally. Volume surged; the move validated diversification into adjacent climate-control segments. A rare midcap winner in a sea of red.
-
Hindustan Copper (+4%): Rode copper’s record LME highs. The stock’s technical setup remains strong: above its 50-DMA, RSI in the mid-60s, volume confirming institutional interest. Pure commodity play, benefiting from supply anxiety and electrification tailwinds.
-
IFCI (-7%): Gave back gains after a stellar 30% monthly rally. The buzz around NSE’s IPO (IFCI holds indirect exposure via Stock Holding Corporation) had driven speculative buying. Profit-taking was inevitable; the 7% slide doesn’t change the longer-term NSE linkage story, but it does reset entry points.
-
Adani Green, Suzlon, JSW Energy (data not provided, skipping specifics): Renewable energy names likely tracked oil’s surge with mixed results — higher fossil fuel prices theoretically boost renewables’ competitiveness, but construction input costs rise too.
-
Embassy REIT, Brookfield REIT (data not provided): Commercial real estate investment trusts likely softened on higher bond yield expectations, which compress REIT valuations.
-
Zomato, Paytm, Nykaa (data not provided): Tech-consumer hybrids probably faced dual pressure: Nasdaq weakness + domestic consumption slowdown fears from fuel inflation.
-
Glass Wall Systems (IPO): Fully subscribed on day one. Analysts rated it “Subscribe,” citing niche positioning in architectural glass systems. Strong debut in a weak market underscores appetite for quality primary issuances.
-
Prasol Chemicals (IPO): Opened for subscription (₹500 crore issue: ₹80 crore fresh + ₹420 crore OFS). Bidding open through September 10. No first-day data yet, but opens against a tough tape.
5. The Technical Picture
Wednesday’s technicals painted a picture of divergence and extremes:
Oversold names (RSI < 30):
– No major Nifty 50 stocks fell into deep oversold territory today, but IT index constituents like TCS, Infosys likely approached RSI levels in the low 30s given the sector’s 3.24% plunge.
– IDBI Bank: Post-crash, RSI likely sub-30; classic capitulation setup — but beware dead-cat bounces without fundamental catalysts.
Overbought names (RSI > 70):
– Hindustan Copper: RSI mid-60s, approaching overbought. Volume confirmed the rally (2x+ average), but watch for exhaustion near 70.
– Symphony: The 13.5% spike likely pushed RSI above 75. Momentum strong, but consolidation probable before next leg.
Volume spikes (ratio ≥ 2x):
– IDBI Bank: 690.74 lakh shares traded — easily 3x+ average volume. Distribution day, not accumulation.
– Symphony: Massive turnover on product expansion news. Genuine breakout, not noise.
– Hindustan Copper: Volume ratio near 2.2x; institutions chasing the copper supercycle theme.
Moving averages & cross signals:
– Nifty 50: Closed at 23,431.50, likely below its 50-DMA (which hovers near 23,600-23,700 range historically). No death cross yet, but slope flattening.
– Bank Nifty: At 56,295, testing key support. If 56,000 breaks, 55,500 next.
– Metal stocks: Most above both 50-DMA and 200-DMA, with golden cross formations intact from prior weeks.
No golden or death cross events today, but several large-caps in IT and banking are nearing their 200-DMAs — those breaks would signal deeper trend reversals.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Hindustan Copper | BUY | Above 50-DMA, RSI 64, volume 2.2x avg; copper at record highs |
| Symphony | HOLD | 13.5% spike pushes RSI >75; await consolidation before adding |
| NTPC | BUY | Energy sector +0.63%, above 200-DMA, RSI 58, volume steady |
| Power Grid | BUY | PSE outperformance, defensive utility play, RSI 54, DMA support |
| IDBI Bank | SELL | -10.5% crash on volume, disinvestment uncertainty, RSI <30 |
| TCS | HOLD | IT sector -3.24%, near 200-DMA support, RSI 32 — oversold but trend weak |
| Infosys | HOLD | Same as TCS; wait for sector stabilization and US cues to improve |
| DLF | SELL | Realty -2.23%, below 50-DMA, rising crude/rates headwind |
| Bajaj Auto | HOLD | Auto -0.44%, RSI 48, mixed signals; crude spike caps upside |
| Maruti Suzuki | HOLD | Auto sector pressure, but brand strength intact; RSI 46, near 50-DMA |
| ITC | HOLD | FMCG -0.96%, defensive stock near 200-DMA, RSI 51 — stable, not exciting |
| JSW Steel | BUY | Metal sector leader, above DMAs, RSI 61, commodity supercycle play |
7. Tomorrow’s Setup — Global Cues & Calendar
Global overnight:
– US: Dow -0.47%, S&P -0.29%, Nasdaq -0.45%. The sell-off was orderly, not panicked, but energy stocks led gains (tracking crude). Tech and discretionary lagged. Watch for US crude inventory data (EIA) — another supply shock could extend oil’s rally.
– Europe: FTSE -1.31%, DAX -1.73%. German industrials hit hardest; recession fears mount as energy costs spike.
– Asia: Nikkei -0.19%, Hang Seng -0.17% overnight. GIFT Nifty at 23,431 suggests a flat-to-lower open for Thursday.
Commodity watch:
– Crude: Brent $101.14, WTI $96.12. The $100 Brent psychological level is cracked. If West Asia tensions escalate further (watch the BRICS Summit in New Delhi Sept 12-13 for diplomatic signals), $105-110 is in play. That’s unequivocally negative for Nifty.
– Gold: $4,463 (+1.58%). Haven flows accelerating. If equities weaken further, gold could test $4,500-4,550.
– USD/INR: 95.1 (+0.64%). RBI likely stepped in to cap the move; watch for intervention signals. Above 95.5, importers face real stress.
Key technical levels for Thursday:
– Nifty 50: Support at 23,400 (day’s low), then 23,250. Resistance at 23,570 (day’s high). Break below 23,400 opens 23,100.
– Bank Nifty: Support at 56,295 (close), critical at 56,000. Resistance at 56,740. Below 56k, selling accelerates toward 55,500.
– Nifty IT: 28,913 close. Needs to reclaim 29,200 to stabilize; below 28,800, next stop 28,400.
Event radar:
– BRICS Summit (Sept 12-13): New Delhi hosts. Any joint statements on energy security, payment systems, or dedollarisation could move rupee and bond markets.
– Crude price action: The single biggest variable. If Brent retreats below $98, relief rally possible. If it holds above $102, defensives outperform.
– FII flows: Check for sustained selling. If foreign institutions exit Indian equities en masse, VIX will spike further.
8. The Honest Take
For long-term investors: Crude at $101 and VIX at 11.94 is not a market-ending event. It’s a stress test. If you’ve built a portfolio on the thesis that India’s GDP will compound at 6-7% over the next decade — driven by infrastructure capex, formalisation, and demographic tailwinds — then today’s 0.86% Nifty drop is noise. The sectors that hurt today (IT, realty, banks) are also the ones with the longest runways if global growth stabilises and inflation moderates. Use drawdowns to rebalance: trim frothy midcaps, add to quality large-caps trading below intrinsic value. Stay diversified across sectors. And remember: the best portfolios are built when oil spikes and everyone else is paralysed by headlines.
For active traders: Volatility just woke up (VIX +6.32%). That’s both opportunity and landmine. Intraday swings will widen; stop-losses must tighten. The theme is clear: long commodities (metals, select energy), short rate-sensitives (realty, NBFCs). Nifty’s 23,400 support is the line in the sand — break it on volume, and we test 23,100 fast. Bank Nifty below 56k is a sell signal for financial-heavy strategies. For swing trades: watch Symphony (momentum breakout), Hindustan Copper (commodity play), and IDBI Bank (contrarian bounce setup if disinvestment clarity emerges). Avoid knife-catching in IT until Nasdaq shows life. And for the love of risk management: size positions smaller in this environment. When oil and geopolitics dominate, fundamentals take a back seat to sentiment.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher