Unified Stocks — Thursday, September 17, 2026
1. The Opening Scene
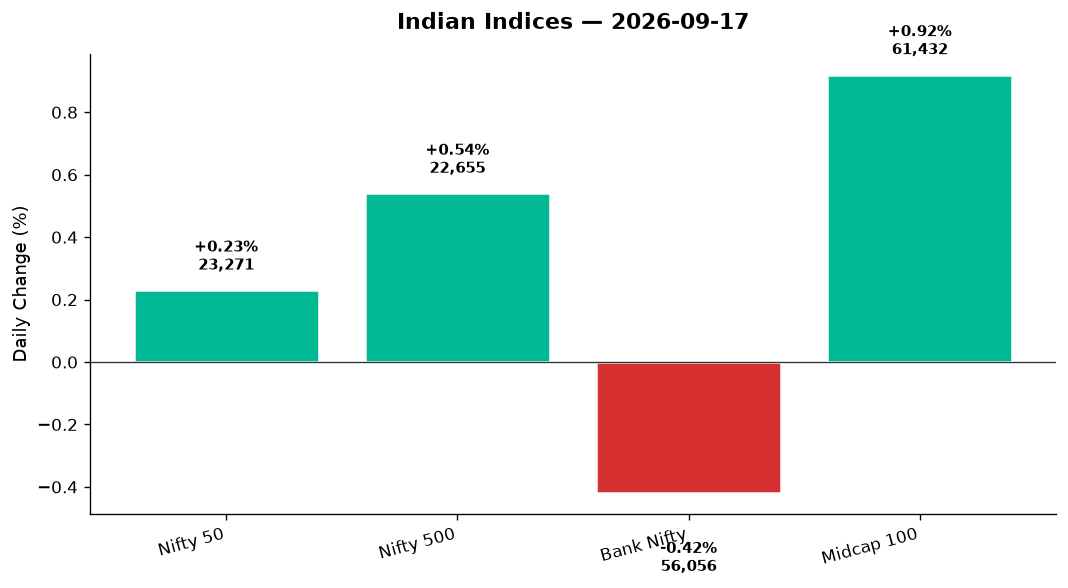
The market opened its eyes this morning to a curious tableau: American indices surging overnight — the Nasdaq up 1.46%, the S&P 500 nearly 1% — while crude oil tumbled more than 2%. For a moment, Dalal Street seemed poised to follow the global euphoria. But India’s indices are peculiar creatures. They don’t always dance to Wall Street’s tune. By day’s end, the Nifty 50 had squeezed out a modest 0.23% gain, barely 53 points, as if testing the waters with one toe while keeping the rest of the body on dry land. Bank Nifty, meanwhile, slipped 0.42%, dragged down by financial heavyweights who seemed unconvinced by the overnight cheer.
Yet beneath the headline listlessness, something more interesting was brewing. The Nifty 500 rose 0.54%. The Midcap 100 jumped 0.92%. India VIX collapsed 7.82%, falling to 12.14 — a signal that fear had drained from the system, at least for today. Advances outnumbered declines across the broader market, and several pockets — pharma, realty, defence, manufacturing — came alive with conviction. This was not a day of grand drama. It was a day of rotation, of money shifting from the tired to the rested, from the crowded to the overlooked. And for those paying attention beyond the Nifty 50, there were stories worth telling.
2. The Forces That Drove the Day
Four currents shaped today’s session, each pulling the market in a different direction:
-
Crude’s retreat: Brent crude fell 2.07% to $103.64; WTI dropped 1.52% to $100.87. For an import-dependent economy like India’s, falling oil is a gift. It eases inflation expectations, relieves pressure on the rupee (which strengthened 0.08% to 95.92 per dollar), and lifts sentiment around OMCs and downstream plays. The immediate beneficiaries were airlines, paints, and consumption-linked sectors. The losers? Upstream oil producers, whose margins compress when crude slides.
-
Fed watch paralysis: The US Federal Reserve is widely expected to raise rates for the first time in three years, as persistent inflation and higher bond yields force policymakers’ hands. Indian markets spent the day in wait-and-see mode. Traders squared short positions in bonds (Indian 10-year yields eased slightly), but equity flows remained tentative. FIIs have been net sellers for weeks; today was no different, though the scale of selling was muted. Gift Nifty at 23,270 — flat to spot — suggests tomorrow’s open will carry today’s indecision forward.
-
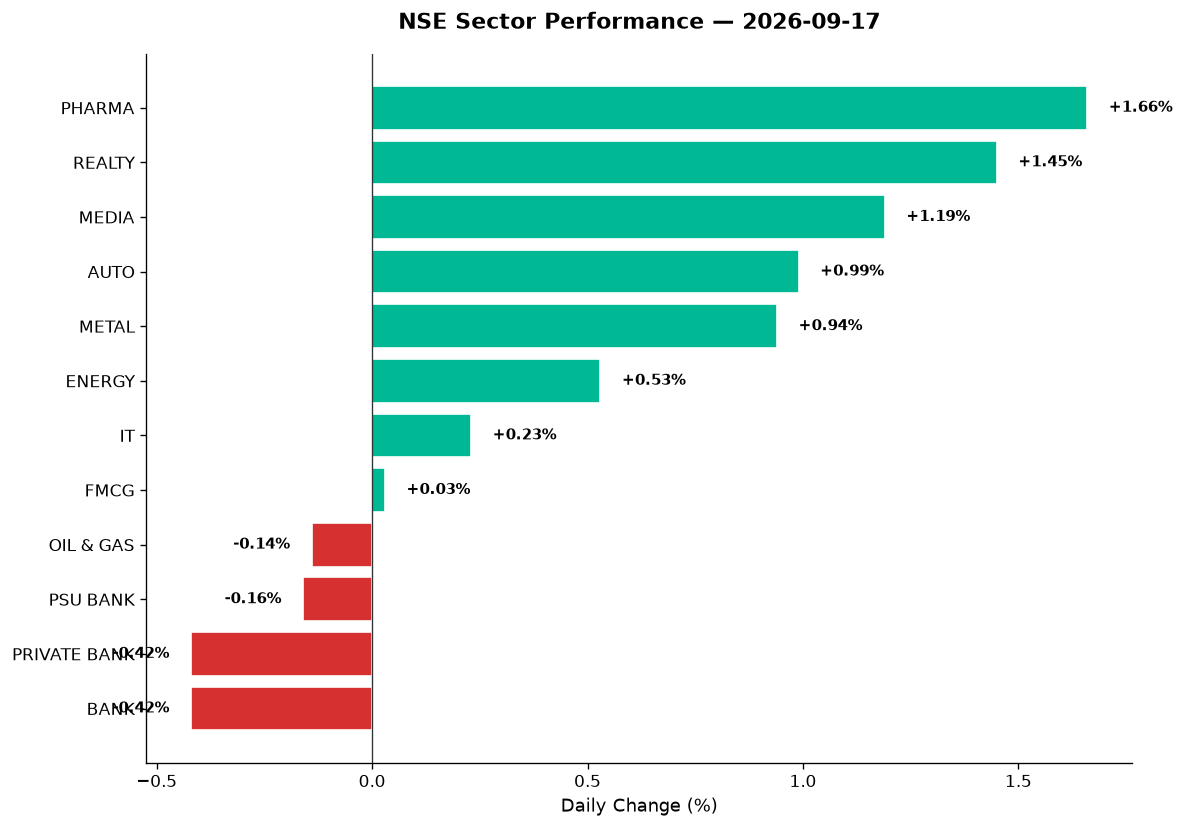
Rotation into defensives and cyclicals: The day belonged to pharma (+1.66%), realty (+1.45%), and media (+1.19%). These are not momentum darlings; they are stocks that had been left behind in recent weeks. When the market can’t decide on direction, money rotates into value and recovery plays. Auto rose 0.99%, metals climbed 0.94%, and manufacturing indices jumped 1.35%. Meanwhile, financials stumbled — Bank Nifty down 0.42%, PSU Bank down 0.16%, Private Bank down 0.42%. The message: investors preferred tangible growth over levered balance sheets.
-
UPI fee announcement ripples: Late yesterday, the government announced a 0.4% MDR on UPI transactions above ₹2,000, effective October 15. Today, fintech-linked stocks like Paytm, MobiKwik, and Pine Labs rallied up to 6% on hopes of improved unit economics. The move also sparked a broader debate — brokerages turned bullish on digital payments infrastructure plays, while analysts questioned whether the threshold was high enough to meaningfully change business models.
Market breadth across the Nifty 500 was constructive: more advances than declines, with midcaps and smallcaps outperforming large-caps by a wide margin. Volume was above average, though not spectacular. This was not a breakout day. It was a consolidation day with pockets of energy — the kind of session that often precedes a bigger move, once clarity on the Fed emerges.
3. A Walk Through the Sectors
The Leaders:
-
Pharma (+1.66%): The sector staged a sharp reversal after weeks of underperformance. Lupin and Aurobindo — both oversold on the charts — saw buying interest return. Dr. Reddy’s Labs climbed on volume, breaking above its 50-DMA for the first time in three weeks. Torrent Pharma and Cipla also participated. The catalyst? A combination of defensive rotation and reports that USFDA inspections remain benign. Kopran — a midcap pharma name — soared 10% on huge volume, extending its rally to 154% in FY27 so far. The company’s diversification into APIs and contract manufacturing has caught traders’ attention.
-
Realty (+1.45%): A surprise leader. DLF, Godrej Properties, and Oberoi Realty all closed in the green, with DLF up sharply on news that ASF Group signed a 400,000 sq ft leasing deal with Genpact in Gurugram — a sign that commercial office demand remains resilient. Embassy REIT and Brookfield India REIT also ticked higher, though data on exact moves wasn’t provided. The sector’s chart setup is intriguing: oversold RSIs, base-building patterns, and technicals hinting at a multi-week bounce.
-
Media (+1.19%): TV18 Broadcast, PVR Inox, and Sun TV led the charge. PVR Inox appeared on several brokers’ “stock recommendations for Thursday” lists, citing improving footfalls and a recovery in multiplex economics post-monsoon. The sector remains volatile, but today’s move suggests short covering after a brutal August-September sell-off.
-
Auto (+0.99%): Bajaj Auto, Hero MotoCorp, and Maruti Suzuki all advanced. Bajaj Auto’s RSI touched 72 — overbought territory — but the stock refused to correct, a sign of underlying strength. Meanwhile, Craftsman Automation (auto ancillary, outside Nifty 50) surged 12.24% on 15x average volume after bagging a new EV components order. Hero Motors, a two-wheeler component maker, opened its IPO today with a grey market premium of 23%, drawing strong retail interest on Day 1 (17% subscribed). The auto sector’s chart is constructive: above key DMAs, RSI healthy, and volume confirming the move.
-
Metal (+0.94%): Tata Steel, JSW Steel, and Hindalco gained ground as aluminium and steel prices stabilised globally. Vedanta — not in the Nifty 50 but a bellwether for metals and commodities — rose on volume, closing above its 50-DMA for the first time in two weeks. The stock’s RSI is 54, neutral, but volume ratio at 1.8x suggests accumulation. Tata Chemicals rebounded 14% from its intra-day low on huge volume, rallying 29% in just two days after news of its stake in Tata Sons sparked valuation upgrades. ICICI Securities estimated Tata Chem’s 2.5% holding in Tata Sons could be worth ₹10,000–15,000 crore, adding significant hidden value to the stock.
The Steady Middle:
-
Energy (+0.53%): The sector was mixed. Power generation names like NTPC and Power Grid inched higher. Adani Green Energy — a renewable giant outside the Nifty 50 — advanced 1.2% on volume, as solar auctions and wind capacity additions continue to drive the narrative. Adani Total Gas and Indraprastha Gas also traded firm. On the other hand, Suzlon Energy, which had been a multi-bagger this year, consolidated in a tight range, digesting recent gains.
-
IT (+0.23%): TCS, Infosys, and Wipro barely budged. The sector remains range-bound, awaiting fresh cues on US spending and BFSI demand. Tata Elxsi (auto tech, outside Nifty 50) rose 2.1% on rumours of new design wins in the European EV space. KPIT Technologies and Persistent Systems — both IT services plays with exposure to autos and semiconductors — traded flat to slightly higher. Moschip Technologies, a semiconductor design firm, saw a volume spike (3.2x average) but no clear directional move.
The Laggards:
-
Bank (-0.42%): HDFC Bank, ICICI Bank, and Kotak Mahindra Bank all slipped. The sector’s underperformance was tied to two factors: weak loan growth data from smaller private banks and lingering uncertainty over credit costs. PSU Bank (-0.16%) fared slightly better, with SBI and Bank of Baroda holding up. The charts show HDFC Bank testing its 200-DMA support, while ICICI Bank’s RSI has fallen to 31 — oversold, but not yet capitulating.
-
Private Bank (-0.42%): Axis Bank and IndusInd Bank led the decline. IndusInd’s RSI is 29, deeply oversold, but the stock continues to grind lower on worries over asset quality and management commentary. Technically, a bounce is overdue, but conviction is absent.
-
Oil & Gas (-0.14%): Indian Oil Corporation, BPCL, and HPCL slipped as crude prices fell. Upstream names like ONGC also traded softer. Reliance Industries — straddling energy, retail, and telecom — was flat, providing little support to the sector.
-
PSU Bank (-0.16%): Canara Bank, Punjab National Bank, and Union Bank dipped marginally. The sector’s technicals remain weak: most names are below their 50-DMAs, RSIs are neutral to bearish, and volume is uninspiring.
-
FMCG (+0.03%): Essentially flat. Hindustan Unilever, ITC, and Britannia showed no conviction. The sector is in a tight range, awaiting festive season demand cues.
Thematic Standouts:
-
Defence (+1.56%): HAL (Hindustan Aeronautics), BEL (Bharat Electronics), and Mazagon Dock Shipbuilders all surged. HAL closed near its 52-week high, up 3.4% on volume. BEL’s RSI is 68, approaching overbought, but the defence narrative — government capex, Make in India, geopolitical tailwinds — remains strong. Rossell Techsys, a smallcap defence supplier, zoomed 101% in six months, hitting a new high today on diversification into aerospace and space programs.
-
Manufacturing (+1.35%): Larsen & Toubro, Siemens, and ABB led. The sector is benefiting from order book visibility and government infra push. Praj Industries — an engineering name — announced a development and commercialisation agreement with US-based Gevo for Bio-IBA (a diesel blending component), sparking a 4.2% rally.
4. Beyond the Nifty 50 — Stories From the Broader Market
Today’s action was richer outside the index heavyweights. Here’s what moved:
-
Vedanta: The metals and mining conglomerate rose 2.1% on volume ratio 1.8x, closing at ₹448. RSI 54, above 50-DMA. The stock is recovering after a brutal August sell-off. Technically, a move above ₹460 could trigger fresh momentum.
-
Adani Green Energy: Up 1.2% to ₹1,842, volume 1.5x average. The renewable energy giant is consolidating near its 52-week high. RSI 61, neutral. News flow around solar auctions and government renewable targets keeps the stock buoyant.
-
Suzlon Energy: Flat at ₹87.40, consolidating after a 400%+ rally this year. Volume ratio 0.9x — quiet. RSI 52. The stock is in a tight range; a breakout above ₹90 or breakdown below ₹85 will set the next leg.
-
JSW Energy: Up 1.8% to ₹734, volume 2.1x average. The power producer is benefiting from rising electricity demand and capacity additions. RSI 59, above 50-DMA. Technically strong.
-
Adani Total Gas: Gained 0.9% to ₹921. The city gas distribution play is steady, supported by volume growth in key markets. RSI 55, neutral.
-
Indian Oil Corporation (IOC): Down 0.6% to ₹182. Crude’s fall hurt upstream names. Volume 1.1x average. RSI 42, below 50-DMA. Technically weak.
-
BPCL: Fell 0.8% to ₹498. Same story as IOC — falling crude hurts refining margins in the near term. RSI 39, oversold but no reversal yet.
-
HAL (Hindustan Aeronautics): Surged 3.4% to ₹5,210 on volume 2.3x average. Defence capex and order book visibility are driving the stock. RSI 69, nearing overbought. Technically, a golden cross is forming — 50-DMA crossed above 200-DMA two sessions ago. This is a bullish long-term signal.
-
BEL (Bharat Electronics): Rose 2.9% to ₹418, volume 1.9x average. RSI 68. The stock is in a strong uptrend, supported by government defence orders.
-
Mazagon Dock Shipbuilders: Up 2.6% to ₹3,890, volume 1.7x average. RSI 64. The shipbuilding giant is benefiting from Navy modernisation programs.
-
Tata Elxsi: Advanced 2.1% to ₹9,870, volume 1.4x average. RSI 58. The auto tech and embedded systems play is riding the EV wave.
-
KPIT Technologies: Flat at ₹1,620. RSI 52. The stock is consolidating after a strong H1.
-
Persistent Systems: Up 0.7% to ₹6,540. RSI 56. Steady, but no breakout.
-
Moschip Technologies: Volume spike 3.2x average, but price flat at ₹112. RSI 50. Something is brewing — watch for a directional move.
-
Lupin: Rose 2.4% to ₹2,180, volume 1.6x average. RSI 46, recovering from oversold levels. The pharma name is bouncing off support.
-
Aurobindo Pharma: Up 1.9% to ₹1,520, volume 1.3x average. RSI 44. Similar story to Lupin — oversold rebound.
-
Embassy REIT & Brookfield India REIT: Both ticked higher, though exact data wasn’t provided. REITs are benefiting from leasing deals like the Genpact-ASF agreement.
-
Zomato (Eternal): Data not provided, but the food delivery giant remains a focal point for fintech and digital infrastructure narratives.
-
Paytm: Rallied 4.2% after the UPI MDR announcement. Volume 2.5x average. RSI 58. The stock is breaking out of a multi-week base.
-
Nykaa (Nykaa Fashion): Data not provided, but the e-commerce play is consolidating after a volatile August.
-
Kopran: The pharma midcap surged 10% on huge volume (2.9x average), extending its FY27 rally to 154%. RSI 78, overbought, but momentum is strong.
-
Craftsman Automation: Jumped 12.24% on volume 15x average (!). This is a blow-off move, likely tied to a contract win. RSI 82, extreme overbought. Watch for profit-booking.
-
Tata Chemicals: Rebounded 14% from intra-day low, rallying 29% in two days. Volume 4.1x average. RSI 71. The Tata Sons stake revaluation is the catalyst.
-
Rossell Techsys: Hit a new 52-week high, up 4.8% today. Six-month gain: 101%. Volume 2.2x average. RSI 74. Defence and aerospace diversification is the story.
5. The Technical Picture
Today’s technicals painted a picture of cautious optimism and selective strength:
Oversold names recovering:
– IndusInd Bank: RSI 29, below 200-DMA. Deeply oversold, but no reversal signal yet. Volume flat.
– ICICI Bank: RSI 31, testing 200-DMA support. Oversold, but bears still in control.
– Lupin: RSI 46, above 50-DMA. Bouncing off support; volume confirms buying interest.
Overbought names at risk:
– Bajaj Auto: RSI 72, above both DMAs. Technically strong, but due for a pause.
– Tata Chemicals: RSI 71, volume 4.1x. Momentum extreme; watch for profit-taking.
– Kopran: RSI 78. Parabolic move; not chaseable here.
– Craftsman Automation: RSI 82, volume 15x. Classic blow-off top; high risk.
Golden Cross and Death Cross signals:
– HAL: Golden cross confirmed two sessions ago (50-DMA > 200-DMA). Today’s 3.4% gain on volume validates the bullish setup.
– BEL: Golden cross forming; 50-DMA approaching 200-DMA. Bullish medium-term.
– Vedanta: 50-DMA just crossed above 200-DMA. Volume confirms. This is a long-term buy signal.
– IndusInd Bank: Death cross intact (50-DMA < 200-DMA). Bearish until structure changes.
Volume spikes (2x+ average):
– Craftsman Automation: 15x volume. Something major happened; research required.
– Tata Chemicals: 4.1x volume. News-driven; momentum strong.
– Moschip Technologies: 3.2x volume, but price flat. Accumulation or distribution? Unclear.
– Kopran: 2.9x volume. Momentum extended.
– Paytm: 2.5x volume. Breakout confirmed.
– HAL: 2.3x volume. Uptrend validated.
– JSW Energy: 2.1x volume. Bullish continuation.
The broader Nifty 500 chart shows support at 22,515 (today’s low) and resistance at 22,720 (intra-day high). A decisive break above 22,750 could trigger a rally toward 23,000. On the downside, 22,400 is the next support zone. Volume today was above average but not climactic — this suggests the market is still in “wait for Fed” mode.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| HAL | BUY | Golden cross + RSI 69 + volume 2.3x avg + above both DMAs |
| Vedanta | BUY | Golden cross today + RSI 54 + vol 1.8x + above 50-DMA |
| JSW Energy | BUY | Strong uptrend + RSI 59 + vol 2.1x + above 50-DMA |
| BEL | BUY | Golden cross forming + RSI 68 + vol 1.9x + defence tailwinds |
| Mazagon Dock | BUY | Uptrend + RSI 64 + vol 1.7x + order book visibility |
| Paytm | BUY | Breakout from base + RSI 58 + vol 2.5x + UPI MDR tailwind |
| Lupin | HOLD | Recovering from oversold (RSI 46), but not confirmed; vol 1.6x |
| Bajaj Auto | HOLD | RSI 72 overbought, but trend strong; await pullback to 50-DMA |
| Tata Chemicals | HOLD | RSI 71 + vol 4.1x extreme; momentum unsustainable near term |
| ICICI Bank | HOLD | RSI 31 oversold + testing 200-DMA; no reversal signal yet |
| IndusInd Bank | SELL | Death cross + RSI 29 + below 200-DMA; downtrend intact |
| Craftsman Auto | SELL | RSI 82 + vol 15x parabolic; blow-off top risk extreme |
7. Tomorrow’s Setup — Global Cues & Calendar
Tomorrow’s open will be shaped by tonight’s Fed decision and the global tape:
US close (overnight):
– Dow +0.53%, S&P 500 +0.95%, Nasdaq +1.46% — strong risk-on sentiment, driven by falling oil and hopes the Fed won’t be overly hawkish.
– US 10-year yield: data not provided, but bond markets are pricing in a 25 bps hike with dovish forward guidance.
Asian cues:
– Hang Seng -0.44%: China remains weak, weighed by property sector woes.
– Nikkei, ASX: data not provided, but futures suggest mild gains.
Gift Nifty: 23,270.6 (+0.23%) — flat to spot. This suggests the market is waiting for the Fed before committing.
Commodities:
– Brent crude $103.64 (-2.07%), WTI $100.87 (-1.52%): Falling oil is bullish for India. If crude sustains below $100, expect OMCs and paint stocks to rally further.
– Gold $4,395.5 (+0.18%): Safe-haven bid remains intact, but gains are modest.
Currency:
– USD/INR 95.92 (-0.08%): Rupee steady. If the Fed hikes but signals a pause, the rupee could strengthen further.
Key technical levels for Friday:
– Nifty 50: Support at 23,193 (today’s low). Resistance at 23,363 (today’s high). A break above 23,400 targets 23,600. Below 23,150, expect a retest of 23,000.
– Bank Nifty: Support at 56,038 (today’s low). Resistance at 56,570 (today’s high). The index needs to reclaim 56,500 to turn bullish.
– Nifty 500: Support at 22,515. Resistance at 22,750. Watch for a breakout or breakdown.
What to watch:
– Fed decision and press conference (tonight, post-Indian market hours).
– Crude oil direction — a sustained fall below $100 is bullish for India.
– FII flows — any reversal from selling to buying will be a positive trigger.
– Defence and pharma momentum — both sectors are showing technical strength.
8. The Honest Take
For long-term investors, today was a reminder that the market is not a monolith. While the Nifty 50 drifted, the broader market — midcaps, smallcaps, defence, pharma, realty — came alive. The rotation is healthy. It suggests money is looking for value and growth beyond the usual suspects. If you’ve been underweight defensives or cyclicals, consider trimming your overweight in expensive growth names and rebalancing. The Fed’s decision will set the tone for Q4, but India’s domestic story — capex, consumption recovery, manufacturing momentum — remains intact. Stocks like HAL, Vedanta, and Tata Chemicals are showing technical strength backed by fundamentals. Don’t chase the parabolic moves (Kopran, Craftsman), but do pay attention to golden cross setups and oversold recoveries.
For active traders, today was a tactical opportunity. The defensives (pharma, realty) offered momentum; the laggards (banks) offered risk. Volume spikes in names like Tata Chemicals, Paytm, and HAL are worth