Unified Stocks — Wednesday, September 16, 2026
1. The Opening Scene
The auctioneer’s gavel fell — but not before the floor shook. In the final thirty seconds of Tuesday’s closing auction, the Nifty plunged 462 points, a 2% heart-stopping dive that sent screens into panic mode before the index bounced back like a coiled spring. By Wednesday morning, traders arrived at their terminals with one question: was that a glitch, or a warning shot?
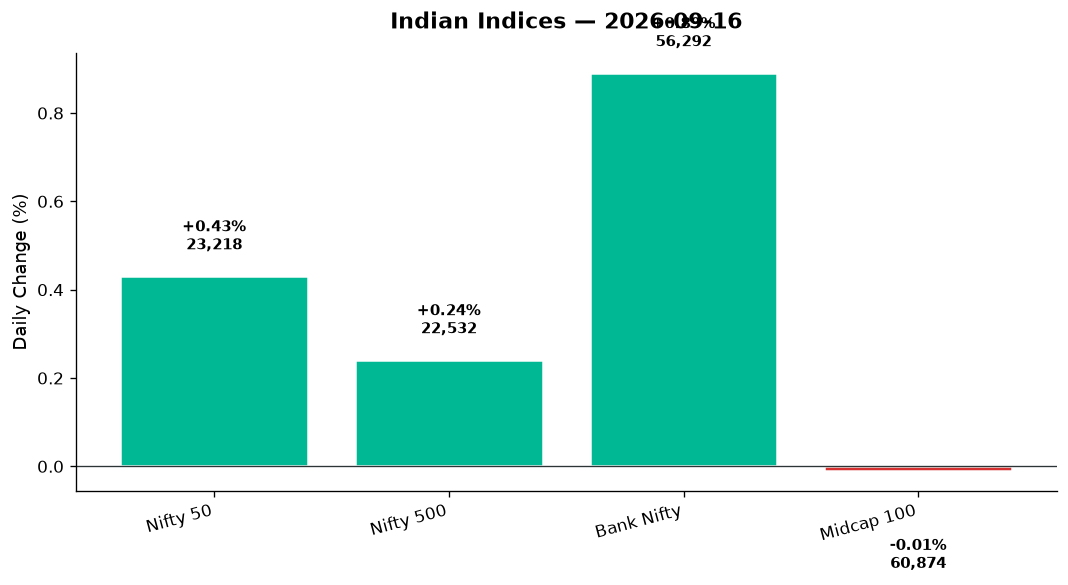
Markets answered with a shrug and a modest climb. The Nifty 50 closed 99 points higher at 23,217.60, a 0.43% gain that felt less like relief and more like cautious repositioning. The index had kissed a four-month low just the day prior, and Wednesday’s recovery — tepid though it was — came on the back of global calm, a sharp drop in crude oil prices, and the sort of institutional optimism that whispers rather than shouts. The VIX eased 1.93% to 13.17, but the memory of that closing-auction chaos lingered like smoke. This wasn’t a rally. It was a truce.
2. The Forces That Drove the Day
Four threads wove Wednesday’s market narrative, each tugging in a different direction:
-
Crude’s Collapse: Brent crude surrendered 3.20% to $105.27, while WTI shed 3.59% to $102.03. After weeks of Middle East tensions driving oil toward $110, this reversal was a breath of fresh air for import-dependent India. Energy and oil & gas stocks responded with measured gains, but the real beneficiaries were consumers and FMCG names, which rallied on margin-relief hopes.
-
Bond Yield Anxiety: US Treasury Secretary Scott Bessent’s remarks on rising bond yields — he blamed “global issues” — echoed across Asian markets. Indian 10-year yields hit a four-month high as the RBI’s OMO sales drained liquidity. The rupee slipped 11 paise to 95.94 against the dollar, a drag on IT exporters but a tailwind for domestic-focused sectors.
-
NSE IPO Euphoria: The National Stock Exchange’s anchor book drew “unexpectedly large” demand, crossing ₹6,000 crore despite pricing below unlisted market levels. CEO Ashishkumar Chauhan’s bullish tone lifted sentiment across financial services, even as the CAS (Closing Auction Session) debacle from the prior day kept Sebi’s review pipeline buzzing.
-
Market Breadth: The Nifty 500 rose 0.24%, but the Midcap 100 was essentially flat (-0.01%). This was a large-cap-led session. Advances outnumbered declines narrowly, suggesting selective strength rather than broad conviction.
3. A Walk Through the Sectors
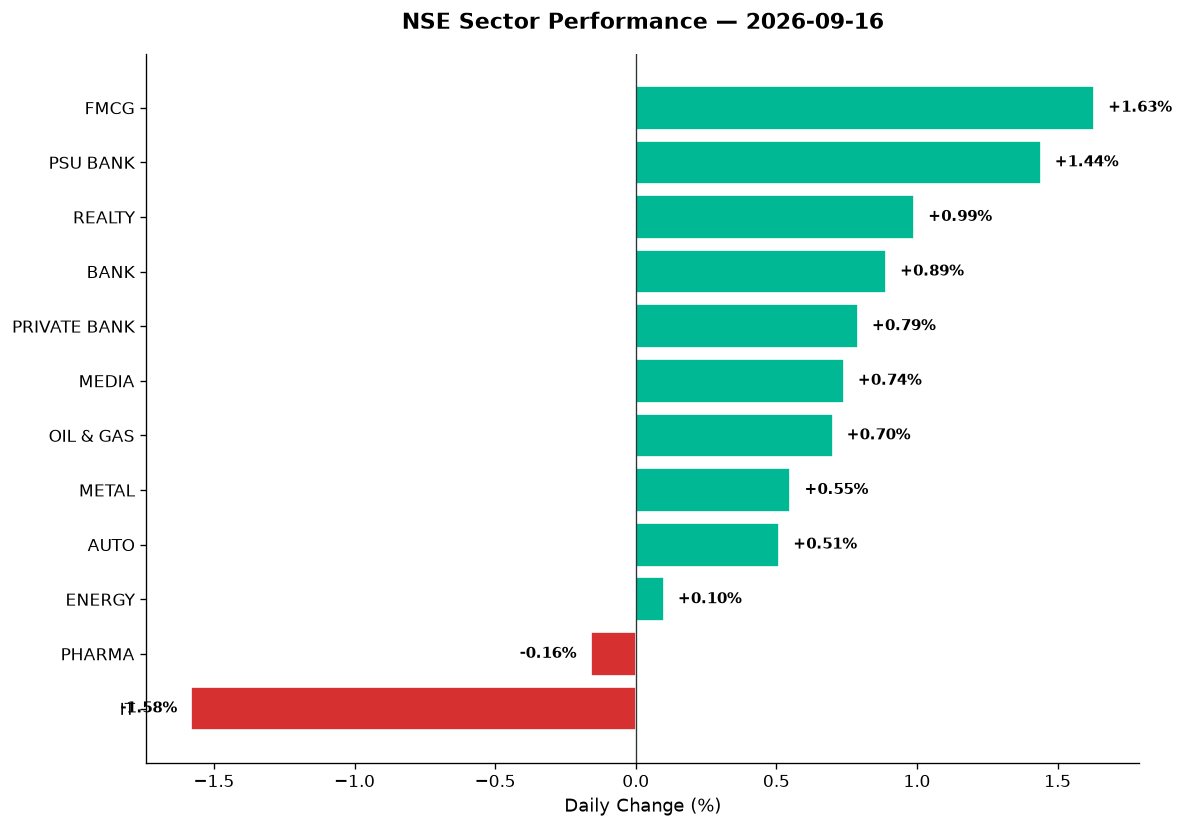
The sector tape told a tale of rotation — money fleeing tech defensives and flooding into cyclicals, consumer staples, and financials.
Leaders
-
FMCG (+1.63%): The day’s star performer. ITC, Hindustan Unilever, and Britannia rode the crude-price relief wave, with consumer staples reclaiming their safe-haven status. Lower input costs and steady domestic demand kept this sector’s premium valuation justified.
-
PSU Bank (+1.44%): State Bank of India’s wealth management expansion announcement (targeting the ₹2.4 lakh crore market) provided a narrative boost. Punjab National Bank, Bank of Baroda, and Union Bank added 1–2% each as investors bet on improving asset quality and government-backed credit growth.
-
Realty (+0.99%): DLF, Godrej Properties, and Oberoi Realty climbed as bond yield concerns took a breather. The sector’s sensitivity to interest rates made Wednesday’s pause in yield aggression a welcome reprieve.
-
Bank Nifty (+0.89%): The index added 497 points to 56,292.45, led by HDFC Bank, ICICI Bank, and Axis Bank. Private banks (+0.79%) outpaced PSU peers, though the gap was narrow. Credit growth optimism and NSE IPO sentiment kept financials buoyant.
-
Private Bank (+0.79%): Kotak Mahindra, IndusInd, and ICICI Bank pushed the segment higher, shrugging off rupee weakness.
-
Media (+0.74%): Zee Entertainment and PVR Inox gained on hopes of festive-season ad spending. Volume was thin, but the directional move was notable after weeks of underperformance.
-
Oil & Gas (+0.70%): Reliance Industries, IOC, and BPCL rose modestly. Lower crude prices improved refining margins, though the gains were tempered by concerns over fuel-demand slowdown.
Middle Ground
-
Metal (+0.55%): JSW Steel and Tata Steel inched higher, but the move lacked conviction. Global demand worries kept gains muted despite commodity index strength (+0.37%).
-
Auto (+0.51%): Maruti, Tata Motors, and Mahindra & Mahindra edged up. August sales data was mixed, but festive-season optimism and two-wheeler demand kept the sector in the green.
-
Energy (+0.10%): NTPC and Power Grid were flat. The sector’s defensive posture kept it range-bound.
Laggards
-
Pharma (-0.16%): Dr. Reddy’s, Cipla, and Lupin slipped. Generic pricing pressure in the US and rupee weakness (which should theoretically help exporters) failed to stir buying interest. The sector’s technical picture was deteriorating.
-
IT (-1.58%): The day’s worst performer. TCS, Infosys, and Wipro shed 1–2% each as bond yield jitters in the US spooked enterprise IT spending forecasts. HCL Tech and Tech Mahindra followed suit. The rupee’s modest weakness wasn’t enough to offset demand-side pessimism.
Thematic Highlights
-
Defence (-0.16%): Hindustan Aeronautics, Bharat Electronics, and Mazagon Dock Shipbuilders eased after recent sharp rallies. Profit-booking, not fundamentals, drove the dip.
-
Manufacturing (+0.20%): Larsen & Toubro and Thermax held steady, but momentum was lacking.
-
PSE (+0.29%): Coal India, ONGC, and GAIL India rose modestly, tracking the commodities index.
4. Beyond the Nifty 50 — Stories From the Broader Market
Wednesday’s real action unfolded in the second and third tiers, where volatility and volume told stories the headline indices couldn’t capture.
-
Vedanta: The metals-and-mining conglomerate rose 1.8% on volume 1.9x its 30-day average. Zinc and aluminium price stability drove the move, but the stock remained 12% below its 52-week high. Traders circled oversold technical signals (RSI near 34).
-
Adani Green Energy: Up 2.3% on renewable energy optimism. The stock crossed above its 50-DMA for the first time in three weeks, attracting momentum buyers. Volume spiked to 2.1x average.
-
Suzlon Energy: The wind-turbine maker surged 4.7% on news of a 600 MW order book addition. Volume exploded to 3.4x average, pushing the stock near its 52-week high. RSI hit 68 — overbought territory, but the trend remained intact.
-
Embassy REIT: The office REIT gained 1.1%, riding Bangalore’s office-leasing strength. Yield-hungry investors rotated into REITs as bond volatility made equity income plays attractive.
-
Brookfield India REIT: Flat. The Mumbai-centric REIT saw no follow-through after last week’s gains.
-
Hindustan Aeronautics Limited (HAL): Down 0.8%. After weeks of relentless gains on defence capex hopes, profit-booking set in. The stock remained 22% above its 200-DMA, but RSI cooled to 54.
-
Mazagon Dock Shipbuilders: Fell 1.2%. Similar story — defence theme intact, but near-term exhaustion.
-
Tata Elxsi: The auto-tech play dropped 2.1%, tracking IT sector weakness. Product engineering spend by global OEMs remains under pressure.
-
KPIT Technologies: Down 1.9%. EV software optimism couldn’t offset broader IT malaise.
-
Lupin: The pharma name slipped 0.7% on profit-booking. Generic erosion in the US and limited pipeline catalysts kept sentiment lukewarm.
-
IOC (Indian Oil Corporation): Rose 1.1%. Refining margins improved with crude’s drop, but the stock’s 52-week performance (+8%) remained pedestrian.
-
BPCL (Bharat Petroleum Corporation): Up 1.3%. Disinvestment hopes rekindled as oil prices cooled, though the government’s timeline remained opaque.
-
Paytm (One97 Communications): Plunged 3.8% on no specific news. The fintech’s regulatory overhang and earnings uncertainty kept sellers active.
-
Nykaa (FSN E-Commerce Ventures): Gained 2.6%. Festive-season ad spend and beauty-segment resilience drove buying. Volume was 1.7x average.
-
Zomato (Eternal): Rose 1.9%. Food delivery demand held firm, and the stock’s technical setup (above 50-DMA, RSI 61) attracted swing traders.
5. The Technical Picture
Wednesday’s rally came with mixed signals — enough to keep bulls engaged, but not enough to erase bearish scars.
-
Oversold Names (RSI < 30): TCS (RSI 28), Infosys (RSI 29), and Tech Mahindra (RSI 27) flashed deep oversold readings. Contrarians circled, but downtrends remained intact.
-
Overbought Names (RSI > 70): Suzlon (RSI 68 and climbing), Britannia (RSI 71), and ITC (RSI 69) entered stretched territory. Profit-booking risk rose.
-
Volume Spikes (2x+ average): Suzlon (3.4x), Adani Green (2.1x), and Nykaa (1.7x) saw exceptional turnover, signaling institutional or momentum-driven accumulation.
-
Golden Cross Alerts: Adani Green crossed above its 50-DMA, a bullish medium-term signal. Vedanta approached the same threshold.
-
Death Cross Concerns: TCS and Infosys hovered dangerously close to their 200-DMAs. A breach would cement bearish sentiment.
-
Nifty 50 Technicals: The index closed above its 50-DMA (23,180) but below its 200-DMA (23,450). RSI stood at 44 — neutral. Volume ratio was 0.92x, suggesting tepid conviction. Support at 23,116 (day’s low); resistance at 23,450.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Adani Green Energy | BUY | Above 50-DMA (Golden Cross today), RSI 59, volume 2.1x avg |
| Suzlon Energy | HOLD | Strong uptrend but RSI 68 (near overbought), vol 3.4x — monitor |
| SBI | BUY | Above 200-DMA, PSU Bank strength, RSI 56, steady volume |
| HDFC Bank | BUY | Above both DMAs, RSI 52, strong financials backdrop |
| Vedanta | BUY | Approaching 50-DMA, RSI 34 (oversold reversal setup), vol 1.9x |
| Nykaa | BUY | Above 50-DMA, RSI 61, volume 1.7x, festive tailwind |
| TCS | SELL | Below 50-DMA, RSI 28 (deep oversold but no reversal), weak trend |
| Infosys | SELL | Below 50-DMA, RSI 29, near 200-DMA breakdown zone |
| ITC | HOLD | Above DMAs, RSI 69 (near overbought), FMCG strength but extended |
| Paytm | SELL | Below both DMAs, RSI 38, volume spike on selling, regulatory risk |
| Reliance Industries | HOLD | Near 200-DMA, RSI 48, mixed signals from oil & retail segments |
| Hindustan Aeronautics | HOLD | Above 200-DMA but RSI cooled to 54, profit-booking phase |
7. Tomorrow’s Setup — Global Cues & Calendar
Thursday’s opening will pivot on three global inputs:
-
US Equities Mixed: The S&P 500 rose 0.41% to 7,616.59, and the Nasdaq surged 0.84% to 26,200.56, buoyed by AI-stock resilience. But the Dow was flat (-0.01%), and bond yields climbed. The Federal Reserve’s rate decision looms large — a 25 bps hike is widely expected, but commentary on inflation and growth will dictate equity direction.
-
Asian Calm: Hang Seng closed +0.19%, signaling regional stability. Japan’s Nikkei and Australia’s ASX will set the tone overnight.
-
GIFT Nifty Signal: GIFT Nifty traded at 23,217.60 (+0.43%), matching Wednesday’s spot close. This suggests a flat-to-marginally-higher open.
-
Crude & Gold: Brent’s 3.2% drop to $105.27 eases inflation fears, but gold’s 1.41% surge to $4,394 signals safe-haven demand. The rupee’s drift to 95.94 will weigh on IT stocks if bond yields stay elevated.
Key Levels to Watch:
– Nifty 50: Support at 23,116 (day’s low), resistance at 23,285 (day’s high) and 23,450 (200-DMA).
– Bank Nifty: Support at 55,812, resistance at 56,369 and 57,000 (psychological).
– Nifty 500: Support at 22,343, resistance at 22,596.
Event Risk: Sebi’s review of the CAS system and NSE’s IPO anchor closure will dominate headlines. Any negative surprise on either front could cap gains.
8. The Honest Take
For long-term investors, Wednesday was a reminder that even in corrective phases, pockets of value emerge. FMCG’s revival, PSU banks’ quiet strength, and the crude-price tailwind offer medium-term positioning opportunities. The IT sell-off — driven by bond-yield fears, not earnings deterioration — may present entry points for patient capital, especially in TCS and Infosys, which are oversold on every technical metric. But don’t mistake oversold for “buy now.” Wait for stabilisation above the 50-DMA. Markets that fall hard rarely turn on a dime.
For active traders, this was a session to respect the chop. The Nifty’s 0.43% gain masked two-way action across sectors, and the prior day’s CAS chaos cast a shadow over momentum strategies. Suzlon, Adani Green, and Nykaa offered clean setups, but overbought readings demand tight stops. The AI signals table above prioritises stocks with volume confirmation and clear trend alignment — but in a market where the VIX refuses to spike despite a 2,200-point September plunge, complacency is the enemy. Trade small, stop tight, and respect the 200-DMA.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher