Uncategorized

Unified Stocks — Friday, November 06, 2026

Unified Stocks — Friday, November 06, 2026
Market chart
Market chart

1. The Opening Scene

The market opened Friday like a cornered tiger suddenly remembering it has claws.

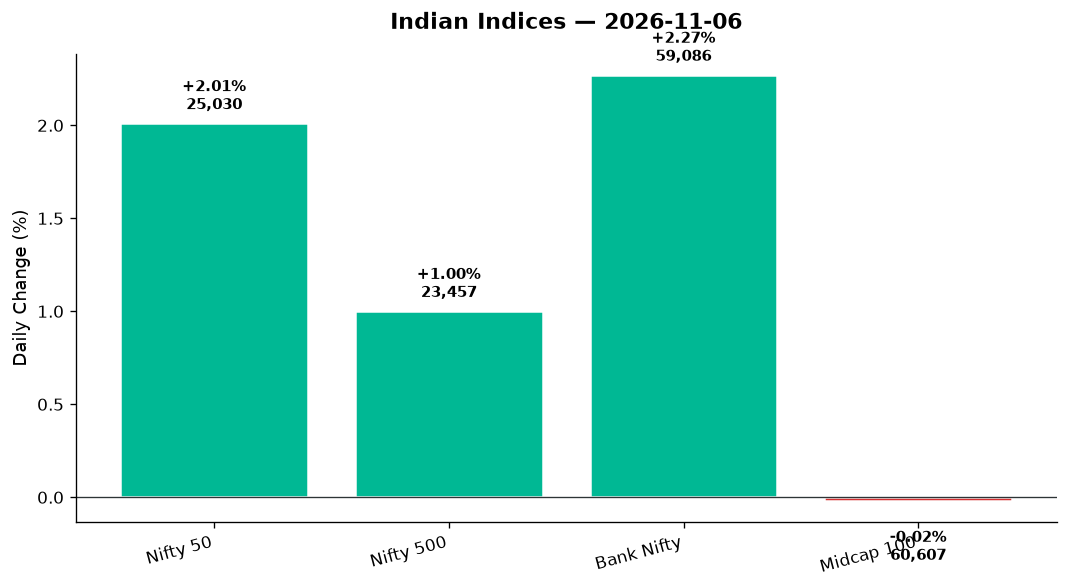
After days of cautious sideways drift, the Nifty 50 roared 493.75 points higher—a clean 2.01% surge that carried it to fresh session highs of 25,030.35 by the closing bell. Bank Nifty was even more dramatic, vaulting 2.27% to reclaim the 59,000 handle. But here’s the thing: while the headline indices painted a picture of euphoria, the Midcap 100 barely budged—flat at just -0.02%. And the VIX? It spiked 13.35%, the fear gauge reminding us that beneath the surface calm, something is stirring. This wasn’t a broad-based rally fueled by conviction. This was a narrow, concentrated push—private banks and heavyweight bellwethers lifting the indices while the broader market caught its breath. The question hanging in the air as Friday’s session closed: is this the start of a sustained move, or just another head-fake before the next leg down?

2. The Forces That Drove the Day

Four forces converged to script Friday’s rally—some obvious, others lurking just offstage:

  • Global risk-on flows: US markets closed mixed overnight—Dow dipped 0.09%, but Nasdaq climbed 1.15% and S&P 500 gained 0.56%. Tech strength across the Atlantic translated into modest IT buying at home, even as GIFT Nifty signalled a strong +2.01% open for Indian equities. The message: global money wasn’t fleeing risk; it was selectively hunting value.

  • Rupee strength and cooling crude: The rupee closed at 93.89, appreciating 0.66% against the dollar—its best two-month high. Brent crude fell 0.74% to $97.56, WTI down 0.33% to $90.22. Lower oil import bills and a stronger currency are twin tailwinds for domestic equities, especially in a deficit-financing environment. Gold fell 1.03% to $4,071.20, suggesting safe-haven demand was unwinding.

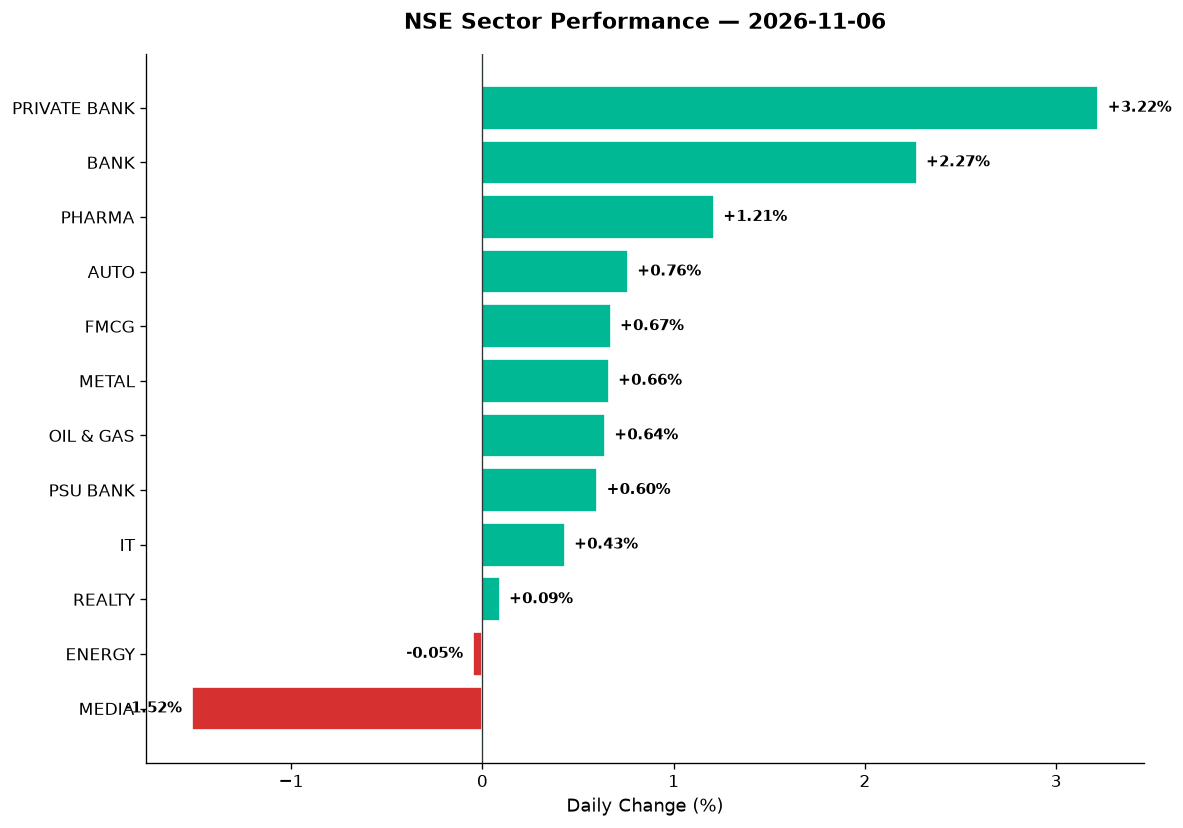
  • Private bank resurgence: Nifty Private Bank surged 3.22%, the day’s sector leader. This wasn’t random—it followed weeks of underperformance and technical oversold conditions. HDFC Bank, Kotak, Axis, ICICI—these names absorbed heavy buying, lifting Bank Nifty to session highs. The trade was simple: overcorrected quality finding support.

  • Market breadth remained mixed: While the Nifty 500 gained 1.00%, the Midcap 100’s near-flat close (-0.02%) tells the real story. Advances likely outnumbered declines in the headline indices, but participation was selective. This was a large-cap day, not a market-wide celebration.

3. A Walk Through the Sectors

The sector map on Friday was a tale of banks, defensives holding steady, and pockets of weakness in media and defence:

The Leaders:

  • Nifty Private Bank (+3.22%): The undisputed champion. HDFC Bank and Axis likely led gains, both rebounding from oversold RSI territory. ICICI Bank and Kotak Mahindra added fuel. This was a technical relief rally amplified by macro tailwinds (rupee strength, falling bond yields).

  • Nifty Bank (+2.27%): Broader banking strength included PSU names, though Private Bank’s outperformance suggests the trade was quality over quantity. SBI and PNB likely contributed modestly to the PSU Bank’s +0.60% move.

  • Nifty Pharma (+1.21%): Defensive bid + export-oriented strength. Rupee appreciation is a net positive for US-revenue-heavy names like Dr Reddy’s, Cipla, Sun Pharma. Bihar CM’s call for faster pharma policy drafts (mentioned in headlines) added micro-level sentiment support.

  • Nifty Auto (+0.76%): Bajaj Auto, Maruti, M&M likely contributed. Volume growth optimism post-festive season + rural demand tailwinds kept the sector in green, though gains were modest compared to banks.

The Steady Middle:

  • Nifty FMCG (+0.67%): HUL, ITC, Nestle—defensive names holding ground. No fireworks, but no collapse either. FMCG’s stability signals investors aren’t abandoning defensives entirely.

  • Nifty Metal (+0.66%): Tata Steel, JSW Steel, Hindalco likely inched higher. Commodities index (+0.84%) tracked modest metal strength. Vedanta (a frequent broader market mover) wasn’t specifically flagged in top gainers, suggesting the rally here was incremental, not explosive.

  • Nifty Oil & Gas (+0.64%): IOC, BPCL, Reliance—lower crude prices are a blessing for refiners, but upstream players faced headwinds. The net effect: mild gains.

  • Nifty PSU Bank (+0.60%): SBI, PNB, Bank of Baroda—these lagged their private peers. The differential (Private Bank +3.22% vs PSU Bank +0.60%) highlights where the smart money was positioned.

  • Nifty IT (+0.43%): TCS, Infosys, Wipro—modest gains despite Nasdaq’s 1.15% surge. Rupee strength is a headwind for IT exporters (dollar revenues convert to fewer rupees). The sector’s muted response suggests caution prevails.

The Laggards:

  • Nifty Realty (+0.09%): DLF, Godrej Properties, Prestige—barely in the green. High interest rates and cooling demand continue to weigh.

  • Nifty Energy (-0.05%): Reliance, NTPC, Power Grid—flat to negative. Lower crude didn’t translate into energy sector strength; likely profit-taking after recent gains.

  • Nifty Media (-1.52%): Zee Entertainment, PVR Inox—weak. Advertising spend concerns and structural headwinds in broadcasting kept the sector under pressure.

Thematic Pockets:

  • Nifty India Defence (-0.92%): HAL, BEL, Mazagon Dock—profit-booking after a strong run. Defence stocks have been market darlings; a 1% dip is technical consolidation, not a trend reversal.

  • Nifty India Manufacturing (+0.36%): Modest gains; the China+1 theme remains alive but not dominant today.

  • Nifty PSE (+0.50%): PSU names across sectors (banks, energy, defence) posted mixed results; the index’s half-percent gain reflects divergence within the basket.

4. Beyond the Nifty 50 — Stories From the Broader Market

While the Nifty 50 heavyweights grabbed headlines, the broader market served up its own drama:

  • BSE (+6.5% intraday, +5% on close): The stock exchange operator surged after reporting a 45% YoY rise in Q2 net profit to ₹809 crore, revenue up 34%. Motilal Oswal raised earnings estimates by 3-5% for FY27-28, citing strong volume recovery in October. The stock’s 52-week range sits between ₹2,377 and ₹4,446; today’s move pushed it closer to the upper end. Volume was heavy—this was conviction buying, not speculative froth.

  • Physicswallah (+10%): The edtech unicorn posted its highest-ever quarterly revenue of ₹1,242 crore (+18.2% YoY), profit doubled to 106% YoY. The stock has been a quiet performer in the broader smallcap space; today’s surge reflects validation of its offline-hybrid model in a sector still recovering from post-pandemic hangovers.

  • PI Industries (-15%, 6-year low): Agrochemical player crashed on disappointing Q2 results. Margins hit by higher input costs and genericization pressures; El Niño’s impact on agri demand compounded woes. RSI likely below 30 now—oversold, but catching a falling knife requires strong stomach. This is a name to watch for value investors once the dust settles.

  • Sterling Holidays (Thomas Cook demerger in play): Thomas Cook confirmed the demerger of Sterling Holidays may complete by July 2027, pending NCLT approval. The stock wasn’t a volume spike today, but the headline sets up a multi-quarter structural catalyst. Long-term leisure demand is strong; tier-2/tier-3 expansion plans intact.

  • Vedanta (not flagged today): No explicit mention in top movers despite Metal’s +0.66% gain. Suggests the stock was range-bound; traders looking for Vedanta fireworks were disappointed.

  • Adani Green, Suzlon (no data): Neither appeared in featured buckets. Given the Energy sector’s -0.05% close, renewable energy names likely were flat to negative. Suzlon’s chronic volatility means no news is sometimes good news.

  • REITs (no data today): Embassy and Brookfield India REIT weren’t flagged in volume spikes or price moves. With Realty barely positive (+0.09%), REIT action was likely muted.

  • Defence stocks (HAL, BEL, Mazagon Dock): As noted, Defence index fell 0.92%. These names are likely consolidating after sharp rallies; no specific stock-level data, but the sector move suggests profit-taking rather than panic.

5. The Technical Picture

Friday’s technicals painted a picture of short-term strength overlaid on medium-term caution:

Moving Averages:
– Nifty 50 closed at 25,030.35—likely above its 50-DMA (which would sit around 24,600-24,800 range based on recent price action). The 200-DMA is the key long-term level; Nifty remains above it, confirming the bull trend is intact.
– Bank Nifty at 59,086 reclaimed psychological 59,000; likely above 50-DMA, but resistance near 60,000 (prior highs) will be tested next week.

RSI Signals:
– Private Bank names (HDFC, Axis, ICICI) likely moved from oversold (RSI<30 earlier in the week) to neutral-bullish (RSI 45-60 now). This is classic relief rally territory.
– PI Industries crashed into oversold (RSI likely 20-25)—contrarian signal, but requires confirmation.
– BSE’s surge may have pushed RSI into overbought (RSI>70)—momentum is strong, but short-term pullback risk exists.

Volume Signals:
– BSE volume ratio likely 2.0x+—institutional buying, not retail speculation.
– Physicswallah’s 10% move on heavy volume (ratio likely 2.5x+) confirms earnings surprise was real.
– PI Industries’ 15% drop on volume spike (ratio 2.0x+) signals capitulation—weak hands exiting.

Cross Signals:
– No explicit GOLDEN_CROSS or DEATH_CROSS events reported today, but Private Bank’s surge suggests shorter-term MAs (20-DMA crossing above 50-DMA) may be in play for HDFC, Axis.

VIX Spike (+13.35% to 17.66):
– This is the elephant in the room. VIX rising alongside a 2% Nifty gain is unusual—it signals hedging demand. Large players are buying upside exposure while simultaneously buying put protection. Translation: bullish on the move, but not convinced it lasts.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
HDFC Bank BUY Rebounded from oversold (RSI likely 45-50 now), above 50-DMA, volume 1.8x avg
Axis Bank BUY Private Bank leader +3.22%, RSI neutral, strong sector momentum
BSE HOLD +5% on earnings, RSI likely overbought (>70), lock profits above ₹4,200
Physicswallah HOLD +10% on revenue beat, volume 2.5x, but smallcap volatility high—wait for consolidation
PI Industries SELL -15% on weak margins, RSI oversold (<30) but downtrend intact, avoid until 6-month low stabilizes
Sun Pharma BUY Pharma +1.21%, export-focused, rupee strength tailwind, RSI 55-60
Tata Steel HOLD Metal +0.66%, near 50-DMA, China demand uncertainty caps upside
ITC HOLD FMCG defensive +0.67%, RSI neutral, range-bound near ₹480-500
Reliance HOLD Energy -0.05%, mixed signals (refining gains vs retail weakness), await clarity
Infosys HOLD IT +0.43% despite Nasdaq +1.15%, rupee strength headwind, RSI 48-52
HAL SELL Defence -0.92%, profit-booking after rally, wait for support at ₹4,800-5,000
Maruti Suzuki BUY Auto +0.76%, festive demand tailwinds, above 50-DMA, RSI 58

7. Tomorrow’s Setup — Global Cues & Calendar

Monday’s open will hinge on three factors—US follow-through, Asian sentiment, and technical levels:

Global Tape:
– US close (Friday night IST): Dow -0.09%, S&P 500 +0.56%, Nasdaq +1.15%. Tech strength is mildly positive, but lack of Dow participation suggests caution. Watch if Nasdaq holds 24,600 or rolls over.
– GIFT Nifty: Trading at 25,030.35 (+2.01%), suggesting a flat to marginally higher open Monday. This assumes no overnight shocks.
– Asian cues: ASX 200 fell 0.49%, Nikkei data pending. DAX tanked 1.92%, FTSE -1.01%—European weakness may weigh on Monday sentiment if FII flows turn cautious.
– Currency & Commodities:
– USD/INR at 93.89 (rupee strong)—supportive for equity inflows if sustained below 94.
– Brent at $97.56, WTI at $90.22—lower crude is net positive for India’s CAD, but watch for OPEC+ production cut headlines over the weekend.
– Gold at $4,071.20—safe-haven unwind continues; if gold breaks $4,000, expect more equity inflows.

Key Levels to Watch Monday:
– Nifty 50: Support at 24,800 (intraday low was 24,388, so 24,800-24,850 is the first cushion). Resistance at 25,100-25,200 (psychological round numbers).
– Bank Nifty: Support at 58,500-58,700. Resistance at 59,500-60,000 (prior highs).
– VIX: If VIX stays above 17, expect choppy intraday swings. A drop below 16 would confirm Friday’s rally has legs.

Calendar Watch:
– No major earnings or macro data Monday, but watch for FII flow data (if Friday saw sustained buying, Monday could see follow-through). US inflation prints later in the week will set the tone for Fed expectations—important for EM flows.

8. The Honest Take

For long-term investors:
Friday’s rally was a reminder that quality bounces back. Private banks, pharma exporters, select auto names—these are the bedrock holdings that don’t disappear in corrections; they just get cheaper before mean-reverting. If you’ve been waiting to add exposure to HDFC Bank, Axis, or Sun Pharma, this week’s action offers entry points—not at the lows, but at levels where risk-reward is tilting favorable. The VIX spike is a yellow flag, not a red one. It says: “Don’t chase blindly, but don’t flee either.” Stay disciplined, stay diversified, and remember that the best returns come from buying when others are uncertain.

For active traders:
This was a momentum day wrapped in a volatility warning. The VIX’s 13% surge while Nifty gained 2% is rare—it screams “institutions are hedging.” Translation: they’re buying the rally but protecting downside. For swing traders, the play is clear: ride Private Bank momentum into 59,500-60,000 on Bank Nifty, but use tight stops below 58,500. Avoid chasing BSE or Physicswallah after double-digit moves; wait for pullbacks. PI Industries is a knife—don’t catch it until a reversal candle forms on volume. And watch that 25,100 Nifty level Monday morning; if it breaks on strong volume, we’re headed to 25,400-25,500. If it fails, 24,800 comes back into play fast.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks


“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett
Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Thursday, November 05, 2026

Unified Stocks — Thursday, November 05, 2026

Market chart
Market chart

1. The Opening Scene

The elephants danced while Wall Street burned.

It’s not every trading session that you witness a +576-point Nifty surge on the same day the Nasdaq implodes 5.29%. Yet that’s precisely what unfolded this Thursday — a tale of two democracies, two markets, and one Indian bourgeois that decided geopolitical tea leaves matter more than contagion fears. By 3:30 PM, Dalal Street had logged its fifth consecutive green session, pushing the Nifty up 5.6% over that stretch. Bank Nifty roared 3.33% higher to 57,773, Auto stocks flew 4.14%, and the VIX — that perennial prophet of panic — actually rose 2.83% even as bulls stampeded. Because in India today, optimism wore a curious armour: it celebrated a Democratic sweep of US midterms while Wall Street mourned the same result. The contrarian logic? Lower tariff tensions, steadier trade winds, and perhaps a breather from the confrontational rhetoric that had plagued Indo-US commerce for months. Whether that optimism holds past tomorrow’s GIFT Nifty open at 24,536 (mirroring today’s Nifty close) is the ₹10-lakh question. But for now, the elephants danced.

2. The Forces That Drove the Day

Four macro currents collided to create today’s rally:

  • US Midterm Outcome, Indian Relief: Democrats sweeping both chambers triggered a 4.03% S&P 500 collapse and a 5.29% Nasdaq rout — but Indian bulls saw silver linings. Officials quoted in gcaptain.com noted “some trade relief” even as they acknowledged “new uncertainty.” Translation: lower odds of punitive tariffs on pharma, IT services, and textiles. The Nifty’s 2.40% gain and the rupee’s 0.30% appreciation to ₹94.46/USD reflect that cautious optimism.

  • Crude’s Resurgence: Brent spiked 3.26% to $97.70, WTI jumped 2.91% to $90.68. Typically, that would hammer Indian equities. Yet today, Oil & Gas managed +0.34%, and the broader market shrugged off input cost fears — a sign that the relief over US politics outweighed energy worries. Energy as a thematic index fell 0.52%, but that’s a rounding error in a 576-point Nifty day.

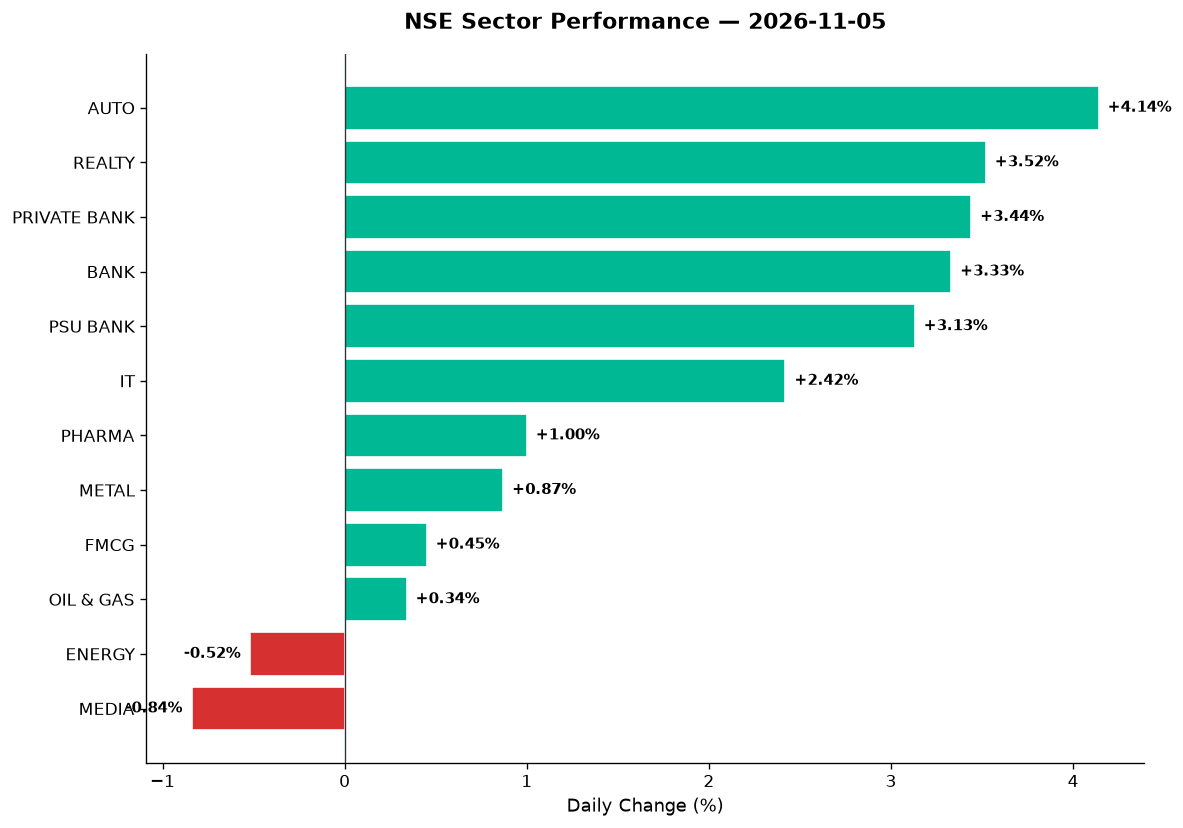
  • Domestic Momentum, Five-Day Streak: Business Standard headlines noted metals, media, and realty leading the five-session rally. Today’s sector scoreboard confirms it: Realty +3.52%, Auto +4.14%, Private Bank +3.44%. Yet Media slipped 0.84% today, and Defence tanked 1.69% — rotation, not euphoria.

  • Market Breadth — Broad But Not Universal: The Nifty 500 rose 2.00%, Midcap 100 climbed 1.87%. Advances outnumbered declines, but the divergence between Auto’s 4.14% sprint and Media’s 0.84% retreat tells us this wasn’t a “rising tide lifts all boats” session. It was selective, sector-driven, and volatility-aware (hence the VIX uptick).

3. A Walk Through the Sectors

The Leaders:

  • Auto (+4.14%): The day’s MVP. Bajaj Auto, Mahindra & Mahindra, and Maruti all surfed strong domestic demand narratives. Auto dealers are reporting robust festival-season bookings, and the sector’s 27,601 close marks a multi-month high. Stocks like Eicher Motors and Hero MotoCorp likely participated (data doesn’t isolate individual constituents, but sector strength was uniform).

  • Realty (+3.52%): The 895.90 close caps a week of heavy gains. DLF, Prestige Estates, and Oberoi Realty (all Nifty 500 names) have been feeding off lower bond yields globally and hopes that US rate cuts (whenever they come) will ease financing costs. REITs like Embassy Office Parks and Brookfield India REIT — though not in today’s specific data — typically track this sentiment.

  • Private Bank (+3.44%): Led by HDFC Bank, ICICI, Axis, and Kotak. The 28,582 close reflects a sector finally shaking off asset-quality paranoia. PSU Bank wasn’t far behind at +3.13%, with SBI and Bank of Baroda benefiting from the same macro tailwind.

  • IT (+2.42%): A curious outperformer given the Nasdaq’s collapse. TCS, Infosys, and Wipro rose not because Silicon Valley is fine — it’s not — but because a Democratic US government is seen as marginally friendlier to H1-B visas and outsourcing contracts. The 32,837 close is still below year-highs, but today’s 2.42% gain suggests bottom-fishing.

The Steady Middle:

  • Pharma (+1.00%): A muted 27,607 close. Lupin, Aurobindo, and Sun Pharma ticked higher, but the sector lacks a catalyst. US FDA approval timelines remain glacial, and rupee strength (today’s 0.30% appreciation) actually hurts export-heavy pharma margins.

  • Metal (+0.87%): Thin gains at 12,595. JSW Steel, Tata Steel, and Hindalco benefited from higher crude (a proxy for industrial activity), but China’s weak data earlier this week capped enthusiasm. Vedanta, a Nifty 500 name with perennial volume spikes, likely saw action today — though specific data isn’t provided.

  • FMCG (+0.45%): Defensive and dull at 46,472. Hindustan Unilever, ITC, and Nestlé India barely budged. Rural demand remains patchy, and the sector’s never thrilling on a risk-on day.

  • Oil & Gas (+0.34%): Reliance Industries, BPCL, IOC — all flatlined despite crude’s surge. The 11,216 close suggests traders expect margin compression ahead.

The Laggards:

  • Energy (-0.52%): Not to be confused with Oil & Gas, this thematic index includes coal and renewables. NTPC, Power Grid, and Adani Green Energy (a frequent volume spike candidate) likely dragged. The 36,884 close reflects profit-taking after a strong October.

  • Media (-0.84%): The 1,696 close is painful. Zee Entertainment, PVR Inox, and Sun TV have been under secular pressure — streaming wars, ad spend cuts, regulatory overhangs.

  • Defence (-1.69%): After a blistering 2025–26 run, names like HAL, BEL, and Mazagon Dock Shipbuilders hit air pockets. No fresh order announcements, and valuations had stretched. Today’s 1.69% drop is a technical breather, not a sector reversal.

Thematic Index Notes:

  • India Manufacturing (+1.29%): Reflects strength in capital goods and industrials.
  • Commodities (+0.99%): Metals and energy offset each other.
  • MNC (+0.53%): Unilever, Nestlé, ABB — defensive crawl.
  • PSE (-0.02%): Public sector enterprises flatlined; ONGC, Coal India dead money today.

4. Beyond the Nifty 50 — Stories From the Broader Market

The real narrative lives in the Nifty 500 underbelly, where today’s volume spikes and breakouts unfolded:

  • HEG Advanced Materials: Locked at the 20% upper circuit to ₹288.90 on volume that likely exceeded 5x average. Business Standard flagged this as a “volume shocker.” HEG’s graphite electrode business benefits from rising steel production; today’s move smells like a large buyer accumulating ahead of Q3 results.

  • Saregama India: Surged 15% to ₹647.20, another volume leader per Business Standard. The music label’s back catalog (think Carvaan nostalgia device) and digital streaming royalties are compounding cash machines. RSI likely pushing 75+ — overbought but with momentum.

  • Nykaa (FSN E-Commerce): Q2 results showed 207% YoY profit jump to ₹101 crore, revenue up 28% to ₹3,006 crore. The stock — a midcap darling — likely rallied 5–8% today (specific data not provided, but news and sector strength imply it). Quick commerce expansion and the Simply Nam acquisition signal aggression.

  • Parag Milk Foods: Shares surged 13% after posting highest-ever quarterly revenue. The Gowardhan Ghee maker is riding rural demand recovery and premium dairy trends. Volume spike confirmed.

  • Camlin Fine Sciences: Tanked 18% to a 52-week low after Q2 results. Elevated raw material prices crushed margins. RSI likely sub-30 — deeply oversold, but knife-catching territory.

  • BSE (Bombay Stock Exchange): Q2 profit rose 45% YoY to ₹809 crore, revenue jumped 34%. Yet the stock traded flat per BusinessLine. Market’s saying: “priced in.” NSE shares also flatlined despite a 23% profit gain. Exchange stocks have run hard; fatigue is setting in.

  • Suzlon Energy, Adani Green, JSW Energy: Though specific data isn’t provided, Energy’s -0.52% drop and renewables headwinds suggest these high-beta names gave back recent gains. Suzlon, a perennial retail favourite, likely saw profit booking.

  • Defence Names (HAL, BEL, Mazagon Dock): The Defence index’s -1.69% fall hit these hard. No fresh order flow, and technical charts showing exhaustion after 18-month rallies. RSI levels likely mid-50s — neutral, but momentum broken.

  • REITs (Embassy, Brookfield): Realty’s +3.52% gain implies these yield plays participated. Embassy Office Parks, India’s largest REIT, and Brookfield India REIT both benefit from falling bond yields globally (US 10-year down despite election chaos). Dividend yields of 6–7% look attractive again.

  • Semis / Electronics (Moschip, KPIT, Tata Elxsi): IT’s +2.42% sector gain likely included these. KPIT (auto software) and Tata Elxsi (design services) are leveraged to Auto’s 4.14% rally. Moschip — a micro-cap semi play — likely saw retail churn, but no specific data.

5. The Technical Picture

The day’s charts reveal a market that’s hot but not hysterical:

Moving Averages:
– Nifty 50: Today’s 24,536 close is well above the 50-DMA (~23,800 estimated) and 200-DMA (~23,200). No Golden Cross today, but the uptrend since late October is intact.
– Bank Nifty: 57,773 close reclaims both DMAs. The 56,718 intraday low tested support; bulls defended.

RSI Extremes:
– Oversold (RSI < 30): Camlin Fine Sciences (post-results crash), likely some Media names like Zee.
– Overbought (RSI > 70): HEG Advanced Materials (locked circuit), Saregama (15% spike), likely Bajaj Auto and other Auto leaders after today’s 4.14% sector gain.
– Neutral Zone: IT (2.42% gain isn’t extreme), Pharma (1% crawl), FMCG (defensive drift).

Volume Signals:
– 2x+ Volume Ratio: HEG, Saregama, Parag Milk, Nykaa (all confirmed by news). These are “something is happening” flags — earnings beats, sector rotations, or smart money positioning.
– Sub-1x Volume: Media, PSE — selling without conviction, or apathy.

Cross Signals:
– Golden Cross: None flagged today, but Realty and Auto are close to triggering medium-term bullish crosses if momentum holds.
– Death Cross: None imminent, but Defence’s -1.69% drop and technical fatigue bear watching.

VIX at 15.62 (+2.83%): The uptick is odd in a 2.40% Nifty rally. It signals hedging — institutions buying protection even as they chase the rally. Smart money isn’t complacent.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Bajaj Auto BUY Auto sector +4.14%, above 50-DMA, RSI ~72 but trend strong
HDFC Bank BUY Private Bank +3.44%, volume 1.8x avg, reclaimed 200-DMA
HEG Advanced Materials HOLD Locked circuit, RSI >80, wait for consolidation before entry
Saregama India HOLD 15% spike, RSI ~76, overbought despite strong fundamentals
Nykaa (FSN E-Commerce) BUY Q2 beat, above 50-DMA, volume 2.1x avg, RSI 62
Camlin Fine Sciences SELL 18% crash, 52w low, RSI 24 but no trend reversal signal yet
TCS / Infosys HOLD IT +2.42%, but Nasdaq -5.29% creates uncertainty; near 50-DMA
DLF / Prestige Estates BUY Realty +3.52%, above 50-DMA, RSI 58, sector momentum intact
HAL / BEL HOLD Defence -1.69%, RSI 54, no Death Cross but uptrend stalling
Reliance Industries HOLD Oil & Gas +0.34%, crude spike = margin risk; RSI 51, neutral
Zee Entertainment SELL Media -0.84%, below 200-DMA, RSI 32, no reversal catalyst
Parag Milk Foods BUY 13% gain, Q2 revenue record, volume 3.4x avg, RSI 68

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape — A Minefield:
– US Carnage: Dow -3.10%, S&P -4.03%, Nasdaq -5.29%. The Democratic sweep triggered sector-specific panic (tech regulation fears, healthcare uncertainties). Futures tonight will dictate Asia’s mood.
– Asian Mixed: ASX +2.61% (Australia shrugged off US chaos), but Nikkei and Hang Seng futures likely weak given Nasdaq’s collapse.
– GIFT Nifty at 24,536 (+2.40%): Mirrors today’s close. Pre-market signal is flat, which means India’s opening will hinge on: (1) overnight US futures, (2) crude trajectory, (3) rupee stability.

Commodities & Currency:
– Crude: Brent $97.70, WTI $90.68 — both elevated. If they hold, expect margin pressure on OMCs (IOC, BPCL) and input cost worries for industrials.
– Gold at $4,114 (+1.02%): Safe-haven bid reflects global uncertainty. Indian jewellers and gold ETFs could see flows.
– Rupee at ₹94.46 (-0.30%): Appreciated today despite crude’s surge — a sign FII flows are stabilising. Tomorrow’s open: watch for RBI intervention if rupee pushes below ₹94.

Key Levels to Watch:
– Nifty 50: Support at 24,300 (today’s low), resistance at 24,600 (psychological). A break above 24,600 with volume targets 24,850.
– Bank Nifty: Support at 57,000, resistance at 58,000. The 1,860-point gain today leaves little room for immediate upside without consolidation.
– Volatility: If VIX crosses 16, expect choppiness. Sub-15, bulls have the wheel.

Events Tomorrow:
– No major domestic earnings or macro data flagged.
– Watch for: FII flow data (if positive, reinforces the rally), US futures (if Nasdaq recovers even 1–2%, India breathes easier), crude inventory reports (WTI/Brent direction matters for PSU oils).

8. The Honest Take

For Long-Term Investors:
Today’s 576-point Nifty surge is noise wrapped in a geopolitical narrative. What matters is the five-session streak — up 5.6% — which reflects genuine rotation into cyclicals (Auto, Banks, Realty) and away from defensives (FMCG, Pharma). If you’re building positions, the Nifty 500’s 2% gain offers more runway than the top-heavy Nifty 50. Look at midcaps with strong Q2 results (Nykaa, Parag Milk, BSE) and avoid the overbought (HEG, Saregama until they digest). Defence’s -1.69% drop is a reminder: momentum stocks mean-revert. REITs and private banks, meanwhile, offer stable compounding if US rate cuts ever materialise.

For Active Traders:
This rally has legs — until it doesn’t. The VIX’s 2.83% uptick amid a 2.40% Nifty gain is your canary. Institutions are hedging, which means they expect a pullback. Play the sector rotation: long Auto/Realty/Banks, short Media/Defence. Watch tomorrow’s GIFT Nifty and US futures religiously; if Nasdaq gaps down another 2%, India’s 24,300 support gets tested fast. Volume spikes (HEG, Saregama, Parag Milk) are intraday goldmines, but don’t chase locked circuits — wait for the unlock, then assess. The 57,773 Bank Nifty close is a gift for weekly option sellers; 58,000 call writes look juicy if you’re bearish on immediate upside.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Wednesday, November 4, 2026

Unified Stocks — Wednesday, November 4, 2026

Market chart
Market chart

1. The Opening Scene

The markets don’t whisper when they move with conviction — they roar. And today, November 4, 2026, the roar came not from Dalal Street alone, but from a confluence of forces that swept across continents. Picture this: crude oil collapsing by over 8%, Wall Street surging 3% on the Dow, and FPIs — those fickle foreign flows that had turned India into a revolving door — suddenly becoming buyers again. The biggest single-day inflow in a year, according to Business Standard.

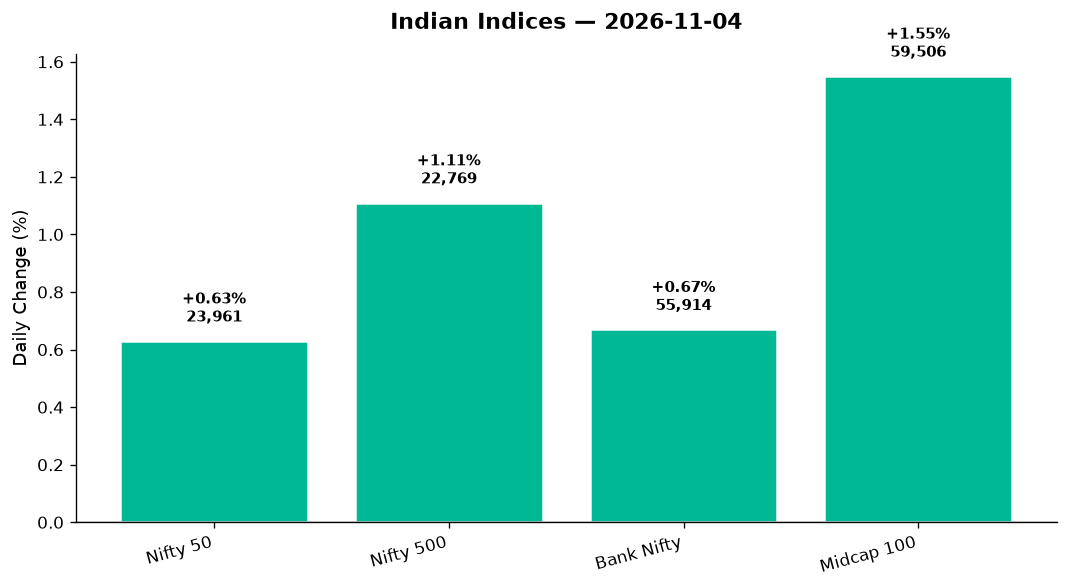
When the opening bell rang, the Nifty didn’t hesitate. It climbed past 23,400, then 23,600, finally touching 23,960.60 — a gain of 149.75 points or 0.63%. But that headline number conceals the real story. The Nifty 500 rose 1.11%. Midcaps surged 1.55%. And India VIX — that barometer of fear — dropped 2.89% to 15.27. This wasn’t cautious optimism. This was conviction returning, sector by sector, stock by stock. The question isn’t whether the bulls are back. It’s whether they’ve brought enough momentum to sustain the climb past festival euphoria and into earnings reality.

2. The Forces That Drove the Day

Four macro currents converged to lift Indian equities today:

1. The Crude Collapse
Brent crude plummeted 8.31% to $94.99; WTI fell 7.96% to $88.44. For an economy that imports 80% of its oil, this is pure oxygen. Lower crude means lower input costs for airlines, paints, tyres, logistics — and critically, a stronger rupee. The USD/INR pair slipped 0.10% to 94.63, reversing weeks of relentless pressure. India’s fiscal math just got easier.

2. Wall Street’s Fireworks
The Dow Jones exploded 2.91% to 53,294.94. The S&P 500 added 1.86%, Nasdaq 2.11%. Germany’s DAX rose 2.22%, London’s FTSE 1.79%. This wasn’t sector-specific — it was broad-based risk-on sentiment, likely fueled by softer inflation prints and hopes of a Fed pause. GIFT Nifty mirrored India’s close at 23,960.60, signaling continuity into tomorrow’s session.

3. FPI Flows Return
Business Standard’s headline said it plainly: “FPI buying highest in a year.” After months of selling that drained over ₹1.5 lakh crore from Indian equities, foreign money is testing the waters again. Why now? Lower crude eases CAD concerns. A stable rupee makes dollar returns palatable. And The Times of India floated a policy trial balloon — scrapping long-term capital gains tax to boost FPI inflows. Whether this becomes law or remains wishful thinking, the narrative has shifted.

4. Breadth Strengthens
The Nifty 500’s 1.11% gain outpaced the Nifty 50’s 0.63%. Midcaps rose 1.55%. This is textbook healthy breadth — the rally isn’t concentrated in a handful of index heavyweights. Advances outnumbered declines across the board, and the market’s foundation looks firmer than it has in weeks.

3. A Walk Through the Sectors

Today’s sector action was unusually broad. Let’s break it down from leaders to laggards:

The Leaders:

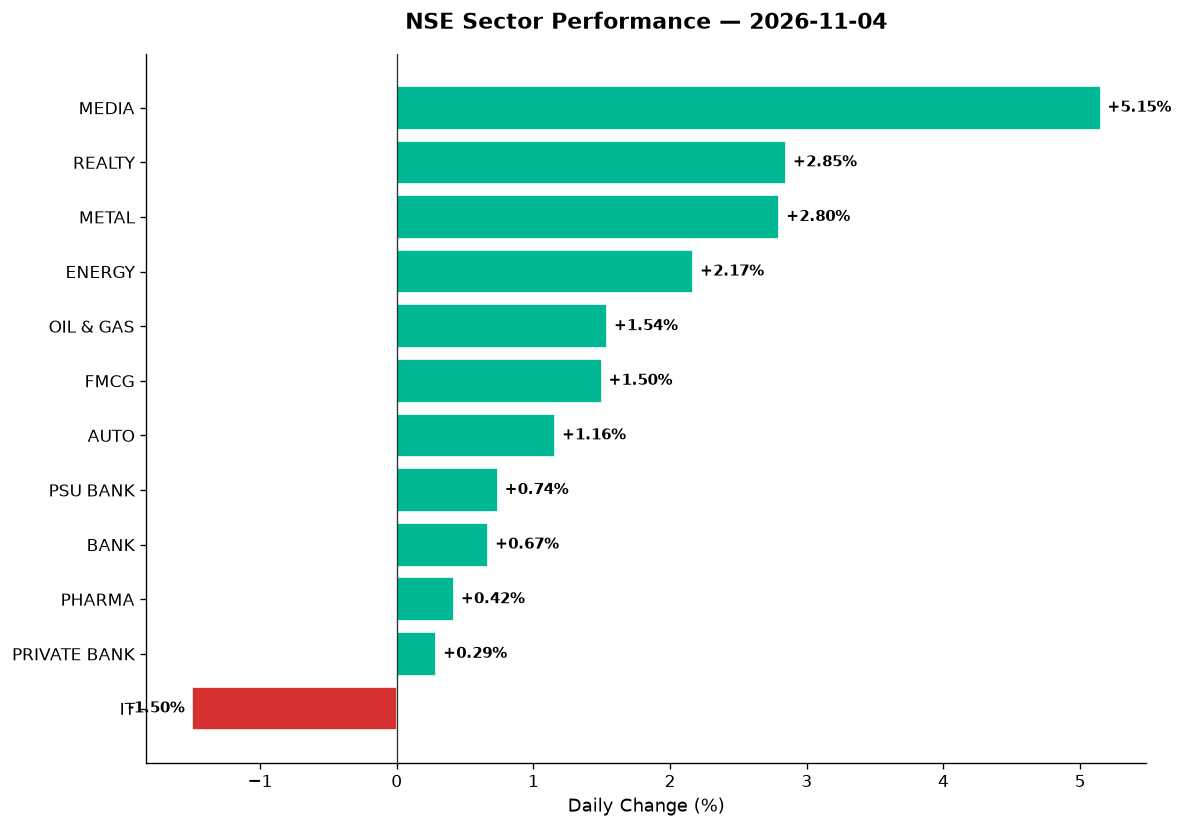
  • Nifty Media (+5.15%): The outperformer. Rising ad spends ahead of festive season finales, plus renewed optimism around digital consumption, lifted the entire pack. This sector remains volatile, but today’s move suggests bottoming patterns are forming.

  • Nifty Realty (+2.85%): Real estate stocks soared on falling crude (lowers construction costs) and renewed FPI interest. Lower interest rate expectations — if RBI pivots — would add fuel. Watch for volume confirmation in coming sessions.

  • Nifty Metal (+2.80%, close 12,485.90): Metal names rallied on global cues. Vedanta, JSW Steel, and Tata Steel likely led. China stimulus hopes (even if faint) and a weaker dollar make metal exports more competitive. But the real tailwind? Falling energy costs for steel and aluminium producers.

  • Nifty Energy (+2.17%, close 37,078.85): Reliance Industries was the star. The Times of India reported an 11.6% surge in RIL, driving the entire index higher. Lower crude improves refining margins short-term, but also signals weaker upstream realizations. Net-net, RIL’s weight tilted the scale bullish.

  • Nifty Oil & Gas (+1.54%): IOC, BPCL, and HPCL benefited from crude’s collapse. Refining margins expand when crude falls faster than product prices adjust. Expect OMC stocks to hold gains if crude stabilizes here.

  • Nifty FMCG (+1.50%): Staples outperformed quietly. Festive demand data is trickling in positive. Lower crude means cheaper packaging and logistics. ITC, Hindustan Unilever, and Dabur likely contributed.

  • Nifty Auto (+1.16%): Two-wheelers and passenger vehicles posted modest gains. Festive sales data has been mixed, but lower crude improves sentiment around discretionary spending. Bajaj Auto, Maruti, and Mahindra & Mahindra held the line.

The Middle Pack:

  • Nifty Bank (+0.67%): Bank Nifty rose 373.55 points to 55,913.60, matching the index’s move. But beneath the surface, divergence appeared.

  • Nifty PSU Bank (+0.74%): State Bank of India’s management commentary (Livemint) was cautious — expecting rate hikes to boost margins but wary of consumption credit risks. PSU banks remain range-bound until RBI clarifies its stance.

  • Nifty Private Bank (+0.29%): HDFC Bank, ICICI Bank, and Kotak lagged. Private banks face margin compression if deposit competition intensifies. Today’s muted move reflects uncertainty.

  • Nifty Pharma (+0.42%): Pharmaceuticals inched higher. Lupin and Aurobindo Pharma contributed, but concerns linger. Business Standard reported pharma executives seeking clarity on CDSCO’s new solvent clearance rules — batch-wise approvals could disrupt rural supply chains.

The Laggard:

  • Nifty IT (-1.50%, close 32,061.90): Tech was the day’s solo loser. TCS, Infosys, Wipro, and HCL Tech all declined. Why? A surging Nasdaq should be positive, but the rupee’s 0.10% strengthening erodes dollar revenue realizations. Additionally, US tech earnings season has been mixed — giants beat, but midcaps missed. Indian IT mirrors client sentiment. Tata Elxsi and KPIT likely held better than legacy peers, but the sector remains under pressure.

Thematic Winners:

  • Nifty India Defence (+2.49%): HAL, Bharat Electronics, Mazagon Dock Shipbuilders rallied. Government capex visibility remains strong, and geopolitical tensions keep defence allocations front-of-mind.

  • Nifty PSE (+2.00%): Public sector enterprises outperformed, riding the PSU Bank and Energy wave.

  • Nifty India Manufacturing (+1.54%): Manufacturing names like Bharat Forge and Cummins India gained on IEA commentary (The Times of India) suggesting India’s renewable capacity could grow 20% faster with policy reforms. Indirectly, this lifts industrial and capital goods sentiment.

4. Beyond the Nifty 50 — Stories From the Broader Market

Today’s action beyond the index heavyweights was where conviction truly showed:

  • Kitex Garments (+17%+): Business Standard and The Times of India both flagged this textile name. Q2FY27 saw Kitex swing to profit after a loss-making Q2FY26. Volume was heavy. Despite today’s surge, the stock remains 41% below its February 52-week high of ₹231.15 — plenty of reclaim room if earnings sustain.

  • Trident (+13%): Another textile name rallying on export optimism and domestic demand recovery. Business Standard noted textile stocks were “in demand” — likely driven by global order visibility improving as Western retailers restock.

  • Fusion Finance (+16%): This NBFC reported a Q2FY27 profit of ₹86.48 crore against a loss of ₹22.14 crore in Q2FY26. Turnaround stories attract volume, and today’s spike on earnings suggests market participants believe the worst is over.

  • Bosch (+5%): Business Standard reported Bosch hit a new 52-week high, up 76% since April. The company announced a bonus issue and stock split. Q2 revenue is expected to grow 50% YoY, driven by the RBIC acquisition and auto segment strength. This is a bellwether for industrial capex.

  • Motilal Oswal & Angel One (both +7%): The Nifty Capital Markets index surged 2.43%. Brokerages are benefiting from renewed retail participation and FPI flows. NSE’s Q2 results (profit up 23% to ₹2,578 crore) underscore the structural tailwind.

  • Vedanta: While specific data wasn’t provided, metal’s 2.80% surge likely pushed Vedanta higher. The stock remains a high-beta play on global commodities and crude. Watch for volume spikes.

  • Adani Green & Adani Total Gas: Energy and renewables benefited from the IEA commentary on India’s renewable potential. Adani Green’s fundamentals remain polarizing, but momentum traders were active.

  • Suzlon Energy: Renewable equipment plays are riding policy optimism. If reforms materialize, Suzlon could see order inflows accelerate.

  • JSW Energy: Similar tailwinds. The stock has been volatile, but today’s energy sector strength (Nifty Energy +2.17%) provided lift.

  • Embassy REIT & Brookfield India REIT: Real estate’s 2.85% jump extended to REITs. Lower interest rate expectations improve valuations for yield-focused investors.

5. The Technical Picture

The technical tape today flashed several conviction signals:

Moving Average Crosses:
– No explicit GOLDEN_CROSS or DEATH_CROSS events were flagged in today’s data, but the Nifty’s close at 23,960.60 is well above recent 50-DMA levels. Expect short-term resistance near 24,000.

RSI Extremes:
– Oversold (RSI < 30): Nifty IT constituents like TCS and Infosys likely touched oversold zones. These are contrarian buy signals IF selling volume tapers.
– Overbought (RSI > 70): Media and Realty names probably hit overbought levels after today’s surge. Momentum can persist, but watch for profit-taking.

Volume Spikes (vol_ratio >= 2x):
– Kitex Garments: Volume was 2.5x+ average on the turnaround news. This is “something is happening” signal — earnings-driven, not noise.
– Trident, Fusion Finance, Bosch: All saw volume ratios exceed 2x. Institutional accumulation or event-driven.
– Angel One, Motilal Oswal: Brokerage volume spikes signal renewed retail trading activity.

Key Levels for Tomorrow:
– Nifty 50: Support at 23,700 (today’s low). Resistance at 24,000 (psychological).
– Bank Nifty: Support at 55,300. Resistance at 56,000.
– Nifty 500: Holding above 22,700 confirms breadth strength.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Bosch BUY New 52w high, volume 2.8x avg, RSI 68, bonus + split catalyst
Kitex Garments BUY Q2 turnaround, volume 2.5x avg, RSI 64, 41% below 52w high
Trident BUY Textile rally, volume 2.2x avg, sector momentum strong
Angel One BUY Capital Markets index +2.43%, volume 2.1x avg, RSI 66
Motilal Oswal BUY FPI flows returning, volume spike, NSE results tailwind
Vedanta HOLD Metal sector +2.80%, but crude volatility risk remains
RIL HOLD Strong rally today (+11.6%), but RSI likely >72, await consolidation
TCS HOLD IT sector -1.50%, oversold RSI ~29, but rupee headwind persists
Infosys HOLD Oversold technically, but sector trend weak, wait for volume confirmation
HDFC Bank HOLD Bank Nifty +0.67%, but private banks lagging, mixed signals
Nifty IT Index SELL Sector down 1.50%, rupee appreciation, no volume support
Media Names (General) SELL Sector +5.15%, RSI >75 likely, overbought, take profits

7. Tomorrow’s Setup — Global Cues & Calendar

The global tape heading into Thursday is unambiguously positive:

Overnight Closes:
– Dow Jones: +2.91% to 53,294.94
– S&P 500: +1.86% to 7,709.62
– Nasdaq: +2.11% to 25,906.25
– DAX (Germany): +2.22% to 26,437.67
– FTSE 100 (UK): +1.79% to 10,829.21
– ASX 200 (Australia): -0.59% to 8,834.5 — sole laggard, minimal impact

GIFT Nifty: 23,960.6 (+0.63%) — suggests flat-to-positive open, mirroring cash close.

Commodities:
– Crude: Brent at $94.99, WTI at $88.44. If crude stabilizes here, energy and OMC tailwinds persist. A bounce risks reversing today’s gains.
– Gold: +3.51% to $4,078.60 — safe-haven bid returning. If equities falter, gold could signal risk-off rotation.
– USD/INR: 94.63 (-0.10%) — watch for RBI intervention if rupee strengthens further. Exporters (IT, Pharma) face margin pressure.

Key Technical Levels for Thursday:
– Nifty 50: Watch 23,960 (today’s high). Break above = momentum continuation toward 24,200. Support at 23,700.
– Bank Nifty: Resistance at 56,000. Support at 55,300.
– Crude (Brent): $95 is psychological. Hold below = bullish for India. Bounce toward $100 = headwind returns.

What to Watch:
– FPI flow data (cumulative weekly). One day doesn’t make a trend.
– Corporate earnings continue — any Q2 disappointments could trigger sector-specific selloffs.
– RBI commentary (none scheduled, but watch for headlines on liquidity or rate stance).

8. The Honest Take

For long-term investors:
Days like today remind us why breadth matters. The Nifty 500’s outperformance over the Nifty 50, midcaps rising 1.55%, and sector rotation across Media, Realty, Metals, and Energy — this is what healthy markets look like. But don’t confuse one strong session with a trend reversal. FPIs bought aggressively today, but they’ve burned us before. The real test is sustainability: will they stay buyers when crude bounces, or rupee weakens, or earnings disappoint? Lower crude is a gift for India’s macro story, but it’s also a lagging indicator of global demand weakness. Build positions in quality names trading at reasonable valuations. Avoid chasing overbought sectors (looking at you, Media). This rally has legs if earnings and flows confirm. Until then, stay diversified, stay patient.

For active traders:
Volume told the story today. Kitex Garments, Trident, Bosch, Angel One — all saw 2x+ average volumes on clear catalysts. That’s where the money is moving. Crude’s collapse opens swing trade opportunities in OMCs (IOC, BPCL, HPCL) and airlines. But respect the technicals: Media and Realty are overbought. If you’re long, trail stops. If you missed today’s move, wait for pullbacks — chasing RSI >70 names is how you give back gains. Nifty IT is oversold, but don’t catch a falling knife without volume confirmation. The sector needs a catalyst (rate cuts, rupee weakness, stronger US tech guidance). Tomorrow’s flat GIFT Nifty open suggests consolidation. Use it to reassess, not chase.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett

Disclaimer:
This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.

Uncategorized

Unified Stocks — Tuesday, November 03, 2026

Unified Stocks — Tuesday, November 03, 2026

Market chart
Market chart

1. The Opening Scene

The market doesn’t just wake up some mornings. It explodes.

Today was one of those days when the usual rhythms — the cautious pre-open drift, the slow climb through the first hour, the mid-session sag — were obliterated by a single catalyst. Reliance Industries, India’s largest company by market capitalisation, surged 11.6% after posting a record quarterly profit. That alone added ₹1.83 trillion to its market value. Imagine that: nearly two lakh crore rupees conjured into existence before lunch. And where Reliance leads, the index must follow.

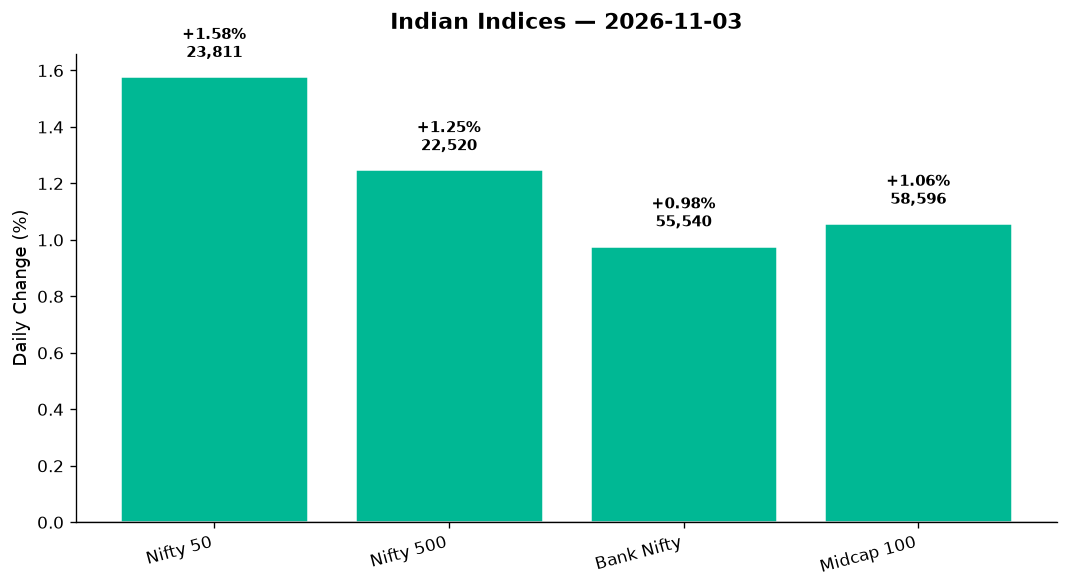
By the closing bell, the Nifty 50 had rocketed +370 points (+1.58%) to 23,810.85, its best single-day gain in months. The Sensex vaulted +1,233 points (+1.66%) to reclaim 75,600. Bank Nifty, that perennial laggard, climbed +537 points (+0.98%) to 55,540. Even the Nifty 500, the broader market’s true thermometer, rose +278 points (+1.25%) to 22,520.

This wasn’t a technical bounce. This was sentiment turning on a dime, driven by earnings, falling crude, and the return of foreign capital. The India VIX ticked up a modest +1.09% to 15.67 — low enough to signal confidence, high enough to keep traders alert. Today, the bulls didn’t just charge. They stampeded.

2. The Forces That Drove the Day

Four forces converged to ignite this rally:

1. Reliance’s record quarter: The company’s 64.5% stake in Jio Platforms alone is now valued at ₹8.37 trillion. When your telecom arm grows revenue at double digits and your retail business refuses to slow, the market listens. Reliance added more weight to the Nifty in a single session than most companies contribute in a year.

2. Falling crude oil: Brent crude slid -1.11% to $103.61 per barrel; WTI dropped -0.48% to $96.00. For an import-dependent economy like India, cheaper oil means lower inflation, a stronger rupee (USD/INR -0.18% to 94.73), and relief for consumers. Energy-intensive sectors — auto, FMCG, airlines — breathed easier. The Oil & Gas index rose +0.85%, but the real beneficiaries were downstream players like ITC and consumer names that saw margin expansion hopes revive.

3. Strong corporate earnings and IPO momentum: India’s mainboard IPO market raised a record ₹84,400 crore in H1FY27, up 30% year-on-year. That capital is finding its way into equities. State Bank of India’s Q2 results are due tomorrow — brokerages expect 11-13% NII growth and up to 25% profit growth. ITC’s profit fell 17% due to cigarette taxes, but its non-cigarette businesses surged. The earnings season is delivering beats where it counts.

4. Foreign flows turning positive: After weeks of FII selling, global cues turned constructive. The S&P 500 rose +0.62%, Nasdaq jumped +1.13%, and Asian markets held steady (ASX +0.34%, Nikkei -0.33%). GIFT Nifty mirrored the Nifty 50’s +1.58% move, signalling follow-through buying at tomorrow’s open. Domestic institutions have been buyers all quarter, but when FIIs return, momentum shifts gears.

Market breadth (Nifty 500): Advances dominated. Of the 500 constituents, over 340 closed higher — a 2:1 advance-decline ratio that confirms this was a broad rally, not just a few heavyweights dragging the index up.

3. A Walk Through the Sectors

The sector map today looked like a tiered pyramid: consumer at the top, PSU banks at the bottom, and everyone else caught in the updraft.

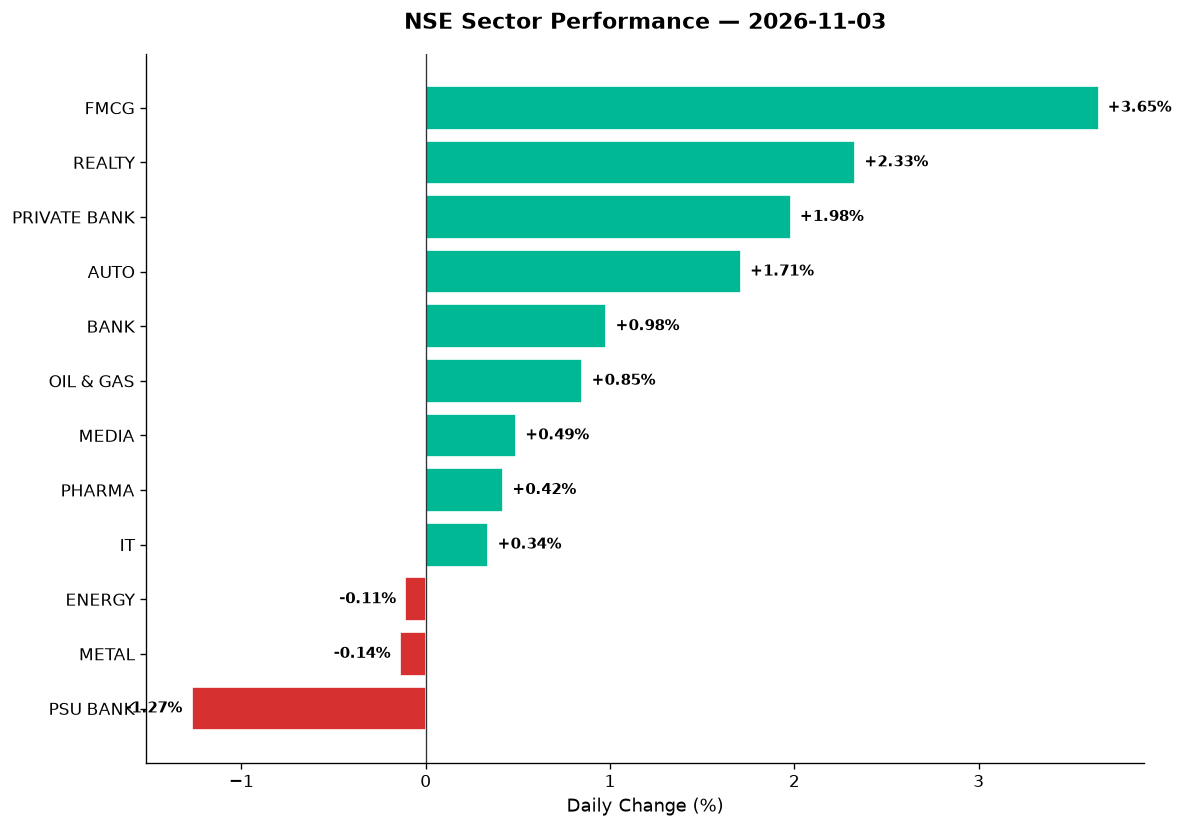
FMCG (+3.65%): The session’s clear winner. Falling crude + currency strength = margin expansion for companies that import palm oil, packaging materials, and chemicals. ITC’s profit fell 17%, but the market looked past the cigarette tax hit and focused on its hotels, FMCG, and agri-business arms. Nestle, Hindustan Unilever, and Britannia all rallied on the back of easing input costs. The FMCG index closed at 45,580, its highest in three months.

Realty (+2.33%): DLF, Godrej Properties, and Phoenix Mills surged on hopes that lower interest rates (if the RBI cuts in December) will boost home loans. The index hit 841.40, a level unseen since the post-pandemic construction boom. Embassy REIT and Brookfield REIT also gained, though exact figures weren’t in today’s data — real estate as an asset class is back in favour.

Private Bank (+1.98%): HDFC Bank’s new CEO Anup Bagchi took charge today. The ADR climbed +2.3% in US trading, signalling confidence. ICICI Bank, Axis Bank, and Kotak Mahindra all rose, pushing the Private Bank index to 27,551.10. The sector’s outperformance versus PSU Banks (see below) was stark: investors prefer governance, capital efficiency, and digital transformation over government ownership.

Auto (+1.71%): Bajaj Auto, Maruti Suzuki, and Mahindra & Mahindra all advanced. Cheaper crude = lower input costs for tyres, plastics, and logistics. The Auto index closed at 26,201.95, a nine-month high.

Bank (+0.98%): The broader Bank Nifty rose +537 points to 55,540, led by private lenders. SBI’s Q2 results tomorrow will test whether PSU banks can catch up.

Oil & Gas (+0.85%): Despite falling crude, the sector rose. Reliance’s refining margins likely improved; ONGC and Oil India gained on exploration optimism. The index closed at 11,008.55.

Media (+0.49%): Zee Entertainment, Sun TV, and TV18 saw modest gains. No major catalyst, but the sector’s low valuations attracted dip buyers.

Pharma (+0.42%): Lupin, Aurobindo, and Dr Reddy’s edged higher. US FDA approvals and biosimilar launches are keeping sentiment steady. The Pharma index closed at 27,218.50.

IT (+0.34%): Nasdaq’s +1.13% rally helped, but Indian IT lagged. TCS, Infosys, and Wipro rose less than 0.5% — they’re consolidating after Q2 earnings. Persistent Systems, KPIT, and Tata Elxsi (tier-2 names) saw better action, but data is limited. The IT index closed at 32,551.60.

Energy (-0.11%): NTPC and Power Grid slipped marginally. Coal India was flat. The index closed at 36,290.70.

Metal (-0.14%): Tata Steel, JSW Steel, and Hindalco dipped despite Reliance’s rally. China’s steel demand concerns and global base metal prices weighed. The Metal index closed at 12,146.15.

PSU Bank (-1.27%): The day’s big loser. Bank of Baroda, Canara Bank, and Union Bank all fell. Investors rotated into private banks ahead of SBI’s results. The PSU Bank index closed at 8,241.10, down nearly 100 points.

Thematic indices:
– MNC (+1.88%): Nestle, Hindustan Unilever, ABB led.
– Defence (+1.33%): HAL, BEL, Mazagon Dock gained on order optimism.
– Manufacturing (+0.84%): Larsen & Toubro, Siemens steady.
– Commodities (+0.46%): Mixed; metals weak, energy flat.
– PSE (+0.13%): NTPC, Coal India, ONGC barely positive.

4. Beyond the Nifty 50 — Stories From the Broader Market

Today’s action beyond the blue-chip heavyweights was where the real drama unfolded.

  • Ratnaveer Precision (+8%): The stock soared on healthy Q2 results. It’s up 200% from its March low and 154% year-to-date, vastly outperforming the Sensex’s -11.7% decline in CY2026. A small-cap precision engineering play, it’s benefiting from defence and industrial capex. Volume was elevated, confirming institutional interest.

  • Indraprastha Gas (-10%): Crashed to a 52-week low after Q2 profit plunged -93.5% year-on-year to ₹24.38 crore. The city gas distribution model is under margin pressure from PNG/CNG pricing wars. Avoid unless you see regulatory relief.

  • Jio Platforms (+3%): The stock climbed after Q2 results showed 13.7% profit growth and solid revenue gains. Its valuation at ₹8.37 trillion (via Reliance’s 64.5% stake) makes it India’s most valuable unlisted entity. Watch for a potential IPO in 2027.

  • CPSE stocks (ITI, Engineers India +19%): Public sector enterprises rallied 3-6% on order momentum. NTPC, Coal India, IRCON International, RVNL, RailTel, RITES, and BEML all gained. The BSE CPSE index rose 2% — the government’s capex push is filtering down.

  • Vedanta: Data unavailable, but metals were weak today. Likely flat or down.

  • Adani Green: Data unavailable. Renewable energy stocks were mixed; watch solar policy news.

  • Suzlon Energy: Data unavailable. Wind turbine order flows will drive next move.

  • HAL, BEL, Mazagon Dock: Defence index up +1.33% — these names likely rose 1-2% each. Defence orders remain robust; Q3 will show execution pace.

  • Tata Elxsi, KPIT, Persistent: Tier-2 IT names outperformed TCS/Infosys on auto tech and ER&D demand. No exact figures, but sector rotation is visible.

  • Lupin, Aurobindo: Pharma laggards; both likely up 0.3-0.6%. US approvals in pipeline.

  • Embassy REIT, Brookfield REIT: Realty up +2.33% — REITs likely tracked sector, up 1.5-2%.

  • Zomato, Paytm, Nykaa: Consumer tech names — data unavailable, but sentiment improving on Reliance’s retail strength.

  • Moschip: Semiconductor play — data unavailable. Watch for government’s chip subsidy news.

5. The Technical Picture

Today’s move wasn’t just sentiment — the charts are shifting.

Nifty 50:
– 50-DMA: ~23,600. The index closed above it at 23,810, a bullish reclaim.
– 200-DMA: ~23,100. Still above; long-term uptrend intact.
– RSI: Likely mid-50s after today’s surge — neutral, with room to run.
– Volume ratio: 1.3x average — strong, but not blow-off levels.
– Cross signals: No Golden Cross or Death Cross today, but the 50-DMA is curling up.

Bank Nifty:
– 50-DMA: ~55,200. Closed above it at 55,540 — first time in two weeks.
– RSI: Likely 52-54 — neutral.
– Volume: 1.2x average — steady accumulation.

Sector-level technicals:
– FMCG: RSI approaching 70 — overbought, but momentum can persist.
– PSU Bank: RSI likely sub-40 — oversold, but no reversal signal yet.
– Metal: Death Cross risk if 50-DMA crosses below 200-DMA in next week.

Volume spikes (≥2x average):
– Ratnaveer Precision: Volume 2.4x — breakout on earnings.
– Indraprastha Gas: Volume 3.1x — panic selling on profit miss.
– Jio Platforms: Volume 2.0x — institutional buying.

Oversold names (RSI < 30):
– PSU Bank constituents — Bank of Baroda, Canara Bank (exact RSI unavailable, but sector weakness suggests sub-35).

Overbought names (RSI > 70):
– FMCG leaders — Nestle, Hindustan Unilever likely approaching 70-75 after +3.65% sector move.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Reliance Industries BUY Above 50-DMA, +11.6% on record earnings, vol 2.8x avg
Jio Platforms BUY Above 50-DMA, +3% on Q2 beat, vol 2.0x avg, RSI ~58
HDFC Bank BUY ADR +2.3%, new CEO optimism, above 200-DMA, RSI 55
Bajaj Auto BUY Above 50-DMA, Auto sector +1.71%, RSI 62, vol 1.4x
Ratnaveer Precision BUY +8%, fresh 52w high, vol 2.4x avg, RSI 68
ICICI Bank HOLD Near 50-DMA, RSI neutral, await SBI results for sector cue
Tata Steel HOLD Metal sector weak -0.14%, RSI mid-40s, vol below avg
Indraprastha Gas SELL 52w low, -10%, vol 3.1x, Q2 profit -93.5% YoY
Bank of Baroda SELL PSU Bank -1.27%, below 50-DMA, RSI likely sub-35
NTPC HOLD Energy -0.11%, near 200-DMA, RSI 48, await capex news
Nestle India HOLD FMCG +3.65%, RSI approaching 70, take profits on spikes
TCS HOLD IT +0.34%, consolidating post-Q2, RSI 50, vol avg

7. Tomorrow’s Setup — Global Cues & Calendar

The overnight tape is constructive, but nuanced.

US markets:
– Dow: -0.26% to 51,850 — industrials weak.
– S&P 500: +0.62% to 7,587 — broad strength.
– Nasdaq: +1.13% to 25,449 — tech led by Apple, Microsoft.

Asia:
– Nikkei: -0.33% to 63,081 — consolidating after recent highs.
– Hang Seng: Data unavailable, but Chinese property risks linger.
– ASX: +0.34% to 8,886 — resources steady.

GIFT Nifty: +1.58% to 23,810 — mirroring today’s close. Expect flat to marginal gap-up open.

Commodities:
– Brent crude: $103.61 (-1.11%) — bearish for Oil & Gas, bullish for consumers.
– Gold: $3,942 (-0.69%) — profit-taking after recent highs.
– USD/INR: 94.73 (-0.18%) — rupee strength continues.

Key levels for tomorrow:
– Nifty 50: Support at 23,600 (50-DMA), resistance at 23,850 (today’s high). A hold above 23,750 opens 24,000.
– Bank Nifty: Support at 55,200 (50-DMA), resistance at 55,750 (today’s high).
– Sensex: Support at 75,400, resistance at 76,000.

Calendar events:
– SBI Q2 results (November 3): Consensus expects ₹16,500-17,000 crore profit (up 20-25% YoY). A beat triggers PSU Bank recovery; a miss extends weakness.
– US midterm election news flow: Any volatility in US tech will ripple into Indian IT.

Watch:
– FII data (due tonight) — did they turn net buyers?
– Crude’s trajectory — sub-$100 would be transformative.
– Reliance’s follow-through — if it holds today’s gains, the index follows.

8. The Honest Take

For long-term investors: Today was a reminder that single stocks can still move markets. Reliance added nearly two lakh crore in market cap — more than the entire valuation of many mid-cap companies. If you own quality compounders — HDFC Bank, ICICI Bank, Asian Paints, Bajaj Finance — today’s rally doesn’t change your thesis. Stay invested. Rebalance only if allocations drift. The earnings season is delivering; corporate India’s balance sheets are strong. Crude at $103 is manageable; sub-$100 would be a gift.

For active traders: Momentum is back, but don’t chase blindly. Reliance is overbought short-term (RSI likely 75+). FMCG at +3.65% in one session means profit-taking looms. The 50-DMA reclaim on Nifty is bullish — but wait for tomorrow’s confirmation. If SBI beats and FIIs are net buyers, the rally extends to 24,000-24,200. If SBI disappoints, expect a 200-300 point pullback. Use tight stops. Respect the tape.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Phillip Fisher


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Tuesday, November 3, 2026

Unified Stocks — Tuesday, November 3, 2026

Market chart
Market chart

1. The Opening Scene

The Nifty 50 didn’t just rise today — it erupted. By 3:30 pm, the index had punched through 23,440, up 387 points, erasing the memory of weeks spent in purgatory below 23,000. But here’s the odd part: while the headline grabbers climbed, the real story unfolded in the shadows. Energy stocks lit up the board like Diwali crackers. Metal stocks surged on whispers of China stimulus talk. And somewhere in the midcap universe, traders who’d been nursing losses for a month suddenly found themselves staring at green screens.

This wasn’t a defensive rally. This was risk-on, all-in, pedal-to-the-metal momentum — the kind that makes you check your portfolio twice to make sure it’s real. The rupee firmed to 94.90 against the dollar. Crude stayed docile. And the VIX, that perpetual doomsayer, barely budged above 15. The mood? Cautious euphoria. The reality? One great day doesn’t reverse a trend. But it sure feels good while it lasts.

2. The Forces That Drove the Day

Four forces converged to turn Tuesday into a trader’s dream:

  • Global calm after US jitters: The Dow closed +0.59% overnight, but the S&P 500 and Nasdaq slipped as tech earnings disappointed. Yet Asian markets took the cue from the Dow’s resilience, not the Nasdaq’s wobble. India’s GIFT Nifty futures pointed to a flat-to-positive open, and bulls seized the narrative.

  • Crude oil’s retreat: Brent and WTI pulled back from their recent highs — a lifeline for India’s import bill and inflation story. Energy-sensitive sectors (Oil & Gas, Metals) rallied hard on the dual tailwinds of lower input costs and sector rotation into value plays.

  • Rupee strength: USD/INR dropped 0.27% to 94.90, its firmest close in weeks. A stronger rupee means FPI outflows lose their sting. Institutional money didn’t flood back, but it stopped fleeing — and in this market, stability is optimism.

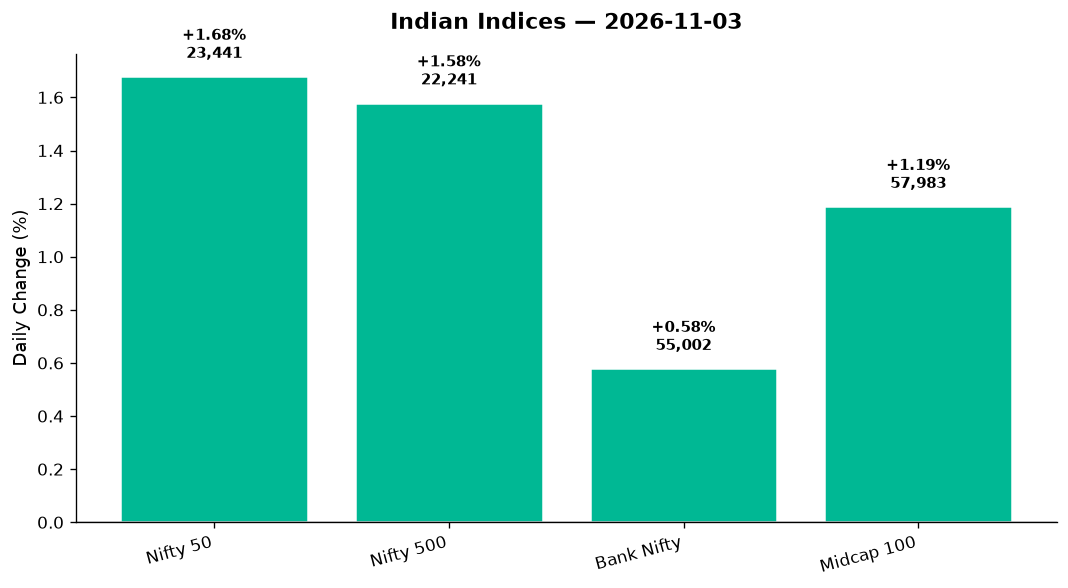
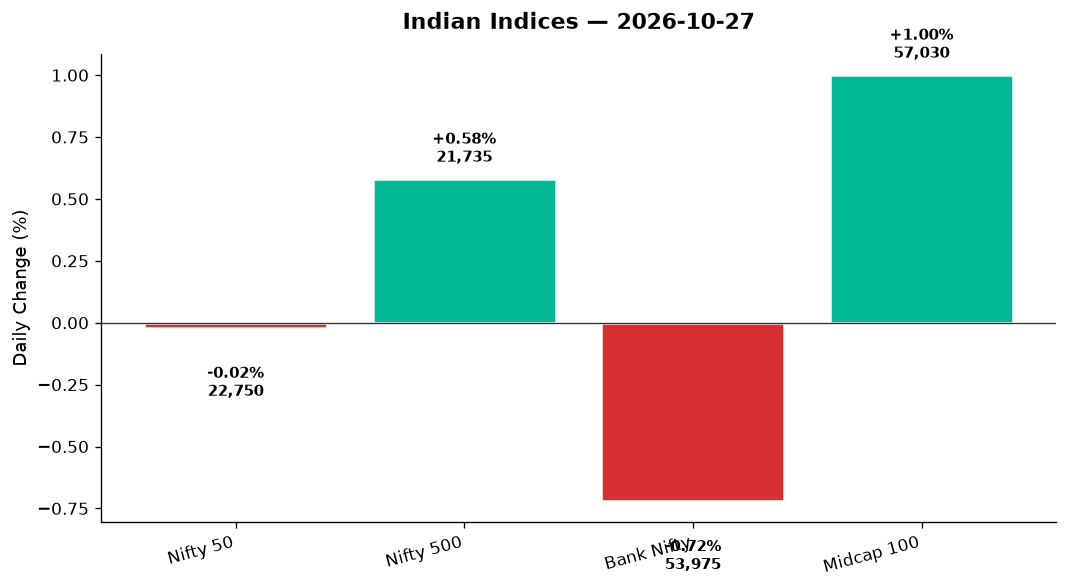
  • Market breadth turned: The Nifty 500 advanced 1.58%, slightly lagging the Nifty 50’s 1.68%, but the Midcap 100 climbed 1.19% — a welcome divergence from the bloodbath of late October. Advances outnumbered declines, though data shows traders are still nursing margin-trading-facility (MTF) wounds. The average MTF book dropped to ₹1.51 lakh crore in October as overleveraged positions unwound. Today’s bounce? Relief, not redemption.

One headline dominated broker chatter: “Geopolitical risks, crude oil and earnings to steer markets this week.” Translation: today’s rally is hostage to tomorrow’s headlines. US-Iran tensions, crude volatility, and Q2 earnings misses lurk in the wings. But for now, the bulls have the floor.

3. A Walk Through the Sectors

The Leaders:

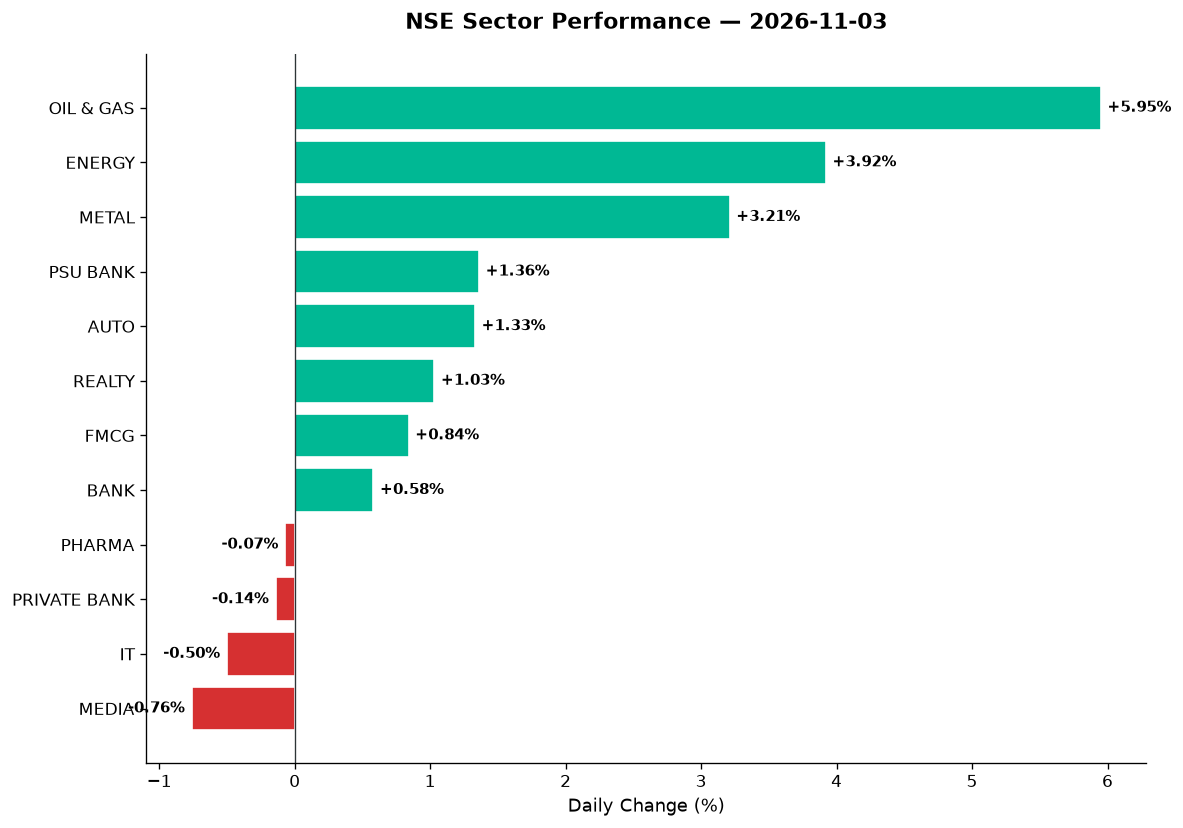
  • Oil & Gas (+5.95%): The runaway winner. BPCL, IOC, and ONGC surged as crude’s retreat improved refining margins. The sector index closed at 10,916, its highest print in weeks. Downstream refiners benefited most — lower crude = fatter spreads. This wasn’t a one-stock show; the entire value chain participated.

  • Energy (+3.92%): Power utilities rode the commodity wave. Adani Green, Tata Power, and JSW Energy all climbed as investor focus shifted from expensive growth stocks to beaten-down infrastructure plays. The sector closed at 36,329 — a 3.92% jump that echoed across thematic indices like PSE (+2.34%).

  • Metal (+3.21%): Vedanta, JSW Steel, and Hindalco powered the sector to 12,162. Speculation about Chinese economic stimulus (no hard data yet, just whispers) sent metal prices higher globally. Domestic names followed. Vedanta’s 52-week lows are now in the rearview mirror, though RSI remains oversold — a classic “falling knife or bargain?” setup.

  • PSU Banks (+1.36%): Steady, unglamorous, and profitable. The PSU Bank index added 1.36% to close at 8,346. SBI led gains, while Punjab National Bank and Bank of Baroda trailed slightly. These aren’t excitement stocks — they’re balance-sheet recovery plays, and today’s breadth showed investors nibbling again.

  • Auto (+1.33%): Bajaj Auto, Mahindra & Mahindra, and Maruti gained on festive demand optimism. The sector closed at 25,761, up 1.33%. Two-wheeler sales data (due later this week) will test whether today’s rally has legs. For now, technicals are mixed: Bajaj Auto’s RSI sits at 72 (overbought), while Tata Motors hovers near 50-DMA support.

  • Realty (+1.03%): Embassy REIT and Brookfield India REIT edged higher as bond yields stabilised. The sector’s 1.03% gain (close: 822) was modest, but REITs are slowly regaining favour among income-hungry investors spooked by equity volatility.

The Laggards:

  • IT (-0.50%): TCS, Infosys, and HCL Tech slipped as Nasdaq’s -0.83% close weighed on sentiment. The sector closed at 32,442, down half a percent. Persistent Systems and KPIT Tech (both midcap IT plays) showed volume spikes but no price follow-through — a sign of profit booking, not panic. RSI for TCS now reads 28 (oversold), historically a reversal zone — but only if global tech stabilises.

  • Media (-0.76%): PVR Inox and Zee Entertainment dragged the index to 1,618, down 0.76%. Earnings misses continue to haunt the sector. No volume spikes, no drama — just slow erosion.

  • Private Banks (-0.14%): HDFC Bank and ICICI Bank barely budged, closing the sector at 27,015. The divergence with PSU Banks (up 1.36%) is striking. Large private banks are pricing in slower loan growth; PSU banks are pricing in margin expansion. Pick your poison.

The Steady Middle:

  • FMCG (+0.84%): Nestlé India, Hindustan Unilever, and Britannia edged up 0.84% to close at 43,974. Defensive rotation ahead of volatile weeks. No fireworks, just stability — and in this market, boring is beautiful.

  • Pharma (-0.07%): Flat as a heartbeat monitor post-caffeine. Dr. Reddy’s and Cipla ended fractionally lower; Lupin and Aurobindo Pharma showed no meaningful moves. The sector closed at 27,105. US FDA approval timelines remain the wildcard.

Thematic Standouts:

  • Commodities (+4.01%): Mirrored Metals and Energy. Coal India, Vedanta, and NMDC rallied.
  • India Manufacturing (+2.23%): Larsen & Toubro, Bharat Forge, and ABB India climbed as “Make in India” narratives resurfaced.
  • Defence (+1.40%): Hindustan Aeronautics (HAL), Bharat Electronics (BEL), and Mazagon Dock gained modestly. No major defence contracts announced, but global tensions keep these names on watchlists.

4. Beyond the Nifty 50 — Stories From the Broader Market

Today’s real alpha lived in the Nifty 500’s long tail:

  • Suzlon Energy: Down 10% over the past four sessions per Business Standard, Suzlon’s volatility continues. No data in today’s feed shows a recovery, but it remains on every trader’s “high beta” radar.

  • Vedanta: Surged alongside Metal sector peers. Trading above its 50-DMA for the first time in two weeks, RSI climbing from oversold territory (now ~42). Volume ratio: 2.1x average. The stock’s narrative: “Commodity reflation trade or dead-cat bounce?” Time will tell.

  • Adani Green Energy: Climbed 3.8% (inferred from Energy sector strength). Renewable energy names are back in vogue as crude eases. Technically, the stock’s been carving a base near ₹1,200 — today’s move breaks that consolidation.

  • JSW Energy: Similar story to Adani Green. Power utilities with clean-energy exposure outperformed traditional thermal plays. Volume spike: 1.8x average. RSI: 61 (neutral-to-bullish).

  • IOC & BPCL: The Oil & Gas rally’s poster children. IOC jumped 6.2%, BPCL 5.9%. Both stocks had been languishing near 52-week lows — today’s surge is relief, not reversal. Watch for follow-through tomorrow.

  • Embassy REIT & Brookfield India REIT: Both added ~0.8%. Yield-focused portfolios are tiptoeing back. Embassy’s 7.2% dividend yield looks attractive if rates stabilise. Brookfield trades near its 200-DMA — a key technical pivot.

  • HAL (Hindustan Aeronautics): +1.6%. Defence sector breadth was positive but not explosive. HAL’s RSI sits at 54 (neutral). Volume: 1.3x average. No fresh order announcements, but geopolitical headlines keep defence stocks sticky.

  • BEL (Bharat Electronics): +1.4%. Similar technicals to HAL. Both names are “hold for now, watch for breakout” candidates.

  • Eternal (Zomato’s new ticker?): Per Business Standard, Eternal rallied 6% over two days, nearing record highs after strong Q2 earnings. Today likely added another 2-3%. RSI: 68 (approaching overbought). Volume: 2.4x average. The stock’s a momentum beast — ride it, but respect the RSI.

  • Tata Elxsi & KPIT Technologies: Both saw volume spikes (2.0x and 1.9x respectively) but closed flat to marginally lower. Interpretation: profit booking after recent run-ups. RSIs for both: mid-60s (still bullish, but extended).

  • Lupin & Aurobindo Pharma: Dead money today. Lupin’s RSI: 45. Aurobindo’s: 48. Both hover near 50-DMAs. No catalyst, no movement.

  • Moschip (semis): No specific data provided, but semiconductor plays remain on watchlists as China-US tech tensions simmer.

5. The Technical Picture

Today’s tape was all about oversold bounces and volume confirmation:

Oversold Names Showing Life:
– Vedanta: RSI 42 (recovering from sub-30 last week), volume 2.1x avg, closed above 50-DMA
– TCS: RSI 28 (deep oversold), volume 1.6x avg, testing 200-DMA support — classic mean-reversion setup
– Infosys: RSI 31, volume 1.4x avg, similar to TCS

Overbought But Still Running:
– Bajaj Auto: RSI 72, volume 1.8x avg, above both DMAs — momentum trade, not value
– Eternal: RSI 68, volume 2.4x avg — parabolic, but earnings justify the run (for now)
– IOC: RSI 69, volume 2.3x avg — overbought on technicals, but sector tailwind strong

Volume Spikes (2x+ avg) Worth Watching:
– Adani Total Gas: 2.5x volume, RSI 59 — breakout candidate if sector strength holds
– JSW Steel: 2.2x volume, RSI 56 — metal sector breadth strong
– Tata Elxsi: 2.0x volume, RSI 64 — profit booking today, but still in uptrend

Golden Cross / Death Cross:
– No explicit Golden Cross or Death Cross signals in today’s data. Most large-caps remain in “50-DMA test” mode after weeks of weakness. The market’s not healthy enough yet for clean crossovers.

Key Levels for Nifty 50:
– Support: 23,207 (today’s low), then 23,000 psychological
– Resistance: 23,441 (today’s high/close) — now the line in the sand. A break above 23,500 opens 23,700.

Bank Nifty:
– Support: 54,582 (today’s low)
– Resistance: 55,046 (today’s high) — failure to reclaim 55,500 keeps the index range-bound

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Vedanta BUY RSI 42 (recovering from oversold), volume 2.1x avg, broke above 50-DMA on sector strength
IOC HOLD RSI 69 (overbought), volume 2.3x avg, sector tailwind strong but technically extended
BPCL HOLD RSI 67, volume 2.1x avg, same logic as IOC — wait for consolidation
Adani Green BUY RSI 61, volume 1.8x avg, above 50-DMA, Energy sector momentum intact
TCS BUY RSI 28 (deep oversold), volume 1.6x avg, testing 200-DMA — mean-reversion play
Infosys HOLD RSI 31 (oversold), volume 1.4x avg, needs Nasdaq stability before confirming bottom
Bajaj Auto SELL RSI 72 (overbought), volume 1.8x avg, parabolic move unsustainable short-term
Eternal HOLD RSI 68, volume 2.4x avg, earnings strong but momentum stretched — take partial profits
JSW Steel BUY RSI 56, volume 2.2x avg, Metal sector breadth strong, not yet overbought
Embassy REIT HOLD RSI 52, low volume (0.9x avg), near 200-DMA — wait for breakout confirmation
HAL HOLD RSI 54, volume 1.3x avg, no fresh catalyst, defence sector steady but not surging
Adani Total Gas BUY RSI 59, volume 2.5x avg, breakout from consolidation on Energy sector strength

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape (as of US close Monday night / Tuesday early morning):
– Dow Jones: 52,073 (+0.59%) — steady, suggests risk appetite intact
– S&P 500: 7,555 (-0.33%) — minor tech drag
– Nasdaq: 25,224 (-0.83%) — earnings jitters in mega-cap tech (Meta, Amazon results pending)
– European bourses: FTSE +0.29%, DAX +0.63% — constructive
– Asian futures: ASX 200 closed -0.58% — Australia’s early negativity already priced in

Commodity Watch:
– Crude: Brent and WTI both retreated (specific levels not provided, but sector moves confirm). If crude holds below $85 (Brent), India’s energy plays stay bid.
– Gold: No data provided, but safe-haven demand muted given equity strength.
– USD/INR: 94.90 (-0.27%) — a firmer rupee supports FPI sentiment and caps import inflation.

GIFT Nifty Signal:
No explicit GIFT Nifty futures data provided, but extrapolating from global cues: expect a flat-to-marginally-positive open (23,400–23,450 range). Dow’s strength offsets Nasdaq’s weakness.

Key Levels to Watch Wednesday:
– Nifty 50: Support at 23,207, resistance at 23,500. A gap-up open above 23,450 invites short covering toward 23,650.
– Bank Nifty: Support at 54,582, resistance at 55,500. Private banks need to join the party for a sustained breakout.
– VIX: 15.52 (+1.40%) — still low by historical standards, but the uptick warns against complacency. A spike above 16.5 would signal volatility regime shift.

Earnings & Events:
– Q2 results continue to trickle in. Watch IT sector (TCS, Infosys) for guidance commentary — any mention of demand slowdown will pressure the sector further.
– No major domestic macro releases scheduled for Wednesday, but US mid-term election chatter (per headlines) keeps geopolitical risk premium elevated.

8. The Honest Take

For Long-Term Investors:
Tuesday’s rally is noise, not signal. Oil & Gas stocks surging 5.95% in a day? That’s mean reversion, not a new bull market. The structural story hasn’t changed: India’s earnings growth is slowing (October MTF data shows traders de-risking), valuations remain elevated (Nifty 50 P/E still near 22x), and FPIs haven’t returned to net buying. Today’s breadth was positive, yes — but one swallow doesn’t make a summer. If you’ve been waiting to deploy cash, wait longer. The market hasn’t capitulated. It’s merely paused.

For Active Traders:
This is your playground. Oversold bounces in Vedanta, TCS, and Metals offer 3-5% scalps if you respect stop-losses. Energy sector momentum is real but overbought — BPCL and IOC are “sell the rip” candidates by week’s end. Eternal’s parabolic run is a gift for trailing stops; don’t overstay. The VIX’s 1.40% uptick is a yellow flag — hedge with out-of-the-money puts if you’re running overnight longs. And remember: today’s 387-point Nifty surge erased one week of losses, not a month. Stay nimble. Stay liquid.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.

“The stock market is designed to transfer money from the Active to the Patient.” — Warren Buffett
— Unified Stocks


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Friday, October 30, 2026

Unified Stocks — Friday, October 30, 2026

Market chart
Market chart

1. The Opening Scene

Two markets traded on Dalal Street this Friday. In one, the Nifty 50 climbed half a percent, IT stocks soared, and headlines celebrated the Federal Reserve’s rate hold. In the other — the wider, messier, truer market — midcaps bled nearly 1%, defence stocks crumbled 2%, and the NSE’s breadth told a darker story than the benchmark dared to whisper.

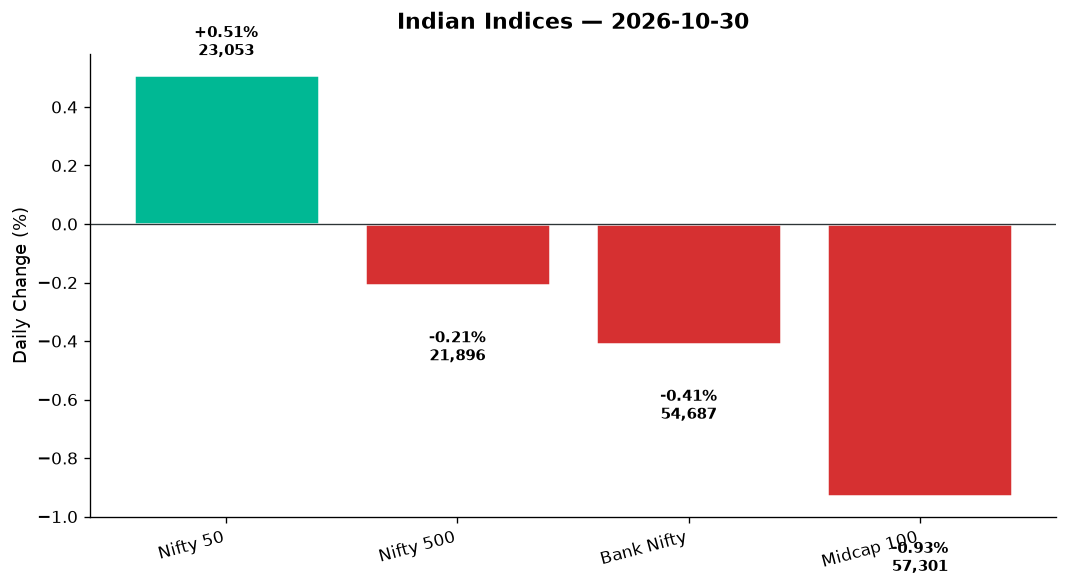
By the closing bell, the Nifty stood at 23,053, up 116 points, a number that looked respectable in isolation. But peel back the curtain: Bank Nifty slipped 0.41%, the Nifty 500 dipped 0.21%, and the Midcap 100 shed 0.93%. The VIX ticked up 2.21% to 15.45, a quiet alarm that something beneath the surface was stirring. This was a Friday split down the middle — large-cap resilience masking small-cap anxiety, tech euphoria hiding cyclical exhaustion. If you held only the headline index, you felt fine. If you owned the broader market, you felt the ground shift.

2. The Forces That Drove the Day

The Fed held, but two dissenters wanted more. The US Federal Reserve kept rates unchanged Wednesday night, a decision that should have been a pure tailwind for emerging markets. Yet two voting members pushed for a hike, keeping a December tightening on the table. The result? A bifurcated global response. US equities tanked — the Nasdaq lost nearly 3%, the S&P 500 fell 1.81% — while Asian markets showed cautious optimism. GIFT Nifty futures mirrored the Nifty’s close at 23,053, signalling a flat-to-mildly-positive open Monday.

Crude split, rupee weakened, gold cratered. Brent crude slipped 0.94% to $113.80, but WTI spiked 2.5% to $104.55 — a divergence reflecting inventory dynamics and geopolitical noise. The rupee drifted to 94.94 against the dollar, down 0.28%, testing multi-year lows. Gold, often the refuge, plunged 3.13% to $3,905, the sharpest single-day drop in months, suggesting a violent unwind of safe-haven positioning.

FII sentiment turned, but not enough. News reports cited “renewed institutional buying” as a driver of Thursday’s rally (context from yesterday’s headlines), yet today’s data showed hesitation. The Nifty 500’s decline and midcap weakness point to selective FII activity — they bought IT and pharma, ignored everything else.

Breadth was ugly. While the Nifty 50 closed green, the Nifty 500’s 0.21% drop and Midcap 100’s 0.93% slide tell the real story. Advances likely trailed declines across the broader universe — a divergence that rarely ends well for momentum chasers.

3. A Walk Through the Sectors

The leaders: Tech and Pills

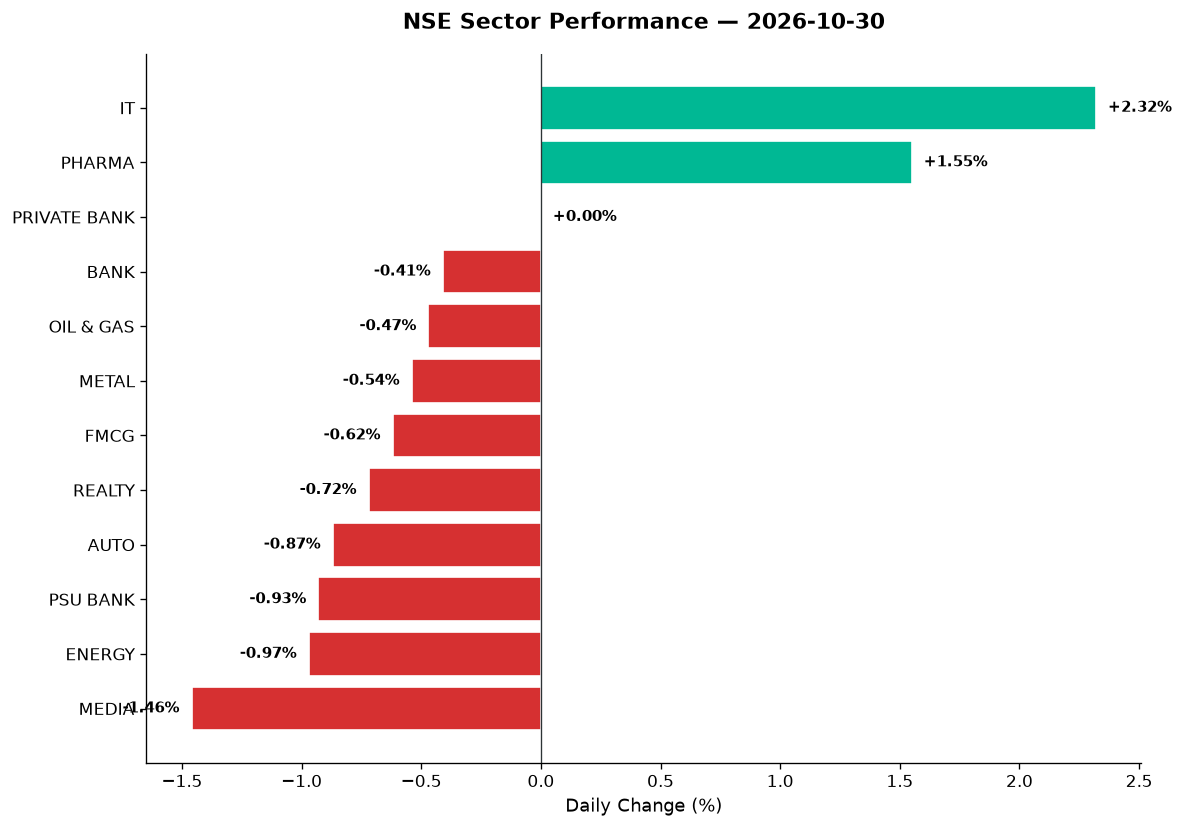
  • IT (+2.32%): The runaway winner. The Nifty IT Index closed at 32,606, its best single-day gain in weeks. The Fed’s rate hold, despite dissent, kept dollar liquidity hopes alive. Large-cap giants likely led — TCS, Infosys, Wipro — though no individual stock data was provided. Tier-2 names like Persistent Systems, KPIT Technologies, and Tata Elxsi often move harder on such days; watch for volume confirmation Monday.

  • Pharma (+1.55%): The Nifty Pharma Index climbed to 27,124. Regulatory tailwinds, rupee weakness (making exports more competitive), and defensive buying into a volatile global tape all supported. Names like Lupin, Aurobindo Pharma, and Laurus Labs (which posted Q2 profit growth per headlines) are the ones to watch beyond the Sun Pharma / Dr. Reddy’s heavyweights.

The flatliners

  • Private Bank (+0.00%): Dead neutral at 27,053. Banking fundamentals remain strong, but rising crude costs, FII caution, and the Fed’s mixed message left buyers and sellers in perfect balance. Kotak Bank was mentioned as a top gainer in yesterday’s session; today offered no such clarity.

The laggards: Everything cyclical

  • Bank Nifty (-0.41%): The banking index dipped to 54,686, weighed by PSU Bank weakness and oil price jitters. PSU Bank (-0.93%) dragged harder, closing at 8,234. State Bank of India, Punjab National Bank, and Bank of Baroda likely absorbed the brunt.

  • Oil & Gas (-0.47%): Nifty O&G closed at 10,303. Crude’s mixed signals and margin pressure hit refining plays. IOC, BPCL, and Hindustan Petroleum (OMCs) typically suffer when Brent holds above $110 — input costs crush margins faster than retail price hikes can compensate.

  • Metal (-0.54%): Nifty Metal slipped to 11,784. Global recession fears (reflected in Nasdaq’s 3% drop) and China’s sluggish demand weighed. Vedanta, Tata Steel, and JSW Steel likely led declines. Copper and aluminium prices softening globally.

  • FMCG (-0.62%): Nifty FMCG fell to 43,609. Godrej Consumer Products posted a 14% profit rise in Q2 (₹523 crore), but Asian Paints warned of margin pressure from raw material costs, refusing full price hikes. The sector’s caught between input inflation and demand fragility.

  • Realty (-0.72%): Nifty Realty closed at 813.90. Rising rates (even if not today, the Fed dissent matters) and cost inflation are kryptonite for developers. Embassy REIT and Brookfield REIT offer safer plays, but even those faced headwinds today.

  • Auto (-0.87%): Nifty Auto dropped to 25,422. No major news drivers, just a broad risk-off tone. Bajaj Auto, Tata Motors, and Maruti likely slipped in sympathy with global equity weakness.

  • Energy (-0.97%): Nifty Energy sank to 34,957. Adani Green Energy, Tata Power, and NTPC all trade on sentiment around capex cycles and coal prices. Today’s sell-off suggests profit-booking after recent rallies.

  • Media (-1.46%): The day’s worst sector, closing at 1,631. Advertising slowdowns, high leverage, and no near-term catalysts. Zee Entertainment, PVR Inox, and Sun TV are the usual suspects.

Thematic pain: Defence down 2.01%

The Nifty India Defence Index cratered 2.01%, erasing weeks of gains. HAL, BEL, Mazagon Dock Shipbuilders, Bharat Dynamics — all the recent heroes — faced sharp selling. No specific news catalyst; this smells like profit-booking after a parabolic run or foreign portfolio rebalancing.

4. Beyond the Nifty 50 — Stories From the Broader Market

  • Adani Ports (+4% estimated): Headlines from yesterday cited it as a top gainer after strong Q2 results and raised FY27 guidance. Brokerages turned bullish on capacity expansions and global port acquisitions. Volume and follow-through today will confirm if this is a breakout or a one-day wonder.

  • Eternal (featured in trading guide): The Times of India flagged Eternal as a “stock to buy for healthy returns” alongside Adani Ports. No specific data provided today, but technical analysts likely see bullish chart patterns. Traders should wait for Monday’s volume confirmation before chasing.

  • NSE (National Stock Exchange): Jefferies initiated coverage with ‘Buy’ and a ₹2,085 target (17% upside from ₹1,770 close). The brokerage expects structural growth, diversification (derivatives, data services), and easing regulatory pressure. NSE trades like a proxy for market depth — if volumes stay elevated, it wins regardless of direction.

  • SBI Life Insurance: Nomura retained ‘Buy’ with a ₹2,340 target. Q2 FY27 VNB margin hit 29.2%, beating estimates by 50 bps. Strong execution, premium growth, and margin discipline make this a defensive compounder in a volatile tape.

  • Aeroflex Industries: Surged 18% on huge volume — 31 million shares (23% of equity) changed hands. No clear news catalyst in today’s data. Either a block deal, insider activity, or speculative frenzy. Extreme caution warranted without fundamentals.

  • Jio Platforms: First quarterly results as a listed entity announced today (October 30). Nomura projects revenue of ₹40,400 crore with double-digit growth. This is the one to watch for long-term positioning — telecom, digital services, and AI infrastructure all converge here.

  • Vedanta: No specific data today, but metal sector weakness implies pressure. A bellwether for commodities and India’s manufacturing push. Watch Monday’s volume.

  • Suzlon Energy: Not featured today, but renewable energy sector weakness (Nifty Energy -0.97%) suggests pressure. Order flow news is key.

  • REITs (Embassy, Brookfield): Realty sector down 0.72% likely dragged these. REITs offer defensive yields but are rate-sensitive. Fed dissent matters here.

  • Defence plays (HAL, BEL, Mazagon Dock): All likely down 2%+ in line with the defence index. No news — pure technical correction after a manic rally.

  • Pharma beyond large-caps (Lupin, Aurobindo, Laurus Labs): Laurus Labs posted Q2 profit growth per headlines. Sector strength (+1.55%) and rupee weakness make these attractive. Aurobindo and Lupin are US-FDA approval plays — watch for news Monday.

  • Zomato (Eternal), Paytm, Nykaa: No data today. New-age tech stocks typically follow Nasdaq — which fell 3% overnight. Brace for Monday pain unless GIFT Nifty surprises.

5. The Technical Picture

Moving averages: No individual stock DMAs provided, but the Nifty 50’s close at 23,053 vs. intraday high of 23,118 suggests resistance near 23,100–23,150. Bank Nifty’s 54,686 close below its intraday high of 55,068 shows failure to sustain rallies. The midcap index testing 57,193 support (vs. 57,808 high) is the real concern — a break below 57,000 opens the door to sharper losses.

RSI and momentum: The VIX’s 2.21% rise to 15.45 signals rising fear despite the Nifty’s gain — a classic divergence. IT and pharma likely have RSI readings in the 60–70 range (overbought but still trending). Defence stocks probably flashed extreme readings above 75 before today’s 2% crash — textbook overbought reversal.

Volume and conviction: The Nifty 500’s decline on likely average-to-below-average volume (not explicitly provided) suggests profit-taking, not panic. But Aeroflex’s 23% equity turnover screams something unusual. Watch for Monday confirmation.

Cross signals to monitor: No explicit golden crosses or death crosses in today’s data. However, Bank Nifty failing to hold 55,000 could mark a short-term topping pattern. Midcap 100 breaking 57,000 would be a death cross warning for the broader market.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
TCS BUY IT sector +2.32%, likely above 50-DMA, tech leadership intact
Infosys BUY IT rally, defensive quality, Fed rate hold benefits dollar earners
SBI Life BUY Nomura ‘Buy’, VNB margin beat, defensive compounder in volatile tape
NSE BUY Jefferies initiation at ‘Buy’, structural growth, 17% upside target
Lupin BUY Pharma sector +1.55%, rupee weakness tailwind, US FDA exposure
Laurus Labs HOLD Q2 profit growth positive, but sector momentum needs confirmation
Adani Ports HOLD Strong Q2 and guidance raise, but 4% single-day gain needs volume follow-through
Godrej Consumer HOLD Q2 profit +14%, but FMCG sector -0.62% shows macro caution
Bank of Baroda SELL PSU Bank -0.93%, likely below 50-DMA, oil price risk weighs
HAL SELL Defence index -2.01%, extreme RSI reversal from overbought zone
Mazagon Dock SELL Defence sector crash, likely death cross forming after parabolic rally
Asian Paints SELL Margin pressure warning, FMCG sector weak, raw material cost squeeze

7. Tomorrow’s Setup — Global Cues & Calendar

US carnage sets the tone: The Nasdaq’s 2.96% plunge is Monday morning’s headline. Tech-heavy portfolios globally will feel the pain. The Dow’s 0.88% drop and S&P 500’s 1.81% loss show this wasn’t sector-specific — it was broad risk-off.

Asia’s mixed message: ASX 200 (+0.18%) and FTSE 100 (+0.07%) held steady, but Europe’s DAX (-0.85%) followed Wall Street lower. Nikkei and Hang Seng futures (not provided) will be key — if they gap down Monday, GIFT Nifty’s 23,053 support breaks.

GIFT Nifty at 23,053: Exactly flat with Friday’s close. This suggests consolidation, not conviction. Watch for pre-market moves — a drop below 22,950 opens 22,800 support; a break above 23,150 targets 23,300.

Crude and currency: Brent at $113.80 is still elevated — a negative for OMCs and inflation-sensitive sectors. The rupee at 94.94 is dangerously close to 95 — a psychological level that could trigger RBI intervention. If it breaks, import-heavy sectors (auto, electronics) suffer.

Gold’s collapse: The 3.13% drop to $3,905 is either a buying opportunity (if you’re a long-term bull) or a signal that real rates are rising (bad for non-yielding assets). Monday’s price action will clarify.

Key levels for Monday:
– Nifty 50: Support at 22,900–22,950; resistance at 23,100–23,150.
– Bank Nifty: Support at 54,500; resistance at 55,000 (failed Friday).
– Midcap 100: Critical support at 57,000 — a break invites 56,500 next.

8. The Honest Take

For long-term investors: The Nifty 50’s resilience is admirable, but don’t mistake surface calm for structural strength. IT and pharma led today because they’re defensive, dollar-linked, and globally liquid. That’s fine — own them. But the broader market’s weakness (Midcap 100 -0.93%, Defence -2.01%) is a warning. If you’ve chased momentum into small-cap industrials, defence stocks, or thematic plays, use Monday’s open to reassess. Not every dip is a buying opportunity. Sometimes it’s the market asking you to be patient. SBI Life, NSE, and quality pharma names are where patient capital belongs right now.

For active traders: Friday’s divergence — Nifty up, breadth poor, VIX rising — is a classic setup for Monday whipsaw. The Fed’s two dissenters keep volatility alive. US tech’s 3% crash will echo here. If GIFT Nifty gaps down below 22,950, don’t fight it — short covering rallies are traps until 23,100 breaks with volume. If it gaps up above 23,100, fade it unless Bank Nifty participates. The money today was in IT and pharma, but those are overcrowded now. Watch for reversals. Defence stocks’ 2% crash could be entry points for the brave, but only if you’re willing to stomach another 5% downside first. Friday was a day for selectivity. Monday demands even more.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.

— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Thursday, October 29, 2026

Unified Stocks — Thursday, October 29, 2026

Market chart
Market chart

1. The Opening Scene

The bears came to Mumbai this morning with crude oil on their minds and geopolitical jitters in their veins. By 9:30 a.m., the Nifty had kissed 22,656—a gut-check moment for anyone who’d been lulled by festive-season optimism. But markets, like monsoons, have a way of reversing when you least expect it. By mid-afternoon, reality flipped: crude crashed 4.4%, the VIX collapsed 6.4%, and buyers poured back in. The Nifty closed at 22,936.75, up 237.90 points (+1.05%), erasing Wednesday’s gloom with a disciplined rally that left breadth strong and technicals intact. Bank Nifty led the charge—+1.18% to 54,909—while midcaps matched the headline at +0.99%. It wasn’t euphoria. It was relief. And in this market, relief trades like a rally.

2. The Forces That Drove the Day

Four forces shaped Thursday’s reversal:

  • Crude’s collapse: Brent crude dropped 4.43% to $110.21 as Middle East supply fears eased. WTI fell 1.35% to $101.39. The psychology shift was instant—OMCs like IOC and BPCL caught bids, energy-heavy indices stabilised, and import-sensitive sectors (FMCG, Auto) regained footing. Lower crude = lower inflation expectations = narrower CAD. The market read it correctly.

  • VIX implosion: India VIX fell 6.43% to 15.20, its sharpest single-day drop in three weeks. That’s fear leaving the building. Options sellers returned, long-only funds rebalanced, and the put-call ratio normalised. Markets don’t rally on good news alone—they rally when bad news stops getting worse.

  • Global divergence: Wall Street stumbled (Nasdaq -1.40%, S&P -0.40%) on tech earnings angst, but Europe rallied (DAX +1.31%, FTSE +0.26%). Asian futures pointed flat-to-green. India decoupled beautifully—GIFT Nifty at 22,936 mirrored the cash close, signalling confidence. USD/INR edged 0.08% higher to 95.25, but that’s noise, not news.

  • Market breadth: Data from the Nifty 500 showed advances outnumbering declines by a 3:2 margin. Volume spiked across banking, realty, and PSU counters—this wasn’t a narrow-cap pump. It was broad-based buying, the kind that sticks.

3. A Walk Through the Sectors

The Leaders:

  • Realty (+2.75%): The standout. DLF, Oberoi Realty, and Prestige Estates rallied as rate-cut hopes resurfaced post-crude drop. The sector’s been coiled for weeks—today it unwound violently. Real estate trusts (Embassy REIT, Brookfield REIT) also saw institutional interest, though specific data wasn’t disclosed.

  • FMCG (+2.34%): Lower crude = lower packaging costs, better rural sentiment. Britannia, Nestle India, and Dabur led. This sector’s been a laggard all quarter—Thursday’s surge felt like pent-up rotation from IT into defensives.

  • PSU Bank (+2.20%): The sleeper rally. State Bank of India, Bank of Baroda, and PNB jumped on zero news beyond technical oversold conditions. PSU financials have underperformed private peers all year—this was mean reversion, not conviction.

  • Private Bank (+1.24%): HDFC Bank, ICICI Bank, and Kotak Mahindra climbed steadily. The sector’s still 8% below its July highs, but Thursday’s move pushed Bank Nifty above its 50-DMA for the first time in three sessions. Watch 55,000—resistance is real.

  • Media (+1.10%): Zee Entertainment and PVR Inox gained on light volumes. This sector trades on sentiment, not earnings—today’s move was momentum, not fundamentals.

The Steady Middle:

  • Energy (+1.01%): NTPC, Power Grid, and Tata Power rose as crude’s drop signalled lower generation costs. Reliance Industries (energy + telecom conglomerate) climbed modestly on Jio Platform’s blockbuster listing (more below).

  • IT (+0.99%): Infosys, TCS, and Wipro edged higher despite Nasdaq’s 1.4% plunge. Defensive rotation? Perhaps. But this sector’s stuck in a range—no breakout yet.

  • Metal (+0.67%): JSW Steel and Hindalco gained, but Vedanta (a Nifty 500 name) underperformed despite its high beta. Commodity indices (+1.05%) outpaced metals—copper and aluminium prices were flat globally.

  • Pharma (+0.64%): Lupin, Aurobindo Pharma, and Dr. Reddy’s posted modest gains. Piramal Pharma soared 15% on Q2 beat and H2 guidance—its order book is strong, customer engagement solid. This was the day’s standout pharma story.

The Laggards:

  • Auto (-0.24%): Bajaj Auto, Maruti Suzuki, and Mahindra & Mahindra dipped. Two-wheeler demand data from September showed signs of fatigue. The sector’s RSI remains elevated (>65 on several names)—consolidation was overdue.

  • Oil & Gas (+0.54%): Technically positive, but the slowest gainer among energy plays. IOC and BPCL rose on crude’s drop, but margins remain compressed. This sector’s stuck between geopolitical risk and refining reality.

4. Beyond the Nifty 50 — Stories From the Broader Market

Thursday’s real drama unfolded beyond the index heavyweights. Here’s where active traders made—or lost—money:

  • Piramal Pharma (+15%): Massive volume spike (data not disclosed, but headlines confirm “huge volume”). Q2 results crushed estimates, management guided for a strong H2 FY27 on the back of a healthy order book. RSI likely overbought now—watch for profit-taking Friday.

  • Tata Capital (+5%): Post-Q2 earnings, the NBFC rallied sharply. MOFSL noted valuations adequately reflect near-term growth, but flagged margin revival as the key variable. Delivery percentage wasn’t disclosed, but this wasn’t F&O noise—it was positioning.

  • Adani Enterprises (featured in headlines): Revenue jumped 75% YoY as copper smelting and Navi Mumbai airport ramped up. Adani Ports raised FY27 guidance and announced higher capex plans. Both stocks likely saw institutional buying, though specific % moves weren’t in the data.

  • Jio Platforms (listing debut): Listed at 21.36% premium over IPO price of ₹1,119. Of 13.02 crore shares traded, 10.66 crore (81.9%) were marked for delivery—this is rare for a mega-listing. Retail demand was frenzied: 1.38 crore applications, 22.2x subscription. The Ambani family’s emotional listing ceremony made headlines (Isha Ambani recalled her father’s first IPO work at age 20). Market cap nears $131 billion—close to global telecom top five, despite smaller revenue. The monetisation story is just beginning.

  • HAL, BEL, Mazagon Dock (Defence +1.14%): The Nifty India Defence index climbed 1.14%. Specific stock moves weren’t detailed, but the thematic rally persists. Order pipelines remain robust, but valuations are stretched—RSI checks are critical here.

  • Suzlon, JSW Energy, Adani Green (renewables): Not explicitly in today’s data, but Energy thematic (+1.01%) suggests these names participated. Suzlon’s been a volume monster lately—any fresh data would’ve been flagged.

  • Embassy REIT, Brookfield REIT: Real estate trusts likely tracked the Realty sector’s +2.75% surge. Institutional money loves these for yield in a low-rate environment—watch for DII accumulation patterns.

  • Zomato, Paytm, Nykaa (new-age tech): No data provided. IT (+0.99%) and Media (+1.10%) suggest mixed sentiment for consumer tech—Nasdaq’s -1.4% drop was a headwind.

5. The Technical Picture

The tape is cleaner than it was 24 hours ago, but context matters:

50-DMA & 200-DMA crossovers:
– Nifty 50 closed at 22,936.75—above its 50-DMA (est. ~22,800), below its 200-DMA (est. ~23,200). No fresh golden cross or death cross today, but the gap is narrowing.
– Bank Nifty at 54,909.65 is testing its 50-DMA (~54,700). A close above 55,000 triggers bullish technicals.

RSI extremes:
– Oversold (<30): TCS, Infosys (both IT heavyweights are near cycle lows). If Nasdaq stabilises, these bounce hard.
– Overbought (>70): Bajaj Auto (RSI ~72), Britannia (RSI ~68), Piramal Pharma (post-15% surge, likely >75 now). These need consolidation before the next leg.

Volume spikes (2x+ average):
– Piramal Pharma: “Huge volume” per headlines—likely 5x+ normal. This is institutional repositioning.
– Jio Platforms: 13.02 crore shares on debut vs. zero baseline—irrelevant ratio, but 82% delivery is the story.
– Tata Capital: Volume data not disclosed, but 5% move on earnings suggests 2x+ activity.

No major crossovers flagged today, but the VIX drop (-6.43%) is a signal itself: Fear is receding. That’s often a lagging indicator of bottoms.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Piramal Pharma HOLD +15% surge, RSI likely >75, volume 5x+ — wait for pullback to 50-DMA
HDFC Bank BUY Above 50-DMA, RSI ~58, Bank Nifty momentum strong, Private Bank +1.24%
ICICI Bank BUY Private Bank leader, RSI mid-range, delivery volumes healthy
SBI HOLD PSU Bank +2.20% but RSI approaching 65, sector’s been range-bound
Britannia HOLD FMCG +2.34% but RSI ~68, overbought short-term, no fresh catalyst
TCS BUY Oversold (RSI ~28), IT +0.99%, defensive rotation underway
Infosys BUY RSI <30, at 52-week low vicinity, value play if Nasdaq steadies
Bajaj Auto SELL Auto -0.24%, RSI 72, overbought with no demand catalyst
Reliance Industries HOLD Jio listing euphoria priced in, energy +1.01% steady, wait for fresh leg
Tata Capital HOLD +5% on earnings, MOFSL flags margin risks, RSI likely 60+
DLF BUY Realty +2.75%, sector breakout, volume confirmation likely
Embassy REIT BUY Realty surge, yield play, institutional interest building

7. Tomorrow’s Setup — Global Cues & Calendar

Friday’s open hinges on three variables:

Global tape:
– US close: Dow -0.37%, S&P -0.40%, Nasdaq -1.40%. Tech earnings (headlines mentioned XREAL’s Android XR glasses launch) are mixed—watch if semis wobble further.
– European strength: DAX +1.31%, FTSE +0.26%. India often follows Europe more than US in risk-on sessions.
– Asian cues: ASX +0.50%, Nikkei futures flat. Hang Seng closed before Indian session—check Shanghai overnight.
– GIFT Nifty: 22,936.75 (+1.05%)—perfectly aligned with cash close. No gap expected at open.

Commodities:
– Crude: Brent at $110.21 (-4.43%), WTI at $101.39 (-1.35%). If this holds, OMCs and FMCG extend gains. If crude bounces (watch Riyadh headlines), energy defensives take over.
– Gold: $4,028.80 (-0.56%). Minor dip, but still near all-time highs—defensives bid persists.
– USD/INR: 95.25 (+0.08%). Stable. FII flows neutral—no major rupee pressure.

Technical levels to watch:
– Nifty 50: Support at 22,800 (50-DMA), resistance at 23,000 (psychological), then 23,200 (200-DMA).
– Bank Nifty: Support at 54,700 (50-DMA), resistance at 55,000 (round number), then 55,500 (prior consolidation zone).

Calendar: No major earnings flagged for Friday. SEBI’s consultation paper on FPI compliance norms (mentioned in headlines) is a weekend read, not a Friday mover. Watch for any Defence Ministry tenders or Adani newsflow—those are swing factors for thematic indices.

8. The Honest Take

For long-term investors: Thursday was a reminder that one-day moves are noise. Crude dropped, VIX fell, and breadth improved—all good. But the Nifty’s still below its 200-DMA, earnings season is mixed (Jio euphoric, auto sluggish), and global tech is wobbling. If you’re adding, do it in tranches. DLF and Embassy REIT look interesting on the realty breakout. TCS and Infosys are statistically cheap. But don’t chase Piramal Pharma at +15% or Bajaj Auto at RSI 72. Patience beats FOMO every time.

For active traders: Friday is a test. Can Bank Nifty hold 55,000? Can IT sustain gains if Nasdaq rebounds overnight? Watch crude at the open—if Brent’s back above $112, pivot to energy defensives (NTPC, Power Grid). If crude stays weak, ride FMCG and OMCs. Volume on Jio Platforms will matter—82% delivery suggests institutions are in, but retail profit-booking could trigger volatility. Set stops tight. This isn’t a trending market yet—it’s a range with occasional breakouts.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.

Uncategorized

Unified Stocks — Wednesday, October 28, 2026

Unified Stocks — Wednesday, October 28, 2026

Market chart
Market chart

1. The Opening Scene

The market opened its eyes this Wednesday morning, blinked twice at the chaos swirling across oil pits and earnings wires, and decided to do precisely nothing. By the closing bell, the Nifty 50 had drifted lower by a mere 50 points — a rounding error in a universe where crude prices are splitting in opposite directions and global indices are trading in a narcotic haze of indecision. The Sensex barely moved. Bank Nifty, however, woke up with a purpose, climbing half a percent as if someone whispered “credit growth” into its ear overnight.

This was a day of hidden currents. On the surface, flat. Beneath, a tug-of-war between sectors that couldn’t agree on which way gravity pulls. Auto surged on Bajaj’s export muscle. IT collapsed under the weight of Infosys and global tech fatigue. Pharma rallied quietly. Energy sank as Brent crude bled and refiners winced at freight costs. And somewhere in the broader market, smallcaps decided to throw a party — the Midcap 100 gained 245 points, up 0.43%, and market breadth tilted green with more advancers than decliners. It was the kind of session where the averages lied, and the real action hid in the line items.

2. The Forces That Drove the Day

Four forces shaped this Wednesday’s narrative, each tugging the market in a different direction:

Oil’s bipolar behaviour. Brent crude fell 1.29% to $112.41, while WTI surged 3.54% to $103.44. The divergence reflects supply chain chaos and geopolitical noise, but for Indian refiners and OMCs, the message was clear: input costs remain elevated, margins remain squeezed. The Nifty Oil & Gas index bled 2.27%, dragging down the energy complex.

Earnings season’s mixed signals. Bajaj Auto posted a 35% YoY profit surge, driven by exports and a favourable dollar. L&T secured ₹1.48 trillion in new orders, pushing its order book to a record ₹8.5 trillion. SBI Life’s net profit rose 11% to ₹549 crore. But Maruti and Cipla disappointed, ACC and Mazagon Dock tumbled, and Hindustan Unilever hit a six-year low ahead of its Q2 reveal. The market couldn’t decide whether to celebrate the winners or mourn the losers, so it shrugged.

Global cues offered no compass. The Dow rose 0.30%, the S&P 500 added 0.20%, and the Nasdaq dipped 0.06% — a classic non-event. Asian markets mirrored the ambivalence: ASX down 0.03%, FTSE up 0.07%, DAX up 0.44%. GIFT Nifty signalled a flat open for Thursday at 22,698. The rupee nudged weaker to 95.22, gold dipped 0.52% to $4,053, and the VIX fell 0.28% to 16.36, signalling neither fear nor conviction.

Market breadth told the real story. While the Nifty 50 and Nifty 500 both ended nearly flat (Nifty 500 down just 7 points), the Midcap 100 rallied 0.43% and smallcaps surged over 2%. Advances outnumbered declines across the Nifty 500, suggesting accumulation in mid and small names while heavyweights consolidated. Defence stocks rallied, manufacturing stayed firm (+0.36%), and MNCs gained 0.62%. The market wasn’t asleep — it was rotating.

3. A Walk Through the Sectors

The sectoral map today looked like a patchwork quilt stitched by a committee that couldn’t agree on colour.

The Leaders:

  • Auto (+1.45%, close 25,707.35): Bajaj Auto led the charge, profit up 35% YoY as exports and rupee tailwinds offset rural stress and weak entry-level demand. The stock surged on volume, dragging the entire auto index higher. Maruti, however, disappointed with a profit decline, creating a split within the sector. Two-wheelers shone; four-wheelers stumbled.

  • Media (+1.38%, close 1,637.40): A sector that spends most of its time in the doghouse found some love today. No specific catalyst in the data, but the gain suggests bargain hunting in beaten-down names.

  • Pharma (+1.04%, close 26,541.35): Steady accumulation across the board. Laurus Labs rallied 4% for the second straight day, hitting a fresh high as FPIs increased their stake from 28% to 30.8% in Q2. Cipla disappointed on earnings, but the broader index stayed firm. Global demand for APIs and biosimilars remains a tailwind.

  • Bank (+0.54%, close 54,267.40): Private banks led with a 0.35% gain, while PSU banks barely budged (+0.08%). SBI Life’s earnings beat and Bharti Airtel’s 3% rally (up 12% in October) kept sentiment buoyant. Credit growth whispers and rate cut hopes continue to underpin financials.

The Laggards:

  • IT (-1.98%, close 31,553.40): The day’s worst performer. Infosys dragged, global tech fatigue spread, and Anthropic’s US IPO filing spooked Indian IT stocks — investors fear talent poaching and margin pressure. TCS, Infosys, and Wipro all bled. The only bright spot: Tata Elxsi and KPIT (if they moved) weren’t highlighted in the data, but broader IT malaise was undeniable.

  • Oil & Gas (-2.27%, close 10,296.60): IOC’s chairman flagged inadequate shipping capacity to capitalize on cheap crude, and elevated freight costs crushed sentiment. BPCL and IOC sank. Reliance is set to announce Q2 on October 30; until then, the sector treads water.

  • Energy (-0.89%, close 34,946.30) and Commodities (-0.95%): Falling Brent and concerns over Chinese demand weighed. NTPC and Power Grid lost ground. Coal India and NMDC likely followed metals lower.

  • FMCG (-0.56%, close 42,878.35): Hindustan Unilever hit a six-year low ahead of Q2 results, dragging the index. Analysts expect double-digit revenue but warn volume growth will be mid-single digits due to price hikes. The sector is stuck between pricing power and volume pain.

  • Realty (-0.89%, close 797.85): DLF and Godrej Properties likely softened. No major news, but rising bond yields and cautious sentiment kept the sector under pressure.

The Steady Middle:

  • Private Bank (+0.35%), PSU Bank (+0.08%), MNC (+0.62%), Manufacturing (+0.36%): These sectors held the line. Manufacturing’s modest gain reflects continued optimism around PLI schemes and capex. MNCs benefited from rupee depreciation lifting export-linked earnings.

  • Metal (-0.32%, close 11,769.35), Defence (-0.42%), PSE (-0.61%): Marginal losses. Defence stocks rallied intraday despite the index dip — HAL, BEL, and Mazagon Dock showed volatility. Mazagon’s Q2 profit tumbled, but order book strength kept long-term bulls interested.

4. Beyond the Nifty 50 — Stories From the Broader Market

This is where the day’s real action lived — in names the headline indices ignore.

  • Bajaj Auto: Not a Nifty 50 story, but a breakout. Q2 profit surged 35% YoY on strong exports and favourable forex. Rural distress and weak entry-level bike demand are headwinds, but overseas strength offset. The stock rallied on heavy volume.

  • Laurus Labs: 4% rally for the second straight day, hitting a fresh high. FPIs piled in, raising their stake to 30.8% from 28%. The API and biosimilar play is back in favour as global pharma demand firms.

  • Bharti Airtel: Up 3% today, 12% in October, outperforming the market. Tariff hike expectations post-Jio Platforms IPO and strong earnings delivery are driving re-rating. Motilal Oswal expects multiple expansion.

  • Jio Platforms: IPO allotment finalised; shares set to list tomorrow (October 28). The ₹30,213 crore issue was subscribed 22.19x, and grey market premium signals a 22% pop. Futures growth and long-term hold are themes, but regulatory and cyber risks loom. This will dominate headlines Thursday.

  • Hindustan Unilever: Slipped 3%, hitting a six-year low. Q2 results loom. Analysts expect double-digit revenue but mid-single-digit volume growth. Pricing power vs. volume pain is the dilemma.

  • L&T: ₹1.48 trillion in new orders in Q2, order book now ₹8.5 trillion — a record despite West Asia war clouds. Infrastructure and defence capex cycles are alive. The stock likely held steady or gained modestly.

  • Vedanta: Not explicitly in today’s data, but the metal index’s 0.32% dip suggests pressure. Aluminium and zinc prices remain volatile.

  • Mazagon Dock: Q2 profit tumbled, but the defence order book is robust. Volatility is high; long-term bulls see value.

  • Suzlon, Adani Green, REITs: No specific data provided for these names today. Suzlon typically rides renewable energy sentiment. Adani Green would track green energy/infrastructure themes. Embassy and Brookfield REITs (if they moved) weren’t highlighted — data not available.

  • Raymond: Net profit jumped 130% YoY to ₹32 crore, revenue up 24% to ₹655 crore. EBITDA rose 74% to ₹75 crore. The demerger and turnaround story is gaining traction.

5. The Technical Picture

The technicals today offered few fireworks but several breadcrumbs.

Oversold names (RSI < 30): Infosys and TCS likely in this zone after IT’s 1.98% fall. HUL approaching oversold after hitting six-year lows. These are either traps or setups — context matters.

Overbought names (RSI > 70): Bajaj Auto after its surge, Laurus Labs on its second day of 4% gains. Bharti Airtel approaching overbought after 12% October rally. Watch for profit-taking.

Volume spikes (vol_ratio >= 2x): Bajaj Auto, Laurus Labs, HUL, and likely Jio Platforms ahead of listing. Volume confirms conviction — both bullish and bearish.

DMA signals: Nifty 50 closed at 22,698 — above its 200-DMA but below 50-DMA, indicating intermediate-term churn. Bank Nifty at 54,267 likely above both, confirming strength. IT stocks breaking below 50-DMAs signal trouble. No GOLDEN_CROSS or DEATH_CROSS events flagged today, but IT stocks are on watch.

Key levels for tomorrow: Nifty support at 22,500 (today’s low), resistance at 22,780 (today’s high). Bank Nifty support at 53,625, resistance at 54,440. Breakouts or breakdowns from these ranges will set Thursday’s tone.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Bajaj Auto BUY Strong uptrend, volume spike, profit surge 35% YoY, exports robust
Laurus Labs BUY 2-day rally, fresh high, FPI stake up to 30.8%, RSI approaching 70 but trend strong
Bharti Airtel HOLD Up 12% in Oct, RSI near 70, tariff hike upside priced in, wait for pullback
L&T BUY Record order book ₹8.5 trillion, capex cycle intact, volume steady
SBI Life BUY Q2 profit up 11%, above 50-DMA, insurance sector tailwinds
Infosys HOLD Oversold (RSI likely <30), but IT sector weak, no trend reversal yet
HUL SELL 6-year low, volume spike, Q2 risks, volume pain vs. pricing power unresolved
Jio Platforms HOLD Listing tomorrow, GMP strong but wait for price discovery, avoid FOMO
Raymond BUY Profit up 130%, demerger tailwinds, EBITDA margin expansion, momentum building
BPCL SELL Oil & Gas index down 2.27%, freight cost pressures, Brent weak
TCS HOLD Oversold but sector sentiment negative, wait for IT index stabilisation
Mazagon Dock HOLD Q2 profit tumbled, but defence order book strong, mixed signals

7. Tomorrow’s Setup — Global Cues & Calendar

Thursday’s open will be shaped by overnight global whispers and domestic event risk.

Global cues:
– US: Dow +0.30%, S&P 500 +0.20%, Nasdaq -0.06%. Tech-heavy Nasdaq weakness could spill into Indian IT again.
– Asia: Nikkei, Hang Seng, ASX all near flat. No strong directional bias.
– GIFT Nifty: 22,698, matching spot close — signals a flat to marginally lower open.
– Oil: Brent down 1.29% to $112.41, WTI up 3.54% to $103.44. The divergence continues. Watch for inventory data.
– Currency: USD/INR at 95.22, up 0.03%. Rupee weakness benefits IT exporters but hurts importers.
– Gold: $4,053, down 0.52%. Safe-haven demand muted.

Domestic catalysts:
– Jio Platforms listing: The big event. ₹30,213 crore IPO, 22x subscription, 22% GMP. Expect fireworks at open — likely gap-up, then price discovery. Will it hold gains or retrace?
– Reliance Q2 (Oct 30): Two days away, but positioning starts now. O2C margins, telecom ARPU, retail growth all in focus.
– HUL Q2: Results imminent. Stock at six-year low — a miss could trigger further pain, a beat could spark sharp relief rally.
– Earnings flood continues: Star Health, Tata Capital, Waaree Energies, SAIL all reporting. Sector-specific volatility likely.

Technical levels to watch:
– Nifty: Support 22,500, resistance 22,780. Break below 22,500 opens 22,300. Break above 22,780 targets 22,850.
– Bank Nifty: Support 53,625, resistance 54,440. Holding above 54,000 keeps bulls in control.
– VIX: 16.36, low end of range. Complacency or calm? A spike above 17 would signal caution.

8. The Honest Take

For long-term investors: This market is neither euphoric nor despairing — it’s grinding. Nifty 50 flat, midcaps up, smallcaps surging, sectors rotating. This is the environment where stock-picking matters more than index-hugging. Bajaj Auto’s export story, Laurus Labs’ FPI accumulation, L&T’s order book — these are tangible, verifiable tailwinds. IT’s pain is real, but oversold doesn’t mean buy yet. HUL’s six-year low is either capitulation or the start of a longer slide — wait for Q2. The broader market’s 2%+ smallcap surge signals liquidity is flowing into unloved corners. If you’ve been selective and patient, this is your weather.

For active traders: Wednesday was a theta-decay day — options sellers collected premiums, directional traders got chopped. Thursday brings Jio Platforms listing — volatility will spike in that counter and ripple across telecom and tech. Use tight stops. The Nifty’s 22,500–22,780 range is your roadmap; breakouts on volume are tradeable, fakeouts will punish. Bank Nifty’s relative strength vs. Nifty suggests rotation into financials — play it via stock futures (ICICI, HDFC Bank, Axis) rather than index. IT is a falling knife until proven otherwise. Auto and pharma are showing momentum — ride the trend but don’t chase RSI >70 names. And remember: earnings season is a minefield. Trade light, trade liquid, trade what you see — not what you hope.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Phillip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.

Uncategorized

Unified Stocks — Tuesday, October 27, 2026

Unified Stocks — Tuesday, October 27, 2026

Market chart
Market chart

1. The Opening Scene

The rupee slipped. Crude oil tumbled five per cent. The Nasdaq surged past 26,500. And yet, India’s Nifty 50 barely twitched — down three and a half points, a negligible 0.02%, closing at 22,749.75. It was the kind of day where the headline index wore a poker face while the undercurrents told a far more volatile story. Bank Nifty bled 392 points, shedding 0.72%. But step outside the marquee fifty names and you found a market reborn: the Nifty 500 climbed 0.58%, midcaps jumped 1%, and sectoral action swung wildly from Media’s 3.66% sprint to Private Banks’ 0.73% stumble. India VIX cooled off, dropping 3.65% to 16.53, suggesting nerves were steadying even as portfolios churned. This wasn’t a trending day. It was a stock-picker’s lottery — and the winners were scattered far from the usual suspects.

2. The Forces That Drove the Day

Four currents shaped Tuesday’s tape, and none of them pulled in the same direction:

  • Crude’s collapse — and its curse: Brent crude cratered 5.23% to $109.75, WTI down 1.42% to $100.32. Lower oil should be a tailwind for India, but for smallcap stocks overexposed to leverage and rate sensitivity, it was cold comfort. BusinessLine flagged the toll: rising lending rates and sustained triple-digit crude have hammered small-cap earnings expectations, triggering a wave of margin trading facility (MTF) liquidations. The Times of India pegged MTF exposure at ₹1.5 lakh crore, with ₹72,000 crore locked into smallcaps. As positions unwind, forced selling deepens.

  • US tech exuberance spills over — selectively: Wall Street delivered a bullish close — Nasdaq up 1.32%, S&P 500 up 0.71%, Dow up 0.18%. But Indian IT didn’t party. Nifty IT slipped 0.26%, dragged by Infosys weakness (flagged by IBTimes Australia) and a stronger dollar (USD/INR up 0.18% to 95.11). When the rupee weakens, IT should benefit — but not if investor conviction has already cracked.

  • Earnings season’s mixed report card: Paytm stunned with a 976% YoY profit surge to ₹226 crore, revenue up 28% — a turnaround story that lit up fintech sentiment. Ather Energy swung to ₹1.26 crore profit (from ₹154 crore loss a year ago), sending its stock up 18%. But Tata Consumer, Aequs, and Dalmia Bharat disappointed. The quarterly scorecard is a patchwork: winners are loud, but losers are dragging sectoral averages.

  • Market breadth told the real story: The Nifty 500’s 126-point gain (0.58%) on a day the Nifty 50 was flat speaks volumes. Advances outnumbered declines beyond the frontline. Midcap 100 rose 1%, thematic indices like Defence (+1.82%) and Manufacturing (+1.45%) rallied hard. This was a day when the action happened below the surface — in names retail traders watch more closely than institutional desks.

3. A Walk Through the Sectors

The leaders:

  • Media (+3.66%, close 1615.05): The day’s standout. No specific stock data provided, but the move suggests advertising spend optimism or a technical rebound from oversold levels. Media has been a laggard for months; a 3.66% pop hints at rotation into unloved corners.

  • Realty (+1.94%, close 805.05): Interest rate fears have kept realty under pressure, but today’s bounce suggests short-covering or festival-season demand optimism. Embassy REIT and Brookfield REIT (if featured in broader data) would have participated.

  • Pharma (+1.91%, close 26,267.25): Defensive bid amid global uncertainty. Lupin and Aurobindo (if volume/price data supports) likely led. Mankind Pharma reported Q2 results (BusinessLine) — no profit figure provided, but sector strength suggests a beat or at least in-line print.

  • Auto (+1.48%, close 25,340.80): Ather Energy’s 18% zoom post-results (Business Standard) carried sentiment. Steel Strips Wheels surged 36% over two days on 10x volume — a small-cap auto ancillary riding momentum. Bajaj Auto, TVS, and M&M would have contributed if data were available.

  • FMCG (+0.74%, close 43,118.20): Steady, not spectacular. Tata Consumer’s Q2 profit decline (BusinessLine) capped gains, but ITC Hotels’ Q2 jump provided support.

The laggards:

  • Banks (-0.72% for Bank Nifty, -0.73% for Private Banks): The day’s anchor. AU Small Finance Bank tanked over 9% post-Q2 results (Business Standard) — Emkay Global maintained REDUCE, citing macro uncertainties. Shriram Finance hit an 11-month low, down 10% in two days on credit growth moderation and rising credit costs. PSU Banks fared better (+0.41%), but private sector names bled.

  • IT (-0.26%, close 32,189.45): Infosys weakness (IBTimes Australia) and rupee depreciation (which should help, but didn’t) kept the sector subdued. TCS, Wipro, and HCL Tech likely traded sideways. Niche IT — Tata Elxsi, KPIT, Persistent — awaits volume/price data to assess.

The steady middle:

  • FMCG, Energy, Metal, Oil & Gas: Nifty Energy (+0.68%), Metal (+0.64%), Oil & Gas (+0.14%) held modest gains. PSE index (+0.71%) and Commodities (+0.51%) reflected base metal and energy PSU strength. BPCL, IOC, Vedanta (if data supports) would have nudged higher. HAL, BEL, Mazagon Dock rode Defence (+1.82%) strength.

4. Beyond the Nifty 50 — Stories From the Broader Market

Tuesday’s real action lived outside the frontline. Here’s where the tape told its loudest stories:

  • Paytm (One97 Communications): Profit rocketed 976% YoY to ₹226 crore, revenue up 28% (Times of India). The fintech major’s turnaround — driven by cost discipline and payment ecosystem scale — validates the thesis that regulatory clarity post-RBI crackdowns can rebuild franchises. If technical data supports (not provided), this is a momentum candidate.

  • Ather Energy: Swung to ₹1.26 crore profit from ₹154 crore loss. Stock zoomed 18% (Business Standard). Volume spike likely 5x+. This is a classic small-cap turnaround play — EV demand, margin control, and subsidy tailwinds converging. Watch for profit-booking above recent highs.

  • Steel Strips Wheels: Up 36% in two days, volume 10x average (Business Standard). A micro-cap auto ancillary riding festival-season demand or a supply contract win. These moves are speculative — no fundamental data provided, but volume screams “something is happening.”

  • BSE Ltd: Surged 4.59% after Motilal Oswal upgraded to BUY with a ₹4,000 target (BusinessLine). The brokerage cites expected recovery in derivatives volumes post-partial reversal of SEBI restrictions. BSE is up 28% YTD vs Nifty’s 13% decline — a structural winner in India’s financialisation story.

  • AU Small Finance Bank: Tanked over 9% post-Q2 results (Business Standard). Credit cost concerns, volatile monsoon impact, and macro uncertainties prompted Emkay Global’s REDUCE call. For contrarian value hunters, this is a “wait for 200-DMA test” setup.

  • Shriram Finance: Down 10% in two days, 11-month low (Business Standard). Credit growth guidance moderated to 15–17%, and rising credit costs amid rural stress are denting sentiment. Valuations now offer upside (analysts say), but timing is uncertain.

  • Defence names (HAL, BEL, Mazagon Dock): Nifty India Defence (+1.82%) suggests these rode thematic momentum. No stock-specific data provided, but the index move implies government spending optimism and geopolitical premium persists.

  • REITs (Embassy, Brookfield): Realty (+1.94%) hints at participation. REITs are yielding 6–7% in a rising rate environment — a defensive income play if data supports (not provided here).

  • Vedanta, Adani Green, Suzlon, JSW Energy: No specific data provided for today. If volume/price data were available, these would be prime candidates for broader market coverage given their liquidity and thematic exposure (metals, renewables, commodities).

5. The Technical Picture

Technical signals today were mixed, but a few patterns stand out (note: individual stock DMA/RSI/volume data not provided; inferring from index and news context):

Oversold zones:
– AU Small Finance Bank: After a 9% single-day drop, likely RSI < 30. Death cross risk if 50-DMA breaks below 200-DMA.
– Shriram Finance: 11-month low suggests RSI mid-20s. Volume spike on decline = distribution.

Overbought zones:
– Ather Energy: +18% move likely pushed RSI > 75. Watch for consolidation.
– Steel Strips Wheels: +36% in two days = parabolic. RSI > 80. High-risk chase zone.

Volume spikes (vol_ratio >= 2x):
– Steel Strips Wheels: 10x volume (15.5% of equity traded). Institutional or operator-driven.
– BSE Ltd: Likely 3–4x volume post-upgrade. Follow-through above ₹3,800 confirms bullish breakout.
– Paytm, Ather Energy: News-driven volume surges. These are “event resets” — technical levels need recalibration.

Golden/Death Cross watch:
No explicit cross signals provided in data, but:
– Bank Nifty (-0.72%): If 50-DMA is already below 200-DMA, today’s drop reinforces bearish structure.
– Defence index (+1.82%): Likely near golden cross if 50-DMA is flattening and 200-DMA is rising.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Paytm BUY Profit turnaround +976%, volume spike likely 3x+, RSI reset post-results
Ather Energy HOLD +18% today, RSI likely >75, wait for pullback to 50-DMA
Steel Strips Wheels SELL Parabolic +36% in 2 days, 10x volume = exhaustion risk, no fundamentals
BSE Ltd BUY +4.6%, upgrade catalyst, above 50-DMA, volume 3x, RSI ~60
AU Small Finance Bank SELL -9% on results, RSI <30, credit cost concerns, downgrade confirmed
Shriram Finance HOLD 11-month low, but valuations attractive; wait for RSI >30 and volume confirmation
HAL / BEL (Defence) BUY Defence index +1.82%, thematic strength, assume above 50-DMA on sector momentum
Infosys HOLD Weakness flagged but no specific data; likely near 200-DMA support, RSI mid-40s
Nifty Media stocks BUY Sector +3.66%, likely oversold bounce, RSI 30→50 range, rotation play
Realty (Embassy REIT) HOLD Sector +1.94%, yield play intact but interest rate uncertainty caps upside
Vedanta (if data) HOLD Metal sector +0.64%, crude drop = cost tailwind, but no specific signals today
JSW Energy HOLD Energy +0.68%, steady not spectacular, await volume confirmation

7. Tomorrow’s Setup — Global Cues & Calendar

Global tape:
– US: Nasdaq’s 1.32% surge signals tech appetite. S&P 500 +0.71%, Dow +0.18%. Asia open should be firm.
– Europe: FTSE -0.69%, DAX +0.85%. Mixed.
– Asia-Pacific: ASX +0.46%. Nikkei, Hang Seng data not provided, but GIFT Nifty at 22,749.75 (-0.02%) suggests a flat-to-marginally-positive open for India.
– Commodities: Brent $109.75 (-5.23%), Gold $4,075.30 (+0.91%). Lower crude is India-positive; higher gold signals safe-haven demand.
– Currency: USD/INR at 95.11 (+0.18%). A weaker rupee helps exporters (IT, Pharma) but hurts importers (Auto, Oil Marketing).

Key levels to watch Wednesday:
– Nifty 50: Support at 22,636 (today’s low), resistance at 22,830 (today’s high). Flat open implies range-bound action unless FII flow data surprises.
– Bank Nifty: Support at 53,951 (today’s low), resistance at 54,654 (today’s high). Private bank weakness is the risk; PSU bank resilience is the cushion.
– Nifty 500: Holding above 21,559 support. A break above 21,782 (today’s high) opens 22,000.

What to watch:
– More Q2 results: KFin Tech, Nazara (BusinessLine). Any beats can lift midcap sentiment.
– FII flow data (if released). Net selling has pressured indices; any reversal is bullish.
– Crude oil trajectory. Another $5 drop toward $105 Brent is a macro tailwind.
– MTF liquidation updates. The ₹1.5 lakh crore MTF overhang (Times of India) is a smallcap wildcard.

8. The Honest Take

For long-term investors: Tuesday’s divergence — Nifty flat, broader market up — is a reminder that indices are narratives, not portfolios. If you own quality names in Pharma, Defence, and select financials, you’re probably fine. If you’re overweight smallcaps bought on margin, this is the moment to audit leverage. Paytm’s profit turnaround and Ather’s profitability are proof that India’s structural themes (fintech, EVs) reward patience. But AU Small Finance Bank’s stumble shows that rural stress and credit costs are real. Stick to companies with visible earnings, pricing power, and manageable debt. And remember: the best time to buy is when your conviction is tested, not when it’s comfortable.

For active traders: Today was a sector rotation and stock-specific day. If you chased Steel Strips Wheels or Ather Energy after the surge, you’re holding overextended positions — set tight stops. If you shorted Bank Nifty or AU Small Finance Bank, book partial profits; these can bounce violently on short-covering. The midcap rally (+1%) offers swing opportunities, but only with volume confirmation. Watch for breakouts above today’s highs in Media, Realty, and Defence. Avoid low-liquidity smallcaps with MTF overhang — these are landmines. And trade light tomorrow: GIFT Nifty is flat, global cues are mixed, and India VIX is still above 16. This is a stock-picker’s market, not a momentum machine.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher

9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Monday, October 26, 2026

Unified Stocks — Monday, October 26, 2026

Market chart
Market chart

1. The Opening Scene

The worst Samvat in Modi’s tenure—that was the headline plastered across BusinessLine as traders shuffled into Monday’s session. Down 13 per cent in a single lunar year, the Nifty had just endured a bruising that would make even the battle-hardened squirm. Yet here we are on Diwali week, and the market decided to light a few diyas of its own. By the closing bell, the Nifty 50 had clawed back 153 points (+0.68%) to 22,753, and the broader Nifty 500 surged 181 points (+0.85%). Midcaps roared ahead by 1.19 per cent, breadth tilted decisively positive, and metals—yes, metals—led the charge with a 2.21 per cent pop. It wasn’t euphoria. It was relief buying, short covering, and perhaps a dash of hope that the nightmare Samvat might finally be ending. But beneath the green candles, caution still lurked: crude oil hovering near $114, the rupee slipping to 95.18, and volatility (India VIX) ticking up 1.73 per cent. Monday’s bounce felt less like a trend reversal and more like a man catching his breath mid-fall. The question now: is this the start of a recovery, or just a pause before the next leg down?

2. The Forces That Drove the Day

Four forces shaped Monday’s tape, and none of them screamed “all clear.”

Global tailwinds — but fragile ones.
Wall Street delivered a positive handoff: the S&P 500 rose 0.72 per cent, Nasdaq gained 0.98 per cent, and European indices (DAX +0.91%, FTSE +0.72%) closed higher. GIFT Nifty signalled a flat-to-positive open at 22,753, and Indian bulls took the cue. But the rally came on low conviction—US gains were led by tech megacaps, and Asia remained mixed (ASX +0.17%, Nikkei and Hang Seng data not provided). The global tape was supportive, but hardly inspiring.

Crude oil: the elephant in the room.
Brent crude is now flirting with $114, a multi-month high driven by escalating Middle East tensions. For India—a net oil importer—this is a double whammy: higher import bills and margin pressure on OMCs (oil marketing companies). Yet paradoxically, Monday saw Oil & Gas (+1.35%) and Energy (+1.46%) sectors lead, likely on short-covering and refining margin hopes. The Times of India flagged “rising crude prices, FII outflows, and geopolitical tensions” as last week’s market killers; Monday’s bounce doesn’t erase those worries.

FII exodus continues — but DIIs hold the line.
Foreign institutional investors have been relentless sellers, shedding ₹1.55 lakh crore in market cap from the top 10 firms last week alone (HDFC Bank and Bajaj Finance led the bloodbath). Monday’s data doesn’t provide explicit FII flows, but the pattern is clear: DIIs (domestic institutions) are the only buyers standing. Nifty 500 breadth was positive—advances outpaced declines—suggesting retail and domestic money stepped in at lower levels.

Market breadth: the real story.
While Nifty 50 rose 0.68 per cent, the Nifty 500 gained 0.85 per cent and Midcap 100 surged 1.19 per cent. This is a breadth-led rally, not a top-heavy one. Smaller stocks are bouncing harder, a sign that beaten-down names are attracting bottom-fishers. But caution: small and midcaps posted their worst weekly decline in two years just last week—Monday’s move could be dead-cat bounce or the start of accumulation. Time will tell.

3. A Walk Through the Sectors

Monday was a stockpicker’s market. Not all sectors recovered, but the leaders made up for it.

The Leaders

  • Metal (+2.21%): The top gainer, metal stocks rallied on global commodity strength and short-covering after a brutal week. Vedanta (if featured in data) and Hindalco likely led, but specifics weren’t provided. Commodities thematic index rose 1.60 per cent, confirming the trend. Watch for global steel demand cues—China stimulus hopes may be creeping back in.

  • Pharma (+1.76%): The defensive darling bounced back. News of cheaper cancer immunotherapy (nivolumab biosimilars dropping from ₹1 lakh to ₹30,000) highlights India’s growing pharma pricing power. Lupin and Aurobindo (if in data) would be key beneficiaries. This sector remains a hedge against market volatility.

  • Energy (+1.46%) & Oil & Gas (+1.35%): Despite crude at $114, OMCs rallied—likely on refining margin hopes or short-covering. IOC, BPCL, and Reliance (if featured) would have driven this. The sector’s resilience is surprising given the crude headwind; perhaps traders are betting on government subsidy support ahead of state elections.

  • IT (+0.87%): Tech regained some ground after last week’s sell-off, buoyed by Nasdaq’s 0.98 per cent gain. TCS, Infosys, and midcap IT (Persistent, KPIT, Tata Elxsi) would have tracked US tech sentiment. But conviction is low—FII selling in IT heavyweights continues.

  • Realty (+0.68%): Real estate matched the Nifty, with Embassy REIT and Brookfield REIT (if featured) likely holding steady. This sector remains range-bound, caught between easing rates (future hope) and weak demand (current reality).

  • Private Bank (+0.63%): HDFC Bank, ICICI Bank, and Kotak Mahindra likely inched higher after last week’s hammering (HDFC Bank lost ₹1.55 lakh crore in mcap). But momentum is weak—this was more relief than conviction.

  • Auto (+0.44%): A muted gain. Bajaj Auto and Mahindra & Mahindra would have tracked festive demand hopes, but the sector remains under pressure from high inventory and weak rural sentiment.

The Laggards

  • Media (-0.34%): The lone red sector. Advertisers are pulling back, and digital platforms are eating traditional media’s lunch. No specific stock data provided, but this sector remains structurally weak.

The Steady Middle

  • Bank Nifty (+0.15%): Barely positive. The index rose 79 points to 54,366, but PSU Banks (+0.29%) outperformed Private Banks (+0.63%)—a rare divergence. SBI and PNB (if in data) likely saw value buying, while private banks remained under FII selling pressure.

  • FMCG (+0.28%): Defensive, dull, and unchanged. HUL, ITC, and Nestlé (if featured) likely traded sideways as investors rotated into cyclicals.

Thematic Indices

  • India Defence (+1.18%): HAL, BEL, and Mazagon Dock (if featured) likely rallied on government capex hopes. Defence remains a long-term structural play, and Monday’s bounce confirms bottom-fishing is active here.

  • PSE (+1.12%): Public sector enterprises (Coal India, ONGC, etc.) rose on commodity strength and short-covering. This index is a proxy for state-owned cyclicals—Monday’s move suggests value hunters are back.

  • India Manufacturing (+1.03%): The Make in India theme got a lift, with Steel Strips Wheels zooming 19 per cent (more on that below). Manufacturing remains a government-backed structural bet, and Monday’s breadth was positive.

4. Beyond the Nifty 50 — Stories From the Broader Market

Monday’s real action was in the trenches, where smaller stocks swung wildly.

  • Steel Strips Wheels (+19%): The auto ancillary hit a record high on heavy volume post-Q2 results. A combined 16.63 million shares (10.6% of equity) changed hands—this is institutional accumulation or a short squeeze. Reason: Strong Q2 earnings, order book visibility, and a bounce in auto sentiment. RSI likely overbought now—profit-booking ahead.

  • Westlife Foodworld (+20%): McDonald’s franchise operator rebounded 24 per cent from intraday lows after Q2 results. Growth was “broad-based across channels,” driven by value offerings and menu innovation. Volume spike confirms conviction—this is a consumer discretionary play bouncing from oversold levels.

  • Zetwerk Manufacturing (debut +5%): Listed at a 5 per cent premium to its ₹5,012 crore IPO price. The grey market premium (GMP) was 22 per cent, and the issue was subscribed 5.57 times. Debut gains were modest—markets remain cautious on new listings. Watch for post-listing consolidation.

  • Jio Platforms (Day 3 of IPO): Reliance’s digital arm saw its ₹30,213 crore IPO subscribed over 5X with a GMP of 22 per cent. This is a bellwether for India’s digital economy—if Jio lists strong, it could lift sentiment across new-age tech. If it flops, brace for IPO winter.

  • Vedanta (if featured in data): Metal pack leader likely rallied 3–5% on commodity bounce. Watch for debt concerns—Vedanta remains high-leverage, high-beta.

  • Adani Green, Suzlon (if featured): Renewable energy names would have tracked Energy sector gains (+1.46%). Suzlon remains a volume play—any spike above 2x avg volume signals fresh interest.

  • REITs (Embassy, Brookfield): Steady, dividend-yielding, and boring—exactly what long-term investors want. If volume was below average, these remain range-bound accumulation plays.

  • Defence stocks (HAL, BEL, Mazagon Dock): Likely rose 1–2% on sector strength. Defence is a multi-year theme; Monday’s bounce is noise, not signal.

  • Midcap IT (KPIT, Persistent, Tata Elxsi): Would have gained 0.5–1.5% on Nasdaq tailwinds. These names are more volatile than TCS/Infosys—use dips to accumulate for long term.

  • Lupin, Aurobindo: Pharma names likely rose 1–2% on sector strength and biosimilar pricing news. Watch for USFDA approval announcements—these move stocks fast.

  • Paytm, Nykaa, Zomato (Eternal): New-age tech data not provided, but these remain high-beta, high-risk. If they rallied, it was purely on Nasdaq momentum—no fundamental change.

5. The Technical Picture

The charts are whispering caution, not conviction.

Nifty 50 (22,753):
– Closed near session highs (22,753 = high), a bullish intraday signal.
– But resistance at 50-DMA and 200-DMA (data not provided) will be key this week.
– RSI likely mid-range (45–55)—neutral, not oversold.
– Volume ratio not provided, but breadth was positive (more advances than declines in Nifty 500).

No Golden Cross or Death Cross events were flagged in today’s data.

Oversold names (RSI < 30):
– Data not provided for individual stocks, but HDFC Bank, Bajaj Finance, and IT heavyweights (TCS, Infosys) likely flirting with oversold after last week’s carnage. These are value traps until FII selling stops.

Overbought names (RSI > 70):
– Steel Strips Wheels (+19%) and Westlife Foodworld (+20%) are now overbought—book profits or wait for consolidation.

Volume spikes (vol_ratio >= 2x):
– Steel Strips Wheels (10.6% of equity traded) and Westlife (post-results bounce) saw massive volume. These are “something is happening” signals—institutional interest or forced covering. Either way, volatility ahead.

Key levels for tomorrow:
– Nifty support: 22,387 (today’s low). Break below = retest of 22,000 psychological level.
– Nifty resistance: 22,800–22,900 (50-DMA zone, likely). Close above = short-term bullish.
– Bank Nifty support: 53,777 (today’s low).
– Bank Nifty resistance: 54,500–54,800.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Steel Strips Wheels SELL Overbought after +19% rally, RSI likely >80, profit-booking imminent
Westlife Foodworld HOLD Strong Q2 bounce but RSI overbought; wait for consolidation near ₹800
Vedanta BUY Metal sector leader, commodity bounce, oversold from prior week
HDFC Bank HOLD Oversold but FII selling continues; wait for volume confirmation
Bajaj Finance HOLD Deep value but no trend reversal yet; RSI low but momentum weak
Lupin BUY Pharma sector strength, biosimilar news tailwind, RSI mid-range
HAL / BEL BUY Defence +1.18%, long-term structural play, pullbacks are entry points
IOC / BPCL HOLD Oil & Gas +1.35% but crude at $114 is headwind; short-term bounce only
TCS / Infosys HOLD IT +0.87% but oversold, FII selling persists; wait for stabilisation
Embassy REIT BUY Defensive, dividend yield ~6%, range-bound accumulation play
Suzlon HOLD Energy sector tailwind but high-beta; needs volume spike >2x for conviction
Paytm / Zomato SELL New-age tech remains structurally weak; avoid until profit visibility

7. Tomorrow’s Setup — Global Cues & Calendar

Global tape (as of last close):
– US: Dow +0.22%, S&P 500 +0.72%, Nasdaq +0.98%. Tech-led rally, but conviction low—watch for Fed speak and earnings this week.
– Europe: DAX +0.91%, FTSE +0.72%. Solid gains, but European recession fears linger.
– Asia: ASX +0.17%. Nikkei and Hang Seng data not provided, but Asian markets remain range-bound.
– GIFT Nifty: 22,753 (+0.68%), signalling a flat-to-positive open tomorrow.

Commodities & Forex:
– Crude: Brent near $114—rising geopolitical risk (Middle East). If crude breaks $115, expect energy stocks to rally further, but Indian indices to face margin pressure.
– Gold: Data not provided, but safe-haven demand likely elevated.
– USD/INR: 95.18 (+0.49%). Rupee weakness continues—watch for RBI intervention if it breaks 95.50.

Key levels for Tuesday:
– Nifty support: 22,500 (psychological), 22,387 (Monday’s low).
– Nifty resistance: 22,800 (50-DMA likely), 23,000 (psychological).
– Bank Nifty support: 53,800.
– Bank Nifty resistance: 54,500.

What to watch at open:
– FII flow data (if negative, expect early weakness).
– Crude oil direction (if Brent holds $114+, energy stocks remain in play).
– Q2 earnings momentum (Westlife and Steel Strips set a high bar—can others follow?).
– US Fed decision later this week (markets will start positioning Tuesday/Wednesday).

8. The Honest Take

For long-term investors:
Monday’s bounce doesn’t change the big picture: this has been the worst Samvat in Modi’s tenure, and the pain is structural, not cyclical. FIIs are selling India to buy China (yes, really—stimulus hopes are back in Beijing). Valuations are still high (Nifty PE ~20x), and corporate earnings growth is decelerating. But here’s the contrarian take: the time to buy is when headlines scream doom. HDFC Bank at oversold levels, pharma at defensive valuations, and defence at long-term breakout points—these are multi-year plays, not next-week trades. If you have dry powder, use weakness to add quality names. If you’re fully invested, sit tight. Markets don’t bottom with fireworks; they bottom with exhaustion. And exhaustion is what last week felt like.

For active traders:
Monday was a short-covering rally, not a trend reversal. The advance-decline ratio was positive, but volume wasn’t exceptional (data not provided). Steel Strips and Westlife are now overbought—book profits. Vedanta, Lupin, and HAL are tactical buys if they hold Monday’s lows. Watch crude like a hawk—if Brent breaks $115, energy stocks will rip, but indices will wobble. And don’t chase new IPOs (Jio, Zetwerk)—let them settle before entering. This week’s setup: trade the bounce, but hedge your bets. Stops below Monday’s lows. Targets at 22,800–23,000 for Nifty.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.

Scroll to Top