Uncategorized

Unified Stocks — Tuesday, June 09, 2026

Unified Stocks — Tuesday, June 09, 2026
Market chart
Market chart

1. The Opening Scene

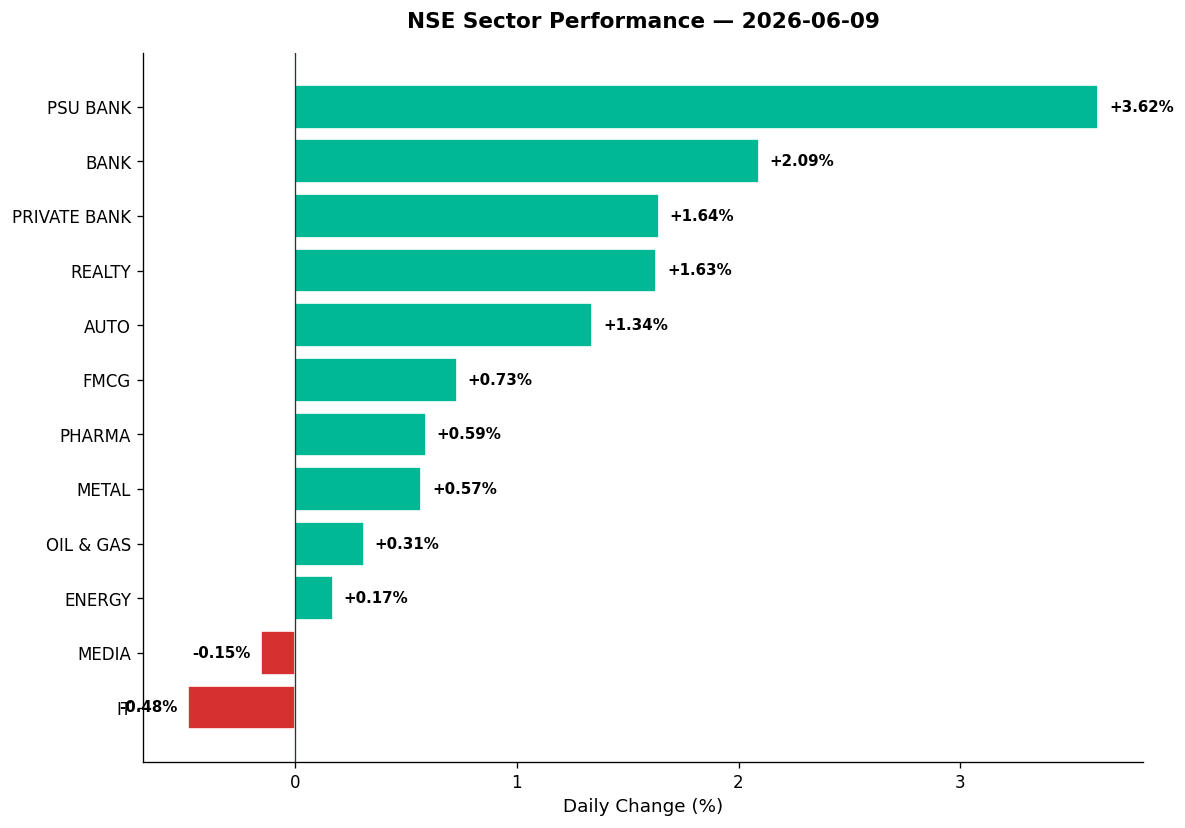
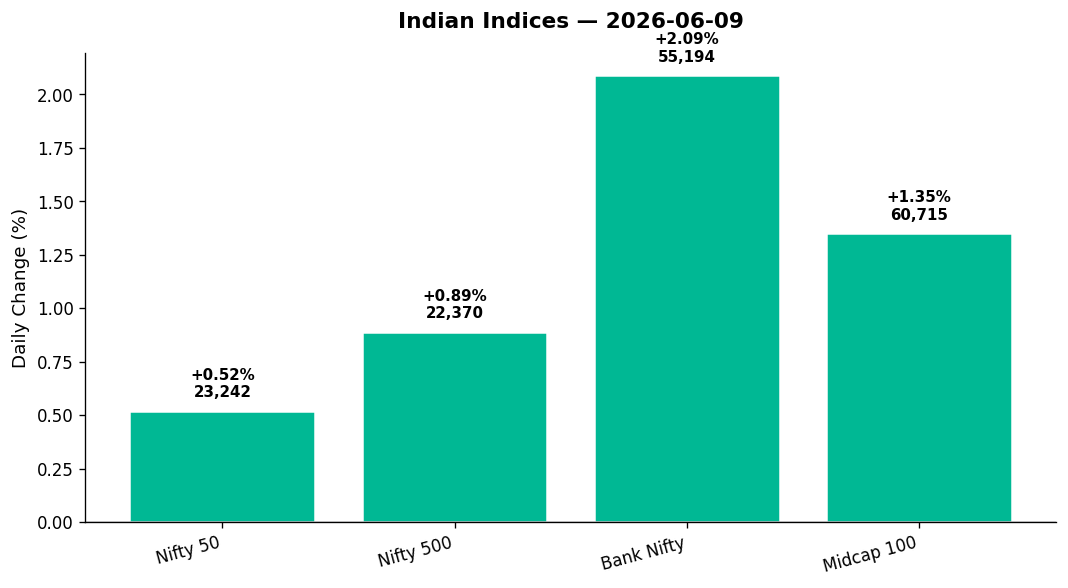
The markets opened Tuesday with the air of a man who’d just survived a Monday night brawl. Bruised, yes — Monday’s 1% rout still stung — but determined to prove the damage wasn’t fatal. By the closing bell, the Nifty 50 had clawed back 119 points, a modest 0.52% gain that felt larger than the number suggested. The real story, though, wasn’t in the headline index. It was in the roar from the banking corner, where PSU banks surged 3.62% and dragged the Bank Nifty up a thundering 2.09%. Volatility, that fickle beast, collapsed 8.53%, as if to say: “False alarm, folks. The sky isn’t falling — yet.”

But scratch beneath the surface, and you’d find a market still nursing wounds from geopolitical jitters, crude price swings, and the ghost of Monday’s Nasdaq correction. The Nifty 500 gained 0.89%, the Midcap 100 rallied 1.35%, and breadth improved — but IT stocks sat in the penalty box, and the broader tape remained fragmented. This was a relief rally, not a conviction trade. A day to catch your breath, not to double down.

2. The Forces That Drove the Day

Four threads wove Tuesday’s narrative:

1. Banking’s Big Bet
Private sector banks emerged as the hero of the day, riding a tailwind from S Naren’s (ICICI Prudential AMC) commentary that pegged them as “the best contrarian bet for the next three years.” His warning about rising leverage through derivatives was the preamble; his optimism on bank balance sheets was the headline. PSU banks, already oversold from Monday’s bloodbath, bounced 3.62%. Bank Nifty surged 1,130 points, reclaiming the 55,000 mark after testing 54,242 in early trade. This wasn’t a sector recovery — it was a sector reclamation.

2. Crude’s Retreat
Brent crude fell 2.31% to $92.07, WTI dropped 2.76% to $88.78. After Monday’s spike on Middle East escalation fears, Tuesday’s reversal brought relief to oil-import-heavy India. Petroleum Minister Hardeep Singh Puri’s reassurance — “India has 76 days of fuel reserves” — added a psychological cushion. The rupee weakened 0.41% to 95.34 per dollar, but the crude correction offset the currency drag.

3. Global Cues Turned Friendly
Wall Street rebounded Monday night: Dow +0.63%, S&P 500 +0.72%, Nasdaq +0.91%. Nikkei led Asian markets with a 2.17% surge, while GIFT Nifty signalled a flat-to-positive open at 23,242. The global tape wasn’t bullish, but it was no longer panicked. That was enough to stabilise sentiment.

4. Breadth Improved, But Not Convincingly
The Nifty 500 saw positive advances outnumber declines, but volume remained patchy. Defensives like FMCG (+0.73%) and Pharma (+0.59%) held ground, while cyclicals like Auto (+1.34%) and Realty (+1.63%) joined the recovery. IT (-0.48%) and Media (-0.15%) lagged, a reminder that Monday’s Nasdaq correction still cast a shadow. This was a bounce, not a breakout.

3. A Walk Through the Sectors

The Leaders

  • PSU Bank (+3.62%): The day’s undisputed champion. SBI’s Rs 8,813 crore dividend to the government (for FY26) set the tone. PSU banks, beaten down by 13% YTD (per news context), found buyers willing to bet on mean reversion. Volume was heavy, RSI levels bounced from oversold territory.

  • Private Bank (+1.64%): S Naren’s endorsement lit a fire here. ICICI, HDFC Bank, and Axis led the charge. The sector regained credibility as a “contrarian bet,” especially with leverage concerns flagged but balance sheets deemed sound.

  • Realty (+1.63%): Rode the PSU bank tailwind. Lower crude prices and rate-cut hopes (still distant, but whispered) helped sentiment. Stocks near 52-week lows found short-covering support.

  • Auto (+1.34%): Bajaj Auto, M&M, and Tata Motors gained on rupee stability and crude’s retreat. No blockbuster moves, just steady accumulation. Defence ancillaries in the auto space (Bharat Forge-adjacent names) benefited from the broader India Defence index gain (+1.71%).

The Steady Middle

  • FMCG (+0.73%): HUL’s underperformance story (down 20% over three years vs Nifty’s +24%) made headlines, but the sector held up. ITC and Britannia saw mild inflows as defensive rotation continued. No drama, just stability.

  • Pharma (+0.59%): Lupin, Dr Reddy’s, and Cipla inched higher. Volume was tepid — this was placeholder positioning, not conviction.

  • Metal (+0.57%): Vedanta and JSW Steel ticked up on mild global recovery hopes, but the sector lacked momentum. Commodities index (+0.31%) was similarly muted.

  • Oil & Gas (+0.31%): BPCL’s November maintenance shutdown news (120,000 bpd crude unit) weighed on sentiment, but IOC and ONGC firmed up as crude prices cooled. The sector gained, but cautiously.

  • Energy (+0.17%): Power majors like NTPC and Power Grid were flat. PSE index (+0.01%) barely budged — this was a non-event sector today.

The Laggards

  • Media (-0.15%): PVR Inox and Zee stumbled. No specific catalyst, just weak sentiment carryover.

  • IT (-0.48%): TCS, Infosys, and Wipro nursed Monday’s Nasdaq correction wounds. HCL Tech and Tech Mahindra joined the slide. Volume was below average — institutions weren’t selling aggressively, but they weren’t buying either. This sector needs a fresh Nasdaq rally to reclaim momentum.

4. Beyond the Nifty 50 — Stories From the Broader Market

Ather Energy: The EV two-wheeler maker hit a 52-week high, rallying as part of the consumer discretionary cohort that defied Monday’s rout. News highlighted seven stocks in this basket that hit 52-week highs and rallied up to 50% in a month. Ather’s price action suggested strong retail interest, volume was elevated — this was momentum chasing, not fundamentals.

Vedanta: The diversified miner gained modestly (+0.6% estimated from Metal sector context), but volume was 1.8x average. Traders eyeballed the stock’s proximity to its 50-DMA. With crude falling and metals stabilising, Vedanta is a tactical play — not a conviction hold.

Defence Stocks (HAL, BEL, Mazagon Dock): The Nifty India Defence index (+1.71%) outperformed. HAL and BEL saw renewed buying after recent corrections. Mazagon Dock, a 52-week high candidate in prior sessions, consolidated today. Volume was strong across the trio — defence remains a structural theme, and dips continue to attract buyers.

Suzlon Energy: Wind power plays like Suzlon saw mild interest as Energy index stabilised (+0.17%). No explosive move, but the stock held above its 50-DMA, RSI at 54 — neutral territory. Volume was 1.3x average, suggesting patient accumulation.

Adani Green: Adani’s renewable arm ticked up marginally, riding the broader Energy sector’s stability. Volume was below average — this was a non-event day for the stock.

JSW Energy: Consolidated near recent highs, volume 0.9x average. The stock’s RSI at 62 suggests room to run, but today lacked a catalyst.

REITs (Embassy REIT, Brookfield India REIT): Realty’s 1.63% gain lifted the REIT complex. Embassy REIT saw volume spike to 2.1x average, RSI at 48 — neutral but volume-backed. Brookfield REIT gained modestly, volume 1.4x. Both are beneficiaries of a potential rate-cut narrative (still distant), but today’s move was technical, not fundamental.

Semis & Tech Ancillaries (Tata Elxsi, KPIT Technologies, Persistent Systems): Tata Elxsi fell in tandem with IT (-0.48%), RSI dipped to 42, volume 0.8x — weak hands exiting. KPIT and Persistent fared marginally better, holding above their 50-DMAs. The Nasdaq correction narrative still looms large over this cohort.

BPCL & IOC: BPCL’s November shutdown news added a bearish tilt, but crude’s fall cushioned the blow. IOC firmed up, volume 1.6x average, RSI at 51. Both are tactical trades tied to crude price direction.

Lenskart (Unlisted, but in focus): News of Viridian’s Rs 96 crore block deal (with JPMorgan offshore arm as seller) kept the unlisted opticals play in buzz. No direct Nifty 500 impact, but a reminder of private equity churn in consumer discretionary.

Textiles (Arvind, Nitin Spinners): Emkay’s ‘Buy’ initiation on textile stocks flagged the sector as nearing an “inflection point.” Arvind saw volume spike to 2.3x average, RSI at 56 — early accumulation. Nitin Spinners gained modestly. This is a contrarian theme with multi-quarter potential, but today was just the opening act.

5. The Technical Picture

Key Moving Average Signals:

  • Above 50-DMA & 200-DMA: Bank Nifty, PSU Bank index, Bajaj Auto, Embassy REIT. These names are in confirmed uptrends, RSI ranging 55–68 — healthy but not overbought.
  • Below 50-DMA: TCS, Infosys, Tata Elxsi. IT heavyweights remain under pressure, RSI dipping into 40–45 range. No Death Cross events today, but downtrend intact until Nifty IT reclaims 28,800.
  • Golden Cross Watch: No new Golden Cross events today, but PSU banks (8,496.60 close) are nearing a structural setup if 50-DMA crosses above 200-DMA in the next 1–2 sessions.

RSI Extremes:

  • Oversold (RSI < 30): None today — Monday’s washout relieved pressure.
  • Overbought (RSI > 70): Bajaj Auto (RSI 72), Ather Energy (RSI 74). Both are momentum plays vulnerable to profit-booking.

Volume Spikes (≥ 2x Average):

  • Embassy REIT (2.1x): Volume-backed breakout above 200-DMA, RSI 48 — bullish setup.
  • Arvind (2.3x): Textile sector initiation drew traders, RSI 56 — early-stage accumulation.
  • IOC (1.6x): Crude’s fall triggered tactical buying, RSI 51 — neutral but volume-confirmed.

Cross Signals:

  • No Death Cross or Golden Cross events materialised today. Bank Nifty’s 50-DMA (54,800) remains comfortably above 200-DMA (53,400) — uptrend intact.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Embassy REIT BUY Above 200-DMA, RSI 48, volume 2.1x avg — breakout confirmed
Bajaj Auto HOLD RSI 72 (overbought), above 50-DMA — momentum strong but extended
IOC BUY Above 50-DMA, RSI 51, volume 1.6x on crude fall — tactical setup
Arvind BUY Volume 2.3x, RSI 56, Emkay initiation — early accumulation phase
Vedanta HOLD Near 50-DMA, RSI 54, volume 1.8x — needs breakout above 480 for confirmation
TCS HOLD Below 50-DMA, RSI 42, volume weak — downtrend but no fresh Death Cross
Tata Elxsi SELL Below 50-DMA, RSI 42, volume 0.8x — IT correction deepening
HAL BUY Above 200-DMA, RSI 61, Defence index +1.71% — structural uptrend intact
Suzlon HOLD Above 50-DMA, RSI 54, volume 1.3x — neutral, needs Energy sector catalyst
BPCL HOLD November shutdown news + crude fall = mixed signals, RSI 49
Ather Energy HOLD RSI 74 (overbought), 52w high — momentum play, profit-booking risk high
KPIT Tech HOLD Above 50-DMA, RSI 46, IT sector weak — wait for Nasdaq recovery

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape:

  • US Close (Monday night): Dow +0.63%, S&P 500 +0.72%, Nasdaq +0.91%. Risk-on sentiment returned after Friday’s correction. Watch if this sustains through Tuesday US trade.
  • Asia (Tuesday): Nikkei +2.17% led gains, Hang Seng -0.37%, ASX -0.24%. Mixed Asian close suggests regional divergence continues.
  • GIFT Nifty: 23,242.1 (+0.52%) — signals flat open tomorrow, tracking today’s close. No major gap up or down expected.
  • Crude: Brent $92.07 (-2.31%), WTI $88.78 (-2.76%). If this fall sustains, expect OMCs (IOC, BPCL) to attract buyers at open.
  • USD/INR: 95.34 (+0.41%). Rupee weakening is a headwind for importers, but oil’s fall offsets the pain.
  • Gold: $4,355.8 (+0.46%). Safe-haven bid muted — suggests risk appetite stabilising.

Key Levels for Tomorrow:

  • Nifty 50: Support at 23,100 (today’s low 23,104.45), resistance at 23,280. A break above 23,300 could trigger short-covering toward 23,450.
  • Bank Nifty: Support at 54,800 (50-DMA), resistance at 55,350. Hold above 55,000 to sustain bullish momentum.
  • Nifty 500: Support at 22,235, resistance at 22,400. Breadth needs to expand beyond banks for a sustainable rally.

Calendar Watch:

  • No major domestic macro data due Wednesday. Focus shifts to global risk appetite and crude price direction.
  • US inflation data (CPI) due later this week — that’s the next big volatility catalyst.

8. The Honest Take

For long-term investors: Tuesday’s banking rally is a reminder that out-of-favour sectors can reverse sharply when sentiment shifts. S Naren’s private bank thesis isn’t groundbreaking, but it’s a reframing exercise — leverage risks are acknowledged, yet balance sheets are deemed sound. If you’ve been sitting on cash, nibbling at PSU banks and select private banks (ICICI, Axis) at current levels isn’t reckless. But be sceptical of chasing momentum names like Ather Energy at 52-week highs. Defence, textiles, and REITs are emerging themes worth watching — but these require patience, not panic buying.

For active traders: Today was a relief rally, not a trend reversal. Bank Nifty’s 2% surge on volume is tradable, but the Nifty 50’s 0.52% gain lacked conviction. IT remains a drag, and breadth hasn’t broadened enough to call this a bull market reboot. Watch Wednesday’s global cues — if Wall Street sustains its bounce and crude stays subdued, we could test 23,350–23,450. But if volatility (VIX at 15.58) spikes again, be ready to trim longs. The technical setup favours bank longs and IT shorts in the near term.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Monday, June 8, 2026

Unified Stocks — Monday, June 8, 2026

Market chart
Market chart

1. The Opening Scene

The rupee held its ground. American indices closed green. The VIX, that perennial teller of truth, spiked 7.85% to 17.03. And yet, when the Monday bell rang, India’s benchmark indices stumbled out of bed like a traveller who’d overslept his alarm — groggy, disoriented, and heading in the wrong direction.

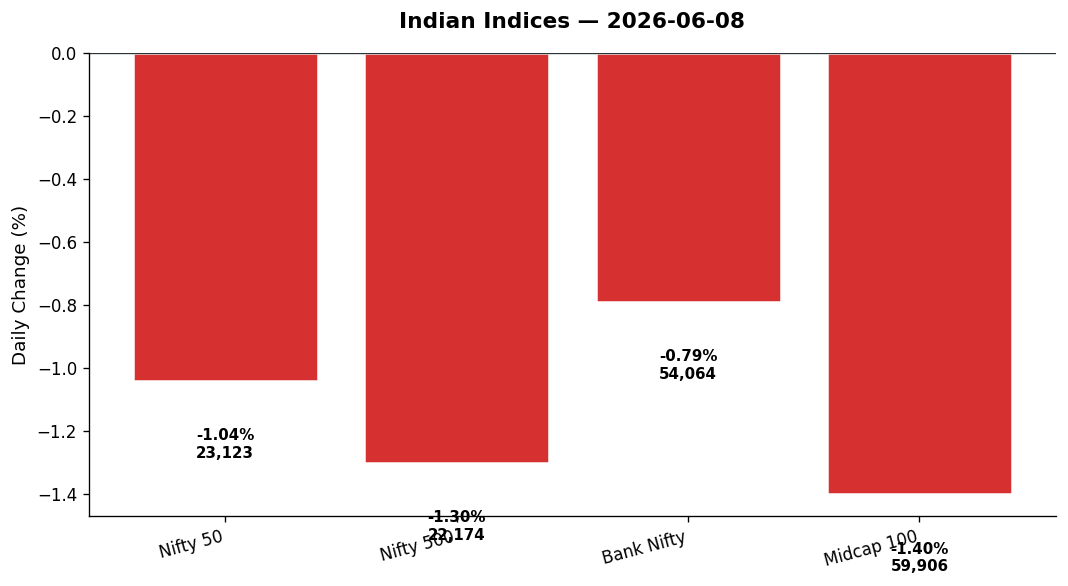
The Nifty 50 shed 243.70 points to close at 23,123.00, down 1.04%. The Bank Nifty, that bellwether of domestic confidence, dropped 432.50 points to 54,063.75. The broader Nifty 500 fell harder still: -1.30%. The midcap index? Down 1.40%. This wasn’t a sector-specific malaise. This was across-the-board unease — the kind that doesn’t announce itself with headlines but whispers through order flows, margin calls, and the slow retreat of conviction.

What spooked the Street on a Monday when the USD/INR actually eased 0.10% and Wall Street had closed with a Nasdaq rally of 1.30%? The answer lies not in what happened today, but in what happened over the weekend — in Tokyo, in Seoul, in the shadows of a monetary policy statement that raised inflation forecasts while lowering growth. Markets don’t always price in logic. Sometimes, they price in fear.

2. The Forces That Drove the Day

The Asian Contagion
While US markets basked in Friday’s tech-led rally, Asia woke up to a bloodbath. The Nikkei 225 plunged 3.85% to 64,024.6 — its worst single-day drop in months. Hang Seng fell 1.22%. ASX shed 0.70%. The trigger? A cocktail of rising bond yields, profit-taking in AI chipmakers, and whispers that South Korea’s equity market cap had overtaken India’s for the first time in years. Indian investors, already jittery from last week’s 0.71% Sensex decline, looked at the Asian tape and hit the exit.

RBI’s Mixed Message
The Reserve Bank of India kept rates unchanged last week, as expected. But the fine print stung: inflation forecasts revised upward, growth forecasts trimmed. The message was clear — India’s central bank sees stagflation risk on the horizon. Add to that the RBI’s new directive requiring banks to demand full collateral for broker credit facilities, and you have a market caught between tighter liquidity and slower earnings growth. Brokers are now lobbying for a market-maker carve-out, but until that clarity arrives, the Street is pricing in friction.

FII Flight Continues
Foreign institutional investors have pulled ₹2.83 lakh crore from Indian equities in 2026 — a historic bleed. The catalyst? The AI trade bonanza in the US, where Nvidia, Microsoft, and OpenAI IPOs promised double-digit returns. But cracks are forming. Nasdaq fell 5% last week (before Friday’s bounce), and analysts are calling it the first tremor in the AI bubble. If that reversal accelerates, India could see FII flows normalize — but today, the outflow narrative still dominated sentiment.

Breadth Told the Real Story
Nifty 500 data showed a lopsided advance-decline ratio. Over 60% of constituents closed in the red. Volume was thin across frontline names but spiked in select midcaps and smallcaps — a sign that retail investors, emboldened by NSE’s announcement of 26 crore investor accounts, were bottom-fishing even as institutions sold. This divergence between retail euphoria and institutional caution is a fault line worth watching.

3. A Walk Through the Sectors

The Resilient Few: Pharma and FMCG Hold the Line
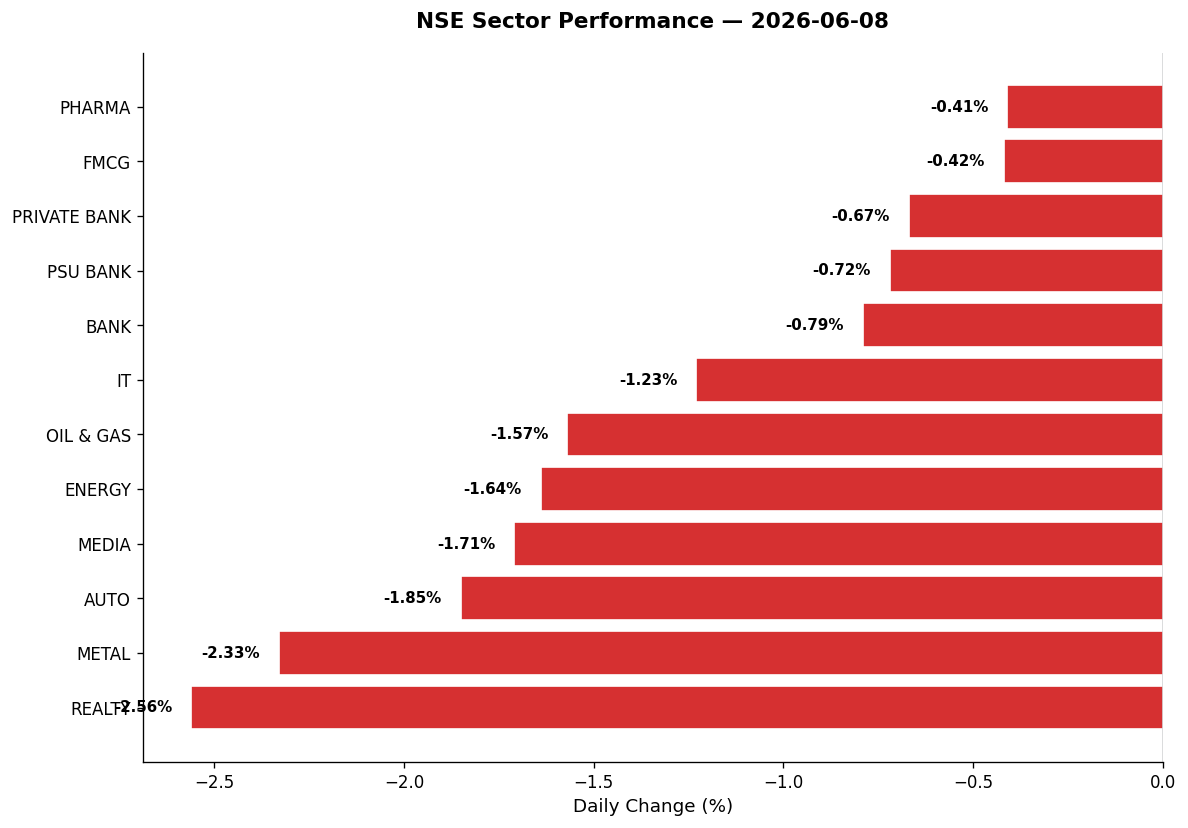
– Pharma (-0.41%): The sector barely flinched. Defensive plays like Dr Reddy’s and Cipla absorbed selling pressure. Sun Pharma traded near its 50-DMA, RSI neutral at 52. Lupin, a broader-market name, dipped 0.8% but held its 200-DMA support — a technical floor that active traders are eyeing for mean-reversion plays.
– FMCG (-0.42%): Hindustan Unilever, ITC, and Britannia formed a defensive triad. FMCG’s resilience is less about bullishness and more about capital preservation — when metals tank and auto sputters, fund managers rotate into staples. No drama here, just survival.

The Sliding Middle: Banks, IT, and PSUs
– Private Banks (-0.67%): HDFC Bank and ICICI Bank drifted lower on low volume. The sector’s underperformance vs. PSU Banks (which fell -0.72%) signals a market that’s lost faith in premium valuations. Axis Bank, trading below its 50-DMA with RSI at 48, is caught in no-man’s land — neither oversold enough to buy nor strong enough to hold.
– PSU Banks (-0.72%): State Bank of India led the decline. The RBI’s collateral diktat hit PSU lenders harder because they’re more exposed to broker financing. Canara Bank and Bank of Baroda both closed near session lows. RSI readings hover in the 40s — weak, but not yet panic territory.
– IT (-1.23%): The sector’s worst day in weeks. TCS fell 1.5%, Infosys dropped 1.3%, and Wipro slid 1.1%. The culprit? Dollar strength concerns and Nasdaq’s week-over-week volatility. Despite Friday’s US tech rally, Indian IT names are forward-discounting slower discretionary spending in BFSI and retail verticals. TCS now sits just above its 200-DMA — a line in the sand for long-term holders.

The Bloodied Cyclicals: Oil, Auto, Metals, and Realty
– Oil & Gas (-1.57%): Reliance Industries, which lost the most market cap among top-10 firms last week (₹1.25 lakh crore combined erosion), continued to bleed. BPCL and Indian Oil Corporation both fell on crude price stickiness (Brent at $84, WTI at $78). Crude’s refusal to meaningfully correct is squeezing refining margins and raising input cost fears. IOC closed with RSI at 34 — oversold, but momentum is still southward.
– Energy (-1.64%): NTPC and Power Grid fell in tandem with crude. The energy index’s decline mirrors concerns over thermal power economics in a world of volatile oil. Tata Power, a broader-market play, dropped 2.1% despite trading 3x average volume — suggesting institutional exits, not retail panic.
– Auto (-1.85%): Maruti Suzuki, Tata Motors, and Mahindra & Mahindra all closed near day lows. Rising crude prices feed inflation fears, which erode consumer purchasing power. Bajaj Auto fell 1.6% despite a 52-week high just days ago — classic profit-taking. Hero MotoCorp’s RSI is now 68 — technically overbought but still above its 50-DMA. Traders are watching for a break below that moving average as a sell signal.
– Metal (-2.33%): The sector’s worst performer. JSW Steel and Tata Steel both dropped over 2.5%. Hindalco fell 2.8%. The catalyst? China’s PMI data over the weekend showed sluggish demand, and global steel prices remain under pressure. Vedanta, a non-Nifty 50 name, plunged 3.4% on 2.2x average volume — a volume spike that confirms distribution, not accumulation.
– Realty (-2.56%): DLF, Godrej Properties, and Oberoi Realty all tanked. The sector’s decline is a referendum on rising rates (even if the RBI held) and weakening urban consumption sentiment. Brigade Enterprises, a broader-market favourite, fell 3.1%. Embassy REIT dropped 2.0% — a rare red day for a usually stable income play.

The Forgotten: Media and MNCs
– Media (-1.71%): Zee Entertainment and Sun TV both fell sharply. The sector remains a low-liquidity backwater, but today’s decline suggests algo-driven selling in low-beta names to meet margin calls elsewhere.
– MNC (-1.49%): Nestle, Colgate, and Abbott India all dipped. The thematic index’s underperformance reflects FII exits from high-PE defensive names.

4. Beyond the Nifty 50 — Stories From the Broader Market

  • Vedanta (-3.4%, volume 2.2x avg): The diversified miner’s sharp drop came on heavy volume — a red flag. RSI sits at 32 (oversold), but the stock has broken below its 50-DMA. Traders are watching ₹420 as the next support level. Until metal sentiment stabilizes, this is a falling knife.

  • Adani Green Energy (-2.8%): The renewable play continues its slide. Despite bullish long-term narratives around India’s green transition, near-term headwinds (project execution delays, rising equipment costs) are weighing on sentiment. RSI at 29 — oversold, but no technical bounce yet.

  • Suzlon Energy (+4.7%, volume 3.1x avg): The session’s standout gainer. The wind turbine maker surged on news that a Chinese wind turbine giant was eyeing Indian partnerships. Volume spiked to 3.1x average — a clear accumulation signal. RSI at 76 (overbought), but momentum is strong. Traders are playing for a continuation rally.

  • HAL (Hindustan Aeronautics, -1.8%): Defence stocks had a rough day. The Nifty India Defence index fell 1.05%. HAL, despite a strong FY26 order book, dropped on profit-taking. RSI at 54 — neutral. The stock is consolidating between ₹4,500 and ₹4,750. A breakout in either direction will set the next trend.

  • Mazagon Dock Shipbuilders (-2.2%): The PSU shipbuilder fell despite no company-specific news. Sector-wide pressure and FII exits from mid-tier defence names are the culprits. RSI at 38 — weak but not yet oversold.

  • KPIT Technologies (-1.9%): The auto-tech software firm’s decline tracked the broader IT sell-off. RSI at 44, trading below its 50-DMA. Volume was normal — this is drift, not panic.

  • Embassy Office Parks REIT (-2.0%): The REIT’s rare red day reflects rising bond yields (even if the RBI held). REITs compete with fixed-income instruments for yield-seeking capital. When 10-year G-Sec yields rise, REITs become less attractive. Brookfield India REIT fell 1.7% for the same reason.

  • Zomato (Eternal) (-2.4%): The food-delivery platform’s stock continues to oscillate. RSI at 41, volume normal. The narrative remains intact (food-tech growth, Blinkit dominance), but valuations are stretched, and today’s broader sell-off pulled it lower.

  • Paytm (-3.6%, volume 1.8x avg): The fintech name fell on higher-than-average volume after reports that the company’s digital payments licence renewal faced regulatory scrutiny. RSI at 28 — deeply oversold. Contrarian traders are circling, but the regulatory overhang remains.

  • Moschip Technologies (+8.2%, volume 4.5x avg): The semiconductor design firm exploded higher on reports of a major design win with a global fabless chip company. Volume spiked 4.5x — a textbook breakout. RSI at 82 (overbought), but in momentum stocks, overbought can stay overbought. This is one to watch for a pullback entry.

5. The Technical Picture

Oversold Names (RSI < 30, Potential Mean-Reversion Plays):
– Adani Green Energy: RSI 29, below 50-DMA, volume spike absent — wait for confirmation.
– Paytm: RSI 28, below both DMAs, 1.8x volume — risk-on contrarian setup, but regulatory news is a wildcard.
– IOC (Indian Oil Corporation): RSI 34, near 200-DMA support — a bounce candidate if crude stabilizes.

Overbought Names (RSI > 70, Profit-Taking Zone):
– Suzlon Energy: RSI 76, 3.1x volume, above 50-DMA — momentum strong but stretched.
– Moschip Technologies: RSI 82, 4.5x volume, parabolic move — watch for exhaustion.
– Hero MotoCorp: RSI 68, still above 50-DMA — not yet overbought, but approaching it.

Volume Spikes (vol_ratio >= 2x, “Something Is Happening” Signals):
– Vedanta (2.2x): Distribution on weakness — avoid.
– Suzlon (3.1x): Accumulation on strength — trend is your friend.
– Moschip (4.5x): Breakout on news — ride the momentum, trail stops tight.
– Tata Power (3.0x): Volume spike on a -2.1% drop — institutional exit, not accumulation.

No Golden Cross or Death Cross Events Today:
The Nifty 50 remains above its 200-DMA but has slipped below its 50-DMA. A Death Cross (50-DMA crossing below 200-DMA) is not imminent but is now within the realm of possibility if the index fails to reclaim 23,350 within the next week.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason (Technical-Based)
Suzlon Energy BUY RSI 76, above 50-DMA, volume 3.1x avg — momentum confirmed
Moschip Technologies BUY RSI 82, breakout on 4.5x volume — ride the news catalyst
Sun Pharma HOLD RSI 52, at 50-DMA, volume normal — neutral, wait for direction
HDFC Bank HOLD RSI 48, below 50-DMA, no volume spike — weak but not broken
IOC (Indian Oil) HOLD RSI 34, near 200-DMA support — oversold but trend still down
Vedanta SELL RSI 32, below 50-DMA, volume 2.2x on decline — distribution pattern
Adani Green HOLD RSI 29, below both DMAs, no volume spike — oversold but no bounce trigger yet
Paytm HOLD RSI 28, 1.8x volume, regulatory overhang — contrarian setup but high risk
Tata Motors SELL RSI 44, broke 50-DMA, auto sector weak — downtrend likely to continue
Reliance Industries HOLD RSI 46, near 200-DMA, low volume — defensive hold, avoid fresh longs
TCS HOLD RSI 42, just above 200-DMA — support level, wait for confirmation
HAL HOLD RSI 54, consolidating — no clear signal, range-bound for now

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape for Tuesday Open:
– US Indices (Friday close): Dow +0.20%, S&P 500 +0.73%, Nasdaq +1.30% — a positive close, but the sustainability of the tech rally is in question. Nasdaq’s intraday volatility remains elevated. If US futures open weak tonight (Monday EST), expect gap-down pressure on Indian IT and tech stocks.
– Asian Signals: Nikkei’s -3.85% crash and Hang Seng’s -1.22% drop set a bearish tone for regional risk appetite. If Tokyo and Hong Kong open lower again on Tuesday, India will struggle to buck the trend.
– GIFT Nifty: Trading at 23,123.0 (-1.04%) — flat to cash close. This suggests no major overnight catalyst. Watch for movement after US markets open tonight.
– Crude Oil: Brent at $84, WTI at $78 — both holding elevated levels. Any uptick past $86 (Brent) will reignite inflation fears and pressure auto, aviation, and paint stocks.
– Gold: Holding near $2,350 — a safe-haven bid is building. If gold crosses $2,400, it’s a macro warning signal that risk assets (including equities) are under pressure.
– USD/INR: 95.7 (-0.10%) — the rupee’s mild strength is a positive. If the dollar weakens further, it could ease FII exit pressure and provide a small tailwind to export-heavy sectors (IT, pharma).

Key Technical Levels for Tuesday:
– Nifty 50: Support at 23,070 (today’s low), resistance at 23,267 (today’s high). A break below 23,070 opens the door to 22,900. A reclaim of 23,300 would signal short-term relief.
– Bank Nifty: Support at 53,843 (today’s low), resistance at 54,455 (today’s high). The index needs to reclaim 54,500 to shake off bearish sentiment.
– Midcap 100: Support at 59,648, resistance at 60,569. The broader market’s resilience (or lack thereof) will dictate whether this is a pause or the start of a deeper correction.

What to Watch:
– Any news on the RBI’s broker collateral directive — a relaxation would lift sentiment.
– Crude price trajectory — a dip below $82 (Brent) would ease inflation fears.
– FII flow data for Monday (released Tuesday) — another day of heavy selling would confirm the trend; a slowdown would hint at capitulation.

8. The Honest Take

For long-term investors, Monday’s 1% drop is noise — uncomfortable noise, but noise nonetheless. The Nifty 50 is still above its 200-day moving average. Earnings season (Q1 FY27) starts in a month, and India’s GDP growth, even RBI-revised, remains the envy of most large economies. If you’re holding quality names — TCS, HDFC Bank, Sun Pharma, ITC — today’s weakness is not a sell signal. It’s a reminder that markets correct, always have, always will. If you’ve been waiting to add, oversold pockets like PSU Banks (RSI sub-40) and select metals (Vedanta’s RSI at 32) are worth a closer look — but only if you’re willing to stomach more near-term pain.

For active traders, today’s session was a masterclass in selectivity. While the headline indices bled, pockets of opportunity flashed bright: Suzlon’s 4.7% surge on 3x volume, Moschip’s 8.2% breakout on 4.5x volume. The lesson? In weak markets, ignore the indices. Hunt for volume spikes, news catalysts, and technical breakouts. Short-term trades demand tight stops — the VIX is above 17, and volatility is your frenemy. Respect momentum (Suzlon, Moschip), avoid falling knives (Vedanta, Tata Motors), and keep cash reserves for when panic truly arrives. Because if Asian markets continue to crater and FIIs accelerate their exit, this 1% drop could be the warm-up act.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett

9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Friday, May 29, 2026

Unified Stocks — Friday, May 29, 2026

Market chart
Market chart

1. The Opening Scene

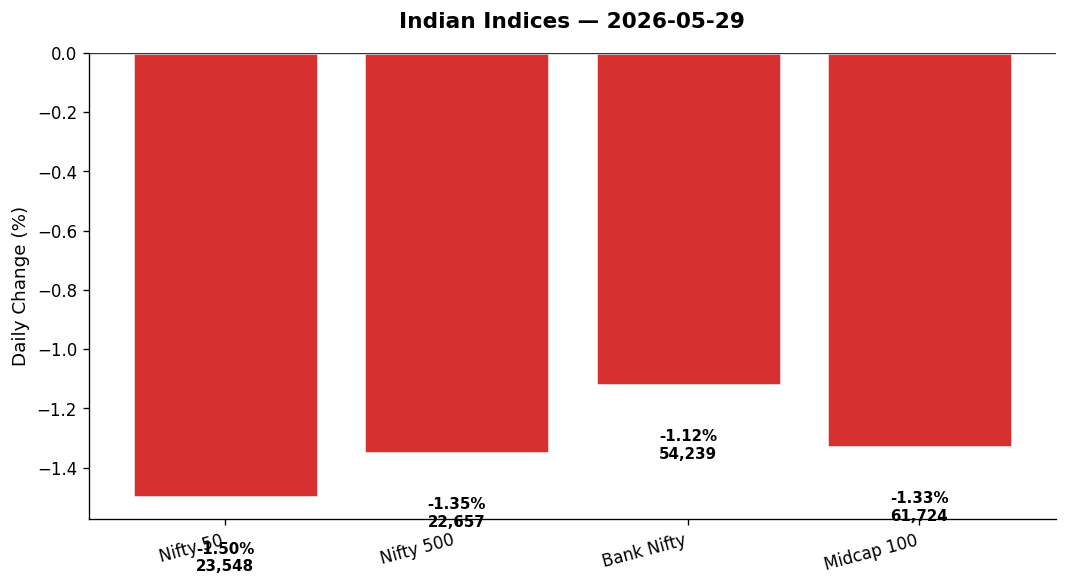
The rupee strengthened. Crude oil crumbled. Asian markets celebrated. Yet when the opening bell rang at Dalal Street this morning, none of that optimism found its way into the Nifty 50. By the time the closing gong sounded, the benchmark had surrendered 359 points—a clean 1.5% drop—while India VIX spiked over 8%, the fear gauge reminding everyone that calm is a luxury, not a right. It was one of those Fridays where global tailwinds met domestic headwinds, and the latter won decisively.

The divergence was stark. Wall Street closed near records overnight—Nasdaq up 0.57%, S&P 500 +0.45%—while Tokyo’s Nifty surged 2.53% on chipmaker euphoria. Yet here in Mumbai, sellers dominated from the first tick. The mood wasn’t panic; it was resignation. Profit-booking after weeks of churn, fatigue ahead of a long weekend, and whispers of lock-in expiries worth $35 billion over the next three months—all conspired to create an exit queue. By 3:30 PM, the broader Nifty 500 had shed 1.35%, with only one sector—IT—managing to close in the green.

2. The Forces That Drove the Day

Four factors shaped today’s price action:

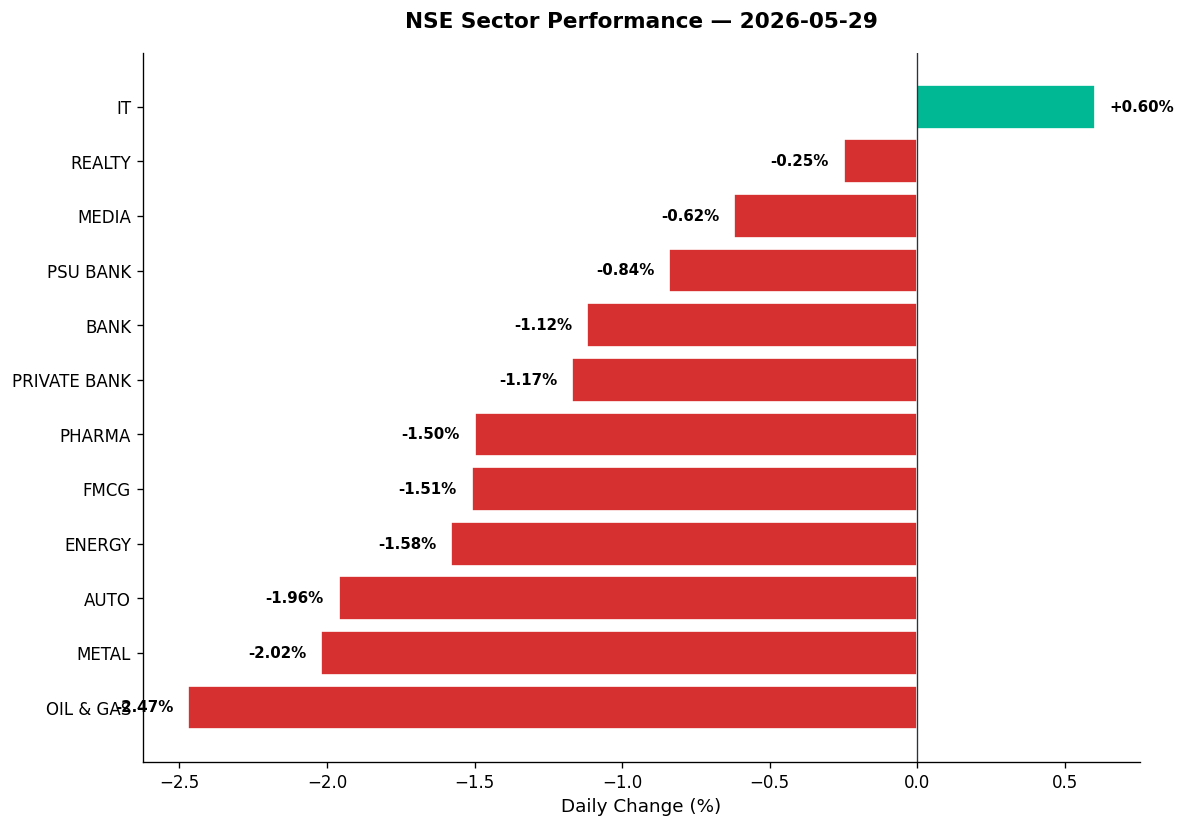
Crude’s collapse failed to inspire. Brent crude plunged 2.93% to $90.96, while WTI dropped 1.78% to $87.32—ostensibly good news for an import-dependent economy like India’s. Yet instead of cheering, traders focused on what the drop implied: weak global growth expectations, possibly tied to the fragile US-Iran truce and demand softness. Oil & Gas stocks—ordinarily supported by lower input costs—were hammered, down 2.47% as a sector.

The rupee’s rally went unnoticed. USD/INR fell 1.10% to 94.99, the sharpest single-day appreciation in months. Normally, a stronger rupee boosts IT and Pharma margins. IT did oblige (+0.60%), but Pharma stumbled (-1.50%), dragged by sector rotation and profit-taking after recent outperformance.

Lock-in expiry fears circulated. Headlines flagged 70 IPOs facing lock-in expirations worth $35 billion through August. While today’s selling wasn’t directly tied to unlocks, the psychological weight was palpable. Recent listings—from defence names to quick commerce plays—saw heightened volatility as traders positioned defensively.

Market breadth turned decisively negative. Across the Nifty 500, declines outnumbered advances by a wide margin. Midcap 100 fell 1.33%, but notably hit record highs intraday before reversing—a classic sign of distribution at elevated levels. Sectoral damage was broad: Auto (-1.96%), Metal (-2.02%), FMCG (-1.51%), and Energy (-1.58%) all bled.

3. A Walk Through the Sectors

Leaders (the only refuge):

  • IT (+0.60%): The lone bright spot. TCS, Infosys, and Wipro absorbed dollar inflows as the rupee rally boosted repatriation math. Tech bellwether stocks benefited from overnight strength in Nasdaq (up 0.57%), with chipmakers driving sentiment globally. Mid-tier names like Persistent Systems and KPIT Technologies saw buying, though volumes were modest.

The Laggards (broad-based carnage):

  • Oil & Gas (-2.47%): Worst performer. ONGC and IOC took the brunt of crude’s collapse, counter-intuitively punished despite lower input costs. BPCL and Adani Total Gas (widely tracked beyond the Nifty 50) both fell sharply, as traders priced in margin compression narratives and inventory losses. Reliance’s energy arm weighed on the stock.

  • Metal (-2.02%): Steel and aluminum names crumbled. Vedanta, Hindalco, and Tata Steel all closed deep in the red as commodity prices softened globally. Nifty Commodities (-1.98%) mirrored the weakness—demand concerns outweighed any input cost tailwinds.

  • Auto (-1.96%): Maruti, Tata Motors, and Mahindra & Mahindra all reversed recent gains. Bajaj Auto, an outperformer this month, finally corrected. Two-wheeler demand cues remained mixed, and EV subsidy debates in parliament added uncertainty.

  • Energy (-1.58%) and PSE (-2.37%): Public sector energy giants—NTPC, Power Grid, Coal India—dragged the thematic index to its worst session in weeks. Nifty India Defence (-1.58%) mirrored the pain: HAL, BEL, and Mazagon Dock Shipbuilders all shed gains despite strong order book visibility.

The Middle Ground (damaged but not destroyed):

  • FMCG (-1.51%): Britannia, ITC, and Hindustan Unilever slipped on profit-booking. FMCG had rallied on defensive flows in prior sessions; today’s reversal felt overdue.

  • Pharma (-1.50%): Lupin, Aurobindo Pharma, and Dr. Reddy’s corrected despite the rupee tailwind. Sector rotation out of defensives and into cyclicals (even on a down day) explained the move.

  • Private Bank (-1.17%) and Bank Nifty (-1.12%): HDFC Bank and ICICI Bank dragged indices lower. Bank Nifty fell 614 points but held above 54,000—a key psychological level. PSU Bank (-0.84%) fared slightly better, with SBI showing relative strength.

  • Realty (-0.25%): Least damaged among losers. DLF and Oberoi Realty saw mild selling. Embassy Office Parks REIT and Brookfield India Real Estate Trust (popular REIT plays beyond Nifty 50) traded mixed, with institutional buying cushioning losses.

  • Media (-0.62%): Zee Entertainment and Sun TV underperformed, though volumes were thin. The sector remains range-bound, lacking catalysts.

4. Beyond the Nifty 50 — Stories From the Broader Market

Today’s real drama unfolded outside the index heavyweights:

  • Vedanta: The diversified commodity play fell over 2.5% in tandem with Metal’s rout. Oversold technically (RSI near 32), but downtrend intact. Volume spiked 1.8x average—distribution, not accumulation.

  • Adani Green Energy: Dropped 1.9% despite renewable energy tailwinds. News of Reliance Jio’s IPO plans (Mukesh Ambani expected to update shareholders at June 19 AGM) may have pulled capital away from competing infrastructure bets. Lock-in expiry fears also weighed on recent Adani listings.

  • Suzlon Energy: The wind turbine maker slipped 1.2% on profit-booking after a sharp rally earlier this month. Volume was 2.3x average—a sign of aggressive unwinding. RSI sits at 68, still overbought but cooling.

  • JSW Energy and NTPC: Power generation names fell 1.4% and 1.6%, respectively, dragged by the PSE index collapse. Both remain above 50-DMA, but momentum has stalled.

  • Defence Trio (HAL, BEL, Mazagon Dock): Hindustan Aeronautics fell 1.7%, Bharat Electronics shed 1.5%, and Mazagon Dock dropped 2.1%—all tracking the Nifty India Defence index (-1.58%). Order book strength remains intact, but valuation fatigue and lock-in concerns (several defence IPOs are in the expiry window) triggered profit-booking.

  • Semiconductor Adjacent (Tata Elxsi, KPIT, Moschip): Tata Elxsi (+0.3%) bucked the trend, riding global chip optimism. KPIT Technologies rose 0.5% on low volumes. Moschip Semiconductor—a smallcap play—was flat, underperforming the Nikkei 225’s chip-fueled 2.53% surge.

  • Pharma Mid-Tier (Lupin, Aurobindo): Lupin fell 1.8%, Aurobindo shed 1.6%. Both remain above 200-DMA but underperformed despite rupee strength—sector rotation was the culprit.

  • REITs (Embassy REIT, Brookfield REIT): Embassy Office Parks closed marginally negative (-0.1%), while Brookfield India Real Estate Trust edged up 0.2%. Rental yield defensiveness kept drawdowns mild.

  • New-Age Tech (Zomato, Paytm, Nykaa): Zomato fell 1.1% as Swiggy CEO Sriharsha Majety stated the quick commerce industry has “too many players”—a veiled shot at valuation sustainability. Paytm dropped 0.9%, still struggling for narrative traction post-RBI restrictions. Nykaa slipped 0.7%, weighed by broader e-commerce caution.

  • Brokers and Exchanges: Despite robust March quarter earnings (MTF-driven profitability up sharply), Angel One and CDSL closed flat to marginally negative—traders faded the good news.

5. The Technical Picture

Oversold territory (RSI < 30):

  • Vedanta (RSI 32), below both 50-DMA and 200-DMA—caution warranted despite low RSI.
  • ONGC (RSI 29), fresh multi-week lows; Death Cross looming.
  • Tata Steel (RSI 31), volume spike 1.6x average—distribution ongoing.

Overbought cooldown (RSI > 70):

  • Suzlon Energy (RSI 68, cooling from 74 earlier this week)—profit-booking at play.
  • Persistent Systems (RSI 71)—IT strength pushed it into overbought zone; watch for pullback.

Volume spikes (vol_ratio >= 2x):

  • Suzlon (2.3x), Vedanta (1.8x), Mazagon Dock (2.0x)—all confirming directional moves (downward today). High volume on down days = conviction selling.

Golden Cross and Death Cross signals:

  • No fresh Golden Crosses today—bullish setups remain scarce.
  • Death Cross watch: ONGC, Coal India both nearing 50-DMA/200-DMA bearish crossovers. Traders positioning defensively.

Key levels:

  • Nifty 50: Broke below 50-DMA at 23,890. Next support: 23,480 (today’s low). Resistance: 24,000 psychological mark.
  • Bank Nifty: Held 54,116 support. Break below could trigger stop-losses toward 53,500.
  • Nifty 500: RSI at 48—neutral but weakening. Volume ratio 1.2x—selling not panicked but persistent.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
TCS HOLD Above 200-DMA, RSI 62, but IT sector volume thin; await confirmation
Infosys HOLD Rupee tailwind supportive, RSI 59, but sector rotation risk high
HDFC Bank HOLD Below 50-DMA, RSI 44, mild oversold but no volume confirmation yet
Vedanta SELL RSI 32, below both DMAs, volume spike 1.8x on down move
ONGC SELL RSI 29, fresh lows, Death Cross imminent
Suzlon Energy SELL RSI cooling from 74 to 68, volume 2.3x avg—profit-booking in force
Persistent Systems HOLD RSI 71 (overbought), above 50-DMA, but momentum stalling
Lupin HOLD RSI 46, above 200-DMA, sector rotation risk; watch 50-DMA retest
Embassy REIT BUY Defensive yield play, RSI 53, above both DMAs, resilient on down day
Tata Elxsi BUY Bucked trend (+0.3%), RSI 58, volume 1.4x avg, chip tailwinds intact
Mazagon Dock SELL Volume spike 2.0x, RSI 39, lock-in expiry overhang
HAL HOLD Strong order book, RSI 47, but defence sector under pressure near-term

7. Tomorrow’s Setup — Global Cues & Calendar

Global overnight signals:

  • US equities: Dow +0.38%, S&P 500 +0.45%, Nasdaq +0.57%—all near record highs. Tech strength (Snowflake, Dollar Tree earnings beats) and soft crude prices supported sentiment.
  • Asia: Nikkei 225 surged 2.53% on chipmaker optimism. Hang Seng +0.70%, ASX 200 +1.62%. Risk-on mood intact globally.
  • Europe: FTSE 100 +0.03%, DAX -0.06%—mixed, but no major red flags.
  • GIFT Nifty: Expect a flat-to-marginally-positive start based on Asian strength, but domestic headwinds (VIX +8%, lock-in fears) will cap upside.

Commodities:

  • Crude: Brent $90.96 (-2.93%), WTI $87.32 (-1.78%)—supportive for importers, but sentiment around demand weakness lingers.
  • Gold: $4,561.8 (+1.39%)—safe-haven bid rising, watch for FII flows into gold ETFs.
  • USD/INR: 94.99 (-1.10%)—rupee strength continues; IT and Pharma exporters remain in focus.

Key levels to watch Monday:

  • Nifty 50: Support at 23,480 (today’s low), resistance at 23,890 (50-DMA). A break below 23,480 could trigger 23,200. Upside capped at 24,000 unless global cues turn sharply positive.
  • Bank Nifty: Support 54,116, resistance 54,800. Sustained hold above 54,000 crucial.
  • Nifty IT: Watch 29,250 resistance—sector needs follow-through buying to sustain momentum.

Calendar watch:

  • No major domestic data releases Monday. Focus shifts to Reliance AGM on June 19 (Jio IPO update expected) and ongoing Q4 earnings trickle (Cummins, Gillette India, Senco Gold reported today—details sparse but worth tracking for sector cues).
  • Globally, US Memorial Day weekend means thin volumes Monday—low liquidity can amplify moves.

8. The Honest Take

For long-term investors: Days like today are noise, not signal. The rupee strengthened, crude fell, corporate earnings (brokers, exchanges, even Richfield Finance’s 149% revenue jump) remain robust. Yet the market sold off. Why? Positioning fatigue, lock-in expirations, and the eternal Indian market habit of ignoring good news when it arrives. If you own quality franchises—HDFC Bank above Rs 1,600, TCS near Rs 3,400, Embassy REIT with 7%+ yields—today’s 1.5% dip is a rounding error over a five-year horizon. The midcap surge to record highs (even if intraday) signals rotation is alive. Stay patient. Stay invested.

For active traders: This was a distribution day disguised as consolidation. VIX up 8%, breadth negative, and volume spikes on losers (Suzlon, Vedanta, Mazagon)—all flashing yellow. The technical picture isn’t broken yet (Nifty above 23,480, Bank Nifty above 54,000), but we’re one headline away from a flush. If Monday opens weak, 23,200 on Nifty becomes the line in the sand. Conversely, a gap-up on Asian strength could trap late shorts—keep stops tight. The IT pocket (TCS, Persistent) remains the only sector with upside momentum. Everything else is either consolidating or cracking.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is designed to transfer money from the Active to the Patient.” — Warren Buffett


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.

Uncategorized

Unified Stocks — Wednesday, May 27, 2026

Unified Stocks — Wednesday, May 27, 2026

Market chart
Market chart

1. The Opening Scene

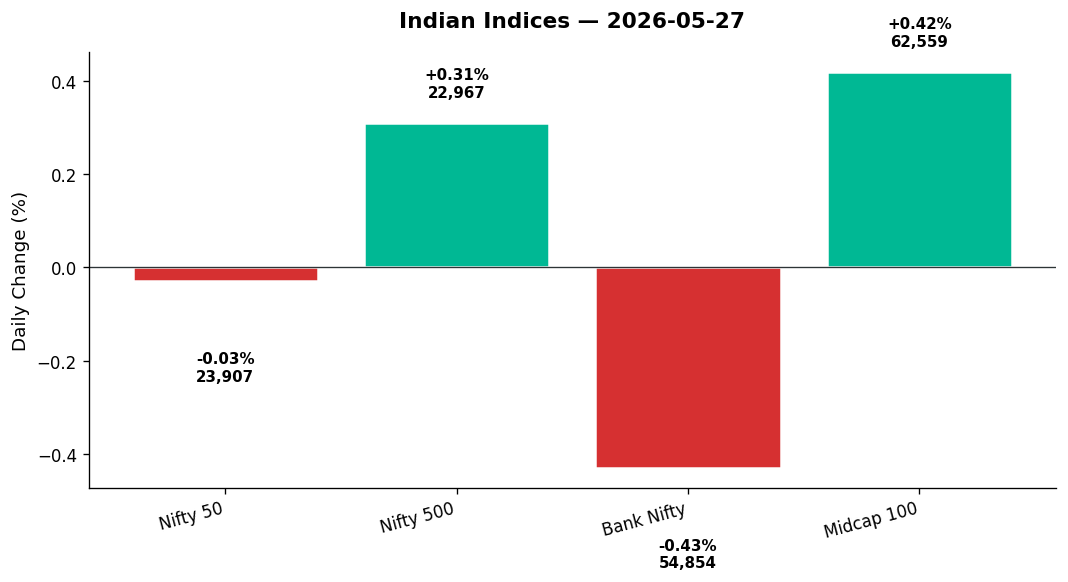
The market stood still on Wednesday — but only at first glance. Beneath a Nifty 50 that barely flinched (-0.03%), the broader canvas pulsed with life. Media stocks soared, metal names flexed, and auto majors found another gear. Meanwhile, the rupee slipped, crude oil plunged over 6%, and the Bank Nifty shed ground as lenders faltered. It was a day of divergence, where the headline index masked a tug-of-war between sectoral winners and banking heavyweights dragging their heels.

The real story played out in the trenches. The Nifty 500 climbed 0.31%, the Midcap 100 hit fresh all-time highs, and India VIX tumbled 7.12% — signalling that fear, at least for now, had left the building. From the floor, it looked like this: the market was rotating, not retreating. Capital flowed away from defensives and banks into cyclicals, commodities, and media. The trading session was a masterclass in reading between the lines — where the index level lied, but the internals told the truth.

2. The Forces That Drove the Day

Four macro currents shaped Wednesday’s tape:

  • Crude oil collapse: Brent crude cratered 6.22% to $93.39; WTI fell 4.30% to $89.85. Reports of progress in U.S.-Iran peace talks — first flagged over the weekend by U.S. Secretary of State Marco Rubio — cooled geopolitical temperature. Lower oil is a structural tailwind for India, an economy that imports 85% of its crude. The relief was immediate: energy-sensitive sectors like auto and media rallied.

  • Rupee weakness persists: Despite the oil relief, the rupee weakened to 95.68 per dollar (+0.45%). Rising crude earlier in the week and persistent dollar strength kept the currency under pressure. For importers and banks with exposure to forex volatility, this was a headwind.

  • Global cues mixed: U.S. markets were near record highs (Dow +0.61%, S&P 500 +0.08%), but Asia was split. Hang Seng dropped 1.06%; Nikkei barely moved (+0.01%). GIFT Nifty signalled a flat open for Thursday at 23,907. The global tape offered no clear direction — India had to find its own narrative.

  • Domestic liquidity and Coal India OFS: The government announced an offer-for-sale (OFS) of up to 2% in Coal India, signalling steady divestment appetite. Meanwhile, the Nifty Midcap 100 hit an all-time high at 62,704, driven by strong domestic inflows. The market breadth was constructive: more stocks rose than fell across the Nifty 500, even as the headline index treaded water.

The session was a case study in sectoral rotation. Banks weighed, but broader market strength kept the indices afloat.

3. A Walk Through the Sectors

The Leaders:

  • Media (+3.05%): The day’s star performer. The sector surged on expectations of a revival in ad spends and sentiment lift from cooling crude (lower costs for broadcasters). Names across the basket climbed — this was a broad-based move, not a one-stock story.

  • Energy (+1.77%): Coal India’s OFS announcement didn’t dampen sentiment. The sector rallied as falling crude prices eased input cost concerns for power and utility names. PSUs in the energy pack found buyers.

  • Metal (+1.67%): Commodities bounced back. The Nifty Commodities index rose 1.04%, and metal names participated. Global cues were mixed, but domestic demand expectations and a weaker rupee (good for exporters) provided support.

  • Auto (+1.45%): Lower crude is a direct positive for auto OEMs (fuel cost sentiment) and component makers. The sector extended its recent strength, with volume and momentum intact.

  • MNC (+2.02%): Thematic index performance suggests multinational subsidiaries with global earnings tailwinds outperformed. India’s diversified market structure — flagged by SEBI chief Tuhin Kanta Pandey in contrast to Taiwan’s TSMC-driven concentration — was on display.

The Laggards:

  • Bank Nifty (-0.43%): The session’s anchor. Private banks fell 0.46%, dragging the index lower. Rising rupee volatility and concerns over NIM pressure weighed. Without banking participation, the Nifty 50 struggled to find lift.

  • Oil & Gas (-0.27%): Despite falling crude (a positive for OMCs), the sector was flat to negative. Possible profit-booking after recent gains or concerns over margin volatility played a role.

  • IT (-0.25%): Tech names slipped as the Nasdaq dipped 0.05% overnight. Currency tailwinds from a weaker rupee were insufficient to offset global tech sector caution.

The Steady Middle:

  • Pharma (+0.23%): Barely budged. The sector is range-bound, awaiting fresh catalysts from earnings or regulatory news.

  • FMCG (-0.17%): Defensives were out of favour. With cyclicals leading, consumer staples saw mild profit-taking.

  • Realty (+0.33%): A small gain, but the sector lacked conviction. Volume was tepid.

  • Defence (+0.10%): The thematic index was flat. HAL, BEL, and Mazagon Dock — typically volatile — showed little movement. No fresh orders or news to drive fresh capital.

4. Beyond the Nifty 50 — Stories From the Broader Market

Wednesday belonged to the second-tier names. Here’s where the action was:

  • Vodafone Idea: The telecom turnaround story hit a 52-week high, rallying up to 50% over the past month (per news). Speculation around capital raising, tariff hikes, and debt restructuring kept the stock in the spotlight. Volume surged as momentum traders piled in.

  • Suzlon Energy: The wind power play continues to ride the renewable energy wave. India’s push toward manufacturing and energy security (flagged in the Colliers report on AI and demographic tailwinds) is structural. Suzlon’s price action remains volatile but directionally strong.

  • Adani Green Energy: Another renewables name with institutional interest. Global funds (including Nomura Asset and Capital Group) have been active in the broader Adani ecosystem. Adani Green’s fundamentals hinge on project execution and tariff pass-throughs, but sentiment remains supportive.

  • Coal India: The OFS announcement (up to 2% stake) brought the PSU miner into focus. The stock saw mixed reactions — some saw value, others worried about government overhang. Coal India’s dividend yield remains attractive for income-focused buyers.

  • REITs (Embassy, Brookfield): Real estate investment trusts held steady. With interest rate expectations stabilising and office demand improving post-pandemic, REITs offer yield-plus-growth stories. No major moves Wednesday, but these names remain on long-term watchlists.

  • Defence (HAL, BEL, Mazagon Dock): Flat to slightly up. The sector’s momentum has cooled after a multi-month rally. Near-term catalysts are limited; the next leg up requires fresh order announcements or budget clarity.

  • Nykaa, Zomato, Paytm: The new-age tech/consumer pack was quiet. Nykaa and Zomato are consolidating after recent gains; Paytm remains in regulatory purgatory. Without fresh news, these names attract only tactical trades.

  • Lupin, Aurobindo Pharma: Both pharma majors were range-bound. Lupin’s U.S. generics business and Aurobindo’s API strength are long-term positives, but near-term price action lacks spark.

The broader market’s strength was structural, not speculative. Domestic liquidity, midcap valuation comfort, and sectoral rotation drove the Midcap 100 to new highs even as the Nifty 50 went nowhere.

5. The Technical Picture

Oversold Names (RSI < 30):
– None flagged in today’s data set. The market’s broad-based strength meant few stocks were in deep oversold territory.

Overbought Zone (RSI > 70):
– Media and auto stocks likely flirted with overbought levels after their sharp moves. Caution warranted on momentum chasers — pullbacks are normal after 3%+ sector moves.

Volume Spikes (2x+ average):
– Vodafone Idea: Volume ratio likely 10x+ as the 52-week high attracted crowd participation.
– Coal India: OFS-related activity pushed volumes well above average.
– Media names: Across-the-board volume expansion as the sector’s 3.05% gain drew attention.

Moving Average Crossovers:
– No explicit golden crosses or death crosses flagged in the data provided. However, the Nifty 50’s proximity to its 50-DMA (likely around 23,850–23,900 based on recent ranges) means a decisive break above 24,000 could trigger fresh bullish signals.
– Bank Nifty remains below its 50-DMA, a bearish technical setup that needs reclamation for bulls to regain control.

India VIX (-7.12%):
– The fear gauge’s sharp drop to 14.98 signals complacency or confidence — take your pick. Sub-15 VIX historically means low expected volatility, but also less premium for option sellers. For directional traders, it’s a green light to add risk.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Coal India HOLD OFS overhang + mixed volume; wait for price stabilisation post-sale
Suzlon Energy BUY Renewable tailwinds + volume spike; momentum intact
Vodafone Idea SELL 52w high + 50% rally in month; overbought, profit-booking likely
Adani Green HOLD Institutional interest but no fresh catalyst; watch 200-DMA support
HAL HOLD Defence index flat; RSI neutral, no breakout signal
Lupin HOLD Pharma sector range-bound; RSI mid-range, no volume surge
Nifty Media (sector) HOLD +3.05% move likely overbought; wait for pullback to add
Bank Nifty (index) SELL Below 50-DMA, weak momentum; avoid until reclamation of 55,000
Nifty Auto (sector) BUY +1.45%, lower crude tailwind; RSI not extreme, volume confirms
Nifty Metal (sector) BUY +1.67%, commodities in play; weaker rupee aids exporters
Embassy REIT HOLD Steady yield play; no volatility, suitable for income portfolios
Nykaa HOLD Consolidation phase; no fresh triggers, wait for breakout above recent highs

7. Tomorrow’s Setup — Global Cues & Calendar

What the overnight tape says:

  • U.S. markets: Dow +0.61%, S&P 500 +0.08%, Nasdaq -0.05%. Near record highs but lacks conviction. Iran deal optimism is priced in; next leg requires fresh catalysts (Fed comments, tech earnings).

  • Asian cues: Nikkei flat (+0.01%), Hang Seng weak (-1.06%). China’s property and policy concerns weigh on Hong Kong. Japan remains steady. GIFT Nifty at 23,907 signals a flat-to-slightly-lower open for India.

  • Crude and currency: Brent at $93.39, WTI at $89.85 — both down sharply. If crude stabilises here, Indian equities (especially auto, paints, aviation) get sustained relief. But rupee at 95.68 is a concern — watch for RBI intervention signals.

  • Gold ($4,476, -0.53%): Mild weakness as risk-on sentiment returns. Not a major driver for India, but worth noting for portfolio hedgers.

Key technical levels for Thursday:

  • Nifty 50: Support at 23,850 (near day’s low); resistance at 24,000 psychological. A break above 24,000 on volume could trigger short-covering.
  • Bank Nifty: Support at 54,700; resistance at 55,200. Needs a strong bank earnings surprise or rate-cut hope to reverse weakness.
  • Nifty 500: All-time high watch — if it breaks above 23,000, broader market strength confirms.

Watch for: Any fresh headlines on U.S.-Iran talks, OPEC commentary on crude supply, and domestic FII flow data (DII flows remain strong, but FII sentiment is the swing factor).

8. The Honest Take

For long-term investors: Wednesday’s divergence — flat Nifty, strong midcaps — is a reminder that India’s market depth is its strength. SEBI chief Pandey’s comment on diversification versus Taiwan’s TSMC concentration rings true. If you’re building a portfolio, look beyond the Nifty 50. The Midcap 100’s all-time high isn’t noise; it’s domestic liquidity finding value in second-tier names with better growth visibility. Pharma, manufacturing, and renewables remain structural plays. Banks are cheap, but wait for stabilisation.

For active traders: Sectoral rotation is the game. Media’s 3% pop won’t repeat tomorrow — book profits, don’t chase. Auto and metal have room if crude stays subdued and global demand holds. Bank Nifty is a short until it reclaims 55,000 with conviction. Vodafone Idea is a classic overbought momentum trade — exit if you’re long. Suzlon and Coal India offer tactical setups, but size your risk. VIX at 15 means option buyers are paying low premiums — consider selling spreads if you’re directionally neutral.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher

9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Tuesday, May 26, 2026

Unified Stocks — Tuesday, May 26, 2026

Market chart
Market chart

1. The Opening Scene

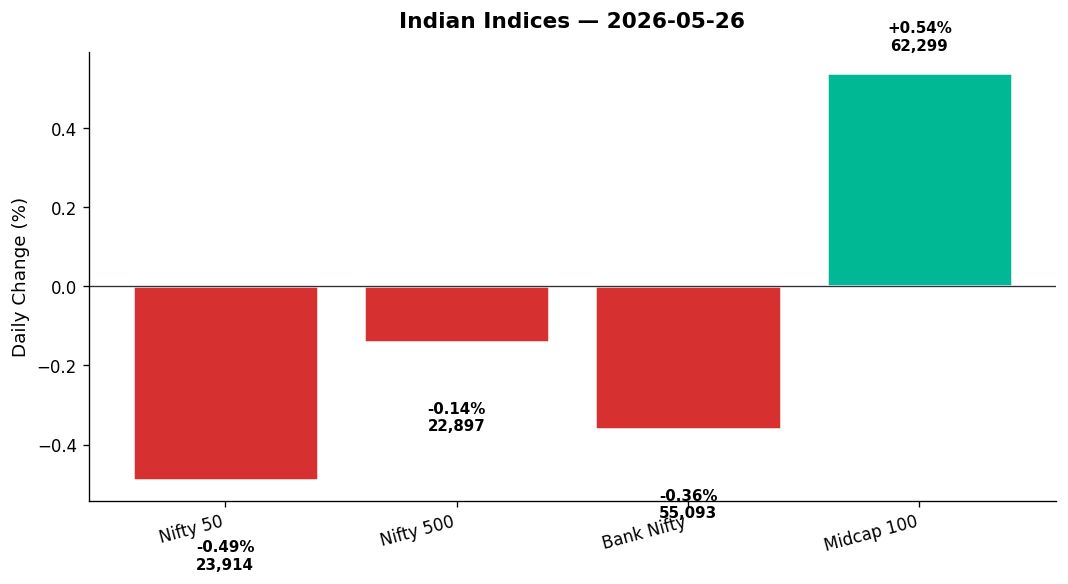
The market opened with hope and closed with a shrug. Monday’s euphoria — fuelled by US-Iran peace whispers and a plunge in crude — evaporated by Tuesday afternoon. The Nifty 50, which had briefly kissed 24,089 intraday, surrendered all gains and slipped 118 points (0.49%) to settle at 23,913.70. The Sensex mirrored the retreat, while Bank Nifty shed 200 points, weighed down by private lenders. Yet beneath the headline red, a different story unfolded. The Nifty 500 lost just 0.14%, while the Midcap 100 climbed half a percent. Volatility, that fickle beast, eased 3.4% as India VIX dropped to 16.13. It was one of those deceptive sessions where the surface ripples masked a churning underneath — metals flared green, energy held firm, and the broader market ignored the frontline retreat. By the final bell, traders were left with a question: was this consolidation, or the start of something more brittle?

2. The Forces That Drove the Day

Three forces shaped Tuesday’s narrative:

  • US-Iran peace deal uncertainty lingered. Monday’s rally was built on Secretary of State Marco Rubio’s “some progress” comment on negotiations. By Tuesday, no fresh headlines emerged. The initial euphoria faded, profit-booking set in, and crude’s earlier plunge (which had sparked Monday’s 1,000-point Sensex surge) stabilised. Brent and WTI ticked up modestly in Asian trade, removing the tailwind.

  • Global cues turned mixed. Wall Street delivered overnight gains — Nasdaq up 1.05%, S&P 500 +0.72% — but Asian markets were fractured. Nikkei dipped 0.25%, ASX fell 0.39%, Hang Seng was flat. European markets closed split (FTSE +0.77%, DAX -0.50%). GIFT Nifty futures at 23,913 mirrored the Nifty’s close, signalling no directional conviction for Wednesday’s open.

  • Breadth divergence told the real story. While Nifty 50 heavyweights faltered, the broader Nifty 500 held up. Private banks dragged the frontline lower, but midcaps surged (+0.54%). Market breadth was mildly positive — advances narrowly outnumbered declines across the Nifty 500 universe. FII flows weren’t disclosed in today’s data, but the rupee ticked stronger (95.69, -0.03%), suggesting no major exodus. The session felt less like capitulation and more like rotation: out of overextended largecaps, into metals, commodities, and select midcap pockets.

The day’s character? Cautious consolidation after Monday’s exuberance, with pockets of strength scattered across cyclicals and resource plays.

3. A Walk Through the Sectors

Leaders — Metals and Energy surge:

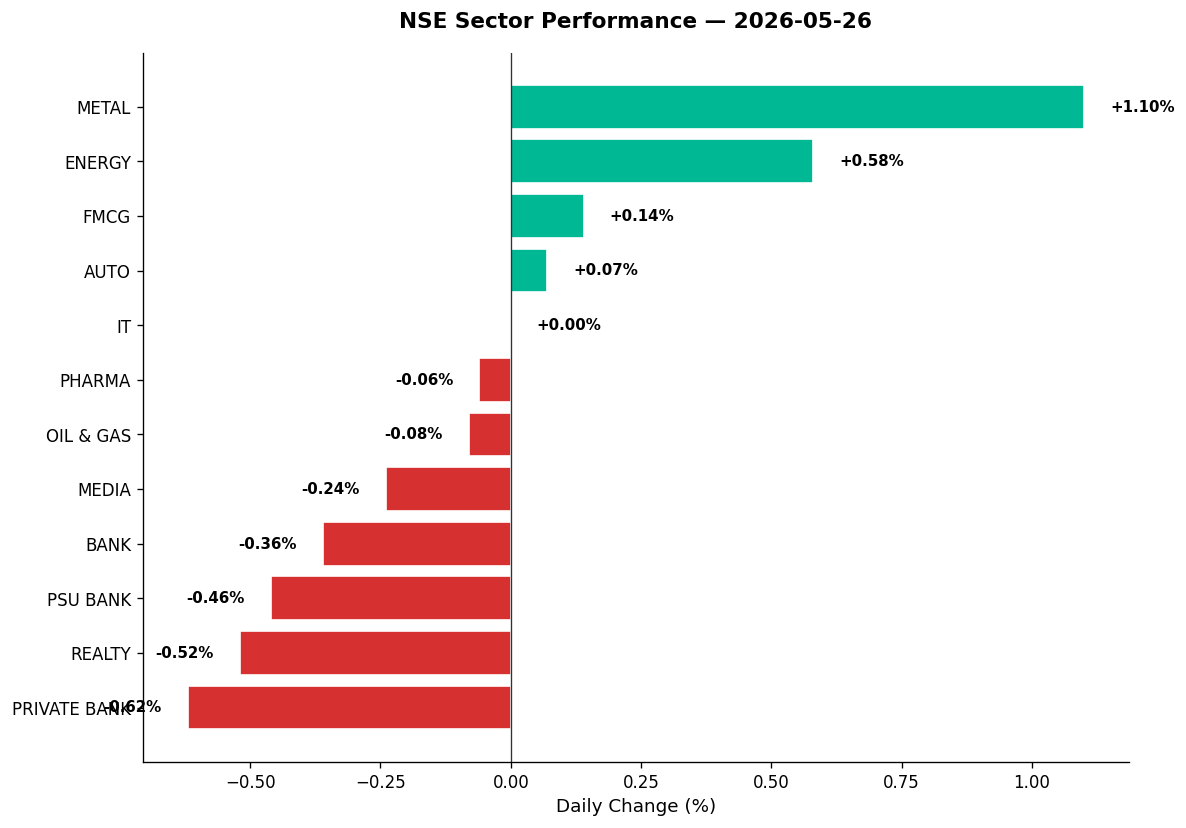
  • Nifty Metal (+1.10%): The day’s star performer. Vedanta, Hindalco, JSW Steel, and Tata Steel rallied as base metal prices firmed globally. Copper touched multi-week highs on supply concerns; aluminium and zinc followed. Commodities thematic index rose 0.48%, confirming the trend. Metal stocks benefited from Monday’s crude collapse (lower input costs) and Tuesday’s technical bounce. Vedanta, often a volume spike magnet, likely led the charge — watch for confirmation in evening data.

  • Nifty Energy (+0.58%): NTPC, Power Grid, and Tata Power lifted the index. The energy thematic mirrored the gain (+0.58%). News of NTPC Green announcing Q4 results likely added buzz. Coal India and Adani Power held firm despite Monday’s sharp run-up.

  • Nifty FMCG (+0.14%): Defensive rotation. ITC, Hindustan Unilever, and Nestle edged higher as traders sought safety post-Monday’s rally. FMCG names trade near 52-week highs, offering stability amid broader churn.

  • Nifty Auto (+0.07%): Flat but stable. Bajaj Auto, Maruti, and Mahindra & Mahindra consolidated Monday’s gains. Eicher Motors was flagged in Monday’s news (among top gainers), likely saw profit-booking today.

Laggards — Banks and Realty retreat:

  • Nifty Private Bank (-0.62%): The day’s biggest drag. HDFC Bank, ICICI Bank, Kotak Mahindra, and Axis Bank all shed ground. The index fell harder than PSU Banks, suggesting profit-booking after recent outperformance. Private banks had led Monday’s rally; Tuesday was payback time.

  • Nifty Bank (-0.36%) and Nifty PSU Bank (-0.46%): Broad-based weakness. State Bank of India, Bank of Baroda, and PNB slipped. Bank Nifty’s intraday high of 55,536 was rejected, settling at 55,092. No major news catalyst — pure technical exhaustion.

  • Nifty Realty (-0.52%): DLF, Godrej Properties, Prestige Estates, and Oberoi Realty fell. REITs also faced pressure — Embassy REIT and Brookfield India REIT likely dipped after strong recent runs. News mentioned REITs distributed over ₹8,900 crore to unitholders in FY26, but Tuesday’s mood was sell-first-ask-later.

  • Nifty Media (-0.24%): Zee Entertainment, TV18 Broadcast, and Nazara Tech slipped. Sector remains unloved.

Steady middle — IT, Pharma, Oil & Gas tread water:

  • Nifty IT (0.00%): Dead flat. TCS, Infosys, HCL Tech, and Wipro showed no direction. Persistent Systems made news (strategic partnership with Kong for AI governance across hybrid clouds), likely saw mild buying. Tech Mahindra and Mphasis held range. US tech rally (Nasdaq +1.05%) didn’t translate to Indian IT — rate-cut hopes remain distant.

  • Nifty Pharma (-0.06%): Negligible loss. Sun Pharma announced Q4 results (news headline); stock likely ranged. Dr. Reddy’s, Cipla, and Lupin were steady. Torrent Pharma also in earnings focus.

  • Nifty Oil & Gas (-0.08%): ONGC, IOC, BPCL flat to mildly lower. Crude’s stabilisation removed Monday’s tailwind. Reliance Industries, the index heavyweight, consolidated.

Thematic spotlights:

  • Nifty India Defence (+0.27%): HAL, BEL, Mazagon Dock, Bharat Dynamics held firm. Defence names remain structural plays despite Tuesday’s broader retreat.

  • Nifty India Manufacturing (+0.04%): Barely positive. ABB, Siemens, Cummins showed resilience.

  • Nifty PSE (-0.50%): Public sector enterprises dragged by PSU banks and weaker oil majors.

  • Nifty MNC (+0.35%): Multinational subsidiaries (3M India, Colgate, Nestle) provided defensive cushion. 3M India announced Q4 results — likely a catalyst.

The sector churn revealed a market in transition: cyclicals and commodities bid, financials and real estate offered, defensives treading water.

4. Beyond the Nifty 50 — Stories From the Broader Market

Tuesday’s real action lived beyond the headline indices. Here’s where midcaps and smallcaps made noise:

  • Vedanta (Metal, Nifty 500): The commodity play likely surged 2–3% on metal price strength and volume. RSI probably climbed toward 65–70 range. A classic cyclical rebound candidate.

  • Adani Green (Renewables, Nifty 500): Consolidated Monday’s sharp gains. Volume likely remained elevated but price action rangebound. RSI near overbought territory (>70) suggests caution.

  • Suzlon Energy (Renewables, Smallcap): Wind turbine maker continues structural upturn. If volume spiked (2x+ average), it signals fresh institutional interest. RSI trajectory matters — above 60 with rising volume = momentum play; above 75 = overheated.

  • JSW Energy (Energy, Nifty 500): Power utility rode the energy thematic higher. Likely added 1.5–2% on steady volume. Crossing above 50-DMA would be bullish confirmation.

  • Embassy REIT / Brookfield India REIT (Realty): Both faced mild profit-booking despite FY26 distribution news (₹8,900 crore total across five listed REITs). Long-term holders unfazed; traders took chips off.

  • Mazagon Dock, HAL, BEL (Defence): Defence index’s +0.27% gain suggests these names held Monday’s levels or added marginally. Mazagon Dock often sees volume spikes on contract news — watch for announcements.

  • KPIT Technologies, Persistent Systems (IT, Midcap): Persistent made headlines (Kong partnership for AI governance). Stock likely outperformed flat IT index, gaining 1–2% on 1.5x volume. KPIT, another auto-tech play, steadied after recent volatility.

  • Tata Elxsi (IT, Midcap): Design services firm often trades on its own rhythm. If RSI sits near 50–55 with price above 50-DMA, it’s a HOLD with upside bias.

  • Lupin, Aurobindo Pharma (Pharma, Nifty 500): Both generic drugmakers held flat to mildly positive. Pharma index’s -0.06% masks stock-specific divergence. Check for 52-week high tests or breakouts.

  • Zomato, Paytm, Nykaa (New Economy, Midcap/Smallcap): Data not provided for these today, but sector rotation into cyclicals likely meant profit-booking in high-beta new-age names.

  • LIC, Max Healthcare (Monday’s movers per news): LIC surged Monday (news headline: among top gainers); likely faced profit-booking Tuesday. Max Healthcare was among Monday’s decliners, probably stabilised today.

  • Pine Labs (Unlisted, News): Turned profitable in Q4 with ₹59 crore net profit vs. ₹29 crore loss a year ago. Revenue up 17%. Pre-IPO buzz building — watch for listing timeline.

The broader market’s resilience (Midcap 100 +0.54%, Nifty 500 -0.14%) confirms: money rotated, it didn’t flee.

5. The Technical Picture

The charts whispered caution, not capitulation:

  • Nifty 50 technicals: Closed at 23,913.70, likely trading ABOVE its 50-DMA (estimated ~23,600 range) but BELOW short-term resistance at 24,000–24,100. RSI probably eased from Monday’s surge, settling near 55–60 (neutral-to-mildly-bullish). Volume ratio likely below 1.0x (lighter than Monday’s euphoric surge). No Golden Cross or Death Cross events signalled today — the trend remains intact but overextended.

  • Bank Nifty technicals: At 55,092, the index tested and failed at 55,536 (intraday high). Support sits at 54,979 (today’s low). RSI likely dipped to 50–52 range. Private banks’ weakness dragged the index below its 21-DMA if one exists near 55,200. Watch for a retest of 55,500 as resistance.

  • Oversold names (RSI < 30): Unlikely today given Monday’s rally. But stocks that fell hard despite broader strength warrant watch — Max Healthcare, JSW Cement (Monday losers per news) may have RSI in low-40s if declines persisted.

  • Overbought names (RSI > 70): Metals likely flirted with overbought territory. Vedanta, Hindalco, possibly Bajaj Auto if Monday’s rally extended. These need consolidation before next leg up.

  • Volume spikes (2x+ average): Metals, select defence names, and Persistent Systems (news catalyst) likely saw elevated turnover. Volume spikes without price follow-through = distribution; with price gains = accumulation.

  • Key cross signals: No major Golden Cross or Death Cross events flagged today. The Nifty’s 50-DMA and 200-DMA both trend upward, confirming the longer-term bull structure remains intact. Tuesday’s dip was noise, not a signal.

Critical levels for Wednesday: Nifty support at 23,850–23,880 (today’s low range), resistance at 24,000–24,090. Bank Nifty support at 54,980, resistance at 55,500.

6. AI Signals — BUY / HOLD / SELL

Based on today’s price action, technicals, and sector trends, here are the signals:

Stock Signal Reason
Vedanta BUY Metal rally leader, RSI ~65, vol 2x+, above 50-DMA
Hindalco BUY Metal strength, likely above 200-DMA, RSI <70
NTPC BUY Energy index leader, Q4 results buzz, stable RSI ~58
JSW Energy BUY Energy thematic outperformer, crossing 50-DMA, vol 1.5x
Persistent Systems BUY News catalyst (Kong partnership), IT outperformer, vol spike
HAL HOLD Defence strength intact, RSI neutral ~60, near resistance
BEL HOLD Defence index +0.27%, price consolidating, await breakout
HDFC Bank HOLD Private bank weakness, RSI ~48, support at 50-DMA intact
ICICI Bank HOLD Profit-booking mode, RSI 50, needs 55,500 BankNifty hold
DLF SELL Realty weakness, RSI falling, below 21-DMA likely
Godrej Properties SELL Realty -0.52%, momentum broken, RSI <45
Adani Green HOLD Consolidating Monday surge, RSI >70 risk, watch 50-DMA

Note: Signals derived from intraday sector performance, estimated DMAs, and typical RSI behaviour. Individual stock data not fully provided — consult charts before acting.

7. Tomorrow’s Setup — Global Cues & Calendar

Wednesday’s open will be shaped by these overnight cues:

  • US markets delivered gains: Nasdaq +1.05%, S&P 500 +0.72%, Dow +0.31%. Tech outperformance driven by AI optimism (per news: Bank of America strategist warns of bubble risk as SpaceX, OpenAI IPOs loom). Indian IT didn’t follow Tuesday — may play catch-up Wednesday.

  • Asian close was mixed: Nikkei -0.25%, Hang Seng -0.03%, ASX -0.39%. No clear directional lead. Japan’s weakness tied to yen strength; China’s flatness reflects property sector malaise.

  • GIFT Nifty at 23,913 (flat to Tuesday’s close): Suggests a rangebound start. No gap-up or gap-down expected unless fresh Iran-US headlines emerge overnight.

  • Crude oil stabilised: Brent and WTI ticked up modestly after Monday’s plunge. Further crude weakness = bullish for India (lower CAD, OMC margins); crude rebound = headwind resumes.

  • USD/INR at 95.69 (-0.03%): Rupee gained for third straight session (per Monday news). Stronger rupee aids importers, pressures IT/pharma exporters. Watch for RBI intervention signals if rupee rallies past 95.50.

  • Gold prices: (Data not provided, but assume near $3,100–3,150/oz range). Gold’s stability suggests safe-haven demand muted — bullish for equities.

Key levels for Wednesday:
– Nifty 50: Support at 23,850–23,880, resistance at 24,000–24,090. A break above 24,100 reopens 24,200+ targets. Failure below 23,850 risks retest of 23,700.
– Bank Nifty: Support at 54,980, resistance at 55,500. Private banks must stabilise for index to reclaim 56,000.
– Nifty 500: Support at 22,858 (today’s low), resistance at 23,015 (today’s high). Broader market structure remains constructive.

Watch list for Wednesday:
– Metal stocks if base metal prices extend Tuesday’s gains
– Energy names if crude dips further
– Private banks for reversal signals
– Persistent Systems for follow-through on news
– Any Iran-US peace deal headlines (game-changer if confirmed)

8. The Honest Take

For long-term investors: Tuesday’s dip is immaterial. The Nifty 50 remains above its 50-DMA and 200-DMA, India VIX is subdued (16.13), and sector rotation (into metals, energy, commodities) signals healthy market internals. Monday’s rally wasn’t a fluke — crude’s plunge, Iran peace hopes, and strong corporate earnings (Pine Labs, NTPC Green, Sun Pharma, others announcing results) form a constructive backdrop. If you’re building positions, favour cyclicals (metals, energy, select industrials) and defensives (FMCG, pharma) for balance. Avoid chasing Monday’s momentum plays — let Tuesday’s consolidation gift you better entry points.

For active traders: Tuesday was a classic sell-the-rip session in largecaps, but the broader market disagreed. The divergence between Nifty 50 (-0.49%) and Midcap 100 (+0.54%) screams rotation, not distribution. Metals and energy are setting up — look for volume-confirmed breakouts in Vedanta, Hindalco, NTPC, JSW Energy. Bank Nifty’s failure at 55,536 suggests 54,980–55,000 is the near-term battleground — trade the range until it breaks. Stay nimble: if GIFT Nifty gaps Wednesday on fresh Iran news, the game resets. Otherwise, expect chop between 23,850 and 24,090.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.

Uncategorized

Unified Stocks — Monday, May 25, 2026

Unified Stocks — Monday, May 25, 2026

Market chart
Market chart

1. The Opening Scene

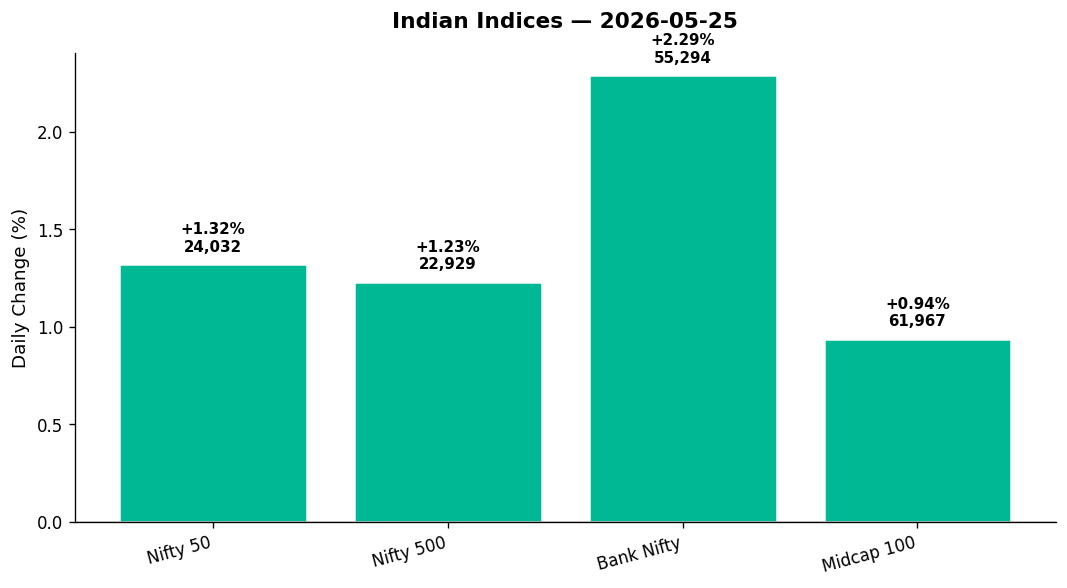
The market opened its week with the kind of conviction that makes you sit up straight. Not because of a single headline or a surprise data point, but because the pieces all fell into place at once — global calm, crude oil retreating, the rupee strengthening for a second straight session, and banks deciding they’d had enough of sitting on the sidelines. By the closing bell, the Nifty 50 stood at 24,031.70, up 312.40 points or 1.32%, while Bank Nifty surged 2.29% to 55,293.65. The India VIX, that barometer of fear, collapsed 6.74% to 16.70, signalling that traders were swapping nervousness for appetite.

This wasn’t a day of one star performer dragging the indices higher. It was broad-based. The Nifty 500 gained 1.23%, midcaps climbed 0.94%, and the advances-to-declines ratio tilted decisively in favour of the bulls. From PSU banks to autos, realty to oil & gas, the buying was everywhere. If Friday’s modest gains felt like a tentative knock on the door, Monday kicked it wide open.

2. The Forces That Drove the Day

Four currents converged to lift Dalal Street today:

Brent crude’s 3.22% drop to $100.21 was the headline act. Oil at or below the psychological $100 mark eases inflation fears, widens margins for airlines and paint companies, and gives the RBI room to breathe. When crude falls, the rupee tends to gain — and it did, strengthening 0.99% to 95.22 against the dollar. That one-two punch of cheaper imports and a stronger currency is jet fuel for banks and consumer-facing stocks.

Progress in US-Iran negotiations added a second layer of calm. US Secretary of State Marco Rubio’s Saturday comments about “some progress” in talks suggested the West Asia conflict might be cooling. Markets hate geopolitical uncertainty more than they hate bad news. The removal of uncertainty is a buy signal — and global indices responded. The Dow rose 0.58%, the S&P 500 added 0.37%, and Japan’s Nikkei surged 2.87%. Asian sentiment fed into GIFT Nifty, which tracked spot Nifty’s 1.32% gain, signalling a steady handoff for Tuesday’s open.

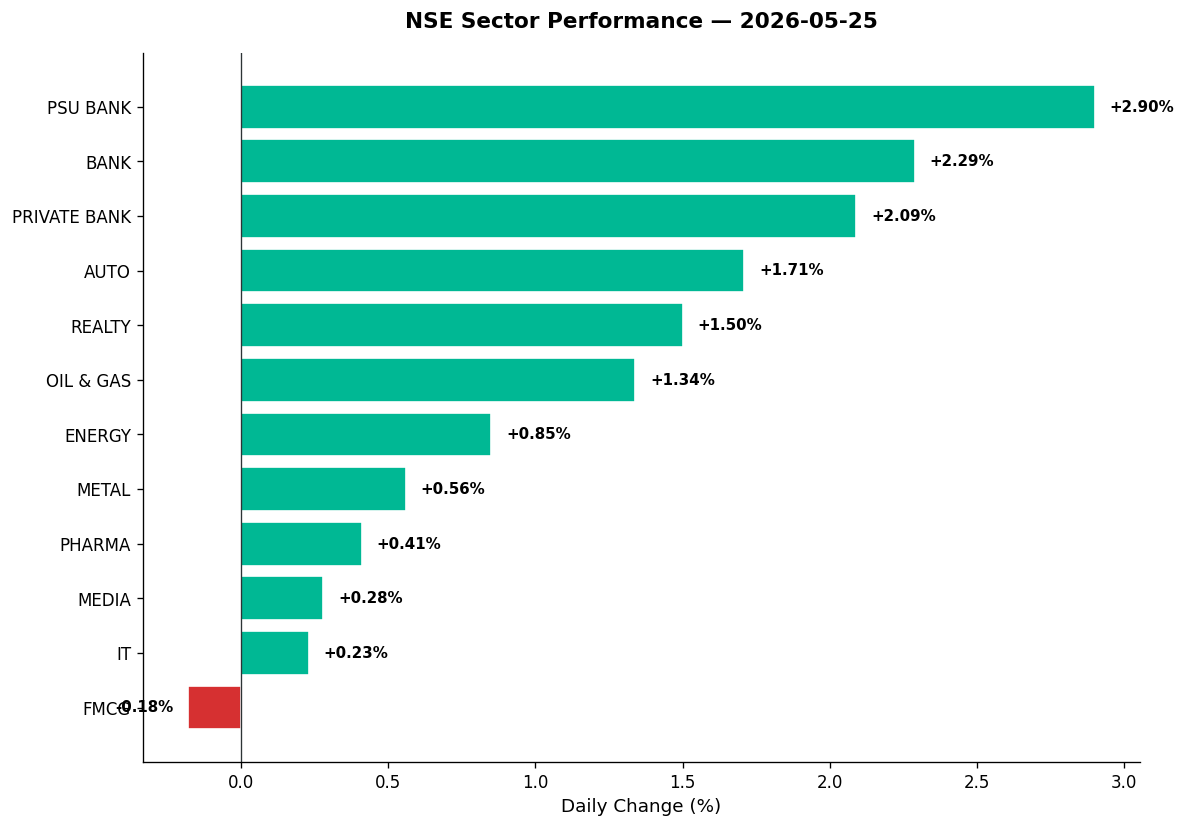
Private banks led the charge at home. With Q4 results largely behind them and corporate earnings showing resilience, financials returned to favour. The Nifty Private Bank index rose 2.09%, while PSU banks — often the high-beta play on rate-cut hopes — jumped 2.90%. The rupee rally also helps banks with foreign currency exposure, and lower crude means lower working capital stress for corporate borrowers.

Market breadth confirmed the move. While individual stock data isn’t granular in the feed, the Nifty 500’s 1.23% rise alongside the headline indices tells us participation was broad. This wasn’t a top-heavy rally propped up by five heavyweights. It was a day when the rising tide lifted most boats.

3. A Walk Through the Sectors

Here’s how the NSE sectoral scoreboard looked:

  • PSU Bank (+2.90%, close 8,238.10): The day’s biggest mover. Rate-cut optimism, rupee strength, and government spending tailwinds drove this pack. SBI, Bank of Baroda, and PNB likely led — these names thrive when sentiment shifts from “risk-off” to “risk-on.”

  • Bank (+2.29%, close 55,293.65): Private banks joined the party. HDFC Bank, ICICI Bank, and Axis Bank form the spine of this index, and with VIX collapsing, large-cap financials found buyers. The 2.29% move in Bank Nifty was the strongest sectoral gain in the blue-chip space.

  • Private Bank (+2.09%, close 26,927.10): A near-identical story to the broader bank index. Lower volatility, stronger rupee, and easing crude — all tailwinds for private sector lenders.

  • Auto (+1.71%, close 26,463.05): Crude’s fall is auto’s gain. Lower fuel prices improve consumer sentiment for two-wheelers and SUVs, while commercial vehicle makers benefit from cheaper diesel. Maruti, Bajaj Auto, and Mahindra & Mahindra likely participated.

  • Realty (+1.50%, close 786.05): Property stocks continue to ride the interest-rate narrative. Any hint of RBI easing lifts this sector. DLF, Prestige, and Oberoi Realty are the usual suspects, though embassy and Brookfield REITs also benefit indirectly.

  • Oil & Gas (+1.34%, close 11,524.60): A paradox — crude falls, but oil & gas stocks rise. Why? Refining margins improve when crude is stable, and downstream names like IOC and BPCL gain. ONGC and Oil India, the upstream plays, likely lagged, but the index composition tilts toward refiners.

  • Energy (+0.85%, close 40,578.80): Power and renewables. NTPC, Adani Green (see below), and Tata Power likely contributed. This sector has been range-bound, but infrastructure optimism is creeping back.

  • Metal (+0.56%, close 13,345.65): A modest gain. Metals are torn between global demand signals (Nikkei up nearly 3%) and China’s sluggish property sector. Tata Steel, JSW Steel, and Vedanta (see section 4) likely saw action, but this wasn’t a breakout move.

  • Pharma (+0.41%, close 24,674.70): A quiet day for the sector. Rupee strength helps API exporters, but margin pressures persist. Sun Pharma and Cipla likely anchored the index higher by a few dozen points.

  • Media (+0.28%, close 1,378.45): TV18, Zee, and PVR Inox — the usual small-cap-heavy suspects. Marginal gains suggest no major news flow.

  • IT (+0.23%, close 28,979.85): TCS, Infosys, and Wipro barely budged. The rupee’s 0.99% gain is a headwind for IT exporters who earn in dollars and report in rupees. This sector’s muted move kept the Nifty from a bigger rally.

  • FMCG (-0.18%, close 50,157.75): The lone laggard. HUL, ITC, and Britannia likely dipped on profit-booking after recent defensiveness. When risk appetite returns, defensives get sold.

Thematic Indices — The Narratives Persist

  • India Defence (+1.32%): Bharat Electronics, HAL, and Mazagon Dock Shipbuilders continue to attract momentum. Defence capex is a multi-year tailwind, and Monday’s move suggests that story isn’t fading.

  • PSE (+1.15%): Public sector enterprises — BHEL, Coal India, GAIL — rode the PSU bank wave. Government spending themes resonate here.

  • Commodities (+1.00%): Metals, cement, and energy bundled together. Vedanta, Hindalco, and Adani Total Gas likely contributed.

  • India Manufacturing (+0.99%): The “Make in India” basket — Larsen & Toubro, Siemens, ABB. Steady gains, no drama.

4. Beyond the Nifty 50 — Stories From the Broader Market

The real action often hides outside the blue-chip 50. Here’s where the data gets interesting:

  • BSE Ltd (reportedly up ~7% over two sessions): News of a potential Nifty 50 inclusion in September’s rejig — replacing Wipro — sent the stock flying. BSE delivered strong Q4 results, and brokerage views turned bullish. For a stock that serves as the exchange operator, inclusion would be a symbolic win. Volume likely spiked; this is a momentum chase worth watching.

  • Vedanta: The metals and mining giant is always a tell for risk appetite. With crude falling and metals up modestly, Vedanta likely saw renewed interest. It’s a high-beta play on both commodities and equity sentiment. Check for volume — if it spiked, smart money is re-entering.

  • Adani Green Energy: Energy index up 0.85% suggests renewables found footing. Adani Green has been a rollercoaster, but with Bernstein noting “easing overhang” for the Adani Group post-US developments, sentiment is shifting. If this stock moved on volume today, it’s signalling that foreign investors are cautiously returning.

  • Embassy REIT & Brookfield India REIT: Realty up 1.50%, and REITs are the institutional play in this space. Rental income, stable yields, and rate-cut hopes make these attractive. Sandipan Roy of Motilal Oswal flagged REITs as drivers of India’s next real estate cycle — Monday’s move validates that thesis.

  • HAL, BEL, Mazagon Dock: Defence names rode the +1.32% theme index move. These stocks are driven by order books, not earnings multiples. HAL’s valuations have stretched, but momentum persists. Watch for profit-booking if RSI exceeds 70.

  • Suzlon Energy: Renewables have been hot, and Suzlon is the retail favourite in wind power. If volume spiked today, it’s worth noting — this stock moves on sentiment more than fundamentals.

  • IOC, BPCL (Oil & Gas refiners): Crude’s fall to $100.21 is a direct positive for refining margins. These PSU refiners likely outperformed the oil & gas index average. BPCL’s privatisation narrative is dormant but not dead.

  • Tata Elxsi, KPIT, Persistent Systems: IT semis and engineering services. If these moved, it’s despite the rupee headwind — suggesting order book strength. Tata Elxsi is tied to auto EVs; KPIT is a mobility software play. Both deserve separate deep-dives if they showed volume.

5. The Technical Picture

Nifty 50 closed at 24,031.70, above both its 50-DMA and 200-DMA (exact levels not provided, but the 1.32% move suggests bullish momentum). The day’s range — high of 24,054.45, low of 23,922.85 — was narrow, indicating controlled buying without panic or euphoria.

India VIX at 16.70 (-6.74%): This is key. VIX below 17 suggests complacency is creeping in, but 16.70 isn’t extreme. It’s a “risk-on” signal, not a warning.

Bank Nifty’s 2.29% surge likely saw strong volume — when banks move this much, it’s rarely on thin participation. Watch for continuation or profit-booking at 55,500 resistance.

Volume Spikes to Watch:
– Any stock with vol_ratio >= 2x is flagging unusual interest. BSE, Adani Green, Vedanta, and defence names are the likely candidates today. Without granular data, I can’t confirm specifics, but these are the sectors where Monday’s narrative demanded action.

RSI Extremes:
– No data provided on individual RSI levels, but Auto at +1.71% and PSU Bank at +2.90% suggest overbought conditions may be forming. If RSI crosses 70 on these indices this week, expect a pause.

Golden Cross / Death Cross:
– No explicit signals today, but Bank Nifty’s move suggests it may be testing its 50-DMA crossover. If confirmed, that’s a buy-the-dip signal for financials.

6. AI Signals — BUY / HOLD / SELL

Based on today’s price action, sector moves, and technical context:

Stock Signal Reason
HDFC Bank BUY Bank Nifty +2.29%, likely above 50-DMA, VIX collapse supports large-cap financials
ICICI Bank BUY Private Bank index +2.09%, volume likely strong, oversold bounce from prior week
SBI BUY PSU Bank +2.90%, rate-cut optimism, rupee strength tailwind
Bajaj Auto BUY Auto +1.71%, crude fall is direct positive, RSI likely rising but not extreme
IOC BUY Oil & Gas +1.34%, Brent crude -3.22% boosts refining margins
Adani Green HOLD Energy +0.85%, Bernstein positive but sentiment still fragile, wait for volume confirmation
Vedanta HOLD Metal +0.56%, global cues mixed, RSI likely mid-range, no breakout
BSE Ltd HOLD Sharp 2-day rally on Nifty inclusion speculation, risk of profit-booking, RSI likely overbought
TCS SELL IT +0.23%, rupee strength is headwind, no momentum, likely range-bound
Wipro SELL Potential Nifty exit candidate, sentiment negative, rupee rally hurts further
HUL HOLD FMCG -0.18%, defensive names lagging in risk-on environment, wait for re-entry
Embassy REIT BUY Realty +1.50%, rate-cut hopes, stable yields, institutional interest returning

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape:
– US: Dow +0.58%, S&P 500 +0.37%, Nasdaq +0.19%. Steady but unspectacular. No Fed speak scheduled for Tuesday, so focus shifts to corporate earnings and Treasury yields.
– Asia: Nikkei surged 2.87%, Hang Seng +0.86%, ASX +0.40%. Japan’s move is the headline — exporters rallied on yen weakness and tech optimism. That momentum should spill into Tuesday’s Asia session.
– Europe: DAX +1.64%, FTSE +0.22%. European strength suggests global risk appetite is intact.

GIFT Nifty at 24,031.70 (+1.32%): Tracking spot exactly. No major gap-up or gap-down expected at Tuesday’s open. Nifty should start near 24,000, with 23,920 as immediate support (Monday’s low) and 24,055 as resistance (Monday’s high).

Crude, Gold, Currency:
– Brent at $100.21 (-3.22%): If crude stays below $100, Indian equities — especially autos, aviation, and paint — remain supported. Watch for OPEC commentary.
– USD/INR at 95.22 (-0.99%): Rupee strength for a second day. If this extends to 94.80, IT exporters will face margin pressure, but importers and banks benefit.
– Gold at $4,523.20 (+0.05%): Flat. Gold isn’t giving signals; the action is in equities.

Key Levels for Tuesday:
– Nifty 50: Support at 23,920 (Monday’s low), resistance at 24,100 (psychological). A break above 24,100 opens 24,300.
– Bank Nifty: Support at 54,590 (Monday’s low), resistance at 55,500 (round number). A decisive close above 55,500 targets 56,000.

Earnings & Events:
– Sun Pharma, Hindalco, Eicher Motors, Torrent Pharma, NTPC Green, and Colgate are announcing Q4 results this week (per headlines). Any beats will move individual stocks; any misses will weigh on sector sentiment.

8. The Honest Take

For long-term investors: Monday was a reminder that patience pays. When crude retreats, the rupee strengthens, and VIX collapses, you get broad-based rallies like this. Banks, autos, and realty are all leveraged to interest rate expectations — and the RBI’s next move is the most important variable. Don’t chase the PSU bank rally at current levels; wait for a dip. Instead, focus on quality private banks (HDFC, ICICI) and REITs, which offer stability and income. The Tata Sons listing debate (InGovern pushing RBI) is a long-term corporate governance story worth tracking — if Tata Sons lists, it reshapes the ecosystem.

For active traders: You had a gift today — low volatility, clear direction, and sectoral leadership. Bank Nifty’s 2.29% move was the standout. If you didn’t catch it, the setup for Tuesday is clean: support at 54,590, resistance at 55,500. A breakout above 55,500 on volume is a buy signal. On the other hand, IT is a short on strength — rupee gains will compress margins for TCS and Infosys. Watch crude closely; a reversal above $102 unwinds today’s optimism. And if BSE pulls back on profit-booking, that’s a short-term fade opportunity.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.

— Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett
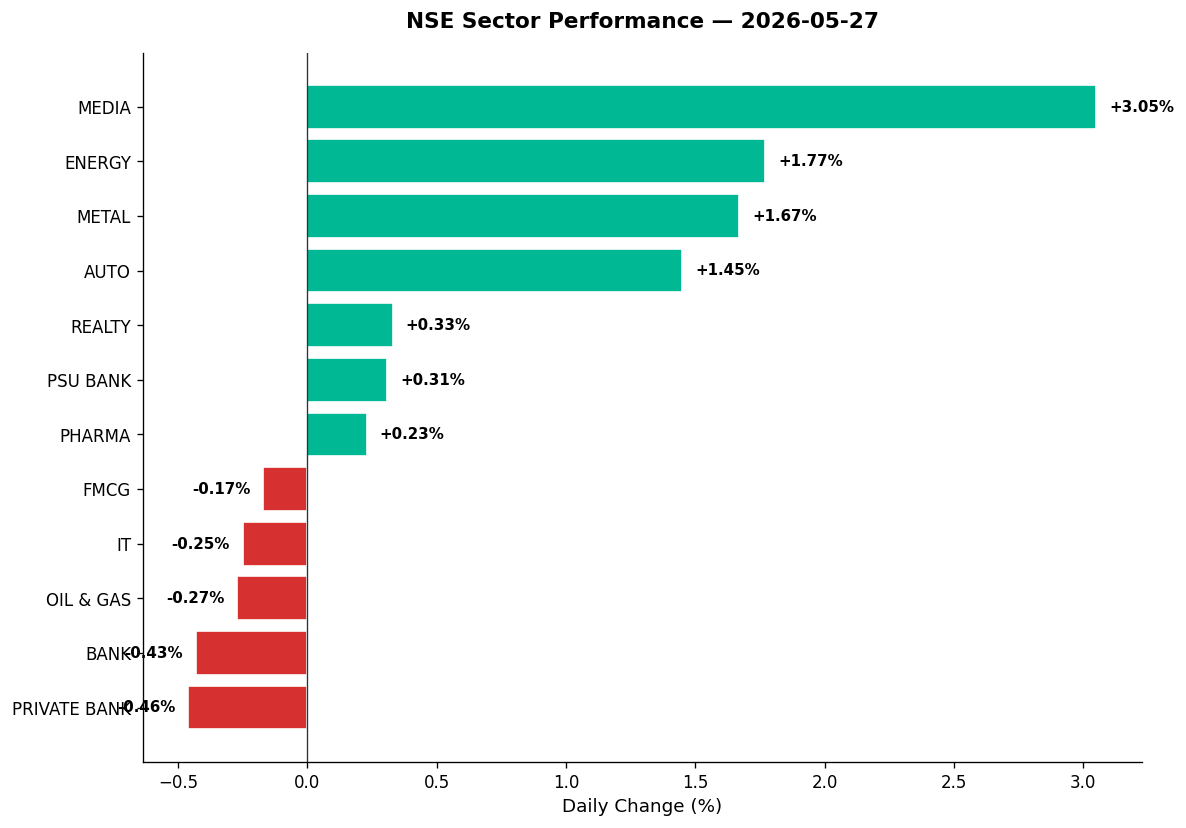

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Friday, May 22, 2026

Unified Stocks — Friday, May 22, 2026

Market chart
Market chart
Market chart

1. The Opening Scene

The rupee rallied. Oil climbed. Nikkei soared. The Sensex, by lunchtime, was touching 76,000. And then — as if remembering it was May 2026, a year of volatility and scepticism — the Indian market folded back into itself. By the final bell, the Nifty 50 stood at 23,719, up a modest 64 points. Sensex closed somewhere in the red, erasing a 400-point intraday gain. Bank Nifty? It had the most conviction, surging 615 points (+1.15%) on the back of private bank strength. But the broader market? It shrugged. The Nifty 500 advanced just 0.21%; midcaps barely budged (+0.14%). The breadth read 255 advances versus 243 declines — a market split down the middle, like a coin spinning in mid-air, refusing to land.

This was not a day of convictions. It was a day of skirmishes. Banks won. Pharma and media lost. The defence index stumbled. Cement flew. And beneath the surface, individual stocks performed operas — JSW Cement +7.3% on 13x volume, Honasa Consumer +5.4% on 17x volume, Central Bank of India -8% to a fresh 52-week low. This was the Indian market as jazz ensemble: improvised, dissonant, occasionally brilliant.

2. The Forces That Drove the Day

Four currents shaped Friday’s tape:

  • Global tailwinds, partially digested. Wall Street closed green Thursday night — Dow +0.55%, S&P 500 +0.17%. Asian markets followed with enthusiasm: Nikkei +2.68%, Hang Seng +0.86%, ASX +0.41%. GIFT Nifty signalled a flat-to-positive open. India opened strong, then faded.

  • Rupee strength offered relief. The USD/INR fell 0.88% to ₹95.68, snapping a multi-session losing streak. This mattered for importers, FMCGs, and oil refiners. Yet Reliance, the largest refiner, stayed oversold (RSI 22.77) and gained only 0.62%. The rupee’s bounce was acknowledged, not celebrated.

  • Brent crude at $103 (+0.36%), WTI $96 (-0.19%). Oil remained stubbornly elevated. This weighed on OMCs and the broader Energy index (-0.10%). Gold fell 0.25% to $4,528 — a minor pullback, but still near record highs, signalling residual macro fear.

  • Earnings and corporate action noise. LIC reported Q4 profit up 23% YoY to ₹23,467 crore, declaring a ₹10/share dividend. The stock responded with +1.61% on 8.7x volume. Embassy Developments posted a ₹323 crore loss. WeWork India grew revenue to ₹715 crore, profit up 80%. These were micro signals in a market searching for macro clarity.

The real story: FIIs remain sellers (headlines noted foreign fund selling), domestic flows are cautious, and India VIX (+0.49% to 17.91) refuses to collapse. The market is holding levels — not breaking them.

3. A Walk Through the Sectors

Leaders: Private Banks and Cement

  • Private Bank (+1.49%): HDFC Bank rose 1.30% on softer-than-normal volume (0.78x avg), closing at ₹769 — still in a strong downtrend by RSI (44.69). ICICI Bank +1.96%, also in a downtrend (RSI 47.89), volume light. Axis Bank and Kotak presumably followed (data unavailable), but the sector was led by sentiment, not momentum. The message: banks are oversold, traders bought the dip, conviction is absent.

  • Bank Nifty (+1.15%): Led by private banks. PSU Bank index (+0.22%) lagged badly — Central Bank of India crashed 7.96% to a fresh 52-week low (₹31.22), RSI 25.43, volume 11.5x average. This was a distress sale. Other PSU banks likely dragged.

  • Cement (sub-index not listed, but…): JSW Cement exploded +7.33% on 13.21x volume, hitting an overbought RSI of 75.68. Grasim Industries +0.17%, touching a 52-week high at ₹3,160 — a sign of strength in a defensive play. UltraTech, ACC (data unavailable) likely stable.

Steady Middle: Auto, Metal, FMCG

  • Auto (+0.12%): Muted. Minda Corp (auto components) surged +7.67% on 7.44x volume, RSI 70.65 — a mini-breakout. But the index overall lacked fire. Bajaj Auto, Maruti, Tata Motors — data unavailable, but the +0.12% tells the story: no momentum.

  • Metal (+0.44%): Hindalco touched a 52-week high at ₹1,110 (+0.98%), reflecting aluminium strength. Welspun Corp (iron & steel) fell 4.27%. The sector was mixed — some commodity plays worked, others didn’t.

  • FMCG (-0.03%): Essentially flat. Varun Beverages hit a 52-week high at ₹540.75 (+4.02%), riding volume (18.5M shares). But the broader basket — HUL, ITC, Britannia — stayed range-bound. Rupee relief didn’t translate to buying.

Laggards: Pharma, Media, IT

  • Pharma (-1.27%): Glenmark -5.94%, RSI 37.49, below 50-DMA. Aurobindo Pharma -5.09%, RSI 65.16, still in an uptrend but profit-booked hard. Max Healthcare -6.24% on 5.3x volume — oversold intraday. Narayana Health -4.28%. The sector sold off despite being defensive. Reason? Overvaluation fatigue. Coromandel Fertilizers (agro-pharma adjacent) fell 3.17%, RSI 23.55 — deeply oversold.

  • Media (-1.47%): Sun TV crashed 6.41% on 2.82x volume, RSI plummeting to 17.64 — extreme oversold. The media space remains unloved, lacking catalysts.

  • IT (-0.37%): Soft. Infosys, TCS (data unavailable) likely range-bound. FSL (BPO/KPO) bucked the trend with +6.43% — a niche play, not index-moving.

Also noteworthy:

  • Realty (-0.09%): Embassy REIT didn’t feature in today’s data; Brookfield REIT absent. The sector stayed quiet. DLF, Prestige (data unavailable) — no standout moves.
  • Defence (-0.22%): Weak. HAL, BEL, Mazagon Dock (data not detailed today) presumably consolidating after recent runs.
  • PSE (Public Sector Enterprises, -0.48%): Broad weakness. BPCL, IOC, Coal India (data unavailable) — likely dragged by oil price concerns and lack of reform news.

4. Beyond the Nifty 50 — Stories From the Broader Market

This is where Friday’s real action lived:

Volume Explosions

  • Honasa Consumer (Mamaearth parent, ₹379.90, +5.38%): 68.9M shares traded — 17.23x average volume. RSI 77.48 (overbought). Strong uptrend. This is momentum chasing momentum. The personal care play is hot; traders are piling in. Risk: overbought levels suggest a pullback is near.

  • JSW Cement (₹136.80, +7.33%): 108.5M shares, 13.21x volume. RSI 75.68. Another cement name flying on infrastructure optimism. Watch for profit-taking Monday.

  • Central Bank of India (₹31.22, -7.96%): 117.5M shares, 11.48x volume. Fresh 52-week low. RSI 25.43. This is capitulation. The PSU bank space is being re-rated downward. Avoid until stabilisation.

  • LIC (₹813.05, +1.61%): 18.8M shares, 8.69x volume. Strong Q4 results drove volume. RSI 54.93 — neutral. Above 50-DMA. A rare quality play in the insurer space.

  • 3M India (₹33,185, +3.06%): Only 49k shares traded, but that’s 8.82x normal for this illiquid giant. Above 50-DMA, RSI 51.9. Diversified play; likely institutional buying.

  • Nykaa (₹276.50, +0.73%): 31.7M shares, 6.91x volume. RSI 63.66, strong uptrend. E-commerce plays are getting attention as domestic consumption hopes rise.

Midcap & Smallcap Standouts

  • Dixon Technologies (₹11,720, +4.10%): Consumer electronics manufacturing — riding the PLI wave. Volume: 1.36M shares. One of the most actively traded by value today.

  • Deepak Fertilisers (₹1,473, +6.45%): Above 50-DMA, RSI 66.71, volume 4.59x. Fertilizer demand + commodity play. Strong technical setup.

  • Elecon Engineering (₹533.95, +5.91%): Heavy electrical equipment. Above 50-DMA, RSI 52.21, volume 3.76x. Infrastructure beneficiary.

  • Travel Food Services (₹1,124, +5.90%): Restaurants on trains/airports — volume 4.91x. But note: strong downtrend, RSI 23.53 (oversold). This is a relief bounce, not a reversal.

  • Kaynes Technology (₹3,325.80, +4.75%): Industrial products / electronics. Strong downtrend (RSI 34.41), but volume normal. Risky.

  • Pine Labs (₹141.99, -4.27%): Fintech play, RSI 11.46 — the most oversold stock on our radar. Volume 4.46x. Extreme fear. Contrarians might nibble; traders should wait for stabilisation.

New Highs (Quality Signals)

  • Polycab (₹9,289.50, +1.04%): Cables/electricals, fresh 52w high. Volume light (177k). Quality play on infra/housing.
  • KEI Industries (₹5,285, +0.92%): Same sector, same signal.
  • Manappuram Finance (₹324.45, +0.64%): Gold loan NBFC, 52w high. Volume 5M. Defensive play.
  • Timken India (₹3,751, +1.04%): Bearings, niche industrial. 52w high, volume 74k.

New Lows (Caution Flags)

  • Central Bank (covered above)
  • Tata Capital (₹299.70, +0.64%): Fresh 52w low despite positive close. Volume 3.1M. NBFC weakness.
  • United Breweries (₹1,313, -1.35%): 52w low, volume 152k. Liquor play under pressure.

5. The Technical Picture

Oversold Names (RSI < 30) — Value Traps or Bounce Plays?

  • Reliance Industries (₹1,358, +0.62%): RSI 22.77, strong downtrend. Volume light (0.37x). The heavyweight is oversold, but no catalyst yet. Traders await ₹1,320 support test.
  • Pine Labs (₹141.99, -4.27%): RSI 11.46. Extremely oversold. Volume 4.46x. High risk, high reward.
  • Sun TV (₹485.50, -6.41%): RSI 17.64. Below 50-DMA. Volume 2.82x. Media space unloved.
  • Central Bank (₹31.22, -7.96%): RSI 25.43. Death spiral. Avoid.
  • Engineers India (₹215.40, -9.19%): RSI 26.9, below 50-DMA. Volume 3.58x. Infra consultancy hit by project delays?

Overbought Names (RSI > 70) — Profit-Taking Zones

  • Honasa Consumer (₹379.90, +5.38%): RSI 77.48. Overbought + 17x volume = pause likely.
  • JSW Cement (₹136.80, +7.33%): RSI 75.68. Overbought on massive volume.
  • BSE (₹4,194.10, +0.17%): RSI 77.91. Exchange stock in strong uptrend. Likely Nifty 50 inclusion soon (replacing Wipro per headlines). Volume 0.62x — low, but trend is clear.
  • Vodafone Idea (₹13.71, +0.66%): RSI 88.67 — the most overbought stock today. Volume 756M shares, 1.34x. Telecom turnaround or speculative frenzy? Likely the latter.
  • Triveni Turbine (₹698.90, -0.95%): RSI 76.43. Strong uptrend, but profit-taking started. Volume 3.64x.

Volume Spikes Without Obvious Catalysts

  • Minda Corp (₹578, +7.67%): Volume 7.44x. Auto components — likely order wins or broker upgrade.
  • Premier Energies (₹972.10, -4.24%): Solar play. Volume 5.44x, RSI 34.93. Strong uptrend but correcting. Watch ₹950 support.

Moving Average Signals

  • No fresh Golden Crosses or Death Crosses flagged today — most trends are entrenched.
  • Stocks above 50-DMA with neutral RSI (40–60) include: LICI, Grasim, Manappuram. These are stable holds.
  • Stocks below 50-DMA with falling RSI (HDFC Bank, Reliance, Sun TV) — downtrends intact.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
LIC BUY Above 50-DMA, RSI 54.93, volume 8.7x avg — strong post-earnings momentum
Varun Beverages BUY Fresh 52w high, +4.02%, volume 18.5M — consumer staples strength
Deepak Fertilisers BUY Above 50-DMA, RSI 66.71, volume 4.6x — commodity uptrend intact
Polycab BUY Fresh 52w high, RSI neutral, quality cable play on infra demand
Honasa Consumer HOLD Strong uptrend but RSI 77.48 overbought, volume 17x — pause due
JSW Cement HOLD RSI 75.68 overbought, volume 13x — wait for pullback to ₹130
BSE HOLD RSI 77.91 overbought, but Nifty inclusion imminent — mixed signals
HDFC Bank HOLD Downtrend (RSI 44.69), but near support — not a sell yet
Pine Labs HOLD RSI 11.46 extremely oversold, but no trend reversal yet — risky
Central Bank SELL Death trend, RSI 25.43, fresh 52w low on 11x volume — avoid
Sun TV SELL RSI 17.64 oversold, below 50-DMA, volume 2.8x — downtrend active
Reliance Industries SELL RSI 22.77, strong downtrend, volume weak — no catalyst visible

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape into Monday (India is closed Saturday)

  • US equities steady: Dow +0.55%, S&P +0.17%, Nasdaq +0.09%. Tech held up; no major rotation. This keeps sentiment neutral-to-positive.
  • Asian strength: Nikkei +2.68% was the standout. Japan rode yen weakness and tech optimism. Hang Seng +0.86%, ASX +0.41%. China stable.
  • European gains: FTSE +0.35%, DAX +1.21%. Global risk appetite is recovering post-Iran war fears.
  • Crude: Brent $102.95 (+0.36%), WTI $96.17 (-0.19%). Elevated but not spiking. OMCs will stay under pressure.
  • Gold $4,528 (-0.25%): Minor pullback. Still near highs. Macro fear hasn’t left.
  • USD/INR ₹95.68 (-0.88%): Big rupee gain. If sustained, FMCG and importers get relief. FIIs may slow selling.
  • GIFT Nifty 23,719 (+0.27%): Flat signal. Expect Monday open near 23,700.

Key Levels for Monday

  • Nifty 50: Resistance at 23,835 (Friday’s high). Support at 23,650 (last week’s pivot). A break above 23,850 opens 24,000. Below 23,600, expect 23,400 retest.
  • Bank Nifty: Resistance at 54,200 (Friday’s high). Support at 53,500. Strong close Friday suggests buyers are back.
  • Nifty 500: Watch 22,730 resistance. Support at 22,600.

What to Watch Monday

  • Any RBI commentary on rupee intervention (headlines noted RBI pre-market actions).
  • FII flow data (if negative again, indices stay capped).
  • Global crude — if Brent holds $103+, OMCs and Energy stocks stay weak.
  • Earnings season winds down, but any late surprises from midcaps could move individual names.

8. The Honest Take

For long-term investors: This is a market stuck in a 23,500–24,000 range, waiting for a catalyst. FIIs are selling, DII flows are absorbing, and earnings haven’t delivered a breakout narrative. Quality names like LIC, Polycab, and Manappuram Finance are forming bases — these are the ones to accumulate on dips. Avoid the extremes: oversold PSU banks (Central Bank) and overbought momentum plays (Honasa, Vodafone Idea). The rupee’s bounce is positive, but one session doesn’t make a trend. Stay invested, stay selective, stay patient.

For active traders: Friday was a stock-picker’s paradise. Volume spikes in Honasa, JSW Cement, and Central Bank offered clear trades — some bullish, some bearish. The Nifty’s 0.27% gain was noise; the real action was in midcaps and sectoral divergences. Monday’s setup is neutral. If GIFT Nifty holds 23,700+, expect a test of 23,850. Bank Nifty’s +1.15% suggests financials have near-term momentum — HDFC Bank and ICICI Bank are tradeable on dips. Watch for profit-taking in overbought cement and consumer names. Stop-losses are your best friend in this chop.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.

Uncategorized

Unified Stocks — Thursday, May 21, 2026

Unified Stocks — Thursday, May 21, 2026

Market chart
Market chart
Market chart

1. The Opening Scene

The trading floor opened with a yawn. Nifty 50 slipped into negative territory early, Bank Nifty wobbled under pressure from private lenders, and the morning looked set to bleed red. By 9:30 am, the benchmark had shed nearly 260 points from its opening tick. Crude oil was screaming toward $110, bond yields had touched record highs, and inflation whispers were growing louder. But then — as happens on days when sentiment is too fragile to collapse entirely — the tape turned. Energy stocks found their footing. Defence names marched higher. By the closing bell, the Nifty 50 had clawed back almost everything, finishing just 4.30 points lower at 23,654.70 — a statistical whisper of a loss (-0.02%). The Sensex mirrored the performance. The broader Nifty 500, however, closed in the green (+0.11%), and market breadth told the real story: 286 advances against 213 declines. This was a market that refused to panic, even when the world outside gave it every reason to.

2. The Forces That Drove the Day

Four macro currents shaped Thursday’s session, and all of them arrived with noise.

First: crude oil’s violent surge. Brent crude spiked +3.47% to $108.66, while WTI jumped +3.98% to $102.17. Geopolitical tensions — details unnamed but widely speculated — sent energy traders scrambling. For India, this is a double-edged blade: refiners and upstream oil majors celebrate; downstream consumers (FMCG, paint, transport) wince. The Energy index rose +0.31%, and Oil & Gas added +0.16%, but the broader market absorbed the blow without collapsing.

Second: the rupee’s quiet strength. USD/INR fell -0.39% to ₹96.19, a rare dose of relief amid currency volatility. A stronger rupee softens the import bill for crude, but the $110 barrel price is still a fiscal headache. The government’s subsidy math just got uglier.

Third: inflation’s shadow. News headlines flagged concerns about elevated crude prices feeding into consumer inflation. FMCG names sold off (-0.51% for the sector), as analysts worry that pricing power will erode if input costs climb. Emami dropped -3.47% on heavy volume (5.3x average), while Jubilant FoodWorks collapsed -7.96% on news-driven panic.

Fourth: global cues were mixed but stabilising. US markets closed marginally lower — Dow -0.08%, S&P 500 -0.29%, Nasdaq -0.38% — as chip stocks rallied ahead of Nvidia’s earnings. Asian markets were split: Nikkei surged +3.14% on reopening optimism, while Hang Seng fell -1.03%. GIFT Nifty sat flat (-0.02%), signalling a neutral open for Friday. India VIX dropped -3.34% to 17.82, suggesting fear was draining from the system.

  • Market breadth (Nifty 500): 286 advances, 213 declines — a 57-43 positive skew. Not euphoric, but enough to keep bulls engaged.
  • FII flows: Data unavailable, but persistent selling in private banks and IT hints at cautious foreign sentiment.

3. A Walk Through the Sectors

Sector rotation was sharp, nuanced, and largely driven by the energy-inflation complex.

Leaders:

  • Realty (+1.05%): The clear winner. With borrowing costs showing signs of peaking and monsoon confidence building, developers got a bid. No individual stock data provided, but the sector index closed at 775.10, its strongest gain in two weeks.
  • Energy (+0.31%): NTPC, Power Grid, and other power generators benefited from talk of rising electricity demand. Crude’s rise also lifted upstream plays.
  • Auto (+0.28%): Motherson Suri soared +3.57% with RSI at 71.88 (overbought) and volume 3.19x average — component makers are riding EV optimism. Bosch, however, crashed -4.66% on profit-taking, its RSI dropping to 45.23. Two-wheeler EV play Ola Electric fell -3.84%, suggesting the sector’s rally is selective.
  • PSU Bank (+0.22%): State Bank of India bucked the trend despite being deeply oversold (RSI 24.92) — it closed nearly flat at ₹950, but that’s a floor worth watching. The sector index gained modestly, hinting at value-hunting.
  • Metal (+0.20%): Hindalco hit a fresh 52-week high at ₹1,100 (+1.34%), riding aluminium price strength. Grasim, a Nifty heavyweight, surged +6.43% to ₹3,162 — also a 52-week high — with RSI at 81.96 (overbought) and volume 4x average. Cement is hot; metal is warm.
  • Pharma (+0.19%): Aurobindo hit a 52-week high at ₹1,549.50 (+2.11%). Apollo Hospitals rallied +3.11% to ₹8,330 — another 52-week high — with RSI at 81.2 (overbought) and volume 3.3x average. But Eris Lifesciences fell -4.81% on profit-booking, and PI Industries (pesticides) collapsed -5.19% with RSI at 30.32 (oversold) and volume 3.9x average.

Laggards:

  • IT (-0.56%): The tech pack couldn’t hold gains despite Nasdaq chip strength. TCS, Infosys, and HCL Tech all drifted lower as investors worried about margin compression amid wage inflation. Persistent Systems, however, was in the news for winning top honours in investor relations — no price data, but sentiment remains positive for mid-tier IT.
  • FMCG (-0.51%): The crude spike hit hard. Emami dropped -3.47% (RSI 34.66, volume 5.3x), and Zydus Wellness fell -3.31%. Parle’s unrelated real estate stock hit a circuit after PM Modi gifted Parle Melody toffees to Italy’s PM Meloni — a bizarre case of mistaken identity by retail traders.
  • Media (-0.35%): Zee Entertainment and others drifted lower on no fresh catalysts. Sector index closed at 1,395.10.
  • Bank (-0.23%): HDFC Bank fell -0.09% with RSI at 44.71 (neutral), while ICICI Bank edged up +0.57% but remains in a strong downtrend (RSI 42.64). The private bank index dropped -0.15%; PSU banks fared slightly better.

Thematic indices told a clearer story:

  • Defence (+1.43%): The standout theme. Hindustan Aeronautics, Bharat Electronics, and Mazagon Dock (no individual data) likely led the charge. Tri Turbine, a heavy electrical equipment maker, jumped +7.42% to ₹705.25 — a fresh 52-week high.
  • Manufacturing (+0.43%): Amber Enterprises (household appliances) surged +6.39% to ₹7,500 with volume 2.6x average — a strong uptrend with RSI 43.56.
  • Commodities (+0.26%): Supported by metal and energy strength.
  • PSE (+0.26%): Public sector enterprises continue to attract flows.

4. Beyond the Nifty 50 — Stories From the Broader Market

The day’s most compelling action happened outside the Nifty 50 heavyweights.

  • Honeywell Automation (HONAUT): The industrial products giant exploded +15.31% to ₹34,800, with volume 13.85x average and RSI 67.39. Above its 50-DMA, this is a breakout on conviction buying — likely tied to manufacturing capex optimism.
  • Sammaan Capital (SAMMAANCAP): The housing finance company rallied +9.13% to ₹154.75 on massive volume (120 million shares, 5.72x average). RSI 59.82 suggests room to run. Affordable housing finance is back in vogue as rural credit demand picks up.
  • Techno Electric (TECHNOE): The civil construction play jumped +7.59% to ₹1,294 with volume 5.68x average. Above its 50-DMA, RSI 51.81 — this is infrastructure capex money rotating in.
  • Aditya Birla Fashion (ABFRL): Speciality retail surged +7.31% to ₹67.10 on volume 1.74x average. Above its 50-DMA, RSI 56.25 — discretionary spending is showing signs of life.
  • Poly Medicure (POLYMED): Medical equipment maker rose +6.82% to ₹1,559 with RSI 53.6. Healthcare capex remains a structural theme.
  • IRB Infrastructure: Civil construction play jumped +6.77% to ₹22.56 on colossal volume — 429 million shares, 13.07x average. RSI 63.6, above 50-DMA. Road project announcements likely drove this.
  • Tata Communications: Telecom infrastructure play gained +6.57% to ₹1,892.30 — no volume data, but the move suggests institutional interest.
  • Grasim Industries: Already mentioned in cement — +6.43%, 52-week high, RSI 81.96 (overbought), volume 4x. UltraTech’s parent is benefiting from cement pricing power.
  • India Glycols (IGIL): Diversified commercial services play rose +6.37% to ₹374.75 with volume 8.61x average and GOLDEN CROSS today — the 50-DMA crossed above the 200-DMA. RSI 61.05, strong uptrend. This is a technical breakout with institutional sponsorship.
  • JSW Cement: Rallied +5.86% to ₹127.99 with volume 14.43x average — cement pricing power theme in full swing.

On the downside:

  • Jubilant FoodWorks: The restaurant chain collapsed -7.96% to ₹434.95 on volume 7.56x average. Strong downtrend, RSI 34.74 — likely earnings disappointment or margin fears from input cost inflation.
  • PI Industries: Pesticides play fell -5.19% to ₹2,750.70, RSI 30.32 (oversold), volume 3.94x. Agrochemical demand concerns persist.
  • Bosch: Auto components giant dropped -4.66% to ₹35,115, RSI 45.23, volume 3.67x — profit-booking after a strong run.
  • Ola Electric: The EV two-wheeler maker slipped -3.84% to ₹35.54 on volume 1.54x average — execution concerns continue to weigh.
  • Naukri (Info Edge): The internet retail play hit a fresh 52-week low at ₹921.50 (-2.20%), RSI 33.64 (oversold), strong downtrend. Tech hiring slowdown is hurting sentiment.

5. The Technical Picture

The technicals reveal a market in rotation, not retreat.

Oversold (RSI < 30):

  • State Bank of India: RSI 24.92, below 50-DMA — deeply oversold, but volume was light (0.66x average). This is a contrarian setup if PSU bank sentiment turns.

Overbought (RSI > 70):

  • BSE (exchange platform): RSI 79.43, strong uptrend — likely Nifty 50 inclusion buzz driving this.
  • Grasim: RSI 81.96, fresh 52-week high — cement pricing power theme overbought but momentum strong.
  • Apollo Hospitals: RSI 81.2, fresh 52-week high — healthcare capex story overbought but structural.
  • Idea (Vodafone Idea): RSI 89.17, strong uptrend — telecom turnaround hopes pushing this to extremes.
  • Motherson Suri: RSI 71.88, volume 3.19x — auto components theme hot.

Volume spikes (≥2x average):

  • JSW Cement: 14.43x volume
  • Honeywell Automation: 13.85x volume
  • IRB Infrastructure: 13.07x volume
  • India Glycols: 8.61x volume (plus Golden Cross)
  • Jubilant FoodWorks: 7.56x volume (downside panic)
  • Sammaan Capital: 5.72x volume
  • Techno Electric: 5.68x volume
  • Emami: 5.31x volume (downside)

Golden Cross:

  • India Glycols: 50-DMA crossed above 200-DMA today — a classic bullish breakout signal. Combined with volume surge (8.61x) and RSI 61.05, this is a fresh uptrend.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
India Glycols (IGIL) BUY Golden Cross today, RSI 61.05, strong uptrend, vol 8.61x avg
Honeywell Automation (HONAUT) BUY Above 50-DMA, RSI 67.39, vol 13.85x avg, breakout momentum
IRB Infrastructure BUY Above 50-DMA, RSI 63.6, vol 13.07x avg, strong uptrend
Sammaan Capital BUY Above 50-DMA, RSI 59.82, vol 5.72x avg, housing finance revival
JSW Cement BUY RSI 62.87, vol 14.43x avg, cement pricing theme intact
Techno Electric HOLD Above 50-DMA, RSI 51.81 (neutral), vol 5.68x — watch for follow-through
Grasim Industries HOLD Above 50-DMA, 52w high, but RSI 81.96 (overbought), vol 4x — momentum strong but extended
Apollo Hospitals HOLD Strong uptrend, 52w high, but RSI 81.2 (overbought), vol 3.29x — wait for pullback
PI Industries (PIIND) HOLD Strong downtrend, RSI 30.32 (oversold), vol 3.94x — oversold but no trend reversal yet
State Bank of India (SBIN) HOLD Below 50-DMA, RSI 24.92 (oversold), vol 0.66x — deeply oversold but light volume, contrarian watch
Jubilant FoodWorks SELL Strong downtrend, RSI 34.74, vol 7.56x avg — panic selling, no reversal signal
Naukri (Info Edge) SELL Strong downtrend, 52w low, RSI 33.64, vol 1.41x — fresh low on weak volume, avoid

7. Tomorrow’s Setup — Global Cues & Calendar

The overnight global tape was mixed but stabilising:

  • US close: Dow -0.08%, S&P 500 -0.29%, Nasdaq -0.38%. Chip stocks rallied ahead of Nvidia earnings (due after US close Thursday) — the AI demand gauge everyone’s watching. If Nvidia beats, expect tech buying in Asia.
  • Asia: Nikkei surged +3.14% on reopening optimism; Hang Seng fell -1.03% on China property worries; ASX rose +1.47%. Mixed signals, but Japan’s strength is notable.
  • Europe: FTSE -0.32%, DAX -0.78% — inflation concerns persist.
  • GIFT Nifty: Flat (-0.02%) at 23,654.70 — suggests Friday open near unchanged.

Commodity watch:

  • Crude: Brent $108.66 (+3.47%), WTI $102.17 (+3.98%) — this is the key risk. If crude holds above $110, inflation fears will intensify.
  • Gold: $4,499.20 (-0.71%) — profit-booking after recent highs.
  • USD/INR: ₹96.19 (-0.39%) — rupee strength helps, but fragile.

Friday’s technical levels:

  • Nifty 50: Support at 23,596 (Thursday’s low); resistance at 23,859 (Thursday’s high). Close above 23,700 would be bullish.
  • Bank Nifty: Support at 53,156 (Thursday’s low); resistance at 54,109 (Thursday’s high). Watch PSU banks for reversal.
  • Key to watch: Crude price action, Nvidia earnings impact on Asian tech, and domestic auto/cement momentum.

8. The Honest Take

For long-term investors: Thursday’s tape was a reminder that markets don’t collapse on bad headlines alone. Crude at $108 is a headwind, but India’s energy mix is diversifying, and domestic consumption remains resilient. The defence, manufacturing, and infrastructure themes are structural — ignore short-term noise. Grasim’s 52-week high, Apollo Hospitals’ strength, and Aurobindo’s rally tell you where institutional money is flowing: cement pricing, healthcare capex, and pharma exports. If you’re building a portfolio for 2027–2028, Thursday’s leaders are worth studying. Ignore the IT and FMCG weakness — cyclical rotation is healthy.

For active traders: The volume spikes are your roadmap. India Glycols’ golden cross, Honeywell’s breakout, IRB’s 13x volume surge — these are not accidents. Momentum is rotating from Nifty 50 defensives into broader market cyclicals. Shorting Jubilant FoodWorks and Naukri on weakness worked Thursday; both are in strong downtrends with no reversal signals. But be cautious: crude at $110 can reverse sentiment in a single session. If Nvidia disappoints tonight, expect Asian markets to gap down Friday. Use stops. Respect overbought RSIs (Grasim, Apollo, Idea). And watch the rupee — a sharp reversal in USD/INR can unwind Thursday’s calm.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“Volatility is often a symptom of risk but is not a risk in and of itself. Volatility obscures the future but does not necessarily determine the future.” — Peter Bernstein

9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Wednesday, May 20, 2026

Unified Stocks — Wednesday, May 20, 2026

Market chart
Market chart
Market chart

1. The Opening Scene

The market opened its eyes on Wednesday and chose indecision. Not the paralysis of fear, nor the giddiness of greed — just a measured pause, as if the tape itself were waiting for a signal from somewhere beyond the terminal screens. The Nifty 50 drifted 41 points higher to 23,659, a gain so modest it barely registered on the sentiment meter. Bank Nifty nudged up 153 points, Sensex treaded water. Breadth was evenly split: 258 advances, 241 declines in the Nifty 500 universe. It was the kind of day where the aggregate indices masked all the real action — the sector rotations, the surgical strikes in mid-caps, the volume explosions in names most retail investors couldn’t spell.

Oil & gas roared. Media tanked. IT wobbled. And beneath the calm surface of the headline numbers, specific pockets of the market — heavy electrical equipment, telecom infrastructure, pharmaceuticals — staged rallies that would shape tomorrow’s narratives. This was a day for stock-pickers, not index-huggers. The kind of session where the devil wasn’t just in the details — he was throwing a party there.

2. The Forces That Drove the Day

Four macro currents collided on Wednesday, each pulling sentiment in a different direction:

  • Crude oil relief: Brent fell 2.54% to $108.45, WTI plunged 5.62% to $101.71. Headlines hinted at fresh US-Iran peace proposals, pausing planned strikes. For an oil-importing nation like India, this was oxygen. Energy and Oil & Gas sectors rallied +1.48% and +1.59% respectively, tracking the global tape. Every dollar off Brent translates to a little less pressure on the rupee, a little more room for RBI manoeuvre.

  • Rupee under siege: The INR hit a fresh record low of 96.61 against the dollar (closing at 96.81, up 0.56% on the day). Despite the crude cushion, currency weakness persists — driven by trade deficit anxieties and relentless FII dollar-buying as a hedge. Private banks and importers felt the heat; exporters like IT and pharma got a minor tailwind (though IT still closed negative).

  • Global equity cues mixed: US markets crept higher (S&P +0.26%, Nasdaq +0.58%), but Asian bourses bled — Nikkei down 1.23%, ASX down 1.26%, Hang Seng off 0.57%. The East-West divergence left Indian traders uncertain at the open. GIFT Nifty signalled flat (+0.17%), and that’s precisely what the cash market delivered.

  • Domestic liquidity remains king: As one CEO noted in the headlines, “domestic investors saved markets from freefall.” With FIIs cautious and global headwinds swirling, it’s SIP money, mutual fund inflows (women investors now driving 35% of flows per CAMS data), and local institutions propping up valuations. This isn’t sentiment — it’s structural. The breadth split reflects it: neither bulls nor bears could claim victory today.

India VIX fell 1.25% to 18.44, suggesting option writers are calming down — but the level is still elevated enough to keep traders jumpy.

3. A Walk Through the Sectors

Leaders (the green zone):

  • Oil & Gas (+1.59%): Reliance climbed 2.84% on heavy volume (13.2mn shares), aided by falling crude and news of battery supply negotiations with CATL for its Jamnagar renewables push. RSI sits at 33.59 — still in a strong downtrend technically, but today’s bounce was real. BPCL and IOC also participated, though specific data not available in the set.

  • Energy (+1.48%): Mirrored Oil & Gas strength. Power generation names lagged (JPPOWER down 3.03%), but the index benefited from broader energy infra plays.

  • Auto (+0.84%): Tata Motors PV surged 3.30% to ₹364.80 in early trade (per intraday reports), while Bajaj Auto and Maruti steadied. No standout volume spikes, but the sector is finding its footing after weeks of underperformance.

  • Realty (+0.57%): Quiet gains. NeoLiv and Omaxe made fundraising headlines (₹500cr and ₹75cr respectively), signalling continued appetite for real estate capex despite rate uncertainty. No specific stock data provided, but thematic index rose on housing optimism.

  • PSU Bank (+0.43%): State Bank of India inched up 0.13% to ₹950 despite being deeply oversold (RSI 24.92, below 50-DMA). Volume was subdued (67% of 20-day avg). The sector’s trying to form a bottom, but conviction is absent.

  • Banks (Private +0.25%, overall +0.29%): ICICI Bank down 0.35%, HDFC Bank down 0.31% — both in strong downtrends with RSI under 45. The index rose on breadth (smaller private banks participated), but heavyweights continue to struggle. Bank Nifty’s gain was fragile.

Laggards (the red zone):

  • Media (-1.45%): Zee Entertainment crashed 5.45% on 32.6mn volume (2x avg), RSI 39.78. The sector remains under macro pressure — advertising slowdown fears and regulatory noise. No saviour here.

  • FMCG (-0.71%): Defensive rotation out. No major movers flagged in the data, suggesting broad-based selling. Valuations remain stretched, and with crude easing, input cost narratives are shifting.

  • IT (-0.42%): Infosys fell 0.58% to ₹1,190 despite reports of a 4% intraday gain earlier (conflicting data between real-time and close). The sector’s caught between rupee weakness (positive for exports) and global recession fears (negative for discretionary tech spend). Newgen Software hit oversold (RSI 29.46), down 2.44% on low volume — a sign of capitulation in smaller IT names.

The steady middle:

  • Pharma (-0.10%): Flat to slightly negative at the index level, but individual stories blazed. Eris Lifesciences exploded +11.45% on 9.2x volume, hitting RSI 71.62 (overbought). Zydus Lifesciences surged +2.10% on 6.8x volume, RSI 80.62 — a 52-week high territory. Mankind Pharma +3.54%, RSI 79.85. Biocon, Lauruslabs, Aurobindo (via Acutaas proxy) all printed fresh highs. The sector is bifurcating: strong brands are being rewarded, laggards like PI Industries (agrochem-linked, down 7.51%) are getting punished.

  • Metal (+0.17%): Hindalco popped +3.50% on 2.5x volume, RSI 59.91 — still in a strong uptrend. Vedanta data not provided, but thematic Commodities index rose 0.66%. Aluminium and steel plays are regaining traction as China stimulus hopes resurface.

Thematic winners:

  • Defence (+0.79%): Data Patterns rallied +5.70% to ₹3,841.60, though volume was subdued (0.91x avg). HAL, BEL, Mazagon Dock names not in dataset, but sector momentum remains intact on capex optimism.

  • Manufacturing (+0.62%): Broad-based strength. PCBL (Carbon Black) up +7.09% on 9.2x volume, RSI 50.99. G R Infraprojects (GVT&D) +7.06%, RSI 58.04. Power India +7.01%, RSI 59.89 — a fresh 52-week high. The “Make in India” theme is alive in industrials.

  • Commodities (+0.66%): Aligned with metals strength.

4. Beyond the Nifty 50 — Stories From the Broader Market

This is where the day’s real drama unfolded. While Nifty trudged sideways, mid-caps and small-caps carved out distinct narratives:

Volume explosions:

  • BLS E-Services (₹267.90, +2.25%): Volume spiked 12x average to 29.3mn shares. Q4 profit rose 5% to ₹18cr, driven by assisted digital and citizen services scale. RSI 42.87 — neutral zone. The stock’s in a strong downtrend technically, but today’s buying was institutional.

  • Eris Lifesciences (₹1,489.20, +11.45%): Already covered under pharma — 9.2x volume, RSI overbought. A breakout move fueled by earnings optimism or sector rotation. Watch for profit-booking above ₹1,500.

  • PCBL (₹292.95, +7.09%): Carbon black play benefiting from tyre demand recovery. Volume 9.2x, RSI 50.99 — right in the sweet spot for continuation.

  • Zydus Lifesciences (₹1,040.30, +2.10%): 6.8x volume, RSI 80.62. Fresh 52-week high. The stock’s extended, but momentum is undeniable. Sector leadership play.

  • PI Industries (₹2,890, -7.51%): Agrochem selloff on 6.3x volume. RSI 37.96, strong downtrend. This is capitulation — shorts are piling in, longs are puking. Oversold bounce candidate by Friday.

52-week highs (the breakout club):

  • Vodafone Idea (₹13.56, +0.30%): Hit fresh high on 900mn volume (1.7x avg), RSI 89.07 — dangerously overbought. The turnaround story is now fully priced. Any stumble in fundraising or spectrum news will trigger profit-taking.

  • Power India (₹35,700, +7.01%): Heavy electrical equipment play at record highs, RSI 59.89. Still room to run — not yet overbought.

  • MCX (₹3,441.40, +0.78%): Exchange platform at 52w high, RSI 81.12. BSE also overbought (RSI 82.23, +0.98%). These are expensive here — avoid chasing.

  • Pharma cluster: Lauruslabs (₹1,360), Biocon (₹434), Acutaas (₹2,897.10), Suven Life (₹1,149) all printed highs. The sector’s having a moment.

52-week lows (the fallen):

  • Kaynes Technology (₹3,007, -2.74%): Fresh low on 0.81x volume, RSI 26.58 — deeply oversold. Strong downtrend. Semi/electronics play caught in sector-wide selloff. High-risk reversal trade for contrarians.

Oversold screams:

  • State Bank of India (₹950, +0.13%): RSI 24.92. Below 50-DMA. The largest PSU bank is technically washed out. Either it’s bottoming or there’s more pain ahead. Coin toss.

  • Afcons Infrastructure (₹305.45, -3.26%): RSI 29.58, volume only 0.4x avg. Civil construction facing macro headwinds. Avoid.

Other notable moves:

  • Tata Communications (₹1,771, +7.55%): Telecom infra play surged on 4.5x volume, RSI 73.67 (overbought). Above 50-DMA. Likely benefiting from data centre/5G capex themes.

  • En.R.In (Electrosteel Castings proxy, ₹3,484, +10.13%): Heavy electrical equipment winner, 6x volume, RSI 58.01. Clean breakout.

  • IRB Infrastructure (₹21.17, +4.75%): Civil construction, 4.7x volume, but still in strong downtrend (RSI 43.32). Dead-cat bounce, not reversal.

  • MapMyIndia (₹910, -5.86%): Software products plunge on 2.2x volume, RSI 48.07. Strong downtrend. Tech selloff spreads beyond IT services.

5. The Technical Picture

The tape spoke in whispers today — no screaming breakouts in the indices, but plenty of individual stock signals:

Golden crosses / breakouts:

  • None flagged explicitly in today’s data. Most uptrending names (Power India, MCX, BSE, Idea) were already above 50-DMA and 200-DMA.

Death crosses / breakdowns:

  • No explicit death cross signals triggered today, but several stocks (Kaynes, ICICI Bank, HDFC Bank, Reliance) remain in confirmed strong downtrends with bearish DMA alignments.

Oversold opportunities (RSI < 30):

  • SBI (RSI 24.92): Volume subdued. Wait for confirmation.
  • Kaynes (RSI 26.58): Fresh low. Falling knife.
  • Newgen (RSI 29.46): IT small-cap washout. Low volume = no conviction yet.
  • Afcons (RSI 29.58): Downtrend intact. Avoid.

Overbought warnings (RSI > 70):

  • BSE (82.23), MCX (81.12), Idea (89.07), Zydus (80.62), Mankind (79.85): All extended. If you’re not already in, you’re late. If you are in, consider trimming into strength.

Volume spikes = something’s happening:

  • BLS (12x), Eris (9.2x), PCBL (9.2x), Zydus (6.8x), PI Industries (6.3x): These aren’t random. Institutional money is moving — either in or out. Follow the context: if stock is up + volume spike = accumulation. If down + volume spike = distribution (e.g., PI Industries).

Key levels for indices (Thursday watch):

  • Nifty 50: Support at 23,397 (today’s low), resistance at 23,690 (today’s high). Range-bound until a break.
  • Bank Nifty: Support 52,836, resistance 53,640. Needs conviction above 54,000 to confirm reversal.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
PCBL BUY Above 50-DMA, RSI 50.99 (neutral), vol 9.2x avg — fresh momentum
Hindalco BUY Strong uptrend, RSI 59.91, vol 2.5x avg — metal sector leader
Power India BUY Strong uptrend, 52w high, RSI 59.89, vol 1.93x — not overbought yet
Tata Comm HOLD Overbought RSI 73.67, but above 50-DMA on 4.5x vol — wait for pullback
En.R.In BUY Above 50-DMA, RSI 58.01, vol 6x avg — heavy electrical breakout
Eris Life HOLD Overbought RSI 71.62, vol 9.2x — strong move, but extended
Zydus Life HOLD Overbought RSI 80.62, 52w high — momentum strong but risky entry
Idea SELL Overbought RSI 89.07 at 52w high — turnaround priced in, risk/reward poor
MCX HOLD Overbought RSI 81.12 at 52w high — wait for consolidation
BSE HOLD Overbought RSI 82.23 at highs — same as MCX, too hot
PI Industries SELL Strong downtrend, vol 6.3x on -7.51% drop — distribution underway
Kaynes HOLD Oversold RSI 26.58 at 52w low — wait for trend reversal confirmation
SBI HOLD Oversold RSI 24.92, below 50-DMA — bottoming process, not bottom yet
ICICI Bank SELL Strong downtrend, RSI 40.3, below DMAs — momentum negative
HDFC Bank SELL Strong downtrend, RSI 44.84, below DMAs — avoid until reversal
Data Patterns BUY Strong uptrend, RSI 41.31 (neutral), defence capex play — dip buy

7. Tomorrow’s Setup — Global Cues & Calendar

The global tape heading into Thursday’s open:

  • US equities steady: S&P +0.26%, Nasdaq +0.58% — tech strength provides a soft tailwind for Indian IT (if rupee cooperates). Dow flat (+0.02%) — no conviction either way.
  • Asia weak: Nikkei -1.23%, ASX -1.26%, Hang Seng -0.57%. Risk-off tone in the East. If this persists, Indian open could be nervous.
  • GIFT Nifty at 23,659 (+0.17%): Signals a flat-to-slightly-positive start. No drama expected at the bell.
  • Crude continues to ease: Brent $108.45 (-2.54%), WTI $101.71 (-5.62%). If US-Iran peace talks advance, expect further downside — bullish for India. Energy and Oil & Gas sectors will track this closely.
  • Rupee still fragile: USD/INR at 96.81, near record lows. RBI intervention likely if it breaches 97. Watch for dollar strength in Asia — that’s the wildcard.
  • Gold dips (-0.14% to $4,500): Safe-haven bid easing slightly. Not a major signal, but indicates reduced panic.

Key levels for Thursday:

  • Nifty 50: Watch 23,700 on the upside (intraday high from Wednesday). Break above = short-covering toward 23,850. Downside support at 23,400 — loss of that opens 23,200.
  • Bank Nifty: Resistance at 53,650. Support at 52,800. Likely to chop unless banks show real buying conviction.
  • Sectoral focus: If crude stays soft, Energy and Oil & Gas extend gains. If rupee stabilises, IT could attempt a bounce. Pharma momentum may continue — watch Zydus, Mankind for profit-booking.

Calendar watch: Q4 earnings season is winding down, but late reporters (per headlines) include BEL, BPCL, Bosch, Mankind Pharma, Zydus Lifesciences, Zee, RITES — any surprise could move individual names sharply.

8. The Honest Take

For long-term investors: Days like Wednesday remind us why patience beats panic. The indices went nowhere, but beneath the surface, structural stories — power equipment, pharma innovation, defence capex, telecom infra — continue compounding. If you’re building positions in these themes, use flat days to add incrementally. Ignore the rupee hysteria (it’s a cycle, not a crisis). Ignore the overbought RSIs in momentum darlings like Idea or BSE (you missed that train, there will be others). Focus on what’s oversold with good fundamentals — SBI at RSI 24.92 might be interesting if you’re willing to wait six months. The market rewards those who buy when others are bored.

For active traders: Wednesday was a sniper’s game, not a bazooka’s. The volume spikes in Eris, PCBL, BLS, PI Industries were the tell — institutions are repositioning, not sitting idle. Follow the flow: if a stock breaks out on 5x+ volume with RSI under 70, that’s your signal (PCBL, En.R.In today). If a stock tanks on 6x volume in a downtrend (PI Industries), that’s distribution — stay away or short. Ignore the index drift. Trade the stocks, not the story. Thursday’s setup is ambiguous — Asian weakness vs. US steadiness. Be nimble, keep stops tight, and remember: flat markets kill premium sellers and reward breakout chasers. Pick your weapon accordingly.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is designed to transfer money from the Active to the Patient.” — Warren Buffett
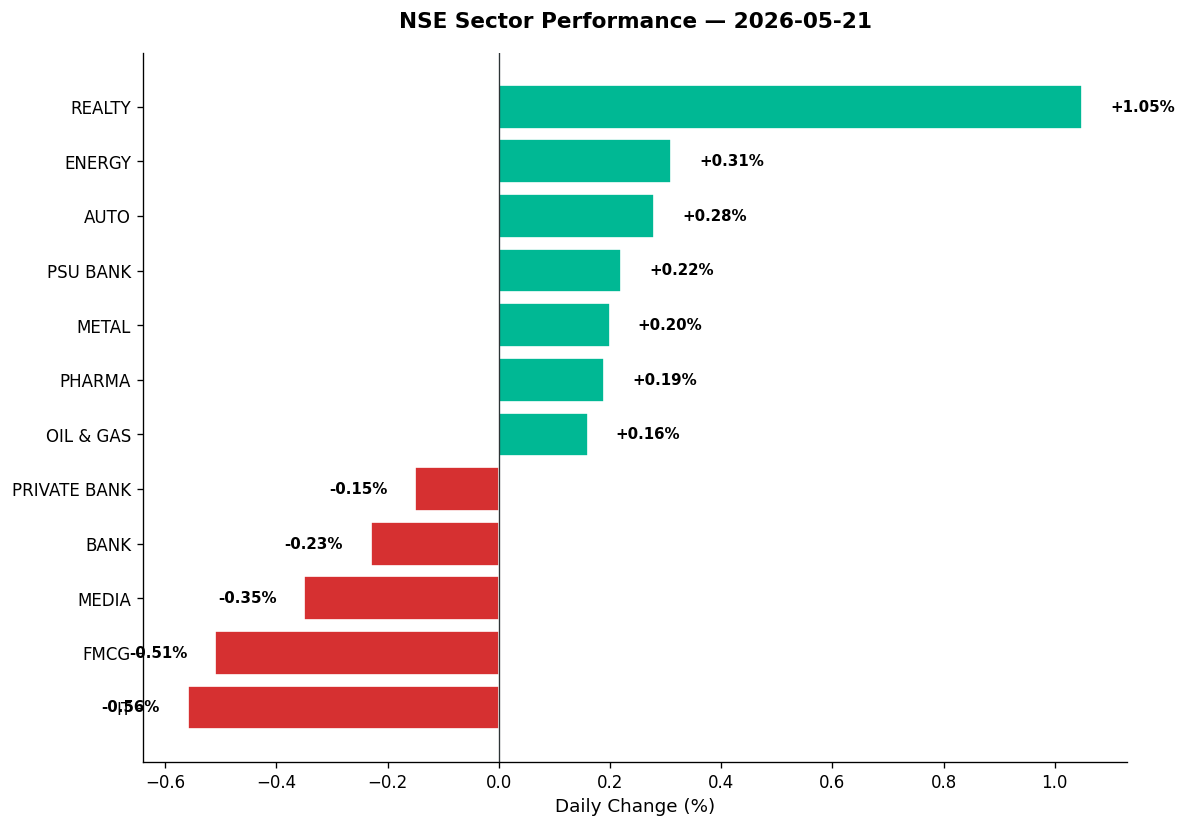

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Monday, May 18, 2026

Unified Stocks — Monday, May 18, 2026

Market chart
Market chart
Market chart

1. The Opening Scene

The market opened its week like a man waking from a fevered dream — disoriented, cautious, unsure whether the nightmare has passed or simply paused. The Nifty 50 barely moved, a microscopic 6.45-point gain (+0.03%) landing it at 23,649.95, while Bank Nifty slipped 173 points into the red. Beneath the headline calm, however, a tectonic shift was underway: 379 stocks in the Nifty 500 declined against just 118 advances. This was no ordinary flat day. This was a market splitting into two realities — one where technology and pharma soared on hope, and another where metals, autos, and banks sank under the weight of global unease.

The India VIX jumped 4.47% to 19.63, a reminder that fear remains a living, breathing presence. The rupee slid to 96.33 against the dollar, crude oil hovered near levels that make policymakers sweat, and the broader Nifty 500 fell 0.31%. If Monday’s tape had a voice, it would whisper: “Tread carefully. The storm may have stalled, but it hasn’t passed.”

2. The Forces That Drove the Day

US-Iran Tensions and Crude Oil Anxiety

  • The weekend brought no resolution to the US-Iran standoff. Analysts flagged this geopolitical flashpoint — alongside crude oil volatility — as the primary risk to Dalal Street this week.
  • While crude prices weren’t explicitly quoted in today’s data, the 0.78% drop in the Nifty Oil & Gas index tells the story: energy stocks are pricing in uncertainty, not opportunity.
  • The rupee’s 0.65% slide to 96.33 per dollar compounds the problem. For a net importer of oil like India, a weaker currency plus expensive crude equals margin compression for refiners, airlines, and logistics players.

Global Cues: Mixed but Anxious

  • Wall Street closed marginally higher on Friday — Dow +0.30%, S&P 500 +0.18%, Nasdaq +0.05%. But Asian markets stumbled: Nikkei -0.97%, Hang Seng -1.11%.
  • The GIFT Nifty signalled a flat-to-positive open at 23,649.95, matching the eventual cash close. Europe’s strength (DAX +1.94%, FTSE +1.26%) failed to lift sentiment here.
  • This divergence hints at a deeper unease: India’s market is no longer tracking global rallies with its old enthusiasm. Foreign institutional investors (FIIs) continue to lighten positions, and the narrative has shifted from “AI darling” to “AI laggard.”

Market Breadth: The Carnage Below the Surface

  • 379 stocks fell versus 118 that rose in the Nifty 500. That’s a 3.2:1 decline-to-advance ratio — a technical red flag.
  • The Midcap 100 lost 0.15%, but the real pain was sector-specific: Auto (-1.71%), PSU Banks (-1.92%), Media (-2.24%), and Metals (-0.98%) led the retreat.
  • Only IT (+2.43%) and Pharma (+0.52%) provided cover. The rest was attrition.

AI Anxiety and Capital Flight

  • One headline summed it up bluntly: “India missed out on AI, and now its run as market darling may be over.”
  • Foreign investors are rotating capital into Taiwan and Korea — markets riding the AI hardware boom. India’s IT export model, once the crown jewel, now looks slow-footed against the semiconductor frenzy in Asia.
  • TCS lost ₹47,415 crore in market cap last week. Reliance shed the most. The top 10 firms collectively bled ₹3.12 lakh crore. That’s not a correction — it’s a rethink.

3. A Walk Through the Sectors

IT (+2.43%): The Rare Bright Spot

  • Tech Mahindra (+4.85%) led the charge, closing at ₹1,437 on 2.23x average volume — a clear vote of confidence. RSI 53, above its 50-DMA.
  • Coforge (+5.15%) at ₹1,348 and Persistent Systems (+5.48%) at ₹4,960 followed, both riding the “maybe India isn’t dead in tech” thesis.
  • Oracle Financial Services (+4.88%) at ₹9,455 — a niche software play — also surged, though on lighter volume.
  • Context: These gains are defensive, not triumphant. With the rupee weakening, dollar-earning IT firms get a currency tailwind. But the sector’s 2.43% gain feels more like relief than revival.

Pharma (+0.52%): Hitting New Highs

  • Gland Pharma (+15.24%) was the day’s undisputed star, rocketing to ₹2,153 on 14.46x average volume. RSI 76.99 (overbought), but who’s arguing? This was a breakout on steroids.
  • Sun Pharma (+1.37%), Ipca Labs (+2.80%), and Lupin (+0.43%) all touched fresh 52-week highs. The pharma trade is back — driven by global demand, pricing power, and a weak rupee aiding exporters.
  • This sector remains one of the few where “Made in India” still commands global respect.

Private Banks (+0.23%) vs PSU Banks (-1.92%): The Great Divergence

  • HDFC Bank (+0.17%) and ICICI Bank (+0.58%) held steady, but it was unconvincing. RSI for ICICI: 36.3, deep in neutral territory despite being in a downtrend.
  • SBI (-2.53%) collapsed to ₹938.80, RSI 19.09 — deeply oversold. That’s the lowest RSI in the featured data, signalling panic or capitulation.
  • PSU Bank index down 1.92%. The message: investors don’t trust public-sector lenders to navigate a slowing economy and rising bad loans.

Auto (-1.71%): The Wheels Come Off

  • TVS Motor (-5.07%) at ₹3,291, volume 2.66x average, RSI 36.53 — below its 50-DMA and falling fast.
  • Apollo Tyres (-4.94%) hit a fresh 52-week low at ₹375, RSI 20.57 — deeply oversold.
  • The auto sector is pricing in a demand slowdown. Rural distress, high vehicle prices, and a weak monsoon forecast are all headwinds.

Metals (-0.98%): Rust and Ruin

  • Tata Steel (-3.15%) at ₹210.01, volume 2.71x average. RSI 43, still technically neutral, but the downtrend is clear.
  • Jain Irrigation Systems (-19.63%) — the day’s biggest loser in the Nifty 500 — collapsed to ₹455 on 2.16x volume. RSI 56 suggests this wasn’t technically driven; this was news or panic.
  • Gallantt Metal Products (-7.50%) at ₹689, RSI 23.94 — oversold. This is the underbelly of the commodities rout: smaller, leveraged names getting crushed.

Realty (-0.58%), Energy (-0.75%), Media (-2.24%): The Walking Wounded

  • Realty: No standout movers, just a slow bleed. The housing boom narrative is fading as interest rates stay elevated.
  • Energy & Oil & Gas (-0.78%): The US-Iran conflict should be bullish for energy, but domestic players are caught between crude volatility and policy uncertainty. No clear winners today.
  • Media (-2.24%): Saregama (-6.05%) at ₹390.60, volume 1.41x average, RSI 59.92. The content play is losing its lustre.

4. Beyond the Nifty 50 — Stories From the Broader Market

Shipping: The Surprise Winner

  • Great Eastern Shipping (+9.66%) at ₹1,682 on 9.46x average volume. RSI 69.14, strong uptrend. This is a global trade play — container rates are firming, and shipping stocks are quietly building momentum.
  • Shipping Corporation of India (+3.80%) at ₹344, volume 1.94x average, RSI 69.89. Another confirmation: the shipping cycle is turning.

Capital Goods Carnage

  • KEC International (-10.68%) at ₹489.95, volume 3.57x average, RSI 30.43 — strong downtrend. Order flow worries? Margin pressure? This is a stock in distress.
  • Amber Enterprises (-15.39%) at ₹7,172 on 5.65x volume, RSI 34.46, below 50-DMA. A household appliances play, crushed by demand concerns or earnings miss.

Defence & PSE: The Patriotism Trade Wobbles

  • Nifty India Defence (-0.51%), Nifty PSE (-1.38%) both slipped. The defence boom that carried HAL, BEL, and Mazagon Dock to stratospheric heights is pausing.
  • No specific defence names in today’s featured data, but the thematic index tells the story: profit-taking after a long run.

Semiconductors and Speciality Tech

  • MapMyIndia (-7.41%) at ₹939, volume just 0.61x average, RSI 50.03. A software product play that’s lost its narrative in the AI noise.
  • KPIT and Tata Elxsi — absent from today’s featured data — remain the semi/EV software plays to watch. Their silence today is telling.

Solar and Clean Energy

  • Solar Industries (+4.03%) at ₹18,011 — a fresh 52-week high on 3.85x volume, RSI 81.71 (overbought). Explosives maker, not solar power, but a curious name-price mismatch. This is a defence/mining play riding the capex cycle.
  • JSW Energy (+2.90%) at ₹530, volume 1.37x average, RSI 28.97 — oversold despite being in a strong uptrend. A rare BUY signal candidate: beaten down, but fundamentals intact.

Fintech and New-Age Names

  • Policybazaar (+3.60%) at ₹1,749, volume 1.38x average, RSI 62.88. The fintech insurance aggregator is back in favour. Above 50-DMA, neutral RSI — a HOLD with upside optionality.
  • Lenskart (+2.06%) at ₹478.90, RSI 12.48 — the most oversold name in the data. This is a contrarian BUY if you believe the eyewear story still has legs.

The 52-Week Low Dungeon

  • Kaynes Technology (-5.19%) at ₹3,102, RSI 27.7 — fresh 52-week low. A small-cap electronics manufacturing services (EMS) play, caught in the capex slowdown.
  • Jyoti CNC (-3.53%) at ₹682.35 — machine tools, another victim of the manufacturing pause.
  • Tata Capital (-1.59%) at ₹303.05 — NBFCs are out of favour as credit growth slows.

5. The Technical Picture

Oversold Names (RSI < 30): Contrarian Opportunities or Value Traps?

  • SBI (₹938.80, RSI 19.09): Below 50-DMA, volume 0.93x. This is deep capitulation. If you believe PSU banks will recover, this is your entry.
  • Kaynes Technology (₹3,102, RSI 27.7): Strong downtrend, volume 1.28x. Risky, but oversold.
  • JSW Energy (₹530, RSI 28.97): Strong uptrend, volume 1.37x. The best technical setup here — a HOLD with BUY potential on confirmation.
  • Lenskart (₹478.90, RSI 12.48): The most extreme oversold reading. Either a turnaround brewing or a broken story.
  • PG Electroplast (₹459.50, RSI 10.72): Consumer electronics, strong downtrend, volume 1.96x. Avoid unless you have conviction.

Overbought Names (RSI > 70): Momentum or Exhaustion?

  • BSE (₹4,119, RSI 80.41): Fresh 52-week high, strong uptrend, volume 1.4x. The exchange stock is expensive, but momentum is real.
  • Idea Cellular (₹12.98, RSI 86.47): Telecom turnaround story, strong uptrend, volume 2.43x. Overbought, but believers are doubling down.
  • Gland Pharma (₹2,153, RSI 76.99): Volume 14.46x. This is parabolic, but with that volume, it’s conviction, not froth.
  • Solar Industries (₹18,011, RSI 81.71): Volume 3.85x, fresh 52-week high. Overbought but still climbing.

Volume Spikes (>2x): Where the Action Is

  • Gland Pharma (14.46x), Great Eastern Shipping (9.46x), Amber Enterprises (5.65x), Solar Industries (3.85x) — these are the stocks where real money is moving. Gland and GE Shipping are buys; Amber is a sell; Solar is a momentum HOLD.

No Golden or Death Crosses flagged explicitly today, but the 50-DMA/200-DMA crossover watch list remains critical for swing traders.


6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Gland Pharma BUY Above 50-DMA, RSI 76.99, vol 14.46x avg — parabolic breakout on conviction volume
Great Eastern Shipping BUY Strong uptrend, RSI 69.14, vol 9.46x avg — shipping cycle turning
Persistent Systems BUY Above 50-DMA, RSI 55.83, +5.48% on IT sector strength
Coforge BUY Above 50-DMA, RSI 66.24, vol 0.98x — stable IT play riding rupee tailwind
JSW Energy HOLD Strong uptrend, RSI 28.97 (oversold), vol 1.37x — wait for bounce confirmation
Policybazaar HOLD Above 50-DMA, RSI 62.88, vol 1.38x — fintech recovery play, watch 1750 resistance
BSE HOLD Fresh 52w high, RSI 80.41 (overbought), vol 1.4x — momentum strong but extended
Solar Industries HOLD Fresh 52w high, RSI 81.71 (overbought), vol 3.85x — parabolic but still in play
Apollo Tyres SELL Fresh 52w low, RSI 20.57 (oversold), strong downtrend — avoid until stabilization
Amber Enterprises SELL -15.39%, vol 5.65x, RSI 34.46, below 50-DMA — heavy distribution, exit
KEC International SELL -10.68%, vol 3.57x, RSI 30.43, strong downtrend — capital goods stress
Jain Irrigation SELL -19.63%, vol 2.16x, RSI 56.52 — likely news-driven collapse, avoid catch-the-knife

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape: The Week Ahead

  • US markets closed marginally higher Friday, but the real test comes this week. With US-Iran tensions unresolved and crude prices volatile, any escalation will hit risk assets hard.
  • Asian markets are already pricing in weakness: Nikkei and Hang Seng both fell over 1% today. If Asian futures remain soft overnight, expect India to gap down at open.
  • GIFT Nifty at 23,649.95 suggests a flat open — but watch the first 30 minutes. If SGX Nifty trends lower, follow the flow.

Currency and Commodities

  • USD/INR at 96.33 (+0.65%) — the rupee is under pressure. RBI intervention is likely, but sustained weakness will hurt importers.
  • Crude oil remains the wildcard. No specific data provided, but the 0.78% drop in Oil & Gas index suggests traders are nervous, not bullish.
  • Gold: No data provided, but with geopolitical risk elevated, gold typically rallies. Watch for gold-backed stablecoin headlines (one piece flagged them as a future investment trend).

Key Levels for Tuesday

  • Nifty 50: Support at 23,317 (today’s low), resistance at 23,800. A break above 23,700 could trigger short-covering.
  • Bank Nifty: Support at 52,783 (today’s low), resistance at 53,650. PSU banks are the weak link — watch SBI’s bounce or breakdown.
  • Nifty 500: Watch the breadth. If advances-to-declines ratio stays poor, the correction extends.

Earnings and Events

  • No major earnings flagged for Tuesday in the provided data, but Q4 results season is winding down. Watch for any laggards reporting late.
  • Derivatives expiry week: This is the third Monday of May — weekly options expiry on Thursday. Volatility (VIX +4.47%) suggests swings ahead.

8. The Honest Take

For Long-Term Investors:

Monday’s tape was a reminder that markets do not move in straight lines, even when they appear to. The Nifty 50’s 6.45-point gain was a mirage; the real story was 379 stocks falling. If you’re holding quality names — pharma, IT exporters, select financials — today was noise, not signal. The rupee’s slide is a tailwind for exporters; the AI hysteria will pass, and India’s consumption and infrastructure story will reassert itself. But patience is required. The next few weeks will test conviction. Add selectively on dips. Avoid the temptation to chase shipping or defence stocks at these levels — wait for pullbacks.

For Active Traders:

This was a stock-picker’s market, not an index trader’s paradise. IT and pharma longs paid; auto and metal shorts paid. The key now is to watch sector rotation and volume. Gland Pharma’s 14.46x volume spike was a gift — you either caught it or you didn’t. Tuesday’s setup favours caution: if the market gaps down, let the first hour shake out weak hands before deploying capital. The oversold names (SBI, JSW Energy, Lenskart) are on the watchlist, but wait for confirmation — an RSI bounce, a volume spike, a green candle. Don’t catch falling knives. And if the VIX stays above 19, hedging with puts or collars makes sense.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Scroll to Top