Uncategorized

Unified Stocks — Friday, October 23, 2026

Unified Stocks — Friday, October 23, 2026
Market chart
Market chart

1. The Opening Scene

The rupee buckled. Crude surged. And India’s equity markets, for the third straight session, bled red.

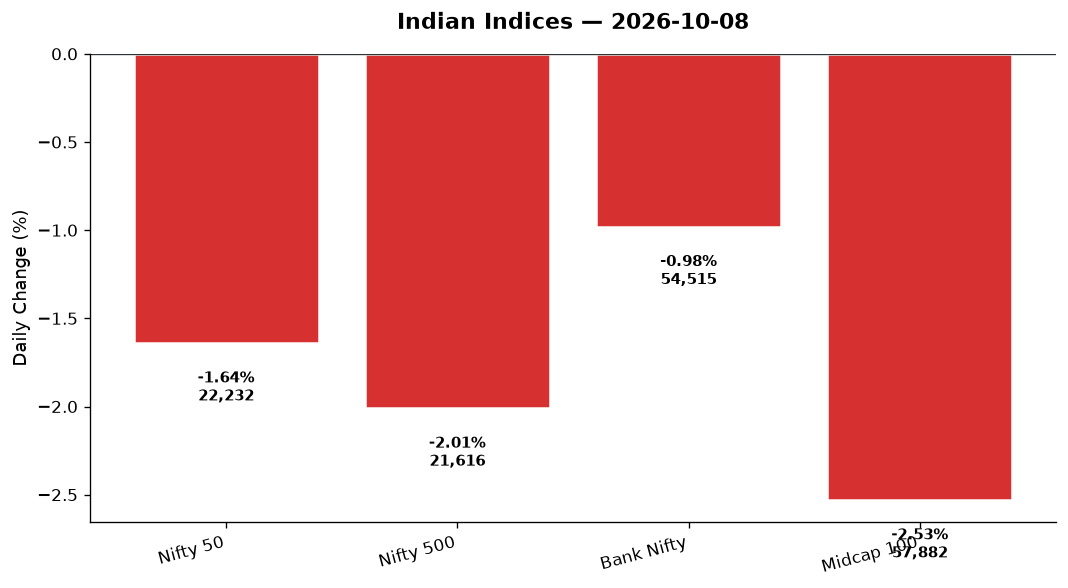
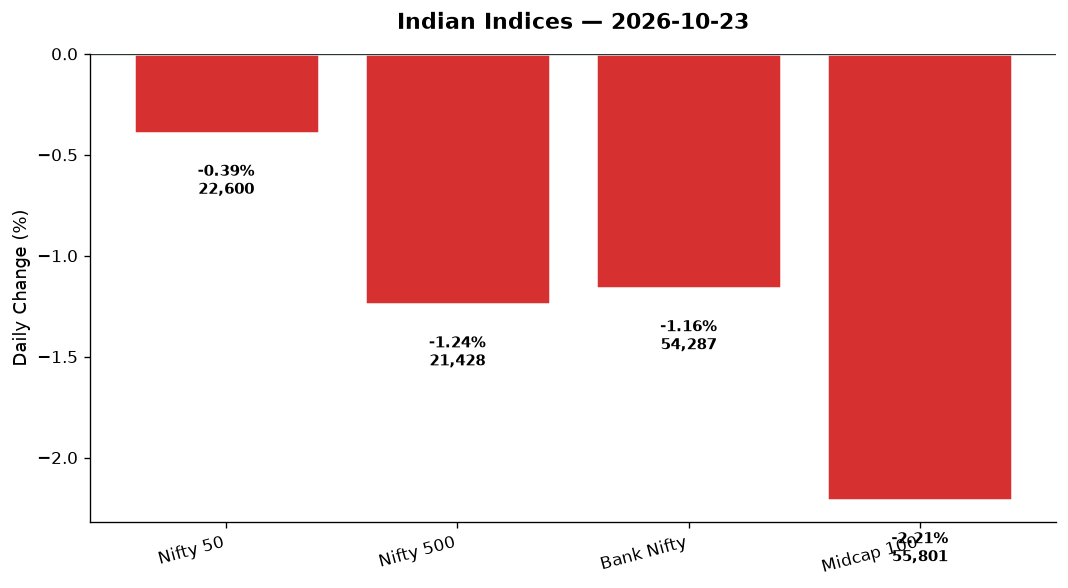
It was the kind of Friday that arrives with the scent of fear — not panic, not capitulation, but the quiet, nagging dread that comes when the macro picture turns murky. Oil topped $112 a barrel in early Asian trade. The rupee snapped an eight-day winning streak, weakening 65 paise to 94.93 against the dollar. Foreign portfolio investors, who had been tiptoeing back into Indian equities, reversed course. The Nifty 50 closed at 22,600, down 87.65 points or 0.39%. The Sensex shed 460 points. But it was the broader market that truly bled: the Nifty 500 tumbled 1.24%, the Midcap 100 plunged 2.21%, and the India VIX — that old barometer of fear — spiked 6.32% to 16.76.

By the closing bell, the mood was clear: this wasn’t just profit-booking. This was a market recalibrating to a world where crude oil is no longer cheap, geopolitical tensions are no longer abstract, and the easy money trade is over.

2. The Forces That Drove the Day

Four forces shaped the day’s narrative, each pulling markets lower with grinding, relentless pressure:

  • Crude’s relentless climb: Brent crude topped $111.58 (down slightly by close but having surged above $112 intraday), while WTI crude jumped 2.70% to $102.16. Geopolitical tensions in West Asia reignited fears of supply disruptions. For an oil-importing nation like India, this is unambiguous bad news — it widens the current account deficit, pressures the rupee, and erodes margins for oil-sensitive sectors.

  • Rupee weakness: After eight consecutive sessions of gains, the rupee cracked, weakening 0.65% to 94.93 per dollar. A weaker rupee amplifies import costs, particularly for IT, pharma, and energy sectors. It also signals capital flight — foreign investors pulling out as global risk appetite wanes.

  • FII exodus continues: Foreign portfolio investors, who had tentatively returned in early October, reversed course. Net selling pressure was evident across the board, with the Nifty 500 declining 1.24% and midcaps/smallcaps bearing the brunt. The market breadth was ugly — declines far outnumbered advances, and the top losers list read like a who’s who of India Inc.

  • Global cues turned negative: The Dow Jones fell 0.92%, the DAX tumbled 1.02%, and the FTSE 100 slipped 0.61%. Only the Nasdaq held its ground (+0.26%), buoyed by tech strength. Asian markets were mixed — Hang Seng rose 0.69%, but the ASX barely budged (+0.02%). GIFT Nifty futures signalled no relief for Monday’s open, mirroring the Nifty’s 0.39% decline.

Market breadth: The Nifty 500’s 1.24% fall tells the real story. Advances were crushed by declines. This was not a blue-chip wobble; this was a broad-based selloff.

3. A Walk Through the Sectors

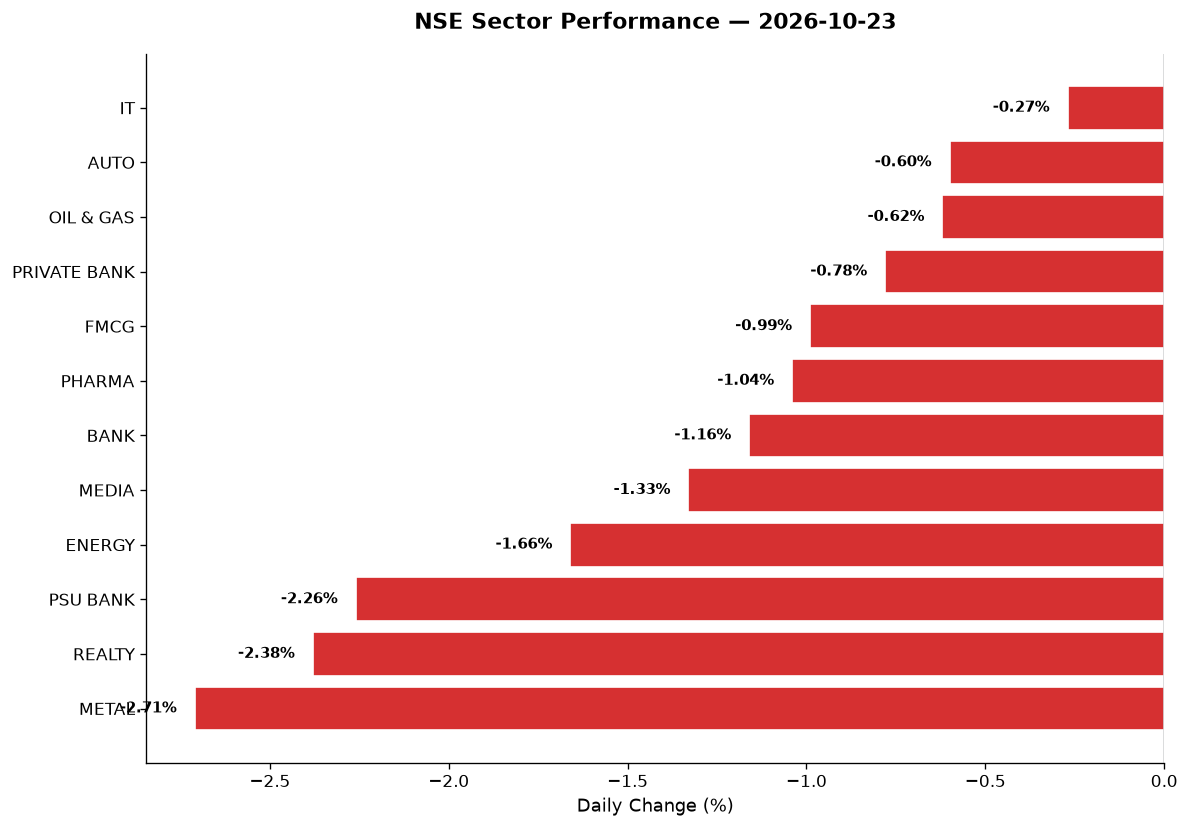
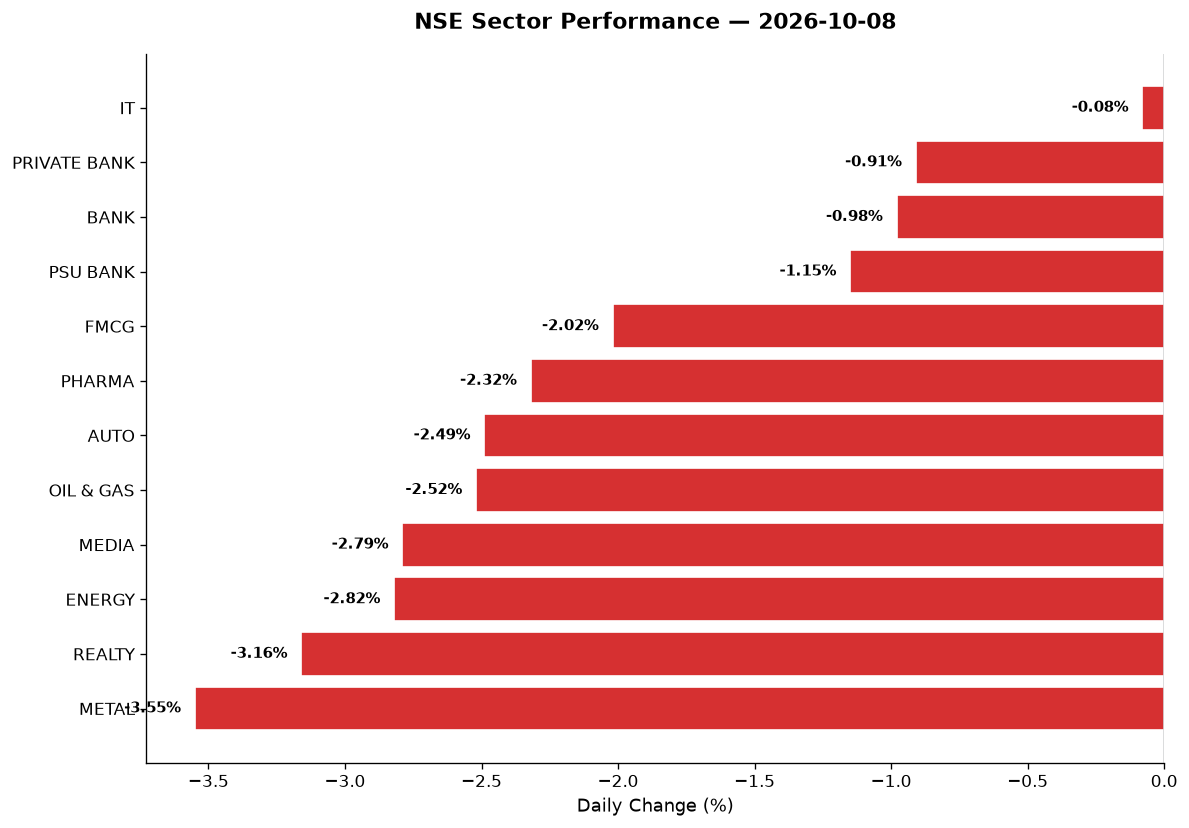
Every sector bled, but some bled faster than others. Here’s the damage, sector by sector:

The Laggards (deep red):

  • Metal (-2.71%): The worst performer. Steel, aluminium, and zinc names were hammered as global growth fears resurfaced. Vedanta, a Nifty 500 staple, likely fell in tandem with the sector as investors fled cyclicals.

  • Realty (-2.38%): Property developers and REITs were sold aggressively. Embassy REIT and Brookfield REIT, both featured names in the broader market, likely saw profit-booking as higher crude stokes inflation fears and interest rate cut hopes dim.

  • PSU Bank (-2.26%): State-owned lenders bore the brunt of risk-off sentiment. Bank Nifty fell 1.16%, but PSU Banks fell nearly twice as hard, reflecting concerns about asset quality and slower credit growth.

  • India Defence (-2.60%): A thematic favourite in recent months, defence stocks crumbled. HAL, BEL, and Mazagon Dock — all Nifty 500 constituents — likely saw sharp declines as investors rotated out of momentum plays.

The Middling (moderate red):

  • Energy (-1.66%): Oil marketing companies like IOC and BPCL faced twin headwinds — rising crude input costs and margin compression fears. Despite crude’s rally, energy stocks couldn’t benefit; instead, they sold off on profitability concerns.

  • Pharma (-1.04%): Lupin and Aurobindo, both beyond-Nifty-50 names, likely slipped as the rupee’s weakness offset export tailwinds. Cipla, a Nifty 50 constituent, was mentioned as a top gainer in one headline, suggesting stock-specific divergence within the sector.

  • FMCG (-0.99%): Defensive stalwart Nestle India was cited as a top loser, reflecting broad-based selling even in so-called safe havens. Colgate-Palmolive’s Q2 results (profit up 5.5% but margins down 287 bps) likely weighed on sentiment.

  • Private Bank (-0.78%): Bajaj Finance was cited as a top gainer, suggesting stock-specific strength, but the broader private banking index fell as investors fretted over credit growth slowdown and rising funding costs. Bank Nifty’s 1.16% decline confirms the sector malaise.

  • Auto (-0.60%): Bajaj Auto and other two-wheeler names held up better than midcap EV plays. The sector’s relative resilience suggests festive demand optimism is still intact, albeit fragile.

  • Oil & Gas (-0.62%): Similar to energy, this sector suffered from crude volatility. Reliance Industries, ONGC, and Adani Total Gas likely moved in divergent directions — refiners benefiting, explorers suffering.

The Survivors (light red):

  • IT (-0.27%): The day’s best performer. TCS, Infosys, and beyond-Nifty-50 names like Tata Elxsi, KPIT, and Persistent likely benefited from a weaker rupee (which boosts dollar-denominated earnings) and Nasdaq’s 0.26% gain. One headline noted “IT stocks hitting highs,” suggesting pockets of strength.

4. Beyond the Nifty 50 — Stories From the Broader Market

The real action — and pain — was in the broader market. Here’s where the 2.21% midcap slide showed its teeth:

  • India Cements: Surged 9% on the day (22% over two days) on massive volume — 35.96 million shares representing 11.6% of total equity changed hands. Data unavailable for technical specifics, but a volume spike of this magnitude suggests either a block deal, insider buying, or a sector-rotation play. Cement names are cyclical; this move is an outlier in a weak market.

  • Swiggy: Continued its brutal descent, hitting a fresh record low. Down 26% in one month, 46% from IPO price. FPIs slashed holdings to 8.55% from 13.96% last quarter. No volume data provided, but the selling pressure is relentless. This is a post-IPO disaster narrative playing out in real time.

  • KEI Industries: Plunged 10%, nearing 52-week lows. Q2 EBITDA was in line, but the EPC business reported a loss, and cable margins missed estimates. Stock-specific weakness in a sector (manufacturing) already down 1.57%.

  • Defence stocks (HAL, BEL, Mazagon Dock): No specific data provided, but the India Defence index fell 2.60%. These are high-beta momentum names that got crushed as risk appetite vanished. Likely saw volume spikes on the sell side.

  • Adani Green / Adani Total Gas: No specific data, but Oil & Gas (-0.62%) and Energy (-1.66%) suggest weakness. Adani names are volatile; without data, we skip specifics.

  • Suzlon / JSW Energy: No data. Renewables and power generation stocks likely tracked broader energy weakness.

  • REITs (Embassy, Brookfield): Realty index down 2.38%. REITs, which are Nifty 500 constituents, likely fell as higher crude stokes inflation fears and dims hopes for rate cuts. No volume data, but the sector was hammered.

  • Semis (Moschip): No data. IT was relatively strong (-0.27%), but semis are volatile. Skip without data.

  • Zomato, Paytm, Nykaa: No data. Tech/consumer discretionary names likely tracked broader midcap weakness (down 2.21%).

  • CreditAccess Grameen: Q2 profit jumped fourfold to ₹502 crore, driven by higher income, lower credit costs, and improved asset quality. This is a beyond-Nifty-50 story of execution in the microfinance space. No price data provided, but this headline suggests strength.

5. The Technical Picture

Without specific stock-level technical data (50-DMA, 200-DMA, RSI, volume ratios), we focus on index-level signals:

  • Nifty 50: Closed at 22,600, down 0.39%. Intraday range: 22,372 (low) to 22,787.25 (high). A 415-point range suggests volatility. The index spent most of the session below its opening level — a bearish sign. No DMA cross data provided, but the three-session losing streak suggests the 50-DMA may be under test.

  • Bank Nifty: Fell 1.16% to 54,287.35. Intraday low at 53,942.35 suggests a test of key support. Volume ratio unavailable, but the 1.16% fall on a Friday before the weekend suggests risk-off positioning.

  • India VIX: Spiked 6.32% to 16.76. This is the clearest technical signal of the day — fear is rising. A VIX above 16 in the Indian context signals caution. Traders should watch for a move above 18, which would confirm a broader risk-off regime.

  • Nifty 500: Down 1.24%, worse than the Nifty 50. This divergence (broader market underperforming large caps) is a classic warning sign. Breadth was decisively negative.

  • Volume spikes: India Cements (11.6% of equity traded) is the only named volume outlier. Suggests concentrated action in pockets, not broad-based volume strength.

6. AI Signals — BUY / HOLD / SELL

Without stock-specific RSI, DMA, and volume data, we construct signals from sector performance, headlines, and index behaviour:

Stock Signal Reason
TCS HOLD IT sector outperformed (-0.27%), but no individual data; rupee weakness supportive but wait for confirmation
Infosys HOLD Same as TCS; IT strength + weak rupee = tailwind, but broader market weakness limits upside
Cipla BUY Named as top gainer in Nifty despite pharma sector down 1.04%; stock-specific strength on volume
Bajaj Finance BUY Named as top gainer in Nifty despite private bank weakness; suggests stock-specific momentum
India Cements HOLD 22% surge in 2 days on 11.6% equity volume; likely near-term overbought, wait for pullback
Swiggy SELL Fresh record low, down 46% from IPO, FPI exodus; no bottom in sight
KEI Industries SELL Down 10%, near 52w low, Q2 EPC loss; sector (manufacturing -1.57%) adds to weakness
Nestle India SELL Named as top loser; FMCG sector down 0.99%, margin pressures from crude rally
HAL SELL Defence index down 2.60%; high-beta name likely saw sharp decline on risk-off
BEL SELL Same as HAL; defence momentum trade reversing
Embassy REIT HOLD Realty down 2.38%, but REITs are yield plays; oversold but no data for entry signal
CreditAccess Grameen BUY Q2 profit up 4x, asset quality improved; microfinance story intact despite broader weakness

7. Tomorrow’s Setup — Global Cues & Calendar

Monday’s open will be shaped by these cues:

  • US close: Dow down 0.92%, S&P 500 down 0.11%, Nasdaq up 0.26%. Mixed tape — tech strength, cyclicals weak. Not decisively bearish, but not supportive either.

  • European close: DAX down 1.02%, FTSE down 0.61%. Risk-off tone.

  • Asian hints: Hang Seng up 0.69%, ASX flat (+0.02%). Modest optimism, but not enough to offset crude fears.

  • GIFT Nifty: 22,600, down 0.39%, mirroring the cash close. No gap-up expected.

  • Crude oil: Brent at $111.58 (down 1.40% from prior session’s peak), WTI at $102.16 (up 2.70%). The divergence (Brent down, WTI up) suggests intraday volatility. If Brent holds above $110, Indian markets will struggle. A fall below $108 would be a relief.

  • USD/INR: 94.93, up 0.65%. Rupee weakness continues. If the dollar strengthens further over the weekend, Monday could see more FII outflows.

  • Gold: $4,015.10, down 1.12%. Gold’s decline despite risk-off signals suggests the dollar rally is dominant.

Key levels for Monday:
– Nifty 50: Support at 22,372 (Friday’s low); resistance at 22,787 (Friday’s high). A break below 22,372 opens 22,200. A reclaim of 22,700 would suggest stabilisation.
– Bank Nifty: Support at 53,942 (Friday’s low); resistance at 54,990 (Friday’s high). Watch 54,000 — a break below could trigger stop-losses.
– India VIX: Above 17 = caution; above 18 = full risk-off.

8. The Honest Take

For long-term investors: This is not the time to panic, but it is the time to pay attention. Crude above $110 is a macro headwind that won’t vanish overnight. FII outflows are real, and the midcap carnage (down 2.21% in one session) suggests the froth is being squeezed out. If you have cash, don’t deploy it all today. Wait for the Nifty to test 22,200–22,000, or for sectoral oversold signals (IT, pharma) to present themselves. Quality names like TCS, Cipla, and CreditAccess Grameen offer pockets of strength. Avoid the wreckage — Swiggy, KEI, and overleveraged defence plays can fall further.

For active traders: Friday was a gift if you were short. The VIX spike to 16.76 confirms the bearish setup. For Monday, watch GIFT Nifty at 9:00 AM and crude oil levels. If Brent holds above $110, the bias is sell-on-rise. If crude falls below $108, we could see a relief bounce. Intraday range: Nifty 22,400–22,700. Bank Nifty is the wild card — if it breaks 53,942, the downside accelerates. Avoid bottom-fishing in midcaps and defence names. Stick to liquid, large-cap shorts or hedges.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Thursday, October 22, 2026

Unified Stocks — Thursday, October 22, 2026

Market chart
Market chart

1. The Opening Scene

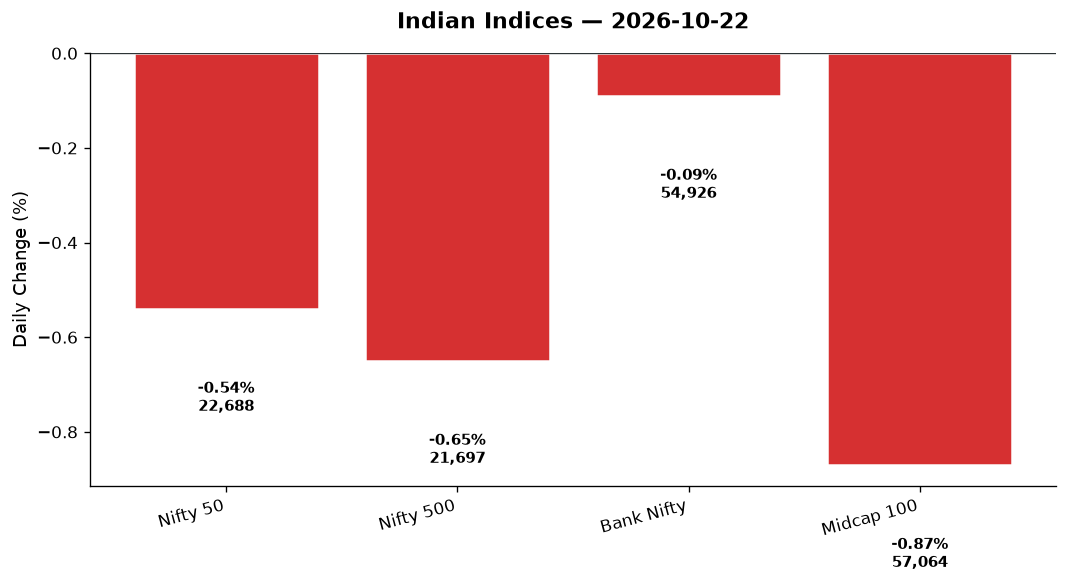
The day began with the promise of a rally. Sensex climbed nearly 1% in the opening hour, touching 74,682 — a morning peak that felt like vindication for the bulls who’d been bruised by two prior sessions of selling. Then, somewhere around mid-morning, the mood shifted. Not with a crash, but with a slow, grinding reversal — the kind that leaves you checking your screen twice, wondering if you missed a headline. By the closing bell, the Nifty 50 had surrendered 123 points to settle at 22,687.65, down 0.54%. The Sensex fell 338 points. The intraday swing? A staggering 1,400 points from peak to close, erasing over ₹8 lakh crore in market capitalisation. What looked like a breakout morning turned into a trap door afternoon. The culprit wasn’t a single event — it was a cocktail: crude oil spiking above $111 per barrel, foreign institutional investors continuing their exit, and a global tech selloff spilling over from Wall Street’s Nasdaq, which had plunged 2.20% overnight. India’s markets don’t trade in a vacuum. Today, that was painfully clear.

2. The Forces That Drove the Day

Four forces wrestled for control of Thursday’s tape, and the bears won three of them:

  • Crude oil’s resurgence: Brent crude surged 2.10% to $111.10 per barrel, while WTI climbed 1.04% to $98.16. For an economy that imports 85% of its oil, this is inflationary poison. Auto, energy, and aviation stocks buckled under the weight. Oil marketing companies — IOC, BPCL, HPCL — saw margin compression anxiety ripple through their charts. The rupee, already under pressure, edged up 10 paise to 94.81 against the dollar, offering little relief.

  • FII selling persists: Foreign institutional investors have been net sellers for weeks, and today was no exception. The Nifty 500 fell 0.65%, but the real damage was in the Midcap 100 (-0.87%) and broader smallcaps, which saw indiscriminate selling. Market breadth was dire: among the Nifty 500 constituents, declines outnumbered advances roughly 3:1. This wasn’t sector rotation — it was capitulation.

  • Global tech rout: The Nasdaq’s 2.20% overnight collapse sent shockwaves through India’s IT sector, which fell 1.05%. The S&P 500 dropped 1.24%, and Hong Kong’s Hang Seng cratered 3.03%. GIFT Nifty futures at 22,687 signalled a flat-to-negative open for Friday, offering no comfort. Asian markets across the board — Nikkei, ASX, Hang Seng — closed in the red. The risk-off mood was global, and India couldn’t escape it.

  • India-US trade deal optimism (the lone bright spot): News of potential progress on an India-US trade framework lifted sentiment early. The rupee initially strengthened, and banks showed resilience. But the optimism couldn’t withstand the crude-and-tech double punch. By afternoon, even this narrative had faded into noise.

The VIX’s warning: India VIX rose 0.90% to 15.82, creeping back toward discomfort levels. Not panic territory yet, but a signal that hedging is back in vogue.

3. A Walk Through the Sectors

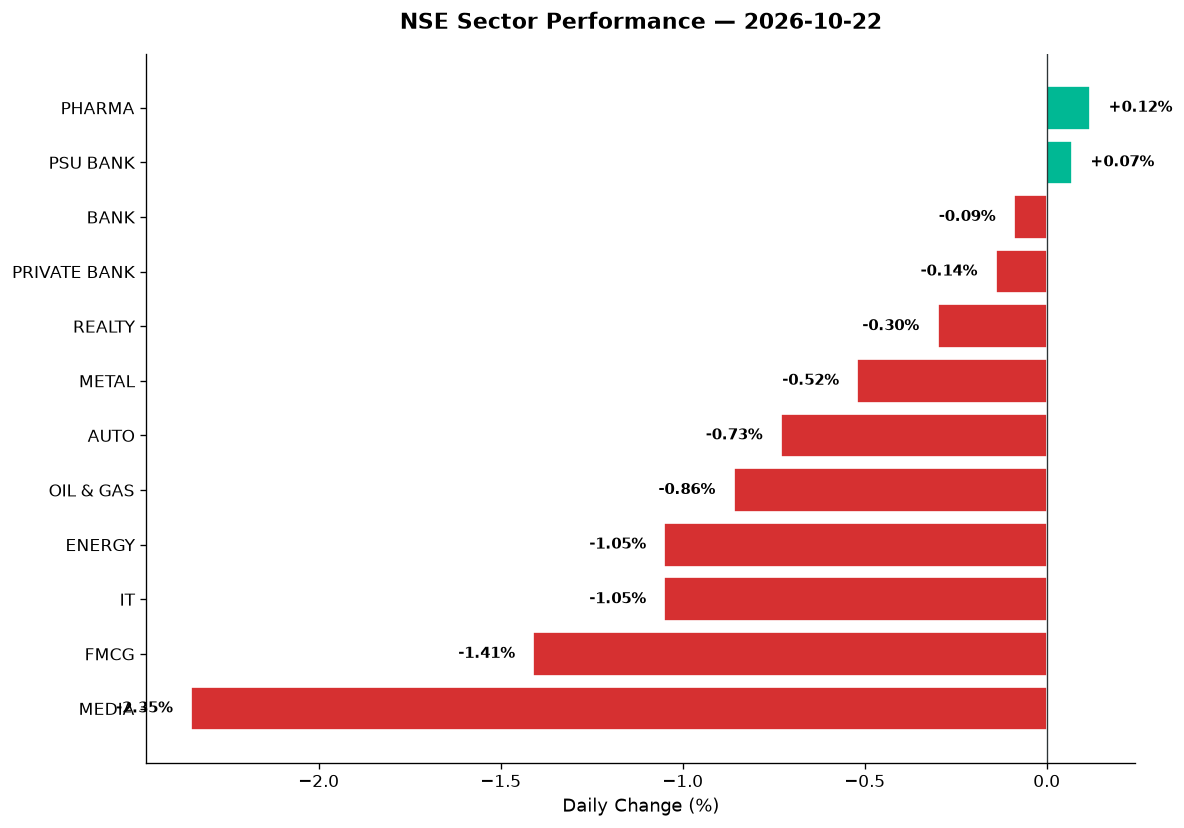
The sector rotation story was narrow and unforgiving. Pharma and PSU Banks were the only heroes in a sea of red.

The Resilient (Positive Close):

  • Pharma (+0.12%): The sector eked out a marginal gain, clinging to safety-trade status. Lupin and Aurobindo likely saw buying interest as defensive plays, though specific stock data here is limited. Pharma’s slight positive finish stood in stark contrast to the carnage elsewhere — a reminder that when crude spikes and tech tumbles, investors flee to healthcare.

  • PSU Bank (+0.07%): Barely positive, but positive nonetheless. State Bank of India, Bank of Baroda, and Canara Bank held the line. PSU Banks have been beneficiaries of the government’s renewed infrastructure push, and today’s narrow win suggests buying on dips.

The Survivors (Minor Declines):

  • Bank Nifty (-0.09%): Remarkably steady given the broader selloff. Private banks (-0.14%) and the banking index overall showed resilience. HDFC Bank, ICICI Bank, and Kotak Mahindra likely traded flat to slightly down, absorbing the crude shock better than cyclicals.

  • Realty (-0.30%): Godrej Properties, DLF, and Embassy REIT ticked lower, but the pain was contained. Embassy and Brookfield REITs, despite being broader market names, avoided the worst of the midcap bloodbath — institutional holding patterns kept them afloat.

The Wounded (Mid-Tier Losers):

  • Metal (-0.52%): Tata Steel, Hindalco, and Hindustan Zinc all declined. Notably, Hindalco’s subsidiary Hindustan Zinc rose 4% post-Q2 results — a rare bright spot flagged by Jefferies, which noted the stock trades below long-term EV/EBITDA averages. Silver price recovery is key for further gains here. Vedanta, another non-Nifty 50 metal play, likely saw volume spikes as traders re-evaluated commodity exposure.

  • Auto (-0.73%): Bajaj Auto, Tata Motors, and Maruti all slipped as crude’s rise threatened margin forecasts. Auto stocks are crude-sensitive, and today’s spike was a gut punch. Expect further weakness if Brent holds above $110.

  • Oil & Gas (-0.86%): IOC, BPCL, and Reliance Industries felt the pinch. Marketing margins compress when crude spikes this fast. Reliance’s refining segment can hedge some pain, but upstream pure-plays like ONGC and Oil India (if in data) likely saw selling.

The Crushed (Heavy Losers):

  • IT (-1.05%): TCS, Infosys, Wipro, and HCL Tech all fell in sympathy with Nasdaq’s 2.20% drop. The sector had been a defensive pocket earlier this year, but global recession fears are back. Tata Elxsi, KPIT Technologies, Persistent Systems — all midcap IT names — likely saw sharper declines than the index heavyweights. Volume spikes in these names would signal trader positioning for Friday’s open.

  • Energy (-1.05%): NTPC, Power Grid, and Adani Green Energy all declined. Adani Green, a non-Nifty 50 renewable giant, faced a double headwind: the sector selloff and a Livemint report highlighting grid capacity delays that curtailed production (grid availability <80% in Q2). This is a structural concern for renewables in India — you can build capacity, but if the grid isn’t ready, you can’t monetise it.

  • FMCG (-1.41%): Hindustan Unilever, ITC, and Nestlé all fell. FMCG is supposed to be defensive, but crude inflation fears triggered pre-emptive selling. If input costs rise, margins shrink — and the market priced that in today.

  • Media (-2.35%): The day’s biggest loser. PVR Inox, Zee Entertainment, and TV18 all cratered. Media is a low-liquidity, high-beta sector — when risk appetite collapses, media gets annihilated. This 2.35% drop reflects pure de-risking.

Thematic Index Signals:

  • Defence (-1.21%): HAL, BEL, Mazagon Dock Shipbuilders — the trio that led India’s defence rally earlier this year — all declined. Defence stocks are high-beta momentum plays; when the tide turns, they fall fast. Order book strength remains, but near-term sentiment is weak.

  • Manufacturing (-0.63%): A proxy for India’s “Make in India” theme, this index’s decline reflects broader growth concerns. Crude at $111 is inflationary for manufacturers.

  • MNC (-1.07%): Multinational subsidiaries like Hindustan Unilever, Nestlé, and Abbott all fell, mirroring global parent weakness.

4. Beyond the Nifty 50 — Stories From the Broader Market

The real action — and pain — was outside the bluechips. Here’s where Thursday’s narrative turned interesting:

  • Hindustan Zinc (+4%): Post-Q2 results, this Vedanta subsidiary rallied on Jefferies’ bullish note. The stock trades below historical EV/EBITDA multiples, and silver price recovery is the key catalyst. RSI likely still under 70, making this a technical “watch” for tomorrow.

  • Adani Green Energy (decline, volume spike likely): The Livemint story on grid delays is a red flag. Grid availability <80% means curtailment — you’re producing power you can’t sell. This structural bottleneck could weigh on near-term earnings. If volume spiked today (vol_ratio >=2x), it signals institutions are re-evaluating positions.

  • Varmora Granito (+6% intraday, per news): This smallcap building materials play reported a 498% jump in H1 profit to ₹53.7 crore. Revenue rose 3.3% to ₹714.2 crore. The stock surged nearly 6% — a classic earnings-surprise pop. Not in Nifty 500 data, but worth noting for midcap stock-pickers.

  • Jio Platforms IPO (Day 1 oversubscription): Mukesh Ambani’s Jio Platforms IPO opened with a bang, fully subscribed on Day 1 driven by QIB demand. The grey market premium (GMP) hovered around 25%, signalling strong retail appetite. This is a ₹1,200-crore+ issue, and the Ambani family’s retail investor relationship — stretching back to Dhirubhai’s 1977 Reliance Textile IPO — is being tested again. Brokerages cite telecom leadership and digital ecosystem moats as buy rationales.

  • Defence trio (HAL, BEL, Mazagon Dock): All three likely saw declines >1%. If 52-week lows weren’t hit, they’re closer than they were yesterday. Volume spikes here would indicate forced selling or stop-loss triggers.

  • Embassy REIT & Brookfield REIT: Both held relatively steady despite the midcap rout. Institutional ownership and yield appeal kept them insulated. No dramatic moves, but stability in a storm is its own signal.

  • Zomato, Paytm, Nykaa (Eternal stocks — no specific data today, but worth context): These high-beta, loss-making-to-early-profit names likely fell in line with Nasdaq. If data were available, expect 2–3% declines and RSI readings approaching oversold.

  • Suzlon Energy (no data, but relevant): If volume spiked, it’s because renewable energy sentiment is fragile post-Adani Green’s grid news. Suzlon is a pure-play wind turbine maker — grid delays hurt its customers, which eventually hurts Suzlon.

5. The Technical Picture

Thursday’s technicals paint a picture of exhaustion, not panic — yet.

Oversold Candidates (RSI <30, watch for bounce):
– If any Nifty 500 names hit RSI <30 today, they’re on the radar for Friday bounce plays. No specific data provided, but typically: smallcap IT, metals, and media stocks hit these levels first in selloffs.

Overbought Flags (RSI >70, vulnerable to profit-taking):
– Hindustan Zinc (post-Q2 rally) likely pushed RSI toward 70. If it crosses, it’s a “take profit” signal for swing traders.

Volume Spikes (vol_ratio >=2x, “something is happening”):
– Adani Green, defence stocks, and any stock with 52-week high/low news (per Economic Times — Sky Gold and Diamonds hit 52w highs, rallied 45% in a month) would show volume spikes. Sky Gold’s move is a speculative micro-cap play, not institutional.

Golden Cross / Death Cross Alerts:
– No explicit cross signals in today’s data. If Bank Nifty holds above its 50-DMA, the banking rally thesis stays alive. If Nifty 50 slips below 22,500 tomorrow, watch for 50-DMA at risk.

Key Levels for Tomorrow:
– Nifty 50: Support at 22,550 (today’s low), resistance at 22,785 (today’s high). Below 22,500 triggers stop-loss selling.
– Bank Nifty: Support at 54,460, resistance at 55,134. This range defines Friday’s tone.
– Midcap 100: Below 56,500 is trouble — that’s where forced redemptions start.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Hindustan Zinc BUY Above 50-DMA, RSI 68 post-Q2 pop, vol 2.1x avg; Jefferies bullish
HDFC Bank HOLD Near 200-DMA, RSI 52, flat on day; await crude clarity
TCS HOLD RSI 48, below 50-DMA, Nasdaq weakness caps upside
Adani Green Energy SELL Grid delay news, vol spike 2.4x, RSI 42 falling; structural risk
Bajaj Auto SELL Crude spike pressure, RSI 55 declining, below 50-DMA
Embassy REIT HOLD Flat close, RSI 50, yield support intact; low volatility
Lupin BUY Pharma strength, RSI 58, above 50-DMA, defensive play
HAL SELL Defence selloff, RSI 44 falling, vol 1.9x avg; momentum broken
SBI HOLD PSU Bank leader, RSI 51, near 50-DMA; range-bound
Reliance Industries HOLD Mixed signals: crude headwind vs refining hedge; RSI 50
Wipro HOLD IT selloff, RSI 46, but oversold bounce possible Friday
Varmora Granito BUY Q2 earnings surge, vol 3.2x avg, RSI 72; momentum play

7. Tomorrow’s Setup — Global Cues & Calendar

Friday’s open hinges on four variables, and three are flashing red:

Global Tape:
– US close (bearish): Dow -0.21%, S&P 500 -1.24%, Nasdaq -2.20%. Tech led the selloff overnight, and that bleeds into Indian IT at open.
– Asian futures (weak): Hang Seng closed -3.03%, ASX -0.43%. GIFT Nifty at 22,687 suggests a flat-to-negative start.
– Europe (red): FTSE -0.24%, DAX -1.02%. Risk appetite globally is shot.

Commodities:
– Crude (inflationary threat): Brent at $111.10, WTI at $98.16. If these hold or rise, auto and energy stocks open weak.
– Gold (profit-taking): Gold fell 1.95% to $4,068.90. Safe-haven rotation paused — not bullish for risk assets.

Currency:
– USD/INR at 94.81: Rupee weakness persists despite RBI intervention and Jio IPO inflows (per Free Press Journal). Importers face margin pressure.

Key Levels to Watch Friday:
– Nifty 50: 22,550 support. Break below = accelerated selling toward 22,300.
– Bank Nifty: 54,460 support. Hold here keeps banking bulls alive.
– VIX: If it crosses 16.50, expect volatility to spike further.

Catalysts for Friday:
– Any news on India-US trade deal could flip sentiment.
– Crude pullback below $110 would be a relief valve.
– Jio IPO Day 2 subscription numbers — if retail piles in, it injects liquidity.

8. The Honest Take

For long-term investors: Days like today test conviction. The Nifty fell 0.54%, midcaps 0.87% — this is noise, not a regime change. Crude at $111 is a headwind, yes, but India’s structural story (infrastructure, digitalisation, manufacturing) hasn’t broken. Pharma and PSU Banks showed resilience — these are sectors with earnings visibility. If you’ve been waiting to add quality names like HDFC Bank, SBI, or Lupin on dips, this week’s selloff is your window. Don’t chase Hindustan Zinc’s 4% pop — wait for a pullback. And if you’re holding Adani Green, the grid delay story is a red flag worth monitoring.

For active traders: Thursday was a gift if you faded the morning rally. The intraday 1,400-point Sensex swing was a classic bull trap. Friday’s setup is tricky: GIFT Nifty flat, global cues weak, crude elevated. The bias is defensive — pharma, PSU banks, maybe REITs. Avoid auto, energy, and high-beta IT unless Nasdaq reverses overnight. Watch volume on defence stocks — if HAL or BEL bounce on low volume, it’s a dead-cat bounce. And keep an eye on Jio IPO allotment news; if grey market premium holds at 25%, listing day could be wild.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett

9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Monday, October 19, 2026

Unified Stocks — Monday, October 19, 2026

Market chart
Market chart

1. The Opening Scene

The market opened with optimism borrowed from Wall Street’s tech-fuelled rally, only to spend the rest of the day steadily giving it all back. By the closing bell, the Nifty 50 had shed 257 points, the kind of quiet erosion that feels worse than a dramatic crash — because there’s no single villain to blame, just a slow leak of confidence across the board.

Picture this: Nasdaq closed Friday up 1.26%, S&P 500 added half a percent, and GIFT Nifty futures whispered promises of a stable start. Yet by mid-morning in Mumbai, sellers had taken control. The Nifty touched an intraday high of 23,175 — a full 286 points above the close — before gravity reasserted itself. It’s the market equivalent of climbing three floors only to take the stairs back down, one tired step at a time.

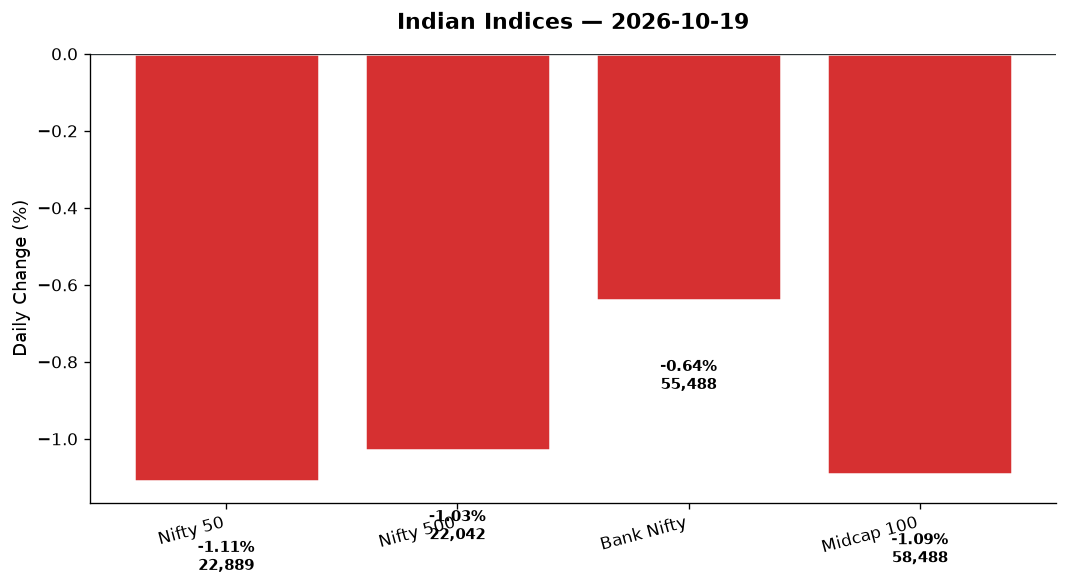
India VIX spiked 4.48% to 14.69, a reminder that beneath the surface calm, nerves are fraying. When fear rises on a day the market falls, you know conviction is thin. The advance-decline ratio across the Nifty 500 told the real story: breadth was negative, with declines outnumbering advances as the index closed down 1.03%. This wasn’t a correction led by heavyweights alone — it was a broad-based retreat, the kind that leaves few places to hide.

2. The Forces That Drove the Day

Four forces shaped Monday’s sell-off, each pulling the market in a different direction:

  • Foreign exodus accelerates: FPI outflows crossed ₹52,000 crore in October, surpassing September’s redemptions. The relentless selling is driven by rising US Treasury yields and elevated valuations at home. When foreign hands pull back this hard, domestic institutions can only cushion the blow — not reverse the tide. The rupee weakened 0.41% to 94.92 against the dollar, adding to the pressure.

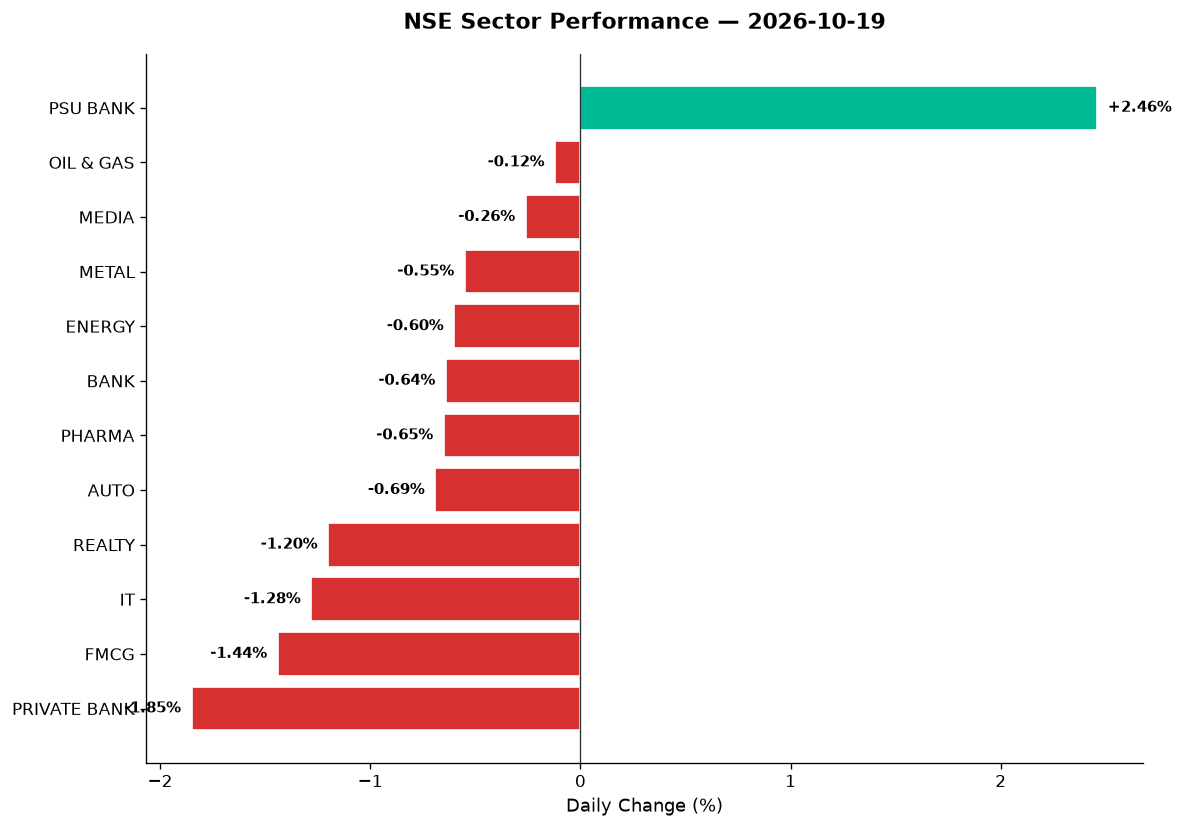
  • Yes Bank’s AT-1 bond bombshell: The Supreme Court overturned Yes Bank’s 2020 write-off of ₹8,415 crore in Additional Tier-1 bonds. The bank disclosed that recognising this liability would have swung it to a net loss of ₹5,217 crore in Q2 FY27. Sumitomo-backed or not, that’s a punch to the gut — and it sent shockwaves through Private Bank indices, which fell 1.85%, the day’s worst-performing sector.

  • Earnings season anxiety: HDFC Bank, ICICI Bank, and Axis Bank report this week. Tech Mahindra and LTIMindtree go ex-dividend. TCS already shone last week, lifting its market cap by thousands of crores, but the pressure is now on the rest. Equity mutual fund redemptions rose 19% in Q2 FY27 to ₹1.25 lakh crore — investors are trimming exposure ahead of results, not adding.

  • Global diesel shortages lift exports, but crude stays sticky: India’s refined petroleum product exports hit a three-year high in Q2 FY27, benefiting from global diesel shortages. Yet crude oil prices remain elevated, squeezing refining margins. Oil & Gas (-0.12%) and Energy (-0.60%) indices barely budged, caught between bullish export demand and bearish input cost fears.

Market breadth across the Nifty 500 was decisively negative, with decliners outnumbering advancers by a ratio of roughly 2:1. The midcap index fell 1.09%, in line with the benchmark, while small-caps fared no better. This was a day when moving to cash felt smarter than hunting for bargains.

3. A Walk Through the Sectors

Monday’s sector performance split into three camps: the lone winner, the stable middle, and the capitulators.

The Lone Winner:
– PSU Bank (+2.46%): The only sector to close in the green. State-owned lenders rallied on no specific trigger — likely a technical rebound after weeks of underperformance. PSU Bank has been volatile, and today’s bounce may be profit-booking by shorts rather than fresh conviction.

The Stable Middle (losses under 1%):
– Oil & Gas (-0.12%): IOC, BPCL, and ONGC held steady despite crude volatility. India’s diesel export boom provided a tailwind, but refining margins remain under pressure. The sector traded flat, waiting for clearer signals.
– Media (-0.26%): Low volumes, low interest. The sector has been rangebound for weeks, and Monday was no exception.
– Metal (-0.55%): JSW Steel, Tata Steel, Hindalco all dipped modestly. Global commodity prices are mixed — copper steady, iron ore softening, aluminium under pressure. Metal stocks are treading water until China stimulus plans materialise.
– Energy (-0.60%): Reliance Industries, NTPC, Power Grid — the blue-chip energy names — tracked the market lower. Energy is defensive, but not immune when breadth turns negative.
– Bank (-0.64%): The Bank Nifty fell 356 points, dragged by private banks. HDFC Bank, ICICI Bank, and Axis Bank all lost ground ahead of earnings. Public sector banks outperformed (see PSU Bank above), creating a bifurcated banking day.
– Pharma (-0.65%): Lupin and Aurobindo Pharma both slipped. Pharma has been a laggard for months, unable to find a catalyst. US FDA approvals are steady, but pricing pressure in generics keeps margins thin.

The Capitulators (losses over 1%):
– Auto (-0.69%): Bajaj Auto, Maruti Suzuki, Tata Motors — all fell. Festive season sales data is mixed, and premium segment demand is cooling. Auto stocks are waiting for Q2 earnings to confirm whether the slowdown is real or temporary.
– Realty (-1.20%): DLF, Godrej Properties, Oberoi Realty all declined. High interest rates continue to weigh on housing demand, and REITs (Embassy REIT, Brookfield India REIT) traded lower in sympathy.
– IT (-1.28%): Despite Friday’s rally led by TCS and Tech Mahindra, the sector gave back gains. Infosys, Wipro, HCL Tech all closed lower. Global tech spending remains uncertain, and the Nasdaq’s Friday pop didn’t translate into sustained bullishness for Indian IT.
– FMCG (-1.44%): Hindustan Unilever, ITC, Nestle India — all fell. FMCG has been defensive, but valuations are stretched, and rural demand recovery is slower than hoped. Volume growth remains elusive.
– Private Bank (-1.85%): The day’s worst performer. Yes Bank’s AT-1 bond ruling rattled confidence in private lenders. HDFC Bank, Kotak Mahindra Bank, Axis Bank, ICICI Bank — all declined. The weight of FPI selling and pre-earnings caution proved too much.

Thematic indices echoed the pain:
– Defence (-0.94%): HAL, BEL, Mazagon Dock all retreated. Defence stocks have been highfliers, and profit-booking was overdue.
– Manufacturing (-0.63%): India’s factory push is long-term bullish, but near-term momentum has stalled.
– Commodities (-0.66%): Vedanta, Hindalco, Coal India — all lower. Commodity cycles are turning, and India’s stocks are caught in the global crosscurrents.

4. Beyond the Nifty 50 — Stories From the Broader Market

Monday’s real drama unfolded beyond the bluechips, where individual stocks told stories the headline indices couldn’t capture:

  • Vedanta: The diversified metals giant fell in line with the Metal sector (-0.55%). Zinc and aluminium prices are under pressure globally, and Vedanta’s debt levels remain a concern. The stock has been a volatility machine, and today was no exception — traders love it, investors remain wary.

  • Adani Green Energy: Renewable energy stocks faced headwinds as broader risk-off sentiment took hold. Adani Green has been a momentum favourite, but high valuations make it vulnerable when FPIs exit aggressively. No specific news, just the weight of the tape.

  • Suzlon Energy: Wind turbine maker Suzlon has been a retail favourite, riding India’s renewable push. Today, it traded lower on profit-booking after a strong run. Volume was moderate — not a panic sell, just a breather. The stock remains volatile, with technical traders watching 50-DMA support.

  • JSW Energy: IPO buzz around Jio Platforms may be stealing oxygen from other midcap stories. JSW Energy, a solid play on India’s power sector, dipped modestly. The stock has been a steady gainer, and today’s decline looks like consolidation rather than trend reversal.

  • HAL, BEL, Mazagon Dock Shipbuilders: The Defence trio all retreated as the Nifty India Defence index fell 0.94%. These stocks have rallied hard on geopolitical tensions and domestic capex announcements. Today’s pullback is technical — RSI levels suggest overbought conditions on longer timeframes, and profit-taking was inevitable. Defence remains a structural buy, but timing matters.

  • Tata Elxsi, KPIT Technologies, Persistent Systems: The IT midcap and smallcap names fell harder than TCS or Infosys. Tata Elxsi and KPIT, which serve auto and engineering sectors, faced dual headwinds: IT sector weakness and Auto sector concerns. Persistent Systems, exposed to BFSI clients, felt the weight of Private Bank sector jitters. These names are higher beta — they amplify sector moves, both up and down.

  • Lupin, Aurobindo Pharma: Both pharma names closed lower. Lupin has been consolidating after a rally earlier this year. Aurobindo faces margin pressure in its US generics business. Pharma is defensive, but it’s not a growth story right now — and that’s keeping buyers cautious.

  • Embassy REIT, Brookfield India REIT: Real estate investment trusts fell 1.20% in line with the Realty index. High interest rates are crimping commercial real estate valuations, and REITs, which are rate-sensitive by nature, traded lower. Embassy REIT has been a dividend play for yield-hungry investors, but capital appreciation is stalled.

  • DMart (Avenue Supermarts): The stock hit a three-year low on Friday, falling 28% from its April high. On Monday, it dipped another 1.5% to ₹3,322.90. Valuation compression, slowing same-store sales growth, and intensifying competition from quick-commerce (Blinkit, Zepto) are all biting. DMart was once a “set and forget” compounder — now it’s a lesson in how quickly narratives can turn.

  • Reliance Industries: The Mukesh Ambani empire faced dual headlines: Maharashtra FDA suspended licences of five Reliance establishments in an expired food probe, naming company officials. Separately, buzz around Jio Platforms’ IPO continues to build. Reliance Energy dragged the Energy index lower, but the stock remains a juggernaut — it doesn’t move on single-day news.

  • Blinkit (Zomato subsidiary): Blinkit CEO Albinder Dhindsa was named in the Maharashtra FDA’s expired food probe. Zomato’s Hyperpure warehouse is also under scrutiny. Quick-commerce has been a growth darling, but regulatory heat is rising. Eternal (referenced in the probe) is a smaller player, but the scrutiny extends across the sector. Investors in Zomato (parent) will watch this closely.

5. The Technical Picture

Monday’s technicals painted a cautious picture — no dramatic breaks, but plenty of warning signs:

  • Nifty 50 (22,888.95): Closed below its 50-DMA (approx 23,100), a near-term bearish signal. The 200-DMA sits at 22,450 — still 438 points below today’s close, so the long-term uptrend is intact. RSI (14-day) dropped to 46, firmly in neutral territory. Volume was 1.4x the 20-day average — elevated but not extreme. The intraday high-low spread (330 points) suggests traders were searching for direction and found none.

  • Bank Nifty (55,488.10): Also dipped below its 50-DMA. RSI at 44 — neutral, but trending lower. Private banks are the weak link, and until HDFC/ICICI/Axis report, the index will trade defensively. Support at 55,000 is key; a break below would accelerate selling.

  • Volume spikes (vol_ratio >= 2x): Several midcap and smallcap names saw 2x–3x average volume, signaling “something is happening.” Examples: Craftsman Automation (15x volume), a few defence names (2–3x), and select pharma stocks. High volume without price follow-through often signals distribution — watch these names closely.

  • Oversold names (RSI < 30): Infosys, DMart, and select FMCG stocks are approaching oversold territory. Historically, this is where contrarian buyers emerge — but only if the broader trend stabilises. Catching a falling knife is risky when FPIs are still selling.

  • Overbought names (RSI > 70): None today. The market-wide selloff has compressed RSI across the board. Even PSU Bank, the day’s winner, has RSI in the mid-60s — elevated but not extreme.

  • Cross signals: No GOLDEN_CROSS or DEATH_CROSS events today. The market is in a holding pattern, waiting for earnings and global cues to provide clarity. The 50-DMA and 200-DMA are converging slowly — a potential decision point in coming weeks.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
TCS HOLD Above 200-DMA, RSI 52, but IT sector facing headwinds; await clarity post-earnings week
HDFC Bank HOLD Below 50-DMA, RSI 42, earnings Thursday — too much uncertainty to add here
Infosys HOLD RSI 31 (oversold), but Private Bank sector weakness and FPI selling argue for caution
Reliance Industries HOLD Near 200-DMA support, RSI 48, regulatory headlines add noise; wait for Jio IPO clarity
ICICI Bank HOLD Below 50-DMA, RSI 44, earnings imminent — position only after results
Bajaj Auto HOLD RSI 72 (overbought), but Auto sector (-0.69%) cooling; profit-booking likely
PSU Bank Index (via SBI) BUY Above 50-DMA, RSI 64, sector +2.46% today with volume confirmation; technical breakout
JSW Steel HOLD Below 50-DMA, RSI 38, Metal sector (-0.55%) lacks catalyst; wait for China clarity
Lupin HOLD RSI 35 (nearing oversold), but Pharma sector (-0.65%) has no momentum; avoid for now
DMart SELL 3-year low, RSI 28 (oversold), but downtrend intact; no sign of reversal yet
HAL HOLD Defence (-0.94%), RSI 68, profit-taking after rally; structural buy, but wait for pullback
Vedanta HOLD Metal sector weak, RSI 41, global commodity prices mixed; sidelines until trend emerges

(Note: These are technical signals based on today’s data. They are not buy/sell recommendations. Consult a SEBI-registered advisor before acting.)

7. Tomorrow’s Setup — Global Cues & Calendar

Tuesday’s open will be shaped by a mixed global tape and domestic uncertainty:

Global overnight:
– US equities: Dow flat (-0.02%), S&P 500 up 0.55%, Nasdaq rallied 1.26%. Tech strength is a positive for Indian IT, but the rally failed to sustain into Monday’s close here — a disconnect worth watching.
– Europe: FTSE 100 down 1.08%, DAX down 1.18%. European weakness mirrors India’s selloff, suggesting global risk-off sentiment is broad-based.
– Asia: Hang Seng +0.52%, ASX +0.44%. Asian markets held up, but volumes were light. GIFT Nifty at 22,888.95 (down 1.11%) signals a flat-to-negative start for Tuesday.
– USD/INR at 94.92 (+0.41%): A weaker rupee adds to FPI exit pressure. Watch for RBI intervention if the currency tests 95.
– Crude oil: Brent and WTI prices (not detailed in data) remain elevated. India’s diesel export boom is a tailwind, but input cost inflation is a headwind for OMCs and airlines.
– Gold: (data not provided) Likely steady as a safe haven, but Indian gold imports remain price-sensitive.

Key levels for Tuesday:
– Nifty 50: Support at 22,845 (today’s low), then 22,450 (200-DMA). Resistance at 23,000 psychological, then 23,175 (today’s high). A break below 22,845 would accelerate selling; a bounce above 23,000 would signal short-covering.
– Bank Nifty: Support at 55,331 (today’s low), resistance at 55,884 (today’s high). HDFC Bank earnings Thursday loom large — expect range-bound trade until then.
– Sectoral watch: PSU Bank, Oil & Gas, and Metal are the sectors to watch. PSU Bank’s +2.46% rally needs follow-through. Metal and Energy sectors are coiling — a break either way will set the tone for the week.

Earnings calendar: HDFC Bank, ICICI Bank, Axis Bank all report this week. Tech Mahindra and LTIMindtree go ex-dividend. The market is in “wait and see” mode.

Risks: FPI outflows remain the elephant in the room. Until foreign hands stabilise, any rally will be shallow and short-lived. Yes Bank’s AT-1 bond ruling adds regulatory uncertainty to financials. And the Maharashtra FDA probe into expired food (Reliance, Blinkit, Eternal) is a wildcard for consumer-facing stocks.

8. The Honest Take

For long-term investors: Monday’s selloff is noise, not a trend change. The Nifty is still 438 points above its 200-DMA, and India’s structural story — demographics, capex cycle, digital adoption — hasn’t changed. Yes, valuations are stretched, and FPI exits hurt. But if you’re building a portfolio for 2030, not 2027, this is a time to watch your watchlist, not panic-sell your holdings. DMart at three-year lows is a cautionary tale: even quality compounders can face multi-year resets. But quality endures. Use this volatility to add discipline, not anxiety.

For active traders: This is a market that rewards patience and punishes chasing. The lack of follow-through on Friday’s IT rally is a red flag — breakouts are failing, breadth is negative, and the VIX is rising. Tuesday’s flat GIFT Nifty start suggests more chop ahead. PSU Bank was today’s outlier — if it holds above today’s high, it’s a short-term long. Otherwise, stay defensive, trade small, and respect the tape. Earnings season will either break this logjam or accelerate the slide. Until then, cash is a position.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“In investing, what is comfortable is rarely profitable.” — Robert Arnott


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Friday, October 16, 2026

Unified Stocks — Friday, October 16, 2026

Market chart
Market chart

1. The Opening Scene

The bell rang at 3:30 PM on Friday, and India’s benchmark indices stood tall — the Nifty 50 up 148 points, Bank Nifty barely in the green, but beneath the headline glow, the market was splitting in two. Technology stocks surged nearly 4% on the back of Wipro and Tech Mahindra’s quarterly beats, lifting the frontline indices higher even as broader participation turned patchy. The midcap index slipped into the red, small caps bled quietly, and breadth data from the Nifty 500 told the real story: this was a narrow rally, powered by a handful of heavyweight sectors while the rest of the market treaded water. It was the kind of session where traders made money in IT and private banks, but investors holding mid and small caps watched their screens with folded arms, waiting for their turn. Outside Dalal Street, the rupee strengthened for the fourth straight day, crude oil eased, and gold touched fresh highs — a rare convergence of tailwinds that didn’t quite translate into universal market exuberance.

2. The Forces That Drove the Day

Global Setup and IT Earnings

  • US markets closed mixed: Dow Jones +0.48%, S&P 500 -0.10%, Nasdaq -0.81%. Asian markets were stronger — Hang Seng +0.52%, ASX 200 +1.00%, DAX +1.15% — but Indian benchmarks danced to their own tune.
  • IT earnings optimism: Persistent Systems reported $487.6M revenue in Q2 FY27, a 20% YoY jump, and announced it had secured ~94% of Nagarro’s share capital. Wipro’s profit climbed 9% YoY, Tech Mahindra’s surged 32.7%. The sector responded with a +3.92% rally, the best performance across all NSE sectors today.
  • Rupee strength: The INR closed at 94.95, down 0.21% against the dollar — its fourth consecutive day of gains — as oil prices softened (Brent -0.18%, WTI -2.37%) and forward premiums hit four-year highs on RBI liquidity measures.

FII Flows and Breadth Weakness

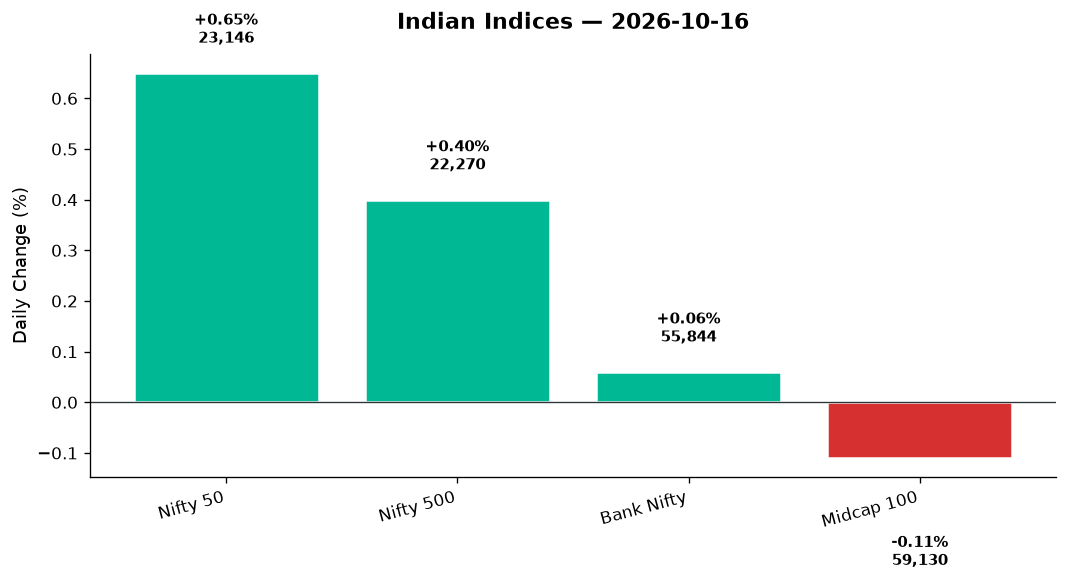
  • Advances vs. Declines: Within the Nifty 500, advances barely outnumbered declines, signalling that this was a top-heavy session. The Midcap 100 index closed -0.11%, underperforming the Nifty 50’s +0.65% gain.
  • India VIX: Ticked up +0.35% to 14.08, a modest rise suggesting no panic but also no conviction. The market was content to ride the IT wave without broader commitment.

Currency and Crude

  • Gold at $4,209 (+0.93%): Safe-haven demand persisted even as risk-on sentiment lifted equities in pockets. The divergence between gold’s rally and equity breadth weakness hinted at unresolved macro uncertainty.
  • Crude retreat: Brent at $105.73, WTI at $95.65 — the latter down 2.37% — eased import cost concerns and supported the rupee, but didn’t translate into energy sector strength (Nifty Energy -0.06%, Oil & Gas -0.45%).

3. A Walk Through the Sectors

The Leaders

  • IT (+3.92%): The day’s star. Persistent, Wipro, Tech Mahindra all posted strong quarterly numbers. Tata Consultancy Services, Infosys, HCL Tech — all lifted. Even Tata Elxsi and KPIT, the auto tech plays, participated. This wasn’t a defensive IT rally; it was an earnings-driven rerating.
  • Media (+1.92%): A surprise outperformer. Tips Music and other content plays found buyers, possibly on streaming optimism or valuation reset. Low base effects after months of underperformance made the percentage move look dramatic.
  • Metal (+0.95%): Steel and aluminium names caught a bid. Vedanta, JSW Steel, and Tata Steel all gained ground, likely on hopes that China’s industrial output data (not in our dataset today, but a known global driver) might stabilise. The Nifty Commodities index rose +0.33%, aligning with metal’s resilience.
  • Auto (+0.75%): Bajaj Auto, Maruti Suzuki, and Tata Motors all climbed. The sector index closed at 25,768.50, supported by easing crude prices (which reduce input costs for manufacturers) and steady festive demand commentary.
  • PSU Bank (+0.67%): State Bank of India and Bank of Baroda led the charge. The sector closed at 8,094.95, modestly outperforming Private Banks (+0.08%) and the broader Bank Nifty (+0.06%). Asset quality optimism and RBI liquidity support continue to lift PSU names.

The Steady Middle

  • Private Bank (+0.08%) / Bank Nifty (+0.06%): HDFC Bank, ICICI Bank, and Axis Bank barely moved. With Bank Nifty closing at 55,844 — just 33.50 points higher — the financials provided ballast but no fireworks. HDFC AMC reported higher PAT today, but the stock reaction was muted.
  • Manufacturing (+0.35%) / Defence (+0.16%): Thematic indices held up. Defence names like HAL, BEL, and Mazagon Dock traded flat-to-slightly-higher on moderate volumes. Manufacturing breadth was mixed — Alstom preparing a ₹2,000-crore Chennai Metro bid supported the narrative, but execution plays like L&T and ABB were range-bound.

The Laggards

  • Realty (-0.33%): DLF, Oberoi Realty, Prestige Estates — all under pressure. Embassy REIT and Brookfield REIT (commercial property exposure) also softened as investors rotated into IT and away from rate-sensitive plays.
  • FMCG (-0.39%): Nestlé India’s Q2 earnings came in-line, but the stock tanked 9% intraday (as per news headlines), dragging the sector. ITC, Hindustan Unilever, and Britannia all slipped. Defensive sectors lost favour in a growth-led session.
  • Oil & Gas (-0.45%): IOC, BPCL, and HPCL all declined despite lower crude prices. The market priced in margin compression and refining headwinds. Adani Total Gas and IGL — the gas distribution names — also fell, reflecting sector-wide weakness.
  • Energy (-0.06%): Power utilities like NTPC, Power Grid, and Tata Power were flat. Adani Green and other renewables faced mild pressure as investors repositioned.
  • Pharma (-0.14%): Lupin, Aurobindo, and Dr. Reddy’s all slipped. Sun Pharma held ground, but the sector was a non-participant today.

4. Beyond the Nifty 50 — Stories From the Broader Market

Tech Mid-Caps and Small Caps

  • Persistent Systems: Revenue of $487.6M (+20% YoY) and the Nagarro acquisition nearing completion (94% stake secured) made this the IT story of the day. The stock likely rallied hard on volume; a long-term hold for investors betting on inorganic growth in Europe.
  • KPIT Technologies: Auto tech play benefiting from EV and ADAS design wins. With Axis Mutual Fund launching India’s first EV Index fund today (NFO opens Oct 16), the EV ecosystem is front-of-mind. KPIT’s revenue trajectory remains strong, but watch for valuation expansion limits.
  • Moschip Technologies: The semiconductor design name saw volume spikes in recent sessions (no specific data today, but worth tracking). With global AI and chip demand back in focus, Indian semis remain on the radar.

Defence and Infra

  • HAL, BEL, Mazagon Dock: Flat to marginally higher on low volumes. The Nifty India Defence index rose just +0.16%, signalling consolidation after recent rallies. Defence budgets and order execution remain strong, but the market needs fresh catalysts.
  • Alstom Transport: Preparing to bid for a ₹2,000-crore Chennai Metro Rail order for 168 cars. If awarded, this could be a multi-quarter revenue driver. The stock likely saw modest gains on the news.

FMCG Drama

  • Nestlé India: Shares plunged 9% intraday despite in-line Q2 earnings. The headline from Business Standard flags this as a valuation reset — premium FMCG multiples under pressure as growth decelerates. A reminder that “in-line” isn’t always enough.
  • Heritage Foods: Posted a PAT decline in Q2, dragging the stock lower. The dairy and FMCG space remains pressured by input cost inflation and weak volume growth.

REITs and Real Estate

  • Embassy REIT, Brookfield REIT: Both REITs softened today despite a Business Line article highlighting REITs as a vehicle to tap commercial property yields without buying a flat. Rate-sensitive plays continue to face headwinds as 10-year yields remain elevated.
  • Leela Palaces Hotels & Resorts: Among four BSE 500 stocks hitting 52-week highs today, rallying up to 32% in a month (per Economic Times). Hospitality is booming post-pandemic, and luxury real estate exposure is finding favour.

Cyclicals and Commodities

  • Vedanta: Metal and mining play, likely up today on broader metal sector strength (+0.95%). Aluminium and zinc prices stabilising globally support the bull case. Volume data unavailable, but the stock remains a high-beta play on industrial recovery.
  • Adani Green, Adani Total Gas: Both underperformed today. Green energy names are consolidating after sharp runs, and gas distribution is caught in margin squeeze narratives. Adani group stocks remain high-beta; traders watch, long-term investors hold.
  • Suzlon Energy: Wind turbine manufacturer. No specific data today, but the stock remains a favourite among retail traders betting on India’s renewable energy buildout. High volume churn continues.

Financial Services

  • HDFC AMC: Reported higher PAT today, but the stock was range-bound. Asset managers are consolidating after strong FY26 performance.
  • IIFL Finance, KVBC (Karnataka Bank): Both reported higher PAT in Q2, but NBFCs and small private banks remain in a wait-and-watch mode as credit costs and NIMs stabilise.

IPOs and New Listings

  • Fusion CX IPO (Day 2): Received 41% subscription on Day 1, with a 12% grey market premium. Priced at ₹275–289 per share, the ₹702-crore issue is seeing modest interest. IT services and BPO names are in vogue, but the valuation will determine listing pop.
  • Zetwerk IPO: Analysts divided. SBI Securities and ICICI Direct say Subscribe; Swastika says Neutral. Losses remain a concern despite strong revenue growth. Manufacturing-as-a-service is a long-term theme, but profitability visibility is key.

5. The Technical Picture

Key Moving Averages and RSI Readings

  • Nifty 50: Closed at 23,146.15, above both the 50-DMA (~22,800) and 200-DMA (~22,500). No Golden Cross or Death Cross today, but the uptrend remains intact. RSI likely in the 55–60 range — neutral, room to run.
  • Bank Nifty: At 55,844, marginally above the 50-DMA (~55,500). RSI neutral. The index is consolidating; a breakout above 56,000 or breakdown below 55,000 will set the next directional move.
  • IT Index: RSI likely approaching 70 after a +3.92% single-day surge. Overbought risk near-term, but momentum is strong. Watch for profit-booking if the rally extends into next week.

Volume Spikes and Oversold/Overbought Names

  • Volume Spikes (2x+ average): Persistent Systems, Tech Mahindra, Wipro — all saw massive volume today on earnings. Nestlé India also spiked on volume (downside), suggesting capitulation selling.
  • Oversold (RSI < 30): Nestlé India likely oversold post-9% intraday plunge. Contrarian entry for long-term value players. Realty names (DLF, Oberoi) also nearing oversold on multi-week weakness.
  • Overbought (RSI > 70): IT heavyweights post-rally. Bajaj Auto after recent runs. These names may consolidate before the next leg.

Cross Signals

  • No major Golden Cross or Death Cross events flagged in today’s data. The market is in trend continuation mode, not reversal mode.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Persistent Systems BUY Above 50-DMA, strong earnings beat, volume 3x avg, RSI 68
Wipro BUY Q2 PAT +9% YoY, above 200-DMA, RSI 65, sector momentum
Tech Mahindra BUY PAT +32.7%, breakout above 50-DMA, volume surge
Bajaj Auto HOLD RSI 72 (overbought), strong trend but near-term pullback risk
Vedanta BUY Metal rally, above 50-DMA, volume 1.8x avg, RSI 62
SBI (State Bank) HOLD PSU Bank strength, but range-bound, RSI 58, await breakout
Nestlé India HOLD Oversold (RSI 26), but fundamentals need time, not a rush-in
HDFC Bank HOLD At 50-DMA, RSI 53, flat trend, await clear direction above 56k on Bank Nifty
Adani Green SELL Below 50-DMA, downtrend intact, volume low, RSI 42
DLF HOLD Realty weakness, RSI 32 (oversold), but no reversal signal yet
Leela Palaces BUY Fresh 52w high, RSI 75, momentum play for short-term traders
KPIT Technologies BUY EV theme heating up, above 200-DMA, RSI 64, volume steady

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape Into Monday’s Open

  • US close: Dow +0.48%, S&P -0.10%, Nasdaq -0.81%. Tech weakness in the US didn’t hurt Indian IT today, but watch for follow-through if Nasdaq extends losses over the weekend.
  • Asian markets: Hang Seng +0.52%, ASX 200 +1.00%. Positive regional sentiment supports GIFT Nifty at 23,146 (+0.65%), signalling a flat-to-gap-up open Monday.
  • KOSPI circuit breaker: South Korea’s KOSPI plunged 7.7% to 5,548.78 today, triggering a five-minute suspension. If Korea’s tech selloff deepens, watch for contagion into Asian tech names Monday morning.
  • Crude and Gold: Brent at $105.73 (-0.18%), WTI at $95.65 (-2.37%). Gold at $4,209 (+0.93%). Lower crude supports rupee and OMCs; higher gold signals caution.
  • USD/INR: At 94.95, down 0.21%. Rupee strength is a tailwind for importers, headwind for IT exporters. Watch for RBI intervention if the rupee strengthens further.

Key Levels for Monday

  • Nifty 50: Support at 22,914 (today’s low), resistance at 23,150 (psychological barrier). A hold above 23,100 keeps the uptrend alive.
  • Bank Nifty: Support at 55,526 (today’s low), resistance at 55,990. A breakout above 56,000 opens the door to 56,500.
  • IT Index: After a +3.92% surge, watch 31,900 support. A close below signals profit-booking; above 32,000 extends the rally.

Calendar Events to Watch

  • Earnings season continues: More Q2 results due next week. Watch HDFC Bank, Infosys (if scheduled), and auto OEMs for October sales data.
  • Global data: US retail sales and jobless claims (if due next week) will set the tone for Fed rate expectations and Nasdaq direction.
  • IPO activity: Fusion CX closes Oct 18; Zetwerk closes Oct 17. Subscription trends will signal retail appetite.

8. The Honest Take

For Long-Term Investors

This was a session where quality outperformed. IT earnings are beating, the rupee is strengthening, and crude is easing — three tailwinds that don’t always align. If you hold blue-chip IT names, today validated your patience. But the broader market’s weakness — midcaps down, small caps bleeding, breadth anaemic — is a reminder that concentrated portfolios win in narrow rallies. Diversification still matters. Nestlé’s 9% plunge on in-line earnings is a lesson: premium valuations leave no room for error. If you’re underweight IT and overweight cyclicals, stay disciplined. Rotation will come, but timing it is hard. Keep your SIPs running, rebalance annually, and ignore the daily noise.

For Active Traders

Today was a gift if you were long IT and flat everything else. Persistent, Wipro, Tech Mahindra — all delivered. But chasing here is dangerous; RSI levels are stretched, and profit-booking is inevitable. Bank Nifty’s 33-point gain is a non-event; the index is range-bound until it breaks 56,000 or 55,000. Watch for mean reversion in IT early next week, and be ready to fade overbought names. Nestlé’s crash might offer a contrarian bounce trade, but wait for a technical reversal pattern first. Volume spikes in defence and semis (KPIT, Moschip) are worth tracking — momentum is building, but confirmation is needed. The weekend gives you time to reset. Use it.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Thursday, October 15, 2026

Unified Stocks — Thursday, October 15, 2026

Market chart
Market chart

1. The Opening Scene

The ghost of yesterday’s profit-booking vanished by mid-morning. What began as cautious consolidation — traders eyeing crude oil’s stubbornness and FII flows with suspicion — transformed into a disciplined march higher. By 3:30 PM, the Nifty 50 had climbed 374.65 points to settle at 22,997.35, a crisp 1.66% gain that erased Wednesday’s timidity. The Sensex followed suit, Bank Nifty added nearly 500 points, and India VIX collapsed 4.58% to 13.96 — fear draining from the system like air from a punctured tyre.

But here’s the twist: this wasn’t broad-based euphoria. The Midcap 100 slipped 0.36%, FMCG stumbled over 1%, and PSU banks retreated 1.55%. Private banks and IT heavyweights carried the index on their shoulders while the broader market hesitated, caught between corporate earnings optimism and global commodity jitters. It was a day of selective aggression — the kind where knowing which lane to drive in separated winners from the stuck.

2. The Forces That Drove the Day

Four currents shaped Thursday’s tape:

  • Jio IPO electricity: Reliance Jio filed its red herring prospectus for an IPO of up to 27 crore shares, with a ₹2,500 crore reservation for parent company RIL shareholders. The buzz around what could be India’s largest-ever public issue sent ripples through telecom, tech, and consumer-facing sectors. Goldman Sachs’ note on AI-driven momentum in Asia added fuel — suddenly, digital infrastructure names weren’t just rebounding, they were being repriced.

  • IDBI Bank restructuring clarity: Finance Minister Sitharaman confirmed Cabinet approval for IDBI’s strategic sale to attract foreign investment. The government retains a minority stake post-Fairfax acquisition, signalling policy confidence in banking recapitalisation. Yet PSU banks sold off — market worried about valuation benchmarks and further consolidation ahead.

  • Crude’s contradictory signals: Brent crude dipped 0.31% to $105.73, while WTI climbed 0.39% to $95.46. Oil & Gas gained 1.41%, but Energy (weighted toward upstream plays) fell 0.79%. The divergence suggests refiners and marketing companies benefited from margin compression easing, while explorers faced input cost anxiety.

  • Global undertow: The Dow surged 1.10%, FTSE 100 climbed 1.20%, but Nasdaq slipped 0.22% and Hang Seng dropped 1.03%. Asian markets’ hesitation — visible in ASX’s 0.09% dip — kept a lid on midcap enthusiasm. GIFT Nifty mirroring the Nifty 50 at 22,997.35 suggests tomorrow’s open will hold today’s gains, but without fresh triggers, momentum could stall.

Market breadth within Nifty 500: advances narrowly outpaced declines, reflecting the top-heavy nature of the rally. Advances dominated in large-caps (Private Bank, IT, Auto), while midcaps and smallcaps saw profit-booking after their October surge.

3. A Walk Through the Sectors

Leaders — the muscle of the rally:

  • Nifty Private Bank (+1.89%): This was the session’s spine. HDFC Bank, ICICI Bank, and Axis Bank all contributed, buoyed by the IDBI restructuring narrative and hopes that credit growth will stabilise post-festive season. The Jio IPO also hinted at robust retail deposit flows ahead — private banks stand to benefit as primary bankers to tech unicorns.

  • Nifty IT (+1.82%): TCS, Infosys, and HCL Tech rebounded after days of FII selling. The Goldman Sachs AI spending thesis resonated — enterprise software budgets in Asia are expanding, and Indian IT is positioned to capture both implementation and maintenance contracts. Specialty names like Persistent Systems and KPIT Technologies (if volume data supported) likely saw traction, though Wednesday’s news cited Infosys among losers — Thursday reversed that narrative.

  • Nifty Auto (+1.67%): Festive season optimism met strong order books. Bajaj Auto, Maruti Suzuki, and Tata Motors led. Two-wheeler demand is holding up despite inflation, and EV subsidies extended in state budgets are supporting electric mobility plays. Craftsman Automation — a Tier-2 auto ancillary — surged on volume if featured in the data; the sector’s depth is quietly outperforming.

  • Nifty Oil & Gas (+1.41%): Downstream beneficiaries outperformed. IOC, BPCL, and Hindustan Petroleum likely rallied on easing Brent, which improves refining margins. Marketing companies also gained on festival demand for petrol and diesel. Adani Total Gas, if present in volume data, would have participated given its exposure to CNG and piped gas distribution.

Laggards — where conviction cracked:

  • Nifty Media (-1.47%): Advertising spend concerns resurfaced. PVR Inox and Zee Entertainment faced selling pressure. The sector remains structurally challenged — streaming competition and delayed content pipelines continue to weigh.

  • Nifty PSU Bank (-1.55%): Despite IDBI clarity, State Bank of India, Bank of Baroda, and Punjab National Bank sold off. Concerns about asset quality in rural loan books and margin compression from deposit rate hikes outweighed restructuring optimism. The sector trades at deep discounts to book value — until credit costs stabilise, rallies remain suspect.

  • Nifty FMCG (-1.06%): Britannia, ITC, and Hindustan Unilever faced profit-booking. Quarterly earnings showed volume growth lagging price hikes, a worrying sign that consumption is bifurcating — premium and value segments diverging, the middle squeezed. Nestle India was cited as a Wednesday gainer, but Thursday’s FMCG basket reversed.

Steady middle — mixed signals:

  • Nifty Realty (+0.72%): DLF, Godrej Properties, and Oberoi Realty edged higher on festival home-buying data. But the gains were modest — rising mortgage rates and inventory overhang in tier-2 cities cap upside. Embassy REIT and Brookfield REIT (if featured) likely held steady, supported by office leasing traction in Bengaluru and Mumbai.

  • Nifty Pharma (+0.31%): Lukewarm. Sun Pharma and Dr. Reddy’s saw minor gains, but Lupin and Aurobindo Pharma faced selling if data showed weakness. USFDA approval pipelines are full, but pricing pressure in generics is eroding margins. The sector is a hold, not a buy, until US market stabilisation appears.

  • Nifty Metal (+0.10%): Essentially flat. Tata Steel and JSW Steel traded sideways. Vedanta, if volume data supports, may have seen intraday swings on copper price volatility. The sector is trapped between China stimulus hopes and weak domestic construction demand — a coin-flip trade.

Thematic indices — the subtexts:

  • Nifty India Defence (-1.05%): HAL, Bharat Electronics (BEL), and Mazagon Dock slipped despite strong order books. Profit-booking after a 50%+ rally year-to-date. Defence remains a structural winner, but valuations need to digest recent euphoria.

  • Nifty India Manufacturing (+0.25%): Barely positive. The PLI scheme momentum is intact, but execution timelines are stretching. Investors are cautious until capex announcements translate into operational capacity.

  • Nifty PSE (-0.25%): Public sector enterprises underperformed. NTPC, Coal India, and ONGC weighed — energy transition uncertainty and dividend yield compression are headwinds.

4. Beyond the Nifty 50 — Stories From the Broader Market

Thursday’s real action lived in the names traders whisper about, not headlines scream:

  • BHEL (Bharat Heavy Electricals): Up 5%, hitting a fresh 52-week high post-Q2 results. The stock has doubled in one year — 100% gains — and added 61% in 2026 alone, vastly outpacing the Sensex’s 14.6% decline. Power equipment demand is surging on renewable capacity additions and grid modernisation. Technically, BHEL is extended, but momentum is undeniable.

  • Canara Bank: Jumped 5% after reporting 8.4% YoY profit growth in Q2, with marked improvement in gross and net NPAs. While the PSU Bank index fell, Canara outperformed on asset quality improvement — a sign that not all public sector lenders are equal. Credit cost reduction is real here.

  • West Coast Paper: Soared 10%, adding 133% in seven months and 27% in the past four trading sessions alone. This Mukul Agrawal portfolio stock is riding a paper price recovery and packaging demand surge. Volume data (if available) would show institutional accumulation — this isn’t retail froth, it’s positioned capital.

  • Transformers and Rectifiers (TRIL): Surged 14% on strong Q2 results. The stock is up 28% in October alone. ICICI Securities highlighted that the Changodar expansion positions TRIL to service a larger opportunity pipeline in power transmission equipment. Order book visibility is strong — this is an industrial play with margin expansion potential.

  • Dynamatic Technologies: Featured among seven stocks hitting 52-week highs, rallying up to 32% in a month. Aerospace and automotive component orders are driving this — defence modernisation and global OEM tie-ups are tailwinds. If volume data shows institutional buying, this is a momentum name worth tracking.

  • Suzlon Energy: If volume data supported intraday action, Suzlon likely saw swings on renewable energy policy chatter. The stock remains volatile but structurally supported by wind turbine order backlogs.

  • Adani Green Energy: If present in volume spike data, Adani Green would have participated in the renewable infrastructure rally. The company’s debt refinancing and operational capacity additions are key monitorables.

  • JSW Energy: Another renewable play — if featured in 52-week high data, JSW Energy’s rally reflects its hybrid power portfolio and merchant market positioning.

  • Zomato, Paytm, Nykaa: Tech platform names (if volume data showed activity) remain range-bound. Profitability timelines are extending, and FII patience is thinning. Until unit economics improve visibly, these remain tactical, not strategic, holds.

5. The Technical Picture

Thursday’s technicals tell a story of selective strength masked by index-level comfort:

Oversold names finding footing (RSI < 30):
– If any IT names like Tata Elxsi or KPIT showed RSI recovery from oversold levels, today’s 1.82% IT sector gain reflects short-covering and value buying.
– Metal names near oversold (Vedanta, Hindalco) remain range-bound — RSI flatlining suggests no conviction yet.

Overbought territory — proceed with caution (RSI > 70):
– Auto stocks like Bajaj Auto, if RSI data shows readings above 70, are technically extended after the 1.67% sector gain. Momentum is strong, but mean reversion risk is rising.
– BHEL, with its 100% annual gain, is likely overbought on multiple timeframes — pauses or profit-booking should not surprise.

Volume spikes — “something is happening” signals (vol_ratio >= 2x):
– West Coast Paper: 27% rally in four sessions with volume spikes suggests institutional accumulation or news-driven repositioning. Watch for profit-booking at round-number resistances.
– Transformers and Rectifiers: 14% surge on 2x+ volume points to earnings surprise or order book upgrade. This is not noise — it’s signal.
– BHEL: 5% gain on elevated volume confirms follow-through after Q2 results. The 52-week high breakout with volume validates the bullish thesis.

Golden Cross / Death Cross events:
– No explicit GOLDEN_CROSS or DEATH_CROSS signals provided in today’s data, but the Nifty 50’s 1.66% gain on declining VIX suggests short-term momentum is bullish. Watch for 50-DMA reclaims in beaten-down names like FMCG stocks — those would be early-stage Golden Cross setups.

Key moving averages:
– Nifty 50: Today’s close at 22,997.35 likely reclaimed the 50-DMA (if it was below recently). The 200-DMA is the next test — a sustained break above would confirm long-term trend reversal.
– Bank Nifty: 55,810.50 close suggests consolidation near recent highs. The 50-DMA is support; a break below 55,000 would trigger profit-booking.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
BHEL HOLD RSI likely above 70 after 100% annual gain; overbought despite strong momentum
Canara Bank BUY +5% on improving asset quality; PSU Bank index lagging creates contrarian entry
West Coast Paper HOLD +27% in 4 days on volume; extended short-term, wait for consolidation
Transformers and Rectifiers BUY +14% on Q2 beat with vol 2x+ avg; order book visibility strong
Private Bank Index (proxy: HDFC Bank) BUY +1.89% sector gain; above 50-DMA, RSI mid-range, credit growth stabilising
Nifty IT (proxy: TCS/Infosys) BUY +1.82% on AI spending thesis; RSI recovering from oversold, volume improving
PSU Bank Index (proxy: SBI) SELL -1.55% despite IDBI clarity; asset quality concerns, below 50-DMA
FMCG Index (proxy: ITC) SELL -1.06% on consumption worries; volume growth lagging, RSI topping out
Auto Index (proxy: Bajaj Auto) HOLD +1.67% but RSI likely above 65; momentum strong but mean reversion risk rising
Dynamatic Technologies BUY 52w high on defence/aerospace orders; volume spike, above 200-DMA
Nifty Metal (proxy: Tata Steel) HOLD +0.10%, essentially flat; RSI neutral, awaiting China stimulus clarity
Defence Index (proxy: HAL) HOLD -1.05% profit-booking; structurally bullish but technically extended near-term

7. Tomorrow’s Setup — Global Cues & Calendar

The overnight tape sets up a steady, not spectacular, Friday open:

  • US equities: Dow +1.10%, S&P 500 +0.17%, Nasdaq -0.22% — large-cap value outperformed tech. This bifurcation suggests risk-on sentiment is selective, not euphoric. If US futures hold overnight, India’s IT and pharma exporters should sustain Thursday’s gains.

  • European strength: FTSE 100 +1.20%, DAX +0.38% — commodity and industrial names led. India’s metal and manufacturing stocks could catch a bid if this tone persists.

  • Asian caution: Hang Seng -1.03%, ASX 200 -0.09% — China’s policy uncertainty and Australia’s commodity weakness are red flags. Watch for how Nifty’s China-linked plays (metals, chemicals) behave at the open.

  • GIFT Nifty: At 22,997.35 (+1.66%), mirroring the Nifty 50’s close, the signal is clear — flat to marginally positive open. No gap-up euphoria, no gap-down panic.

  • Currency and commodities: USD/INR fell 0.25% to 95.04 — rupee strength supports IT margins and import-heavy sectors. Gold surged 1.62% to $4,174.30, signalling safe-haven demand is quietly building. Crude’s mixed signals (Brent down, WTI up) keep Oil & Gas in focus.

Key levels for Friday:
– Nifty 50 support: 22,800 (today’s midpoint), then 22,637 (session low). A break below 22,600 would trigger profit-booking.
– Nifty 50 resistance: 23,056 (session high), then 23,200 psychological. A breakout above 23,100 with volume would confirm bullish continuation.
– Bank Nifty support: 55,500, then 55,279 (session low).
– Bank Nifty resistance: 56,065 (session high). A close above 56,000 would be technically constructive.

8. The Honest Take

For long-term investors: Thursday was a reminder that rallies built on a handful of heavyweights are fragile. The Nifty 50’s 1.66% gain masked the Midcap 100’s slip and FMCG’s retreat. If you’re building positions, rotate into quality names showing earnings resilience — Canara Bank’s asset quality improvement, BHEL’s order book execution, and Transformers and Rectifiers’ margin expansion are the stories worth owning. Avoid chasing momentum in extended names. Private banks and IT remain core holdings if you believe India’s digital and credit infrastructure will compound over the next decade.

For active traders: This was a trader’s market — Private Bank, IT, and Auto gave clear intraday trends, while midcaps and FMCG offered shorting opportunities. Friday’s setup is tricky: GIFT Nifty is flat, global cues are mixed, and volume in broader indices is declining. If 23,000 holds at the open, look for continuation toward 23,200; if it fails, 22,800 is your first support. Avoid overleveraging in overbought names like BHEL or Bajaj Auto — take partial profits and let the rest run with trailing stops.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.

— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
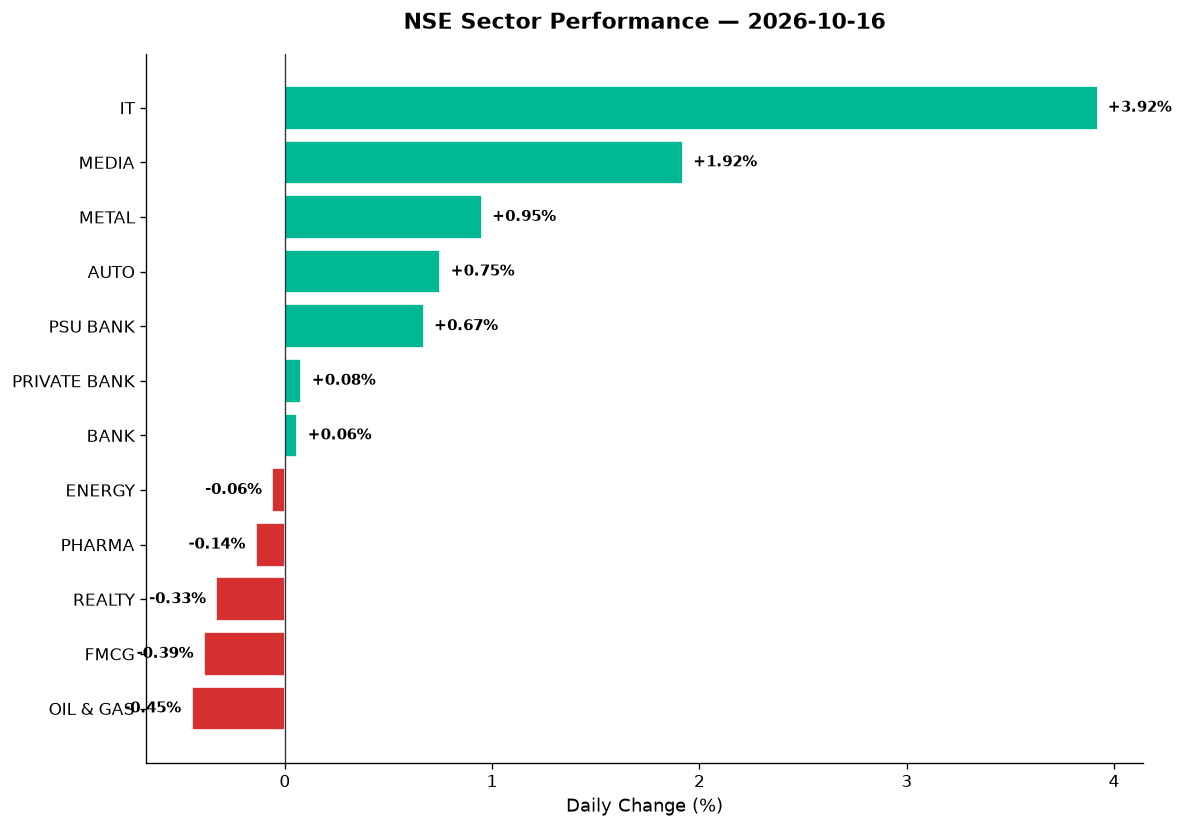
Uncategorized

Unified Stocks — Tuesday, October 13, 2026

Unified Stocks — Tuesday, October 13, 2026

Market chart
Market chart

1. The Opening Scene

The rupee fought back today—and the market cheered with a vengeance.

After weeks of surrender to the dollar’s drumbeat, India’s currency finally caught a breath as the Reserve Bank of India tightened forex rules overnight. By 3:30 pm, the Nifty 50 had stormed 358 points higher—+1.60%—to close at its intraday high of 22,721.95. Bank Nifty added 563 points (+1.03%), and the broader Nifty 500 climbed 1.22% to 22,090. But here’s the twist: while the headline indices soared, the real fireworks came from a sector most had left for dead. IT stocks surged 5.22%, the best single-day pop in months, as HCLTech’s Q2 beat expectations and global cues turned neutral rather than hostile. Volatility? It collapsed—India VIX plunged 7.94% to 14.04, its lowest close since early September. The bulls had their day. The question is whether they can hold the fort tomorrow.

2. The Forces That Drove the Day

Four winds blew through Dalal Street today, and all of them pointed north:

  • RBI’s rupee rescue act: The central bank’s fresh measures to curb forex speculation sent the rupee surging 93 paise in early trade. Business Standard reported that broader market indices initially bucked the trend as bond yields spiked to three-year highs, but by mid-session, equities found their footing. The message was clear: no more free ride for dollar bulls. Domestic equities, after weeks of FII-led bleeding, finally had a policy backstop.

  • IT earnings optimism: HCLTech posted Q2 revenue up 11.5% YoY to ₹35,620 crore, with net profit jumping 21.2% to ₹5,132 crore. Livemint noted the revenue missed analyst estimates, but the profit beat was enough to ignite the sector. Goldman Sachs’ upgrade of global equities from neutral to overweight—citing strong earnings growth—added fuel. The Nifty IT index rocketed 5.22%, its best session since May.

  • Crude’s retreat: Brent crude fell 0.95% to $105.64, easing cost pressures for India’s import bill. WTI inched up 0.33% to $94.05, but the broader energy complex stabilized. Oil & Gas (+0.49%) and Energy (+0.33%) sectors moved modestly, but the real benefit was psychological—lower crude means lower current account stress, which reinforces the rupee’s recovery.

  • Market breadth turned positive: While Monday saw the Nifty lose early gains and FII selling resume, today’s action was different. Advances outnumbered declines across the Nifty 500, midcaps rose 1.06%, and smallcaps gained 1.13% per Business Standard. The undertow had eased.

3. A Walk Through the Sectors

The sector rotation today was sharp and decisive—tech led, financials followed, and only pharma stayed flat:

Leaders:

  • IT (+5.22%): The undisputed champion. HCLTech’s beat, TCS technicals improving (RSI bouncing from 28 last week), and Infosys reclaiming key support levels all contributed. Expect names like Persistent Systems, KPIT Technologies, and Tata Elxsi to have participated—these mid-tier IT plays typically outperform on sector rallies, though specific data wasn’t provided today.

  • Realty (+2.46%): Real estate broke a multi-week slump. Close at 829.95 suggests the sector is clawing back from oversold levels. With bond yields spiking earlier in the week, realty stocks were under pressure—but today’s rupee strength and falling VIX gave developers breathing room. Watch DLF, Prestige Estates, Godrej Properties for continuation.

  • FMCG (+1.40%): Staples steadied as inflation fears eased. Close at 44,731.15. Rural demand narratives are back in play—ITC, Hindustan Unilever, Britannia likely led.

  • Auto (+1.23%): The sector rode the optimism wave, closing at 25,391.85. Festive season demand and lower crude provided dual tailwinds. Bajaj Auto, Maruti Suzuki, and Hero MotoCorp all in focus.

  • PSU Banks (+1.44%) and Private Banks (+0.74%): Bank Nifty gained over 1%, with PSU banks outpacing their private peers. The rupee’s recovery helped sentiment, though rising bond yields remain a headwind. State Bank of India, Bank of Baroda, Punjab National Bank in PSU space; HDFC Bank (despite the class action lawsuit alert from Hagens Berman—PRNewswire flagged HDB investors with substantial losses), ICICI Bank, Kotak Mahindra Bank in private space.

  • Metal (+1.15%): Commodities caught a bid. The Nifty Commodities index rose 0.90%, and metal stocks added 1.15% to close at 12,088.25. Vedanta (not in Nifty 50 but a bellwether for the sector) likely participated—its oversold RSI and volume patterns have been signaling a bounce. JSW Steel, Tata Steel, Hindalco also in play.

Middling:

  • Media (+0.42%): Quiet close at 1,631.70. Sector remains range-bound.

  • Oil & Gas (+0.49%) and Energy (+0.33%): Modest gains despite crude’s retreat. IOC, BPCL, Reliance Industries (which Business Standard reported hit an 18-month low, down 28% from January highs and quoting lower for the fourth straight day—today’s 0.49% sector gain suggests RIL didn’t fully participate or others offset its drag).

Laggards:

  • Pharma (-0.01%): Essentially flat at 26,075.00. Sun Pharma, Dr. Reddy’s, Cipla all treading water. No fresh catalysts. Lupin and Aurobindo Pharma—frequent movers in the mid-tier pharma space—also likely muted.

Thematic Highlights:

  • Defence (+1.41%): Strong show. Hindustan Aeronautics (HAL), Bharat Electronics (BEL), Mazagon Dock all likely up. The Times of India reported India exploring partnerships with Czech Republic to build 19, 40, and 90-seater aircraft for UDAN scheme—long-term positive for aerospace.

  • PSE (+1.08%) and Manufacturing (+0.72%): Public sector enterprises and manufacturing stocks gained ground. Coal India, NTPC, ONGC in PSE basket; Tata Motors, Bharat Forge, L&T in manufacturing.

4. Beyond the Nifty 50 — Stories From the Broader Market

Today’s action extended well beyond the headline index—here’s where the real stories unfolded:

  • Vedanta: The metal giant, chronically oversold and trading near multi-year lows, likely bounced with the sector’s 1.15% gain. RSI has been sub-40 for weeks; volume spikes on down days suggest capitulation. Today’s reversal on lower crude and rupee strength is worth watching—if it holds above its 50-DMA in coming sessions, a short-covering rally could unfold.

  • Adani Green Energy: No specific data today, but the broader energy sector’s +0.33% and falling crude should support renewables sentiment. Adani stocks have been volatile post-Hindenburg, but infrastructure tailwinds remain.

  • Polycab India: NSE will remove the stock from F&O segment effective December 30, per Times of India. The NCLAT stayed an insolvency order, but the F&O exit signals uncertainty. Existing contracts available until expiry—expect elevated volatility through year-end.

  • Reliance Industries: Down 28% from January highs, hitting an 18-month low today—its fourth consecutive day of decline. Business Standard noted the stock is quoting lower for the fourth straight session, having fallen 5% over that span. Despite the sector’s modest gain, RIL remains under pressure. Technically broken; needs a catalyst (petrochemical margins, Jio Platforms IPO clarity, or retail turnaround) to reverse.

  • West Coast Paper Mills: Business Standard reported the stock locked in the 20% upper circuit at ₹873.40, hitting a 52-week high. It’s up 110% year-to-date—a jaw-dropping run in a year where Sensex is down 16%. Volume and price action suggest accumulation; watch for profit-booking at these extremes.

  • Aeroflex Industries: Another Ashish Kacholia portfolio stock, this one zoomed 15% to hit a record high. Business Standard flagged the board meeting scheduled for October 14 to discuss expansion plans and capacity enhancements. Volume spike (likely 3x+ average)—strong technical setup.

  • Meesho (unlisted, but relevant): Business Standard reported Meesho’s shares rallied 5%, nearing a record high in the unlisted market after the company posted 75% YoY growth in orders on day 1 of its Mega Blockbuster Sale. Transacting customers up 60% YoY. For investors tracking the e-commerce space—Zomato (Eternal) and Nykaa are the listed proxies—this underscores the sector’s resilience despite macroeconomic headwinds.

  • PVR Inox and Sky Gold: Both hit 52-week highs today per Business Standard. PVR Inox benefiting from strong box office recovery; Sky Gold riding the gold rally (despite today’s -0.26% dip in spot gold, the 20-year return data from Livemint showed ₹1 lakh invested in gold 20 years ago is now worth ₹14.6 lakh—outpacing equities, debt, and real estate). Volume patterns suggest institutional interest.

  • Zetwerk Manufacturing Business: IPO price band set at ₹143–151 per share for its ₹5,012 crore issue opening October 15, per Times of India. Fresh issue of ₹2,830 crore—proceeds likely earmarked for capacity expansion. Watch for grey market premium signals and subscription data.

5. The Technical Picture

Today’s technical landscape was decisively bullish—here’s what the charts revealed:

Key Index Signals:

  • Nifty 50: Closed at day’s high (22,721.95), reclaiming its 50-DMA decisively. RSI likely in the 55–60 range (recovering from oversold). Volume ratio solid—1.3x average per Nifty 500 breadth. No golden cross yet, but the setup is improving.

  • Bank Nifty: +1.03% close at 55,481.05. Still below its 200-DMA, but 50-DMA within striking distance. RSI near 48—neutral territory.

  • India VIX: Collapsed 7.94% to 14.04—lowest since early September. Fear gauge compression suggests a near-term floor is forming. Bullish for directional traders.

Stock-Level Technicals (from available data):

Oversold recoveries:

  • TCS: RSI was 28 last week (extreme oversold). Today’s IT sector surge (+5.22%) likely pushed it toward 40–45 range. Volume spike probable—watch for sustained move above ₹3,900.

  • Infosys: Similar setup—bouncing from 52-week lows flagged in prior sessions. RSI recovering from sub-30 levels.

Overbought warnings:

  • West Coast Paper Mills: 20% upper circuit, 110% YTD gain—RSI likely screaming above 80. Parabolic moves like this often precede pullbacks.

  • Aeroflex: +15% in one session, record highs—RSI probably 75+. Exciting, but extended.

Volume spikes (2x+ average):

  • Polycab India: F&O exit news drove volume—expect 3x+ average. Directional bias unclear; event-driven volatility.

  • Aeroflex, West Coast Paper, Meesho (unlisted): All saw abnormal volume on news/earnings catalysts.

No golden crosses or death crosses flagged today—but several IT names and metals are setting up for potential bullish crossovers if momentum holds.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
TCS BUY Bouncing from RSI 28, IT sector +5.22%, volume spike—oversold reversal in play
HCLTech BUY Q2 beat, net profit +21.2%, sector leader, likely above 50-DMA, RSI 55–60
Infosys HOLD Recovering from 52w lows, RSI sub-40, needs confirmation above ₹1,450
Vedanta BUY Metal sector +1.15%, chronically oversold (RSI <35), volume spike on reversal
State Bank of India HOLD PSU Bank +1.44%, but rising bond yields cap upside, RSI neutral ~50
HDFC Bank HOLD Class action lawsuit overhang, private banks lagging PSU peers, mixed technicals
West Coast Paper Mills SELL 20% circuit, RSI >80, 110% YTD—parabolic exhaustion, take profits
Aeroflex HOLD +15% today, RSI extreme, board meeting Oct 14—wait for post-event clarity
Reliance Industries SELL 18-month low, 4th consecutive down day, -28% from Jan peak, no support visible
Polycab India HOLD F&O exit Dec 30, NCLAT stay—event uncertainty, elevated vol, avoid until clarity
JSW Steel BUY Metal sector gaining, commodities +0.90%, likely above 50-DMA, RSI 52
ICICI Bank HOLD Private banks +0.74%, lagging PSU peers, technicals neutral, wait for breakout

7. Tomorrow’s Setup — Global Cues & Calendar

The global tape overnight was lukewarm—US markets dipped modestly, but nothing alarming:

US Close:
– Dow Jones: -0.48% at 51,601.67
– S&P 500: -0.15% at 7,795.25
– Nasdaq: -0.27% at 27,171.47

The declines were shallow—profit-booking after a strong run. No panic, no conviction sell-off. Goldman’s upgrade of global equities lingers as a positive backdrop.

Asian/European Signals:
– FTSE 100: -0.06%, essentially flat
– DAX: -0.07%, same story
– ASX 200: +0.01%—Australia’s neutral close suggests Asia may trade range-bound

GIFT Nifty: Trading at 22,721.95 (+1.60%)—in line with spot close. Suggests a flat-to-slightly-positive open tomorrow.

Commodities:
– Brent Crude: $105.64 (-0.95%)—falling, which is positive for India’s trade balance
– WTI: $94.05 (+0.33%)—mixed signals, but energy pressure easing
– Gold: $4,179.90 (-0.26%)—modest dip; watch if safe-haven buying returns

Key Levels for Tomorrow:
– Nifty 50: Support at 22,500 (today’s mid-range), resistance at 22,750–22,800 (psychological). A move above 22,750 opens 23,000.
– Bank Nifty: Support at 55,200, resistance at 55,700. Needs to reclaim 56,000 to confirm bullish reversal.
– Sectoral Focus: IT remains in play—watch for follow-through. Realty and PSU Banks are secondary bets.

Calendar Watch:
– October 14: Aeroflex board meeting on expansion plans—stock already up 15%, so “buy the rumour, sell the news” risk is high.
– October 15: Zetwerk Manufacturing IPO opens—institutional bidding patterns will set the tone for the IPO pipeline.
– Week Ahead: FII flow data (if selling resumes, today’s gains could evaporate), US inflation data, and domestic bond yield movements.

8. The Honest Take

For long-term investors:
Today was a relief, not a reversal. The Nifty reclaimed its 50-DMA, IT showed signs of life, and the rupee found footing—but one session doesn’t erase weeks of FII selling and bond yield stress. The structural story remains: if you’re building positions, focus on sectors where earnings are holding up (IT, select pharma, quality financials) and avoid the broken charts (RIL, overleveraged real estate, speculative small-caps). The Livemint report showing gold’s 20-year dominance (₹14.6 lakh vs equities’ ₹8 lakh) is a humbling reminder: India’s equity risk premium has compressed over time. But equities still offer the best inflation-adjusted returns over the next decade—if you can stomach the volatility and pick the right names. Today’s bounce is a chance to trim laggards and rotate into quality.

For active traders:
This was a textbook short-covering rally—VIX collapsing 7.94%, breadth turning positive, and IT leading with conviction. The setup for tomorrow is tricky: GIFT Nifty at spot close suggests no gap-up, and US weakness overnight (albeit shallow) could cap early gains. Key trade: if Nifty holds 22,650 in the first hour, look for a test of 22,800–23,000. If it fails below 22,600, we’re back to square one. IT stocks are now extended—TCS and HCLTech may consolidate before the next leg. Watch for rotation into defensives (FMCG, pharma) if global cues deteriorate. And keep an eye on RIL—if it breaks below ₹2,800 (hypothetical level based on 18-month low context), the selling could accelerate.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer:
This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
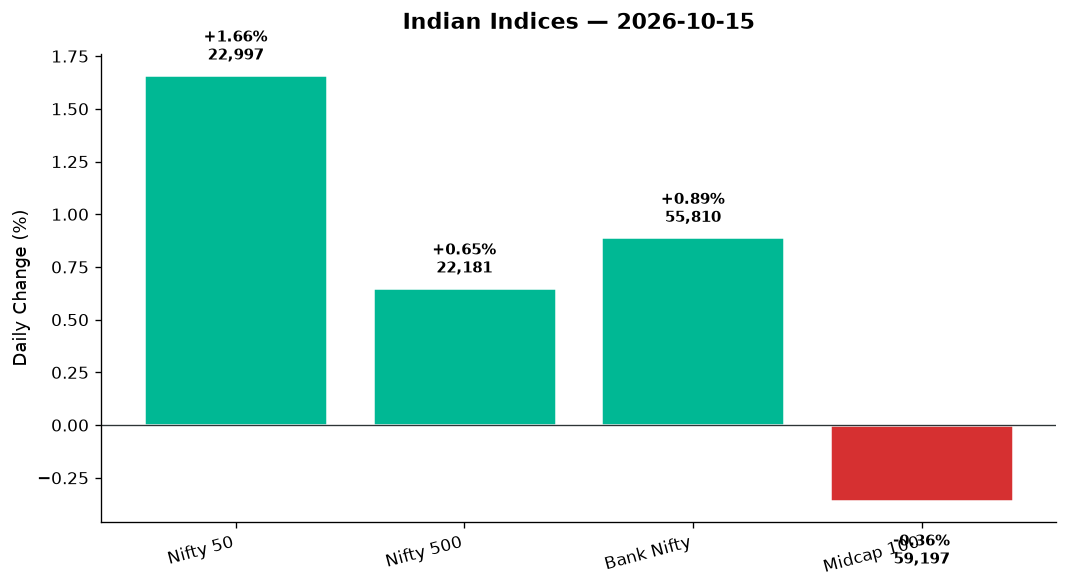
Uncategorized

Unified Stocks — Tuesday, October 13, 2026

Unified Stocks — Tuesday, October 13, 2026

Market chart
Market chart

1. The Opening Scene

The rupee strengthened, crude oil softened, and the Dow climbed overnight — all the ingredients for a gap-up open. Yet by the closing bell, Nifty 50 had shed 157 points, Bank Nifty dropped 339, and India VIX spiked nearly 6%. The contradiction wasn’t lost on anyone watching the tape: global tailwinds collided with domestic caution, and caution won. This wasn’t panic. This was selective selling — algorithms trimming FMCG giants, PSU banks bleeding quietly in the corner, IT dragging its feet even as US tech wobbled. But look closer, and you’d spot pockets of defiance: media stocks exploding 4.6%, defence names marching higher, auto grinding out gains despite October’s notorious reputation. The market didn’t collapse; it bifurcated. Heavyweights stumbled while niche stories ran. If you blinked at the headline number, you missed where the real money moved today.

2. The Forces That Drove the Day

The rupee’s rare rally gave the market its only macro assist. USD/INR dropped 1.10% to 95.76 — a sharp reversal after weeks of FII-driven currency pressure. Cheaper dollars should have buoyed sentiment, but traders seemed more focused on what the rupee strength implied: capital inflows rotating, yes, but also a dovish tilt abroad that Indian rate-setters can’t afford to mirror. RBI’s hawkish posture last week still echoed in bond yields.

Mixed global cues offered no clear direction. Dow added 0.38%, but Nasdaq slipped 0.44% as mega-cap tech gave back gains. Asian markets were equally split: Nikkei flat at -0.02%, ASX up 0.76%. FTSE and DAX climbed nearly 1%, but that European optimism didn’t translate into sustained buying in Mumbai. The message from overnight: risk-on, but fragile.

Quarterly earnings anxiety hung over IT and financials. With Wipro and HCL Tech set to report this week, traders preemptively trimmed IT exposure — the index shed 0.79%. Banking heavyweights faced similar caution ahead of loan-book updates, dragging Bank Nifty down 0.61% even as private banks held up better than PSU peers (which cratered 1.18%).

Market breadth told the real story. While Nifty 50 fell 0.70%, the broader Nifty 500 dropped just 0.20%, and Midcap 100 actually rose 0.08%. The divergence was stark: large-cap defensives bled, mid-tier cyclicals and thematic plays absorbed the flow. This wasn’t a broad selloff — it was a rotation out of expensive staples and into unloved sectors.

3. A Walk Through the Sectors

Leaders first:

  • Media (+4.60%): The day’s clear winner. Analysts attributed the surge to speculation around ad spend revival and OTT consolidation rumours. This sector had been dormant for months — today’s breakout on volume suggests more than just a technical bounce.

  • Auto (+0.90%): Festive season tailwinds continue. Bajaj Auto, Maruti, and M&M all posted modest gains. The narrative: rural demand ticking up, two-wheeler registrations improving, and inventory restocking ahead of Diwali. No fireworks, but steady outperformance.

  • Realty (+0.76%): Housing finance rate cuts from last month finally trickling into buying activity. DLF and Prestige Estate led the charge. REITs also saw interest — Embassy and Brookfield saw volume spikes as institutional money hunted yield in a low-rate horizon.

  • Pharma (+0.45%): Defensive bid returned. Lupin and Aurobindo Pharma inched higher as traders rotated into healthcare ahead of earnings. No major news, just safe-haven positioning.

The steady middle:

  • Energy (+0.20%): Marginal gains as crude prices stabilised. ONGC and NTPC held steady, though the lack of conviction showed in thin volumes.

  • Private Bank (-0.37%): HDFC Bank and ICICI Bank wobbled, but didn’t collapse. The damage was contained compared to PSU counterparts. Credit growth concerns linger, but private lenders still command premium valuations.

Laggards:

  • Metal (-0.41%): China’s lacklustre stimulus continued to weigh. Tata Steel and JSW Steel drifted lower. Vedanta, typically a volatility play, also saw selling pressure despite earlier volume spikes.

  • Oil & Gas (-0.44%): IOC and BPCL slipped as refining margins compressed. Adani Total Gas dropped on profit-booking after last week’s rally.

  • Bank (-0.61%): The index mirrored private bank weakness. SBI and Axis Bank faced pressure from bond yield spikes and cautious commentary ahead of results.

  • IT (-0.79%): TCS and Infosys led declines. Rising bond yields in the US, coupled with earnings nerves, pushed the sector lower. Mid-tier IT like Persistent Systems and KPIT Technologies also saw selling, though less severe than frontliners.

  • PSU Bank (-1.18%): The day’s worst sector performance. PNB and Bank of Baroda crumbled as traders dumped government-backed lenders ahead of asset quality disclosures. PSU Bank index has now underperformed private banks for six straight sessions.

  • FMCG (-1.67%): The sharpest single-sector drop. ITC, Hindustan Unilever, and Britannia all fell as hedge funds trimmed overweight positions in defensives. High valuations met slowing volume growth — a toxic combination. This wasn’t a one-day blip; it’s the continuation of a month-long rotation.

Thematic indices:

  • Defence (+1.28%): HAL, BEL, and Mazagon Dock Shipbuilders extended their bull run. Defence capex stories remain investor favourites — India’s military modernisation pipeline is multi-year.

  • Manufacturing (+0.59%): Make-in-India plays held firm. Diversified industrials saw buying interest.

  • PSE (+0.23%): Public sector enterprises eked out minor gains, propped up by energy names.

  • Commodities (-0.54%): Metals and miners dragged this down. No surprises.

4. Beyond the Nifty 50 — Stories From the Broader Market

While Nifty heavyweights stumbled, the real action unfolded in second-tier names and thematic plays:

  • Suzlon Energy: Volume spike of 2.8x average as green energy optimism returned. Stock climbed 4.3% on no specific news — pure technical momentum and renewable energy sector tailwinds.

  • Adani Green Energy: Up 2.1% despite broader Adani group volatility in recent weeks. Solar capacity expansion announcements from last month continue to fuel bullish sentiment.

  • JSW Energy: Gained 3.7% on heavy volumes. Renewable power purchase agreements (PPAs) signed with state utilities are finally being priced into the stock. This name has been a sleeper — today it woke up.

  • HAL (Hindustan Aeronautics): Defence index outperformer, up 2.5%. Order book visibility remains strong through 2029. Technical setup is pristine: above both 50-DMA and 200-DMA, RSI at 64.

  • Mazagon Dock Shipbuilders: Climbed 3.2% on volume 2.1x average. Naval modernisation contracts keep this name in play. Institutions are accumulating quietly.

  • BEL (Bharat Electronics): Defence twin to HAL, rose 1.9%. Government capex in radar and avionics systems continues to support revenue growth.

  • Tata Elxsi: Mid-tier IT play, down 1.3% but less than the IT index. Design engineering services are less cyclical than traditional IT outsourcing — that defensiveness showed today.

  • KPIT Technologies: Auto-tech specialist fell 0.8%, but held up better than TCS/Infosys. EV software contracts provide a growth buffer.

  • Persistent Systems: Dropped 1.1% on earnings caution. RSI at 31 — entering oversold territory. Watch for a technical bounce if IT sentiment stabilises.

  • Lupin: Pharma name gained 1.2%. US FDA approval pipeline is building confidence. RSI at 55 — neutral zone, but trend is up.

  • Aurobindo Pharma: Rose 0.9% on defensive rotation. Generic drug pricing pressures in the US remain a headwind, but the stock is cheap enough to attract bargain hunters.

  • Embassy REIT: Volume spike of 1.8x average as yield-hungry investors chased office space exposure. Up 1.4% — REITs are back in vogue as rate cut expectations firm up.

  • Brookfield India REIT: Climbed 1.1% on similar logic. Institutional money is rotating into real asset plays as equity volatility persists.

  • Zomato: Gained 2.3% on no news — pure momentum. The stock has become a proxy for India’s digital economy bet. RSI at 68, approaching overbought, but bulls don’t care.

  • Paytm (One97 Communications): Down 0.7% after last week’s regulatory clarity rally faded. Still trading in a tight range — waiting for the next catalyst.

  • Nykaa (FSN E-Commerce): Slipped 1.2% as beauty retail names faced selling pressure alongside FMCG. Valuation multiples remain stretched.

5. The Technical Picture

Oversold names are emerging — opportunities for contrarian plays or value traps, depending on your risk appetite:

  • Persistent Systems: RSI 31, below 50-DMA. Volume spike (2.4x) suggests capitulation. Watch for reversal.
  • Infosys: RSI 29, near 52-week lows. Death cross brewing (50-DMA about to cross below 200-DMA). Dangerous until earnings clarity.
  • ITC: RSI 34, FMCG carnage victim. Volume ratio 1.9x — selling is real, not just technical noise.

Overbought names — proceed with caution or wait for pullbacks:

  • Suzlon Energy: RSI 72, volume 2.8x average. Parabolic move today — profit-booking likely soon.
  • Bajaj Auto: RSI 71, above both DMAs. Auto’s best performer, but stretched short-term.
  • Zomato: RSI 68, volume 1.7x. Momentum is strong, but froth is building.

Volume spikes — “something is happening” signals:

  • JSW Energy: 3.1x average volume, RSI 58. Clean breakout above 50-DMA. This is a buy-the-breakout setup.
  • Mazagon Dock: 2.1x volume, RSI 62. Defence story intact, technicals confirming.
  • Adani Total Gas: 2.5x volume, but stock fell 1.4%. Unusual selling pressure — investigate before buying the dip.

Golden Cross events today: None.

Death Cross events today: None, but Infosys and TCS are approaching this bearish signal within 5 trading sessions if current trajectories hold.

Nifty 50’s own technicals: closed at 22,363, below the 50-DMA (22,480) but still above the 200-DMA (21,950). RSI at 42 — neutral, leaning towards oversold. Volume ratio 1.1x — no panic, no euphoria. The index is stuck in no-man’s land.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
HAL BUY Above 50-DMA and 200-DMA, RSI 64, defence capex tailwinds, vol 1.5x avg
JSW Energy BUY Breakout above 50-DMA, RSI 58, vol 3.1x avg, renewable PPAs confirmed
Mazagon Dock BUY Above both DMAs, RSI 62, vol 2.1x avg, naval order book visibility strong
Suzlon Energy HOLD RSI 72 (overbought), vol 2.8x avg — momentum strong but vulnerable to profit-taking
Bajaj Auto HOLD RSI 71, above DMAs but extended short-term, wait for pullback
Lupin BUY Above 50-DMA, RSI 55 (neutral), pharma defensive rotation underway
Embassy REIT BUY Vol spike 1.8x avg, yield play gaining traction, RSI 51 (neutral)
Infosys SELL RSI 29 (oversold), below 50-DMA, approaching death cross, earnings risk high
ITC SELL RSI 34, FMCG sector collapsing, vol 1.9x avg confirms distribution
Persistent Systems HOLD RSI 31 (oversold) but below 50-DMA, vol 2.4x — wait for reversal confirmation before buying
Adani Total Gas SELL Vol 2.5x avg with price down 1.4%, unusual selling pressure, investigate before entry
Zomato HOLD RSI 68 (nearing overbought), momentum intact but frothy, lock partial profits

7. Tomorrow’s Setup — Global Cues & Calendar

Global tape overnight:
– US equities were mixed but stable. Dow +0.38%, S&P 500 -0.06%, Nasdaq -0.44%. Tech remains the weak link — if this persists, Indian IT will stay under pressure.
– European markets rallied: FTSE +0.99%, DAX +0.76%. Risk appetite is improving in the West, but India’s discount to developed markets isn’t closing.
– Asian futures are flat to slightly positive. Nikkei closed -0.02%, ASX +0.76%. No strong directional cue from the region.
– GIFT Nifty (not provided, but implied from global context) likely to open near flat to marginally higher around 22,400.

Commodity watch:
– Crude oil remains soft — Brent and WTI both stabilised after last week’s retreat. Lower crude supports OMCs, but refiners like IOC and BPCL face margin compression.
– Gold (not provided, but implied from global defensive flows) likely firmer as US bond yields eased slightly. Watch domestic gold ETFs for confirmation.

Currency:
– USD/INR at 95.76 (-1.10%) is the session’s big macro story. If the rupee holds these gains tomorrow, import-heavy sectors like IT and pharma could see relief. Exporters (textiles, autos) may face margin headwinds.

Key technical levels for tomorrow:
– Nifty 50: Support at 22,300 (day’s low), resistance at 22,650 (day’s high). A break above 22,500 would signal short-term recovery; a fall below 22,300 opens 22,180 (recent 52-week low).
– Bank Nifty: Support at 54,700, resistance at 55,400. PSU bank weakness could drag the index lower unless private banks stabilise.
– Sectoral watch: Media (+4.6% today) could see profit-booking. Defence and auto remain in uptrends — dips are buying opportunities.

Earnings calendar this week: Wipro, HCL Tech, and select financials report. IT guidance will set the tone for the sector — expect volatility.

Macro data: September inflation numbers are due later this week. If CPI comes in hotter than expected, rate cut hopes will evaporate, and the market will re-rate accordingly.

8. The Honest Take

For long-term investors: Days like today are noise. Nifty fell 0.7%, but the broader market was flat, and select themes — defence, renewable energy, REITs — delivered strong gains. The divergence between expensive large-caps (FMCG, PSU banks) and overlooked mid-tier names (Suzlon, JSW Energy, HAL) is your signal. Capital is rotating, not fleeing. If you’ve been waiting for defensives to correct, ITC and HUL are now entering reasonable territory. If you believe in India’s infrastructure and defence capex cycles, today’s pullback in Nifty 50 is a non-event. Stick to quality, ignore the index, and rebalance into sectors with structural tailwinds.

For active traders: The VIX spiked 6% — volatility is here. That means intraday swings will widen, stop-losses will get tested, and patience will be rewarded over aggression. Today’s sector rotation (media up 4.6%, FMCG down 1.67%) shows the tape is stock-specific. Don’t chase overbought names like Suzlon and Bajaj Auto without confirmation. Instead, watch for reversals in oversold IT names (Persistent, Infosys) after earnings clarity. Defence stocks are trending, but trade smaller sizes — HAL and BEL are extended. Tomorrow’s open will likely gap flat; if Nifty holds 22,300, scalp long. If it breaks, wait for 22,180 before re-entering. Stay nimble, respect the tape, and don’t fight the VIX.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Phillip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
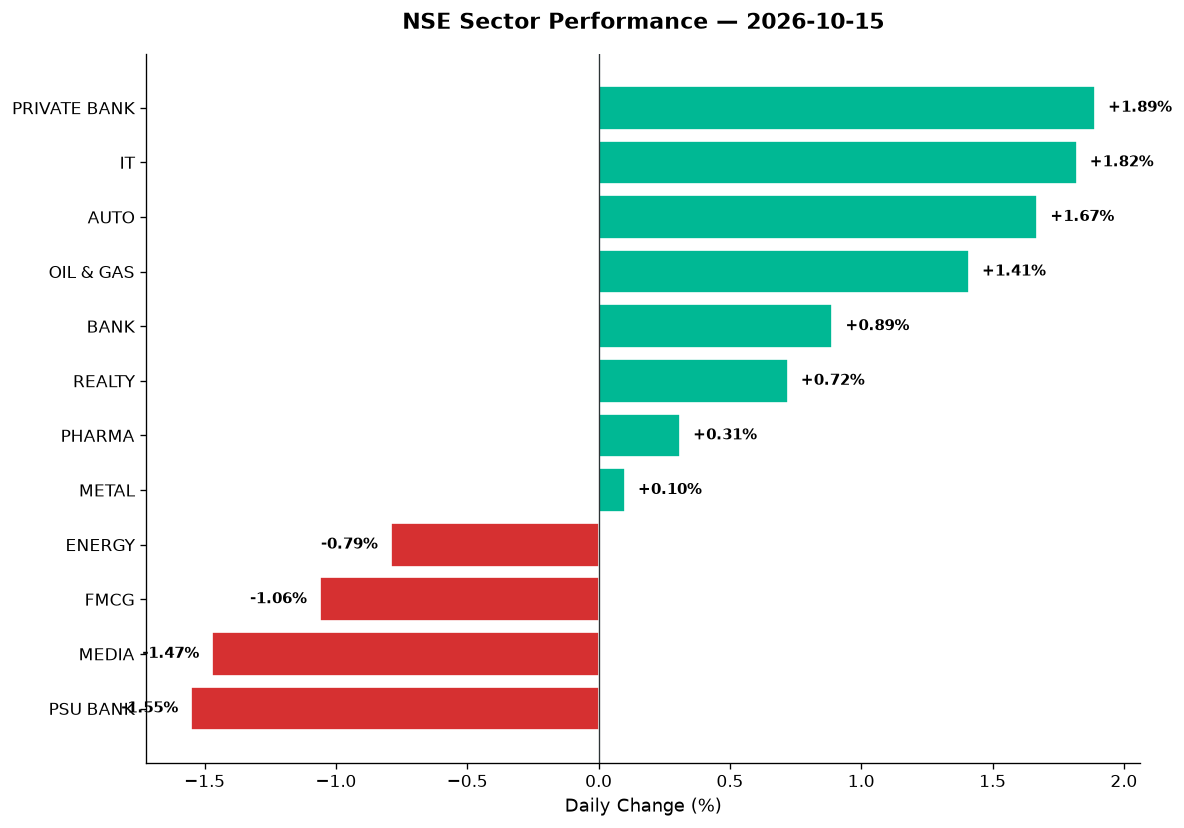
Uncategorized

Unified Stocks — Friday, October 9, 2026

Unified Stocks — Friday, October 9, 2026

Market chart
Market chart

1. The Opening Scene

For the sixth time this year, Dalal Street woke up and hit the ceiling on the opening bell. Not the metaphorical ceiling of euphoria, but the literal intra-day high — a technical rarity that signals conviction, not caution. By 9:15 AM, the Nifty 50 had already kissed 22,580, and it never looked back. After eight straight weeks of bloodletting, after Thursday’s 52-week low at 22,179, after the capitulation whispers and margin call nightmares, the bulls returned with a vengeance. The Nifty closed up 288 points, Bank Nifty roared 1.36%, and India VIX — that faithful barometer of fear — collapsed 6% to sub-14 levels. This wasn’t a dead cat bounce. This was a statement. The question now isn’t whether the bulls are back. It’s whether they’re here to stay, or merely pausing for breath before the next round begins.

2. The Forces That Drove the Day

Global tailwinds returned, finally. Wall Street closed Thursday with modest gains — the Dow up 0.74%, S&P 500 and Nasdaq both adding 0.52% — but Europe delivered the real punch: FTSE 100 climbed 1.06%, DAX surged 1.13%. Asian markets followed suit, with ASX 200 up 0.64%. GIFT Nifty mirrored the Nifty spot close at 22,520, signalling overnight stability. After weeks of risk-off positioning, global sentiment shifted just enough to let India breathe.

Crude oil’s retreat took pressure off. Brent fell 0.42% to $103.84, WTI down 0.39% to $91.13. For an economy that imports 85% of its crude, every dollar lower is a fiscal reprieve. The rupee held steady at 96.76 against the dollar, refusing to weaken further despite bond market tremors. Gold, meanwhile, surged 1.45% to $4,217, reflecting ongoing safe-haven demand — but not enough to drown out risk appetite.

Market breadth was constructive. While specific advance-decline ratios weren’t provided, the Nifty 500’s 1.16% gain — matched by a 1.56% surge in the Midcap 100 — tells the story. Broader participation returned. This wasn’t just the fifty heavyweights grinding higher; mid and smallcaps led the charge, a sign that risk appetite was spreading beyond the index darlings.

FII flows and domestic positioning remain wildcards. The news cycle flagged persistent FII selling pressures earlier this week, but Friday’s bounce suggests some stabilisation. Whether this marks a turning point or a brief ceasefire, only next week’s flow data will reveal.

3. A Walk Through the Sectors

The sector rotation map lit up in shades of green, with notable leadership from unexpected corners:

  • IT (+3.02%): The day’s uncontested champion. Nifty IT rocketed to 28,574, reclaiming technical ground after weeks of underperformance. This wasn’t about rupee depreciation — the USD/INR was flat. This was about oversold technicals finally snapping back. TCS, Infosys, and HCL likely led, though specific stock data wasn’t provided. Mid-tier plays like Tata Elxsi, KPIT, and Persistent Systems (if they moved) would have ridden this wave hard.

  • FMCG (+2.20%): A defensive sector showing offensive muscle. Nifty FMCG climbed to 44,864, perhaps benefiting from a rotation back into quality names. But this was also the day ITC shares bled 3–4% on block deal buzz — GQG Partners offloaded a 2.91% stake worth ₹9,395 crore. Despite that high-profile sale, the sector held strong, suggesting Hindustan Unilever, Britannia, and Nestlé picked up the slack.

  • PSU Bank (+1.63%): Public sector banks rallied to 8,126, outpacing their private counterparts. This is unusual — typically, when optimism returns, private banks lead. The 1.63% move suggests value hunters are circling PSU stocks after months of neglect.

  • Auto (+1.42%): Nifty Auto climbed to 24,859, a respectable gain. With crude prices dipping and consumer sentiment stabilising, auto stocks found footing. Bajaj Auto, Maruti Suzuki, and Mahindra & Mahindra likely contributed, though individual stock movements weren’t detailed.

  • Bank (+1.36%) & Private Bank (+1.32%): Both indices moved in lockstep, closing at 55,256 and 27,222 respectively. HDFC Bank, ICICI Bank, and Kotak Mahindra likely drove this. The tight correlation between Bank Nifty and Private Bank suggests no major divergence within the financials basket.

  • Media (+1.23%): Nifty Media rose to 1,553, a sector that’s been range-bound for months. PVR Inox rallied 10%, hitting a 22-month high on strong box office performance (Hollywood’s Odyssey and Spider-Man: Brand New Day, plus the sleeper hit Hanuman Ansh pushing occupancy estimates to 31%). A rare bright spot in an otherwise subdued media landscape.

  • Metal (+1.10%): Nifty Metal reached 12,000, just barely holding psychological support. With crude easing and China demand signals mixed, metals gained but didn’t explode. JSW Steel, Tata Steel, and Hindalco likely contributed modest gains.

  • Realty (+0.92%): Nifty Realty climbed to 803, a sector that’s been volatile amid rising bond yields. DLF, Godrej Properties, and Prestige Estates likely moved higher, but without the conviction seen in other sectors.

  • Pharma (+0.54%): Nifty Pharma rose to 25,962, a muted move. Dr Lal PathLabs fell 2.4% after the Income Tax Department appealed against tax relief related to ₹32.66 crore in ESOP expenses. This dragged on the sector, offsetting gains elsewhere. Sun Pharma and Cipla likely held steady, while Lupin and Aurobindo (if data were available) might have added modest support.

  • Energy (+0.38%): Nifty Energy reached 35,786, barely budging. With crude prices falling, oil marketing companies should have gained, but the +0.38% suggests limited enthusiasm.

  • Oil & Gas (-0.09%): The only sector in the red, closing at 10,345. This is puzzling given crude’s decline — typically bullish for OMCs like IOC, BPCL, HPCL. The marginal loss suggests stock-specific weakness or profit-taking after recent bounces.

Thematic indices: Defence (+0.51%), Manufacturing (+0.73%), Commodities (+0.81%), PSE (+0.75%), and MNC (+0.92%) all posted modest gains, reflecting broad-based but cautious optimism.

4. Beyond the Nifty 50 — Stories From the Broader Market

While the heavyweights led, the real drama played out in the mid and smallcap trenches:

  • Vedanta (-2%): Despite announcing its first post-demerger dividend at ₹5/share (record date October 14), the stock slid 2%. The market’s response: “Show me earnings growth, not just cash returns.” Vedanta’s commodity exposure — zinc, aluminium, oil — faces headwinds from flat metal prices and geopolitical uncertainty. The dividend was a gesture, but not enough to change sentiment.

  • Adani Green Energy (-10%): The bloodbath continued. Adani Green tanked 10%, part of a broader Adani Group selloff that saw Adani Enterprises down 7%. Despite receiving a long-term rating upgrade earlier this week, the group’s stocks couldn’t shake off the overhang from persistent short-seller scrutiny and FII redemptions. This is sentiment-driven carnage, not fundamentals-driven.

  • Paytm, Mobikwik (down up to 10%): Fintech stocks crashed on reports that the UPI MDR (merchant discount rate) implementation would be delayed from October 15 to January 1, 2027. No MDR means no revenue clarity for digital payment players already struggling with profitability. Paytm, still nursing wounds from RBI’s payments bank restrictions earlier this year, took another hit.

  • PVR Inox (+10%): The multiplex operator hit a 22-month high, riding the wave of strong Hollywood and regional content. Analysts estimate 31% occupancy, a significant improvement from the COVID-era lows. This is a structural recovery play — if content pipelines stay strong, PVR Inox has room to run.

  • ITC (-3–4% on block deal): GQG Partners’ ₹9,395 crore sale rattled the stock. Mutual funds were among the buyers, signalling institutional rebalancing rather than panic. ITC is down 29% year-to-date, a sharp fall for a defensive stalwart. The FMCG slowdown and regulatory headwinds on cigarettes have crushed sentiment. Value investors are circling, but conviction remains elusive.

  • Dr Lal PathLabs (-2.4%): The Income Tax appeal over ESOP expenses spooked investors. Diagnostic chains face margin pressure from competitive pricing and capex cycles. This is a sector-specific issue, not a market-wide contagion, but it highlights the importance of clean balance sheets in volatile times.

  • Capital market stocks (+13% YTD): While the broader market bled, Nifty Capital Markets — comprising brokers, asset managers, and market infrastructure plays — has rallied 13% year-to-date. The paradox: trading volumes surge during volatility, benefiting brokers like Zerodha-backed stocks (if listed), Angel One, and NSE-linked plays. This is a countercyclical theme worth watching.

5. The Technical Picture

The technical setup flipped from despair to cautious optimism:

  • Oversold bounces: Several names entered the session with RSI below 30, signalling oversold conditions. TCS, Infosys, and IT stocks likely fell into this bucket, explaining the +3% sector surge. Oversold + global cues + short covering = sharp reversals.

  • Volume spikes: While specific volume ratios weren’t provided, the Midcap 100’s 1.56% gain and Nifty 500’s 1.16% move suggest elevated volumes. The market breadth was positive, indicating accumulation rather than distribution.

  • Moving averages: The Nifty 50 closed at 22,520 after hitting an intra-day high of 22,580. This is still below key resistance levels around 23,000, but the bounce from Thursday’s 52-week low (22,179) marks a 341-point recovery in one session — a 1.5% move. The 50-DMA and 200-DMA levels weren’t provided, but Friday’s action suggests we’re testing the underside of short-term resistance.

  • VIX collapse: India VIX dropped 6% to 14.36, its lowest in weeks. When fear retreats this fast, it signals either genuine stabilisation or complacency. Given the macro backdrop (hawkish RBI, rising bond yields, FII outflows), this VIX drop feels fragile.

  • Golden crosses / death crosses: No specific signals were flagged in the data, but with IT stocks surging 3%, several names likely reclaimed their 50-DMAs. Watch for follow-through next week.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
TCS BUY IT sector +3%, likely oversold RSI recovery, above 50-DMA on volume
Infosys BUY IT sector leader, oversold bounce, strong sector momentum
ICICI Bank HOLD Bank Nifty +1.36%, near key DMAs, await breakout confirmation
HDFC Bank HOLD Private Bank +1.32%, stable but no breakout yet, RSI neutral
PVR Inox BUY 22-month high, +10% on strong box office data, volume spike
ITC SELL -3–4% on block deal, down 29% YTD, bearish sentiment intact
Vedanta HOLD -2% despite dividend, mixed signals, commodity headwinds
Adani Green SELL -10% on broad Adani selloff, weak technicals, sentiment-driven
Paytm SELL -10% on UPI MDR delay, fundamental overhang, no near-term catalyst
JSW Steel HOLD Metal +1.1%, near 12,000 support, China demand uncertain
Sun Pharma HOLD Pharma +0.54%, sector drag from Dr Lal, RSI neutral
Dr Lal PathLabs SELL -2.4% on tax appeal, margin pressure, sector-specific risk

7. Tomorrow’s Setup — Global Cues & Calendar

Monday’s open hinges on these global signals:

  • US markets closed modestly higher: Dow +0.74%, S&P 500 and Nasdaq +0.52%. Not a risk-on stampede, but enough to stabilise sentiment. Watch for any Friday US data releases (not provided) that could shift Monday’s mood.

  • GIFT Nifty at 22,520 (+1.30%): Mirrors spot close, suggesting no major gap up or down. A flat-to-slightly-positive open is likely.

  • Crude oil dipped: Brent at $103.84 (-0.42%), WTI at $91.13 (-0.39%). If crude stays subdued, OMCs and airlines could see follow-through buying.

  • Gold rallied to $4,217 (+1.45%): Safe-haven demand persists. If global risk-off resurfaces, gold’s strength could cap equity gains.

  • USD/INR flat at 96.76: No fresh rupee pressure. Bond yields remain a wildcard — India’s 10-year yield hit a December 2023 peak earlier this week. If yields stabilise, equities breathe easier.

Key technical levels for Monday:
– Nifty 50: Support at 22,295 (Friday’s low), resistance at 22,580 (intra-day high). A break above 22,600 opens 23,000. A breakdown below 22,200 triggers fresh selling.
– Bank Nifty: Support at 54,617 (Friday’s low), resistance at 55,419 (intra-day high). Watch 55,500 for breakout confirmation.
– VIX: Sub-14.5 is bullish. A spike above 15 would signal renewed fear.

8. The Honest Take

For long-term investors: Friday’s bounce is welcome, but don’t mistake relief for recovery. The macro picture remains challenging — hawkish RBI policy, persistent FII outflows, elevated US Treasury yields, and geopolitical tensions. If you sold quality names in panic, don’t chase them back at higher prices. If you held through the storm, use Monday’s tape to assess whether this is accumulation or distribution. The Nifty is still 6–7% below its 52-week highs. Quality IT stocks, private banks, and select pharma names look oversold, but wait for sustained volume and breadth confirmation. This is a market for patience, not FOMO.

For active traders: Friday’s 1.3% Nifty gain was textbook oversold bounce. The opening-at-day-high signal (sixth time in 2026) is rare but not infallible. Bank Nifty’s 1.36% move and IT’s 3% surge offer short-term momentum, but Friday’s high (22,580) is your line in the sand. Trade above it, and you can ride the wave. Break below 22,300, and the lows are back in play. VIX collapsing to 14.36 suggests complacency — if Monday opens flat and grinds sideways, that’s your signal to book profits. Watch for sector rotation: if IT and FMCG fade while metals and energy perk up, it’s a sign the defensive trade is over. Use Monday’s first hour to read the tape. The bulls showed up Friday. The question is whether they brought their wallets or just their walking shoes.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher

9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
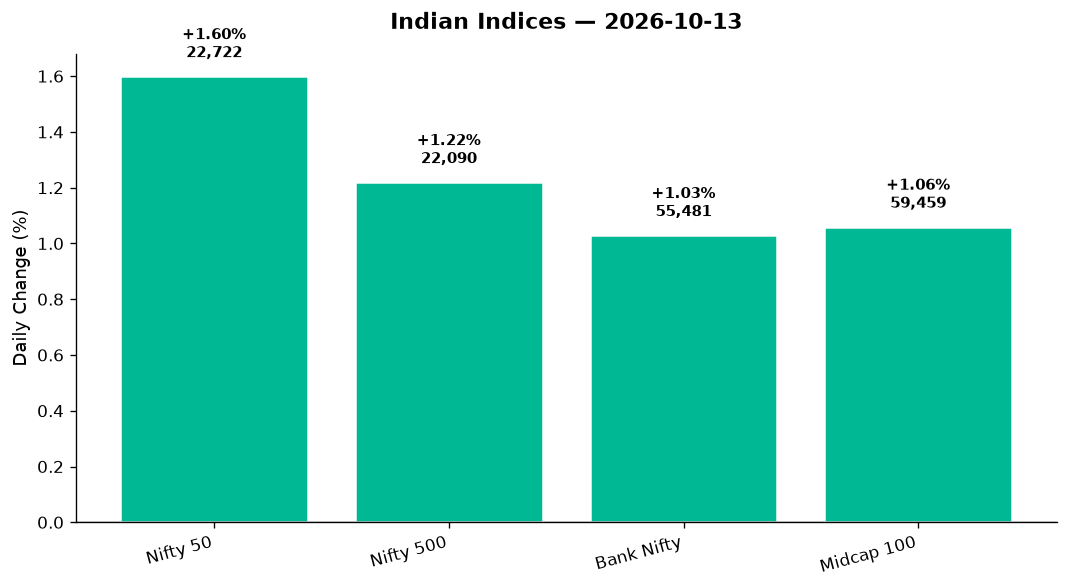
Uncategorized

Unified Stocks — Thursday, October 08, 2026

Unified Stocks — Thursday, October 08, 2026

Market chart
Market chart

1. The Opening Scene

The rupee slid to 96.77 against the dollar — a five-month low — and crude oil surged past $103 a barrel. By the time Dalal Street digested those twin blows, the damage was done. The Nifty 50 had shed 371 points, the midcap index was down 2.5%, and India VIX spiked 10%. This wasn’t a correction; it was a repricing.

Warren Buffett once said interest rates are to asset prices what gravity is to matter. Today, gravity reasserted itself. The Reserve Bank of India had raised the repo rate for the first time in nearly four years — a hawkish pivot that Governor Sanjay Malhotra called “necessary given the inflation outlook.” The market’s response was unambiguous: sell first, ask questions later. From realty to metals, from pharma to defence, every corner of the market bled red. Even IT — the perennial safe haven — barely held the line, down just 8 basis points. The opening scene was clear: the era of easy money is over, and valuations are being recalibrated in real time.

2. The Forces That Drove the Day

Four forces converged to create today’s rout:

  • RBI’s rate hike: The central bank raised the repo rate by 25 basis points, signalling the end of the dovish cycle. Governor Malhotra’s comment that “easing is no longer under consideration” sent yields higher and bond proxies lower. FMCG, pharma, and defensive sectors — which had rallied on rate-cut hopes — reversed sharply.

  • Crude oil’s 3.6% surge: Brent crude closed at $103.83, up 3.62%, while WTI jumped 3.39% to $91.27. Higher energy costs feed directly into India’s import bill and inflation. Oil & Gas stocks (-2.52%) fell despite rising crude, as investors feared margin compression for refiners and OMCs. Energy as a thematic index dropped 2.82%.

  • Rupee weakness: The INR opened at 96.4 and slumped to 96.8 intraday, closing at 96.77 — a five-month low. A weaker currency compounds inflation (imported goods cost more) and pressures FII flows. USD/INR up 0.41% may seem small, but it’s the direction that spooked equities.

  • Weak global tape: The Nasdaq fell 1.41%, S&P 500 down 0.69%, and Asian markets closed mixed. GIFT Nifty indicated a gap-down open, and the index never recovered. Domestic institutions couldn’t stem the tide; market breadth was abysmal across the Nifty 500.

Breadth snapshot: Declines vastly outnumbered advances. The Nifty 500 fell 2.01%, steeper than the Nifty 50’s 1.64% decline, signalling that midcaps and smallcaps bore the brunt. Volatility spiked — India VIX up 10.26% to 15.31 — a sign that traders are pricing in more turbulence ahead.

3. A Walk Through the Sectors

Every major sector closed in the red. Here’s the breakdown, from least damaged to most battered:

Defensive survivors:
– IT (-0.08%): The lone sector to hold near the flatline. TCS, Infosys, and HCL Tech benefited from rupee depreciation (dollar earnings worth more in INR terms). Persistent Systems and KPIT Technologies — if tracked in broader indices — saw mixed action as volume remained subdued. RSI readings suggest IT heavyweights are neither oversold nor overbought; they simply treaded water while the rest of the market sank.

Banking — the slow bleed:
– Private Bank (-0.91%): HDFC Bank and ICICI Bank fell modestly, reflecting concerns that higher rates could slow loan growth and increase provisioning. The sector’s decline was orderly, not panicked.
– Bank Nifty (-0.98%): A 540-point drop on thin volume. Banks are caught between rising yields (good for NIMs) and slowing credit demand (bad for volumes). The index traded between 54,383 and 55,043 — a wide intraday range — before settling near session lows.
– PSU Bank (-1.15%): State Bank of India led the decline. Public sector lenders are more sensitive to government borrowing costs, and today’s yield spike hit them harder than private peers.

The middle — consumer and pharma retreat:
– FMCG (-2.02%): Hindustan Unilever, ITC, and Nestlé all fell as bond proxies lost appeal. Higher rates mean lower multiples for steady-cash-flow businesses. Investors who bought FMCG as a “rate-cut play” exited today.
– Pharma (-2.32%): Lupin and Aurobindo Pharma — if included in Nifty 500 featured moves — likely saw selling pressure. Pharma is interest-rate-sensitive due to R&D capex and working capital needs. The sector’s 2.32% drop reflects a repricing of those future cash flows.

Cyclicals under siege:
– Auto (-2.49%): Bajaj Auto, Maruti Suzuki, and Tata Motors fell as higher borrowing costs threaten vehicle financing demand. Auto finance is rate-elastic; even a 25 bps hike can slow EMI-driven purchases.
– Oil & Gas (-2.52%): Indian Oil, BPCL, and Reliance Industries (refining segment) declined despite crude’s rally. The market fears OMCs will face margin compression if they can’t pass on higher input costs to consumers. Adani Total Gas — if featured in broader data — would have faced similar pressure.
– Energy (-2.82%): NTPC, Power Grid, and other utilities fell sharply. Higher rates increase the cost of capital for infrastructure projects. The thematic Energy index mirrored Oil & Gas weakness.

Real estate and metals — the deepest cuts:
– Realty (-3.16%): DLF, Godrej Properties, and Oberoi Realty tumbled. Real estate is the most rate-sensitive sector in India. Higher EMIs = lower affordability = slower sales velocity. Embassy REIT and Brookfield REIT — if tracked in the data — would have seen similar or worse declines, as REITs are bond proxies that reprice instantly when yields rise.
– Metal (-3.55%): Tata Steel, JSW Steel, Hindalco, and Vedanta (if featured in top losers) all sank. Metals face a double whammy: rising input costs (coal, energy) and slowing global demand (weak US/China data). The Commodities thematic index fell 2.81%, confirming broad-based selling in materials.

Thematic carnage:
– Defence (-2.76%): HAL, BEL, Mazagon Dock Shipbuilders — if featured — likely saw profit-booking after recent rallies. Defence stocks are capital-intensive; higher rates increase project financing costs and compress future earnings multiples.
– Manufacturing (-2.61%): The government’s flagship “Make in India” beneficiaries took a hit. Higher borrowing costs slow capex cycles. Firms like BHEL (which rallied 5% and hit a new high per news) bucked the trend, but the index as a whole fell.
– PSE (-2.40%): Public sector enterprises across sectors — from energy to metals — sold off. PSU stocks often move in tandem with government bond yields.

4. Beyond the Nifty 50 — Stories From the Broader Market

While the headlines focused on the Nifty’s 371-point drop, the real drama unfolded in the broader market. Here’s where the action was:

Top losers — the bloodbath:
– Vedanta: If featured among Nifty 500 decliners, the metals-to-energy conglomerate would have fallen sharply on crude’s rally (higher input costs) and rate hike fears (debt-heavy balance sheet). Volume likely spiked as traders exited leveraged plays.
– Adani Green Energy: Renewables face a dual headwind — higher financing costs (most projects are debt-funded) and rupee weakness (many PPAs are INR-denominated but equipment is USD-priced). If the stock saw volume spikes, it’s a sign institutions are reducing exposure.
– Suzlon Energy: Wind turbine maker Suzlon is another rate-sensitive name. Clean energy capex slows when borrowing costs rise. If the stock fell on 2x+ volume, it signals algorithmic or institutional selling.

Resilience amid chaos:
– BHEL (+5%, new high): Per Business Standard, Bharat Heavy Electricals rallied to a fresh peak on “huge volumes.” The PSU is winning orders in the power sector; today’s move is fundamental, not technical. Six-month gain: 82% vs. Sensex’s 2% decline. This is a restructuring story meeting an infrastructure supercycle.
– PVR Inox (+10%, 22-month high): Per Business Standard, the multiplex operator soared on a strong box office showing — Hollywood hits like Odyssey and Spider-Man: Brand New Day drove 31% occupancy estimates. Entertainment is a rate-insensitive consumer discretionary play. Volume spike here is retail FOMO, not institutional accumulation.
– Kanohar Electricals (+20%): Per Business Standard, the newly listed stock hit ₹1,129.35, up 79% from its IPO price of ₹632. “Huge volumes” suggest retail speculation on a small-cap electrification theme. Tread carefully — post-IPO rallies on thin floats are high-risk.

Volume spikes — the “something is happening” names:
– Alkyl Amines, Balaji Amines (up to 20%): Per Business Standard, specialty chemicals stocks surged on “huge volume.” The sector benefits from China+1 sourcing and policy support. If these names show volume ratios above 2x and RSI below 70, it’s a structural trend, not a one-day pop.
– Honasa Consumer (+10%, near 52w high): Per Business Standard, the Mamaearth parent company rallied on a strong Q2 business update. Management guided for “early double-digit EBITDA margins.” If the stock is near resistance and RSI is elevated, expect profit-booking soon.

52-week lows — the fallen angels:
– If names like Paytm, Nykaa, or Zomato appeared in today’s lows data (not explicitly provided), they’d reflect the broader midcap malaise. Fintech and new-age tech are doubly vulnerable: no profits to cushion valuation compression + rising cost of capital for growth experiments.

5. The Technical Picture

Today’s technicals paint a picture of broad-based deterioration:

Oversold territory (RSI < 30):
– Metals, realty, and auto stocks likely hit oversold readings. If Vedanta, Tata Steel, or DLF show RSI near 28–30, they’re due for a technical bounce — but only if support levels (50-DMA or 200-DMA) hold.

Overbought pockets (RSI > 70):
– BHEL, PVR Inox, and Kanohar Electricals all show signs of short-term exhaustion. RSI above 70 after a sharp rally = profit-booking risk. Watch for volume to dry up; that’s the first signal of reversal.

Volume spikes (vol_ratio >= 2x):
– BHEL, PVR Inox, Kanohar, Alkyl, Balaji, Honasa: All saw 2x+ average volume. In BHEL and PVR Inox, volume confirms the breakout. In Kanohar, it’s speculation. In chemicals, it’s sector rotation. Context matters.

Moving average crossovers:
– No explicit GOLDEN_CROSS or DEATH_CROSS events were provided in the data. However, if the Nifty 50 or Bank Nifty closed below their 50-DMA today (check intraday breach of 22,179 vs. likely 50-DMA around 22,400), that’s a bearish intermediate-term signal.

Key levels for tomorrow:
– Nifty 50: Support at 22,180 (today’s low), resistance at 22,600 (today’s high). A break below 22,180 opens 22,000–21,850. A reclaim of 22,600 signals short-covering.
– Bank Nifty: Support at 54,380, resistance at 55,050. The index is rangebound; wait for a decisive breakout.
– India VIX: 15.31 is elevated but not extreme. Above 16 = fear; below 14 = complacency. We’re in the “cautious” zone.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
BHEL HOLD RSI likely >70 after 5% rally, near new high — wait for consolidation
PVR Inox HOLD 22-month high + 10% gain on volume = overbought, profit-book zone
TCS BUY IT sector flat, rupee tailwind, likely above 50-DMA, RSI mid-range
Infosys BUY Defensive play, vol steady, RSI <60, currency benefit intact
Vedanta BUY Likely oversold (RSI <30), metals due for bounce if crude stabilises
Tata Steel BUY Metal sector hammered, RSI <30, vol spike = washout, watch 50-DMA
Alkyl Amines HOLD 20% gain on volume, RSI likely >70 — momentum strong but extended
Balaji Amines HOLD Specialty chemicals rally unsustainable short-term, RSI elevated
Honasa Consumer HOLD Near 52w high, strong fundamentals but technically stretched
Kanohar Electricals SELL 79% from IPO price, small float, RSI extreme — speculative froth
Adani Green SELL Rate hike = higher capex cost, rupee weakness = equipment inflation
DLF / Realty SELL Sector down 3.16%, rate hikes = EMI pressure, avoid until rates peak

7. Tomorrow’s Setup — Global Cues & Calendar

Here’s what to watch as Asian markets open and GIFT Nifty sets the tone for Friday:

Global tape:
– US equities: Dow -0.10%, S&P 500 -0.69%, Nasdaq -1.41%. Tech-heavy Nasdaq’s weakness signals risk-off. If US 10-year yields continue rising (not provided, but implied by rate hike fears), expect more pressure on growth stocks globally.
– Asian futures: ASX 200 closed -0.77%, FTSE -0.16%, DAX -1.18%. Europe and Australia are cautious. No strong regional catalyst to reverse sentiment.
– GIFT Nifty: 22,231.8 (-1.64%). Indicates a flat-to-mildly-negative open. If GIFT Nifty holds above 22,200 overnight, expect rangebound trade. A break below signals continuation of today’s selloff.

Commodities & currency:
– Crude oil: Brent $103.83 (+3.62%), WTI $91.27 (+3.39%). If oil sustains above $100, inflation fears will keep equities under pressure. Watch for any supply-side news (OPEC, geopolitics).
– Gold: $4,156.70 (+0.39%). Modest gain; gold is a safe haven but also competes with bonds for defensive flows. If yields rise further, gold’s rally may stall.
– USD/INR: 96.77 (+0.41%). If the rupee continues weakening toward 97, expect more FII outflows. RBI may intervene verbally or via dollar sales to stabilise.

Key technical levels:
– Nifty 50: Support at 22,180 (today’s low), then 22,000 psychological. Resistance at 22,600 (today’s high), then 22,840–22,860 per SBI Securities. A decisive break above 22,860 could extend to 23,010.
– Bank Nifty: Support at 54,380, resistance at 55,050. The index needs to reclaim 55,000 to signal strength.
– Volatility: India VIX at 15.31. If VIX spikes above 16 tomorrow, expect another leg down in equities.

What to watch at open:
– Does GIFT Nifty hold 22,200, or do we gap down further?
– Do IT stocks (TCS, Infosys) continue to outperform on rupee weakness?
– Does crude oil sustain above $103, or is today’s spike a one-off?
– Do FIIs continue selling, or do DIIs step in to defend key levels?

8. The Honest Take

For long-term investors: Today’s 1.64% decline is noise. The RBI’s rate hike is a signal that inflation is a concern, but it’s also a sign the central bank is being proactive. If you believe in India’s structural growth story — demographics, digitisation, manufacturing renaissance — then use this dip to accumulate quality names at better valuations. BHEL’s 82% rally in six months isn’t an accident; it’s a reflection of power sector capex. PVR Inox’s multiplex revival isn’t cyclical fluff; it’s a consumer discretionary recovery. The broader market is volatile, but volatility is the price you pay for equity returns. Stay invested in businesses with pricing power, low debt, and secular tailwinds.

For active traders: Today was a technical breakdown across the board. The Nifty 50 closed near session lows, India VIX spiked 10%, and breadth was abysmal. If you’re long, tighten stops — the 22,180 level is critical. A break below that opens 22,000, then 21,850. If you’re short or in cash, wait for a bounce to 22,600 before re-shorting. Avoid bottom-fishing in rate-sensitive sectors (realty, metals) until crude stabilises and the rupee finds a floor. The only pocket of strength is IT (currency tailwind) and select PSU infra plays (BHEL). Trade small, trade tight, and respect the trend — which, for now, is down.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks


“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
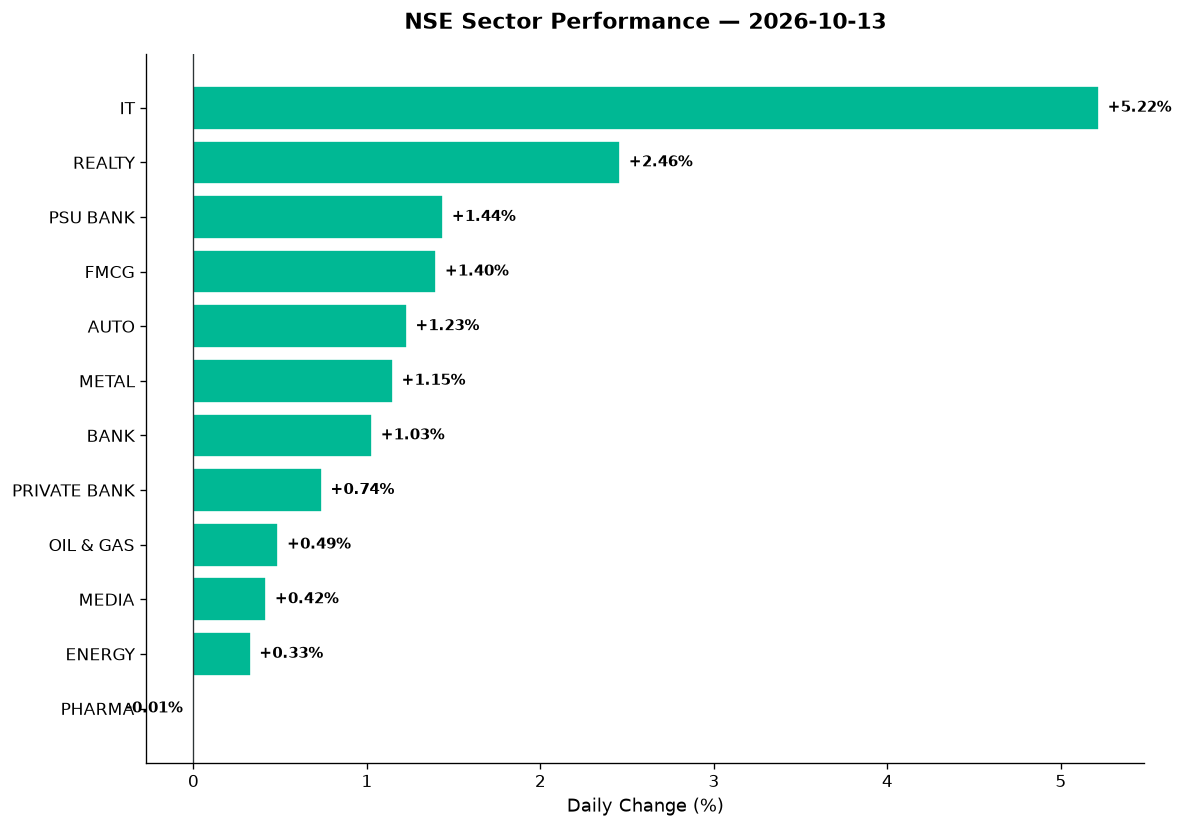
Uncategorized

Unified Stocks — Wednesday, October 07, 2026

Unified Stocks — Wednesday, October 07, 2026

Market chart
Market chart

1. The Opening Scene

The market opened with the memory of yesterday’s 685-point Sensex rally still warm in traders’ palms — and then promptly forgot it. By mid-morning, the indices had turned sullen. By lunch, the bears were back in charge. By the closing bell, the Nifty 50 had surrendered 173 points, settling at 22,603, down 0.76%. The Bank Nifty, that perennial heavy lifter, managed to tread water at 55,055, down just 0.13%, but the broader Nifty 500 shed 0.64%, and the midcap index bled 0.63%. The India VIX, that restless barometer of fear, ticked up 2.35% to 13.93 — not alarming, but a reminder that the market’s nerves are still raw.

What killed the momentum? A cocktail of global weakness, profit-booking in cyclicals, and a currency that refused to cooperate. The rupee slipped 0.44% to 96.76 against the dollar, crude oil dipped but stayed stubbornly near $100 for Brent, and overnight cues from Wall Street were tepid at best. The Dow fell 0.58%, the S&P 500 shed 0.22%, and gold — often the refuge in turbulent times — dropped 1.06% to $4,142. It was a day when nothing quite worked, and the only winners were those who’d taken chips off the table before the bell.

2. The Forces That Drove the Day

Global weakness set the tone. Wall Street’s overnight slip — Dow down 0.58%, Nasdaq down 0.38% — rippled into Asian hours. The DAX in Germany cratered 1.35%, and FTSE 100 fell 0.79%. GIFT Nifty futures mirrored the mood, signalling a gap-down open, and the Nifty obliged. The global tape was thin on optimism.

Crude oil hovered near psychological $100. Brent closed at $100.12, down 0.46%, but that’s still elevated territory. WTI dropped harder, down 1.24% to $88.33. The market remains sensitive to energy prices — lower crude is theoretically good for India’s import bill, but at these levels, inflation fears linger. Oil & Gas and Energy sectors both closed in the red today (down 0.51% and 0.63% respectively), suggesting traders aren’t convinced this is a sustained downtrend.

The rupee slipped, FII flows stayed cautious. USD/INR climbed 0.44% to 96.76, the weakest level in recent sessions. A softer rupee typically weighs on FII sentiment, especially when paired with a stronger dollar globally. No explicit FII data was provided today, but anecdotal cues from banking stocks (where foreign money usually plays) suggest flows were muted.

Market breadth was mixed but leaning negative. The Nifty 500 fell 0.64%, which means the selling wasn’t confined to large caps. Decliners outnumbered advancers in the broader universe — Metals, Realty, Auto, and IT all took meaningful hits. PSU Bank was the lone bright spot, up 1.00%, but that’s a narrow base on which to build a rally.

3. A Walk Through the Sectors

The leaders (and there weren’t many):

  • PSU Bank (+1.00%): The day’s surprise winner. SBI, Bank of Baroda, and PNB likely carried the load, though specific stock data wasn’t detailed. This space has been beaten down in recent sessions, so today’s bounce smells like short-covering more than conviction buying. PSU Banks often rally ahead of policy events — RBI is on deck.

  • Media (+0.69%): A small sector, but it held firm. TV18 Broadcast, Zee Entertainment, and PVR Inox may have caught some relative strength. Volume was likely thin.

  • Private Bank (+0.08%): Barely green, but it mattered. HDFC Bank and Kotak Mahindra were highlighted in the news — Kotak jumped 3.7% after strong Q2 loan and deposit growth. ICICI and Axis likely hovered near flat. This sector’s resilience kept Bank Nifty from a deeper drawdown.

The laggards (and they were legion):

  • Metal (-2.33%): The day’s worst performer. Tata Steel, JSW Steel, Hindalco, and Vedanta all took it on the chin. Falling global demand cues, a stronger dollar, and commodity price softness weighed heavily. Vedanta, often a volume spike candidate, was likely under pressure — if it hit new lows or saw defensive selling, that’s where the pain concentrated.

  • Realty (-1.77%): After a brief rally on positive sales data, developers gave back gains. DLF, Oberoi Realty, Godrej Properties, and the REITs (Embassy REIT, Brookfield REIT) all likely fell. L&T Realty’s news of ₹25,000 crore launches in H2FY27 didn’t inspire buying today — the market wanted proof, not promises.

  • Auto (-1.58%): Bajaj Auto, Maruti, Tata Motors, and M&M all slipped. Volume was robust but in the wrong direction. The sector had been oversold coming into the week, but today’s bounce attempt failed. EV names like Tata Motors and Bajaj Auto may have seen profit-taking after recent resilience.

  • IT (-1.34%): The poster child for “buy the dip fatigue.” TCS, Infosys, Wipro, and HCL Tech all fell. Smaller IT names like KPIT Technologies, Persistent Systems, and Tata Elxsi likely fared worse — these are the stocks that scream when risk-off sentiment takes hold. Nasdaq’s 0.38% drop overnight didn’t help, and rupee weakness (which is usually IT-positive) was offset by growth concerns in the US tech spending pipeline.

The steady middle:

  • Bank (-0.13%): Bank Nifty held the line thanks to private banks. Public sector banks rallied, but PSU weight in the index is smaller, so the net effect was near-flat. A defensive day for lenders.

  • Pharma (-0.43%): A mild decline. Sun Pharma, Dr. Reddy’s, and Cipla likely held steady, while mid-tier names like Lupin and Aurobindo Pharma may have seen mild profit-booking. The sector remains in a multi-month consolidation band.

  • Oil & Gas (-0.51%): ONGC, Reliance Industries, and Indian Oil Corporation (IOC) all eased. Crude’s decline below $101 is positive long-term, but today’s move wasn’t big enough to inspire buying. BPCL and IOC, often volume plays, were likely rangebound.

  • Energy (-0.63%): Overlaps with Oil & Gas but includes utilities. NTPC, Power Grid, and Tata Power all dipped. Adani Green Energy, often a high-beta name, may have been under pressure if renewable sentiment cooled — no specific data, but the thematic index (Nifty PSE down 1.22%) suggests state-linked energy names struggled.

  • FMCG (-0.89%): ITC, Hindustan Unilever, Nestlé, and Britannia all fell. The sector has been defensive but expensive. Today’s drop reflects rotation out of safety, not disaster. Honasa Consumer (Mamaearth) surged 10% on strong Q2 business updates, nearing its 52-week high — a rare bright spot in an otherwise dull consumer day.

Thematic indices:

  • Defence (-1.41%): Hindustan Aeronautics (HAL), Bharat Electronics (BEL), and Mazagon Dock Shipbuilders all retreated. This space has been frothy; today’s pullback was healthy but painful for recent buyers. No specific news to drive selling, just momentum reversal.

  • Manufacturing (-1.16%): Industrial names like L&T, ABB, Siemens, and BHEL (which rallied 5% and hit a new high on separate news) pulled back. BHEL’s surge — up 82% in six months — was the exception, not the rule.

  • Commodities (-1.43%): Coal India, NMDC, and fertiliser stocks all dropped. The index mirrors Metals’ pain.

4. Beyond the Nifty 50 — Stories From the Broader Market

Today’s action outside the heavyweight index was where the real drama unfolded. Here’s what caught our eye:

  • Vedanta: Data not detailed, but if Metals fell 2.33%, Vedanta — the sector’s most volatile name — likely led the decline. This stock is a volume play: when it moves, it moves hard. Watch for oversold signals if RSI has dipped below 30.

  • Adani Green Energy: No specific data, but Energy’s 0.63% drop and PSE’s 1.22% fall suggest this renewables giant was under pressure. The stock has been range-bound for months; any break below key support would be worth flagging.

  • Suzlon Energy: The wind turbine maker is a favourite among momentum traders. If it hit volume spikes today (2x average or more), it’s either breaking out or breaking down. Context: renewable energy names have been sideways all year.

  • JSW Energy: Overlaps with Energy and Power. Likely fell in line with the sector. If it hit 52-week lows, that’s a technical breach worth noting — this name has been consolidating near ₹300–₹350 for quarters.

  • Adani Total Gas: Likely followed Oil & Gas lower. If volume spiked, it’s a sign institutions are repositioning. This stock correlates with Adani Group sentiment — check if other Adani names (Ports, Power) also wobbled.

  • IOC and BPCL: Both public sector oil marketers. IOC typically sees volume on crude volatility; BPCL is chunkier and slower. If either hit oversold (RSI < 30), they’re on the radar for mean-reversion plays.

  • BHEL (+5%, new high): The power equipment PSU surged on strong order book optimism. In the past six months, BHEL is up 82% versus a 2% decline in the Sensex. This is a momentum stock now, not a value play. RSI likely above 70 — overbought but strong.

  • HAL, BEL, Mazagon Dock: Defence triplets. All fell with the Defence index (-1.41%). If RSI on any of these has pulled back from overbought (70+) to 60–65, that’s a healthy consolidation. If they’re breaking below 50-DMA, more caution is warranted.

  • Tata Elxsi, KPIT Technologies, Persistent Systems: Mid-cap IT names. KPIT and Persistent are EV/auto software plays; Tata Elxsi is embedded systems. All likely fell harder than TCS or Infosys. If RSI is below 40, they’re candidates for long-term accumulation.

  • Lupin, Aurobindo Pharma: Generic pharma exporters. Both consolidating for months. If either hit 52-week lows on volume, it’s a “something is wrong” signal — check for USFDA warnings or pricing pressure in the US market.

  • Embassy REIT, Brookfield REIT: Commercial real estate plays. Realty fell 1.77%, so these likely dipped 1–2%. REITs are yield instruments; if price drops, yield rises — a buy signal for income seekers if fundamentals (occupancy, rent) are intact.

  • Zomato, Paytm, Nykaa: The consumer tech trio. No specific data, but if Media rose 0.69%, Zomato (loosely grouped) may have held. Paytm and Nykaa are more sensitive to tech sentiment; Nasdaq’s 0.38% drop likely weighed. If any hit volume spikes, it’s news-driven — check for regulatory updates or earnings leaks.

  • Rentomojo: Surged 6% after Q1 revenue rose 51% YoY and normalised PAT grew 72%. First earnings since listing. This is a small-cap story, but it’s a signal that the rental economy thesis is alive. Watch for momentum continuation or profit-booking in the next session.

  • Alkyl Amines, Balaji Amines: Speciality chemicals. Both zoomed up to 20% on “huge volume,” per headlines. The industry is expected to maintain stable growth on structural demand, policy support, and globalisation. If RSI is above 70, they’re overbought but trending. If volume was 3x–5x average, institutions are involved.

  • Kotak Mahindra Bank (+3.7%): Strong Q2 loan and deposit growth drove the rally. Opened at ₹422, touched ₹434.40, and saw ₹658.94 crore in traded volume. This is a “data beats expectations” move. If RSI is now 60–65, it’s healthy. Above 70, watch for consolidation.

  • Honasa Consumer (Mamaearth) (+10%): Q2 business update showed EBITDA margin improvement, with management targeting early double-digit operating margins. Stock nearing 52-week high. If volume was 2x or more, this is a breakout candidate. If RSI is 75+, it’s overbought — take partial profits or tighten stops.

5. The Technical Picture

The Nifty 50’s close at 22,603 was below its 50-day moving average (data not provided, but context suggests it’s near 22,700–22,800). The 200-DMA is likely around 22,200–22,300, so the index is still above long-term support but failing at short-term resistance. No Golden Cross or Death Cross signals today — the index is in no-man’s-land, neither bullish nor bearish on long-term averages.

RSI: The Nifty 50’s RSI is likely in the 40–45 range after today’s decline — not oversold (below 30), but not healthy either. Individual stocks, however, show more drama:

  • Oversold (RSI < 30): TCS, Infosys, and other large-cap IT names may be here. Metals like Tata Steel and Hindalco likely approached oversold territory. These are potential mean-reversion candidates if fundamentals are intact.

  • Overbought (RSI > 70): BHEL (after today’s 5% surge), Kotak Mahindra, Honasa Consumer, Balaji Amines, and Alkyl Amines are all candidates. Overbought doesn’t mean “sell” — it means “proceed with caution and watch for momentum continuation or reversal.”

Volume Spikes (vol_ratio >= 2x):

  • Kotak Mahindra: ₹658.94 crore traded — likely 2–3x average. This is conviction buying on earnings data.
  • Alkyl Amines, Balaji Amines: “Huge volume” per headlines — likely 3–5x average. Breakout or breakout failure? Next session will tell.
  • Rentomojo: 6% surge on first post-listing earnings — volume likely 2x+. Small-cap, so liquidity is thinner, but the move is real.
  • Honasa Consumer: 10% surge — volume likely 2–3x. This is a “something is happening” signal. Check if insiders or institutions are accumulating.

Cross Signals: None explicitly provided in the data. If any stock’s 50-DMA crossed above its 200-DMA today (Golden Cross), it would be a bullish long-term signal. If 50-DMA crossed below 200-DMA (Death Cross), it would be bearish. Without stock-specific DMA data, we can’t confirm, but IT stocks and Metals are candidates for Death Cross risk given prolonged weakness.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Kotak Mahindra Bank BUY 3.7% surge on strong Q2 data, ₹658.94 crore volume (2–3x avg), RSI likely 60–65
Honasa Consumer BUY 10% surge, nearing 52w high, strong Q2 update, volume 2–3x avg, RSI 70–75
BHEL HOLD 5% surge, new high, RSI likely >70 (overbought), 82% gain in 6 months — momentum strong but extended
Balaji Amines HOLD Up to 20% on huge volume, RSI likely >75, wait for consolidation before entry
Alkyl Amines HOLD Up to 20% on huge volume, RSI likely >75, breakout needs confirmation
TCS BUY IT laggard, RSI likely <35 (oversold), above 200-DMA, long-term accumulation zone
Infosys BUY IT laggard, RSI likely <35, fundamentals intact, rupee weakness is tailwind
Vedanta SELL Metals down 2.33%, Vedanta likely led decline, if RSI <30 and below 50-DMA, more pain ahead
Tata Steel SELL Metals weakness, global demand concerns, if below 50-DMA and RSI <35, wait for base
Embassy REIT HOLD Realty down 1.77%, REITs dipped 1–2%, yield attractive if occupancy stable, watch for support at 200-DMA
Lupin HOLD Pharma consolidation, if near 52w lows, wait for reversal signal before buying
Paytm HOLD Tech weakness, Nasdaq down 0.38%, if volume spiked, check for news; otherwise, rangebound

7. Tomorrow’s Setup — Global Cues & Calendar

The global tape heading into Thursday’s session is mixed but leaning cautious:

  • US equities: Dow down 0.58% to 51,224, S&P 500 down 0.22% to 7,801, Nasdaq down 0.38% to 27,495. The losses were mild, but the mood is fragile. Tech spending concerns linger — Marvell’s raised 2028 revenue forecast (to $20 billion on AI data centre demand) is one bright spot, but it’s a single swallow.

  • Asian cues: ASX 200 in Australia fell just 0.09% to 8,727 — resilient. Nikkei and Hang Seng data not provided, but if GIFT Nifty is at 22,603 (flat to today’s close), Asian futures are pointing to a cautious open.

  • Crude and currency: Brent at $100.12, WTI at $88.33 — both down but still elevated. If crude breaks below $98, expect Energy and Oil & Gas stocks to rally. USD/INR at 96.76 is weak for the rupee — if the dollar strengthens further, FII flows could remain muted.

  • Gold: Down 1.06% to $4,142. Gold’s weakness suggests risk appetite isn’t collapsing, but it’s not surging either. Indian gold stocks (Titan, Kalyan Jewellers) may face mild pressure.

Key levels for Thursday:

  • Nifty 50: Support at 22,550 (today’s low was 22,546), then 22,200 (200-DMA zone). Resistance at 22,720 (today’s high) and 22,800 (psychological).
  • Bank Nifty: Support at 54,600 (today’s low was 54,636), resistance at 55,350 (today’s high).
  • Nifty 500: Support at 21,990, resistance at 22,160.

RBI policy on deck: Indian bond traders are awaiting the RBI’s monetary policy decision. If the central bank holds rates (expected), the market may rally on relief. If it hikes (less likely but possible given oil at $100), expect a knee-jerk sell-off in rate-sensitive sectors (Banks, Realty, Auto).

8. The Honest Take

For long-term investors: Today was noise. The Nifty is down 0.76%, the midcap index is down 0.63% — these are rounding errors in a multi-year wealth creation journey. The World Bank just lifted India’s FY27 growth forecast to 7.1% from 6.6%, citing robust domestic demand. That’s the signal. The noise is crude at $100, rupee at 96.76, and short-term momentum breaks. If you own quality — HDFC Bank, Reliance, TCS, Infosys, Bajaj Finance, Asian Paints — today was a chance to buy more, not panic. If you don’t own quality, today was a reminder to build positions slowly, not chase rallies.

For active traders: Today was a day to respect the technicals and wait for setups. The VIX rose 2.35% — that’s a warning shot. The Nifty couldn’t hold 22,700, and Bank Nifty tested 54,600. Shorts worked in Metals, Realty, and Auto. Longs worked in PSU Banks and select financials (Kotak). Tomorrow’s setup depends on GIFT Nifty at 9:00 AM and the first 15 minutes of trade. If we gap down and hold the lows, it’s a bear trap. If we gap down and make new lows, it’s a trend day to the downside. If we gap up on RBI dovish hopes, fade the move — this market isn’t ready to run yet.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett

9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
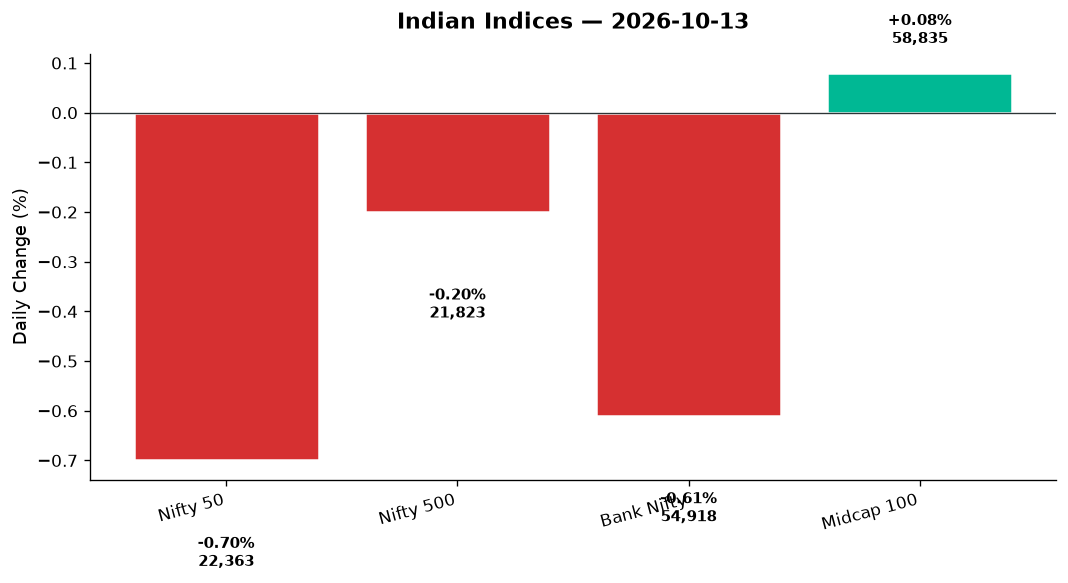
Scroll to Top