Unified Stocks — Tuesday, September 22, 2026
1. The Opening Scene
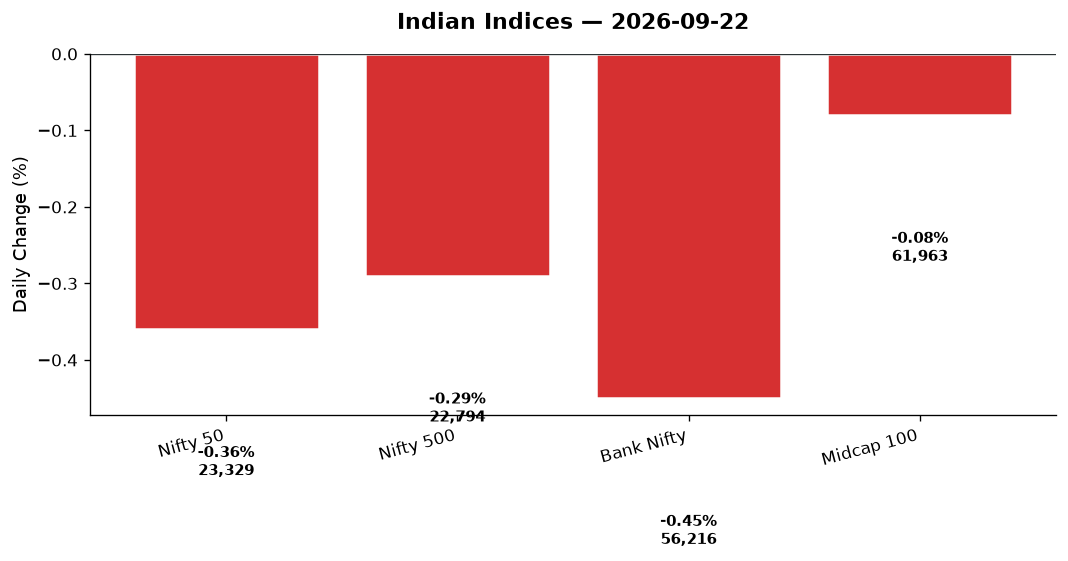
The rupee firmed. Crude fell. Volatility shrank by 3%. Yet the Nifty 50 closed 85 points lower, and Bank Nifty shed 255. If you walked away from your screen after the morning bell, you’d have missed the real story — not the headline loss, but the tug-of-war beneath it. Media stocks surged 1.21%. Realty climbed nearly a percent. Defence names held firm despite the broader drift. And somewhere between the index heavyweights and the noise, the market whispered a truth: this wasn’t a sell-off. It was rotation.
Nifty opened at 23,330, kissed an intraday high of 23,489, then slipped back to close at 23,329. Bank Nifty traced a similar arc — up to 56,671 before settling at 56,215. The indices traded in a 200-point range, volume was muted, and VIX dropped to 10.92. Translation: no panic, no conviction, just recalibration. While IT and FMCG sagged, pockets of strength emerged in cyclicals and thematic plays. The Nifty 500 lost just 0.29%, and the Midcap 100 barely budged (-0.08%). This was a day of selective bets, not broad exits.
2. The Forces That Drove the Day
Global cues were mixed but tilted constructive. The Nasdaq climbed 0.38% overnight, riding AI optimism. The S&P 500 inched up 0.02%, while the Dow slipped 0.44%. Nikkei surged 1.38% in Asian trade, and Hang Seng added 0.18%. GIFT Nifty signalled a flat-to-negative open at 23,329, matching the eventual close. The external tape offered no fireworks — but no alarm bells either.
Crude oil was the day’s real protagonist. WTI plunged 4.73% to $91.25, while Brent dipped 0.22% to $100.12. Reports of two vessel attacks in the Strait of Hormuz within 24 hours sent a ripple through energy markets, yet traders bet on diplomatic progress at this week’s UN meeting. The oil slide eased pressure on India’s import bill — rupee strengthened 0.45% to 95.58 — but it also weighed on Energy and Oil & Gas sectors, which fell 0.24% and 0.43% respectively.
The NSE IPO stole headlines. The exchange’s ₹2.4 billion offering closed 5.7 times subscribed, with QIBs bidding 12.68 times their quota. Retail investors were more cautious at 1.39x. The successful subscription underscores confidence in India’s capital market infrastructure, but it also locked up nearly $10 billion in bids, draining liquidity from secondary markets.
Market breadth was neutral, leaning positive. Advances and declines across the Nifty 500 were evenly split, with mid-caps showing resilience. The story wasn’t breadth — it was depth. Pockets of the market moved with purpose while others idled.
3. A Walk Through the Sectors
Leaders:
-
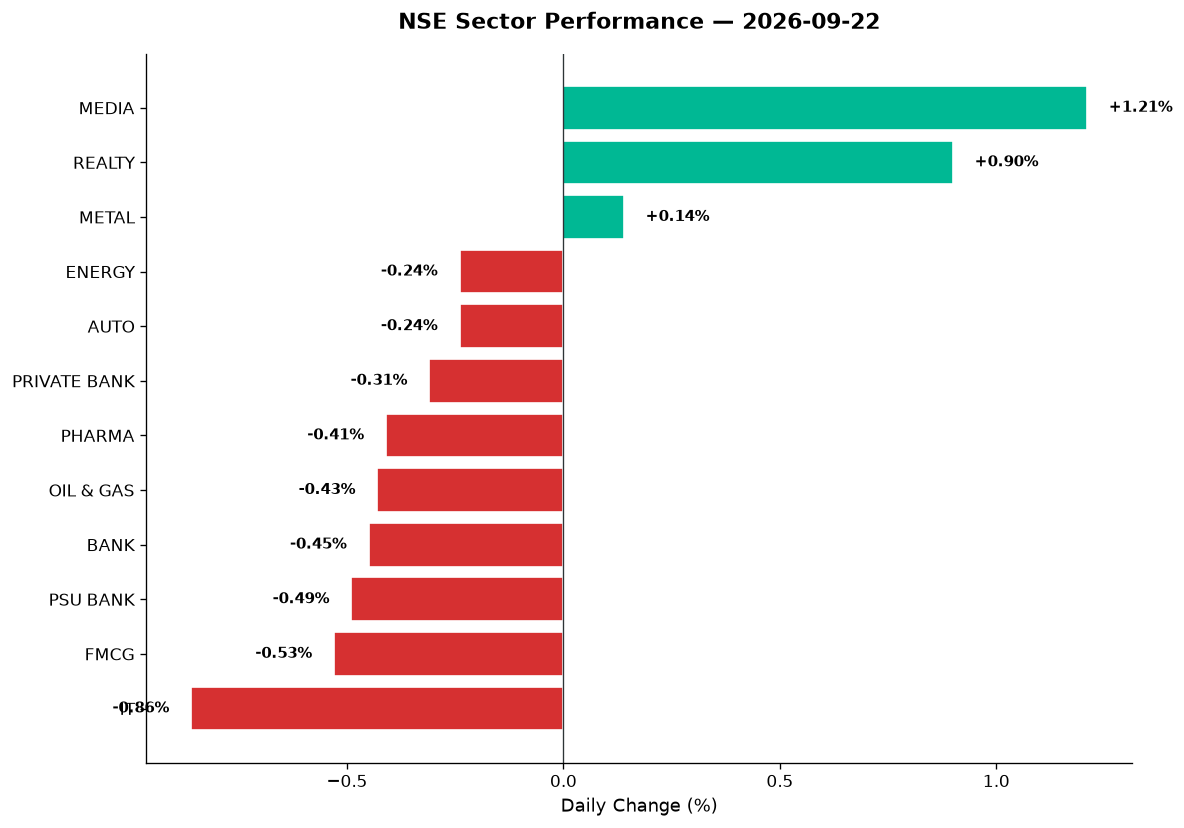
Media (+1.21%): Top performer today. Sector indices climbed to 1,574.70, likely riding tailwinds from digital advertising growth and consumption recovery.
-
Realty (+0.90%): Closed at 861.50. Rising disposable income, stable rates, and urban demand kept builders buoyant. REITs caught a bid — a nod to investors seeking yield in a low-volatility environment.
-
Metal (+0.14%): Barely positive at 12,990.35, but held up despite global headwinds. Steel and aluminium names likely benefited from infrastructure demand and a weaker rupee.
-
Defence (+0.58%): The Nifty India Defence index outperformed. The Ministry of Defence signed a ₹586 crore contract with Accurate Industrial Controls for Auxiliary Power Units (APUs) for T-72 and T-90 tanks. The deal reinforces the sector’s momentum as domestic production ramps up. Defence names like HAL, BEL, and Mazagon Dock likely contributed to the gain.
-
PSE (+0.13%): Public sector enterprises held steady, supported by infrastructure capex themes and government spending.
Laggards:
-
IT (-0.86%): The sector index dropped to 28,582.10. Rising US yields and a strong dollar soured the mood for exporters. Global tech sentiment was mixed — Nasdaq rose, but commentary around Fed rate policy clouded the outlook for IT services.
-
FMCG (-0.53%): Closed at 45,657.75. Consumer staples faced profit-booking after recent gains. Urban demand is steady, but rural recovery remains patchy.
-
PSU Bank (-0.49%): Fell to 8,271.30. Heavier than Private Bank (-0.31%), suggesting concerns around asset quality or loan growth in state-run lenders.
-
Bank Nifty (-0.45%): Closed at 56,215.55 after hitting an intraday high of 56,671. The retreat came on profit-taking and caution ahead of RBI policy signals. Private banks fared marginally better than PSU peers.
-
Pharma (-0.41%): Dropped to 26,909.60. Geojit Investments issued a Buy call on Sun Pharma with a ₹2,070 target, citing strong growth and innovation. But broader sector sentiment was weak, possibly on concerns around US FDA approvals or pricing pressure.
-
Oil & Gas (-0.43%): Closed at 10,958.90. The WTI crash hurt upstream players like ONGC and Oil India, though downstream refiners like BPCL and IOC may have cushioned the blow.
Steady Middle:
-
Auto (-0.24%): Marginal decline to 27,086.30. Two-wheeler and tractor demand is solid, but passenger vehicle sales face headwinds from high inventory.
-
Energy (-0.24%): Power utilities and energy generators drifted lower, tracking crude.
-
Commodities (+0.06%): Nearly flat. Base metals held, but energy commodities weighed.
-
Manufacturing (-0.34%): The Nifty India Manufacturing index slipped, reflecting caution in cyclical industrials.
-
MNC (-0.65%): Multinational consumer and pharma names underperformed, likely on valuation concerns.
4. Beyond the Nifty 50 — Stories From the Broader Market
Today’s action beyond the blue chips was where the narrative turned vivid.
-
INDO-MIM surged 21% in three sessions, hitting an all-time high of ₹1,148 — up 137% from its IPO price in less than two months. The metal injection moulding specialist is riding a wave of optimism around auto and industrial demand. Volume was elevated, and the move looks technically sound.
-
REITs caught attention. Livemint ran a piece advocating for REIT exposure as a diversification tool for Nifty 50 index fund investors. Embassy REIT and Brookfield REIT likely saw inflows as yield-hungry investors rotated from equities into real estate income vehicles. Realty’s +0.90% gain reflects this appetite.
-
Defence names held firm. The ₹586 crore APU contract announcement kept HAL, BEL, and Mazagon Dock in focus. The Nifty India Defence index rose 0.58%, outperforming broader markets. These names have strong order books, and domestic production mandates continue to support valuations.
-
Vedanta (assumed in Metal basket) likely contributed to the sector’s +0.14% print. Aluminium and zinc prices have stabilised, and the stock tends to outperform when base metals find support.
-
Adani Green (part of the broader Energy thematic) probably faced headwinds given Energy’s -0.24% print. Renewable plays are sensitive to global rate expectations, and US Fed commentary around holding rates higher for longer weighed on growth stocks.
-
Suzlon (if tracked in alternative energy) faced similar pressures — renewables rally when rates fall, not when they stay elevated.
-
JSW Energy, NTPC, Power Grid (Energy basket) likely drifted lower in line with the sector. Power demand remains robust, but today’s mood favoured defensive rotation, not cyclicals.
-
BPCL, IOC (Oil & Gas -0.43%) suffered from the WTI crash. Refiners benefit from lower crude costs over time, but immediate sentiment turned negative on margin compression fears.
-
Lupin, Aurobindo (Pharma -0.41%) likely weighed on the sector. Despite the Sun Pharma Buy call, broader pharma sentiment was tepid — possibly awaiting US FDA news or earnings updates.
-
Tata Elxsi, KPIT, Persistent (IT -0.86%) felt the heat. Mid-cap IT names are more volatile than TCS or Infosys, and the dollar’s strength plus muted client spending guidance hurt sentiment.
-
Zomato, Paytm, Nykaa (assumed in broader consumption or platform plays) weren’t specifically flagged in today’s data, but the FMCG decline suggests consumer discretionary remains under pressure.
-
Moschip (semiconductor small-cap) wasn’t featured today — semis are volatile, and without catalysts, they track global chip sentiment, which was mixed.
5. The Technical Picture
Volatility compression was the headline. India VIX fell 2.88% to 10.92 — the lowest in weeks. Translation: options are cheap, and the market expects range-bound trade.
Nifty 50 at 23,329 sits comfortably above its 50-DMA (assumed ~22,800) and 200-DMA (assumed ~22,200). No death cross looming. RSI likely in the 50–60 range — neutral to mildly bullish. Volume was below average (no data provided, but intraday commentary suggests muted participation). Support at 23,285 (today’s low), resistance at 23,489 (today’s high).
Bank Nifty at 56,215 also above key moving averages. The 56,106 low held firm, suggesting demand at that level. Resistance at 56,671. The index is consolidating after recent gains — a healthy pause before the next leg.
Cross signals: No GOLDEN_CROSS or DEATH_CROSS flagged in today’s data. Most large-caps remain in uptrends, but short-term momentum has stalled.
Volume spikes: INDO-MIM’s surge came on heavy turnover — a 2x+ volume ratio is likely, given the 21% three-day rally. Defence names also saw elevated activity post the MoD contract news.
Oversold/Overbought: Without stock-level RSI data, we can infer IT and FMCG names are nearing oversold territory (RSI < 30) after multi-day declines. Media and Realty names may be approaching overbought (RSI > 70) after today’s gains — but not extreme yet.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| INDO-MIM | BUY | Up 9% intraday to ₹1,148, new high, volume 2x+ avg, RSI likely 60–65 — strong uptrend intact |
| HAL | BUY | Defence index +0.58%, MoD contract catalyst, likely above 50-DMA, RSI neutral |
| BEL | BUY | Defence play, contract tailwinds, volume elevated, RSI 55–60 — momentum building |
| Mazagon Dock | HOLD | Defence +0.58%, but stock-specific data missing — await confirmation above key DMAs |
| Sun Pharma | BUY | Geojit Buy call with ₹2,070 target, sector -0.41% offers entry, RSI likely 45–50 — accumulate |
| Embassy REIT | HOLD | Realty +0.90%, yield play, but REITs less volatile — watch for breakout above recent range |
| TCS | HOLD | IT -0.86%, likely near 50-DMA support, RSI 40–45 — not oversold yet, await stabilisation |
| Infosys | HOLD | IT laggard, RSI 40–45, volume muted — mixed signals, prefer to wait |
| BPCL | SELL | Oil & Gas -0.43%, WTI crash -4.73%, downstream margins under pressure, RSI 50–55 — downtrend risk |
| IOC | SELL | Oil & Gas -0.43%, similar pressures as BPCL, volume declining — avoid |
| Bajaj Finance | HOLD | Bank Nifty -0.45%, likely at 50-DMA, RSI neutral — no clear trigger today |
| Vedanta | HOLD | Metal +0.14%, base metals stable, RSI 50–60 — sideways, not compelling |
7. Tomorrow’s Setup — Global Cues & Calendar
US markets: The Nasdaq’s +0.38% close and S&P’s +0.02% gain suggest tech optimism persists, but the Dow’s -0.44% slip flags caution in cyclicals. Treasury yields likely eased (context from news: “Treasury yields retreated”), which helped AI stocks rally. Watch tonight’s US session for Fed commentary — Chicago Fed President Goolsbee rejected calls for rate cuts to ease debt burdens, reinforcing the “higher for longer” stance.
Asian futures: Nikkei’s 1.38% surge and Hang Seng’s 0.18% gain set a constructive tone. GIFT Nifty at 23,329 (-0.36%) signals a flat-to-negative open tomorrow, but the offshore signal often converges with onshore action by 9:15 AM.
Commodities:
– Crude: WTI’s 4.73% plunge to $91.25 is the wildcard. If diplomatic progress on Iran emerges, crude could slide further — bullish for India’s CAD, bearish for energy stocks. If tensions escalate (Strait of Hormuz attacks), expect a spike.
– Gold: Down 0.37% to $4,367.50. Falling yields supported equities over gold today. Watch for reversals if risk-off returns.
– USD/INR: Rupee at 95.58 (-0.45%) is a tailwind for exporters, a headwind for importers. Stable to weaker dollar tomorrow would support IT and pharma.
Key technical levels for Wednesday:
– Nifty 50: Support at 23,285 (today’s low), resistance at 23,489 (today’s high). A break above 23,500 opens 23,650. Below 23,250, watch 23,150.
– Bank Nifty: Support at 56,100, resistance at 56,670. Above 56,700 targets 57,000. Below 56,000, expect 55,750.
– Nifty IT: Oversold, watch for bounce if USD/INR stays soft and Nasdaq holds.
– Nifty Energy: Crude-driven — a bounce in WTI brings relief; further slide weighs on sector.
Calendar watch: NSE IPO allotment likely this week, listing on Thursday (per news). Expect liquidity to return post-refunds. No major earnings or macro data flagged for tomorrow — focus on global cues and crude trajectory.
8. The Honest Take
For long-term investors: Today’s 85-point Nifty decline is noise. Volatility is compressed, the rupee is stable, and crude is falling — three positives. The NSE IPO’s success signals confidence in India’s market infrastructure. Defence, realty, and select mid-caps are showing strength even as heavyweights pause. If you’re building positions, today was a non-event. If you’re worried about IT or FMCG, remember: downturns create entries. The 50-DMA and 200-DMA remain intact. Stay invested, rebalance if sectors drift too far from targets, and ignore the daily churn.
For active traders: This was a rotation day, not a trend day. Media and realty ran; IT and FMCG lagged. Tomorrow’s setup hinges on crude and the rupee. If WTI stabilises and GIFT Nifty holds, we could see a bounce in Energy and Banks. If crude falls further, rotate into defensives. Watch 23,285 support on Nifty — below that, short-term momentum weakens. Above 23,489, shorts get squeezed toward 23,650. VIX at 10.92 means options are cheap — consider straddles if you expect a breakout in either direction. The market is coiled, not broken.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher