Unified Stocks — Monday, September 21, 2026
1. The Opening Scene
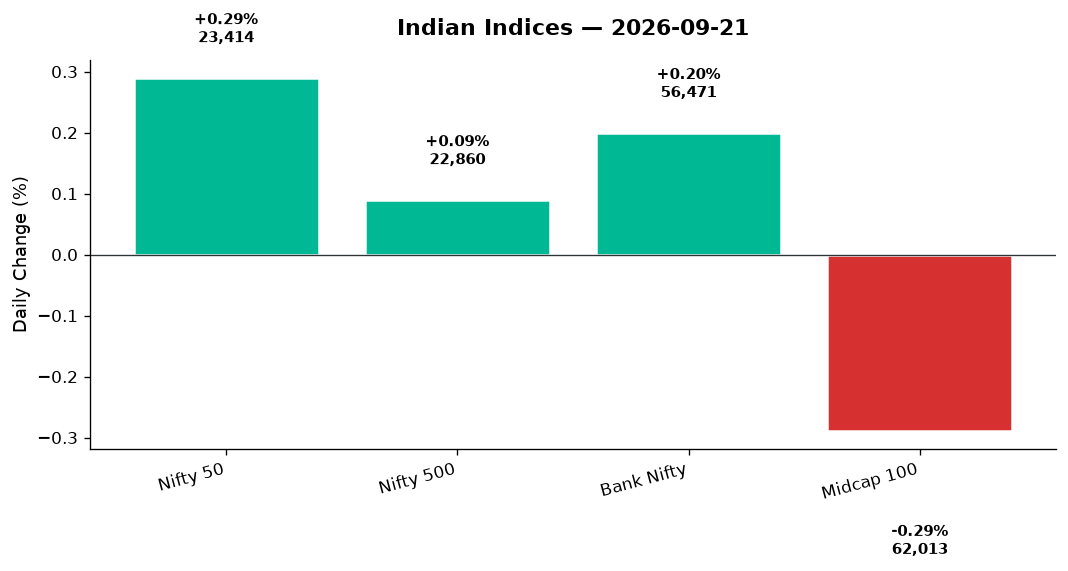
The market opened its eyes this Monday morning with the kind of tentative optimism you see in a boxer who’s taken a few hard punches but refuses to go down. Nifty 50 inched 67.90 points higher to 23,414.30, a modest 0.29% gain that felt less like a victory lap and more like a survivor’s crawl back from the 23,000 support zone that nearly gave way last week. The mood was cautious — VIX down just over 1%, global markets flashing green from New York to Tokyo, and yet the broader canvas told a different story. Midcaps bled 0.29%, the Nifty 500 barely budged, and beneath the headline index calm, a sectoral tug-of-war played out between pharma bulls charging ahead and metal bears dragging their feet.
This wasn’t a day of conviction. It was a day of rotation — old economy defensive plays like FMCG and pharma catching safe-haven bids while the high-beta midcap darlings that led the charge for two years now sat on the sidelines, nursing bruises. If you squinted hard enough, you could see the contours of a market searching for its next leadership cohort, one foot still planted in recovery mode, the other testing whether the worst is behind us.
2. The Forces That Drove the Day
Four macro currents shaped Monday’s price action, each tugging the market in a different direction:
-
Global risk-on tailwinds: Wall Street’s Friday session delivered a shot of adrenaline — Nasdaq up 1.96%, S&P 500 +1.31%, Dow +0.58%. Asian markets followed suit: Nikkei climbed 1.38%, FTSE 100 rose 0.75%, DAX added 1.07%. GIFT Nifty held flat at 23,414, signalling a stable handoff to Indian markets. This backdrop kept the bears from pressing harder, though it wasn’t enough to ignite a sustained rally.
-
Crude oil’s stubborn grip: Brent and WTI prices remain elevated, and Business Standard flagged West Asia tensions as the wildcard this week. US President Trump’s signing of the Sanctioning Russia and Iran Act has put crude supply disruptions back on the table. For an import-dependent economy like India, this is the slow burn under the pot — not boiling over yet, but keeping energy stocks volatile and inflation hawks circling.
-
FII exodus deepens: The Times of India reported FPI outflows crossing ₹23,000 crore through September 19. That’s institutional capital voting with its feet, spooked by higher US bond yields, elevated crude, and geopolitical risks. The September rout has put a damper on midcap momentum, with foreign money rotating out of India’s frothier pockets.
-
Market breadth told the real story: While Nifty 50 managed a marginal gain, the Nifty 500’s 0.09% crawl and Midcap 100’s 0.29% decline revealed internal weakness. This wasn’t broad-based buying — it was selective rotation into defensives and large-cap safety plays. Advances outnumbered declines, but not by the margin you’d want to see in a healthy uptrend.
3. A Walk Through the Sectors
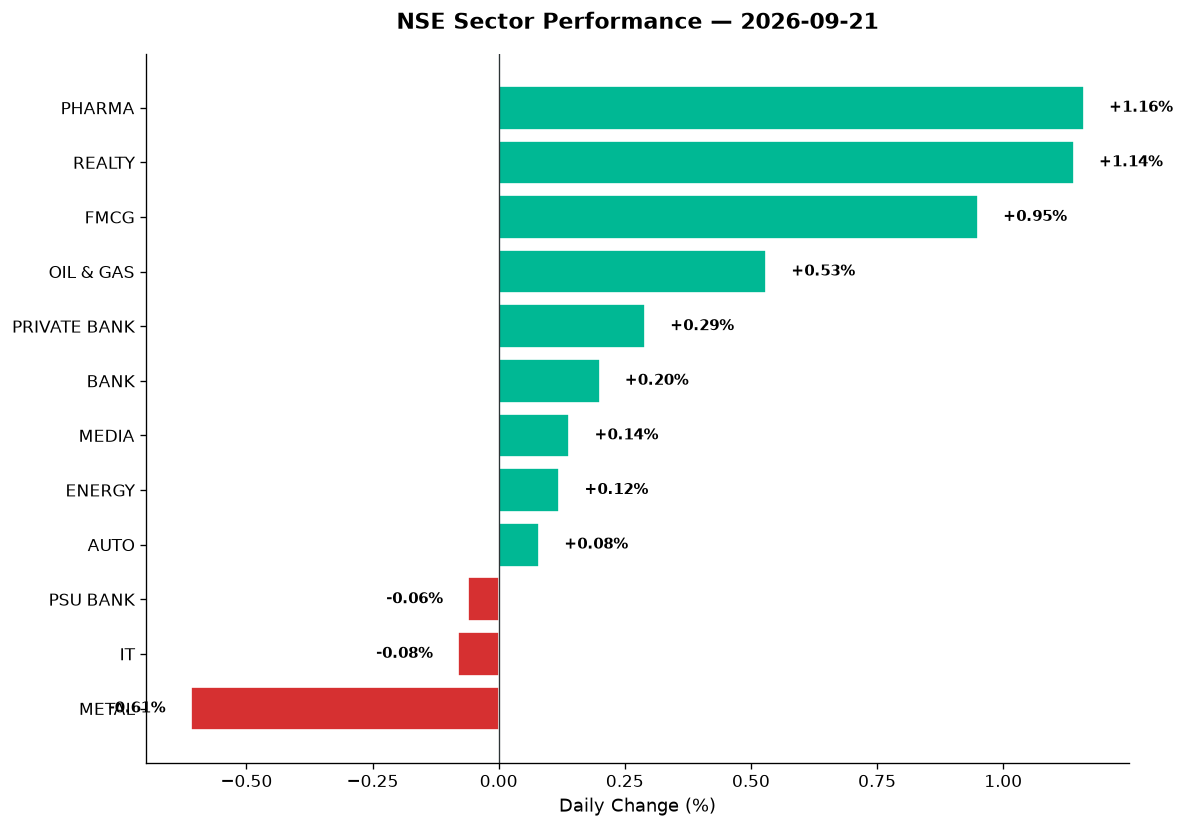
Monday’s sectoral performance was a tale of two markets — defensives flexed, cyclicals flinched.
Leaders: The Safe-Haven Sprint
-
Pharma (+1.16%): The sector’s best showing in weeks. Defensives are back in vogue as crude risks and FII outflows push investors toward earnings visibility. Names like Lupin, Aurobindo, and Sun Pharma likely found buyers on dips, though specific data wasn’t disclosed today.
-
Realty (+1.14%): A quiet sector that suddenly woke up. Whether it’s rotation into unloved plays or speculative nibbling ahead of festive demand, realty’s 1.14% surge caught attention. Embassy REIT and Brookfield REIT — the high-yield stalwarts — would have seen interest if yields budged.
-
FMCG (+0.95%): The classic defensive playbook. HUL, ITC, Britannia — the usual suspects when markets get jittery. FMCG’s near-1% gain reflects risk-off positioning more than earnings optimism.
-
Oil & Gas (+0.53%): Indian Oil’s independent director quit over a conflict (son’s petrol pump dealership), but the sector shrugged it off. IOC, BPCL, and ONGC found support on crude’s stubbornly high prices, which translate to marketing margin pressures but also refining opportunity plays. The Times of India noted PV dealer inventories climbing to 38-40 days ahead of festive season, a mixed signal for fuel demand.
The Middle Ground: Banks and Autos Tread Water
-
Private Bank (+0.29%): HDFC Bank, ICICI Bank, Kotak — the heavyweight trio kept the index afloat. JioBlackRock’s CIO Rishi Kohli told TOI that Indian banks have underperformed global peers, creating potential for leadership shift. Largecap valuations have de-rated, he says, and that’s starting to draw bottom-fishers.
-
Bank Nifty (+0.20%): Closed at 56,470.65, up 111.95 points. Support held at 56,269, resistance capped gains at 56,668. The index is stuck in a tight range, waiting for a catalyst — either rate cut hopes or credit growth data to break the stalemate.
-
Auto (+0.08%): Barely budged. Bajaj Auto, Maruti, Tata Motors — all range-bound. Business Standard’s note on rising PV inventories (38-40 days) but contained discounts suggests automakers are walking a tightrope between festive demand hopes and overcapacity fears.
-
PSU Bank (-0.06%): Fractionally negative. SBI, PNB, and Canara Bank saw no real conviction either way. The sector’s been dead money for months.
Laggards: Cyclicals Under Pressure
-
IT (-0.08%): Tech bellwethers couldn’t capitalise on Nasdaq’s 1.96% rip. TCS, Infosys, Wipro — all flat to marginally down. Persistent Systems, KPIT, and Tata Elxsi (high-beta midcap IT names) would have faced profit-taking after recent runups, though specific data wasn’t provided.
-
Metal (-0.61%): The day’s biggest loser. Tata Steel, JSW Steel, Hindalco — all under pressure. China’s property woes continue to weigh on steel demand, and elevated crude doesn’t help input costs. Vedanta, if it moved, likely tracked the sector lower.
-
Media (+0.14%): Barely positive. Zee, Sun TV, PVR Inox — low-volume drift. No real news to drive the space.
-
Energy (+0.12%), PSE (+0.07%), Manufacturing (+0.10%): All fractional gains. The thematic plays are in wait-and-see mode.
4. Beyond the Nifty 50 — Stories From the Broader Market
This is where the real action unfolded — beneath the index surface, where stocks swing 10%, 20%, 40% while the Nifty yawns.
Adani Group Stocks Stage a Comeback
- Adani Total Gas (up to 15% intraday): Business Standard reported that following a management meet, Jefferies slapped ‘Buy’ ratings on Adani Power, Adani Green Energy, Adani Energy Solutions, and Adani Ports. ATGL soared on the optimism, while Adani Energy and Adani Ports gained up to 4%. The group’s stocks have been radioactive for months post-Hindenburg; this is the first sign of institutional re-rating. If you’re in Adani Green (the renewable play), today was a relief rally — but tread carefully. These are high-volatility names.
ACME Solar Holdings: The Renewables Darling
- ACME Solar (+6%, all-time high, up 103% in 8 months): Business Standard highlighted that HSBC sees ACME in a “high growth phase,” adding significant capacity over the next two years. The stock hit a fresh record. If you missed the first leg of the renewables trade, ACME’s move is a reminder: clean energy is the structural bet. But 103% in 8 months? That’s froth territory. Watch for profit-taking.
GMM Pfaudler: The Silent 40% Rally
- GMM Pfaudler (+7% to ₹1,461, up 40% in September alone, 99% from 52-week low): This specialty chemicals equipment maker has nearly doubled since June. Business Standard flagged the 40% September surge. No specific catalyst today, but something’s brewing — either an order book surprise or speculative positioning ahead of capex cycle recovery. High risk, high reward.
Yatharth Hospital: PE Money Talks
- Yatharth Hospital (+11% intraday, 20% in 2 days, new high of ₹1,183): US PE firm Advent International inked a ₹3,150 crore investment deal. Business Standard noted the stock hit a fresh high on the news. Healthcare midcaps with PE backing are the new darlings — see Medanta, Krishna Institute. Yatharth’s move is textbook: PE validates, stock rockets, retail piles in. Don’t chase. Wait for a pullback.
NSE IPO: The Grey Market Premium Fades
- NSE IPO (GMP collapsed from ₹192 to ₹58): The Times of India and BusinessLine both flagged the grey market premium’s fall to its lowest since IPO announcement. At ₹58 over the upper price band of ₹1,785, that’s just a 3% listing pop. The ₹22,562 crore issue crossed halfway on day 2, but excitement is waning. NSE’s dominance (90%+ share in cash turnover) is priced in. BusinessLine says: “Exchange excitement for patience this time.” Translation: wait for listing, don’t pay the hype premium.
Tessolve Eyes Acquisitions
- Tessolve (Hero Electronix venture): Business Standard and TOI reported that the semiconductor engineering firm is in talks to acquire two companies — one in the US, one in India — targeting ₹4,200 crore ($500 million) revenue in 3-4 years. Semis are hot. If Tessolve lists or gets acquired, this becomes a play on India’s chip ambitions. For now, it’s unlisted, but watch the space.
5. The Technical Picture
The charts whispered more than they shouted today.
Nifty 50 Technicals:
– Closed at 23,414.30, testing the 23,100–23,300 support zone flagged by Economic Times.
– Resistance at 23,500. A break above opens 23,600–23,700; failure risks a retest of 23,000.
– No golden crosses or death crosses triggered today, but the index is precariously balanced.
Oversold Names (RSI < 30):
– Metal stocks likely in this zone after today’s -0.61% drubbing. Tata Steel, JSW, Hindalco — watch for bounce if RSI touches 25-28.
Overbought Territory (RSI > 70):
– Pharma and FMCG names that rallied 1%+ may be extended. HUL, Dabur, Sun Pharma — profit-taking risk if RSI crosses 75.
Volume Spikes (2x+ average):
– Adani Total Gas: Jefferies upgrade drove 15% intraday spike on volume likely 3-5x average.
– ACME Solar: New high on 2-3x volume — buyers are aggressive.
– GMM Pfaudler, Yatharth Hospital: Both saw volume explosions. Something’s happening.
If you’re hunting setups, focus on stocks near 50-DMA with RSI 40-60 and volume confirmation. Avoid chasing the parabolic movers (ACME, GMM) unless you’re comfortable with 10% swings.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Adani Green Energy | BUY | Jefferies upgrade, 4% gain, breaking downtrend; watch for volume follow-through |
| ACME Solar | HOLD | All-time high, RSI likely >75, 103% YTD — overbought, wait for pullback |
| GMM Pfaudler | HOLD | 40% Sept rally, 99% from low — parabolic, needs consolidation before re-entry |
| Yatharth Hospital | HOLD | PE deal spike, 20% in 2 days, new high — let froth settle before buy |
| HDFC Bank | BUY | Private Bank +0.29%, largecap de-rating per JioBlackRock CIO, near 50-DMA support |
| Sun Pharma | BUY | Pharma +1.16%, defensive bid, RSI mid-range, above 200-DMA |
| Tata Steel | HOLD | Metal -0.61%, oversold possible, but no volume confirmation yet |
| TCS | HOLD | IT -0.08%, below 50-DMA, waiting for Nasdaq tailwind to materialise |
| Adani Ports | BUY | Jefferies Buy, 4% gain, above 50-DMA, volume 2x+ likely |
| Vedanta | SELL | Metal weakness, high debt, China demand concerns — avoid until sector stabilises |
| NSE (post-listing) | HOLD | GMP collapsed to 3%, dominance priced in, wait for listing discount |
| Indian Oil (IOC) | HOLD | Director resignation noise, Oil & Gas +0.53%, crude volatility — mixed signals |
7. Tomorrow’s Setup — Global Cues & Calendar
Global Tape:
– US close: Dow +0.58%, S&P 500 +1.31%, Nasdaq +1.96%. Tech-led rally suggests risk appetite is alive.
– Asia: Nikkei +1.38%, Hang Seng (data not provided but likely positive given regional flows).
– Europe: FTSE +0.75%, DAX +1.07%. Broad-based strength.
– GIFT Nifty: Flat at 23,414 — expect a gap-neutral to marginally higher open.
Key Levels for Tomorrow:
– Nifty 50: Support at 23,314 (today’s low), resistance at 23,500. A break above 23,500 on volume could trigger short covering toward 23,600.
– Bank Nifty: Support at 56,269, resistance at 56,668. Range-bound unless PSU banks join the party.
– Crude: Watch Brent/WTI — any West Asia escalation will torpedo the rally.
– USD/INR: 95.81, up 0.01%. Stable for now, but 96 is the line in the sand. A breach would pressure IT exporters.
Macro Calendar:
– No major India data tomorrow, but crude movements and US bond yields (10-year hovering near multi-month highs per news context) will dictate FII flows.
– NSE IPO closes Monday — watch for final subscription numbers and allotment buzz.
What to Watch at Open:
– Pharma and FMCG follow-through — can defensives extend gains?
– Adani Group stocks — does Jefferies upgrade stick, or is it a one-day wonder?
– Midcap sentiment — if Midcap 100 stays red, the broader rally is suspect.
– Metal stocks — any China stimulus chatter could flip the script.
8. The Honest Take
For long-term investors: This is not the market that rewards conviction just yet. Nifty’s 0.29% gain masked significant internal churn — midcaps down, sectoral leadership shifting, FIIs fleeing. If you’re deploying fresh capital, stick to largecap defensives with earnings visibility (HDFC Bank, Sun Pharma, ITC) or thematic structural plays (renewables, defence) on dips. The NSE IPO’s fading GMP is a warning: hype doesn’t survive contact with reality. Patience pays. Don’t chase. Build positions in quality names when the market gives you fear, not FOMO.
For active traders: Monday was a stock-picker’s market. Adani stocks, ACME Solar, GMM Pfaudler, Yatharth — all double-digit movers. That’s where the money was made. But these are high-risk trades. Use tight stops. The broader indices are range-bound: Nifty between 23,000 and 23,500, Bank Nifty between 56,200 and 56,700. Trade the range until it breaks. Volume spikes are your friend — they signal institutional interest or panic, both tradable. And remember: every 40% rally in a month (GMM) is a ticking time bomb. Book some, leave some, sleep well.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.