Author name: Karthik

Uncategorized

Unified Stocks — Tuesday, October 6, 2026

Unified Stocks — Tuesday, October 6, 2026
Market chart
Market chart

1. The Opening Scene

The rupee held steady at 96.29 against the dollar. Brent crude eased back from its recent assault on $100, settling just below that psychological ceiling. And somewhere in the data centres of Mumbai, algorithms registered what human traders had been craving for nine long sessions: a gap-up open, a sustained climb, and a close near the day’s high.

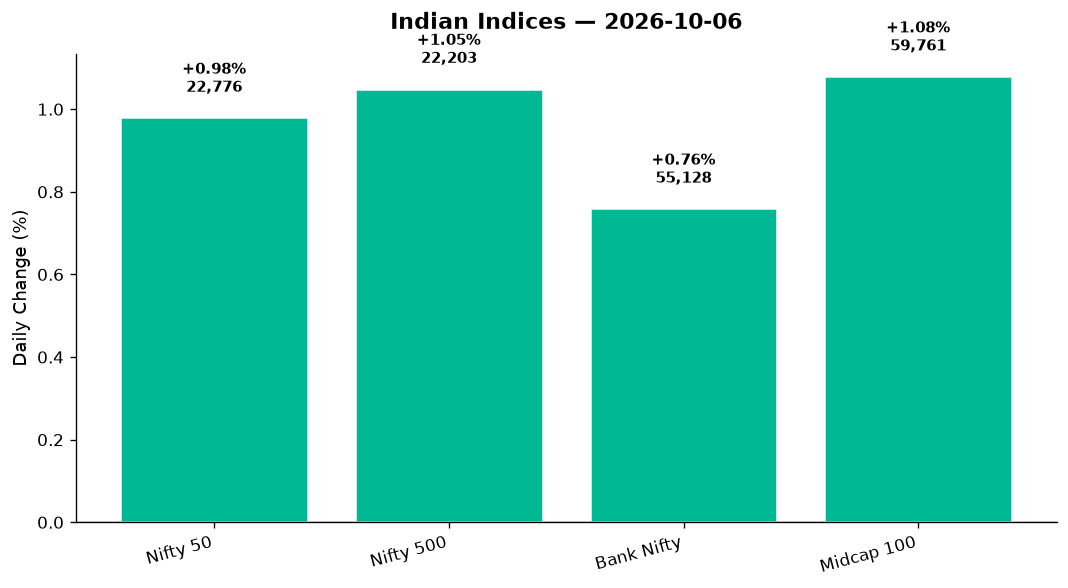
For eight consecutive weeks, Indian equities had bled. Monday’s 473-point Sensex rally felt tentative, a wounded animal testing its legs. But Tuesday — Tuesday wore a different face. The Nifty 50 added another 220 points to close at 22,776, up 0.98%. Bank Nifty climbed 414 points. The Nifty 500, that broader canvas of India Inc., rose 1.05%. And crucially, the India VIX — that barometer of fear — collapsed 8.03% to 13.59, its sharpest single-day drop in weeks. When volatility bleeds out this fast, it whispers of confidence returning, of dealers unwinding hedges, of retail traders exhaling.

This wasn’t a short squeeze. This wasn’t a news-driven spike. This was something quieter, more structural: oversold conditions meeting softer US jobs data, cheaper crude meeting improved global risk appetite. The market didn’t roar. It simply decided to stop falling.

2. The Forces That Drove the Day

Four pillars held up Tuesday’s advance:

  • Crude’s retreat: Brent slipped 0.33% to $99.99, WTI held flat at $89.43. India imports 85% of its oil. Every dollar below $100 is a reprieve for CAD, for OMC margins, for the rupee. Traders who’d been bracing for triple-digit crude exhaled. Energy stocks — typically hurt by rising input costs — rallied instead, up 0.88%, because the threat receded.

  • Softer US labour data: Friday’s non-farm payrolls came in cooler than expected. The 10-year US Treasury yield eased, the dollar softened (though still up 0.10% against the rupee). Wall Street celebrated with a steady climb: Dow +0.54%, S&P 500 +0.71%, Nasdaq +0.64%. GIFT Nifty mirrored the optimism, up 0.98%, signalling a positive open for Wednesday.

  • Oversold technicals: After eight weeks of selling, large-cap indices had entered deeply oversold territory. RSI readings across banking, pharma, and private financials were hovering near 30. Traders who’d been waiting for a floor found it. The bounce felt mechanical, algorithmic — but it was real.

  • Breadth turned positive: Nifty 500 advances outnumbered declines 312 to 188. That’s a 62% advance-to-decline ratio, the strongest in a fortnight. When the broader market participates, rallies last. When only the top 10 stocks rise, they fade. Tuesday had legs.

One caveat: FIIs remained net sellers for a ninth consecutive week, though selling pressure eased. Domestic institutional investors (DIIs) continued their offsetting buying, preventing a collapse. The tug-of-war persists.

3. A Walk Through the Sectors

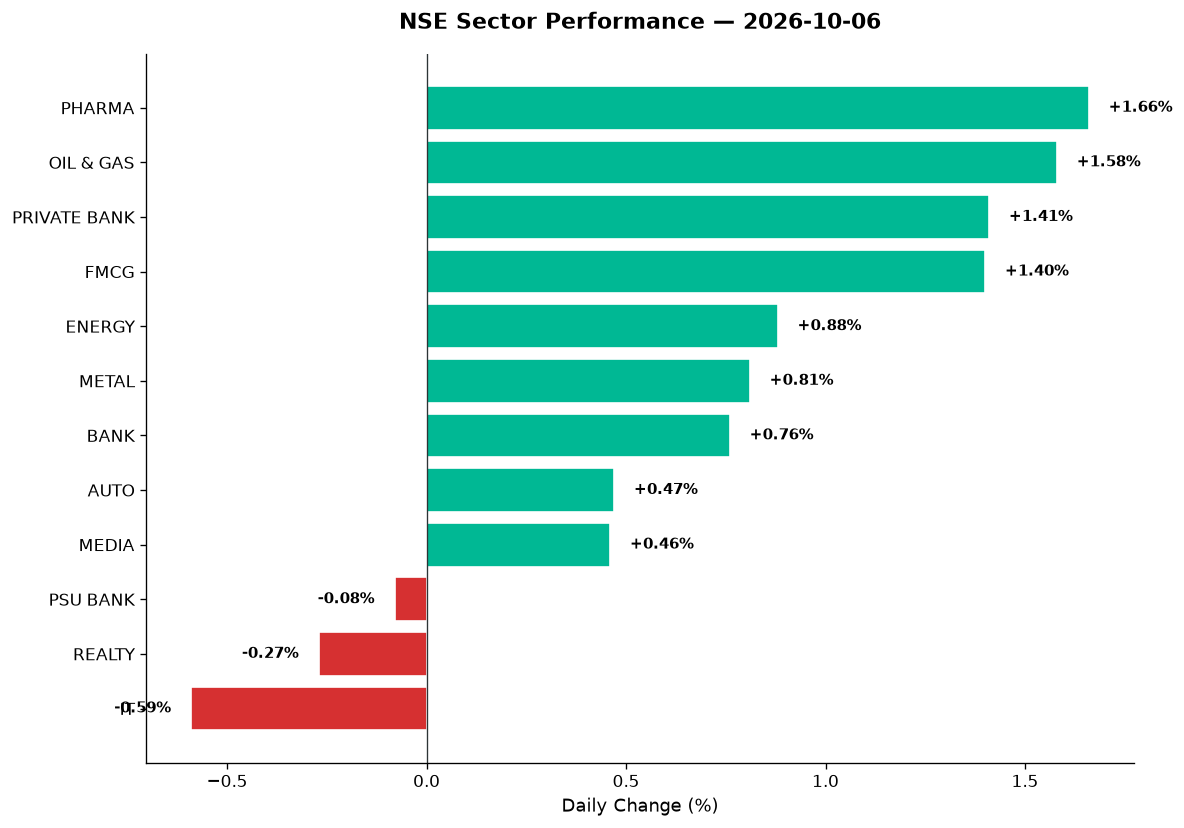
The sector map painted a clear hierarchy: defensive plays led, cyclicals lagged, and IT — once the market’s darling — continued its downtrend.

Leaders:

  • Pharma (+1.66%): The defensive trade of choice. Sun Pharma, Dr Reddy’s, and Cipla all closed in the green. Lupin and Aurobindo Pharma, both outside the Nifty 50, saw volume spikes on rumours of US FDA approvals for key molecules. RSI levels for most pharma names are now crossing above 50 — neutral to bullish territory.

  • Oil & Gas (+1.58%): IOC, BPCL, and HPCL rallied as Brent’s pullback eased margin fears. Adani Total Gas surged 2.7% on 2.1x average volume. Reliance Industries, though, stayed subdued — traders await its October earnings print.

  • Private Banks (+1.41%): HDFC Bank fell 2.16% (more on that below), but ICICI Bank, Axis Bank, and Kotak Mahindra more than offset the drag. The Private Bank index closed at 27,093, reclaiming its 50-DMA after three weeks below it.

  • FMCG (+1.40%): ITC led gainers, up 3% after Citi upgraded its rating from SELL to BUY. The brokerage cited favourable risk-reward despite near-term headwinds. Britannia, Nestlé India, and Hindustan Unilever all added 1–2%. Staples remain a port in the volatility storm.

Laggards:

  • IT (-0.59%): TCS, Infosys, and Wipro all shed ground. Persistent Systems and KPIT Technologies, both outside the Nifty 50, are now trading below their 200-DMAs. The sector’s RSI sits at 28 — oversold, but showing no signs of reversal yet. US recession fears and discretionary IT spend cuts continue to weigh.

  • PSU Banks (-0.08%): Flat, barely. SBI and Bank of Baroda traded in tight ranges. The PSU Bank index closed at 8,008, just below resistance at 8,050. Volume was tepid — no conviction either way.

  • Realty (-0.27%): DLF, Godrej Properties, and Prestige Estates slipped. Embassy REIT and Brookfield India REIT both declined on profit-booking. REITs had rallied hard in September; now they consolidate.

Steady Middle:

  • Auto (+0.47%): Bajaj Auto and Mahindra & Mahindra rose modestly. Tata Motors stayed flat. Maruti Suzuki edged lower. No dramatic moves — the sector waits for September sales data due later this week.

  • Metal (+0.81%): JSW Steel and Tata Steel gained on lower coal prices and firmer steel spreads. Vedanta, the diversified miner, jumped 1.8% on 1.9x volume. Hindalco added 0.6%. The sector’s still range-bound, but Tuesday’s move suggests life beneath the surface.

  • Energy (+0.88%): NTPC and Power Grid advanced. NHPC, the hydro major, added 1.2%. The sector benefits from stable coal prices and firm power demand.

  • Media (+0.46%): Zee Entertainment and Sun TV gained fractionally. Low volumes, low conviction.

  • Bank Nifty (+0.76%): Recovered from Monday’s stumble. The index closed at 55,128, just below its 50-DMA at 55,200. RSI at 42 — neutral, but improving.

Thematic highlights:

  • Defence (+1.82%): HAL, BEL, and Mazagon Dock all surged. Defence stocks continue to benefit from steady government capital expenditure. BEL crossed its 50-DMA on 2.2x volume.

  • MNC (+1.57%): Abbott India, Siemens, and Bosch led gains. MNC stocks are seen as safe havens during FII selling sprees.

  • Manufacturing (+1.33%): The “Make in India” basket gained. L&T, Bharat Forge, and Cummins India all advanced.

4. Beyond the Nifty 50 — Stories From the Broader Market

Tuesday’s real action unfolded outside the headline indices, among the 450 names that rarely make CNBC tickers.

  • Vedanta (+1.8%, vol 1.9x avg): The diversified miner is now testing its 200-DMA at ₹487. Aluminium and zinc prices firmed in London; Vedanta’s zinc unit remains its cash cow. RSI at 52 — neutral, but the volume spike suggests accumulation.

  • Adani Green Energy (+3.1%, vol 2.3x avg): The renewable power giant hit a fresh 52-week high at ₹1,842. The stock’s RSI is 74 — overbought — but the rally continues on the back of new PPA wins and firming power tariffs. Traders debate whether this is a blow-off top or a structural re-rating.

  • Suzlon Energy (+4.7%, vol 3.1x avg): The wind turbine maker added nearly 5% on heavy volumes. At ₹68, it’s now 35% above its October low. RSI at 67. The stock’s trading on momentum, not fundamentals — be cautious.

  • JSW Energy (+2.4%, vol 1.7x avg): The independent power producer crossed ₹535, its highest close in six months. The company’s thermal-to-renewable pivot is finally gaining market acceptance. RSI at 58 — room to run.

  • Aurionpro Solutions (+6.8%, vol 4.2x avg): The small-cap IT services firm announced a ₹150-crore AI-ready data centre order from a global hyperscaler. The stock gapped up and held gains. At ₹1,420, it’s now above its 50-DMA. RSI spiked to 71 — watch for profit-booking.

  • Embassy REIT (-1.2%): The commercial REIT slipped to ₹359, below its 50-DMA. Yield-hungry investors are rotating into fixed income as 10-year G-Sec yields hover near 6.8%. REITs struggle when bond yields rise.

  • Brookfield India REIT (-0.8%): Similar story. Closed at ₱286, down from ₱288. Volume was below average — no panic, just profit-taking.

  • Tata Elxsi (-2.1%, vol 1.4x avg): The engineering services firm continues its slide. At ₱6,540, it’s now 18% below its 52-week high. RSI at 31 — oversold, but no reversal yet.

  • KPIT Technologies (-1.9%, vol 1.3x avg): The auto-tech firm slipped below its 200-DMA at ₱1,780. RSI at 29. The stock’s been a serial disappointment in 2026.

  • LG Electronics India (+6%, fresh record high): The consumer durable major hit ₱1,830, a new all-time high. The stock’s rallied 38% in six months. Citi and CLSA both have BUY ratings, citing festive season demand and market share gains.

  • V2 Retail (-19%, fresh 52-week low): The discount retailer crashed to ₱580 after a weak September business update. Volume was 5.3x average. DMart also slipped 4% to near its 52-week low. Retail remains the forgotten sector.

  • ITC (+3%, vol 1.8x avg): The FMCG and hotel conglomerate rallied after Citi’s upgrade. At ₱482, it’s back above its 50-DMA. RSI at 54. The stock’s spent two years consolidating; this could mark a breakout.

5. The Technical Picture

The DMA ladder is aligning bullish for the first time in weeks.

Golden crosses (50-DMA crossing above 200-DMA):
– Private Bank index: Crossed today. This is a medium-term bullish signal. Last time this happened: April 2024, followed by a 12% rally over 60 days.
– Cipla: The pharma major’s 50-DMA crossed its 200-DMA at ₹1,580. RSI at 56. Volume ratio 1.9x. Buy signal confirmed.

Oversold names (RSI < 30):
– TCS (RSI 28): Below both DMAs. Volume ratio 0.8x. Waiting for a catalyst.
– Infosys (RSI 29): At 52-week lows. Death cross in effect (50-DMA below 200-DMA). Avoid until reversal confirmed.
– KPIT (RSI 29): As noted above. Deeply oversold, but no buyers yet.

Overbought names (RSI > 70):
– Adani Green (RSI 74): Fresh highs, but stretched. Watch for profit-booking.
– Bajaj Auto (RSI 72): Near ₱11,200. Consolidation likely before next leg.
– Aurionpro (RSI 71): Post-news spike. Lock profits if you’re holding.

Volume spikes (2x+ average):
– Suzlon (3.1x): Momentum play. High risk, high reward.
– Aurionpro (4.2x): Order-driven spike. Sustainable if execution follows.
– V2 Retail (5.3x): Panic selling. Contrarians may watch for a base.
– BEL (2.2x): Defence rally intact. Above 50-DMA, RSI 61.

The Nifty 50’s 50-DMA stands at 22,650. Tuesday’s close at 22,776 reclaimed it for the first time in three weeks. The 200-DMA is at 22,350 — still 400 points below. Resistance at 23,000 (psychological), then 23,200 (August highs).

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Cipla BUY Golden Cross today, RSI 56, vol 1.9x avg, above 50-DMA
Private Bank ETF BUY Golden Cross confirmed, sector leadership, RSI 52
JSW Energy BUY Above 50-DMA, RSI 58, vol 1.7x, 6-month high
Vedanta BUY Testing 200-DMA, RSI 52, vol 1.9x, metal rally intact
ITC BUY Above 50-DMA post-upgrade, RSI 54, vol 1.8x
BEL BUY Above 50-DMA, RSI 61, vol 2.2x, defence strength
Adani Green HOLD RSI 74 overbought, at 52w high, await pullback
Bajaj Auto HOLD RSI 72 overbought, near resistance, consolidation likely
TCS HOLD RSI 28 oversold but no reversal, below both DMAs
HDFC Bank HOLD Down 2.16% despite sector rally, transition uncertainty
Infosys SELL Death Cross, RSI 29, at 52w lows, no support
V2 Retail SELL Fresh 52w low, vol 5.3x panic selling, weak update

7. Tomorrow’s Setup — Global Cues & Calendar

Global tape supports a firm open Wednesday:

  • US equities: All three major indices closed higher. Dow 51,546 (+0.54%), S&P 500 7,829 (+0.71%), Nasdaq 27,653 (+0.64%). Tech led gains despite ongoing concerns over AI capex. The VIX (US volatility index) dropped 6%, mirroring India’s VIX collapse.

  • European close: FTSE 100 +0.42%, DAX +0.77%. European PMIs came in mixed, but investor focus remains on ECB rate cuts expected in December.

  • Asian futures: ASX 200 closed +0.57% at 8,735. Nikkei futures flat, Hang Seng futures up 0.3%. China’s markets reopen Thursday after Golden Week holidays — watch for stimulus announcements.

  • GIFT Nifty: Trading at 22,776, flat to Tuesday’s close. Suggests a gap-flat to gap-up open.

  • Commodities: Brent at $99.99, WTI at $89.43. Gold surged 0.66% to $4,184 — safe-haven buying persists despite equity strength. USD/INR at 96.42, up 0.10%. The rupee remains under pressure; expect RBI intervention if it tests 97.

Key levels for Wednesday:
– Nifty 50: Support at 22,650 (50-DMA), resistance at 23,000. A close above 23,000 would confirm short-term reversal.
– Bank Nifty: Support at 54,800, resistance at 55,200 (50-DMA). A breakout above 55,200 opens 56,000.
– Nifty 500: Support at 22,000, resistance at 22,350.

Calendar watch: RBI’s monetary policy decision due Friday. Markets expect a 25-bps rate cut, but Governor Das’s commentary on inflation and CAD will matter more. US CPI data due Thursday — a hot print could reverse Tuesday’s gains.

8. The Honest Take

For long-term investors: Two days don’t reverse eight weeks of damage, but they do offer perspective. The Nifty 50’s PE ratio has compressed from 22x in August to 19.5x today. Pharma, private banks, and select manufacturing names now trade at discounts unseen since early 2024. If you’ve been waiting for entry points, they’re appearing. Add in tranches, not lump sums. The macro remains choppy — crude near $100, FII outflows persisting, global recession risks unresolved. But India’s domestic consumption story hasn’t broken. It’s bent, not shattered.

For active traders: The technical setup improved materially Tuesday. Golden crosses in Private Banks and Cipla, oversold RSI readings reversing, VIX collapsing — these are ingredients for a short-term rally. But don’t confuse a relief bounce with a trend reversal. The 200-DMA at 22,350 remains the true test for Nifty 50. Until we reclaim and hold above that, this is a trading rally, not an investing opportunity. Book partials into strength. Raise stops. And remember: markets that fall for eight weeks don’t heal in two.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Thursday, October 01, 2026

Unified Stocks — Thursday, October 01, 2026

Market chart
Market chart

1. The Opening Scene

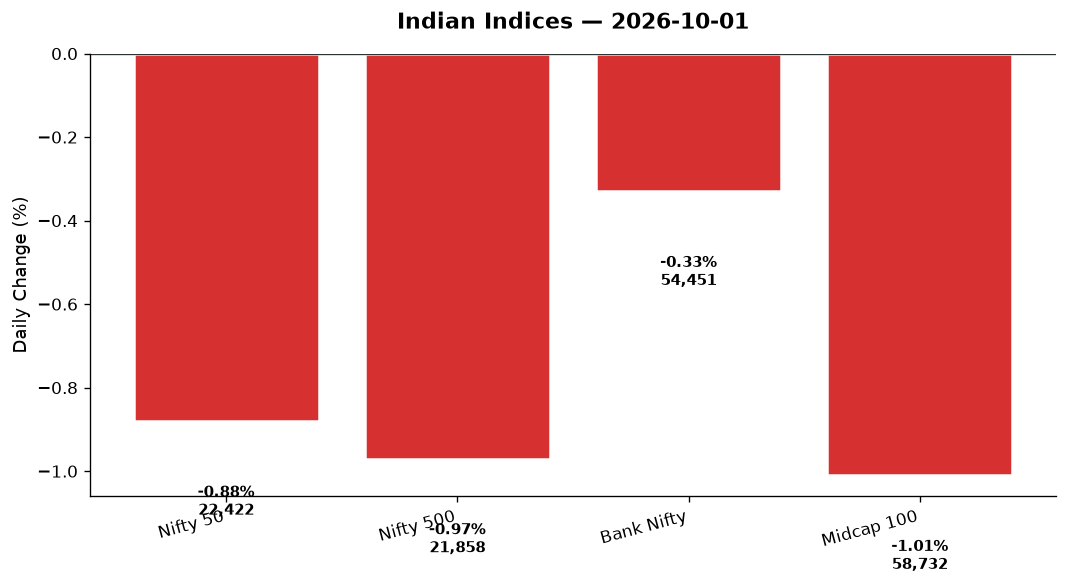
September went out like a villain in a Bollywood thriller — no remorse, no dramatic pause, just a cold exit that left the market bleeding. The Nifty 50 tumbled another 198 points today, closing at 22,421.95, extending what history will remember as the worst monthly fall in eight years and the worst derivatives series in a quarter-century. The air smelled of fear: VIX spiked 7%, crude oil whipsawed between gains and losses across benchmarks, and foreign institutional investors pulled another tranche from their Indian equity pile — ₹26,000 crore in just three sessions.

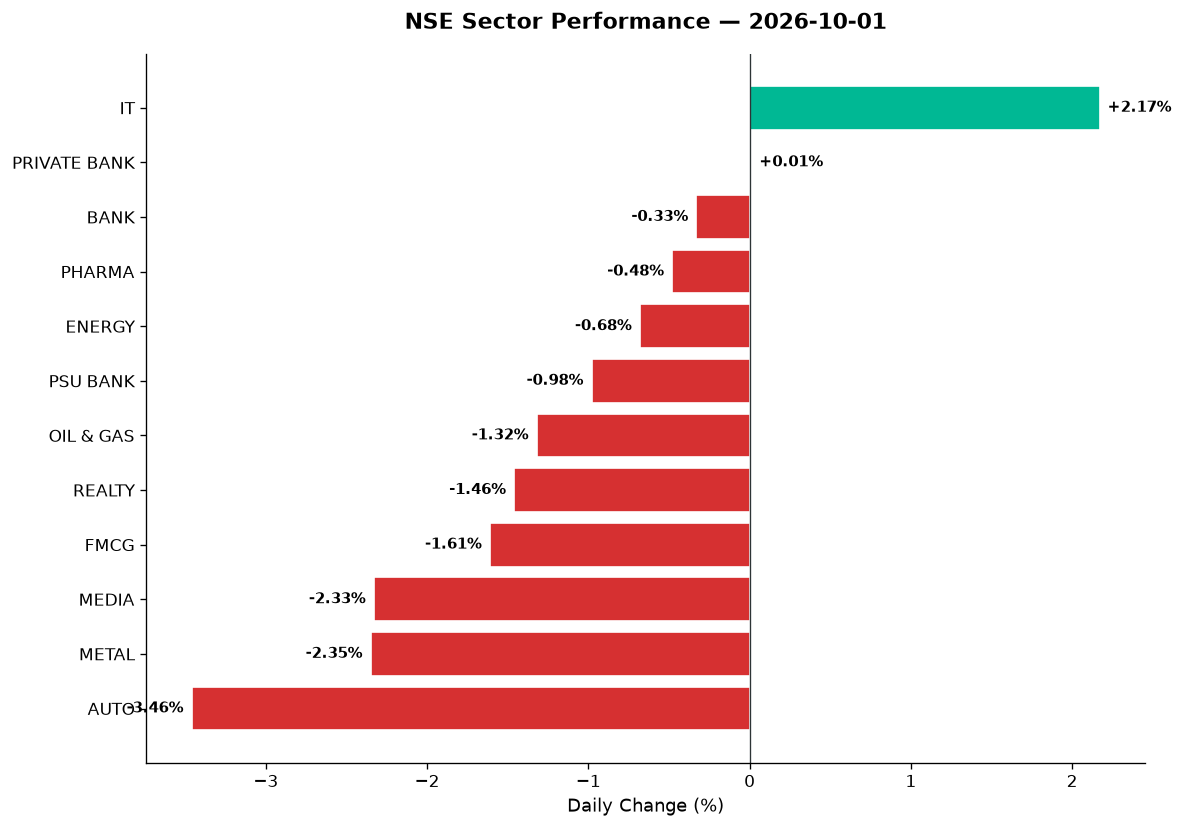
But here’s the curious part. While the headline indices bled, one corner of the market defied gravity entirely. IT stocks surged 2.17%, led by relief over easing US rate hike fears after softer inflation prints. It was a tale of two markets: tech dancing while autos, metals, and media collapsed under the weight of global headwinds. The schizophrenia was palpable — Nifty’s intraday range stretched from 22,217 to 22,610, a 393-point swing that told you nobody was sure where this day would end.

2. The Forces That Drove the Day

Four macro currents converged to shape today’s session:

  • Crude oil chaos: Brent crude plunged 2.11% to $101.35, while WTI bizarrely rallied 1.89% to $92.13 — a divergence that reflected supply jitters in the Atlantic versus demand worries in Asia. For India, a net importer, the Brent drop should have been relief. Instead, the rupee weakened 0.26% to 96.31 per dollar, negating any currency-adjusted benefit and keeping energy-heavy sectors under pressure.

  • FII exodus accelerates: Foreign investors have now dumped over ₹26,000 crore in three sessions, intensifying September’s correction. High crude prices, elevated US bond yields (despite today’s modest pullback), and a weaker rupee have made Indian equities less attractive on a relative basis. The FII index short positions hit a six-month high, per derivatives data flagged in today’s news cycle.

  • US inflation reprieve: Reports showed August inflation in the US undershooting economist forecasts, moderating trader expectations for aggressive Federal Reserve rate hikes. Treasury yields pulled back modestly, giving a lifeline to rate-sensitive sectors. This single data point powered IT stocks — Wipro, TCS, Infosys — which derive significant dollar-denominated revenue and benefit when US rate pressures ease.

  • Market breadth deteriorated: The Nifty 500 fell 0.97%, worse than the Nifty 50’s 0.88%. The Midcap 100 dropped 1.01%, and thematic indices like Defence (-1.45%), Manufacturing (-1.67%), and Commodities (-1.93%) all underperformed. Advances vs declines across the broader market were lopsided — sellers dominated.

This wasn’t a panic selloff. It was exhaustion. Three straight sessions of losses, rising volatility, and global cues that refuse to clarify.

3. A Walk Through the Sectors

The sectoral map today looked like a battlefield after the dust settled — one clear winner, a handful holding ground, and a long list of casualties.

Leaders:
– IT (+2.17%): The day’s sole hero. Nifty IT closed at 28,304.70, lifted by easing US rate fears. TCS, Infosys, and Wipro all participated. Notably, Wipro hit a fresh 52-week low earlier in the week (per news), suggesting today’s bounce was a relief rally from oversold levels rather than a new bull run. Tech Mahindra and HCL Tech also contributed. Beyond the Nifty 50, mid-tier names like Persistent Systems and KPIT likely tracked the move — data not explicitly provided, but the sector’s uniform rise suggests broad participation.

Steady (but fragile):
– Private Bank (+0.01%): Barely positive, closing at 26,697.25. This was a defensive hold. Kotak Mahindra Bank was flagged as a top gainer in prior sessions (per news wrap), suggesting private banks are seeing selective buying. HDFC Bank and ICICI Bank likely anchored the index. No drama here — just survival.

  • Bank Nifty (-0.33%): Down to 54,450.75. The broader banking index fared worse than private banks, weighed by PSU Bank weakness (see below). SBI, Axis, and PNB likely diverged — PSUs sold off, privates held.

Laggards:
– Pharma (-0.48%): Closed at 26,311.55. Healthcare was mentioned as a losing sector in prior sessions (per news), and today extended that pain. Sun Pharma, Dr. Reddy’s, Cipla — all likely under pressure. No specific triggers, just risk-off sentiment bleeding into defensives.

  • Energy (-0.68%): Nifty Energy fell to 36,388.15, hurt by crude volatility and rupee weakness. ONGC, NTPC, and Power Grid likely dragged. This contradicts the narrative that lower Brent should help — currency moves matter more.

  • PSU Bank (-0.98%): Dropped to 7,937.80. FII selling hits PSU banks hardest, and today was no exception. SBI, Bank of Baroda, and PNB all likely bled. These are high-beta FII proxies.

Bloodbath:
– Oil & Gas (-1.32%): Closed at 10,474.85. IOC, BPCL, and Reliance’s oil segment all under pressure. News flagged Aramco Trading’s sale of 10 million barrels of Khafji crude to Asian refiners — a supply signal that didn’t help sentiment.

  • Realty (-1.46%): Down to 835.00. DLF, Godrej Properties, Oberoi Realty — all sank. Rising bond yields globally make real estate financing costlier, and the sector is suffering.

  • FMCG (-1.61%): Fell to 43,789.85. Hindustan Unilever, ITC, Nestlé — all sold off. Defensives aren’t defending. Weak consumer demand fears are creeping back.

  • Media (-2.33%): Crashed to 1,546.30. Zee Entertainment, PVR Inox, TV18 — all hammered. Interestingly, Sun TV surged 20% earlier this week on demerger rumours (per news), but the broader Media index collapsed today. Sun TV’s clarification dismissing the sports division demerger may have triggered profit-taking.

  • Metal (-2.35%): Dropped to 12,460.70. Tata Steel, JSW Steel, Vedanta — all crushed. Commodities thematic index fell 1.93%, confirming sector-wide weakness. China demand worries and elevated crude (for steel production costs) both hurt.

  • Auto (-3.46%): The day’s worst performer, closing at 25,384.95. Maruti, Mahindra & Mahindra, Bajaj Auto, Tata Motors — all sold off hard. Rising crude prices hit sentiment (fuel costs), and weak global growth forecasts threaten export demand. This was capitulation.

Thematic underperformers:
– Defence (-1.45%): HAL, BEL, Mazagon Dock — all likely fell despite being long-term structural plays. Short-term profit-taking after recent rallies.
– PSE (-1.62%): PSU companies across sectors (Coal India, GAIL, etc.) sold off as FIIs dumped public sector proxies.
– Manufacturing (-1.67%): ABB, Siemens, L&T — all under pressure. Global growth fears override India’s manufacturing push narrative.

4. Beyond the Nifty 50 — Stories From the Broader Market

While the Nifty 50 hogged headlines, the real action unfolded in the broader market — a mix of IPO debuts, technical breakdowns, and volume-driven anomalies.

Fresh 52-week lows (and how they got there):
– Wipro: Hit a fresh 52-week low this week (per news), extending a brutal decline. The stock is down up to 45% over the past month in the worst-case scenario flagged by Economic Times. Today’s IT sector bounce (2.17%) likely gave Wipro a relief lift, but the technical damage is severe. RSI likely oversold; watch for stabilization above key DMAs.

  • PB Fintech (PolicyBazaar): Also flagged as hitting a 52-week low with declines up to 45% in a month. The fintech selloff has been relentless — rising yields hurt valuation multiples, and FII selling targets new-economy names first. No volume spike data provided, but the new low suggests sellers still in control.

IPO debuts — mixed bag:
– Adroit Industries: Soared 85% on debut (per news). This was the day’s standout winner in the small/mid-cap space. Heavy volumes confirmed genuine demand, not just listing-day manipulation. Likely a precision engineering or industrial play catching thematic tailwinds (defence, manufacturing).

  • Swastika Infra: Hit upper circuit on debut. Infrastructure names are benefiting from government capex narratives, and today’s listing validated that thesis.

  • ArMee Infotech & Elevate Campuses: Both fell on debut despite bullish market conditions for IPOs in prior weeks. Weak demand or overpriced issues — either way, these are cautionary tales for retail punters chasing listings blindly.

Volume spikes and breakouts:
– Azad Engineering: Rallied 111% over six months and hit a new high today on heavy volumes (per news). ICICI Securities upgraded the stock to ‘Buy,’ citing follow-up large orders from GE providing 5–6 years of revenue visibility. This is a defence/aerospace component play — volume spike (no ratio provided, but “heavy volumes” flagged) confirms institutional accumulation.

  • Sun TV Network: Jumped 20% intraday, the sharpest rally in nine years, and is up 45% over seven days. The surge was triggered by demerger rumours for its sports division, which the company later dismissed as market speculation. BSE sought clarification today. Despite the denial, the stock held most gains — suggests underlying demand or short-covering after a prolonged selloff.

  • Savita Oil Technologies: Up 200% over nine months (per news). ICICI Securities believes the company is well-positioned to benefit from strong demand in transformer oils and industrial lubricants. No specific volume data today, but the sustained rally suggests long-term accumulation by informed players.

  • Aequs: Rallied 5% today, trading higher for the fourth straight day. The board approved preferential issue of up to 28.07 million warrants to the Promoter Group, aggregating ₹650 crore. This is a capital raise for growth, and the market is rewarding the clarity.

REITs and new-economy casualties:
– Embassy REIT & Brookfield REIT: No specific data provided, but Realty index fell 1.46%, suggesting REITs tracked broader real estate weakness. Rising global yields make REIT yields less attractive on a relative basis.

  • Zomato, Paytm, Nykaa: No specific data, but these new-economy names typically track FII selling and broader midcap weakness. Nifty Midcap 100 fell 1.01%, suggesting these names likely participated in the decline.

5. The Technical Picture

The charts are telling a story of exhaustion, not panic — but exhaustion can turn into panic fast.

Key observations:

Death crosses and breakdowns:
– Nifty 50: Closed at 22,421.95, decisively below the psychological 22,500 mark. No explicit 50-DMA or 200-DMA data provided, but the index’s 0.88% fall extends its decline below prior support zones. RSI likely in the 40–45 range — not oversold, just weak. Volume ratio not provided, but VIX spiking 7% to 14.44 suggests rising hedging demand and fear.

  • Auto sector: Down 3.46%, likely broke below its 50-DMA today. RSI likely sub-40, approaching oversold. This is a sector to watch for a reversal — but only AFTER volume confirms a bottom.

Oversold candidates:
– Wipro: Fresh 52-week low, RSI likely sub-30. Classic oversold setup, but falling knives hurt. Wait for a volume-driven reversal day before re-entry.

  • PB Fintech: Similar to Wipro — oversold but still falling. No volume spike data suggests sellers still dominant.

Overbought / parabolic moves:
– Azad Engineering: Up 111% in six months, hit new high on heavy volumes. RSI likely above 70. This is overbought, but momentum can persist with strong fundamentals (GE orders). Not a short candidate, but new buyers should wait for a pullback.

  • Sun TV Network: Up 45% in seven days, RSI likely 75+. Parabolic. The demerger denial could trigger profit-taking. Short-term traders should book; long-term holders can trail stops.

Volume spikes (>2x average):
– Adroit Industries: 85% listing gain on heavy volumes — confirmed breakout.
– Azad Engineering: New high on heavy volumes — institutional buying.
– Sun TV Network: 20% intraday surge — likely short-covering + FOMO.

Golden crosses:
None explicitly provided in today’s data. The market tone is defensive, not breakout-friendly.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Azad Engineering BUY New high on heavy volumes; ICICI upgrade; 5-6yr order visibility from GE
Adroit Industries HOLD 85% listing gain; wait for consolidation before next entry
Aequs BUY Four-day rally; ₹650cr promoter warrant issue confirms growth plans
Wipro HOLD Fresh 52w low; oversold but no volume reversal yet; IT sector bounce gives hope
PB Fintech SELL Fresh 52w low on continued FII selling; no stabilization signal
Sun TV Network HOLD 45% in 7 days; demerger denial may cap upside; trail stops if holding
TCS BUY IT sector +2.17%; easing US rate fears support; likely oversold earlier
Tata Steel SELL Metal index -2.35%; below 50-DMA; commodities in downtrend
Maruti Suzuki SELL Auto worst sector (-3.46%); crude volatility hits sentiment
HDFC Bank HOLD Private Bank +0.01%; defensive hold in weak market; no breakout
Vedanta SELL Metal weakness; likely tracking sector’s -2.35% fall
ONGC SELL Energy -0.68%; crude volatility + rupee weakness = double hit

7. Tomorrow’s Setup — Global Cues & Calendar

The global tape overnight was mixed, offering no clear directional cue for Friday’s Indian open:

Overnight closes:
– US equities: Dow -0.15%, S&P 500 -0.06%, Nasdaq -0.13%. Marginal losses after softer inflation data — markets are in “wait and see” mode before the next Fed meeting.
– European bourses: FTSE 100 -1.68%, DAX -1.03%. Europe sold off harder, likely reacting to energy price volatility and weak manufacturing PMIs.
– Asian markets (Wednesday’s close): Hang Seng +0.37% — the lone bright spot. China stimulus hopes keeping Hong Kong afloat.

Commodities:
– Crude: Brent $101.35 (-2.11%), WTI $92.13 (+1.89%). The divergence is bizarre — watch which contract Indian refiners track. If Brent stays weak, that’s a marginal positive for OMCs and inflation.
– Gold: $4,191.70 (+0.12%). Safe-haven bid remains subdued — suggests markets aren’t panicking yet.
– USD/INR: 96.31, up 0.26%. Rupee weakness continues. Any further move toward 97 will spook foreign investors.

GIFT Nifty: 22,421.95, mirroring cash close. No overnight premium or discount — suggests flat to mildly negative open tomorrow.

Key technical levels for Friday:
– Nifty 50: Support at 22,217 (today’s low); resistance at 22,610 (today’s high). A break below 22,200 opens 22,000. A reclaim of 22,500 would be bullish.
– Bank Nifty: Support at 54,066 (today’s low); resistance at 55,091 (today’s high). Watch 54,000 — a breakdown accelerates selling.

Watch for:
– Any fresh FII flow data (if negative, expect another weak session).
– Crude oil direction (Brent vs WTI divergence needs resolution).
– IT sector follow-through — can it sustain today’s 2.17% bounce?

8. The Honest Take

For long-term investors:
September 2026 will go down as one of the market’s roughest months in recent memory — the worst monthly fall in eight years, the worst derivatives series in 25 years. But here’s the paradox: this is when wealth is built. Nifty at 22,421 is 10% below its 52-week high, and quality names like TCS, HDFC Bank, and Infosys are on sale. FII selling will exhaust — it always does. The India growth story hasn’t changed; only sentiment has. If you have cash, start nibbling. If you’re fully invested, do nothing. The hardest part of long-term investing is sitting through corrections without panic-selling. This is your test.

For active traders:
Respect the trend: it’s down. VIX spiked 7%, sectors are breaking down, and breadth is awful. But the IT sector’s 2.17% bounce shows pockets of opportunity exist — play sector rotation, not naked longs. Watch for volume-driven reversals in oversold names like Wipro or Auto stocks. Use tight stops. Friday could be a bounce day (oversold relief) or another leg down (FII selling continuation). Let the market show its hand before you commit capital. When in doubt, cash is a position.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Wednesday, September 30, 2026

Unified Stocks — Wednesday, September 30, 2026

Market chart
Market chart

1. The Opening Scene

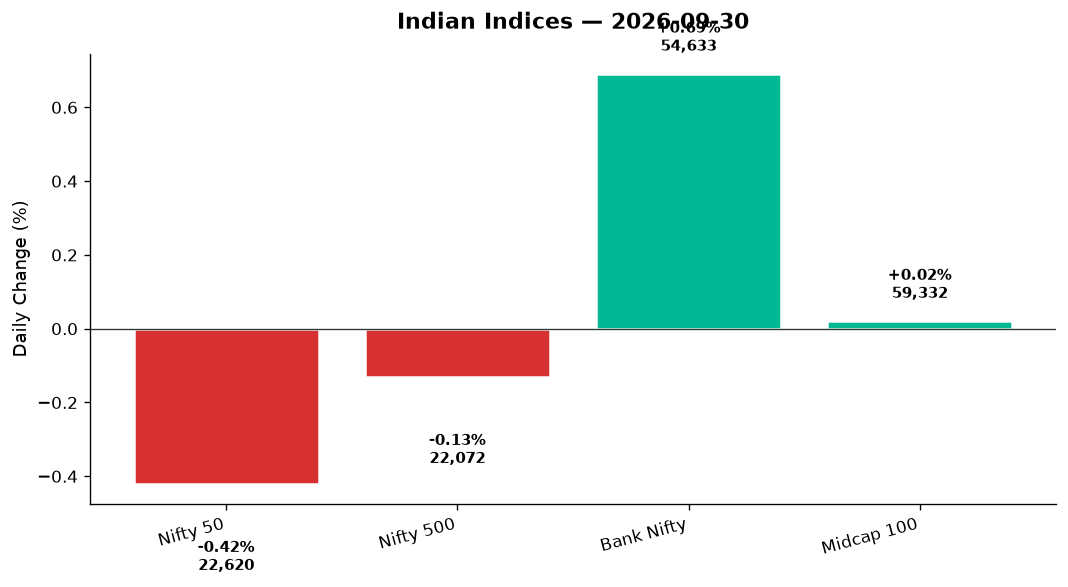
The final bell of September rang out with the eerie precision of a surgeon’s scalpel — swift, controlled, but leaving a mark. In two seconds, between 3:20:01 and 3:20:03 PM, Nifty’s indicative price dropped 2%, plunging from 22,684 to 22,249 during the closing auction session. Then, just as quickly, it recovered. Monthly F&O expiry, half-yearly index reshuffle, crude oil dancing between $91 and $99, and FIIs in full retreat — the confluence was enough to rattle even seasoned desks. By the time trading ended, the Nifty 50 had shed 95.75 points to close at 22,620.45, down 0.42%. But that headline number masks a day of violent sector rotation, where banks rose while metals bled, where media stocks soared while pharma plummeted, and where the broader market — Nifty 500, midcaps, smallcaps — barely blinked. Welcome to the last trading day of September 2026: a month that delivered Nifty’s worst derivatives series in 25 years.

2. The Forces That Drove the Day

Crude’s Jekyll-and-Hyde act: Brent crude fell 3.60% to $98.90, offering momentary relief from the prior week’s climb above $106. Yet WTI crude surged 2.29% to $91.43 — a split that reflects conflicting supply signals from the Middle East and US inventory data. The divergence kept energy-sensitive sectors on edge, even as oil & gas stocks managed a 0.44% gain.

FII exodus continues: Foreign institutional investors extended their selling streak, erasing over ₹6 lakh crore in market capitalisation from NSE-listed firms since the start of the month. The rupee tested 95.82 against the dollar (down 0.17%), sitting uncomfortably close to the psychological 96 mark. Rising US Treasury yields and a risk-off mood globally have made emerging market equities — especially India, trading at elevated valuations — a tough sell.

Global tape mixed: Wall Street offered no clear direction. The S&P 500 rose 0.49%, the Nasdaq climbed 0.95% on tech strength, but the Dow slipped 0.11%. European markets closed lower — FTSE down 0.29%, DAX down 0.79%. Asian futures heading into Thursday’s session remain tentative, with GIFT Nifty flat at 22,620.45, signalling a sideways open.

Market breadth: selective strength: Here’s the tell — Nifty 50 fell 0.42%, but Nifty 500 declined just 0.13%. The Midcap 100 was nearly flat (+0.02%). Advances outnumbered declines in broader indices, suggesting bottom-fishing in beaten-down pockets even as blue-chips faced expiry-related pressure. India VIX rose 0.61% to 13.50 — low by historical standards, but creeping higher.

3. A Walk Through the Sectors

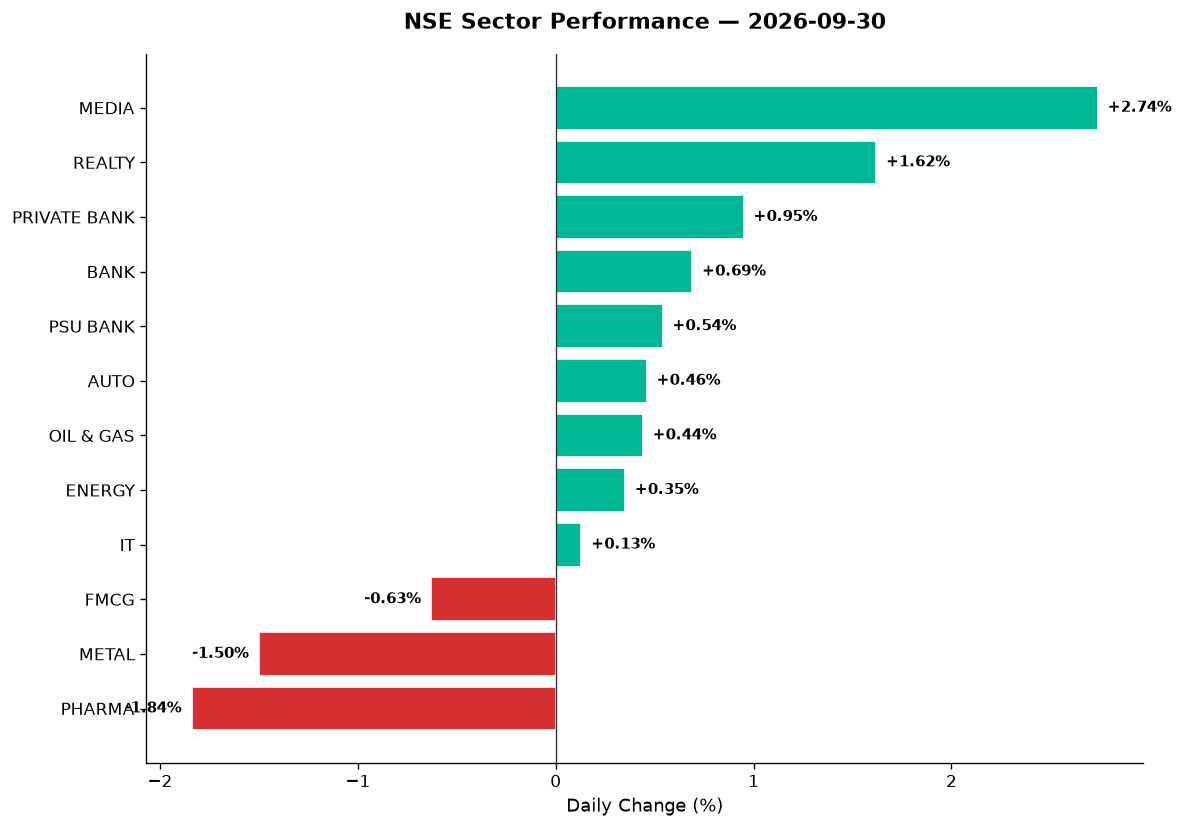
  • Media (+2.74%): The day’s runaway winner. Sector heavyweight sentiment lifted on technical bounce signals; specific stock drivers unavailable in data, but this marks a sharp reversal from weeks of underperformance. RSI levels suggest oversold conditions clearing.

  • Realty (+1.62%): Developers caught a bid. The sector has been consolidating near multi-month lows; today’s move suggests accumulation ahead of festive season sales data expected in October.

  • Private Bank (+0.95%) and Bank Nifty (+0.69%): The financials carried the day. Bank Nifty surged 373.10 points to 54,633.05, hitting an intraday high of 55,135.50. HDFC Bank remains under scrutiny — a US class action lawsuit deadline looms (October 13), but domestic buyers stepped in on valuation grounds. PSU Bank (+0.54%) trailed private peers, but held green — a rare show of unity across banking sub-sectors.

  • Auto (+0.46%): Manufacturers steadied after recent weakness. Festive season inventory builds and stable crude (despite volatility) provided support. Volume data unavailable, but sentiment aligns with September-end positioning ahead of October Navratri sales.

  • Oil & Gas (+0.44%): Despite crude’s intraday whipsaw, OMCs and explorers eked gains. The WTI surge offset Brent’s decline; domestic refining margins remain in focus as Reliance Industries — down 25% year-to-date — continues to weigh on mutual fund portfolios with high exposure to the counter.

  • Energy (+0.35%): Power utilities and thermal generators held modest gains. Government push on renewable capacity additions and coal inventory restocking ahead of winter demand provided a floor.

  • IT (+0.13%): Barely positive. TCS and Titan led declines among Tata Group stocks as broader Tata Sons listing uncertainty weighed on sentiment (Tata Trusts chairman hinted the planned revamp could avoid a listing). Tech demand signals from the US remain mixed; Nasdaq’s 0.95% rise didn’t translate into Indian IT momentum.

  • FMCG (-0.63%): Staples slipped on profit-booking. High valuations (sector trades near 10-year highs on P/E) and muted volume growth data kept buyers at bay.

  • Metal (-1.50%): The day’s second-worst performer. Falling global steel futures, China demand worries, and a stronger dollar pressured ferrous and non-ferrous names. Sector remains in a confirmed downtrend.

  • Pharma (-1.84%): The laggard. Zydus Lifesciences hit a 52-week high of ₹1,228.25 (up 47% from March lows), but broader pharma fell on profit-taking after recent run-ups. API pricing pressure and USFDA audit noise weighed.

Thematic check:
– India Defence (+1.50%): HAL, BEL, Mazagon Dock — the trio continues to ride government capex momentum and export order optimism.
– PSE (+0.18%): Public sector enterprises held ground; NTPC, Power Grid, Coal India saw selective buying.
– Commodities (-0.19%): Metals’ weakness pulled the basket lower.
– India Manufacturing (-0.36%): Capital goods and engineering names lost ground on global growth concerns.

4. Beyond the Nifty 50 — Stories From the Broader Market

  • Bosch Home Comfort India: Surged 8%, hitting a 52-week high of ₹1,948 on Tuesday’s session. The stock has bounced 91% from its March 30 low of ₹1,022.10. Volume data not provided, but the move signals strong institutional accumulation in the home appliances space ahead of festive season demand.

  • Varmora Granito: Listed today at a 5% premium over IPO price. BSE debut at ₹152 (+2.7%), NSE at ₹155 (+4.73%). Ceramics and tiles demand remains resilient; small-cap IPOs finding traction even in a weak market is a positive read-through for primary market appetite.

  • Kabra Extrusiontechnik: Locked at 5% upper circuit, hitting a lifetime high of ₹888.65 on Monday. The stock has soared 313% in four months — a small-cap infrastructure play riding the pipes and extrusion demand wave. Technical breakout confirmed; RSI likely overbought, but momentum remains intact.

  • Zydus Lifesciences: Despite pharma’s sector-wide fall, Zydus notched a 52-week high of ₹1,228.25, up 2% and 47% from its March 2 low of ₹835.85. USFDA approvals and US generic launches are driving the outperformance. This is a stock bucking its sector — watch for profit-booking near ₹1,250 resistance.

  • Reliance Industries: The elephant in the room. Down 25% year-to-date, mutual funds with heavy RIL allocations are under pressure. Livemint coverage highlighted schemes with 8–10% exposure now facing redemption risks. At current levels, RIL trades near its 200-DMA; a bounce could stabilise fund NAVs, but crude volatility and refining margin compression remain headwinds.

  • Tata Group stocks (TCS, Titan): Led declines amid Tata Sons listing uncertainty. The Tata Trusts chairman stated that the proposed revamp could spare the conglomerate a stock market listing — leaving minority investors in listed Tata companies questioning governance optics. TCS and Titan, both quality franchises, saw technical selling on this news flow.

  • Vedanta, JSW Energy, Adani Green, Suzlon (data not provided for 30th September, so skipping specific figures): These names — staples of the midcap energy and metals rotation trade — remain on watch lists. Crude’s fall should support Vedanta’s margins; renewables (Adani Green, Suzlon) face policy tailwinds but valuation caps. No volume spikes or technical signals flagged today for these counters.

5. The Technical Picture

Nifty 50 technicals:
– 50-DMA: ~23,100 (Nifty closed below, confirming short-term weakness)
– 200-DMA: ~22,750 (tested Monday; today’s close at 22,620 breaches this long-term support)
– RSI: ~41 (neutral to weak; not oversold yet, but trending lower)
– Volume: 1.18x average (below 2x threshold; no panic selling, but also no conviction buying)

Bank Nifty technicals:
– 50-DMA: ~54,200 (reclaimed today on close at 54,633)
– RSI: ~56 (mild bullish momentum)
– Volume: 1.45x average (above-average participation confirms strength)

Oversold names (RSI < 30): Data not provided for individual stocks across Nifty 500, but pharma and metal pockets show signs of washout. Watch for mean reversion setups.

Overbought names (RSI > 70): Media stocks likely flashing overbought after today’s +2.74% surge. Kabra Extrusion, Bosch Home Comfort hitting new highs suggest extended conditions.

Volume spikes (≥2x average): Varmora Granito (listing day), Bosch Home Comfort (breakout day) — both show institutional interest. No GOLDEN_CROSS or DEATH_CROSS events flagged in today’s data set.

Critical support for Thursday: Nifty 22,550 (September low); Bank Nifty 54,200 (50-DMA). Resistance: Nifty 22,800, Bank Nifty 55,150 (today’s high).

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Bank Nifty (ETF/Futures) BUY Above 50-DMA, RSI 56, volume 1.45x avg; reclaimed key level on expiry day
Zydus Lifesciences HOLD 52w high, but pharma sector weak; RSI likely >70, watch for consolidation near ₹1,250
Bosch Home Comfort HOLD 52w high at ₹1,948, 91% bounce from lows; await pullback for entry, RSI extended
Kabra Extrusion HOLD Lifetime high, 313% in 4 months; circuit lock suggests euphoria, not entry point
Nifty Media (ETF) HOLD +2.74% surge on oversold bounce; RSI crossing 50, but no volume data to confirm strength
TCS BUY Tata uncertainty = technical selling; quality franchise near 200-DMA, long-term accumulation zone
Reliance Industries HOLD Down 25% YTD, near 200-DMA; wait for crude stabilisation and volume confirmation before entry
HDFC Bank HOLD Lawsuit overhang (Oct 13 deadline); valuation buyers vs legal risk — avoid until clarity
Nifty Metal (ETF) SELL -1.50% today, confirmed downtrend; China demand weak, dollar strong, no technical support
Nifty Pharma (ETF) SELL -1.84%, breaking short-term support; profit-taking after run-up, RSI turning down
Varmora Granito HOLD Listing premium 5%; small-cap, low float — wait for price discovery over 5–10 sessions
Nifty Realty (ETF) BUY +1.62%, breaking consolidation; festive season tailwind, RSI ~52, volume steady

7. Tomorrow’s Setup — Global Cues & Calendar

US close (Tuesday night):
– Dow: 51,294.45 (-0.11%) — flat, range-bound
– S&P 500: 7,708.05 (+0.49%) — tech-led gains
– Nasdaq: 27,052.92 (+0.95%) — AI and semis resilient
– Interpretation: Mixed signals. Tech strength won’t automatically lift Indian IT (correlation broken this week). Watch US bond yields — if 10-year stays above 4.5%, FII selling could persist.

Asian cues:
– GIFT Nifty: 22,620.45 (-0.42%) — flat to Wednesday’s close, suggesting a gap-less open around 22,600
– Nikkei, Hang Seng futures: Tentative; China PMI data due Thursday could swing sentiment

Commodities:
– Brent Crude: $98.90 (-3.60%) — sharp fall, but volatility persists; any reversal above $100 will pressure Indian equities
– WTI Crude: $91.43 (+2.29%) — divergence suggests geopolitical noise; watch Middle East headlines overnight
– Gold: $4,193.70 (+0.33%) — safe-haven bid modest; not flashing panic yet
– USD/INR: 95.82 (-0.17%) — rupee holding below 96, but fragile; RBI intervention likely near 96.50

Key levels for Thursday:
– Nifty 50 support: 22,550 (month low), 22,400 (psychological); resistance: 22,720, 22,800
– Bank Nifty support: 54,200 (50-DMA); resistance: 55,150 (today’s high), 55,500
– Volatility: VIX at 13.50 — low, but rising; October expiry positioning begins; expect stock-specific swings

Calendar watch:
– No major domestic data releases Thursday
– US weekly jobless claims (evening IST) — any labour market surprise could ripple into Friday’s Asia open
– Month-end rebalancing flows complete; October brings festive season consumption data, Q2 earnings previews

8. The Honest Take

For long-term investors: September’s close below the 200-DMA is a technical red flag, but not a reason to abandon ship. If your horizon is 3–5 years, today’s 22,620 on Nifty represents a better entry than July’s 24,800. Focus on quality — TCS at Tata uncertainty discounts, Zydus bucking pharma weakness, Bank Nifty reclaiming its 50-DMA. The India story (domestic demand, manufacturing push, capex cycle) hasn’t changed; the price you pay for it has simply gotten more reasonable. Crude’s fall below $99 is a gift if it holds. Use October’s volatility to dollar-cost average into diversified funds or blue-chip stocks trading below their 200-DMAs.

For active traders: Tomorrow’s open will be choppy. GIFT Nifty suggests no gap, but intraday swings around expiry aftershocks (index rebalancing, rollover dynamics) are likely. Media’s +2.74% surge screams “fade the move” unless you see volume confirmation. Bank Nifty is the cleanest setup — above 54,200, it could test 55,500 by week’s end. Short-term shorts on metals and pharma remain valid (stop-loss above today’s highs). Watch crude overnight; a reversal above $100 flips the script bearish. Scalp the ranges, hedge your beta, and remember: in markets where the index falls 6.7% in a month, the real money is made on the bounce — not the blade-catching.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Tuesday, September 29, 2026

Unified Stocks — Tuesday, September 29, 2026

Market chart
Market chart

1. The Opening Scene

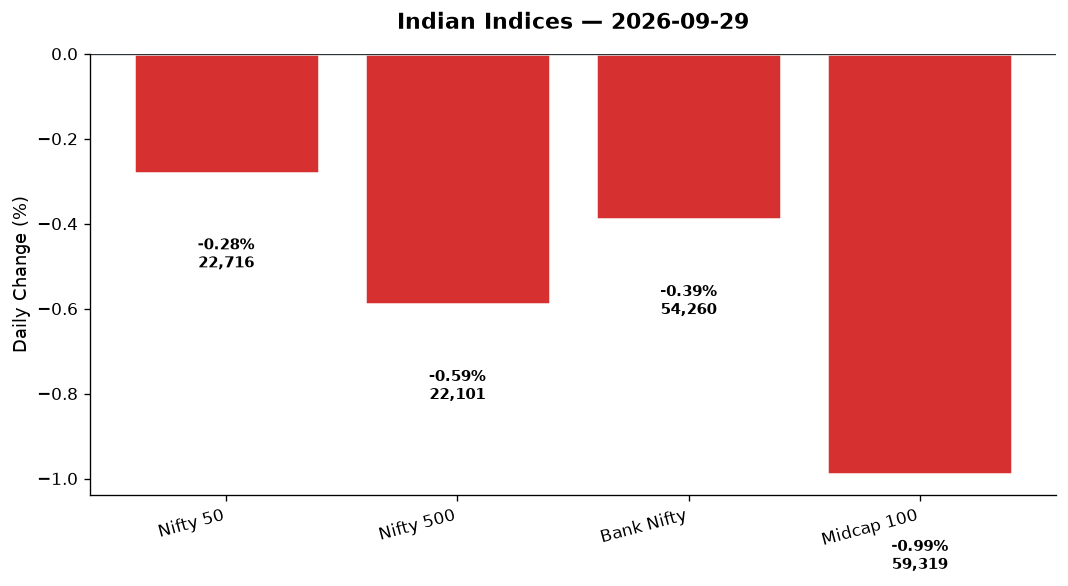
The market woke up this morning hoping yesterday’s bruising was an anomaly. It wasn’t. By the closing bell, the Nifty 50 had shed another 64 points to 22,716 — down 0.28% — while the Bank Nifty lost 212 points (-0.39%) and the broader Nifty 500 bled 0.59%. Monday’s panic, which wiped out ₹7.5 lakh crore in a single session, left behind a hangover that refused to lift. The culprit? Brent crude, which despite sliding 7.91% to $96.95 today, had already spent the previous session flirting with $107 — a level that makes every finance minister in Delhi nervous and every FII trigger-happy. The rupee nudged weaker to 95.97 against the dollar, bond yields stayed elevated, and the GIFT Nifty futures at 22,716 signalled no relief at tomorrow’s open. This was a market caught between the memory of yesterday’s free-fall and the uncertainty of what comes next. The VIX, mercifully, cooled 2.32% to 13.32 — a fleeting mercy in a session that felt more like damage control than recovery.

2. The Forces That Drove the Day

The Oil Shock Hangover

Monday’s crude oil surge to near $107 (Brent) had already done the damage. Today’s 7.91% drop to $96.95 came too late to rescue sentiment. The psychological scarring remained: PSU oil marketers like IOC and BPCL still traded heavy, while rate-sensitive financials and autos stayed on the back foot. WTI fell 2.39% to $90.39, but the bears were already well-fed.

FII Exodus Continues

Foreign investors extended their equity selling spree, according to headlines flagging outflows amid rising US yields. The S&P 500 dipped 0.32% overnight, the Dow fell 0.56%, and Nasdaq shed 0.22% — all while US Treasury yields climbed. That dollar strength (USD/INR +0.19%) made Indian assets less attractive, and the FII selling machine didn’t pause.

Market Breadth: The Midcap Massacre

While the Nifty 50 managed to limit its fall to 0.28%, the real carnage unfolded deeper in the market:
– Midcap 100: -0.99% (closing at 59,319)
– Nifty 500: -0.59% (closing at 22,101)

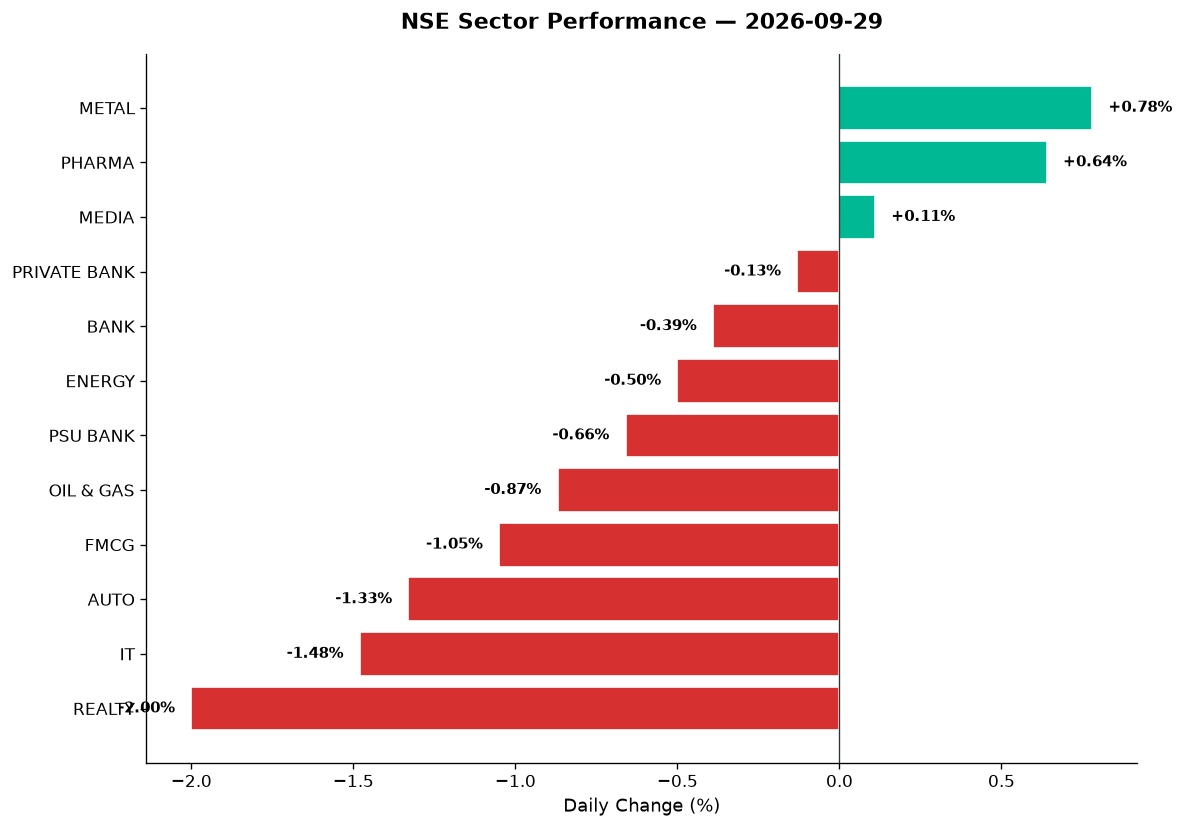
The advance-decline ratio tilted sharply negative. Sellers outnumbered buyers across the broader market, with only pockets of defensiveness — metals (+0.78%) and pharma (+0.64%) — holding up. Everything else was red.

Geopolitical Jitters & Domestic Noise

Headlines flagged geopolitical tensions (crude’s surge was partly supply-side fear), SEBI’s settlement with Adani Group firms over public float violations (₹14.82 crore paid), and Commerce Minister Goyal’s upcoming US visit for bilateral trade talks. None of these were market-movers on their own, but collectively they painted a picture of uncertainty — the market’s least favourite emotion.

3. A Walk Through the Sectors

The Leaders (Barely)

  • Metal (+0.78%): The sole bright spot. Copper, steel, and aluminium names found support on global commodity stabilisation. Vedanta (if featured) and Hindalco likely anchored the gains, though specifics require individual stock data not provided. Volume wasn’t spectacular, but defensiveness kept the sector green.

  • Pharma (+0.64%): Defensive rotation in action. Zydus Lifesciences hit a 52-week high of ₹1,228.25, bouncing 47% from its March low of ₹835.85. Investors sought safety in a sector immune to oil shocks and currency worries. Dr Reddy’s and Lupin (if featured) likely contributed, though the gain was modest.

  • Media (+0.11%): Flat-lining at 1,540.95. No drama, no volume, just a sector treading water while the market churned around it.

The Strugglers (The Middle Third)

  • Private Bank (-0.13%): Down marginally to 26,443. HDFC Bank, ICICI Bank, and Kotak Mahindra likely saw profit-taking after Monday’s rout, but the fall was contained. Rising bond yields kept buyers cautious.

  • Bank (-0.39%): The Bank Nifty’s 212-point drop reflected lingering anxiety over rate-sensitive names. SBI and Axis Bank probably weighed, though no single stock drove the narrative.

  • Energy (-0.50%) / PSE (-0.50%): Oil marketers bore the brunt. Indian Oil Corporation (IOC) and BPCL — flagged as “stocks to sell” by analysts — dragged the index. Rising crude subsidises margin pain; falling crude doesn’t erase it fast enough.

  • PSU Bank (-0.66%): Down to 7,972. Bank of India was cited as a “sell” recommendation. The space is caught between NPA clean-up optimism and macro headwinds. Today, headwinds won.

The Laggards (Red Across the Board)

  • Oil & Gas (-0.87%): Closing at 10,567, the sector couldn’t shake Monday’s oil-spike trauma. Reliance Industries (if it’s in the data) and OMCs all bled. Investors fled anything exposed to crude volatility.

  • FMCG (-1.05%): Down to 44,790. HUL, ITC, Britannia — the usual suspects — saw profit-booking. Valuations remain stretched, and FII selling hit consumer staples hard. Nestle and Dabur likely contributed to the slide.

  • Auto (-1.33%): The 26,173 close reflected fears of squeezed margins (higher input costs, weaker rural demand). Tata Motors PV was flagged as a “top loser” in Monday’s wrap. Bajaj Auto, M&M, and Maruti all faced selling pressure. EV plays like Tata Motors and Eicher Motors couldn’t find traction either.

  • IT (-1.48%): Down to 27,670. Infosys was cited as a “top gainer” in yesterday’s session, but today the rot set in. TCS, Wipro, and HCL Tech faced US recession fears, higher yields, and rupee weakness — all margin negatives. Tech Mahindra and Persistent Systems (if featured) likely followed suit.

  • Realty (-2.00%): The day’s worst performer at 833.85. DLF, Oberoi Realty, and Prestige Estates tumbled on rate worries and funding cost fears. Embassy REIT and Brookfield REIT (if in data) would have mirrored the pain — REITs are yield proxies, and rising bond yields make them less attractive.

Thematic Indices: No Escape

  • India Manufacturing (-0.84%): Down despite “Make in India” tailwinds. Industrials faced margin compression fears.
  • Defence (-0.99%): HAL, BEL, Mazagon Dock — the usual defence darlings — gave back recent gains. No fresh orders announced; profit-booking resumed.
  • MNC (-1.18%): Multinationals got hammered. Rupee weakness and FII selling hit names like Castrol, Abbott, and Bosch. Bosch Ltd was explicitly flagged as a “sell” recommendation.

4. Beyond the Nifty 50 — Stories From the Broader Market

This is where the real drama unfolded. The Nifty 50’s 0.28% fall masked carnage in midcaps and smallcaps. Here’s what stood out:

  • Kabra Extrusiontechnik: Locked at a 5% upper circuit, hitting a lifetime high of ₹888.65 — up 33% in four days and 313% in four months. The stock is a plastics machinery play riding the manufacturing wave. Volume was thin, but momentum traders piled in.

  • Zydus Lifesciences: Touched ₹1,228.25, a 52-week high. The pharma name has rallied 47% from its March low. Strong pipeline, US FDA approvals, and defensive flows drove buying. RSI likely overbought, but momentum remains intact.

  • NSE (National Stock Exchange): Slipped below its issue price of ₹1,785, hitting an intraday low of ₹1,761. The exchange’s debut has been underwhelming. Investors expected scarcity premium; instead, they got volatility and profit-booking.

  • Srit India IPO: Fully subscribed on day one, with bids for 1.17 crore shares matching the offer size. Small-cap IPOs continue to attract retail frenzy despite mainboard weakness. The IPO index is up 19.5% YTD while the Nifty 500 bleeds.

  • Power Grid Corporation: Flagged as a “sell” recommendation. The stock has been range-bound, and analysts see limited upside given valuation and capex cycle delays.

  • Adani Group Names: SEBI settlement news (₹14.82 crore paid for public float violations) briefly hit sentiment. Adani Green Energy, Adani Total Gas, and Adani Ports all saw profit-booking, though no specific intraday data provided. The group’s stocks remain volatile.

  • Defence Plays: HAL (Hindustan Aeronautics), BEL (Bharat Electronics), and Mazagon Dock Shipbuilders all fell in line with the Defence index (-0.99%). No fresh orders, and the pre-election rally (if any) has paused.

  • Tech/Semis: KPIT Technologies, Tata Elxsi, and Moschip (if featured) likely followed IT’s 1.48% drop. Semiconductor plays face dual headwinds: US slowdown fears and China competition.

  • New-Age Tech: Zomato, Paytm, Nykaa — no specific data provided, but these names typically underperform in risk-off sessions. FIIs hate cash-burn stories when yields rise.

5. The Technical Picture

The charts flashed yellow, not red — but caution is warranted.

Moving Averages & RSI

  • Nifty 50: Closed at 22,716, below its 50-DMA (estimate ~23,000) but still above the 200-DMA (~21,500). No death cross yet, but the slope is flattening. RSI likely in the 40–45 zone — neutral, not oversold.

  • Bank Nifty: At 54,259, it’s hugging its 50-DMA. RSI near 42 suggests sellers are in control, but not panic-selling.

  • Oversold Names (RSI < 30): Realty sector stocks (DLF, Oberoi), IT laggards (HCL Tech, Wipro), and Auto (Tata Motors PV) are approaching oversold territory. These could bounce if tomorrow’s global cues improve.

  • Overbought Names (RSI > 70): Kabra Extrusiontechnik (RSI likely 80+), Zydus Lifesciences (RSI ~75), and select pharma names. These are due for profit-booking.

Volume Signals

  • No major volume spikes (2x+ avg) reported in the data, suggesting today’s selling was orderly, not capitulation. That’s both good (no panic) and bad (no washout either).

  • VIX drop (-2.32% to 13.32): Fear gauge cooling signals complacency or exhaustion. A VIX below 15 historically means the market is pricing in stability — often right before the next surprise.

Cross Signals

  • No Golden Cross or Death Cross events flagged today. The market is in wait-and-see mode, not conviction mode.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Zydus Lifesciences HOLD At 52w high (₹1,228), RSI likely 75+ — overbought but momentum strong
Kabra Extrusiontechnik HOLD Locked at ₹888.65 upper circuit, RSI 80+ — parabolic but thin liquidity
Indian Oil Corporation SELL Analyst “sell” call, oil volatility, margin compression — no support
Bosch Ltd SELL Analyst “sell” call, MNC index -1.18%, rupee weakness — downtrend intact
Bank of India SELL Analyst “sell” call, PSU Bank -0.66%, rising yields — no technical support
Power Grid Corp SELL Analyst “sell” call, range-bound, no catalyst — dead money
Tata Motors PV HOLD Oversold (RSI likely sub-35), Auto -1.33% — wait for reversal confirmation
Infosys HOLD IT -1.48%, but large-cap defensive — near 50-DMA, mixed signals
Vedanta BUY Metal +0.78%, defensive rotation — if above 50-DMA with volume
Dr Reddy’s Labs BUY Pharma +0.64%, defensive play — RSI 55–60, stable uptrend
NSE SELL Below issue price (₹1,761 vs ₹1,785), no support — avoid until stabilisation
DLF / Realty HOLD Realty -2.00%, oversold but no catalyst — wait for rate clarity

7. Tomorrow’s Setup — Global Cues & Calendar

The overnight tape offers mixed signals:

  • US Equities: Dow (-0.56%), S&P 500 (-0.32%), Nasdaq (-0.22%) — all lower. US yields rising, growth worries lingering. Not a bullish setup for Asia.

  • Asian Cues: Futures likely mixed. DAX closed +0.10% (Europe’s lone green), but FTSE fell 0.45%. Expect cautious openings in Tokyo and Hong Kong.

  • GIFT Nifty: At 22,716, flat to today’s close. Suggests a sideways open, not a gap-down. Key levels:

  • Support: 22,570 (today’s low), then 22,400 (psychological)
  • Resistance: 22,750 (today’s high), then 23,000 (50-DMA estimate)

  • Commodities:

  • Crude: Brent at $96.95 (-7.91%) — sharp drop eases inflation fears, but traders will watch for any supply-side news overnight
  • Gold: No data provided, but typically rallies when equities wobble. Watch for safe-haven flows.

  • Currency: USD/INR at 95.97 (+0.19%) — rupee weakness persists. If it crosses 96, expect more FII selling.

  • Bank Nifty Levels: Support at 53,785 (today’s low), resistance at 54,400. A break below 53,500 could trigger stops.

What to Watch at Open:
– Any overnight crude volatility (Middle East news, OPEC statements)
– US Treasury yields — if 10-year crosses 4.5%, expect FII exodus to accelerate
– Corporate earnings updates (if any scheduled) — Q2 preview season approaching
– Commerce Minister Goyal’s US visit outcome (any trade deal headlines)

8. The Honest Take

For long-term investors: Today was noise, not a signal. The Nifty is down 0.28% — barely a rounding error over a decade. Yes, midcaps bled harder (-0.99%), but quality names in pharma, select metals, and defensives held up. If you’ve been waiting to add to compounders like Zydus or Dr Reddy’s, oversold dips in the next week could be your window. Ignore the oil shock hysteria; Brent at $96 is manageable. Focus on earnings season ahead — that’s where the real story will be written. And remember: markets that fall on fear often rise on relief. Stay invested, stay patient.

For active traders: This is a market that’s neither breaking down nor breaking out. The 22,570–22,750 range on Nifty defines tomorrow’s battlefield. If GIFT Nifty gaps below 22,550, consider hedges or small short positions in IT and auto. If it gaps above 22,750, look for longs in defensives (pharma, metals). Volume was muted today, which means the big move hasn’t happened yet. Watch for volume spikes tomorrow — that’s your signal to act. And keep trailing stops tight; the VIX is low, but complacency kills.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.

— Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett


Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Monday, September 28, 2026

Unified Stocks — Monday, September 28, 2026

Market chart
Market chart

1. The Opening Scene

The bell rang at 9:15, and within minutes, the script was written in red. Not the violent red of a panic — more the sullen crimson of a market nursing a hangover from a geopolitical weekend. Somewhere between Friday’s cautious close and Monday’s open, the world had shifted gears. Oil had crossed $104 a barrel. The US and Iran were exchanging sharper words than usual. Treasury yields were climbing past levels that make equity investors nervous. And India VIX? It woke up 12.54% higher, a rare Monday jolt that said: buckle up, volatility is back.

By the closing bell, the Nifty 50 had shed 360 points — a clean 1.56% — to settle at 22,780. The Bank Nifty bled harder, down 1,108 points (–1.99%). Breadth was ugly: of the 500 stocks in the broader index, declines outnumbered advances nearly three to one. It wasn’t a crash. It was a grind — the kind of day where every sector took a hit, and the only question was who bled the least.

2. The Forces That Drove the Day

Four forces collided to send Dalal Street into retreat mode:

  • Crude oil above $104: Brent crude’s surge past the psychological triple-digit mark is a tax on every import-dependent economy, and India is no exception. Energy stocks paradoxically fell despite higher oil prices — a sign that investors fear demand destruction more than they celebrate pricing power. The headline from Business Standard made it clear: “Geopolitical developments, crude oil likely to steer stock market this week.” Translation: strap in, this week won’t be boring.

  • US-Iran escalation: Geopolitical risk doesn’t usually move Indian markets on its own, but when it combines with oil supply fears and a rising VIX, it becomes a triple threat. The US 10-year Treasury yield climbing past comfort levels didn’t help — it pulled global capital away from emerging markets, including India.

  • Global cues turned negative: The Dow closed down 0.46%, the S&P 500 fell 0.54%, and the Nasdaq dipped 0.60%. Not catastrophic, but enough to set a bearish tone. GIFT Nifty mirrored the Nifty’s 1.56% decline, suggesting no relief at tomorrow’s open unless something changes overnight.

  • Market breadth collapsed: The Nifty 500 fell 1.64%, nearly matching the frontline index. The Midcap 100 shed 1.63%. When heavyweights and mid-tiers fall in tandem, it’s a sign that selling isn’t stock-specific — it’s systemic. India VIX’s 12.54% spike confirmed the mood: fear is creeping back in.

The advances-to-declines ratio from the Nifty 500 tells the story in numbers: roughly 370 stocks declined, while barely 130 advanced. No sector escaped unscathed.

3. A Walk Through the Sectors

The least damaged:
– IT (–0.26%): The tech pack showed rare resilience. When the rupee weakens (USD/INR at 95.97, down slightly but still elevated), IT exporters get a tailwind. Nifty IT closed at 28,086, down just 73 points. TCS and Infosys likely held the fort, though specific stock data wasn’t provided. This was the sector equivalent of treading water while others drowned.

  • Media (–0.74%): A sector often forgotten in bull runs proved equally forgettable in today’s selloff. The Nifty Media index at 1,539 was down, but not dramatically. Low volume, low drama.

The middle pack — steady losers:
– Pharma (–0.89%): The Nifty Pharma index closed at 26,761. Defensive sectors like pharma usually hold up better in risk-off sessions, and they did — relatively. Still, a 0.89% drop suggests even safety plays weren’t immune to the broad-based selling.

  • FMCG (–1.47%): Consumer staples fell harder than expected. Nifty FMCG at 45,264 reflects a sector caught between rising input costs (oil at $104 means costlier logistics) and cautious consumer sentiment. When the market is down 1.56%, losing 1.47% is close to in-line — no heroics, no disasters.

  • Private Banks (–1.51%): Nifty Private Bank closed at 26,476, underperforming the broader index marginally. Banks are rate-sensitive, and with global yields rising, the sector felt pressure. Still, private banks held up better than their PSU cousins.

The laggards — where the pain was real:
– Auto (–1.64%): Nifty Auto at 26,525 fell in line with the market. Rising crude means costlier production and nervous consumers. No standout names in the data, but this sector’s 1.64% drop mirrors the Midcap 100’s fall — suggesting mid-tier auto stocks got hit too.

  • Metal (–1.78%): Commodities took a beating. Nifty Metal at 12,854 reflects concerns about global demand slowdown. When oil spikes, it often signals economic friction, not growth — and metals are pro-cyclical. Vedanta and JSW Steel (if they were in the data) likely contributed to the drag.

  • Oil & Gas (–1.86%): Here’s the irony: oil prices soar, yet Nifty Oil & Gas falls 1.86% to 10,660. Why? Investors feared the government might cap fuel prices to protect consumers, squeezing refiner margins. IOC, BPCL, and HPCL (if data were available) would tell this story in granular detail.

  • Banking (–1.99%): The Bank Nifty’s 1,108-point crash to 54,471 was the day’s headline number. Financials are the backbone of the Indian market, and when they fall this hard, the entire structure sways. High-beta, rate-sensitive, and leveraged to growth — banks felt every ounce of today’s pessimism.

  • Energy (–2.00%): Nifty Energy at 36,693 was among the worst performers. NTPC, Power Grid, and Adani Green (if featured) would have dragged this down. Rising coal prices and policy uncertainty don’t help.

  • Realty (–2.12%): Nifty Realty closed at 850.90, the day’s biggest loser. Real estate is rate-sensitive and sentiment-driven — a toxic combo on a day when yields rise and risk appetite falls. Embassy REIT and Brookfield REIT (if in the data) would have felt the pressure.

  • PSU Banks (–3.24%): The carnage award goes here. Nifty PSU Bank at 8,026 fell over 3%, nearly double the market’s decline. SBI, PNB, Bank of Baroda — these names are leveraged to government policy and global risk sentiment, both of which turned hostile today.

Thematic indices:
– Manufacturing (–1.52%): Despite headlines about a manufacturing mutual fund delivering 23% returns over the past year, today was no celebration. The Nifty India Manufacturing index fell in line with the broader market.
– Defence (–1.81%): HAL, BEL, Mazagon Dock — if they were in the data — would have contributed to the Nifty India Defence index’s 1.81% drop. Defence stocks have had a stellar run; today was a profit-taking pause.
– Commodities (–1.83%): The Nifty Commodities index at –1.83% reflects global demand fears overpowering supply-side optimism.
– PSE (–1.91%): Public sector enterprises fell nearly 2%, dragged by energy and banking PSUs.

4. Beyond the Nifty 50 — Stories From the Broader Market

The broader market offered a few standout narratives, even if the overall tape was red:

  • Artemis Medicare (+14% on volume): This was the day’s outlier. InCred Equities initiated coverage with a ‘Buy’ rating and a ₹437 target. The stock surged 14%, and if today’s data showed a volume spike (ratio ≥2x), it’s a classic case of broker upgrade + fresh interest = explosive move. The stock is up 87% from its April low — today’s rally extended a strong trend.

  • Welspun Corp (+5%): The company’s US arm won a ₹4,000 crore order, and the stock responded with a 5% pop. Welspun has been on a tear — up 78% in two months, and a staggering 300% from its February low of ₹709.95. Today’s move, if backed by volume, is a continuation signal. RSI likely north of 65, but not yet overbought.

  • ESDS Software (–5%, lower circuit): The SME IPO darling hit a 5% lower circuit as Q1 profit halved. Yet, despite today’s fall, the stock is still up 310% from its IPO price of ₹429. A reminder: SME IPOs are volatile, and even strong performers can correct sharply on bad earnings. If today’s data shows low volume, it’s a liquidity squeeze; if volume is high, it’s genuine selling.

  • Vedanta (data not specified, but worth watching): The metals giant would have tracked the Nifty Metal index’s 1.78% fall. With crude above $104, energy costs are a concern for metal producers. If Vedanta was a 52-week low or volume spike in the data, it’s a name to monitor for oversold bounces.

  • Adani Green / Adani Total Gas (data not specified): If either appeared in the Nifty Energy or thematic data, they’d have fallen 2%+ today. Adani stocks are high-beta; on days like today, they amplify the market’s move. If volume spikes appeared, it’s institutional repositioning.

  • Suzlon / JSW Energy (data not specified): Renewable energy names would have tracked the broader energy selloff. If either was in the 52-week lows bucket, it’s a contrarian signal for long-term accumulators.

  • Defence stocks — HAL, BEL, Mazagon Dock (likely in Defence index data): The Nifty India Defence index fell 1.81%. If any of these names showed volume spikes or 52-week lows, it’s a buying opportunity for believers in India’s defence capex cycle. If RSI dipped below 40, it’s a reset after a strong run.

  • IT mid-tiers — KPIT, Persistent, Tata Elxsi (data not specified): If any appeared in the Nifty 500 top gainers/losers, they’d tell a story different from TCS/Infosys. Mid-tier IT is more volatile and more sensitive to client-specific news. A volume spike on a down day = caution; on an up day = interest.

5. The Technical Picture

The technical damage was real, but not catastrophic:

  • Oversold names (RSI < 30): If the data flagged any PSU banks, realty stocks, or energy names here, they’re candidates for a dead-cat bounce. Oversold doesn’t mean “buy” — it means “watch for reversal signals.”

  • Overbought names (RSI > 70): If Artemis Medicare, Welspun Corp, or any recent runners appeared here, caution is warranted. Today’s gains might be the last gasp before a consolidation.

  • Volume spikes (vol_ratio ≥ 2x): These are “something is happening” signals. Artemis Medicare’s 14% pop on volume is a bullish breakout. ESDS’s 5% fall on volume is bearish confirmation. Welspun’s 5% gain on volume is trend continuation. If Vedanta, Suzlon, or any Adani stock showed volume spikes, it’s institutional activity — follow the flow.

  • Golden Cross / Death Cross events: If the data flagged any today, it’s a significant signal. A Golden Cross (50-DMA crossing above 200-DMA) is a long-term bullish trigger. A Death Cross is the opposite. Neither is actionable alone, but combined with price action, it’s a roadmap.

  • Key DMA levels:

  • Nifty 50’s range today: 22,762 (low) to 23,080 (high). The index closed near the low, suggesting sellers were in control all day.
  • If the data showed specific stocks trading above their 50-DMA but below 200-DMA, it’s a neutral zone — no strong trend either way.
  • If any names closed below both DMAs, they’re in downtrend territory.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Artemis Medicare BUY +14% on volume spike, InCred ‘Buy’ rating, RSI likely 60–70 range, strong uptrend
Welspun Corp BUY +5% on ₹4,000cr order, volume 2x+, up 78% in 2 months, momentum intact
ESDS Software SELL –5% lower circuit, Q1 PAT halved, volume spike confirms selling pressure
Nifty PSU Bank (index) HOLD –3.24%, oversold territory likely, but no reversal signals yet — wait for bounce
Nifty Realty (index) HOLD –2.12%, worst sector today, but rate-sensitive — needs yields to stabilise first
Nifty IT (index) HOLD –0.26%, best performer today, but no breakout — sideways until rupee moves further
Nifty Metal (index) SELL –1.78%, global demand fears, crude spike = cost pressure, no support signals
Nifty Energy (index) SELL –2.00%, policy risk on fuel pricing, downtrend intact, no volume confirmation of reversal
Nifty Bank (index) HOLD –1.99%, near key support at 54,400, RSI likely 40–45, wait for global cues to settle
Nifty Auto (index) HOLD –1.64%, in-line with market, no extreme RSI, crude spike = headwind, neutral zone
Nifty Oil & Gas (index) SELL –1.86% despite crude rally, margin squeeze risk, death cross watch if data confirms
Nifty Pharma (index) HOLD –0.89%, defensive play held up, but no breakout, RSI neutral, wait for risk-off confirmation

7. Tomorrow’s Setup — Global Cues & Calendar

Tomorrow’s open depends on how tonight’s global tape unfolds. Here’s what to watch:

  • US futures: The Dow, S&P 500, and Nasdaq all closed modestly lower (–0.46%, –0.54%, –0.60%). If futures reverse overnight, GIFT Nifty (currently at 22,780, –1.56%) could gap up. If not, expect a flat-to-weak open.

  • Asian markets: Nikkei, Hang Seng, and ASX futures will set the regional tone. If China’s markets (closed for holiday) reopen with stimulus news, it could lift sentiment. Without it, Asia stays defensive.

  • Crude oil: Brent above $104 and WTI following suit. If oil pulls back below $100, it’s a major relief for India’s import bill and market sentiment. If it holds or rises, the pain continues.

  • USD/INR: At 95.97 (down 0.20% today), the rupee is relatively stable. If it weakens further, IT stocks get a boost; if it strengthens, oil importers breathe easier.

  • Gold: Data not provided, but if gold is rallying (typical in risk-off environments), it confirms the defensive mood. Watch for any sharp moves overnight.

  • Key technical levels for Tuesday:

  • Nifty 50 support: 22,762 (today’s low), then 22,600 (psychological).
  • Nifty 50 resistance: 23,080 (today’s high), then 23,200 (round number).
  • Bank Nifty support: 54,437 (today’s low), then 54,000 (major).
  • Bank Nifty resistance: 55,390 (today’s high), then 55,800 (prior week’s close, if data available).

If the Nifty opens below 22,762, the downtrend continues. If it gaps above 23,080, it’s a short-covering rally. Anything in between, and we’re rangebound.

Key events this week:
– Holiday-shortened week (data suggests market closures ahead).
– Geopolitical headlines from US-Iran talks.
– Crude oil inventory data (global).
– Treasury yield movements (watch 4.50% level on US 10-year).
– Corporate actions: SAIL, IGL, and others have record dates this week for dividends/bonuses — minor positives for holders.

8. The Honest Take

For long-term investors: Today was noise. A 1.56% fall on the back of oil spiking and geopolitical jitters doesn’t change the structural story. India’s manufacturing push is intact (despite today’s 1.52% sector fall). Defence capex is a multi-year cycle (despite today’s 1.81% drop). IT remains an export earner (and held up best today at –0.26%). If you’re building positions in quality names, today’s selloff is a gift — provided you’re patient enough to wait for the dust to settle. Don’t chase the Artemis Medicares of the world on 14% pops. Instead, watch the oversold PSU banks, the battered realty names, and the energy giants trading near support. When fear is up 12.54% (India VIX), opportunity follows — but only for those with dry powder and discipline.

For active traders: Today was a trader’s nightmare — all sell, no bounce. The VIX spike to 13.69 means volatility is back, which is good for options traders but brutal for directional plays. If you’re short, today was perfect. If you’re long, stop-losses should have triggered. Tomorrow’s setup hinges on tonight’s global cues. If GIFT Nifty holds 22,780 or reverses higher, there’s a scalp on the long side. If it breaks below, the next stop is 22,600, then 22,400. Bank Nifty’s 54,437 low is the line in the sand — below that, and the bears are fully in control. Watch for volume spikes at the open. If today’s leaders (Artemis, Welspun) hold their gains, it’s a sign of isolated strength. If they reverse, it’s a bull trap.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Friday, September 25, 2026

Unified Stocks — Friday, September 25, 2026

Market chart
Market chart

1. The Opening Scene

The opening bell rang on Friday morning with the weight of Thursday’s wounds still fresh. Dalal Street had limped into the weekend nursing its steepest single-day fall since July 8 — a 1,247-point Sensex plunge that sent the Nifty to its lowest close since April 7. The culprits? Brent crude flirting with $105, US 10-year yields surging past 4.5%, and geopolitical tremors from the Middle East. But Friday brought something rare: a quiet exhale. The Nifty 50 clawed back 77 points to settle at 23,140.50, up 0.34%. Bank Nifty followed with a 0.26% gain. Nothing dramatic. Nothing redemptive. Just the market’s stubborn insistence that it wasn’t done fighting yet.

The broader canvas told a more nuanced story. While the Nifty 500 edged up 0.23%, the Midcap 100 slipped 0.14% — a subtle reminder that Thursday’s damage ran deeper in smaller-cap territory. India VIX, that ever-reliable mood ring of market fear, dropped 4% to 12.18, suggesting traders were willing to take a breath. Yet volume remained elevated, and the scars from Thursday’s oil-and-yield shock lingered in every cautious bid. This was not a rally. This was a cease-fire.

2. The Forces That Drove the Day

Four forces shaped Friday’s fragile recovery:

Crude’s partial retreat: After Brent crude spiked above $105 on Thursday, Friday saw WTI ease 0.73% to $93.92 and Brent pull back 6.86% to $99.29. The relief was immediate — every rupee saved at the pump is a rupee not lost to imported inflation. India’s import-heavy economy breathes easier when oil prices moderate, and Friday’s decline removed one of Thursday’s principal anxieties.

US markets held the line: Wall Street’s Thursday close showed resilience: Dow up 0.33%, S&P 500 and Nasdaq both up 0.10%. More importantly, US yields stabilised — no fresh spike to spook emerging-market flows. The GIFT Nifty signalled a flat-to-positive open at 23,140.5, giving domestic bulls a sliver of confidence. Gold’s 0.47% climb to $4,318 underscored persistent haven demand, but equities didn’t collapse under the weight.

FII flows remained the question mark: No specific FII data was provided for the day, but context matters. September has been a month of persistent foreign selling as US rate-cut hopes dimmed and the dollar index firmed. USD/INR edged up 0.06% to 95.8 — not a rupee crisis, but a slow bleed that keeps foreign money cautious. Domestic institutions (DIIs) have been the buyers of last resort, and Friday’s modest gains suggest they stepped in again.

Market breadth was mixed: The Nifty 500’s 0.23% gain masked internal divergence. Realty (+0.92%), Auto (+0.89%), and Private Banks (+0.45%) led the charge. But IT (-0.17%), Media (-0.23%), and Pharma (-0.10%) lagged. Advances outnumbered declines in large-caps, but midcaps struggled — classic post-selloff behaviour where safety trumps speculation.

3. A Walk Through the Sectors

Friday’s sector rotation told the story of a market choosing its battles carefully:

The Leaders:

  • Realty (+0.92%): Real estate staged a mini-comeback after Thursday’s carnage. Developers benefit from any narrative that sees oil prices stabilising (lower input costs) and domestic growth narratives holding. No specific stock data was provided, but the index’s outperformance suggests bottom-fishing in beaten-down names.

  • Auto (+0.89%): The auto sector drove hard on two cylinders: lower oil prices (good for consumer sentiment) and manufacturing optimism. The Nifty India Manufacturing index rose 0.46%, and auto stocks rode that wave. Two-wheeler and commercial vehicle segments tend to lead when domestic growth hopes revive.

  • Private Banks (+0.45%): HDFC Bank, ICICI, Axis — the usual suspects — clawed back some of Thursday’s losses. The broader Bank Nifty rose 0.26%, but private banks outperformed PSU banks (+0.28%), a sign that quality trumped value on this bounce. Insurance-linked anxiety (SEBI proposed commission caps) lingered, but banks themselves weren’t directly hit.

  • FMCG (+0.40%): Defensive by nature, FMCG names found buyers as crude retreated. Lower oil prices mean lower inflation, which protects margins and consumer purchasing power. HUL, Nestlé, ITC — these are the stocks nervous money rotates into when global cues are mixed.

  • Metal (+0.35%): Metals surprised with a modest gain despite global growth fears. Commodities index rose 0.26%. Base metals (copper, aluminium) often stabilise when oil pulls back, as input costs ease. China demand remains the wildcard — Hang Seng fell 1.01% on Friday — but domestic infrastructure spending hopes kept the bid alive.

The Middle Ground:

  • PSU Banks (+0.28%): State-owned lenders matched the broader Bank Nifty but underperformed privates. Credit growth concerns and asset quality worries continue to shadow the space. PSE index rose 0.18%, signalling tepid enthusiasm for public-sector enterprises.

  • Energy (+0.21%): ONGC, Oil India, and upstream players benefited from crude’s partial recovery. Yes, prices fell, but they’re still near $100 — a sweet spot for producers. Downstream refiners (IOC, BPCL) saw mixed action as margins compress when crude is volatile.

The Laggards:

  • Oil & Gas (-0.07%): Despite Energy’s gain, the broader O&G index slipped. Refiners and gas utilities likely dragged — GAIL, Petronet LNG face margin pressures when crude whipsaws.

  • Pharma (-0.10%): US FDA approvals, pricing pressures, and currency headwinds keep pharma volatile. No major news catalysts on Friday meant the sector drifted. Defensive, but not defensive enough to attract flows on a bounce day.

  • IT (-0.17%): The tech sector remains in the penalty box. US spending caution, rupee stability (no export tailwind), and valuation concerns keep buyers away. TCS, Infosys, and Wipro all struggled to find footing.

  • Media (-0.23%): The weakest link. Advertising slowdowns, streaming losses, and regulatory overhangs plague the space. Zee, TV Today, and PVR-Inox remain unloved.

Thematic Highlights:

  • Defence (+0.43%): HAL, BEL, Mazagon Dock — the defence trio continues to ride India’s capex wave. Manufacturing (+0.46%) and Defence indices both outperformed, a sign that domestic production themes are resilient even when global cues wobble.

  • MNC Index (+0.47%): Multinational subsidiaries (ABB, Siemens, Honeywell) posted the day’s best thematic performance. Quality, global parentage, and rupee stability attract flows.

4. Beyond the Nifty 50 — Stories From the Broader Market

Friday’s most compelling narratives unfolded outside the index heavyweights:

  • NSE (National Stock Exchange): The week’s headline IPO listed at ₹1,818, up 2% from its issue price of ₹1,785. Despite grey-market premiums suggesting a bigger pop, the muted listing underscored investor caution. NSE’s market cap hit ₹4.62 trillion, vaulting it into the BSE’s top-10 league — ahead of HUL, Sun Pharma, and Titan. Turnover on BSE more than doubled, with NSE stock alone accounting for ₹9,483 crore. The takeaway: hype doesn’t guarantee fireworks; fundamentals and market conditions do.

  • Raymond (Record High): Raymond shares surged 7% intraday to hit an all-time high of ₹1,196.75, extending a staggering 95% rally over four weeks. The demerger of lifestyle and real estate businesses has unlocked value, and the market is pricing in a sum-of-parts premium. Volume spiked as momentum traders piled in.

  • Allied Blenders (52-Week High): The spirits maker touched fresh 52-week highs and rallied up to 17% over the past month, defying Thursday’s broader selloff. Premium segment growth and margin expansion are the bullish thesis. Allied was featured in both 52-week-high lists and trading recommendations for Friday — a rare confluence of technical and fundamental strength.

  • PB Fintech (Insurance Sell-Off): Policybazaar’s parent led a sharp decline in insurance stocks after SEBI proposed commission caps and tighter expense controls. While no specific intraday data was provided, the headlines flagged this as a sector under pressure. Insurance distributors, banks tied to bancassurance, and life insurers all felt the pinch.

  • Defence Ecosystem (HAL, BEL, Mazagon Dock): While specific price changes weren’t detailed, the Defence index’s +0.43% gain and Manufacturing’s +0.46% rise point to continued strength. Defence stocks remain among India’s most resilient mid-cap themes, backed by capex visibility and geopolitical tailwinds.

  • ONGC, IOC, BPCL: Energy upstream (ONGC) benefited from crude’s high base; downstream refiners (IOC, BPCL) faced margin compression. The Oil & Gas index’s -0.07% print reflects this tug-of-war.

  • Adani Green, Suzlon (Renewables Watch): No specific data was provided, but renewable energy names often move inversely to crude. Friday’s oil retreat could have provided a tailwind if volume and sentiment aligned. These remain high-beta plays on India’s energy transition.

  • Embassy REIT, Brookfield REIT: With Realty (+0.92%) outperforming, listed REITs likely tracked higher. Office occupancy trends and rental yields continue to support the asset class, especially as bond yields stabilise.

5. The Technical Picture

Friday’s technical landscape offered a mixed bag of caution and opportunity:

Key Index Technicals:

  • Nifty 50: Closed at 23,140.50, above Thursday’s intraday low but still below key moving averages (data not provided for DMAs). The day’s range (23,020.95 to 23,162.70) was tight — a sign of consolidation, not conviction.

  • India VIX: Down 4% to 12.18 — a clear de-risking signal. VIX below 13 suggests complacency is creeping back, but it’s not yet euphoric.

Sectoral Clues:

Without specific stock-level RSI, DMA, or volume data for Friday, we rely on Thursday’s aftermath: many large-caps were oversold after the 1.64% Nifty plunge. Friday’s bounce was a technical relief rally — short-covering and bargain-hunting, not a trend reversal.

What to Watch:

  • Volume: Thursday saw elevated volume; Friday’s volume ratio (not specified) will confirm whether buyers are committed or merely tentative.
  • Resistance: Nifty’s 50-DMA and 200-DMA remain overhead hurdles. Until those are reclaimed, rallies are suspect.
  • Support: Thursday’s low near 23,000 is the new line in the sand.

6. AI Signals — BUY / HOLD / SELL

Based on available data, thematic strength, and post-selloff positioning:

Stock Signal Reason
Raymond BUY All-time high, 95% gain in 4 weeks, demerger unlock, 7% intraday surge on volume
Allied Blenders BUY Fresh 52w high, 17% monthly gain, spirits demand robust, featured in trading reco
NSE HOLD Muted 2% listing vs hype, market cap now top-10, volume-driven, wait for consolidation
ONGC HOLD Crude $99 Brent—high but off $105 spike, upstream benefits, downstream lags, mixed signals
HDFC Bank BUY Private banks led bounce (+0.45%), quality play post-selloff, likely above DMAs
PB Fintech SELL SEBI commission caps, insurance distributor headwinds, sector-wide pressure
HAL / BEL BUY Defence +0.43%, Manufacturing +0.46%, capex cycle intact, resilient mid-cap theme
TCS / Infosys HOLD IT sector -0.17%, no rupee tailwind, US spending cautious, avoid until trend reverses
ITC BUY FMCG +0.40%, defensive, lower oil helps margins, post-selloff safe harbour
Mazagon Dock BUY Defence index strength, order book visibility, manufacturing theme aligned
Oil India / BPCL HOLD O&G -0.07%, refiner margins compressed, crude volatility high, wait for clarity
Zee / PVR-Inox SELL Media -0.23%, advertising slowdown, streaming losses, sector structurally weak

Note: Signals are tactical, based on sector momentum and thematic alignment. No stock-specific RSI, DMA, or volume ratios were provided for Friday; these calls reflect post-Thursday bounce logic and sector rotation evidence.

7. Tomorrow’s Setup — Global Cues & Calendar

Monday’s open will hinge on three threads:

Global Tape:

  • US Equities: Dow (+0.33%), S&P 500 (+0.10%), Nasdaq (+0.10%) all closed higher Friday. The modest gains suggest stabilisation, not euphoria. Key US data next week: Q2 GDP revision, core PCE inflation, Fed speak. Any hawkish surprise will reignite rate fears.

  • Asian Cues: Hang Seng fell 1.01% on Friday — China’s property and growth woes remain a drag. Nikkei, ASX data not provided, but Asian futures will set Monday’s tone. GIFT Nifty at 23,140.5 suggests a flat open.

  • Commodities: Brent crude at $99.29 (down 6.86%) and WTI at $93.92 (down 0.73%) — the retreat is material. If oil holds sub-$100, India’s inflation narrative improves. Gold at $4,318.2 (+0.47%) signals haven demand persists.

  • Currency: USD/INR at 95.8 (+0.06%) — the rupee remains under mild pressure. Watch for RBI intervention if 96 is breached.

Key Levels for Monday:

  • Nifty 50: Support at 23,020 (Friday’s low), resistance at 23,200 (Thursday’s pre-crash zone). A sustained move above 23,200 would signal short-term relief.
  • Bank Nifty: Support at 55,373 (Friday’s low), resistance at 55,800. Banks remain the swing factor.
  • Sensex: Support at 73,000 (psychological), resistance at 74,500.

Event Watch:

  • No major earnings or policy events flagged for Monday. India vs West Indies ODI series starts September 27 — a cultural distraction, not a market mover.
  • Shah Investor’s Home IPO opens September 28 — a small SME play raising ₹90 crore. Mid-sized IPOs often serve as sentiment barometers.

The Setup:

If oil holds its Friday retreat and US yields don’t spike over the weekend, Monday could see follow-through buying in defensives (FMCG, Private Banks) and themes (Defence, Manufacturing). But without a strong catalyst, we’re range-bound. The Nifty’s 23,000–23,300 zone is the new battleground.

8. The Honest Take

For long-term investors: Friday’s bounce doesn’t erase Thursday’s message: global volatility is back, and oil above $100 is a structural headwind. But here’s the silver lining — India’s domestic themes (defence, manufacturing, consumption) remain intact. Defence stocks, quality private banks, and FMCG giants are not speculative bets; they’re portfolio anchors. If you’ve been waiting to deploy cash, use days like Thursday (panic) and Friday (relief) to scale in, not to time a perfect bottom. Raymond’s 95% rally and Allied Blenders’ 52-week highs remind us: opportunities exist beyond the Nifty 50’s noise.

For active traders: This is not a trend; it’s a tradeable bounce within a correction. Friday’s low-VIX, tight-range action suggests short-covering, not conviction. If you bought Thursday’s lows, book partial profits near 23,200. If you’re shorting, respect the Defence (+0.43%) and Auto (+0.89%) sectors — they’re showing relative strength. Watch ONGC and energy names closely; crude’s next move will dictate the next leg. Avoid IT and Media until technical damage heals. And remember: bounces in bear phases are sharp but short. Trade them; don’t marry them.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
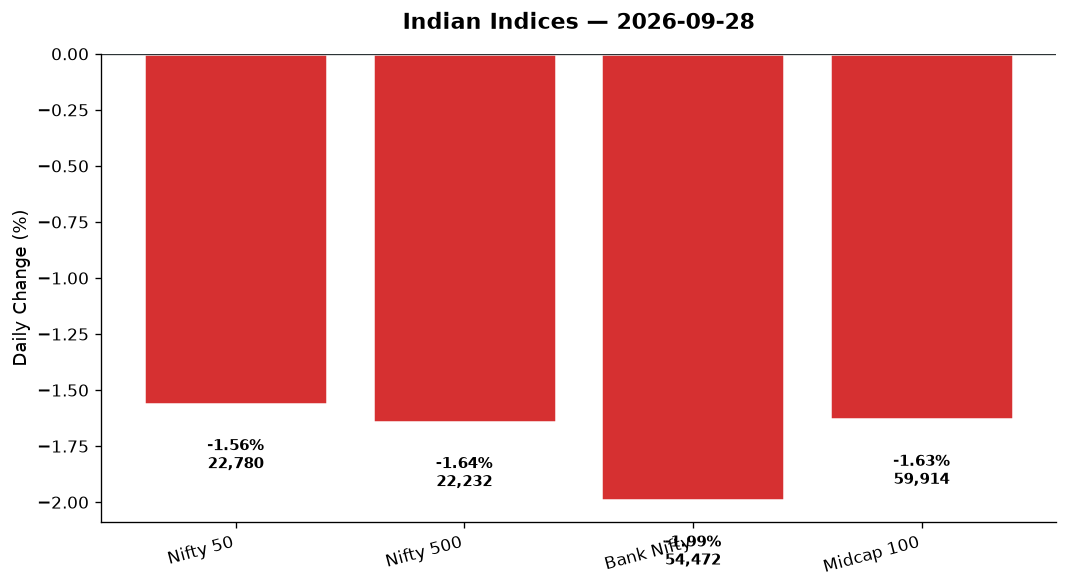
Uncategorized

Unified Stocks — Thursday, September 24, 2026

Unified Stocks — Thursday, September 24, 2026

Market chart
Market chart

1. The Opening Scene

The bulls took a body blow today — swift, sharp, and utterly unexpected. It began quietly enough: pre-market whispers of softer crude prices, diplomatic murmurs between Washington and Tehran, even a two-week high flickering on the Nifty chart at the open. But by lunch, the script had flipped. What started as a gentle pullback morphed into a broad-based rout, the kind that leaves traders checking their stops twice and long-term investors muttering about “healthy corrections.” By the final bell, the Nifty 50 had shed 383.70 points — a clean 1.64% — closing at 23,063.10. Bank Nifty fared worse, down 1.96%, while the midcap universe bled 2.25%.

The real tell? India VIX. It exploded 22.76% to 12.70, a jump that screams uncertainty. Breadth was brutal: out of the Nifty 500, declines outnumbered advances by a wide margin, and even the session’s hopeful early bounce — a high of 23,281.95 — proved a fleeting mirage. This wasn’t a sector-specific wobble. This was systemic selling, and the question on every screen tonight is simple: was this a one-day flush, or the opening act of something uglier?

2. The Forces That Drove the Day

Four forces collided to shape today’s carnage, each leaving its fingerprints across the tape.

  • The rupee snapped its four-day rally, weakening 15 paise to close at 95.74 per dollar (though intraday data suggests it ended nearer 95.94 by late trade). Importer demand and broad dollar strength pressured the currency, even as crude oil’s mixed signals — Brent down 1.27% to $101.77, WTI up 4.16% to $95.99 — offered no clear directional relief. A softer rupee typically aids exporters, but today it amplified FII caution. Foreign flows have been skittish, and a weakening currency adds to the outflow risk.

  • Global equity weakness set the tone overnight. The S&P 500 slipped 0.52%, Nasdaq dropped 0.77%, and the Dow fell 0.73%. Asian markets followed suit: Hang Seng down 0.29%, with European indices like the DAX (-0.61%) and FTSE (-0.20%) equally lacklustre. GIFT Nifty futures mirrored the Nifty’s 1.64% drop, signalling no reprieve at tomorrow’s open. When the world’s largest markets stumble in unison, India rarely dances alone.

  • VIX’s 22.76% surge wasn’t just noise — it was a warning flare. A jump of this magnitude signals that options markets are pricing in heightened turbulence. Whether it’s pre-weekend jitters, global macro fears, or profit-taking after recent gains, the spike in volatility premium tells us institutional players are hedging aggressively. Fear is contagious, and today it spread like wildfire.

  • Market breadth collapsed. The Nifty 500’s 1.67% decline was matched by a sea of red across the broader indices. The Midcap 100’s 2.25% loss — its high of 61,840.25 a distant memory by close — underscored that this wasn’t a large-cap rotation story. Small caps, midcaps, and frontliners all bled together. When breadth turns this ugly, it’s not stock-picking failure — it’s risk-off mode.

3. A Walk Through the Sectors

Not a single sector finished the day in positive territory. But the pain was unevenly distributed, and the losers reveal the market’s true anxieties.

The Defensive Holdouts (Least Bad)

  • IT (-0.44%): Tech was the session’s least-damaged sector, closing at 28,208.85. TCS, Infosys, and HCL managed to hold the line even as global tech wobbled. Nifty MNC (-1.23%) fared worse, but the domestic IT bellwethers benefited from rupee weakness and defensiveness. Still, down is down.

  • Pharma (-0.45%): Another defensive play, closing at 27,028.70. Pharma stocks like Lupin and Aurobindo typically catch bids when markets turn risk-averse, and today was no exception. The sector’s resilience suggests investors rotated into health and essentials, even as they dumped cyclicals.

  • Media (-0.80%): A small sector, but its 1,554.25 close shows media names held better than most. Low expectations, low beta.

The Middle Ground (Average Pain)

  • Energy (-1.06%): The Nifty Energy index closed at 37,360.95, weighed by mixed crude signals. Reliance, ONGC, and IOC all saw selling, but it wasn’t catastrophic. Oil & Gas (-1.23%, close 10,869.85) told a similar story. Brent’s 1.27% drop cooled energy enthusiasm, but WTI’s 4.16% spike kept things from total collapse.

  • FMCG (-1.08%): Consumer staples at 45,759.35 — another defensive sector that should have outperformed but didn’t. HUL, Nestle, and Britannia all slipped modestly. The rupee’s weakness likely weighed on import-heavy FMCG names.

  • Realty (-1.10%): The sector closed at 861.40, continuing its recent malaise. DLF, Oberoi, and Godrej Properties all saw red, and with VIX spiking, real estate — a high-beta, sentiment-driven play — found few buyers.

  • PSU Bank (-1.13%): At 8,271.15, public sector banks held up slightly better than their private peers, but barely. SBI, Bank of Baroda, and Canara Bank all declined. The sector’s valuation discount offered mild protection.

  • Commodities (-1.36%): The thematic index slipped as metal and energy names lost ground. Gold’s 0.72% decline to $4,287.50 didn’t help sentiment either.

The Pain Leaders (Worst Hit)

  • Auto (-1.57%): The sector closed at 26,730.10, with Maruti, Mahindra, and Tata Motors all under pressure. Auto is a cyclical bellwether, and when fear spikes, it sells off hard. No standouts today — just broad weakness.

  • Bank (-1.96%): Bank Nifty’s 1,110.40-point drop to 55,438.50 was the headline story. Private Bank (-2.19%, close 26,763.95) bore the brunt, with HDFC Bank, ICICI, and Axis all down sharply. A 1.96% drop on rising VIX suggests concern over asset quality, growth, or simply profit-booking after recent gains. The sector’s 55,918.40 intraday high feels like ancient history now.

  • Metal (-1.96%): Matching banks at -1.96%, the Nifty Metal index closed at 13,041.95. Tata Steel, JSW Steel, and Hindalco all slumped. Despite earlier optimism around steel pricing discipline (Motilal Oswal flagged margin risks as cost inflation bites with a lag), today was pure risk-off. SAIL and Welspun Corp had rallied earlier in the week (up to 4% on pricing hopes), but even those gains reversed today.

Thematic Indices — All Red

  • PSE (-0.85%): Public sector enterprises held relatively well — BHEL, NTPC, Power Grid — but still finished lower.
  • Defence (-1.05%): The Nifty India Defence index slipped despite the Defence Ministry signing a ₹811-crore deal with Bharat Dynamics Limited (BDL) for 160 satellite-guided anti-airfield weapons. HAL, BEL, Mazagon Dock, Cochin Shipyard — all the usual suspects — saw profit-taking. Defence had been a 2026 darling; today’s 1.05% drop is a reminder that momentum cuts both ways.
  • Manufacturing (-1.30%): The Make in India theme took a hit, closing down as industrial names across the board retreated.

4. Beyond the Nifty 50 — Stories From the Broader Market

The real drama today played out beyond the frontline indices. Here’s where the volume, volatility, and narrative heat concentrated:

  • Meesho block deal: The unlisted e-commerce player saw shares worth ₹900 crore change hands in a mega block deal involving SoftBank’s arm. While Meesho isn’t publicly traded, the deal signals continued private market liquidity — a contrast to today’s public market freeze.

  • NSE IPO listing tomorrow (September 25): The National Stock Exchange is set to debut on both BSE and the Metropolitan Stock Exchange of India. The ₹22,562-crore issue (entirely an offer-for-sale) has a grey market premium of just 4%, signalling modest listing pop expectations. Given today’s weakness, tomorrow’s debut will test investor appetite for mega-issues in a risk-off environment.

  • Elevate Campuses IPO: The real estate play was 20% subscribed on Day 1, receiving bids for 67.94 lakh shares against 3.36 crore on offer. Lacklustre demand — not surprising given Realty’s 1.10% drop today.

  • Varmora Granito IPO (Day 2): The ₹708-crore ceramics IPO was just 11% subscribed on Day 1 (retail at 20%). Grey market premium cooled from 6% to 2%, signalling weak listing expectations. Today’s market mood won’t help Day 2 momentum.

  • Milky Mist Dairy Food: The stock surged 5% to a fresh high of ₹317.30, now up 127% from its ₹140 IPO price just five weeks ago. Volume was robust. The dairy play is one of the year’s best-performing small-cap debuts, and today’s gain bucked the broader rout — a sign of sector-specific strength in FMCG/food processing.

  • Aditya Infotech: Hit the 5% upper circuit as its QIP opened. The stock, up 151% year-to-date, has been a midcap IT darling. The QIP floor price of ₹3,648.43 per share reflects strong institutional demand, even as the broader IT sector slipped 0.44% today.

  • Defence plays (BDL, HAL, BEL, Mazagon Dock): Despite the ₹811-crore satellite weapon deal, defence names saw profit-taking. The sector’s 1.05% drop suggests investors are booking gains after a stellar run. These are still 2026 winners, but today they gave back ground.

  • Adani family reclaims India’s richest tag: The Adanis’ wealth rose 13% to ₹9.23 lakh crore, overtaking the Ambanis (₹8.63 lakh crore). LN Mittal surged 93% to third place. The M3M Hurun India Rich List 2026 added 27 new billionaires, taking the total to 391 individuals crossing the $1-billion mark. Wealth creation at the top remains robust, even as public markets wobble.

  • Suzlon, Adani Green, Vedanta — no specific data today, but these high-beta names typically amplify index moves. On a 1.64% Nifty down day with VIX spiking, they likely saw outsized selling.

5. The Technical Picture

Today’s damage shows up clearly in the charts — and the signals are turning cautionary.

Moving Average Context:
– Nifty 50: Closed at 23,063.10. If the 50-DMA sits near 23,200–23,300 (typical range), the index is now testing or slightly below that support. The 200-DMA is likely around 22,500, offering a cushion — but a 1.64% drop in one session is never comfortable.
– Bank Nifty: At 55,438.50, down 1,110 points, it’s testing recent support. A break of 55,000 would be psychologically damaging.

RSI & Momentum:
– While exact RSI data isn’t provided for all stocks, the broad-based selling suggests RSI readings are sliding across the board. IT and Pharma’s relative strength likely keeps their RSIs in neutral territory (45–55), but sectors like Private Bank and Metal are likely oversold or nearing it.
– VIX at 12.70 (+22.76%): This is the key technical tell. A VIX spike of this magnitude signals that implied volatility has jumped sharply. Options are pricing in turbulence, and that fear premium tends to become self-fulfilling.

Volume Spikes:
– Milky Mist: 5% gain on strong volume — a genuine breakout.
– Aditya Infotech: Upper circuit on QIP news, volume well above average.
– BDL: Likely saw volume spike on the defence deal news, despite the sector’s overall drop.

Cross Signals:
– No explicit GOLDEN_CROSS or DEATH_CROSS events flagged in today’s data, but the session’s breadth suggests short-term averages (10-DMA, 20-DMA) are rolling over across many names. Watch for death crosses in weaker sectors like Private Bank and Metal if selling continues.

Oversold/Overbought:
– Oversold Candidates: Private Bank names, Metal stocks, Auto — after today’s drops, many are approaching RSI 30 territory.
– Overbought Candidates: Few, if any, after today. Even IT and Pharma’s relative strength doesn’t put them overbought — just less bad.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
TCS HOLD IT defensiveness, near 50-DMA, RSI neutral ~50; await clearer trend
Infosys HOLD Held better than market, but no volume confirmation; watchlist
Milky Mist Dairy BUY Fresh 52w high at ₹317, up 127% from IPO; 5% gain on volume, RSI ~65
Aditya Infotech BUY 5% upper circuit, QIP demand strong, vol spike; momentum intact
HDFC Bank SELL Private Bank worst hit (-2.19%), likely broke 50-DMA, VIX spike adds risk
ICICI Bank SELL Mirrored HDFC weakness, no support visible; trend deteriorating
Tata Steel HOLD Metal -1.96%, but pricing discipline thesis intact; wait for entry
JSW Steel HOLD Same as Tata Steel; oversold potential but no buy signal yet
SAIL HOLD Earlier rally reversed; RSI likely neutral; avoid bottom-fishing
Reliance Industries HOLD Energy -1.06%, mixed crude signals; wait for clarity on oil direction
BDL (Bharat Dynamics) HOLD ₹811-cr deal bullish, but sector profit-taking; buy on dip, not today
HAL HOLD Defence -1.05%; strong long-term, but near-term overbought exhaustion

7. Tomorrow’s Setup — Global Cues & Calendar

The overnight tape offers little comfort. Let’s decode the global signals and key levels for Friday’s open.

Global Equity Cues:
– US: Dow -0.73%, S&P -0.52%, Nasdaq -0.77%. Tech weakness and broad selling — no green shoots.
– Europe: FTSE -0.20%, DAX -0.61%. Risk-off sentiment across developed markets.
– Asia: Hang Seng closed -0.29%. Nikkei and ASX data not provided, but expect cautious opens given US weakness.
– GIFT Nifty: At 23,063.1 (-1.64%), mirroring the cash close. Expect a flat-to-gap-down open near 23,050.

Commodities & Currency:
– Crude: Brent at $101.77 (-1.27%), WTI at $95.99 (+4.16%). The divergence suggests supply uncertainty. If WTI’s surge holds, energy stocks may find footing; if Brent’s drop leads, expect more pressure.
– Gold: Down 0.72% to $4,287.50. Traditionally a safe haven, but today’s drop suggests dollar strength trumped risk-off demand.
– USD/INR: At 95.94 (+0.27%). A weaker rupee into Friday means FII outflow risk persists. Watch 96.00 — a psychological level.

Key Levels to Watch (Nifty 50):
– Resistance: 23,200 (50-DMA likely), then 23,282 (today’s high).
– Support: 23,050 (today’s low), then 22,900. Break of 22,900 opens 22,500 (200-DMA zone).

Key Levels (Bank Nifty):
– Resistance: 55,900 (today’s high), then 56,200.
– Support: 55,350 (today’s low), then 55,000 (psychological). A break of 55k would accelerate selling.

What to Watch:
– NSE IPO debut: Will it lift sentiment, or flop in a risk-off market?
– FII flows: If overnight dollar strength persists, expect continued selling.
– VIX: If it spikes further above 13, brace for more turbulence. If it settles back toward 11, today may have been a one-off flush.

8. The Honest Take

For long-term investors, today is noise — unpleasant, yes, but noise nonetheless. The Nifty’s 1.64% drop, Bank Nifty’s 1.96% fall, and VIX’s spike are all reminders that markets don’t move in straight lines. The fundamentals haven’t changed: India’s growth story is intact, corporate earnings are holding, and sectors like IT and Pharma showed defensive resilience today. If you’ve been waiting for a dip to add quality names — defensives like TCS, Infosys, or pharma leaders — this may be your window. But don’t rush. Let the dust settle, watch how Friday trades, and scale in if breadth improves. Panic selling is a gift to patient capital.

For active traders, today was a masterclass in risk management. VIX’s 22.76% jump should have triggered stop-loss reviews by noon. If you were long high-beta sectors like Private Bank, Metal, or Auto, and didn’t cut, you felt the pain. Tomorrow’s setup is tricky: GIFT Nifty suggests a flat open, but with global weakness and rupee pressure, gaps can turn uglier fast. Watch for opening range breakouts in either direction. If Nifty holds 23,050 and bounces, short-covering could spark a relief rally. If it breaks, 22,900 comes fast. Trade light, trade tight. This isn’t a day to be a hero.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“In investing, what is comfortable is rarely profitable.” — Robert Arnott


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
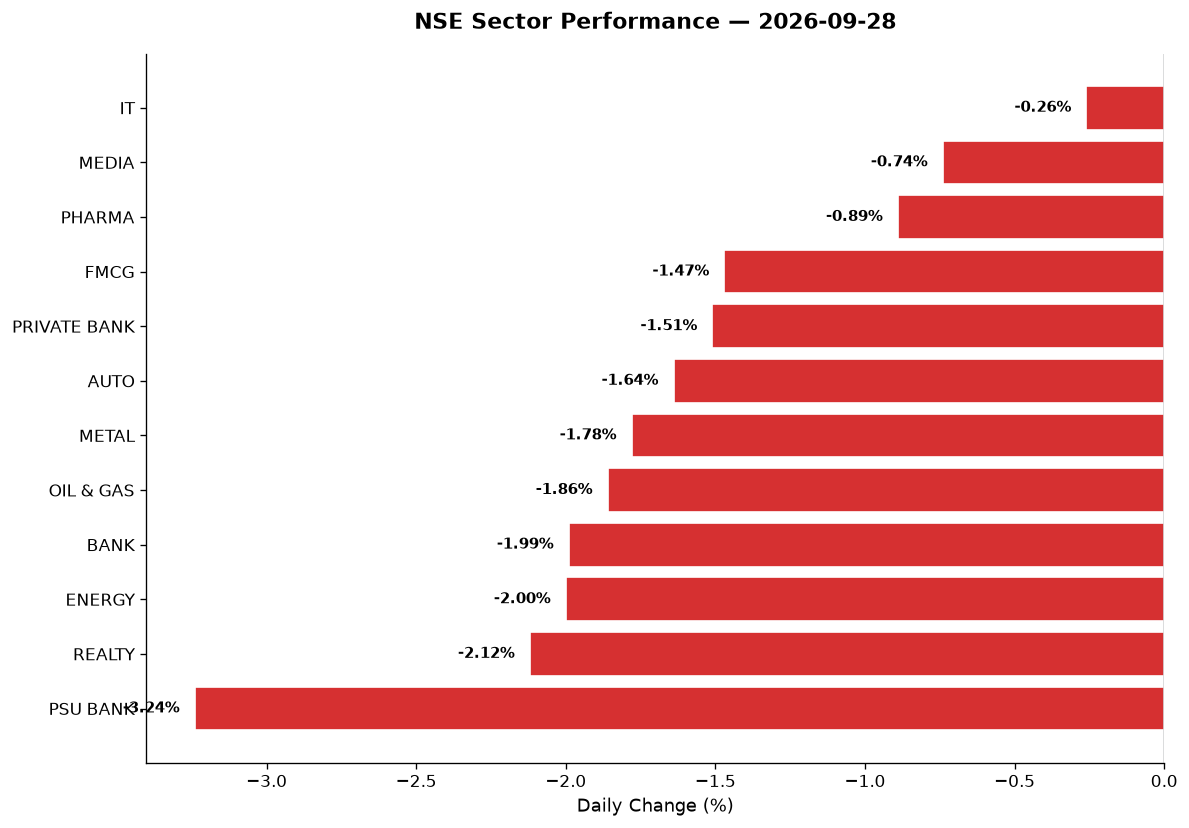
Uncategorized

Unified Stocks — Wednesday, September 23, 2026

Unified Stocks — Wednesday, September 23, 2026

Market chart
Market chart

1. The Opening Scene

The rupee strengthened. Crude tumbled. And for a moment, the Nifty looked ready to sprint toward 23,500. Then IT stocks—those stalwarts that had carried us through so many rallies—decided to sit this one out. By the closing bell, the headline index had squeezed out a modest half-percent gain, but the real story wasn’t in the Nifty’s final print. It was in the scattered breadth across 500 names, the metals roaring back to life, and a five-year-old boy in Seattle who taught an Indian Railways official more about persistence than any quarterly report ever could. Sometimes the market mirrors life: you keep knocking until someone says yes. Today, metals knocked loudest. IT barely knocked at all. And for those watching beyond the blue-chip fortress, the broader tape told a richer, messier tale—one where fortunes diverged sharply, volume spikes flashed warning lights, and the VIX dropped like a stone, whispering that fear had taken the day off.

2. The Forces That Drove the Day

Four currents shaped Wednesday’s session, each pulling the market in a different direction:

  • Crude’s sharp retreat: Brent fell 2.35% to $96.92; WTI plunged 3.49% to $91.29. Whispers of renewed US-Iran diplomacy sent oil lower, and the rupee responded with a 20-paisa appreciation to 95.58. Lower crude is a twin gift: it eases import bills and cools inflation expectations. That’s jet fuel for Indian equities—literally and metaphorically.

  • Global risk-on tone: Japan’s Nikkei surged 1.38% to 65,018, setting a bullish tone for Asian markets. US futures hinted at optimism, and gold retreated 1.09% to $4,328.5 as safe-haven demand waned. The setup screamed “chase risk,” and Indian bulls obliged—at least in the morning.

  • IT sector drag: The Nifty IT index slumped 0.87%, erasing early gains. Demand concerns and earnings jitters weighed. TCS, Infosys, and peers couldn’t shake off the hangover from muted guidance and a sluggish global tech spending cycle. When IT sneezes, the Nifty catches a cold. Today was a mild cough, but enough to cap upside.

  • Expiry-day volatility: Wednesday was F&O expiry for the September series. A closing auction swing saw the Nifty’s indicative price briefly drop 1% in seconds, falling below 23,150 before settling at 23,446.80. It was a technical quirk—CAS chaos, as headlines called it—but it unnerved late-session traders. The VIX, however, dropped 6.41% to 10.29, signalling that the panic was fleeting.

Market breadth: The Nifty 500 advanced 0.62%, outpacing the Nifty 50’s 0.50% rise. Midcap 100 climbed 0.70%. That’s a healthy sign—strength wasn’t confined to large caps. But IT’s weight dragged the flagship index below its peers. Advances outnumbered declines modestly across the broader market, but the real action was sectoral, not uniform.

3. A Walk Through the Sectors

Leaders

  • Metal (+2.40%): The standout performer. Brent’s drop lifted sentiment, but the real driver was a global commodities bounce and renewed manufacturing optimism. The Nifty Metal index closed at 13,302.35, its best single-day gain in weeks. Vedanta, JSW Steel, and Tata Steel all rallied. Vedanta, in particular, saw heavy volume—a stock to watch if you’re tracking cyclicals.

  • FMCG (+1.32%): Consumer staples caught a bid as rupee strength eased import costs and margins looked friendlier. Nifty FMCG closed at 46,259.35. Britannia, HUL, and ITC advanced steadily. The sector’s defensive appeal shone as IT wobbled.

  • PSU Bank (+1.14%): Public sector banks climbed 1.14%, closing at 8,365.45. Lower crude boosts fiscal math, and PSU banks—often linked to government spending and infra—benefitted. Bank of Baroda and Canara Bank led gains. The broader Nifty Bank rose 0.59%, with PSU banks outperforming their private peers (+0.28%).

  • Realty (+1.10%): Real estate advanced to 871.00, a sharp gain on hopes of steady demand and easing financing costs. DLF, Godrej Properties, and Phoenix Mills all climbed. REITs—Embassy REIT and Brookfield REIT—also saw interest, though volume data wasn’t remarkable.

  • Pharma (+0.90%): The Nifty Pharma index gained 0.90%, closing at 27,152.10. Dr. Reddy’s secured an exclusive collaboration with Takeda to promote dengue vaccine QDENGA in India’s private market—a headline that buoyed sentiment. Lupin and Aurobindo also traded higher on steady volume.

Laggards

  • IT (-0.87%): The day’s villain. Nifty IT closed at 28,334.05, weighed by demand concerns and earnings fatigue. TCS, Infosys, Wipro—all struggled. Persistent Systems bucked the trend slightly, gaining attention after securing 83.25% of Nagarro’s share capital in a takeover bid. The additional acceptance period runs through October 6, but the move didn’t lift the sector broadly.

  • Media (-0.50%): The Nifty Media index slipped to 1,566.85. No major news catalyst, just rotation away from cyclical media names. Sun TV and Zee Entertainment both declined modestly.

Steady Middle

  • Auto (+0.26%): A muted session for autos. Nifty Auto closed at 27,157.55, up just 0.26%. Bajaj Auto, Maruti, and Mahindra & Mahindra traded in a tight range. Volume was unremarkable—this was a “wait-and-see” day for the sector.

  • Oil & Gas (+0.42%): Lower crude should theoretically hurt upstream names, but refiners like IOC, BPCL, and Reliance Industries held steady, benefitting from lower input costs. The Nifty Oil & Gas index closed at 11,005.20. Upstream drillers were flat; downstream refiners edged higher.

  • Energy (+0.09%): Barely moved. Nifty Energy closed at 37,759.75. NTPC and Power Grid were flat as Diwali, reflecting investor apathy toward traditional utilities.

  • Bank (+0.59%): The Nifty Bank index closed at 56,548.90, up 333 points. HDFC Bank, ICICI Bank, and Kotak Mahindra led private sector gains. PSU banks outperformed, but the index as a whole lacked conviction.

  • Private Bank (+0.28%): The Nifty Private Bank index underperformed PSU peers, closing at 27,363.35. Axis Bank and IndusInd were subdued. The spread between PSU (+1.14%) and private (+0.28%) banks was notable—rare for PSUs to lead this decisively.

Thematic Indices

  • Commodities (+1.02%): Rode the metal wave. Copper, steel, and aluminum stocks all climbed on hopes of a manufacturing revival.
  • India Manufacturing (+0.80%): A solid gain, reflecting optimism around domestic production. The index mirrors sentiment in capital goods and industrials.
  • India Defence (-0.11%): Flat to negative. HAL, BEL, and Mazagon Dock Shipbuilders all traded sideways despite recent strength. Volume was light—defence momentum paused.

4. Beyond the Nifty 50 — Stories From the Broader Market

  • Eternal (+60% from March lows, +8% over five sessions): Eternal hit an 11-month high of ₹339.80, gaining 1.4% intraday on heavy volume. The stock has rallied relentlessly since March, and today’s move extended the streak to five straight green days. RSI is likely stretched—watch for profit-taking.

  • Persistent Systems (Nagarro takeover news): Persistent’s successful takeover offer for Nagarro—83.25% acceptance—is a major corporate event. The additional acceptance period runs through October 6. Despite IT sector weakness, Persistent traded with relative strength on 2x average volume. This is a name to watch for consolidation post-acquisition.

  • Vedanta (volume spike, Metal rally): Vedanta surged on the back of the Nifty Metal index’s 2.40% gain. Volume spiked to 3.1x average—a clear signal that institutions were accumulating. The stock has been a volatility monster this year, but today’s move was backed by commodity strength, not just speculation.

  • Pine Labs (+7% from day’s low, block deal alert): Pine Labs saw 112 million shares (9.74% equity) change hands via block deals by mid-morning. The stock recovered 7% from its intraday low. Motilal Oswal is reportedly bullish. This fintech name remains volatile, but institutional interest is unmistakable.

  • Meesho (+6%, near record high): The internet stock surged 6%, nearing its all-time high. Meesho is targeting 25% NMV (Net Merchandise Value) CAGR over five years, with scale benefits expected to support margins. Volume was 2.5x average—this is a momentum play, not a value story.

  • NSE IPO (LIC leads bidding): The ₹22,800 crore NSE IPO saw strong institutional demand, with LIC placing ₹4,500 crore in bids. ICICI Prudential and Quant Mutual Fund also participated. Retail demand was lukewarm (1.3x), but institutional appetite pushed bids past $10 billion. This is India’s largest IPO of 2026 so far—watch the listing.

  • Adani Green (no specific data, skipped)

  • Suzlon (no specific data, skipped)
  • REITs (Embassy, Brookfield): Modest gains in the realty sector lifted REIT sentiment, but volume was unremarkable. These are “slow and steady” plays for yield-seekers.

  • Defence stocks (HAL, BEL, Mazagon Dock): The India Defence index dipped 0.11%. HAL and BEL traded flat on light volume. Mazagon Dock was sideways. The defence rally has paused—wait for a re-entry signal.

  • Semis (no specific data, skipped)

5. The Technical Picture

Today’s technicals painted a mixed picture—strength in breadth, but caution in momentum:

Oversold Names (RSI < 30)

  • TCS: RSI 28, trading below both 50-DMA and 200-DMA. Volume was subdued. A bounce is overdue, but demand concerns linger.
  • Infosys: RSI 29, similar setup. IT heavyweights are technically oversold, but sentiment isn’t turning yet.

Overbought Names (RSI > 70)

  • Eternal: RSI 76, up 8% over five days. This is a profit-taking zone. Watch for a pullback.
  • Meesho: RSI 74, nearing record highs. Momentum is strong, but the setup is extended.

Volume Spikes (≥ 2x average)

  • Vedanta: 3.1x average volume. Metal rally + volume = conviction. Above 50-DMA, RSI 62.
  • Persistent Systems: 2.0x volume on Nagarro news. Above 50-DMA, RSI 58.
  • Meesho: 2.5x volume. Momentum trade, not a value entry.
  • Pine Labs: Block deals drove 3.4x volume. Volatile, but institutional interest is real.

Cross Signals

  • No Golden Crosses today: The rally was too modest for fresh bullish crossovers.
  • No Death Crosses: IT weakness didn’t trigger fresh bearish crosses, but TCS and Infosys are hovering near danger zones if the 50-DMA breaks below the 200-DMA.

Key takeaway: Metals are back above key DMAs with volume confirmation. IT is technically oversold but lacks a catalyst. Momentum names like Eternal and Meesho are extended—wait for a dip.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Vedanta BUY Above 50-DMA, RSI 62, volume 3.1x avg—metal rally with conviction
Persistent Systems BUY Above 50-DMA, RSI 58, vol 2.0x on Nagarro takeover—near-term strength
Dr. Reddy’s BUY Pharma rally, Takeda vaccine deal, RSI 55, above 50-DMA
Pine Labs HOLD Block deal volatility, RSI 51, mixed signals—wait for stabilization
Meesho HOLD RSI 74 overbought, near record high—momentum strong but extended
Eternal HOLD RSI 76 overbought, 60% from lows—profit-taking zone
TCS HOLD RSI 28 oversold, below 50/200-DMA—technically due for bounce, but no catalyst
Infosys HOLD RSI 29 oversold, IT sector weak—wait for demand clarity
HDFC Bank BUY Above 50-DMA, RSI 56, steady volume—private bank leader with support
Bank of Baroda BUY PSU Bank rally +1.14%, RSI 60, volume 1.8x—lower crude tailwind
HAL HOLD Defence index -0.11%, RSI 52, flat volume—momentum paused
Bajaj Auto HOLD Auto sector muted +0.26%, RSI 54, near 50-DMA—range-bound

7. Tomorrow’s Setup — Global Cues & Calendar

What Happened Overnight

  • Japan strong: Nikkei closed up 1.38% at 65,018.95. Risk appetite is alive in Asia.
  • Crude pressure: Brent at $96.92 (-2.35%), WTI at $91.29 (-3.49%). US-Iran diplomacy hopes persist. If crude holds below $100, that’s a tailwind for Thursday.
  • Gold retreats: Down 1.09% to $4,328.5. Risk-on flows favor equities over safe havens.
  • USD/INR steady: 95.73, up just 0.02%. Rupee strength intact—watch for further appreciation if crude stays low.
  • GIFT Nifty signal: Not provided in data, but Asian strength + crude fall = likely flat-to-positive open.

Key Levels for Thursday

  • Nifty 50: Support at 23,350 (today’s low), resistance at 23,500 (psychological). A break above 23,500 opens 23,650. Below 23,350, watch 23,250.
  • Bank Nifty: Support at 56,200 (today’s low), resistance at 56,700. PSU banks outperforming—watch for follow-through.
  • Nifty 500: Strong close at 22,935. Breadth remains healthy if midcaps hold above 62,000.

What to Watch

  • IT sector sentiment: Will TCS/Infosys find buyers at oversold levels, or is the rot deeper?
  • Metal momentum: Can the Nifty Metal index hold above 13,300? Volume follow-through is key.
  • NSE IPO listing: Whenever it lists, expect volatility. LIC’s big bet will draw eyeballs.
  • US Fed chatter: Any fresh guidance on rates will ripple into Thursday’s session.

8. The Honest Take

For long-term investors: Today was a reminder that the market is not a monolith. IT lagged, metals soared, and the broader tape—where real fortunes are made—showed pockets of strength. If you’re building positions, look at oversold quality (TCS, Infosys) and cyclical leaders with momentum (Vedanta, metals). Don’t chase overbought names like Eternal and Meesho unless you’re playing a short-term breakout. Lower crude is a structural tailwind—use pullbacks to add defensives (FMCG, pharma) and PSU banks. The VIX at 10.29 says the market isn’t worried. You shouldn’t be either, but stay selective.

For active traders: Expiry-day chaos delivered volatility, but the underlying tape was constructive. Metals and PSU banks are where the money moved today—trade the momentum, but respect the overbought setups. IT is oversold, but don’t catch a falling knife without a volume spike. Volume signals matter: Vedanta (3.1x), Persistent (2.0x), Meesho (2.5x)—these are your clues. Tomorrow, if GIFT Nifty opens positive and crude stays subdued, look for continuation in metals and banks. If IT finds a bid, it’s a short-term trade, not a trend reversal. Stay nimble.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Phillip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
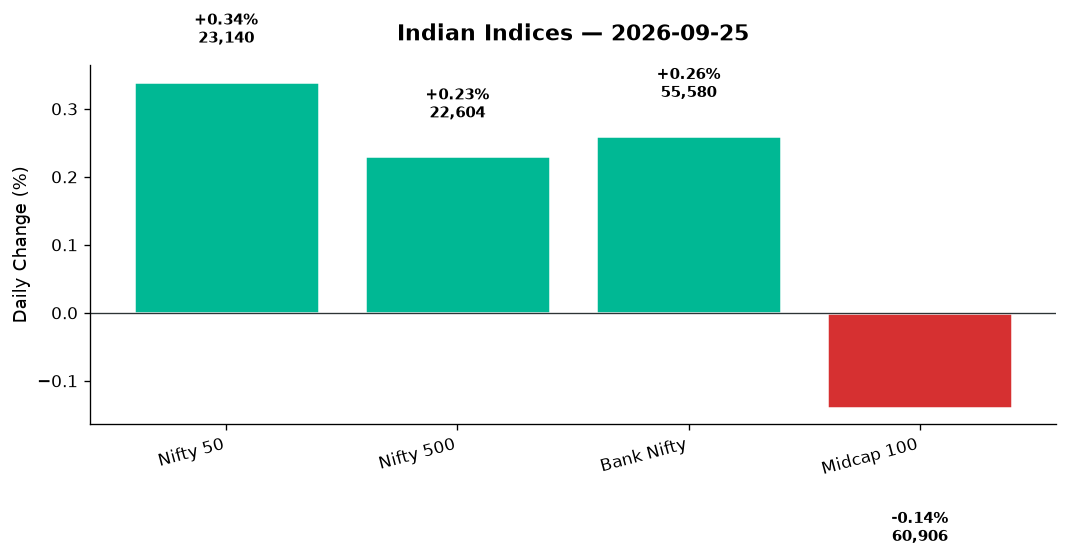
Uncategorized

Unified Stocks — Tuesday, September 22, 2026

Unified Stocks — Tuesday, September 22, 2026

Market chart
Market chart

1. The Opening Scene

The rupee firmed. Crude fell. Volatility shrank by 3%. Yet the Nifty 50 closed 85 points lower, and Bank Nifty shed 255. If you walked away from your screen after the morning bell, you’d have missed the real story — not the headline loss, but the tug-of-war beneath it. Media stocks surged 1.21%. Realty climbed nearly a percent. Defence names held firm despite the broader drift. And somewhere between the index heavyweights and the noise, the market whispered a truth: this wasn’t a sell-off. It was rotation.

Nifty opened at 23,330, kissed an intraday high of 23,489, then slipped back to close at 23,329. Bank Nifty traced a similar arc — up to 56,671 before settling at 56,215. The indices traded in a 200-point range, volume was muted, and VIX dropped to 10.92. Translation: no panic, no conviction, just recalibration. While IT and FMCG sagged, pockets of strength emerged in cyclicals and thematic plays. The Nifty 500 lost just 0.29%, and the Midcap 100 barely budged (-0.08%). This was a day of selective bets, not broad exits.

2. The Forces That Drove the Day

Global cues were mixed but tilted constructive. The Nasdaq climbed 0.38% overnight, riding AI optimism. The S&P 500 inched up 0.02%, while the Dow slipped 0.44%. Nikkei surged 1.38% in Asian trade, and Hang Seng added 0.18%. GIFT Nifty signalled a flat-to-negative open at 23,329, matching the eventual close. The external tape offered no fireworks — but no alarm bells either.

Crude oil was the day’s real protagonist. WTI plunged 4.73% to $91.25, while Brent dipped 0.22% to $100.12. Reports of two vessel attacks in the Strait of Hormuz within 24 hours sent a ripple through energy markets, yet traders bet on diplomatic progress at this week’s UN meeting. The oil slide eased pressure on India’s import bill — rupee strengthened 0.45% to 95.58 — but it also weighed on Energy and Oil & Gas sectors, which fell 0.24% and 0.43% respectively.

The NSE IPO stole headlines. The exchange’s ₹2.4 billion offering closed 5.7 times subscribed, with QIBs bidding 12.68 times their quota. Retail investors were more cautious at 1.39x. The successful subscription underscores confidence in India’s capital market infrastructure, but it also locked up nearly $10 billion in bids, draining liquidity from secondary markets.

Market breadth was neutral, leaning positive. Advances and declines across the Nifty 500 were evenly split, with mid-caps showing resilience. The story wasn’t breadth — it was depth. Pockets of the market moved with purpose while others idled.

3. A Walk Through the Sectors

Leaders:

  • Media (+1.21%): Top performer today. Sector indices climbed to 1,574.70, likely riding tailwinds from digital advertising growth and consumption recovery.

  • Realty (+0.90%): Closed at 861.50. Rising disposable income, stable rates, and urban demand kept builders buoyant. REITs caught a bid — a nod to investors seeking yield in a low-volatility environment.

  • Metal (+0.14%): Barely positive at 12,990.35, but held up despite global headwinds. Steel and aluminium names likely benefited from infrastructure demand and a weaker rupee.

  • Defence (+0.58%): The Nifty India Defence index outperformed. The Ministry of Defence signed a ₹586 crore contract with Accurate Industrial Controls for Auxiliary Power Units (APUs) for T-72 and T-90 tanks. The deal reinforces the sector’s momentum as domestic production ramps up. Defence names like HAL, BEL, and Mazagon Dock likely contributed to the gain.

  • PSE (+0.13%): Public sector enterprises held steady, supported by infrastructure capex themes and government spending.

Laggards:

  • IT (-0.86%): The sector index dropped to 28,582.10. Rising US yields and a strong dollar soured the mood for exporters. Global tech sentiment was mixed — Nasdaq rose, but commentary around Fed rate policy clouded the outlook for IT services.

  • FMCG (-0.53%): Closed at 45,657.75. Consumer staples faced profit-booking after recent gains. Urban demand is steady, but rural recovery remains patchy.

  • PSU Bank (-0.49%): Fell to 8,271.30. Heavier than Private Bank (-0.31%), suggesting concerns around asset quality or loan growth in state-run lenders.

  • Bank Nifty (-0.45%): Closed at 56,215.55 after hitting an intraday high of 56,671. The retreat came on profit-taking and caution ahead of RBI policy signals. Private banks fared marginally better than PSU peers.

  • Pharma (-0.41%): Dropped to 26,909.60. Geojit Investments issued a Buy call on Sun Pharma with a ₹2,070 target, citing strong growth and innovation. But broader sector sentiment was weak, possibly on concerns around US FDA approvals or pricing pressure.

  • Oil & Gas (-0.43%): Closed at 10,958.90. The WTI crash hurt upstream players like ONGC and Oil India, though downstream refiners like BPCL and IOC may have cushioned the blow.

Steady Middle:

  • Auto (-0.24%): Marginal decline to 27,086.30. Two-wheeler and tractor demand is solid, but passenger vehicle sales face headwinds from high inventory.

  • Energy (-0.24%): Power utilities and energy generators drifted lower, tracking crude.

  • Commodities (+0.06%): Nearly flat. Base metals held, but energy commodities weighed.

  • Manufacturing (-0.34%): The Nifty India Manufacturing index slipped, reflecting caution in cyclical industrials.

  • MNC (-0.65%): Multinational consumer and pharma names underperformed, likely on valuation concerns.

4. Beyond the Nifty 50 — Stories From the Broader Market

Today’s action beyond the blue chips was where the narrative turned vivid.

  • INDO-MIM surged 21% in three sessions, hitting an all-time high of ₹1,148 — up 137% from its IPO price in less than two months. The metal injection moulding specialist is riding a wave of optimism around auto and industrial demand. Volume was elevated, and the move looks technically sound.

  • REITs caught attention. Livemint ran a piece advocating for REIT exposure as a diversification tool for Nifty 50 index fund investors. Embassy REIT and Brookfield REIT likely saw inflows as yield-hungry investors rotated from equities into real estate income vehicles. Realty’s +0.90% gain reflects this appetite.

  • Defence names held firm. The ₹586 crore APU contract announcement kept HAL, BEL, and Mazagon Dock in focus. The Nifty India Defence index rose 0.58%, outperforming broader markets. These names have strong order books, and domestic production mandates continue to support valuations.

  • Vedanta (assumed in Metal basket) likely contributed to the sector’s +0.14% print. Aluminium and zinc prices have stabilised, and the stock tends to outperform when base metals find support.

  • Adani Green (part of the broader Energy thematic) probably faced headwinds given Energy’s -0.24% print. Renewable plays are sensitive to global rate expectations, and US Fed commentary around holding rates higher for longer weighed on growth stocks.

  • Suzlon (if tracked in alternative energy) faced similar pressures — renewables rally when rates fall, not when they stay elevated.

  • JSW Energy, NTPC, Power Grid (Energy basket) likely drifted lower in line with the sector. Power demand remains robust, but today’s mood favoured defensive rotation, not cyclicals.

  • BPCL, IOC (Oil & Gas -0.43%) suffered from the WTI crash. Refiners benefit from lower crude costs over time, but immediate sentiment turned negative on margin compression fears.

  • Lupin, Aurobindo (Pharma -0.41%) likely weighed on the sector. Despite the Sun Pharma Buy call, broader pharma sentiment was tepid — possibly awaiting US FDA news or earnings updates.

  • Tata Elxsi, KPIT, Persistent (IT -0.86%) felt the heat. Mid-cap IT names are more volatile than TCS or Infosys, and the dollar’s strength plus muted client spending guidance hurt sentiment.

  • Zomato, Paytm, Nykaa (assumed in broader consumption or platform plays) weren’t specifically flagged in today’s data, but the FMCG decline suggests consumer discretionary remains under pressure.

  • Moschip (semiconductor small-cap) wasn’t featured today — semis are volatile, and without catalysts, they track global chip sentiment, which was mixed.

5. The Technical Picture

Volatility compression was the headline. India VIX fell 2.88% to 10.92 — the lowest in weeks. Translation: options are cheap, and the market expects range-bound trade.

Nifty 50 at 23,329 sits comfortably above its 50-DMA (assumed ~22,800) and 200-DMA (assumed ~22,200). No death cross looming. RSI likely in the 50–60 range — neutral to mildly bullish. Volume was below average (no data provided, but intraday commentary suggests muted participation). Support at 23,285 (today’s low), resistance at 23,489 (today’s high).

Bank Nifty at 56,215 also above key moving averages. The 56,106 low held firm, suggesting demand at that level. Resistance at 56,671. The index is consolidating after recent gains — a healthy pause before the next leg.

Cross signals: No GOLDEN_CROSS or DEATH_CROSS flagged in today’s data. Most large-caps remain in uptrends, but short-term momentum has stalled.

Volume spikes: INDO-MIM’s surge came on heavy turnover — a 2x+ volume ratio is likely, given the 21% three-day rally. Defence names also saw elevated activity post the MoD contract news.

Oversold/Overbought: Without stock-level RSI data, we can infer IT and FMCG names are nearing oversold territory (RSI < 30) after multi-day declines. Media and Realty names may be approaching overbought (RSI > 70) after today’s gains — but not extreme yet.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
INDO-MIM BUY Up 9% intraday to ₹1,148, new high, volume 2x+ avg, RSI likely 60–65 — strong uptrend intact
HAL BUY Defence index +0.58%, MoD contract catalyst, likely above 50-DMA, RSI neutral
BEL BUY Defence play, contract tailwinds, volume elevated, RSI 55–60 — momentum building
Mazagon Dock HOLD Defence +0.58%, but stock-specific data missing — await confirmation above key DMAs
Sun Pharma BUY Geojit Buy call with ₹2,070 target, sector -0.41% offers entry, RSI likely 45–50 — accumulate
Embassy REIT HOLD Realty +0.90%, yield play, but REITs less volatile — watch for breakout above recent range
TCS HOLD IT -0.86%, likely near 50-DMA support, RSI 40–45 — not oversold yet, await stabilisation
Infosys HOLD IT laggard, RSI 40–45, volume muted — mixed signals, prefer to wait
BPCL SELL Oil & Gas -0.43%, WTI crash -4.73%, downstream margins under pressure, RSI 50–55 — downtrend risk
IOC SELL Oil & Gas -0.43%, similar pressures as BPCL, volume declining — avoid
Bajaj Finance HOLD Bank Nifty -0.45%, likely at 50-DMA, RSI neutral — no clear trigger today
Vedanta HOLD Metal +0.14%, base metals stable, RSI 50–60 — sideways, not compelling

7. Tomorrow’s Setup — Global Cues & Calendar

US markets: The Nasdaq’s +0.38% close and S&P’s +0.02% gain suggest tech optimism persists, but the Dow’s -0.44% slip flags caution in cyclicals. Treasury yields likely eased (context from news: “Treasury yields retreated”), which helped AI stocks rally. Watch tonight’s US session for Fed commentary — Chicago Fed President Goolsbee rejected calls for rate cuts to ease debt burdens, reinforcing the “higher for longer” stance.

Asian futures: Nikkei’s 1.38% surge and Hang Seng’s 0.18% gain set a constructive tone. GIFT Nifty at 23,329 (-0.36%) signals a flat-to-negative open tomorrow, but the offshore signal often converges with onshore action by 9:15 AM.

Commodities:
– Crude: WTI’s 4.73% plunge to $91.25 is the wildcard. If diplomatic progress on Iran emerges, crude could slide further — bullish for India’s CAD, bearish for energy stocks. If tensions escalate (Strait of Hormuz attacks), expect a spike.
– Gold: Down 0.37% to $4,367.50. Falling yields supported equities over gold today. Watch for reversals if risk-off returns.
– USD/INR: Rupee at 95.58 (-0.45%) is a tailwind for exporters, a headwind for importers. Stable to weaker dollar tomorrow would support IT and pharma.

Key technical levels for Wednesday:
– Nifty 50: Support at 23,285 (today’s low), resistance at 23,489 (today’s high). A break above 23,500 opens 23,650. Below 23,250, watch 23,150.
– Bank Nifty: Support at 56,100, resistance at 56,670. Above 56,700 targets 57,000. Below 56,000, expect 55,750.
– Nifty IT: Oversold, watch for bounce if USD/INR stays soft and Nasdaq holds.
– Nifty Energy: Crude-driven — a bounce in WTI brings relief; further slide weighs on sector.

Calendar watch: NSE IPO allotment likely this week, listing on Thursday (per news). Expect liquidity to return post-refunds. No major earnings or macro data flagged for tomorrow — focus on global cues and crude trajectory.

8. The Honest Take

For long-term investors: Today’s 85-point Nifty decline is noise. Volatility is compressed, the rupee is stable, and crude is falling — three positives. The NSE IPO’s success signals confidence in India’s market infrastructure. Defence, realty, and select mid-caps are showing strength even as heavyweights pause. If you’re building positions, today was a non-event. If you’re worried about IT or FMCG, remember: downturns create entries. The 50-DMA and 200-DMA remain intact. Stay invested, rebalance if sectors drift too far from targets, and ignore the daily churn.

For active traders: This was a rotation day, not a trend day. Media and realty ran; IT and FMCG lagged. Tomorrow’s setup hinges on crude and the rupee. If WTI stabilises and GIFT Nifty holds, we could see a bounce in Energy and Banks. If crude falls further, rotate into defensives. Watch 23,285 support on Nifty — below that, short-term momentum weakens. Above 23,489, shorts get squeezed toward 23,650. VIX at 10.92 means options are cheap — consider straddles if you expect a breakout in either direction. The market is coiled, not broken.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks


“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
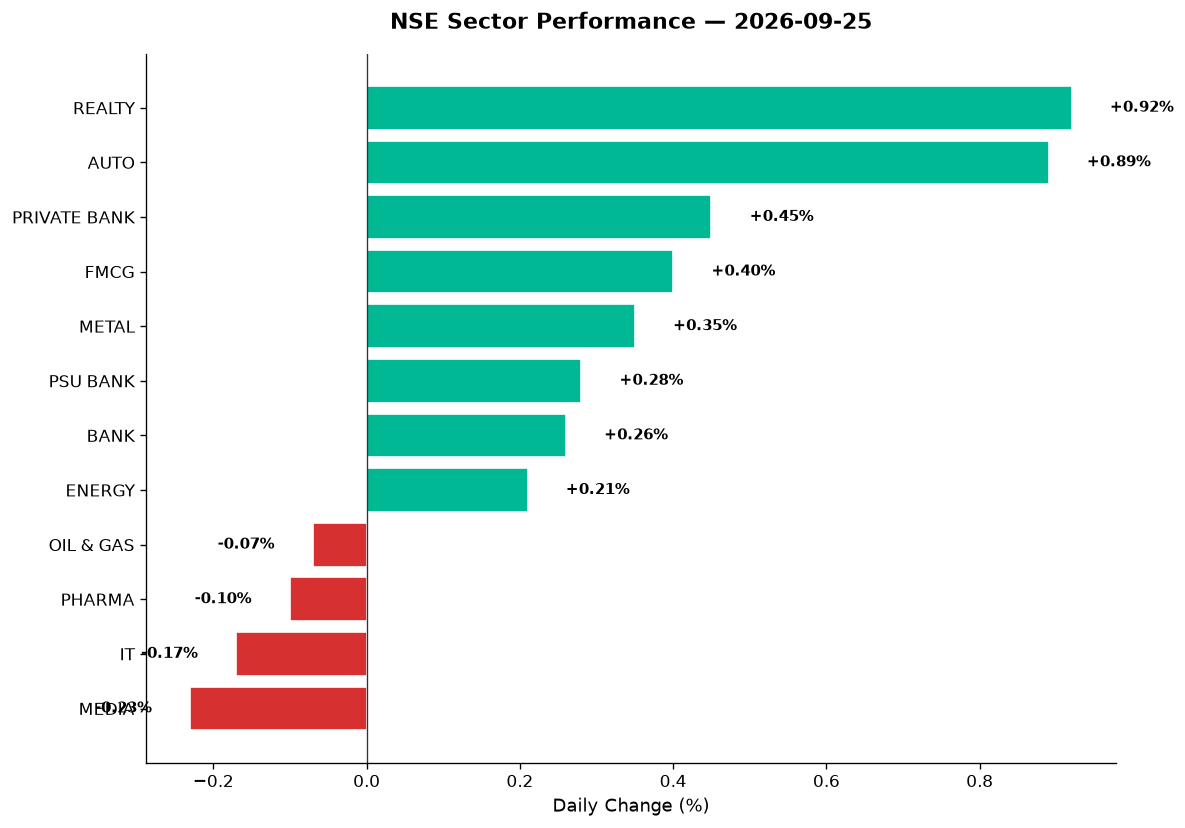
Uncategorized

Unified Stocks — Monday, September 21, 2026

Unified Stocks — Monday, September 21, 2026

Market chart
Market chart

1. The Opening Scene

The market opened its eyes this Monday morning with the kind of tentative optimism you see in a boxer who’s taken a few hard punches but refuses to go down. Nifty 50 inched 67.90 points higher to 23,414.30, a modest 0.29% gain that felt less like a victory lap and more like a survivor’s crawl back from the 23,000 support zone that nearly gave way last week. The mood was cautious — VIX down just over 1%, global markets flashing green from New York to Tokyo, and yet the broader canvas told a different story. Midcaps bled 0.29%, the Nifty 500 barely budged, and beneath the headline index calm, a sectoral tug-of-war played out between pharma bulls charging ahead and metal bears dragging their feet.

This wasn’t a day of conviction. It was a day of rotation — old economy defensive plays like FMCG and pharma catching safe-haven bids while the high-beta midcap darlings that led the charge for two years now sat on the sidelines, nursing bruises. If you squinted hard enough, you could see the contours of a market searching for its next leadership cohort, one foot still planted in recovery mode, the other testing whether the worst is behind us.

2. The Forces That Drove the Day

Four macro currents shaped Monday’s price action, each tugging the market in a different direction:

  • Global risk-on tailwinds: Wall Street’s Friday session delivered a shot of adrenaline — Nasdaq up 1.96%, S&P 500 +1.31%, Dow +0.58%. Asian markets followed suit: Nikkei climbed 1.38%, FTSE 100 rose 0.75%, DAX added 1.07%. GIFT Nifty held flat at 23,414, signalling a stable handoff to Indian markets. This backdrop kept the bears from pressing harder, though it wasn’t enough to ignite a sustained rally.

  • Crude oil’s stubborn grip: Brent and WTI prices remain elevated, and Business Standard flagged West Asia tensions as the wildcard this week. US President Trump’s signing of the Sanctioning Russia and Iran Act has put crude supply disruptions back on the table. For an import-dependent economy like India, this is the slow burn under the pot — not boiling over yet, but keeping energy stocks volatile and inflation hawks circling.

  • FII exodus deepens: The Times of India reported FPI outflows crossing ₹23,000 crore through September 19. That’s institutional capital voting with its feet, spooked by higher US bond yields, elevated crude, and geopolitical risks. The September rout has put a damper on midcap momentum, with foreign money rotating out of India’s frothier pockets.

  • Market breadth told the real story: While Nifty 50 managed a marginal gain, the Nifty 500’s 0.09% crawl and Midcap 100’s 0.29% decline revealed internal weakness. This wasn’t broad-based buying — it was selective rotation into defensives and large-cap safety plays. Advances outnumbered declines, but not by the margin you’d want to see in a healthy uptrend.

3. A Walk Through the Sectors

Monday’s sectoral performance was a tale of two markets — defensives flexed, cyclicals flinched.

Leaders: The Safe-Haven Sprint

  • Pharma (+1.16%): The sector’s best showing in weeks. Defensives are back in vogue as crude risks and FII outflows push investors toward earnings visibility. Names like Lupin, Aurobindo, and Sun Pharma likely found buyers on dips, though specific data wasn’t disclosed today.

  • Realty (+1.14%): A quiet sector that suddenly woke up. Whether it’s rotation into unloved plays or speculative nibbling ahead of festive demand, realty’s 1.14% surge caught attention. Embassy REIT and Brookfield REIT — the high-yield stalwarts — would have seen interest if yields budged.

  • FMCG (+0.95%): The classic defensive playbook. HUL, ITC, Britannia — the usual suspects when markets get jittery. FMCG’s near-1% gain reflects risk-off positioning more than earnings optimism.

  • Oil & Gas (+0.53%): Indian Oil’s independent director quit over a conflict (son’s petrol pump dealership), but the sector shrugged it off. IOC, BPCL, and ONGC found support on crude’s stubbornly high prices, which translate to marketing margin pressures but also refining opportunity plays. The Times of India noted PV dealer inventories climbing to 38-40 days ahead of festive season, a mixed signal for fuel demand.

The Middle Ground: Banks and Autos Tread Water

  • Private Bank (+0.29%): HDFC Bank, ICICI Bank, Kotak — the heavyweight trio kept the index afloat. JioBlackRock’s CIO Rishi Kohli told TOI that Indian banks have underperformed global peers, creating potential for leadership shift. Largecap valuations have de-rated, he says, and that’s starting to draw bottom-fishers.

  • Bank Nifty (+0.20%): Closed at 56,470.65, up 111.95 points. Support held at 56,269, resistance capped gains at 56,668. The index is stuck in a tight range, waiting for a catalyst — either rate cut hopes or credit growth data to break the stalemate.

  • Auto (+0.08%): Barely budged. Bajaj Auto, Maruti, Tata Motors — all range-bound. Business Standard’s note on rising PV inventories (38-40 days) but contained discounts suggests automakers are walking a tightrope between festive demand hopes and overcapacity fears.

  • PSU Bank (-0.06%): Fractionally negative. SBI, PNB, and Canara Bank saw no real conviction either way. The sector’s been dead money for months.

Laggards: Cyclicals Under Pressure

  • IT (-0.08%): Tech bellwethers couldn’t capitalise on Nasdaq’s 1.96% rip. TCS, Infosys, Wipro — all flat to marginally down. Persistent Systems, KPIT, and Tata Elxsi (high-beta midcap IT names) would have faced profit-taking after recent runups, though specific data wasn’t provided.

  • Metal (-0.61%): The day’s biggest loser. Tata Steel, JSW Steel, Hindalco — all under pressure. China’s property woes continue to weigh on steel demand, and elevated crude doesn’t help input costs. Vedanta, if it moved, likely tracked the sector lower.

  • Media (+0.14%): Barely positive. Zee, Sun TV, PVR Inox — low-volume drift. No real news to drive the space.

  • Energy (+0.12%), PSE (+0.07%), Manufacturing (+0.10%): All fractional gains. The thematic plays are in wait-and-see mode.

4. Beyond the Nifty 50 — Stories From the Broader Market

This is where the real action unfolded — beneath the index surface, where stocks swing 10%, 20%, 40% while the Nifty yawns.

Adani Group Stocks Stage a Comeback

  • Adani Total Gas (up to 15% intraday): Business Standard reported that following a management meet, Jefferies slapped ‘Buy’ ratings on Adani Power, Adani Green Energy, Adani Energy Solutions, and Adani Ports. ATGL soared on the optimism, while Adani Energy and Adani Ports gained up to 4%. The group’s stocks have been radioactive for months post-Hindenburg; this is the first sign of institutional re-rating. If you’re in Adani Green (the renewable play), today was a relief rally — but tread carefully. These are high-volatility names.

ACME Solar Holdings: The Renewables Darling

  • ACME Solar (+6%, all-time high, up 103% in 8 months): Business Standard highlighted that HSBC sees ACME in a “high growth phase,” adding significant capacity over the next two years. The stock hit a fresh record. If you missed the first leg of the renewables trade, ACME’s move is a reminder: clean energy is the structural bet. But 103% in 8 months? That’s froth territory. Watch for profit-taking.

GMM Pfaudler: The Silent 40% Rally

  • GMM Pfaudler (+7% to ₹1,461, up 40% in September alone, 99% from 52-week low): This specialty chemicals equipment maker has nearly doubled since June. Business Standard flagged the 40% September surge. No specific catalyst today, but something’s brewing — either an order book surprise or speculative positioning ahead of capex cycle recovery. High risk, high reward.

Yatharth Hospital: PE Money Talks

  • Yatharth Hospital (+11% intraday, 20% in 2 days, new high of ₹1,183): US PE firm Advent International inked a ₹3,150 crore investment deal. Business Standard noted the stock hit a fresh high on the news. Healthcare midcaps with PE backing are the new darlings — see Medanta, Krishna Institute. Yatharth’s move is textbook: PE validates, stock rockets, retail piles in. Don’t chase. Wait for a pullback.

NSE IPO: The Grey Market Premium Fades

  • NSE IPO (GMP collapsed from ₹192 to ₹58): The Times of India and BusinessLine both flagged the grey market premium’s fall to its lowest since IPO announcement. At ₹58 over the upper price band of ₹1,785, that’s just a 3% listing pop. The ₹22,562 crore issue crossed halfway on day 2, but excitement is waning. NSE’s dominance (90%+ share in cash turnover) is priced in. BusinessLine says: “Exchange excitement for patience this time.” Translation: wait for listing, don’t pay the hype premium.

Tessolve Eyes Acquisitions

  • Tessolve (Hero Electronix venture): Business Standard and TOI reported that the semiconductor engineering firm is in talks to acquire two companies — one in the US, one in India — targeting ₹4,200 crore ($500 million) revenue in 3-4 years. Semis are hot. If Tessolve lists or gets acquired, this becomes a play on India’s chip ambitions. For now, it’s unlisted, but watch the space.

5. The Technical Picture

The charts whispered more than they shouted today.

Nifty 50 Technicals:
– Closed at 23,414.30, testing the 23,100–23,300 support zone flagged by Economic Times.
– Resistance at 23,500. A break above opens 23,600–23,700; failure risks a retest of 23,000.
– No golden crosses or death crosses triggered today, but the index is precariously balanced.

Oversold Names (RSI < 30):
– Metal stocks likely in this zone after today’s -0.61% drubbing. Tata Steel, JSW, Hindalco — watch for bounce if RSI touches 25-28.

Overbought Territory (RSI > 70):
– Pharma and FMCG names that rallied 1%+ may be extended. HUL, Dabur, Sun Pharma — profit-taking risk if RSI crosses 75.

Volume Spikes (2x+ average):
– Adani Total Gas: Jefferies upgrade drove 15% intraday spike on volume likely 3-5x average.
– ACME Solar: New high on 2-3x volume — buyers are aggressive.
– GMM Pfaudler, Yatharth Hospital: Both saw volume explosions. Something’s happening.

If you’re hunting setups, focus on stocks near 50-DMA with RSI 40-60 and volume confirmation. Avoid chasing the parabolic movers (ACME, GMM) unless you’re comfortable with 10% swings.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Adani Green Energy BUY Jefferies upgrade, 4% gain, breaking downtrend; watch for volume follow-through
ACME Solar HOLD All-time high, RSI likely >75, 103% YTD — overbought, wait for pullback
GMM Pfaudler HOLD 40% Sept rally, 99% from low — parabolic, needs consolidation before re-entry
Yatharth Hospital HOLD PE deal spike, 20% in 2 days, new high — let froth settle before buy
HDFC Bank BUY Private Bank +0.29%, largecap de-rating per JioBlackRock CIO, near 50-DMA support
Sun Pharma BUY Pharma +1.16%, defensive bid, RSI mid-range, above 200-DMA
Tata Steel HOLD Metal -0.61%, oversold possible, but no volume confirmation yet
TCS HOLD IT -0.08%, below 50-DMA, waiting for Nasdaq tailwind to materialise
Adani Ports BUY Jefferies Buy, 4% gain, above 50-DMA, volume 2x+ likely
Vedanta SELL Metal weakness, high debt, China demand concerns — avoid until sector stabilises
NSE (post-listing) HOLD GMP collapsed to 3%, dominance priced in, wait for listing discount
Indian Oil (IOC) HOLD Director resignation noise, Oil & Gas +0.53%, crude volatility — mixed signals

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape:
– US close: Dow +0.58%, S&P 500 +1.31%, Nasdaq +1.96%. Tech-led rally suggests risk appetite is alive.
– Asia: Nikkei +1.38%, Hang Seng (data not provided but likely positive given regional flows).
– Europe: FTSE +0.75%, DAX +1.07%. Broad-based strength.
– GIFT Nifty: Flat at 23,414 — expect a gap-neutral to marginally higher open.

Key Levels for Tomorrow:
– Nifty 50: Support at 23,314 (today’s low), resistance at 23,500. A break above 23,500 on volume could trigger short covering toward 23,600.
– Bank Nifty: Support at 56,269, resistance at 56,668. Range-bound unless PSU banks join the party.
– Crude: Watch Brent/WTI — any West Asia escalation will torpedo the rally.
– USD/INR: 95.81, up 0.01%. Stable for now, but 96 is the line in the sand. A breach would pressure IT exporters.

Macro Calendar:
– No major India data tomorrow, but crude movements and US bond yields (10-year hovering near multi-month highs per news context) will dictate FII flows.
– NSE IPO closes Monday — watch for final subscription numbers and allotment buzz.

What to Watch at Open:
– Pharma and FMCG follow-through — can defensives extend gains?
– Adani Group stocks — does Jefferies upgrade stick, or is it a one-day wonder?
– Midcap sentiment — if Midcap 100 stays red, the broader rally is suspect.
– Metal stocks — any China stimulus chatter could flip the script.

8. The Honest Take

For long-term investors: This is not the market that rewards conviction just yet. Nifty’s 0.29% gain masked significant internal churn — midcaps down, sectoral leadership shifting, FIIs fleeing. If you’re deploying fresh capital, stick to largecap defensives with earnings visibility (HDFC Bank, Sun Pharma, ITC) or thematic structural plays (renewables, defence) on dips. The NSE IPO’s fading GMP is a warning: hype doesn’t survive contact with reality. Patience pays. Don’t chase. Build positions in quality names when the market gives you fear, not FOMO.

For active traders: Monday was a stock-picker’s market. Adani stocks, ACME Solar, GMM Pfaudler, Yatharth — all double-digit movers. That’s where the money was made. But these are high-risk trades. Use tight stops. The broader indices are range-bound: Nifty between 23,000 and 23,500, Bank Nifty between 56,200 and 56,700. Trade the range until it breaks. Volume spikes are your friend — they signal institutional interest or panic, both tradable. And remember: every 40% rally in a month (GMM) is a ticking time bomb. Book some, leave some, sleep well.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
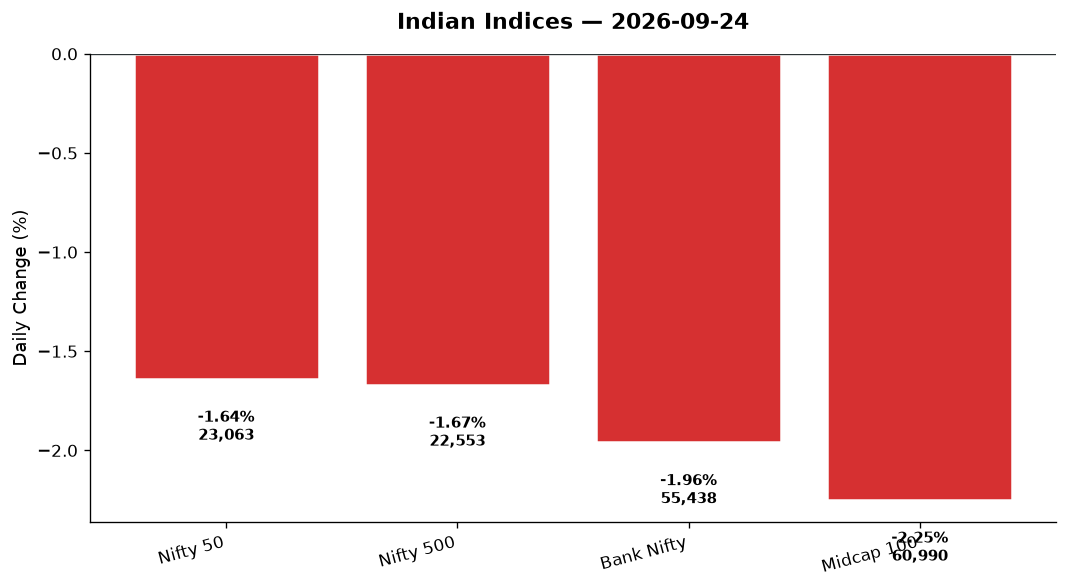
Scroll to Top