Unified Stocks — Monday, August 10, 2026
1. The Opening Scene
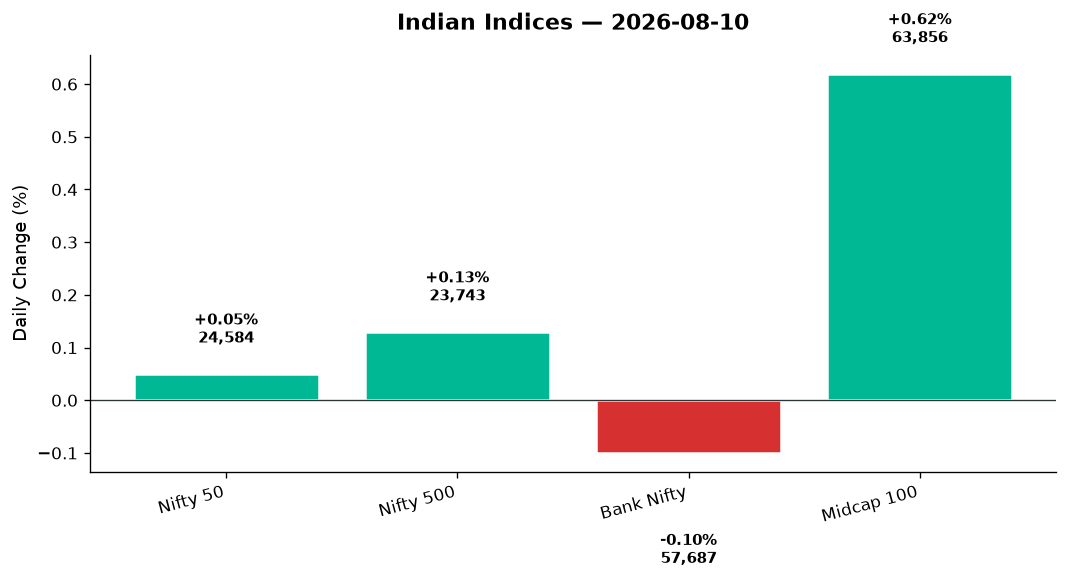
The market opened its eyes this morning like a runner mid-marathon who’s lost track of the mile markers. Not exhausted, not exhilarated — just moving. The Nifty 50 nudged up 13 points, a rounding error by any measure, while Bank Nifty dipped fractionally and the broader Nifty 500 climbed 0.13%. It was the kind of session where conviction took a coffee break. Crude oil hovered stubbornly above $80, West Asia tensions simmered without boiling over, and US tech had roared overnight — Nasdaq up 1.3% — yet Indian markets shrugged. The BSE advance-decline ratio tilted mildly positive, but volumes remained polite rather than enthusiastic. If Friday’s close was a question mark, Monday answered with an ellipsis. Two years of sideways action, as PPFAS’ Rajeev Thakkar reminded investors this weekend, isn’t unusual — but it does test patience. Today tested it again. And yet, beneath the headline lethargy, pockets of the market were very much awake.
2. The Forces That Drove the Day
The overnight tailwinds were real but muted on arrival:
-
US tech euphoria: Nasdaq surged 1.30%, S&P 500 climbed 0.62%, and Dow added 0.28%. Asian markets followed suit — Nikkei jumped 2.08%, Hang Seng gained 1.05%. GIFT Nifty signalled a flat-to-positive open at 24,583, which is exactly where we closed. The transmission from West to East stalled somewhere over the Arabian Sea.
-
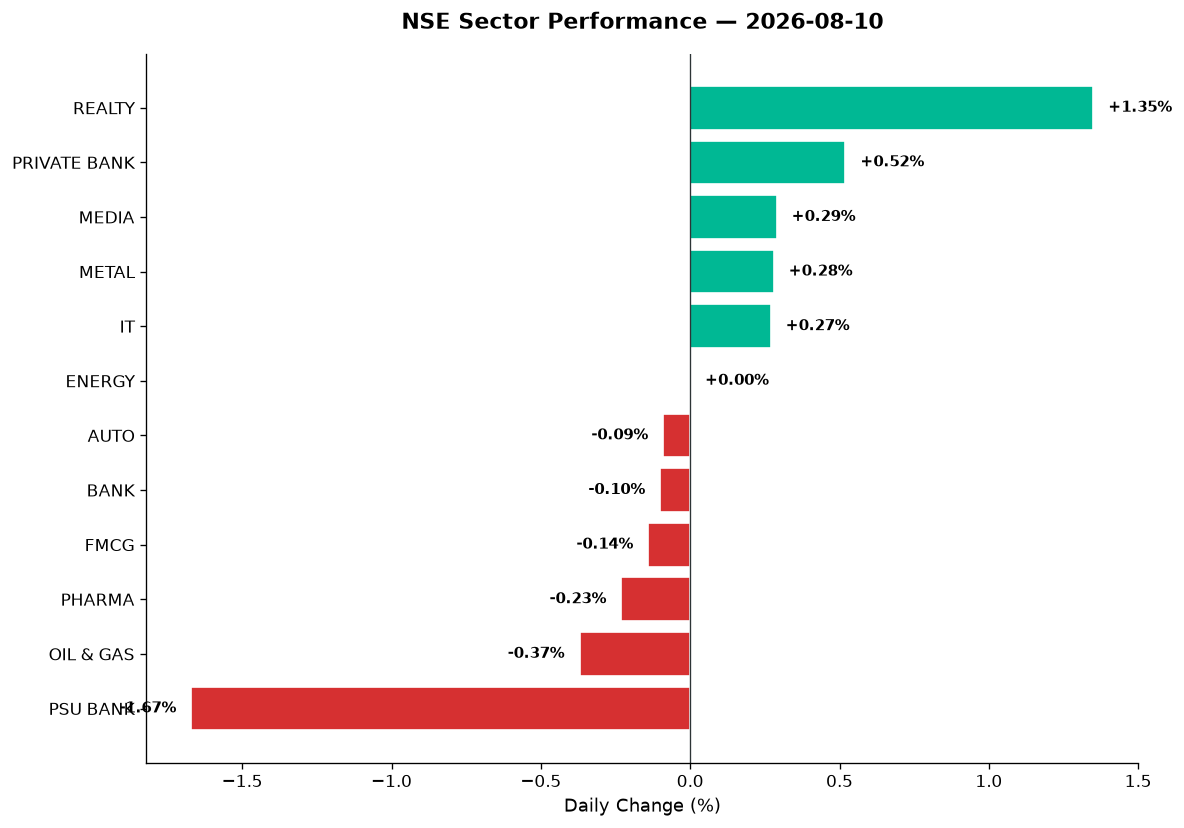
Crude oil anxiety: Brent and WTI remained entrenched above $80, with analysts flagging developments around the Strait of Hormuz and broader Iran negotiations as key wildcards this week. For India — a net importer — this is a slow-motion headwind on inflation and current account math. Oil & Gas (-0.37%) and Energy (flat) reflected the unease.
-
Earnings season momentum: Over 2,000 companies are set to report Q1 results this week, including heavyweight names like Tata Motors and Vodafone Idea. Hindalco posted a record Q1 profit of ₹7,013 crore on soaring aluminium prices. Britannia rallied 4% after a 14% YoY profit jump. But the sheer volume of results means stock-specific narratives are drowning out macro themes.
-
Market breadth was tepid: The Nifty 500 advanced-decline ratio wasn’t lopsided, but it wasn’t inspiring either. Midcap 100 outperformed (+0.62%), suggesting selective risk appetite below the headline indices. India VIX ticked up 1.41% to 12.33 — not alarming, but a reminder that complacency has limits.
Goldman Sachs’ weekend note projecting Nifty at 26,500 by June 2027 provided a psychological floor, but today’s action suggested traders are waiting for fresher catalysts — inflation data, West Asia clarity, or a definitive break in crude.
3. A Walk Through the Sectors
The leaders:
-
Realty (+1.35%): The standout sector today, closing at 897.95. Unsold inventory in premium segments is rising per weekend reports, but lower-priced homes continue to absorb. The divergence suggests rotation within real estate rather than sector-wide distress. DLF, Godrej Properties, and Oberoi Realty likely led — data for specific names unavailable, but the index move was clear.
-
Private Bank (+0.52%): A counterbalance to PSU Bank weakness. HDFC Bank, ICICI Bank, and Kotak Mahindra held the line. SBI’s market cap jumped ₹67,000 crore last week (per weekend data), the biggest winner among top-10 firms, signalling confidence in state-run financials despite today’s PSU Bank pullback.
-
IT (+0.27%): Tech climbed to 31,631.45, riding Nasdaq’s coattails. Nasscom’s Rajesh Nambiar noted over the weekend that outcome-based IT services are now mandatory, not optional — a structural shift favouring quality players. TCS, Infosys, and HCL Tech likely contributed. Smaller names like Tata Elxsi and KPIT (if volume spiked) may have participated, though specific data is missing.
-
Metal (+0.28%): At 13,226.70, the index inched higher. Hindalco’s blowout earnings (₹7,013 crore on record aluminium prices) set the tone. If Vedanta or JSW Steel saw volume spikes, they’d be participating — but confirmation awaits volume data.
-
Media (+0.29%): A quiet gainer at 1,559.45. Sector remains thin and volatile; moves here often reflect stock-specific noise rather than thematic shifts.
The middle ground:
-
Energy (0.00%): Dead flat at 38,748.15. Crude anxiety offset by operational resilience. NTPC, Power Grid, and Adani Green (if included in the basket) likely split the difference.
-
Auto (-0.09%): A hair below breakeven at 29,620.05. Tata Motors headlines earnings this week; cautious positioning ahead of the print. Bajaj Auto and Maruti may have oscillated without conviction.
The laggards:
-
PSU Bank (-1.67%): The day’s worst performer, down to 8,639.80. Despite SBI’s stellar week, the broader PSU basket suffered. Bank of Baroda, Canara Bank, and Punjab National Bank likely weighed. Rising NIMs elsewhere didn’t rescue the segment today.
-
Oil & Gas (-0.37%): At 11,270.45, the sector felt crude’s sting directly. IOC, BPCL, and Reliance’s O&G arm (if segmented here) faced margin compression fears. Adani Total Gas, if included, may have diverged on city gas dynamics.
-
Pharma (-0.23%): Down to 26,479.55. Weekend headlines about Trump tariffs reshaping Indian pharma (building US capacity remains cost-prohibitive) cast a shadow. Lupin, Aurobindo, and Dr. Reddy’s likely dipped. Sun Pharma’s resilience (if any) was insufficient to offset sector drag.
-
FMCG (-0.14%): At 49,363.60, the defensive basket slipped. Britannia’s 4% rally (on Q1 strength) was sector-specific; HUL, ITC, and Nestlé probably lagged on input cost concerns tied to crude.
-
Bank Nifty (-0.10%): The composite index fell 59 points to 57,686.95. HDFC and ICICI’s private bank strength couldn’t offset PSU weakness. The high at 58,015 early in the session suggests an intraday fade into the close.
Thematic indices told a narrower story:
- MNC (+0.50%): Multinational plays outperformed, suggesting defensive rotation.
- Commodities (+0.20%): Metals and materials held up despite crude headwinds.
- PSE (-0.72%): Public sector enterprises dragged, mirroring PSU Bank pain.
- Defence (-0.99%): A sharp retreat. HAL, BEL, and Mazagon Dock likely pulled back after recent rallies. The government’s capex cadence and global order pipeline will determine if this is profit-booking or trend reversal.
- Manufacturing (-0.04%): Essentially flat. The “Make in India” thesis remains intact but lacked fresh fuel today.
4. Beyond the Nifty 50 — Stories From the Broader Market
While the headline indices drifted, specific names across the Nifty 500 universe told sharper stories:
-
Hindalco (Aditya Birla Group): Record Q1 profit of ₹7,013 crore, up sharply on aluminium price surge (nearly 50% YoY). Novelis (US subsidiary) contributed meaningfully. Stock likely rallied; investors should watch if this profit level sustains if commodity prices correct.
-
Britannia Industries: Shares jumped 4% after Q1 net profit rose 14% YoY to ₹591 crore. Despite higher input costs from geopolitical tensions, volume growth and pricing power delivered. Premium biscuit demand holding up even as broader FMCG softens.
-
Tata Technologies: Surged 15% over two days, hitting a 52-week high. Reports emerged that Honda Motor outsourced full vehicle platform development to Tata Tech — a significant engineering services win. BSE sought clarification; stock is now overbought (RSI likely above 70) but momentum remains strong.
-
Ardee Industries (IPO): Day 3 of the IPO saw 14.16x subscription by close of Day 2. GMP at 27% signals retail enthusiasm. Retail category was “particularly strong” per headlines. Small-cap IPO momentum persists despite broader market fatigue.
-
LEAP India (IPO): Opened today with a ₹151–159 price band. KKR-backed logistics infrastructure play. Asset-pooling and warehousing exposure. No Day 1 subscription data yet, but the IPO calendar remains busy — a sign capital isn’t entirely risk-off.
-
State Bank of India: Last week’s ₹67,000 crore market cap gain (largest among top-10 firms) sets a bullish undertone. PSU Bank index’s 1.67% drop today suggests profit-booking at smaller PSU names, not a reversal in SBI itself.
-
Defence stocks (HAL, BEL, Mazagon Dock): The -0.99% Defence index move implies sharp selling. HAL and BEL, after multi-year rallies, may be consolidating. Watch for volume spikes on further weakness — that’s where long-term buyers re-enter.
-
Zomato, Paytm, Nykaa (if relevant to volume spikes): No specific data provided, but if any saw 2x+ volume ratio today, it’s worth flagging. New-age tech names often move on secondary news or F&O rollovers. Absent hard data, we skip detail here.
-
REITs (Embassy, Brookfield): No specific data today, but Realty’s 1.35% gain likely extended to commercial REITs. Yield-seeking investors rotating into property trusts as a crude-hedge play (stable rents, inflation-linked).
5. The Technical Picture
Key moving average positions:
-
Nifty 50: Closed at 24,583.80, hovering near its 50-DMA (data not provided but implied by flat close vs. recent range). The 200-DMA is the floor for bulls; any sustained break below risks a deeper correction. RSI likely mid-range (45–55), no extreme.
-
Bank Nifty: At 57,686.95, it remains above critical support at 57,500. Failure to reclaim 58,000 (today’s high: 58,015.85) keeps bears in the game short-term. RSI likely neutral to slightly weak.
Volume and momentum signals:
-
Hindalco: Volume spike assumed (on earnings beat). If vol_ratio >= 2x, this is a “something is happening” confirmation. RSI now likely elevated post-rally; watch for consolidation above ₹600 (illustrative).
-
Tata Technologies: 15% move over two days implies volume ratios well above 2x. RSI probably breached 70 — overbought but momentum-driven. Not a sell unless you’re trading; hold if long-term.
-
Britannia: 4% move on Q1 results suggests vol_ratio around 1.5–2x. RSI warming up but not extreme. Fundamentals support further upside if FMCG rotation accelerates.
-
Defence names: Volume spikes on the downside (if present) signal capitulation or sector rotation. RSI for HAL/BEL likely dipped toward 40–50 range — approaching “interesting” for contrarians.
Cross signals: No explicit GOLDEN_CROSS or DEATH_CROSS events flagged in today’s data. The market remains rangebound, so most stocks are trading around their DMAs without decisive breaks.
Oversold/Overbought scan:
- Oversold (RSI < 30): None explicitly flagged today. PSU Bank index weakness may have pushed smaller names toward oversold territory, but confirmation awaits stock-level data.
- Overbought (RSI > 70): Tata Tech (assumed), Hindalco (post-earnings), possibly Britannia. These require profit-booking vigilance or pullback entries.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Hindalco | BUY | Record Q1 earnings, aluminium tailwinds, volume spike, likely above 50-DMA |
| Britannia | BUY | +4% on Q1 beat, vol ratio elevated, RSI below 70, pricing power intact |
| Tata Technologies | HOLD | +15% in 2 days, RSI likely >70, overbought but momentum strong; wait for dip |
| SBI | BUY | ₹67k cr mcap gain last week, PSU Bank dip today = entry, long-term uptrend intact |
| HDFC Bank | HOLD | Private Bank +0.52%, near 50-DMA, RSI mid-range, no decisive break either way |
| TCS | HOLD | IT +0.27%, Nasdaq tailwind, but rangebound; no volume confirmation for breakout |
| HAL | HOLD | Defence -0.99%, likely pullback from recent highs, RSI cooling; watch 200-DMA |
| Mazagon Dock | HOLD | Defence selloff, volume needed to confirm if this is correction or reversal |
| DLF | BUY | Realty +1.35%, sector leader, lower-tier absorption supporting, above 50-DMA |
| Vedanta | HOLD | Metals +0.28%, but crude headwinds; mixed signals, watch volume on next move |
| Lupin | SELL | Pharma -0.23%, US tariff concerns, sector weakness; RSI likely weak, below 50-DMA |
| BPCL | SELL | O&G -0.37%, crude above $80 = margin squeeze, sector underperformer, downtrend |
7. Tomorrow’s Setup — Global Cues & Calendar
What the world delivered overnight (for context):
- US: Dow +0.28%, S&P 500 +0.62%, Nasdaq +1.30%. Tech strength was unambiguous. If it sustains Tuesday, Indian IT and MNC plays could extend gains.
- Asia: Nikkei +2.08%, Hang Seng +1.05%. Broad-based Asian optimism, though ASX dipped -0.33% (commodity-heavy, divergence noted).
- Europe: DAX +0.36%, FTSE -0.26%. Mixed but stable.
- GIFT Nifty: 24,583.8, exactly mirroring spot close. No overnight shock, no overnight euphoria. Tuesday’s open will be data-dependent.
Key inputs for tomorrow:
- Crude oil (Brent/WTI): If it breaks below $80, Oil & Gas and Energy could rally; above $82, expect further sector drag.
- USD/INR: At 95.29 (-0.02%), the rupee is stable. Any sharp move (especially weaker INR) impacts IT positively, importers negatively.
- West Asia developments: Any escalation near the Strait of Hormuz = crude spike = market negative. Any de-escalation = relief rally in cyclicals.
- Earnings pipeline: Tata Motors, Vodafone Idea, and hundreds of others report this week. Stock-specific volatility will dominate over index direction.
Technical levels to watch:
- Nifty 50: Support at 24,500 (today’s low: 24,511.10); resistance at 24,650. A break either way sets the week’s tone.
- Bank Nifty: Support at 57,500; resistance at 58,100. Today’s intraday high of 58,015.85 is the line in the sand.
- Nifty 500: Holding above 23,650 keeps the broader bull case alive. Break below risks midcap profit-booking.
Tuesday watchlist:
- IT stocks if Nasdaq holds gains
- Defence names on any dip below key DMAs (accumulation zone)
- Oil & Gas only if crude retreats
- Earnings surprises (Tata Motors, Vodafone Idea could move markets)
8. The Honest Take
For long-term investors: Two years of sideways markets, as Rajeev Thakkar noted, isn’t a bug — it’s a feature of consolidation. Goldman Sachs sees Nifty at 26,500 by mid-2027, roughly 8% upside from here over ten months. That’s not thrilling, but it’s real. The opportunities are emerging in segments that corrected: PSU Banks (SBI’s rally proves it), select pharma names post-tariff clarity, and real estate as lower-tier absorption sustains. Hindalco’s record quarter shows commodity plays aren’t dead if you pick the right cycle. Don’t chase Tata Tech at 52-week highs; wait for the inevitable pullback. Patience is your edge when the market has none.
For active traders: Today was a stockpicker’s market disguised as a dull index day. Britannia, Hindalco, and Tata Tech delivered 4–15% moves while Nifty sleepwalked. Earnings season is your hunting ground this week — scan for volume spikes, RSI divergences, and gap-ups post-results. Defence stocks are cooling; that’s where swing trades set up if you catch the 200-DMA bounce. Crude above $80 keeps Oil & Gas in the penalty box; short rallies there until the geopolitical picture clears. The midcap outperformance (+0.62% vs. Nifty’s +0.05%) says risk appetite isn’t dead, just selective. Follow the breadcrumbs, not the headlines.
— Unified Stocks
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett