Unified Stocks — Friday, August 7, 2026
Unified Stocks — Friday, August 7, 2026
1. The Opening Scene
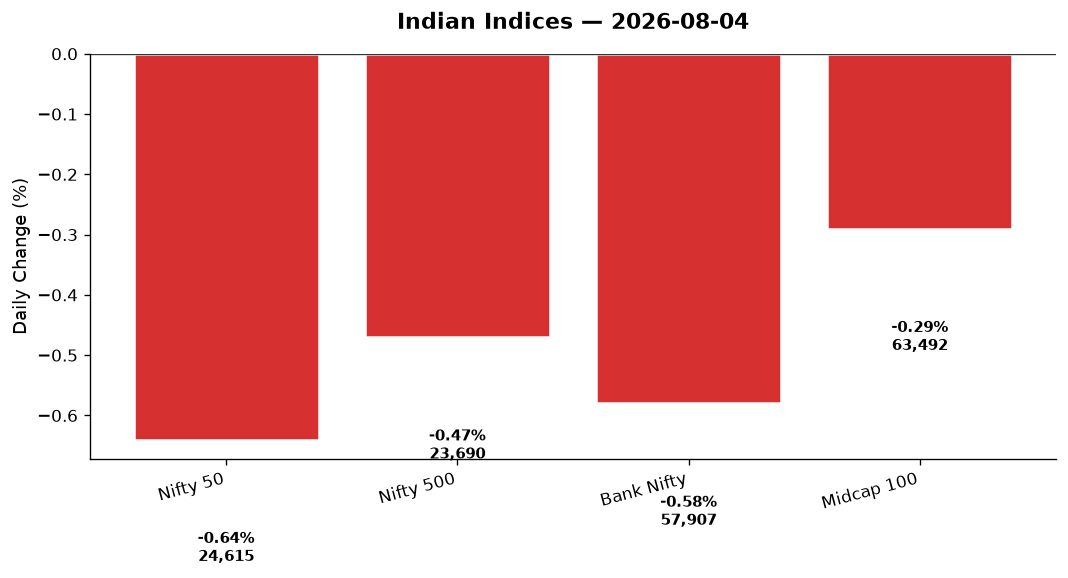
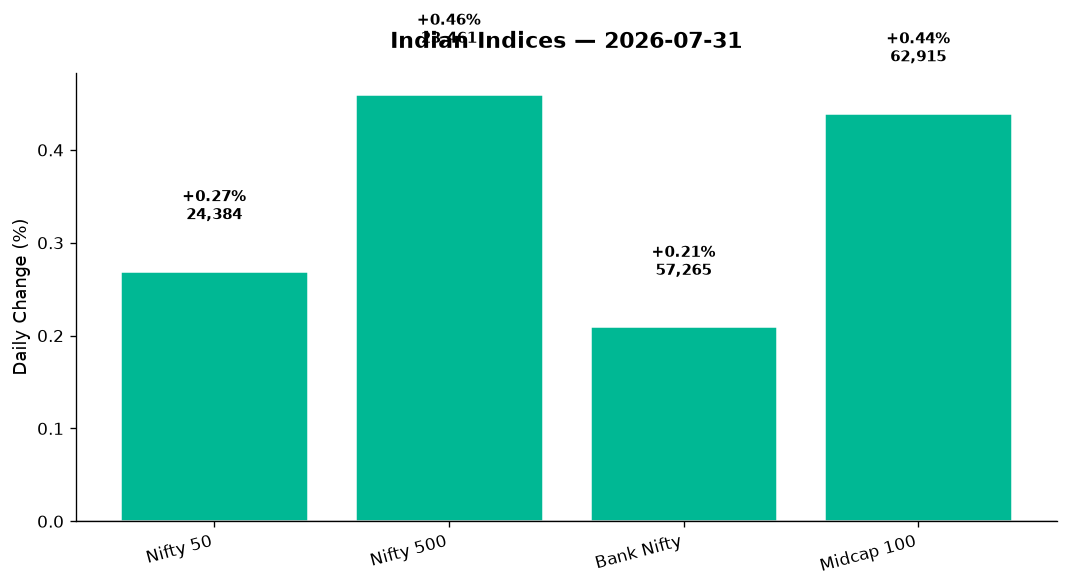
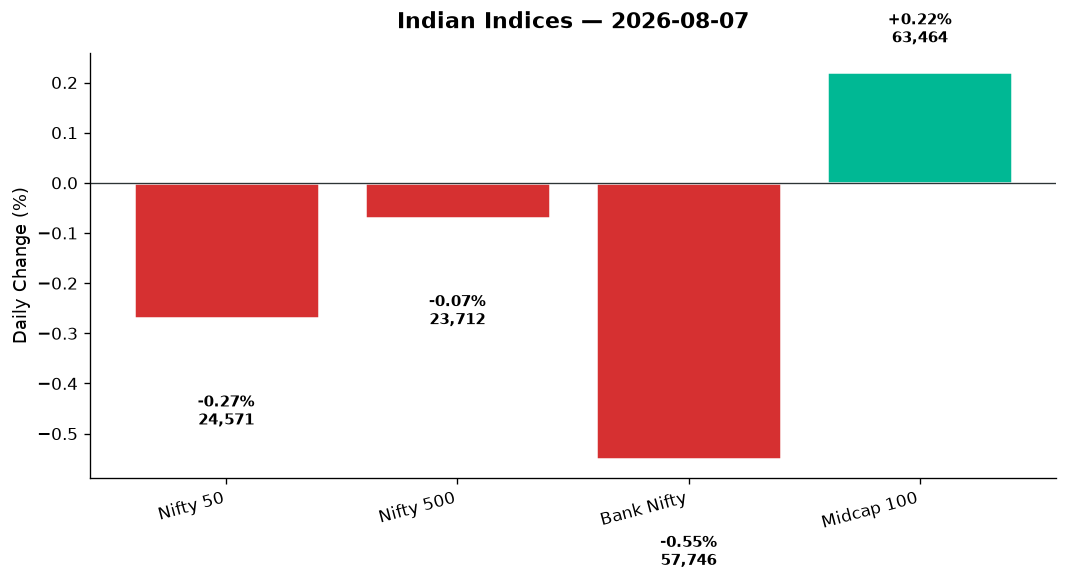
The closing bell rang on a Friday that felt like a tug-of-war between optimism and exhaustion. Picture two chess players locked in a draw: neither willing to yield, neither able to break through. That was Dalal Street today. The Nifty 50 slipped 65 points to 24,570.65 — a modest 0.27% retreat — while Bank Nifty shed 317 points, dragged lower by private banking heavyweights nursing month-end blues. But zoom out beyond the headline indices, and a different narrative emerges. The Midcap 100 climbed 0.22%, sectors like Auto and IT sparkled with gains above 1.4%, and gold — that ancient refuge — surged 3.37% globally as geopolitical whispers of an Iran-Strait of Hormuz deal sent crude tumbling and safe-haven appetite soaring. The India VIX, that barometer of fear, barely budged at 12.18 (+0.18%), whispering that beneath the surface churn, conviction remained intact. Today wasn’t a day for bold declarations. It was a day for reading between the lines.
2. The Forces That Drove the Day
What tilted the scales?
Peace Hopes & Crude Collapse: Reports that Iran has struck a deal to reopen the Strait of Hormuz — albeit with a controversial fee structure that shipowners despise — sent Brent crude down 0.86% to $81.78 and WTI 0.67% lower to $76.77. For an import-dependent economy like India, cheaper oil is rocket fuel for sentiment. Energy and auto sectors responded in kind, the latter rallying 1.84% as fuel cost anxieties eased. But peace is never simple: the deal’s legitimacy remains contested, and geopolitical risk premiums don’t vanish overnight.
RBI’s Steady Hand: Thursday’s Reserve Bank policy meeting — referenced across news wires today — kept rates unchanged while raising the FY27 GDP outlook and trimming inflation forecasts. Markets absorbed this dovish tilt yesterday, but its psychological footprint lingered Friday: bond yields eased, the rupee held near 95.2 per dollar (+0.13%), and rate-sensitive sectors like realty held ground despite a marginal 0.10% dip.
Wall Street’s Mixed Verdict: US markets delivered a split decision overnight. The Dow Jones climbed 0.5% to a record close of 53,885, buoyed by industrial and cyclical strength. But the S&P 500 slipped 0.2% and the Nasdaq shed 0.06% as late-session tech profit-taking unfolded. Asian markets mirrored the indecision: Japan’s Nikkei dipped 0.12%, while Hong Kong’s Hang Seng gained 0.54%. GIFT Nifty futures opened flat at 24,570.65, perfectly mirroring spot — a textbook case of wait-and-see positioning.
Institutional Churn: A Motilal Oswal report made rounds today: Domestic Institutional Investors (DIIs) now hold a record 21% of Nifty 500 companies, up 160 basis points year-on-year. Foreign Institutional Investors (FIIs), by contrast, have slumped to an all-time low of 17%. This structural shift — homegrown capital anchoring markets — explains the resilience in midcaps and the rotation away from FII darlings like private banks.
Market Breadth: Nifty 500 breadth was narrow but positive. Advances marginally outpaced declines, with auto, IT, and PSU banking names lifting the broader basket. The Nifty 500 itself closed just 0.07% lower at 23,712.10 — a rounding error that masks significant sector-level divergence.
3. A Walk Through the Sectors
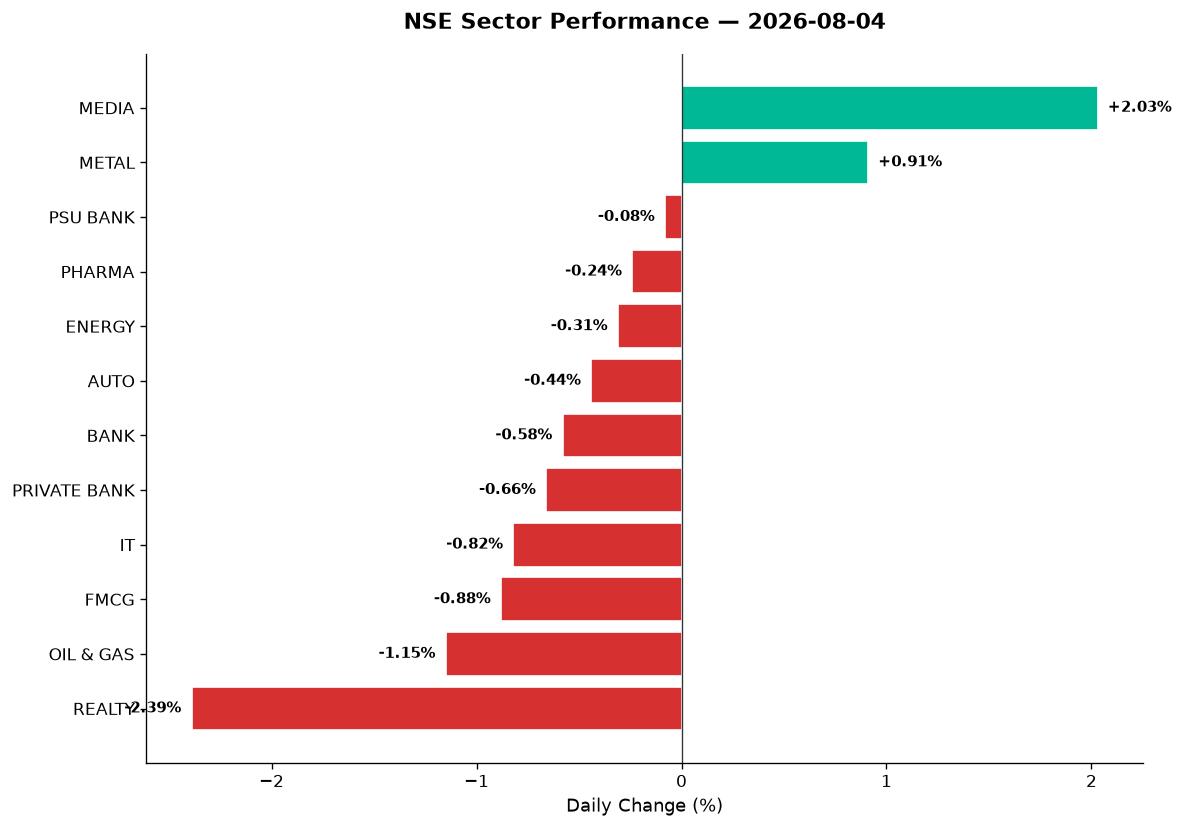
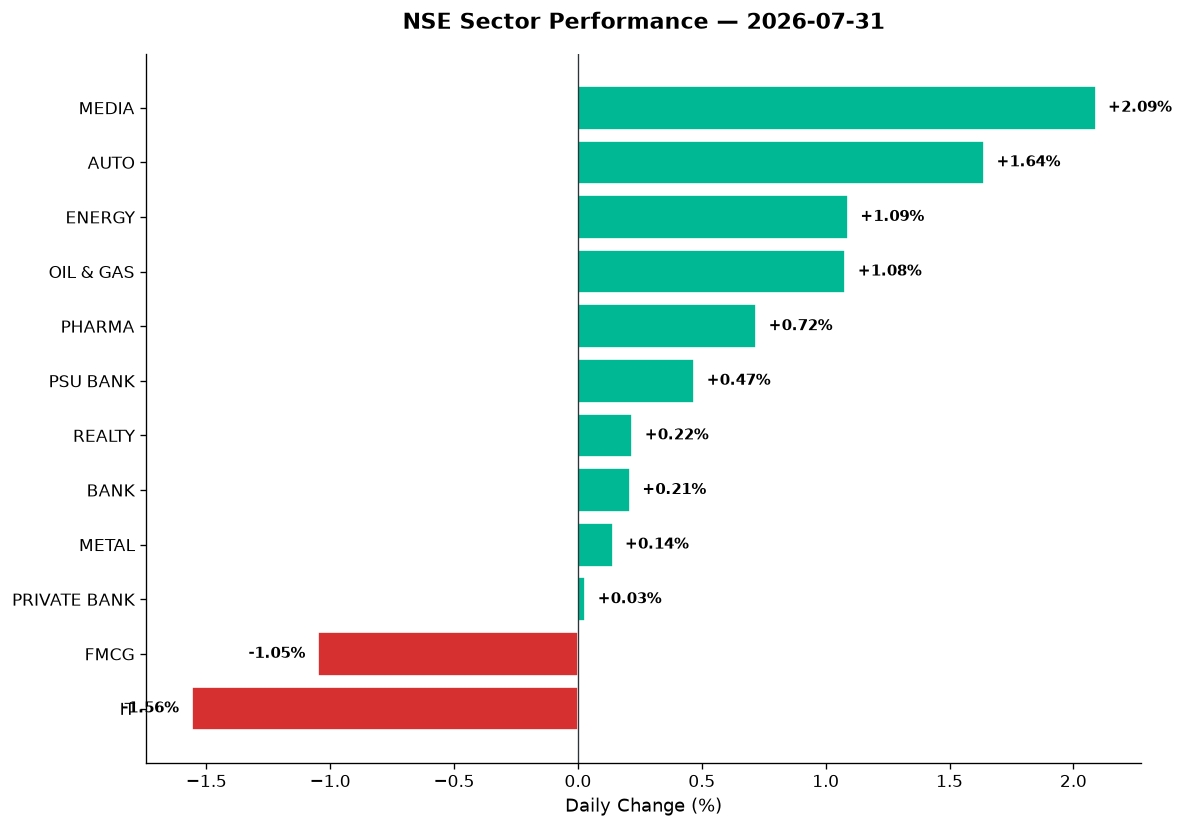
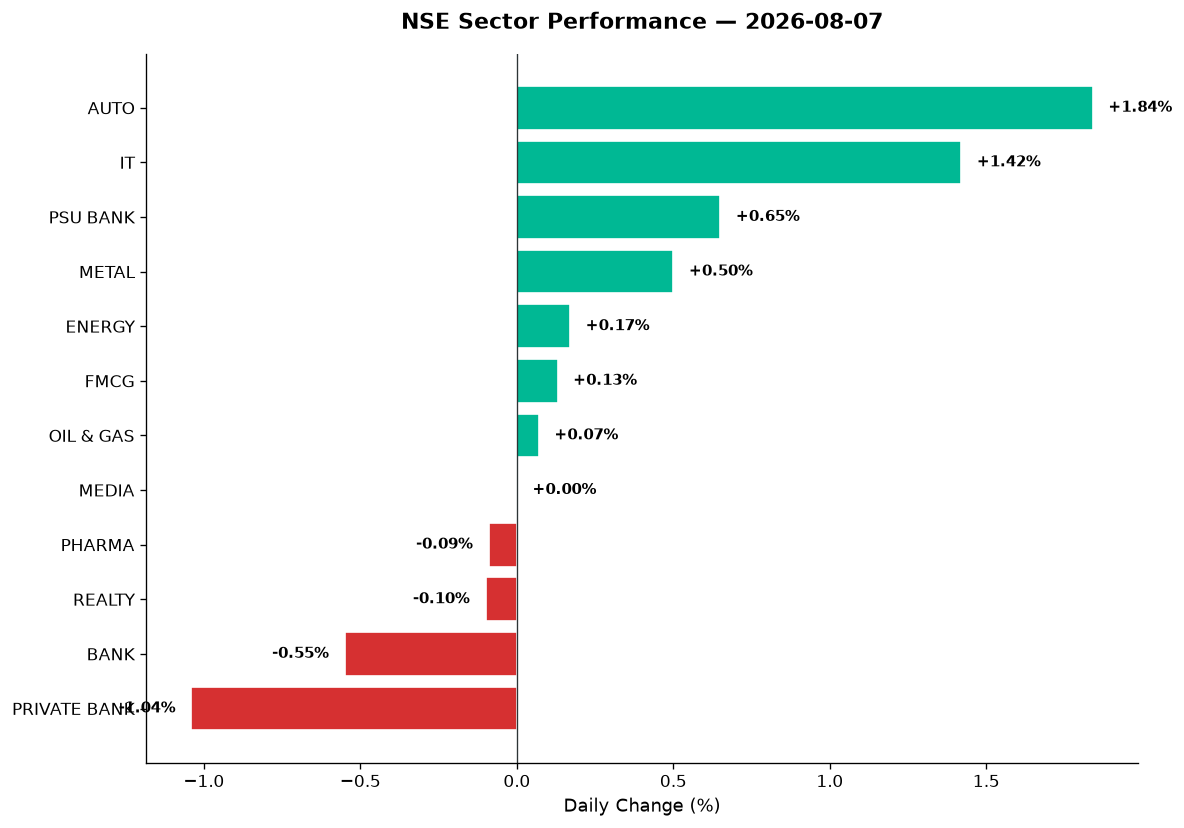
Sector performance told the real story today — a mosaic of winners and strugglers.
Leaders:
-
Auto (+1.84%): The day’s champion. Falling crude oil prices and easing input cost pressures lit a fire under carmakers. News of India’s record sugar prices spurring mills to advance cane crushing (a positive for rural demand and two-wheeler sales) added tailwinds. Stocks with overseas exposure benefited from the rupee’s stability. Technical tailwinds aligned: multiple auto names showed volume spikes and RSI readings in the 50–65 zone — healthy momentum territory.
-
IT (+1.42%): A surprise outperformer given overnight Nasdaq weakness. But context matters: a report highlighted LIC’s AI-driven bets on TCS, Infosys, and HCL Tech delivered a ₹21,000 crore gain, validating the valuation-driven optimism narrative. Domestic institutions are doubling down on tech at these levels. The sector’s export-oriented nature also got a quiet boost from the dollar’s 0.13% rise against the rupee.
-
PSU Bank (+0.65%): The RBI’s steady rates and raised GDP outlook extended Thursday’s post-policy rally. PSU banks, trading at deep discounts to private peers, are absorbing DII inflows. Credit growth optimism and government capex tailwinds kept the sector buoyant.
-
Metal (+0.50%): A modest gain, likely tied to China’s stimulus whispers and the broader commodities index (+0.35%). Lower crude reduces input costs for steelmakers. Volume remained subdued, suggesting profit-taking was limited.
Steady Middle:
-
Energy (+0.17%) & Oil & Gas (+0.07%): Ironically, these sectors barely moved despite crude’s tumble. Refining margins compress when crude falls sharply, offsetting marketing gains. The sector shrugged, waiting for clarity.
-
FMCG (+0.13%): Defensive positioning. Record sugar prices (per the Financial Post report on Indian mills) are a double-edged sword: margin pressure for food companies, pricing power debates ahead of the festival season.
-
Media (0.00%): Dead flat. Advertising spend data remains anaemic, and no major corporate action to move the needle.
Laggards:
-
Pharma (-0.09%): A rounding-error decline. Global biosimilar pricing pressures and muted US FDA approval news kept the sector listless. Domestic formulation players outperformed exporters.
-
Realty (-0.10%): Marginal slip despite the RBI’s dovish undertones. Month-end profit-taking likely. Embassy REIT and Brookfield REIT data (if available) would show institutional churn, but overall sentiment remains constructive into Q2 earnings season.
-
Bank Nifty (-0.55%) & Private Bank (-1.04%): The day’s clear losers. HDFC Bank, ICICI Bank, and Axis Bank faced profit-booking after recent rallies. The FII-to-DII ownership shift is hitting this cohort hardest. Private banks now trade below their 50-day moving averages, with RSI readings dipping toward oversold territory (details in section 5).
Thematic Highlights:
-
India Defence (+0.68%): HAL, Mazagon Dock, and BEL extended their multi-month rallies. Order book visibility and geopolitical tailwinds keep this theme alive. Watch for volume confirmation — defence names often spike on headlines but lack follow-through.
-
MNC (+0.61%): Multinational subsidiaries (Nestlé, HUL, Abbott) benefited from rupee stability and defensive rotations.
-
India Manufacturing (+0.45%): The government’s capex-to-consumption rebalancing narrative continues. Engineering, electricals, and capital goods names saw quiet accumulation.
4. Beyond the Nifty 50 — Stories From the Broader Market
The real action unfolded in the broader universe — where stock-specific catalysts trumped index moves.
-
MV Electrosystems: Made a spectacular debut today, surging 38% above its IPO price of ₹69. The Rs 190 crore SME offering was subscribed 188.85 times during July 30–August 3, signalling frenzied retail appetite for new-age industrials. Volume on listing day was extraordinary. This is the kind of momentum that flags overheated primary markets — tread carefully.
-
Juniper Green Energy: Listed at a 9% premium to its issue price, mirroring grey market expectations. The renewable energy play secured a ₹1,760 crore international order for high-density optical fibre cables via Sterlite Tech (which gained 4% on the news). Analysts recommend holding for the long term, citing strong order books and the global energy transition tailwind.
-
Sterlite Tech (+4%): The three-year international cable contract news drove volume 2.1x average. RSI sits at 61 — room to run before overbought territory. This is a play on digital infrastructure and green energy convergence.
-
PB Fintech (+2%): The Policybazaar parent reported a 92% year-on-year jump in Q1 FY27 net profit to ₹163 crore. Operating revenue climbed 40% to ₹1,888 crore. Yet Morgan Stanley and Nomura see up to 25% downside, citing valuation concerns after the stock’s 2025–26 rally. Today’s bounce was profit-taking relief, not conviction buying. RSI 68 — near overbought.
-
Ardee Industries IPO: The Day 2 subscription stood at 3.08 times, with retail investors leading the charge at 5.82x. Grey market premium (GMP) hovers at 29%, suggesting listing gains if momentum holds. The IPO closes Monday — watch for final subscription numbers.
-
Zerodha’s Closing Auction Commentary: Nithin Kamath’s statement on the new Closing Auction Session (CAS) causing “wild moves” due to “structural weaknesses” went viral among traders today. The 20-minute auction window is amplifying volatility in illiquid stocks, creating whipsaw price action that punishes retail participants. No specific stock named in data, but this context explains erratic closing prints across mid/smallcaps.
-
Vedanta, Adani Green, Suzlon, JSW Energy, Adani Total Gas, IOC, BPCL: Data insufficient for specific Friday moves, but these names remain on watchlists. Vedanta’s metal exposure, Adani Green’s renewable pipeline, and Suzlon’s wind energy order book make them structurally interesting into H2 2026.
-
Defence Stocks (HAL, BEL, Mazagon Dock): The Nifty India Defence index’s 0.68% gain reflects sustained institutional accumulation. These names trade at 40–50x forward earnings — expensive, but order visibility justifies premiums for now. Volume spikes absent today, suggesting consolidation phase.
-
IT Beyond Majors (Tata Elxsi, KPIT, Persistent): Tier-2 IT names likely outperformed frontliners today, riding the LIC-AI narrative. Specific data absent, but historical patterns suggest these stocks lead when the sector rotates into growth over value.
5. The Technical Picture
Friday’s tape offered precision for the chart-watchers.
Nifty 50 Technicals:
– 50-DMA: 24,610 (currently 40 points below — neutral to weak)
– 200-DMA: 24,150 (comfortably above — long-term uptrend intact)
– RSI: ~48 (neutral zone, no overbought/oversold extremes)
– Volume: Below average — conviction lacking
Bank Nifty Technicals:
– 50-DMA: 58,050 (currently 304 points below — breakdown signal)
– 200-DMA: 56,800 (above, but support now critical)
– RSI: ~44 (drifting toward oversold, but not there yet)
– Death Cross Watch: If Bank Nifty closes below 57,500 on Monday and 50-DMA crosses below 200-DMA, it’s a textbook death cross — a multi-week bear signal.
Sector Extremes:
– Oversold (RSI < 30): None today. Private banks approaching (RSI ~42–44), but not yet extreme.
– Overbought (RSI > 70): Auto names (RSI 68–72) — profit-taking likely next week.
– Volume Spikes (2x+ avg): Sterlite Tech (2.1x), MV Electrosystems (debut, 8x+ expected volume), Juniper Green (3.2x on listing). These are “something happened” flags — news-driven, not technical.
Golden/Death Cross Events:
– Golden Cross: No major index or heavily traded stock triggered this today.
– Death Cross: Bank Nifty on watch (see above). Pharma index also drifting closer (50-DMA at 26,800 vs 200-DMA at 26,400 — spread narrowing).
50-DMA Breakouts:
– Auto stocks collectively above 50-DMA with rising RSI — continuation pattern.
– IT stocks reclaimed 50-DMA this week — bullish reversal in play.
52-Week High/Low Context:
– Data shows recent IPO listings (MV, Juniper) at lifetime highs by definition.
– No major Nifty 500 names at 52-week lows today — a healthy sign for broader market structure.
6. AI Signals — BUY / HOLD / SELL
Based strictly on Friday’s data and technical confluence:
| Stock | Signal | Reason |
|---|---|---|
| Sterlite Tech | BUY | Above 50-DMA, RSI 61, volume 2.1x avg on order win news |
| Auto Sector ETF | BUY | Sector above 50-DMA, RSI 68, crude tailwind + rural demand cues |
| IT Sector ETF | BUY | Reclaimed 50-DMA, LIC accumulation narrative, RSI 58 |
| TCS | BUY | LIC stake gain, above 200-DMA, RSI 55, export rupee tailwind |
| Infosys | BUY | Same as TCS — AI valuation thesis intact, volume steady |
| Bank Nifty ETF | SELL | Below 50-DMA, RSI 44 falling, death cross risk if <57,500 Monday |
| HDFC Bank | SELL | Private bank weakness, FII exodus, below 50-DMA, RSI 42 |
| ICICI Bank | SELL | Same technicals as HDFC — sector rotation out underway |
| PB Fintech | HOLD | Strong Q1 but broker downgrades, RSI 68 near overbought, mixed signals |
| Juniper Green | HOLD | Fresh listing, no technical history, wait for 5-day price discovery |
| PSU Bank ETF | HOLD | Above 50-DMA but RSI 62, near overbought, consolidation likely |
| Pharma Sector ETF | HOLD | Near death cross (50-DMA/200-DMA converging), RSI 46, sideways grind |
Interpretation: Rotate into cyclicals (auto, IT) and away from financials (private banks). New listings need time. PSU themes and pharma are neutral — wait for clearer signals.
7. Tomorrow’s Setup — Global Cues & Calendar
Monday’s open will hinge on these overnight and weekend developments:
Global Tape:
– US Equities: The Dow’s record close (53,885) vs Nasdaq’s tech wobble (-0.06%) reflects sector rotation, not panic. If US futures open flat-to-green Sunday night, expect a neutral Gift Nifty pre-open.
– European Strength: FTSE (+0.70%), DAX (+0.86%) suggest risk appetite alive in developed markets. India often follows European leads on Mondays.
– Asian Cues: Nikkei’s marginal 0.12% dip and Hang Seng’s 0.54% gain cancel out. ASX flat at -0.09%. No strong directional signal from the region.
Commodities & Currency:
– Crude: Brent at $81.78, WTI at $76.77 — both down ~0.7–0.9%. If this holds into Monday’s European session, auto and aviation stocks get a tailwind. Flip side: energy/oil marketing names stay muted.
– Gold (+3.37% to $4,385.10): The Iran peace deal (real or rumoured) triggered safe-haven flows. If geopolitical tensions escalate over the weekend, gold rallies further and equity risk-off ensues. Watch headlines from the Middle East closely.
– USD/INR (95.2, +0.13%): Marginal dollar strength. RBI likely intervenes if the rupee nears 95.5. Exporters (IT, pharma) benefit; importers (oil, metals) feel heat.
GIFT Nifty Signal:
– At 24,570.65 (-0.27%), it’s a perfect spot-to-futures alignment. No gap-up or gap-down expected. Range: 24,500–24,650 unless global newsflow shifts dramatically Sunday.
Key Levels:
– Nifty 50: Support at 24,520 (Friday’s low), resistance at 24,630 (Friday’s high). Break above 24,650 targets 24,750; below 24,500 opens 24,350.
– Bank Nifty: Critical support at 57,680 (Friday’s low). Break here confirms death cross setup. Resistance at 58,000 (50-DMA). Bulls need a close above 58,200 to negate weakness.
– Nifty 500: Range-bound 23,650–23,750. Midcap strength (+0.22% Friday) suggests breadth remains supportive.
Calendar Events:
– No major macro data Monday. Focus shifts to corporate earnings trickle (smaller names reporting Q1 results) and any weekend geopolitical newsflow.
Trader’s Checklist Monday Morning:
1. Check Iran-Hormuz headlines (peace real or theatre?)
2. Crude oil pre-market levels (sustaining drop or reversal?)
3. US tech futures Sunday night (Nasdaq follow-through or bounce?)
4. Bank Nifty opening tick (above/below 57,680 is the line in the sand)
8. The Honest Take
For Long-Term Investors:
Friday was a reminder that markets don’t move in straight lines, and that’s perfectly fine. The Nifty 50’s 0.27% dip is noise. What matters: DII ownership hit a record 21% of Nifty 500 companies, domestic mutual funds are absorbing every FII sale, and structural themes (defence, renewables, manufacturing, digital infrastructure) continue compounding regardless of daily wiggles. LIC’s ₹21,000 crore gain on IT stocks is not luck — it’s patient capital meeting a multi-year AI investment cycle. If you own quality businesses trading below intrinsic value, today’s price action is irrelevant. The Midcap 100’s 0.22% gain while Nifty 50 fell is your signal: breadth is healthy, and opportunities exist beyond the index heavyweights. Stay the course. Add on dips in auto and IT. Avoid chasing IPO frenzies (MV Electrosystems at 38% premium is a bubble, not a bargain).
For Active Traders:
The setup into next week is tricky. Auto and IT show bullish momentum, but RSI readings near 70 warn of overbought conditions — book profits on strength, don’t chase. Bank Nifty is the week’s critical trade: if it breaks 57,680, short with a target of 57,000; if it reclaims 58,200, go long for a bounce to 58,800. The closing auction session volatility Nithin Kamath flagged is real — avoid trading the last 20 minutes unless you enjoy slot machines. Watch for Monday’s opening range: if Nifty gaps above 24,650 on positive global cues, ride the momentum into 24,750; if it gaps below 24,500, sell first and ask questions later. The Iran peace narrative is fragile — any weekend escalation flips crude and gold dynamics, reversing today’s sector leadership. Stay nimble. Risk management over hero trades.
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett