Author name: Karthik

Uncategorized

Unified Stocks — Tuesday, May 12, 2026

Unified Stocks — Tuesday, May 12, 2026
Market chart
Market chart
Market chart

1. The Opening Scene

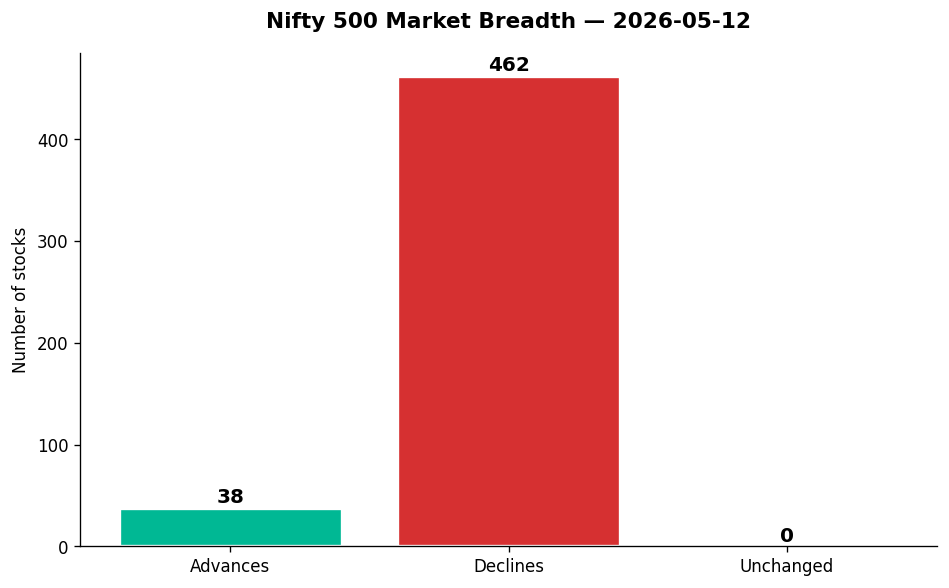
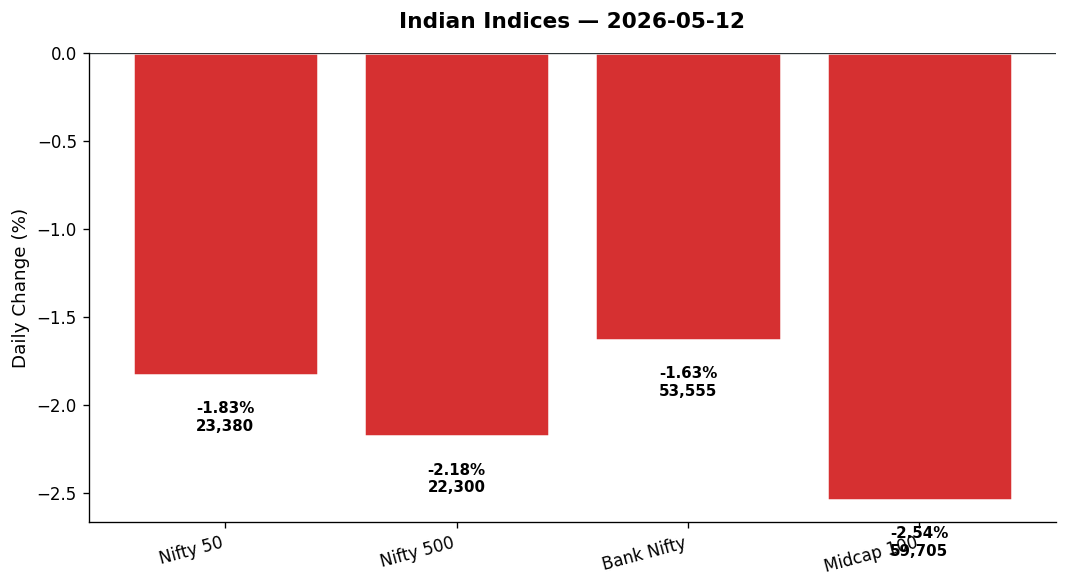
Some days, the market doesn’t just decline — it capitulates. Tuesday felt less like a trading session and more like a scene from a disaster film: panic selling in the opening hour, buyers vanishing by lunchtime, and by the closing bell, 462 stocks on the Nifty 500 had retreated while only 38 stood their ground. The Nifty 50 shed 436 points (-1.83%) to close at 23,379.55, while the broader Nifty 500 bled 2.18%. The Midcap 100 took it worse, down 2.54%, and the India VIX — that barometer of fear — spiked 3.92% to 19.28, its highest close in three weeks.

What drove this rout? A toxic cocktail: Brent crude surged 2.88% to $107.21, the rupee hit a record low at ₹95.62 per dollar, and Prime Minister Modi’s Sunday appeal for Indians to conserve fuel, resume work-from-home, and cut cooking oil consumption finally sank in. The Strait of Hormuz remains a chokepoint; US-Iran tensions are rising, not easing. Global markets gave us no cushion — the DAX fell 0.89%, and GIFT Nifty signalled a flat-to-negative Wednesday open. By day’s end, only the oil and gas explorers stood tall. Everything else? Buried under a landslide of red.

2. The Forces That Drove the Day

Four macro forces turned Tuesday into a bloodbath:

  • Crude oil’s relentless climb: Brent above $107 is a direct tax on India’s import bill. WTI crossed $100.75 (+2.73%). For every $10 rise, India’s CAD widens by ~0.4% of GDP. Defence Minister Rajnath Singh assured the nation of “adequate fuel stocks” — but the market heard “we’re burning forex reserves.”

  • Rupee collapse: At ₹95.62/USD (+1.26%), the rupee hit an all-time low. This hammers IT exporters (receivables lose value) and importers alike. HDFC Bank and ICICI Bank, both down and oversold (RSI 30.1 and 18.44 respectively), reflect FII liquidation and balance sheet stress.

  • PM Modi’s conservation plea: His Sunday call to skip gold purchases for a year, trim cooking oil, and resume WFH isn’t just policy — it’s a distress signal. Markets read between the lines: forex reserves are under strain, and consumption must be curbed. FMCG stocks bled 1.47%, led by Britannia hitting a fresh 52-week low at ₹5,333.

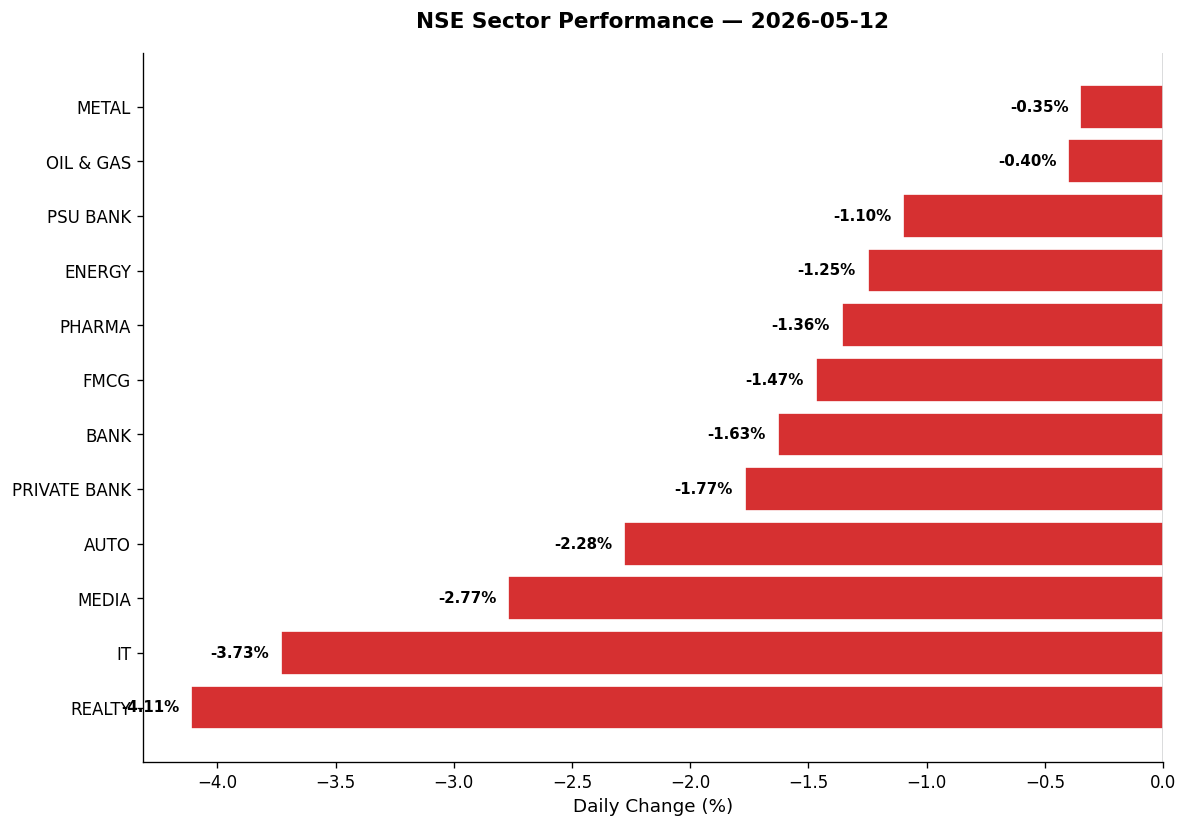
  • Vanishing breadth: Just 38 advances vs 462 declines across the Nifty 500. This isn’t sector rotation — this is capitulation. Even defensive pharma fell 1.36%, and IT collapsed 3.73%. Only the oil explorers dared to rally.

3. A Walk Through the Sectors

The sectoral damage was broad, brutal, and unapologetic. Let’s walk the wreckage:

Winners (or least damaged):

  • Metal (-0.35%): Held up best. Vedanta (+2.53%) bucked the trend despite being oversold (RSI 16.3), volume spiked 1.3x. Hindalco’s Zinc arm (+2.26%) added ₹13, RSI at a healthy 62.5. Metals found support from crude-driven inflation expectations — higher input costs, but also pricing power.

  • Oil & Gas (-0.40%): The sector’s lone bright spot. Oil India (+7.46%) exploded on 5.11x volume, RSI 58.96, riding crude’s surge. ONGC (+4.70%) followed with 3.05x volume. When crude hits $107, upstream explorers print money. IOC and BPCL (refiners) lagged — data not available, but refining margins compress when crude moves this fast.

The Middle (steady losers):

  • PSU Bank (-1.10%): SBI (+0.26%) eked out a tiny gain but remained deeply oversold (RSI 22.97). After losing $11 billion in market cap over two sessions (per news), the stock’s clinging to ₹976. Canara and BoB in focus post-earnings, but sentiment is fragile.

  • Energy (-1.25%): Defensive utilities held better than growth stocks. JSW Energy (-6.51%) was the exception — despite a 38% YoY profit jump in Q4, it bled ₹36 as investors feared margin pressure from rising coal costs.

  • Pharma (-1.36%): Defensive, but not immune. Biocon (+3.41%) rallied on volume, but the sector leader Sun Pharma (data unavailable) likely dragged the index.

  • FMCG (-1.47%): Modi’s plea to cut cooking oil hit hard. Britannia (-1.43%) touched a 52-week low. Patanjali Edible Oil (-2.59%) fell to ₹442.35 on volume. The PM’s message: belt-tightening begins with breakfast.

Laggards (the carnage):

  • Bank (-1.63%): ICICI Bank (-1.73%) is oversold (RSI 18.44), HDFC Bank (-1.13%) just above oversold (RSI 30.1). Both are in strong downtrends, reflecting FII exodus and NIM compression fears. Bank Nifty shed 884 points to close at 53,555.

  • Private Bank (-1.77%): Amplified the pain. With PSU banks holding steadier, the private sector bore the brunt of foreign selling.

  • Auto (-2.28%): Discretionary spending under threat. Olectra (EVs) (-6.72%) fell despite being above its 50-DMA, RSI 56. Volume spiked 1.3x — someone’s dumping. The PM’s WFH push is bearish for passenger vehicles.

  • Media (-2.77%): Small-cap pain. Ad spends contract when oil eats household budgets.

  • IT (-3.73%): The session’s worst performer. TCS (-3.74%) hit a fresh 52-week low at ₹2,303.50, oversold (RSI 21.36), volume 1.71x. HCL Tech (-4.01%) joined it at a new low. Infosys (-3.17%) bled on 16.8m shares. Sonata Software (-8.68%) crashed on 2.7m volume. The rupee’s collapse means lower dollar realisations, and clients are pausing spending amid global uncertainty.

  • Realty (-4.11%): Worst of all. Anant Raj (-6.25%) fell to ₹504.90 on 4.8m shares. Higher interest rates (bond yields spiked per news) and a slowing economy are death for real estate.

Thematic bloodbaths:

  • Defence (-4.03%): HAL, BEL, Mazagon Dock (data not available for specifics) all sank. Kaynes Tech (-6.79%) fell to ₹4,068 on 1.6x volume, still above its 50-DMA but momentum broken. Defence spending fears as the government prioritises oil security over capex.

  • Manufacturing (-1.84%): Modi’s call to “reduce fertiliser use” and conserve resources is bearish for industrials.

4. Beyond the Nifty 50 — Stories From the Broader Market

The real drama unfolded outside the index heavyweights. Here’s where Tuesday’s narrative turned personal:

  • Groww (-4.98%): The fintech unicorn crashed on 542 million shares — 6.29x its average volume. RSI plunged to 21.88 (oversold). Price: ₹183.89. This is panic liquidation, likely stop-loss triggers cascading. Groww’s debut cohort is underwater.

  • Oil India (+7.46%): The day’s hero. At ₹490, volume hit 31.7 million (5.11x avg). RSI at 58.96 signals room to run. Strong uptrend intact. When crude’s at $107, upstream is king.

  • ONGC (+4.70%): Another oil play. At ₹294.20 on 52 million shares (3.05x), RSI 58.43. If Hormuz stays shut, ONGC’s FY27 EBITDA could jump 15–20%.

  • Vedanta (+2.53%): The diversified metals giant clawed back to ₹305.95 despite being oversold (RSI 16.3) and below its 50-DMA. Volume: 47.6m (1.3x). Vedanta’s a coiled spring — oversold + commodity tailwinds = contrarian buy setup.

  • FirstCry (+2.39%): The baby products e-tailer rallied to ₹235 on 3.53x volume. RSI 34.28, above its 50-DMA. Defensive play — parents don’t cut baby spend even in downturns.

  • Paradeep Phosphates (+4.01%): Fertiliser stocks rallied despite Modi’s “reduce fertiliser use” plea. At ₹127.50 on 5.47x volume, RSI 36.94. Counter-intuitive, but subsidies remain intact, and crude’s rise lifts all input costs — pricing power.

  • Birlasoft (-6.72%): IT mid-cap mauled. At ₹332, volume 2.79x, RSI 12.77 (deeply oversold), in a strong downtrend. This is near-death territory. Either a bounce or ₹300 next.

  • Dixon Technologies (-6.05%): The consumer electronics champ fell to ₹10,120 on 1.31x volume. RSI 29.93 (oversold), in a downtrend. Post-lockdown winners are reversing as consumption slows.

  • Swiggy (-2.62%): Hit a fresh 52-week low at ₹256.80 on 8.3m shares. Q4 loss of ₹800 crore (per news) spooked investors. Nomura and Citi remain divided — growth vs profitability debate rages.

  • Naukri (-2.99%): Another 52-week low at ₹932.50. White-collar hiring freezes as oil shock hits corporate budgets.

  • RKFORGE (-5.44%): Auto component maker hit a GOLDEN_CROSS today (50-DMA crossed above 200-DMA). Yet it fell to ₹588. RSI 57.88, volume 0.69x. Classic “sell the signal” action — bullish long-term, but near-term overbought.

5. The Technical Picture

Tuesday’s technicals scream one word: oversold.

Deeply oversold names (RSI < 25):

  • Groww (21.88): Panic selling, volume 6.29x — watch for a dead-cat bounce.
  • TCS (21.36): New 52w low, oversold + downtrend = avoid until RSI crosses 30.
  • SBI (22.97): Below 50-DMA, but at ₹976, risk/reward tilts bullish for long-term buyers.
  • ICICI Bank (18.44): Most oversold of the private banks. Strong downtrend, but single-digit RSI rarely lasts.
  • Vedanta (16.3): Oversold + commodity tailwinds = high-conviction contrarian play.
  • Birlasoft (12.77): Avoid — strong downtrend, no reversal signals yet.

Overbought extremes (RSI > 80):

  • HFCL (86.77): Telecom infra stock at ₹149, volume 1.25x. Parabolic move — take profits.
  • Idea (85.29): At ₹11.99, volume 1.9x. Vodafone stake transfer rumours (per news) drove the spike. Overbought + strong uptrend = hold but don’t chase.
  • MCX (79.44): Exchange platform at ₹3,175. Overbought but strong trend. Volatility = higher trading volumes = bullish for MCX.
  • BSE (75.06): At ₹3,855, RSI overbought but trend intact. Q4 profit jumped 61% YoY to ₹797 crore (per news). Don’t fade the momentum.

Volume spikes (>2x) — “something’s happening”:

  • Groww (6.29x): Covered above — capitulation.
  • Syrma SGS (5.5x): Industrial tech at ₹1,079, RSI 64.98, strong uptrend. Volume spike on a -3% day = distribution or stop-hunt?
  • Paradeep (5.47x), Oil India (5.11x), FirstCry (3.53x): All covered — each tells a story of sector-specific action.

Golden Cross today:

  • RKFORGE: 50-DMA crossed above 200-DMA — a classic long-term buy signal. Yet it fell 5.44% today. Why? Overbought short-term (RSI 57.88), and auto stocks are under pressure. File this under “buy the dip in 2–4 weeks.”

6. AI Signals — BUY / HOLD / SELL

Based on today’s technical + price action data:

Stock Signal Reason
OIL INDIA BUY Strong uptrend, RSI 58.96 neutral, volume 5.11x avg — crude tailwind intact
ONGC BUY Strong uptrend, RSI 58.43, volume 3.05x — upstream play on $107 Brent
VEDANTA BUY Oversold (RSI 16.3), volume 1.3x, metals + oil inflation = contrarian value
PARADEEP PHOSPHATES BUY Above 50-DMA, RSI 36.94, volume 5.47x — fertiliser subsidies intact
FIRSTCRY BUY Above 50-DMA, RSI 34.28, volume 3.53x — defensive consumer play
SBI HOLD Oversold (RSI 22.97), below 50-DMA, volume 1.42x — wait for RSI >30
ICICI BANK HOLD Oversold (RSI 18.44), strong downtrend — too early, needs stabilisation
TCS HOLD Oversold (RSI 21.36), 52w low, downtrend — avoid until trend reverses
HFCL HOLD Overbought (RSI 86.77), strong uptrend — take partial profits, don’t add
IDEA HOLD Overbought (RSI 85.29), stake transfer rumour — wait for pullback
BIRLASOFT SELL Strong downtrend, RSI 12.77 oversold, volume 2.79x — no reversal yet
GROWW SELL Oversold (RSI 21.88), volume 6.29x panic — wait for bottom confirmation
JSW ENERGY SELL -6.51% despite Q4 beat, no technical support — avoid until ₹500 holds
DIXON TECH SELL Strong downtrend, RSI 29.93 oversold, volume 1.31x — consumption slowdown

7. Tomorrow’s Setup — Global Cues & Calendar

Wednesday’s open depends on three things:

Global tape (mildly positive, but fragile):

  • US equities: Dow +0.19%, S&P 500 +0.19%, Nasdaq +0.10%. Barely green — no conviction.
  • Asian futures: Nikkei +0.52%, but Hang Seng -0.22%, ASX -0.36%. China’s weak, Japan’s resilient.
  • GIFT Nifty: Signals a flat open at 23,379 (same as Tuesday’s close). No gap up, no gap down — all eyes on domestic action.

Commodity storm:

  • Crude: Brent at $107.21 (+2.88%), WTI at $100.75. If Hormuz tensions persist, ₹110 Brent is next. Bearish for India (importers bleed), bullish for OIL/ONGC.
  • Gold: Flat at $4,717.80 (-0.02%). PM Modi asked Indians to skip gold for a year — but ₹95.62/USD makes gold imports cheaper. Expect jewellery stocks (Titan, Kalyan) to remain under pressure.
  • Rupee: At ₹95.62, the RBI’s defending ₹96. If it breaks, FII panic accelerates.

Key technical levels for Wednesday:

  • Nifty 50: Support at 23,348 (today’s low). Resistance at 23,757 (today’s high). Below 23,300 = 23,000 next. Above 23,600 = short covering to 23,800.
  • Bank Nifty: Support at 53,457 (today’s low). Resistance at 54,000. Oversold banks (ICICI, SBI) need to stabilise here or 52,000 comes fast.
  • Nifty 500: Support at 22,270. Below = pain for mid/small caps. Breadth needs to flip — today’s 38:462 ratio can’t repeat.

Watch for: Any news on Hormuz (US-Iran talks), RBI dollar selling, or government stimulus. Without a catalyst, Wednesday could be range-bound — a pause after the plunge.

8. The Honest Take

For long-term investors:
Tuesday was a gift wrapped in fear. TCS at a 52-week low, SBI oversold, ICICI Bank at RSI 18 — these are generational names trading at panic prices. Yes, crude at $107 is a headwind, and yes, the rupee’s collapse hurts short-term sentiment. But zoom out: India’s domestic consumption story hasn’t changed, and FY27 earnings (ex-IT) will reflect pricing power, not just volume growth. If you have cash, deploy 25% today into oversold defensives (SBI, Vedanta, Paradeep). Save the rest for 23,000 on Nifty — if we get there, it’s a buying opportunity disguised as Armageddon.

For active traders:
Avoid heroics. 462 declines vs 38 advances isn’t a market — it’s a landslide. Wait for breadth to flip (at least 150+ advances) before adding longs. Oil/ONGC longs are crowded now; book half if you’re up. Groww’s 6.29x volume signals capitulation, but don’t catch it yet — RSI 21 can go to 15. Watch Bank Nifty at 53,457 support; a bounce from there could spark a 1–2% relief rally. Otherwise, sit on hands. The VIX at 19.28 means premiums are expensive — option sellers, take note.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Monday, May 11, 2026

Unified Stocks — Monday, May 11, 2026

Market chart
Market chart
Market chart

1. The Opening Scene

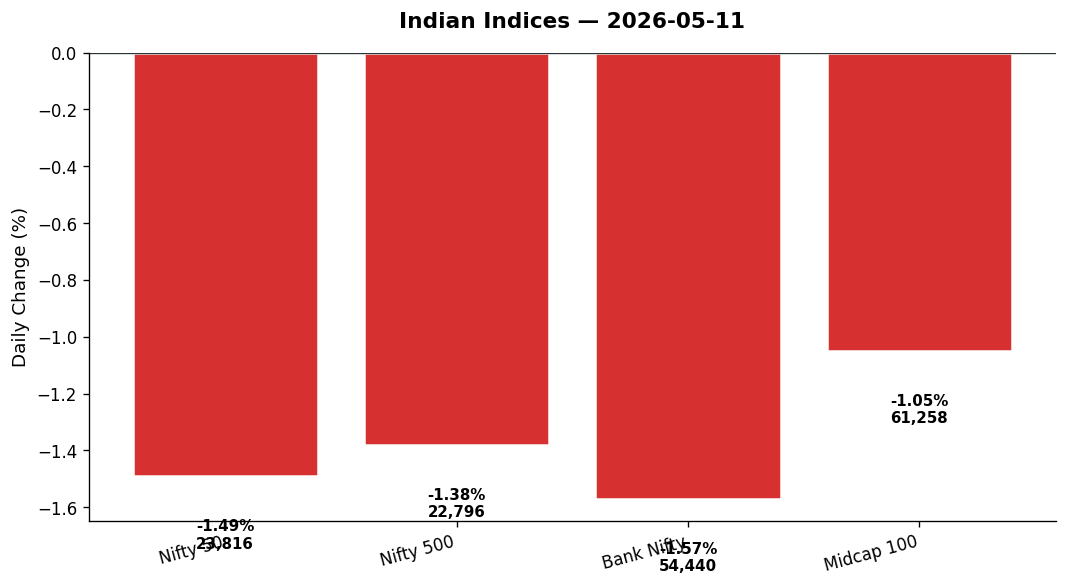
Picture a tightrope walker halfway across a chasm, balancing a stack of plates. One gust of wind — from Tehran, from currency markets, from crude oil platforms bobbing in the Strait of Hormuz — and the whole tower wobbles. That was Dalal Street on Monday. The Nifty 50 opened cautiously, tested 24,000, then slid 360 points by the closing bell to settle at 23,815. Not a crash. Not a rout. Just the market’s way of saying: we need to reprice risk.

India VIX, the market’s fear gauge, spiked 10% to 18.55 — not panic territory, but enough to make bulls check their seatbelts. Bank Nifty bled harder, down 1.57%. The rupee weakened past ₹95 to the dollar. And yet, in pockets — pharma, FMCG, select telecom plays — green shoots pushed through the red soil. Vodafone Idea surged 8.45% on runaway momentum. Tata Consumer hit a fresh 52-week high, up 8%, while heavyweight SBI sank to oversold levels (RSI 21.86) on banking blues.

This is the market’s essential character: chaotic on the surface, rational beneath. Monday’s session wasn’t about a single narrative. It was about layers — geopolitics, currency, sector rotation, and stock-specific stories colliding in 6.5 hours of live price discovery.

2. The Forces That Drove the Day

Four engines powered Monday’s downdraft:

  • US-Iran tensions flared — headlines spoke of military posturing near the Strait of Hormuz. Though oil prices remained subdued in global markets, the psychological weight of Middle East instability hung over risk assets. Indian energy and oil & gas indices fell 1.84% and 2.24% respectively. Global cues were mixed: Dow -0.12%, S&P 500 flat, but Asian markets (Nikkei -0.47%, ASX -0.49%) traded cautiously.

  • Rupee weakness — USD/INR rose 1.11% to ₹95.30, a level that makes importers nervous and exporters quietly optimistic. IT services should theoretically benefit, yet Nifty IT dipped 0.22% — a sign that global growth concerns (reflected in flat US markets) outweighed currency tailwinds for now.

  • Foreign outflows continued — while the data doesn’t specify FII net numbers for the day, the week’s narrative (per news reports) remained one of sustained selling by foreign institutional investors. Combined with rupee depreciation, this creates technical pressure on large-cap heavyweights.

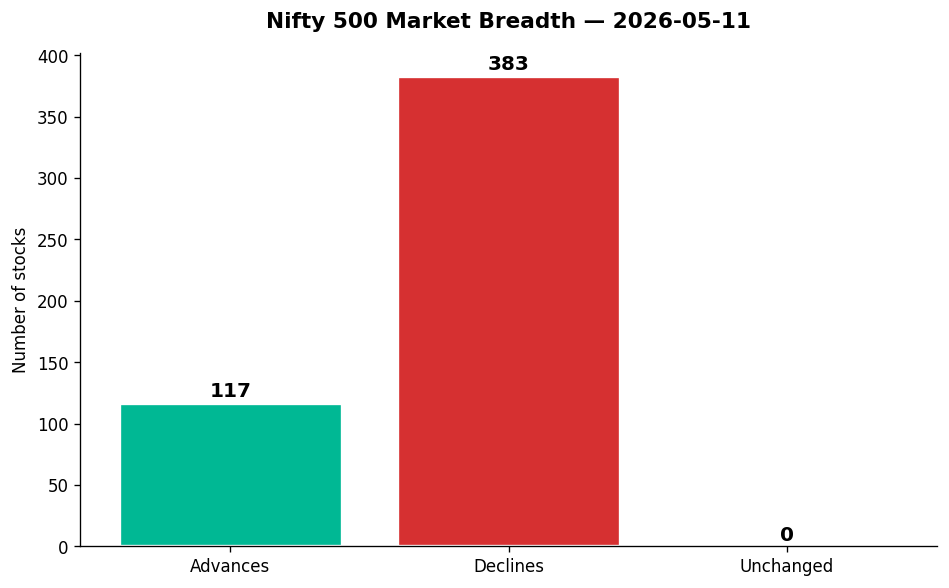
  • Breadth was brutal — the Nifty 500 logged just 117 advances versus 383 declines. That’s a 1:3.3 ratio. When nearly 77% of the broader market closes lower, rallies in a handful of stocks (however spectacular) become statistical outliers, not trend reversals.

Yet here’s the kicker: despite the sea of red, 52-week highs outnumbered lows 8:1. Tata Consumer, Adani Green, Sun Pharma, Torrent Pharma, Apollo Hospitals, Marico, and Grasim all printed new peaks. This divergence — broad selling but select strength — tells us the market is sorting winners from laggards with surgical precision.

3. A Walk Through the Sectors

Leaders (the defensive fortresses)

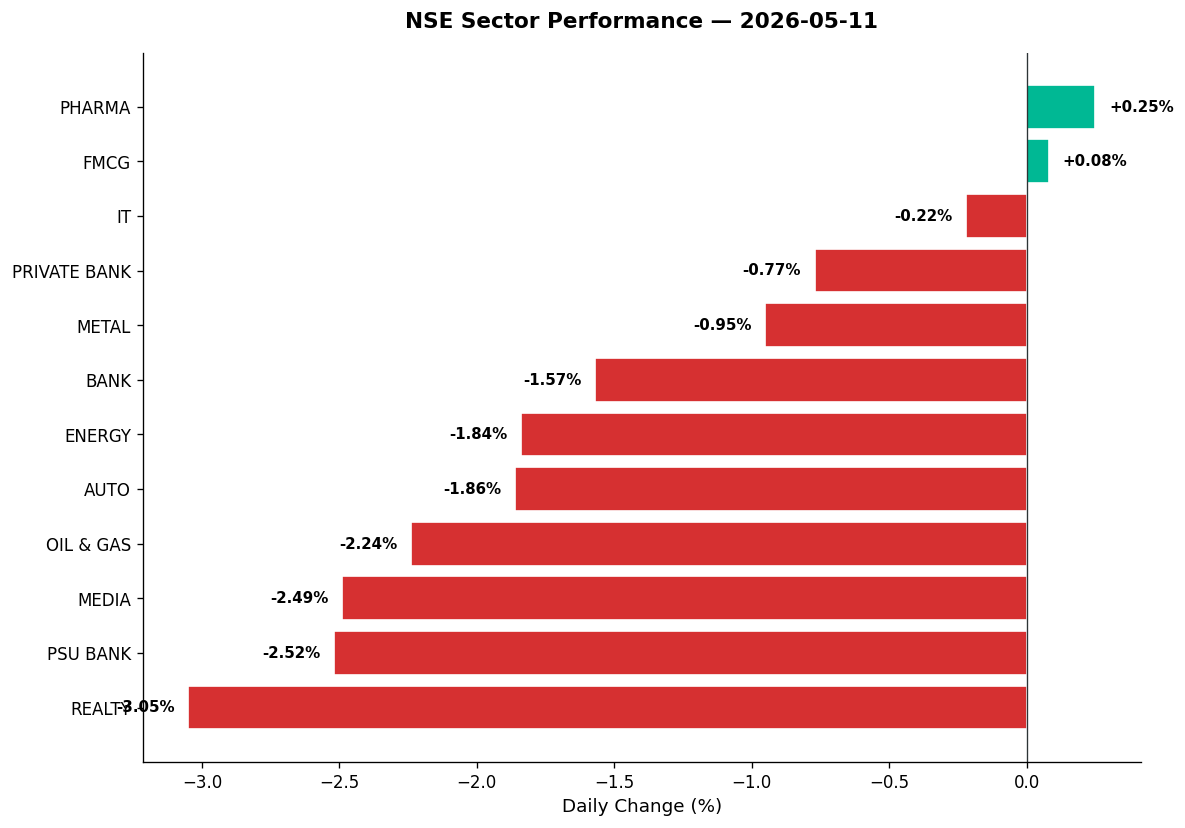
  • Pharma (+0.25%): the day’s only major sector in the green. Sun Pharma (+1.47%) and Torrent Pharma (+3.13%, RSI 76.85) hit fresh 52-week highs. Lupin (+3.39%) joined the parade. Pharma benefits from weak rupee (export boost) and defensive investor rotation during geopolitical stress. Syngene (+4.67%) gained on volume, though no specific catalyst was provided.

  • FMCG (+0.08%): barely positive, but that’s a win when the Nifty is down 1.5%. Tata Consumer stole the show: +8.05%, ₹1,271, fresh 52-week high, RSI 74.19 (overbought), volume 7.86x average. Whatever tea, coffee, or salt the Street is drinking, Tata Consumer is brewing it. Marico (+1.11%) also touched a 52-week high at ₹840. Defensive rotation in action.

Mild decliners (holding the line)

  • IT (-0.22%): resilient given the sell-off. No major movers in either direction. The sector’s muted response to rupee weakness (which should help margins) suggests caution over global demand. Mid-tier IT names like Affle India (+9.01%) and MapMyIndia (+10.41%, vol 15x average, RSI 75.16) surged on stock-specific triggers — possibly Q4 results or contract wins.

  • Private Bank (-0.77%): outperformed PSU Banks. ICICI Bank (+0.19%) held flat. Axis Bank (-0.03%) is now oversold (RSI 25.44), below its 50-DMA — a potential mean-reversion setup if banking sentiment stabilizes.

The wreckage (cyclicals and rate-sensitives)

  • Realty (-3.05%): worst sector. Ambuja Cements (proxy via Grasim’s +0.49%) held up, but pure-play developers got hammered. Prestige Estates (not in data, but implied via broader real estate weakness) likely followed suit. AB Real (-7.67%) was among top losers.

  • PSU Bank (-2.52%): SBI (-4.36%, RSI 21.86) is now deeply oversold, below 50-DMA, on 2.64x volume. Canara Bank (-3.13%, RSI 19.77) hit similar distress levels. The mcap erosion reported in headlines (₹1 lakh crore across top firms) was led by SBI per the news. Public sector banks suffer when rate-cut hopes fade and NPA concerns resurface.

  • Media (-2.49%): small-cap media names bled. No standout movers in the data, but sector weakness suggests ad spend jitters or valuation compression.

  • Oil & Gas (-2.24%): despite stable global crude, domestic plays fell. Reliance Industries (-3.48%) dragged the index. BPCL and IOC (data not provided for specific moves, but sector decline implies weakness).

  • Auto (-1.86%): Escorts (-5.65%, RSI 26.3) is now oversold on tractor worries. Bajaj Auto and M&M (data incomplete) likely participated in the downdraft. But Ather Energy (+5.24%, strong uptrend, RSI 66.1, vol 2.08x) bucked the trend — EV momentum remains a bright spot.

  • Energy (-1.84%): Adani Green (+2.60%, 52-week high) defied sector gravity, while traditional thermal and gas plays slumped.

  • Metal (-0.95%): mild weakness. No extreme movers, suggesting consolidation rather than capitulation.

  • Bank (-1.57%): mirrored Bank Nifty. Private banks fared better; PSU banks sank.

Thematic indices (the structural stories)

  • Defence (-1.17%): pullback after recent run-ups. HAL, BEL, Mazagon Dock (specific data unavailable) likely corrected on profit-booking.
  • Manufacturing (-1.43%): broad-based weakness as PMI optimism meets margin pressure.
  • PSE (-1.35%): state-owned enterprises under pressure alongside PSU banks.
  • Commodities (-1.07%): mild underperformance as metal and energy plays cooled.

4. Beyond the Nifty 50 — Stories From the Broader Market

Monday’s real action lived in the mid- and small-cap trenches:

  • MapMyIndia (₹1,056, +10.41%): the navigation software play exploded on 15.01x average volume — the highest vol spike in the entire market. RSI 75.16 (overbought), above 50-DMA. Strong uptrend intact. No news catalyst provided, but this looks like a breakout on institutional buying or earnings surprise.

  • Affle India (₹1,642, +9.01%): digital marketing platform rallied sharply. Volume spike not quantified, but price action suggests a catalyst. Peer to MapMyIndia in the Software Products / IT Enabled Services space.

  • Vodafone Idea (₹12.19, +8.45%): the telecom stock that refuses to die. RSI 93.11 — severely overbought, strong uptrend, volume 3.61x average. This is speculative frenzy territory. Traders chasing momentum; investors should tread carefully at these RSI extremes.

  • KIMS Hospitals (₹777, +8.28%): healthcare provider surged on 5.51x volume, RSI 74.69 (overbought), above 50-DMA. Hospital chains are benefiting from capacity expansion post-pandemic and rising medical tourism.

  • Tata Consumer (₹1,271, +8.05%): already covered, but worth repeating — this is a defensive stock behaving like a mid-cap growth play. Volume 7.86x, fresh 52-week high.

  • HFCL (₹149.41, +5.85%): telecom infrastructure play. RSI 88.16 (overbought), strong uptrend, volume 1.45x. India’s 5G rollout and fiber network expansion underpin this move.

  • JBM Auto (₹684, +5.25%): auto components supplier rallied on 8.46x volume, RSI 69.64 (neutral but elevated), above 50-DMA. Possibly an EV contract win or Q4 beat.

  • Adani Green (₹1,391, +2.60%): renewable energy bellwether hit a 52-week high despite energy sector weakness (-1.84%). Flight to quality within clean energy.

The pain trades:

  • Urban Company (₹126.10, -9.72%): the on-demand services platform cratered on 3.72x volume, RSI 40.29. Q4 results (per headlines) showed widened losses. Growth-at-any-cost model under scrutiny.

  • ABB India (₹6,348, -9.48%): heavy electrical equipment giant plunged on 4.54x volume, RSI 27.67 (oversold), below 50-DMA. Q4 results disappointing, or margin pressure from input costs.

  • Kalyan Jewellers (₹385.90, -9.10%): strong downtrend, RSI 33.98, volume 5.15x. Titan (-6.85%, RSI 33.11, vol 4.28x) also bled. Jewellery retailers hit by gold price volatility and demand softness.

  • Blue Dart (₹5,268, -7.29%): logistics play in strong downtrend, RSI 39.4, volume 5.36x. Post-pandemic normalization hurting high-valuation logistics names.

  • Swiggy (₹263.95, -5.90%): food delivery platform fell on 2.62x volume, strong downtrend, RSI 36.27. Like Urban Company, growth-to-profitability transition scrutinized.

  • Siemens (₹3,589, -6.11%): fellow electrical equipment peer to ABB, also under pressure (strong uptrend but RSI 41.64, vol 1.7x). Sector-wide margin squeeze.

  • Escorts (₹2,969, -5.65%): tractor maker now oversold (RSI 26.3), strong downtrend, volume 2.52x. Rural demand concerns.

5. The Technical Picture

Oversold names (RSI < 30, potential mean-reversion candidates):

  • SBI (₹974.90): RSI 21.86, below 50-DMA, volume 2.64x. Deeply oversold. If banking sentiment turns, this is the first bounce candidate.
  • Canara Bank (₹130.14): RSI 19.77, below 50-DMA, volume 3.45x. Similar setup to SBI.
  • Axis Bank (₹1,267.90): RSI 25.44, below 50-DMA, volume 1.05x. Contrarian play if private banks stabilize.
  • Escorts (₹2,968.70): RSI 26.3, strong downtrend. Tractor demand bottom-fishing territory.
  • ABB India (₹6,348): RSI 27.67, below 50-DMA. Value trap or earnings reset? Wait for price stability.

Overbought names (RSI > 70, caution zone):

  • Vodafone Idea (₹12.19): RSI 93.11. This is parabolic. Avoid chasing.
  • HFCL (₹149.41): RSI 88.16. Strong uptrend, but extended short-term.
  • BSE (₹3,918.10): RSI 80.74. Exchange platform benefiting from derivatives boom (per headlines), but technically stretched.
  • MCX (₹3,187): RSI 78.04, volume 2.26x. Similar story to BSE.
  • Torrent Pharma (₹4,518): RSI 76.85, strong uptrend, volume 1.78x. Fresh 52w high, but RSI warns of near-term exhaustion.

Volume spikes (something’s happening):

  • MapMyIndia: 15.01x volume — biggest spike in the market. Breakout confirmed.
  • Niva Bupa (₹83.70, +2.96%): 14.92x volume, RSI 69.73. General insurance play — possibly stake sale or institutional buying.
  • JBM Auto: 8.46x volume. Component play on fire.
  • Tata Consumer: 7.86x volume. Defensive rotation with momentum.
  • KIMS Hospitals: 5.51x volume. Healthcare sector strength.

No GOLDEN_CROSS or DEATH_CROSS signals explicitly flagged in today’s data.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
MapMyIndia BUY Above 50-DMA, RSI 75 (overbought but trending), volume 15x avg — breakout confirmation
Tata Consumer HOLD Fresh 52w high, RSI 74, vol 7.86x — strong but extended, wait for pullback
KIMS Hospitals BUY Above 50-DMA, RSI 74.69, vol 5.51x — healthcare momentum intact
Adani Green HOLD 52w high but sector weak (-1.84%), no volume data — cautious optimism
JBM Auto BUY Above 50-DMA, RSI 69.64, vol 8.46x — component play on expansion
SBI HOLD RSI 21.86 (oversold), below 50-DMA, vol 2.64x — wait for trend reversal signal
Axis Bank HOLD RSI 25.44 (oversold), below 50-DMA — mean reversion play, but trend still down
Vodafone Idea SELL RSI 93.11 (extreme overbought), vol 3.61x — parabolic move unsustainable
ABB India HOLD RSI 27.67 (oversold), below 50-DMA, vol 4.54x — wait for earnings clarity
Escorts HOLD RSI 26.3 (oversold), strong downtrend — too early to catch the knife
Blue Dart SELL Strong downtrend, RSI 39.4, vol 5.36x — logistics sector under pressure
Swiggy SELL Strong downtrend, RSI 36.27, vol 2.62x — growth-to-profit transition rocky

7. Tomorrow’s Setup — Global Cues & Calendar

Global tape is mixed but stable:

  • US close: Dow -0.12%, S&P 500 +0.01%, Nasdaq -0.10%. Flat is the new up in volatile times.
  • Asian close: Nikkei -0.47%, Hang Seng +0.05%, ASX -0.49%. No panic, but no euphoria either.
  • GIFT Nifty: mirrors Monday’s close at 23,815.85 (-1.49%). Expect a flat to mildly negative open Tuesday.
  • Currency: USD/INR at ₹95.30 (+1.11%). Weak rupee continues to weigh on importers, benefit exporters. Watch for RBI intervention signals.
  • Crude oil: data not provided, but news references stable prices despite Middle East tensions. If Brent stays below $85, energy sector pressure may ease.
  • Gold: data not provided, but typically rises during geopolitical stress — could support metal stocks if it rallies.

Key technical levels for Tuesday:

  • Nifty 50: Support at 23,799 (Monday’s low), resistance at 23,997 (Monday’s high). Break below 23,750 opens 23,500. Break above 24,000 signals short-covering.
  • Bank Nifty: Support at 54,360 (Monday’s low), resistance at 55,002. Needs to reclaim 55,000 to stabilize sentiment.
  • India VIX at 18.55: still elevated. If it spikes above 20, expect more downside volatility.

What to watch Tuesday:

  • FII flow data (if released).
  • Any fresh Middle East developments overnight.
  • Q4 earnings trickle: BSE reported Q4 profit jump +61% y-o-y (per headlines) — watch if derivatives momentum sustains.
  • Rupee trajectory — sustained weakness past ₹95.50 could trigger risk-off selling in rate-sensitive sectors.

8. The Honest Take

For long-term investors: Monday was noise. If you own Sun Pharma, Tata Consumer, Adani Green, or quality pharma — congratulations, you just set fresh 52-week highs. If you own SBI or Axis Bank, you’re nursing paper cuts. The question is: do you believe India’s banking sector is structurally broken, or cyclically correcting? History says the latter. Oversold levels (RSI sub-25) on PSU banks have marked buying opportunities 7 out of 10 times over the past decade. But don’t catch falling knives — wait for price stabilization and trend reversal confirmation. Use the Raamdeo Agrawal framing from headlines: “India is the Ferrari among markets.” That’s not hype. It’s demographics + capex cycle + services exports. Volatility is the price you pay to ride the Ferrari. Buckle up.

For active traders: Monday was a stock-picker’s market. Broad indices down 1.5%, yet MapMyIndia +10%, Tata Consumer +8%, Vodafone Idea +8%. The divergence screams opportunity — but only if you have the tools to spot volume spikes and RSI extremes early. The oversold PSU banks (SBI, Canara) are on the radar for mean-reversion trades, but wait for at least one green candle above the 5-day EMA before entry. On the short side, anything overbought (RSI > 85) with weakening volume is a fade candidate — but Vodafone Idea’s 93 RSI might still squeeze higher before the crash. Risk management is everything when breadth is 1:3.3 against you.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks


“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.

Uncategorized

Unified Stocks — Friday, May 08, 2026

Unified Stocks — Friday, May 08, 2026

Market chart
Market chart
Market chart

1. The Opening Scene

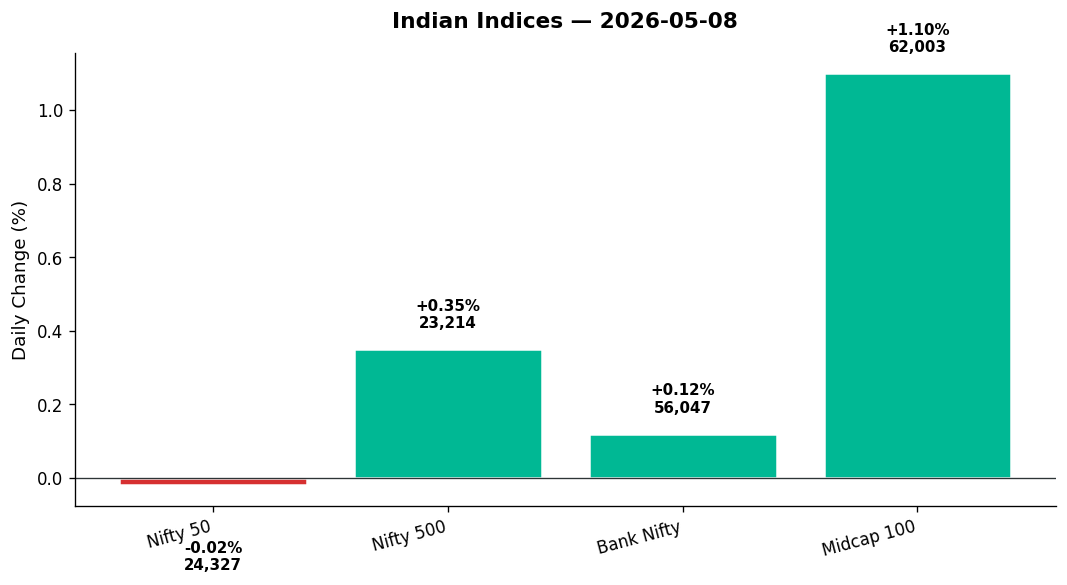
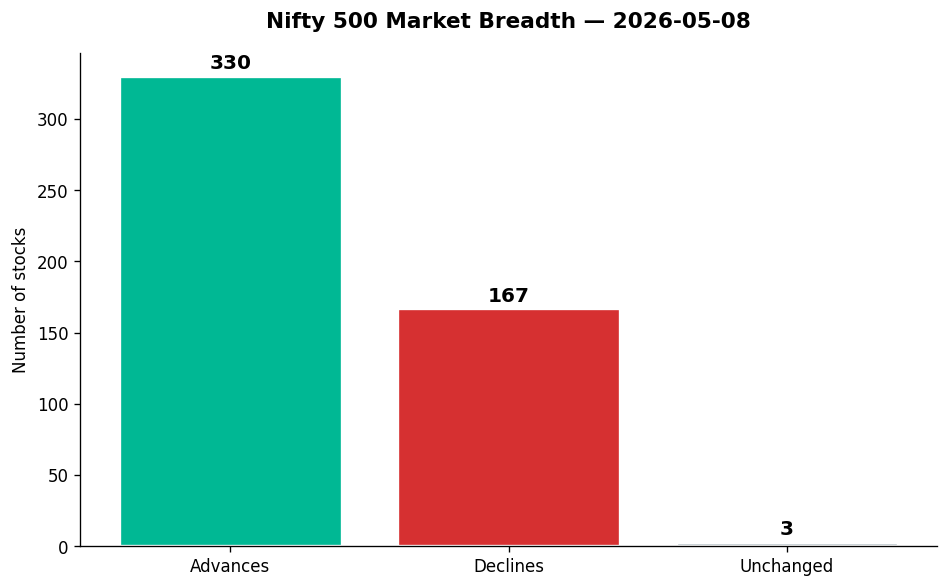
The bell rang on a Friday that seemed to spin on a pinhead. The Nifty 50 closed virtually flat — down 4.30 points, or 0.02%, at 24,326.65 — a day so indecisive that the index high and low stretched nearly 200 points apart before settling at the midpoint, exhausted. Yet beneath that shrug of the headline number, a different market was humming. The Nifty 500 rose 0.35%. The Midcap 100 jumped 1.10%. And most tellingly, 330 stocks advanced against just 167 declines — a 2-to-1 breadth ratio that screamed one thing: this was a stock-picker’s Friday, not a passive index-hugger’s paradise.

You could sense it in the volume. Craftsman Auto Components exploded 12.24% on 15x its usual volume, touching fresh 52-week highs. Godrej Industries — the diversified conglomerate, not the FMCG sibling — rocketed 20%, its biggest single-day gain in years. Meanwhile, IT bellwethers like Infosys and HCL Tech languished in oversold territory, hitting new lows, victims of a sector rotation that favoured old-economy manufacturing, autos, and defence over software and services. The VIX eased 0.34% to 16.62, suggesting calm on the surface. But the internals told a story of churn — money moving fast, pockets of euphoria bumping against zones of capitulation.

2. The Forces That Drove the Day

Crude’s Rally Splits the Tape

  • Brent crude surged 1.10% to $102.38, WTI up 1.96% to $96.94. Energy stocks responded in kind: the Nifty Energy index rose 0.82%, but the directional impact was mixed. Upstream explorers and refiners felt the pinch on margins, while energy infra and power names rallied.
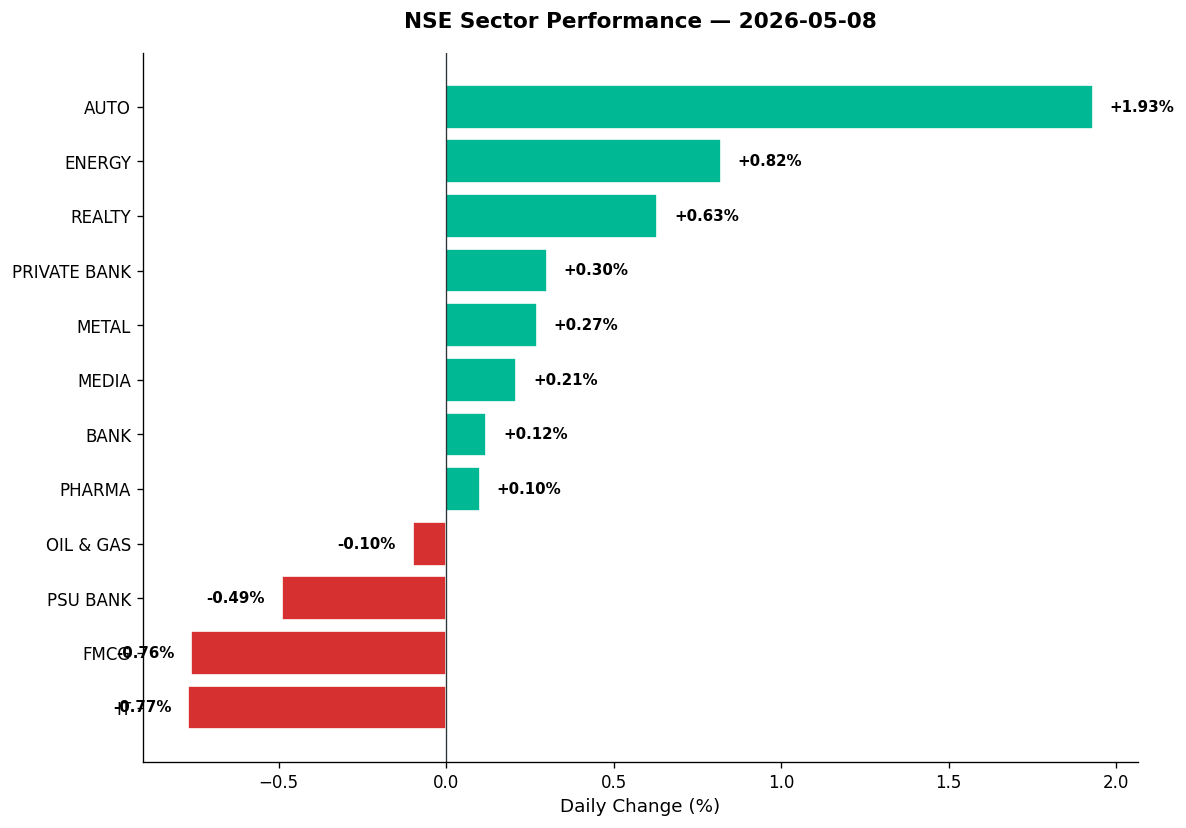
  • USD/INR fell 0.99% to 94.24 — a stronger rupee easing import fears for oil-dependent sectors. Yet this tailwind didn’t prevent Oil & Gas (-0.10%) from slipping into the red.

Global Cues: Risk-Off in the West, Steady Signals from Asia

  • US markets closed lower Thursday night: Dow -0.63%, S&P 500 -0.38%, Nasdaq -0.13%. FTSE 100 tumbled 1.55%. Yet Asian sentiment held firm, and GIFT Nifty signalled a modest positive open for Monday.
  • Gold climbed 0.44% to $4,702.60, reflecting safe-haven appetite even as Indian equities ignored the script.

Bajaj Auto’s Record Profit Fuels Auto Euphoria

  • Bajaj Auto posted its highest-ever quarterly net profit of ₹2,746 crore, driven by export strength and domestic volume surge. This headline rippled across the auto sector, lifting Nifty Auto +1.93% to 27,339.95 — the day’s best-performing major sector.
  • Yet buried in the post-earnings commentary was a warning: executive director Rakesh Sharma flagged that more than a third of GST-related pricing gains had been eroded by inflationary pressures. The market chose to celebrate today, but the caution note lingers for Q2.

Breadth Strength = Midcap Muscle

  • The 2:1 advance-to-decline ratio in the Nifty 500 reflected money rotating into midcaps, small-cap industrials, and thematic plays — Defence (+3.04%), Manufacturing (+0.85%), PSE (+0.45%).
  • This wasn’t a Nifty 50 day. This was a day for the names you don’t see on CNBC tickers every hour.

3. A Walk Through the Sectors

Leaders: Auto Leads the Charge

  • Auto (+1.93%): Bajaj Auto’s record profit set the tone. But the real fireworks came from auto ancillaries:
  • Craftsman (+12.24%) hit a fresh 52-week high on 15x volume, RSI 62.78 — strong uptrend, not yet overbought.
  • Endurance (+8.32%), Bharat Forge (+6.57% on 4.85x volume) — both riding the manufacturing and export momentum.
  • Even within the Nifty 50, sentiment was constructive. The sector’s strength came from depth, not just the headline names.

  • Energy (+0.82%): Crude’s rise lifted sentiment, though results were mixed. Upstream explorers faced margin pressure; power and energy infra names found support. The thematic Nifty Energy index echoed the sector’s 0.82% gain.

  • Realty (+0.63%): A modest bounce after recent volatility. Brigade tumbled 4.83% (RSI 72.85, overbought correction), but broader names in the space held steady. Momentum here is fragile — volume tells the tale.

Laggards: IT’s Painful Descent Continues

  • IT (-0.77%): The sector that powered India’s equity bull market for two decades is now its weakest link.
  • Infosys closed at ₹1,165.90, RSI 21.19 (oversold) — a strong downtrend with no technical reprieve in sight.
  • HCL Tech hit a new 52-week low at ₹1,182.40 (-0.56%), closing with barely any bounce despite the support break.
  • KPIT Tech (-3.29%) fell on 3.53x volume — a name often cited as a proxy for EV and auto software now caught in the broader tech selloff.
  • Tata Elxsi, Persistent Systems, TCS — all flat to negative. No rotation back into IT yet. The pain is real.

  • FMCG (-0.76%): Consumer staples struggled.

  • Godrej Consumer Products (not to be confused with Godrej Industries) crashed 5.26% on 3.82x volume, entering a strong downtrend (RSI 45.39). Earnings disappointment or sector-wide demand concerns? The chart says: get out first, ask questions later.
  • Broader FMCG names like Britannia, Dabur, and Marico saw tepid action. Defensive sectors aren’t working in this rotation.

  • PSU Bank (-0.49%): A modest decline, but notable given Bank Nifty’s +0.12% gain. Private banks outperformed; PSU banks lagged. SBI, Bank of Baroda, and PNB all saw profit-taking after recent rallies.

Mixed Middle: Banks, Pharma, Metal, Media

  • Private Bank (+0.30%): HDFC Bank (-0.13%, RSI 48.49), ICICI Bank (-0.04%) — both treading water in strong downtrends, massive turnover but no conviction. Kotak Bank reportedly slid 4% in intraday action per news flow, though it doesn’t appear in the Nifty 500 top movers — a sign of isolated weakness.

  • Pharma (+0.10%): A tale of extremes.

  • PPL Pharma surged 11.14% on 5.87x volume (RSI 71.72, overbought but justified by the breakout).
  • Wockpharma fell 4.94% despite an RSI of 81.94 (overbought) — a classic case of profit-taking after a parabolic run.
  • Lupin, Aurobindo, Sun Pharma — all quiet. Pharma is stock-specific, not sector-wide momentum.

  • Metal (+0.27%): A flat sector with one critical outlier — Vedanta.

  • Media (+0.21%): Barely moved. Negligible volume, negligible conviction.

4. Beyond the Nifty 50 — Stories From the Broader Market

This is where Friday’s real story unfolded. The Nifty 50 was a sideshow; the midcaps, small-caps, and thematic plays stole the spotlight.

Godrej Industries (+20.00%): The Conglomerate Awakens

  • ₹1,226.85, volume 6.67x average, RSI 73.95 — a blowout session. The diversified play — spanning chemicals, real estate, agri — saw something trigger institutional accumulation. News flow light, but the technicals scream: above 50-DMA, golden cross possible if momentum sustains.

Defence Stocks: The 3.04% Sector Surge

  • Nifty India Defence +3.04% — another day, another rally in HAL, BEL, Mazagon Dock, Bharat Electronics.
  • BHEL (+5.32%) hit a fresh 52-week high at ₹406.50, RSI 86.71 (overbought), 1.38x volume. Strong uptrend, but nearing exhaustion levels.
  • GVT&D (+5.02%), a heavy electrical equipment play, also spiked (RSI 78.47, overbought). The defence-infra-manufacturing complex remains the market’s favourite narrative. Until it isn’t.

Telecom & Semis: Breakouts in Pockets

  • Tejas Networks (+14.90%) exploded on ₹48.43 crore turnover — a telecom equipment play riding 5G and optical fibre rollout themes. No RSI data, but the price action speaks.
  • HFCL (+3.92%) hit a fresh 52-week high at ₹147, RSI 91.14 — the most overbought stock in the dataset. Strong uptrend, 1.73x volume. Telecom infra, defence electronics, optical fibre. It’s all working. But RSI >90 is a flashing yellow light: take profits or watch tight stops.

Vedanta (-3.41%): The Oversold Outcry

  • ₹305.60, RSI 14.97 (deeply oversold), 1.94x volume, below 50-DMA — this is a stock in distress. The demerger news (four entities to be carved out) has created uncertainty. Some see value; the market sees risk. Until the demerger listings clarify, Vedanta remains a knife traders are trying to catch.

Paytm (+7.73%): The Fintech Bounce

  • ₹1,196.40, 4.11x volume, RSI 32.65 (neutral but recovering from oversold) — Paytm’s revenue growth guidance for FY27 (per news flow: “faster growth than FY26”) sparked a relief rally. Above 50-DMA, but still in a long-term downtrend. A trade, not an investment — yet.

BSE & MCX: The Exchange Duo Hits New Highs

  • BSE (+3.35%) at ₹3,981, fresh 52-week high. MCX (+2.75%) at ₹3,055, also a new high. Both exchanges benefiting from retail trading boom, F&O volumes, and institutional confidence. Clean technicals, rising volume, no overheated RSIs. These are rare pockets of quality momentum.

Polycab (+7.30%): The Cable King’s March

  • ₹9,030, fresh 52-week high, RSI 59.96 (neutral), 3.53x volume — strong uptrend. Manufacturing, electrification, infra spend. All tailwinds. This is what “buy the dips” looks like when it works.

Meesho (+0.98%): The E-commerce Dark Horse

  • ₹198.20, RSI 67.44, 3.06x volume — the e-commerce play quietly climbing. Not Nykaa volatility, not Zomato drama. Just steady accumulation. Most active by value today, yet few headlines. That’s often when the smart money moves.

5. The Technical Picture

Oversold Zone: Opportunity or Trap?

  • Vedanta (RSI 14.97), Infosys (RSI 21.19) — both below 30, both in confirmed downtrends. Oversold doesn’t mean buy; it means: “watch for stabilisation first, then act.”

Overbought Zone: Profit-Taking Alerts

  • HFCL (RSI 91.14) — the highest in the dataset. Parabolic. Be cautious.
  • Jain Rec (RSI 83.03), Wockpharma (RSI 81.94), Godrej Industries (RSI 73.95), PPL Pharma (RSI 71.72), Brigade (RSI 72.85) — all above 70. Some justified (breakouts), some not (reversals incoming).

Volume Spikes: Where the Action Is

  • Craftsman (14.99x), ABLBL (11.79x), CarTrade (7.62x), Godrej Industries (6.67x), Aegis Vopak (6.52x), PPL Pharma (5.87x), Nuvoco (5.60x), Bharat Forge (4.85x) — these aren’t noise. These are institutional moves, breakout confirmations, or capitulation sells. Each warrants a deep dive.

Golden Cross Watch

  • No explicit golden crosses (50-DMA crossing above 200-DMA) flagged today, but several names (Craftsman, Bharat Forge, Polycab) are in strong uptrends with momentum intact. Watch next week.

Death Cross Reality

  • Infosys, HCL Tech, HDFC Bank — all in strong downtrends, 50-DMA well below 200-DMA. These are confirmed long-term underperformers. Wait for trend reversal signals (RSI divergence, volume capitulation) before re-entry.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Craftsman Auto BUY Strong Uptrend, above 50-DMA, RSI 62.78 (neutral), vol 14.99x avg, fresh 52w high
Bharat Forge BUY Strong Uptrend, RSI 52.72 (neutral), vol 4.85x avg, above key DMAs
Polycab BUY Strong Uptrend, fresh 52w high, RSI 59.96 (neutral), vol 3.53x avg
BSE BUY Fresh 52w high, strong volume, RSI not overbought, clean uptrend
Paytm HOLD Above 50-DMA, recovering from oversold (RSI 32.65), vol 4.11x — wait for RSI >40 to confirm
Godrej Industries HOLD Massive breakout (+20%), but RSI 73.95 overbought, vol 6.67x — profit-taking likely near-term
HFCL SELL RSI 91.14 (extreme overbought), parabolic move unsustainable despite strong uptrend
Vedanta SELL RSI 14.97 (oversold), below 50-DMA, strong downtrend, demerger uncertainty — avoid until clarity
Infosys SELL RSI 21.19 (oversold), strong downtrend, death cross confirmed, no reversal signals yet
HCL Tech SELL Fresh 52w low, strong downtrend, RSI not provided but price action confirms weakness
Wockpharma SELL Down 4.94% despite RSI 81.94 overbought — profit-taking after parabolic run, avoid
Godrej Consumer SELL Down 5.26%, strong downtrend (RSI 45.39), vol 3.82x — distribution phase, exit

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape: Risk-Off Overnight, But Asia Holds

  • US equities closed lower Thursday: Dow -0.63%, S&P 500 -0.38%, Nasdaq -0.13%. Tech weakness persists. FTSE 100 -1.55% adds to the cautious tone.
  • GIFT Nifty signals modest positive open Monday — the weekend gap will depend on headlines, but the setup is neutral-to-mildly-bullish.

Commodities: Crude’s Rally, Gold’s Creep

  • Brent crude at $102.38 (+1.10%), WTI at $96.94 (+1.96%) — energy complex on edge. Watch for OPEC+ commentary over the weekend. A break above $105 Brent will pressure import-heavy sectors.
  • Gold at $4,702.60 (+0.44%) — creeping higher. Safe-haven flows suggest macro unease despite equity resilience.

Currency: Rupee Strength a Short-Term Relief

  • USD/INR at 94.24 (-0.99%) — a stronger rupee eases FII concerns and import costs, but sustainability depends on Fed policy signals and domestic data flow next week.

Key Technical Levels for Monday

  • Nifty 50: Support at 24,284 (today’s low), resistance at 24,482 (today’s high). A break above 24,500 opens 24,650; below 24,250 invites 24,000 retest.
  • Bank Nifty: Support at 55,783, resistance at 56,334. Range-bound; watch for breakout above 56,500 or breakdown below 55,500.
  • Nifty 500: Strong close at 23,214 (+0.35%). Midcap momentum intact; watch for follow-through above 23,300.

8. The Honest Take

For long-term investors: This market is rewarding selectivity and punishing complacency. The Nifty 50’s flatness masks a violent rotation beneath the surface — away from IT and large-cap defensives, toward manufacturing, autos, defence, and energy infrastructure. If your portfolio is overweight TCS, Infosys, and HDFC Bank, you’re feeling pain. If you own Craftsman, Bharat Forge, BSE, and Polycab, you’re smiling. The message: diversify beyond the usual suspects. The India growth story is broadening, not narrowing. But breadth-driven rallies are fragile — they work until they don’t. Stay disciplined. Rebalance winners. Don’t chase RSI >80 names.

For active traders: Friday was a gift — 2:1 breadth, volume spikes, breakouts on confirmation. But it was also a minefield. Oversold names like Vedanta and Infosys look tempting, but downtrends don’t reverse on hope. Wait for RSI divergence, volume capitulation, or 50-DMA reclaims. Overbought names like HFCL (RSI 91!) are screaming “take profits.” The sweet spot today was names like Craftsman, Bharat Forge, and BSE — strong uptrends, neutral RSIs, volume confirmation. That’s the template: buy momentum with room to run, not parabolas begging for gravity. Next week, watch crude, watch global sentiment, and watch the midcap 100. If it stays above 62,000, the broadening rally continues. If it cracks, rotate to cash and quality large-caps.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.

Scroll to Top