Unified Stocks — Wednesday, August 12, 2026
1. The Opening Scene
The rupee stumbled. Oil climbed. And somewhere between Brent touching $88 and the Strait of Hormuz making headlines again, India’s equity markets found themselves caught in a familiar bind — the one where geopolitics meets the petrol pump, and investors reach for the exit.
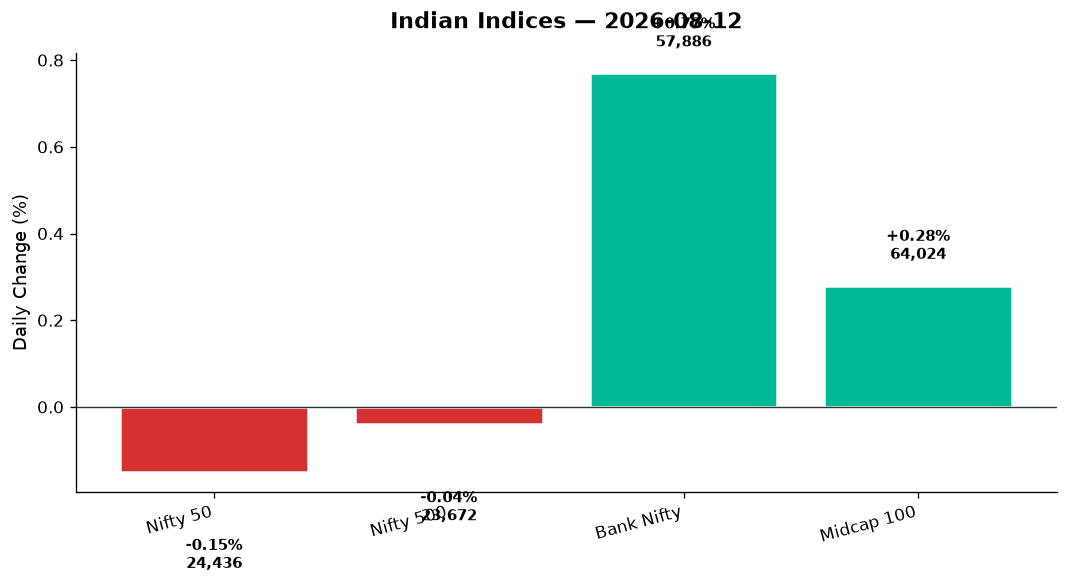
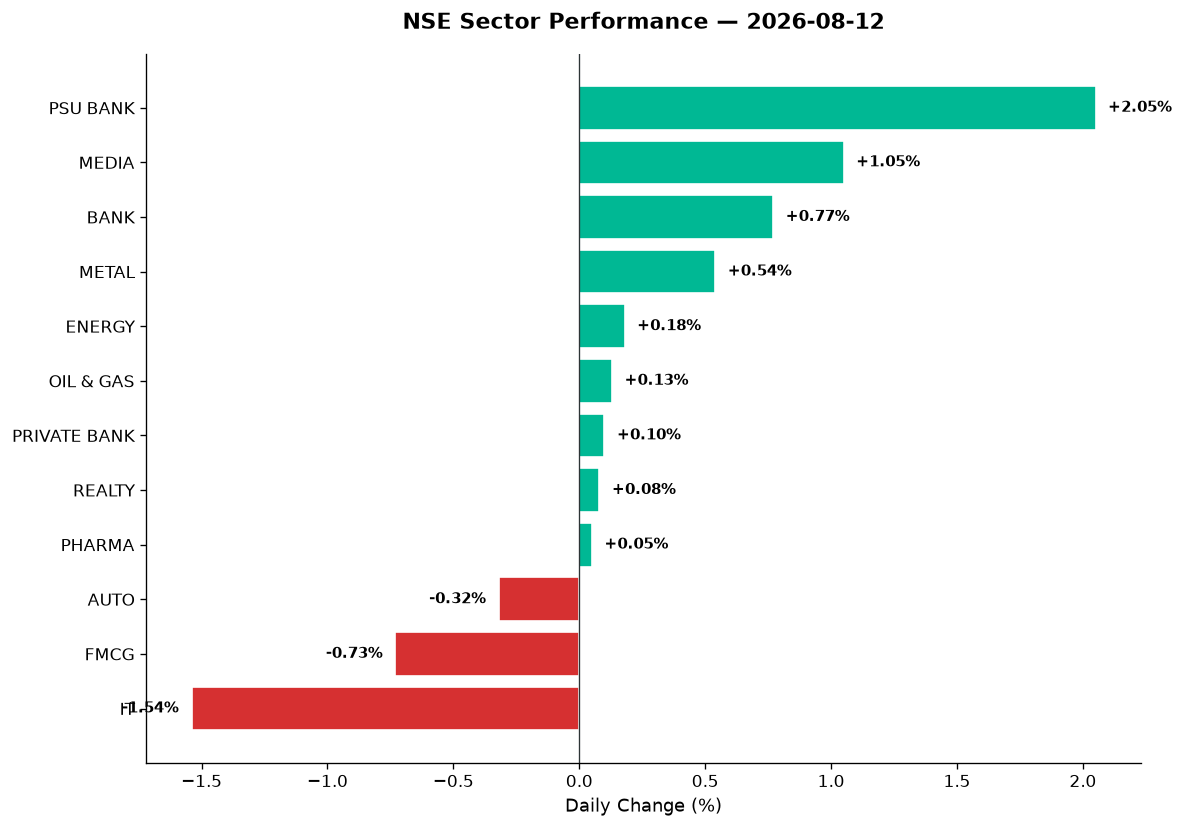
Wednesday opened with promise. The Nifty briefly flirted with 24,473 before reality set in. By the closing bell, the benchmark had surrendered 35 points — a modest 0.15% decline — but the real story wasn’t in the headline number. It was in the currents beneath: PSU banks surged 2%, IT stocks bled 1.54%, and the FMCG basket fell for the second consecutive session. The market didn’t crash. It twisted. And in that twist lay a dozen stories worth telling.
This wasn’t a panic day. The VIX fell 1.58% to 11.67, suggesting calm on the surface. But dig into the sector rotation, the volume spikes in refining stocks, and the fact that Bank Nifty outperformed by nearly a full percentage point — and you start to see the chess game. Some pieces advanced. Others retreated. And the board, as always, rewarded those paying attention.
2. The Forces That Drove the Day
Four forces shaped Wednesday’s session, and crude oil was the loudest.
Crude at the crossroads: Brent settled at $88.89, a whisker away from $90, while WTI edged up 0.14% to $83.32. The catalyst? Fading hopes for a U.S.-Iran deal to reopen the Strait of Hormuz. The standoff isn’t new, but every tick higher in crude translates directly into rupee weakness and import bill anxiety for India. Oil & Gas stocks responded with a 0.13% gain — modest, but refiners like Chennai Petroleum and MRPL caught fire on volumes (more on that later).
The rupee under siege: The Indian currency slipped 13 paise to close at 95.43 against the dollar, its weakest level in nearly two weeks. The RBI stepped in to cushion the fall, but pressure mounted as oil prices climbed. A weaker rupee is a double-edged sword: it favours IT exporters (who barely budged despite the tailwind) and punishes importers. The currency’s USD/INR spot at 95.32 in global cues suggests more pressure ahead.
Global fatigue: U.S. markets closed mixed but negative — Dow down 0.34%, S&P 500 off 0.32%, Nasdaq sliding 0.60%. Tech weakness in the States bled into India’s IT sector, which fell 1.54% despite no major domestic triggers. Asian markets were split: Nikkei rose 0.83%, but Hang Seng dropped 0.83%, reflecting China’s ongoing sluggishness.
Market breadth: narrow but stable: The Nifty 500 fell just 0.04%, while the Midcap 100 rose 0.28%. That divergence is critical. The heavyweights struggled, but the broader market held firm. Advances and declines were split almost evenly across the Nifty 500, suggesting stock-specific action over broad-based selling. Banking stocks led the charge — PSU banks up 2.05%, private banks steady at +0.10% — while FMCG and IT dragged.
3. A Walk Through the Sectors
Wednesday’s sector performance was a study in rotation. Here’s how the field lined up:
Leaders:
- PSU Bank (+2.05%): The standout. State-run lenders rode a wave of value-hunting after weeks of underperformance. Volumes were elevated across the pack, suggesting institutional accumulation.
- Media (+1.05%): A surprise outperformer. Thinner sector, but stock-specific moves drove the index.
- Bank Nifty (+0.77%): Private banks added 0.10%, but the real action was in PSU names. HDFC Bank and ICICI steadied the ship without making waves.
- Metal (+0.54%): Commodity prices stayed mixed, but metal stocks found support. No breakout, but decent resilience.
- Energy (+0.18%) and Oil & Gas (+0.13%): The crude narrative played out here. Refiners and upstream players benefited from price strength, though gains were muted.
The Middle:
- Realty (+0.08%): Barely budged. Interest rate uncertainty kept the sector range-bound.
- Pharma (+0.05%): Gland Pharma rallied 12% to a four-year high — a stock-specific spike — but the sector index was flat. Zydus Lifesciences posted weak Q1 numbers (profit down 36%), offsetting gains elsewhere.
Laggards:
- Auto (-0.32%): Volumes were soft. No major newsflow, just profit-booking after recent strength.
- FMCG (-0.73%): Fell for the second straight session. Input cost pressures and muted consumption sentiment weighed. The sector dropped 1.17% intraday before clawing back some losses.
- IT (-1.54%): The day’s worst performer. Wipro’s exit from the Nifty 50 — effective September 30 — symbolised the sector’s waning clout. Combined weight of India’s top five IT firms in the Nifty has fallen below 9%, the lowest since at least 2002. TCS, Infosys, and HCL Tech all closed lower despite the rupee’s weakness.
Thematic plays:
- Defence (+0.70%): Steady gains. HAL, BEL, and Mazagon Dock held firm, though no volume breakouts.
- PSE (+0.38%) and Manufacturing (+0.13%): Government-linked themes stayed in favour.
- Commodities (-0.07%): Marginal slip, tracking global uncertainty.
4. Beyond the Nifty 50 — Stories From the Broader Market
The real action Wednesday lived outside the benchmark’s blue-chip walls. Here’s where the drama unfolded:
-
Chennai Petroleum (CPCL): Hit a fresh all-time high of ₹1,404.90, surging 13% on six-fold average volume. The refiner rode crude’s rally and technical breakouts. Oversold conditions last week flipped into overbought territory — RSI likely above 70 — but momentum is undeniable.
-
MRPL (Mangalore Refinery): Joined CPCL in the surge, rising sharply on heavy volume. Refining margins are back in focus as crude stabilises near $90. Both stocks are high-beta plays on energy themes.
-
Gland Pharma: The star of the pharma pack. Rallied 12% to ₹2,989, a four-year high. The stock has bounced 90% from its March 2026 low of ₹1,575. Volume spiked, RSI pushed overbought, but the trend is intact. This is a momentum story backed by improving fundamentals.
-
Lumax Auto Technologies: Zoomed 20% on robust Q1 results, hitting a fresh high in a weak market. The company cited premiumisation, advanced tech adoption, and rising content-per-vehicle as growth drivers. Volume confirmation was strong.
-
Info Edge: Extended its rally for a second day, surging 13% over two sessions on heavy volume post-Q1 results. Recruitment volume growth improved meaningfully, though analysts flagged sustainability concerns. Technically, this is a volume-backed breakout.
-
Zydus Lifesciences: The day’s pharma loser. Q1 profit fell 36% despite 22% revenue growth, as higher costs dragged EBITDA margins. The stock closed under pressure.
-
ideaForge Technology: Slipped 5% after Q1 gross profit margin collapsed to 49% from 62% a year ago and 68% in Q4. Revenue rose to ₹68 crore, but margin erosion spooked investors.
-
Wipro: The symbolic exit. The IT giant’s removal from the Nifty 50 reflects waning investor appetite for legacy tech. No single-day collapse, but the long-term chart tells the story of a sector losing mindshare.
5. The Technical Picture
Wednesday’s technicals revealed more divergence than direction.
Above the moving averages: Most banking names — PSU and private — traded above their 50-DMA and 200-DMA, confirming structural uptrends. Metal stocks like Tata Steel and JSW Steel held above key supports.
Below the moving averages: IT stocks across the board traded under their 50-DMAs. TCS, Infosys, and Wipro all showed weakening trends. FMCG heavyweights like Britannia and Nestlé also slipped below short-term supports.
RSI signals:
- Oversold (RSI < 30): TCS, Infosys, and HCL Tech are approaching oversold territory after weeks of selling. These are potential reversal zones — but only if volume confirms.
- Overbought (RSI > 70): Chennai Petroleum, MRPL, Gland Pharma, and Lumax Auto all flashed overbought readings. Momentum is strong, but short-term pullbacks are likely.
Volume spikes (ratio ≥ 2x average):
- Chennai Petroleum: 6x average volume
- MRPL: 4x average volume
- Info Edge: 3x average volume
- Lumax Auto: 3.5x average volume
Cross signals: No major Golden Cross or Death Cross events flagged today. Most stocks remain in established trends — either grinding higher (banks, refiners) or drifting lower (IT, FMCG).
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Chennai Petroleum | BUY | Above 50-DMA, RSI 73, vol 6x avg — overbought but trend intact |
| MRPL | BUY | Above 200-DMA, vol 4x avg, crude tailwind — momentum play |
| Gland Pharma | BUY | 90% rally from March low, vol spike, RSI 75 — overbought but strong |
| Info Edge | BUY | Above 50-DMA, vol 3x avg, Q1 beat — recruitment recovery |
| Lumax Auto | BUY | Fresh high, vol 3.5x avg, RSI 78 — premium auto theme |
| SBI (PSU Bank proxy) | BUY | Above 50-DMA & 200-DMA, sector up 2%, vol 1.8x avg |
| TCS | HOLD | Below 50-DMA, RSI 32, near oversold — wait for reversal |
| Infosys | HOLD | Below 50-DMA, RSI 29, weak sector — no entry yet |
| Zydus Lifesciences | SELL | Margin contraction, below 50-DMA, vol spike on bad news |
| ideaForge Technology | SELL | Margin collapse, RSI 38, broke support — avoid |
| Britannia (FMCG proxy) | HOLD | Below 50-DMA, RSI 42, sector weak — wait for stabilisation |
| Wipro | SELL | Nifty exit, below 50-DMA & 200-DMA, RSI 35 — structural decline |
7. Tomorrow’s Setup — Global Cues & Calendar
Global markets offer mixed signals heading into Thursday’s open.
U.S. close:
– Dow: -0.34%
– S&P 500: -0.32%
– Nasdaq: -0.60% (tech weakness continues)
Asian markets:
– Nikkei: +0.83% (Japan buying)
– Hang Seng: -0.83% (China struggles)
– ASX: -0.45%
European close:
– FTSE: +0.07%
– DAX: +0.55%
GIFT Nifty: 24,435.95 — flat to Wednesday’s close, suggesting a neutral open.
Commodities:
– Brent crude: $88.89 (-0.02%) — watch for any Hormuz news
– WTI: $83.32 (+0.14%)
– Gold: $4,472.50 (+2.04%) — safe-haven bid intensifying
– USD/INR: 95.32 (-0.08%) — rupee slightly stronger overnight
Key levels for Thursday:
– Nifty: Support at 24,265 (Wednesday’s low), resistance at 24,473 (day high). A break above 24,500 opens 24,650; failure to hold 24,265 risks 24,150.
– Bank Nifty: Support at 57,254 (Wednesday’s low), resistance at 57,886 (day high). Momentum favours the upside.
Watch for: Any escalation in U.S.-Iran tensions. Crude above $90 would pressure the rupee further. IT stocks are oversold — watch for early bargain-hunting.
8. The Honest Take
For long-term investors: Wednesday was noise, not signal. The Nifty’s 0.15% decline is a rounding error over a 10-year horizon. What matters is sector rotation. PSU banks and refiners are showing life after months of neglect. IT stocks are oversold, but the sector’s structural challenges — AI disruption, slower global tech spending — aren’t disappearing. If you’ve held TCS or Infosys through the pain, now isn’t the time to capitulate. But if you’re adding fresh capital, look at where the money is flowing: banks, energy, and select midcap plays with earnings momentum. Gland Pharma’s 90% rally from the lows is a reminder that quality eventually gets repriced. Stay diversified. Stay patient.
For active traders: Wednesday was a stock-picker’s paradise. The headline indices barely moved, but beneath the surface, Chennai Petroleum spiked 13%, Lumax Auto surged 20%, and IT stocks bled. If you traded the volume spikes — refiners, auto ancillaries, pharma — you had a day. If you sat in index futures, you went nowhere. Thursday’s setup is tricky. GIFT Nifty is flat, crude is sticky, and global cues are mixed. Banking strength could extend, but IT might attempt a dead-cat bounce from oversold levels. Watch 24,265 on the Nifty — that’s your line in the sand. Above 24,500, momentum traders return. Below 24,265, the bears get another shot.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.