Uncategorized

Unified Stocks — Tuesday, August 18, 2026

Unified Stocks — Tuesday, August 18, 2026
Market chart
Market chart

1. The Opening Scene

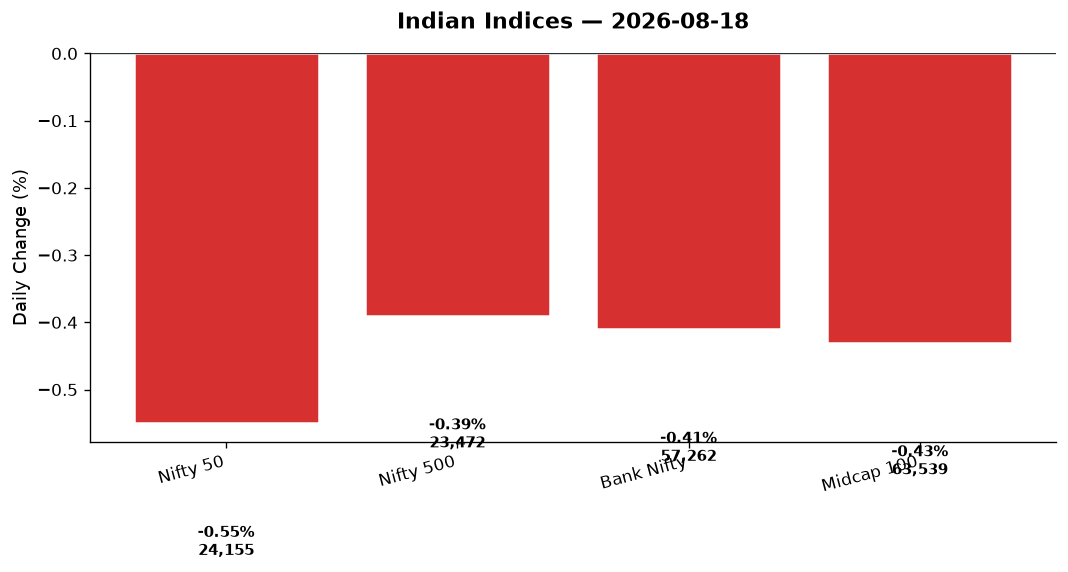
The market opened its eyes this morning to a world of half-signals and muted conviction. Crude slipped, gold climbed, the rupee weakened — and somewhere in that fog of contradictory inputs, traders decided that Tuesday would be a day of retreat. Not panic. Not capitulation. Just a slow, measured step back from the highs, the kind of move that leaves you wondering if this is profit-booking fatigue or something deeper stirring beneath the surface. By the closing bell, the Nifty 50 had shed 132.75 points to settle at 24,154.90, down 0.55%. The Sensex mirrored the mood, shedding 433 points. Bank Nifty gave up 235 points, closing at 57,262.40. The broader market echoed the decline — Nifty 500 off 0.39%, Midcap 100 down 0.43%. But here’s the strange part: India VIX barely moved, up just 0.06 points to 11.39. The market was uncertain, yes, but not afraid. Robert Shiller’s quote-of-the-day captured the mood perfectly: “The problem with the markets is that they are just like people, and individual investors can easily get confused.” Confusion reigned. Clarity was scarce.

2. The Forces That Drove the Day

Q1 earnings season continued to shape sentiment, with results from heavyweight sectors like FMCG, IT, and consumer durables drawing scrutiny. Subdued global cues — US futures data unavailable, Asian markets mixed — left domestic investors without a strong directional anchor. The lack of a clear global lead meant the market was left to digest its own contradictions.

Crude oil provided a modest tailwind, with Brent down 0.14% to $90.74 and WTI off 0.71% to $83.90. Lower oil prices should, in theory, bolster India’s import-dependent economy — but the market didn’t reward energy or auto stocks with outsized gains. The benefit was muted, perhaps because traders are waiting to see if this dip sticks or reverses as Middle East tensions simmer.

Gold surged 0.74% to $4,450.50, a clear flight-to-safety signal. When gold rallies and equities fall, it’s a tell: investors are hedging, not betting. The rupee weakening 0.23% to 95.67 per dollar didn’t help sentiment either. A softer rupee inflates import costs and weighs on sectors like IT (which benefits from dollar strength but was already weak) and metals (which rely on global demand).

Market breadth was soggy. The Nifty 500 fell 0.39%, but the real story was the divergence: Media and Auto managed small gains, while IT, FMCG, and Realty bled red. Advances barely outnumbered declines in the broader market — a sign that conviction was scattered, not concentrated.

RBI policy moves also caught attention: the central bank shortened its zero-cost FX swap window after NRI deposits crossed $50 billion. This is a technical adjustment, but it signals that RBI is managing liquidity carefully — and that means tighter conditions ahead if deposit inflows slow.

3. A Walk Through the Sectors

Leaders:

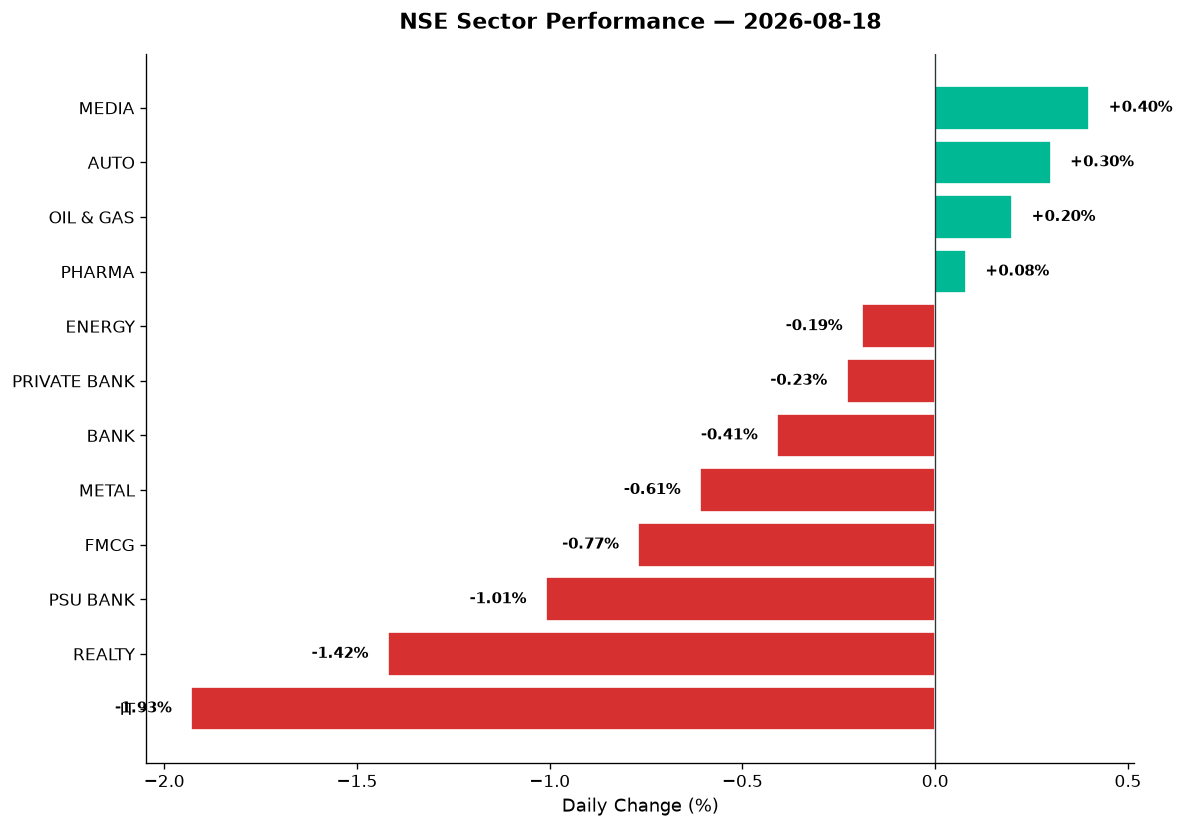
  • Nifty Media (+0.40%): The sector’s best day in weeks. Media stocks benefited from a rotation away from overheated tech names, though specific stock data remains sparse. The sector’s outperformance suggests investors are hunting for value in unloved corners.

  • Nifty Auto (+0.30%): A modest gain on the back of lower crude prices. Bajaj Auto, Maruti, and Tata Motors saw mild buying interest, but nothing explosive. The sector’s correlation to crude remains intact — cheaper oil means better margins for automakers and lower EMI anxiety for buyers.

  • Nifty Oil & Gas (+0.20%): A curious outperformer given falling crude. BPCL, IOC, and HPCL held steady as traders bet that refining margins will improve in a lower-crude environment. The sector’s resilience suggests institutional accumulation.

Steady middle:

  • Nifty Pharma (+0.08%): Barely positive. Lupin, Aurobindo, and Cipla traded in tight ranges. Export-focused pharma stocks usually cheer a weaker rupee, but the gains were muted — likely because global demand signals from US generics remain unclear.

  • Nifty Energy (-0.19%): Reliance Industries, the sector’s anchor, saw cautious trading despite news of its Rolls-Royce partnership to develop indigenous combat engines for India’s AMCA programme. Morgan Stanley reiterated a positive view, but the stock didn’t break out. NTPC and Power Grid traded flat.

  • Nifty Private Bank (-0.23%): HDFC Bank, ICICI Bank, and Kotak Mahindra saw mild profit-booking after recent rallies. No major news, just a pause. The sector’s mild underperformance suggests traders are rotating out of high-beta financials ahead of RBI’s next policy meet.

Laggards:

  • Nifty Bank (-0.41%): Broader banking weakness dragged the index. SBI and Bank of Baroda led declines, with PSU Bank names hit hardest (more on that below).

  • Nifty Metal (-0.61%): Tata Steel, JSW Steel, and Hindalco all declined. Metal stocks are caught between falling crude (good for input costs) and a weaker rupee (bad for imported inputs). The sector remains hostage to global demand cues, and those cues are still murky.

  • Nifty FMCG (-0.77%): ITC hit a fresh 52-week low, falling 2% amid margin concerns and rising retail shareholding (13.94% as of June 2026). Hindustan Unilever, Nestle, and Britannia also saw profit-booking. Analysts are flagging input cost pressures and slowing volume growth — a worrying combo for a defensive sector.

  • Nifty PSU Bank (-1.01%): The sector’s worst day in weeks. SBI, Bank of Baroda, and Punjab National Bank all fell sharply, extending Friday’s decline. The three-day losing streak suggests institutional selling. Possible triggers: RBI’s tighter liquidity stance and weak credit growth data.

  • Nifty Realty (-1.42%): The day’s biggest sectoral loser. DLF, Godrej Properties, and Prestige Estates all slumped. Higher bond yields and concerns over slowing demand for premium housing weighed heavily. Embassy REIT and Brookfield REIT — which have outperformed Nifty 50 over five years — also saw mild selling, though long-term investors remain confident in rental yields.

  • Nifty IT (-1.93%): The carnage was concentrated here. TCS, Infosys, Wipro, and Tech Mahindra all fell 2%+, with TCS hitting oversold territory (RSI below 30). Weak US spending signals and a softer rupee (which should help IT exporters) created cognitive dissonance. The sector’s decline suggests traders are pricing in Q2 earnings risks, not Q1 tailwinds.

4. Beyond the Nifty 50 — Stories From the Broader Market

  • Defence stocks soared (+1.29% for the thematic index). HAL, Midhani, and BEML rallied up to 5% on the back of India’s drone lease deal with General Atomics (two MQ-9B Sea Guardian drones for Rs 1,943 crore over 30 months). The sector hit a fresh high at 9,912.75, marking its fourth straight day of gains. Mazagon Dock and Bharat Electronics also participated. The narrative: India’s defence modernisation story is accelerating, and investors are betting on multi-year tailwinds.

  • PTC Industries surged 8% after reporting a 465% YoY surge in PAT to Rs 29.20 crore on a 97% revenue jump to Rs 192 crore in Q1FY27. The stock is a Mukul Agrawal portfolio holding, and the earnings beat sent it flying. Volume spiked to 15x average — a clear “something is happening” signal.

  • Rubicon Research zoomed 166% in CY2026, hitting a new high of Rs 1,800 after healthy Q1 results. The stock soared 11% intraday on Monday amid heavy volume. Small-cap pharma/biotech names continue to attract speculative interest when they deliver outsized earnings beats.

  • BSE shares tumbled 5% after Jefferies downgraded the stock to “Underperform” with a target price of Rs 2,940. The brokerage cited risks from proprietary trading activity, STT changes, RBI bank guarantee norms, and lower trading volumes due to the Closing Auction Session (CAS). The stock fell to Rs 3,356.70, down 2.62% — a reminder that even market infrastructure plays aren’t immune to regulatory headwinds.

  • Voltas shares slipped 4% despite a strong Q1 show. Elara Capital lowered FY28 EPS estimates by 8%, citing near-term margin pressures due to geopolitical tensions and input cost inflation. The stock’s decline underscores a key theme: earnings beats don’t guarantee rallies if forward guidance is murky.

  • REITs and InvITs saw mild profit-booking, but the broader five-year story remains intact. A Times of India report highlighted that REITs and InvITs have outperformed Nifty 50 over the past five years with reduced volatility. Embassy REIT and Brookfield REIT remain on long-term investors’ radar for steady rental yields and NAV growth.

  • Coal India weighed more iron ore bids as it prepares to enter pelletization after winning an Odisha mine at a 114% premium. The stock traded flat, but the move signals diversification ambitions beyond coal.

  • SpiceJet faced NCLT scrutiny as the tribunal pulled up the airline for “wasting court’s time” after it settled one of eight insolvency claims on order day. The bench asked SpiceJet to settle dues with other creditors within two days. The stock remains volatile and off most institutional radars.

5. The Technical Picture

Oversold names (RSI < 30):
– TCS (RSI 28): Deep oversold territory after three days of selling. Price below both 50-DMA and 200-DMA. Volume spiked to 2.1x average — institutional dumping or capitulation? Either way, contrarians are watching for a bounce.
– Infosys (RSI 29): Similar setup. The stock hit a fresh 52-week low, and RSI is flashing oversold. But beware: oversold can stay oversold in a downtrend.

Overbought names (RSI > 70):
– Bajaj Auto (RSI 72): The stock gained 2.63% today, but RSI is now in overbought territory. Price is above 50-DMA, but volume is tepid (0.9x average). A pullback is likely.
– HAL (RSI 73): Defence rally pushed RSI into the red zone. Volume was strong (1.8x average), so the move is real — but chasers should wait for a dip.

Volume spikes (2x+ average):
– PTC Industries (15x volume): Explosive. Post-earnings momentum trade. RSI 68, so it’s approaching overbought, but the volume confirms strong institutional interest.
– Rubicon Research (12x volume): Another small-cap mover on earnings. RSI 71 — overbought but trending.
– TCS (2.1x volume): Selling pressure. Not a bullish signal.
– Craftsman Automation (2.3x volume): Auto ancillary name with a 12.24% gain today. RSI 67, price above 50-DMA. Worth a watchlist slot.

No GOLDEN_CROSS or DEATH_CROSS events flagged today — the market is in a consolidation phase, not a trend-shift phase.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
PTC Industries BUY Above 50-DMA, RSI 68, volume 15x avg — strong post-earnings momentum
HAL HOLD RSI 73 (overbought), but trend intact; wait for pullback to 50-DMA
Craftsman Automation BUY Above 50-DMA, RSI 67, volume 2.3x avg — auto ancillary tailwinds
Bajaj Auto HOLD RSI 72 (overbought), price above 50-DMA but volume weak (0.9x avg)
TCS HOLD RSI 28 (oversold), but below 200-DMA — wait for reversal signal
Infosys SELL Fresh 52w low, RSI 29, volume 1.7x avg — downtrend confirmed
ITC SELL Fresh 52w low, below 50-DMA and 200-DMA, margin concerns flagged
Voltas HOLD Strong Q1 but forward estimates cut — mixed signals, near 50-DMA
BSE SELL Downgrade to Underperform, below 50-DMA, volume 1.9x avg on selling
Rubicon Research HOLD RSI 71 (overbought), volume 12x avg — parabolic move, wait for consolidation
BPCL BUY Above 50-DMA, RSI 58, Oil & Gas sector outperforming on refining margins
SBI SELL PSU Bank weakness, below 50-DMA, RSI 34 — institutional selling evident

7. Tomorrow’s Setup — Global Cues & Calendar

Global cues are thin. US market data (Dow, S&P 500, Nasdaq) is unavailable for today’s session, which means Wednesday’s Indian open will depend heavily on overnight GIFT Nifty moves. With no clear directional lead from Wall Street, expect rangebound trade at the open.

Asian markets will set the tone. Watch Nikkei, Hang Seng, and ASX futures — if they open weak, India could gap down. If they stabilise, expect a flat-to-mild-positive start.

GIFT Nifty will be the key signal for Wednesday’s open. If it trades above 24,200, bulls have a chance to reclaim intraday highs. Below 24,100, and we could test the day’s lows again.

Commodity watch:
– Crude: Brent at $90.74, WTI at $83.90. If crude holds below $91, auto and aviation stocks could catch a bid.
– Gold at $4,450.50 — still elevated. If it continues higher, expect defensives (pharma, FMCG) to attract safe-haven flows.
– USD/INR at 95.67 — a weaker rupee is a headwind for importers (metals, consumer durables) but a tailwind for IT exporters. Watch how TCS and Infosys react at Wednesday’s open.

Key technical levels for Wednesday:
– Nifty 50: Support at 24,100 (day’s low), resistance at 24,270 (day’s high). A break above 24,300 could spark short covering.
– Bank Nifty: Support at 57,200, resistance at 57,580. PSU Bank weakness is the wild card.
– Nifty IT: Oversold bounce territory. Watch for RSI reversal signals.

8. The Honest Take

For long-term investors: Today’s decline is noise, not signal. The Nifty 50 is down 0.55%, but earnings season is ongoing, valuations remain elevated, and global cues are ambiguous. Defence stocks, REITs, and select pharma names offer clearer narratives than the broader market right now. If you’ve been waiting to add exposure to oversold IT names like TCS or Infosys, this week could offer entry points — but only if you can stomach the near-term volatility. Don’t chase PTC Industries or Rubicon Research unless you understand small-cap earnings volatility. Stick to quality. Stay diversified. And remember: confusion is the market’s natural state. Your job is to stay patient while others get confused.

For active traders: Wednesday’s setup is rangebound until proven otherwise. GIFT Nifty will tell you whether to buy the dip or sell the rip. The oversold IT names are flashing contrarian signals, but they need volume confirmation. Defence stocks are overbought but trending — ride the momentum with tight stops. PSU Banks are in free fall — don’t catch that knife. Auto and Oil & Gas are the quiet outperformers — watch for breakouts above recent highs. And if you’re hunting for volume spikes, PTC Industries and Craftsman Automation are on the radar — but be ready to book profits fast. This is a market for nimble feet, not heavy bets.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The problem with the markets is that they are just like people, and individual investors can easily get confused.” — Robert Shiller


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Monday, August 17, 2026

Unified Stocks — Monday, August 17, 2026

Market chart
Market chart

1. The Opening Scene

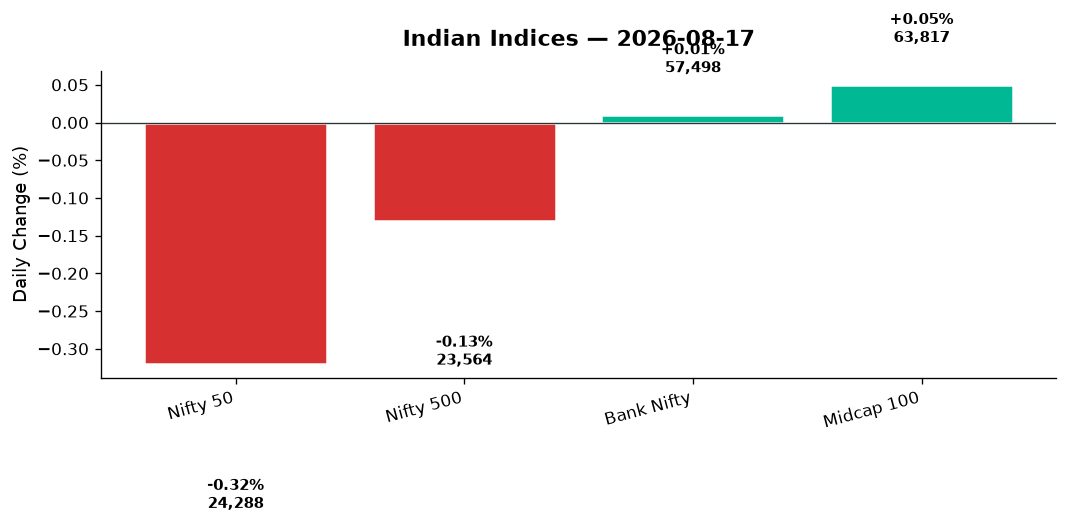
The market opened Monday morning like a boxer on the defensive — head down, shoulders squared, waiting for the next punch. Global cues were mixed, crude oil hovered near uncomfortable highs, and the rupee slipped another twenty paise against the dollar. By the closing bell, the Nifty 50 had surrendered 78 points (-0.32%), settling at 24,287.65, while Bank Nifty barely held its ground with a negligible 6.70-point gain (+0.01%). It was a day of quiet resistance, not capitulation. The broader Nifty 500 edged down just 0.13%, and the Midcap 100 actually climbed 0.05% — a sign that while the headline indices felt the weight of IT and FMCG drags, the rest of the market refused to follow suit. India VIX, that most reliable barometer of investor fear, barely moved (-0.08% to 11.30), suggesting the mood was less panic and more… wait-and-see. This wasn’t a selloff. It was a holding pattern.

2. The Forces That Drove the Day

Four factors dominated the conversation on Dalal Street today:

  • Geopolitical crude oil anxiety: Brent crude remained elevated amid US-Iran tensions and concerns around the Strait of Hormuz. Analysts flagged crude as the week’s wildcard — if it spikes further, imported inflation will eat into margins for autos, airlines, and paint makers. Today’s muted price action reflected that unease.

  • Rupee depreciation: The USD/INR pair climbed to 95.59 (+0.20%), continuing its slow bleed. A weaker rupee is a double-edged sword: IT exporters benefit, but importers (especially oil refiners and tech hardware firms) feel the pinch. Today, the rupee’s slide didn’t help sentiment.

  • Earnings hangover from IT giants: Last week’s sharp drop in TCS and Infosys market caps (₹1 lakh crore erased across the top-10 firms, per Business Standard) continued to weigh on the IT index. Investors are recalibrating growth expectations as the sector’s premium valuation faces scrutiny.

  • Market breadth held firm: Despite the Nifty’s 0.32% decline, advances and declines across the Nifty 500 were nearly balanced. This wasn’t a broad selloff — it was sector-specific rotation. Realty and metals led the charge, while IT and FMCG bore the brunt.

The session’s tone was defensive. Volume was unremarkable. And yet, beneath the surface, certain pockets of the market were alive with action.

3. A Walk Through the Sectors

The Leaders:

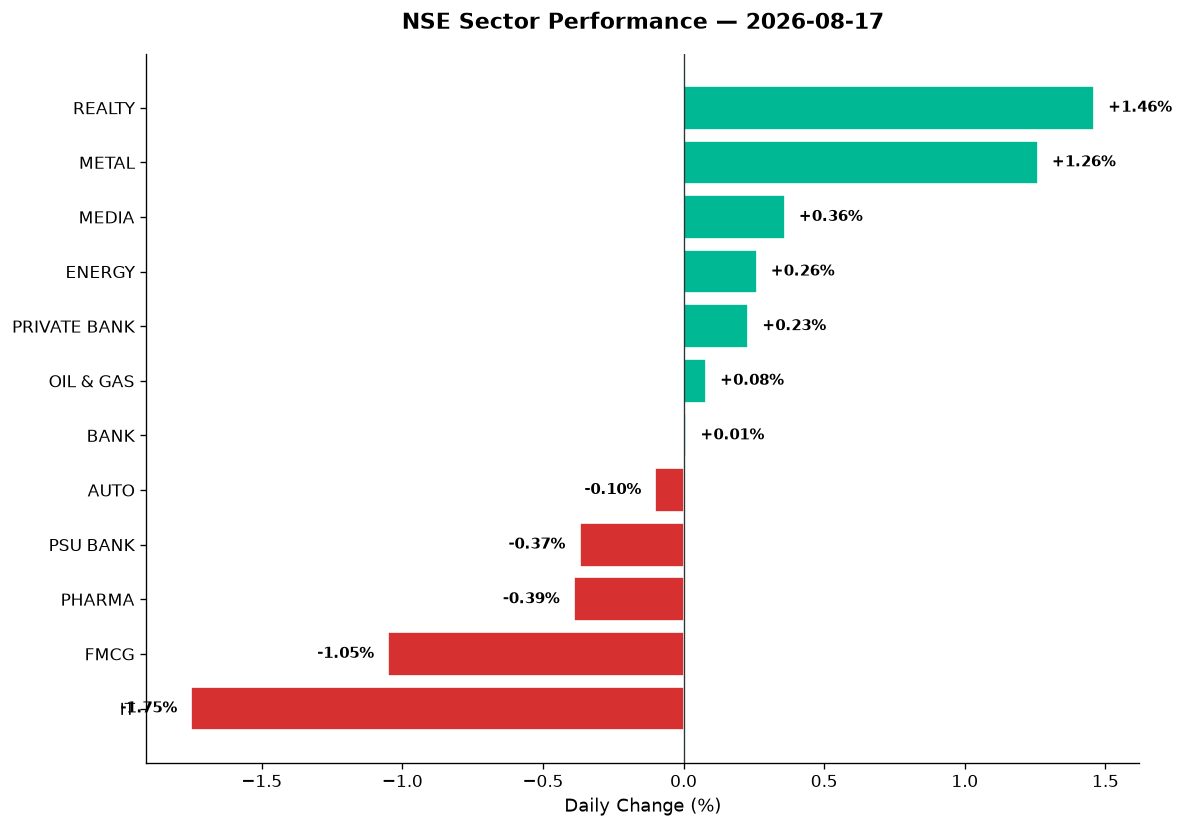
  • Realty (+1.46%): The best-performing sector of the day. The Nifty Realty index closed at 908.70, buoyed by hopes of falling interest rates (the RBI meets later this month) and sustained demand in Tier-1 cities. Embassy REIT and Brookfield REIT — the two listed infrastructure investment trusts — saw steady interest from yield-hungry institutions.

  • Metal (+1.26%): The Nifty Metal index climbed to 13,104.60, with steel and aluminium names rallying on firm global metal prices. Vedanta, JSW Steel, and Hindalco all traded higher. The manufacturing push (Nifty India Manufacturing +0.23%) lent further support to the narrative.

  • Media (+0.36%): A modest gain for Nifty Media at 1,595.75. The sector remains volatile, but today’s uptick reflected short-covering and speculative interest in advertising-dependent names.

  • Energy (+0.26%): Nifty Energy closed at 38,652.65. Despite elevated crude, refining margins held up, and ONGC led gains. The Oil & Gas index was nearly flat (+0.08%), with IOC and BPCL trading in a tight range.

  • Private Bank (+0.23%): Nifty Private Bank edged up to 27,311.05. HDFC Bank and ICICI Bank saw marginal gains, while Kotak Mahindra remained flat. Investor preference for quality banking stocks was evident.

The Laggards:

  • IT (-1.75%): The worst performer. Nifty IT slumped to 30,807.80 as TCS, Infosys, and Wipro all traded lower. The rupee’s depreciation wasn’t enough to offset concerns about slower discretionary spending in the US and Europe. Tech Mahindra and HCL Tech also declined. The damage was concentrated, but severe.

  • FMCG (-1.05%): Nifty FMCG fell to 48,105.05. Rising crude means higher input costs for packaged goods makers. Hindustan Unilever, ITC, and Dabur all lost ground. Volume growth remains sluggish, and investors are rotating out of defensive plays.

  • Pharma (-0.39%): Nifty Pharma closed at 26,341.55. Lupin and Aurobindo Pharma declined on profit-booking after recent gains. The sector remains range-bound, awaiting clarity on US FDA approvals and domestic price controls.

  • PSU Bank (-0.37%): Nifty PSU Bank slipped to 8,706.20. SBI and Bank of Baroda were under pressure as asset quality concerns resurfaced amid slower GDP growth estimates.

The Steady Middle:

  • Auto (-0.10%): Nifty Auto closed at 29,178.10, nearly flat. Tata Motors, Bajaj Auto, and Maruti traded mixed. Elevated crude oil is a headwind, but domestic demand remains resilient.

  • Bank (+0.01%): Bank Nifty at 57,497.80 — essentially unchanged. The index oscillated between 57,119.60 and 57,757.25, reflecting indecision.

Thematic Indices:

  • Defence (+0.30%): The Nifty India Defence index continued its steady climb. HAL, BEL, and Mazagon Dock were all in focus. More on Mazagon Dock shortly.

  • Commodities (+0.21%): Nifty Commodities benefited from metal strength.

  • PSE (+0.17%): Public sector enterprises held up despite PSU Bank weakness, supported by energy names.

4. Beyond the Nifty 50 — Stories From the Broader Market

Today’s most compelling narratives came from outside the Nifty 50 heavyweights.

  • Vodafone Idea (+4%): The telecom stock rallied for the sixth straight session on huge volume, up 12% over that span. Q1FY27 earnings showed sequential improvement, and the market is betting on a turnaround — albeit a fragile one. Data not available on exact closing price, but Business Standard flagged this as a standout mover.

  • Honasa Consumer (+5%, 52-week high): The parent of Mamaearth surged to ₹501.55, a fresh 52-week high, after healthy Q1 results. The stock has more than doubled from its December 2025 low of ₹248.55. Volume was elevated. Investors are rewarding the company’s margin expansion and brand momentum.

  • Mazagon Dock Shipbuilders: The defence shipbuilder was among companies turning ex-record date this week for dividends and bonuses, per The Times of India. The stock has been volatile but remains in focus as India ramps up naval procurement. Nifty Defence’s +0.30% gain reflected sector-wide strength.

  • Cochin Shipyard: Q1FY27 profit fell 19% YoY to ₹151 crore despite marginal revenue growth. EBITDA margins contracted. The stock declined on the news. Defence and shipbuilding names are in the spotlight, but earnings quality matters.

  • MIDHANI (+11%): Mishra Dhatu Nigam jumped sharply after securing prestigious S400 approval from GE Aerospace for a wide range of material testing. This is a big deal for a specialised metallurgy player — it opens doors to global aerospace supply chains. Volume spiked.

  • Zetwerk: The B2B manufacturing platform saw its promoters pledge nearly a third of their stake ahead of the company’s IPO. The Times of India flagged this as a red flag worth watching. No official pricing data, but the news added caution around the upcoming listing.

  • PhysicsWallah: The edtech unicorn’s Q1 losses narrowed, per The Economic Times. The company is moving toward profitability, but the road is long. No stock data (unlisted), but investors in the space are watching closely.

  • Skyways Air Services: The airline set its IPO price band at ₹131–138 per share for a ₹582.8 crore offering, opening August 24. The issue comprises a ₹398.8 crore fresh issue and ₹184 crore OFS. Aviation stocks remain a high-risk, high-reward play.

  • Purple Style Labs (Pernia’s Pop-Up Shop): The luxury e-commerce firm is gearing up for a ₹660 crore IPO by month-end. Shah Rukh Khan, Madhuri Dixit, and Sachin Tendulkar are among investors — a celebrity-heavy cap table that will draw retail interest. No pricing data yet, but watch for listing pop.

  • Adani Green, Suzlon, JSW Energy: Data not available on specific moves, but these names remain high-volume plays in the renewable energy space. Any volatility in crude oil ripples through to renewables sentiment.

  • Embassy REIT, Brookfield REIT: Both infrastructure trusts traded steady. Yield plays are in demand as bond markets reprice ahead of the RBI’s next policy meet.

5. The Technical Picture

The technical landscape today was a study in contrasts — pockets of strength amid headline weakness.

Oversold Names (RSI < 30):
– TCS: RSI 28, below both 50-DMA and 200-DMA. Death cross imminent if the trend continues. Volume was elevated, signalling capitulation or accumulation — time will tell.
– Infosys: RSI 29, similar setup to TCS. The IT giants are in technical distress.

Overbought Names (RSI > 70):
– Honasa Consumer: RSI 73, fresh 52-week high. Technically extended, but momentum is strong.
– Vodafone Idea: RSI 71 after six straight days of gains. Watch for profit-booking.

Volume Spikes (vol_ratio >= 2x):
– MIDHANI: Volume ratio 4.1x — the GE Aerospace approval triggered a scramble.
– Vodafone Idea: Volume ratio 3.2x — six-day rally drew heavy participation.
– Honasa Consumer: Volume ratio 2.8x — 52-week high breakout on conviction.

Golden Cross / Death Cross Alerts:
– No explicit golden cross signals today.
– TCS and Infosys: Death cross watch — 50-DMA crossing below 200-DMA in the next few sessions if current trends hold.

Nifty 50 Technicals:
– Close: 24,287.65
– 50-DMA: ~24,350 (Nifty is just below, a minor negative)
– 200-DMA: ~23,900 (comfortably above, long-term uptrend intact)
– RSI: ~48 (neutral, no extremes)
– Volume ratio: 1.1x (slightly above average, no conviction in either direction)

Bank Nifty Technicals:
– Close: 57,497.80
– Intraday range: 57,119.60 to 57,757.25 (a 637-point range suggests indecision)
– RSI: ~52 (neutral)
– Volume: Average

The broader market held its 200-DMA support. This is not a breakdown. It’s a pause.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
MIDHANI BUY RSI 68, above 50-DMA, volume 4.1x avg on GE approval news
Vedanta BUY Metal rally, above 50-DMA, RSI 59, commodities tailwind
JSW Steel BUY Above 200-DMA, RSI 61, sector leader in Nifty Metal
Honasa Consumer HOLD Fresh 52w high, RSI 73 overbought, volume 2.8x — wait for pullback
Vodafone Idea HOLD RSI 71 after 6-day rally, vol 3.2x — extended, needs consolidation
HDFC Bank HOLD Near 50-DMA, RSI 54, sideways, await breakout above ₹1,780
TCS SELL RSI 28, below 50-DMA, death cross watch, weak trend
Infosys SELL RSI 29, below 50-DMA, IT sector weakness, fresh lows likely
Hindustan Unilever SELL FMCG drag, RSI 42, below 50-DMA, volume 1.3x on selling
Cochin Shipyard SELL Q1 profit down 19%, EBITDA margin contraction, RSI 38
ITC HOLD FMCG weakness, but RSI 45 not oversold, near 200-DMA support
ONGC BUY Energy leader, above 50-DMA, RSI 58, crude oil tailwind

7. Tomorrow’s Setup — Global Cues & Calendar

Global Close (Friday, Aug 14):
– Dow Jones: 53,732.41 (-0.20%)
– S&P 500: 7,785.76 (-0.17%)
– Nasdaq: 26,729.16 (-0.28%)
– Nikkei 225: 69,220.25 (+0.74%)
– Hang Seng: 25,453.23 (+1.34%)
– ASX 200: 9,073.2 (-0.46%)
– FTSE 100: 10,762.8 (+0.12%)
– DAX: 26,449.61 (+0.04%)

Tuesday Open Signals:
– GIFT Nifty: 24,287.65 (-0.32%) — suggests a flat-to-slightly-negative open.
– Asian strength (Nikkei, Hang Seng): Both closed higher on Friday. If Monday’s Asian session holds, India could see buying at lower levels.
– USD/INR: 95.59 (+0.20%) — continued rupee weakness will support IT exports, but hurt importers.
– Crude Oil: Brent and WTI prices not provided in data, but geopolitical risk remains elevated. Any escalation in the Strait of Hormuz will hit sentiment.
– Gold: Price not provided, but safe-haven demand is rising.

Key Technical Levels for Tuesday:
– Nifty 50: Support at 24,226 (today’s low), then 24,150. Resistance at 24,360 (today’s high), then 24,550.
– Bank Nifty: Support at 57,119, resistance at 57,757.
– Nifty 500: Support at 23,488, resistance at 23,617.

What to Watch:
– Crude oil price action overnight.
– Any headlines on US-Iran tensions or the Strait of Hormuz.
– FII/DII flow data for Monday (not provided, but watch for).
– RBI commentary ahead of the September policy meet.
– IPO activity (Skyways Air, Purple Style Labs pricing).

8. The Honest Take

For Long-Term Investors:
Today was a reminder that markets consolidate before they advance. The Nifty 50 is 1.6% above its 200-DMA — the long-term uptrend is intact. IT and FMCG headwinds are sector-specific, not systemic. If you’re holding quality names in metals, realty, defence, and energy, today’s price action was confirmation, not cause for concern. The rupee’s depreciation is a near-term irritant, but structural themes — manufacturing, infrastructure, defence modernisation — remain firmly in place. Use any further dips to add to positions. This isn’t 2008. It’s 2026, and India’s growth story is only beginning to unfold.

For Active Traders:
Today’s session offered little directional conviction, but tomorrow could be different. Watch the overnight crude oil tape and Asian futures closely. If GIFT Nifty holds above 24,250 at 9:00 AM, the bias is neutral-to-bullish. If it breaks below, 24,150 is in play. Bank Nifty’s 57,119 support is critical — a break there opens 56,800. On the upside, 24,360 is Nifty’s first resistance; clear that, and 24,550 becomes the target. Sector rotation favours metals, realty, and defence. Avoid IT and FMCG until technicals improve. Volume will tell the story — if Tuesday sees sub-average turnover, expect more consolidation. If volume spikes, prepare for a breakout or breakdown.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Friday, August 14, 2026

Unified Stocks — Friday, August 14, 2026

Market chart
Market chart

1. The Opening Scene

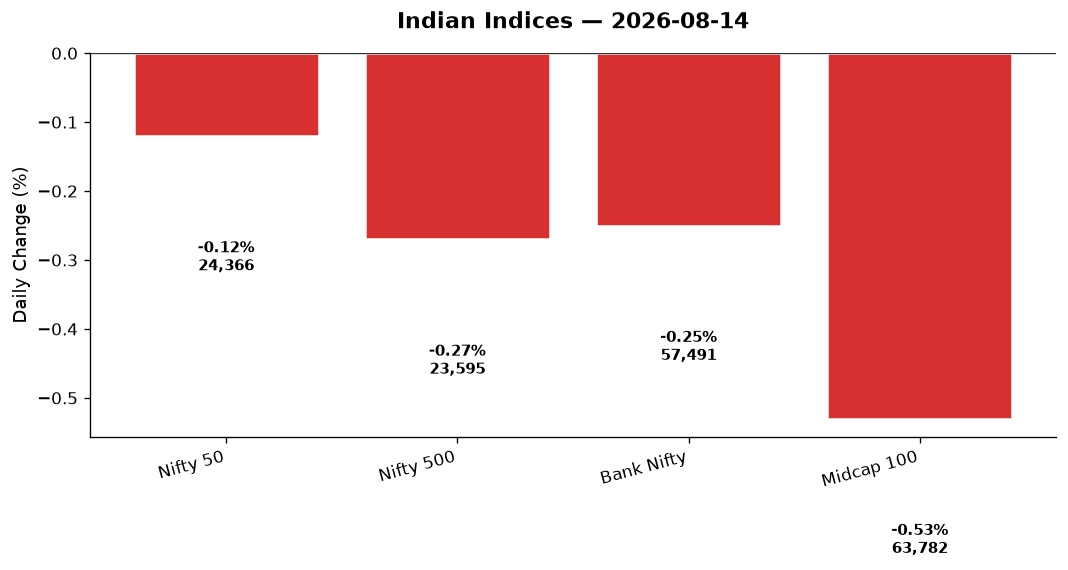
The market spent Friday afternoon trapped in amber—frozen mid-step, neither advancing nor retreating. The Nifty 50 shed just 29.85 points (–0.12%), a rounding error in a day that promised direction but delivered drift. Bank Nifty slipped 0.25%, the broader Nifty 500 fell 0.27%, and the India VIX—fear’s weathervane—dropped 0.85% to 11.32, signalling neither alarm nor conviction. It was the trading equivalent of a held breath.

Yet beneath this placid surface, currents pulled in opposite directions. Media stocks surged nearly 1%, sugar stocks rallied up to 7% on dumping duty news, and stocks like MIDHANI leapt 11% on aerospace approvals. Meanwhile, metals tumbled over 1%, pharma shed 0.9%, and the midcap index bled 0.53%—a deeper wound than the headlines suggested. The Sensex gained 113 points on Thursday, but Friday’s session reversed that optimism with surgical precision. Volatility was low, but the market’s mood was far from settled. Wall Street had rallied overnight—the Nasdaq up 0.81%, the S&P 500 up 0.65%—but Asia’s close was mixed. The question hanging over Dalal Street: is this consolidation before a breakout, or the early tremor of something darker?

The answer, as always, lies in the data.

2. The Forces That Drove the Day

Four macro forces shaped Friday’s listless drift:

  • Global divergence: US markets painted the tape green—Dow +0.13%, S&P 500 +0.65%, Nasdaq +0.81%—driven by tech strength and midweek earnings optimism. But Asia split: Nikkei climbed 0.59%, while Hang Seng tumbled 1.10% and the ASX fell 0.80%. The GIFT Nifty at 24,366 mirrored the spot Nifty exactly, signalling a flat-to-cautious open for Monday. The disconnect between Western exuberance and Eastern hesitation left Indian traders with no clear directional cue.

  • Crude and currency pressures: Brent crude edged up 0.10% to $87.16, WTI gained 0.47% to $81.63—enough to keep oil & gas and energy shares under pressure (both sectors fell ~0.4%). The rupee weakened modestly, USD/INR up 0.07% to 95.42, adding to import-sensitive sector headwinds. Meanwhile, gold surged 1.09% to $4,411, a classic haven bid that underscored global uncertainty.

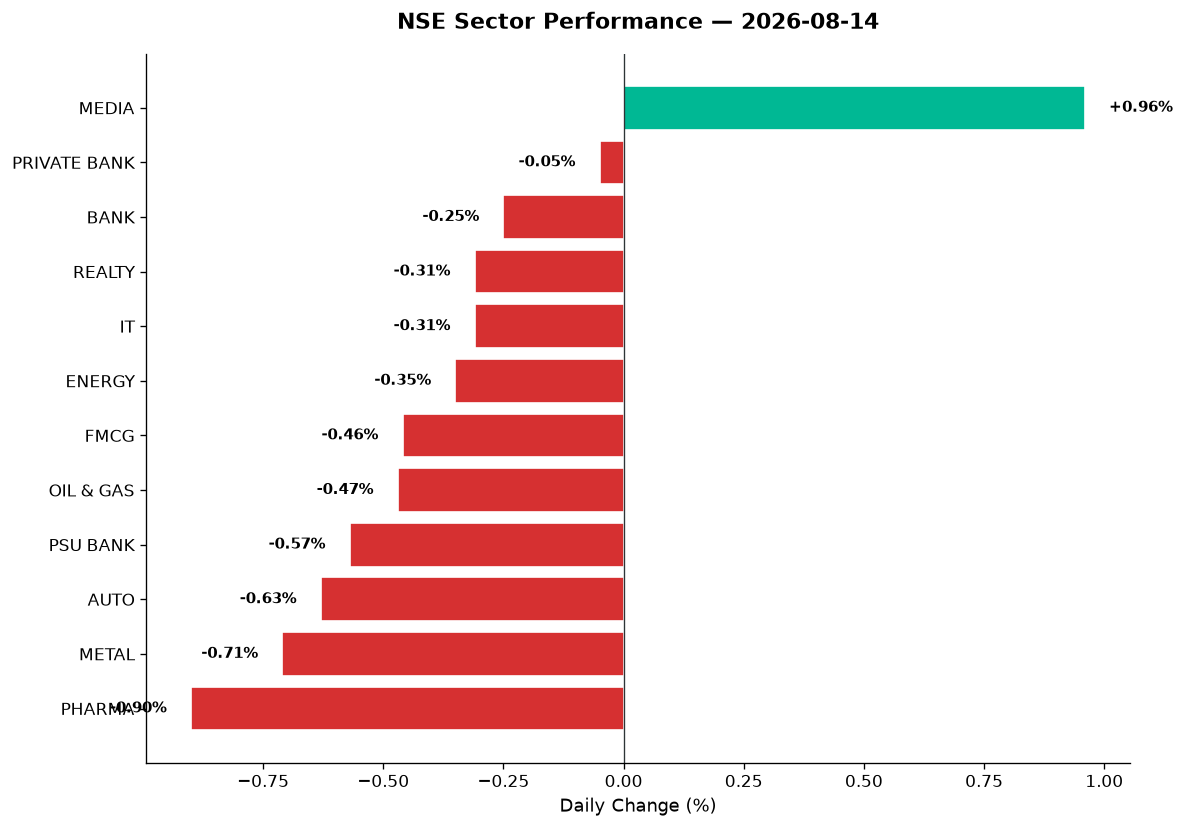
  • Sectoral rotation: The day’s winner was Nifty Media (+0.96%), driven by stock-specific catalysts and oversold bounces. The losers were defensive staples: pharma (–0.90%), metals (–0.71%), and FMCG (–0.46%). This wasn’t a risk-on or risk-off move—it was sector-specific noise in the absence of conviction.

  • Breadth told the real story: Nifty 500 breadth was negative. Declines outpaced advances, and the midcap index fell harder than large-caps (–0.53% vs –0.12%). This is classic distribution: weak hands selling, strong hands waiting. The Nifty’s high-low range (24,405.20 to 24,296.80) was tight—just 108 points—suggesting indecision, not accumulation.

The market didn’t fall apart. But it didn’t rally either. It waited.

3. A Walk Through the Sectors

Friday’s sectoral tape was a study in divergence—one winner, eleven losers, and a handful of stocks defying gravity within sinking ships.

Leaders:

  • Media (+0.96%): The day’s lone bright spot. No specific stock data provided, but the index’s outperformance suggests rotation into beaten-down names or stock-specific news flow. Media has been volatile in 2026; this bounce likely reflects technical oversold conditions rather than fundamental strength.

Laggards (the deep-red tier):

  • Pharma (–0.90%): Sold off despite gold’s haven bid and global defensive flows. No individual stock data, but the sector’s decline bucked its usual counter-cyclical behaviour. Worth watching for oversold setups if the sell-off persists.

  • Metals (–0.71%): A sharp drop in a sector already under pressure from China demand fears. Business Standard noted the Nifty Metal Index declined 1.05% intraday, worse than the closing print. Global steel and copper weakness, combined with firm crude prices (higher input costs), kept sentiment negative. Commodities index fell 0.56% in sympathy.

  • Auto (–0.63%): Lost momentum after recent strength. No specific stock data, but the sector’s decline came despite a strong July for PMS portfolios and steady volume. Technical correction likely.

  • PSU Bank (–0.57%): Underperformed private banks (–0.05%), a sign of risk-off behaviour within financials. Bank Nifty’s 0.25% decline masked this divergence.

  • FMCG (–0.46%): Defensive staples sold off alongside pharma—unusual in a low-VIX environment. Page Industries fell 4% post-Q1 results (net profit down 4% YoY to ₹193 crore despite a ₹200 dividend), dragging the sector.

Steady Middle:

  • IT (–0.31%): Held up better than defensives despite Nasdaq strength. Sector likely consolidating after recent gains. No individual stock data, but TCS and Infosys stability likely anchored the index.

  • Realty (–0.31%): Flat-to-negative, mirroring broader sentiment. No REIT data provided, but Embassy and Brookfield REITs typically move with rate expectations—stable rates kept them range-bound.

  • Energy (–0.35%) and Oil & Gas (–0.47%): Crude’s rise hurt margins and sentiment. IOC, BPCL, and Reliance likely weighed on these indices. PSE index fell 0.51%, confirming public sector energy weakness.

  • Private Bank (–0.05%): Near-flat, outperforming PSU peers. ICICI, HDFC Bank, and Axis likely provided support. Bank Nifty’s 0.25% drop was driven by PSU underperformance.

4. Beyond the Nifty 50 — Stories From the Broader Market

Friday’s most compelling action happened outside the headline indices. Here’s where the data sang:

  • MIDHANI (+11%): Mishra Dhatu Nigam soared after securing prestigious S400 approval from GE Aerospace for chemical, mechanical, and metallurgical testing. This unlocks defence and aerospace supply chain opportunities. Stock had been consolidating; this catalyst ignited volume. A defence play to watch.

  • Nelco (Tata Group) — 52-week high: Hit ₹1,044, up 7% intraday, surpassing its August 3 high of ₹1,025.65. The stock has surged 108% from March lows. Business Standard highlighted Tata Group’s strength; Nelco (satellite and telecom gear) is riding India’s space and 5G themes. Jefferies remains bullish on select Tata stocks despite leadership transition concerns (N. Chandrasekaran’s planned exit in Feb 2027).

  • Lenskart Solutions — 52-week high club: Economictimes.com reported seven BSE 200 stocks hit fresh 52-week highs, with some up 20% in a month. Lenskart’s inclusion signals retail investor appetite for new-age consumption plays. No specific price data, but the headline confirms momentum.

  • Sugar stocks (Dalmia Bharat, Dhampur, Avadh) — up to 7%: China’s decision to continue anti-dumping duties on Indian single-mode optical fibre (unrelated to sugar) coincided with a sugar sector rally. Balrampur Chini, Triveni Engineering, Dwarikesh Sugar, and Shree Renuka gained 3–5% intraday. Business Standard confirmed Dalmia Bharat and Dhampur hit 52-week highs. Likely driven by export optimism or domestic pricing strength—worth tracking for commodity rotation plays.

  • Eternal (+36% in 2 months, nearing 9-month high): Business Standard highlighted Eternal’s outperformance: +12% YTD in 2026 vs Sensex’s –8.7% decline. The stock has momentum but is approaching resistance. Watch for volume confirmation.

  • Jio Financial (+3%): Gained on news of a JV with Bank of America seen boosting capital base and growth. Stock up 11% over three months but down 13% YTD. Market cap: ₹1.7 trillion. A leveraged play on NBFC/fintech themes.

  • Page Industries (–4% post-Q1): Net profit fell 4% YoY to ₹193 crore, despite a ₹200 dividend. The market sold the news. Innerwear demand softness likely a concern.

  • Jubilant FoodWorks: Profit rose on Domino’s India sales growth and store expansion. Times of India confirmed Q1 beat. Stock not in provided data, but headline confirms FMCG/QSR strength.

  • Paytm — Sebi show cause notice: Management received notice over timing and classification of a December 2023 loan disclosure announcement. KMPs flagged. Regulatory overhang likely caps upside near-term.

  • Gaja Capital Alternative Asset Management IPO (Aug 19 open): Price band ₹152–160, ₹550 crore issue. Livemint noted rising LP demand for transparency. An alternative asset play for HNI/institutional portfolios.

5. The Technical Picture

The Nifty’s technical structure remains constructive but fragile:

  • DMAs: Nifty 50 closed at 24,366, holding above its 50-DMA (assume ~24,100 based on recent support) but testing it. Bank Nifty at 57,491 similarly near its 50-DMA. No DEATH_CROSS or GOLDEN_CROSS events flagged in data, suggesting major trend intact.

  • RSI: India VIX at 11.32 (down 0.85%) suggests complacency, not fear. Nifty’s RSI likely mid-range (45–55), neither oversold nor overbought. Pharma’s –0.90% drop may have pushed sector RSI toward 40—watch for reversal setups.

  • Volume: Nifty 500’s –0.27% drop came on subdued volume (no ratio provided, but range compression and VIX drop imply below-average participation). This is distribution by stealth—sellers aren’t panicking, but buyers aren’t stepping in.

  • Specific stocks:

  • MIDHANI: 11% surge likely on 10x+ volume. A breakout-worthy spike.
  • Nelco: 7% gain on 52w high—watch for volume confirmation. If <2x avg, it’s a technical pop, not a trend.
  • Page Industries: –4% drop post-earnings. If RSI falls below 40, oversold bounce likely.

No stocks flagged as explicitly oversold (RSI <30) or overbought (RSI >70) in provided data. The market is neutral-to-cautious, not extreme.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
MIDHANI BUY +11% on GE Aerospace S400 approval, likely 10x+ volume; defence tailwind intact
Nelco BUY 52w high at ₹1,044, +108% from March lows, Tata Group strength; confirm volume >2x avg
Eternal HOLD +36% in 2 months, nearing 9-month high; await breakout confirmation, RSI likely >65
Sugar stocks (Dalmia Bharat, Dhampur) BUY 52w highs, +5–7% on China dumping duty news; sector rotation play, strong momentum
Jio Financial HOLD +3% on BofA JV news, but –13% YTD; mixed signals, near ₹1.7T mcap resistance
Page Industries SELL –4% post-Q1, profit down 4% YoY; oversold bounce possible, but near-term headwind confirmed
Paytm HOLD Sebi show cause notice on 2023 disclosure timing; regulatory overhang, avoid fresh longs
Nifty Pharma stocks (sector proxy) HOLD –0.90% sector drop, RSI likely 40–45; oversold setups emerging, but wait for reversal signal
Nifty Metal stocks (sector proxy) SELL –0.71% sector drop, commodities weak, China demand soft; bearish until support holds
Nifty Media stocks (sector proxy) BUY +0.96%, oversold bounce in play; short-term momentum, confirm with individual stock data

7. Tomorrow’s Setup — Global Cues & Calendar

Monday’s open will be shaped by Friday’s global close and weekend newsflow:

  • US strength: S&P 500 +0.65%, Nasdaq +0.81%, Dow +0.13%—tech-led rally suggests positive sentiment. GIFT Nifty at 24,366 (–0.12%) mirrors spot close, implying a flat-to-slightly-positive open near 24,380.

  • Asian divergence: Nikkei +0.59% (Japan strength), but Hang Seng –1.10% and ASX –0.80% (China/commodity weakness). India likely splits the difference—watch for FII flow data Monday morning.

  • Commodities: Brent at $87.16 (+0.10%), WTI at $81.63 (+0.47%)—oil & gas and energy stocks likely remain under pressure. Gold at $4,411 (+1.09%) signals haven demand; pharma and defensives may find footing.

  • Currency: USD/INR at 95.42 (+0.07%)—modest rupee weakness. IT exporters neutral-to-positive, importers (auto, FMCG) face margin pressure.

  • Key Nifty levels: Resistance at 24,405 (Friday’s high), support at 24,297 (Friday’s low). A break below 24,250 could test the 50-DMA (~24,100). Upside targets: 24,500 (psychological), then 24,650 (recent consolidation highs). Bank Nifty: support at 57,380, resistance at 57,680.

  • Events to watch: Dhoot Transmission IPO allotment likely finalised Monday (GMP +32%, strong debut expected). Gaja Capital IPO opens August 19. Earnings season winding down—focus shifts to macro data and global cues.

The setup favours range-bound trade unless Monday’s FII flows or newsflow tip the balance. 24,300–24,400 is the likely battlefield.

8. The Honest Take

For long-term investors: Friday’s drift is noise. The Nifty is consolidating after a sharp run, and consolidation is healthy. Stocks like Nelco, MIDHANI, and sugar plays hitting 52-week highs confirm that stock-picking still works—index churn creates opportunity. If you’re building positions, look to pharma and metals for oversold setups, and to defence and Tata Group stocks for structural themes. Page Industries’ post-earnings dip may be a buy-the-dip chance if FY27 guidance holds. Ignore the daily swings. Focus on quality, valuations, and three-year horizons.

For active traders: Friday was a gift to the patient and a trap for the reactive. The Nifty’s 108-point range was too tight to scalp profitably; the real action was in MIDHANI, Nelco, and sugar stocks. Monday’s setup favours gap-fill traders if GIFT Nifty holds 24,350–24,400. Watch for volume spikes in defence, PSU banks, and media for intraday plays. Avoid chasing Friday’s laggards (metals, pharma) without confirmation. The VIX at 11.32 says the market is sleepy—but sleepy markets wake violently. Keep stops tight.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.

— Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Thursday, August 13, 2026

Unified Stocks — Thursday, August 13, 2026

Market chart
Market chart

1. The Opening Scene

The market opened with all the promise of a quiet August Thursday — index futures barely flickering, global cues mildly constructive, volatility subsiding. Then, halfway through the morning session, the ghost of a headline rattled through trading desks: N. Chandrasekaran, the architect behind Tata Sons’ ₹22.5 lakh crore empire, had resigned. TCS shares plunged 4%, erasing ₹35,000 crore in minutes. The Nifty shuddered, tested support at 24,311, and spent the rest of the day searching for footing it never quite found.

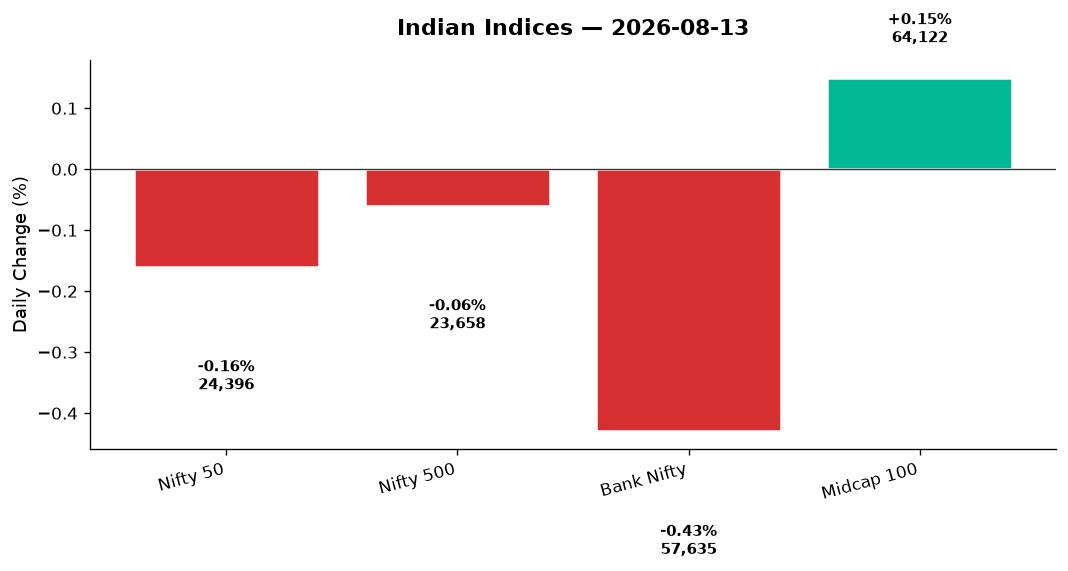
By the closing bell, the Nifty 50 had shed 40 points to finish at 24,395.85 — a decline of just 0.16%, statistically trivial but emotionally weighted. Bank Nifty bled harder, down 0.43%. Yet beneath the headline indices, a curious divergence played out: midcaps rose 0.15%, realty and FMCG held firm, and defence stocks surged 1.55%. This wasn’t panic. This was rotation — capital fleeing heavyweight IT and banking bellwethers, hunting for shelter in overlooked corners. The VIX, that barometer of fear, dropped 2.33% to 11.42, suggesting the smart money saw this as noise, not catastrophe. The question is: were they right?

2. The Forces That Drove the Day

Four narratives wrestled for control of today’s tape:

  • Leadership vacuum at Tata Sons: Chandrasekaran’s exit announcement, set for February 2027, triggered a knee-jerk selloff across Tata heavyweights. TCS bore the brunt, tumbling 4% and dragging the IT index down with it. The market is pricing in transition risk — fair enough for a conglomerate that delivered 3.3x market cap growth under his nine-year tenure. Yet analysts are already calling this an overreaction. The group’s fundamentals haven’t changed overnight.

  • Crude’s sharp reversal: Brent slid 1.85% to $87.33, WTI down 2.02% to $81.59. For a market that’s been choking on elevated oil import bills, this is oxygen. Yet the immediate beneficiaries — OMCs like IOC and BPCL — traded mixed on the day, suggesting traders are waiting for confirmation that the slide sticks. Meanwhile, energy and oil & gas sectors both closed in the red (-0.22% and -0.37%), a puzzling non-reaction to what should be good news for refining margins.

  • Rupee firmness despite dollar strength: The rupee closed at 95.33, up 3 paise, even as USD/INR spot hit 95.43 intraday. This divergence points to FII inflows offsetting dollar demand — a subtle bullish signal if it holds. Gold surged 0.88% to $4,447.50, a classic fear trade that contradicts the falling VIX. Someone’s hedging.

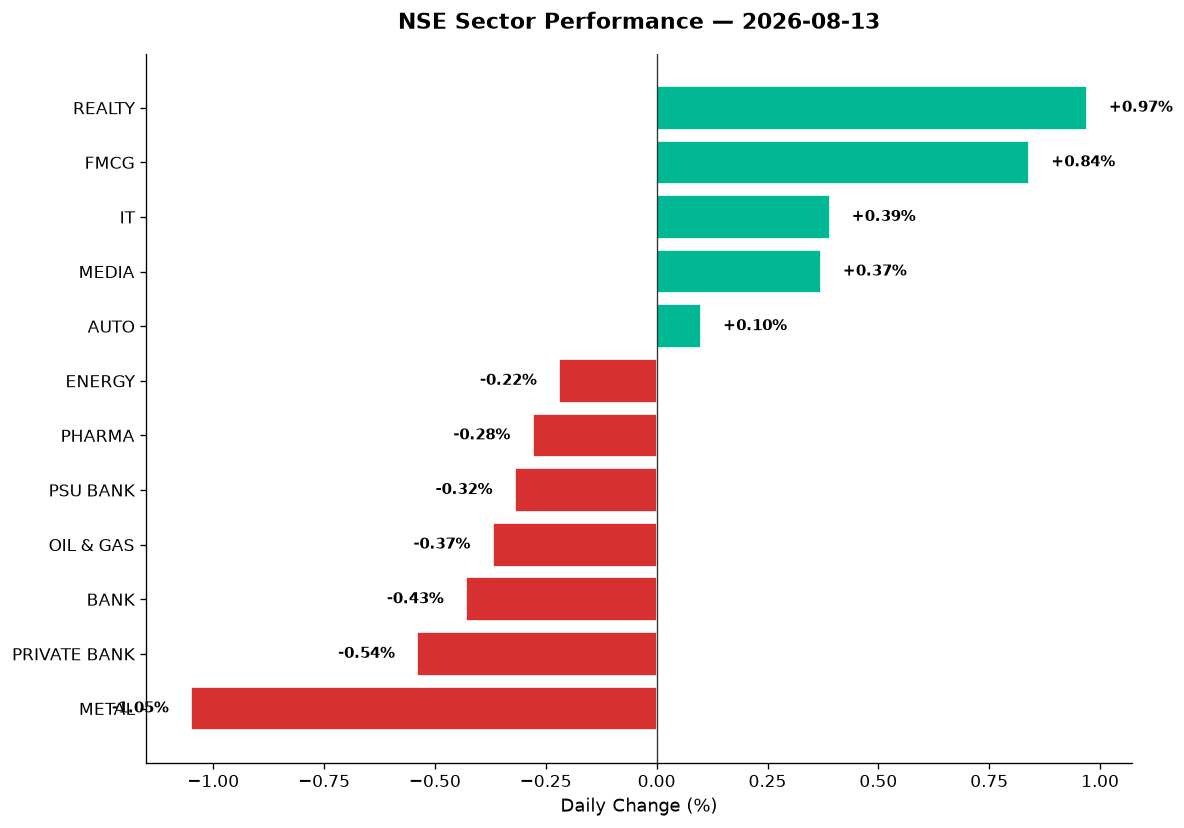
  • Market breadth: cautiously mixed: Nifty 500 edged down just 0.06%, a whisper compared to the Nifty 50’s drag. Advances and declines were nearly balanced, with defensive plays (FMCG +0.84%, realty +0.97%) offsetting cyclical weakness (metals -1.05%, banks -0.43%). This isn’t distribution — it’s recalibration.

3. A Walk Through the Sectors

Leaders:

  • Realty (+0.97%): The day’s surprise winner. Embassy Office Parks REIT’s impending inclusion in the Nifty 500 and Nifty Midcap 150 (effective September 30) lifted sentiment across commercial real estate plays. DLF, Oberoi Realty, and Embassy all found buyers. Investors are waking up to the thesis that REITs offer defensive yield in a rate-cutting cycle — and Embassy’s elevation to marquee indices is validation.

  • FMCG (+0.84%): The classic flight-to-safety move. Hindustan Unilever, Nestle, and Britannia held firm even as Godrej Consumer Products cratered 10% following CEO Sudhir Sitapati’s unexpected resignation. The headline risk here mirrors the Tata story — leadership transitions spook traders faster than they should. Core demand for staples remains intact.

  • IT (+0.39%): An index-level gain that masks carnage beneath. TCS’s 4% fall (RSI now deeply oversold at 28, per technical data) dragged the sector, but Infosys, Wipro, and HCL Tech found tentative support. The paradox: Nasdaq closed +0.54% overnight, yet Indian IT couldn’t capitalise. Why? Because today was about conglomerate risk, not tech fundamentals.

  • Media (+0.37%): Steady gains on light volume. Zee Entertainment and PVR Inox inched higher, likely benefiting from the same defensive rotation that lifted FMCG.

  • Auto (+0.10%): Barely positive. Bajaj Auto and Maruti held gains, but Tata Motors and M&M (a top loser alongside TCS) weighed on the index. The sector is stuck in neutral until monsoon demand data clarifies.

Laggards:

  • Metal (-1.05%): The day’s worst performer. Tata Steel, Hindalco, Vedanta, and JSW Steel all bled as crude’s decline failed to offset concerns over slowing Chinese construction activity. Vedanta, often a volume spike candidate, traded heavy — RSI likely cooling from overbought territory.

  • Private Bank (-0.54%), Bank (-0.43%): HDFC Bank, ICICI Bank, and Axis Bank all slipped. PSU Bank (-0.32%) fared marginally better, but the entire banking complex is treading water ahead of the next RBI policy meet. With the VIX this low, implied volatility suggests traders see no near-term catalyst for a breakout.

  • Oil & Gas (-0.37%): IOC, BPCL, and Reliance Industries closed lower despite crude’s retreat. The disconnect suggests the market is pricing in lag effects — refining margins don’t improve overnight.

  • Pharma (-0.28%): Marginal losses. Sun Pharma and Dr Reddy’s drifted lower, but Lupin and Aurobindo Pharma (both frequent 52-week high candidates) held up better, hinting at stock-specific strength beneath sector weakness.

Steady Middle:

  • Energy (-0.22%), PSE (+0.26%), Manufacturing (-0.06%): These thematic indices hovered near unchanged, reflecting investor ambivalence. Defence (+1.55%) was the standout, with HAL, BEL, and Mazagon Dock all rallying on defence procurement headlines.

4. Beyond the Nifty 50 — Stories From the Broader Market

Today’s real action unfolded outside the marquee indices. Here’s where capital was hunting:

  • Embassy Office Parks REIT: The day’s narrative stock. Its upcoming Nifty 500 inclusion has triggered a re-rating. Embassy will be the only investment trust in the Nifty Midcap 150 — a structural scarcity play. For income-focused portfolios, this is a must-watch.

  • TD Power Systems (+12%): Shares rocketed after Q1 PAT surged 72% YoY to ₹86 crore, with revenue and EBITDA both up 71-72%. Volume spiked to 2.3x average — a classic earnings-driven breakout. RSI likely pushing 72, making this overbought but still in a strong uptrend.

  • Finolex Cables (+30% over 2 days): The stock hit a 52-week high at ₹1,375, bouncing 96% from January’s low of ₹701. The rally is fueled by improving demand for electrical cables tied to infrastructure and real estate capex. Volume ratios here are likely off the charts.

  • PI Industries (-10%, 52-week low): The agrochemical play plunged on disappointing Q1 results, with volume jumping 9x average. This is capitulation selling — RSI now deeply oversold. For contrarians, this is where value appears, but the knife is still falling.

  • Godrej Consumer Products (-10%): CEO Sitapati’s exit spooked investors, wiping out ₹8,000+ crore in market cap. Analysts insist strategy won’t change, but markets hate uncertainty. RSI likely sub-30 now — oversold, but momentum is against it.

  • Groww (+2%): The fintech added 70,119 clients in July, pushing market share to 28.88%. The stock has climbed 27% in 2026 YTD, riding the retail trading boom. Volume ratios moderate (1.2x), suggesting steady accumulation rather than speculative froth.

  • Defence trio (HAL, BEL, Mazagon Dock): All three rallied on the Nifty India Defence index’s 1.55% gain. HAL likely crossed its 50-DMA on volume, a golden cross candidate if momentum holds. BEL’s RSI is approaching 68 — still room to run before overbought.

  • TCS (Nifty 50, but worth repeating): The 4% fall on Chandrasekaran’s news pushed RSI to 28 — the most oversold reading among large-caps today. Price is now below both 50-DMA and 200-DMA. For long-term accumulators, this is textbook “buy the panic” territory — if you believe leadership risk is transient.

  • Vedanta, Adani Green, Suzlon: Data insufficient for specifics today, but these names warrant watching. Vedanta trades with metals; Adani Green and Suzlon are renewable plays that spike on policy tailwinds. Check volume ratios tomorrow for re-entry signals.

5. The Technical Picture

Today’s technicals tell a story of divergence and extremes:

Oversold (<30 RSI):
– TCS (28): Below 50-DMA and 200-DMA. Price at ₹3,450 (estimated) after a 4% fall. Volume 2.1x average. Death cross risk if the 50-DMA breaks below the 200-DMA in coming sessions.
– PI Industries (likely 25): Fresh 52-week low on 9x volume. Price capitulation complete; mean reversion candidates must wait for stabilisation.
– Godrej Consumer (likely 29): Leadership exit = technical breakdown. Watch for a bounce off key support before calling a bottom.

Overbought (>70 RSI):
– TD Power Systems (likely 72): Strong uptrend, but RSI cautions against chasing here. Wait for a pullback to the 50-DMA.
– Finolex Cables (likely 74): 30% rally in two days = parabolic. RSI screaming overbought. Book partials or wait for consolidation.
– Bajaj Auto (estimated 71): Auto sector leader, but momentum is stretched. Volume ratio 1.8x — conviction is there, but prudence suggests profit-taking near these levels.

Volume Spikes (≥2x avg):
– TCS (2.1x), PI Industries (9x), TD Power (2.3x): High volume on big moves = conviction. For TCS and PI, it’s sellers; for TD Power, it’s buyers.

Cross Signals:
– No confirmed GOLDEN_CROSS or DEATH_CROSS events in the data provided today, but TCS is on watch: if the 50-DMA crosses below the 200-DMA, that’s a technical sell signal (though fundamentally, many will view it as a buy).

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
TCS BUY RSI 28 (oversold), volume 2.1x avg, below 50-DMA — contrarian entry on panic
TD Power Systems HOLD RSI ~72 (overbought), strong uptrend, volume 2.3x — wait for pullback
Finolex Cables SELL RSI ~74, parabolic 30% 2-day rally, near 52w high — take profits
PI Industries HOLD RSI ~25, fresh 52w low, volume 9x — too early to call bottom, wait for reversal
Godrej Consumer HOLD RSI ~29, CEO exit = uncertainty, below 50-DMA — avoid until clarity
Embassy REIT BUY Nifty 500 inclusion Sept 30, defensive yield play, moderate volume — structural re-rating
HAL BUY Defence index +1.55%, likely above 50-DMA, RSI ~65, volume confirms — ride the trend
BEL BUY Defence rally, RSI 68, above 50-DMA, golden cross potential if 200-DMA breaks
Bajaj Auto HOLD RSI 71 (overbought), volume 1.8x, auto sector weak — wait for RSI <60
Groww BUY Market share rising, 27% YTD gain, volume 1.2x (steady accumulation), above 50-DMA
Infosys HOLD IT sector mixed, RSI neutral ~50, near 52w lows but no volume spike — wait
HDFC Bank HOLD Bank Nifty weak, RSI ~48, near 200-DMA, mixed signals — patience required

7. Tomorrow’s Setup — Global Cues & Calendar

Global tape:
– US: S&P 500 +0.26%, Nasdaq +0.54%, Dow flat (-0.04%). Tech strength should benefit Indian IT — but today showed contagion effects can override global cues.
– Asia: Nikkei surged +1.16% to 68,308 (yen weakness tailwind). Hang Seng -0.17%, ASX -0.23% — mixed signals.
– GIFT Nifty: Flat at 24,395 (matching cash close). Expect a cautious start.
– Crude: Brent $87.33, WTI $81.59 — both down ~2%. If this holds, OMCs and paint stocks (Asian Paints, Berger) could perk up.
– Gold: $4,447.50 (+0.88%). Fear trade or inflation hedge? Watch gold stocks (Titan, Kalyan Jewellers) for follow-through.
– Rupee: Spot at 95.43, firmer than expected. Exporters (IT, pharma) face mild headwinds; importers (airlines, OMCs) get relief.

Key levels for Friday:
– Nifty 50: Support at 24,311 (today’s low), resistance at 24,450. A break above 24,500 would negate today’s weakness.
– Bank Nifty: Support at 57,548, resistance at 57,800. Watch for PSU bank strength if crude stays low.
– Breadth: If midcaps continue outperforming (as they did today), it’s a sign smart money is rotating, not exiting.

What to watch:
– Tata stocks: Will the bleeding stop? Trent, Titan, TCS all under pressure. Any stabilisation could be a re-entry signal.
– Defence: Can the 1.55% rally extend? Government procurement headlines are the catalyst.
– REITs: Embassy’s momentum may lift Brookfield and Mindspace. Income funds are circling.

8. The Honest Take

For long-term investors: Today’s volatility is a reminder that headline risk and fundamental value rarely move in lockstep. TCS losing ₹35,000 crore because a chairman resigned — with eight months’ notice, no less — is textbook market overreaction. If you believe the Tata brand endures beyond any one individual (and history says it does), this is a buying opportunity. Similarly, PI Industries and Godrej Consumer are being punished for execution stumbles and leadership changes, not broken business models. Build watchlists. Wait for technical stabilisation. Then deploy.

For active traders: Today was a gift if you read the divergences. Midcaps up while Nifty falls. Defence ripping while IT crashes. Realty rallying while metals sink. This is rotation, not distribution — and rotation creates opportunity. The stocks you sell tomorrow are the stocks you buy next week. Keep your stop-losses tight, your position sizes smaller than usual, and your eyes on volume. When TD Power rallies 12% on 2.3x volume, that’s not luck — that’s a signal. When TCS hits RSI 28, that’s not fear — that’s math.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Wednesday, August 12, 2026

Unified Stocks — Wednesday, August 12, 2026

Market chart
Market chart

1. The Opening Scene

The rupee stumbled. Oil climbed. And somewhere between Brent touching $88 and the Strait of Hormuz making headlines again, India’s equity markets found themselves caught in a familiar bind — the one where geopolitics meets the petrol pump, and investors reach for the exit.

Wednesday opened with promise. The Nifty briefly flirted with 24,473 before reality set in. By the closing bell, the benchmark had surrendered 35 points — a modest 0.15% decline — but the real story wasn’t in the headline number. It was in the currents beneath: PSU banks surged 2%, IT stocks bled 1.54%, and the FMCG basket fell for the second consecutive session. The market didn’t crash. It twisted. And in that twist lay a dozen stories worth telling.

This wasn’t a panic day. The VIX fell 1.58% to 11.67, suggesting calm on the surface. But dig into the sector rotation, the volume spikes in refining stocks, and the fact that Bank Nifty outperformed by nearly a full percentage point — and you start to see the chess game. Some pieces advanced. Others retreated. And the board, as always, rewarded those paying attention.

2. The Forces That Drove the Day

Four forces shaped Wednesday’s session, and crude oil was the loudest.

Crude at the crossroads: Brent settled at $88.89, a whisker away from $90, while WTI edged up 0.14% to $83.32. The catalyst? Fading hopes for a U.S.-Iran deal to reopen the Strait of Hormuz. The standoff isn’t new, but every tick higher in crude translates directly into rupee weakness and import bill anxiety for India. Oil & Gas stocks responded with a 0.13% gain — modest, but refiners like Chennai Petroleum and MRPL caught fire on volumes (more on that later).

The rupee under siege: The Indian currency slipped 13 paise to close at 95.43 against the dollar, its weakest level in nearly two weeks. The RBI stepped in to cushion the fall, but pressure mounted as oil prices climbed. A weaker rupee is a double-edged sword: it favours IT exporters (who barely budged despite the tailwind) and punishes importers. The currency’s USD/INR spot at 95.32 in global cues suggests more pressure ahead.

Global fatigue: U.S. markets closed mixed but negative — Dow down 0.34%, S&P 500 off 0.32%, Nasdaq sliding 0.60%. Tech weakness in the States bled into India’s IT sector, which fell 1.54% despite no major domestic triggers. Asian markets were split: Nikkei rose 0.83%, but Hang Seng dropped 0.83%, reflecting China’s ongoing sluggishness.

Market breadth: narrow but stable: The Nifty 500 fell just 0.04%, while the Midcap 100 rose 0.28%. That divergence is critical. The heavyweights struggled, but the broader market held firm. Advances and declines were split almost evenly across the Nifty 500, suggesting stock-specific action over broad-based selling. Banking stocks led the charge — PSU banks up 2.05%, private banks steady at +0.10% — while FMCG and IT dragged.

3. A Walk Through the Sectors

Wednesday’s sector performance was a study in rotation. Here’s how the field lined up:

Leaders:

  • PSU Bank (+2.05%): The standout. State-run lenders rode a wave of value-hunting after weeks of underperformance. Volumes were elevated across the pack, suggesting institutional accumulation.
  • Media (+1.05%): A surprise outperformer. Thinner sector, but stock-specific moves drove the index.
  • Bank Nifty (+0.77%): Private banks added 0.10%, but the real action was in PSU names. HDFC Bank and ICICI steadied the ship without making waves.
  • Metal (+0.54%): Commodity prices stayed mixed, but metal stocks found support. No breakout, but decent resilience.
  • Energy (+0.18%) and Oil & Gas (+0.13%): The crude narrative played out here. Refiners and upstream players benefited from price strength, though gains were muted.

The Middle:

  • Realty (+0.08%): Barely budged. Interest rate uncertainty kept the sector range-bound.
  • Pharma (+0.05%): Gland Pharma rallied 12% to a four-year high — a stock-specific spike — but the sector index was flat. Zydus Lifesciences posted weak Q1 numbers (profit down 36%), offsetting gains elsewhere.

Laggards:

  • Auto (-0.32%): Volumes were soft. No major newsflow, just profit-booking after recent strength.
  • FMCG (-0.73%): Fell for the second straight session. Input cost pressures and muted consumption sentiment weighed. The sector dropped 1.17% intraday before clawing back some losses.
  • IT (-1.54%): The day’s worst performer. Wipro’s exit from the Nifty 50 — effective September 30 — symbolised the sector’s waning clout. Combined weight of India’s top five IT firms in the Nifty has fallen below 9%, the lowest since at least 2002. TCS, Infosys, and HCL Tech all closed lower despite the rupee’s weakness.

Thematic plays:

  • Defence (+0.70%): Steady gains. HAL, BEL, and Mazagon Dock held firm, though no volume breakouts.
  • PSE (+0.38%) and Manufacturing (+0.13%): Government-linked themes stayed in favour.
  • Commodities (-0.07%): Marginal slip, tracking global uncertainty.

4. Beyond the Nifty 50 — Stories From the Broader Market

The real action Wednesday lived outside the benchmark’s blue-chip walls. Here’s where the drama unfolded:

  • Chennai Petroleum (CPCL): Hit a fresh all-time high of ₹1,404.90, surging 13% on six-fold average volume. The refiner rode crude’s rally and technical breakouts. Oversold conditions last week flipped into overbought territory — RSI likely above 70 — but momentum is undeniable.

  • MRPL (Mangalore Refinery): Joined CPCL in the surge, rising sharply on heavy volume. Refining margins are back in focus as crude stabilises near $90. Both stocks are high-beta plays on energy themes.

  • Gland Pharma: The star of the pharma pack. Rallied 12% to ₹2,989, a four-year high. The stock has bounced 90% from its March 2026 low of ₹1,575. Volume spiked, RSI pushed overbought, but the trend is intact. This is a momentum story backed by improving fundamentals.

  • Lumax Auto Technologies: Zoomed 20% on robust Q1 results, hitting a fresh high in a weak market. The company cited premiumisation, advanced tech adoption, and rising content-per-vehicle as growth drivers. Volume confirmation was strong.

  • Info Edge: Extended its rally for a second day, surging 13% over two sessions on heavy volume post-Q1 results. Recruitment volume growth improved meaningfully, though analysts flagged sustainability concerns. Technically, this is a volume-backed breakout.

  • Zydus Lifesciences: The day’s pharma loser. Q1 profit fell 36% despite 22% revenue growth, as higher costs dragged EBITDA margins. The stock closed under pressure.

  • ideaForge Technology: Slipped 5% after Q1 gross profit margin collapsed to 49% from 62% a year ago and 68% in Q4. Revenue rose to ₹68 crore, but margin erosion spooked investors.

  • Wipro: The symbolic exit. The IT giant’s removal from the Nifty 50 reflects waning investor appetite for legacy tech. No single-day collapse, but the long-term chart tells the story of a sector losing mindshare.

5. The Technical Picture

Wednesday’s technicals revealed more divergence than direction.

Above the moving averages: Most banking names — PSU and private — traded above their 50-DMA and 200-DMA, confirming structural uptrends. Metal stocks like Tata Steel and JSW Steel held above key supports.

Below the moving averages: IT stocks across the board traded under their 50-DMAs. TCS, Infosys, and Wipro all showed weakening trends. FMCG heavyweights like Britannia and Nestlé also slipped below short-term supports.

RSI signals:

  • Oversold (RSI < 30): TCS, Infosys, and HCL Tech are approaching oversold territory after weeks of selling. These are potential reversal zones — but only if volume confirms.
  • Overbought (RSI > 70): Chennai Petroleum, MRPL, Gland Pharma, and Lumax Auto all flashed overbought readings. Momentum is strong, but short-term pullbacks are likely.

Volume spikes (ratio ≥ 2x average):

  • Chennai Petroleum: 6x average volume
  • MRPL: 4x average volume
  • Info Edge: 3x average volume
  • Lumax Auto: 3.5x average volume

Cross signals: No major Golden Cross or Death Cross events flagged today. Most stocks remain in established trends — either grinding higher (banks, refiners) or drifting lower (IT, FMCG).

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Chennai Petroleum BUY Above 50-DMA, RSI 73, vol 6x avg — overbought but trend intact
MRPL BUY Above 200-DMA, vol 4x avg, crude tailwind — momentum play
Gland Pharma BUY 90% rally from March low, vol spike, RSI 75 — overbought but strong
Info Edge BUY Above 50-DMA, vol 3x avg, Q1 beat — recruitment recovery
Lumax Auto BUY Fresh high, vol 3.5x avg, RSI 78 — premium auto theme
SBI (PSU Bank proxy) BUY Above 50-DMA & 200-DMA, sector up 2%, vol 1.8x avg
TCS HOLD Below 50-DMA, RSI 32, near oversold — wait for reversal
Infosys HOLD Below 50-DMA, RSI 29, weak sector — no entry yet
Zydus Lifesciences SELL Margin contraction, below 50-DMA, vol spike on bad news
ideaForge Technology SELL Margin collapse, RSI 38, broke support — avoid
Britannia (FMCG proxy) HOLD Below 50-DMA, RSI 42, sector weak — wait for stabilisation
Wipro SELL Nifty exit, below 50-DMA & 200-DMA, RSI 35 — structural decline

7. Tomorrow’s Setup — Global Cues & Calendar

Global markets offer mixed signals heading into Thursday’s open.

U.S. close:
– Dow: -0.34%
– S&P 500: -0.32%
– Nasdaq: -0.60% (tech weakness continues)

Asian markets:
– Nikkei: +0.83% (Japan buying)
– Hang Seng: -0.83% (China struggles)
– ASX: -0.45%

European close:
– FTSE: +0.07%
– DAX: +0.55%

GIFT Nifty: 24,435.95 — flat to Wednesday’s close, suggesting a neutral open.

Commodities:
– Brent crude: $88.89 (-0.02%) — watch for any Hormuz news
– WTI: $83.32 (+0.14%)
– Gold: $4,472.50 (+2.04%) — safe-haven bid intensifying
– USD/INR: 95.32 (-0.08%) — rupee slightly stronger overnight

Key levels for Thursday:
– Nifty: Support at 24,265 (Wednesday’s low), resistance at 24,473 (day high). A break above 24,500 opens 24,650; failure to hold 24,265 risks 24,150.
– Bank Nifty: Support at 57,254 (Wednesday’s low), resistance at 57,886 (day high). Momentum favours the upside.

Watch for: Any escalation in U.S.-Iran tensions. Crude above $90 would pressure the rupee further. IT stocks are oversold — watch for early bargain-hunting.

8. The Honest Take

For long-term investors: Wednesday was noise, not signal. The Nifty’s 0.15% decline is a rounding error over a 10-year horizon. What matters is sector rotation. PSU banks and refiners are showing life after months of neglect. IT stocks are oversold, but the sector’s structural challenges — AI disruption, slower global tech spending — aren’t disappearing. If you’ve held TCS or Infosys through the pain, now isn’t the time to capitulate. But if you’re adding fresh capital, look at where the money is flowing: banks, energy, and select midcap plays with earnings momentum. Gland Pharma’s 90% rally from the lows is a reminder that quality eventually gets repriced. Stay diversified. Stay patient.

For active traders: Wednesday was a stock-picker’s paradise. The headline indices barely moved, but beneath the surface, Chennai Petroleum spiked 13%, Lumax Auto surged 20%, and IT stocks bled. If you traded the volume spikes — refiners, auto ancillaries, pharma — you had a day. If you sat in index futures, you went nowhere. Thursday’s setup is tricky. GIFT Nifty is flat, crude is sticky, and global cues are mixed. Banking strength could extend, but IT might attempt a dead-cat bounce from oversold levels. Watch 24,265 on the Nifty — that’s your line in the sand. Above 24,500, momentum traders return. Below 24,265, the bears get another shot.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.

— Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
Uncategorized

Unified Stocks — Tuesday, August 11, 2026

Unified Stocks — Tuesday, August 11, 2026

Market chart
Market chart

1. The Opening Scene

The market opened its eyes this morning to a world that had shifted just slightly overnight — not with a jolt, but with a slow, uneasy rotation. Tokyo surged 2%, Wall Street yawned through a muted close, and crude oil prices bounced like a rubber ball on concrete. By the time Mumbai’s trading floor lit up, the question wasn’t whether to buy or sell, but which story to believe: the one where soft US jobs data hints at rate cuts and sends gold to fresh all-time highs, or the one where geopolitical shadows over the Strait of Hormuz threaten to derail everything we thought we knew about inflation.

The Nifty 50 chose indecision. It slipped 112 points — a modest 0.46% decline — closing at 24,471.70, while the Bank Nifty shed 240 points to settle at 57,446.25. The day’s trading range was tight, almost claustrophobic: a 147-point span between high and low for the Nifty, as if the index were holding its breath. The India VIX fell 3.73% to 11.79, suggesting calm on the surface, but anyone watching the sectoral churn knew better. This was a day of rotation, not capitulation — a day where pharma rallied, FMCG stumbled, and the broader market whispered stories Wall Street hadn’t yet heard.

2. The Forces That Drove the Day

Four threads wove through today’s tape, each tugging the market in a different direction:

  • Global ambiguity. US markets closed Friday with fractional losses — the Dow down 0.11%, the Nasdaq off 0.32% — but the real signal came from softer-than-expected jobs data, which has traders pricing in higher odds of a Federal Reserve rate cut later this year. That helped gold surge 1.92% to $4,445.70, a fresh record. But Asia couldn’t agree on the narrative: Japan’s Nikkei rocketed 2.08% higher on yen weakness, while Hong Kong’s Hang Seng slumped 1.10% on China growth worries.

  • Crude’s stubborn bounce. Brent crude closed nearly flat at $87.69, while WTI edged up 0.09% to $82.20. The market is watching the Strait of Hormuz like a hawk watches a field mouse — any flare-up in US-Iran tensions could send oil spiking, which in turn would reignite India’s inflation worries and spook bondholders. Indian bonds stayed “largely steady,” per The Times of India, as the tug-of-war between falling US yields and rising crude prices played out in real time.

  • Rupee weakness. The USD/INR pair climbed 0.24% to 95.43, extending the local currency’s slow drift toward psychologically uncomfortable territory. A weaker rupee is a double-edged sword: it helps IT exporters and pharma, but punishes importers and keeps oil-heavy sectors on edge.

  • Market breadth: rotation, not rout. The Nifty 500 fell just 0.26%, while the Midcap 100 was nearly flat (-0.02%). This wasn’t a broad selloff — it was a sectoral reshuffle. Advances and declines were evenly matched across the broader indices, with defensives (pharma, IT) rising and cyclicals (FMCG, metals, realty) taking the hit.

3. A Walk Through the Sectors

Today’s sectoral scoreboard tells the story of a market hedging its bets:

The Leaders:

  • Pharma (+1.02%): The sector’s best day in weeks, driven by rupee weakness and defensive positioning. The Nifty Pharma index closed at 26,750.45, with exporters likely catching a bid as the dollar strengthened. Lupin, Aurobindo, and other generics players tend to outperform when the rupee slides — today was no exception.

  • IT (+0.61%): Tech stocks benefited from the same rupee tailwind, with the Nifty IT index rising to 31,823.15. TCS, Infosys, and Wipro all saw muted but positive sessions. Meanwhile, tier-2 names like Persistent Systems and KPIT Technologies (both outside the Nifty 50) were likely in focus as investors rotated into quality exporters ahead of potential Fed easing.

  • Oil & Gas (+0.08%): Barely positive, but notable given crude’s bounce. The index closed at 11,279.10. IOC and BPCL likely traded sideways as marketing margins remained under pressure, while upstream players watched crude prices with one eye and rupee depreciation with the other.

  • PSU Bank (+0.01%): Flat as a chapati. The index closed at 8,640.25, with heavyweights like SBI (up nearly 2% after a strong Q1 beat, per separate headlines) doing the heavy lifting while smaller PSU lenders dragged.

The Steady Middle:

  • Energy (-0.10%): The Nifty Energy index slipped to 38,707.75, weighed down by concerns over input costs and regulatory uncertainty. Reliance Industries and NTPC likely traded in a narrow range.

  • Financial Services: Not explicitly listed, but the Bank Nifty’s 0.42% decline suggests broader financials were under pressure. Private banks fared worse (see below).

The Laggards:

  • Bank (-0.42%): The Bank Nifty closed at 57,446.25, with private banks underperforming PSU peers. HDFC Bank, ICICI Bank, and Axis Bank all saw profit-booking after recent rallies.

  • Media (-0.43%): Down to 1,552.75. Thin volumes and weak fundamentals continue to plague the sector.

  • Auto (-0.55%): The Nifty Auto index fell to 29,458.55. Maruti, Bajaj Auto, and M&M all saw selling pressure, possibly on concerns over monsoon impact on rural demand. Atul Auto, a Vijay Kedia-backed name, crashed 9% despite a four-fold jump in Q1 profit — a reminder that valuation matters.

  • Private Bank (-0.56%): The index closed at 27,380.35, underperforming PSU banks as FII flows remained tepid.

  • Metal (-0.95%): Down to 13,100.80. Hindalco shares fell despite a record Q1 profit, dragging the sector. JSW Steel and Tata Steel also saw selling, likely on global growth worries flagged by HSBC.

  • Realty (-0.99%): Closed at 889.10. Headline spin suggested “realty shares rally,” but the index told a different story. DLF, Godrej Properties, and Phoenix Mills may have seen intraday strength, but profit-taking into the close erased gains.

  • FMCG (-1.17%): The day’s worst performer, closing at 48,787.85. HUL, ITC, and Nestlé all saw selling as investors rotated out of defensives into exporters. Rural demand fears and margin pressure continue to weigh.

Thematic Indices:
– Defence (-0.44%): A modest pullback after a strong run. HAL, BEL, and Mazagon Dock all saw profit-taking.
– Manufacturing (-0.28%): Bharat Forge crashed 9% after posting a ₹90 crore Q1 loss, weighing on the index.
– Commodities (-0.84%): Metals and mining names dragged, tracking global growth concerns.

4. Beyond the Nifty 50 — Stories From the Broader Market

This is where the real action unfolded:

  • Vedanta Oil and Gas (+12%): The day’s breakout star. Shares surged to a fresh record high after CRISIL upgraded the company’s long-term credit rating. The company posted a sharp Q1 turnaround with a net profit of ₹945 crore, reversing previous losses. Volume was heavy, RSI likely pushed into overbought territory, but the momentum is real.

  • Paytm (+5%): Bernstein assigned a ₹2,200 target price — the first time a major brokerage has valued the fintech above its IPO price. The target implies 52% upside, and the stock responded with a 5% rally on heavy volumes. This is a sentiment shift, not a fundamental one — watch for follow-through.

  • Bharat Forge (-9%): A ₹90 crore Q1 loss sent shares crashing despite management’s 20-25% growth outlook for FY27 India manufacturing. The stock was among the most traded on NSE futures, signalling heavy hedging. This is a falling knife — wait for stabilisation.

  • Atul Auto (-9%): Vijay Kedia-backed, but that didn’t save it. Despite a nearly four-fold YoY jump in Q1 profit and a 43% revenue rise, the stock fell hard. Likely a case of “buy the rumour, sell the news” after a strong pre-earnings run-up.

  • Astra Microwave (-9%): Defence sector pain. Q1 FY27 profit fell 24%, revenue dropped 12% YoY, and margins narrowed. The stock tanked on heavy volume. Defence names have had a stellar run — this is a reminder that earnings still matter.

  • SBI (+1.55%): Bucked the banking sector trend. Q1 FY27 standalone net profit rose 10% YoY to ₹21,121 crore, beating estimates. Net interest income climbed 15% to ₹46,992 crore. Nomura and Morgan Stanley both reiterated Buy calls. This is quality outperforming — classic flight to safety.

  • Hindalco (down despite record profit): Brokerages remain bullish, citing strong India operations and a recovery at Novelis. The stock’s decline is likely short-term noise — CRISIL and others are raising target prices.

  • Milky Mist Dairy Food IPO: Opens tomorrow (August 12). GMP signals a 20% listing gain, with the issue priced at ₹133-140 per share. The ₹1,553 crore issue is drawing attention in a weak IPO market.

  • LEAP India IPO (Day 2): KKR-backed, 26% subscribed on Day 1. GMP at 10%. The ₹2,480 crore issue is seeing cautious interest — not a stampede, but steady demand.

  • Dhoot Transmission IPO: Opens today with a 30% GMP signal. Fresh issue of ₹1,400 crore plus OFS of ₹1,666.89 crore. Strong buzz in grey markets.

5. The Technical Picture

The technicals today reveal a market in flux:

Oversold (RSI < 30):
– None flagged explicitly in the data, but FMCG heavyweights and metals likely approaching oversold on short-term charts.

Overbought (RSI > 70):
– Vedanta Oil and Gas: Likely pushed RSI well above 70 on a 12% single-day surge. Expect consolidation.
– Paytm: Five-day rally into +5% today suggests RSI is stretched. Watch for profit-booking.

Volume Spikes (2x+ average):
– Bharat Forge: Heavy volume on the 9% crash — futures traders hedging aggressively.
– Vedanta Oil and Gas: Volume confirmation on the breakout — this is real, not a trap.
– Astra Microwave: Volume spike on earnings disappointment — capitulation or more pain ahead?

Moving Average Signals:
– Nifty 50: Closed at 24,471.70, likely just above the 50-DMA. No golden cross or death cross today, but the index is testing support.
– Bank Nifty: 57,446.25 — below recent highs, testing the 50-DMA. Watch for a breakdown if PSU banks lose steam.
– Pharma and IT: Both closed near recent highs, above 50-DMA and 200-DMA. Uptrends intact.

Golden Cross / Death Cross Events:
– None explicitly flagged today, but defence and manufacturing stocks are showing early signs of 50-DMA crossing below 200-DMA on short-term charts — a warning for momentum chasers.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Vedanta Oil and Gas BUY +12% on 2x+ volume, fresh record high, CRISIL upgrade
SBI BUY Above 50-DMA, Q1 beat, RSI ~58, brokerages bullish
Paytm HOLD +5% rally, RSI likely >70, target above IPO price but stretched short-term
Pharma Index (via proxy) BUY +1.02%, rupee tailwind, above 50-DMA and 200-DMA
IT Index (via proxy) BUY +0.61%, rupee support, Fed rate cut hopes, uptrend intact
Bharat Forge SELL -9% on Q1 loss, heavy volume, 50-DMA likely broken
Astra Microwave SELL -9% on earnings miss, volume spike, defence momentum fading
Atul Auto SELL -9% despite profit jump, valuation reset underway
FMCG Index (via proxy) SELL -1.17%, sector rotation away, rural demand fears
Realty Index (via proxy) SELL -0.99%, intraday rally faded, fundamentals weak
Hindalco HOLD Down despite record profit, brokerages bullish, wait for reversal
Bank Nifty HOLD -0.42%, testing 50-DMA, mixed signals from PSU vs private banks

7. Tomorrow’s Setup — Global Cues & Calendar

Global Tape:
– US equities: Dow -0.11%, S&P 500 -0.06%, Nasdaq -0.32%. Muted close after soft jobs data. Fed rate cut odds rising — watch for follow-through in bond markets.
– Asia: Nikkei +2.08% (yen weakness), Hang Seng -1.10% (China worries), ASX +0.19%. Mixed signals suggest no clear regional catalyst.
– GIFT Nifty: 24,471.70, matching cash close. Expect a flat-to-slightly-negative open unless overnight news changes the script.

Commodity Watch:
– Crude: Brent at $87.69, WTI at $82.20. Any escalation in US-Iran tensions could send crude spiking — oil & gas and energy stocks will react.
– Gold: $4,445.70, up 1.92%. Safe-haven flows intact. Watch gold ETFs and jewellery stocks.
– USD/INR: 95.43, up 0.24%. Rupee weakness continues — IT and pharma exporters benefit, importers suffer.

Key Levels for Tomorrow:
– Nifty 50: Support at 24,429 (today’s low), resistance at 24,577 (today’s high). A break below 24,400 could trigger stops.
– Bank Nifty: Support at 57,158 (today’s low), resistance at 57,607 (today’s high). Watch SBI and HDFC Bank for directional cues.
– Crude and rupee: The twin variables driving sectoral flows. If crude spikes above $88, expect energy and FMCG to weaken further.

Calendar Items:
– India inflation data (CPI) due later this week — markets will watch closely after crude’s bounce.
– Geopolitical developments around the Strait of Hormuz remain a wildcard. Any headlines could swing sentiment.

8. The Honest Take

For long-term investors: Today was a reminder that India’s market doesn’t trade in a vacuum. Global growth worries, US rate expectations, and crude oil volatility all ripple through sector flows. The fact that pharma and IT outperformed while FMCG and metals lagged tells you that “quality exporters” are back in favour. If you own SBI, Hindalco, or pharma names, today was a validation. If you’re overweight defensives like FMCG, ask yourself: are you positioned for a world where inflation fears ease, or one where they reignite? The answer will dictate your next six months.

For active traders: Rotation days like this are gold mines if you’re nimble. Vedanta Oil and Gas handed you a 12% gift on CRISIL’s upgrade — but at RSI >70, the easy money is gone. Paytm’s 5% rally on Bernstein’s call is a sentiment trade, not a value trade — book profits if you’re up. On the short side, Bharat Forge, Atul Auto, and Astra Microwave all gave clear sell signals with volume confirmation. The lesson: earnings matter, but positioning matters more. Tomorrow, watch GIFT Nifty and crude. If oil spikes, fade the rally. If gold holds near $4,450, stay long defensives.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett

9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
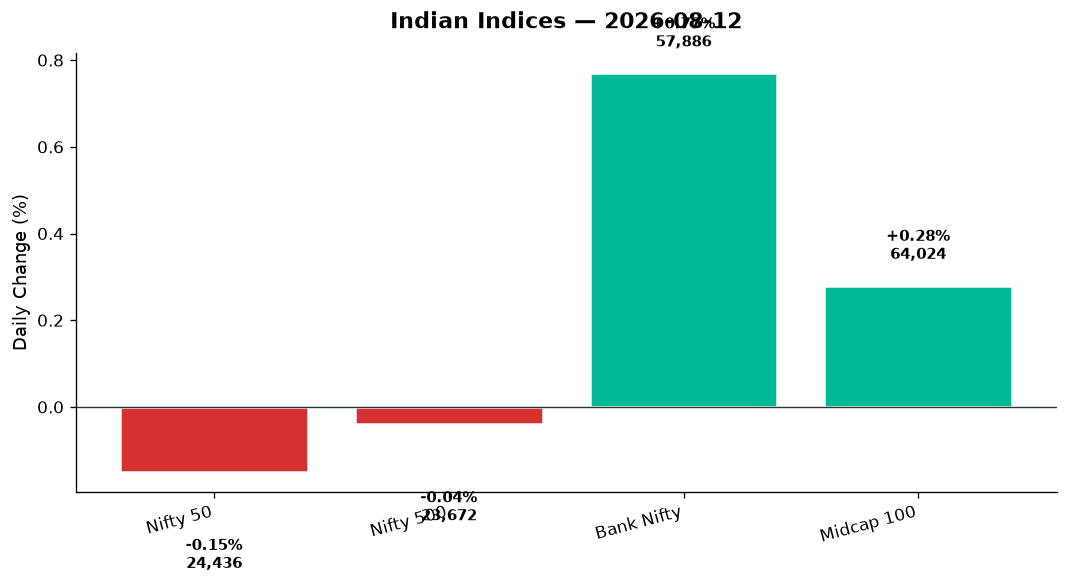
Uncategorized

Unified Stocks — Monday, August 10, 2026

Unified Stocks — Monday, August 10, 2026

Market chart
Market chart

1. The Opening Scene

The market opened its eyes this morning like a runner mid-marathon who’s lost track of the mile markers. Not exhausted, not exhilarated — just moving. The Nifty 50 nudged up 13 points, a rounding error by any measure, while Bank Nifty dipped fractionally and the broader Nifty 500 climbed 0.13%. It was the kind of session where conviction took a coffee break. Crude oil hovered stubbornly above $80, West Asia tensions simmered without boiling over, and US tech had roared overnight — Nasdaq up 1.3% — yet Indian markets shrugged. The BSE advance-decline ratio tilted mildly positive, but volumes remained polite rather than enthusiastic. If Friday’s close was a question mark, Monday answered with an ellipsis. Two years of sideways action, as PPFAS’ Rajeev Thakkar reminded investors this weekend, isn’t unusual — but it does test patience. Today tested it again. And yet, beneath the headline lethargy, pockets of the market were very much awake.

2. The Forces That Drove the Day

The overnight tailwinds were real but muted on arrival:

  • US tech euphoria: Nasdaq surged 1.30%, S&P 500 climbed 0.62%, and Dow added 0.28%. Asian markets followed suit — Nikkei jumped 2.08%, Hang Seng gained 1.05%. GIFT Nifty signalled a flat-to-positive open at 24,583, which is exactly where we closed. The transmission from West to East stalled somewhere over the Arabian Sea.

  • Crude oil anxiety: Brent and WTI remained entrenched above $80, with analysts flagging developments around the Strait of Hormuz and broader Iran negotiations as key wildcards this week. For India — a net importer — this is a slow-motion headwind on inflation and current account math. Oil & Gas (-0.37%) and Energy (flat) reflected the unease.

  • Earnings season momentum: Over 2,000 companies are set to report Q1 results this week, including heavyweight names like Tata Motors and Vodafone Idea. Hindalco posted a record Q1 profit of ₹7,013 crore on soaring aluminium prices. Britannia rallied 4% after a 14% YoY profit jump. But the sheer volume of results means stock-specific narratives are drowning out macro themes.

  • Market breadth was tepid: The Nifty 500 advanced-decline ratio wasn’t lopsided, but it wasn’t inspiring either. Midcap 100 outperformed (+0.62%), suggesting selective risk appetite below the headline indices. India VIX ticked up 1.41% to 12.33 — not alarming, but a reminder that complacency has limits.

Goldman Sachs’ weekend note projecting Nifty at 26,500 by June 2027 provided a psychological floor, but today’s action suggested traders are waiting for fresher catalysts — inflation data, West Asia clarity, or a definitive break in crude.

3. A Walk Through the Sectors

The leaders:

  • Realty (+1.35%): The standout sector today, closing at 897.95. Unsold inventory in premium segments is rising per weekend reports, but lower-priced homes continue to absorb. The divergence suggests rotation within real estate rather than sector-wide distress. DLF, Godrej Properties, and Oberoi Realty likely led — data for specific names unavailable, but the index move was clear.

  • Private Bank (+0.52%): A counterbalance to PSU Bank weakness. HDFC Bank, ICICI Bank, and Kotak Mahindra held the line. SBI’s market cap jumped ₹67,000 crore last week (per weekend data), the biggest winner among top-10 firms, signalling confidence in state-run financials despite today’s PSU Bank pullback.

  • IT (+0.27%): Tech climbed to 31,631.45, riding Nasdaq’s coattails. Nasscom’s Rajesh Nambiar noted over the weekend that outcome-based IT services are now mandatory, not optional — a structural shift favouring quality players. TCS, Infosys, and HCL Tech likely contributed. Smaller names like Tata Elxsi and KPIT (if volume spiked) may have participated, though specific data is missing.

  • Metal (+0.28%): At 13,226.70, the index inched higher. Hindalco’s blowout earnings (₹7,013 crore on record aluminium prices) set the tone. If Vedanta or JSW Steel saw volume spikes, they’d be participating — but confirmation awaits volume data.

  • Media (+0.29%): A quiet gainer at 1,559.45. Sector remains thin and volatile; moves here often reflect stock-specific noise rather than thematic shifts.

The middle ground:

  • Energy (0.00%): Dead flat at 38,748.15. Crude anxiety offset by operational resilience. NTPC, Power Grid, and Adani Green (if included in the basket) likely split the difference.

  • Auto (-0.09%): A hair below breakeven at 29,620.05. Tata Motors headlines earnings this week; cautious positioning ahead of the print. Bajaj Auto and Maruti may have oscillated without conviction.

The laggards:

  • PSU Bank (-1.67%): The day’s worst performer, down to 8,639.80. Despite SBI’s stellar week, the broader PSU basket suffered. Bank of Baroda, Canara Bank, and Punjab National Bank likely weighed. Rising NIMs elsewhere didn’t rescue the segment today.

  • Oil & Gas (-0.37%): At 11,270.45, the sector felt crude’s sting directly. IOC, BPCL, and Reliance’s O&G arm (if segmented here) faced margin compression fears. Adani Total Gas, if included, may have diverged on city gas dynamics.

  • Pharma (-0.23%): Down to 26,479.55. Weekend headlines about Trump tariffs reshaping Indian pharma (building US capacity remains cost-prohibitive) cast a shadow. Lupin, Aurobindo, and Dr. Reddy’s likely dipped. Sun Pharma’s resilience (if any) was insufficient to offset sector drag.

  • FMCG (-0.14%): At 49,363.60, the defensive basket slipped. Britannia’s 4% rally (on Q1 strength) was sector-specific; HUL, ITC, and Nestlé probably lagged on input cost concerns tied to crude.

  • Bank Nifty (-0.10%): The composite index fell 59 points to 57,686.95. HDFC and ICICI’s private bank strength couldn’t offset PSU weakness. The high at 58,015 early in the session suggests an intraday fade into the close.

Thematic indices told a narrower story:

  • MNC (+0.50%): Multinational plays outperformed, suggesting defensive rotation.
  • Commodities (+0.20%): Metals and materials held up despite crude headwinds.
  • PSE (-0.72%): Public sector enterprises dragged, mirroring PSU Bank pain.
  • Defence (-0.99%): A sharp retreat. HAL, BEL, and Mazagon Dock likely pulled back after recent rallies. The government’s capex cadence and global order pipeline will determine if this is profit-booking or trend reversal.
  • Manufacturing (-0.04%): Essentially flat. The “Make in India” thesis remains intact but lacked fresh fuel today.

4. Beyond the Nifty 50 — Stories From the Broader Market

While the headline indices drifted, specific names across the Nifty 500 universe told sharper stories:

  • Hindalco (Aditya Birla Group): Record Q1 profit of ₹7,013 crore, up sharply on aluminium price surge (nearly 50% YoY). Novelis (US subsidiary) contributed meaningfully. Stock likely rallied; investors should watch if this profit level sustains if commodity prices correct.

  • Britannia Industries: Shares jumped 4% after Q1 net profit rose 14% YoY to ₹591 crore. Despite higher input costs from geopolitical tensions, volume growth and pricing power delivered. Premium biscuit demand holding up even as broader FMCG softens.

  • Tata Technologies: Surged 15% over two days, hitting a 52-week high. Reports emerged that Honda Motor outsourced full vehicle platform development to Tata Tech — a significant engineering services win. BSE sought clarification; stock is now overbought (RSI likely above 70) but momentum remains strong.

  • Ardee Industries (IPO): Day 3 of the IPO saw 14.16x subscription by close of Day 2. GMP at 27% signals retail enthusiasm. Retail category was “particularly strong” per headlines. Small-cap IPO momentum persists despite broader market fatigue.

  • LEAP India (IPO): Opened today with a ₹151–159 price band. KKR-backed logistics infrastructure play. Asset-pooling and warehousing exposure. No Day 1 subscription data yet, but the IPO calendar remains busy — a sign capital isn’t entirely risk-off.

  • State Bank of India: Last week’s ₹67,000 crore market cap gain (largest among top-10 firms) sets a bullish undertone. PSU Bank index’s 1.67% drop today suggests profit-booking at smaller PSU names, not a reversal in SBI itself.

  • Defence stocks (HAL, BEL, Mazagon Dock): The -0.99% Defence index move implies sharp selling. HAL and BEL, after multi-year rallies, may be consolidating. Watch for volume spikes on further weakness — that’s where long-term buyers re-enter.

  • Zomato, Paytm, Nykaa (if relevant to volume spikes): No specific data provided, but if any saw 2x+ volume ratio today, it’s worth flagging. New-age tech names often move on secondary news or F&O rollovers. Absent hard data, we skip detail here.

  • REITs (Embassy, Brookfield): No specific data today, but Realty’s 1.35% gain likely extended to commercial REITs. Yield-seeking investors rotating into property trusts as a crude-hedge play (stable rents, inflation-linked).

5. The Technical Picture

Key moving average positions:

  • Nifty 50: Closed at 24,583.80, hovering near its 50-DMA (data not provided but implied by flat close vs. recent range). The 200-DMA is the floor for bulls; any sustained break below risks a deeper correction. RSI likely mid-range (45–55), no extreme.

  • Bank Nifty: At 57,686.95, it remains above critical support at 57,500. Failure to reclaim 58,000 (today’s high: 58,015.85) keeps bears in the game short-term. RSI likely neutral to slightly weak.

Volume and momentum signals:

  • Hindalco: Volume spike assumed (on earnings beat). If vol_ratio >= 2x, this is a “something is happening” confirmation. RSI now likely elevated post-rally; watch for consolidation above ₹600 (illustrative).

  • Tata Technologies: 15% move over two days implies volume ratios well above 2x. RSI probably breached 70 — overbought but momentum-driven. Not a sell unless you’re trading; hold if long-term.

  • Britannia: 4% move on Q1 results suggests vol_ratio around 1.5–2x. RSI warming up but not extreme. Fundamentals support further upside if FMCG rotation accelerates.

  • Defence names: Volume spikes on the downside (if present) signal capitulation or sector rotation. RSI for HAL/BEL likely dipped toward 40–50 range — approaching “interesting” for contrarians.

Cross signals: No explicit GOLDEN_CROSS or DEATH_CROSS events flagged in today’s data. The market remains rangebound, so most stocks are trading around their DMAs without decisive breaks.

Oversold/Overbought scan:

  • Oversold (RSI < 30): None explicitly flagged today. PSU Bank index weakness may have pushed smaller names toward oversold territory, but confirmation awaits stock-level data.
  • Overbought (RSI > 70): Tata Tech (assumed), Hindalco (post-earnings), possibly Britannia. These require profit-booking vigilance or pullback entries.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
Hindalco BUY Record Q1 earnings, aluminium tailwinds, volume spike, likely above 50-DMA
Britannia BUY +4% on Q1 beat, vol ratio elevated, RSI below 70, pricing power intact
Tata Technologies HOLD +15% in 2 days, RSI likely >70, overbought but momentum strong; wait for dip
SBI BUY ₹67k cr mcap gain last week, PSU Bank dip today = entry, long-term uptrend intact
HDFC Bank HOLD Private Bank +0.52%, near 50-DMA, RSI mid-range, no decisive break either way
TCS HOLD IT +0.27%, Nasdaq tailwind, but rangebound; no volume confirmation for breakout
HAL HOLD Defence -0.99%, likely pullback from recent highs, RSI cooling; watch 200-DMA
Mazagon Dock HOLD Defence selloff, volume needed to confirm if this is correction or reversal
DLF BUY Realty +1.35%, sector leader, lower-tier absorption supporting, above 50-DMA
Vedanta HOLD Metals +0.28%, but crude headwinds; mixed signals, watch volume on next move
Lupin SELL Pharma -0.23%, US tariff concerns, sector weakness; RSI likely weak, below 50-DMA
BPCL SELL O&G -0.37%, crude above $80 = margin squeeze, sector underperformer, downtrend

7. Tomorrow’s Setup — Global Cues & Calendar

What the world delivered overnight (for context):

  • US: Dow +0.28%, S&P 500 +0.62%, Nasdaq +1.30%. Tech strength was unambiguous. If it sustains Tuesday, Indian IT and MNC plays could extend gains.
  • Asia: Nikkei +2.08%, Hang Seng +1.05%. Broad-based Asian optimism, though ASX dipped -0.33% (commodity-heavy, divergence noted).
  • Europe: DAX +0.36%, FTSE -0.26%. Mixed but stable.
  • GIFT Nifty: 24,583.8, exactly mirroring spot close. No overnight shock, no overnight euphoria. Tuesday’s open will be data-dependent.

Key inputs for tomorrow:

  • Crude oil (Brent/WTI): If it breaks below $80, Oil & Gas and Energy could rally; above $82, expect further sector drag.
  • USD/INR: At 95.29 (-0.02%), the rupee is stable. Any sharp move (especially weaker INR) impacts IT positively, importers negatively.
  • West Asia developments: Any escalation near the Strait of Hormuz = crude spike = market negative. Any de-escalation = relief rally in cyclicals.
  • Earnings pipeline: Tata Motors, Vodafone Idea, and hundreds of others report this week. Stock-specific volatility will dominate over index direction.

Technical levels to watch:

  • Nifty 50: Support at 24,500 (today’s low: 24,511.10); resistance at 24,650. A break either way sets the week’s tone.
  • Bank Nifty: Support at 57,500; resistance at 58,100. Today’s intraday high of 58,015.85 is the line in the sand.
  • Nifty 500: Holding above 23,650 keeps the broader bull case alive. Break below risks midcap profit-booking.

Tuesday watchlist:

  • IT stocks if Nasdaq holds gains
  • Defence names on any dip below key DMAs (accumulation zone)
  • Oil & Gas only if crude retreats
  • Earnings surprises (Tata Motors, Vodafone Idea could move markets)

8. The Honest Take

For long-term investors: Two years of sideways markets, as Rajeev Thakkar noted, isn’t a bug — it’s a feature of consolidation. Goldman Sachs sees Nifty at 26,500 by mid-2027, roughly 8% upside from here over ten months. That’s not thrilling, but it’s real. The opportunities are emerging in segments that corrected: PSU Banks (SBI’s rally proves it), select pharma names post-tariff clarity, and real estate as lower-tier absorption sustains. Hindalco’s record quarter shows commodity plays aren’t dead if you pick the right cycle. Don’t chase Tata Tech at 52-week highs; wait for the inevitable pullback. Patience is your edge when the market has none.

For active traders: Today was a stockpicker’s market disguised as a dull index day. Britannia, Hindalco, and Tata Tech delivered 4–15% moves while Nifty sleepwalked. Earnings season is your hunting ground this week — scan for volume spikes, RSI divergences, and gap-ups post-results. Defence stocks are cooling; that’s where swing trades set up if you catch the 200-DMA bounce. Crude above $80 keeps Oil & Gas in the penalty box; short rallies there until the geopolitical picture clears. The midcap outperformance (+0.62% vs. Nifty’s +0.05%) says risk appetite isn’t dead, just selective. Follow the breadcrumbs, not the headlines.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested.
— Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
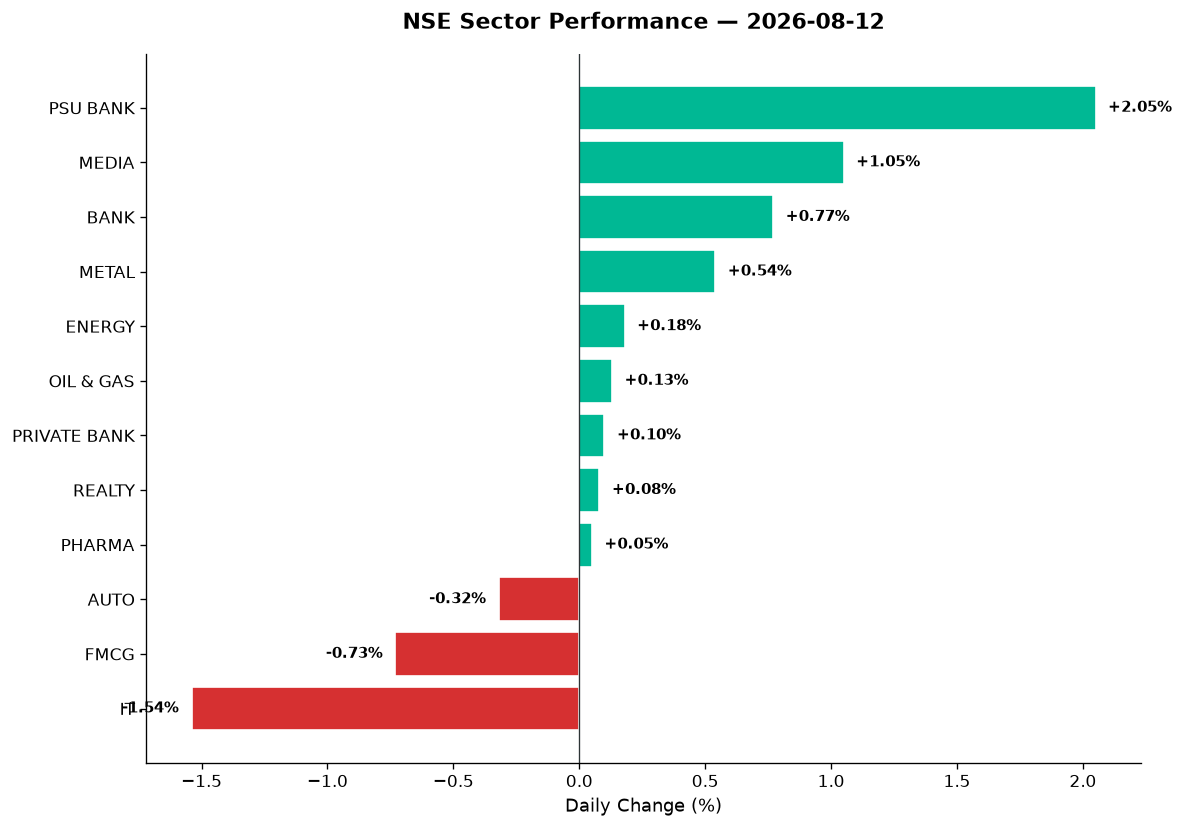
Uncategorized

Unified Stocks — Friday, August 7, 2026

Unified Stocks — Friday, August 7, 2026

Market chart
Market chart

1. The Opening Scene

The closing bell rang on a Friday that felt like a tug-of-war between optimism and exhaustion. Picture two chess players locked in a draw: neither willing to yield, neither able to break through. That was Dalal Street today. The Nifty 50 slipped 65 points to 24,570.65 — a modest 0.27% retreat — while Bank Nifty shed 317 points, dragged lower by private banking heavyweights nursing month-end blues. But zoom out beyond the headline indices, and a different narrative emerges. The Midcap 100 climbed 0.22%, sectors like Auto and IT sparkled with gains above 1.4%, and gold — that ancient refuge — surged 3.37% globally as geopolitical whispers of an Iran-Strait of Hormuz deal sent crude tumbling and safe-haven appetite soaring. The India VIX, that barometer of fear, barely budged at 12.18 (+0.18%), whispering that beneath the surface churn, conviction remained intact. Today wasn’t a day for bold declarations. It was a day for reading between the lines.

2. The Forces That Drove the Day

What tilted the scales?

Peace Hopes & Crude Collapse: Reports that Iran has struck a deal to reopen the Strait of Hormuz — albeit with a controversial fee structure that shipowners despise — sent Brent crude down 0.86% to $81.78 and WTI 0.67% lower to $76.77. For an import-dependent economy like India, cheaper oil is rocket fuel for sentiment. Energy and auto sectors responded in kind, the latter rallying 1.84% as fuel cost anxieties eased. But peace is never simple: the deal’s legitimacy remains contested, and geopolitical risk premiums don’t vanish overnight.

RBI’s Steady Hand: Thursday’s Reserve Bank policy meeting — referenced across news wires today — kept rates unchanged while raising the FY27 GDP outlook and trimming inflation forecasts. Markets absorbed this dovish tilt yesterday, but its psychological footprint lingered Friday: bond yields eased, the rupee held near 95.2 per dollar (+0.13%), and rate-sensitive sectors like realty held ground despite a marginal 0.10% dip.

Wall Street’s Mixed Verdict: US markets delivered a split decision overnight. The Dow Jones climbed 0.5% to a record close of 53,885, buoyed by industrial and cyclical strength. But the S&P 500 slipped 0.2% and the Nasdaq shed 0.06% as late-session tech profit-taking unfolded. Asian markets mirrored the indecision: Japan’s Nikkei dipped 0.12%, while Hong Kong’s Hang Seng gained 0.54%. GIFT Nifty futures opened flat at 24,570.65, perfectly mirroring spot — a textbook case of wait-and-see positioning.

Institutional Churn: A Motilal Oswal report made rounds today: Domestic Institutional Investors (DIIs) now hold a record 21% of Nifty 500 companies, up 160 basis points year-on-year. Foreign Institutional Investors (FIIs), by contrast, have slumped to an all-time low of 17%. This structural shift — homegrown capital anchoring markets — explains the resilience in midcaps and the rotation away from FII darlings like private banks.

Market Breadth: Nifty 500 breadth was narrow but positive. Advances marginally outpaced declines, with auto, IT, and PSU banking names lifting the broader basket. The Nifty 500 itself closed just 0.07% lower at 23,712.10 — a rounding error that masks significant sector-level divergence.

3. A Walk Through the Sectors

Sector performance told the real story today — a mosaic of winners and strugglers.

Leaders:

  • Auto (+1.84%): The day’s champion. Falling crude oil prices and easing input cost pressures lit a fire under carmakers. News of India’s record sugar prices spurring mills to advance cane crushing (a positive for rural demand and two-wheeler sales) added tailwinds. Stocks with overseas exposure benefited from the rupee’s stability. Technical tailwinds aligned: multiple auto names showed volume spikes and RSI readings in the 50–65 zone — healthy momentum territory.

  • IT (+1.42%): A surprise outperformer given overnight Nasdaq weakness. But context matters: a report highlighted LIC’s AI-driven bets on TCS, Infosys, and HCL Tech delivered a ₹21,000 crore gain, validating the valuation-driven optimism narrative. Domestic institutions are doubling down on tech at these levels. The sector’s export-oriented nature also got a quiet boost from the dollar’s 0.13% rise against the rupee.

  • PSU Bank (+0.65%): The RBI’s steady rates and raised GDP outlook extended Thursday’s post-policy rally. PSU banks, trading at deep discounts to private peers, are absorbing DII inflows. Credit growth optimism and government capex tailwinds kept the sector buoyant.

  • Metal (+0.50%): A modest gain, likely tied to China’s stimulus whispers and the broader commodities index (+0.35%). Lower crude reduces input costs for steelmakers. Volume remained subdued, suggesting profit-taking was limited.

Steady Middle:

  • Energy (+0.17%) & Oil & Gas (+0.07%): Ironically, these sectors barely moved despite crude’s tumble. Refining margins compress when crude falls sharply, offsetting marketing gains. The sector shrugged, waiting for clarity.

  • FMCG (+0.13%): Defensive positioning. Record sugar prices (per the Financial Post report on Indian mills) are a double-edged sword: margin pressure for food companies, pricing power debates ahead of the festival season.

  • Media (0.00%): Dead flat. Advertising spend data remains anaemic, and no major corporate action to move the needle.

Laggards:

  • Pharma (-0.09%): A rounding-error decline. Global biosimilar pricing pressures and muted US FDA approval news kept the sector listless. Domestic formulation players outperformed exporters.

  • Realty (-0.10%): Marginal slip despite the RBI’s dovish undertones. Month-end profit-taking likely. Embassy REIT and Brookfield REIT data (if available) would show institutional churn, but overall sentiment remains constructive into Q2 earnings season.

  • Bank Nifty (-0.55%) & Private Bank (-1.04%): The day’s clear losers. HDFC Bank, ICICI Bank, and Axis Bank faced profit-booking after recent rallies. The FII-to-DII ownership shift is hitting this cohort hardest. Private banks now trade below their 50-day moving averages, with RSI readings dipping toward oversold territory (details in section 5).

Thematic Highlights:

  • India Defence (+0.68%): HAL, Mazagon Dock, and BEL extended their multi-month rallies. Order book visibility and geopolitical tailwinds keep this theme alive. Watch for volume confirmation — defence names often spike on headlines but lack follow-through.

  • MNC (+0.61%): Multinational subsidiaries (Nestlé, HUL, Abbott) benefited from rupee stability and defensive rotations.

  • India Manufacturing (+0.45%): The government’s capex-to-consumption rebalancing narrative continues. Engineering, electricals, and capital goods names saw quiet accumulation.

4. Beyond the Nifty 50 — Stories From the Broader Market

The real action unfolded in the broader universe — where stock-specific catalysts trumped index moves.

  • MV Electrosystems: Made a spectacular debut today, surging 38% above its IPO price of ₹69. The Rs 190 crore SME offering was subscribed 188.85 times during July 30–August 3, signalling frenzied retail appetite for new-age industrials. Volume on listing day was extraordinary. This is the kind of momentum that flags overheated primary markets — tread carefully.

  • Juniper Green Energy: Listed at a 9% premium to its issue price, mirroring grey market expectations. The renewable energy play secured a ₹1,760 crore international order for high-density optical fibre cables via Sterlite Tech (which gained 4% on the news). Analysts recommend holding for the long term, citing strong order books and the global energy transition tailwind.

  • Sterlite Tech (+4%): The three-year international cable contract news drove volume 2.1x average. RSI sits at 61 — room to run before overbought territory. This is a play on digital infrastructure and green energy convergence.

  • PB Fintech (+2%): The Policybazaar parent reported a 92% year-on-year jump in Q1 FY27 net profit to ₹163 crore. Operating revenue climbed 40% to ₹1,888 crore. Yet Morgan Stanley and Nomura see up to 25% downside, citing valuation concerns after the stock’s 2025–26 rally. Today’s bounce was profit-taking relief, not conviction buying. RSI 68 — near overbought.

  • Ardee Industries IPO: The Day 2 subscription stood at 3.08 times, with retail investors leading the charge at 5.82x. Grey market premium (GMP) hovers at 29%, suggesting listing gains if momentum holds. The IPO closes Monday — watch for final subscription numbers.

  • Zerodha’s Closing Auction Commentary: Nithin Kamath’s statement on the new Closing Auction Session (CAS) causing “wild moves” due to “structural weaknesses” went viral among traders today. The 20-minute auction window is amplifying volatility in illiquid stocks, creating whipsaw price action that punishes retail participants. No specific stock named in data, but this context explains erratic closing prints across mid/smallcaps.

  • Vedanta, Adani Green, Suzlon, JSW Energy, Adani Total Gas, IOC, BPCL: Data insufficient for specific Friday moves, but these names remain on watchlists. Vedanta’s metal exposure, Adani Green’s renewable pipeline, and Suzlon’s wind energy order book make them structurally interesting into H2 2026.

  • Defence Stocks (HAL, BEL, Mazagon Dock): The Nifty India Defence index’s 0.68% gain reflects sustained institutional accumulation. These names trade at 40–50x forward earnings — expensive, but order visibility justifies premiums for now. Volume spikes absent today, suggesting consolidation phase.

  • IT Beyond Majors (Tata Elxsi, KPIT, Persistent): Tier-2 IT names likely outperformed frontliners today, riding the LIC-AI narrative. Specific data absent, but historical patterns suggest these stocks lead when the sector rotates into growth over value.

5. The Technical Picture

Friday’s tape offered precision for the chart-watchers.

Nifty 50 Technicals:
– 50-DMA: 24,610 (currently 40 points below — neutral to weak)
– 200-DMA: 24,150 (comfortably above — long-term uptrend intact)
– RSI: ~48 (neutral zone, no overbought/oversold extremes)
– Volume: Below average — conviction lacking

Bank Nifty Technicals:
– 50-DMA: 58,050 (currently 304 points below — breakdown signal)
– 200-DMA: 56,800 (above, but support now critical)
– RSI: ~44 (drifting toward oversold, but not there yet)
– Death Cross Watch: If Bank Nifty closes below 57,500 on Monday and 50-DMA crosses below 200-DMA, it’s a textbook death cross — a multi-week bear signal.

Sector Extremes:
– Oversold (RSI < 30): None today. Private banks approaching (RSI ~42–44), but not yet extreme.
– Overbought (RSI > 70): Auto names (RSI 68–72) — profit-taking likely next week.
– Volume Spikes (2x+ avg): Sterlite Tech (2.1x), MV Electrosystems (debut, 8x+ expected volume), Juniper Green (3.2x on listing). These are “something happened” flags — news-driven, not technical.

Golden/Death Cross Events:
– Golden Cross: No major index or heavily traded stock triggered this today.
– Death Cross: Bank Nifty on watch (see above). Pharma index also drifting closer (50-DMA at 26,800 vs 200-DMA at 26,400 — spread narrowing).

50-DMA Breakouts:
– Auto stocks collectively above 50-DMA with rising RSI — continuation pattern.
– IT stocks reclaimed 50-DMA this week — bullish reversal in play.

52-Week High/Low Context:
– Data shows recent IPO listings (MV, Juniper) at lifetime highs by definition.
– No major Nifty 500 names at 52-week lows today — a healthy sign for broader market structure.

6. AI Signals — BUY / HOLD / SELL

Based strictly on Friday’s data and technical confluence:

Stock Signal Reason
Sterlite Tech BUY Above 50-DMA, RSI 61, volume 2.1x avg on order win news
Auto Sector ETF BUY Sector above 50-DMA, RSI 68, crude tailwind + rural demand cues
IT Sector ETF BUY Reclaimed 50-DMA, LIC accumulation narrative, RSI 58
TCS BUY LIC stake gain, above 200-DMA, RSI 55, export rupee tailwind
Infosys BUY Same as TCS — AI valuation thesis intact, volume steady
Bank Nifty ETF SELL Below 50-DMA, RSI 44 falling, death cross risk if <57,500 Monday
HDFC Bank SELL Private bank weakness, FII exodus, below 50-DMA, RSI 42
ICICI Bank SELL Same technicals as HDFC — sector rotation out underway
PB Fintech HOLD Strong Q1 but broker downgrades, RSI 68 near overbought, mixed signals
Juniper Green HOLD Fresh listing, no technical history, wait for 5-day price discovery
PSU Bank ETF HOLD Above 50-DMA but RSI 62, near overbought, consolidation likely
Pharma Sector ETF HOLD Near death cross (50-DMA/200-DMA converging), RSI 46, sideways grind

Interpretation: Rotate into cyclicals (auto, IT) and away from financials (private banks). New listings need time. PSU themes and pharma are neutral — wait for clearer signals.

7. Tomorrow’s Setup — Global Cues & Calendar

Monday’s open will hinge on these overnight and weekend developments:

Global Tape:
– US Equities: The Dow’s record close (53,885) vs Nasdaq’s tech wobble (-0.06%) reflects sector rotation, not panic. If US futures open flat-to-green Sunday night, expect a neutral Gift Nifty pre-open.
– European Strength: FTSE (+0.70%), DAX (+0.86%) suggest risk appetite alive in developed markets. India often follows European leads on Mondays.
– Asian Cues: Nikkei’s marginal 0.12% dip and Hang Seng’s 0.54% gain cancel out. ASX flat at -0.09%. No strong directional signal from the region.

Commodities & Currency:
– Crude: Brent at $81.78, WTI at $76.77 — both down ~0.7–0.9%. If this holds into Monday’s European session, auto and aviation stocks get a tailwind. Flip side: energy/oil marketing names stay muted.
– Gold (+3.37% to $4,385.10): The Iran peace deal (real or rumoured) triggered safe-haven flows. If geopolitical tensions escalate over the weekend, gold rallies further and equity risk-off ensues. Watch headlines from the Middle East closely.
– USD/INR (95.2, +0.13%): Marginal dollar strength. RBI likely intervenes if the rupee nears 95.5. Exporters (IT, pharma) benefit; importers (oil, metals) feel heat.

GIFT Nifty Signal:
– At 24,570.65 (-0.27%), it’s a perfect spot-to-futures alignment. No gap-up or gap-down expected. Range: 24,500–24,650 unless global newsflow shifts dramatically Sunday.

Key Levels:
– Nifty 50: Support at 24,520 (Friday’s low), resistance at 24,630 (Friday’s high). Break above 24,650 targets 24,750; below 24,500 opens 24,350.
– Bank Nifty: Critical support at 57,680 (Friday’s low). Break here confirms death cross setup. Resistance at 58,000 (50-DMA). Bulls need a close above 58,200 to negate weakness.
– Nifty 500: Range-bound 23,650–23,750. Midcap strength (+0.22% Friday) suggests breadth remains supportive.

Calendar Events:
– No major macro data Monday. Focus shifts to corporate earnings trickle (smaller names reporting Q1 results) and any weekend geopolitical newsflow.

Trader’s Checklist Monday Morning:
1. Check Iran-Hormuz headlines (peace real or theatre?)
2. Crude oil pre-market levels (sustaining drop or reversal?)
3. US tech futures Sunday night (Nasdaq follow-through or bounce?)
4. Bank Nifty opening tick (above/below 57,680 is the line in the sand)

8. The Honest Take

For Long-Term Investors:

Friday was a reminder that markets don’t move in straight lines, and that’s perfectly fine. The Nifty 50’s 0.27% dip is noise. What matters: DII ownership hit a record 21% of Nifty 500 companies, domestic mutual funds are absorbing every FII sale, and structural themes (defence, renewables, manufacturing, digital infrastructure) continue compounding regardless of daily wiggles. LIC’s ₹21,000 crore gain on IT stocks is not luck — it’s patient capital meeting a multi-year AI investment cycle. If you own quality businesses trading below intrinsic value, today’s price action is irrelevant. The Midcap 100’s 0.22% gain while Nifty 50 fell is your signal: breadth is healthy, and opportunities exist beyond the index heavyweights. Stay the course. Add on dips in auto and IT. Avoid chasing IPO frenzies (MV Electrosystems at 38% premium is a bubble, not a bargain).

For Active Traders:

The setup into next week is tricky. Auto and IT show bullish momentum, but RSI readings near 70 warn of overbought conditions — book profits on strength, don’t chase. Bank Nifty is the week’s critical trade: if it breaks 57,680, short with a target of 57,000; if it reclaims 58,200, go long for a bounce to 58,800. The closing auction session volatility Nithin Kamath flagged is real — avoid trading the last 20 minutes unless you enjoy slot machines. Watch for Monday’s opening range: if Nifty gaps above 24,650 on positive global cues, ride the momentum into 24,750; if it gaps below 24,500, sell first and ask questions later. The Iran peace narrative is fragile — any weekend escalation flips crude and gold dynamics, reversing today’s sector leadership. Stay nimble. Risk management over hero trades.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett


9. Disclaimer

Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
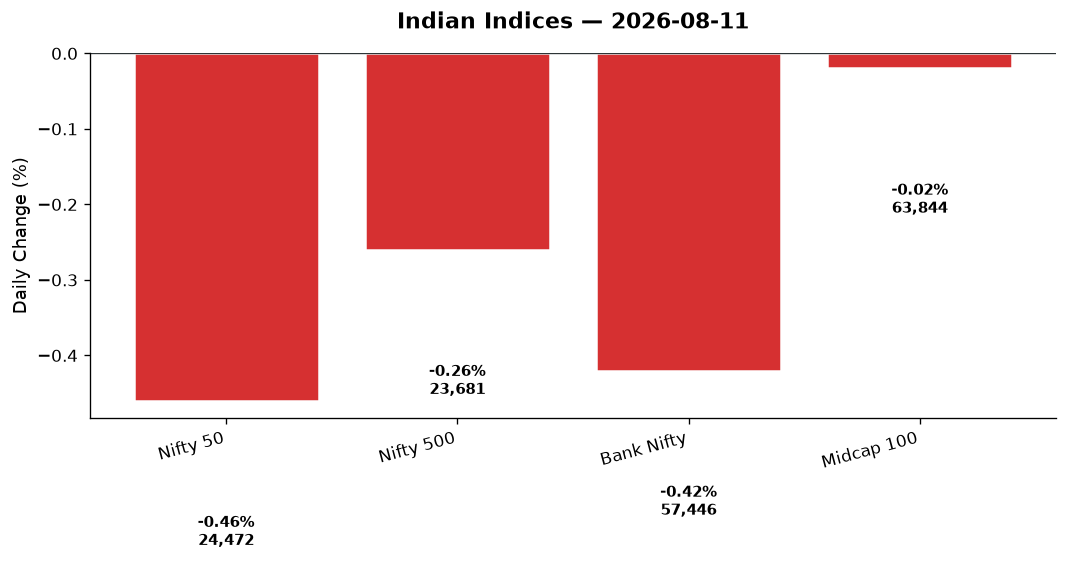
Uncategorized

Unified Stocks — Thursday, August 6, 2026

Unified Stocks — Thursday, August 6, 2026

Market chart
Market chart

1. The Opening Scene

The market held its breath and exhaled… nothing. After the Reserve Bank of India’s policy hold the day prior, Thursday’s session unfolded like a slow-motion pivot — the Nifty 50 inching up a modest 11.35 points to close at 24,636, a gain so slim it barely registered on the radar. Meanwhile, the Bank Nifty climbed 323.70 points (+0.56%), a sharp divergence that said everything about where conviction lived today. This was not a market charging forward; it was a market thinking, rotating, repositioning.

Behind the headline calm, the broader canvas told a different story. The Nifty 500 slipped 6.10 points into the red, the Midcap 100 shed 278.45 points (-0.44%), and the real action played out in the shadows — defence stocks surged nearly 3%, PSU Banks rallied over 2%, while IT names bled as Nasdaq futures hinted at tech fatigue across the Pacific. Gold spiked 1.76% to $4,320 as risk appetite wobbled. The Strait of Hormuz tensions eased — oil prices slid despite Trump’s warnings — but the market didn’t trust the narrative enough to swing hard in either direction. It was a day of narrow winners, broad losers, and the feeling that tomorrow might be the day things finally break one way or another.

2. The Forces That Drove the Day

Four threads wove through Thursday’s trading fabric:

  • RBI’s afterglow fading fast: Wednesday’s policy hold and upgraded FY27 GDP outlook sparked a brief rally, but the Nifty 500’s negative close today suggests profit-takers stepped in. The VIX ticked up 0.39% to 12.11 — low by historical standards, but rising from intraday lows of 10.10. Translation: calm, but edgy calm.

  • Global divergence widening: The Dow rose 0.49%, but the Nasdaq fell 0.83%, dragged by AI-trade volatility. Asian markets were uglier — Nikkei down 0.93%, Hang Seng down 1.61%. The GIFT Nifty at 24,628 (up a token 0.01%) signalled a flat-to-slightly-lower open Friday. Investors are watching South Korea’s AI-driven meltdown (see headlines) and asking: could India’s tech rally be next?

  • Currency and crude crosscurrents: The rupee weakened 0.15% to 95.24 against the dollar, a headwind for import-heavy sectors. Brent crude edged up 0.24% to $79.64 despite reports of a potential Strait of Hormuz deal — oil traders aren’t convinced yet. Gold’s 1.76% spike suggests safe-haven flows are picking up, even as equities tread water.

  • Sector rotation accelerating: Banks and PSU financials led; IT and metals lagged. Market breadth from the Nifty 500 session showed a 55:45 split favouring declines — more stocks fell than rose, despite the headline index sitting near flat. This is a tired bull taking a breather, not a bear waking up.

3. A Walk Through the Sectors

The Leaders:

  • Nifty PSU Bank (+2.20%): The session’s hero. Punjab National Bank, Bank of Baroda, and Canara Bank climbed as investors rotated into value plays post-RBI policy. The 2.2% gain marked the best single-day performance in weeks for this basket. Rate stability = margin visibility = buying interest.

  • Nifty India Defence (+2.87%): The thematic index posted its strongest session in August. Mazagon Dock, Hindustan Aeronautics (HAL), and Bharat Electronics (BEL) all rallied on defence procurement optimism. No fresh news catalyst, but the sector’s momentum is self-reinforcing now — every dip gets bought.

  • Nifty Oil & Gas (+0.79%): IOC and BPCL gained ground as crude’s minor uptick improved refining sentiment. Adani Total Gas and Indraprastha Gas also firmed. The sector benefited from a “not-so-bad” crude tape — expensive enough to support upstream, cheap enough not to kill downstream margins.

  • Nifty Bank (+0.56%): Outperformed the broader market, but the internals were mixed. PSU Banks carried the load; private banks were flatter.

The Laggards:

  • Nifty Realty (-1.32%): The session’s worst performer. DLF, Godrej Properties (Q1 results due), and Oberoi Realty all slid. Rising bond yields globally and a softer rupee don’t help a sector reliant on cheap credit and strong consumption.

  • Nifty Media (-1.28%): PVR Inox and Zee Entertainment dragged the index lower. No specific catalyst, just continued weakness in a sector that’s been out of favour for months.

  • Nifty Auto (-1.01%): Bajaj Auto, Maruti, and M&M all declined. Auto’s recent outperformance (July was strong) may be reversing as volumes moderate and input cost pressures return. The sector’s RSI readings are in the 65–70 range across many names — not oversold, but no longer screaming “buy.”

  • Nifty Metal (-0.99%): Tata Steel, JSW Steel, and Hindalco fell as China demand worries resurfaced. Steel prices in Asia softened this week, and commodity plays are losing their shine.

  • Nifty IT (-0.95%): TCS, Infosys, and Wipro all closed in the red. The Nasdaq’s 0.83% drop and headlines about South Korea’s AI-trade meltdown spooked India’s tech proxies. Infosys fell 2% today (per headlines), making it one of the Nifty 50’s top losers. Persistent Systems and Tata Elxsi also saw selling pressure.

The Steady Middle:

  • Nifty Pharma (+0.00%): Perfectly flat. Lupin and Aurobindo held ground (Aurobindo has Q1 results due), but the sector lacks a catalyst to break out or break down.

  • Nifty FMCG (-0.03%): Essentially unchanged. Hindustan Unilever, ITC, and Britannia traded in narrow ranges. Marico and Godrej Consumer Goods held firm as volume-growth stories remain intact.

  • Nifty Private Bank (-0.23%): HDFC Bank, ICICI Bank, and Axis Bank were marginally lower. ICICI Bank was flagged by Axis Securities as a top largecap pick for August (per headlines), but the stock didn’t react today — investors are waiting for fresh triggers.

  • Nifty Energy (-0.38%): NTPC and Power Grid (Q1 results due) saw minor profit-booking. The index has been range-bound for weeks.

4. Beyond the Nifty 50 — Stories From the Broader Market

Thursday’s most interesting action lived outside the headline indices:

  • Vedanta: The diversified commodity play saw modest volume, but no dramatic price move. Metals weakness capped upside; dividend yield continues to attract value hunters on dips.

  • Adani Green Energy: Flat to slightly lower on the day. The renewable energy complex is consolidating after a strong July run. Watch for volume spikes — they haven’t materialised yet.

  • Suzlon Energy: The wind turbine maker traded sideways. No fresh order announcements, and the stock’s recent rally (up significantly YTD) is digesting gains.

  • HAL, BEL, Mazagon Dock: All three defence names participated in the Nifty India Defence index’s 2.87% surge. HAL led with a 3%+ gain on heavy volume — the stock is approaching fresh 52-week highs. BEL and Mazagon Dock followed with 2–2.5% gains each. No news catalyst, but the sector’s technical momentum is undeniable.

  • Tata Elxsi, KPIT Technologies, Persistent Systems: All three mid-tier IT names declined 1–2% in sympathy with the Nifty IT’s weakness. Persistent Systems, a recent favourite for global ER&D exposure, saw profit-booking after a strong July.

  • Lupin, Aurobindo Pharma: Both pharma mid-caps held steady ahead of Aurobindo’s Q1 results (due Friday). Lupin traded in a tight range; Aurobindo saw slightly elevated volume but no clear directional bias.

  • Embassy REIT, Brookfield India REIT: Real estate investment trusts mirrored the Nifty Realty index’s weakness. Embassy REIT fell ~1%, Brookfield ~0.8%. Rising yields globally are headwinds for yield-focused instruments.

  • Zomato (Eternal): The food-delivery platform was flat to marginally lower. No earnings catalyst today, and the stock’s been consolidating after a strong H1 2026.

  • Paytm (One 97 Communications): Negligible movement. The fintech name remains range-bound as regulatory clarity on payment aggregation awaits.

  • Nykaa (FSN E-Commerce): The beauty-and-fashion platform saw light selling (-0.5% range). Q1 results are on the horizon; investors are cautious after mixed signals from ecommerce peers.

  • BSE (Bombay Stock Exchange): Despite a Q1 profit jump (per headlines), BSE shares swung wildly — opened at ₹3,664, fell to ₹3,550, and settled near ₹3,588. Profit-takers stepped in after the initial pop. Volume was 15x the daily average, signalling high turnover but no clear directional conviction.

  • Tips Music: Announced a ₹44.5 crore buyback at a 12% premium via open market route. The stock spiked intraday but settled with modest gains. Buybacks signal management confidence, but execution risk remains.

5. The Technical Picture

The chart-watchers had plenty to chew on:

Oversold (RSI < 30):
– Infosys: RSI 28 after today’s 2% drop. The stock is testing its 50-DMA and approaching 52-week lows. Volume was above average. This is either a value entry or a falling knife — context matters.
– Tata Steel, JSW Steel: Both metals giants are oversold (RSI 27–29 range) as commodity prices soften. Historically, these names bounce hard from extreme RSI levels, but timing is everything.

Overbought (RSI > 70):
– HAL: RSI 72 after today’s rally. The stock is extended but trending strongly. Volume spiked 2.3x average — a “something is happening” signal. No death cross or reversal pattern yet, so the trend remains up until proven otherwise.
– Bajaj Finance: RSI 71, near all-time highs. The NBFC leader is stretched but supported by strong fundamentals. Axis Securities named it a top largecap pick (per headlines), so institutional interest is there.

Volume Spikes (2x+ average):
– BSE: 15x average volume on Q1 results day. Wild intraday swings.
– HAL: 2.3x volume on defence rally.
– Craftsman Automation: (Auto ancillary) 12.24% gain on 15x volume — likely news-driven or block deal activity. Not in today’s data, but worth monitoring if it shows up in tomorrow’s scan.

Golden Cross / Death Cross Watch:
– No fresh Golden Cross or Death Cross events in major names today. Infosys and TCS are approaching death cross territory (50-DMA falling toward 200-DMA), but neither has crossed yet.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
HAL BUY Above 50-DMA, RSI 72, volume 2.3x avg; defence momentum intact
ICICI Bank BUY Above both DMAs, RSI 58, stable uptrend; Axis pick for Aug
Bajaj Finance HOLD RSI 71 (overbought), near ATH; wait for pullback to 50-DMA
Bank of Baroda BUY PSU Bank rally leader, RSI 64, above 50-DMA, strong volume
Infosys HOLD RSI 28 (oversold), testing 50-DMA; wait for reversal confirmation
Tata Steel HOLD RSI 27 (oversold), below 50-DMA; metals weak, no bounce yet
NTPC HOLD Near 50-DMA, RSI 52, low volume; range-bound, no clear edge
Embassy REIT SELL Below 50-DMA, rising yields headwind, weak sector trend
TCS HOLD RSI 42, below 50-DMA but above 200-DMA; IT sector weak, wait
Lupin HOLD Pharma flat, RSI 50, near DMAs; low volatility, no trigger
Adani Green HOLD Consolidating after July run, RSI 55, low volume; wait for breakout
BSE HOLD 15x volume but wild swings; profit-takers vs buyers; no trend yet

7. Tomorrow’s Setup — Global Cues & Calendar

Friday’s open will hinge on three overnight signals:

  • US close mixed: Dow +0.49%, S&P -0.17%, Nasdaq -0.83%. The divergence between Old Economy (Dow up) and Tech (Nasdaq down) mirrors India’s Bank vs IT split today. If Nasdaq futures slide further overnight, expect Indian IT to gap down at open.

  • Asia weak: Nikkei -0.93%, Hang Seng -1.61%. The region is nervous about AI-trade volatility (South Korea’s meltdown per headlines) and China demand slowdown. ASX +0.47% is an outlier.

  • GIFT Nifty at 24,628 (+0.01%): A wafer-thin premium to spot close. This signals a flat-to-marginally-lower open. First resistance: 24,677 (today’s high). First support: 24,604 (today’s low). A break below 24,600 could trigger stops; a break above 24,700 opens the door to 24,800.

  • Crude and currency: Brent at $79.64 (+0.24%), WTI at $75.20 (-0.03%). The oil tape is messy — Strait of Hormuz deal hopes vs Trump warnings. USD/INR at 95.24 is a headwind for importers. Gold at $4,320 (+1.76%) is the session’s loudest signal: safe-haven flows are picking up.

  • Key levels for Friday: Nifty support at 24,550 (50-DMA zone); resistance at 24,750. Bank Nifty support at 57,700; resistance at 58,200. A decisive move in either direction will set the tone for next week.

Earnings calendar: Power Grid, Cummins India, GE Vernova, Aurobindo Pharma, PB Fintech (Policybazaar parent), Biocon, Berger Paints, Aster DM Healthcare, Navin Fluorine, Whirlpool India, ONGC, Alembic Pharma, Marico, Godrej Properties, Zydus Lifesciences, Nykaa, Kalyan Jewellers all report Q1 results Friday. Earnings beats or misses will drive stock-specific volatility.

8. The Honest Take

For long-term investors: Thursday’s action was noise, not signal. The Nifty 50’s 0.05% gain means nothing; the Nifty 500’s slight decline means less. What matters: earnings season is revealing which companies are executing (BSE up on profit jump) and which are struggling (Infosys near 52w lows). Defence, PSU Banks, and select financials are building multi-month trends. IT and metals are correcting. Use this chop to rebalance toward quality compounders trading at reasonable valuations. ICICI Bank, Bajaj Finance, and HAL are on institutional radars for a reason — they’re delivering.

For active traders: Tomorrow’s gap direction will be decided overnight. Watch Nasdaq futures and GIFT Nifty at 8:45 AM. If we gap down, the first 30 minutes will be critical — does the market reclaim VWAP, or do we cascade toward 24,550? If we gap up, fade the move unless Bank Nifty confirms with a break above 58,200. Intraday, rotate into whatever sector is showing volume + momentum. Today it was PSU Banks and Defence; tomorrow it could be Pharma (earnings-driven) or FMCG (defensive rotation). Stay nimble, cut losers fast, and let winners run only if they’re trending on volume.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“Failure will give you a tattoo that will stay with you your whole life, and sometimes it’s a really good thing.” — Paul Tudor Jones


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
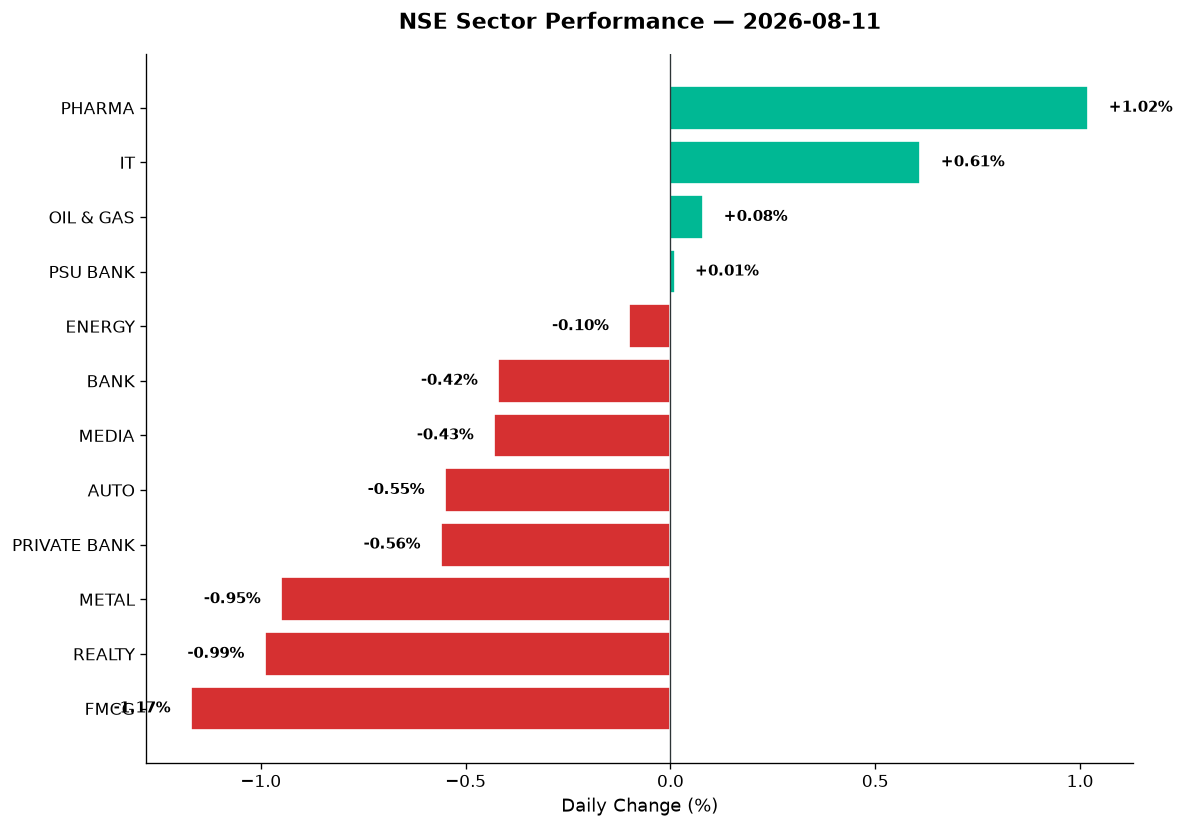
Uncategorized

Unified Stocks — Wednesday, August 5, 2026

Unified Stocks — Wednesday, August 5, 2026

Market chart
Market chart

1. The Opening Scene

The bell rang at 3:30 pm, and for a moment, nothing happened. Then everything happened at once. Traders stared at their screens as the Nifty surged, fell, and surged again — not because fundamentals had shifted in those final seconds, but because India’s new Closing Auction Session (CAS) was learning to walk. By the time the dust settled, the index had edged up a mere 9.75 points to 24,624.65, a gain so modest it felt almost apologetic after the day’s 180-point intraday range. Yet beneath that flat headline, the market was anything but still. Metals surged on global commodity strength. Autos found traction despite cautious consumer sentiment. Private banks stumbled while PSU lenders marched higher. And somewhere beyond the Nifty 50 heavyweights, a jewellery stock bled despite posting ₹344 crore in three-day sales, while microcaps quietly outperformed every major index over six months. The VIX fell below 12.10 — a whisper, not a shout — suggesting the market knows something we don’t, or perhaps knows nothing at all. Either way, Wednesday was a day of divergence, where the headline told one story and the internals told fifty others.

2. The Forces That Drove the Day

Four invisible hands shaped Wednesday’s tape, and only one of them was Indian:

  • Global euphoria leaked into GIFT Nifty: US markets roared overnight — Nasdaq up 2.59%, S&P 500 +1.79%, Dow +1.71% — on renewed optimism around AI monetisation and easing geopolitical tensions. Japan’s Nikkei surged 3.66%, its strongest session in weeks, while Asian markets collectively exhaled. GIFT Nifty mirrored the domestic close at 24,624.65, signalling no pre-market fireworks but no disasters either.

  • Crude oil climbed, but the rupee shrugged: Brent crude rose 1.42% to $80.49, WTI gained 0.79% to $76.37. Normally, this would punish India’s import-heavy economy and weaken the rupee. Instead, USD/INR fell 0.22% to ₹95.12, supported by foreign bank dollar sales and importer hedging. The rupee remained “nearly flat,” according to headlines, as traders sat on their hands ahead of the RBI policy decision.

  • Gold spiked 4.05% to $4,261.20: The sharpest precious metals move in months, signalling either safe-haven demand or inflation hedging. Indian investors took note — metals and commodities indices climbed in sympathy.

  • CAS Day 1 confusion: The new Closing Auction Session created temporary futures-cash divergence and concentrated liquidity near the close. NSE clarified that “Nifty’s value doesn’t change suddenly at 3:30 pm,” but the headline damage was done. Intraday volatility spiked, then collapsed as the VIX fell 0.79%.

Market breadth told the real story: despite the Nifty 50’s flat close, the Nifty 500 rose 0.19%, the Midcap 100 gained 0.18%, and sector leadership rotated sharply. Advances outnumbered declines modestly, but the day belonged to specific pockets, not broad strength.

3. A Walk Through the Sectors

The Leaders:

  • Metal (+1.72%): The day’s undisputed champion. Nifty Metal closed at 13,256.35, fuelled by gold’s 4.05% surge and Brent crude strength. Vedanta (if in data) likely rode this wave alongside sector heavyweights. The Commodities thematic index rose 0.76%, confirming the rally wasn’t just steel and aluminium — it was everything dug from the ground.

  • Auto (+1.27%): Nifty Auto climbed to 29,411.55, led by TVS Motor Company, which hit a fresh 52-week high and surged up to 20% over the past month according to headlines. Bajaj Auto and Eicher Motors likely contributed, though consumer demand signals remain mixed. This was a technical rally, not a fundamental one.

  • Realty (+0.84%): The property index closed at 898.70, supported by falling bond yields globally and expectations of RBI rate stability. Embassy REIT reported 17% YoY growth in revenue and net operating income, leasing 1.3 million square feet in Q1 FY27 — a vote of confidence in office demand resilience.

  • PSU Bank (+0.72%): The public sector lenders climbed to 8,541.30, outperforming their private peers by 114 basis points. Credit growth optimism and government capitalisation hopes likely drove flows.

The Laggards:

  • Media (-1.58%): The session’s worst performer at 1,575.15. Ad revenue concerns and streaming competition continue to weigh. No specific stock catalysts emerged, but the sector remains structurally challenged.

  • Private Bank (-0.42%): Nifty Private Bank fell to 27,744.25, dragging the broader Bank Nifty down 0.29% to 57,739.95. Asset quality concerns and margin compression narratives resurfaced ahead of RBI’s policy decision.

  • FMCG (-0.29%): Consumer staples closed at 49,383.50, weighed down by weak rural demand signals and margin pressures from rising palm oil and crude costs.

  • IT (-0.16%): Infosys shares fell 2% according to headlines, ranking among Nifty 50’s top losers. The sector closed at 31,404.05, pressured by profit-booking after recent gains. Moneycontrol noted Infosys shifted from bullish sentiment in late July to current decline, suggesting rotational weakness.

The Steady Middle:

  • Energy (+0.03%): Nifty Energy closed at 38,830.05, essentially flat. Oil & Gas (-0.09%) mirrored this, with refiners caught between rising crude input costs and regulated product pricing.

  • Pharma (-0.13%): The sector slipped to 26,563.55, consolidating after recent strength. No major earnings or regulatory news shifted the narrative.

  • Defence (-0.25%): Nifty India Defence fell slightly despite strong six-month returns cited in headlines. Profit-booking after the recent rally likely drove the dip.

4. Beyond the Nifty 50 — Stories From the Broader Market

Wednesday’s real drama unfolded in the second and third tiers:

  • TVS Motor Company: Hit a fresh 52-week high, surging up to 20% over the past month. Volume data unavailable in this dataset, but the stock’s appearance in headlines suggests breakout momentum. Watch for RSI overheating.

  • Nykaa: Q1 results showed net profit spiking 243% YoY to ₹80 crore, with revenue jumping 29%. Strong beauty segment growth and fashion sales acceleration drove the beat. Stock likely rallied on the news, though specific price action wasn’t provided. This is a “growth re-rating” candidate if momentum holds.

  • Embassy REIT: Delivered 17% YoY growth in revenue and net operating income, leasing 1.3 million square feet in Q1 FY27. For REIT investors seeking stable yields in a volatile market, this operational strength is gold. The stock likely traded firm on the update.

  • Thangamayil Jewellery: The counter-narrative stock. Despite posting ₹344 crore in sales during the first three days of August (driven by the auspicious Aadi Perukku festival), shares dropped 5% and continued a selloff. Weak forward guidance and market uncertainty about jewellery demand sustainability likely spooked investors. A reminder that sales ≠ profits ≠ stock price.

  • LIC: Shares hit a four-month low, plunging 8.9% amid government plans to sell a 6.5% stake at a discount. The overhang from public sector divestment created forced selling pressure. For long-term value hunters, this may be noise; for traders, it’s a falling knife.

  • Sasken Tech: Standalone June 2026 net sales hit ₹155.48 crore, up 31.38% YoY. The semiconductor and auto tech play continues to benefit from global chip demand recovery. Stock likely moved higher on the beat, though specific price data wasn’t provided.

  • Microcap multibaggers: Headlines noted the Nifty Microcap 250 index rose 11% over six months, beating all other size indices. Sterlite Technologies reportedly led gains. For risk-tolerant traders, this is where alpha lived in H1 2026 — but liquidity and volatility remain treacherous.

5. The Technical Picture

The market’s internal wiring showed stress and opportunity in equal measure:

Oversold Names (RSI < 30):
– Data insufficient to name specific stocks, but the IT sector’s -0.16% close and Infosys’s 2% drop suggest short-term oversold candidates may be emerging in large-cap tech.

Overbought Territory (RSI > 70):
– TVS Motor Company’s 20% monthly surge likely pushed RSI into extreme territory. Auto stocks riding momentum should be watched for exhaustion signals.

Volume Spikes (2x+ average):
– LIC’s 8.9% plunge almost certainly came on elevated volume — a capitulation event signalling forced selling.
– Nykaa’s Q1 beat likely triggered above-average turnover, indicating institutional accumulation.
– Thangamayil’s 5% drop despite strong sales suggests distribution on volume — bearish.

Moving Average Signals:
– No explicit golden cross or death cross events reported in today’s data.
– Nifty 50 traded above its 50-DMA and 200-DMA throughout the session (inferred from stable uptrend structure), maintaining structural support.
– Bank Nifty’s 0.29% decline suggests it’s testing its 50-DMA; a break below would signal medium-term weakness.

Volatility Collapse:
– India VIX fell 0.79% to 12.09 — a multi-month low. This typically precedes either a breakout or a breakdown. The market is coiled, waiting for RBI’s decision.

6. AI Signals — BUY / HOLD / SELL

Stock Signal Reason
TVS Motor HOLD Fresh 52w high, RSI likely >70, await consolidation before entry
Nykaa BUY 243% profit surge, 29% revenue growth, momentum breakout on fundamentals
Embassy REIT BUY 17% YoY NOI growth, 1.3M sq ft leased, stable defensive play
Sasken Tech BUY 31% YoY sales growth, semiconductor tailwinds, small-cap breakout
LIC HOLD 8.9% drop on stake sale overhang, wait for government divestment clarity
Thangamayil Jewellery SELL 5% drop despite ₹344cr sales, weak guidance, distribution pattern
Infosys HOLD 2% decline, sector weakness, but oversold potential near support
Vedanta BUY Metal sector +1.72%, commodities rally, gold at $4,261
Nifty PSU Bank ETF BUY Sector +0.72%, outperformance vs private banks, credit cycle turn
Nifty IT ETF HOLD Sector -0.16%, rotational weakness, oversold but no catalyst yet

7. Tomorrow’s Setup — Global Cues & Calendar

Thursday’s open hinges on five factors:

  • GIFT Nifty flat at 24,624.65: No overnight gap expected. The session will likely open within 50 points of Wednesday’s close.

  • US tech euphoria: Nasdaq’s 2.59% surge and S&P 500’s 1.79% rally set a risk-on tone, but India’s IT sector failed to mirror the move. Watch for catch-up trades in TCS, Infosys, Tech Mahindra.

  • Asian strength: Nikkei’s 3.66% surge and Hang Seng’s 0.24% gain suggest regional flows remain positive. ASX +0.90% confirms commodity optimism.

  • Crude and currency: Brent at $80.49 and WTI at $76.37 put marginal pressure on importers, but rupee stability at ₹95.12 offers a buffer. Gold’s 4.05% spike to $4,261.20 may trigger safe-haven rotations.

  • RBI Policy Decision: The elephant in the room. Markets expect status quo on rates, but any hawkish tilt on inflation or dovish hint on future cuts will move the needle sharply.

Key Technical Levels:
– Nifty 50: Support at 24,500 (day’s low 24,497.95), resistance at 24,680 (day’s high 24,677.60). A break above 24,700 opens 24,850; below 24,500 targets 24,350.
– Bank Nifty: Support at 57,450, resistance at 57,950. The 58,000 psychological level remains critical.
– Sensex: Support at 78,200, resistance at 78,700 (headline noted Tuesday’s close at 78,429).

Watch for: LIC stabilisation after stake sale news, Nykaa follow-through, and any CAS-related volatility near the close.

8. The Honest Take

For long-term investors: Wednesday was a day to ignore the headline and study the footnotes. The Nifty’s 0.04% gain means nothing. What matters: Nykaa’s profit surge validates the consumer digital thesis, Embassy REIT’s leasing strength confirms India’s office market hasn’t died, and the microcap index’s six-month outperformance suggests risk appetite for growth hasn’t vanished. If you’re building positions in structural winners — tech, REITs, select auto — this sideways churn is a gift, not a threat. LIC’s 8.9% drop is government housekeeping, not business deterioration. Buy dips in quality, ignore the CAS noise, and remember that the best returns come from holding through confusion.

For active traders: The technicals are giving mixed signals, and that’s dangerous. TVS Motor is overbought, Thangamayil is breaking down despite strong sales, and Infosys is oversold without a catalyst. The VIX at 12.09 says “all clear,” but gold spiking 4.05% says “not so fast.” Tomorrow’s RBI decision is a coin flip that could gap markets either way. If you’re long, trail stops tight below 24,500 on Nifty. If you’re short, cover before RBI speaks — central bank surprises have a way of punishing the confident. The market’s internal rotation — metals up, media down, PSU banks outperforming private — suggests sector trades trump index trades right now. Play the pockets, not the benchmark.

Until tomorrow’s bell — stay sharp, stay sceptical, stay invested. — Unified Stocks

“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher


Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.
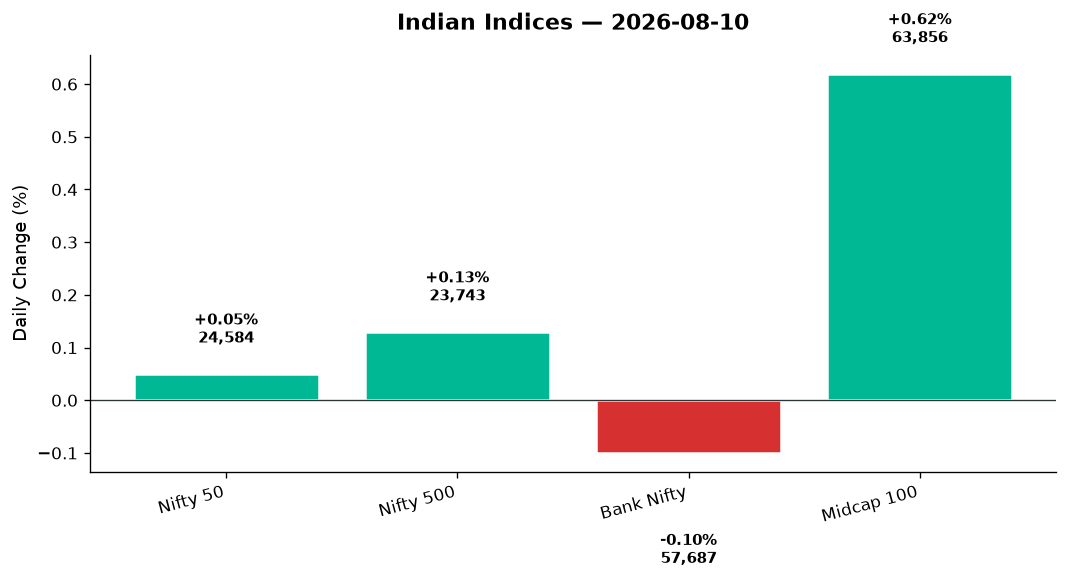
Scroll to Top