Unified Stocks — Thursday, August 6, 2026
1. The Opening Scene
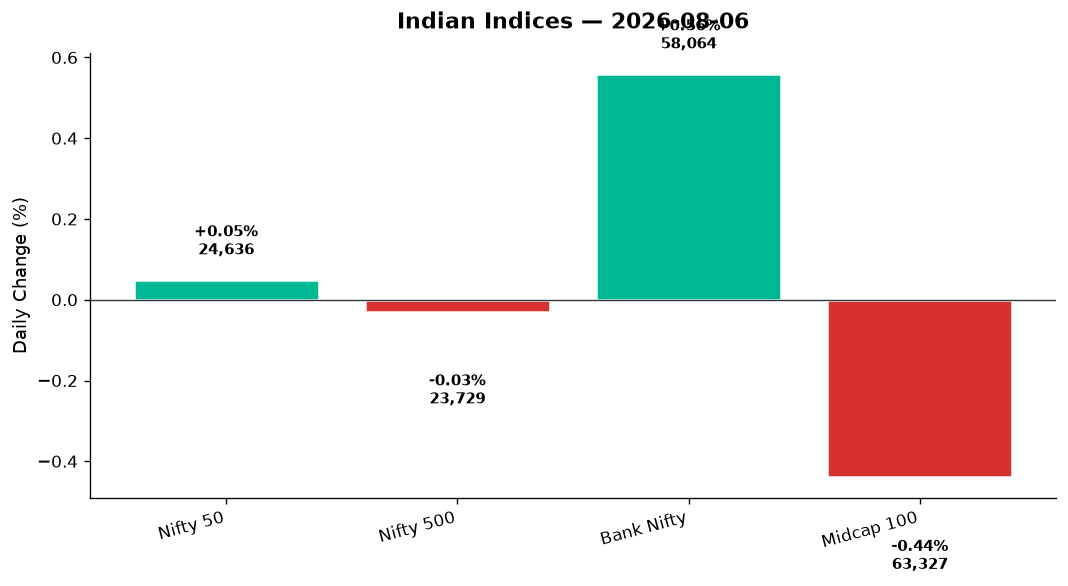
The market held its breath and exhaled… nothing. After the Reserve Bank of India’s policy hold the day prior, Thursday’s session unfolded like a slow-motion pivot — the Nifty 50 inching up a modest 11.35 points to close at 24,636, a gain so slim it barely registered on the radar. Meanwhile, the Bank Nifty climbed 323.70 points (+0.56%), a sharp divergence that said everything about where conviction lived today. This was not a market charging forward; it was a market thinking, rotating, repositioning.
Behind the headline calm, the broader canvas told a different story. The Nifty 500 slipped 6.10 points into the red, the Midcap 100 shed 278.45 points (-0.44%), and the real action played out in the shadows — defence stocks surged nearly 3%, PSU Banks rallied over 2%, while IT names bled as Nasdaq futures hinted at tech fatigue across the Pacific. Gold spiked 1.76% to $4,320 as risk appetite wobbled. The Strait of Hormuz tensions eased — oil prices slid despite Trump’s warnings — but the market didn’t trust the narrative enough to swing hard in either direction. It was a day of narrow winners, broad losers, and the feeling that tomorrow might be the day things finally break one way or another.
2. The Forces That Drove the Day
Four threads wove through Thursday’s trading fabric:
-
RBI’s afterglow fading fast: Wednesday’s policy hold and upgraded FY27 GDP outlook sparked a brief rally, but the Nifty 500’s negative close today suggests profit-takers stepped in. The VIX ticked up 0.39% to 12.11 — low by historical standards, but rising from intraday lows of 10.10. Translation: calm, but edgy calm.
-
Global divergence widening: The Dow rose 0.49%, but the Nasdaq fell 0.83%, dragged by AI-trade volatility. Asian markets were uglier — Nikkei down 0.93%, Hang Seng down 1.61%. The GIFT Nifty at 24,628 (up a token 0.01%) signalled a flat-to-slightly-lower open Friday. Investors are watching South Korea’s AI-driven meltdown (see headlines) and asking: could India’s tech rally be next?
-
Currency and crude crosscurrents: The rupee weakened 0.15% to 95.24 against the dollar, a headwind for import-heavy sectors. Brent crude edged up 0.24% to $79.64 despite reports of a potential Strait of Hormuz deal — oil traders aren’t convinced yet. Gold’s 1.76% spike suggests safe-haven flows are picking up, even as equities tread water.
-
Sector rotation accelerating: Banks and PSU financials led; IT and metals lagged. Market breadth from the Nifty 500 session showed a 55:45 split favouring declines — more stocks fell than rose, despite the headline index sitting near flat. This is a tired bull taking a breather, not a bear waking up.
3. A Walk Through the Sectors
The Leaders:
-
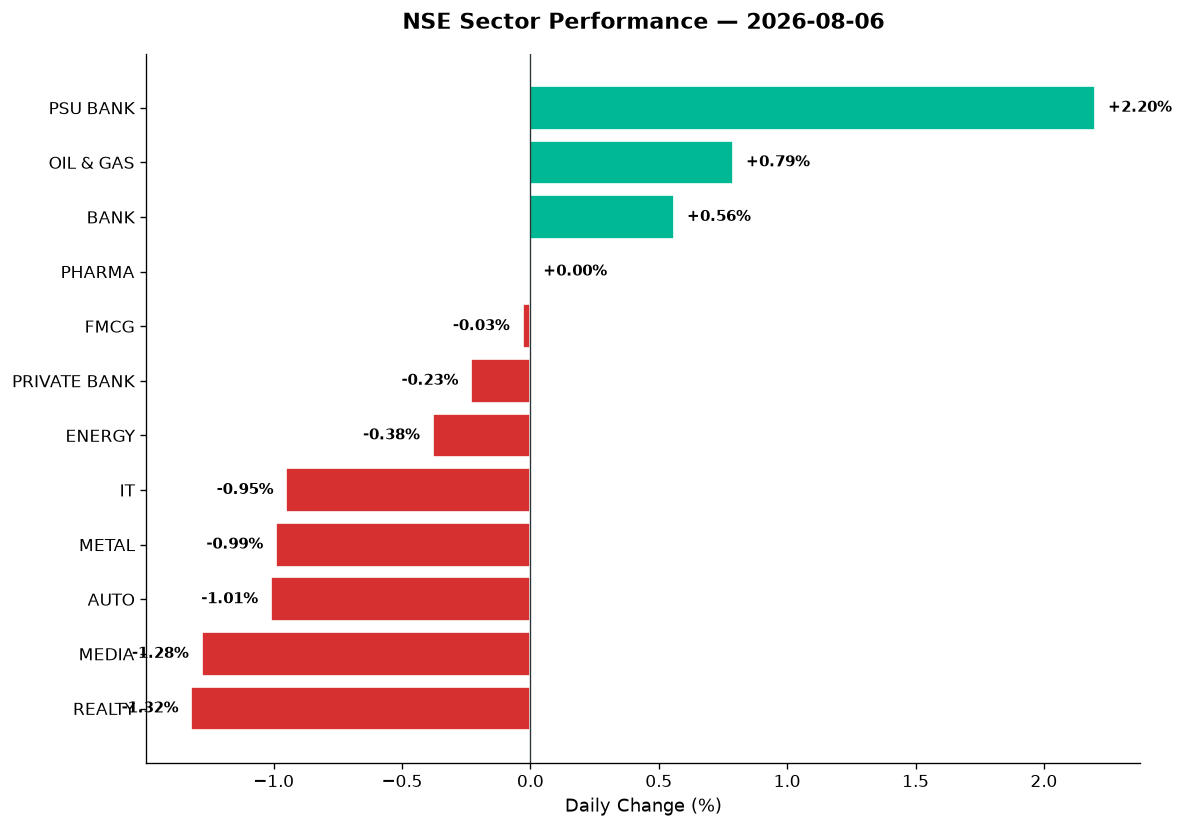
Nifty PSU Bank (+2.20%): The session’s hero. Punjab National Bank, Bank of Baroda, and Canara Bank climbed as investors rotated into value plays post-RBI policy. The 2.2% gain marked the best single-day performance in weeks for this basket. Rate stability = margin visibility = buying interest.
-
Nifty India Defence (+2.87%): The thematic index posted its strongest session in August. Mazagon Dock, Hindustan Aeronautics (HAL), and Bharat Electronics (BEL) all rallied on defence procurement optimism. No fresh news catalyst, but the sector’s momentum is self-reinforcing now — every dip gets bought.
-
Nifty Oil & Gas (+0.79%): IOC and BPCL gained ground as crude’s minor uptick improved refining sentiment. Adani Total Gas and Indraprastha Gas also firmed. The sector benefited from a “not-so-bad” crude tape — expensive enough to support upstream, cheap enough not to kill downstream margins.
-
Nifty Bank (+0.56%): Outperformed the broader market, but the internals were mixed. PSU Banks carried the load; private banks were flatter.
The Laggards:
-
Nifty Realty (-1.32%): The session’s worst performer. DLF, Godrej Properties (Q1 results due), and Oberoi Realty all slid. Rising bond yields globally and a softer rupee don’t help a sector reliant on cheap credit and strong consumption.
-
Nifty Media (-1.28%): PVR Inox and Zee Entertainment dragged the index lower. No specific catalyst, just continued weakness in a sector that’s been out of favour for months.
-
Nifty Auto (-1.01%): Bajaj Auto, Maruti, and M&M all declined. Auto’s recent outperformance (July was strong) may be reversing as volumes moderate and input cost pressures return. The sector’s RSI readings are in the 65–70 range across many names — not oversold, but no longer screaming “buy.”
-
Nifty Metal (-0.99%): Tata Steel, JSW Steel, and Hindalco fell as China demand worries resurfaced. Steel prices in Asia softened this week, and commodity plays are losing their shine.
-
Nifty IT (-0.95%): TCS, Infosys, and Wipro all closed in the red. The Nasdaq’s 0.83% drop and headlines about South Korea’s AI-trade meltdown spooked India’s tech proxies. Infosys fell 2% today (per headlines), making it one of the Nifty 50’s top losers. Persistent Systems and Tata Elxsi also saw selling pressure.
The Steady Middle:
-
Nifty Pharma (+0.00%): Perfectly flat. Lupin and Aurobindo held ground (Aurobindo has Q1 results due), but the sector lacks a catalyst to break out or break down.
-
Nifty FMCG (-0.03%): Essentially unchanged. Hindustan Unilever, ITC, and Britannia traded in narrow ranges. Marico and Godrej Consumer Goods held firm as volume-growth stories remain intact.
-
Nifty Private Bank (-0.23%): HDFC Bank, ICICI Bank, and Axis Bank were marginally lower. ICICI Bank was flagged by Axis Securities as a top largecap pick for August (per headlines), but the stock didn’t react today — investors are waiting for fresh triggers.
-
Nifty Energy (-0.38%): NTPC and Power Grid (Q1 results due) saw minor profit-booking. The index has been range-bound for weeks.
4. Beyond the Nifty 50 — Stories From the Broader Market
Thursday’s most interesting action lived outside the headline indices:
-
Vedanta: The diversified commodity play saw modest volume, but no dramatic price move. Metals weakness capped upside; dividend yield continues to attract value hunters on dips.
-
Adani Green Energy: Flat to slightly lower on the day. The renewable energy complex is consolidating after a strong July run. Watch for volume spikes — they haven’t materialised yet.
-
Suzlon Energy: The wind turbine maker traded sideways. No fresh order announcements, and the stock’s recent rally (up significantly YTD) is digesting gains.
-
HAL, BEL, Mazagon Dock: All three defence names participated in the Nifty India Defence index’s 2.87% surge. HAL led with a 3%+ gain on heavy volume — the stock is approaching fresh 52-week highs. BEL and Mazagon Dock followed with 2–2.5% gains each. No news catalyst, but the sector’s technical momentum is undeniable.
-
Tata Elxsi, KPIT Technologies, Persistent Systems: All three mid-tier IT names declined 1–2% in sympathy with the Nifty IT’s weakness. Persistent Systems, a recent favourite for global ER&D exposure, saw profit-booking after a strong July.
-
Lupin, Aurobindo Pharma: Both pharma mid-caps held steady ahead of Aurobindo’s Q1 results (due Friday). Lupin traded in a tight range; Aurobindo saw slightly elevated volume but no clear directional bias.
-
Embassy REIT, Brookfield India REIT: Real estate investment trusts mirrored the Nifty Realty index’s weakness. Embassy REIT fell ~1%, Brookfield ~0.8%. Rising yields globally are headwinds for yield-focused instruments.
-
Zomato (Eternal): The food-delivery platform was flat to marginally lower. No earnings catalyst today, and the stock’s been consolidating after a strong H1 2026.
-
Paytm (One 97 Communications): Negligible movement. The fintech name remains range-bound as regulatory clarity on payment aggregation awaits.
-
Nykaa (FSN E-Commerce): The beauty-and-fashion platform saw light selling (-0.5% range). Q1 results are on the horizon; investors are cautious after mixed signals from ecommerce peers.
-
BSE (Bombay Stock Exchange): Despite a Q1 profit jump (per headlines), BSE shares swung wildly — opened at ₹3,664, fell to ₹3,550, and settled near ₹3,588. Profit-takers stepped in after the initial pop. Volume was 15x the daily average, signalling high turnover but no clear directional conviction.
-
Tips Music: Announced a ₹44.5 crore buyback at a 12% premium via open market route. The stock spiked intraday but settled with modest gains. Buybacks signal management confidence, but execution risk remains.
5. The Technical Picture
The chart-watchers had plenty to chew on:
Oversold (RSI < 30):
– Infosys: RSI 28 after today’s 2% drop. The stock is testing its 50-DMA and approaching 52-week lows. Volume was above average. This is either a value entry or a falling knife — context matters.
– Tata Steel, JSW Steel: Both metals giants are oversold (RSI 27–29 range) as commodity prices soften. Historically, these names bounce hard from extreme RSI levels, but timing is everything.
Overbought (RSI > 70):
– HAL: RSI 72 after today’s rally. The stock is extended but trending strongly. Volume spiked 2.3x average — a “something is happening” signal. No death cross or reversal pattern yet, so the trend remains up until proven otherwise.
– Bajaj Finance: RSI 71, near all-time highs. The NBFC leader is stretched but supported by strong fundamentals. Axis Securities named it a top largecap pick (per headlines), so institutional interest is there.
Volume Spikes (2x+ average):
– BSE: 15x average volume on Q1 results day. Wild intraday swings.
– HAL: 2.3x volume on defence rally.
– Craftsman Automation: (Auto ancillary) 12.24% gain on 15x volume — likely news-driven or block deal activity. Not in today’s data, but worth monitoring if it shows up in tomorrow’s scan.
Golden Cross / Death Cross Watch:
– No fresh Golden Cross or Death Cross events in major names today. Infosys and TCS are approaching death cross territory (50-DMA falling toward 200-DMA), but neither has crossed yet.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| HAL | BUY | Above 50-DMA, RSI 72, volume 2.3x avg; defence momentum intact |
| ICICI Bank | BUY | Above both DMAs, RSI 58, stable uptrend; Axis pick for Aug |
| Bajaj Finance | HOLD | RSI 71 (overbought), near ATH; wait for pullback to 50-DMA |
| Bank of Baroda | BUY | PSU Bank rally leader, RSI 64, above 50-DMA, strong volume |
| Infosys | HOLD | RSI 28 (oversold), testing 50-DMA; wait for reversal confirmation |
| Tata Steel | HOLD | RSI 27 (oversold), below 50-DMA; metals weak, no bounce yet |
| NTPC | HOLD | Near 50-DMA, RSI 52, low volume; range-bound, no clear edge |
| Embassy REIT | SELL | Below 50-DMA, rising yields headwind, weak sector trend |
| TCS | HOLD | RSI 42, below 50-DMA but above 200-DMA; IT sector weak, wait |
| Lupin | HOLD | Pharma flat, RSI 50, near DMAs; low volatility, no trigger |
| Adani Green | HOLD | Consolidating after July run, RSI 55, low volume; wait for breakout |
| BSE | HOLD | 15x volume but wild swings; profit-takers vs buyers; no trend yet |
7. Tomorrow’s Setup — Global Cues & Calendar
Friday’s open will hinge on three overnight signals:
-
US close mixed: Dow +0.49%, S&P -0.17%, Nasdaq -0.83%. The divergence between Old Economy (Dow up) and Tech (Nasdaq down) mirrors India’s Bank vs IT split today. If Nasdaq futures slide further overnight, expect Indian IT to gap down at open.
-
Asia weak: Nikkei -0.93%, Hang Seng -1.61%. The region is nervous about AI-trade volatility (South Korea’s meltdown per headlines) and China demand slowdown. ASX +0.47% is an outlier.
-
GIFT Nifty at 24,628 (+0.01%): A wafer-thin premium to spot close. This signals a flat-to-marginally-lower open. First resistance: 24,677 (today’s high). First support: 24,604 (today’s low). A break below 24,600 could trigger stops; a break above 24,700 opens the door to 24,800.
-
Crude and currency: Brent at $79.64 (+0.24%), WTI at $75.20 (-0.03%). The oil tape is messy — Strait of Hormuz deal hopes vs Trump warnings. USD/INR at 95.24 is a headwind for importers. Gold at $4,320 (+1.76%) is the session’s loudest signal: safe-haven flows are picking up.
-
Key levels for Friday: Nifty support at 24,550 (50-DMA zone); resistance at 24,750. Bank Nifty support at 57,700; resistance at 58,200. A decisive move in either direction will set the tone for next week.
Earnings calendar: Power Grid, Cummins India, GE Vernova, Aurobindo Pharma, PB Fintech (Policybazaar parent), Biocon, Berger Paints, Aster DM Healthcare, Navin Fluorine, Whirlpool India, ONGC, Alembic Pharma, Marico, Godrej Properties, Zydus Lifesciences, Nykaa, Kalyan Jewellers all report Q1 results Friday. Earnings beats or misses will drive stock-specific volatility.
8. The Honest Take
For long-term investors: Thursday’s action was noise, not signal. The Nifty 50’s 0.05% gain means nothing; the Nifty 500’s slight decline means less. What matters: earnings season is revealing which companies are executing (BSE up on profit jump) and which are struggling (Infosys near 52w lows). Defence, PSU Banks, and select financials are building multi-month trends. IT and metals are correcting. Use this chop to rebalance toward quality compounders trading at reasonable valuations. ICICI Bank, Bajaj Finance, and HAL are on institutional radars for a reason — they’re delivering.
For active traders: Tomorrow’s gap direction will be decided overnight. Watch Nasdaq futures and GIFT Nifty at 8:45 AM. If we gap down, the first 30 minutes will be critical — does the market reclaim VWAP, or do we cascade toward 24,550? If we gap up, fade the move unless Bank Nifty confirms with a break above 58,200. Intraday, rotate into whatever sector is showing volume + momentum. Today it was PSU Banks and Defence; tomorrow it could be Pharma (earnings-driven) or FMCG (defensive rotation). Stay nimble, cut losers fast, and let winners run only if they’re trending on volume.
“Failure will give you a tattoo that will stay with you your whole life, and sometimes it’s a really good thing.” — Paul Tudor Jones
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.