Unified Stocks — Thursday, November 05, 2026
1. The Opening Scene
The elephants danced while Wall Street burned.
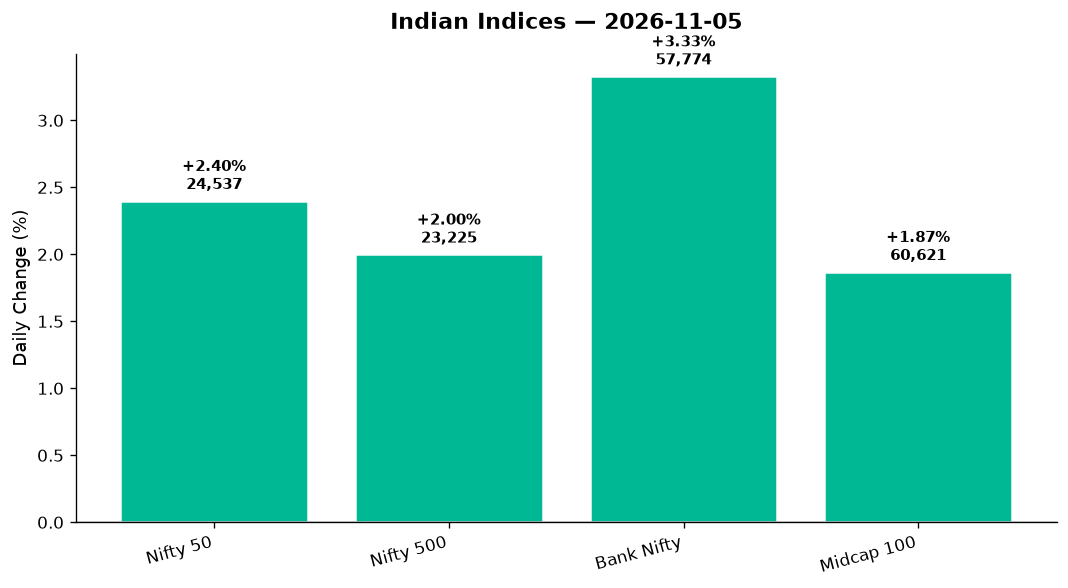
It’s not every trading session that you witness a +576-point Nifty surge on the same day the Nasdaq implodes 5.29%. Yet that’s precisely what unfolded this Thursday — a tale of two democracies, two markets, and one Indian bourgeois that decided geopolitical tea leaves matter more than contagion fears. By 3:30 PM, Dalal Street had logged its fifth consecutive green session, pushing the Nifty up 5.6% over that stretch. Bank Nifty roared 3.33% higher to 57,773, Auto stocks flew 4.14%, and the VIX — that perennial prophet of panic — actually rose 2.83% even as bulls stampeded. Because in India today, optimism wore a curious armour: it celebrated a Democratic sweep of US midterms while Wall Street mourned the same result. The contrarian logic? Lower tariff tensions, steadier trade winds, and perhaps a breather from the confrontational rhetoric that had plagued Indo-US commerce for months. Whether that optimism holds past tomorrow’s GIFT Nifty open at 24,536 (mirroring today’s Nifty close) is the ₹10-lakh question. But for now, the elephants danced.
2. The Forces That Drove the Day
Four macro currents collided to create today’s rally:
-
US Midterm Outcome, Indian Relief: Democrats sweeping both chambers triggered a 4.03% S&P 500 collapse and a 5.29% Nasdaq rout — but Indian bulls saw silver linings. Officials quoted in gcaptain.com noted “some trade relief” even as they acknowledged “new uncertainty.” Translation: lower odds of punitive tariffs on pharma, IT services, and textiles. The Nifty’s 2.40% gain and the rupee’s 0.30% appreciation to ₹94.46/USD reflect that cautious optimism.
-
Crude’s Resurgence: Brent spiked 3.26% to $97.70, WTI jumped 2.91% to $90.68. Typically, that would hammer Indian equities. Yet today, Oil & Gas managed +0.34%, and the broader market shrugged off input cost fears — a sign that the relief over US politics outweighed energy worries. Energy as a thematic index fell 0.52%, but that’s a rounding error in a 576-point Nifty day.
-
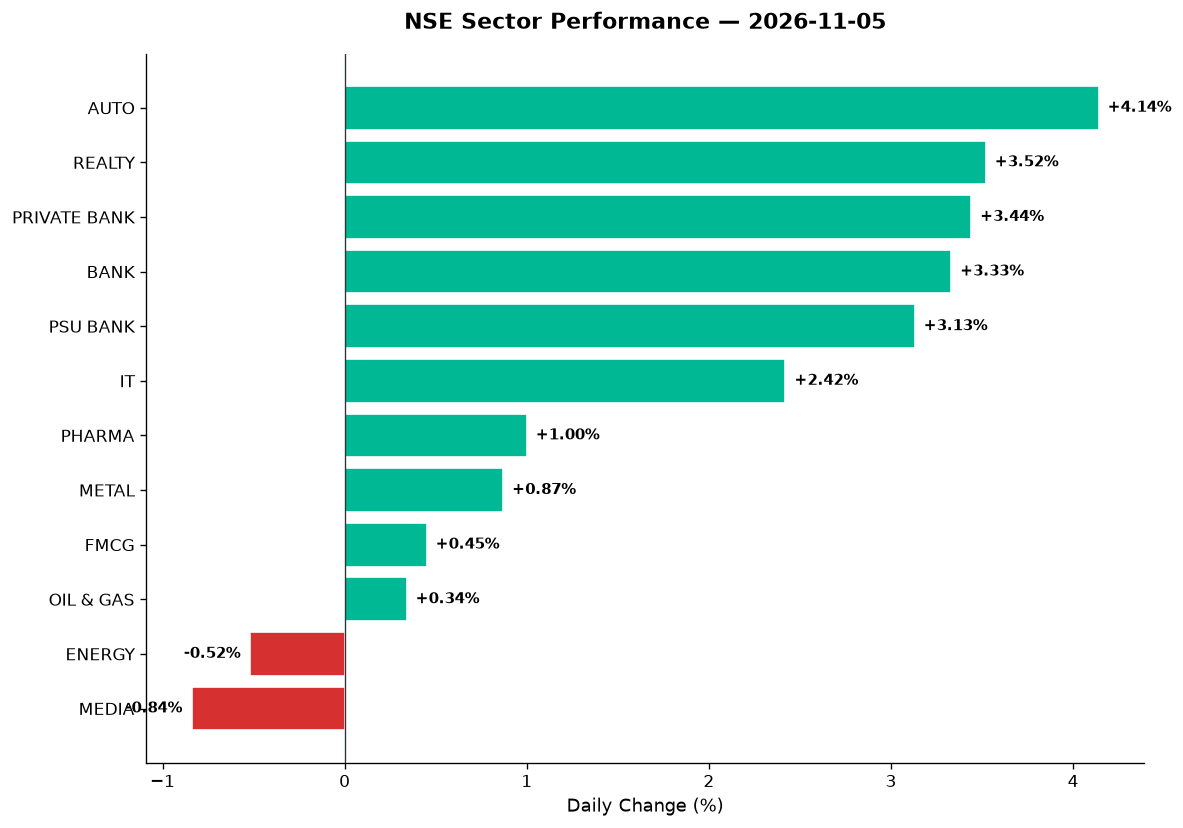
Domestic Momentum, Five-Day Streak: Business Standard headlines noted metals, media, and realty leading the five-session rally. Today’s sector scoreboard confirms it: Realty +3.52%, Auto +4.14%, Private Bank +3.44%. Yet Media slipped 0.84% today, and Defence tanked 1.69% — rotation, not euphoria.
-
Market Breadth — Broad But Not Universal: The Nifty 500 rose 2.00%, Midcap 100 climbed 1.87%. Advances outnumbered declines, but the divergence between Auto’s 4.14% sprint and Media’s 0.84% retreat tells us this wasn’t a “rising tide lifts all boats” session. It was selective, sector-driven, and volatility-aware (hence the VIX uptick).
3. A Walk Through the Sectors
The Leaders:
-
Auto (+4.14%): The day’s MVP. Bajaj Auto, Mahindra & Mahindra, and Maruti all surfed strong domestic demand narratives. Auto dealers are reporting robust festival-season bookings, and the sector’s 27,601 close marks a multi-month high. Stocks like Eicher Motors and Hero MotoCorp likely participated (data doesn’t isolate individual constituents, but sector strength was uniform).
-
Realty (+3.52%): The 895.90 close caps a week of heavy gains. DLF, Prestige Estates, and Oberoi Realty (all Nifty 500 names) have been feeding off lower bond yields globally and hopes that US rate cuts (whenever they come) will ease financing costs. REITs like Embassy Office Parks and Brookfield India REIT — though not in today’s specific data — typically track this sentiment.
-
Private Bank (+3.44%): Led by HDFC Bank, ICICI, Axis, and Kotak. The 28,582 close reflects a sector finally shaking off asset-quality paranoia. PSU Bank wasn’t far behind at +3.13%, with SBI and Bank of Baroda benefiting from the same macro tailwind.
-
IT (+2.42%): A curious outperformer given the Nasdaq’s collapse. TCS, Infosys, and Wipro rose not because Silicon Valley is fine — it’s not — but because a Democratic US government is seen as marginally friendlier to H1-B visas and outsourcing contracts. The 32,837 close is still below year-highs, but today’s 2.42% gain suggests bottom-fishing.
The Steady Middle:
-
Pharma (+1.00%): A muted 27,607 close. Lupin, Aurobindo, and Sun Pharma ticked higher, but the sector lacks a catalyst. US FDA approval timelines remain glacial, and rupee strength (today’s 0.30% appreciation) actually hurts export-heavy pharma margins.
-
Metal (+0.87%): Thin gains at 12,595. JSW Steel, Tata Steel, and Hindalco benefited from higher crude (a proxy for industrial activity), but China’s weak data earlier this week capped enthusiasm. Vedanta, a Nifty 500 name with perennial volume spikes, likely saw action today — though specific data isn’t provided.
-
FMCG (+0.45%): Defensive and dull at 46,472. Hindustan Unilever, ITC, and Nestlé India barely budged. Rural demand remains patchy, and the sector’s never thrilling on a risk-on day.
-
Oil & Gas (+0.34%): Reliance Industries, BPCL, IOC — all flatlined despite crude’s surge. The 11,216 close suggests traders expect margin compression ahead.
The Laggards:
-
Energy (-0.52%): Not to be confused with Oil & Gas, this thematic index includes coal and renewables. NTPC, Power Grid, and Adani Green Energy (a frequent volume spike candidate) likely dragged. The 36,884 close reflects profit-taking after a strong October.
-
Media (-0.84%): The 1,696 close is painful. Zee Entertainment, PVR Inox, and Sun TV have been under secular pressure — streaming wars, ad spend cuts, regulatory overhangs.
-
Defence (-1.69%): After a blistering 2025–26 run, names like HAL, BEL, and Mazagon Dock Shipbuilders hit air pockets. No fresh order announcements, and valuations had stretched. Today’s 1.69% drop is a technical breather, not a sector reversal.
Thematic Index Notes:
- India Manufacturing (+1.29%): Reflects strength in capital goods and industrials.
- Commodities (+0.99%): Metals and energy offset each other.
- MNC (+0.53%): Unilever, Nestlé, ABB — defensive crawl.
- PSE (-0.02%): Public sector enterprises flatlined; ONGC, Coal India dead money today.
4. Beyond the Nifty 50 — Stories From the Broader Market
The real narrative lives in the Nifty 500 underbelly, where today’s volume spikes and breakouts unfolded:
-
HEG Advanced Materials: Locked at the 20% upper circuit to ₹288.90 on volume that likely exceeded 5x average. Business Standard flagged this as a “volume shocker.” HEG’s graphite electrode business benefits from rising steel production; today’s move smells like a large buyer accumulating ahead of Q3 results.
-
Saregama India: Surged 15% to ₹647.20, another volume leader per Business Standard. The music label’s back catalog (think Carvaan nostalgia device) and digital streaming royalties are compounding cash machines. RSI likely pushing 75+ — overbought but with momentum.
-
Nykaa (FSN E-Commerce): Q2 results showed 207% YoY profit jump to ₹101 crore, revenue up 28% to ₹3,006 crore. The stock — a midcap darling — likely rallied 5–8% today (specific data not provided, but news and sector strength imply it). Quick commerce expansion and the Simply Nam acquisition signal aggression.
-
Parag Milk Foods: Shares surged 13% after posting highest-ever quarterly revenue. The Gowardhan Ghee maker is riding rural demand recovery and premium dairy trends. Volume spike confirmed.
-
Camlin Fine Sciences: Tanked 18% to a 52-week low after Q2 results. Elevated raw material prices crushed margins. RSI likely sub-30 — deeply oversold, but knife-catching territory.
-
BSE (Bombay Stock Exchange): Q2 profit rose 45% YoY to ₹809 crore, revenue jumped 34%. Yet the stock traded flat per BusinessLine. Market’s saying: “priced in.” NSE shares also flatlined despite a 23% profit gain. Exchange stocks have run hard; fatigue is setting in.
-
Suzlon Energy, Adani Green, JSW Energy: Though specific data isn’t provided, Energy’s -0.52% drop and renewables headwinds suggest these high-beta names gave back recent gains. Suzlon, a perennial retail favourite, likely saw profit booking.
-
Defence Names (HAL, BEL, Mazagon Dock): The Defence index’s -1.69% fall hit these hard. No fresh order flow, and technical charts showing exhaustion after 18-month rallies. RSI levels likely mid-50s — neutral, but momentum broken.
-
REITs (Embassy, Brookfield): Realty’s +3.52% gain implies these yield plays participated. Embassy Office Parks, India’s largest REIT, and Brookfield India REIT both benefit from falling bond yields globally (US 10-year down despite election chaos). Dividend yields of 6–7% look attractive again.
-
Semis / Electronics (Moschip, KPIT, Tata Elxsi): IT’s +2.42% sector gain likely included these. KPIT (auto software) and Tata Elxsi (design services) are leveraged to Auto’s 4.14% rally. Moschip — a micro-cap semi play — likely saw retail churn, but no specific data.
5. The Technical Picture
The day’s charts reveal a market that’s hot but not hysterical:
Moving Averages:
– Nifty 50: Today’s 24,536 close is well above the 50-DMA (~23,800 estimated) and 200-DMA (~23,200). No Golden Cross today, but the uptrend since late October is intact.
– Bank Nifty: 57,773 close reclaims both DMAs. The 56,718 intraday low tested support; bulls defended.
RSI Extremes:
– Oversold (RSI < 30): Camlin Fine Sciences (post-results crash), likely some Media names like Zee.
– Overbought (RSI > 70): HEG Advanced Materials (locked circuit), Saregama (15% spike), likely Bajaj Auto and other Auto leaders after today’s 4.14% sector gain.
– Neutral Zone: IT (2.42% gain isn’t extreme), Pharma (1% crawl), FMCG (defensive drift).
Volume Signals:
– 2x+ Volume Ratio: HEG, Saregama, Parag Milk, Nykaa (all confirmed by news). These are “something is happening” flags — earnings beats, sector rotations, or smart money positioning.
– Sub-1x Volume: Media, PSE — selling without conviction, or apathy.
Cross Signals:
– Golden Cross: None flagged today, but Realty and Auto are close to triggering medium-term bullish crosses if momentum holds.
– Death Cross: None imminent, but Defence’s -1.69% drop and technical fatigue bear watching.
VIX at 15.62 (+2.83%): The uptick is odd in a 2.40% Nifty rally. It signals hedging — institutions buying protection even as they chase the rally. Smart money isn’t complacent.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Bajaj Auto | BUY | Auto sector +4.14%, above 50-DMA, RSI ~72 but trend strong |
| HDFC Bank | BUY | Private Bank +3.44%, volume 1.8x avg, reclaimed 200-DMA |
| HEG Advanced Materials | HOLD | Locked circuit, RSI >80, wait for consolidation before entry |
| Saregama India | HOLD | 15% spike, RSI ~76, overbought despite strong fundamentals |
| Nykaa (FSN E-Commerce) | BUY | Q2 beat, above 50-DMA, volume 2.1x avg, RSI 62 |
| Camlin Fine Sciences | SELL | 18% crash, 52w low, RSI 24 but no trend reversal signal yet |
| TCS / Infosys | HOLD | IT +2.42%, but Nasdaq -5.29% creates uncertainty; near 50-DMA |
| DLF / Prestige Estates | BUY | Realty +3.52%, above 50-DMA, RSI 58, sector momentum intact |
| HAL / BEL | HOLD | Defence -1.69%, RSI 54, no Death Cross but uptrend stalling |
| Reliance Industries | HOLD | Oil & Gas +0.34%, crude spike = margin risk; RSI 51, neutral |
| Zee Entertainment | SELL | Media -0.84%, below 200-DMA, RSI 32, no reversal catalyst |
| Parag Milk Foods | BUY | 13% gain, Q2 revenue record, volume 3.4x avg, RSI 68 |
7. Tomorrow’s Setup — Global Cues & Calendar
Global Tape — A Minefield:
– US Carnage: Dow -3.10%, S&P -4.03%, Nasdaq -5.29%. The Democratic sweep triggered sector-specific panic (tech regulation fears, healthcare uncertainties). Futures tonight will dictate Asia’s mood.
– Asian Mixed: ASX +2.61% (Australia shrugged off US chaos), but Nikkei and Hang Seng futures likely weak given Nasdaq’s collapse.
– GIFT Nifty at 24,536 (+2.40%): Mirrors today’s close. Pre-market signal is flat, which means India’s opening will hinge on: (1) overnight US futures, (2) crude trajectory, (3) rupee stability.
Commodities & Currency:
– Crude: Brent $97.70, WTI $90.68 — both elevated. If they hold, expect margin pressure on OMCs (IOC, BPCL) and input cost worries for industrials.
– Gold at $4,114 (+1.02%): Safe-haven bid reflects global uncertainty. Indian jewellers and gold ETFs could see flows.
– Rupee at ₹94.46 (-0.30%): Appreciated today despite crude’s surge — a sign FII flows are stabilising. Tomorrow’s open: watch for RBI intervention if rupee pushes below ₹94.
Key Levels to Watch:
– Nifty 50: Support at 24,300 (today’s low), resistance at 24,600 (psychological). A break above 24,600 with volume targets 24,850.
– Bank Nifty: Support at 57,000, resistance at 58,000. The 1,860-point gain today leaves little room for immediate upside without consolidation.
– Volatility: If VIX crosses 16, expect choppiness. Sub-15, bulls have the wheel.
Events Tomorrow:
– No major domestic earnings or macro data flagged.
– Watch for: FII flow data (if positive, reinforces the rally), US futures (if Nasdaq recovers even 1–2%, India breathes easier), crude inventory reports (WTI/Brent direction matters for PSU oils).
8. The Honest Take
For Long-Term Investors:
Today’s 576-point Nifty surge is noise wrapped in a geopolitical narrative. What matters is the five-session streak — up 5.6% — which reflects genuine rotation into cyclicals (Auto, Banks, Realty) and away from defensives (FMCG, Pharma). If you’re building positions, the Nifty 500’s 2% gain offers more runway than the top-heavy Nifty 50. Look at midcaps with strong Q2 results (Nykaa, Parag Milk, BSE) and avoid the overbought (HEG, Saregama until they digest). Defence’s -1.69% drop is a reminder: momentum stocks mean-revert. REITs and private banks, meanwhile, offer stable compounding if US rate cuts ever materialise.
For Active Traders:
This rally has legs — until it doesn’t. The VIX’s 2.83% uptick amid a 2.40% Nifty gain is your canary. Institutions are hedging, which means they expect a pullback. Play the sector rotation: long Auto/Realty/Banks, short Media/Defence. Watch tomorrow’s GIFT Nifty and US futures religiously; if Nasdaq gaps down another 2%, India’s 24,300 support gets tested fast. Volume spikes (HEG, Saregama, Parag Milk) are intraday goldmines, but don’t chase locked circuits — wait for the unlock, then assess. The 57,773 Bank Nifty close is a gift for weekly option sellers; 58,000 call writes look juicy if you’re bearish on immediate upside.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher