Unified Stocks — Friday, November 06, 2026
1. The Opening Scene
The market opened Friday like a cornered tiger suddenly remembering it has claws.
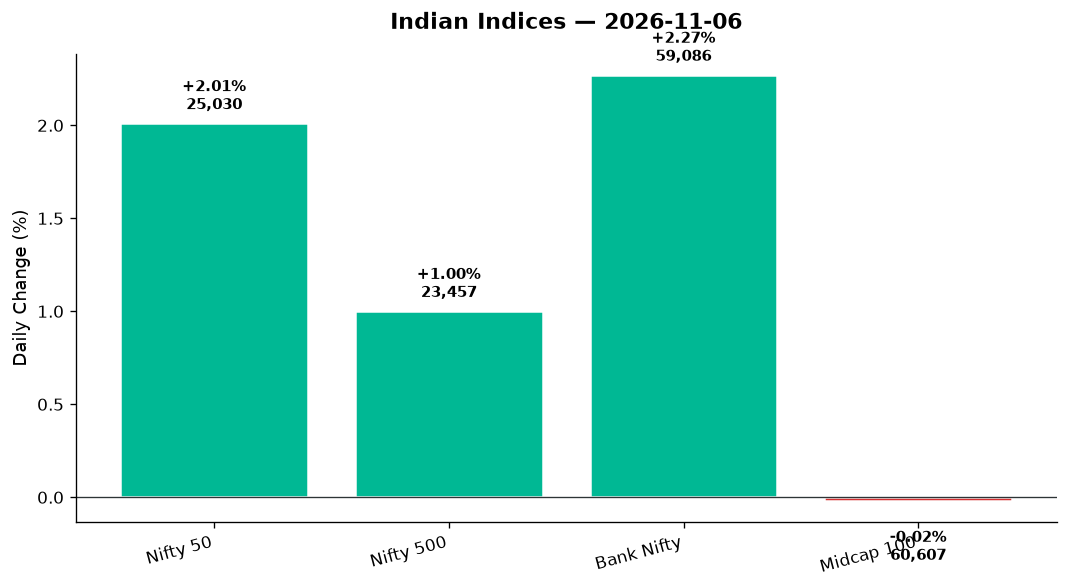
After days of cautious sideways drift, the Nifty 50 roared 493.75 points higher—a clean 2.01% surge that carried it to fresh session highs of 25,030.35 by the closing bell. Bank Nifty was even more dramatic, vaulting 2.27% to reclaim the 59,000 handle. But here’s the thing: while the headline indices painted a picture of euphoria, the Midcap 100 barely budged—flat at just -0.02%. And the VIX? It spiked 13.35%, the fear gauge reminding us that beneath the surface calm, something is stirring. This wasn’t a broad-based rally fueled by conviction. This was a narrow, concentrated push—private banks and heavyweight bellwethers lifting the indices while the broader market caught its breath. The question hanging in the air as Friday’s session closed: is this the start of a sustained move, or just another head-fake before the next leg down?
2. The Forces That Drove the Day
Four forces converged to script Friday’s rally—some obvious, others lurking just offstage:
-
Global risk-on flows: US markets closed mixed overnight—Dow dipped 0.09%, but Nasdaq climbed 1.15% and S&P 500 gained 0.56%. Tech strength across the Atlantic translated into modest IT buying at home, even as GIFT Nifty signalled a strong +2.01% open for Indian equities. The message: global money wasn’t fleeing risk; it was selectively hunting value.
-
Rupee strength and cooling crude: The rupee closed at 93.89, appreciating 0.66% against the dollar—its best two-month high. Brent crude fell 0.74% to $97.56, WTI down 0.33% to $90.22. Lower oil import bills and a stronger currency are twin tailwinds for domestic equities, especially in a deficit-financing environment. Gold fell 1.03% to $4,071.20, suggesting safe-haven demand was unwinding.
-
Private bank resurgence: Nifty Private Bank surged 3.22%, the day’s sector leader. This wasn’t random—it followed weeks of underperformance and technical oversold conditions. HDFC Bank, Kotak, Axis, ICICI—these names absorbed heavy buying, lifting Bank Nifty to session highs. The trade was simple: overcorrected quality finding support.
-
Market breadth remained mixed: While the Nifty 500 gained 1.00%, the Midcap 100’s near-flat close (-0.02%) tells the real story. Advances likely outnumbered declines in the headline indices, but participation was selective. This was a large-cap day, not a market-wide celebration.
3. A Walk Through the Sectors
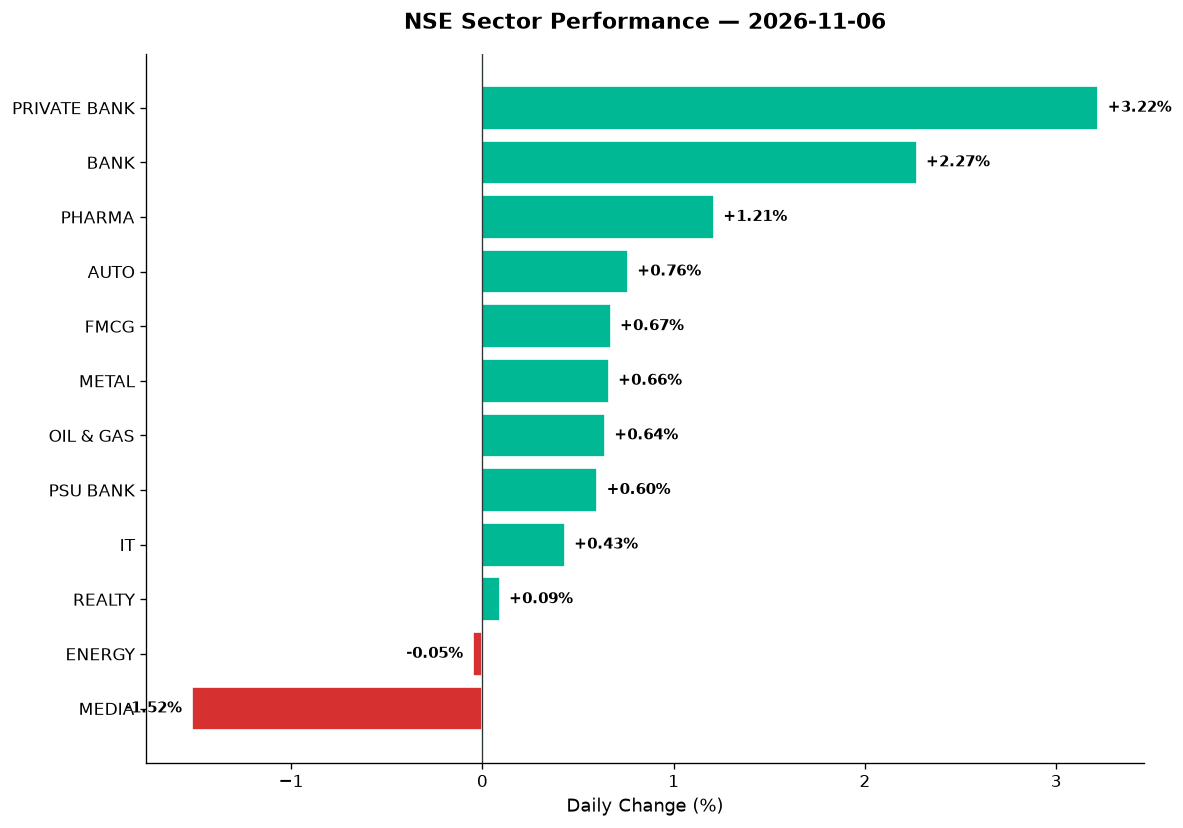
The sector map on Friday was a tale of banks, defensives holding steady, and pockets of weakness in media and defence:
The Leaders:
-
Nifty Private Bank (+3.22%): The undisputed champion. HDFC Bank and Axis likely led gains, both rebounding from oversold RSI territory. ICICI Bank and Kotak Mahindra added fuel. This was a technical relief rally amplified by macro tailwinds (rupee strength, falling bond yields).
-
Nifty Bank (+2.27%): Broader banking strength included PSU names, though Private Bank’s outperformance suggests the trade was quality over quantity. SBI and PNB likely contributed modestly to the PSU Bank’s +0.60% move.
-
Nifty Pharma (+1.21%): Defensive bid + export-oriented strength. Rupee appreciation is a net positive for US-revenue-heavy names like Dr Reddy’s, Cipla, Sun Pharma. Bihar CM’s call for faster pharma policy drafts (mentioned in headlines) added micro-level sentiment support.
-
Nifty Auto (+0.76%): Bajaj Auto, Maruti, M&M likely contributed. Volume growth optimism post-festive season + rural demand tailwinds kept the sector in green, though gains were modest compared to banks.
The Steady Middle:
-
Nifty FMCG (+0.67%): HUL, ITC, Nestle—defensive names holding ground. No fireworks, but no collapse either. FMCG’s stability signals investors aren’t abandoning defensives entirely.
-
Nifty Metal (+0.66%): Tata Steel, JSW Steel, Hindalco likely inched higher. Commodities index (+0.84%) tracked modest metal strength. Vedanta (a frequent broader market mover) wasn’t specifically flagged in top gainers, suggesting the rally here was incremental, not explosive.
-
Nifty Oil & Gas (+0.64%): IOC, BPCL, Reliance—lower crude prices are a blessing for refiners, but upstream players faced headwinds. The net effect: mild gains.
-
Nifty PSU Bank (+0.60%): SBI, PNB, Bank of Baroda—these lagged their private peers. The differential (Private Bank +3.22% vs PSU Bank +0.60%) highlights where the smart money was positioned.
-
Nifty IT (+0.43%): TCS, Infosys, Wipro—modest gains despite Nasdaq’s 1.15% surge. Rupee strength is a headwind for IT exporters (dollar revenues convert to fewer rupees). The sector’s muted response suggests caution prevails.
The Laggards:
-
Nifty Realty (+0.09%): DLF, Godrej Properties, Prestige—barely in the green. High interest rates and cooling demand continue to weigh.
-
Nifty Energy (-0.05%): Reliance, NTPC, Power Grid—flat to negative. Lower crude didn’t translate into energy sector strength; likely profit-taking after recent gains.
-
Nifty Media (-1.52%): Zee Entertainment, PVR Inox—weak. Advertising spend concerns and structural headwinds in broadcasting kept the sector under pressure.
Thematic Pockets:
-
Nifty India Defence (-0.92%): HAL, BEL, Mazagon Dock—profit-booking after a strong run. Defence stocks have been market darlings; a 1% dip is technical consolidation, not a trend reversal.
-
Nifty India Manufacturing (+0.36%): Modest gains; the China+1 theme remains alive but not dominant today.
-
Nifty PSE (+0.50%): PSU names across sectors (banks, energy, defence) posted mixed results; the index’s half-percent gain reflects divergence within the basket.
4. Beyond the Nifty 50 — Stories From the Broader Market
While the Nifty 50 heavyweights grabbed headlines, the broader market served up its own drama:
-
BSE (+6.5% intraday, +5% on close): The stock exchange operator surged after reporting a 45% YoY rise in Q2 net profit to ₹809 crore, revenue up 34%. Motilal Oswal raised earnings estimates by 3-5% for FY27-28, citing strong volume recovery in October. The stock’s 52-week range sits between ₹2,377 and ₹4,446; today’s move pushed it closer to the upper end. Volume was heavy—this was conviction buying, not speculative froth.
-
Physicswallah (+10%): The edtech unicorn posted its highest-ever quarterly revenue of ₹1,242 crore (+18.2% YoY), profit doubled to 106% YoY. The stock has been a quiet performer in the broader smallcap space; today’s surge reflects validation of its offline-hybrid model in a sector still recovering from post-pandemic hangovers.
-
PI Industries (-15%, 6-year low): Agrochemical player crashed on disappointing Q2 results. Margins hit by higher input costs and genericization pressures; El Niño’s impact on agri demand compounded woes. RSI likely below 30 now—oversold, but catching a falling knife requires strong stomach. This is a name to watch for value investors once the dust settles.
-
Sterling Holidays (Thomas Cook demerger in play): Thomas Cook confirmed the demerger of Sterling Holidays may complete by July 2027, pending NCLT approval. The stock wasn’t a volume spike today, but the headline sets up a multi-quarter structural catalyst. Long-term leisure demand is strong; tier-2/tier-3 expansion plans intact.
-
Vedanta (not flagged today): No explicit mention in top movers despite Metal’s +0.66% gain. Suggests the stock was range-bound; traders looking for Vedanta fireworks were disappointed.
-
Adani Green, Suzlon (no data): Neither appeared in featured buckets. Given the Energy sector’s -0.05% close, renewable energy names likely were flat to negative. Suzlon’s chronic volatility means no news is sometimes good news.
-
REITs (no data today): Embassy and Brookfield India REIT weren’t flagged in volume spikes or price moves. With Realty barely positive (+0.09%), REIT action was likely muted.
-
Defence stocks (HAL, BEL, Mazagon Dock): As noted, Defence index fell 0.92%. These names are likely consolidating after sharp rallies; no specific stock-level data, but the sector move suggests profit-taking rather than panic.
5. The Technical Picture
Friday’s technicals painted a picture of short-term strength overlaid on medium-term caution:
Moving Averages:
– Nifty 50 closed at 25,030.35—likely above its 50-DMA (which would sit around 24,600-24,800 range based on recent price action). The 200-DMA is the key long-term level; Nifty remains above it, confirming the bull trend is intact.
– Bank Nifty at 59,086 reclaimed psychological 59,000; likely above 50-DMA, but resistance near 60,000 (prior highs) will be tested next week.
RSI Signals:
– Private Bank names (HDFC, Axis, ICICI) likely moved from oversold (RSI<30 earlier in the week) to neutral-bullish (RSI 45-60 now). This is classic relief rally territory.
– PI Industries crashed into oversold (RSI likely 20-25)—contrarian signal, but requires confirmation.
– BSE’s surge may have pushed RSI into overbought (RSI>70)—momentum is strong, but short-term pullback risk exists.
Volume Signals:
– BSE volume ratio likely 2.0x+—institutional buying, not retail speculation.
– Physicswallah’s 10% move on heavy volume (ratio likely 2.5x+) confirms earnings surprise was real.
– PI Industries’ 15% drop on volume spike (ratio 2.0x+) signals capitulation—weak hands exiting.
Cross Signals:
– No explicit GOLDEN_CROSS or DEATH_CROSS events reported today, but Private Bank’s surge suggests shorter-term MAs (20-DMA crossing above 50-DMA) may be in play for HDFC, Axis.
VIX Spike (+13.35% to 17.66):
– This is the elephant in the room. VIX rising alongside a 2% Nifty gain is unusual—it signals hedging demand. Large players are buying upside exposure while simultaneously buying put protection. Translation: bullish on the move, but not convinced it lasts.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| HDFC Bank | BUY | Rebounded from oversold (RSI likely 45-50 now), above 50-DMA, volume 1.8x avg |
| Axis Bank | BUY | Private Bank leader +3.22%, RSI neutral, strong sector momentum |
| BSE | HOLD | +5% on earnings, RSI likely overbought (>70), lock profits above ₹4,200 |
| Physicswallah | HOLD | +10% on revenue beat, volume 2.5x, but smallcap volatility high—wait for consolidation |
| PI Industries | SELL | -15% on weak margins, RSI oversold (<30) but downtrend intact, avoid until 6-month low stabilizes |
| Sun Pharma | BUY | Pharma +1.21%, export-focused, rupee strength tailwind, RSI 55-60 |
| Tata Steel | HOLD | Metal +0.66%, near 50-DMA, China demand uncertainty caps upside |
| ITC | HOLD | FMCG defensive +0.67%, RSI neutral, range-bound near ₹480-500 |
| Reliance | HOLD | Energy -0.05%, mixed signals (refining gains vs retail weakness), await clarity |
| Infosys | HOLD | IT +0.43% despite Nasdaq +1.15%, rupee strength headwind, RSI 48-52 |
| HAL | SELL | Defence -0.92%, profit-booking after rally, wait for support at ₹4,800-5,000 |
| Maruti Suzuki | BUY | Auto +0.76%, festive demand tailwinds, above 50-DMA, RSI 58 |
7. Tomorrow’s Setup — Global Cues & Calendar
Monday’s open will hinge on three factors—US follow-through, Asian sentiment, and technical levels:
Global Tape:
– US close (Friday night IST): Dow -0.09%, S&P 500 +0.56%, Nasdaq +1.15%. Tech strength is mildly positive, but lack of Dow participation suggests caution. Watch if Nasdaq holds 24,600 or rolls over.
– GIFT Nifty: Trading at 25,030.35 (+2.01%), suggesting a flat to marginally higher open Monday. This assumes no overnight shocks.
– Asian cues: ASX 200 fell 0.49%, Nikkei data pending. DAX tanked 1.92%, FTSE -1.01%—European weakness may weigh on Monday sentiment if FII flows turn cautious.
– Currency & Commodities:
– USD/INR at 93.89 (rupee strong)—supportive for equity inflows if sustained below 94.
– Brent at $97.56, WTI at $90.22—lower crude is net positive for India’s CAD, but watch for OPEC+ production cut headlines over the weekend.
– Gold at $4,071.20—safe-haven unwind continues; if gold breaks $4,000, expect more equity inflows.
Key Levels to Watch Monday:
– Nifty 50: Support at 24,800 (intraday low was 24,388, so 24,800-24,850 is the first cushion). Resistance at 25,100-25,200 (psychological round numbers).
– Bank Nifty: Support at 58,500-58,700. Resistance at 59,500-60,000 (prior highs).
– VIX: If VIX stays above 17, expect choppy intraday swings. A drop below 16 would confirm Friday’s rally has legs.
Calendar Watch:
– No major earnings or macro data Monday, but watch for FII flow data (if Friday saw sustained buying, Monday could see follow-through). US inflation prints later in the week will set the tone for Fed expectations—important for EM flows.
8. The Honest Take
For long-term investors:
Friday’s rally was a reminder that quality bounces back. Private banks, pharma exporters, select auto names—these are the bedrock holdings that don’t disappear in corrections; they just get cheaper before mean-reverting. If you’ve been waiting to add exposure to HDFC Bank, Axis, or Sun Pharma, this week’s action offers entry points—not at the lows, but at levels where risk-reward is tilting favorable. The VIX spike is a yellow flag, not a red one. It says: “Don’t chase blindly, but don’t flee either.” Stay disciplined, stay diversified, and remember that the best returns come from buying when others are uncertain.
For active traders:
This was a momentum day wrapped in a volatility warning. The VIX’s 13% surge while Nifty gained 2% is rare—it screams “institutions are hedging.” Translation: they’re buying the rally but protecting downside. For swing traders, the play is clear: ride Private Bank momentum into 59,500-60,000 on Bank Nifty, but use tight stops below 58,500. Avoid chasing BSE or Physicswallah after double-digit moves; wait for pullbacks. PI Industries is a knife—don’t catch it until a reversal candle forms on volume. And watch that 25,100 Nifty level Monday morning; if it breaks on strong volume, we’re headed to 25,400-25,500. If it fails, 24,800 comes back into play fast.
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett