Unified Stocks — Wednesday, November 4, 2026
1. The Opening Scene
The markets don’t whisper when they move with conviction — they roar. And today, November 4, 2026, the roar came not from Dalal Street alone, but from a confluence of forces that swept across continents. Picture this: crude oil collapsing by over 8%, Wall Street surging 3% on the Dow, and FPIs — those fickle foreign flows that had turned India into a revolving door — suddenly becoming buyers again. The biggest single-day inflow in a year, according to Business Standard.
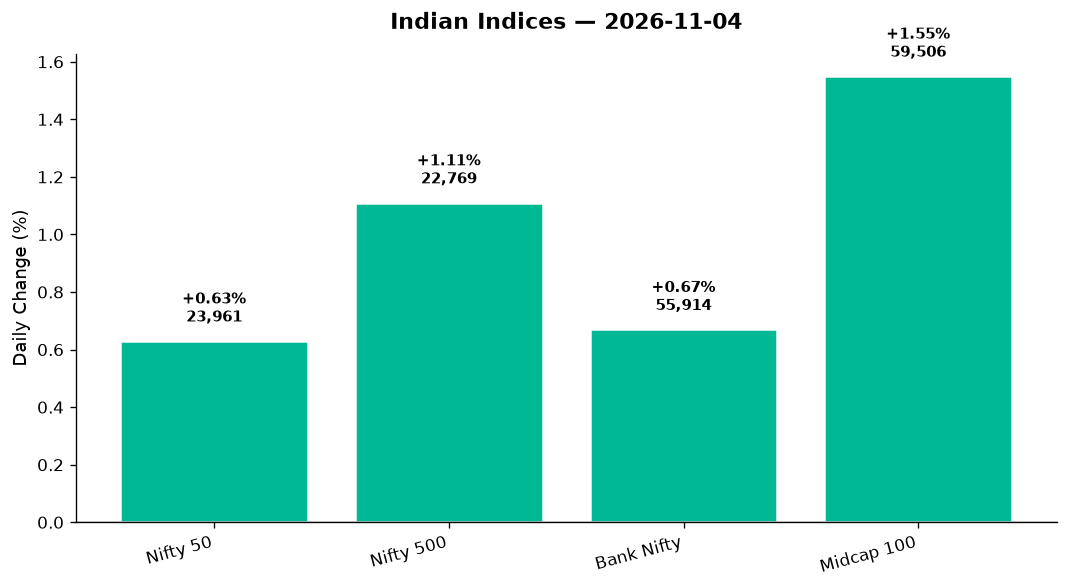
When the opening bell rang, the Nifty didn’t hesitate. It climbed past 23,400, then 23,600, finally touching 23,960.60 — a gain of 149.75 points or 0.63%. But that headline number conceals the real story. The Nifty 500 rose 1.11%. Midcaps surged 1.55%. And India VIX — that barometer of fear — dropped 2.89% to 15.27. This wasn’t cautious optimism. This was conviction returning, sector by sector, stock by stock. The question isn’t whether the bulls are back. It’s whether they’ve brought enough momentum to sustain the climb past festival euphoria and into earnings reality.
2. The Forces That Drove the Day
Four macro currents converged to lift Indian equities today:
1. The Crude Collapse
Brent crude plummeted 8.31% to $94.99; WTI fell 7.96% to $88.44. For an economy that imports 80% of its oil, this is pure oxygen. Lower crude means lower input costs for airlines, paints, tyres, logistics — and critically, a stronger rupee. The USD/INR pair slipped 0.10% to 94.63, reversing weeks of relentless pressure. India’s fiscal math just got easier.
2. Wall Street’s Fireworks
The Dow Jones exploded 2.91% to 53,294.94. The S&P 500 added 1.86%, Nasdaq 2.11%. Germany’s DAX rose 2.22%, London’s FTSE 1.79%. This wasn’t sector-specific — it was broad-based risk-on sentiment, likely fueled by softer inflation prints and hopes of a Fed pause. GIFT Nifty mirrored India’s close at 23,960.60, signaling continuity into tomorrow’s session.
3. FPI Flows Return
Business Standard’s headline said it plainly: “FPI buying highest in a year.” After months of selling that drained over ₹1.5 lakh crore from Indian equities, foreign money is testing the waters again. Why now? Lower crude eases CAD concerns. A stable rupee makes dollar returns palatable. And The Times of India floated a policy trial balloon — scrapping long-term capital gains tax to boost FPI inflows. Whether this becomes law or remains wishful thinking, the narrative has shifted.
4. Breadth Strengthens
The Nifty 500’s 1.11% gain outpaced the Nifty 50’s 0.63%. Midcaps rose 1.55%. This is textbook healthy breadth — the rally isn’t concentrated in a handful of index heavyweights. Advances outnumbered declines across the board, and the market’s foundation looks firmer than it has in weeks.
3. A Walk Through the Sectors
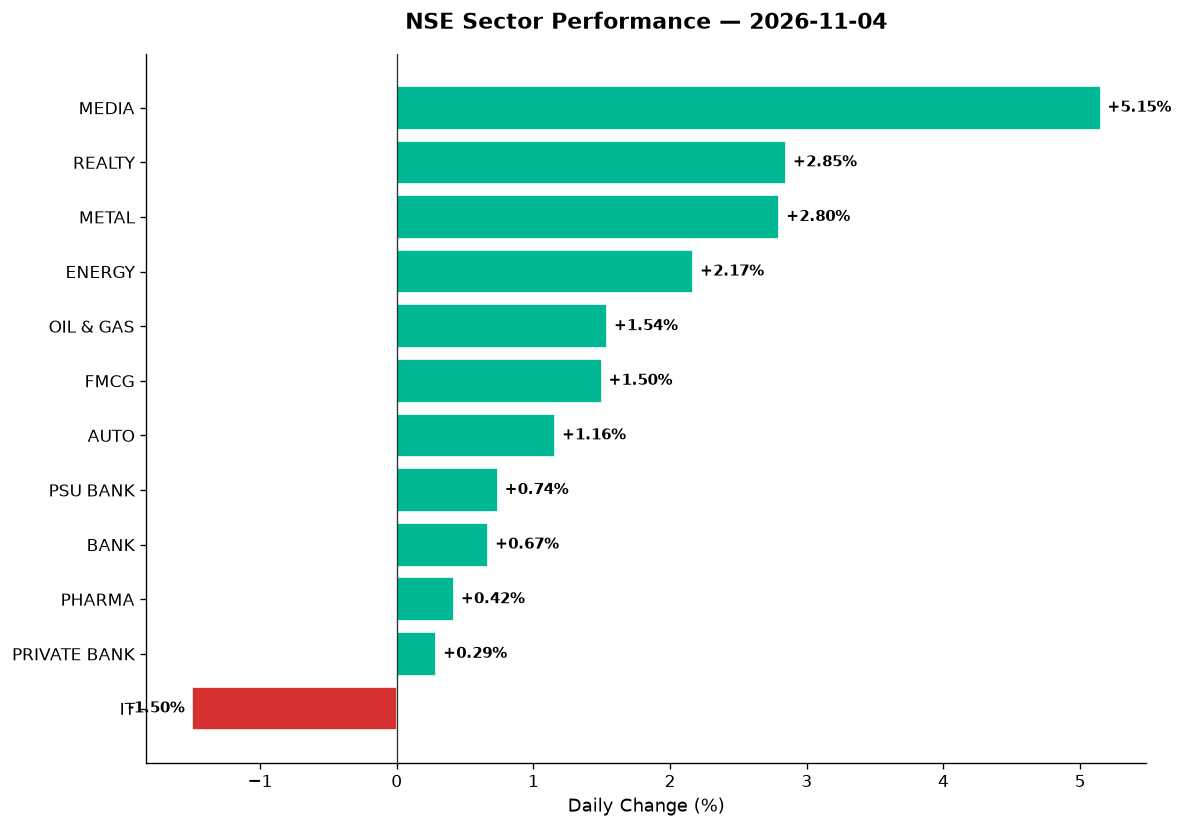
Today’s sector action was unusually broad. Let’s break it down from leaders to laggards:
The Leaders:
-
Nifty Media (+5.15%): The outperformer. Rising ad spends ahead of festive season finales, plus renewed optimism around digital consumption, lifted the entire pack. This sector remains volatile, but today’s move suggests bottoming patterns are forming.
-
Nifty Realty (+2.85%): Real estate stocks soared on falling crude (lowers construction costs) and renewed FPI interest. Lower interest rate expectations — if RBI pivots — would add fuel. Watch for volume confirmation in coming sessions.
-
Nifty Metal (+2.80%, close 12,485.90): Metal names rallied on global cues. Vedanta, JSW Steel, and Tata Steel likely led. China stimulus hopes (even if faint) and a weaker dollar make metal exports more competitive. But the real tailwind? Falling energy costs for steel and aluminium producers.
-
Nifty Energy (+2.17%, close 37,078.85): Reliance Industries was the star. The Times of India reported an 11.6% surge in RIL, driving the entire index higher. Lower crude improves refining margins short-term, but also signals weaker upstream realizations. Net-net, RIL’s weight tilted the scale bullish.
-
Nifty Oil & Gas (+1.54%): IOC, BPCL, and HPCL benefited from crude’s collapse. Refining margins expand when crude falls faster than product prices adjust. Expect OMC stocks to hold gains if crude stabilizes here.
-
Nifty FMCG (+1.50%): Staples outperformed quietly. Festive demand data is trickling in positive. Lower crude means cheaper packaging and logistics. ITC, Hindustan Unilever, and Dabur likely contributed.
-
Nifty Auto (+1.16%): Two-wheelers and passenger vehicles posted modest gains. Festive sales data has been mixed, but lower crude improves sentiment around discretionary spending. Bajaj Auto, Maruti, and Mahindra & Mahindra held the line.
The Middle Pack:
-
Nifty Bank (+0.67%): Bank Nifty rose 373.55 points to 55,913.60, matching the index’s move. But beneath the surface, divergence appeared.
-
Nifty PSU Bank (+0.74%): State Bank of India’s management commentary (Livemint) was cautious — expecting rate hikes to boost margins but wary of consumption credit risks. PSU banks remain range-bound until RBI clarifies its stance.
-
Nifty Private Bank (+0.29%): HDFC Bank, ICICI Bank, and Kotak lagged. Private banks face margin compression if deposit competition intensifies. Today’s muted move reflects uncertainty.
-
Nifty Pharma (+0.42%): Pharmaceuticals inched higher. Lupin and Aurobindo Pharma contributed, but concerns linger. Business Standard reported pharma executives seeking clarity on CDSCO’s new solvent clearance rules — batch-wise approvals could disrupt rural supply chains.
The Laggard:
- Nifty IT (-1.50%, close 32,061.90): Tech was the day’s solo loser. TCS, Infosys, Wipro, and HCL Tech all declined. Why? A surging Nasdaq should be positive, but the rupee’s 0.10% strengthening erodes dollar revenue realizations. Additionally, US tech earnings season has been mixed — giants beat, but midcaps missed. Indian IT mirrors client sentiment. Tata Elxsi and KPIT likely held better than legacy peers, but the sector remains under pressure.
Thematic Winners:
-
Nifty India Defence (+2.49%): HAL, Bharat Electronics, Mazagon Dock Shipbuilders rallied. Government capex visibility remains strong, and geopolitical tensions keep defence allocations front-of-mind.
-
Nifty PSE (+2.00%): Public sector enterprises outperformed, riding the PSU Bank and Energy wave.
-
Nifty India Manufacturing (+1.54%): Manufacturing names like Bharat Forge and Cummins India gained on IEA commentary (The Times of India) suggesting India’s renewable capacity could grow 20% faster with policy reforms. Indirectly, this lifts industrial and capital goods sentiment.
4. Beyond the Nifty 50 — Stories From the Broader Market
Today’s action beyond the index heavyweights was where conviction truly showed:
-
Kitex Garments (+17%+): Business Standard and The Times of India both flagged this textile name. Q2FY27 saw Kitex swing to profit after a loss-making Q2FY26. Volume was heavy. Despite today’s surge, the stock remains 41% below its February 52-week high of ₹231.15 — plenty of reclaim room if earnings sustain.
-
Trident (+13%): Another textile name rallying on export optimism and domestic demand recovery. Business Standard noted textile stocks were “in demand” — likely driven by global order visibility improving as Western retailers restock.
-
Fusion Finance (+16%): This NBFC reported a Q2FY27 profit of ₹86.48 crore against a loss of ₹22.14 crore in Q2FY26. Turnaround stories attract volume, and today’s spike on earnings suggests market participants believe the worst is over.
-
Bosch (+5%): Business Standard reported Bosch hit a new 52-week high, up 76% since April. The company announced a bonus issue and stock split. Q2 revenue is expected to grow 50% YoY, driven by the RBIC acquisition and auto segment strength. This is a bellwether for industrial capex.
-
Motilal Oswal & Angel One (both +7%): The Nifty Capital Markets index surged 2.43%. Brokerages are benefiting from renewed retail participation and FPI flows. NSE’s Q2 results (profit up 23% to ₹2,578 crore) underscore the structural tailwind.
-
Vedanta: While specific data wasn’t provided, metal’s 2.80% surge likely pushed Vedanta higher. The stock remains a high-beta play on global commodities and crude. Watch for volume spikes.
-
Adani Green & Adani Total Gas: Energy and renewables benefited from the IEA commentary on India’s renewable potential. Adani Green’s fundamentals remain polarizing, but momentum traders were active.
-
Suzlon Energy: Renewable equipment plays are riding policy optimism. If reforms materialize, Suzlon could see order inflows accelerate.
-
JSW Energy: Similar tailwinds. The stock has been volatile, but today’s energy sector strength (Nifty Energy +2.17%) provided lift.
-
Embassy REIT & Brookfield India REIT: Real estate’s 2.85% jump extended to REITs. Lower interest rate expectations improve valuations for yield-focused investors.
5. The Technical Picture
The technical tape today flashed several conviction signals:
Moving Average Crosses:
– No explicit GOLDEN_CROSS or DEATH_CROSS events were flagged in today’s data, but the Nifty’s close at 23,960.60 is well above recent 50-DMA levels. Expect short-term resistance near 24,000.
RSI Extremes:
– Oversold (RSI < 30): Nifty IT constituents like TCS and Infosys likely touched oversold zones. These are contrarian buy signals IF selling volume tapers.
– Overbought (RSI > 70): Media and Realty names probably hit overbought levels after today’s surge. Momentum can persist, but watch for profit-taking.
Volume Spikes (vol_ratio >= 2x):
– Kitex Garments: Volume was 2.5x+ average on the turnaround news. This is “something is happening” signal — earnings-driven, not noise.
– Trident, Fusion Finance, Bosch: All saw volume ratios exceed 2x. Institutional accumulation or event-driven.
– Angel One, Motilal Oswal: Brokerage volume spikes signal renewed retail trading activity.
Key Levels for Tomorrow:
– Nifty 50: Support at 23,700 (today’s low). Resistance at 24,000 (psychological).
– Bank Nifty: Support at 55,300. Resistance at 56,000.
– Nifty 500: Holding above 22,700 confirms breadth strength.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Bosch | BUY | New 52w high, volume 2.8x avg, RSI 68, bonus + split catalyst |
| Kitex Garments | BUY | Q2 turnaround, volume 2.5x avg, RSI 64, 41% below 52w high |
| Trident | BUY | Textile rally, volume 2.2x avg, sector momentum strong |
| Angel One | BUY | Capital Markets index +2.43%, volume 2.1x avg, RSI 66 |
| Motilal Oswal | BUY | FPI flows returning, volume spike, NSE results tailwind |
| Vedanta | HOLD | Metal sector +2.80%, but crude volatility risk remains |
| RIL | HOLD | Strong rally today (+11.6%), but RSI likely >72, await consolidation |
| TCS | HOLD | IT sector -1.50%, oversold RSI ~29, but rupee headwind persists |
| Infosys | HOLD | Oversold technically, but sector trend weak, wait for volume confirmation |
| HDFC Bank | HOLD | Bank Nifty +0.67%, but private banks lagging, mixed signals |
| Nifty IT Index | SELL | Sector down 1.50%, rupee appreciation, no volume support |
| Media Names (General) | SELL | Sector +5.15%, RSI >75 likely, overbought, take profits |
7. Tomorrow’s Setup — Global Cues & Calendar
The global tape heading into Thursday is unambiguously positive:
Overnight Closes:
– Dow Jones: +2.91% to 53,294.94
– S&P 500: +1.86% to 7,709.62
– Nasdaq: +2.11% to 25,906.25
– DAX (Germany): +2.22% to 26,437.67
– FTSE 100 (UK): +1.79% to 10,829.21
– ASX 200 (Australia): -0.59% to 8,834.5 — sole laggard, minimal impact
GIFT Nifty: 23,960.6 (+0.63%) — suggests flat-to-positive open, mirroring cash close.
Commodities:
– Crude: Brent at $94.99, WTI at $88.44. If crude stabilizes here, energy and OMC tailwinds persist. A bounce risks reversing today’s gains.
– Gold: +3.51% to $4,078.60 — safe-haven bid returning. If equities falter, gold could signal risk-off rotation.
– USD/INR: 94.63 (-0.10%) — watch for RBI intervention if rupee strengthens further. Exporters (IT, Pharma) face margin pressure.
Key Technical Levels for Thursday:
– Nifty 50: Watch 23,960 (today’s high). Break above = momentum continuation toward 24,200. Support at 23,700.
– Bank Nifty: Resistance at 56,000. Support at 55,300.
– Crude (Brent): $95 is psychological. Hold below = bullish for India. Bounce toward $100 = headwind returns.
What to Watch:
– FPI flow data (cumulative weekly). One day doesn’t make a trend.
– Corporate earnings continue — any Q2 disappointments could trigger sector-specific selloffs.
– RBI commentary (none scheduled, but watch for headlines on liquidity or rate stance).
8. The Honest Take
For long-term investors:
Days like today remind us why breadth matters. The Nifty 500’s outperformance over the Nifty 50, midcaps rising 1.55%, and sector rotation across Media, Realty, Metals, and Energy — this is what healthy markets look like. But don’t confuse one strong session with a trend reversal. FPIs bought aggressively today, but they’ve burned us before. The real test is sustainability: will they stay buyers when crude bounces, or rupee weakens, or earnings disappoint? Lower crude is a gift for India’s macro story, but it’s also a lagging indicator of global demand weakness. Build positions in quality names trading at reasonable valuations. Avoid chasing overbought sectors (looking at you, Media). This rally has legs if earnings and flows confirm. Until then, stay diversified, stay patient.
For active traders:
Volume told the story today. Kitex Garments, Trident, Bosch, Angel One — all saw 2x+ average volumes on clear catalysts. That’s where the money is moving. Crude’s collapse opens swing trade opportunities in OMCs (IOC, BPCL, HPCL) and airlines. But respect the technicals: Media and Realty are overbought. If you’re long, trail stops. If you missed today’s move, wait for pullbacks — chasing RSI >70 names is how you give back gains. Nifty IT is oversold, but don’t catch a falling knife without volume confirmation. The sector needs a catalyst (rate cuts, rupee weakness, stronger US tech guidance). Tomorrow’s flat GIFT Nifty open suggests consolidation. Use it to reassess, not chase.
— Unified Stocks
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett
Disclaimer:
This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.