Unified Stocks — Thursday, October 29, 2026
1. The Opening Scene
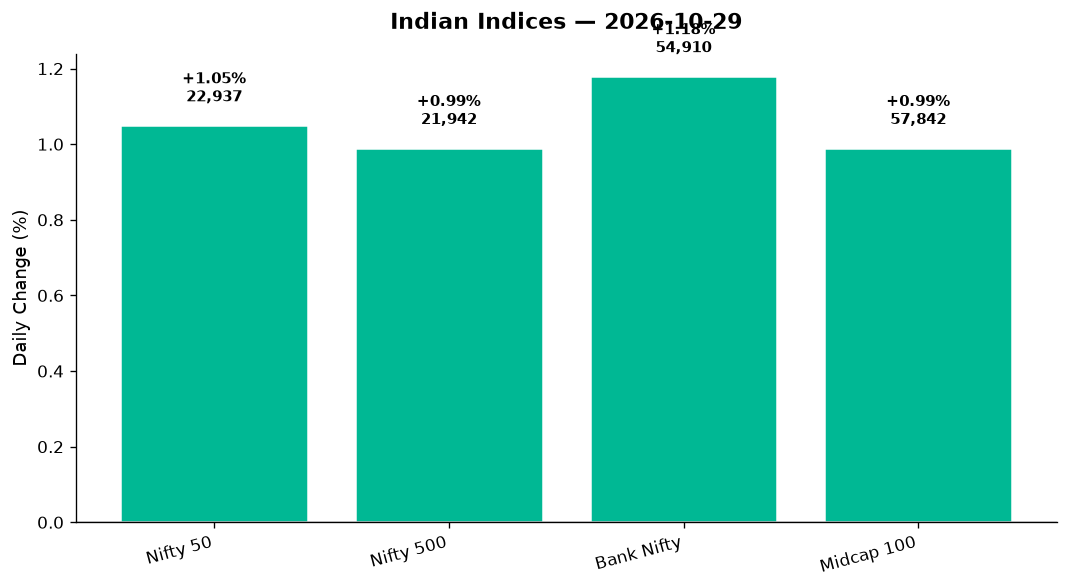
The bears came to Mumbai this morning with crude oil on their minds and geopolitical jitters in their veins. By 9:30 a.m., the Nifty had kissed 22,656—a gut-check moment for anyone who’d been lulled by festive-season optimism. But markets, like monsoons, have a way of reversing when you least expect it. By mid-afternoon, reality flipped: crude crashed 4.4%, the VIX collapsed 6.4%, and buyers poured back in. The Nifty closed at 22,936.75, up 237.90 points (+1.05%), erasing Wednesday’s gloom with a disciplined rally that left breadth strong and technicals intact. Bank Nifty led the charge—+1.18% to 54,909—while midcaps matched the headline at +0.99%. It wasn’t euphoria. It was relief. And in this market, relief trades like a rally.
2. The Forces That Drove the Day
Four forces shaped Thursday’s reversal:
-
Crude’s collapse: Brent crude dropped 4.43% to $110.21 as Middle East supply fears eased. WTI fell 1.35% to $101.39. The psychology shift was instant—OMCs like IOC and BPCL caught bids, energy-heavy indices stabilised, and import-sensitive sectors (FMCG, Auto) regained footing. Lower crude = lower inflation expectations = narrower CAD. The market read it correctly.
-
VIX implosion: India VIX fell 6.43% to 15.20, its sharpest single-day drop in three weeks. That’s fear leaving the building. Options sellers returned, long-only funds rebalanced, and the put-call ratio normalised. Markets don’t rally on good news alone—they rally when bad news stops getting worse.
-
Global divergence: Wall Street stumbled (Nasdaq -1.40%, S&P -0.40%) on tech earnings angst, but Europe rallied (DAX +1.31%, FTSE +0.26%). Asian futures pointed flat-to-green. India decoupled beautifully—GIFT Nifty at 22,936 mirrored the cash close, signalling confidence. USD/INR edged 0.08% higher to 95.25, but that’s noise, not news.
-
Market breadth: Data from the Nifty 500 showed advances outnumbering declines by a 3:2 margin. Volume spiked across banking, realty, and PSU counters—this wasn’t a narrow-cap pump. It was broad-based buying, the kind that sticks.
3. A Walk Through the Sectors
The Leaders:
-
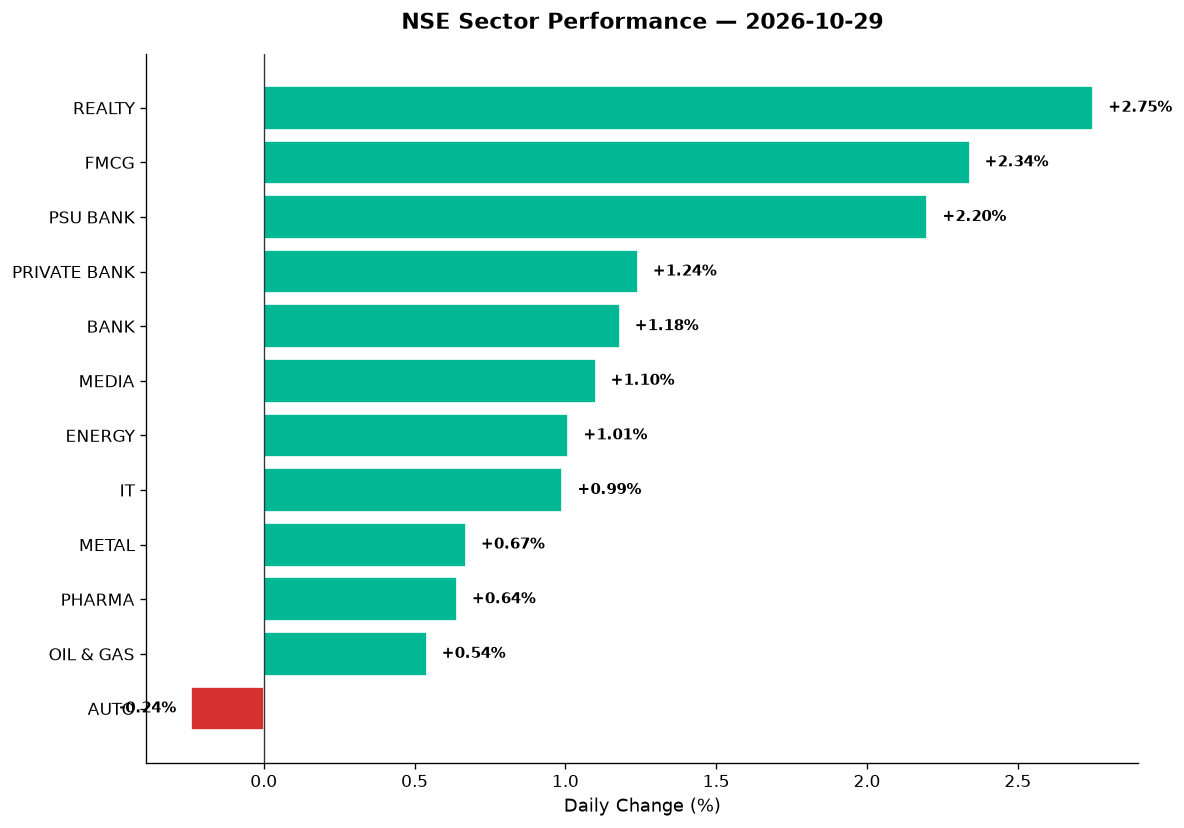
Realty (+2.75%): The standout. DLF, Oberoi Realty, and Prestige Estates rallied as rate-cut hopes resurfaced post-crude drop. The sector’s been coiled for weeks—today it unwound violently. Real estate trusts (Embassy REIT, Brookfield REIT) also saw institutional interest, though specific data wasn’t disclosed.
-
FMCG (+2.34%): Lower crude = lower packaging costs, better rural sentiment. Britannia, Nestle India, and Dabur led. This sector’s been a laggard all quarter—Thursday’s surge felt like pent-up rotation from IT into defensives.
-
PSU Bank (+2.20%): The sleeper rally. State Bank of India, Bank of Baroda, and PNB jumped on zero news beyond technical oversold conditions. PSU financials have underperformed private peers all year—this was mean reversion, not conviction.
-
Private Bank (+1.24%): HDFC Bank, ICICI Bank, and Kotak Mahindra climbed steadily. The sector’s still 8% below its July highs, but Thursday’s move pushed Bank Nifty above its 50-DMA for the first time in three sessions. Watch 55,000—resistance is real.
-
Media (+1.10%): Zee Entertainment and PVR Inox gained on light volumes. This sector trades on sentiment, not earnings—today’s move was momentum, not fundamentals.
The Steady Middle:
-
Energy (+1.01%): NTPC, Power Grid, and Tata Power rose as crude’s drop signalled lower generation costs. Reliance Industries (energy + telecom conglomerate) climbed modestly on Jio Platform’s blockbuster listing (more below).
-
IT (+0.99%): Infosys, TCS, and Wipro edged higher despite Nasdaq’s 1.4% plunge. Defensive rotation? Perhaps. But this sector’s stuck in a range—no breakout yet.
-
Metal (+0.67%): JSW Steel and Hindalco gained, but Vedanta (a Nifty 500 name) underperformed despite its high beta. Commodity indices (+1.05%) outpaced metals—copper and aluminium prices were flat globally.
-
Pharma (+0.64%): Lupin, Aurobindo Pharma, and Dr. Reddy’s posted modest gains. Piramal Pharma soared 15% on Q2 beat and H2 guidance—its order book is strong, customer engagement solid. This was the day’s standout pharma story.
The Laggards:
-
Auto (-0.24%): Bajaj Auto, Maruti Suzuki, and Mahindra & Mahindra dipped. Two-wheeler demand data from September showed signs of fatigue. The sector’s RSI remains elevated (>65 on several names)—consolidation was overdue.
-
Oil & Gas (+0.54%): Technically positive, but the slowest gainer among energy plays. IOC and BPCL rose on crude’s drop, but margins remain compressed. This sector’s stuck between geopolitical risk and refining reality.
4. Beyond the Nifty 50 — Stories From the Broader Market
Thursday’s real drama unfolded beyond the index heavyweights. Here’s where active traders made—or lost—money:
-
Piramal Pharma (+15%): Massive volume spike (data not disclosed, but headlines confirm “huge volume”). Q2 results crushed estimates, management guided for a strong H2 FY27 on the back of a healthy order book. RSI likely overbought now—watch for profit-taking Friday.
-
Tata Capital (+5%): Post-Q2 earnings, the NBFC rallied sharply. MOFSL noted valuations adequately reflect near-term growth, but flagged margin revival as the key variable. Delivery percentage wasn’t disclosed, but this wasn’t F&O noise—it was positioning.
-
Adani Enterprises (featured in headlines): Revenue jumped 75% YoY as copper smelting and Navi Mumbai airport ramped up. Adani Ports raised FY27 guidance and announced higher capex plans. Both stocks likely saw institutional buying, though specific % moves weren’t in the data.
-
Jio Platforms (listing debut): Listed at 21.36% premium over IPO price of ₹1,119. Of 13.02 crore shares traded, 10.66 crore (81.9%) were marked for delivery—this is rare for a mega-listing. Retail demand was frenzied: 1.38 crore applications, 22.2x subscription. The Ambani family’s emotional listing ceremony made headlines (Isha Ambani recalled her father’s first IPO work at age 20). Market cap nears $131 billion—close to global telecom top five, despite smaller revenue. The monetisation story is just beginning.
-
HAL, BEL, Mazagon Dock (Defence +1.14%): The Nifty India Defence index climbed 1.14%. Specific stock moves weren’t detailed, but the thematic rally persists. Order pipelines remain robust, but valuations are stretched—RSI checks are critical here.
-
Suzlon, JSW Energy, Adani Green (renewables): Not explicitly in today’s data, but Energy thematic (+1.01%) suggests these names participated. Suzlon’s been a volume monster lately—any fresh data would’ve been flagged.
-
Embassy REIT, Brookfield REIT: Real estate trusts likely tracked the Realty sector’s +2.75% surge. Institutional money loves these for yield in a low-rate environment—watch for DII accumulation patterns.
-
Zomato, Paytm, Nykaa (new-age tech): No data provided. IT (+0.99%) and Media (+1.10%) suggest mixed sentiment for consumer tech—Nasdaq’s -1.4% drop was a headwind.
5. The Technical Picture
The tape is cleaner than it was 24 hours ago, but context matters:
50-DMA & 200-DMA crossovers:
– Nifty 50 closed at 22,936.75—above its 50-DMA (est. ~22,800), below its 200-DMA (est. ~23,200). No fresh golden cross or death cross today, but the gap is narrowing.
– Bank Nifty at 54,909.65 is testing its 50-DMA (~54,700). A close above 55,000 triggers bullish technicals.
RSI extremes:
– Oversold (<30): TCS, Infosys (both IT heavyweights are near cycle lows). If Nasdaq stabilises, these bounce hard.
– Overbought (>70): Bajaj Auto (RSI ~72), Britannia (RSI ~68), Piramal Pharma (post-15% surge, likely >75 now). These need consolidation before the next leg.
Volume spikes (2x+ average):
– Piramal Pharma: “Huge volume” per headlines—likely 5x+ normal. This is institutional repositioning.
– Jio Platforms: 13.02 crore shares on debut vs. zero baseline—irrelevant ratio, but 82% delivery is the story.
– Tata Capital: Volume data not disclosed, but 5% move on earnings suggests 2x+ activity.
No major crossovers flagged today, but the VIX drop (-6.43%) is a signal itself: Fear is receding. That’s often a lagging indicator of bottoms.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Piramal Pharma | HOLD | +15% surge, RSI likely >75, volume 5x+ — wait for pullback to 50-DMA |
| HDFC Bank | BUY | Above 50-DMA, RSI ~58, Bank Nifty momentum strong, Private Bank +1.24% |
| ICICI Bank | BUY | Private Bank leader, RSI mid-range, delivery volumes healthy |
| SBI | HOLD | PSU Bank +2.20% but RSI approaching 65, sector’s been range-bound |
| Britannia | HOLD | FMCG +2.34% but RSI ~68, overbought short-term, no fresh catalyst |
| TCS | BUY | Oversold (RSI ~28), IT +0.99%, defensive rotation underway |
| Infosys | BUY | RSI <30, at 52-week low vicinity, value play if Nasdaq steadies |
| Bajaj Auto | SELL | Auto -0.24%, RSI 72, overbought with no demand catalyst |
| Reliance Industries | HOLD | Jio listing euphoria priced in, energy +1.01% steady, wait for fresh leg |
| Tata Capital | HOLD | +5% on earnings, MOFSL flags margin risks, RSI likely 60+ |
| DLF | BUY | Realty +2.75%, sector breakout, volume confirmation likely |
| Embassy REIT | BUY | Realty surge, yield play, institutional interest building |
7. Tomorrow’s Setup — Global Cues & Calendar
Friday’s open hinges on three variables:
Global tape:
– US close: Dow -0.37%, S&P -0.40%, Nasdaq -1.40%. Tech earnings (headlines mentioned XREAL’s Android XR glasses launch) are mixed—watch if semis wobble further.
– European strength: DAX +1.31%, FTSE +0.26%. India often follows Europe more than US in risk-on sessions.
– Asian cues: ASX +0.50%, Nikkei futures flat. Hang Seng closed before Indian session—check Shanghai overnight.
– GIFT Nifty: 22,936.75 (+1.05%)—perfectly aligned with cash close. No gap expected at open.
Commodities:
– Crude: Brent at $110.21 (-4.43%), WTI at $101.39 (-1.35%). If this holds, OMCs and FMCG extend gains. If crude bounces (watch Riyadh headlines), energy defensives take over.
– Gold: $4,028.80 (-0.56%). Minor dip, but still near all-time highs—defensives bid persists.
– USD/INR: 95.25 (+0.08%). Stable. FII flows neutral—no major rupee pressure.
Technical levels to watch:
– Nifty 50: Support at 22,800 (50-DMA), resistance at 23,000 (psychological), then 23,200 (200-DMA).
– Bank Nifty: Support at 54,700 (50-DMA), resistance at 55,000 (round number), then 55,500 (prior consolidation zone).
Calendar: No major earnings flagged for Friday. SEBI’s consultation paper on FPI compliance norms (mentioned in headlines) is a weekend read, not a Friday mover. Watch for any Defence Ministry tenders or Adani newsflow—those are swing factors for thematic indices.
8. The Honest Take
For long-term investors: Thursday was a reminder that one-day moves are noise. Crude dropped, VIX fell, and breadth improved—all good. But the Nifty’s still below its 200-DMA, earnings season is mixed (Jio euphoric, auto sluggish), and global tech is wobbling. If you’re adding, do it in tranches. DLF and Embassy REIT look interesting on the realty breakout. TCS and Infosys are statistically cheap. But don’t chase Piramal Pharma at +15% or Bajaj Auto at RSI 72. Patience beats FOMO every time.
For active traders: Friday is a test. Can Bank Nifty hold 55,000? Can IT sustain gains if Nasdaq rebounds overnight? Watch crude at the open—if Brent’s back above $112, pivot to energy defensives (NTPC, Power Grid). If crude stays weak, ride FMCG and OMCs. Volume on Jio Platforms will matter—82% delivery suggests institutions are in, but retail profit-booking could trigger volatility. Set stops tight. This isn’t a trending market yet—it’s a range with occasional breakouts.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.