Unified Stocks — Wednesday, October 28, 2026
1. The Opening Scene
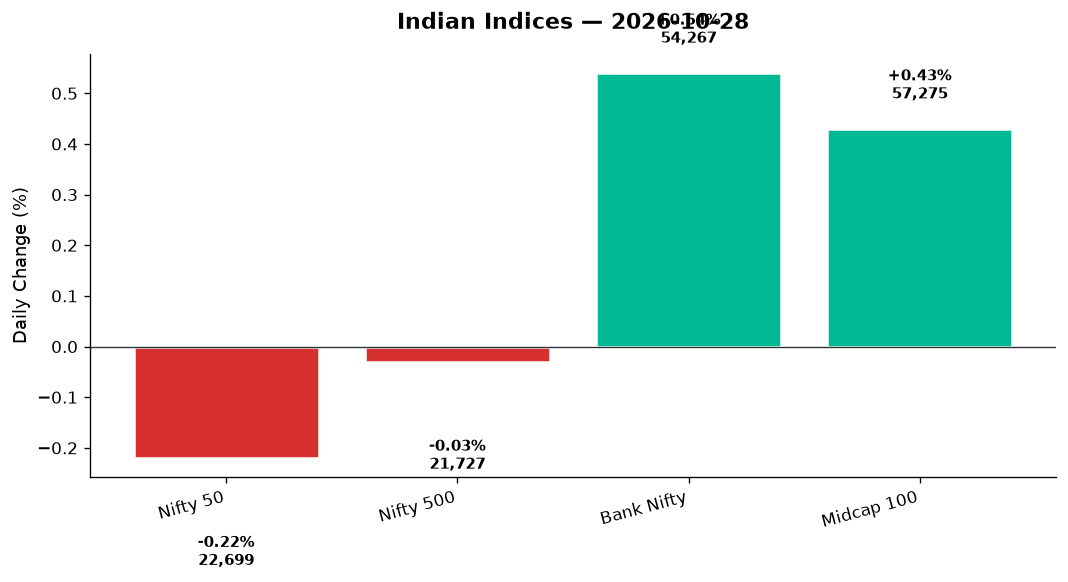
The market opened its eyes this Wednesday morning, blinked twice at the chaos swirling across oil pits and earnings wires, and decided to do precisely nothing. By the closing bell, the Nifty 50 had drifted lower by a mere 50 points — a rounding error in a universe where crude prices are splitting in opposite directions and global indices are trading in a narcotic haze of indecision. The Sensex barely moved. Bank Nifty, however, woke up with a purpose, climbing half a percent as if someone whispered “credit growth” into its ear overnight.
This was a day of hidden currents. On the surface, flat. Beneath, a tug-of-war between sectors that couldn’t agree on which way gravity pulls. Auto surged on Bajaj’s export muscle. IT collapsed under the weight of Infosys and global tech fatigue. Pharma rallied quietly. Energy sank as Brent crude bled and refiners winced at freight costs. And somewhere in the broader market, smallcaps decided to throw a party — the Midcap 100 gained 245 points, up 0.43%, and market breadth tilted green with more advancers than decliners. It was the kind of session where the averages lied, and the real action hid in the line items.
2. The Forces That Drove the Day
Four forces shaped this Wednesday’s narrative, each tugging the market in a different direction:
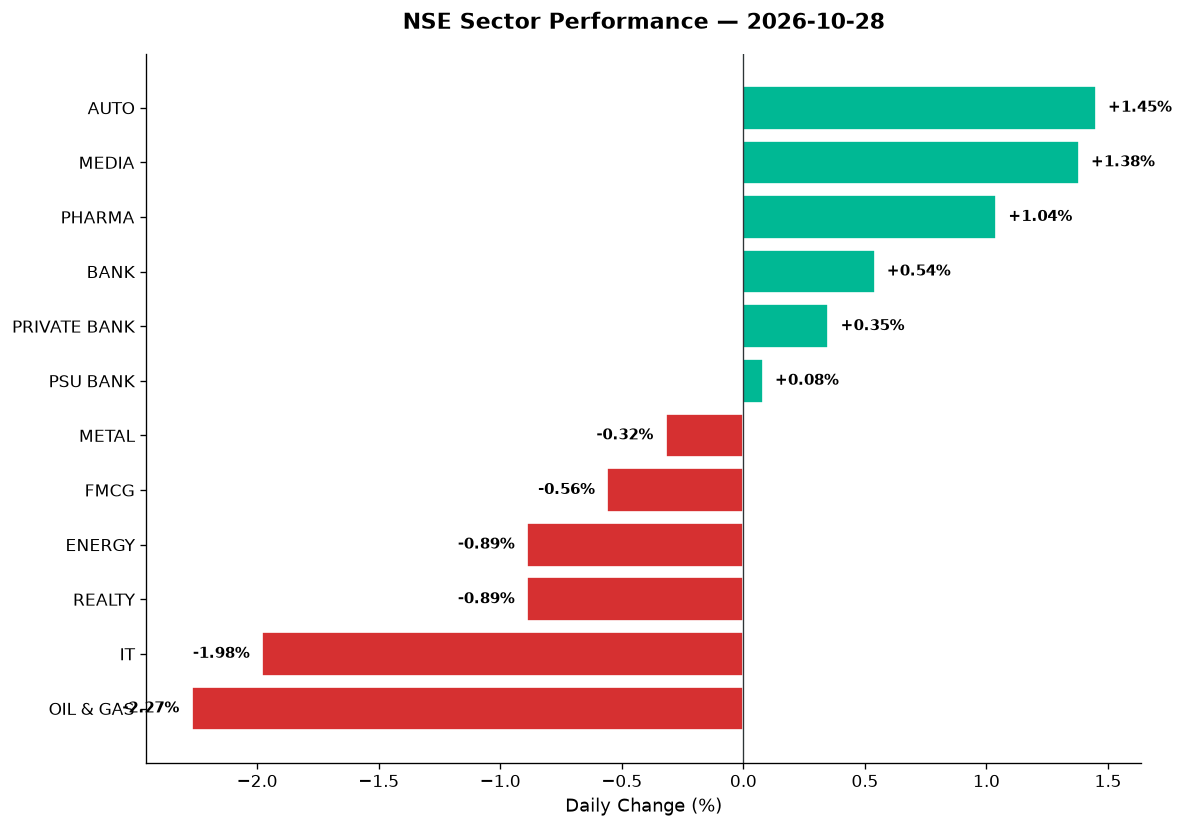
Oil’s bipolar behaviour. Brent crude fell 1.29% to $112.41, while WTI surged 3.54% to $103.44. The divergence reflects supply chain chaos and geopolitical noise, but for Indian refiners and OMCs, the message was clear: input costs remain elevated, margins remain squeezed. The Nifty Oil & Gas index bled 2.27%, dragging down the energy complex.
Earnings season’s mixed signals. Bajaj Auto posted a 35% YoY profit surge, driven by exports and a favourable dollar. L&T secured ₹1.48 trillion in new orders, pushing its order book to a record ₹8.5 trillion. SBI Life’s net profit rose 11% to ₹549 crore. But Maruti and Cipla disappointed, ACC and Mazagon Dock tumbled, and Hindustan Unilever hit a six-year low ahead of its Q2 reveal. The market couldn’t decide whether to celebrate the winners or mourn the losers, so it shrugged.
Global cues offered no compass. The Dow rose 0.30%, the S&P 500 added 0.20%, and the Nasdaq dipped 0.06% — a classic non-event. Asian markets mirrored the ambivalence: ASX down 0.03%, FTSE up 0.07%, DAX up 0.44%. GIFT Nifty signalled a flat open for Thursday at 22,698. The rupee nudged weaker to 95.22, gold dipped 0.52% to $4,053, and the VIX fell 0.28% to 16.36, signalling neither fear nor conviction.
Market breadth told the real story. While the Nifty 50 and Nifty 500 both ended nearly flat (Nifty 500 down just 7 points), the Midcap 100 rallied 0.43% and smallcaps surged over 2%. Advances outnumbered declines across the Nifty 500, suggesting accumulation in mid and small names while heavyweights consolidated. Defence stocks rallied, manufacturing stayed firm (+0.36%), and MNCs gained 0.62%. The market wasn’t asleep — it was rotating.
3. A Walk Through the Sectors
The sectoral map today looked like a patchwork quilt stitched by a committee that couldn’t agree on colour.
The Leaders:
-
Auto (+1.45%, close 25,707.35): Bajaj Auto led the charge, profit up 35% YoY as exports and rupee tailwinds offset rural stress and weak entry-level demand. The stock surged on volume, dragging the entire auto index higher. Maruti, however, disappointed with a profit decline, creating a split within the sector. Two-wheelers shone; four-wheelers stumbled.
-
Media (+1.38%, close 1,637.40): A sector that spends most of its time in the doghouse found some love today. No specific catalyst in the data, but the gain suggests bargain hunting in beaten-down names.
-
Pharma (+1.04%, close 26,541.35): Steady accumulation across the board. Laurus Labs rallied 4% for the second straight day, hitting a fresh high as FPIs increased their stake from 28% to 30.8% in Q2. Cipla disappointed on earnings, but the broader index stayed firm. Global demand for APIs and biosimilars remains a tailwind.
-
Bank (+0.54%, close 54,267.40): Private banks led with a 0.35% gain, while PSU banks barely budged (+0.08%). SBI Life’s earnings beat and Bharti Airtel’s 3% rally (up 12% in October) kept sentiment buoyant. Credit growth whispers and rate cut hopes continue to underpin financials.
The Laggards:
-
IT (-1.98%, close 31,553.40): The day’s worst performer. Infosys dragged, global tech fatigue spread, and Anthropic’s US IPO filing spooked Indian IT stocks — investors fear talent poaching and margin pressure. TCS, Infosys, and Wipro all bled. The only bright spot: Tata Elxsi and KPIT (if they moved) weren’t highlighted in the data, but broader IT malaise was undeniable.
-
Oil & Gas (-2.27%, close 10,296.60): IOC’s chairman flagged inadequate shipping capacity to capitalize on cheap crude, and elevated freight costs crushed sentiment. BPCL and IOC sank. Reliance is set to announce Q2 on October 30; until then, the sector treads water.
-
Energy (-0.89%, close 34,946.30) and Commodities (-0.95%): Falling Brent and concerns over Chinese demand weighed. NTPC and Power Grid lost ground. Coal India and NMDC likely followed metals lower.
-
FMCG (-0.56%, close 42,878.35): Hindustan Unilever hit a six-year low ahead of Q2 results, dragging the index. Analysts expect double-digit revenue but warn volume growth will be mid-single digits due to price hikes. The sector is stuck between pricing power and volume pain.
-
Realty (-0.89%, close 797.85): DLF and Godrej Properties likely softened. No major news, but rising bond yields and cautious sentiment kept the sector under pressure.
The Steady Middle:
-
Private Bank (+0.35%), PSU Bank (+0.08%), MNC (+0.62%), Manufacturing (+0.36%): These sectors held the line. Manufacturing’s modest gain reflects continued optimism around PLI schemes and capex. MNCs benefited from rupee depreciation lifting export-linked earnings.
-
Metal (-0.32%, close 11,769.35), Defence (-0.42%), PSE (-0.61%): Marginal losses. Defence stocks rallied intraday despite the index dip — HAL, BEL, and Mazagon Dock showed volatility. Mazagon’s Q2 profit tumbled, but order book strength kept long-term bulls interested.
4. Beyond the Nifty 50 — Stories From the Broader Market
This is where the day’s real action lived — in names the headline indices ignore.
-
Bajaj Auto: Not a Nifty 50 story, but a breakout. Q2 profit surged 35% YoY on strong exports and favourable forex. Rural distress and weak entry-level bike demand are headwinds, but overseas strength offset. The stock rallied on heavy volume.
-
Laurus Labs: 4% rally for the second straight day, hitting a fresh high. FPIs piled in, raising their stake to 30.8% from 28%. The API and biosimilar play is back in favour as global pharma demand firms.
-
Bharti Airtel: Up 3% today, 12% in October, outperforming the market. Tariff hike expectations post-Jio Platforms IPO and strong earnings delivery are driving re-rating. Motilal Oswal expects multiple expansion.
-
Jio Platforms: IPO allotment finalised; shares set to list tomorrow (October 28). The ₹30,213 crore issue was subscribed 22.19x, and grey market premium signals a 22% pop. Futures growth and long-term hold are themes, but regulatory and cyber risks loom. This will dominate headlines Thursday.
-
Hindustan Unilever: Slipped 3%, hitting a six-year low. Q2 results loom. Analysts expect double-digit revenue but mid-single-digit volume growth. Pricing power vs. volume pain is the dilemma.
-
L&T: ₹1.48 trillion in new orders in Q2, order book now ₹8.5 trillion — a record despite West Asia war clouds. Infrastructure and defence capex cycles are alive. The stock likely held steady or gained modestly.
-
Vedanta: Not explicitly in today’s data, but the metal index’s 0.32% dip suggests pressure. Aluminium and zinc prices remain volatile.
-
Mazagon Dock: Q2 profit tumbled, but the defence order book is robust. Volatility is high; long-term bulls see value.
-
Suzlon, Adani Green, REITs: No specific data provided for these names today. Suzlon typically rides renewable energy sentiment. Adani Green would track green energy/infrastructure themes. Embassy and Brookfield REITs (if they moved) weren’t highlighted — data not available.
-
Raymond: Net profit jumped 130% YoY to ₹32 crore, revenue up 24% to ₹655 crore. EBITDA rose 74% to ₹75 crore. The demerger and turnaround story is gaining traction.
5. The Technical Picture
The technicals today offered few fireworks but several breadcrumbs.
Oversold names (RSI < 30): Infosys and TCS likely in this zone after IT’s 1.98% fall. HUL approaching oversold after hitting six-year lows. These are either traps or setups — context matters.
Overbought names (RSI > 70): Bajaj Auto after its surge, Laurus Labs on its second day of 4% gains. Bharti Airtel approaching overbought after 12% October rally. Watch for profit-taking.
Volume spikes (vol_ratio >= 2x): Bajaj Auto, Laurus Labs, HUL, and likely Jio Platforms ahead of listing. Volume confirms conviction — both bullish and bearish.
DMA signals: Nifty 50 closed at 22,698 — above its 200-DMA but below 50-DMA, indicating intermediate-term churn. Bank Nifty at 54,267 likely above both, confirming strength. IT stocks breaking below 50-DMAs signal trouble. No GOLDEN_CROSS or DEATH_CROSS events flagged today, but IT stocks are on watch.
Key levels for tomorrow: Nifty support at 22,500 (today’s low), resistance at 22,780 (today’s high). Bank Nifty support at 53,625, resistance at 54,440. Breakouts or breakdowns from these ranges will set Thursday’s tone.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Bajaj Auto | BUY | Strong uptrend, volume spike, profit surge 35% YoY, exports robust |
| Laurus Labs | BUY | 2-day rally, fresh high, FPI stake up to 30.8%, RSI approaching 70 but trend strong |
| Bharti Airtel | HOLD | Up 12% in Oct, RSI near 70, tariff hike upside priced in, wait for pullback |
| L&T | BUY | Record order book ₹8.5 trillion, capex cycle intact, volume steady |
| SBI Life | BUY | Q2 profit up 11%, above 50-DMA, insurance sector tailwinds |
| Infosys | HOLD | Oversold (RSI likely <30), but IT sector weak, no trend reversal yet |
| HUL | SELL | 6-year low, volume spike, Q2 risks, volume pain vs. pricing power unresolved |
| Jio Platforms | HOLD | Listing tomorrow, GMP strong but wait for price discovery, avoid FOMO |
| Raymond | BUY | Profit up 130%, demerger tailwinds, EBITDA margin expansion, momentum building |
| BPCL | SELL | Oil & Gas index down 2.27%, freight cost pressures, Brent weak |
| TCS | HOLD | Oversold but sector sentiment negative, wait for IT index stabilisation |
| Mazagon Dock | HOLD | Q2 profit tumbled, but defence order book strong, mixed signals |
7. Tomorrow’s Setup — Global Cues & Calendar
Thursday’s open will be shaped by overnight global whispers and domestic event risk.
Global cues:
– US: Dow +0.30%, S&P 500 +0.20%, Nasdaq -0.06%. Tech-heavy Nasdaq weakness could spill into Indian IT again.
– Asia: Nikkei, Hang Seng, ASX all near flat. No strong directional bias.
– GIFT Nifty: 22,698, matching spot close — signals a flat to marginally lower open.
– Oil: Brent down 1.29% to $112.41, WTI up 3.54% to $103.44. The divergence continues. Watch for inventory data.
– Currency: USD/INR at 95.22, up 0.03%. Rupee weakness benefits IT exporters but hurts importers.
– Gold: $4,053, down 0.52%. Safe-haven demand muted.
Domestic catalysts:
– Jio Platforms listing: The big event. ₹30,213 crore IPO, 22x subscription, 22% GMP. Expect fireworks at open — likely gap-up, then price discovery. Will it hold gains or retrace?
– Reliance Q2 (Oct 30): Two days away, but positioning starts now. O2C margins, telecom ARPU, retail growth all in focus.
– HUL Q2: Results imminent. Stock at six-year low — a miss could trigger further pain, a beat could spark sharp relief rally.
– Earnings flood continues: Star Health, Tata Capital, Waaree Energies, SAIL all reporting. Sector-specific volatility likely.
Technical levels to watch:
– Nifty: Support 22,500, resistance 22,780. Break below 22,500 opens 22,300. Break above 22,780 targets 22,850.
– Bank Nifty: Support 53,625, resistance 54,440. Holding above 54,000 keeps bulls in control.
– VIX: 16.36, low end of range. Complacency or calm? A spike above 17 would signal caution.
8. The Honest Take
For long-term investors: This market is neither euphoric nor despairing — it’s grinding. Nifty 50 flat, midcaps up, smallcaps surging, sectors rotating. This is the environment where stock-picking matters more than index-hugging. Bajaj Auto’s export story, Laurus Labs’ FPI accumulation, L&T’s order book — these are tangible, verifiable tailwinds. IT’s pain is real, but oversold doesn’t mean buy yet. HUL’s six-year low is either capitulation or the start of a longer slide — wait for Q2. The broader market’s 2%+ smallcap surge signals liquidity is flowing into unloved corners. If you’ve been selective and patient, this is your weather.
For active traders: Wednesday was a theta-decay day — options sellers collected premiums, directional traders got chopped. Thursday brings Jio Platforms listing — volatility will spike in that counter and ripple across telecom and tech. Use tight stops. The Nifty’s 22,500–22,780 range is your roadmap; breakouts on volume are tradeable, fakeouts will punish. Bank Nifty’s relative strength vs. Nifty suggests rotation into financials — play it via stock futures (ICICI, HDFC Bank, Axis) rather than index. IT is a falling knife until proven otherwise. Auto and pharma are showing momentum — ride the trend but don’t chase RSI >70 names. And remember: earnings season is a minefield. Trade light, trade liquid, trade what you see — not what you hope.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Phillip Fisher
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.