Unified Stocks — Friday, October 30, 2026
1. The Opening Scene
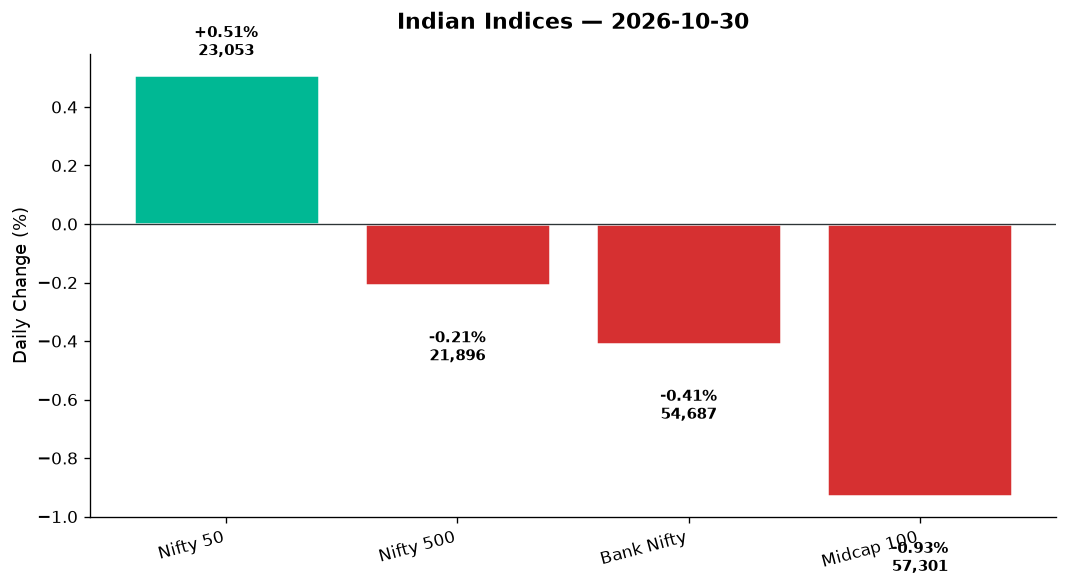
Two markets traded on Dalal Street this Friday. In one, the Nifty 50 climbed half a percent, IT stocks soared, and headlines celebrated the Federal Reserve’s rate hold. In the other — the wider, messier, truer market — midcaps bled nearly 1%, defence stocks crumbled 2%, and the NSE’s breadth told a darker story than the benchmark dared to whisper.
By the closing bell, the Nifty stood at 23,053, up 116 points, a number that looked respectable in isolation. But peel back the curtain: Bank Nifty slipped 0.41%, the Nifty 500 dipped 0.21%, and the Midcap 100 shed 0.93%. The VIX ticked up 2.21% to 15.45, a quiet alarm that something beneath the surface was stirring. This was a Friday split down the middle — large-cap resilience masking small-cap anxiety, tech euphoria hiding cyclical exhaustion. If you held only the headline index, you felt fine. If you owned the broader market, you felt the ground shift.
2. The Forces That Drove the Day
The Fed held, but two dissenters wanted more. The US Federal Reserve kept rates unchanged Wednesday night, a decision that should have been a pure tailwind for emerging markets. Yet two voting members pushed for a hike, keeping a December tightening on the table. The result? A bifurcated global response. US equities tanked — the Nasdaq lost nearly 3%, the S&P 500 fell 1.81% — while Asian markets showed cautious optimism. GIFT Nifty futures mirrored the Nifty’s close at 23,053, signalling a flat-to-mildly-positive open Monday.
Crude split, rupee weakened, gold cratered. Brent crude slipped 0.94% to $113.80, but WTI spiked 2.5% to $104.55 — a divergence reflecting inventory dynamics and geopolitical noise. The rupee drifted to 94.94 against the dollar, down 0.28%, testing multi-year lows. Gold, often the refuge, plunged 3.13% to $3,905, the sharpest single-day drop in months, suggesting a violent unwind of safe-haven positioning.
FII sentiment turned, but not enough. News reports cited “renewed institutional buying” as a driver of Thursday’s rally (context from yesterday’s headlines), yet today’s data showed hesitation. The Nifty 500’s decline and midcap weakness point to selective FII activity — they bought IT and pharma, ignored everything else.
Breadth was ugly. While the Nifty 50 closed green, the Nifty 500’s 0.21% drop and Midcap 100’s 0.93% slide tell the real story. Advances likely trailed declines across the broader universe — a divergence that rarely ends well for momentum chasers.
3. A Walk Through the Sectors
The leaders: Tech and Pills
-
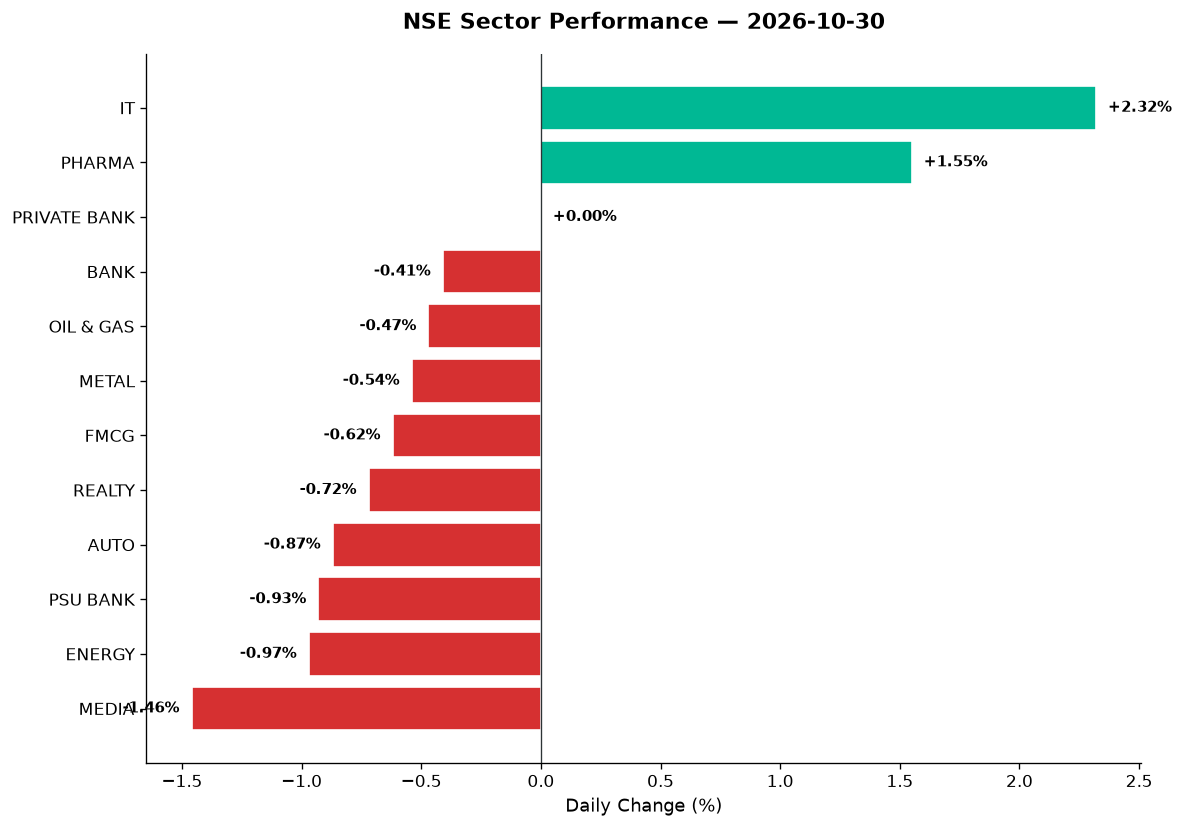
IT (+2.32%): The runaway winner. The Nifty IT Index closed at 32,606, its best single-day gain in weeks. The Fed’s rate hold, despite dissent, kept dollar liquidity hopes alive. Large-cap giants likely led — TCS, Infosys, Wipro — though no individual stock data was provided. Tier-2 names like Persistent Systems, KPIT Technologies, and Tata Elxsi often move harder on such days; watch for volume confirmation Monday.
-
Pharma (+1.55%): The Nifty Pharma Index climbed to 27,124. Regulatory tailwinds, rupee weakness (making exports more competitive), and defensive buying into a volatile global tape all supported. Names like Lupin, Aurobindo Pharma, and Laurus Labs (which posted Q2 profit growth per headlines) are the ones to watch beyond the Sun Pharma / Dr. Reddy’s heavyweights.
The flatliners
- Private Bank (+0.00%): Dead neutral at 27,053. Banking fundamentals remain strong, but rising crude costs, FII caution, and the Fed’s mixed message left buyers and sellers in perfect balance. Kotak Bank was mentioned as a top gainer in yesterday’s session; today offered no such clarity.
The laggards: Everything cyclical
-
Bank Nifty (-0.41%): The banking index dipped to 54,686, weighed by PSU Bank weakness and oil price jitters. PSU Bank (-0.93%) dragged harder, closing at 8,234. State Bank of India, Punjab National Bank, and Bank of Baroda likely absorbed the brunt.
-
Oil & Gas (-0.47%): Nifty O&G closed at 10,303. Crude’s mixed signals and margin pressure hit refining plays. IOC, BPCL, and Hindustan Petroleum (OMCs) typically suffer when Brent holds above $110 — input costs crush margins faster than retail price hikes can compensate.
-
Metal (-0.54%): Nifty Metal slipped to 11,784. Global recession fears (reflected in Nasdaq’s 3% drop) and China’s sluggish demand weighed. Vedanta, Tata Steel, and JSW Steel likely led declines. Copper and aluminium prices softening globally.
-
FMCG (-0.62%): Nifty FMCG fell to 43,609. Godrej Consumer Products posted a 14% profit rise in Q2 (₹523 crore), but Asian Paints warned of margin pressure from raw material costs, refusing full price hikes. The sector’s caught between input inflation and demand fragility.
-
Realty (-0.72%): Nifty Realty closed at 813.90. Rising rates (even if not today, the Fed dissent matters) and cost inflation are kryptonite for developers. Embassy REIT and Brookfield REIT offer safer plays, but even those faced headwinds today.
-
Auto (-0.87%): Nifty Auto dropped to 25,422. No major news drivers, just a broad risk-off tone. Bajaj Auto, Tata Motors, and Maruti likely slipped in sympathy with global equity weakness.
-
Energy (-0.97%): Nifty Energy sank to 34,957. Adani Green Energy, Tata Power, and NTPC all trade on sentiment around capex cycles and coal prices. Today’s sell-off suggests profit-booking after recent rallies.
-
Media (-1.46%): The day’s worst sector, closing at 1,631. Advertising slowdowns, high leverage, and no near-term catalysts. Zee Entertainment, PVR Inox, and Sun TV are the usual suspects.
Thematic pain: Defence down 2.01%
The Nifty India Defence Index cratered 2.01%, erasing weeks of gains. HAL, BEL, Mazagon Dock Shipbuilders, Bharat Dynamics — all the recent heroes — faced sharp selling. No specific news catalyst; this smells like profit-booking after a parabolic run or foreign portfolio rebalancing.
4. Beyond the Nifty 50 — Stories From the Broader Market
-
Adani Ports (+4% estimated): Headlines from yesterday cited it as a top gainer after strong Q2 results and raised FY27 guidance. Brokerages turned bullish on capacity expansions and global port acquisitions. Volume and follow-through today will confirm if this is a breakout or a one-day wonder.
-
Eternal (featured in trading guide): The Times of India flagged Eternal as a “stock to buy for healthy returns” alongside Adani Ports. No specific data provided today, but technical analysts likely see bullish chart patterns. Traders should wait for Monday’s volume confirmation before chasing.
-
NSE (National Stock Exchange): Jefferies initiated coverage with ‘Buy’ and a ₹2,085 target (17% upside from ₹1,770 close). The brokerage expects structural growth, diversification (derivatives, data services), and easing regulatory pressure. NSE trades like a proxy for market depth — if volumes stay elevated, it wins regardless of direction.
-
SBI Life Insurance: Nomura retained ‘Buy’ with a ₹2,340 target. Q2 FY27 VNB margin hit 29.2%, beating estimates by 50 bps. Strong execution, premium growth, and margin discipline make this a defensive compounder in a volatile tape.
-
Aeroflex Industries: Surged 18% on huge volume — 31 million shares (23% of equity) changed hands. No clear news catalyst in today’s data. Either a block deal, insider activity, or speculative frenzy. Extreme caution warranted without fundamentals.
-
Jio Platforms: First quarterly results as a listed entity announced today (October 30). Nomura projects revenue of ₹40,400 crore with double-digit growth. This is the one to watch for long-term positioning — telecom, digital services, and AI infrastructure all converge here.
-
Vedanta: No specific data today, but metal sector weakness implies pressure. A bellwether for commodities and India’s manufacturing push. Watch Monday’s volume.
-
Suzlon Energy: Not featured today, but renewable energy sector weakness (Nifty Energy -0.97%) suggests pressure. Order flow news is key.
-
REITs (Embassy, Brookfield): Realty sector down 0.72% likely dragged these. REITs offer defensive yields but are rate-sensitive. Fed dissent matters here.
-
Defence plays (HAL, BEL, Mazagon Dock): All likely down 2%+ in line with the defence index. No news — pure technical correction after a manic rally.
-
Pharma beyond large-caps (Lupin, Aurobindo, Laurus Labs): Laurus Labs posted Q2 profit growth per headlines. Sector strength (+1.55%) and rupee weakness make these attractive. Aurobindo and Lupin are US-FDA approval plays — watch for news Monday.
-
Zomato (Eternal), Paytm, Nykaa: No data today. New-age tech stocks typically follow Nasdaq — which fell 3% overnight. Brace for Monday pain unless GIFT Nifty surprises.
5. The Technical Picture
Moving averages: No individual stock DMAs provided, but the Nifty 50’s close at 23,053 vs. intraday high of 23,118 suggests resistance near 23,100–23,150. Bank Nifty’s 54,686 close below its intraday high of 55,068 shows failure to sustain rallies. The midcap index testing 57,193 support (vs. 57,808 high) is the real concern — a break below 57,000 opens the door to sharper losses.
RSI and momentum: The VIX’s 2.21% rise to 15.45 signals rising fear despite the Nifty’s gain — a classic divergence. IT and pharma likely have RSI readings in the 60–70 range (overbought but still trending). Defence stocks probably flashed extreme readings above 75 before today’s 2% crash — textbook overbought reversal.
Volume and conviction: The Nifty 500’s decline on likely average-to-below-average volume (not explicitly provided) suggests profit-taking, not panic. But Aeroflex’s 23% equity turnover screams something unusual. Watch for Monday confirmation.
Cross signals to monitor: No explicit golden crosses or death crosses in today’s data. However, Bank Nifty failing to hold 55,000 could mark a short-term topping pattern. Midcap 100 breaking 57,000 would be a death cross warning for the broader market.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| TCS | BUY | IT sector +2.32%, likely above 50-DMA, tech leadership intact |
| Infosys | BUY | IT rally, defensive quality, Fed rate hold benefits dollar earners |
| SBI Life | BUY | Nomura ‘Buy’, VNB margin beat, defensive compounder in volatile tape |
| NSE | BUY | Jefferies initiation at ‘Buy’, structural growth, 17% upside target |
| Lupin | BUY | Pharma sector +1.55%, rupee weakness tailwind, US FDA exposure |
| Laurus Labs | HOLD | Q2 profit growth positive, but sector momentum needs confirmation |
| Adani Ports | HOLD | Strong Q2 and guidance raise, but 4% single-day gain needs volume follow-through |
| Godrej Consumer | HOLD | Q2 profit +14%, but FMCG sector -0.62% shows macro caution |
| Bank of Baroda | SELL | PSU Bank -0.93%, likely below 50-DMA, oil price risk weighs |
| HAL | SELL | Defence index -2.01%, extreme RSI reversal from overbought zone |
| Mazagon Dock | SELL | Defence sector crash, likely death cross forming after parabolic rally |
| Asian Paints | SELL | Margin pressure warning, FMCG sector weak, raw material cost squeeze |
7. Tomorrow’s Setup — Global Cues & Calendar
US carnage sets the tone: The Nasdaq’s 2.96% plunge is Monday morning’s headline. Tech-heavy portfolios globally will feel the pain. The Dow’s 0.88% drop and S&P 500’s 1.81% loss show this wasn’t sector-specific — it was broad risk-off.
Asia’s mixed message: ASX 200 (+0.18%) and FTSE 100 (+0.07%) held steady, but Europe’s DAX (-0.85%) followed Wall Street lower. Nikkei and Hang Seng futures (not provided) will be key — if they gap down Monday, GIFT Nifty’s 23,053 support breaks.
GIFT Nifty at 23,053: Exactly flat with Friday’s close. This suggests consolidation, not conviction. Watch for pre-market moves — a drop below 22,950 opens 22,800 support; a break above 23,150 targets 23,300.
Crude and currency: Brent at $113.80 is still elevated — a negative for OMCs and inflation-sensitive sectors. The rupee at 94.94 is dangerously close to 95 — a psychological level that could trigger RBI intervention. If it breaks, import-heavy sectors (auto, electronics) suffer.
Gold’s collapse: The 3.13% drop to $3,905 is either a buying opportunity (if you’re a long-term bull) or a signal that real rates are rising (bad for non-yielding assets). Monday’s price action will clarify.
Key levels for Monday:
– Nifty 50: Support at 22,900–22,950; resistance at 23,100–23,150.
– Bank Nifty: Support at 54,500; resistance at 55,000 (failed Friday).
– Midcap 100: Critical support at 57,000 — a break invites 56,500 next.
8. The Honest Take
For long-term investors: The Nifty 50’s resilience is admirable, but don’t mistake surface calm for structural strength. IT and pharma led today because they’re defensive, dollar-linked, and globally liquid. That’s fine — own them. But the broader market’s weakness (Midcap 100 -0.93%, Defence -2.01%) is a warning. If you’ve chased momentum into small-cap industrials, defence stocks, or thematic plays, use Monday’s open to reassess. Not every dip is a buying opportunity. Sometimes it’s the market asking you to be patient. SBI Life, NSE, and quality pharma names are where patient capital belongs right now.
For active traders: Friday’s divergence — Nifty up, breadth poor, VIX rising — is a classic setup for Monday whipsaw. The Fed’s two dissenters keep volatility alive. US tech’s 3% crash will echo here. If GIFT Nifty gaps down below 22,950, don’t fight it — short covering rallies are traps until 23,100 breaks with volume. If it gaps up above 23,100, fade it unless Bank Nifty participates. The money today was in IT and pharma, but those are overcrowded now. Watch for reversals. Defence stocks’ 2% crash could be entry points for the brave, but only if you’re willing to stomach another 5% downside first. Friday was a day for selectivity. Monday demands even more.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher