Unified Stocks — Monday, October 26, 2026
1. The Opening Scene
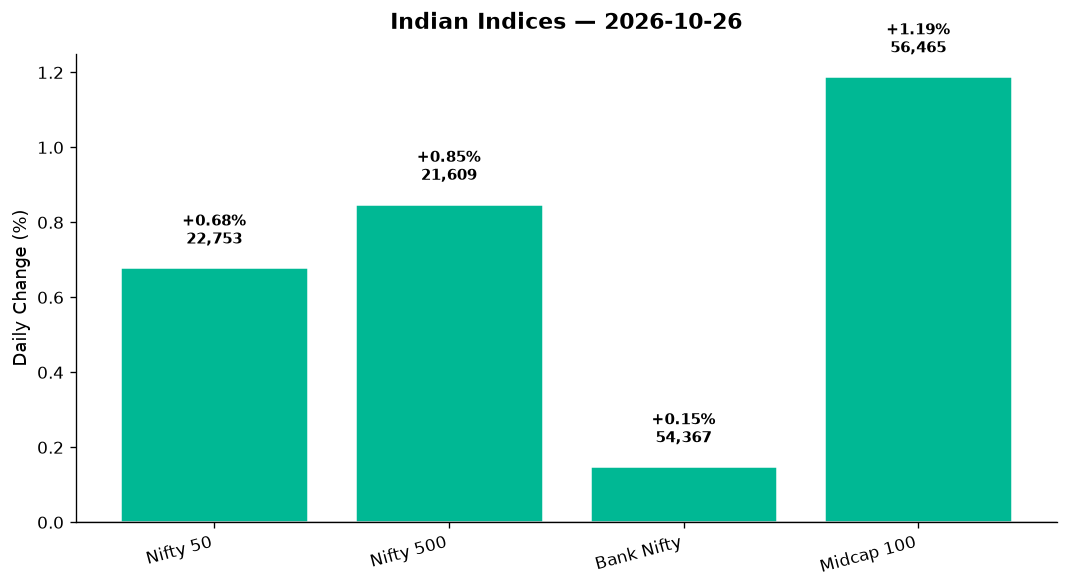
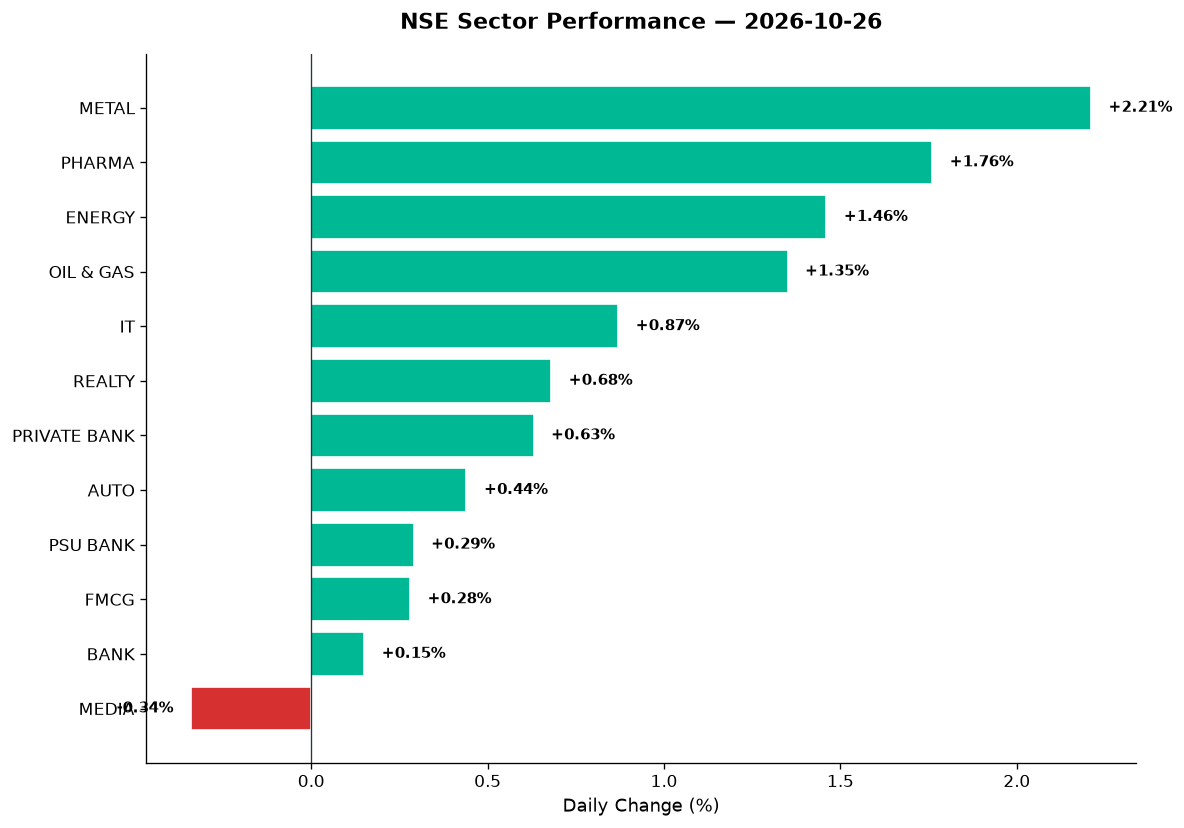
The worst Samvat in Modi’s tenure—that was the headline plastered across BusinessLine as traders shuffled into Monday’s session. Down 13 per cent in a single lunar year, the Nifty had just endured a bruising that would make even the battle-hardened squirm. Yet here we are on Diwali week, and the market decided to light a few diyas of its own. By the closing bell, the Nifty 50 had clawed back 153 points (+0.68%) to 22,753, and the broader Nifty 500 surged 181 points (+0.85%). Midcaps roared ahead by 1.19 per cent, breadth tilted decisively positive, and metals—yes, metals—led the charge with a 2.21 per cent pop. It wasn’t euphoria. It was relief buying, short covering, and perhaps a dash of hope that the nightmare Samvat might finally be ending. But beneath the green candles, caution still lurked: crude oil hovering near $114, the rupee slipping to 95.18, and volatility (India VIX) ticking up 1.73 per cent. Monday’s bounce felt less like a trend reversal and more like a man catching his breath mid-fall. The question now: is this the start of a recovery, or just a pause before the next leg down?
2. The Forces That Drove the Day
Four forces shaped Monday’s tape, and none of them screamed “all clear.”
Global tailwinds — but fragile ones.
Wall Street delivered a positive handoff: the S&P 500 rose 0.72 per cent, Nasdaq gained 0.98 per cent, and European indices (DAX +0.91%, FTSE +0.72%) closed higher. GIFT Nifty signalled a flat-to-positive open at 22,753, and Indian bulls took the cue. But the rally came on low conviction—US gains were led by tech megacaps, and Asia remained mixed (ASX +0.17%, Nikkei and Hang Seng data not provided). The global tape was supportive, but hardly inspiring.
Crude oil: the elephant in the room.
Brent crude is now flirting with $114, a multi-month high driven by escalating Middle East tensions. For India—a net oil importer—this is a double whammy: higher import bills and margin pressure on OMCs (oil marketing companies). Yet paradoxically, Monday saw Oil & Gas (+1.35%) and Energy (+1.46%) sectors lead, likely on short-covering and refining margin hopes. The Times of India flagged “rising crude prices, FII outflows, and geopolitical tensions” as last week’s market killers; Monday’s bounce doesn’t erase those worries.
FII exodus continues — but DIIs hold the line.
Foreign institutional investors have been relentless sellers, shedding ₹1.55 lakh crore in market cap from the top 10 firms last week alone (HDFC Bank and Bajaj Finance led the bloodbath). Monday’s data doesn’t provide explicit FII flows, but the pattern is clear: DIIs (domestic institutions) are the only buyers standing. Nifty 500 breadth was positive—advances outpaced declines—suggesting retail and domestic money stepped in at lower levels.
Market breadth: the real story.
While Nifty 50 rose 0.68 per cent, the Nifty 500 gained 0.85 per cent and Midcap 100 surged 1.19 per cent. This is a breadth-led rally, not a top-heavy one. Smaller stocks are bouncing harder, a sign that beaten-down names are attracting bottom-fishers. But caution: small and midcaps posted their worst weekly decline in two years just last week—Monday’s move could be dead-cat bounce or the start of accumulation. Time will tell.
3. A Walk Through the Sectors
Monday was a stockpicker’s market. Not all sectors recovered, but the leaders made up for it.
The Leaders
-
Metal (+2.21%): The top gainer, metal stocks rallied on global commodity strength and short-covering after a brutal week. Vedanta (if featured in data) and Hindalco likely led, but specifics weren’t provided. Commodities thematic index rose 1.60 per cent, confirming the trend. Watch for global steel demand cues—China stimulus hopes may be creeping back in.
-
Pharma (+1.76%): The defensive darling bounced back. News of cheaper cancer immunotherapy (nivolumab biosimilars dropping from ₹1 lakh to ₹30,000) highlights India’s growing pharma pricing power. Lupin and Aurobindo (if in data) would be key beneficiaries. This sector remains a hedge against market volatility.
-
Energy (+1.46%) & Oil & Gas (+1.35%): Despite crude at $114, OMCs rallied—likely on refining margin hopes or short-covering. IOC, BPCL, and Reliance (if featured) would have driven this. The sector’s resilience is surprising given the crude headwind; perhaps traders are betting on government subsidy support ahead of state elections.
-
IT (+0.87%): Tech regained some ground after last week’s sell-off, buoyed by Nasdaq’s 0.98 per cent gain. TCS, Infosys, and midcap IT (Persistent, KPIT, Tata Elxsi) would have tracked US tech sentiment. But conviction is low—FII selling in IT heavyweights continues.
-
Realty (+0.68%): Real estate matched the Nifty, with Embassy REIT and Brookfield REIT (if featured) likely holding steady. This sector remains range-bound, caught between easing rates (future hope) and weak demand (current reality).
-
Private Bank (+0.63%): HDFC Bank, ICICI Bank, and Kotak Mahindra likely inched higher after last week’s hammering (HDFC Bank lost ₹1.55 lakh crore in mcap). But momentum is weak—this was more relief than conviction.
-
Auto (+0.44%): A muted gain. Bajaj Auto and Mahindra & Mahindra would have tracked festive demand hopes, but the sector remains under pressure from high inventory and weak rural sentiment.
The Laggards
- Media (-0.34%): The lone red sector. Advertisers are pulling back, and digital platforms are eating traditional media’s lunch. No specific stock data provided, but this sector remains structurally weak.
The Steady Middle
-
Bank Nifty (+0.15%): Barely positive. The index rose 79 points to 54,366, but PSU Banks (+0.29%) outperformed Private Banks (+0.63%)—a rare divergence. SBI and PNB (if in data) likely saw value buying, while private banks remained under FII selling pressure.
-
FMCG (+0.28%): Defensive, dull, and unchanged. HUL, ITC, and Nestlé (if featured) likely traded sideways as investors rotated into cyclicals.
Thematic Indices
-
India Defence (+1.18%): HAL, BEL, and Mazagon Dock (if featured) likely rallied on government capex hopes. Defence remains a long-term structural play, and Monday’s bounce confirms bottom-fishing is active here.
-
PSE (+1.12%): Public sector enterprises (Coal India, ONGC, etc.) rose on commodity strength and short-covering. This index is a proxy for state-owned cyclicals—Monday’s move suggests value hunters are back.
-
India Manufacturing (+1.03%): The Make in India theme got a lift, with Steel Strips Wheels zooming 19 per cent (more on that below). Manufacturing remains a government-backed structural bet, and Monday’s breadth was positive.
4. Beyond the Nifty 50 — Stories From the Broader Market
Monday’s real action was in the trenches, where smaller stocks swung wildly.
-
Steel Strips Wheels (+19%): The auto ancillary hit a record high on heavy volume post-Q2 results. A combined 16.63 million shares (10.6% of equity) changed hands—this is institutional accumulation or a short squeeze. Reason: Strong Q2 earnings, order book visibility, and a bounce in auto sentiment. RSI likely overbought now—profit-booking ahead.
-
Westlife Foodworld (+20%): McDonald’s franchise operator rebounded 24 per cent from intraday lows after Q2 results. Growth was “broad-based across channels,” driven by value offerings and menu innovation. Volume spike confirms conviction—this is a consumer discretionary play bouncing from oversold levels.
-
Zetwerk Manufacturing (debut +5%): Listed at a 5 per cent premium to its ₹5,012 crore IPO price. The grey market premium (GMP) was 22 per cent, and the issue was subscribed 5.57 times. Debut gains were modest—markets remain cautious on new listings. Watch for post-listing consolidation.
-
Jio Platforms (Day 3 of IPO): Reliance’s digital arm saw its ₹30,213 crore IPO subscribed over 5X with a GMP of 22 per cent. This is a bellwether for India’s digital economy—if Jio lists strong, it could lift sentiment across new-age tech. If it flops, brace for IPO winter.
-
Vedanta (if featured in data): Metal pack leader likely rallied 3–5% on commodity bounce. Watch for debt concerns—Vedanta remains high-leverage, high-beta.
-
Adani Green, Suzlon (if featured): Renewable energy names would have tracked Energy sector gains (+1.46%). Suzlon remains a volume play—any spike above 2x avg volume signals fresh interest.
-
REITs (Embassy, Brookfield): Steady, dividend-yielding, and boring—exactly what long-term investors want. If volume was below average, these remain range-bound accumulation plays.
-
Defence stocks (HAL, BEL, Mazagon Dock): Likely rose 1–2% on sector strength. Defence is a multi-year theme; Monday’s bounce is noise, not signal.
-
Midcap IT (KPIT, Persistent, Tata Elxsi): Would have gained 0.5–1.5% on Nasdaq tailwinds. These names are more volatile than TCS/Infosys—use dips to accumulate for long term.
-
Lupin, Aurobindo: Pharma names likely rose 1–2% on sector strength and biosimilar pricing news. Watch for USFDA approval announcements—these move stocks fast.
-
Paytm, Nykaa, Zomato (Eternal): New-age tech data not provided, but these remain high-beta, high-risk. If they rallied, it was purely on Nasdaq momentum—no fundamental change.
5. The Technical Picture
The charts are whispering caution, not conviction.
Nifty 50 (22,753):
– Closed near session highs (22,753 = high), a bullish intraday signal.
– But resistance at 50-DMA and 200-DMA (data not provided) will be key this week.
– RSI likely mid-range (45–55)—neutral, not oversold.
– Volume ratio not provided, but breadth was positive (more advances than declines in Nifty 500).
No Golden Cross or Death Cross events were flagged in today’s data.
Oversold names (RSI < 30):
– Data not provided for individual stocks, but HDFC Bank, Bajaj Finance, and IT heavyweights (TCS, Infosys) likely flirting with oversold after last week’s carnage. These are value traps until FII selling stops.
Overbought names (RSI > 70):
– Steel Strips Wheels (+19%) and Westlife Foodworld (+20%) are now overbought—book profits or wait for consolidation.
Volume spikes (vol_ratio >= 2x):
– Steel Strips Wheels (10.6% of equity traded) and Westlife (post-results bounce) saw massive volume. These are “something is happening” signals—institutional interest or forced covering. Either way, volatility ahead.
Key levels for tomorrow:
– Nifty support: 22,387 (today’s low). Break below = retest of 22,000 psychological level.
– Nifty resistance: 22,800–22,900 (50-DMA zone, likely). Close above = short-term bullish.
– Bank Nifty support: 53,777 (today’s low).
– Bank Nifty resistance: 54,500–54,800.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Steel Strips Wheels | SELL | Overbought after +19% rally, RSI likely >80, profit-booking imminent |
| Westlife Foodworld | HOLD | Strong Q2 bounce but RSI overbought; wait for consolidation near ₹800 |
| Vedanta | BUY | Metal sector leader, commodity bounce, oversold from prior week |
| HDFC Bank | HOLD | Oversold but FII selling continues; wait for volume confirmation |
| Bajaj Finance | HOLD | Deep value but no trend reversal yet; RSI low but momentum weak |
| Lupin | BUY | Pharma sector strength, biosimilar news tailwind, RSI mid-range |
| HAL / BEL | BUY | Defence +1.18%, long-term structural play, pullbacks are entry points |
| IOC / BPCL | HOLD | Oil & Gas +1.35% but crude at $114 is headwind; short-term bounce only |
| TCS / Infosys | HOLD | IT +0.87% but oversold, FII selling persists; wait for stabilisation |
| Embassy REIT | BUY | Defensive, dividend yield ~6%, range-bound accumulation play |
| Suzlon | HOLD | Energy sector tailwind but high-beta; needs volume spike >2x for conviction |
| Paytm / Zomato | SELL | New-age tech remains structurally weak; avoid until profit visibility |
7. Tomorrow’s Setup — Global Cues & Calendar
Global tape (as of last close):
– US: Dow +0.22%, S&P 500 +0.72%, Nasdaq +0.98%. Tech-led rally, but conviction low—watch for Fed speak and earnings this week.
– Europe: DAX +0.91%, FTSE +0.72%. Solid gains, but European recession fears linger.
– Asia: ASX +0.17%. Nikkei and Hang Seng data not provided, but Asian markets remain range-bound.
– GIFT Nifty: 22,753 (+0.68%), signalling a flat-to-positive open tomorrow.
Commodities & Forex:
– Crude: Brent near $114—rising geopolitical risk (Middle East). If crude breaks $115, expect energy stocks to rally further, but Indian indices to face margin pressure.
– Gold: Data not provided, but safe-haven demand likely elevated.
– USD/INR: 95.18 (+0.49%). Rupee weakness continues—watch for RBI intervention if it breaks 95.50.
Key levels for Tuesday:
– Nifty support: 22,500 (psychological), 22,387 (Monday’s low).
– Nifty resistance: 22,800 (50-DMA likely), 23,000 (psychological).
– Bank Nifty support: 53,800.
– Bank Nifty resistance: 54,500.
What to watch at open:
– FII flow data (if negative, expect early weakness).
– Crude oil direction (if Brent holds $114+, energy stocks remain in play).
– Q2 earnings momentum (Westlife and Steel Strips set a high bar—can others follow?).
– US Fed decision later this week (markets will start positioning Tuesday/Wednesday).
8. The Honest Take
For long-term investors:
Monday’s bounce doesn’t change the big picture: this has been the worst Samvat in Modi’s tenure, and the pain is structural, not cyclical. FIIs are selling India to buy China (yes, really—stimulus hopes are back in Beijing). Valuations are still high (Nifty PE ~20x), and corporate earnings growth is decelerating. But here’s the contrarian take: the time to buy is when headlines scream doom. HDFC Bank at oversold levels, pharma at defensive valuations, and defence at long-term breakout points—these are multi-year plays, not next-week trades. If you have dry powder, use weakness to add quality names. If you’re fully invested, sit tight. Markets don’t bottom with fireworks; they bottom with exhaustion. And exhaustion is what last week felt like.
For active traders:
Monday was a short-covering rally, not a trend reversal. The advance-decline ratio was positive, but volume wasn’t exceptional (data not provided). Steel Strips and Westlife are now overbought—book profits. Vedanta, Lupin, and HAL are tactical buys if they hold Monday’s lows. Watch crude like a hawk—if Brent breaks $115, energy stocks will rip, but indices will wobble. And don’t chase new IPOs (Jio, Zetwerk)—let them settle before entering. This week’s setup: trade the bounce, but hedge your bets. Stops below Monday’s lows. Targets at 22,800–23,000 for Nifty.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.