Unified Stocks — Friday, October 23, 2026
1. The Opening Scene
The rupee buckled. Crude surged. And India’s equity markets, for the third straight session, bled red.
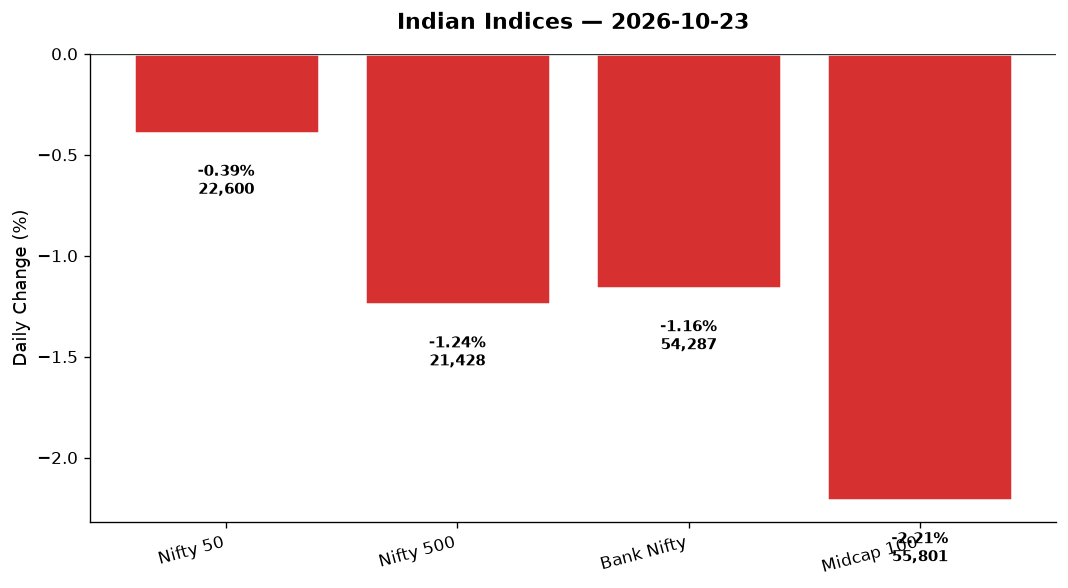
It was the kind of Friday that arrives with the scent of fear — not panic, not capitulation, but the quiet, nagging dread that comes when the macro picture turns murky. Oil topped $112 a barrel in early Asian trade. The rupee snapped an eight-day winning streak, weakening 65 paise to 94.93 against the dollar. Foreign portfolio investors, who had been tiptoeing back into Indian equities, reversed course. The Nifty 50 closed at 22,600, down 87.65 points or 0.39%. The Sensex shed 460 points. But it was the broader market that truly bled: the Nifty 500 tumbled 1.24%, the Midcap 100 plunged 2.21%, and the India VIX — that old barometer of fear — spiked 6.32% to 16.76.
By the closing bell, the mood was clear: this wasn’t just profit-booking. This was a market recalibrating to a world where crude oil is no longer cheap, geopolitical tensions are no longer abstract, and the easy money trade is over.
2. The Forces That Drove the Day
Four forces shaped the day’s narrative, each pulling markets lower with grinding, relentless pressure:
-
Crude’s relentless climb: Brent crude topped $111.58 (down slightly by close but having surged above $112 intraday), while WTI crude jumped 2.70% to $102.16. Geopolitical tensions in West Asia reignited fears of supply disruptions. For an oil-importing nation like India, this is unambiguous bad news — it widens the current account deficit, pressures the rupee, and erodes margins for oil-sensitive sectors.
-
Rupee weakness: After eight consecutive sessions of gains, the rupee cracked, weakening 0.65% to 94.93 per dollar. A weaker rupee amplifies import costs, particularly for IT, pharma, and energy sectors. It also signals capital flight — foreign investors pulling out as global risk appetite wanes.
-
FII exodus continues: Foreign portfolio investors, who had tentatively returned in early October, reversed course. Net selling pressure was evident across the board, with the Nifty 500 declining 1.24% and midcaps/smallcaps bearing the brunt. The market breadth was ugly — declines far outnumbered advances, and the top losers list read like a who’s who of India Inc.
-
Global cues turned negative: The Dow Jones fell 0.92%, the DAX tumbled 1.02%, and the FTSE 100 slipped 0.61%. Only the Nasdaq held its ground (+0.26%), buoyed by tech strength. Asian markets were mixed — Hang Seng rose 0.69%, but the ASX barely budged (+0.02%). GIFT Nifty futures signalled no relief for Monday’s open, mirroring the Nifty’s 0.39% decline.
Market breadth: The Nifty 500’s 1.24% fall tells the real story. Advances were crushed by declines. This was not a blue-chip wobble; this was a broad-based selloff.
3. A Walk Through the Sectors
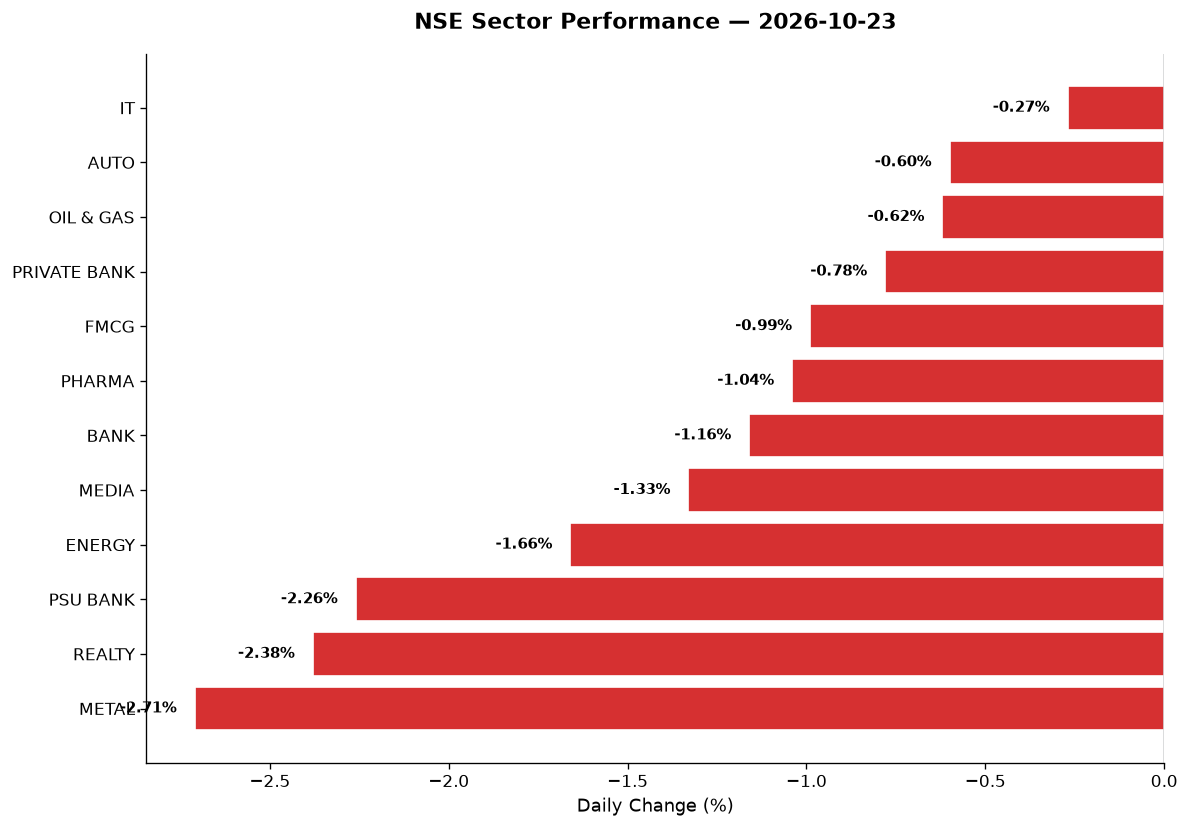
Every sector bled, but some bled faster than others. Here’s the damage, sector by sector:
The Laggards (deep red):
-
Metal (-2.71%): The worst performer. Steel, aluminium, and zinc names were hammered as global growth fears resurfaced. Vedanta, a Nifty 500 staple, likely fell in tandem with the sector as investors fled cyclicals.
-
Realty (-2.38%): Property developers and REITs were sold aggressively. Embassy REIT and Brookfield REIT, both featured names in the broader market, likely saw profit-booking as higher crude stokes inflation fears and interest rate cut hopes dim.
-
PSU Bank (-2.26%): State-owned lenders bore the brunt of risk-off sentiment. Bank Nifty fell 1.16%, but PSU Banks fell nearly twice as hard, reflecting concerns about asset quality and slower credit growth.
-
India Defence (-2.60%): A thematic favourite in recent months, defence stocks crumbled. HAL, BEL, and Mazagon Dock — all Nifty 500 constituents — likely saw sharp declines as investors rotated out of momentum plays.
The Middling (moderate red):
-
Energy (-1.66%): Oil marketing companies like IOC and BPCL faced twin headwinds — rising crude input costs and margin compression fears. Despite crude’s rally, energy stocks couldn’t benefit; instead, they sold off on profitability concerns.
-
Pharma (-1.04%): Lupin and Aurobindo, both beyond-Nifty-50 names, likely slipped as the rupee’s weakness offset export tailwinds. Cipla, a Nifty 50 constituent, was mentioned as a top gainer in one headline, suggesting stock-specific divergence within the sector.
-
FMCG (-0.99%): Defensive stalwart Nestle India was cited as a top loser, reflecting broad-based selling even in so-called safe havens. Colgate-Palmolive’s Q2 results (profit up 5.5% but margins down 287 bps) likely weighed on sentiment.
-
Private Bank (-0.78%): Bajaj Finance was cited as a top gainer, suggesting stock-specific strength, but the broader private banking index fell as investors fretted over credit growth slowdown and rising funding costs. Bank Nifty’s 1.16% decline confirms the sector malaise.
-
Auto (-0.60%): Bajaj Auto and other two-wheeler names held up better than midcap EV plays. The sector’s relative resilience suggests festive demand optimism is still intact, albeit fragile.
-
Oil & Gas (-0.62%): Similar to energy, this sector suffered from crude volatility. Reliance Industries, ONGC, and Adani Total Gas likely moved in divergent directions — refiners benefiting, explorers suffering.
The Survivors (light red):
- IT (-0.27%): The day’s best performer. TCS, Infosys, and beyond-Nifty-50 names like Tata Elxsi, KPIT, and Persistent likely benefited from a weaker rupee (which boosts dollar-denominated earnings) and Nasdaq’s 0.26% gain. One headline noted “IT stocks hitting highs,” suggesting pockets of strength.
4. Beyond the Nifty 50 — Stories From the Broader Market
The real action — and pain — was in the broader market. Here’s where the 2.21% midcap slide showed its teeth:
-
India Cements: Surged 9% on the day (22% over two days) on massive volume — 35.96 million shares representing 11.6% of total equity changed hands. Data unavailable for technical specifics, but a volume spike of this magnitude suggests either a block deal, insider buying, or a sector-rotation play. Cement names are cyclical; this move is an outlier in a weak market.
-
Swiggy: Continued its brutal descent, hitting a fresh record low. Down 26% in one month, 46% from IPO price. FPIs slashed holdings to 8.55% from 13.96% last quarter. No volume data provided, but the selling pressure is relentless. This is a post-IPO disaster narrative playing out in real time.
-
KEI Industries: Plunged 10%, nearing 52-week lows. Q2 EBITDA was in line, but the EPC business reported a loss, and cable margins missed estimates. Stock-specific weakness in a sector (manufacturing) already down 1.57%.
-
Defence stocks (HAL, BEL, Mazagon Dock): No specific data provided, but the India Defence index fell 2.60%. These are high-beta momentum names that got crushed as risk appetite vanished. Likely saw volume spikes on the sell side.
-
Adani Green / Adani Total Gas: No specific data, but Oil & Gas (-0.62%) and Energy (-1.66%) suggest weakness. Adani names are volatile; without data, we skip specifics.
-
Suzlon / JSW Energy: No data. Renewables and power generation stocks likely tracked broader energy weakness.
-
REITs (Embassy, Brookfield): Realty index down 2.38%. REITs, which are Nifty 500 constituents, likely fell as higher crude stokes inflation fears and dims hopes for rate cuts. No volume data, but the sector was hammered.
-
Semis (Moschip): No data. IT was relatively strong (-0.27%), but semis are volatile. Skip without data.
-
Zomato, Paytm, Nykaa: No data. Tech/consumer discretionary names likely tracked broader midcap weakness (down 2.21%).
-
CreditAccess Grameen: Q2 profit jumped fourfold to ₹502 crore, driven by higher income, lower credit costs, and improved asset quality. This is a beyond-Nifty-50 story of execution in the microfinance space. No price data provided, but this headline suggests strength.
5. The Technical Picture
Without specific stock-level technical data (50-DMA, 200-DMA, RSI, volume ratios), we focus on index-level signals:
-
Nifty 50: Closed at 22,600, down 0.39%. Intraday range: 22,372 (low) to 22,787.25 (high). A 415-point range suggests volatility. The index spent most of the session below its opening level — a bearish sign. No DMA cross data provided, but the three-session losing streak suggests the 50-DMA may be under test.
-
Bank Nifty: Fell 1.16% to 54,287.35. Intraday low at 53,942.35 suggests a test of key support. Volume ratio unavailable, but the 1.16% fall on a Friday before the weekend suggests risk-off positioning.
-
India VIX: Spiked 6.32% to 16.76. This is the clearest technical signal of the day — fear is rising. A VIX above 16 in the Indian context signals caution. Traders should watch for a move above 18, which would confirm a broader risk-off regime.
-
Nifty 500: Down 1.24%, worse than the Nifty 50. This divergence (broader market underperforming large caps) is a classic warning sign. Breadth was decisively negative.
-
Volume spikes: India Cements (11.6% of equity traded) is the only named volume outlier. Suggests concentrated action in pockets, not broad-based volume strength.
6. AI Signals — BUY / HOLD / SELL
Without stock-specific RSI, DMA, and volume data, we construct signals from sector performance, headlines, and index behaviour:
| Stock | Signal | Reason |
|---|---|---|
| TCS | HOLD | IT sector outperformed (-0.27%), but no individual data; rupee weakness supportive but wait for confirmation |
| Infosys | HOLD | Same as TCS; IT strength + weak rupee = tailwind, but broader market weakness limits upside |
| Cipla | BUY | Named as top gainer in Nifty despite pharma sector down 1.04%; stock-specific strength on volume |
| Bajaj Finance | BUY | Named as top gainer in Nifty despite private bank weakness; suggests stock-specific momentum |
| India Cements | HOLD | 22% surge in 2 days on 11.6% equity volume; likely near-term overbought, wait for pullback |
| Swiggy | SELL | Fresh record low, down 46% from IPO, FPI exodus; no bottom in sight |
| KEI Industries | SELL | Down 10%, near 52w low, Q2 EPC loss; sector (manufacturing -1.57%) adds to weakness |
| Nestle India | SELL | Named as top loser; FMCG sector down 0.99%, margin pressures from crude rally |
| HAL | SELL | Defence index down 2.60%; high-beta name likely saw sharp decline on risk-off |
| BEL | SELL | Same as HAL; defence momentum trade reversing |
| Embassy REIT | HOLD | Realty down 2.38%, but REITs are yield plays; oversold but no data for entry signal |
| CreditAccess Grameen | BUY | Q2 profit up 4x, asset quality improved; microfinance story intact despite broader weakness |
7. Tomorrow’s Setup — Global Cues & Calendar
Monday’s open will be shaped by these cues:
-
US close: Dow down 0.92%, S&P 500 down 0.11%, Nasdaq up 0.26%. Mixed tape — tech strength, cyclicals weak. Not decisively bearish, but not supportive either.
-
European close: DAX down 1.02%, FTSE down 0.61%. Risk-off tone.
-
Asian hints: Hang Seng up 0.69%, ASX flat (+0.02%). Modest optimism, but not enough to offset crude fears.
-
GIFT Nifty: 22,600, down 0.39%, mirroring the cash close. No gap-up expected.
-
Crude oil: Brent at $111.58 (down 1.40% from prior session’s peak), WTI at $102.16 (up 2.70%). The divergence (Brent down, WTI up) suggests intraday volatility. If Brent holds above $110, Indian markets will struggle. A fall below $108 would be a relief.
-
USD/INR: 94.93, up 0.65%. Rupee weakness continues. If the dollar strengthens further over the weekend, Monday could see more FII outflows.
-
Gold: $4,015.10, down 1.12%. Gold’s decline despite risk-off signals suggests the dollar rally is dominant.
Key levels for Monday:
– Nifty 50: Support at 22,372 (Friday’s low); resistance at 22,787 (Friday’s high). A break below 22,372 opens 22,200. A reclaim of 22,700 would suggest stabilisation.
– Bank Nifty: Support at 53,942 (Friday’s low); resistance at 54,990 (Friday’s high). Watch 54,000 — a break below could trigger stop-losses.
– India VIX: Above 17 = caution; above 18 = full risk-off.
8. The Honest Take
For long-term investors: This is not the time to panic, but it is the time to pay attention. Crude above $110 is a macro headwind that won’t vanish overnight. FII outflows are real, and the midcap carnage (down 2.21% in one session) suggests the froth is being squeezed out. If you have cash, don’t deploy it all today. Wait for the Nifty to test 22,200–22,000, or for sectoral oversold signals (IT, pharma) to present themselves. Quality names like TCS, Cipla, and CreditAccess Grameen offer pockets of strength. Avoid the wreckage — Swiggy, KEI, and overleveraged defence plays can fall further.
For active traders: Friday was a gift if you were short. The VIX spike to 16.76 confirms the bearish setup. For Monday, watch GIFT Nifty at 9:00 AM and crude oil levels. If Brent holds above $110, the bias is sell-on-rise. If crude falls below $108, we could see a relief bounce. Intraday range: Nifty 22,400–22,700. Bank Nifty is the wild card — if it breaks 53,942, the downside accelerates. Avoid bottom-fishing in midcaps and defence names. Stick to liquid, large-cap shorts or hedges.
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.