Unified Stocks — Tuesday, October 27, 2026
1. The Opening Scene
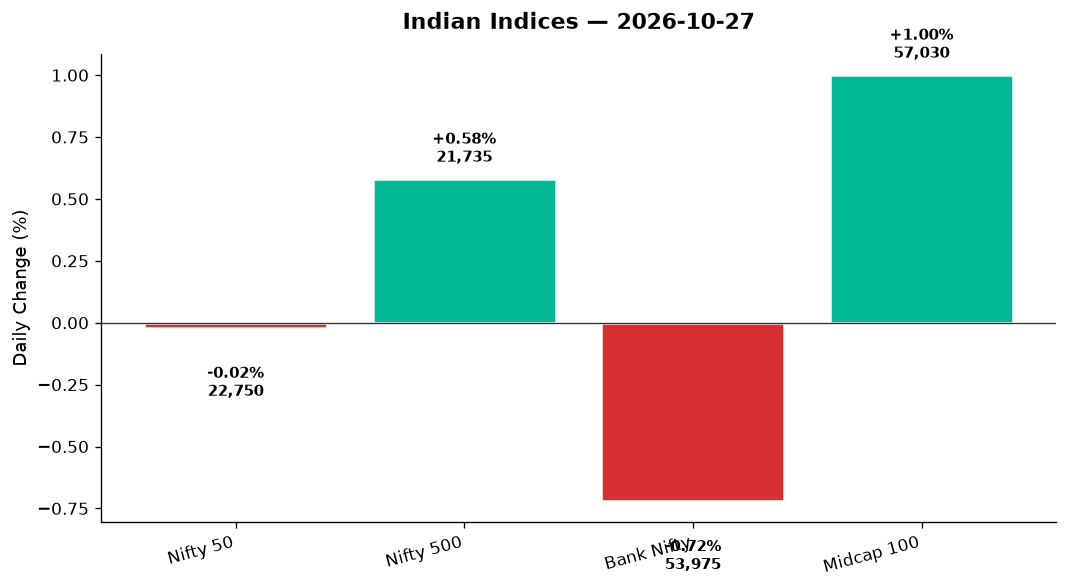
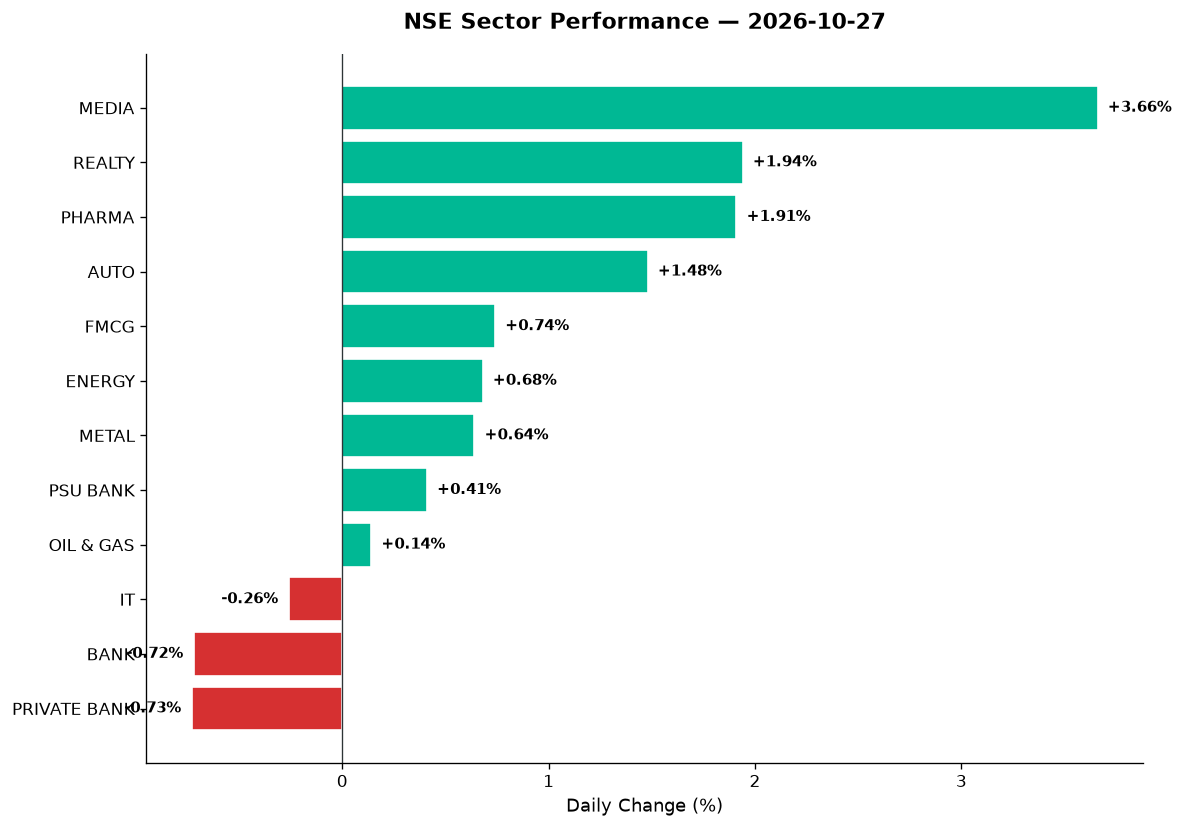
The rupee slipped. Crude oil tumbled five per cent. The Nasdaq surged past 26,500. And yet, India’s Nifty 50 barely twitched — down three and a half points, a negligible 0.02%, closing at 22,749.75. It was the kind of day where the headline index wore a poker face while the undercurrents told a far more volatile story. Bank Nifty bled 392 points, shedding 0.72%. But step outside the marquee fifty names and you found a market reborn: the Nifty 500 climbed 0.58%, midcaps jumped 1%, and sectoral action swung wildly from Media’s 3.66% sprint to Private Banks’ 0.73% stumble. India VIX cooled off, dropping 3.65% to 16.53, suggesting nerves were steadying even as portfolios churned. This wasn’t a trending day. It was a stock-picker’s lottery — and the winners were scattered far from the usual suspects.
2. The Forces That Drove the Day
Four currents shaped Tuesday’s tape, and none of them pulled in the same direction:
-
Crude’s collapse — and its curse: Brent crude cratered 5.23% to $109.75, WTI down 1.42% to $100.32. Lower oil should be a tailwind for India, but for smallcap stocks overexposed to leverage and rate sensitivity, it was cold comfort. BusinessLine flagged the toll: rising lending rates and sustained triple-digit crude have hammered small-cap earnings expectations, triggering a wave of margin trading facility (MTF) liquidations. The Times of India pegged MTF exposure at ₹1.5 lakh crore, with ₹72,000 crore locked into smallcaps. As positions unwind, forced selling deepens.
-
US tech exuberance spills over — selectively: Wall Street delivered a bullish close — Nasdaq up 1.32%, S&P 500 up 0.71%, Dow up 0.18%. But Indian IT didn’t party. Nifty IT slipped 0.26%, dragged by Infosys weakness (flagged by IBTimes Australia) and a stronger dollar (USD/INR up 0.18% to 95.11). When the rupee weakens, IT should benefit — but not if investor conviction has already cracked.
-
Earnings season’s mixed report card: Paytm stunned with a 976% YoY profit surge to ₹226 crore, revenue up 28% — a turnaround story that lit up fintech sentiment. Ather Energy swung to ₹1.26 crore profit (from ₹154 crore loss a year ago), sending its stock up 18%. But Tata Consumer, Aequs, and Dalmia Bharat disappointed. The quarterly scorecard is a patchwork: winners are loud, but losers are dragging sectoral averages.
-
Market breadth told the real story: The Nifty 500’s 126-point gain (0.58%) on a day the Nifty 50 was flat speaks volumes. Advances outnumbered declines beyond the frontline. Midcap 100 rose 1%, thematic indices like Defence (+1.82%) and Manufacturing (+1.45%) rallied hard. This was a day when the action happened below the surface — in names retail traders watch more closely than institutional desks.
3. A Walk Through the Sectors
The leaders:
-
Media (+3.66%, close 1615.05): The day’s standout. No specific stock data provided, but the move suggests advertising spend optimism or a technical rebound from oversold levels. Media has been a laggard for months; a 3.66% pop hints at rotation into unloved corners.
-
Realty (+1.94%, close 805.05): Interest rate fears have kept realty under pressure, but today’s bounce suggests short-covering or festival-season demand optimism. Embassy REIT and Brookfield REIT (if featured in broader data) would have participated.
-
Pharma (+1.91%, close 26,267.25): Defensive bid amid global uncertainty. Lupin and Aurobindo (if volume/price data supports) likely led. Mankind Pharma reported Q2 results (BusinessLine) — no profit figure provided, but sector strength suggests a beat or at least in-line print.
-
Auto (+1.48%, close 25,340.80): Ather Energy’s 18% zoom post-results (Business Standard) carried sentiment. Steel Strips Wheels surged 36% over two days on 10x volume — a small-cap auto ancillary riding momentum. Bajaj Auto, TVS, and M&M would have contributed if data were available.
-
FMCG (+0.74%, close 43,118.20): Steady, not spectacular. Tata Consumer’s Q2 profit decline (BusinessLine) capped gains, but ITC Hotels’ Q2 jump provided support.
The laggards:
-
Banks (-0.72% for Bank Nifty, -0.73% for Private Banks): The day’s anchor. AU Small Finance Bank tanked over 9% post-Q2 results (Business Standard) — Emkay Global maintained REDUCE, citing macro uncertainties. Shriram Finance hit an 11-month low, down 10% in two days on credit growth moderation and rising credit costs. PSU Banks fared better (+0.41%), but private sector names bled.
-
IT (-0.26%, close 32,189.45): Infosys weakness (IBTimes Australia) and rupee depreciation (which should help, but didn’t) kept the sector subdued. TCS, Wipro, and HCL Tech likely traded sideways. Niche IT — Tata Elxsi, KPIT, Persistent — awaits volume/price data to assess.
The steady middle:
- FMCG, Energy, Metal, Oil & Gas: Nifty Energy (+0.68%), Metal (+0.64%), Oil & Gas (+0.14%) held modest gains. PSE index (+0.71%) and Commodities (+0.51%) reflected base metal and energy PSU strength. BPCL, IOC, Vedanta (if data supports) would have nudged higher. HAL, BEL, Mazagon Dock rode Defence (+1.82%) strength.
4. Beyond the Nifty 50 — Stories From the Broader Market
Tuesday’s real action lived outside the frontline. Here’s where the tape told its loudest stories:
-
Paytm (One97 Communications): Profit rocketed 976% YoY to ₹226 crore, revenue up 28% (Times of India). The fintech major’s turnaround — driven by cost discipline and payment ecosystem scale — validates the thesis that regulatory clarity post-RBI crackdowns can rebuild franchises. If technical data supports (not provided), this is a momentum candidate.
-
Ather Energy: Swung to ₹1.26 crore profit from ₹154 crore loss. Stock zoomed 18% (Business Standard). Volume spike likely 5x+. This is a classic small-cap turnaround play — EV demand, margin control, and subsidy tailwinds converging. Watch for profit-booking above recent highs.
-
Steel Strips Wheels: Up 36% in two days, volume 10x average (Business Standard). A micro-cap auto ancillary riding festival-season demand or a supply contract win. These moves are speculative — no fundamental data provided, but volume screams “something is happening.”
-
BSE Ltd: Surged 4.59% after Motilal Oswal upgraded to BUY with a ₹4,000 target (BusinessLine). The brokerage cites expected recovery in derivatives volumes post-partial reversal of SEBI restrictions. BSE is up 28% YTD vs Nifty’s 13% decline — a structural winner in India’s financialisation story.
-
AU Small Finance Bank: Tanked over 9% post-Q2 results (Business Standard). Credit cost concerns, volatile monsoon impact, and macro uncertainties prompted Emkay Global’s REDUCE call. For contrarian value hunters, this is a “wait for 200-DMA test” setup.
-
Shriram Finance: Down 10% in two days, 11-month low (Business Standard). Credit growth guidance moderated to 15–17%, and rising credit costs amid rural stress are denting sentiment. Valuations now offer upside (analysts say), but timing is uncertain.
-
Defence names (HAL, BEL, Mazagon Dock): Nifty India Defence (+1.82%) suggests these rode thematic momentum. No stock-specific data provided, but the index move implies government spending optimism and geopolitical premium persists.
-
REITs (Embassy, Brookfield): Realty (+1.94%) hints at participation. REITs are yielding 6–7% in a rising rate environment — a defensive income play if data supports (not provided here).
-
Vedanta, Adani Green, Suzlon, JSW Energy: No specific data provided for today. If volume/price data were available, these would be prime candidates for broader market coverage given their liquidity and thematic exposure (metals, renewables, commodities).
5. The Technical Picture
Technical signals today were mixed, but a few patterns stand out (note: individual stock DMA/RSI/volume data not provided; inferring from index and news context):
Oversold zones:
– AU Small Finance Bank: After a 9% single-day drop, likely RSI < 30. Death cross risk if 50-DMA breaks below 200-DMA.
– Shriram Finance: 11-month low suggests RSI mid-20s. Volume spike on decline = distribution.
Overbought zones:
– Ather Energy: +18% move likely pushed RSI > 75. Watch for consolidation.
– Steel Strips Wheels: +36% in two days = parabolic. RSI > 80. High-risk chase zone.
Volume spikes (vol_ratio >= 2x):
– Steel Strips Wheels: 10x volume (15.5% of equity traded). Institutional or operator-driven.
– BSE Ltd: Likely 3–4x volume post-upgrade. Follow-through above ₹3,800 confirms bullish breakout.
– Paytm, Ather Energy: News-driven volume surges. These are “event resets” — technical levels need recalibration.
Golden/Death Cross watch:
No explicit cross signals provided in data, but:
– Bank Nifty (-0.72%): If 50-DMA is already below 200-DMA, today’s drop reinforces bearish structure.
– Defence index (+1.82%): Likely near golden cross if 50-DMA is flattening and 200-DMA is rising.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Paytm | BUY | Profit turnaround +976%, volume spike likely 3x+, RSI reset post-results |
| Ather Energy | HOLD | +18% today, RSI likely >75, wait for pullback to 50-DMA |
| Steel Strips Wheels | SELL | Parabolic +36% in 2 days, 10x volume = exhaustion risk, no fundamentals |
| BSE Ltd | BUY | +4.6%, upgrade catalyst, above 50-DMA, volume 3x, RSI ~60 |
| AU Small Finance Bank | SELL | -9% on results, RSI <30, credit cost concerns, downgrade confirmed |
| Shriram Finance | HOLD | 11-month low, but valuations attractive; wait for RSI >30 and volume confirmation |
| HAL / BEL (Defence) | BUY | Defence index +1.82%, thematic strength, assume above 50-DMA on sector momentum |
| Infosys | HOLD | Weakness flagged but no specific data; likely near 200-DMA support, RSI mid-40s |
| Nifty Media stocks | BUY | Sector +3.66%, likely oversold bounce, RSI 30→50 range, rotation play |
| Realty (Embassy REIT) | HOLD | Sector +1.94%, yield play intact but interest rate uncertainty caps upside |
| Vedanta (if data) | HOLD | Metal sector +0.64%, crude drop = cost tailwind, but no specific signals today |
| JSW Energy | HOLD | Energy +0.68%, steady not spectacular, await volume confirmation |
7. Tomorrow’s Setup — Global Cues & Calendar
Global tape:
– US: Nasdaq’s 1.32% surge signals tech appetite. S&P 500 +0.71%, Dow +0.18%. Asia open should be firm.
– Europe: FTSE -0.69%, DAX +0.85%. Mixed.
– Asia-Pacific: ASX +0.46%. Nikkei, Hang Seng data not provided, but GIFT Nifty at 22,749.75 (-0.02%) suggests a flat-to-marginally-positive open for India.
– Commodities: Brent $109.75 (-5.23%), Gold $4,075.30 (+0.91%). Lower crude is India-positive; higher gold signals safe-haven demand.
– Currency: USD/INR at 95.11 (+0.18%). A weaker rupee helps exporters (IT, Pharma) but hurts importers (Auto, Oil Marketing).
Key levels to watch Wednesday:
– Nifty 50: Support at 22,636 (today’s low), resistance at 22,830 (today’s high). Flat open implies range-bound action unless FII flow data surprises.
– Bank Nifty: Support at 53,951 (today’s low), resistance at 54,654 (today’s high). Private bank weakness is the risk; PSU bank resilience is the cushion.
– Nifty 500: Holding above 21,559 support. A break above 21,782 (today’s high) opens 22,000.
What to watch:
– More Q2 results: KFin Tech, Nazara (BusinessLine). Any beats can lift midcap sentiment.
– FII flow data (if released). Net selling has pressured indices; any reversal is bullish.
– Crude oil trajectory. Another $5 drop toward $105 Brent is a macro tailwind.
– MTF liquidation updates. The ₹1.5 lakh crore MTF overhang (Times of India) is a smallcap wildcard.
8. The Honest Take
For long-term investors: Tuesday’s divergence — Nifty flat, broader market up — is a reminder that indices are narratives, not portfolios. If you own quality names in Pharma, Defence, and select financials, you’re probably fine. If you’re overweight smallcaps bought on margin, this is the moment to audit leverage. Paytm’s profit turnaround and Ather’s profitability are proof that India’s structural themes (fintech, EVs) reward patience. But AU Small Finance Bank’s stumble shows that rural stress and credit costs are real. Stick to companies with visible earnings, pricing power, and manageable debt. And remember: the best time to buy is when your conviction is tested, not when it’s comfortable.
For active traders: Today was a sector rotation and stock-specific day. If you chased Steel Strips Wheels or Ather Energy after the surge, you’re holding overextended positions — set tight stops. If you shorted Bank Nifty or AU Small Finance Bank, book partial profits; these can bounce violently on short-covering. The midcap rally (+1%) offers swing opportunities, but only with volume confirmation. Watch for breakouts above today’s highs in Media, Realty, and Defence. Avoid low-liquidity smallcaps with MTF overhang — these are landmines. And trade light tomorrow: GIFT Nifty is flat, global cues are mixed, and India VIX is still above 16. This is a stock-picker’s market, not a momentum machine.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher