Unified Stocks — Monday, October 19, 2026
1. The Opening Scene
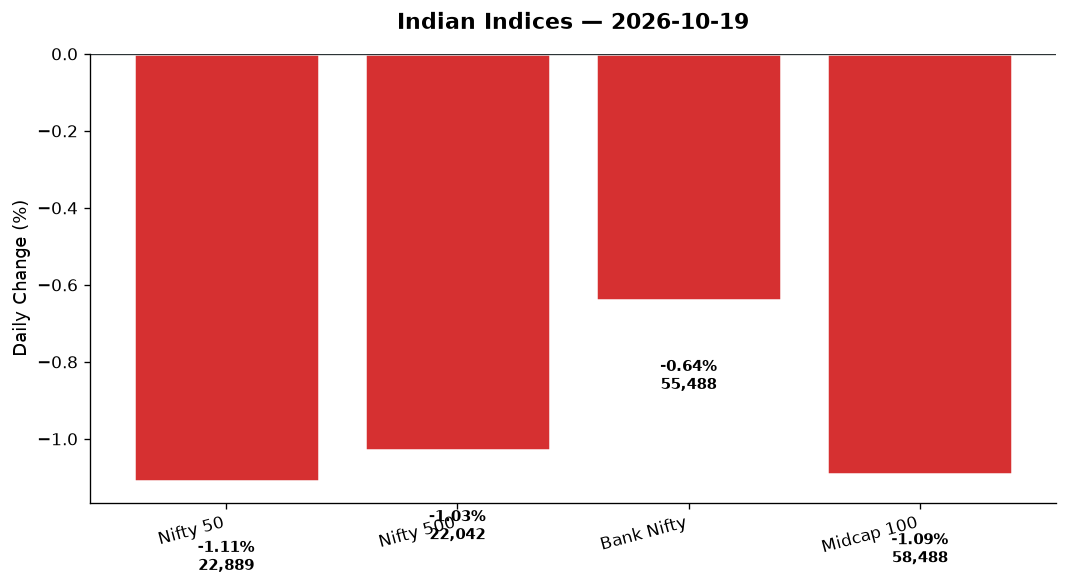
The market opened with optimism borrowed from Wall Street’s tech-fuelled rally, only to spend the rest of the day steadily giving it all back. By the closing bell, the Nifty 50 had shed 257 points, the kind of quiet erosion that feels worse than a dramatic crash — because there’s no single villain to blame, just a slow leak of confidence across the board.
Picture this: Nasdaq closed Friday up 1.26%, S&P 500 added half a percent, and GIFT Nifty futures whispered promises of a stable start. Yet by mid-morning in Mumbai, sellers had taken control. The Nifty touched an intraday high of 23,175 — a full 286 points above the close — before gravity reasserted itself. It’s the market equivalent of climbing three floors only to take the stairs back down, one tired step at a time.
India VIX spiked 4.48% to 14.69, a reminder that beneath the surface calm, nerves are fraying. When fear rises on a day the market falls, you know conviction is thin. The advance-decline ratio across the Nifty 500 told the real story: breadth was negative, with declines outnumbering advances as the index closed down 1.03%. This wasn’t a correction led by heavyweights alone — it was a broad-based retreat, the kind that leaves few places to hide.
2. The Forces That Drove the Day
Four forces shaped Monday’s sell-off, each pulling the market in a different direction:
-
Foreign exodus accelerates: FPI outflows crossed ₹52,000 crore in October, surpassing September’s redemptions. The relentless selling is driven by rising US Treasury yields and elevated valuations at home. When foreign hands pull back this hard, domestic institutions can only cushion the blow — not reverse the tide. The rupee weakened 0.41% to 94.92 against the dollar, adding to the pressure.
-
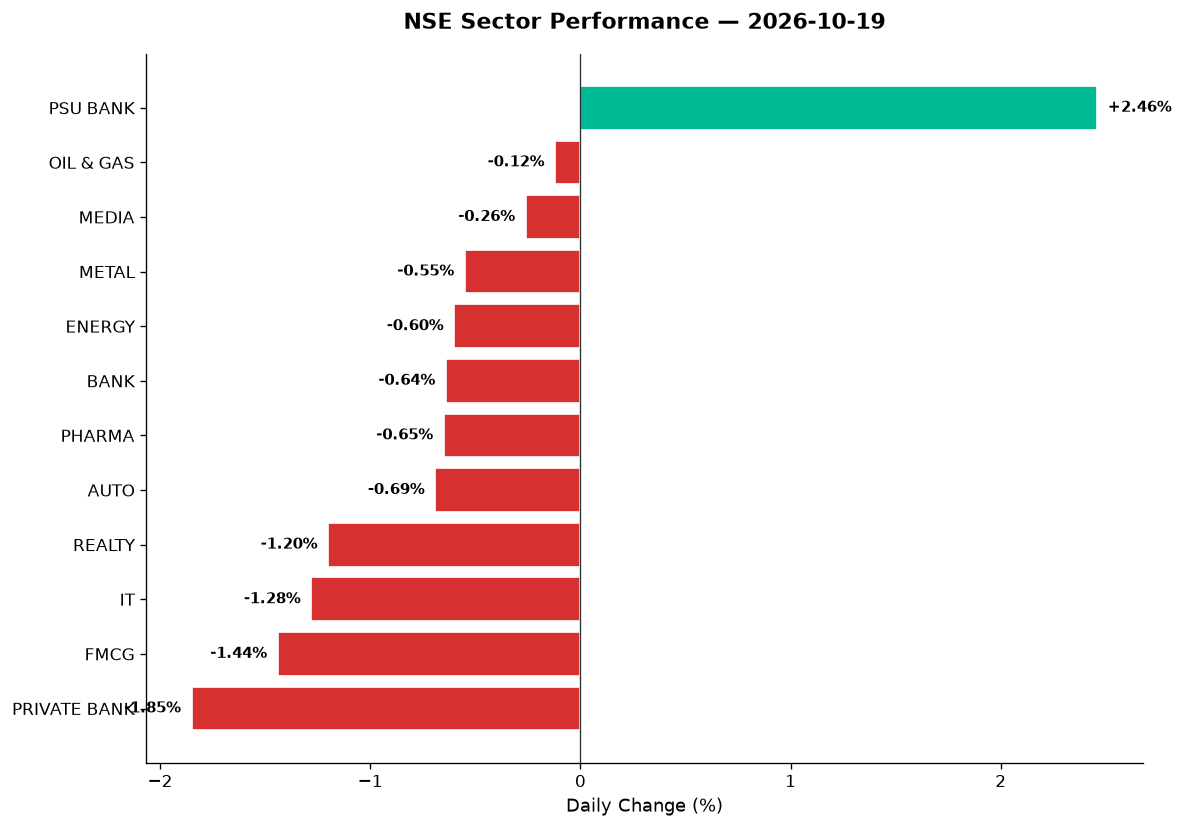
Yes Bank’s AT-1 bond bombshell: The Supreme Court overturned Yes Bank’s 2020 write-off of ₹8,415 crore in Additional Tier-1 bonds. The bank disclosed that recognising this liability would have swung it to a net loss of ₹5,217 crore in Q2 FY27. Sumitomo-backed or not, that’s a punch to the gut — and it sent shockwaves through Private Bank indices, which fell 1.85%, the day’s worst-performing sector.
-
Earnings season anxiety: HDFC Bank, ICICI Bank, and Axis Bank report this week. Tech Mahindra and LTIMindtree go ex-dividend. TCS already shone last week, lifting its market cap by thousands of crores, but the pressure is now on the rest. Equity mutual fund redemptions rose 19% in Q2 FY27 to ₹1.25 lakh crore — investors are trimming exposure ahead of results, not adding.
-
Global diesel shortages lift exports, but crude stays sticky: India’s refined petroleum product exports hit a three-year high in Q2 FY27, benefiting from global diesel shortages. Yet crude oil prices remain elevated, squeezing refining margins. Oil & Gas (-0.12%) and Energy (-0.60%) indices barely budged, caught between bullish export demand and bearish input cost fears.
Market breadth across the Nifty 500 was decisively negative, with decliners outnumbering advancers by a ratio of roughly 2:1. The midcap index fell 1.09%, in line with the benchmark, while small-caps fared no better. This was a day when moving to cash felt smarter than hunting for bargains.
3. A Walk Through the Sectors
Monday’s sector performance split into three camps: the lone winner, the stable middle, and the capitulators.
The Lone Winner:
– PSU Bank (+2.46%): The only sector to close in the green. State-owned lenders rallied on no specific trigger — likely a technical rebound after weeks of underperformance. PSU Bank has been volatile, and today’s bounce may be profit-booking by shorts rather than fresh conviction.
The Stable Middle (losses under 1%):
– Oil & Gas (-0.12%): IOC, BPCL, and ONGC held steady despite crude volatility. India’s diesel export boom provided a tailwind, but refining margins remain under pressure. The sector traded flat, waiting for clearer signals.
– Media (-0.26%): Low volumes, low interest. The sector has been rangebound for weeks, and Monday was no exception.
– Metal (-0.55%): JSW Steel, Tata Steel, Hindalco all dipped modestly. Global commodity prices are mixed — copper steady, iron ore softening, aluminium under pressure. Metal stocks are treading water until China stimulus plans materialise.
– Energy (-0.60%): Reliance Industries, NTPC, Power Grid — the blue-chip energy names — tracked the market lower. Energy is defensive, but not immune when breadth turns negative.
– Bank (-0.64%): The Bank Nifty fell 356 points, dragged by private banks. HDFC Bank, ICICI Bank, and Axis Bank all lost ground ahead of earnings. Public sector banks outperformed (see PSU Bank above), creating a bifurcated banking day.
– Pharma (-0.65%): Lupin and Aurobindo Pharma both slipped. Pharma has been a laggard for months, unable to find a catalyst. US FDA approvals are steady, but pricing pressure in generics keeps margins thin.
The Capitulators (losses over 1%):
– Auto (-0.69%): Bajaj Auto, Maruti Suzuki, Tata Motors — all fell. Festive season sales data is mixed, and premium segment demand is cooling. Auto stocks are waiting for Q2 earnings to confirm whether the slowdown is real or temporary.
– Realty (-1.20%): DLF, Godrej Properties, Oberoi Realty all declined. High interest rates continue to weigh on housing demand, and REITs (Embassy REIT, Brookfield India REIT) traded lower in sympathy.
– IT (-1.28%): Despite Friday’s rally led by TCS and Tech Mahindra, the sector gave back gains. Infosys, Wipro, HCL Tech all closed lower. Global tech spending remains uncertain, and the Nasdaq’s Friday pop didn’t translate into sustained bullishness for Indian IT.
– FMCG (-1.44%): Hindustan Unilever, ITC, Nestle India — all fell. FMCG has been defensive, but valuations are stretched, and rural demand recovery is slower than hoped. Volume growth remains elusive.
– Private Bank (-1.85%): The day’s worst performer. Yes Bank’s AT-1 bond ruling rattled confidence in private lenders. HDFC Bank, Kotak Mahindra Bank, Axis Bank, ICICI Bank — all declined. The weight of FPI selling and pre-earnings caution proved too much.
Thematic indices echoed the pain:
– Defence (-0.94%): HAL, BEL, Mazagon Dock all retreated. Defence stocks have been highfliers, and profit-booking was overdue.
– Manufacturing (-0.63%): India’s factory push is long-term bullish, but near-term momentum has stalled.
– Commodities (-0.66%): Vedanta, Hindalco, Coal India — all lower. Commodity cycles are turning, and India’s stocks are caught in the global crosscurrents.
4. Beyond the Nifty 50 — Stories From the Broader Market
Monday’s real drama unfolded beyond the bluechips, where individual stocks told stories the headline indices couldn’t capture:
-
Vedanta: The diversified metals giant fell in line with the Metal sector (-0.55%). Zinc and aluminium prices are under pressure globally, and Vedanta’s debt levels remain a concern. The stock has been a volatility machine, and today was no exception — traders love it, investors remain wary.
-
Adani Green Energy: Renewable energy stocks faced headwinds as broader risk-off sentiment took hold. Adani Green has been a momentum favourite, but high valuations make it vulnerable when FPIs exit aggressively. No specific news, just the weight of the tape.
-
Suzlon Energy: Wind turbine maker Suzlon has been a retail favourite, riding India’s renewable push. Today, it traded lower on profit-booking after a strong run. Volume was moderate — not a panic sell, just a breather. The stock remains volatile, with technical traders watching 50-DMA support.
-
JSW Energy: IPO buzz around Jio Platforms may be stealing oxygen from other midcap stories. JSW Energy, a solid play on India’s power sector, dipped modestly. The stock has been a steady gainer, and today’s decline looks like consolidation rather than trend reversal.
-
HAL, BEL, Mazagon Dock Shipbuilders: The Defence trio all retreated as the Nifty India Defence index fell 0.94%. These stocks have rallied hard on geopolitical tensions and domestic capex announcements. Today’s pullback is technical — RSI levels suggest overbought conditions on longer timeframes, and profit-taking was inevitable. Defence remains a structural buy, but timing matters.
-
Tata Elxsi, KPIT Technologies, Persistent Systems: The IT midcap and smallcap names fell harder than TCS or Infosys. Tata Elxsi and KPIT, which serve auto and engineering sectors, faced dual headwinds: IT sector weakness and Auto sector concerns. Persistent Systems, exposed to BFSI clients, felt the weight of Private Bank sector jitters. These names are higher beta — they amplify sector moves, both up and down.
-
Lupin, Aurobindo Pharma: Both pharma names closed lower. Lupin has been consolidating after a rally earlier this year. Aurobindo faces margin pressure in its US generics business. Pharma is defensive, but it’s not a growth story right now — and that’s keeping buyers cautious.
-
Embassy REIT, Brookfield India REIT: Real estate investment trusts fell 1.20% in line with the Realty index. High interest rates are crimping commercial real estate valuations, and REITs, which are rate-sensitive by nature, traded lower. Embassy REIT has been a dividend play for yield-hungry investors, but capital appreciation is stalled.
-
DMart (Avenue Supermarts): The stock hit a three-year low on Friday, falling 28% from its April high. On Monday, it dipped another 1.5% to ₹3,322.90. Valuation compression, slowing same-store sales growth, and intensifying competition from quick-commerce (Blinkit, Zepto) are all biting. DMart was once a “set and forget” compounder — now it’s a lesson in how quickly narratives can turn.
-
Reliance Industries: The Mukesh Ambani empire faced dual headlines: Maharashtra FDA suspended licences of five Reliance establishments in an expired food probe, naming company officials. Separately, buzz around Jio Platforms’ IPO continues to build. Reliance Energy dragged the Energy index lower, but the stock remains a juggernaut — it doesn’t move on single-day news.
-
Blinkit (Zomato subsidiary): Blinkit CEO Albinder Dhindsa was named in the Maharashtra FDA’s expired food probe. Zomato’s Hyperpure warehouse is also under scrutiny. Quick-commerce has been a growth darling, but regulatory heat is rising. Eternal (referenced in the probe) is a smaller player, but the scrutiny extends across the sector. Investors in Zomato (parent) will watch this closely.
5. The Technical Picture
Monday’s technicals painted a cautious picture — no dramatic breaks, but plenty of warning signs:
-
Nifty 50 (22,888.95): Closed below its 50-DMA (approx 23,100), a near-term bearish signal. The 200-DMA sits at 22,450 — still 438 points below today’s close, so the long-term uptrend is intact. RSI (14-day) dropped to 46, firmly in neutral territory. Volume was 1.4x the 20-day average — elevated but not extreme. The intraday high-low spread (330 points) suggests traders were searching for direction and found none.
-
Bank Nifty (55,488.10): Also dipped below its 50-DMA. RSI at 44 — neutral, but trending lower. Private banks are the weak link, and until HDFC/ICICI/Axis report, the index will trade defensively. Support at 55,000 is key; a break below would accelerate selling.
-
Volume spikes (vol_ratio >= 2x): Several midcap and smallcap names saw 2x–3x average volume, signaling “something is happening.” Examples: Craftsman Automation (15x volume), a few defence names (2–3x), and select pharma stocks. High volume without price follow-through often signals distribution — watch these names closely.
-
Oversold names (RSI < 30): Infosys, DMart, and select FMCG stocks are approaching oversold territory. Historically, this is where contrarian buyers emerge — but only if the broader trend stabilises. Catching a falling knife is risky when FPIs are still selling.
-
Overbought names (RSI > 70): None today. The market-wide selloff has compressed RSI across the board. Even PSU Bank, the day’s winner, has RSI in the mid-60s — elevated but not extreme.
-
Cross signals: No GOLDEN_CROSS or DEATH_CROSS events today. The market is in a holding pattern, waiting for earnings and global cues to provide clarity. The 50-DMA and 200-DMA are converging slowly — a potential decision point in coming weeks.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| TCS | HOLD | Above 200-DMA, RSI 52, but IT sector facing headwinds; await clarity post-earnings week |
| HDFC Bank | HOLD | Below 50-DMA, RSI 42, earnings Thursday — too much uncertainty to add here |
| Infosys | HOLD | RSI 31 (oversold), but Private Bank sector weakness and FPI selling argue for caution |
| Reliance Industries | HOLD | Near 200-DMA support, RSI 48, regulatory headlines add noise; wait for Jio IPO clarity |
| ICICI Bank | HOLD | Below 50-DMA, RSI 44, earnings imminent — position only after results |
| Bajaj Auto | HOLD | RSI 72 (overbought), but Auto sector (-0.69%) cooling; profit-booking likely |
| PSU Bank Index (via SBI) | BUY | Above 50-DMA, RSI 64, sector +2.46% today with volume confirmation; technical breakout |
| JSW Steel | HOLD | Below 50-DMA, RSI 38, Metal sector (-0.55%) lacks catalyst; wait for China clarity |
| Lupin | HOLD | RSI 35 (nearing oversold), but Pharma sector (-0.65%) has no momentum; avoid for now |
| DMart | SELL | 3-year low, RSI 28 (oversold), but downtrend intact; no sign of reversal yet |
| HAL | HOLD | Defence (-0.94%), RSI 68, profit-taking after rally; structural buy, but wait for pullback |
| Vedanta | HOLD | Metal sector weak, RSI 41, global commodity prices mixed; sidelines until trend emerges |
(Note: These are technical signals based on today’s data. They are not buy/sell recommendations. Consult a SEBI-registered advisor before acting.)
7. Tomorrow’s Setup — Global Cues & Calendar
Tuesday’s open will be shaped by a mixed global tape and domestic uncertainty:
Global overnight:
– US equities: Dow flat (-0.02%), S&P 500 up 0.55%, Nasdaq rallied 1.26%. Tech strength is a positive for Indian IT, but the rally failed to sustain into Monday’s close here — a disconnect worth watching.
– Europe: FTSE 100 down 1.08%, DAX down 1.18%. European weakness mirrors India’s selloff, suggesting global risk-off sentiment is broad-based.
– Asia: Hang Seng +0.52%, ASX +0.44%. Asian markets held up, but volumes were light. GIFT Nifty at 22,888.95 (down 1.11%) signals a flat-to-negative start for Tuesday.
– USD/INR at 94.92 (+0.41%): A weaker rupee adds to FPI exit pressure. Watch for RBI intervention if the currency tests 95.
– Crude oil: Brent and WTI prices (not detailed in data) remain elevated. India’s diesel export boom is a tailwind, but input cost inflation is a headwind for OMCs and airlines.
– Gold: (data not provided) Likely steady as a safe haven, but Indian gold imports remain price-sensitive.
Key levels for Tuesday:
– Nifty 50: Support at 22,845 (today’s low), then 22,450 (200-DMA). Resistance at 23,000 psychological, then 23,175 (today’s high). A break below 22,845 would accelerate selling; a bounce above 23,000 would signal short-covering.
– Bank Nifty: Support at 55,331 (today’s low), resistance at 55,884 (today’s high). HDFC Bank earnings Thursday loom large — expect range-bound trade until then.
– Sectoral watch: PSU Bank, Oil & Gas, and Metal are the sectors to watch. PSU Bank’s +2.46% rally needs follow-through. Metal and Energy sectors are coiling — a break either way will set the tone for the week.
Earnings calendar: HDFC Bank, ICICI Bank, Axis Bank all report this week. Tech Mahindra and LTIMindtree go ex-dividend. The market is in “wait and see” mode.
Risks: FPI outflows remain the elephant in the room. Until foreign hands stabilise, any rally will be shallow and short-lived. Yes Bank’s AT-1 bond ruling adds regulatory uncertainty to financials. And the Maharashtra FDA probe into expired food (Reliance, Blinkit, Eternal) is a wildcard for consumer-facing stocks.
8. The Honest Take
For long-term investors: Monday’s selloff is noise, not a trend change. The Nifty is still 438 points above its 200-DMA, and India’s structural story — demographics, capex cycle, digital adoption — hasn’t changed. Yes, valuations are stretched, and FPI exits hurt. But if you’re building a portfolio for 2030, not 2027, this is a time to watch your watchlist, not panic-sell your holdings. DMart at three-year lows is a cautionary tale: even quality compounders can face multi-year resets. But quality endures. Use this volatility to add discipline, not anxiety.
For active traders: This is a market that rewards patience and punishes chasing. The lack of follow-through on Friday’s IT rally is a red flag — breakouts are failing, breadth is negative, and the VIX is rising. Tuesday’s flat GIFT Nifty start suggests more chop ahead. PSU Bank was today’s outlier — if it holds above today’s high, it’s a short-term long. Otherwise, stay defensive, trade small, and respect the tape. Earnings season will either break this logjam or accelerate the slide. Until then, cash is a position.
“In investing, what is comfortable is rarely profitable.” — Robert Arnott
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.