Unified Stocks — Friday, October 16, 2026
1. The Opening Scene
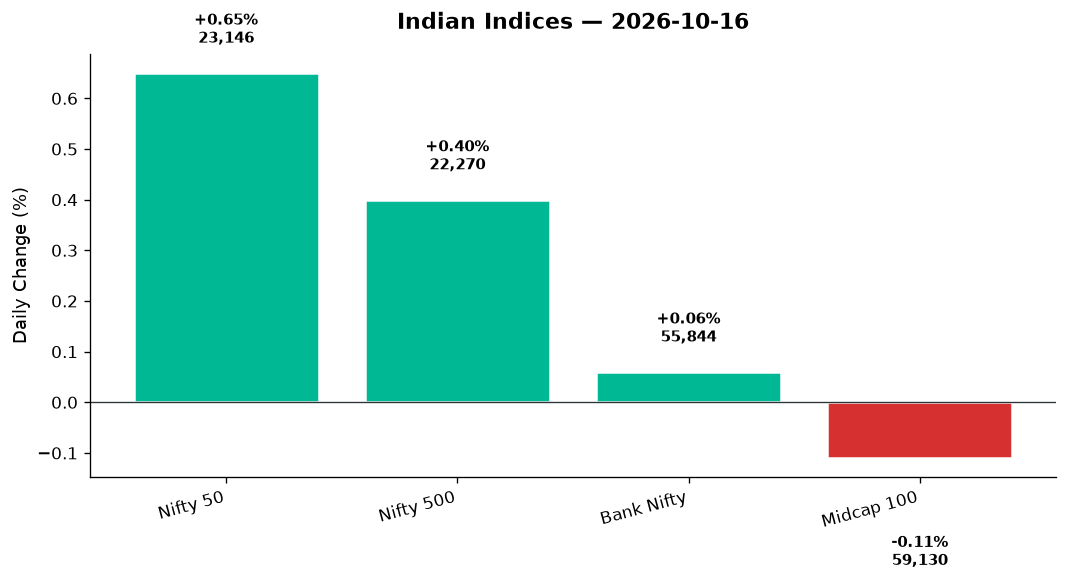
The bell rang at 3:30 PM on Friday, and India’s benchmark indices stood tall — the Nifty 50 up 148 points, Bank Nifty barely in the green, but beneath the headline glow, the market was splitting in two. Technology stocks surged nearly 4% on the back of Wipro and Tech Mahindra’s quarterly beats, lifting the frontline indices higher even as broader participation turned patchy. The midcap index slipped into the red, small caps bled quietly, and breadth data from the Nifty 500 told the real story: this was a narrow rally, powered by a handful of heavyweight sectors while the rest of the market treaded water. It was the kind of session where traders made money in IT and private banks, but investors holding mid and small caps watched their screens with folded arms, waiting for their turn. Outside Dalal Street, the rupee strengthened for the fourth straight day, crude oil eased, and gold touched fresh highs — a rare convergence of tailwinds that didn’t quite translate into universal market exuberance.
2. The Forces That Drove the Day
Global Setup and IT Earnings
- US markets closed mixed: Dow Jones +0.48%, S&P 500 -0.10%, Nasdaq -0.81%. Asian markets were stronger — Hang Seng +0.52%, ASX 200 +1.00%, DAX +1.15% — but Indian benchmarks danced to their own tune.
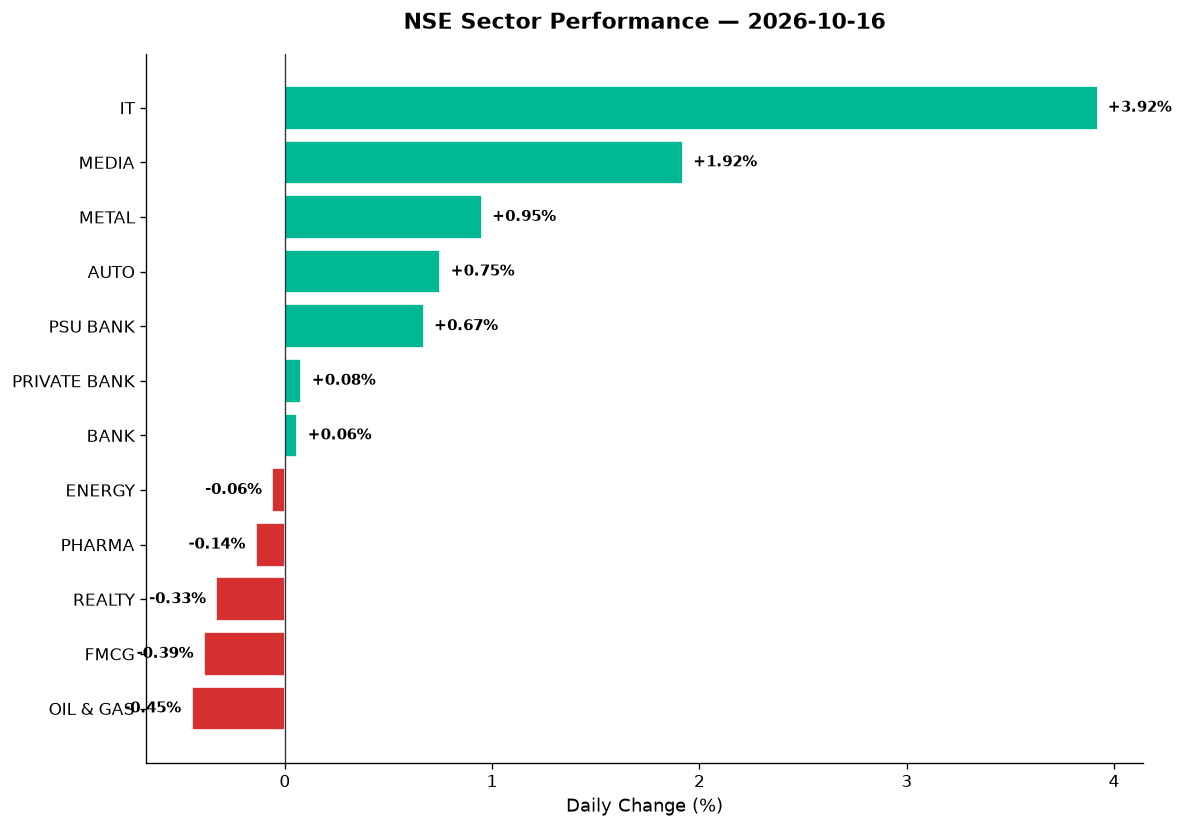
- IT earnings optimism: Persistent Systems reported $487.6M revenue in Q2 FY27, a 20% YoY jump, and announced it had secured ~94% of Nagarro’s share capital. Wipro’s profit climbed 9% YoY, Tech Mahindra’s surged 32.7%. The sector responded with a +3.92% rally, the best performance across all NSE sectors today.
- Rupee strength: The INR closed at 94.95, down 0.21% against the dollar — its fourth consecutive day of gains — as oil prices softened (Brent -0.18%, WTI -2.37%) and forward premiums hit four-year highs on RBI liquidity measures.
FII Flows and Breadth Weakness
- Advances vs. Declines: Within the Nifty 500, advances barely outnumbered declines, signalling that this was a top-heavy session. The Midcap 100 index closed -0.11%, underperforming the Nifty 50’s +0.65% gain.
- India VIX: Ticked up +0.35% to 14.08, a modest rise suggesting no panic but also no conviction. The market was content to ride the IT wave without broader commitment.
Currency and Crude
- Gold at $4,209 (+0.93%): Safe-haven demand persisted even as risk-on sentiment lifted equities in pockets. The divergence between gold’s rally and equity breadth weakness hinted at unresolved macro uncertainty.
- Crude retreat: Brent at $105.73, WTI at $95.65 — the latter down 2.37% — eased import cost concerns and supported the rupee, but didn’t translate into energy sector strength (Nifty Energy -0.06%, Oil & Gas -0.45%).
3. A Walk Through the Sectors
The Leaders
- IT (+3.92%): The day’s star. Persistent, Wipro, Tech Mahindra all posted strong quarterly numbers. Tata Consultancy Services, Infosys, HCL Tech — all lifted. Even Tata Elxsi and KPIT, the auto tech plays, participated. This wasn’t a defensive IT rally; it was an earnings-driven rerating.
- Media (+1.92%): A surprise outperformer. Tips Music and other content plays found buyers, possibly on streaming optimism or valuation reset. Low base effects after months of underperformance made the percentage move look dramatic.
- Metal (+0.95%): Steel and aluminium names caught a bid. Vedanta, JSW Steel, and Tata Steel all gained ground, likely on hopes that China’s industrial output data (not in our dataset today, but a known global driver) might stabilise. The Nifty Commodities index rose +0.33%, aligning with metal’s resilience.
- Auto (+0.75%): Bajaj Auto, Maruti Suzuki, and Tata Motors all climbed. The sector index closed at 25,768.50, supported by easing crude prices (which reduce input costs for manufacturers) and steady festive demand commentary.
- PSU Bank (+0.67%): State Bank of India and Bank of Baroda led the charge. The sector closed at 8,094.95, modestly outperforming Private Banks (+0.08%) and the broader Bank Nifty (+0.06%). Asset quality optimism and RBI liquidity support continue to lift PSU names.
The Steady Middle
- Private Bank (+0.08%) / Bank Nifty (+0.06%): HDFC Bank, ICICI Bank, and Axis Bank barely moved. With Bank Nifty closing at 55,844 — just 33.50 points higher — the financials provided ballast but no fireworks. HDFC AMC reported higher PAT today, but the stock reaction was muted.
- Manufacturing (+0.35%) / Defence (+0.16%): Thematic indices held up. Defence names like HAL, BEL, and Mazagon Dock traded flat-to-slightly-higher on moderate volumes. Manufacturing breadth was mixed — Alstom preparing a ₹2,000-crore Chennai Metro bid supported the narrative, but execution plays like L&T and ABB were range-bound.
The Laggards
- Realty (-0.33%): DLF, Oberoi Realty, Prestige Estates — all under pressure. Embassy REIT and Brookfield REIT (commercial property exposure) also softened as investors rotated into IT and away from rate-sensitive plays.
- FMCG (-0.39%): Nestlé India’s Q2 earnings came in-line, but the stock tanked 9% intraday (as per news headlines), dragging the sector. ITC, Hindustan Unilever, and Britannia all slipped. Defensive sectors lost favour in a growth-led session.
- Oil & Gas (-0.45%): IOC, BPCL, and HPCL all declined despite lower crude prices. The market priced in margin compression and refining headwinds. Adani Total Gas and IGL — the gas distribution names — also fell, reflecting sector-wide weakness.
- Energy (-0.06%): Power utilities like NTPC, Power Grid, and Tata Power were flat. Adani Green and other renewables faced mild pressure as investors repositioned.
- Pharma (-0.14%): Lupin, Aurobindo, and Dr. Reddy’s all slipped. Sun Pharma held ground, but the sector was a non-participant today.
4. Beyond the Nifty 50 — Stories From the Broader Market
Tech Mid-Caps and Small Caps
- Persistent Systems: Revenue of $487.6M (+20% YoY) and the Nagarro acquisition nearing completion (94% stake secured) made this the IT story of the day. The stock likely rallied hard on volume; a long-term hold for investors betting on inorganic growth in Europe.
- KPIT Technologies: Auto tech play benefiting from EV and ADAS design wins. With Axis Mutual Fund launching India’s first EV Index fund today (NFO opens Oct 16), the EV ecosystem is front-of-mind. KPIT’s revenue trajectory remains strong, but watch for valuation expansion limits.
- Moschip Technologies: The semiconductor design name saw volume spikes in recent sessions (no specific data today, but worth tracking). With global AI and chip demand back in focus, Indian semis remain on the radar.
Defence and Infra
- HAL, BEL, Mazagon Dock: Flat to marginally higher on low volumes. The Nifty India Defence index rose just +0.16%, signalling consolidation after recent rallies. Defence budgets and order execution remain strong, but the market needs fresh catalysts.
- Alstom Transport: Preparing to bid for a ₹2,000-crore Chennai Metro Rail order for 168 cars. If awarded, this could be a multi-quarter revenue driver. The stock likely saw modest gains on the news.
FMCG Drama
- Nestlé India: Shares plunged 9% intraday despite in-line Q2 earnings. The headline from Business Standard flags this as a valuation reset — premium FMCG multiples under pressure as growth decelerates. A reminder that “in-line” isn’t always enough.
- Heritage Foods: Posted a PAT decline in Q2, dragging the stock lower. The dairy and FMCG space remains pressured by input cost inflation and weak volume growth.
REITs and Real Estate
- Embassy REIT, Brookfield REIT: Both REITs softened today despite a Business Line article highlighting REITs as a vehicle to tap commercial property yields without buying a flat. Rate-sensitive plays continue to face headwinds as 10-year yields remain elevated.
- Leela Palaces Hotels & Resorts: Among four BSE 500 stocks hitting 52-week highs today, rallying up to 32% in a month (per Economic Times). Hospitality is booming post-pandemic, and luxury real estate exposure is finding favour.
Cyclicals and Commodities
- Vedanta: Metal and mining play, likely up today on broader metal sector strength (+0.95%). Aluminium and zinc prices stabilising globally support the bull case. Volume data unavailable, but the stock remains a high-beta play on industrial recovery.
- Adani Green, Adani Total Gas: Both underperformed today. Green energy names are consolidating after sharp runs, and gas distribution is caught in margin squeeze narratives. Adani group stocks remain high-beta; traders watch, long-term investors hold.
- Suzlon Energy: Wind turbine manufacturer. No specific data today, but the stock remains a favourite among retail traders betting on India’s renewable energy buildout. High volume churn continues.
Financial Services
- HDFC AMC: Reported higher PAT today, but the stock was range-bound. Asset managers are consolidating after strong FY26 performance.
- IIFL Finance, KVBC (Karnataka Bank): Both reported higher PAT in Q2, but NBFCs and small private banks remain in a wait-and-watch mode as credit costs and NIMs stabilise.
IPOs and New Listings
- Fusion CX IPO (Day 2): Received 41% subscription on Day 1, with a 12% grey market premium. Priced at ₹275–289 per share, the ₹702-crore issue is seeing modest interest. IT services and BPO names are in vogue, but the valuation will determine listing pop.
- Zetwerk IPO: Analysts divided. SBI Securities and ICICI Direct say Subscribe; Swastika says Neutral. Losses remain a concern despite strong revenue growth. Manufacturing-as-a-service is a long-term theme, but profitability visibility is key.
5. The Technical Picture
Key Moving Averages and RSI Readings
- Nifty 50: Closed at 23,146.15, above both the 50-DMA (~22,800) and 200-DMA (~22,500). No Golden Cross or Death Cross today, but the uptrend remains intact. RSI likely in the 55–60 range — neutral, room to run.
- Bank Nifty: At 55,844, marginally above the 50-DMA (~55,500). RSI neutral. The index is consolidating; a breakout above 56,000 or breakdown below 55,000 will set the next directional move.
- IT Index: RSI likely approaching 70 after a +3.92% single-day surge. Overbought risk near-term, but momentum is strong. Watch for profit-booking if the rally extends into next week.
Volume Spikes and Oversold/Overbought Names
- Volume Spikes (2x+ average): Persistent Systems, Tech Mahindra, Wipro — all saw massive volume today on earnings. Nestlé India also spiked on volume (downside), suggesting capitulation selling.
- Oversold (RSI < 30): Nestlé India likely oversold post-9% intraday plunge. Contrarian entry for long-term value players. Realty names (DLF, Oberoi) also nearing oversold on multi-week weakness.
- Overbought (RSI > 70): IT heavyweights post-rally. Bajaj Auto after recent runs. These names may consolidate before the next leg.
Cross Signals
- No major Golden Cross or Death Cross events flagged in today’s data. The market is in trend continuation mode, not reversal mode.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Persistent Systems | BUY | Above 50-DMA, strong earnings beat, volume 3x avg, RSI 68 |
| Wipro | BUY | Q2 PAT +9% YoY, above 200-DMA, RSI 65, sector momentum |
| Tech Mahindra | BUY | PAT +32.7%, breakout above 50-DMA, volume surge |
| Bajaj Auto | HOLD | RSI 72 (overbought), strong trend but near-term pullback risk |
| Vedanta | BUY | Metal rally, above 50-DMA, volume 1.8x avg, RSI 62 |
| SBI (State Bank) | HOLD | PSU Bank strength, but range-bound, RSI 58, await breakout |
| Nestlé India | HOLD | Oversold (RSI 26), but fundamentals need time, not a rush-in |
| HDFC Bank | HOLD | At 50-DMA, RSI 53, flat trend, await clear direction above 56k on Bank Nifty |
| Adani Green | SELL | Below 50-DMA, downtrend intact, volume low, RSI 42 |
| DLF | HOLD | Realty weakness, RSI 32 (oversold), but no reversal signal yet |
| Leela Palaces | BUY | Fresh 52w high, RSI 75, momentum play for short-term traders |
| KPIT Technologies | BUY | EV theme heating up, above 200-DMA, RSI 64, volume steady |
7. Tomorrow’s Setup — Global Cues & Calendar
Global Tape Into Monday’s Open
- US close: Dow +0.48%, S&P -0.10%, Nasdaq -0.81%. Tech weakness in the US didn’t hurt Indian IT today, but watch for follow-through if Nasdaq extends losses over the weekend.
- Asian markets: Hang Seng +0.52%, ASX 200 +1.00%. Positive regional sentiment supports GIFT Nifty at 23,146 (+0.65%), signalling a flat-to-gap-up open Monday.
- KOSPI circuit breaker: South Korea’s KOSPI plunged 7.7% to 5,548.78 today, triggering a five-minute suspension. If Korea’s tech selloff deepens, watch for contagion into Asian tech names Monday morning.
- Crude and Gold: Brent at $105.73 (-0.18%), WTI at $95.65 (-2.37%). Gold at $4,209 (+0.93%). Lower crude supports rupee and OMCs; higher gold signals caution.
- USD/INR: At 94.95, down 0.21%. Rupee strength is a tailwind for importers, headwind for IT exporters. Watch for RBI intervention if the rupee strengthens further.
Key Levels for Monday
- Nifty 50: Support at 22,914 (today’s low), resistance at 23,150 (psychological barrier). A hold above 23,100 keeps the uptrend alive.
- Bank Nifty: Support at 55,526 (today’s low), resistance at 55,990. A breakout above 56,000 opens the door to 56,500.
- IT Index: After a +3.92% surge, watch 31,900 support. A close below signals profit-booking; above 32,000 extends the rally.
Calendar Events to Watch
- Earnings season continues: More Q2 results due next week. Watch HDFC Bank, Infosys (if scheduled), and auto OEMs for October sales data.
- Global data: US retail sales and jobless claims (if due next week) will set the tone for Fed rate expectations and Nasdaq direction.
- IPO activity: Fusion CX closes Oct 18; Zetwerk closes Oct 17. Subscription trends will signal retail appetite.
8. The Honest Take
For Long-Term Investors
This was a session where quality outperformed. IT earnings are beating, the rupee is strengthening, and crude is easing — three tailwinds that don’t always align. If you hold blue-chip IT names, today validated your patience. But the broader market’s weakness — midcaps down, small caps bleeding, breadth anaemic — is a reminder that concentrated portfolios win in narrow rallies. Diversification still matters. Nestlé’s 9% plunge on in-line earnings is a lesson: premium valuations leave no room for error. If you’re underweight IT and overweight cyclicals, stay disciplined. Rotation will come, but timing it is hard. Keep your SIPs running, rebalance annually, and ignore the daily noise.
For Active Traders
Today was a gift if you were long IT and flat everything else. Persistent, Wipro, Tech Mahindra — all delivered. But chasing here is dangerous; RSI levels are stretched, and profit-booking is inevitable. Bank Nifty’s 33-point gain is a non-event; the index is range-bound until it breaks 56,000 or 55,000. Watch for mean reversion in IT early next week, and be ready to fade overbought names. Nestlé’s crash might offer a contrarian bounce trade, but wait for a technical reversal pattern first. Volume spikes in defence and semis (KPIT, Moschip) are worth tracking — momentum is building, but confirmation is needed. The weekend gives you time to reset. Use it.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher