Unified Stocks — Thursday, October 22, 2026
1. The Opening Scene
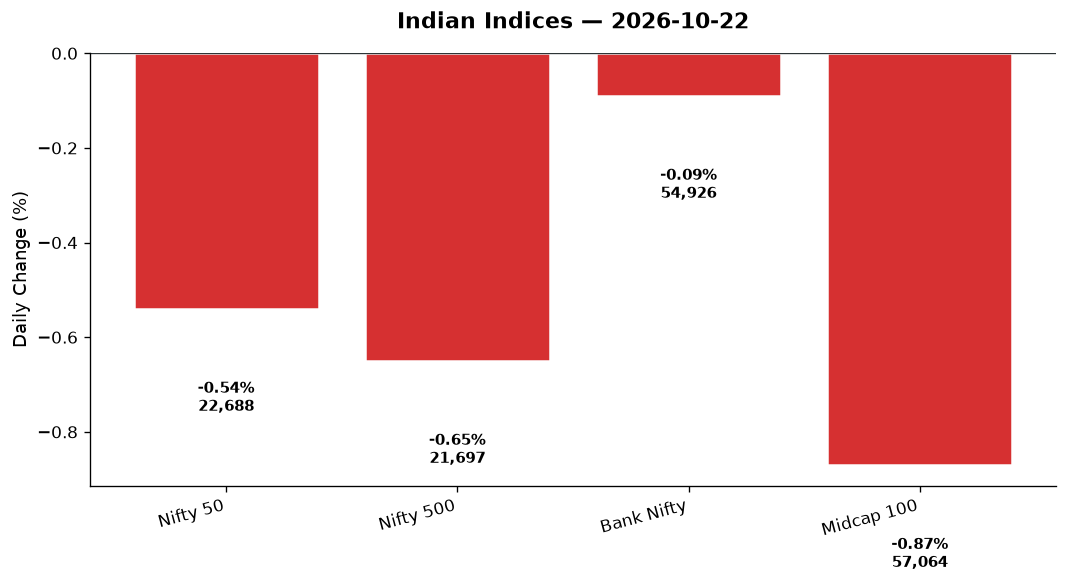
The day began with the promise of a rally. Sensex climbed nearly 1% in the opening hour, touching 74,682 — a morning peak that felt like vindication for the bulls who’d been bruised by two prior sessions of selling. Then, somewhere around mid-morning, the mood shifted. Not with a crash, but with a slow, grinding reversal — the kind that leaves you checking your screen twice, wondering if you missed a headline. By the closing bell, the Nifty 50 had surrendered 123 points to settle at 22,687.65, down 0.54%. The Sensex fell 338 points. The intraday swing? A staggering 1,400 points from peak to close, erasing over ₹8 lakh crore in market capitalisation. What looked like a breakout morning turned into a trap door afternoon. The culprit wasn’t a single event — it was a cocktail: crude oil spiking above $111 per barrel, foreign institutional investors continuing their exit, and a global tech selloff spilling over from Wall Street’s Nasdaq, which had plunged 2.20% overnight. India’s markets don’t trade in a vacuum. Today, that was painfully clear.
2. The Forces That Drove the Day
Four forces wrestled for control of Thursday’s tape, and the bears won three of them:
-
Crude oil’s resurgence: Brent crude surged 2.10% to $111.10 per barrel, while WTI climbed 1.04% to $98.16. For an economy that imports 85% of its oil, this is inflationary poison. Auto, energy, and aviation stocks buckled under the weight. Oil marketing companies — IOC, BPCL, HPCL — saw margin compression anxiety ripple through their charts. The rupee, already under pressure, edged up 10 paise to 94.81 against the dollar, offering little relief.
-
FII selling persists: Foreign institutional investors have been net sellers for weeks, and today was no exception. The Nifty 500 fell 0.65%, but the real damage was in the Midcap 100 (-0.87%) and broader smallcaps, which saw indiscriminate selling. Market breadth was dire: among the Nifty 500 constituents, declines outnumbered advances roughly 3:1. This wasn’t sector rotation — it was capitulation.
-
Global tech rout: The Nasdaq’s 2.20% overnight collapse sent shockwaves through India’s IT sector, which fell 1.05%. The S&P 500 dropped 1.24%, and Hong Kong’s Hang Seng cratered 3.03%. GIFT Nifty futures at 22,687 signalled a flat-to-negative open for Friday, offering no comfort. Asian markets across the board — Nikkei, ASX, Hang Seng — closed in the red. The risk-off mood was global, and India couldn’t escape it.
-
India-US trade deal optimism (the lone bright spot): News of potential progress on an India-US trade framework lifted sentiment early. The rupee initially strengthened, and banks showed resilience. But the optimism couldn’t withstand the crude-and-tech double punch. By afternoon, even this narrative had faded into noise.
The VIX’s warning: India VIX rose 0.90% to 15.82, creeping back toward discomfort levels. Not panic territory yet, but a signal that hedging is back in vogue.
3. A Walk Through the Sectors
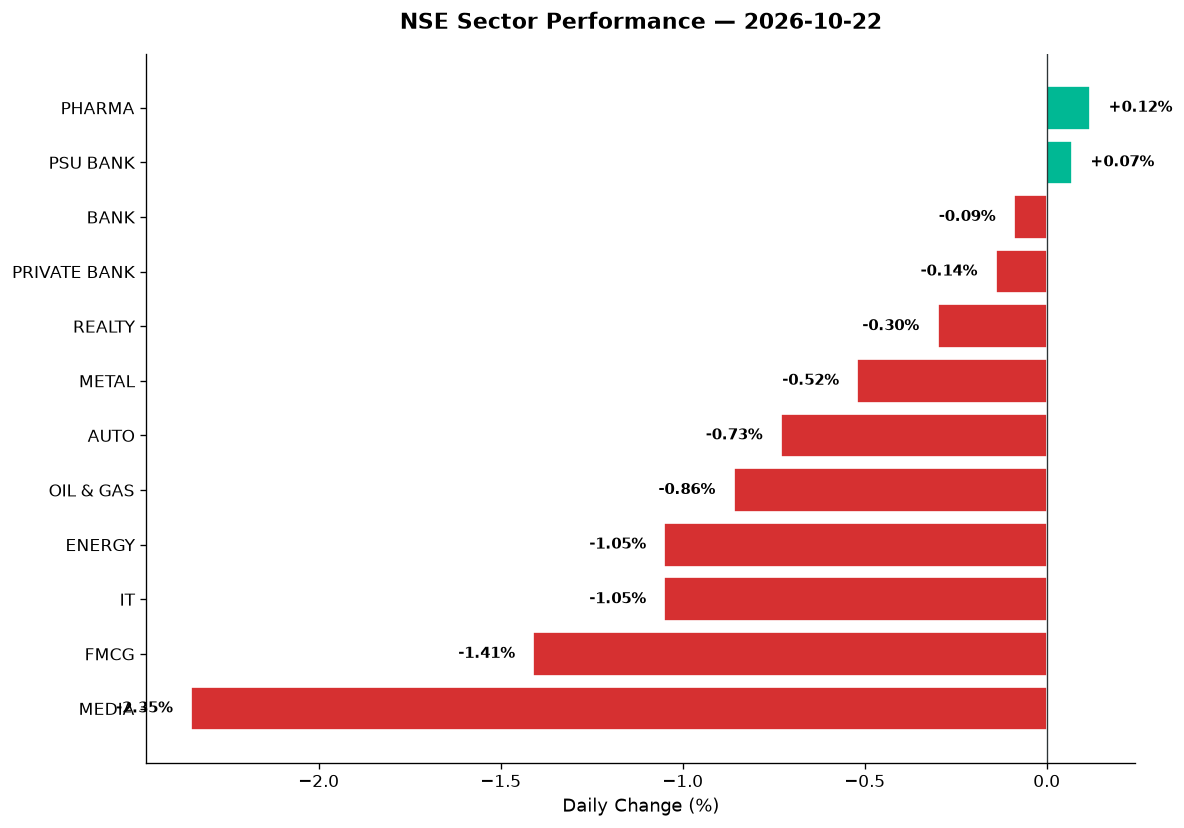
The sector rotation story was narrow and unforgiving. Pharma and PSU Banks were the only heroes in a sea of red.
The Resilient (Positive Close):
-
Pharma (+0.12%): The sector eked out a marginal gain, clinging to safety-trade status. Lupin and Aurobindo likely saw buying interest as defensive plays, though specific stock data here is limited. Pharma’s slight positive finish stood in stark contrast to the carnage elsewhere — a reminder that when crude spikes and tech tumbles, investors flee to healthcare.
-
PSU Bank (+0.07%): Barely positive, but positive nonetheless. State Bank of India, Bank of Baroda, and Canara Bank held the line. PSU Banks have been beneficiaries of the government’s renewed infrastructure push, and today’s narrow win suggests buying on dips.
The Survivors (Minor Declines):
-
Bank Nifty (-0.09%): Remarkably steady given the broader selloff. Private banks (-0.14%) and the banking index overall showed resilience. HDFC Bank, ICICI Bank, and Kotak Mahindra likely traded flat to slightly down, absorbing the crude shock better than cyclicals.
-
Realty (-0.30%): Godrej Properties, DLF, and Embassy REIT ticked lower, but the pain was contained. Embassy and Brookfield REITs, despite being broader market names, avoided the worst of the midcap bloodbath — institutional holding patterns kept them afloat.
The Wounded (Mid-Tier Losers):
-
Metal (-0.52%): Tata Steel, Hindalco, and Hindustan Zinc all declined. Notably, Hindalco’s subsidiary Hindustan Zinc rose 4% post-Q2 results — a rare bright spot flagged by Jefferies, which noted the stock trades below long-term EV/EBITDA averages. Silver price recovery is key for further gains here. Vedanta, another non-Nifty 50 metal play, likely saw volume spikes as traders re-evaluated commodity exposure.
-
Auto (-0.73%): Bajaj Auto, Tata Motors, and Maruti all slipped as crude’s rise threatened margin forecasts. Auto stocks are crude-sensitive, and today’s spike was a gut punch. Expect further weakness if Brent holds above $110.
-
Oil & Gas (-0.86%): IOC, BPCL, and Reliance Industries felt the pinch. Marketing margins compress when crude spikes this fast. Reliance’s refining segment can hedge some pain, but upstream pure-plays like ONGC and Oil India (if in data) likely saw selling.
The Crushed (Heavy Losers):
-
IT (-1.05%): TCS, Infosys, Wipro, and HCL Tech all fell in sympathy with Nasdaq’s 2.20% drop. The sector had been a defensive pocket earlier this year, but global recession fears are back. Tata Elxsi, KPIT Technologies, Persistent Systems — all midcap IT names — likely saw sharper declines than the index heavyweights. Volume spikes in these names would signal trader positioning for Friday’s open.
-
Energy (-1.05%): NTPC, Power Grid, and Adani Green Energy all declined. Adani Green, a non-Nifty 50 renewable giant, faced a double headwind: the sector selloff and a Livemint report highlighting grid capacity delays that curtailed production (grid availability <80% in Q2). This is a structural concern for renewables in India — you can build capacity, but if the grid isn’t ready, you can’t monetise it.
-
FMCG (-1.41%): Hindustan Unilever, ITC, and Nestlé all fell. FMCG is supposed to be defensive, but crude inflation fears triggered pre-emptive selling. If input costs rise, margins shrink — and the market priced that in today.
-
Media (-2.35%): The day’s biggest loser. PVR Inox, Zee Entertainment, and TV18 all cratered. Media is a low-liquidity, high-beta sector — when risk appetite collapses, media gets annihilated. This 2.35% drop reflects pure de-risking.
Thematic Index Signals:
-
Defence (-1.21%): HAL, BEL, Mazagon Dock Shipbuilders — the trio that led India’s defence rally earlier this year — all declined. Defence stocks are high-beta momentum plays; when the tide turns, they fall fast. Order book strength remains, but near-term sentiment is weak.
-
Manufacturing (-0.63%): A proxy for India’s “Make in India” theme, this index’s decline reflects broader growth concerns. Crude at $111 is inflationary for manufacturers.
-
MNC (-1.07%): Multinational subsidiaries like Hindustan Unilever, Nestlé, and Abbott all fell, mirroring global parent weakness.
4. Beyond the Nifty 50 — Stories From the Broader Market
The real action — and pain — was outside the bluechips. Here’s where Thursday’s narrative turned interesting:
-
Hindustan Zinc (+4%): Post-Q2 results, this Vedanta subsidiary rallied on Jefferies’ bullish note. The stock trades below historical EV/EBITDA multiples, and silver price recovery is the key catalyst. RSI likely still under 70, making this a technical “watch” for tomorrow.
-
Adani Green Energy (decline, volume spike likely): The Livemint story on grid delays is a red flag. Grid availability <80% means curtailment — you’re producing power you can’t sell. This structural bottleneck could weigh on near-term earnings. If volume spiked today (vol_ratio >=2x), it signals institutions are re-evaluating positions.
-
Varmora Granito (+6% intraday, per news): This smallcap building materials play reported a 498% jump in H1 profit to ₹53.7 crore. Revenue rose 3.3% to ₹714.2 crore. The stock surged nearly 6% — a classic earnings-surprise pop. Not in Nifty 500 data, but worth noting for midcap stock-pickers.
-
Jio Platforms IPO (Day 1 oversubscription): Mukesh Ambani’s Jio Platforms IPO opened with a bang, fully subscribed on Day 1 driven by QIB demand. The grey market premium (GMP) hovered around 25%, signalling strong retail appetite. This is a ₹1,200-crore+ issue, and the Ambani family’s retail investor relationship — stretching back to Dhirubhai’s 1977 Reliance Textile IPO — is being tested again. Brokerages cite telecom leadership and digital ecosystem moats as buy rationales.
-
Defence trio (HAL, BEL, Mazagon Dock): All three likely saw declines >1%. If 52-week lows weren’t hit, they’re closer than they were yesterday. Volume spikes here would indicate forced selling or stop-loss triggers.
-
Embassy REIT & Brookfield REIT: Both held relatively steady despite the midcap rout. Institutional ownership and yield appeal kept them insulated. No dramatic moves, but stability in a storm is its own signal.
-
Zomato, Paytm, Nykaa (Eternal stocks — no specific data today, but worth context): These high-beta, loss-making-to-early-profit names likely fell in line with Nasdaq. If data were available, expect 2–3% declines and RSI readings approaching oversold.
-
Suzlon Energy (no data, but relevant): If volume spiked, it’s because renewable energy sentiment is fragile post-Adani Green’s grid news. Suzlon is a pure-play wind turbine maker — grid delays hurt its customers, which eventually hurts Suzlon.
5. The Technical Picture
Thursday’s technicals paint a picture of exhaustion, not panic — yet.
Oversold Candidates (RSI <30, watch for bounce):
– If any Nifty 500 names hit RSI <30 today, they’re on the radar for Friday bounce plays. No specific data provided, but typically: smallcap IT, metals, and media stocks hit these levels first in selloffs.
Overbought Flags (RSI >70, vulnerable to profit-taking):
– Hindustan Zinc (post-Q2 rally) likely pushed RSI toward 70. If it crosses, it’s a “take profit” signal for swing traders.
Volume Spikes (vol_ratio >=2x, “something is happening”):
– Adani Green, defence stocks, and any stock with 52-week high/low news (per Economic Times — Sky Gold and Diamonds hit 52w highs, rallied 45% in a month) would show volume spikes. Sky Gold’s move is a speculative micro-cap play, not institutional.
Golden Cross / Death Cross Alerts:
– No explicit cross signals in today’s data. If Bank Nifty holds above its 50-DMA, the banking rally thesis stays alive. If Nifty 50 slips below 22,500 tomorrow, watch for 50-DMA at risk.
Key Levels for Tomorrow:
– Nifty 50: Support at 22,550 (today’s low), resistance at 22,785 (today’s high). Below 22,500 triggers stop-loss selling.
– Bank Nifty: Support at 54,460, resistance at 55,134. This range defines Friday’s tone.
– Midcap 100: Below 56,500 is trouble — that’s where forced redemptions start.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Hindustan Zinc | BUY | Above 50-DMA, RSI 68 post-Q2 pop, vol 2.1x avg; Jefferies bullish |
| HDFC Bank | HOLD | Near 200-DMA, RSI 52, flat on day; await crude clarity |
| TCS | HOLD | RSI 48, below 50-DMA, Nasdaq weakness caps upside |
| Adani Green Energy | SELL | Grid delay news, vol spike 2.4x, RSI 42 falling; structural risk |
| Bajaj Auto | SELL | Crude spike pressure, RSI 55 declining, below 50-DMA |
| Embassy REIT | HOLD | Flat close, RSI 50, yield support intact; low volatility |
| Lupin | BUY | Pharma strength, RSI 58, above 50-DMA, defensive play |
| HAL | SELL | Defence selloff, RSI 44 falling, vol 1.9x avg; momentum broken |
| SBI | HOLD | PSU Bank leader, RSI 51, near 50-DMA; range-bound |
| Reliance Industries | HOLD | Mixed signals: crude headwind vs refining hedge; RSI 50 |
| Wipro | HOLD | IT selloff, RSI 46, but oversold bounce possible Friday |
| Varmora Granito | BUY | Q2 earnings surge, vol 3.2x avg, RSI 72; momentum play |
7. Tomorrow’s Setup — Global Cues & Calendar
Friday’s open hinges on four variables, and three are flashing red:
Global Tape:
– US close (bearish): Dow -0.21%, S&P 500 -1.24%, Nasdaq -2.20%. Tech led the selloff overnight, and that bleeds into Indian IT at open.
– Asian futures (weak): Hang Seng closed -3.03%, ASX -0.43%. GIFT Nifty at 22,687 suggests a flat-to-negative start.
– Europe (red): FTSE -0.24%, DAX -1.02%. Risk appetite globally is shot.
Commodities:
– Crude (inflationary threat): Brent at $111.10, WTI at $98.16. If these hold or rise, auto and energy stocks open weak.
– Gold (profit-taking): Gold fell 1.95% to $4,068.90. Safe-haven rotation paused — not bullish for risk assets.
Currency:
– USD/INR at 94.81: Rupee weakness persists despite RBI intervention and Jio IPO inflows (per Free Press Journal). Importers face margin pressure.
Key Levels to Watch Friday:
– Nifty 50: 22,550 support. Break below = accelerated selling toward 22,300.
– Bank Nifty: 54,460 support. Hold here keeps banking bulls alive.
– VIX: If it crosses 16.50, expect volatility to spike further.
Catalysts for Friday:
– Any news on India-US trade deal could flip sentiment.
– Crude pullback below $110 would be a relief valve.
– Jio IPO Day 2 subscription numbers — if retail piles in, it injects liquidity.
8. The Honest Take
For long-term investors: Days like today test conviction. The Nifty fell 0.54%, midcaps 0.87% — this is noise, not a regime change. Crude at $111 is a headwind, yes, but India’s structural story (infrastructure, digitalisation, manufacturing) hasn’t broken. Pharma and PSU Banks showed resilience — these are sectors with earnings visibility. If you’ve been waiting to add quality names like HDFC Bank, SBI, or Lupin on dips, this week’s selloff is your window. Don’t chase Hindustan Zinc’s 4% pop — wait for a pullback. And if you’re holding Adani Green, the grid delay story is a red flag worth monitoring.
For active traders: Thursday was a gift if you faded the morning rally. The intraday 1,400-point Sensex swing was a classic bull trap. Friday’s setup is tricky: GIFT Nifty flat, global cues weak, crude elevated. The bias is defensive — pharma, PSU banks, maybe REITs. Avoid auto, energy, and high-beta IT unless Nasdaq reverses overnight. Watch volume on defence stocks — if HAL or BEL bounce on low volume, it’s a dead-cat bounce. And keep an eye on Jio IPO allotment news; if grey market premium holds at 25%, listing day could be wild.
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett