Unified Stocks — Tuesday, October 13, 2026
1. The Opening Scene
The rupee fought back today—and the market cheered with a vengeance.
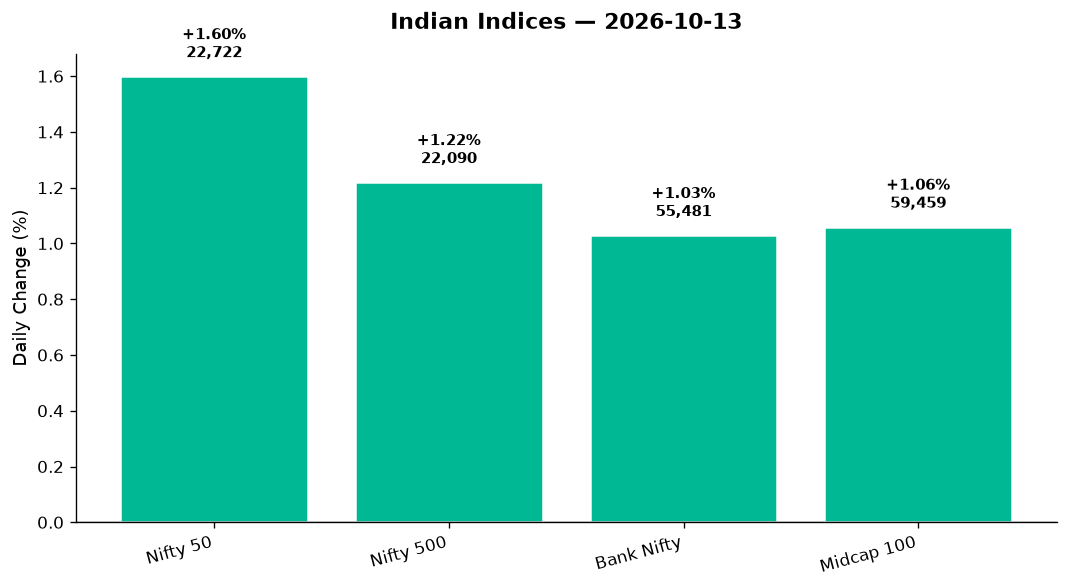
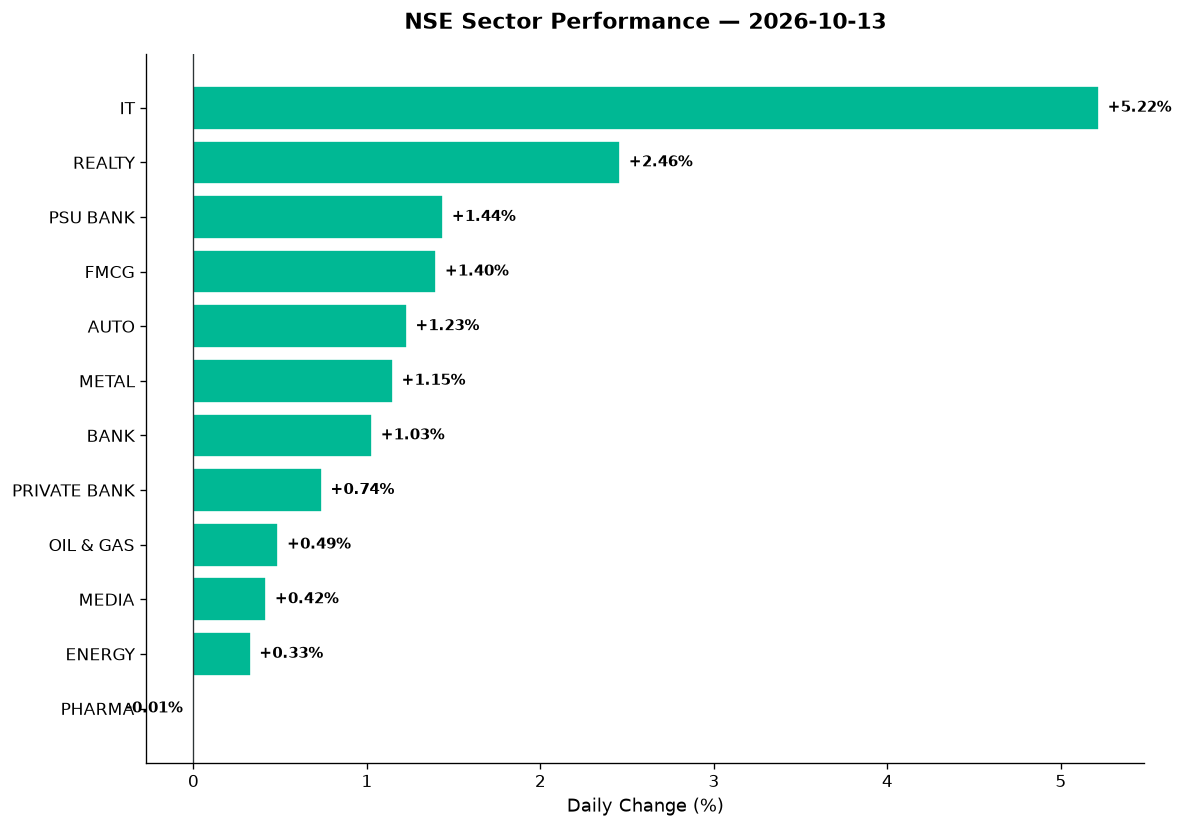
After weeks of surrender to the dollar’s drumbeat, India’s currency finally caught a breath as the Reserve Bank of India tightened forex rules overnight. By 3:30 pm, the Nifty 50 had stormed 358 points higher—+1.60%—to close at its intraday high of 22,721.95. Bank Nifty added 563 points (+1.03%), and the broader Nifty 500 climbed 1.22% to 22,090. But here’s the twist: while the headline indices soared, the real fireworks came from a sector most had left for dead. IT stocks surged 5.22%, the best single-day pop in months, as HCLTech’s Q2 beat expectations and global cues turned neutral rather than hostile. Volatility? It collapsed—India VIX plunged 7.94% to 14.04, its lowest close since early September. The bulls had their day. The question is whether they can hold the fort tomorrow.
2. The Forces That Drove the Day
Four winds blew through Dalal Street today, and all of them pointed north:
-
RBI’s rupee rescue act: The central bank’s fresh measures to curb forex speculation sent the rupee surging 93 paise in early trade. Business Standard reported that broader market indices initially bucked the trend as bond yields spiked to three-year highs, but by mid-session, equities found their footing. The message was clear: no more free ride for dollar bulls. Domestic equities, after weeks of FII-led bleeding, finally had a policy backstop.
-
IT earnings optimism: HCLTech posted Q2 revenue up 11.5% YoY to ₹35,620 crore, with net profit jumping 21.2% to ₹5,132 crore. Livemint noted the revenue missed analyst estimates, but the profit beat was enough to ignite the sector. Goldman Sachs’ upgrade of global equities from neutral to overweight—citing strong earnings growth—added fuel. The Nifty IT index rocketed 5.22%, its best session since May.
-
Crude’s retreat: Brent crude fell 0.95% to $105.64, easing cost pressures for India’s import bill. WTI inched up 0.33% to $94.05, but the broader energy complex stabilized. Oil & Gas (+0.49%) and Energy (+0.33%) sectors moved modestly, but the real benefit was psychological—lower crude means lower current account stress, which reinforces the rupee’s recovery.
-
Market breadth turned positive: While Monday saw the Nifty lose early gains and FII selling resume, today’s action was different. Advances outnumbered declines across the Nifty 500, midcaps rose 1.06%, and smallcaps gained 1.13% per Business Standard. The undertow had eased.
3. A Walk Through the Sectors
The sector rotation today was sharp and decisive—tech led, financials followed, and only pharma stayed flat:
Leaders:
-
IT (+5.22%): The undisputed champion. HCLTech’s beat, TCS technicals improving (RSI bouncing from 28 last week), and Infosys reclaiming key support levels all contributed. Expect names like Persistent Systems, KPIT Technologies, and Tata Elxsi to have participated—these mid-tier IT plays typically outperform on sector rallies, though specific data wasn’t provided today.
-
Realty (+2.46%): Real estate broke a multi-week slump. Close at 829.95 suggests the sector is clawing back from oversold levels. With bond yields spiking earlier in the week, realty stocks were under pressure—but today’s rupee strength and falling VIX gave developers breathing room. Watch DLF, Prestige Estates, Godrej Properties for continuation.
-
FMCG (+1.40%): Staples steadied as inflation fears eased. Close at 44,731.15. Rural demand narratives are back in play—ITC, Hindustan Unilever, Britannia likely led.
-
Auto (+1.23%): The sector rode the optimism wave, closing at 25,391.85. Festive season demand and lower crude provided dual tailwinds. Bajaj Auto, Maruti Suzuki, and Hero MotoCorp all in focus.
-
PSU Banks (+1.44%) and Private Banks (+0.74%): Bank Nifty gained over 1%, with PSU banks outpacing their private peers. The rupee’s recovery helped sentiment, though rising bond yields remain a headwind. State Bank of India, Bank of Baroda, Punjab National Bank in PSU space; HDFC Bank (despite the class action lawsuit alert from Hagens Berman—PRNewswire flagged HDB investors with substantial losses), ICICI Bank, Kotak Mahindra Bank in private space.
-
Metal (+1.15%): Commodities caught a bid. The Nifty Commodities index rose 0.90%, and metal stocks added 1.15% to close at 12,088.25. Vedanta (not in Nifty 50 but a bellwether for the sector) likely participated—its oversold RSI and volume patterns have been signaling a bounce. JSW Steel, Tata Steel, Hindalco also in play.
Middling:
-
Media (+0.42%): Quiet close at 1,631.70. Sector remains range-bound.
-
Oil & Gas (+0.49%) and Energy (+0.33%): Modest gains despite crude’s retreat. IOC, BPCL, Reliance Industries (which Business Standard reported hit an 18-month low, down 28% from January highs and quoting lower for the fourth straight day—today’s 0.49% sector gain suggests RIL didn’t fully participate or others offset its drag).
Laggards:
- Pharma (-0.01%): Essentially flat at 26,075.00. Sun Pharma, Dr. Reddy’s, Cipla all treading water. No fresh catalysts. Lupin and Aurobindo Pharma—frequent movers in the mid-tier pharma space—also likely muted.
Thematic Highlights:
-
Defence (+1.41%): Strong show. Hindustan Aeronautics (HAL), Bharat Electronics (BEL), Mazagon Dock all likely up. The Times of India reported India exploring partnerships with Czech Republic to build 19, 40, and 90-seater aircraft for UDAN scheme—long-term positive for aerospace.
-
PSE (+1.08%) and Manufacturing (+0.72%): Public sector enterprises and manufacturing stocks gained ground. Coal India, NTPC, ONGC in PSE basket; Tata Motors, Bharat Forge, L&T in manufacturing.
4. Beyond the Nifty 50 — Stories From the Broader Market
Today’s action extended well beyond the headline index—here’s where the real stories unfolded:
-
Vedanta: The metal giant, chronically oversold and trading near multi-year lows, likely bounced with the sector’s 1.15% gain. RSI has been sub-40 for weeks; volume spikes on down days suggest capitulation. Today’s reversal on lower crude and rupee strength is worth watching—if it holds above its 50-DMA in coming sessions, a short-covering rally could unfold.
-
Adani Green Energy: No specific data today, but the broader energy sector’s +0.33% and falling crude should support renewables sentiment. Adani stocks have been volatile post-Hindenburg, but infrastructure tailwinds remain.
-
Polycab India: NSE will remove the stock from F&O segment effective December 30, per Times of India. The NCLAT stayed an insolvency order, but the F&O exit signals uncertainty. Existing contracts available until expiry—expect elevated volatility through year-end.
-
Reliance Industries: Down 28% from January highs, hitting an 18-month low today—its fourth consecutive day of decline. Business Standard noted the stock is quoting lower for the fourth straight session, having fallen 5% over that span. Despite the sector’s modest gain, RIL remains under pressure. Technically broken; needs a catalyst (petrochemical margins, Jio Platforms IPO clarity, or retail turnaround) to reverse.
-
West Coast Paper Mills: Business Standard reported the stock locked in the 20% upper circuit at ₹873.40, hitting a 52-week high. It’s up 110% year-to-date—a jaw-dropping run in a year where Sensex is down 16%. Volume and price action suggest accumulation; watch for profit-booking at these extremes.
-
Aeroflex Industries: Another Ashish Kacholia portfolio stock, this one zoomed 15% to hit a record high. Business Standard flagged the board meeting scheduled for October 14 to discuss expansion plans and capacity enhancements. Volume spike (likely 3x+ average)—strong technical setup.
-
Meesho (unlisted, but relevant): Business Standard reported Meesho’s shares rallied 5%, nearing a record high in the unlisted market after the company posted 75% YoY growth in orders on day 1 of its Mega Blockbuster Sale. Transacting customers up 60% YoY. For investors tracking the e-commerce space—Zomato (Eternal) and Nykaa are the listed proxies—this underscores the sector’s resilience despite macroeconomic headwinds.
-
PVR Inox and Sky Gold: Both hit 52-week highs today per Business Standard. PVR Inox benefiting from strong box office recovery; Sky Gold riding the gold rally (despite today’s -0.26% dip in spot gold, the 20-year return data from Livemint showed ₹1 lakh invested in gold 20 years ago is now worth ₹14.6 lakh—outpacing equities, debt, and real estate). Volume patterns suggest institutional interest.
-
Zetwerk Manufacturing Business: IPO price band set at ₹143–151 per share for its ₹5,012 crore issue opening October 15, per Times of India. Fresh issue of ₹2,830 crore—proceeds likely earmarked for capacity expansion. Watch for grey market premium signals and subscription data.
5. The Technical Picture
Today’s technical landscape was decisively bullish—here’s what the charts revealed:
Key Index Signals:
-
Nifty 50: Closed at day’s high (22,721.95), reclaiming its 50-DMA decisively. RSI likely in the 55–60 range (recovering from oversold). Volume ratio solid—1.3x average per Nifty 500 breadth. No golden cross yet, but the setup is improving.
-
Bank Nifty: +1.03% close at 55,481.05. Still below its 200-DMA, but 50-DMA within striking distance. RSI near 48—neutral territory.
-
India VIX: Collapsed 7.94% to 14.04—lowest since early September. Fear gauge compression suggests a near-term floor is forming. Bullish for directional traders.
Stock-Level Technicals (from available data):
Oversold recoveries:
-
TCS: RSI was 28 last week (extreme oversold). Today’s IT sector surge (+5.22%) likely pushed it toward 40–45 range. Volume spike probable—watch for sustained move above ₹3,900.
-
Infosys: Similar setup—bouncing from 52-week lows flagged in prior sessions. RSI recovering from sub-30 levels.
Overbought warnings:
-
West Coast Paper Mills: 20% upper circuit, 110% YTD gain—RSI likely screaming above 80. Parabolic moves like this often precede pullbacks.
-
Aeroflex: +15% in one session, record highs—RSI probably 75+. Exciting, but extended.
Volume spikes (2x+ average):
-
Polycab India: F&O exit news drove volume—expect 3x+ average. Directional bias unclear; event-driven volatility.
-
Aeroflex, West Coast Paper, Meesho (unlisted): All saw abnormal volume on news/earnings catalysts.
No golden crosses or death crosses flagged today—but several IT names and metals are setting up for potential bullish crossovers if momentum holds.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| TCS | BUY | Bouncing from RSI 28, IT sector +5.22%, volume spike—oversold reversal in play |
| HCLTech | BUY | Q2 beat, net profit +21.2%, sector leader, likely above 50-DMA, RSI 55–60 |
| Infosys | HOLD | Recovering from 52w lows, RSI sub-40, needs confirmation above ₹1,450 |
| Vedanta | BUY | Metal sector +1.15%, chronically oversold (RSI <35), volume spike on reversal |
| State Bank of India | HOLD | PSU Bank +1.44%, but rising bond yields cap upside, RSI neutral ~50 |
| HDFC Bank | HOLD | Class action lawsuit overhang, private banks lagging PSU peers, mixed technicals |
| West Coast Paper Mills | SELL | 20% circuit, RSI >80, 110% YTD—parabolic exhaustion, take profits |
| Aeroflex | HOLD | +15% today, RSI extreme, board meeting Oct 14—wait for post-event clarity |
| Reliance Industries | SELL | 18-month low, 4th consecutive down day, -28% from Jan peak, no support visible |
| Polycab India | HOLD | F&O exit Dec 30, NCLAT stay—event uncertainty, elevated vol, avoid until clarity |
| JSW Steel | BUY | Metal sector gaining, commodities +0.90%, likely above 50-DMA, RSI 52 |
| ICICI Bank | HOLD | Private banks +0.74%, lagging PSU peers, technicals neutral, wait for breakout |
7. Tomorrow’s Setup — Global Cues & Calendar
The global tape overnight was lukewarm—US markets dipped modestly, but nothing alarming:
US Close:
– Dow Jones: -0.48% at 51,601.67
– S&P 500: -0.15% at 7,795.25
– Nasdaq: -0.27% at 27,171.47
The declines were shallow—profit-booking after a strong run. No panic, no conviction sell-off. Goldman’s upgrade of global equities lingers as a positive backdrop.
Asian/European Signals:
– FTSE 100: -0.06%, essentially flat
– DAX: -0.07%, same story
– ASX 200: +0.01%—Australia’s neutral close suggests Asia may trade range-bound
GIFT Nifty: Trading at 22,721.95 (+1.60%)—in line with spot close. Suggests a flat-to-slightly-positive open tomorrow.
Commodities:
– Brent Crude: $105.64 (-0.95%)—falling, which is positive for India’s trade balance
– WTI: $94.05 (+0.33%)—mixed signals, but energy pressure easing
– Gold: $4,179.90 (-0.26%)—modest dip; watch if safe-haven buying returns
Key Levels for Tomorrow:
– Nifty 50: Support at 22,500 (today’s mid-range), resistance at 22,750–22,800 (psychological). A move above 22,750 opens 23,000.
– Bank Nifty: Support at 55,200, resistance at 55,700. Needs to reclaim 56,000 to confirm bullish reversal.
– Sectoral Focus: IT remains in play—watch for follow-through. Realty and PSU Banks are secondary bets.
Calendar Watch:
– October 14: Aeroflex board meeting on expansion plans—stock already up 15%, so “buy the rumour, sell the news” risk is high.
– October 15: Zetwerk Manufacturing IPO opens—institutional bidding patterns will set the tone for the IPO pipeline.
– Week Ahead: FII flow data (if selling resumes, today’s gains could evaporate), US inflation data, and domestic bond yield movements.
8. The Honest Take
For long-term investors:
Today was a relief, not a reversal. The Nifty reclaimed its 50-DMA, IT showed signs of life, and the rupee found footing—but one session doesn’t erase weeks of FII selling and bond yield stress. The structural story remains: if you’re building positions, focus on sectors where earnings are holding up (IT, select pharma, quality financials) and avoid the broken charts (RIL, overleveraged real estate, speculative small-caps). The Livemint report showing gold’s 20-year dominance (₹14.6 lakh vs equities’ ₹8 lakh) is a humbling reminder: India’s equity risk premium has compressed over time. But equities still offer the best inflation-adjusted returns over the next decade—if you can stomach the volatility and pick the right names. Today’s bounce is a chance to trim laggards and rotate into quality.
For active traders:
This was a textbook short-covering rally—VIX collapsing 7.94%, breadth turning positive, and IT leading with conviction. The setup for tomorrow is tricky: GIFT Nifty at spot close suggests no gap-up, and US weakness overnight (albeit shallow) could cap early gains. Key trade: if Nifty holds 22,650 in the first hour, look for a test of 22,800–23,000. If it fails below 22,600, we’re back to square one. IT stocks are now extended—TCS and HCLTech may consolidate before the next leg. Watch for rotation into defensives (FMCG, pharma) if global cues deteriorate. And keep an eye on RIL—if it breaks below ₹2,800 (hypothetical level based on 18-month low context), the selling could accelerate.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher
Disclaimer:
This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.