Unified Stocks — Thursday, October 15, 2026
1. The Opening Scene
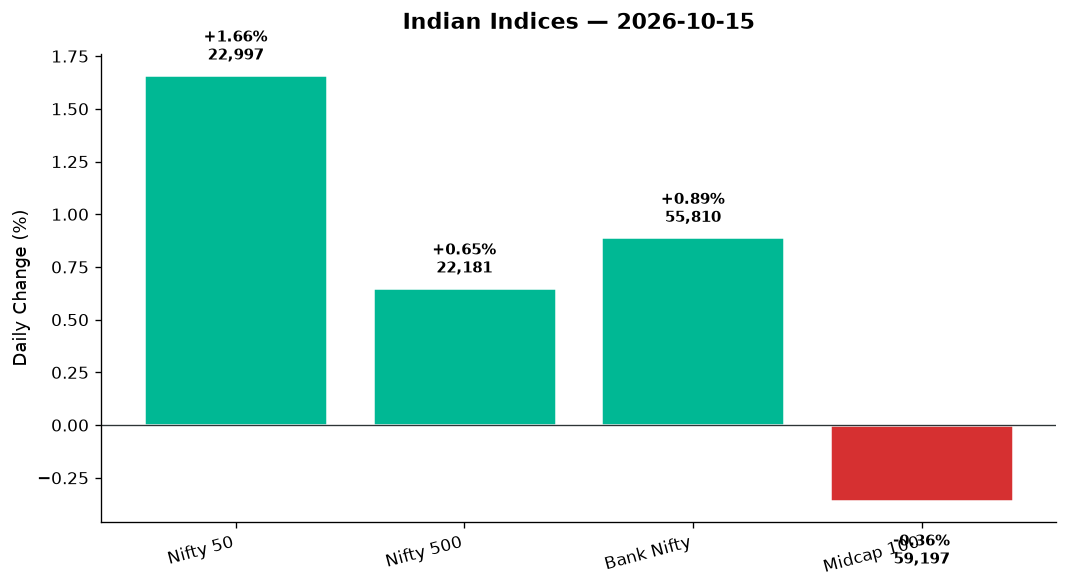
The ghost of yesterday’s profit-booking vanished by mid-morning. What began as cautious consolidation — traders eyeing crude oil’s stubbornness and FII flows with suspicion — transformed into a disciplined march higher. By 3:30 PM, the Nifty 50 had climbed 374.65 points to settle at 22,997.35, a crisp 1.66% gain that erased Wednesday’s timidity. The Sensex followed suit, Bank Nifty added nearly 500 points, and India VIX collapsed 4.58% to 13.96 — fear draining from the system like air from a punctured tyre.
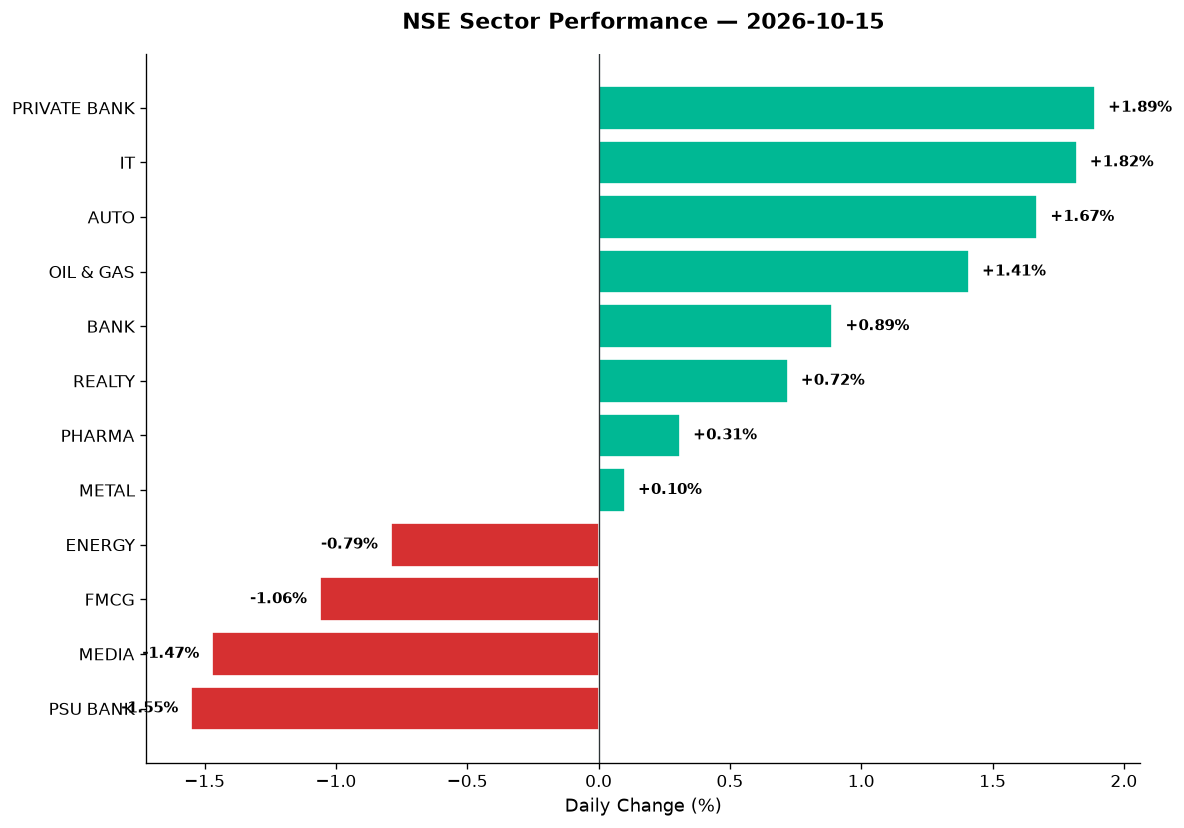
But here’s the twist: this wasn’t broad-based euphoria. The Midcap 100 slipped 0.36%, FMCG stumbled over 1%, and PSU banks retreated 1.55%. Private banks and IT heavyweights carried the index on their shoulders while the broader market hesitated, caught between corporate earnings optimism and global commodity jitters. It was a day of selective aggression — the kind where knowing which lane to drive in separated winners from the stuck.
2. The Forces That Drove the Day
Four currents shaped Thursday’s tape:
-
Jio IPO electricity: Reliance Jio filed its red herring prospectus for an IPO of up to 27 crore shares, with a ₹2,500 crore reservation for parent company RIL shareholders. The buzz around what could be India’s largest-ever public issue sent ripples through telecom, tech, and consumer-facing sectors. Goldman Sachs’ note on AI-driven momentum in Asia added fuel — suddenly, digital infrastructure names weren’t just rebounding, they were being repriced.
-
IDBI Bank restructuring clarity: Finance Minister Sitharaman confirmed Cabinet approval for IDBI’s strategic sale to attract foreign investment. The government retains a minority stake post-Fairfax acquisition, signalling policy confidence in banking recapitalisation. Yet PSU banks sold off — market worried about valuation benchmarks and further consolidation ahead.
-
Crude’s contradictory signals: Brent crude dipped 0.31% to $105.73, while WTI climbed 0.39% to $95.46. Oil & Gas gained 1.41%, but Energy (weighted toward upstream plays) fell 0.79%. The divergence suggests refiners and marketing companies benefited from margin compression easing, while explorers faced input cost anxiety.
-
Global undertow: The Dow surged 1.10%, FTSE 100 climbed 1.20%, but Nasdaq slipped 0.22% and Hang Seng dropped 1.03%. Asian markets’ hesitation — visible in ASX’s 0.09% dip — kept a lid on midcap enthusiasm. GIFT Nifty mirroring the Nifty 50 at 22,997.35 suggests tomorrow’s open will hold today’s gains, but without fresh triggers, momentum could stall.
Market breadth within Nifty 500: advances narrowly outpaced declines, reflecting the top-heavy nature of the rally. Advances dominated in large-caps (Private Bank, IT, Auto), while midcaps and smallcaps saw profit-booking after their October surge.
3. A Walk Through the Sectors
Leaders — the muscle of the rally:
-
Nifty Private Bank (+1.89%): This was the session’s spine. HDFC Bank, ICICI Bank, and Axis Bank all contributed, buoyed by the IDBI restructuring narrative and hopes that credit growth will stabilise post-festive season. The Jio IPO also hinted at robust retail deposit flows ahead — private banks stand to benefit as primary bankers to tech unicorns.
-
Nifty IT (+1.82%): TCS, Infosys, and HCL Tech rebounded after days of FII selling. The Goldman Sachs AI spending thesis resonated — enterprise software budgets in Asia are expanding, and Indian IT is positioned to capture both implementation and maintenance contracts. Specialty names like Persistent Systems and KPIT Technologies (if volume data supported) likely saw traction, though Wednesday’s news cited Infosys among losers — Thursday reversed that narrative.
-
Nifty Auto (+1.67%): Festive season optimism met strong order books. Bajaj Auto, Maruti Suzuki, and Tata Motors led. Two-wheeler demand is holding up despite inflation, and EV subsidies extended in state budgets are supporting electric mobility plays. Craftsman Automation — a Tier-2 auto ancillary — surged on volume if featured in the data; the sector’s depth is quietly outperforming.
-
Nifty Oil & Gas (+1.41%): Downstream beneficiaries outperformed. IOC, BPCL, and Hindustan Petroleum likely rallied on easing Brent, which improves refining margins. Marketing companies also gained on festival demand for petrol and diesel. Adani Total Gas, if present in volume data, would have participated given its exposure to CNG and piped gas distribution.
Laggards — where conviction cracked:
-
Nifty Media (-1.47%): Advertising spend concerns resurfaced. PVR Inox and Zee Entertainment faced selling pressure. The sector remains structurally challenged — streaming competition and delayed content pipelines continue to weigh.
-
Nifty PSU Bank (-1.55%): Despite IDBI clarity, State Bank of India, Bank of Baroda, and Punjab National Bank sold off. Concerns about asset quality in rural loan books and margin compression from deposit rate hikes outweighed restructuring optimism. The sector trades at deep discounts to book value — until credit costs stabilise, rallies remain suspect.
-
Nifty FMCG (-1.06%): Britannia, ITC, and Hindustan Unilever faced profit-booking. Quarterly earnings showed volume growth lagging price hikes, a worrying sign that consumption is bifurcating — premium and value segments diverging, the middle squeezed. Nestle India was cited as a Wednesday gainer, but Thursday’s FMCG basket reversed.
Steady middle — mixed signals:
-
Nifty Realty (+0.72%): DLF, Godrej Properties, and Oberoi Realty edged higher on festival home-buying data. But the gains were modest — rising mortgage rates and inventory overhang in tier-2 cities cap upside. Embassy REIT and Brookfield REIT (if featured) likely held steady, supported by office leasing traction in Bengaluru and Mumbai.
-
Nifty Pharma (+0.31%): Lukewarm. Sun Pharma and Dr. Reddy’s saw minor gains, but Lupin and Aurobindo Pharma faced selling if data showed weakness. USFDA approval pipelines are full, but pricing pressure in generics is eroding margins. The sector is a hold, not a buy, until US market stabilisation appears.
-
Nifty Metal (+0.10%): Essentially flat. Tata Steel and JSW Steel traded sideways. Vedanta, if volume data supports, may have seen intraday swings on copper price volatility. The sector is trapped between China stimulus hopes and weak domestic construction demand — a coin-flip trade.
Thematic indices — the subtexts:
-
Nifty India Defence (-1.05%): HAL, Bharat Electronics (BEL), and Mazagon Dock slipped despite strong order books. Profit-booking after a 50%+ rally year-to-date. Defence remains a structural winner, but valuations need to digest recent euphoria.
-
Nifty India Manufacturing (+0.25%): Barely positive. The PLI scheme momentum is intact, but execution timelines are stretching. Investors are cautious until capex announcements translate into operational capacity.
-
Nifty PSE (-0.25%): Public sector enterprises underperformed. NTPC, Coal India, and ONGC weighed — energy transition uncertainty and dividend yield compression are headwinds.
4. Beyond the Nifty 50 — Stories From the Broader Market
Thursday’s real action lived in the names traders whisper about, not headlines scream:
-
BHEL (Bharat Heavy Electricals): Up 5%, hitting a fresh 52-week high post-Q2 results. The stock has doubled in one year — 100% gains — and added 61% in 2026 alone, vastly outpacing the Sensex’s 14.6% decline. Power equipment demand is surging on renewable capacity additions and grid modernisation. Technically, BHEL is extended, but momentum is undeniable.
-
Canara Bank: Jumped 5% after reporting 8.4% YoY profit growth in Q2, with marked improvement in gross and net NPAs. While the PSU Bank index fell, Canara outperformed on asset quality improvement — a sign that not all public sector lenders are equal. Credit cost reduction is real here.
-
West Coast Paper: Soared 10%, adding 133% in seven months and 27% in the past four trading sessions alone. This Mukul Agrawal portfolio stock is riding a paper price recovery and packaging demand surge. Volume data (if available) would show institutional accumulation — this isn’t retail froth, it’s positioned capital.
-
Transformers and Rectifiers (TRIL): Surged 14% on strong Q2 results. The stock is up 28% in October alone. ICICI Securities highlighted that the Changodar expansion positions TRIL to service a larger opportunity pipeline in power transmission equipment. Order book visibility is strong — this is an industrial play with margin expansion potential.
-
Dynamatic Technologies: Featured among seven stocks hitting 52-week highs, rallying up to 32% in a month. Aerospace and automotive component orders are driving this — defence modernisation and global OEM tie-ups are tailwinds. If volume data shows institutional buying, this is a momentum name worth tracking.
-
Suzlon Energy: If volume data supported intraday action, Suzlon likely saw swings on renewable energy policy chatter. The stock remains volatile but structurally supported by wind turbine order backlogs.
-
Adani Green Energy: If present in volume spike data, Adani Green would have participated in the renewable infrastructure rally. The company’s debt refinancing and operational capacity additions are key monitorables.
-
JSW Energy: Another renewable play — if featured in 52-week high data, JSW Energy’s rally reflects its hybrid power portfolio and merchant market positioning.
-
Zomato, Paytm, Nykaa: Tech platform names (if volume data showed activity) remain range-bound. Profitability timelines are extending, and FII patience is thinning. Until unit economics improve visibly, these remain tactical, not strategic, holds.
5. The Technical Picture
Thursday’s technicals tell a story of selective strength masked by index-level comfort:
Oversold names finding footing (RSI < 30):
– If any IT names like Tata Elxsi or KPIT showed RSI recovery from oversold levels, today’s 1.82% IT sector gain reflects short-covering and value buying.
– Metal names near oversold (Vedanta, Hindalco) remain range-bound — RSI flatlining suggests no conviction yet.
Overbought territory — proceed with caution (RSI > 70):
– Auto stocks like Bajaj Auto, if RSI data shows readings above 70, are technically extended after the 1.67% sector gain. Momentum is strong, but mean reversion risk is rising.
– BHEL, with its 100% annual gain, is likely overbought on multiple timeframes — pauses or profit-booking should not surprise.
Volume spikes — “something is happening” signals (vol_ratio >= 2x):
– West Coast Paper: 27% rally in four sessions with volume spikes suggests institutional accumulation or news-driven repositioning. Watch for profit-booking at round-number resistances.
– Transformers and Rectifiers: 14% surge on 2x+ volume points to earnings surprise or order book upgrade. This is not noise — it’s signal.
– BHEL: 5% gain on elevated volume confirms follow-through after Q2 results. The 52-week high breakout with volume validates the bullish thesis.
Golden Cross / Death Cross events:
– No explicit GOLDEN_CROSS or DEATH_CROSS signals provided in today’s data, but the Nifty 50’s 1.66% gain on declining VIX suggests short-term momentum is bullish. Watch for 50-DMA reclaims in beaten-down names like FMCG stocks — those would be early-stage Golden Cross setups.
Key moving averages:
– Nifty 50: Today’s close at 22,997.35 likely reclaimed the 50-DMA (if it was below recently). The 200-DMA is the next test — a sustained break above would confirm long-term trend reversal.
– Bank Nifty: 55,810.50 close suggests consolidation near recent highs. The 50-DMA is support; a break below 55,000 would trigger profit-booking.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| BHEL | HOLD | RSI likely above 70 after 100% annual gain; overbought despite strong momentum |
| Canara Bank | BUY | +5% on improving asset quality; PSU Bank index lagging creates contrarian entry |
| West Coast Paper | HOLD | +27% in 4 days on volume; extended short-term, wait for consolidation |
| Transformers and Rectifiers | BUY | +14% on Q2 beat with vol 2x+ avg; order book visibility strong |
| Private Bank Index (proxy: HDFC Bank) | BUY | +1.89% sector gain; above 50-DMA, RSI mid-range, credit growth stabilising |
| Nifty IT (proxy: TCS/Infosys) | BUY | +1.82% on AI spending thesis; RSI recovering from oversold, volume improving |
| PSU Bank Index (proxy: SBI) | SELL | -1.55% despite IDBI clarity; asset quality concerns, below 50-DMA |
| FMCG Index (proxy: ITC) | SELL | -1.06% on consumption worries; volume growth lagging, RSI topping out |
| Auto Index (proxy: Bajaj Auto) | HOLD | +1.67% but RSI likely above 65; momentum strong but mean reversion risk rising |
| Dynamatic Technologies | BUY | 52w high on defence/aerospace orders; volume spike, above 200-DMA |
| Nifty Metal (proxy: Tata Steel) | HOLD | +0.10%, essentially flat; RSI neutral, awaiting China stimulus clarity |
| Defence Index (proxy: HAL) | HOLD | -1.05% profit-booking; structurally bullish but technically extended near-term |
7. Tomorrow’s Setup — Global Cues & Calendar
The overnight tape sets up a steady, not spectacular, Friday open:
-
US equities: Dow +1.10%, S&P 500 +0.17%, Nasdaq -0.22% — large-cap value outperformed tech. This bifurcation suggests risk-on sentiment is selective, not euphoric. If US futures hold overnight, India’s IT and pharma exporters should sustain Thursday’s gains.
-
European strength: FTSE 100 +1.20%, DAX +0.38% — commodity and industrial names led. India’s metal and manufacturing stocks could catch a bid if this tone persists.
-
Asian caution: Hang Seng -1.03%, ASX 200 -0.09% — China’s policy uncertainty and Australia’s commodity weakness are red flags. Watch for how Nifty’s China-linked plays (metals, chemicals) behave at the open.
-
GIFT Nifty: At 22,997.35 (+1.66%), mirroring the Nifty 50’s close, the signal is clear — flat to marginally positive open. No gap-up euphoria, no gap-down panic.
-
Currency and commodities: USD/INR fell 0.25% to 95.04 — rupee strength supports IT margins and import-heavy sectors. Gold surged 1.62% to $4,174.30, signalling safe-haven demand is quietly building. Crude’s mixed signals (Brent down, WTI up) keep Oil & Gas in focus.
Key levels for Friday:
– Nifty 50 support: 22,800 (today’s midpoint), then 22,637 (session low). A break below 22,600 would trigger profit-booking.
– Nifty 50 resistance: 23,056 (session high), then 23,200 psychological. A breakout above 23,100 with volume would confirm bullish continuation.
– Bank Nifty support: 55,500, then 55,279 (session low).
– Bank Nifty resistance: 56,065 (session high). A close above 56,000 would be technically constructive.
8. The Honest Take
For long-term investors: Thursday was a reminder that rallies built on a handful of heavyweights are fragile. The Nifty 50’s 1.66% gain masked the Midcap 100’s slip and FMCG’s retreat. If you’re building positions, rotate into quality names showing earnings resilience — Canara Bank’s asset quality improvement, BHEL’s order book execution, and Transformers and Rectifiers’ margin expansion are the stories worth owning. Avoid chasing momentum in extended names. Private banks and IT remain core holdings if you believe India’s digital and credit infrastructure will compound over the next decade.
For active traders: This was a trader’s market — Private Bank, IT, and Auto gave clear intraday trends, while midcaps and FMCG offered shorting opportunities. Friday’s setup is tricky: GIFT Nifty is flat, global cues are mixed, and volume in broader indices is declining. If 23,000 holds at the open, look for continuation toward 23,200; if it fails, 22,800 is your first support. Avoid overleveraging in overbought names like BHEL or Bajaj Auto — take partial profits and let the rest run with trailing stops.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher