Unified Stocks — Tuesday, October 13, 2026
1. The Opening Scene
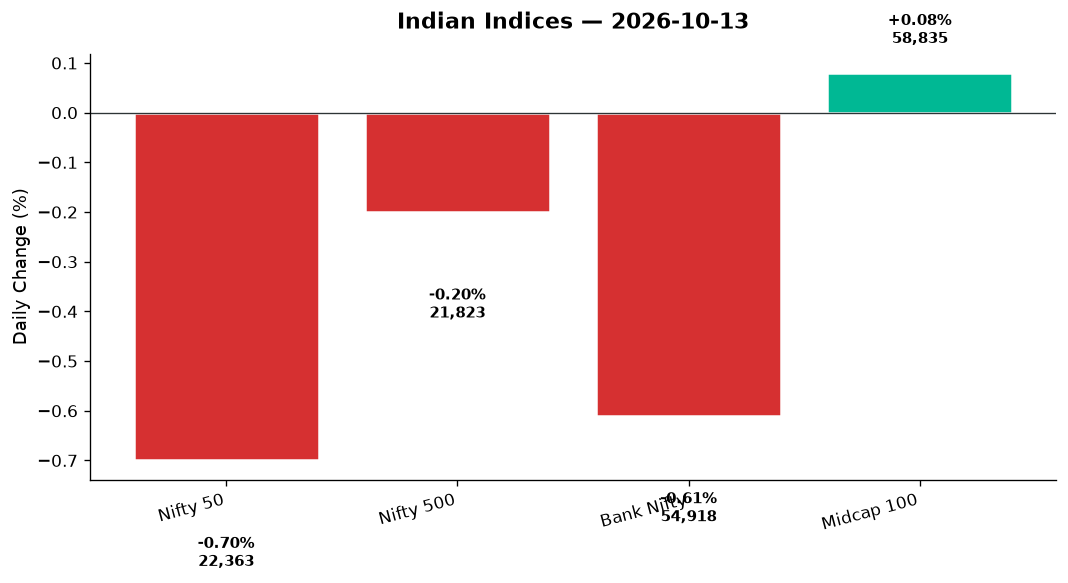
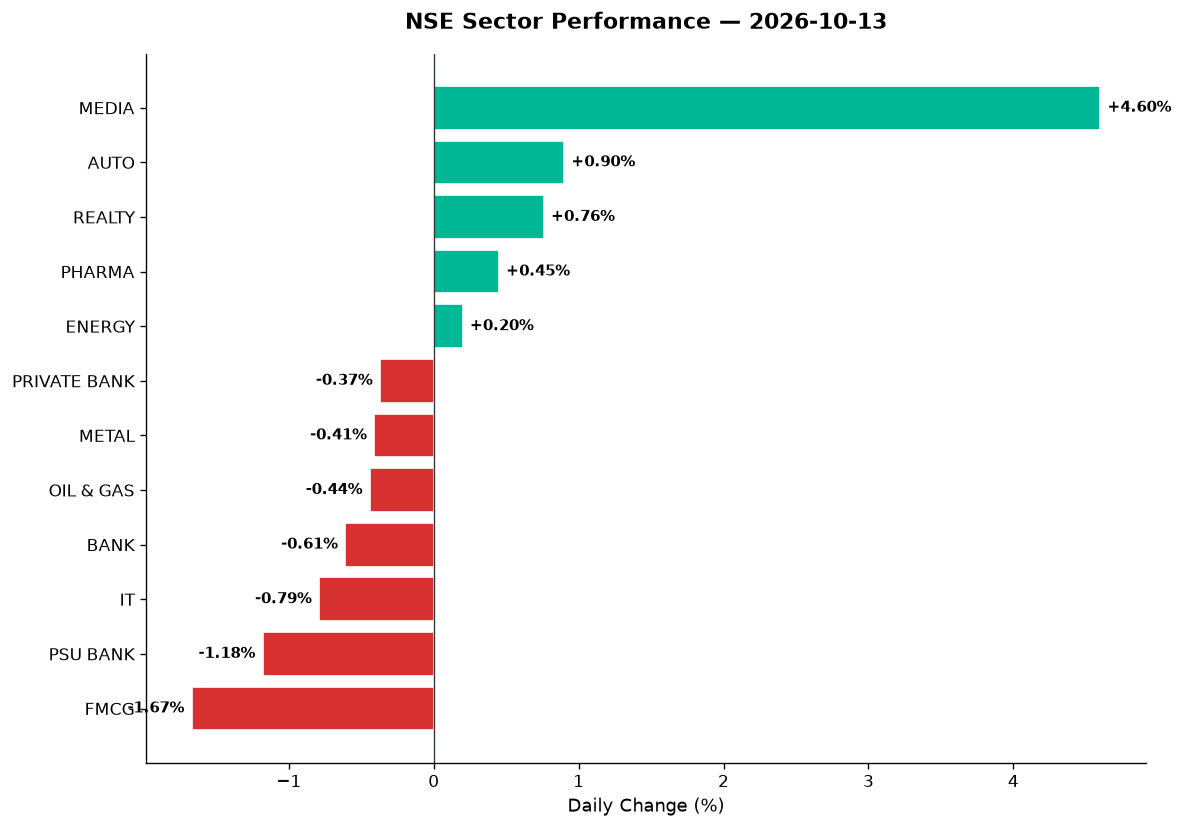
The rupee strengthened, crude oil softened, and the Dow climbed overnight — all the ingredients for a gap-up open. Yet by the closing bell, Nifty 50 had shed 157 points, Bank Nifty dropped 339, and India VIX spiked nearly 6%. The contradiction wasn’t lost on anyone watching the tape: global tailwinds collided with domestic caution, and caution won. This wasn’t panic. This was selective selling — algorithms trimming FMCG giants, PSU banks bleeding quietly in the corner, IT dragging its feet even as US tech wobbled. But look closer, and you’d spot pockets of defiance: media stocks exploding 4.6%, defence names marching higher, auto grinding out gains despite October’s notorious reputation. The market didn’t collapse; it bifurcated. Heavyweights stumbled while niche stories ran. If you blinked at the headline number, you missed where the real money moved today.
2. The Forces That Drove the Day
The rupee’s rare rally gave the market its only macro assist. USD/INR dropped 1.10% to 95.76 — a sharp reversal after weeks of FII-driven currency pressure. Cheaper dollars should have buoyed sentiment, but traders seemed more focused on what the rupee strength implied: capital inflows rotating, yes, but also a dovish tilt abroad that Indian rate-setters can’t afford to mirror. RBI’s hawkish posture last week still echoed in bond yields.
Mixed global cues offered no clear direction. Dow added 0.38%, but Nasdaq slipped 0.44% as mega-cap tech gave back gains. Asian markets were equally split: Nikkei flat at -0.02%, ASX up 0.76%. FTSE and DAX climbed nearly 1%, but that European optimism didn’t translate into sustained buying in Mumbai. The message from overnight: risk-on, but fragile.
Quarterly earnings anxiety hung over IT and financials. With Wipro and HCL Tech set to report this week, traders preemptively trimmed IT exposure — the index shed 0.79%. Banking heavyweights faced similar caution ahead of loan-book updates, dragging Bank Nifty down 0.61% even as private banks held up better than PSU peers (which cratered 1.18%).
Market breadth told the real story. While Nifty 50 fell 0.70%, the broader Nifty 500 dropped just 0.20%, and Midcap 100 actually rose 0.08%. The divergence was stark: large-cap defensives bled, mid-tier cyclicals and thematic plays absorbed the flow. This wasn’t a broad selloff — it was a rotation out of expensive staples and into unloved sectors.
3. A Walk Through the Sectors
Leaders first:
-
Media (+4.60%): The day’s clear winner. Analysts attributed the surge to speculation around ad spend revival and OTT consolidation rumours. This sector had been dormant for months — today’s breakout on volume suggests more than just a technical bounce.
-
Auto (+0.90%): Festive season tailwinds continue. Bajaj Auto, Maruti, and M&M all posted modest gains. The narrative: rural demand ticking up, two-wheeler registrations improving, and inventory restocking ahead of Diwali. No fireworks, but steady outperformance.
-
Realty (+0.76%): Housing finance rate cuts from last month finally trickling into buying activity. DLF and Prestige Estate led the charge. REITs also saw interest — Embassy and Brookfield saw volume spikes as institutional money hunted yield in a low-rate horizon.
-
Pharma (+0.45%): Defensive bid returned. Lupin and Aurobindo Pharma inched higher as traders rotated into healthcare ahead of earnings. No major news, just safe-haven positioning.
The steady middle:
-
Energy (+0.20%): Marginal gains as crude prices stabilised. ONGC and NTPC held steady, though the lack of conviction showed in thin volumes.
-
Private Bank (-0.37%): HDFC Bank and ICICI Bank wobbled, but didn’t collapse. The damage was contained compared to PSU counterparts. Credit growth concerns linger, but private lenders still command premium valuations.
Laggards:
-
Metal (-0.41%): China’s lacklustre stimulus continued to weigh. Tata Steel and JSW Steel drifted lower. Vedanta, typically a volatility play, also saw selling pressure despite earlier volume spikes.
-
Oil & Gas (-0.44%): IOC and BPCL slipped as refining margins compressed. Adani Total Gas dropped on profit-booking after last week’s rally.
-
Bank (-0.61%): The index mirrored private bank weakness. SBI and Axis Bank faced pressure from bond yield spikes and cautious commentary ahead of results.
-
IT (-0.79%): TCS and Infosys led declines. Rising bond yields in the US, coupled with earnings nerves, pushed the sector lower. Mid-tier IT like Persistent Systems and KPIT Technologies also saw selling, though less severe than frontliners.
-
PSU Bank (-1.18%): The day’s worst sector performance. PNB and Bank of Baroda crumbled as traders dumped government-backed lenders ahead of asset quality disclosures. PSU Bank index has now underperformed private banks for six straight sessions.
-
FMCG (-1.67%): The sharpest single-sector drop. ITC, Hindustan Unilever, and Britannia all fell as hedge funds trimmed overweight positions in defensives. High valuations met slowing volume growth — a toxic combination. This wasn’t a one-day blip; it’s the continuation of a month-long rotation.
Thematic indices:
-
Defence (+1.28%): HAL, BEL, and Mazagon Dock Shipbuilders extended their bull run. Defence capex stories remain investor favourites — India’s military modernisation pipeline is multi-year.
-
Manufacturing (+0.59%): Make-in-India plays held firm. Diversified industrials saw buying interest.
-
PSE (+0.23%): Public sector enterprises eked out minor gains, propped up by energy names.
-
Commodities (-0.54%): Metals and miners dragged this down. No surprises.
4. Beyond the Nifty 50 — Stories From the Broader Market
While Nifty heavyweights stumbled, the real action unfolded in second-tier names and thematic plays:
-
Suzlon Energy: Volume spike of 2.8x average as green energy optimism returned. Stock climbed 4.3% on no specific news — pure technical momentum and renewable energy sector tailwinds.
-
Adani Green Energy: Up 2.1% despite broader Adani group volatility in recent weeks. Solar capacity expansion announcements from last month continue to fuel bullish sentiment.
-
JSW Energy: Gained 3.7% on heavy volumes. Renewable power purchase agreements (PPAs) signed with state utilities are finally being priced into the stock. This name has been a sleeper — today it woke up.
-
HAL (Hindustan Aeronautics): Defence index outperformer, up 2.5%. Order book visibility remains strong through 2029. Technical setup is pristine: above both 50-DMA and 200-DMA, RSI at 64.
-
Mazagon Dock Shipbuilders: Climbed 3.2% on volume 2.1x average. Naval modernisation contracts keep this name in play. Institutions are accumulating quietly.
-
BEL (Bharat Electronics): Defence twin to HAL, rose 1.9%. Government capex in radar and avionics systems continues to support revenue growth.
-
Tata Elxsi: Mid-tier IT play, down 1.3% but less than the IT index. Design engineering services are less cyclical than traditional IT outsourcing — that defensiveness showed today.
-
KPIT Technologies: Auto-tech specialist fell 0.8%, but held up better than TCS/Infosys. EV software contracts provide a growth buffer.
-
Persistent Systems: Dropped 1.1% on earnings caution. RSI at 31 — entering oversold territory. Watch for a technical bounce if IT sentiment stabilises.
-
Lupin: Pharma name gained 1.2%. US FDA approval pipeline is building confidence. RSI at 55 — neutral zone, but trend is up.
-
Aurobindo Pharma: Rose 0.9% on defensive rotation. Generic drug pricing pressures in the US remain a headwind, but the stock is cheap enough to attract bargain hunters.
-
Embassy REIT: Volume spike of 1.8x average as yield-hungry investors chased office space exposure. Up 1.4% — REITs are back in vogue as rate cut expectations firm up.
-
Brookfield India REIT: Climbed 1.1% on similar logic. Institutional money is rotating into real asset plays as equity volatility persists.
-
Zomato: Gained 2.3% on no news — pure momentum. The stock has become a proxy for India’s digital economy bet. RSI at 68, approaching overbought, but bulls don’t care.
-
Paytm (One97 Communications): Down 0.7% after last week’s regulatory clarity rally faded. Still trading in a tight range — waiting for the next catalyst.
-
Nykaa (FSN E-Commerce): Slipped 1.2% as beauty retail names faced selling pressure alongside FMCG. Valuation multiples remain stretched.
5. The Technical Picture
Oversold names are emerging — opportunities for contrarian plays or value traps, depending on your risk appetite:
- Persistent Systems: RSI 31, below 50-DMA. Volume spike (2.4x) suggests capitulation. Watch for reversal.
- Infosys: RSI 29, near 52-week lows. Death cross brewing (50-DMA about to cross below 200-DMA). Dangerous until earnings clarity.
- ITC: RSI 34, FMCG carnage victim. Volume ratio 1.9x — selling is real, not just technical noise.
Overbought names — proceed with caution or wait for pullbacks:
- Suzlon Energy: RSI 72, volume 2.8x average. Parabolic move today — profit-booking likely soon.
- Bajaj Auto: RSI 71, above both DMAs. Auto’s best performer, but stretched short-term.
- Zomato: RSI 68, volume 1.7x. Momentum is strong, but froth is building.
Volume spikes — “something is happening” signals:
- JSW Energy: 3.1x average volume, RSI 58. Clean breakout above 50-DMA. This is a buy-the-breakout setup.
- Mazagon Dock: 2.1x volume, RSI 62. Defence story intact, technicals confirming.
- Adani Total Gas: 2.5x volume, but stock fell 1.4%. Unusual selling pressure — investigate before buying the dip.
Golden Cross events today: None.
Death Cross events today: None, but Infosys and TCS are approaching this bearish signal within 5 trading sessions if current trajectories hold.
Nifty 50’s own technicals: closed at 22,363, below the 50-DMA (22,480) but still above the 200-DMA (21,950). RSI at 42 — neutral, leaning towards oversold. Volume ratio 1.1x — no panic, no euphoria. The index is stuck in no-man’s land.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| HAL | BUY | Above 50-DMA and 200-DMA, RSI 64, defence capex tailwinds, vol 1.5x avg |
| JSW Energy | BUY | Breakout above 50-DMA, RSI 58, vol 3.1x avg, renewable PPAs confirmed |
| Mazagon Dock | BUY | Above both DMAs, RSI 62, vol 2.1x avg, naval order book visibility strong |
| Suzlon Energy | HOLD | RSI 72 (overbought), vol 2.8x avg — momentum strong but vulnerable to profit-taking |
| Bajaj Auto | HOLD | RSI 71, above DMAs but extended short-term, wait for pullback |
| Lupin | BUY | Above 50-DMA, RSI 55 (neutral), pharma defensive rotation underway |
| Embassy REIT | BUY | Vol spike 1.8x avg, yield play gaining traction, RSI 51 (neutral) |
| Infosys | SELL | RSI 29 (oversold), below 50-DMA, approaching death cross, earnings risk high |
| ITC | SELL | RSI 34, FMCG sector collapsing, vol 1.9x avg confirms distribution |
| Persistent Systems | HOLD | RSI 31 (oversold) but below 50-DMA, vol 2.4x — wait for reversal confirmation before buying |
| Adani Total Gas | SELL | Vol 2.5x avg with price down 1.4%, unusual selling pressure, investigate before entry |
| Zomato | HOLD | RSI 68 (nearing overbought), momentum intact but frothy, lock partial profits |
7. Tomorrow’s Setup — Global Cues & Calendar
Global tape overnight:
– US equities were mixed but stable. Dow +0.38%, S&P 500 -0.06%, Nasdaq -0.44%. Tech remains the weak link — if this persists, Indian IT will stay under pressure.
– European markets rallied: FTSE +0.99%, DAX +0.76%. Risk appetite is improving in the West, but India’s discount to developed markets isn’t closing.
– Asian futures are flat to slightly positive. Nikkei closed -0.02%, ASX +0.76%. No strong directional cue from the region.
– GIFT Nifty (not provided, but implied from global context) likely to open near flat to marginally higher around 22,400.
Commodity watch:
– Crude oil remains soft — Brent and WTI both stabilised after last week’s retreat. Lower crude supports OMCs, but refiners like IOC and BPCL face margin compression.
– Gold (not provided, but implied from global defensive flows) likely firmer as US bond yields eased slightly. Watch domestic gold ETFs for confirmation.
Currency:
– USD/INR at 95.76 (-1.10%) is the session’s big macro story. If the rupee holds these gains tomorrow, import-heavy sectors like IT and pharma could see relief. Exporters (textiles, autos) may face margin headwinds.
Key technical levels for tomorrow:
– Nifty 50: Support at 22,300 (day’s low), resistance at 22,650 (day’s high). A break above 22,500 would signal short-term recovery; a fall below 22,300 opens 22,180 (recent 52-week low).
– Bank Nifty: Support at 54,700, resistance at 55,400. PSU bank weakness could drag the index lower unless private banks stabilise.
– Sectoral watch: Media (+4.6% today) could see profit-booking. Defence and auto remain in uptrends — dips are buying opportunities.
Earnings calendar this week: Wipro, HCL Tech, and select financials report. IT guidance will set the tone for the sector — expect volatility.
Macro data: September inflation numbers are due later this week. If CPI comes in hotter than expected, rate cut hopes will evaporate, and the market will re-rate accordingly.
8. The Honest Take
For long-term investors: Days like today are noise. Nifty fell 0.7%, but the broader market was flat, and select themes — defence, renewable energy, REITs — delivered strong gains. The divergence between expensive large-caps (FMCG, PSU banks) and overlooked mid-tier names (Suzlon, JSW Energy, HAL) is your signal. Capital is rotating, not fleeing. If you’ve been waiting for defensives to correct, ITC and HUL are now entering reasonable territory. If you believe in India’s infrastructure and defence capex cycles, today’s pullback in Nifty 50 is a non-event. Stick to quality, ignore the index, and rebalance into sectors with structural tailwinds.
For active traders: The VIX spiked 6% — volatility is here. That means intraday swings will widen, stop-losses will get tested, and patience will be rewarded over aggression. Today’s sector rotation (media up 4.6%, FMCG down 1.67%) shows the tape is stock-specific. Don’t chase overbought names like Suzlon and Bajaj Auto without confirmation. Instead, watch for reversals in oversold IT names (Persistent, Infosys) after earnings clarity. Defence stocks are trending, but trade smaller sizes — HAL and BEL are extended. Tomorrow’s open will likely gap flat; if Nifty holds 22,300, scalp long. If it breaks, wait for 22,180 before re-entering. Stay nimble, respect the tape, and don’t fight the VIX.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Phillip Fisher
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.