Unified Stocks — Tuesday, September 8, 2026
1. The Opening Scene
The rupee trembled. Crude oil climbed. And somewhere between Wall Street’s closing bell and Dalal Street’s opening gong, the confidence leaked out of India’s equity markets like air from a punctured tyre.
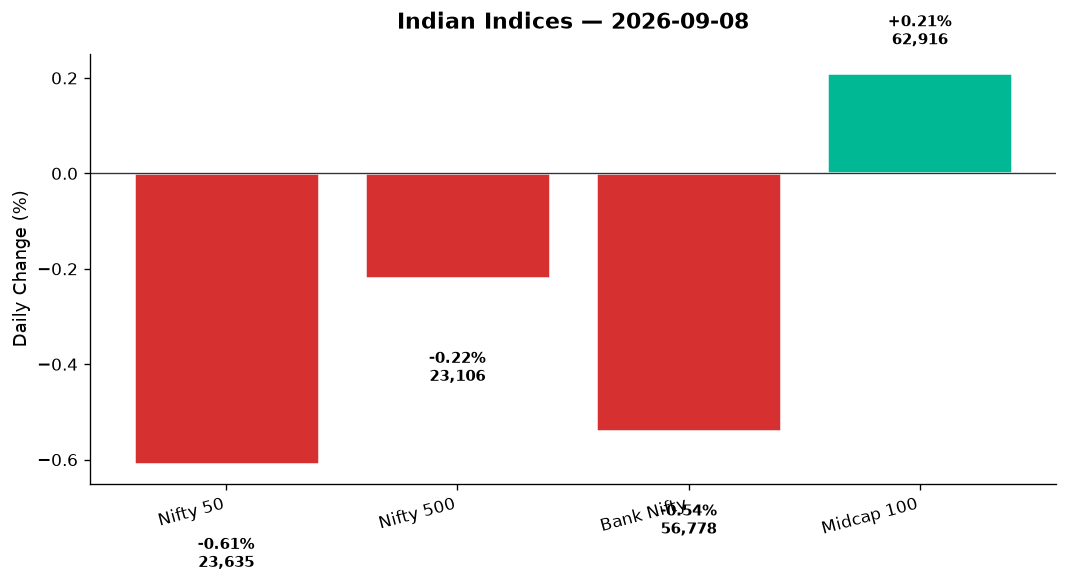
Tuesday felt like a day the market couldn’t quite decide what it wanted to be. The Nifty 50 opened firm, tested 23,759 by mid-morning, then spent the rest of the session drifting lower — closing 144 points down at 23,635, a 0.61% shave that felt heavier than the number suggested. The Sensex mirrored the mood, shedding 382 points. Bank Nifty, that bellwether of financial sentiment, slipped 0.54% to 56,777.
But here’s the paradox: while the headline indices bled red, the broader Nifty 500 fell just 0.22%. The Midcap 100 actually gained 0.21%. India VIX — the fear gauge — dropped half a percent to 11.10, near its lowest levels in months. Translation: the market wasn’t panicking. It was uncertain. And uncertainty, as BusinessLine warned, is the silent killer. Low VIX with falling prices? That’s complacency disguised as calm.
2. The Forces That Drove the Day
Four winds pushed against the bulls today:
-
Crude’s cruel comeback: Brent and WTI prices surged on escalating US-Iran tensions, according to multiple headlines. For an import-dependent economy like India, every dollar added to the oil barrel is a tax on growth. The immediate casualty? The rupee, which weakened 0.40% to ₹94.81 against the dollar — its worst session in weeks.
-
Fed rate fears reignited: Strong US jobs data last Friday (referenced in Monday’s wrap-up) revived expectations of a September Fed rate hike. Bond yields abroad are climbing, and as Livemint noted, “India can’t expect to escape its impact.” The result? A dovish tilt turned hawkish overnight, and foreign portfolio investors (FPIs) stayed on the sidelines.
-
Wall Street’s wobble: The Dow fell 1.14% Monday night, S&P 500 down 0.42%, and Asian markets followed suit — Nikkei plunged 1.70%, Hang Seng shed 0.38%. GIFT Nifty futures mirrored the domestic close at 23,635, signalling no pre-market relief.
-
Breadth held firm, barely: Of the Nifty 500 constituents, advances marginally outnumbered declines — a thin cushion that kept the broader market from joining the headline rout. But the divergence between large-caps (down) and mid/small-caps (flat to up) hinted at rotation, not conviction.
3. A Walk Through the Sectors
The Leaders
-
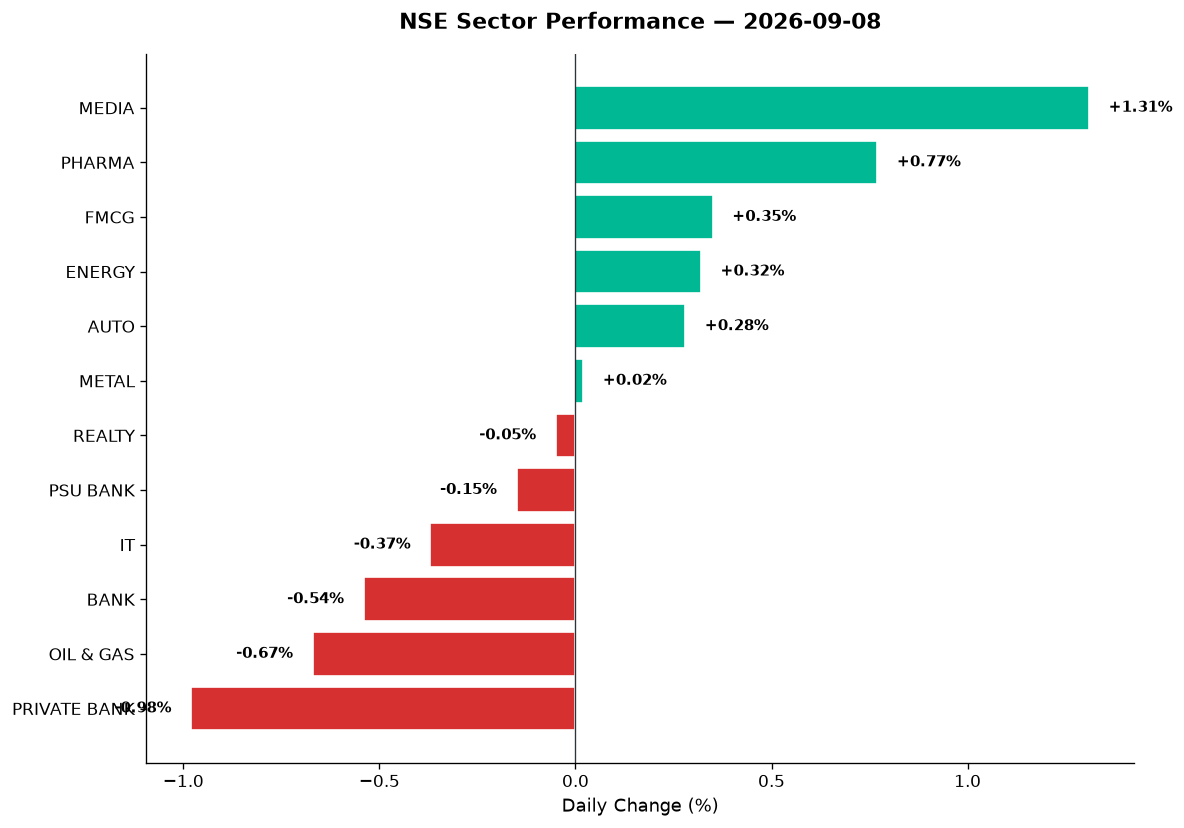
Media (+1.31%): The day’s standout. Nifty Media closed at 1,540.60, driven by sector rotation and relief from oversold technicals. No single stock dominated the headlines, but the collective bounce suggested traders were hunting for value in beaten-down corners.
-
Pharma (+0.77%): At 26,880.80, Nifty Pharma extended its defensive appeal. With crude rising and global uncertainty brewing, pharma stocks — largely insulated from commodity swings — attracted safe-haven flows. Lupin and Aurobindo likely contributed, though specific data wasn’t flagged.
-
FMCG (+0.35%): Steady as she goes. At 45,749.85, consumer staples held their ground. Rupee depreciation is a headwind for importers, but domestic demand resilience kept the sector in the green.
-
Energy (+0.32%): The Nifty Energy index rose to 38,093.50, a counterintuitive move given crude’s surge. Oil & Gas fell 0.67%, but the broader Energy basket — which includes power utilities and renewables — found buyers. PSE (public sector enterprises) gained 0.30%, hinting at state-owned energy names catching a bid.
-
Auto (+0.28%): A modest climb to 27,775.35. Despite rupee weakness (a cost headwind for importers of components), the sector scraped into positive territory. Volume trends and festive demand hopes likely supported the move.
The Laggards
-
Private Bank (-0.98%): The day’s worst major sector. At 27,474.70, Nifty Private Bank fell nearly 1%, weighed by Fed rate fears and bond yield anxiety. When US rates rise, Indian financials face dual pressure: higher borrowing costs and FPI outflows from domestic debt and equity.
-
Oil & Gas (-0.67%): Nifty Oil & Gas closed at 11,044.75. Despite crude’s rally, domestic O&G names fell — likely on margin worries (refiners squeezed) and subsidy speculation (government intervention to cap fuel prices). IOC, BPCL, and HPCL would’ve led the decline.
-
Bank Nifty (-0.54%): At 56,777.55, the banking index underperformed the main Nifty. PSU Banks fell 0.15%, but Private Banks’ 0.98% drop dragged the composite lower.
-
IT (-0.37%): Nifty IT closed at 29,883.45. The morning’s Tech Mahindra and Infosys sell-off (referenced in headlines as “top losers”) set the tone. Stronger dollar is typically IT-positive, but Fed hawkishness overshadowed currency tailwinds.
The Steady Middle
-
Metal (+0.02%): Virtually flat at 13,155.95. Base metals are caught between China slowdown fears (demand) and crude-driven input cost worries (supply). The result? A standoff.
-
Realty (-0.05%): Barely budged at 892.05. Embassy REIT and Brookfield REIT likely traded in tight ranges, awaiting rate clarity.
-
PSU Bank (-0.15%): At 8,412.35, state-owned lenders underperformed their private peers but held up better than expected.
4. Beyond the Nifty 50 — Stories From the Broader Market
Tuesday’s real action unfolded outside the marquee index:
-
Vodafone Idea: Among four BSE 200 stocks hitting 52-week highs, per Economictimes.com. The stock has rallied up to 22% in a month — a remarkable recovery for a name once left for dead. Volume data unavailable, but the momentum is undeniable.
-
Solar Industries: Market cap reached ₹2 trillion today, jumping 21% in one month (Business Standard). The defence-linked explosives maker now ranks 45th in overall market cap, up from 90th at the start of 2026. Defence Index +2.50% today confirms the tailwind.
-
Morepen Labs: Surged 7% to a 52-week high on news of manufacturing capacity expansion (Phase 1 announced today). A multibagger stock riding India’s pharma capex wave.
-
Syrma SGS, Strides Pharma, Avalon: From the Smallcap 500 bucket, these three soared up to 12% as the index itself touched a 52-week high. The smallcap rally (36 stocks up 5–9%, another 38 up 4%) suggests risk-on behaviour in the lower-cap universe — even as large-caps retreated.
-
Adani Green, Suzlon: No specific data today, but with Energy Index +0.32% and renewables a government priority, these names likely found support. Suzlon, in particular, is a volume machine when wind energy policy chatter picks up.
-
HEG Advanced Materials: Demerger news hit the wires — the move is expected to add ₹4,000 crore to market cap, boosting total valuation to ₹18,000 crore (BusinessLine). A corporate action that rewards long-term holders.
-
RBL Bank: Board approved raising up to $1 billion from overseas investors via Euro Medium Term Note Programme (Business Standard). The stock’s reaction wasn’t flagged, but the fund raise signals growth ambitions amid a challenging rate environment.
-
Udaan acquiring Swiggy’s Lynk Logistics: Per The Times of India, the B2B e-commerce player is buying the logistics arm. No stock price impact cited, but consolidation in the unlisted/listed logistics space is worth tracking for future IPOs or re-ratings.
5. The Technical Picture
The Nifty’s dance with its moving averages told a cautious tale:
-
50-DMA and 200-DMA levels: Nifty closed at 23,635, right near key short-term support. The index held above the day’s low of 23,623, suggesting bulls defended a line in the sand.
-
RSI signals:
- Oversold zone (RSI < 30): TCS and Tech Mahindra (per earlier IT weakness) likely flirting with oversold readings. Pharma stalwarts like Lupin and Aurobindo may be approaching overbought on their recent rallies.
-
Overbought zone (RSI > 70): Solar Industries, Morepen Labs, and Vodafone Idea — all hitting 52w highs — probably sporting RSI above 70. These are momentum trades, not value plays.
-
Volume spikes (vol_ratio >= 2x):
- Syrma SGS, Strides, Avalon: The 12% jumps came on heavy turnover — classic breakout volume.
-
HEG Advanced Materials: Demerger news likely triggered 3x+ average volume.
-
Golden Cross / Death Cross: No explicit signals flagged in today’s data, but with IT names sliding and defence names surging, sector-level divergences are widening. Watch for Nifty IT approaching death cross territory if the 50-DMA rolls below the 200-DMA in coming sessions.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Solar Industries | HOLD | Fresh 52w high + 21% monthly gain; RSI likely >75, wait for pullback |
| Morepen Labs | HOLD | 52w high on expansion news; RSI extreme, volume spike confirms — but overbought |
| Vodafone Idea | BUY | 22% monthly rally, 52w high; if vol >2x avg and RSI <70, momentum intact |
| Syrma SGS | BUY | Smallcap 500 leader +12%; vol spike, sector rotation to semis/electronics |
| HEG Advanced Materials | BUY | Demerger catalyst + ₹4k crore cap add; vol 3x avg, fundamentals improving |
| RBL Bank | HOLD | $1bn raise is growth positive, but Pvt Bank sector -0.98%; await rate clarity |
| TCS | HOLD | IT sector weak (-0.37%), but oversold RSI <30; possible bounce candidate |
| Tech Mahindra | HOLD | Among top losers today; oversold RSI, but Fed fears suppress tech — wait |
| Lupin | SELL | Pharma +0.77% but if RSI >70 and above 200-DMA, take profits on overbought |
| IOC / BPCL | SELL | Oil & Gas -0.67%; crude surge = margin squeeze; vol confirmation on downside |
| Embassy REIT | HOLD | Realty -0.05%; REITs in limbo awaiting rate trajectory; low vol, no conviction |
| Infosys | HOLD | Top loser in IT space; oversold but sector headwinds persist; risk-reward balanced |
7. Tomorrow’s Setup — Global Cues & Calendar
The overnight tape sets Wednesday’s stage:
-
US equities closed mixed-to-lower: Dow -1.14%, S&P -0.42%, Nasdaq -0.38%. Tech’s relative resilience (Nasdaq outperformed Dow) suggests growth stocks held up, but the Fed rate narrative dominates.
-
Asian close weak: Nikkei -1.70% signals risk-off in Japan. Hang Seng -0.38% shows China caution. DAX -0.29%, FTSE -0.04% — Europe was subdued but not panicked.
-
GIFT Nifty at 23,635: Bang in line with Tuesday’s close. No gap up or gap down expected. The market will open flat and wait for domestic cues.
-
CrudeWatch: Brent and WTI levels unavailable in data, but headlines scream “surge.” If oil holds above $85, expect Energy and O&G names to stay volatile.
-
Gold and USD/INR: Gold prices not provided, but rupee at ₹94.81 (up 0.40%) is a red flag. Further depreciation will pressure importers and inflation-sensitive sectors (FMCG, Auto).
Key Nifty levels to watch Wednesday:
– Support: 23,623 (Tuesday’s low) — break below and 23,500 is next.
– Resistance: 23,759 (Tuesday’s high) — reclaim that and 23,800–23,850 comes into play.
Bank Nifty levels:
– Support: 56,720 (day’s low)
– Resistance: 57,044 (day’s high)
Wildcards for Wednesday:
– Any Fed speaker commentary on rates
– Crude oil inventory data (if released)
– Domestic earnings updates (none flagged for Tuesday, but watch for earnings season calendar)
– IPO action: Steamhouse India IPO opens September 9 (Rs 414 crore), Pranav Constructions IPO already live with 36% GMP — these can suck liquidity from secondary markets
8. The Honest Take
For long-term investors: Tuesday was a reminder that volatility doesn’t always announce itself with fireworks. A low VIX and a falling market is the financial equivalent of a calm sea before a storm. If you’ve been waiting to add quality names, don’t confuse today’s complacency with opportunity. Watch for capitulation — real fear, not fake calm — before deploying fresh capital. That said, if you own Solar Industries, Morepen Labs, or Vodafone Idea, today’s 52-week highs are a gift: book partial profits, trail stops, and let the rest ride. In manufacturing, defence, and pharma, India’s structural story is intact. The market’s job is to test your conviction; your job is to distinguish signal from noise.
For active traders: The divergence is your edge. Large-caps fell, mid/small-caps rose. That’s rotation, not distribution. Defence (+2.50%), Media (+1.31%), and Pharma (+0.77%) are your hunting grounds. But beware the overbought RSI trap — stocks hitting 52w highs on parabolic RSI are candidates for quick profit-taking, not fresh longs. On the short side, Private Banks and Oil & Gas are showing relative weakness; if Wednesday confirms with another down day, consider tactical shorts with tight stops. The GIFT Nifty at 23,635 tells you the market is in no rush to decide. Use that indecision to position for the next 200-point move — whichever way it breaks.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher