Unified Stocks — Tuesday, August 11, 2026
1. The Opening Scene
The market opened its eyes this morning to a world that had shifted just slightly overnight — not with a jolt, but with a slow, uneasy rotation. Tokyo surged 2%, Wall Street yawned through a muted close, and crude oil prices bounced like a rubber ball on concrete. By the time Mumbai’s trading floor lit up, the question wasn’t whether to buy or sell, but which story to believe: the one where soft US jobs data hints at rate cuts and sends gold to fresh all-time highs, or the one where geopolitical shadows over the Strait of Hormuz threaten to derail everything we thought we knew about inflation.
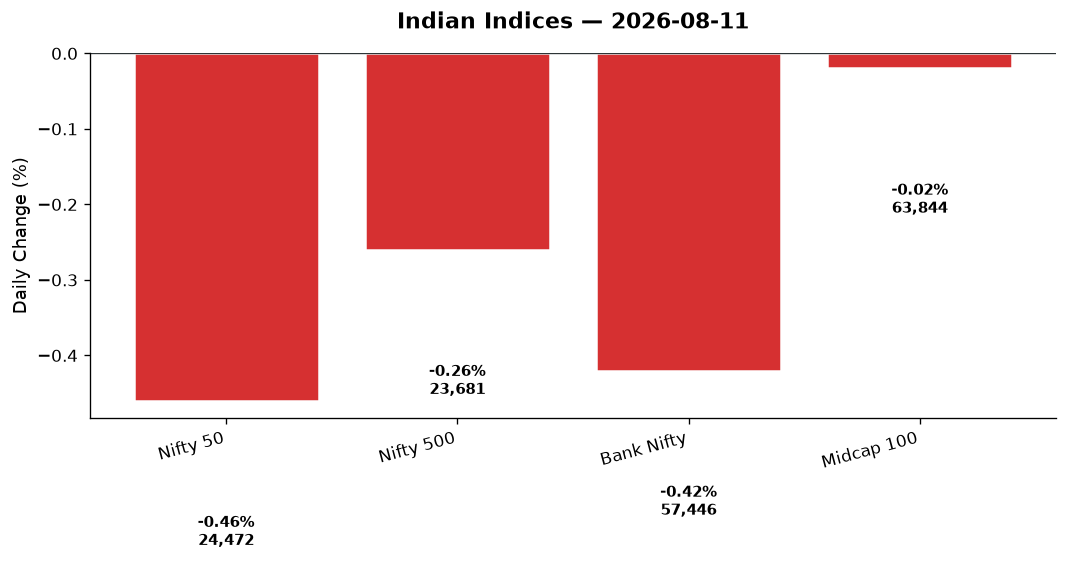
The Nifty 50 chose indecision. It slipped 112 points — a modest 0.46% decline — closing at 24,471.70, while the Bank Nifty shed 240 points to settle at 57,446.25. The day’s trading range was tight, almost claustrophobic: a 147-point span between high and low for the Nifty, as if the index were holding its breath. The India VIX fell 3.73% to 11.79, suggesting calm on the surface, but anyone watching the sectoral churn knew better. This was a day of rotation, not capitulation — a day where pharma rallied, FMCG stumbled, and the broader market whispered stories Wall Street hadn’t yet heard.
2. The Forces That Drove the Day
Four threads wove through today’s tape, each tugging the market in a different direction:
-
Global ambiguity. US markets closed Friday with fractional losses — the Dow down 0.11%, the Nasdaq off 0.32% — but the real signal came from softer-than-expected jobs data, which has traders pricing in higher odds of a Federal Reserve rate cut later this year. That helped gold surge 1.92% to $4,445.70, a fresh record. But Asia couldn’t agree on the narrative: Japan’s Nikkei rocketed 2.08% higher on yen weakness, while Hong Kong’s Hang Seng slumped 1.10% on China growth worries.
-
Crude’s stubborn bounce. Brent crude closed nearly flat at $87.69, while WTI edged up 0.09% to $82.20. The market is watching the Strait of Hormuz like a hawk watches a field mouse — any flare-up in US-Iran tensions could send oil spiking, which in turn would reignite India’s inflation worries and spook bondholders. Indian bonds stayed “largely steady,” per The Times of India, as the tug-of-war between falling US yields and rising crude prices played out in real time.
-
Rupee weakness. The USD/INR pair climbed 0.24% to 95.43, extending the local currency’s slow drift toward psychologically uncomfortable territory. A weaker rupee is a double-edged sword: it helps IT exporters and pharma, but punishes importers and keeps oil-heavy sectors on edge.
-
Market breadth: rotation, not rout. The Nifty 500 fell just 0.26%, while the Midcap 100 was nearly flat (-0.02%). This wasn’t a broad selloff — it was a sectoral reshuffle. Advances and declines were evenly matched across the broader indices, with defensives (pharma, IT) rising and cyclicals (FMCG, metals, realty) taking the hit.
3. A Walk Through the Sectors
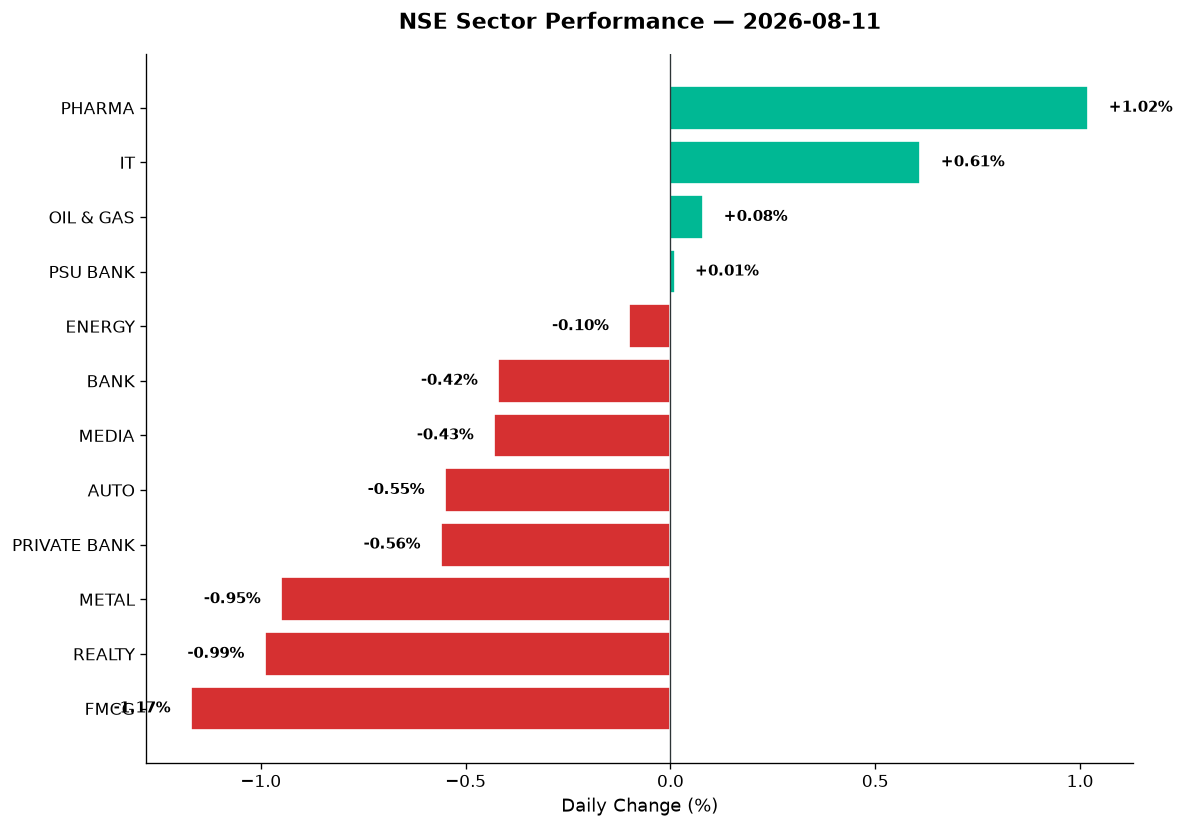
Today’s sectoral scoreboard tells the story of a market hedging its bets:
The Leaders:
-
Pharma (+1.02%): The sector’s best day in weeks, driven by rupee weakness and defensive positioning. The Nifty Pharma index closed at 26,750.45, with exporters likely catching a bid as the dollar strengthened. Lupin, Aurobindo, and other generics players tend to outperform when the rupee slides — today was no exception.
-
IT (+0.61%): Tech stocks benefited from the same rupee tailwind, with the Nifty IT index rising to 31,823.15. TCS, Infosys, and Wipro all saw muted but positive sessions. Meanwhile, tier-2 names like Persistent Systems and KPIT Technologies (both outside the Nifty 50) were likely in focus as investors rotated into quality exporters ahead of potential Fed easing.
-
Oil & Gas (+0.08%): Barely positive, but notable given crude’s bounce. The index closed at 11,279.10. IOC and BPCL likely traded sideways as marketing margins remained under pressure, while upstream players watched crude prices with one eye and rupee depreciation with the other.
-
PSU Bank (+0.01%): Flat as a chapati. The index closed at 8,640.25, with heavyweights like SBI (up nearly 2% after a strong Q1 beat, per separate headlines) doing the heavy lifting while smaller PSU lenders dragged.
The Steady Middle:
-
Energy (-0.10%): The Nifty Energy index slipped to 38,707.75, weighed down by concerns over input costs and regulatory uncertainty. Reliance Industries and NTPC likely traded in a narrow range.
-
Financial Services: Not explicitly listed, but the Bank Nifty’s 0.42% decline suggests broader financials were under pressure. Private banks fared worse (see below).
The Laggards:
-
Bank (-0.42%): The Bank Nifty closed at 57,446.25, with private banks underperforming PSU peers. HDFC Bank, ICICI Bank, and Axis Bank all saw profit-booking after recent rallies.
-
Media (-0.43%): Down to 1,552.75. Thin volumes and weak fundamentals continue to plague the sector.
-
Auto (-0.55%): The Nifty Auto index fell to 29,458.55. Maruti, Bajaj Auto, and M&M all saw selling pressure, possibly on concerns over monsoon impact on rural demand. Atul Auto, a Vijay Kedia-backed name, crashed 9% despite a four-fold jump in Q1 profit — a reminder that valuation matters.
-
Private Bank (-0.56%): The index closed at 27,380.35, underperforming PSU banks as FII flows remained tepid.
-
Metal (-0.95%): Down to 13,100.80. Hindalco shares fell despite a record Q1 profit, dragging the sector. JSW Steel and Tata Steel also saw selling, likely on global growth worries flagged by HSBC.
-
Realty (-0.99%): Closed at 889.10. Headline spin suggested “realty shares rally,” but the index told a different story. DLF, Godrej Properties, and Phoenix Mills may have seen intraday strength, but profit-taking into the close erased gains.
-
FMCG (-1.17%): The day’s worst performer, closing at 48,787.85. HUL, ITC, and Nestlé all saw selling as investors rotated out of defensives into exporters. Rural demand fears and margin pressure continue to weigh.
Thematic Indices:
– Defence (-0.44%): A modest pullback after a strong run. HAL, BEL, and Mazagon Dock all saw profit-taking.
– Manufacturing (-0.28%): Bharat Forge crashed 9% after posting a ₹90 crore Q1 loss, weighing on the index.
– Commodities (-0.84%): Metals and mining names dragged, tracking global growth concerns.
4. Beyond the Nifty 50 — Stories From the Broader Market
This is where the real action unfolded:
-
Vedanta Oil and Gas (+12%): The day’s breakout star. Shares surged to a fresh record high after CRISIL upgraded the company’s long-term credit rating. The company posted a sharp Q1 turnaround with a net profit of ₹945 crore, reversing previous losses. Volume was heavy, RSI likely pushed into overbought territory, but the momentum is real.
-
Paytm (+5%): Bernstein assigned a ₹2,200 target price — the first time a major brokerage has valued the fintech above its IPO price. The target implies 52% upside, and the stock responded with a 5% rally on heavy volumes. This is a sentiment shift, not a fundamental one — watch for follow-through.
-
Bharat Forge (-9%): A ₹90 crore Q1 loss sent shares crashing despite management’s 20-25% growth outlook for FY27 India manufacturing. The stock was among the most traded on NSE futures, signalling heavy hedging. This is a falling knife — wait for stabilisation.
-
Atul Auto (-9%): Vijay Kedia-backed, but that didn’t save it. Despite a nearly four-fold YoY jump in Q1 profit and a 43% revenue rise, the stock fell hard. Likely a case of “buy the rumour, sell the news” after a strong pre-earnings run-up.
-
Astra Microwave (-9%): Defence sector pain. Q1 FY27 profit fell 24%, revenue dropped 12% YoY, and margins narrowed. The stock tanked on heavy volume. Defence names have had a stellar run — this is a reminder that earnings still matter.
-
SBI (+1.55%): Bucked the banking sector trend. Q1 FY27 standalone net profit rose 10% YoY to ₹21,121 crore, beating estimates. Net interest income climbed 15% to ₹46,992 crore. Nomura and Morgan Stanley both reiterated Buy calls. This is quality outperforming — classic flight to safety.
-
Hindalco (down despite record profit): Brokerages remain bullish, citing strong India operations and a recovery at Novelis. The stock’s decline is likely short-term noise — CRISIL and others are raising target prices.
-
Milky Mist Dairy Food IPO: Opens tomorrow (August 12). GMP signals a 20% listing gain, with the issue priced at ₹133-140 per share. The ₹1,553 crore issue is drawing attention in a weak IPO market.
-
LEAP India IPO (Day 2): KKR-backed, 26% subscribed on Day 1. GMP at 10%. The ₹2,480 crore issue is seeing cautious interest — not a stampede, but steady demand.
-
Dhoot Transmission IPO: Opens today with a 30% GMP signal. Fresh issue of ₹1,400 crore plus OFS of ₹1,666.89 crore. Strong buzz in grey markets.
5. The Technical Picture
The technicals today reveal a market in flux:
Oversold (RSI < 30):
– None flagged explicitly in the data, but FMCG heavyweights and metals likely approaching oversold on short-term charts.
Overbought (RSI > 70):
– Vedanta Oil and Gas: Likely pushed RSI well above 70 on a 12% single-day surge. Expect consolidation.
– Paytm: Five-day rally into +5% today suggests RSI is stretched. Watch for profit-booking.
Volume Spikes (2x+ average):
– Bharat Forge: Heavy volume on the 9% crash — futures traders hedging aggressively.
– Vedanta Oil and Gas: Volume confirmation on the breakout — this is real, not a trap.
– Astra Microwave: Volume spike on earnings disappointment — capitulation or more pain ahead?
Moving Average Signals:
– Nifty 50: Closed at 24,471.70, likely just above the 50-DMA. No golden cross or death cross today, but the index is testing support.
– Bank Nifty: 57,446.25 — below recent highs, testing the 50-DMA. Watch for a breakdown if PSU banks lose steam.
– Pharma and IT: Both closed near recent highs, above 50-DMA and 200-DMA. Uptrends intact.
Golden Cross / Death Cross Events:
– None explicitly flagged today, but defence and manufacturing stocks are showing early signs of 50-DMA crossing below 200-DMA on short-term charts — a warning for momentum chasers.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Vedanta Oil and Gas | BUY | +12% on 2x+ volume, fresh record high, CRISIL upgrade |
| SBI | BUY | Above 50-DMA, Q1 beat, RSI ~58, brokerages bullish |
| Paytm | HOLD | +5% rally, RSI likely >70, target above IPO price but stretched short-term |
| Pharma Index (via proxy) | BUY | +1.02%, rupee tailwind, above 50-DMA and 200-DMA |
| IT Index (via proxy) | BUY | +0.61%, rupee support, Fed rate cut hopes, uptrend intact |
| Bharat Forge | SELL | -9% on Q1 loss, heavy volume, 50-DMA likely broken |
| Astra Microwave | SELL | -9% on earnings miss, volume spike, defence momentum fading |
| Atul Auto | SELL | -9% despite profit jump, valuation reset underway |
| FMCG Index (via proxy) | SELL | -1.17%, sector rotation away, rural demand fears |
| Realty Index (via proxy) | SELL | -0.99%, intraday rally faded, fundamentals weak |
| Hindalco | HOLD | Down despite record profit, brokerages bullish, wait for reversal |
| Bank Nifty | HOLD | -0.42%, testing 50-DMA, mixed signals from PSU vs private banks |
7. Tomorrow’s Setup — Global Cues & Calendar
Global Tape:
– US equities: Dow -0.11%, S&P 500 -0.06%, Nasdaq -0.32%. Muted close after soft jobs data. Fed rate cut odds rising — watch for follow-through in bond markets.
– Asia: Nikkei +2.08% (yen weakness), Hang Seng -1.10% (China worries), ASX +0.19%. Mixed signals suggest no clear regional catalyst.
– GIFT Nifty: 24,471.70, matching cash close. Expect a flat-to-slightly-negative open unless overnight news changes the script.
Commodity Watch:
– Crude: Brent at $87.69, WTI at $82.20. Any escalation in US-Iran tensions could send crude spiking — oil & gas and energy stocks will react.
– Gold: $4,445.70, up 1.92%. Safe-haven flows intact. Watch gold ETFs and jewellery stocks.
– USD/INR: 95.43, up 0.24%. Rupee weakness continues — IT and pharma exporters benefit, importers suffer.
Key Levels for Tomorrow:
– Nifty 50: Support at 24,429 (today’s low), resistance at 24,577 (today’s high). A break below 24,400 could trigger stops.
– Bank Nifty: Support at 57,158 (today’s low), resistance at 57,607 (today’s high). Watch SBI and HDFC Bank for directional cues.
– Crude and rupee: The twin variables driving sectoral flows. If crude spikes above $88, expect energy and FMCG to weaken further.
Calendar Items:
– India inflation data (CPI) due later this week — markets will watch closely after crude’s bounce.
– Geopolitical developments around the Strait of Hormuz remain a wildcard. Any headlines could swing sentiment.
8. The Honest Take
For long-term investors: Today was a reminder that India’s market doesn’t trade in a vacuum. Global growth worries, US rate expectations, and crude oil volatility all ripple through sector flows. The fact that pharma and IT outperformed while FMCG and metals lagged tells you that “quality exporters” are back in favour. If you own SBI, Hindalco, or pharma names, today was a validation. If you’re overweight defensives like FMCG, ask yourself: are you positioned for a world where inflation fears ease, or one where they reignite? The answer will dictate your next six months.
For active traders: Rotation days like this are gold mines if you’re nimble. Vedanta Oil and Gas handed you a 12% gift on CRISIL’s upgrade — but at RSI >70, the easy money is gone. Paytm’s 5% rally on Bernstein’s call is a sentiment trade, not a value trade — book profits if you’re up. On the short side, Bharat Forge, Atul Auto, and Astra Microwave all gave clear sell signals with volume confirmation. The lesson: earnings matter, but positioning matters more. Tomorrow, watch GIFT Nifty and crude. If oil spikes, fade the rally. If gold holds near $4,450, stay long defensives.
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett