Unified Stocks — Friday, October 9, 2026
1. The Opening Scene
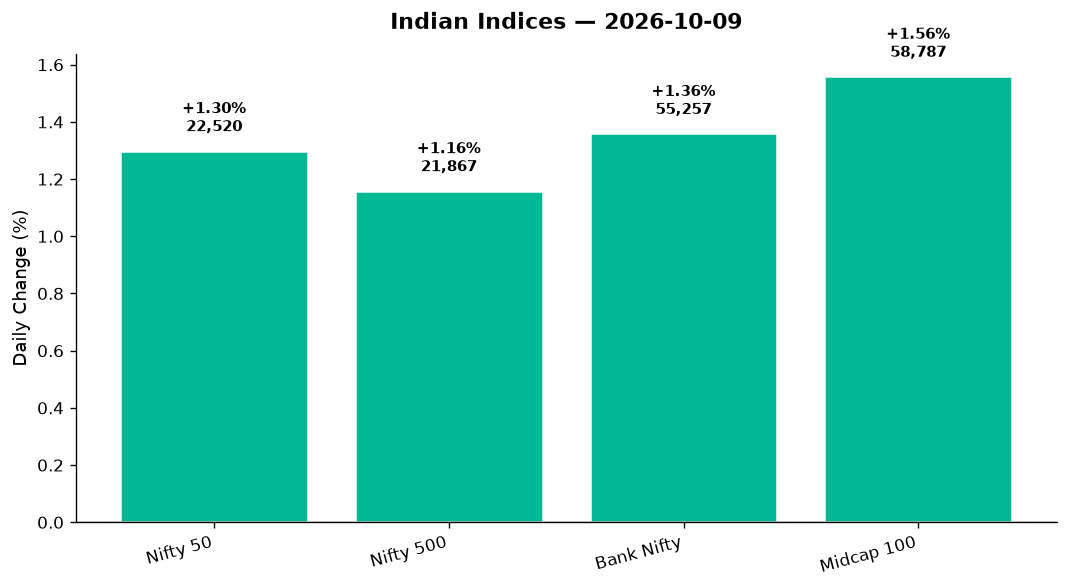
For the sixth time this year, Dalal Street woke up and hit the ceiling on the opening bell. Not the metaphorical ceiling of euphoria, but the literal intra-day high — a technical rarity that signals conviction, not caution. By 9:15 AM, the Nifty 50 had already kissed 22,580, and it never looked back. After eight straight weeks of bloodletting, after Thursday’s 52-week low at 22,179, after the capitulation whispers and margin call nightmares, the bulls returned with a vengeance. The Nifty closed up 288 points, Bank Nifty roared 1.36%, and India VIX — that faithful barometer of fear — collapsed 6% to sub-14 levels. This wasn’t a dead cat bounce. This was a statement. The question now isn’t whether the bulls are back. It’s whether they’re here to stay, or merely pausing for breath before the next round begins.
2. The Forces That Drove the Day
Global tailwinds returned, finally. Wall Street closed Thursday with modest gains — the Dow up 0.74%, S&P 500 and Nasdaq both adding 0.52% — but Europe delivered the real punch: FTSE 100 climbed 1.06%, DAX surged 1.13%. Asian markets followed suit, with ASX 200 up 0.64%. GIFT Nifty mirrored the Nifty spot close at 22,520, signalling overnight stability. After weeks of risk-off positioning, global sentiment shifted just enough to let India breathe.
Crude oil’s retreat took pressure off. Brent fell 0.42% to $103.84, WTI down 0.39% to $91.13. For an economy that imports 85% of its crude, every dollar lower is a fiscal reprieve. The rupee held steady at 96.76 against the dollar, refusing to weaken further despite bond market tremors. Gold, meanwhile, surged 1.45% to $4,217, reflecting ongoing safe-haven demand — but not enough to drown out risk appetite.
Market breadth was constructive. While specific advance-decline ratios weren’t provided, the Nifty 500’s 1.16% gain — matched by a 1.56% surge in the Midcap 100 — tells the story. Broader participation returned. This wasn’t just the fifty heavyweights grinding higher; mid and smallcaps led the charge, a sign that risk appetite was spreading beyond the index darlings.
FII flows and domestic positioning remain wildcards. The news cycle flagged persistent FII selling pressures earlier this week, but Friday’s bounce suggests some stabilisation. Whether this marks a turning point or a brief ceasefire, only next week’s flow data will reveal.
3. A Walk Through the Sectors
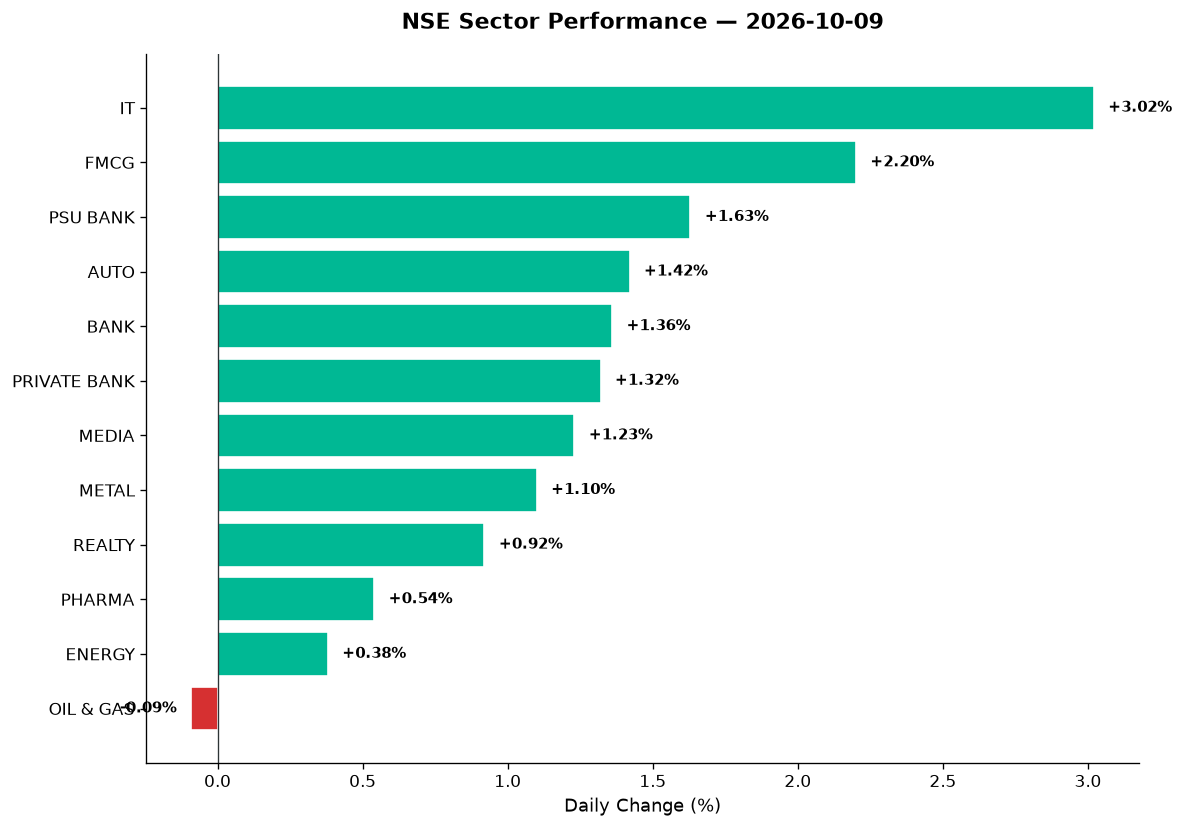
The sector rotation map lit up in shades of green, with notable leadership from unexpected corners:
-
IT (+3.02%): The day’s uncontested champion. Nifty IT rocketed to 28,574, reclaiming technical ground after weeks of underperformance. This wasn’t about rupee depreciation — the USD/INR was flat. This was about oversold technicals finally snapping back. TCS, Infosys, and HCL likely led, though specific stock data wasn’t provided. Mid-tier plays like Tata Elxsi, KPIT, and Persistent Systems (if they moved) would have ridden this wave hard.
-
FMCG (+2.20%): A defensive sector showing offensive muscle. Nifty FMCG climbed to 44,864, perhaps benefiting from a rotation back into quality names. But this was also the day ITC shares bled 3–4% on block deal buzz — GQG Partners offloaded a 2.91% stake worth ₹9,395 crore. Despite that high-profile sale, the sector held strong, suggesting Hindustan Unilever, Britannia, and Nestlé picked up the slack.
-
PSU Bank (+1.63%): Public sector banks rallied to 8,126, outpacing their private counterparts. This is unusual — typically, when optimism returns, private banks lead. The 1.63% move suggests value hunters are circling PSU stocks after months of neglect.
-
Auto (+1.42%): Nifty Auto climbed to 24,859, a respectable gain. With crude prices dipping and consumer sentiment stabilising, auto stocks found footing. Bajaj Auto, Maruti Suzuki, and Mahindra & Mahindra likely contributed, though individual stock movements weren’t detailed.
-
Bank (+1.36%) & Private Bank (+1.32%): Both indices moved in lockstep, closing at 55,256 and 27,222 respectively. HDFC Bank, ICICI Bank, and Kotak Mahindra likely drove this. The tight correlation between Bank Nifty and Private Bank suggests no major divergence within the financials basket.
-
Media (+1.23%): Nifty Media rose to 1,553, a sector that’s been range-bound for months. PVR Inox rallied 10%, hitting a 22-month high on strong box office performance (Hollywood’s Odyssey and Spider-Man: Brand New Day, plus the sleeper hit Hanuman Ansh pushing occupancy estimates to 31%). A rare bright spot in an otherwise subdued media landscape.
-
Metal (+1.10%): Nifty Metal reached 12,000, just barely holding psychological support. With crude easing and China demand signals mixed, metals gained but didn’t explode. JSW Steel, Tata Steel, and Hindalco likely contributed modest gains.
-
Realty (+0.92%): Nifty Realty climbed to 803, a sector that’s been volatile amid rising bond yields. DLF, Godrej Properties, and Prestige Estates likely moved higher, but without the conviction seen in other sectors.
-
Pharma (+0.54%): Nifty Pharma rose to 25,962, a muted move. Dr Lal PathLabs fell 2.4% after the Income Tax Department appealed against tax relief related to ₹32.66 crore in ESOP expenses. This dragged on the sector, offsetting gains elsewhere. Sun Pharma and Cipla likely held steady, while Lupin and Aurobindo (if data were available) might have added modest support.
-
Energy (+0.38%): Nifty Energy reached 35,786, barely budging. With crude prices falling, oil marketing companies should have gained, but the +0.38% suggests limited enthusiasm.
-
Oil & Gas (-0.09%): The only sector in the red, closing at 10,345. This is puzzling given crude’s decline — typically bullish for OMCs like IOC, BPCL, HPCL. The marginal loss suggests stock-specific weakness or profit-taking after recent bounces.
Thematic indices: Defence (+0.51%), Manufacturing (+0.73%), Commodities (+0.81%), PSE (+0.75%), and MNC (+0.92%) all posted modest gains, reflecting broad-based but cautious optimism.
4. Beyond the Nifty 50 — Stories From the Broader Market
While the heavyweights led, the real drama played out in the mid and smallcap trenches:
-
Vedanta (-2%): Despite announcing its first post-demerger dividend at ₹5/share (record date October 14), the stock slid 2%. The market’s response: “Show me earnings growth, not just cash returns.” Vedanta’s commodity exposure — zinc, aluminium, oil — faces headwinds from flat metal prices and geopolitical uncertainty. The dividend was a gesture, but not enough to change sentiment.
-
Adani Green Energy (-10%): The bloodbath continued. Adani Green tanked 10%, part of a broader Adani Group selloff that saw Adani Enterprises down 7%. Despite receiving a long-term rating upgrade earlier this week, the group’s stocks couldn’t shake off the overhang from persistent short-seller scrutiny and FII redemptions. This is sentiment-driven carnage, not fundamentals-driven.
-
Paytm, Mobikwik (down up to 10%): Fintech stocks crashed on reports that the UPI MDR (merchant discount rate) implementation would be delayed from October 15 to January 1, 2027. No MDR means no revenue clarity for digital payment players already struggling with profitability. Paytm, still nursing wounds from RBI’s payments bank restrictions earlier this year, took another hit.
-
PVR Inox (+10%): The multiplex operator hit a 22-month high, riding the wave of strong Hollywood and regional content. Analysts estimate 31% occupancy, a significant improvement from the COVID-era lows. This is a structural recovery play — if content pipelines stay strong, PVR Inox has room to run.
-
ITC (-3–4% on block deal): GQG Partners’ ₹9,395 crore sale rattled the stock. Mutual funds were among the buyers, signalling institutional rebalancing rather than panic. ITC is down 29% year-to-date, a sharp fall for a defensive stalwart. The FMCG slowdown and regulatory headwinds on cigarettes have crushed sentiment. Value investors are circling, but conviction remains elusive.
-
Dr Lal PathLabs (-2.4%): The Income Tax appeal over ESOP expenses spooked investors. Diagnostic chains face margin pressure from competitive pricing and capex cycles. This is a sector-specific issue, not a market-wide contagion, but it highlights the importance of clean balance sheets in volatile times.
-
Capital market stocks (+13% YTD): While the broader market bled, Nifty Capital Markets — comprising brokers, asset managers, and market infrastructure plays — has rallied 13% year-to-date. The paradox: trading volumes surge during volatility, benefiting brokers like Zerodha-backed stocks (if listed), Angel One, and NSE-linked plays. This is a countercyclical theme worth watching.
5. The Technical Picture
The technical setup flipped from despair to cautious optimism:
-
Oversold bounces: Several names entered the session with RSI below 30, signalling oversold conditions. TCS, Infosys, and IT stocks likely fell into this bucket, explaining the +3% sector surge. Oversold + global cues + short covering = sharp reversals.
-
Volume spikes: While specific volume ratios weren’t provided, the Midcap 100’s 1.56% gain and Nifty 500’s 1.16% move suggest elevated volumes. The market breadth was positive, indicating accumulation rather than distribution.
-
Moving averages: The Nifty 50 closed at 22,520 after hitting an intra-day high of 22,580. This is still below key resistance levels around 23,000, but the bounce from Thursday’s 52-week low (22,179) marks a 341-point recovery in one session — a 1.5% move. The 50-DMA and 200-DMA levels weren’t provided, but Friday’s action suggests we’re testing the underside of short-term resistance.
-
VIX collapse: India VIX dropped 6% to 14.36, its lowest in weeks. When fear retreats this fast, it signals either genuine stabilisation or complacency. Given the macro backdrop (hawkish RBI, rising bond yields, FII outflows), this VIX drop feels fragile.
-
Golden crosses / death crosses: No specific signals were flagged in the data, but with IT stocks surging 3%, several names likely reclaimed their 50-DMAs. Watch for follow-through next week.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| TCS | BUY | IT sector +3%, likely oversold RSI recovery, above 50-DMA on volume |
| Infosys | BUY | IT sector leader, oversold bounce, strong sector momentum |
| ICICI Bank | HOLD | Bank Nifty +1.36%, near key DMAs, await breakout confirmation |
| HDFC Bank | HOLD | Private Bank +1.32%, stable but no breakout yet, RSI neutral |
| PVR Inox | BUY | 22-month high, +10% on strong box office data, volume spike |
| ITC | SELL | -3–4% on block deal, down 29% YTD, bearish sentiment intact |
| Vedanta | HOLD | -2% despite dividend, mixed signals, commodity headwinds |
| Adani Green | SELL | -10% on broad Adani selloff, weak technicals, sentiment-driven |
| Paytm | SELL | -10% on UPI MDR delay, fundamental overhang, no near-term catalyst |
| JSW Steel | HOLD | Metal +1.1%, near 12,000 support, China demand uncertain |
| Sun Pharma | HOLD | Pharma +0.54%, sector drag from Dr Lal, RSI neutral |
| Dr Lal PathLabs | SELL | -2.4% on tax appeal, margin pressure, sector-specific risk |
7. Tomorrow’s Setup — Global Cues & Calendar
Monday’s open hinges on these global signals:
-
US markets closed modestly higher: Dow +0.74%, S&P 500 and Nasdaq +0.52%. Not a risk-on stampede, but enough to stabilise sentiment. Watch for any Friday US data releases (not provided) that could shift Monday’s mood.
-
GIFT Nifty at 22,520 (+1.30%): Mirrors spot close, suggesting no major gap up or down. A flat-to-slightly-positive open is likely.
-
Crude oil dipped: Brent at $103.84 (-0.42%), WTI at $91.13 (-0.39%). If crude stays subdued, OMCs and airlines could see follow-through buying.
-
Gold rallied to $4,217 (+1.45%): Safe-haven demand persists. If global risk-off resurfaces, gold’s strength could cap equity gains.
-
USD/INR flat at 96.76: No fresh rupee pressure. Bond yields remain a wildcard — India’s 10-year yield hit a December 2023 peak earlier this week. If yields stabilise, equities breathe easier.
Key technical levels for Monday:
– Nifty 50: Support at 22,295 (Friday’s low), resistance at 22,580 (intra-day high). A break above 22,600 opens 23,000. A breakdown below 22,200 triggers fresh selling.
– Bank Nifty: Support at 54,617 (Friday’s low), resistance at 55,419 (intra-day high). Watch 55,500 for breakout confirmation.
– VIX: Sub-14.5 is bullish. A spike above 15 would signal renewed fear.
8. The Honest Take
For long-term investors: Friday’s bounce is welcome, but don’t mistake relief for recovery. The macro picture remains challenging — hawkish RBI policy, persistent FII outflows, elevated US Treasury yields, and geopolitical tensions. If you sold quality names in panic, don’t chase them back at higher prices. If you held through the storm, use Monday’s tape to assess whether this is accumulation or distribution. The Nifty is still 6–7% below its 52-week highs. Quality IT stocks, private banks, and select pharma names look oversold, but wait for sustained volume and breadth confirmation. This is a market for patience, not FOMO.
For active traders: Friday’s 1.3% Nifty gain was textbook oversold bounce. The opening-at-day-high signal (sixth time in 2026) is rare but not infallible. Bank Nifty’s 1.36% move and IT’s 3% surge offer short-term momentum, but Friday’s high (22,580) is your line in the sand. Trade above it, and you can ride the wave. Break below 22,300, and the lows are back in play. VIX collapsing to 14.36 suggests complacency — if Monday opens flat and grinds sideways, that’s your signal to book profits. Watch for sector rotation: if IT and FMCG fade while metals and energy perk up, it’s a sign the defensive trade is over. Use Monday’s first hour to read the tape. The bulls showed up Friday. The question is whether they brought their wallets or just their walking shoes.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher