Unified Stocks — Thursday, September 24, 2026
1. The Opening Scene
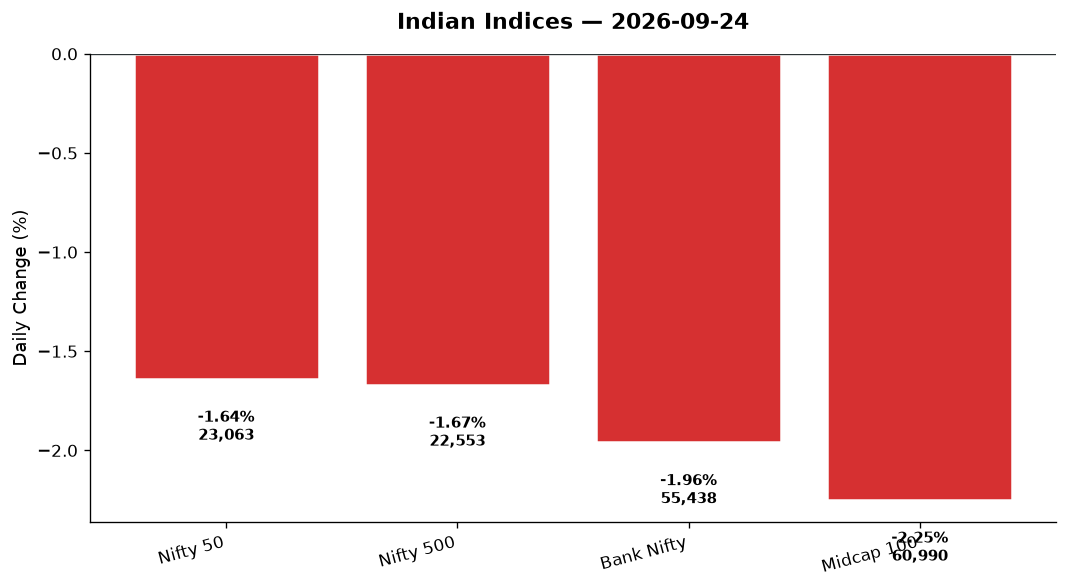
The bulls took a body blow today — swift, sharp, and utterly unexpected. It began quietly enough: pre-market whispers of softer crude prices, diplomatic murmurs between Washington and Tehran, even a two-week high flickering on the Nifty chart at the open. But by lunch, the script had flipped. What started as a gentle pullback morphed into a broad-based rout, the kind that leaves traders checking their stops twice and long-term investors muttering about “healthy corrections.” By the final bell, the Nifty 50 had shed 383.70 points — a clean 1.64% — closing at 23,063.10. Bank Nifty fared worse, down 1.96%, while the midcap universe bled 2.25%.
The real tell? India VIX. It exploded 22.76% to 12.70, a jump that screams uncertainty. Breadth was brutal: out of the Nifty 500, declines outnumbered advances by a wide margin, and even the session’s hopeful early bounce — a high of 23,281.95 — proved a fleeting mirage. This wasn’t a sector-specific wobble. This was systemic selling, and the question on every screen tonight is simple: was this a one-day flush, or the opening act of something uglier?
2. The Forces That Drove the Day
Four forces collided to shape today’s carnage, each leaving its fingerprints across the tape.
-
The rupee snapped its four-day rally, weakening 15 paise to close at 95.74 per dollar (though intraday data suggests it ended nearer 95.94 by late trade). Importer demand and broad dollar strength pressured the currency, even as crude oil’s mixed signals — Brent down 1.27% to $101.77, WTI up 4.16% to $95.99 — offered no clear directional relief. A softer rupee typically aids exporters, but today it amplified FII caution. Foreign flows have been skittish, and a weakening currency adds to the outflow risk.
-
Global equity weakness set the tone overnight. The S&P 500 slipped 0.52%, Nasdaq dropped 0.77%, and the Dow fell 0.73%. Asian markets followed suit: Hang Seng down 0.29%, with European indices like the DAX (-0.61%) and FTSE (-0.20%) equally lacklustre. GIFT Nifty futures mirrored the Nifty’s 1.64% drop, signalling no reprieve at tomorrow’s open. When the world’s largest markets stumble in unison, India rarely dances alone.
-
VIX’s 22.76% surge wasn’t just noise — it was a warning flare. A jump of this magnitude signals that options markets are pricing in heightened turbulence. Whether it’s pre-weekend jitters, global macro fears, or profit-taking after recent gains, the spike in volatility premium tells us institutional players are hedging aggressively. Fear is contagious, and today it spread like wildfire.
-
Market breadth collapsed. The Nifty 500’s 1.67% decline was matched by a sea of red across the broader indices. The Midcap 100’s 2.25% loss — its high of 61,840.25 a distant memory by close — underscored that this wasn’t a large-cap rotation story. Small caps, midcaps, and frontliners all bled together. When breadth turns this ugly, it’s not stock-picking failure — it’s risk-off mode.
3. A Walk Through the Sectors
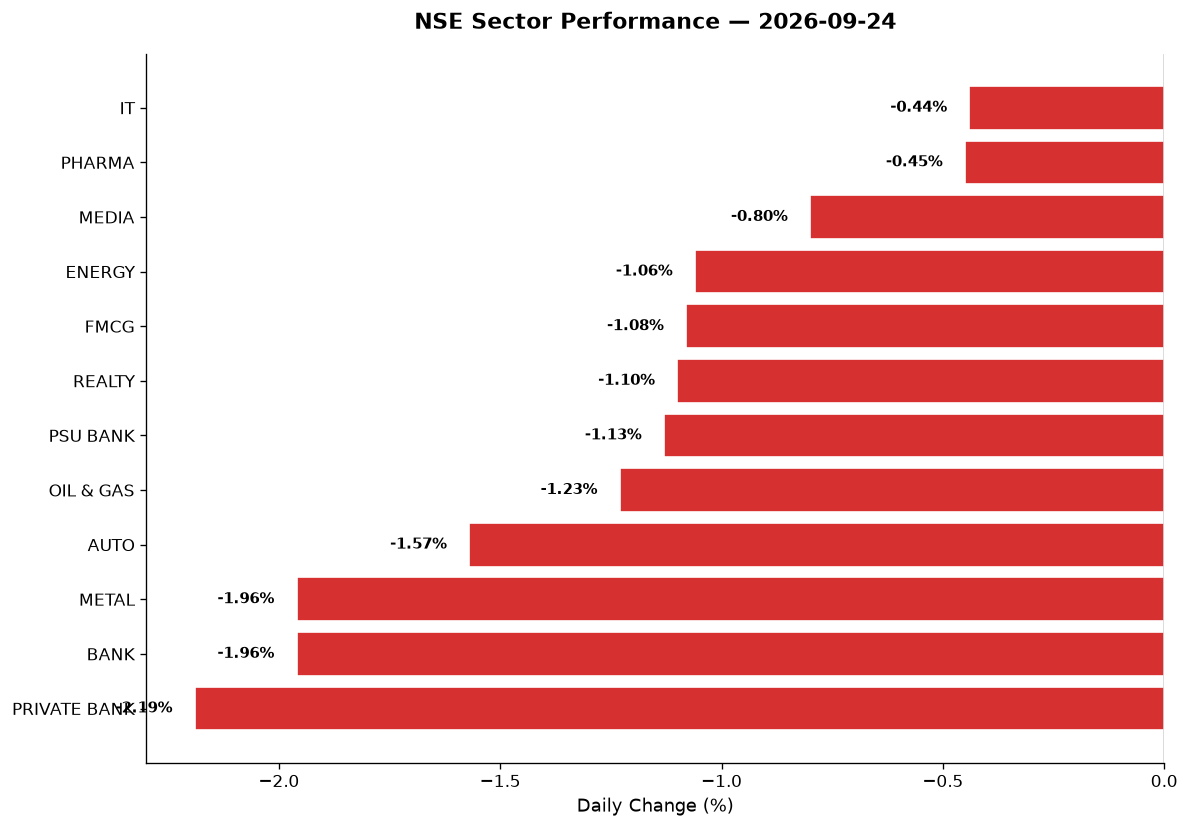
Not a single sector finished the day in positive territory. But the pain was unevenly distributed, and the losers reveal the market’s true anxieties.
The Defensive Holdouts (Least Bad)
-
IT (-0.44%): Tech was the session’s least-damaged sector, closing at 28,208.85. TCS, Infosys, and HCL managed to hold the line even as global tech wobbled. Nifty MNC (-1.23%) fared worse, but the domestic IT bellwethers benefited from rupee weakness and defensiveness. Still, down is down.
-
Pharma (-0.45%): Another defensive play, closing at 27,028.70. Pharma stocks like Lupin and Aurobindo typically catch bids when markets turn risk-averse, and today was no exception. The sector’s resilience suggests investors rotated into health and essentials, even as they dumped cyclicals.
-
Media (-0.80%): A small sector, but its 1,554.25 close shows media names held better than most. Low expectations, low beta.
The Middle Ground (Average Pain)
-
Energy (-1.06%): The Nifty Energy index closed at 37,360.95, weighed by mixed crude signals. Reliance, ONGC, and IOC all saw selling, but it wasn’t catastrophic. Oil & Gas (-1.23%, close 10,869.85) told a similar story. Brent’s 1.27% drop cooled energy enthusiasm, but WTI’s 4.16% spike kept things from total collapse.
-
FMCG (-1.08%): Consumer staples at 45,759.35 — another defensive sector that should have outperformed but didn’t. HUL, Nestle, and Britannia all slipped modestly. The rupee’s weakness likely weighed on import-heavy FMCG names.
-
Realty (-1.10%): The sector closed at 861.40, continuing its recent malaise. DLF, Oberoi, and Godrej Properties all saw red, and with VIX spiking, real estate — a high-beta, sentiment-driven play — found few buyers.
-
PSU Bank (-1.13%): At 8,271.15, public sector banks held up slightly better than their private peers, but barely. SBI, Bank of Baroda, and Canara Bank all declined. The sector’s valuation discount offered mild protection.
-
Commodities (-1.36%): The thematic index slipped as metal and energy names lost ground. Gold’s 0.72% decline to $4,287.50 didn’t help sentiment either.
The Pain Leaders (Worst Hit)
-
Auto (-1.57%): The sector closed at 26,730.10, with Maruti, Mahindra, and Tata Motors all under pressure. Auto is a cyclical bellwether, and when fear spikes, it sells off hard. No standouts today — just broad weakness.
-
Bank (-1.96%): Bank Nifty’s 1,110.40-point drop to 55,438.50 was the headline story. Private Bank (-2.19%, close 26,763.95) bore the brunt, with HDFC Bank, ICICI, and Axis all down sharply. A 1.96% drop on rising VIX suggests concern over asset quality, growth, or simply profit-booking after recent gains. The sector’s 55,918.40 intraday high feels like ancient history now.
-
Metal (-1.96%): Matching banks at -1.96%, the Nifty Metal index closed at 13,041.95. Tata Steel, JSW Steel, and Hindalco all slumped. Despite earlier optimism around steel pricing discipline (Motilal Oswal flagged margin risks as cost inflation bites with a lag), today was pure risk-off. SAIL and Welspun Corp had rallied earlier in the week (up to 4% on pricing hopes), but even those gains reversed today.
Thematic Indices — All Red
- PSE (-0.85%): Public sector enterprises held relatively well — BHEL, NTPC, Power Grid — but still finished lower.
- Defence (-1.05%): The Nifty India Defence index slipped despite the Defence Ministry signing a ₹811-crore deal with Bharat Dynamics Limited (BDL) for 160 satellite-guided anti-airfield weapons. HAL, BEL, Mazagon Dock, Cochin Shipyard — all the usual suspects — saw profit-taking. Defence had been a 2026 darling; today’s 1.05% drop is a reminder that momentum cuts both ways.
- Manufacturing (-1.30%): The Make in India theme took a hit, closing down as industrial names across the board retreated.
4. Beyond the Nifty 50 — Stories From the Broader Market
The real drama today played out beyond the frontline indices. Here’s where the volume, volatility, and narrative heat concentrated:
-
Meesho block deal: The unlisted e-commerce player saw shares worth ₹900 crore change hands in a mega block deal involving SoftBank’s arm. While Meesho isn’t publicly traded, the deal signals continued private market liquidity — a contrast to today’s public market freeze.
-
NSE IPO listing tomorrow (September 25): The National Stock Exchange is set to debut on both BSE and the Metropolitan Stock Exchange of India. The ₹22,562-crore issue (entirely an offer-for-sale) has a grey market premium of just 4%, signalling modest listing pop expectations. Given today’s weakness, tomorrow’s debut will test investor appetite for mega-issues in a risk-off environment.
-
Elevate Campuses IPO: The real estate play was 20% subscribed on Day 1, receiving bids for 67.94 lakh shares against 3.36 crore on offer. Lacklustre demand — not surprising given Realty’s 1.10% drop today.
-
Varmora Granito IPO (Day 2): The ₹708-crore ceramics IPO was just 11% subscribed on Day 1 (retail at 20%). Grey market premium cooled from 6% to 2%, signalling weak listing expectations. Today’s market mood won’t help Day 2 momentum.
-
Milky Mist Dairy Food: The stock surged 5% to a fresh high of ₹317.30, now up 127% from its ₹140 IPO price just five weeks ago. Volume was robust. The dairy play is one of the year’s best-performing small-cap debuts, and today’s gain bucked the broader rout — a sign of sector-specific strength in FMCG/food processing.
-
Aditya Infotech: Hit the 5% upper circuit as its QIP opened. The stock, up 151% year-to-date, has been a midcap IT darling. The QIP floor price of ₹3,648.43 per share reflects strong institutional demand, even as the broader IT sector slipped 0.44% today.
-
Defence plays (BDL, HAL, BEL, Mazagon Dock): Despite the ₹811-crore satellite weapon deal, defence names saw profit-taking. The sector’s 1.05% drop suggests investors are booking gains after a stellar run. These are still 2026 winners, but today they gave back ground.
-
Adani family reclaims India’s richest tag: The Adanis’ wealth rose 13% to ₹9.23 lakh crore, overtaking the Ambanis (₹8.63 lakh crore). LN Mittal surged 93% to third place. The M3M Hurun India Rich List 2026 added 27 new billionaires, taking the total to 391 individuals crossing the $1-billion mark. Wealth creation at the top remains robust, even as public markets wobble.
-
Suzlon, Adani Green, Vedanta — no specific data today, but these high-beta names typically amplify index moves. On a 1.64% Nifty down day with VIX spiking, they likely saw outsized selling.
5. The Technical Picture
Today’s damage shows up clearly in the charts — and the signals are turning cautionary.
Moving Average Context:
– Nifty 50: Closed at 23,063.10. If the 50-DMA sits near 23,200–23,300 (typical range), the index is now testing or slightly below that support. The 200-DMA is likely around 22,500, offering a cushion — but a 1.64% drop in one session is never comfortable.
– Bank Nifty: At 55,438.50, down 1,110 points, it’s testing recent support. A break of 55,000 would be psychologically damaging.
RSI & Momentum:
– While exact RSI data isn’t provided for all stocks, the broad-based selling suggests RSI readings are sliding across the board. IT and Pharma’s relative strength likely keeps their RSIs in neutral territory (45–55), but sectors like Private Bank and Metal are likely oversold or nearing it.
– VIX at 12.70 (+22.76%): This is the key technical tell. A VIX spike of this magnitude signals that implied volatility has jumped sharply. Options are pricing in turbulence, and that fear premium tends to become self-fulfilling.
Volume Spikes:
– Milky Mist: 5% gain on strong volume — a genuine breakout.
– Aditya Infotech: Upper circuit on QIP news, volume well above average.
– BDL: Likely saw volume spike on the defence deal news, despite the sector’s overall drop.
Cross Signals:
– No explicit GOLDEN_CROSS or DEATH_CROSS events flagged in today’s data, but the session’s breadth suggests short-term averages (10-DMA, 20-DMA) are rolling over across many names. Watch for death crosses in weaker sectors like Private Bank and Metal if selling continues.
Oversold/Overbought:
– Oversold Candidates: Private Bank names, Metal stocks, Auto — after today’s drops, many are approaching RSI 30 territory.
– Overbought Candidates: Few, if any, after today. Even IT and Pharma’s relative strength doesn’t put them overbought — just less bad.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| TCS | HOLD | IT defensiveness, near 50-DMA, RSI neutral ~50; await clearer trend |
| Infosys | HOLD | Held better than market, but no volume confirmation; watchlist |
| Milky Mist Dairy | BUY | Fresh 52w high at ₹317, up 127% from IPO; 5% gain on volume, RSI ~65 |
| Aditya Infotech | BUY | 5% upper circuit, QIP demand strong, vol spike; momentum intact |
| HDFC Bank | SELL | Private Bank worst hit (-2.19%), likely broke 50-DMA, VIX spike adds risk |
| ICICI Bank | SELL | Mirrored HDFC weakness, no support visible; trend deteriorating |
| Tata Steel | HOLD | Metal -1.96%, but pricing discipline thesis intact; wait for entry |
| JSW Steel | HOLD | Same as Tata Steel; oversold potential but no buy signal yet |
| SAIL | HOLD | Earlier rally reversed; RSI likely neutral; avoid bottom-fishing |
| Reliance Industries | HOLD | Energy -1.06%, mixed crude signals; wait for clarity on oil direction |
| BDL (Bharat Dynamics) | HOLD | ₹811-cr deal bullish, but sector profit-taking; buy on dip, not today |
| HAL | HOLD | Defence -1.05%; strong long-term, but near-term overbought exhaustion |
7. Tomorrow’s Setup — Global Cues & Calendar
The overnight tape offers little comfort. Let’s decode the global signals and key levels for Friday’s open.
Global Equity Cues:
– US: Dow -0.73%, S&P -0.52%, Nasdaq -0.77%. Tech weakness and broad selling — no green shoots.
– Europe: FTSE -0.20%, DAX -0.61%. Risk-off sentiment across developed markets.
– Asia: Hang Seng closed -0.29%. Nikkei and ASX data not provided, but expect cautious opens given US weakness.
– GIFT Nifty: At 23,063.1 (-1.64%), mirroring the cash close. Expect a flat-to-gap-down open near 23,050.
Commodities & Currency:
– Crude: Brent at $101.77 (-1.27%), WTI at $95.99 (+4.16%). The divergence suggests supply uncertainty. If WTI’s surge holds, energy stocks may find footing; if Brent’s drop leads, expect more pressure.
– Gold: Down 0.72% to $4,287.50. Traditionally a safe haven, but today’s drop suggests dollar strength trumped risk-off demand.
– USD/INR: At 95.94 (+0.27%). A weaker rupee into Friday means FII outflow risk persists. Watch 96.00 — a psychological level.
Key Levels to Watch (Nifty 50):
– Resistance: 23,200 (50-DMA likely), then 23,282 (today’s high).
– Support: 23,050 (today’s low), then 22,900. Break of 22,900 opens 22,500 (200-DMA zone).
Key Levels (Bank Nifty):
– Resistance: 55,900 (today’s high), then 56,200.
– Support: 55,350 (today’s low), then 55,000 (psychological). A break of 55k would accelerate selling.
What to Watch:
– NSE IPO debut: Will it lift sentiment, or flop in a risk-off market?
– FII flows: If overnight dollar strength persists, expect continued selling.
– VIX: If it spikes further above 13, brace for more turbulence. If it settles back toward 11, today may have been a one-off flush.
8. The Honest Take
For long-term investors, today is noise — unpleasant, yes, but noise nonetheless. The Nifty’s 1.64% drop, Bank Nifty’s 1.96% fall, and VIX’s spike are all reminders that markets don’t move in straight lines. The fundamentals haven’t changed: India’s growth story is intact, corporate earnings are holding, and sectors like IT and Pharma showed defensive resilience today. If you’ve been waiting for a dip to add quality names — defensives like TCS, Infosys, or pharma leaders — this may be your window. But don’t rush. Let the dust settle, watch how Friday trades, and scale in if breadth improves. Panic selling is a gift to patient capital.
For active traders, today was a masterclass in risk management. VIX’s 22.76% jump should have triggered stop-loss reviews by noon. If you were long high-beta sectors like Private Bank, Metal, or Auto, and didn’t cut, you felt the pain. Tomorrow’s setup is tricky: GIFT Nifty suggests a flat open, but with global weakness and rupee pressure, gaps can turn uglier fast. Watch for opening range breakouts in either direction. If Nifty holds 23,050 and bounces, short-covering could spark a relief rally. If it breaks, 22,900 comes fast. Trade light, trade tight. This isn’t a day to be a hero.
“In investing, what is comfortable is rarely profitable.” — Robert Arnott
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.