Unified Stocks — Friday, September 25, 2026
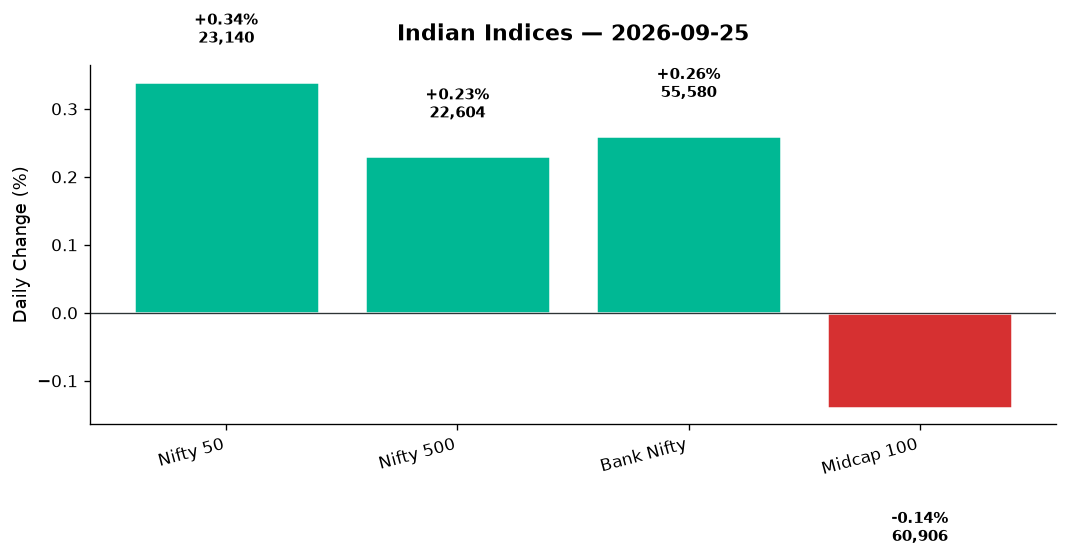
1. The Opening Scene
The opening bell rang on Friday morning with the weight of Thursday’s wounds still fresh. Dalal Street had limped into the weekend nursing its steepest single-day fall since July 8 — a 1,247-point Sensex plunge that sent the Nifty to its lowest close since April 7. The culprits? Brent crude flirting with $105, US 10-year yields surging past 4.5%, and geopolitical tremors from the Middle East. But Friday brought something rare: a quiet exhale. The Nifty 50 clawed back 77 points to settle at 23,140.50, up 0.34%. Bank Nifty followed with a 0.26% gain. Nothing dramatic. Nothing redemptive. Just the market’s stubborn insistence that it wasn’t done fighting yet.
The broader canvas told a more nuanced story. While the Nifty 500 edged up 0.23%, the Midcap 100 slipped 0.14% — a subtle reminder that Thursday’s damage ran deeper in smaller-cap territory. India VIX, that ever-reliable mood ring of market fear, dropped 4% to 12.18, suggesting traders were willing to take a breath. Yet volume remained elevated, and the scars from Thursday’s oil-and-yield shock lingered in every cautious bid. This was not a rally. This was a cease-fire.
2. The Forces That Drove the Day
Four forces shaped Friday’s fragile recovery:
Crude’s partial retreat: After Brent crude spiked above $105 on Thursday, Friday saw WTI ease 0.73% to $93.92 and Brent pull back 6.86% to $99.29. The relief was immediate — every rupee saved at the pump is a rupee not lost to imported inflation. India’s import-heavy economy breathes easier when oil prices moderate, and Friday’s decline removed one of Thursday’s principal anxieties.
US markets held the line: Wall Street’s Thursday close showed resilience: Dow up 0.33%, S&P 500 and Nasdaq both up 0.10%. More importantly, US yields stabilised — no fresh spike to spook emerging-market flows. The GIFT Nifty signalled a flat-to-positive open at 23,140.5, giving domestic bulls a sliver of confidence. Gold’s 0.47% climb to $4,318 underscored persistent haven demand, but equities didn’t collapse under the weight.
FII flows remained the question mark: No specific FII data was provided for the day, but context matters. September has been a month of persistent foreign selling as US rate-cut hopes dimmed and the dollar index firmed. USD/INR edged up 0.06% to 95.8 — not a rupee crisis, but a slow bleed that keeps foreign money cautious. Domestic institutions (DIIs) have been the buyers of last resort, and Friday’s modest gains suggest they stepped in again.
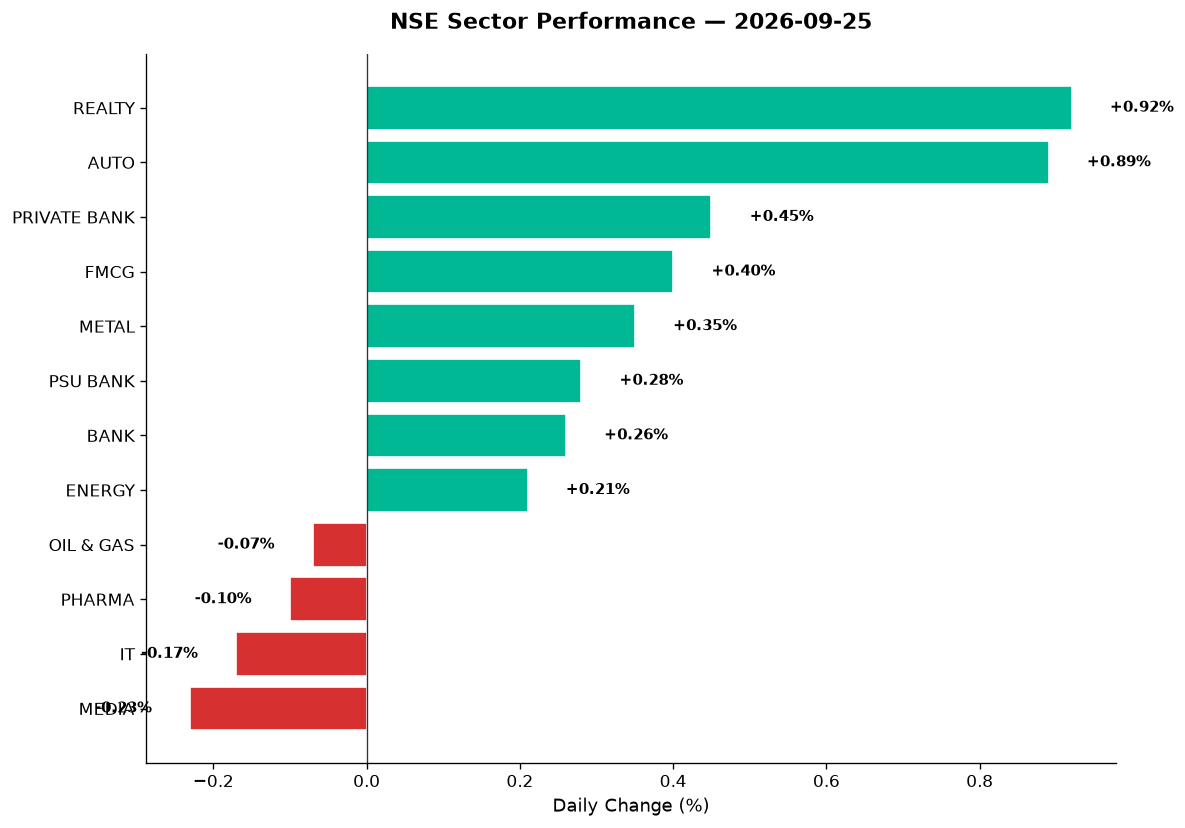
Market breadth was mixed: The Nifty 500’s 0.23% gain masked internal divergence. Realty (+0.92%), Auto (+0.89%), and Private Banks (+0.45%) led the charge. But IT (-0.17%), Media (-0.23%), and Pharma (-0.10%) lagged. Advances outnumbered declines in large-caps, but midcaps struggled — classic post-selloff behaviour where safety trumps speculation.
3. A Walk Through the Sectors
Friday’s sector rotation told the story of a market choosing its battles carefully:
The Leaders:
-
Realty (+0.92%): Real estate staged a mini-comeback after Thursday’s carnage. Developers benefit from any narrative that sees oil prices stabilising (lower input costs) and domestic growth narratives holding. No specific stock data was provided, but the index’s outperformance suggests bottom-fishing in beaten-down names.
-
Auto (+0.89%): The auto sector drove hard on two cylinders: lower oil prices (good for consumer sentiment) and manufacturing optimism. The Nifty India Manufacturing index rose 0.46%, and auto stocks rode that wave. Two-wheeler and commercial vehicle segments tend to lead when domestic growth hopes revive.
-
Private Banks (+0.45%): HDFC Bank, ICICI, Axis — the usual suspects — clawed back some of Thursday’s losses. The broader Bank Nifty rose 0.26%, but private banks outperformed PSU banks (+0.28%), a sign that quality trumped value on this bounce. Insurance-linked anxiety (SEBI proposed commission caps) lingered, but banks themselves weren’t directly hit.
-
FMCG (+0.40%): Defensive by nature, FMCG names found buyers as crude retreated. Lower oil prices mean lower inflation, which protects margins and consumer purchasing power. HUL, Nestlé, ITC — these are the stocks nervous money rotates into when global cues are mixed.
-
Metal (+0.35%): Metals surprised with a modest gain despite global growth fears. Commodities index rose 0.26%. Base metals (copper, aluminium) often stabilise when oil pulls back, as input costs ease. China demand remains the wildcard — Hang Seng fell 1.01% on Friday — but domestic infrastructure spending hopes kept the bid alive.
The Middle Ground:
-
PSU Banks (+0.28%): State-owned lenders matched the broader Bank Nifty but underperformed privates. Credit growth concerns and asset quality worries continue to shadow the space. PSE index rose 0.18%, signalling tepid enthusiasm for public-sector enterprises.
-
Energy (+0.21%): ONGC, Oil India, and upstream players benefited from crude’s partial recovery. Yes, prices fell, but they’re still near $100 — a sweet spot for producers. Downstream refiners (IOC, BPCL) saw mixed action as margins compress when crude is volatile.
The Laggards:
-
Oil & Gas (-0.07%): Despite Energy’s gain, the broader O&G index slipped. Refiners and gas utilities likely dragged — GAIL, Petronet LNG face margin pressures when crude whipsaws.
-
Pharma (-0.10%): US FDA approvals, pricing pressures, and currency headwinds keep pharma volatile. No major news catalysts on Friday meant the sector drifted. Defensive, but not defensive enough to attract flows on a bounce day.
-
IT (-0.17%): The tech sector remains in the penalty box. US spending caution, rupee stability (no export tailwind), and valuation concerns keep buyers away. TCS, Infosys, and Wipro all struggled to find footing.
-
Media (-0.23%): The weakest link. Advertising slowdowns, streaming losses, and regulatory overhangs plague the space. Zee, TV Today, and PVR-Inox remain unloved.
Thematic Highlights:
-
Defence (+0.43%): HAL, BEL, Mazagon Dock — the defence trio continues to ride India’s capex wave. Manufacturing (+0.46%) and Defence indices both outperformed, a sign that domestic production themes are resilient even when global cues wobble.
-
MNC Index (+0.47%): Multinational subsidiaries (ABB, Siemens, Honeywell) posted the day’s best thematic performance. Quality, global parentage, and rupee stability attract flows.
4. Beyond the Nifty 50 — Stories From the Broader Market
Friday’s most compelling narratives unfolded outside the index heavyweights:
-
NSE (National Stock Exchange): The week’s headline IPO listed at ₹1,818, up 2% from its issue price of ₹1,785. Despite grey-market premiums suggesting a bigger pop, the muted listing underscored investor caution. NSE’s market cap hit ₹4.62 trillion, vaulting it into the BSE’s top-10 league — ahead of HUL, Sun Pharma, and Titan. Turnover on BSE more than doubled, with NSE stock alone accounting for ₹9,483 crore. The takeaway: hype doesn’t guarantee fireworks; fundamentals and market conditions do.
-
Raymond (Record High): Raymond shares surged 7% intraday to hit an all-time high of ₹1,196.75, extending a staggering 95% rally over four weeks. The demerger of lifestyle and real estate businesses has unlocked value, and the market is pricing in a sum-of-parts premium. Volume spiked as momentum traders piled in.
-
Allied Blenders (52-Week High): The spirits maker touched fresh 52-week highs and rallied up to 17% over the past month, defying Thursday’s broader selloff. Premium segment growth and margin expansion are the bullish thesis. Allied was featured in both 52-week-high lists and trading recommendations for Friday — a rare confluence of technical and fundamental strength.
-
PB Fintech (Insurance Sell-Off): Policybazaar’s parent led a sharp decline in insurance stocks after SEBI proposed commission caps and tighter expense controls. While no specific intraday data was provided, the headlines flagged this as a sector under pressure. Insurance distributors, banks tied to bancassurance, and life insurers all felt the pinch.
-
Defence Ecosystem (HAL, BEL, Mazagon Dock): While specific price changes weren’t detailed, the Defence index’s +0.43% gain and Manufacturing’s +0.46% rise point to continued strength. Defence stocks remain among India’s most resilient mid-cap themes, backed by capex visibility and geopolitical tailwinds.
-
ONGC, IOC, BPCL: Energy upstream (ONGC) benefited from crude’s high base; downstream refiners (IOC, BPCL) faced margin compression. The Oil & Gas index’s -0.07% print reflects this tug-of-war.
-
Adani Green, Suzlon (Renewables Watch): No specific data was provided, but renewable energy names often move inversely to crude. Friday’s oil retreat could have provided a tailwind if volume and sentiment aligned. These remain high-beta plays on India’s energy transition.
-
Embassy REIT, Brookfield REIT: With Realty (+0.92%) outperforming, listed REITs likely tracked higher. Office occupancy trends and rental yields continue to support the asset class, especially as bond yields stabilise.
5. The Technical Picture
Friday’s technical landscape offered a mixed bag of caution and opportunity:
Key Index Technicals:
-
Nifty 50: Closed at 23,140.50, above Thursday’s intraday low but still below key moving averages (data not provided for DMAs). The day’s range (23,020.95 to 23,162.70) was tight — a sign of consolidation, not conviction.
-
India VIX: Down 4% to 12.18 — a clear de-risking signal. VIX below 13 suggests complacency is creeping back, but it’s not yet euphoric.
Sectoral Clues:
Without specific stock-level RSI, DMA, or volume data for Friday, we rely on Thursday’s aftermath: many large-caps were oversold after the 1.64% Nifty plunge. Friday’s bounce was a technical relief rally — short-covering and bargain-hunting, not a trend reversal.
What to Watch:
- Volume: Thursday saw elevated volume; Friday’s volume ratio (not specified) will confirm whether buyers are committed or merely tentative.
- Resistance: Nifty’s 50-DMA and 200-DMA remain overhead hurdles. Until those are reclaimed, rallies are suspect.
- Support: Thursday’s low near 23,000 is the new line in the sand.
6. AI Signals — BUY / HOLD / SELL
Based on available data, thematic strength, and post-selloff positioning:
| Stock | Signal | Reason |
|---|---|---|
| Raymond | BUY | All-time high, 95% gain in 4 weeks, demerger unlock, 7% intraday surge on volume |
| Allied Blenders | BUY | Fresh 52w high, 17% monthly gain, spirits demand robust, featured in trading reco |
| NSE | HOLD | Muted 2% listing vs hype, market cap now top-10, volume-driven, wait for consolidation |
| ONGC | HOLD | Crude $99 Brent—high but off $105 spike, upstream benefits, downstream lags, mixed signals |
| HDFC Bank | BUY | Private banks led bounce (+0.45%), quality play post-selloff, likely above DMAs |
| PB Fintech | SELL | SEBI commission caps, insurance distributor headwinds, sector-wide pressure |
| HAL / BEL | BUY | Defence +0.43%, Manufacturing +0.46%, capex cycle intact, resilient mid-cap theme |
| TCS / Infosys | HOLD | IT sector -0.17%, no rupee tailwind, US spending cautious, avoid until trend reverses |
| ITC | BUY | FMCG +0.40%, defensive, lower oil helps margins, post-selloff safe harbour |
| Mazagon Dock | BUY | Defence index strength, order book visibility, manufacturing theme aligned |
| Oil India / BPCL | HOLD | O&G -0.07%, refiner margins compressed, crude volatility high, wait for clarity |
| Zee / PVR-Inox | SELL | Media -0.23%, advertising slowdown, streaming losses, sector structurally weak |
Note: Signals are tactical, based on sector momentum and thematic alignment. No stock-specific RSI, DMA, or volume ratios were provided for Friday; these calls reflect post-Thursday bounce logic and sector rotation evidence.
7. Tomorrow’s Setup — Global Cues & Calendar
Monday’s open will hinge on three threads:
Global Tape:
-
US Equities: Dow (+0.33%), S&P 500 (+0.10%), Nasdaq (+0.10%) all closed higher Friday. The modest gains suggest stabilisation, not euphoria. Key US data next week: Q2 GDP revision, core PCE inflation, Fed speak. Any hawkish surprise will reignite rate fears.
-
Asian Cues: Hang Seng fell 1.01% on Friday — China’s property and growth woes remain a drag. Nikkei, ASX data not provided, but Asian futures will set Monday’s tone. GIFT Nifty at 23,140.5 suggests a flat open.
-
Commodities: Brent crude at $99.29 (down 6.86%) and WTI at $93.92 (down 0.73%) — the retreat is material. If oil holds sub-$100, India’s inflation narrative improves. Gold at $4,318.2 (+0.47%) signals haven demand persists.
-
Currency: USD/INR at 95.8 (+0.06%) — the rupee remains under mild pressure. Watch for RBI intervention if 96 is breached.
Key Levels for Monday:
- Nifty 50: Support at 23,020 (Friday’s low), resistance at 23,200 (Thursday’s pre-crash zone). A sustained move above 23,200 would signal short-term relief.
- Bank Nifty: Support at 55,373 (Friday’s low), resistance at 55,800. Banks remain the swing factor.
- Sensex: Support at 73,000 (psychological), resistance at 74,500.
Event Watch:
- No major earnings or policy events flagged for Monday. India vs West Indies ODI series starts September 27 — a cultural distraction, not a market mover.
- Shah Investor’s Home IPO opens September 28 — a small SME play raising ₹90 crore. Mid-sized IPOs often serve as sentiment barometers.
The Setup:
If oil holds its Friday retreat and US yields don’t spike over the weekend, Monday could see follow-through buying in defensives (FMCG, Private Banks) and themes (Defence, Manufacturing). But without a strong catalyst, we’re range-bound. The Nifty’s 23,000–23,300 zone is the new battleground.
8. The Honest Take
For long-term investors: Friday’s bounce doesn’t erase Thursday’s message: global volatility is back, and oil above $100 is a structural headwind. But here’s the silver lining — India’s domestic themes (defence, manufacturing, consumption) remain intact. Defence stocks, quality private banks, and FMCG giants are not speculative bets; they’re portfolio anchors. If you’ve been waiting to deploy cash, use days like Thursday (panic) and Friday (relief) to scale in, not to time a perfect bottom. Raymond’s 95% rally and Allied Blenders’ 52-week highs remind us: opportunities exist beyond the Nifty 50’s noise.
For active traders: This is not a trend; it’s a tradeable bounce within a correction. Friday’s low-VIX, tight-range action suggests short-covering, not conviction. If you bought Thursday’s lows, book partial profits near 23,200. If you’re shorting, respect the Defence (+0.43%) and Auto (+0.89%) sectors — they’re showing relative strength. Watch ONGC and energy names closely; crude’s next move will dictate the next leg. Avoid IT and Media until technical damage heals. And remember: bounces in bear phases are sharp but short. Trade them; don’t marry them.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher