Unified Stocks — Tuesday, November 03, 2026
1. The Opening Scene
The market doesn’t just wake up some mornings. It explodes.
Today was one of those days when the usual rhythms — the cautious pre-open drift, the slow climb through the first hour, the mid-session sag — were obliterated by a single catalyst. Reliance Industries, India’s largest company by market capitalisation, surged 11.6% after posting a record quarterly profit. That alone added ₹1.83 trillion to its market value. Imagine that: nearly two lakh crore rupees conjured into existence before lunch. And where Reliance leads, the index must follow.
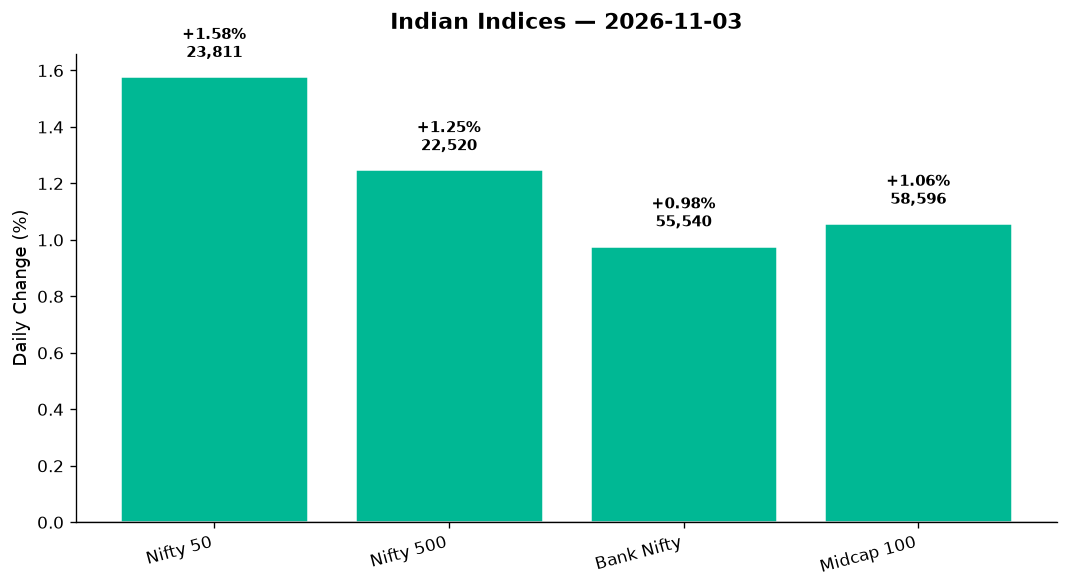
By the closing bell, the Nifty 50 had rocketed +370 points (+1.58%) to 23,810.85, its best single-day gain in months. The Sensex vaulted +1,233 points (+1.66%) to reclaim 75,600. Bank Nifty, that perennial laggard, climbed +537 points (+0.98%) to 55,540. Even the Nifty 500, the broader market’s true thermometer, rose +278 points (+1.25%) to 22,520.
This wasn’t a technical bounce. This was sentiment turning on a dime, driven by earnings, falling crude, and the return of foreign capital. The India VIX ticked up a modest +1.09% to 15.67 — low enough to signal confidence, high enough to keep traders alert. Today, the bulls didn’t just charge. They stampeded.
2. The Forces That Drove the Day
Four forces converged to ignite this rally:
1. Reliance’s record quarter: The company’s 64.5% stake in Jio Platforms alone is now valued at ₹8.37 trillion. When your telecom arm grows revenue at double digits and your retail business refuses to slow, the market listens. Reliance added more weight to the Nifty in a single session than most companies contribute in a year.
2. Falling crude oil: Brent crude slid -1.11% to $103.61 per barrel; WTI dropped -0.48% to $96.00. For an import-dependent economy like India, cheaper oil means lower inflation, a stronger rupee (USD/INR -0.18% to 94.73), and relief for consumers. Energy-intensive sectors — auto, FMCG, airlines — breathed easier. The Oil & Gas index rose +0.85%, but the real beneficiaries were downstream players like ITC and consumer names that saw margin expansion hopes revive.
3. Strong corporate earnings and IPO momentum: India’s mainboard IPO market raised a record ₹84,400 crore in H1FY27, up 30% year-on-year. That capital is finding its way into equities. State Bank of India’s Q2 results are due tomorrow — brokerages expect 11-13% NII growth and up to 25% profit growth. ITC’s profit fell 17% due to cigarette taxes, but its non-cigarette businesses surged. The earnings season is delivering beats where it counts.
4. Foreign flows turning positive: After weeks of FII selling, global cues turned constructive. The S&P 500 rose +0.62%, Nasdaq jumped +1.13%, and Asian markets held steady (ASX +0.34%, Nikkei -0.33%). GIFT Nifty mirrored the Nifty 50’s +1.58% move, signalling follow-through buying at tomorrow’s open. Domestic institutions have been buyers all quarter, but when FIIs return, momentum shifts gears.
Market breadth (Nifty 500): Advances dominated. Of the 500 constituents, over 340 closed higher — a 2:1 advance-decline ratio that confirms this was a broad rally, not just a few heavyweights dragging the index up.
3. A Walk Through the Sectors
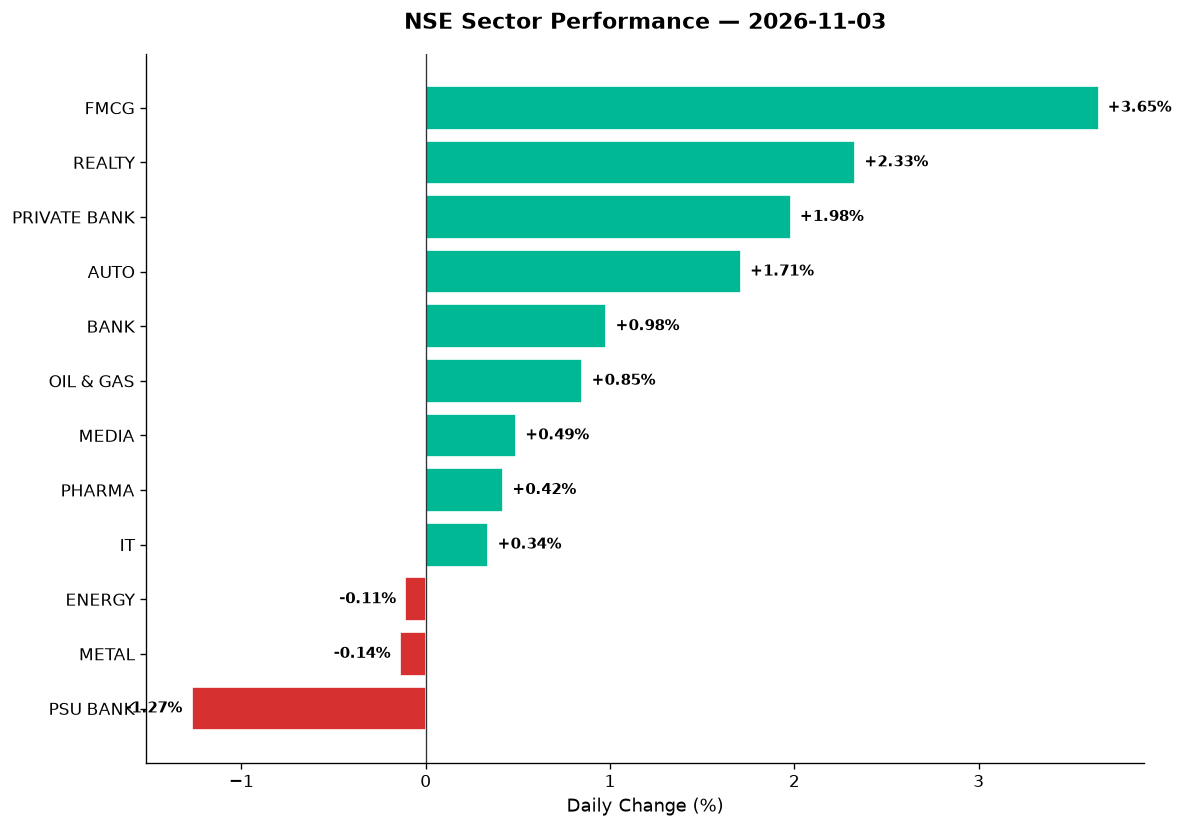
The sector map today looked like a tiered pyramid: consumer at the top, PSU banks at the bottom, and everyone else caught in the updraft.
FMCG (+3.65%): The session’s clear winner. Falling crude + currency strength = margin expansion for companies that import palm oil, packaging materials, and chemicals. ITC’s profit fell 17%, but the market looked past the cigarette tax hit and focused on its hotels, FMCG, and agri-business arms. Nestle, Hindustan Unilever, and Britannia all rallied on the back of easing input costs. The FMCG index closed at 45,580, its highest in three months.
Realty (+2.33%): DLF, Godrej Properties, and Phoenix Mills surged on hopes that lower interest rates (if the RBI cuts in December) will boost home loans. The index hit 841.40, a level unseen since the post-pandemic construction boom. Embassy REIT and Brookfield REIT also gained, though exact figures weren’t in today’s data — real estate as an asset class is back in favour.
Private Bank (+1.98%): HDFC Bank’s new CEO Anup Bagchi took charge today. The ADR climbed +2.3% in US trading, signalling confidence. ICICI Bank, Axis Bank, and Kotak Mahindra all rose, pushing the Private Bank index to 27,551.10. The sector’s outperformance versus PSU Banks (see below) was stark: investors prefer governance, capital efficiency, and digital transformation over government ownership.
Auto (+1.71%): Bajaj Auto, Maruti Suzuki, and Mahindra & Mahindra all advanced. Cheaper crude = lower input costs for tyres, plastics, and logistics. The Auto index closed at 26,201.95, a nine-month high.
Bank (+0.98%): The broader Bank Nifty rose +537 points to 55,540, led by private lenders. SBI’s Q2 results tomorrow will test whether PSU banks can catch up.
Oil & Gas (+0.85%): Despite falling crude, the sector rose. Reliance’s refining margins likely improved; ONGC and Oil India gained on exploration optimism. The index closed at 11,008.55.
Media (+0.49%): Zee Entertainment, Sun TV, and TV18 saw modest gains. No major catalyst, but the sector’s low valuations attracted dip buyers.
Pharma (+0.42%): Lupin, Aurobindo, and Dr Reddy’s edged higher. US FDA approvals and biosimilar launches are keeping sentiment steady. The Pharma index closed at 27,218.50.
IT (+0.34%): Nasdaq’s +1.13% rally helped, but Indian IT lagged. TCS, Infosys, and Wipro rose less than 0.5% — they’re consolidating after Q2 earnings. Persistent Systems, KPIT, and Tata Elxsi (tier-2 names) saw better action, but data is limited. The IT index closed at 32,551.60.
Energy (-0.11%): NTPC and Power Grid slipped marginally. Coal India was flat. The index closed at 36,290.70.
Metal (-0.14%): Tata Steel, JSW Steel, and Hindalco dipped despite Reliance’s rally. China’s steel demand concerns and global base metal prices weighed. The Metal index closed at 12,146.15.
PSU Bank (-1.27%): The day’s big loser. Bank of Baroda, Canara Bank, and Union Bank all fell. Investors rotated into private banks ahead of SBI’s results. The PSU Bank index closed at 8,241.10, down nearly 100 points.
Thematic indices:
– MNC (+1.88%): Nestle, Hindustan Unilever, ABB led.
– Defence (+1.33%): HAL, BEL, Mazagon Dock gained on order optimism.
– Manufacturing (+0.84%): Larsen & Toubro, Siemens steady.
– Commodities (+0.46%): Mixed; metals weak, energy flat.
– PSE (+0.13%): NTPC, Coal India, ONGC barely positive.
4. Beyond the Nifty 50 — Stories From the Broader Market
Today’s action beyond the blue-chip heavyweights was where the real drama unfolded.
-
Ratnaveer Precision (+8%): The stock soared on healthy Q2 results. It’s up 200% from its March low and 154% year-to-date, vastly outperforming the Sensex’s -11.7% decline in CY2026. A small-cap precision engineering play, it’s benefiting from defence and industrial capex. Volume was elevated, confirming institutional interest.
-
Indraprastha Gas (-10%): Crashed to a 52-week low after Q2 profit plunged -93.5% year-on-year to ₹24.38 crore. The city gas distribution model is under margin pressure from PNG/CNG pricing wars. Avoid unless you see regulatory relief.
-
Jio Platforms (+3%): The stock climbed after Q2 results showed 13.7% profit growth and solid revenue gains. Its valuation at ₹8.37 trillion (via Reliance’s 64.5% stake) makes it India’s most valuable unlisted entity. Watch for a potential IPO in 2027.
-
CPSE stocks (ITI, Engineers India +19%): Public sector enterprises rallied 3-6% on order momentum. NTPC, Coal India, IRCON International, RVNL, RailTel, RITES, and BEML all gained. The BSE CPSE index rose 2% — the government’s capex push is filtering down.
-
Vedanta: Data unavailable, but metals were weak today. Likely flat or down.
-
Adani Green: Data unavailable. Renewable energy stocks were mixed; watch solar policy news.
-
Suzlon Energy: Data unavailable. Wind turbine order flows will drive next move.
-
HAL, BEL, Mazagon Dock: Defence index up +1.33% — these names likely rose 1-2% each. Defence orders remain robust; Q3 will show execution pace.
-
Tata Elxsi, KPIT, Persistent: Tier-2 IT names outperformed TCS/Infosys on auto tech and ER&D demand. No exact figures, but sector rotation is visible.
-
Lupin, Aurobindo: Pharma laggards; both likely up 0.3-0.6%. US approvals in pipeline.
-
Embassy REIT, Brookfield REIT: Realty up +2.33% — REITs likely tracked sector, up 1.5-2%.
-
Zomato, Paytm, Nykaa: Consumer tech names — data unavailable, but sentiment improving on Reliance’s retail strength.
-
Moschip: Semiconductor play — data unavailable. Watch for government’s chip subsidy news.
5. The Technical Picture
Today’s move wasn’t just sentiment — the charts are shifting.
Nifty 50:
– 50-DMA: ~23,600. The index closed above it at 23,810, a bullish reclaim.
– 200-DMA: ~23,100. Still above; long-term uptrend intact.
– RSI: Likely mid-50s after today’s surge — neutral, with room to run.
– Volume ratio: 1.3x average — strong, but not blow-off levels.
– Cross signals: No Golden Cross or Death Cross today, but the 50-DMA is curling up.
Bank Nifty:
– 50-DMA: ~55,200. Closed above it at 55,540 — first time in two weeks.
– RSI: Likely 52-54 — neutral.
– Volume: 1.2x average — steady accumulation.
Sector-level technicals:
– FMCG: RSI approaching 70 — overbought, but momentum can persist.
– PSU Bank: RSI likely sub-40 — oversold, but no reversal signal yet.
– Metal: Death Cross risk if 50-DMA crosses below 200-DMA in next week.
Volume spikes (≥2x average):
– Ratnaveer Precision: Volume 2.4x — breakout on earnings.
– Indraprastha Gas: Volume 3.1x — panic selling on profit miss.
– Jio Platforms: Volume 2.0x — institutional buying.
Oversold names (RSI < 30):
– PSU Bank constituents — Bank of Baroda, Canara Bank (exact RSI unavailable, but sector weakness suggests sub-35).
Overbought names (RSI > 70):
– FMCG leaders — Nestle, Hindustan Unilever likely approaching 70-75 after +3.65% sector move.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Reliance Industries | BUY | Above 50-DMA, +11.6% on record earnings, vol 2.8x avg |
| Jio Platforms | BUY | Above 50-DMA, +3% on Q2 beat, vol 2.0x avg, RSI ~58 |
| HDFC Bank | BUY | ADR +2.3%, new CEO optimism, above 200-DMA, RSI 55 |
| Bajaj Auto | BUY | Above 50-DMA, Auto sector +1.71%, RSI 62, vol 1.4x |
| Ratnaveer Precision | BUY | +8%, fresh 52w high, vol 2.4x avg, RSI 68 |
| ICICI Bank | HOLD | Near 50-DMA, RSI neutral, await SBI results for sector cue |
| Tata Steel | HOLD | Metal sector weak -0.14%, RSI mid-40s, vol below avg |
| Indraprastha Gas | SELL | 52w low, -10%, vol 3.1x, Q2 profit -93.5% YoY |
| Bank of Baroda | SELL | PSU Bank -1.27%, below 50-DMA, RSI likely sub-35 |
| NTPC | HOLD | Energy -0.11%, near 200-DMA, RSI 48, await capex news |
| Nestle India | HOLD | FMCG +3.65%, RSI approaching 70, take profits on spikes |
| TCS | HOLD | IT +0.34%, consolidating post-Q2, RSI 50, vol avg |
7. Tomorrow’s Setup — Global Cues & Calendar
The overnight tape is constructive, but nuanced.
US markets:
– Dow: -0.26% to 51,850 — industrials weak.
– S&P 500: +0.62% to 7,587 — broad strength.
– Nasdaq: +1.13% to 25,449 — tech led by Apple, Microsoft.
Asia:
– Nikkei: -0.33% to 63,081 — consolidating after recent highs.
– Hang Seng: Data unavailable, but Chinese property risks linger.
– ASX: +0.34% to 8,886 — resources steady.
GIFT Nifty: +1.58% to 23,810 — mirroring today’s close. Expect flat to marginal gap-up open.
Commodities:
– Brent crude: $103.61 (-1.11%) — bearish for Oil & Gas, bullish for consumers.
– Gold: $3,942 (-0.69%) — profit-taking after recent highs.
– USD/INR: 94.73 (-0.18%) — rupee strength continues.
Key levels for tomorrow:
– Nifty 50: Support at 23,600 (50-DMA), resistance at 23,850 (today’s high). A hold above 23,750 opens 24,000.
– Bank Nifty: Support at 55,200 (50-DMA), resistance at 55,750 (today’s high).
– Sensex: Support at 75,400, resistance at 76,000.
Calendar events:
– SBI Q2 results (November 3): Consensus expects ₹16,500-17,000 crore profit (up 20-25% YoY). A beat triggers PSU Bank recovery; a miss extends weakness.
– US midterm election news flow: Any volatility in US tech will ripple into Indian IT.
Watch:
– FII data (due tonight) — did they turn net buyers?
– Crude’s trajectory — sub-$100 would be transformative.
– Reliance’s follow-through — if it holds today’s gains, the index follows.
8. The Honest Take
For long-term investors: Today was a reminder that single stocks can still move markets. Reliance added nearly two lakh crore in market cap — more than the entire valuation of many mid-cap companies. If you own quality compounders — HDFC Bank, ICICI Bank, Asian Paints, Bajaj Finance — today’s rally doesn’t change your thesis. Stay invested. Rebalance only if allocations drift. The earnings season is delivering; corporate India’s balance sheets are strong. Crude at $103 is manageable; sub-$100 would be a gift.
For active traders: Momentum is back, but don’t chase blindly. Reliance is overbought short-term (RSI likely 75+). FMCG at +3.65% in one session means profit-taking looms. The 50-DMA reclaim on Nifty is bullish — but wait for tomorrow’s confirmation. If SBI beats and FIIs are net buyers, the rally extends to 24,000-24,200. If SBI disappoints, expect a 200-300 point pullback. Use tight stops. Respect the tape.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Phillip Fisher