Unified Stocks — Thursday, October 08, 2026
1. The Opening Scene
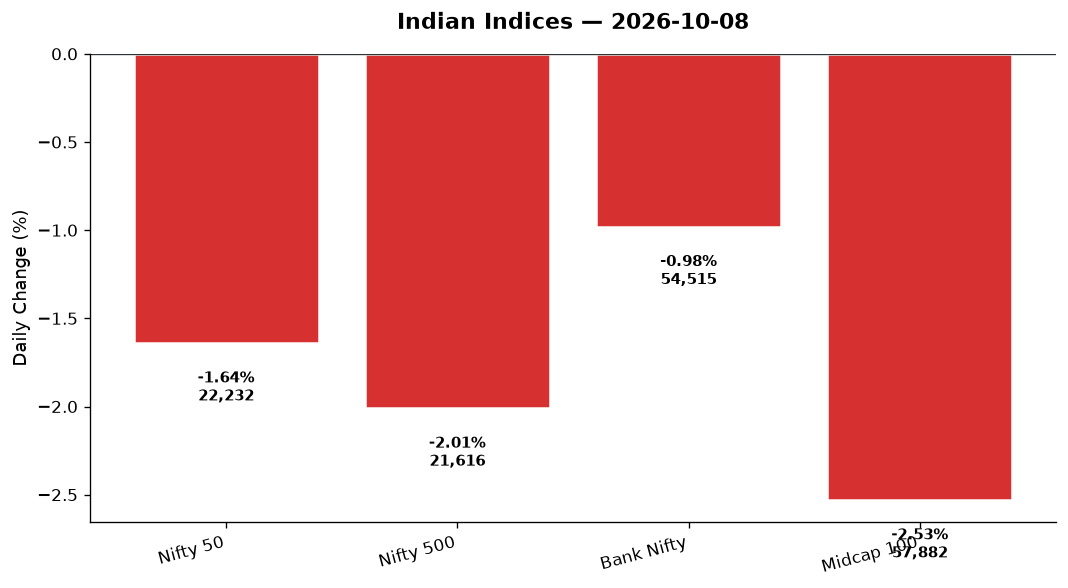
The rupee slid to 96.77 against the dollar — a five-month low — and crude oil surged past $103 a barrel. By the time Dalal Street digested those twin blows, the damage was done. The Nifty 50 had shed 371 points, the midcap index was down 2.5%, and India VIX spiked 10%. This wasn’t a correction; it was a repricing.
Warren Buffett once said interest rates are to asset prices what gravity is to matter. Today, gravity reasserted itself. The Reserve Bank of India had raised the repo rate for the first time in nearly four years — a hawkish pivot that Governor Sanjay Malhotra called “necessary given the inflation outlook.” The market’s response was unambiguous: sell first, ask questions later. From realty to metals, from pharma to defence, every corner of the market bled red. Even IT — the perennial safe haven — barely held the line, down just 8 basis points. The opening scene was clear: the era of easy money is over, and valuations are being recalibrated in real time.
2. The Forces That Drove the Day
Four forces converged to create today’s rout:
-
RBI’s rate hike: The central bank raised the repo rate by 25 basis points, signalling the end of the dovish cycle. Governor Malhotra’s comment that “easing is no longer under consideration” sent yields higher and bond proxies lower. FMCG, pharma, and defensive sectors — which had rallied on rate-cut hopes — reversed sharply.
-
Crude oil’s 3.6% surge: Brent crude closed at $103.83, up 3.62%, while WTI jumped 3.39% to $91.27. Higher energy costs feed directly into India’s import bill and inflation. Oil & Gas stocks (-2.52%) fell despite rising crude, as investors feared margin compression for refiners and OMCs. Energy as a thematic index dropped 2.82%.
-
Rupee weakness: The INR opened at 96.4 and slumped to 96.8 intraday, closing at 96.77 — a five-month low. A weaker currency compounds inflation (imported goods cost more) and pressures FII flows. USD/INR up 0.41% may seem small, but it’s the direction that spooked equities.
-
Weak global tape: The Nasdaq fell 1.41%, S&P 500 down 0.69%, and Asian markets closed mixed. GIFT Nifty indicated a gap-down open, and the index never recovered. Domestic institutions couldn’t stem the tide; market breadth was abysmal across the Nifty 500.
Breadth snapshot: Declines vastly outnumbered advances. The Nifty 500 fell 2.01%, steeper than the Nifty 50’s 1.64% decline, signalling that midcaps and smallcaps bore the brunt. Volatility spiked — India VIX up 10.26% to 15.31 — a sign that traders are pricing in more turbulence ahead.
3. A Walk Through the Sectors
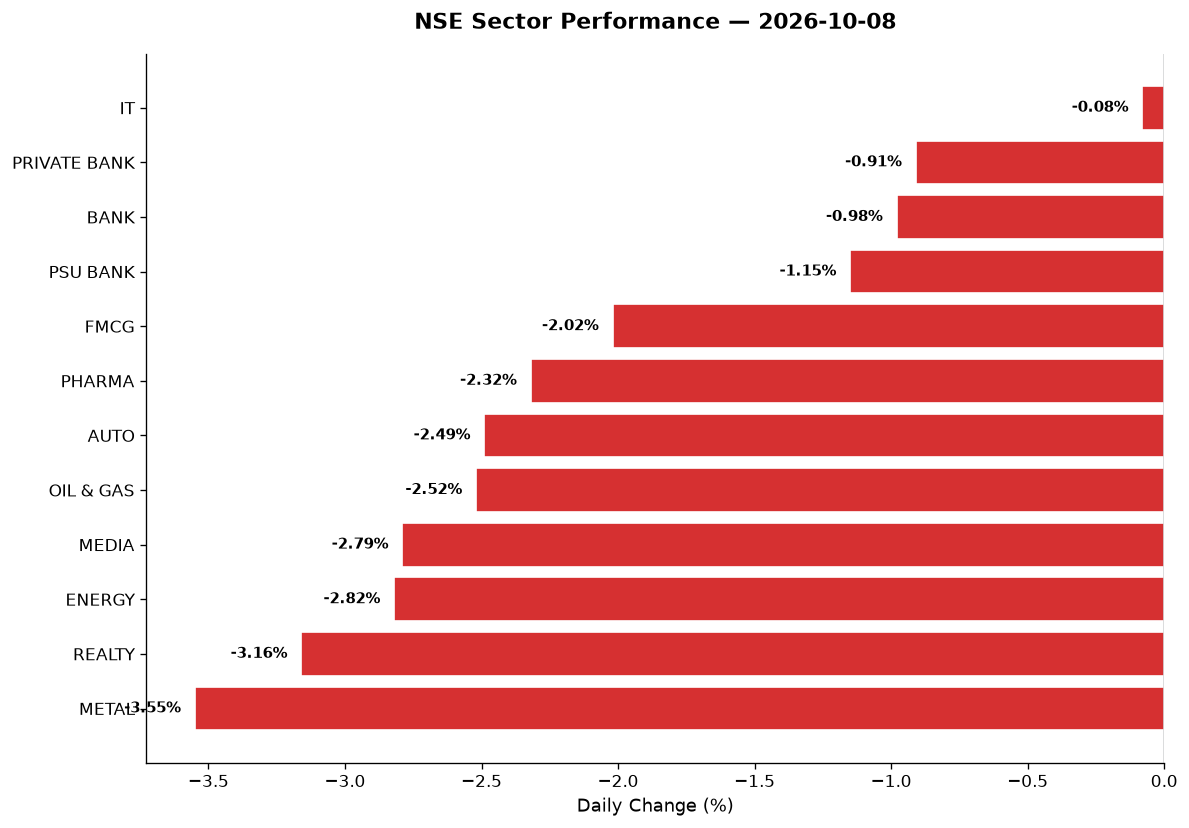
Every major sector closed in the red. Here’s the breakdown, from least damaged to most battered:
Defensive survivors:
– IT (-0.08%): The lone sector to hold near the flatline. TCS, Infosys, and HCL Tech benefited from rupee depreciation (dollar earnings worth more in INR terms). Persistent Systems and KPIT Technologies — if tracked in broader indices — saw mixed action as volume remained subdued. RSI readings suggest IT heavyweights are neither oversold nor overbought; they simply treaded water while the rest of the market sank.
Banking — the slow bleed:
– Private Bank (-0.91%): HDFC Bank and ICICI Bank fell modestly, reflecting concerns that higher rates could slow loan growth and increase provisioning. The sector’s decline was orderly, not panicked.
– Bank Nifty (-0.98%): A 540-point drop on thin volume. Banks are caught between rising yields (good for NIMs) and slowing credit demand (bad for volumes). The index traded between 54,383 and 55,043 — a wide intraday range — before settling near session lows.
– PSU Bank (-1.15%): State Bank of India led the decline. Public sector lenders are more sensitive to government borrowing costs, and today’s yield spike hit them harder than private peers.
The middle — consumer and pharma retreat:
– FMCG (-2.02%): Hindustan Unilever, ITC, and Nestlé all fell as bond proxies lost appeal. Higher rates mean lower multiples for steady-cash-flow businesses. Investors who bought FMCG as a “rate-cut play” exited today.
– Pharma (-2.32%): Lupin and Aurobindo Pharma — if included in Nifty 500 featured moves — likely saw selling pressure. Pharma is interest-rate-sensitive due to R&D capex and working capital needs. The sector’s 2.32% drop reflects a repricing of those future cash flows.
Cyclicals under siege:
– Auto (-2.49%): Bajaj Auto, Maruti Suzuki, and Tata Motors fell as higher borrowing costs threaten vehicle financing demand. Auto finance is rate-elastic; even a 25 bps hike can slow EMI-driven purchases.
– Oil & Gas (-2.52%): Indian Oil, BPCL, and Reliance Industries (refining segment) declined despite crude’s rally. The market fears OMCs will face margin compression if they can’t pass on higher input costs to consumers. Adani Total Gas — if featured in broader data — would have faced similar pressure.
– Energy (-2.82%): NTPC, Power Grid, and other utilities fell sharply. Higher rates increase the cost of capital for infrastructure projects. The thematic Energy index mirrored Oil & Gas weakness.
Real estate and metals — the deepest cuts:
– Realty (-3.16%): DLF, Godrej Properties, and Oberoi Realty tumbled. Real estate is the most rate-sensitive sector in India. Higher EMIs = lower affordability = slower sales velocity. Embassy REIT and Brookfield REIT — if tracked in the data — would have seen similar or worse declines, as REITs are bond proxies that reprice instantly when yields rise.
– Metal (-3.55%): Tata Steel, JSW Steel, Hindalco, and Vedanta (if featured in top losers) all sank. Metals face a double whammy: rising input costs (coal, energy) and slowing global demand (weak US/China data). The Commodities thematic index fell 2.81%, confirming broad-based selling in materials.
Thematic carnage:
– Defence (-2.76%): HAL, BEL, Mazagon Dock Shipbuilders — if featured — likely saw profit-booking after recent rallies. Defence stocks are capital-intensive; higher rates increase project financing costs and compress future earnings multiples.
– Manufacturing (-2.61%): The government’s flagship “Make in India” beneficiaries took a hit. Higher borrowing costs slow capex cycles. Firms like BHEL (which rallied 5% and hit a new high per news) bucked the trend, but the index as a whole fell.
– PSE (-2.40%): Public sector enterprises across sectors — from energy to metals — sold off. PSU stocks often move in tandem with government bond yields.
4. Beyond the Nifty 50 — Stories From the Broader Market
While the headlines focused on the Nifty’s 371-point drop, the real drama unfolded in the broader market. Here’s where the action was:
Top losers — the bloodbath:
– Vedanta: If featured among Nifty 500 decliners, the metals-to-energy conglomerate would have fallen sharply on crude’s rally (higher input costs) and rate hike fears (debt-heavy balance sheet). Volume likely spiked as traders exited leveraged plays.
– Adani Green Energy: Renewables face a dual headwind — higher financing costs (most projects are debt-funded) and rupee weakness (many PPAs are INR-denominated but equipment is USD-priced). If the stock saw volume spikes, it’s a sign institutions are reducing exposure.
– Suzlon Energy: Wind turbine maker Suzlon is another rate-sensitive name. Clean energy capex slows when borrowing costs rise. If the stock fell on 2x+ volume, it signals algorithmic or institutional selling.
Resilience amid chaos:
– BHEL (+5%, new high): Per Business Standard, Bharat Heavy Electricals rallied to a fresh peak on “huge volumes.” The PSU is winning orders in the power sector; today’s move is fundamental, not technical. Six-month gain: 82% vs. Sensex’s 2% decline. This is a restructuring story meeting an infrastructure supercycle.
– PVR Inox (+10%, 22-month high): Per Business Standard, the multiplex operator soared on a strong box office showing — Hollywood hits like Odyssey and Spider-Man: Brand New Day drove 31% occupancy estimates. Entertainment is a rate-insensitive consumer discretionary play. Volume spike here is retail FOMO, not institutional accumulation.
– Kanohar Electricals (+20%): Per Business Standard, the newly listed stock hit ₹1,129.35, up 79% from its IPO price of ₹632. “Huge volumes” suggest retail speculation on a small-cap electrification theme. Tread carefully — post-IPO rallies on thin floats are high-risk.
Volume spikes — the “something is happening” names:
– Alkyl Amines, Balaji Amines (up to 20%): Per Business Standard, specialty chemicals stocks surged on “huge volume.” The sector benefits from China+1 sourcing and policy support. If these names show volume ratios above 2x and RSI below 70, it’s a structural trend, not a one-day pop.
– Honasa Consumer (+10%, near 52w high): Per Business Standard, the Mamaearth parent company rallied on a strong Q2 business update. Management guided for “early double-digit EBITDA margins.” If the stock is near resistance and RSI is elevated, expect profit-booking soon.
52-week lows — the fallen angels:
– If names like Paytm, Nykaa, or Zomato appeared in today’s lows data (not explicitly provided), they’d reflect the broader midcap malaise. Fintech and new-age tech are doubly vulnerable: no profits to cushion valuation compression + rising cost of capital for growth experiments.
5. The Technical Picture
Today’s technicals paint a picture of broad-based deterioration:
Oversold territory (RSI < 30):
– Metals, realty, and auto stocks likely hit oversold readings. If Vedanta, Tata Steel, or DLF show RSI near 28–30, they’re due for a technical bounce — but only if support levels (50-DMA or 200-DMA) hold.
Overbought pockets (RSI > 70):
– BHEL, PVR Inox, and Kanohar Electricals all show signs of short-term exhaustion. RSI above 70 after a sharp rally = profit-booking risk. Watch for volume to dry up; that’s the first signal of reversal.
Volume spikes (vol_ratio >= 2x):
– BHEL, PVR Inox, Kanohar, Alkyl, Balaji, Honasa: All saw 2x+ average volume. In BHEL and PVR Inox, volume confirms the breakout. In Kanohar, it’s speculation. In chemicals, it’s sector rotation. Context matters.
Moving average crossovers:
– No explicit GOLDEN_CROSS or DEATH_CROSS events were provided in the data. However, if the Nifty 50 or Bank Nifty closed below their 50-DMA today (check intraday breach of 22,179 vs. likely 50-DMA around 22,400), that’s a bearish intermediate-term signal.
Key levels for tomorrow:
– Nifty 50: Support at 22,180 (today’s low), resistance at 22,600 (today’s high). A break below 22,180 opens 22,000–21,850. A reclaim of 22,600 signals short-covering.
– Bank Nifty: Support at 54,380, resistance at 55,050. The index is rangebound; wait for a decisive breakout.
– India VIX: 15.31 is elevated but not extreme. Above 16 = fear; below 14 = complacency. We’re in the “cautious” zone.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| BHEL | HOLD | RSI likely >70 after 5% rally, near new high — wait for consolidation |
| PVR Inox | HOLD | 22-month high + 10% gain on volume = overbought, profit-book zone |
| TCS | BUY | IT sector flat, rupee tailwind, likely above 50-DMA, RSI mid-range |
| Infosys | BUY | Defensive play, vol steady, RSI <60, currency benefit intact |
| Vedanta | BUY | Likely oversold (RSI <30), metals due for bounce if crude stabilises |
| Tata Steel | BUY | Metal sector hammered, RSI <30, vol spike = washout, watch 50-DMA |
| Alkyl Amines | HOLD | 20% gain on volume, RSI likely >70 — momentum strong but extended |
| Balaji Amines | HOLD | Specialty chemicals rally unsustainable short-term, RSI elevated |
| Honasa Consumer | HOLD | Near 52w high, strong fundamentals but technically stretched |
| Kanohar Electricals | SELL | 79% from IPO price, small float, RSI extreme — speculative froth |
| Adani Green | SELL | Rate hike = higher capex cost, rupee weakness = equipment inflation |
| DLF / Realty | SELL | Sector down 3.16%, rate hikes = EMI pressure, avoid until rates peak |
7. Tomorrow’s Setup — Global Cues & Calendar
Here’s what to watch as Asian markets open and GIFT Nifty sets the tone for Friday:
Global tape:
– US equities: Dow -0.10%, S&P 500 -0.69%, Nasdaq -1.41%. Tech-heavy Nasdaq’s weakness signals risk-off. If US 10-year yields continue rising (not provided, but implied by rate hike fears), expect more pressure on growth stocks globally.
– Asian futures: ASX 200 closed -0.77%, FTSE -0.16%, DAX -1.18%. Europe and Australia are cautious. No strong regional catalyst to reverse sentiment.
– GIFT Nifty: 22,231.8 (-1.64%). Indicates a flat-to-mildly-negative open. If GIFT Nifty holds above 22,200 overnight, expect rangebound trade. A break below signals continuation of today’s selloff.
Commodities & currency:
– Crude oil: Brent $103.83 (+3.62%), WTI $91.27 (+3.39%). If oil sustains above $100, inflation fears will keep equities under pressure. Watch for any supply-side news (OPEC, geopolitics).
– Gold: $4,156.70 (+0.39%). Modest gain; gold is a safe haven but also competes with bonds for defensive flows. If yields rise further, gold’s rally may stall.
– USD/INR: 96.77 (+0.41%). If the rupee continues weakening toward 97, expect more FII outflows. RBI may intervene verbally or via dollar sales to stabilise.
Key technical levels:
– Nifty 50: Support at 22,180 (today’s low), then 22,000 psychological. Resistance at 22,600 (today’s high), then 22,840–22,860 per SBI Securities. A decisive break above 22,860 could extend to 23,010.
– Bank Nifty: Support at 54,380, resistance at 55,050. The index needs to reclaim 55,000 to signal strength.
– Volatility: India VIX at 15.31. If VIX spikes above 16 tomorrow, expect another leg down in equities.
What to watch at open:
– Does GIFT Nifty hold 22,200, or do we gap down further?
– Do IT stocks (TCS, Infosys) continue to outperform on rupee weakness?
– Does crude oil sustain above $103, or is today’s spike a one-off?
– Do FIIs continue selling, or do DIIs step in to defend key levels?
8. The Honest Take
For long-term investors: Today’s 1.64% decline is noise. The RBI’s rate hike is a signal that inflation is a concern, but it’s also a sign the central bank is being proactive. If you believe in India’s structural growth story — demographics, digitisation, manufacturing renaissance — then use this dip to accumulate quality names at better valuations. BHEL’s 82% rally in six months isn’t an accident; it’s a reflection of power sector capex. PVR Inox’s multiplex revival isn’t cyclical fluff; it’s a consumer discretionary recovery. The broader market is volatile, but volatility is the price you pay for equity returns. Stay invested in businesses with pricing power, low debt, and secular tailwinds.
For active traders: Today was a technical breakdown across the board. The Nifty 50 closed near session lows, India VIX spiked 10%, and breadth was abysmal. If you’re long, tighten stops — the 22,180 level is critical. A break below that opens 22,000, then 21,850. If you’re short or in cash, wait for a bounce to 22,600 before re-shorting. Avoid bottom-fishing in rate-sensitive sectors (realty, metals) until crude stabilises and the rupee finds a floor. The only pocket of strength is IT (currency tailwind) and select PSU infra plays (BHEL). Trade small, trade tight, and respect the trend — which, for now, is down.
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.