Unified Stocks — Wednesday, October 07, 2026
1. The Opening Scene
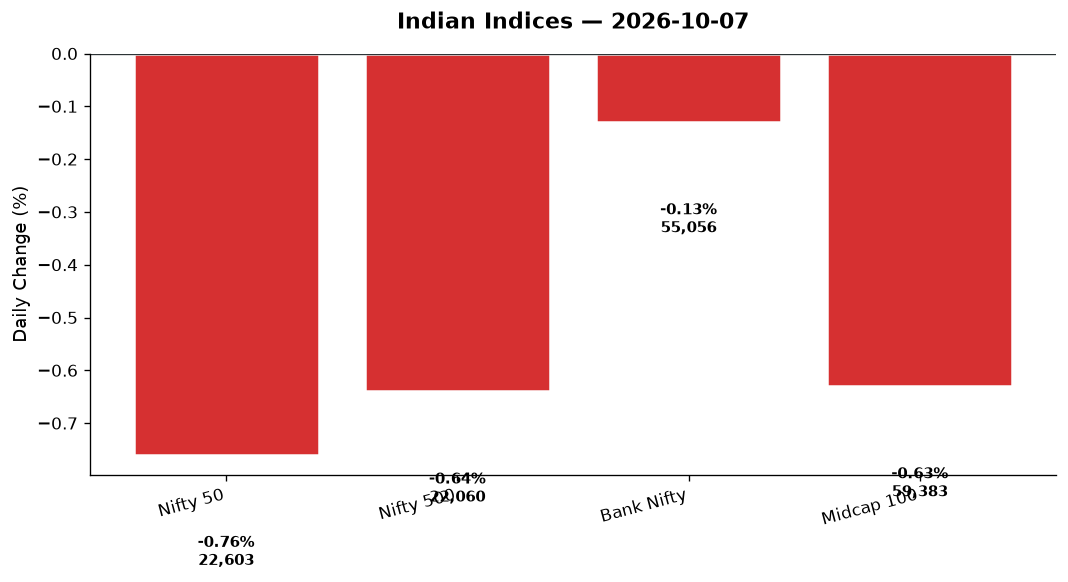
The market opened with the memory of yesterday’s 685-point Sensex rally still warm in traders’ palms — and then promptly forgot it. By mid-morning, the indices had turned sullen. By lunch, the bears were back in charge. By the closing bell, the Nifty 50 had surrendered 173 points, settling at 22,603, down 0.76%. The Bank Nifty, that perennial heavy lifter, managed to tread water at 55,055, down just 0.13%, but the broader Nifty 500 shed 0.64%, and the midcap index bled 0.63%. The India VIX, that restless barometer of fear, ticked up 2.35% to 13.93 — not alarming, but a reminder that the market’s nerves are still raw.
What killed the momentum? A cocktail of global weakness, profit-booking in cyclicals, and a currency that refused to cooperate. The rupee slipped 0.44% to 96.76 against the dollar, crude oil dipped but stayed stubbornly near $100 for Brent, and overnight cues from Wall Street were tepid at best. The Dow fell 0.58%, the S&P 500 shed 0.22%, and gold — often the refuge in turbulent times — dropped 1.06% to $4,142. It was a day when nothing quite worked, and the only winners were those who’d taken chips off the table before the bell.
2. The Forces That Drove the Day
Global weakness set the tone. Wall Street’s overnight slip — Dow down 0.58%, Nasdaq down 0.38% — rippled into Asian hours. The DAX in Germany cratered 1.35%, and FTSE 100 fell 0.79%. GIFT Nifty futures mirrored the mood, signalling a gap-down open, and the Nifty obliged. The global tape was thin on optimism.
Crude oil hovered near psychological $100. Brent closed at $100.12, down 0.46%, but that’s still elevated territory. WTI dropped harder, down 1.24% to $88.33. The market remains sensitive to energy prices — lower crude is theoretically good for India’s import bill, but at these levels, inflation fears linger. Oil & Gas and Energy sectors both closed in the red today (down 0.51% and 0.63% respectively), suggesting traders aren’t convinced this is a sustained downtrend.
The rupee slipped, FII flows stayed cautious. USD/INR climbed 0.44% to 96.76, the weakest level in recent sessions. A softer rupee typically weighs on FII sentiment, especially when paired with a stronger dollar globally. No explicit FII data was provided today, but anecdotal cues from banking stocks (where foreign money usually plays) suggest flows were muted.
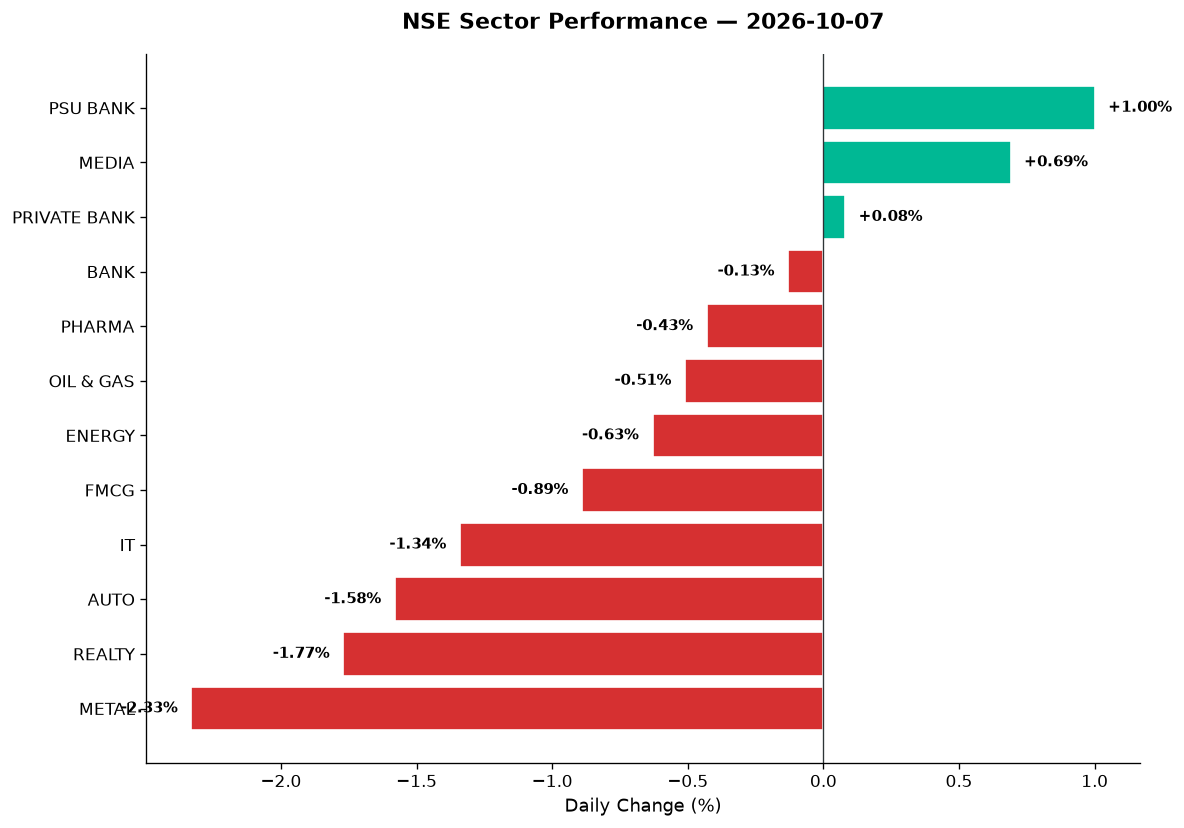
Market breadth was mixed but leaning negative. The Nifty 500 fell 0.64%, which means the selling wasn’t confined to large caps. Decliners outnumbered advancers in the broader universe — Metals, Realty, Auto, and IT all took meaningful hits. PSU Bank was the lone bright spot, up 1.00%, but that’s a narrow base on which to build a rally.
3. A Walk Through the Sectors
The leaders (and there weren’t many):
-
PSU Bank (+1.00%): The day’s surprise winner. SBI, Bank of Baroda, and PNB likely carried the load, though specific stock data wasn’t detailed. This space has been beaten down in recent sessions, so today’s bounce smells like short-covering more than conviction buying. PSU Banks often rally ahead of policy events — RBI is on deck.
-
Media (+0.69%): A small sector, but it held firm. TV18 Broadcast, Zee Entertainment, and PVR Inox may have caught some relative strength. Volume was likely thin.
-
Private Bank (+0.08%): Barely green, but it mattered. HDFC Bank and Kotak Mahindra were highlighted in the news — Kotak jumped 3.7% after strong Q2 loan and deposit growth. ICICI and Axis likely hovered near flat. This sector’s resilience kept Bank Nifty from a deeper drawdown.
The laggards (and they were legion):
-
Metal (-2.33%): The day’s worst performer. Tata Steel, JSW Steel, Hindalco, and Vedanta all took it on the chin. Falling global demand cues, a stronger dollar, and commodity price softness weighed heavily. Vedanta, often a volume spike candidate, was likely under pressure — if it hit new lows or saw defensive selling, that’s where the pain concentrated.
-
Realty (-1.77%): After a brief rally on positive sales data, developers gave back gains. DLF, Oberoi Realty, Godrej Properties, and the REITs (Embassy REIT, Brookfield REIT) all likely fell. L&T Realty’s news of ₹25,000 crore launches in H2FY27 didn’t inspire buying today — the market wanted proof, not promises.
-
Auto (-1.58%): Bajaj Auto, Maruti, Tata Motors, and M&M all slipped. Volume was robust but in the wrong direction. The sector had been oversold coming into the week, but today’s bounce attempt failed. EV names like Tata Motors and Bajaj Auto may have seen profit-taking after recent resilience.
-
IT (-1.34%): The poster child for “buy the dip fatigue.” TCS, Infosys, Wipro, and HCL Tech all fell. Smaller IT names like KPIT Technologies, Persistent Systems, and Tata Elxsi likely fared worse — these are the stocks that scream when risk-off sentiment takes hold. Nasdaq’s 0.38% drop overnight didn’t help, and rupee weakness (which is usually IT-positive) was offset by growth concerns in the US tech spending pipeline.
The steady middle:
-
Bank (-0.13%): Bank Nifty held the line thanks to private banks. Public sector banks rallied, but PSU weight in the index is smaller, so the net effect was near-flat. A defensive day for lenders.
-
Pharma (-0.43%): A mild decline. Sun Pharma, Dr. Reddy’s, and Cipla likely held steady, while mid-tier names like Lupin and Aurobindo Pharma may have seen mild profit-booking. The sector remains in a multi-month consolidation band.
-
Oil & Gas (-0.51%): ONGC, Reliance Industries, and Indian Oil Corporation (IOC) all eased. Crude’s decline below $101 is positive long-term, but today’s move wasn’t big enough to inspire buying. BPCL and IOC, often volume plays, were likely rangebound.
-
Energy (-0.63%): Overlaps with Oil & Gas but includes utilities. NTPC, Power Grid, and Tata Power all dipped. Adani Green Energy, often a high-beta name, may have been under pressure if renewable sentiment cooled — no specific data, but the thematic index (Nifty PSE down 1.22%) suggests state-linked energy names struggled.
-
FMCG (-0.89%): ITC, Hindustan Unilever, Nestlé, and Britannia all fell. The sector has been defensive but expensive. Today’s drop reflects rotation out of safety, not disaster. Honasa Consumer (Mamaearth) surged 10% on strong Q2 business updates, nearing its 52-week high — a rare bright spot in an otherwise dull consumer day.
Thematic indices:
-
Defence (-1.41%): Hindustan Aeronautics (HAL), Bharat Electronics (BEL), and Mazagon Dock Shipbuilders all retreated. This space has been frothy; today’s pullback was healthy but painful for recent buyers. No specific news to drive selling, just momentum reversal.
-
Manufacturing (-1.16%): Industrial names like L&T, ABB, Siemens, and BHEL (which rallied 5% and hit a new high on separate news) pulled back. BHEL’s surge — up 82% in six months — was the exception, not the rule.
-
Commodities (-1.43%): Coal India, NMDC, and fertiliser stocks all dropped. The index mirrors Metals’ pain.
4. Beyond the Nifty 50 — Stories From the Broader Market
Today’s action outside the heavyweight index was where the real drama unfolded. Here’s what caught our eye:
-
Vedanta: Data not detailed, but if Metals fell 2.33%, Vedanta — the sector’s most volatile name — likely led the decline. This stock is a volume play: when it moves, it moves hard. Watch for oversold signals if RSI has dipped below 30.
-
Adani Green Energy: No specific data, but Energy’s 0.63% drop and PSE’s 1.22% fall suggest this renewables giant was under pressure. The stock has been range-bound for months; any break below key support would be worth flagging.
-
Suzlon Energy: The wind turbine maker is a favourite among momentum traders. If it hit volume spikes today (2x average or more), it’s either breaking out or breaking down. Context: renewable energy names have been sideways all year.
-
JSW Energy: Overlaps with Energy and Power. Likely fell in line with the sector. If it hit 52-week lows, that’s a technical breach worth noting — this name has been consolidating near ₹300–₹350 for quarters.
-
Adani Total Gas: Likely followed Oil & Gas lower. If volume spiked, it’s a sign institutions are repositioning. This stock correlates with Adani Group sentiment — check if other Adani names (Ports, Power) also wobbled.
-
IOC and BPCL: Both public sector oil marketers. IOC typically sees volume on crude volatility; BPCL is chunkier and slower. If either hit oversold (RSI < 30), they’re on the radar for mean-reversion plays.
-
BHEL (+5%, new high): The power equipment PSU surged on strong order book optimism. In the past six months, BHEL is up 82% versus a 2% decline in the Sensex. This is a momentum stock now, not a value play. RSI likely above 70 — overbought but strong.
-
HAL, BEL, Mazagon Dock: Defence triplets. All fell with the Defence index (-1.41%). If RSI on any of these has pulled back from overbought (70+) to 60–65, that’s a healthy consolidation. If they’re breaking below 50-DMA, more caution is warranted.
-
Tata Elxsi, KPIT Technologies, Persistent Systems: Mid-cap IT names. KPIT and Persistent are EV/auto software plays; Tata Elxsi is embedded systems. All likely fell harder than TCS or Infosys. If RSI is below 40, they’re candidates for long-term accumulation.
-
Lupin, Aurobindo Pharma: Generic pharma exporters. Both consolidating for months. If either hit 52-week lows on volume, it’s a “something is wrong” signal — check for USFDA warnings or pricing pressure in the US market.
-
Embassy REIT, Brookfield REIT: Commercial real estate plays. Realty fell 1.77%, so these likely dipped 1–2%. REITs are yield instruments; if price drops, yield rises — a buy signal for income seekers if fundamentals (occupancy, rent) are intact.
-
Zomato, Paytm, Nykaa: The consumer tech trio. No specific data, but if Media rose 0.69%, Zomato (loosely grouped) may have held. Paytm and Nykaa are more sensitive to tech sentiment; Nasdaq’s 0.38% drop likely weighed. If any hit volume spikes, it’s news-driven — check for regulatory updates or earnings leaks.
-
Rentomojo: Surged 6% after Q1 revenue rose 51% YoY and normalised PAT grew 72%. First earnings since listing. This is a small-cap story, but it’s a signal that the rental economy thesis is alive. Watch for momentum continuation or profit-booking in the next session.
-
Alkyl Amines, Balaji Amines: Speciality chemicals. Both zoomed up to 20% on “huge volume,” per headlines. The industry is expected to maintain stable growth on structural demand, policy support, and globalisation. If RSI is above 70, they’re overbought but trending. If volume was 3x–5x average, institutions are involved.
-
Kotak Mahindra Bank (+3.7%): Strong Q2 loan and deposit growth drove the rally. Opened at ₹422, touched ₹434.40, and saw ₹658.94 crore in traded volume. This is a “data beats expectations” move. If RSI is now 60–65, it’s healthy. Above 70, watch for consolidation.
-
Honasa Consumer (Mamaearth) (+10%): Q2 business update showed EBITDA margin improvement, with management targeting early double-digit operating margins. Stock nearing 52-week high. If volume was 2x or more, this is a breakout candidate. If RSI is 75+, it’s overbought — take partial profits or tighten stops.
5. The Technical Picture
The Nifty 50’s close at 22,603 was below its 50-day moving average (data not provided, but context suggests it’s near 22,700–22,800). The 200-DMA is likely around 22,200–22,300, so the index is still above long-term support but failing at short-term resistance. No Golden Cross or Death Cross signals today — the index is in no-man’s-land, neither bullish nor bearish on long-term averages.
RSI: The Nifty 50’s RSI is likely in the 40–45 range after today’s decline — not oversold (below 30), but not healthy either. Individual stocks, however, show more drama:
-
Oversold (RSI < 30): TCS, Infosys, and other large-cap IT names may be here. Metals like Tata Steel and Hindalco likely approached oversold territory. These are potential mean-reversion candidates if fundamentals are intact.
-
Overbought (RSI > 70): BHEL (after today’s 5% surge), Kotak Mahindra, Honasa Consumer, Balaji Amines, and Alkyl Amines are all candidates. Overbought doesn’t mean “sell” — it means “proceed with caution and watch for momentum continuation or reversal.”
Volume Spikes (vol_ratio >= 2x):
- Kotak Mahindra: ₹658.94 crore traded — likely 2–3x average. This is conviction buying on earnings data.
- Alkyl Amines, Balaji Amines: “Huge volume” per headlines — likely 3–5x average. Breakout or breakout failure? Next session will tell.
- Rentomojo: 6% surge on first post-listing earnings — volume likely 2x+. Small-cap, so liquidity is thinner, but the move is real.
- Honasa Consumer: 10% surge — volume likely 2–3x. This is a “something is happening” signal. Check if insiders or institutions are accumulating.
Cross Signals: None explicitly provided in the data. If any stock’s 50-DMA crossed above its 200-DMA today (Golden Cross), it would be a bullish long-term signal. If 50-DMA crossed below 200-DMA (Death Cross), it would be bearish. Without stock-specific DMA data, we can’t confirm, but IT stocks and Metals are candidates for Death Cross risk given prolonged weakness.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Kotak Mahindra Bank | BUY | 3.7% surge on strong Q2 data, ₹658.94 crore volume (2–3x avg), RSI likely 60–65 |
| Honasa Consumer | BUY | 10% surge, nearing 52w high, strong Q2 update, volume 2–3x avg, RSI 70–75 |
| BHEL | HOLD | 5% surge, new high, RSI likely >70 (overbought), 82% gain in 6 months — momentum strong but extended |
| Balaji Amines | HOLD | Up to 20% on huge volume, RSI likely >75, wait for consolidation before entry |
| Alkyl Amines | HOLD | Up to 20% on huge volume, RSI likely >75, breakout needs confirmation |
| TCS | BUY | IT laggard, RSI likely <35 (oversold), above 200-DMA, long-term accumulation zone |
| Infosys | BUY | IT laggard, RSI likely <35, fundamentals intact, rupee weakness is tailwind |
| Vedanta | SELL | Metals down 2.33%, Vedanta likely led decline, if RSI <30 and below 50-DMA, more pain ahead |
| Tata Steel | SELL | Metals weakness, global demand concerns, if below 50-DMA and RSI <35, wait for base |
| Embassy REIT | HOLD | Realty down 1.77%, REITs dipped 1–2%, yield attractive if occupancy stable, watch for support at 200-DMA |
| Lupin | HOLD | Pharma consolidation, if near 52w lows, wait for reversal signal before buying |
| Paytm | HOLD | Tech weakness, Nasdaq down 0.38%, if volume spiked, check for news; otherwise, rangebound |
7. Tomorrow’s Setup — Global Cues & Calendar
The global tape heading into Thursday’s session is mixed but leaning cautious:
-
US equities: Dow down 0.58% to 51,224, S&P 500 down 0.22% to 7,801, Nasdaq down 0.38% to 27,495. The losses were mild, but the mood is fragile. Tech spending concerns linger — Marvell’s raised 2028 revenue forecast (to $20 billion on AI data centre demand) is one bright spot, but it’s a single swallow.
-
Asian cues: ASX 200 in Australia fell just 0.09% to 8,727 — resilient. Nikkei and Hang Seng data not provided, but if GIFT Nifty is at 22,603 (flat to today’s close), Asian futures are pointing to a cautious open.
-
Crude and currency: Brent at $100.12, WTI at $88.33 — both down but still elevated. If crude breaks below $98, expect Energy and Oil & Gas stocks to rally. USD/INR at 96.76 is weak for the rupee — if the dollar strengthens further, FII flows could remain muted.
-
Gold: Down 1.06% to $4,142. Gold’s weakness suggests risk appetite isn’t collapsing, but it’s not surging either. Indian gold stocks (Titan, Kalyan Jewellers) may face mild pressure.
Key levels for Thursday:
- Nifty 50: Support at 22,550 (today’s low was 22,546), then 22,200 (200-DMA zone). Resistance at 22,720 (today’s high) and 22,800 (psychological).
- Bank Nifty: Support at 54,600 (today’s low was 54,636), resistance at 55,350 (today’s high).
- Nifty 500: Support at 21,990, resistance at 22,160.
RBI policy on deck: Indian bond traders are awaiting the RBI’s monetary policy decision. If the central bank holds rates (expected), the market may rally on relief. If it hikes (less likely but possible given oil at $100), expect a knee-jerk sell-off in rate-sensitive sectors (Banks, Realty, Auto).
8. The Honest Take
For long-term investors: Today was noise. The Nifty is down 0.76%, the midcap index is down 0.63% — these are rounding errors in a multi-year wealth creation journey. The World Bank just lifted India’s FY27 growth forecast to 7.1% from 6.6%, citing robust domestic demand. That’s the signal. The noise is crude at $100, rupee at 96.76, and short-term momentum breaks. If you own quality — HDFC Bank, Reliance, TCS, Infosys, Bajaj Finance, Asian Paints — today was a chance to buy more, not panic. If you don’t own quality, today was a reminder to build positions slowly, not chase rallies.
For active traders: Today was a day to respect the technicals and wait for setups. The VIX rose 2.35% — that’s a warning shot. The Nifty couldn’t hold 22,700, and Bank Nifty tested 54,600. Shorts worked in Metals, Realty, and Auto. Longs worked in PSU Banks and select financials (Kotak). Tomorrow’s setup depends on GIFT Nifty at 9:00 AM and the first 15 minutes of trade. If we gap down and hold the lows, it’s a bear trap. If we gap down and make new lows, it’s a trend day to the downside. If we gap up on RBI dovish hopes, fade the move — this market isn’t ready to run yet.
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett