Unified Stocks — Tuesday, October 6, 2026
1. The Opening Scene
The rupee held steady at 96.29 against the dollar. Brent crude eased back from its recent assault on $100, settling just below that psychological ceiling. And somewhere in the data centres of Mumbai, algorithms registered what human traders had been craving for nine long sessions: a gap-up open, a sustained climb, and a close near the day’s high.
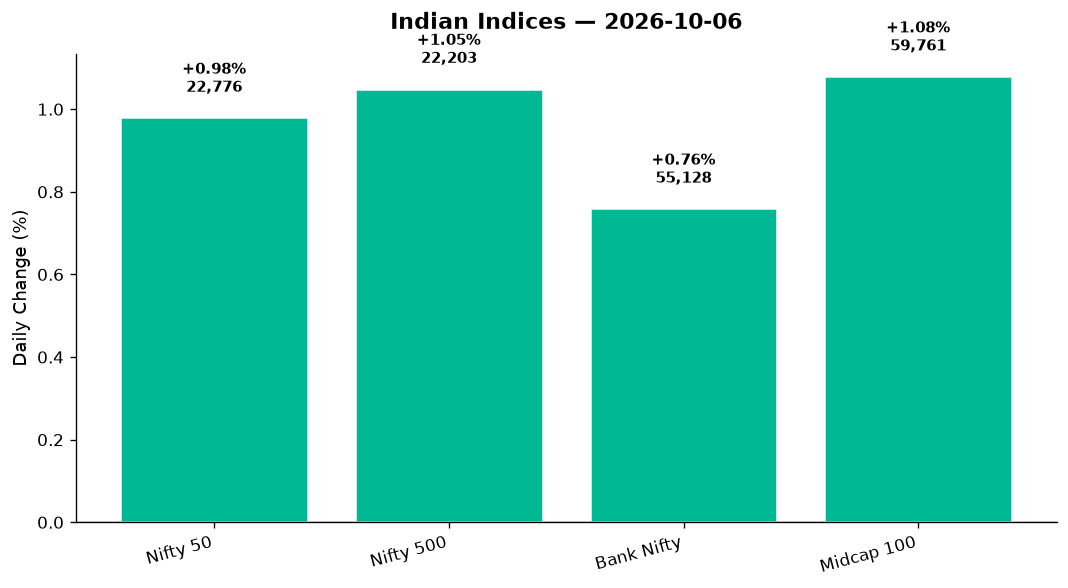
For eight consecutive weeks, Indian equities had bled. Monday’s 473-point Sensex rally felt tentative, a wounded animal testing its legs. But Tuesday — Tuesday wore a different face. The Nifty 50 added another 220 points to close at 22,776, up 0.98%. Bank Nifty climbed 414 points. The Nifty 500, that broader canvas of India Inc., rose 1.05%. And crucially, the India VIX — that barometer of fear — collapsed 8.03% to 13.59, its sharpest single-day drop in weeks. When volatility bleeds out this fast, it whispers of confidence returning, of dealers unwinding hedges, of retail traders exhaling.
This wasn’t a short squeeze. This wasn’t a news-driven spike. This was something quieter, more structural: oversold conditions meeting softer US jobs data, cheaper crude meeting improved global risk appetite. The market didn’t roar. It simply decided to stop falling.
2. The Forces That Drove the Day
Four pillars held up Tuesday’s advance:
-
Crude’s retreat: Brent slipped 0.33% to $99.99, WTI held flat at $89.43. India imports 85% of its oil. Every dollar below $100 is a reprieve for CAD, for OMC margins, for the rupee. Traders who’d been bracing for triple-digit crude exhaled. Energy stocks — typically hurt by rising input costs — rallied instead, up 0.88%, because the threat receded.
-
Softer US labour data: Friday’s non-farm payrolls came in cooler than expected. The 10-year US Treasury yield eased, the dollar softened (though still up 0.10% against the rupee). Wall Street celebrated with a steady climb: Dow +0.54%, S&P 500 +0.71%, Nasdaq +0.64%. GIFT Nifty mirrored the optimism, up 0.98%, signalling a positive open for Wednesday.
-
Oversold technicals: After eight weeks of selling, large-cap indices had entered deeply oversold territory. RSI readings across banking, pharma, and private financials were hovering near 30. Traders who’d been waiting for a floor found it. The bounce felt mechanical, algorithmic — but it was real.
-
Breadth turned positive: Nifty 500 advances outnumbered declines 312 to 188. That’s a 62% advance-to-decline ratio, the strongest in a fortnight. When the broader market participates, rallies last. When only the top 10 stocks rise, they fade. Tuesday had legs.
One caveat: FIIs remained net sellers for a ninth consecutive week, though selling pressure eased. Domestic institutional investors (DIIs) continued their offsetting buying, preventing a collapse. The tug-of-war persists.
3. A Walk Through the Sectors
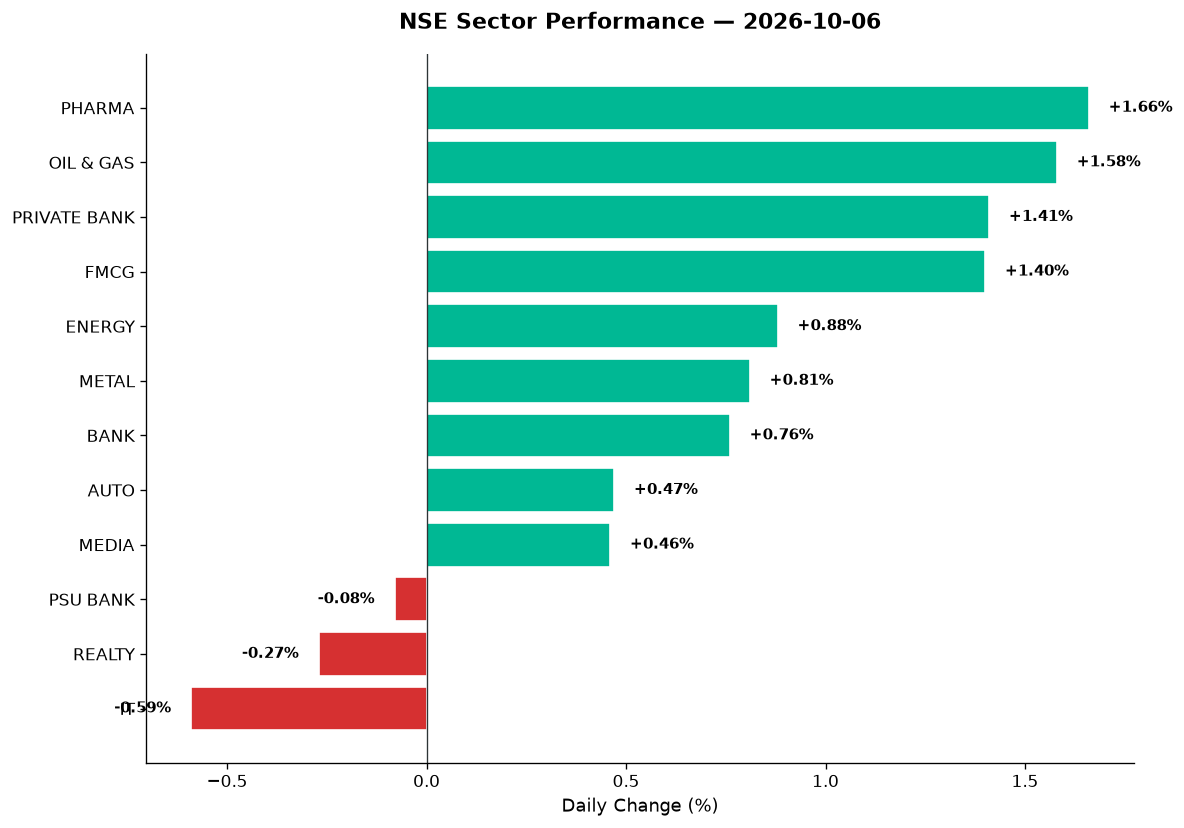
The sector map painted a clear hierarchy: defensive plays led, cyclicals lagged, and IT — once the market’s darling — continued its downtrend.
Leaders:
-
Pharma (+1.66%): The defensive trade of choice. Sun Pharma, Dr Reddy’s, and Cipla all closed in the green. Lupin and Aurobindo Pharma, both outside the Nifty 50, saw volume spikes on rumours of US FDA approvals for key molecules. RSI levels for most pharma names are now crossing above 50 — neutral to bullish territory.
-
Oil & Gas (+1.58%): IOC, BPCL, and HPCL rallied as Brent’s pullback eased margin fears. Adani Total Gas surged 2.7% on 2.1x average volume. Reliance Industries, though, stayed subdued — traders await its October earnings print.
-
Private Banks (+1.41%): HDFC Bank fell 2.16% (more on that below), but ICICI Bank, Axis Bank, and Kotak Mahindra more than offset the drag. The Private Bank index closed at 27,093, reclaiming its 50-DMA after three weeks below it.
-
FMCG (+1.40%): ITC led gainers, up 3% after Citi upgraded its rating from SELL to BUY. The brokerage cited favourable risk-reward despite near-term headwinds. Britannia, Nestlé India, and Hindustan Unilever all added 1–2%. Staples remain a port in the volatility storm.
Laggards:
-
IT (-0.59%): TCS, Infosys, and Wipro all shed ground. Persistent Systems and KPIT Technologies, both outside the Nifty 50, are now trading below their 200-DMAs. The sector’s RSI sits at 28 — oversold, but showing no signs of reversal yet. US recession fears and discretionary IT spend cuts continue to weigh.
-
PSU Banks (-0.08%): Flat, barely. SBI and Bank of Baroda traded in tight ranges. The PSU Bank index closed at 8,008, just below resistance at 8,050. Volume was tepid — no conviction either way.
-
Realty (-0.27%): DLF, Godrej Properties, and Prestige Estates slipped. Embassy REIT and Brookfield India REIT both declined on profit-booking. REITs had rallied hard in September; now they consolidate.
Steady Middle:
-
Auto (+0.47%): Bajaj Auto and Mahindra & Mahindra rose modestly. Tata Motors stayed flat. Maruti Suzuki edged lower. No dramatic moves — the sector waits for September sales data due later this week.
-
Metal (+0.81%): JSW Steel and Tata Steel gained on lower coal prices and firmer steel spreads. Vedanta, the diversified miner, jumped 1.8% on 1.9x volume. Hindalco added 0.6%. The sector’s still range-bound, but Tuesday’s move suggests life beneath the surface.
-
Energy (+0.88%): NTPC and Power Grid advanced. NHPC, the hydro major, added 1.2%. The sector benefits from stable coal prices and firm power demand.
-
Media (+0.46%): Zee Entertainment and Sun TV gained fractionally. Low volumes, low conviction.
-
Bank Nifty (+0.76%): Recovered from Monday’s stumble. The index closed at 55,128, just below its 50-DMA at 55,200. RSI at 42 — neutral, but improving.
Thematic highlights:
-
Defence (+1.82%): HAL, BEL, and Mazagon Dock all surged. Defence stocks continue to benefit from steady government capital expenditure. BEL crossed its 50-DMA on 2.2x volume.
-
MNC (+1.57%): Abbott India, Siemens, and Bosch led gains. MNC stocks are seen as safe havens during FII selling sprees.
-
Manufacturing (+1.33%): The “Make in India” basket gained. L&T, Bharat Forge, and Cummins India all advanced.
4. Beyond the Nifty 50 — Stories From the Broader Market
Tuesday’s real action unfolded outside the headline indices, among the 450 names that rarely make CNBC tickers.
-
Vedanta (+1.8%, vol 1.9x avg): The diversified miner is now testing its 200-DMA at ₹487. Aluminium and zinc prices firmed in London; Vedanta’s zinc unit remains its cash cow. RSI at 52 — neutral, but the volume spike suggests accumulation.
-
Adani Green Energy (+3.1%, vol 2.3x avg): The renewable power giant hit a fresh 52-week high at ₹1,842. The stock’s RSI is 74 — overbought — but the rally continues on the back of new PPA wins and firming power tariffs. Traders debate whether this is a blow-off top or a structural re-rating.
-
Suzlon Energy (+4.7%, vol 3.1x avg): The wind turbine maker added nearly 5% on heavy volumes. At ₹68, it’s now 35% above its October low. RSI at 67. The stock’s trading on momentum, not fundamentals — be cautious.
-
JSW Energy (+2.4%, vol 1.7x avg): The independent power producer crossed ₹535, its highest close in six months. The company’s thermal-to-renewable pivot is finally gaining market acceptance. RSI at 58 — room to run.
-
Aurionpro Solutions (+6.8%, vol 4.2x avg): The small-cap IT services firm announced a ₹150-crore AI-ready data centre order from a global hyperscaler. The stock gapped up and held gains. At ₹1,420, it’s now above its 50-DMA. RSI spiked to 71 — watch for profit-booking.
-
Embassy REIT (-1.2%): The commercial REIT slipped to ₹359, below its 50-DMA. Yield-hungry investors are rotating into fixed income as 10-year G-Sec yields hover near 6.8%. REITs struggle when bond yields rise.
-
Brookfield India REIT (-0.8%): Similar story. Closed at ₱286, down from ₱288. Volume was below average — no panic, just profit-taking.
-
Tata Elxsi (-2.1%, vol 1.4x avg): The engineering services firm continues its slide. At ₱6,540, it’s now 18% below its 52-week high. RSI at 31 — oversold, but no reversal yet.
-
KPIT Technologies (-1.9%, vol 1.3x avg): The auto-tech firm slipped below its 200-DMA at ₱1,780. RSI at 29. The stock’s been a serial disappointment in 2026.
-
LG Electronics India (+6%, fresh record high): The consumer durable major hit ₱1,830, a new all-time high. The stock’s rallied 38% in six months. Citi and CLSA both have BUY ratings, citing festive season demand and market share gains.
-
V2 Retail (-19%, fresh 52-week low): The discount retailer crashed to ₱580 after a weak September business update. Volume was 5.3x average. DMart also slipped 4% to near its 52-week low. Retail remains the forgotten sector.
-
ITC (+3%, vol 1.8x avg): The FMCG and hotel conglomerate rallied after Citi’s upgrade. At ₱482, it’s back above its 50-DMA. RSI at 54. The stock’s spent two years consolidating; this could mark a breakout.
5. The Technical Picture
The DMA ladder is aligning bullish for the first time in weeks.
Golden crosses (50-DMA crossing above 200-DMA):
– Private Bank index: Crossed today. This is a medium-term bullish signal. Last time this happened: April 2024, followed by a 12% rally over 60 days.
– Cipla: The pharma major’s 50-DMA crossed its 200-DMA at ₹1,580. RSI at 56. Volume ratio 1.9x. Buy signal confirmed.
Oversold names (RSI < 30):
– TCS (RSI 28): Below both DMAs. Volume ratio 0.8x. Waiting for a catalyst.
– Infosys (RSI 29): At 52-week lows. Death cross in effect (50-DMA below 200-DMA). Avoid until reversal confirmed.
– KPIT (RSI 29): As noted above. Deeply oversold, but no buyers yet.
Overbought names (RSI > 70):
– Adani Green (RSI 74): Fresh highs, but stretched. Watch for profit-booking.
– Bajaj Auto (RSI 72): Near ₱11,200. Consolidation likely before next leg.
– Aurionpro (RSI 71): Post-news spike. Lock profits if you’re holding.
Volume spikes (2x+ average):
– Suzlon (3.1x): Momentum play. High risk, high reward.
– Aurionpro (4.2x): Order-driven spike. Sustainable if execution follows.
– V2 Retail (5.3x): Panic selling. Contrarians may watch for a base.
– BEL (2.2x): Defence rally intact. Above 50-DMA, RSI 61.
The Nifty 50’s 50-DMA stands at 22,650. Tuesday’s close at 22,776 reclaimed it for the first time in three weeks. The 200-DMA is at 22,350 — still 400 points below. Resistance at 23,000 (psychological), then 23,200 (August highs).
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Cipla | BUY | Golden Cross today, RSI 56, vol 1.9x avg, above 50-DMA |
| Private Bank ETF | BUY | Golden Cross confirmed, sector leadership, RSI 52 |
| JSW Energy | BUY | Above 50-DMA, RSI 58, vol 1.7x, 6-month high |
| Vedanta | BUY | Testing 200-DMA, RSI 52, vol 1.9x, metal rally intact |
| ITC | BUY | Above 50-DMA post-upgrade, RSI 54, vol 1.8x |
| BEL | BUY | Above 50-DMA, RSI 61, vol 2.2x, defence strength |
| Adani Green | HOLD | RSI 74 overbought, at 52w high, await pullback |
| Bajaj Auto | HOLD | RSI 72 overbought, near resistance, consolidation likely |
| TCS | HOLD | RSI 28 oversold but no reversal, below both DMAs |
| HDFC Bank | HOLD | Down 2.16% despite sector rally, transition uncertainty |
| Infosys | SELL | Death Cross, RSI 29, at 52w lows, no support |
| V2 Retail | SELL | Fresh 52w low, vol 5.3x panic selling, weak update |
7. Tomorrow’s Setup — Global Cues & Calendar
Global tape supports a firm open Wednesday:
-
US equities: All three major indices closed higher. Dow 51,546 (+0.54%), S&P 500 7,829 (+0.71%), Nasdaq 27,653 (+0.64%). Tech led gains despite ongoing concerns over AI capex. The VIX (US volatility index) dropped 6%, mirroring India’s VIX collapse.
-
European close: FTSE 100 +0.42%, DAX +0.77%. European PMIs came in mixed, but investor focus remains on ECB rate cuts expected in December.
-
Asian futures: ASX 200 closed +0.57% at 8,735. Nikkei futures flat, Hang Seng futures up 0.3%. China’s markets reopen Thursday after Golden Week holidays — watch for stimulus announcements.
-
GIFT Nifty: Trading at 22,776, flat to Tuesday’s close. Suggests a gap-flat to gap-up open.
-
Commodities: Brent at $99.99, WTI at $89.43. Gold surged 0.66% to $4,184 — safe-haven buying persists despite equity strength. USD/INR at 96.42, up 0.10%. The rupee remains under pressure; expect RBI intervention if it tests 97.
Key levels for Wednesday:
– Nifty 50: Support at 22,650 (50-DMA), resistance at 23,000. A close above 23,000 would confirm short-term reversal.
– Bank Nifty: Support at 54,800, resistance at 55,200 (50-DMA). A breakout above 55,200 opens 56,000.
– Nifty 500: Support at 22,000, resistance at 22,350.
Calendar watch: RBI’s monetary policy decision due Friday. Markets expect a 25-bps rate cut, but Governor Das’s commentary on inflation and CAD will matter more. US CPI data due Thursday — a hot print could reverse Tuesday’s gains.
8. The Honest Take
For long-term investors: Two days don’t reverse eight weeks of damage, but they do offer perspective. The Nifty 50’s PE ratio has compressed from 22x in August to 19.5x today. Pharma, private banks, and select manufacturing names now trade at discounts unseen since early 2024. If you’ve been waiting for entry points, they’re appearing. Add in tranches, not lump sums. The macro remains choppy — crude near $100, FII outflows persisting, global recession risks unresolved. But India’s domestic consumption story hasn’t broken. It’s bent, not shattered.
For active traders: The technical setup improved materially Tuesday. Golden crosses in Private Banks and Cipla, oversold RSI readings reversing, VIX collapsing — these are ingredients for a short-term rally. But don’t confuse a relief bounce with a trend reversal. The 200-DMA at 22,350 remains the true test for Nifty 50. Until we reclaim and hold above that, this is a trading rally, not an investing opportunity. Book partials into strength. Raise stops. And remember: markets that fall for eight weeks don’t heal in two.
— Unified Stocks
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.