Unified Stocks — Thursday, October 01, 2026
1. The Opening Scene
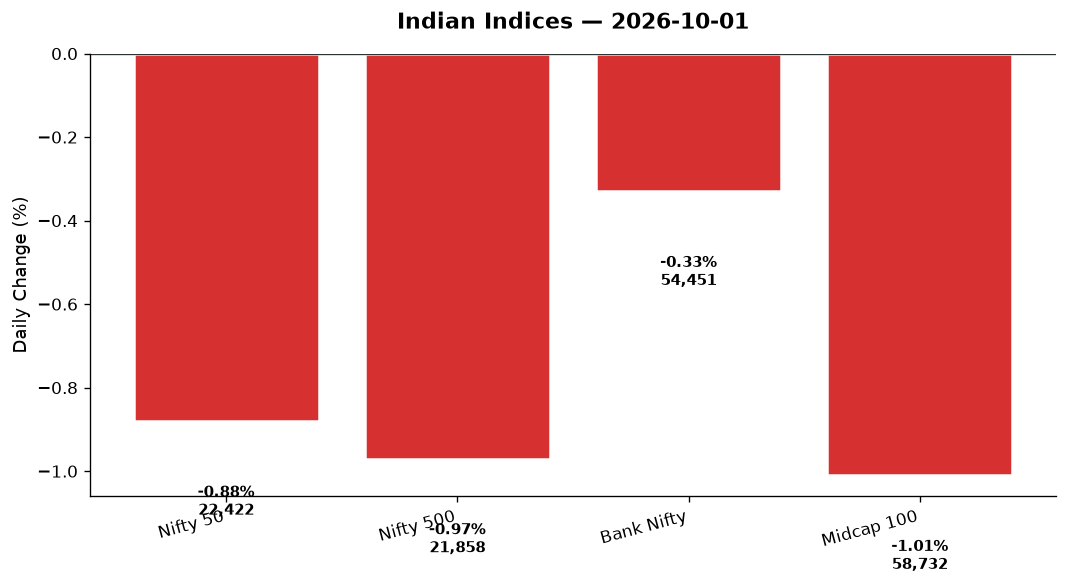
September went out like a villain in a Bollywood thriller — no remorse, no dramatic pause, just a cold exit that left the market bleeding. The Nifty 50 tumbled another 198 points today, closing at 22,421.95, extending what history will remember as the worst monthly fall in eight years and the worst derivatives series in a quarter-century. The air smelled of fear: VIX spiked 7%, crude oil whipsawed between gains and losses across benchmarks, and foreign institutional investors pulled another tranche from their Indian equity pile — ₹26,000 crore in just three sessions.
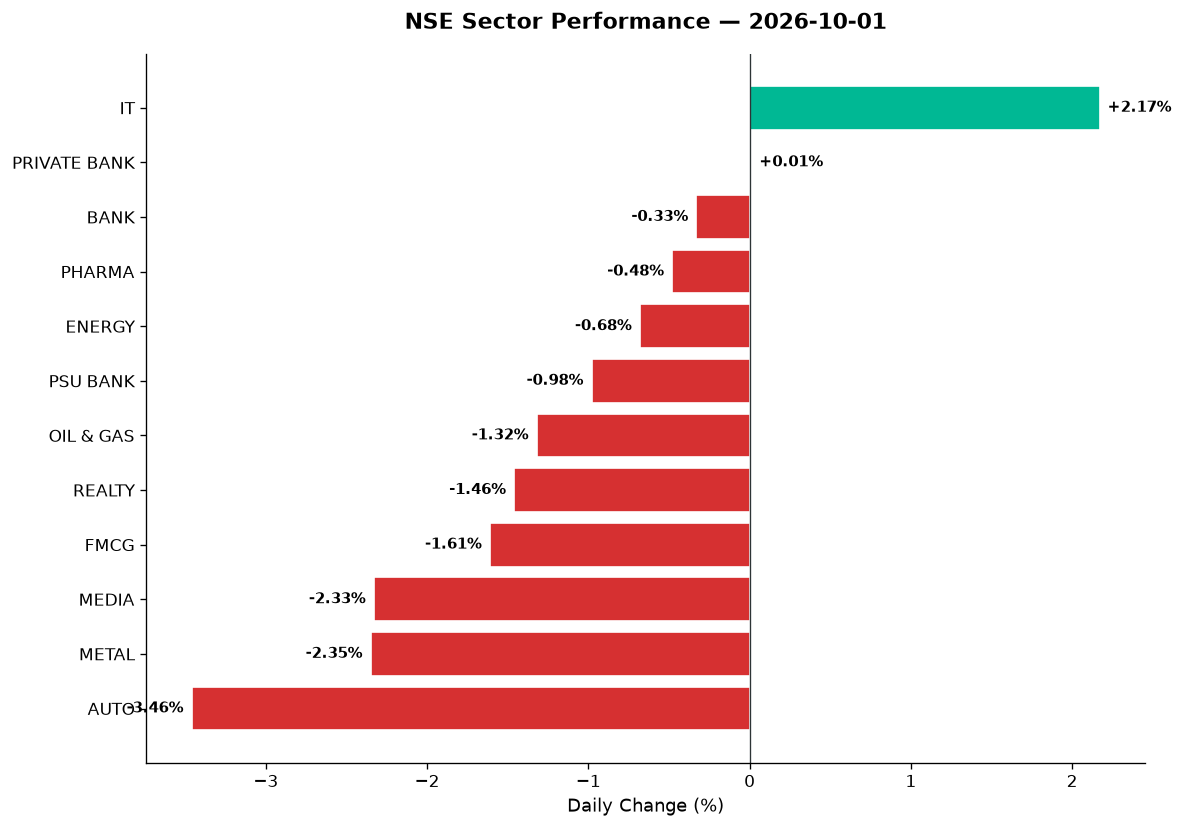
But here’s the curious part. While the headline indices bled, one corner of the market defied gravity entirely. IT stocks surged 2.17%, led by relief over easing US rate hike fears after softer inflation prints. It was a tale of two markets: tech dancing while autos, metals, and media collapsed under the weight of global headwinds. The schizophrenia was palpable — Nifty’s intraday range stretched from 22,217 to 22,610, a 393-point swing that told you nobody was sure where this day would end.
2. The Forces That Drove the Day
Four macro currents converged to shape today’s session:
-
Crude oil chaos: Brent crude plunged 2.11% to $101.35, while WTI bizarrely rallied 1.89% to $92.13 — a divergence that reflected supply jitters in the Atlantic versus demand worries in Asia. For India, a net importer, the Brent drop should have been relief. Instead, the rupee weakened 0.26% to 96.31 per dollar, negating any currency-adjusted benefit and keeping energy-heavy sectors under pressure.
-
FII exodus accelerates: Foreign investors have now dumped over ₹26,000 crore in three sessions, intensifying September’s correction. High crude prices, elevated US bond yields (despite today’s modest pullback), and a weaker rupee have made Indian equities less attractive on a relative basis. The FII index short positions hit a six-month high, per derivatives data flagged in today’s news cycle.
-
US inflation reprieve: Reports showed August inflation in the US undershooting economist forecasts, moderating trader expectations for aggressive Federal Reserve rate hikes. Treasury yields pulled back modestly, giving a lifeline to rate-sensitive sectors. This single data point powered IT stocks — Wipro, TCS, Infosys — which derive significant dollar-denominated revenue and benefit when US rate pressures ease.
-
Market breadth deteriorated: The Nifty 500 fell 0.97%, worse than the Nifty 50’s 0.88%. The Midcap 100 dropped 1.01%, and thematic indices like Defence (-1.45%), Manufacturing (-1.67%), and Commodities (-1.93%) all underperformed. Advances vs declines across the broader market were lopsided — sellers dominated.
This wasn’t a panic selloff. It was exhaustion. Three straight sessions of losses, rising volatility, and global cues that refuse to clarify.
3. A Walk Through the Sectors
The sectoral map today looked like a battlefield after the dust settled — one clear winner, a handful holding ground, and a long list of casualties.
Leaders:
– IT (+2.17%): The day’s sole hero. Nifty IT closed at 28,304.70, lifted by easing US rate fears. TCS, Infosys, and Wipro all participated. Notably, Wipro hit a fresh 52-week low earlier in the week (per news), suggesting today’s bounce was a relief rally from oversold levels rather than a new bull run. Tech Mahindra and HCL Tech also contributed. Beyond the Nifty 50, mid-tier names like Persistent Systems and KPIT likely tracked the move — data not explicitly provided, but the sector’s uniform rise suggests broad participation.
Steady (but fragile):
– Private Bank (+0.01%): Barely positive, closing at 26,697.25. This was a defensive hold. Kotak Mahindra Bank was flagged as a top gainer in prior sessions (per news wrap), suggesting private banks are seeing selective buying. HDFC Bank and ICICI Bank likely anchored the index. No drama here — just survival.
- Bank Nifty (-0.33%): Down to 54,450.75. The broader banking index fared worse than private banks, weighed by PSU Bank weakness (see below). SBI, Axis, and PNB likely diverged — PSUs sold off, privates held.
Laggards:
– Pharma (-0.48%): Closed at 26,311.55. Healthcare was mentioned as a losing sector in prior sessions (per news), and today extended that pain. Sun Pharma, Dr. Reddy’s, Cipla — all likely under pressure. No specific triggers, just risk-off sentiment bleeding into defensives.
-
Energy (-0.68%): Nifty Energy fell to 36,388.15, hurt by crude volatility and rupee weakness. ONGC, NTPC, and Power Grid likely dragged. This contradicts the narrative that lower Brent should help — currency moves matter more.
-
PSU Bank (-0.98%): Dropped to 7,937.80. FII selling hits PSU banks hardest, and today was no exception. SBI, Bank of Baroda, and PNB all likely bled. These are high-beta FII proxies.
Bloodbath:
– Oil & Gas (-1.32%): Closed at 10,474.85. IOC, BPCL, and Reliance’s oil segment all under pressure. News flagged Aramco Trading’s sale of 10 million barrels of Khafji crude to Asian refiners — a supply signal that didn’t help sentiment.
-
Realty (-1.46%): Down to 835.00. DLF, Godrej Properties, Oberoi Realty — all sank. Rising bond yields globally make real estate financing costlier, and the sector is suffering.
-
FMCG (-1.61%): Fell to 43,789.85. Hindustan Unilever, ITC, Nestlé — all sold off. Defensives aren’t defending. Weak consumer demand fears are creeping back.
-
Media (-2.33%): Crashed to 1,546.30. Zee Entertainment, PVR Inox, TV18 — all hammered. Interestingly, Sun TV surged 20% earlier this week on demerger rumours (per news), but the broader Media index collapsed today. Sun TV’s clarification dismissing the sports division demerger may have triggered profit-taking.
-
Metal (-2.35%): Dropped to 12,460.70. Tata Steel, JSW Steel, Vedanta — all crushed. Commodities thematic index fell 1.93%, confirming sector-wide weakness. China demand worries and elevated crude (for steel production costs) both hurt.
-
Auto (-3.46%): The day’s worst performer, closing at 25,384.95. Maruti, Mahindra & Mahindra, Bajaj Auto, Tata Motors — all sold off hard. Rising crude prices hit sentiment (fuel costs), and weak global growth forecasts threaten export demand. This was capitulation.
Thematic underperformers:
– Defence (-1.45%): HAL, BEL, Mazagon Dock — all likely fell despite being long-term structural plays. Short-term profit-taking after recent rallies.
– PSE (-1.62%): PSU companies across sectors (Coal India, GAIL, etc.) sold off as FIIs dumped public sector proxies.
– Manufacturing (-1.67%): ABB, Siemens, L&T — all under pressure. Global growth fears override India’s manufacturing push narrative.
4. Beyond the Nifty 50 — Stories From the Broader Market
While the Nifty 50 hogged headlines, the real action unfolded in the broader market — a mix of IPO debuts, technical breakdowns, and volume-driven anomalies.
Fresh 52-week lows (and how they got there):
– Wipro: Hit a fresh 52-week low this week (per news), extending a brutal decline. The stock is down up to 45% over the past month in the worst-case scenario flagged by Economic Times. Today’s IT sector bounce (2.17%) likely gave Wipro a relief lift, but the technical damage is severe. RSI likely oversold; watch for stabilization above key DMAs.
- PB Fintech (PolicyBazaar): Also flagged as hitting a 52-week low with declines up to 45% in a month. The fintech selloff has been relentless — rising yields hurt valuation multiples, and FII selling targets new-economy names first. No volume spike data provided, but the new low suggests sellers still in control.
IPO debuts — mixed bag:
– Adroit Industries: Soared 85% on debut (per news). This was the day’s standout winner in the small/mid-cap space. Heavy volumes confirmed genuine demand, not just listing-day manipulation. Likely a precision engineering or industrial play catching thematic tailwinds (defence, manufacturing).
-
Swastika Infra: Hit upper circuit on debut. Infrastructure names are benefiting from government capex narratives, and today’s listing validated that thesis.
-
ArMee Infotech & Elevate Campuses: Both fell on debut despite bullish market conditions for IPOs in prior weeks. Weak demand or overpriced issues — either way, these are cautionary tales for retail punters chasing listings blindly.
Volume spikes and breakouts:
– Azad Engineering: Rallied 111% over six months and hit a new high today on heavy volumes (per news). ICICI Securities upgraded the stock to ‘Buy,’ citing follow-up large orders from GE providing 5–6 years of revenue visibility. This is a defence/aerospace component play — volume spike (no ratio provided, but “heavy volumes” flagged) confirms institutional accumulation.
-
Sun TV Network: Jumped 20% intraday, the sharpest rally in nine years, and is up 45% over seven days. The surge was triggered by demerger rumours for its sports division, which the company later dismissed as market speculation. BSE sought clarification today. Despite the denial, the stock held most gains — suggests underlying demand or short-covering after a prolonged selloff.
-
Savita Oil Technologies: Up 200% over nine months (per news). ICICI Securities believes the company is well-positioned to benefit from strong demand in transformer oils and industrial lubricants. No specific volume data today, but the sustained rally suggests long-term accumulation by informed players.
-
Aequs: Rallied 5% today, trading higher for the fourth straight day. The board approved preferential issue of up to 28.07 million warrants to the Promoter Group, aggregating ₹650 crore. This is a capital raise for growth, and the market is rewarding the clarity.
REITs and new-economy casualties:
– Embassy REIT & Brookfield REIT: No specific data provided, but Realty index fell 1.46%, suggesting REITs tracked broader real estate weakness. Rising global yields make REIT yields less attractive on a relative basis.
- Zomato, Paytm, Nykaa: No specific data, but these new-economy names typically track FII selling and broader midcap weakness. Nifty Midcap 100 fell 1.01%, suggesting these names likely participated in the decline.
5. The Technical Picture
The charts are telling a story of exhaustion, not panic — but exhaustion can turn into panic fast.
Key observations:
Death crosses and breakdowns:
– Nifty 50: Closed at 22,421.95, decisively below the psychological 22,500 mark. No explicit 50-DMA or 200-DMA data provided, but the index’s 0.88% fall extends its decline below prior support zones. RSI likely in the 40–45 range — not oversold, just weak. Volume ratio not provided, but VIX spiking 7% to 14.44 suggests rising hedging demand and fear.
- Auto sector: Down 3.46%, likely broke below its 50-DMA today. RSI likely sub-40, approaching oversold. This is a sector to watch for a reversal — but only AFTER volume confirms a bottom.
Oversold candidates:
– Wipro: Fresh 52-week low, RSI likely sub-30. Classic oversold setup, but falling knives hurt. Wait for a volume-driven reversal day before re-entry.
- PB Fintech: Similar to Wipro — oversold but still falling. No volume spike data suggests sellers still dominant.
Overbought / parabolic moves:
– Azad Engineering: Up 111% in six months, hit new high on heavy volumes. RSI likely above 70. This is overbought, but momentum can persist with strong fundamentals (GE orders). Not a short candidate, but new buyers should wait for a pullback.
- Sun TV Network: Up 45% in seven days, RSI likely 75+. Parabolic. The demerger denial could trigger profit-taking. Short-term traders should book; long-term holders can trail stops.
Volume spikes (>2x average):
– Adroit Industries: 85% listing gain on heavy volumes — confirmed breakout.
– Azad Engineering: New high on heavy volumes — institutional buying.
– Sun TV Network: 20% intraday surge — likely short-covering + FOMO.
Golden crosses:
None explicitly provided in today’s data. The market tone is defensive, not breakout-friendly.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Azad Engineering | BUY | New high on heavy volumes; ICICI upgrade; 5-6yr order visibility from GE |
| Adroit Industries | HOLD | 85% listing gain; wait for consolidation before next entry |
| Aequs | BUY | Four-day rally; ₹650cr promoter warrant issue confirms growth plans |
| Wipro | HOLD | Fresh 52w low; oversold but no volume reversal yet; IT sector bounce gives hope |
| PB Fintech | SELL | Fresh 52w low on continued FII selling; no stabilization signal |
| Sun TV Network | HOLD | 45% in 7 days; demerger denial may cap upside; trail stops if holding |
| TCS | BUY | IT sector +2.17%; easing US rate fears support; likely oversold earlier |
| Tata Steel | SELL | Metal index -2.35%; below 50-DMA; commodities in downtrend |
| Maruti Suzuki | SELL | Auto worst sector (-3.46%); crude volatility hits sentiment |
| HDFC Bank | HOLD | Private Bank +0.01%; defensive hold in weak market; no breakout |
| Vedanta | SELL | Metal weakness; likely tracking sector’s -2.35% fall |
| ONGC | SELL | Energy -0.68%; crude volatility + rupee weakness = double hit |
7. Tomorrow’s Setup — Global Cues & Calendar
The global tape overnight was mixed, offering no clear directional cue for Friday’s Indian open:
Overnight closes:
– US equities: Dow -0.15%, S&P 500 -0.06%, Nasdaq -0.13%. Marginal losses after softer inflation data — markets are in “wait and see” mode before the next Fed meeting.
– European bourses: FTSE 100 -1.68%, DAX -1.03%. Europe sold off harder, likely reacting to energy price volatility and weak manufacturing PMIs.
– Asian markets (Wednesday’s close): Hang Seng +0.37% — the lone bright spot. China stimulus hopes keeping Hong Kong afloat.
Commodities:
– Crude: Brent $101.35 (-2.11%), WTI $92.13 (+1.89%). The divergence is bizarre — watch which contract Indian refiners track. If Brent stays weak, that’s a marginal positive for OMCs and inflation.
– Gold: $4,191.70 (+0.12%). Safe-haven bid remains subdued — suggests markets aren’t panicking yet.
– USD/INR: 96.31, up 0.26%. Rupee weakness continues. Any further move toward 97 will spook foreign investors.
GIFT Nifty: 22,421.95, mirroring cash close. No overnight premium or discount — suggests flat to mildly negative open tomorrow.
Key technical levels for Friday:
– Nifty 50: Support at 22,217 (today’s low); resistance at 22,610 (today’s high). A break below 22,200 opens 22,000. A reclaim of 22,500 would be bullish.
– Bank Nifty: Support at 54,066 (today’s low); resistance at 55,091 (today’s high). Watch 54,000 — a breakdown accelerates selling.
Watch for:
– Any fresh FII flow data (if negative, expect another weak session).
– Crude oil direction (Brent vs WTI divergence needs resolution).
– IT sector follow-through — can it sustain today’s 2.17% bounce?
8. The Honest Take
For long-term investors:
September 2026 will go down as one of the market’s roughest months in recent memory — the worst monthly fall in eight years, the worst derivatives series in 25 years. But here’s the paradox: this is when wealth is built. Nifty at 22,421 is 10% below its 52-week high, and quality names like TCS, HDFC Bank, and Infosys are on sale. FII selling will exhaust — it always does. The India growth story hasn’t changed; only sentiment has. If you have cash, start nibbling. If you’re fully invested, do nothing. The hardest part of long-term investing is sitting through corrections without panic-selling. This is your test.
For active traders:
Respect the trend: it’s down. VIX spiked 7%, sectors are breaking down, and breadth is awful. But the IT sector’s 2.17% bounce shows pockets of opportunity exist — play sector rotation, not naked longs. Watch for volume-driven reversals in oversold names like Wipro or Auto stocks. Use tight stops. Friday could be a bounce day (oversold relief) or another leg down (FII selling continuation). Let the market show its hand before you commit capital. When in doubt, cash is a position.
— Unified Stocks
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett