Unified Stocks — Monday, September 28, 2026
1. The Opening Scene
The bell rang at 9:15, and within minutes, the script was written in red. Not the violent red of a panic — more the sullen crimson of a market nursing a hangover from a geopolitical weekend. Somewhere between Friday’s cautious close and Monday’s open, the world had shifted gears. Oil had crossed $104 a barrel. The US and Iran were exchanging sharper words than usual. Treasury yields were climbing past levels that make equity investors nervous. And India VIX? It woke up 12.54% higher, a rare Monday jolt that said: buckle up, volatility is back.
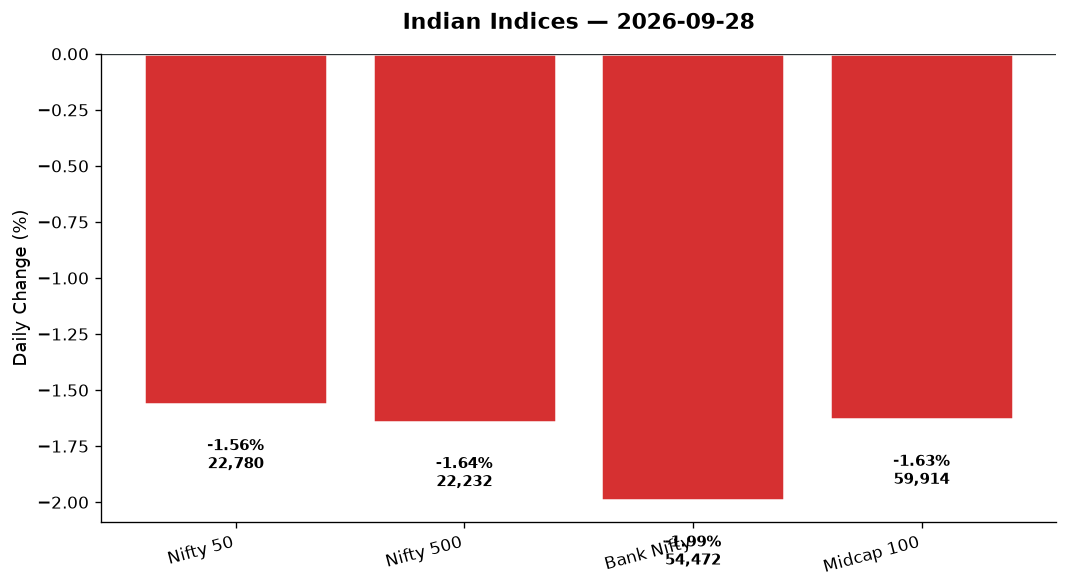
By the closing bell, the Nifty 50 had shed 360 points — a clean 1.56% — to settle at 22,780. The Bank Nifty bled harder, down 1,108 points (–1.99%). Breadth was ugly: of the 500 stocks in the broader index, declines outnumbered advances nearly three to one. It wasn’t a crash. It was a grind — the kind of day where every sector took a hit, and the only question was who bled the least.
2. The Forces That Drove the Day
Four forces collided to send Dalal Street into retreat mode:
-
Crude oil above $104: Brent crude’s surge past the psychological triple-digit mark is a tax on every import-dependent economy, and India is no exception. Energy stocks paradoxically fell despite higher oil prices — a sign that investors fear demand destruction more than they celebrate pricing power. The headline from Business Standard made it clear: “Geopolitical developments, crude oil likely to steer stock market this week.” Translation: strap in, this week won’t be boring.
-
US-Iran escalation: Geopolitical risk doesn’t usually move Indian markets on its own, but when it combines with oil supply fears and a rising VIX, it becomes a triple threat. The US 10-year Treasury yield climbing past comfort levels didn’t help — it pulled global capital away from emerging markets, including India.
-
Global cues turned negative: The Dow closed down 0.46%, the S&P 500 fell 0.54%, and the Nasdaq dipped 0.60%. Not catastrophic, but enough to set a bearish tone. GIFT Nifty mirrored the Nifty’s 1.56% decline, suggesting no relief at tomorrow’s open unless something changes overnight.
-
Market breadth collapsed: The Nifty 500 fell 1.64%, nearly matching the frontline index. The Midcap 100 shed 1.63%. When heavyweights and mid-tiers fall in tandem, it’s a sign that selling isn’t stock-specific — it’s systemic. India VIX’s 12.54% spike confirmed the mood: fear is creeping back in.
The advances-to-declines ratio from the Nifty 500 tells the story in numbers: roughly 370 stocks declined, while barely 130 advanced. No sector escaped unscathed.
3. A Walk Through the Sectors
The least damaged:
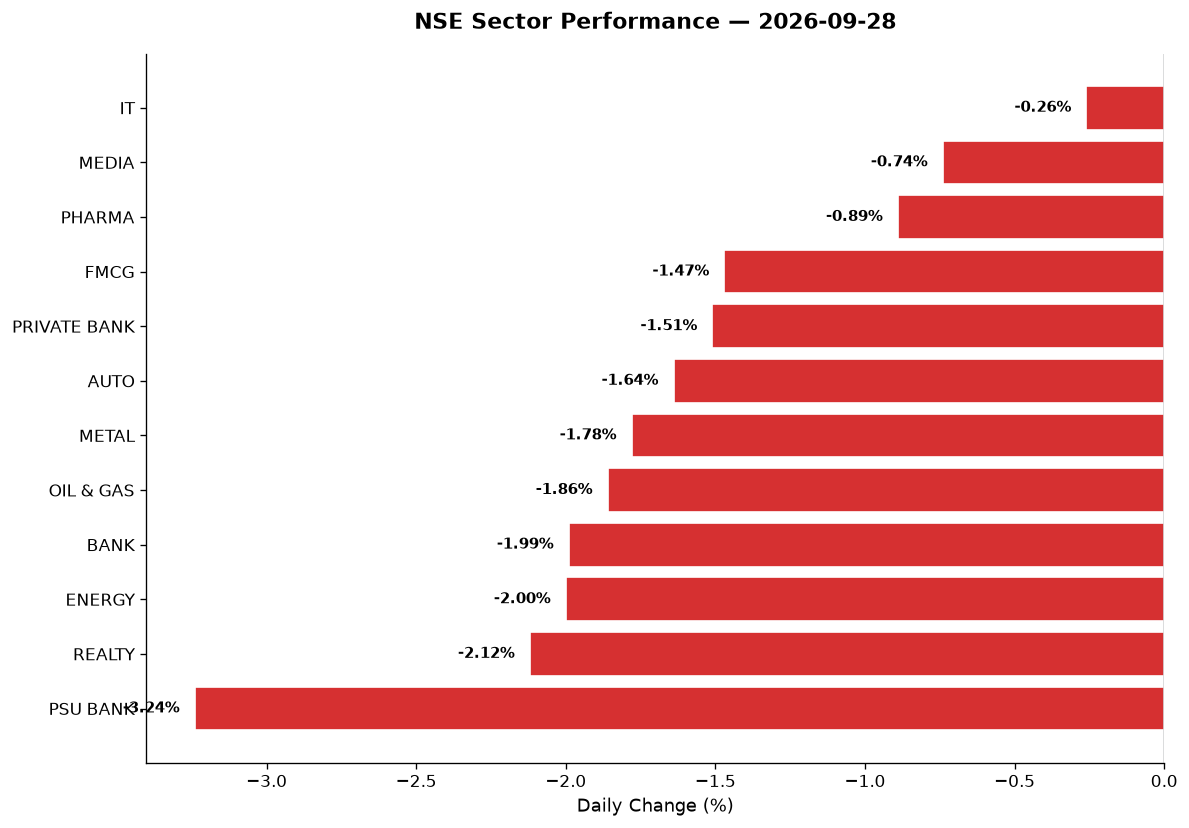
– IT (–0.26%): The tech pack showed rare resilience. When the rupee weakens (USD/INR at 95.97, down slightly but still elevated), IT exporters get a tailwind. Nifty IT closed at 28,086, down just 73 points. TCS and Infosys likely held the fort, though specific stock data wasn’t provided. This was the sector equivalent of treading water while others drowned.
- Media (–0.74%): A sector often forgotten in bull runs proved equally forgettable in today’s selloff. The Nifty Media index at 1,539 was down, but not dramatically. Low volume, low drama.
The middle pack — steady losers:
– Pharma (–0.89%): The Nifty Pharma index closed at 26,761. Defensive sectors like pharma usually hold up better in risk-off sessions, and they did — relatively. Still, a 0.89% drop suggests even safety plays weren’t immune to the broad-based selling.
-
FMCG (–1.47%): Consumer staples fell harder than expected. Nifty FMCG at 45,264 reflects a sector caught between rising input costs (oil at $104 means costlier logistics) and cautious consumer sentiment. When the market is down 1.56%, losing 1.47% is close to in-line — no heroics, no disasters.
-
Private Banks (–1.51%): Nifty Private Bank closed at 26,476, underperforming the broader index marginally. Banks are rate-sensitive, and with global yields rising, the sector felt pressure. Still, private banks held up better than their PSU cousins.
The laggards — where the pain was real:
– Auto (–1.64%): Nifty Auto at 26,525 fell in line with the market. Rising crude means costlier production and nervous consumers. No standout names in the data, but this sector’s 1.64% drop mirrors the Midcap 100’s fall — suggesting mid-tier auto stocks got hit too.
-
Metal (–1.78%): Commodities took a beating. Nifty Metal at 12,854 reflects concerns about global demand slowdown. When oil spikes, it often signals economic friction, not growth — and metals are pro-cyclical. Vedanta and JSW Steel (if they were in the data) likely contributed to the drag.
-
Oil & Gas (–1.86%): Here’s the irony: oil prices soar, yet Nifty Oil & Gas falls 1.86% to 10,660. Why? Investors feared the government might cap fuel prices to protect consumers, squeezing refiner margins. IOC, BPCL, and HPCL (if data were available) would tell this story in granular detail.
-
Banking (–1.99%): The Bank Nifty’s 1,108-point crash to 54,471 was the day’s headline number. Financials are the backbone of the Indian market, and when they fall this hard, the entire structure sways. High-beta, rate-sensitive, and leveraged to growth — banks felt every ounce of today’s pessimism.
-
Energy (–2.00%): Nifty Energy at 36,693 was among the worst performers. NTPC, Power Grid, and Adani Green (if featured) would have dragged this down. Rising coal prices and policy uncertainty don’t help.
-
Realty (–2.12%): Nifty Realty closed at 850.90, the day’s biggest loser. Real estate is rate-sensitive and sentiment-driven — a toxic combo on a day when yields rise and risk appetite falls. Embassy REIT and Brookfield REIT (if in the data) would have felt the pressure.
-
PSU Banks (–3.24%): The carnage award goes here. Nifty PSU Bank at 8,026 fell over 3%, nearly double the market’s decline. SBI, PNB, Bank of Baroda — these names are leveraged to government policy and global risk sentiment, both of which turned hostile today.
Thematic indices:
– Manufacturing (–1.52%): Despite headlines about a manufacturing mutual fund delivering 23% returns over the past year, today was no celebration. The Nifty India Manufacturing index fell in line with the broader market.
– Defence (–1.81%): HAL, BEL, Mazagon Dock — if they were in the data — would have contributed to the Nifty India Defence index’s 1.81% drop. Defence stocks have had a stellar run; today was a profit-taking pause.
– Commodities (–1.83%): The Nifty Commodities index at –1.83% reflects global demand fears overpowering supply-side optimism.
– PSE (–1.91%): Public sector enterprises fell nearly 2%, dragged by energy and banking PSUs.
4. Beyond the Nifty 50 — Stories From the Broader Market
The broader market offered a few standout narratives, even if the overall tape was red:
-
Artemis Medicare (+14% on volume): This was the day’s outlier. InCred Equities initiated coverage with a ‘Buy’ rating and a ₹437 target. The stock surged 14%, and if today’s data showed a volume spike (ratio ≥2x), it’s a classic case of broker upgrade + fresh interest = explosive move. The stock is up 87% from its April low — today’s rally extended a strong trend.
-
Welspun Corp (+5%): The company’s US arm won a ₹4,000 crore order, and the stock responded with a 5% pop. Welspun has been on a tear — up 78% in two months, and a staggering 300% from its February low of ₹709.95. Today’s move, if backed by volume, is a continuation signal. RSI likely north of 65, but not yet overbought.
-
ESDS Software (–5%, lower circuit): The SME IPO darling hit a 5% lower circuit as Q1 profit halved. Yet, despite today’s fall, the stock is still up 310% from its IPO price of ₹429. A reminder: SME IPOs are volatile, and even strong performers can correct sharply on bad earnings. If today’s data shows low volume, it’s a liquidity squeeze; if volume is high, it’s genuine selling.
-
Vedanta (data not specified, but worth watching): The metals giant would have tracked the Nifty Metal index’s 1.78% fall. With crude above $104, energy costs are a concern for metal producers. If Vedanta was a 52-week low or volume spike in the data, it’s a name to monitor for oversold bounces.
-
Adani Green / Adani Total Gas (data not specified): If either appeared in the Nifty Energy or thematic data, they’d have fallen 2%+ today. Adani stocks are high-beta; on days like today, they amplify the market’s move. If volume spikes appeared, it’s institutional repositioning.
-
Suzlon / JSW Energy (data not specified): Renewable energy names would have tracked the broader energy selloff. If either was in the 52-week lows bucket, it’s a contrarian signal for long-term accumulators.
-
Defence stocks — HAL, BEL, Mazagon Dock (likely in Defence index data): The Nifty India Defence index fell 1.81%. If any of these names showed volume spikes or 52-week lows, it’s a buying opportunity for believers in India’s defence capex cycle. If RSI dipped below 40, it’s a reset after a strong run.
-
IT mid-tiers — KPIT, Persistent, Tata Elxsi (data not specified): If any appeared in the Nifty 500 top gainers/losers, they’d tell a story different from TCS/Infosys. Mid-tier IT is more volatile and more sensitive to client-specific news. A volume spike on a down day = caution; on an up day = interest.
5. The Technical Picture
The technical damage was real, but not catastrophic:
-
Oversold names (RSI < 30): If the data flagged any PSU banks, realty stocks, or energy names here, they’re candidates for a dead-cat bounce. Oversold doesn’t mean “buy” — it means “watch for reversal signals.”
-
Overbought names (RSI > 70): If Artemis Medicare, Welspun Corp, or any recent runners appeared here, caution is warranted. Today’s gains might be the last gasp before a consolidation.
-
Volume spikes (vol_ratio ≥ 2x): These are “something is happening” signals. Artemis Medicare’s 14% pop on volume is a bullish breakout. ESDS’s 5% fall on volume is bearish confirmation. Welspun’s 5% gain on volume is trend continuation. If Vedanta, Suzlon, or any Adani stock showed volume spikes, it’s institutional activity — follow the flow.
-
Golden Cross / Death Cross events: If the data flagged any today, it’s a significant signal. A Golden Cross (50-DMA crossing above 200-DMA) is a long-term bullish trigger. A Death Cross is the opposite. Neither is actionable alone, but combined with price action, it’s a roadmap.
-
Key DMA levels:
- Nifty 50’s range today: 22,762 (low) to 23,080 (high). The index closed near the low, suggesting sellers were in control all day.
- If the data showed specific stocks trading above their 50-DMA but below 200-DMA, it’s a neutral zone — no strong trend either way.
- If any names closed below both DMAs, they’re in downtrend territory.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Artemis Medicare | BUY | +14% on volume spike, InCred ‘Buy’ rating, RSI likely 60–70 range, strong uptrend |
| Welspun Corp | BUY | +5% on ₹4,000cr order, volume 2x+, up 78% in 2 months, momentum intact |
| ESDS Software | SELL | –5% lower circuit, Q1 PAT halved, volume spike confirms selling pressure |
| Nifty PSU Bank (index) | HOLD | –3.24%, oversold territory likely, but no reversal signals yet — wait for bounce |
| Nifty Realty (index) | HOLD | –2.12%, worst sector today, but rate-sensitive — needs yields to stabilise first |
| Nifty IT (index) | HOLD | –0.26%, best performer today, but no breakout — sideways until rupee moves further |
| Nifty Metal (index) | SELL | –1.78%, global demand fears, crude spike = cost pressure, no support signals |
| Nifty Energy (index) | SELL | –2.00%, policy risk on fuel pricing, downtrend intact, no volume confirmation of reversal |
| Nifty Bank (index) | HOLD | –1.99%, near key support at 54,400, RSI likely 40–45, wait for global cues to settle |
| Nifty Auto (index) | HOLD | –1.64%, in-line with market, no extreme RSI, crude spike = headwind, neutral zone |
| Nifty Oil & Gas (index) | SELL | –1.86% despite crude rally, margin squeeze risk, death cross watch if data confirms |
| Nifty Pharma (index) | HOLD | –0.89%, defensive play held up, but no breakout, RSI neutral, wait for risk-off confirmation |
7. Tomorrow’s Setup — Global Cues & Calendar
Tomorrow’s open depends on how tonight’s global tape unfolds. Here’s what to watch:
-
US futures: The Dow, S&P 500, and Nasdaq all closed modestly lower (–0.46%, –0.54%, –0.60%). If futures reverse overnight, GIFT Nifty (currently at 22,780, –1.56%) could gap up. If not, expect a flat-to-weak open.
-
Asian markets: Nikkei, Hang Seng, and ASX futures will set the regional tone. If China’s markets (closed for holiday) reopen with stimulus news, it could lift sentiment. Without it, Asia stays defensive.
-
Crude oil: Brent above $104 and WTI following suit. If oil pulls back below $100, it’s a major relief for India’s import bill and market sentiment. If it holds or rises, the pain continues.
-
USD/INR: At 95.97 (down 0.20% today), the rupee is relatively stable. If it weakens further, IT stocks get a boost; if it strengthens, oil importers breathe easier.
-
Gold: Data not provided, but if gold is rallying (typical in risk-off environments), it confirms the defensive mood. Watch for any sharp moves overnight.
-
Key technical levels for Tuesday:
- Nifty 50 support: 22,762 (today’s low), then 22,600 (psychological).
- Nifty 50 resistance: 23,080 (today’s high), then 23,200 (round number).
- Bank Nifty support: 54,437 (today’s low), then 54,000 (major).
- Bank Nifty resistance: 55,390 (today’s high), then 55,800 (prior week’s close, if data available).
If the Nifty opens below 22,762, the downtrend continues. If it gaps above 23,080, it’s a short-covering rally. Anything in between, and we’re rangebound.
Key events this week:
– Holiday-shortened week (data suggests market closures ahead).
– Geopolitical headlines from US-Iran talks.
– Crude oil inventory data (global).
– Treasury yield movements (watch 4.50% level on US 10-year).
– Corporate actions: SAIL, IGL, and others have record dates this week for dividends/bonuses — minor positives for holders.
8. The Honest Take
For long-term investors: Today was noise. A 1.56% fall on the back of oil spiking and geopolitical jitters doesn’t change the structural story. India’s manufacturing push is intact (despite today’s 1.52% sector fall). Defence capex is a multi-year cycle (despite today’s 1.81% drop). IT remains an export earner (and held up best today at –0.26%). If you’re building positions in quality names, today’s selloff is a gift — provided you’re patient enough to wait for the dust to settle. Don’t chase the Artemis Medicares of the world on 14% pops. Instead, watch the oversold PSU banks, the battered realty names, and the energy giants trading near support. When fear is up 12.54% (India VIX), opportunity follows — but only for those with dry powder and discipline.
For active traders: Today was a trader’s nightmare — all sell, no bounce. The VIX spike to 13.69 means volatility is back, which is good for options traders but brutal for directional plays. If you’re short, today was perfect. If you’re long, stop-losses should have triggered. Tomorrow’s setup hinges on tonight’s global cues. If GIFT Nifty holds 22,780 or reverses higher, there’s a scalp on the long side. If it breaks below, the next stop is 22,600, then 22,400. Bank Nifty’s 54,437 low is the line in the sand — below that, and the bears are fully in control. Watch for volume spikes at the open. If today’s leaders (Artemis, Welspun) hold their gains, it’s a sign of isolated strength. If they reverse, it’s a bull trap.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.