Unified Stocks — Wednesday, September 23, 2026
1. The Opening Scene
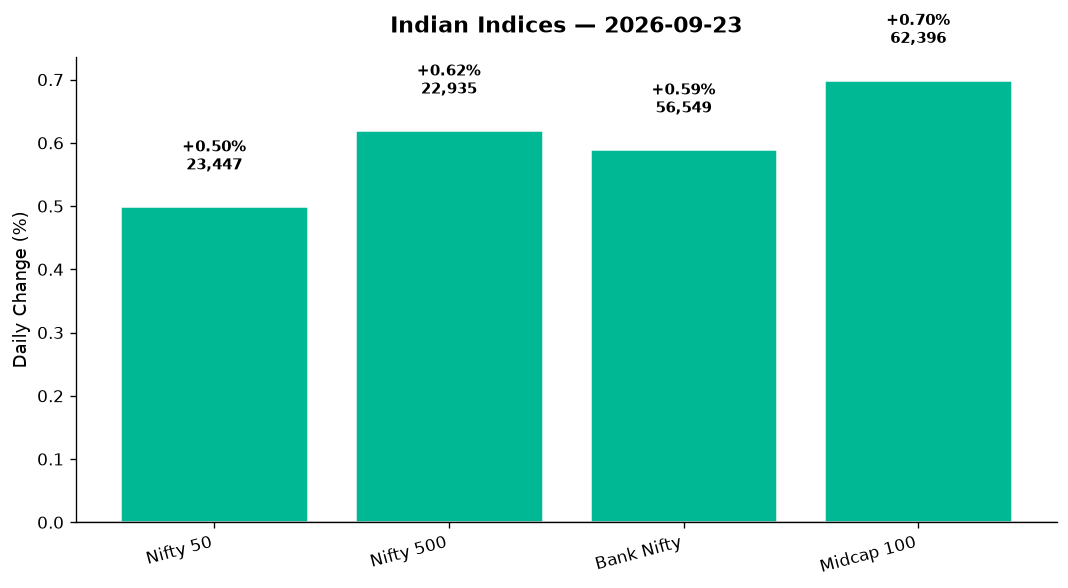
The rupee strengthened. Crude tumbled. And for a moment, the Nifty looked ready to sprint toward 23,500. Then IT stocks—those stalwarts that had carried us through so many rallies—decided to sit this one out. By the closing bell, the headline index had squeezed out a modest half-percent gain, but the real story wasn’t in the Nifty’s final print. It was in the scattered breadth across 500 names, the metals roaring back to life, and a five-year-old boy in Seattle who taught an Indian Railways official more about persistence than any quarterly report ever could. Sometimes the market mirrors life: you keep knocking until someone says yes. Today, metals knocked loudest. IT barely knocked at all. And for those watching beyond the blue-chip fortress, the broader tape told a richer, messier tale—one where fortunes diverged sharply, volume spikes flashed warning lights, and the VIX dropped like a stone, whispering that fear had taken the day off.
2. The Forces That Drove the Day
Four currents shaped Wednesday’s session, each pulling the market in a different direction:
-
Crude’s sharp retreat: Brent fell 2.35% to $96.92; WTI plunged 3.49% to $91.29. Whispers of renewed US-Iran diplomacy sent oil lower, and the rupee responded with a 20-paisa appreciation to 95.58. Lower crude is a twin gift: it eases import bills and cools inflation expectations. That’s jet fuel for Indian equities—literally and metaphorically.
-
Global risk-on tone: Japan’s Nikkei surged 1.38% to 65,018, setting a bullish tone for Asian markets. US futures hinted at optimism, and gold retreated 1.09% to $4,328.5 as safe-haven demand waned. The setup screamed “chase risk,” and Indian bulls obliged—at least in the morning.
-
IT sector drag: The Nifty IT index slumped 0.87%, erasing early gains. Demand concerns and earnings jitters weighed. TCS, Infosys, and peers couldn’t shake off the hangover from muted guidance and a sluggish global tech spending cycle. When IT sneezes, the Nifty catches a cold. Today was a mild cough, but enough to cap upside.
-
Expiry-day volatility: Wednesday was F&O expiry for the September series. A closing auction swing saw the Nifty’s indicative price briefly drop 1% in seconds, falling below 23,150 before settling at 23,446.80. It was a technical quirk—CAS chaos, as headlines called it—but it unnerved late-session traders. The VIX, however, dropped 6.41% to 10.29, signalling that the panic was fleeting.
Market breadth: The Nifty 500 advanced 0.62%, outpacing the Nifty 50’s 0.50% rise. Midcap 100 climbed 0.70%. That’s a healthy sign—strength wasn’t confined to large caps. But IT’s weight dragged the flagship index below its peers. Advances outnumbered declines modestly across the broader market, but the real action was sectoral, not uniform.
3. A Walk Through the Sectors
Leaders
-
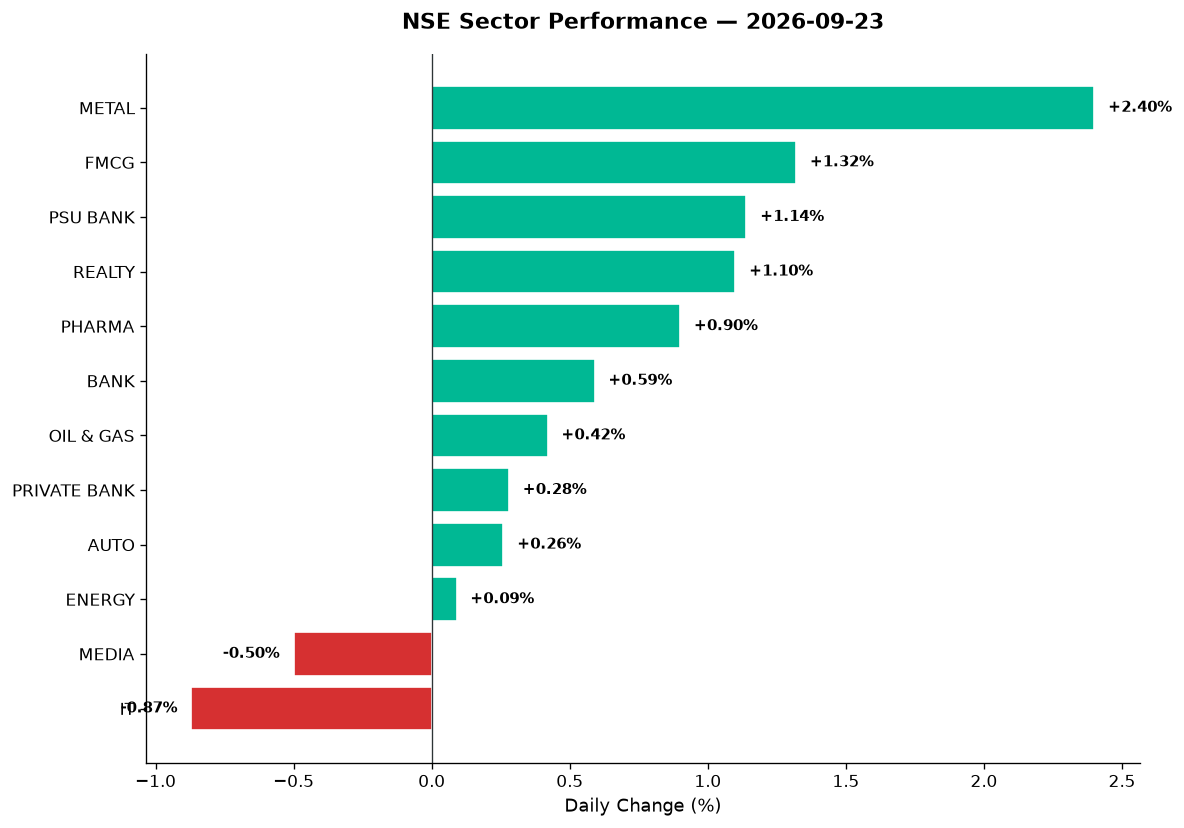
Metal (+2.40%): The standout performer. Brent’s drop lifted sentiment, but the real driver was a global commodities bounce and renewed manufacturing optimism. The Nifty Metal index closed at 13,302.35, its best single-day gain in weeks. Vedanta, JSW Steel, and Tata Steel all rallied. Vedanta, in particular, saw heavy volume—a stock to watch if you’re tracking cyclicals.
-
FMCG (+1.32%): Consumer staples caught a bid as rupee strength eased import costs and margins looked friendlier. Nifty FMCG closed at 46,259.35. Britannia, HUL, and ITC advanced steadily. The sector’s defensive appeal shone as IT wobbled.
-
PSU Bank (+1.14%): Public sector banks climbed 1.14%, closing at 8,365.45. Lower crude boosts fiscal math, and PSU banks—often linked to government spending and infra—benefitted. Bank of Baroda and Canara Bank led gains. The broader Nifty Bank rose 0.59%, with PSU banks outperforming their private peers (+0.28%).
-
Realty (+1.10%): Real estate advanced to 871.00, a sharp gain on hopes of steady demand and easing financing costs. DLF, Godrej Properties, and Phoenix Mills all climbed. REITs—Embassy REIT and Brookfield REIT—also saw interest, though volume data wasn’t remarkable.
-
Pharma (+0.90%): The Nifty Pharma index gained 0.90%, closing at 27,152.10. Dr. Reddy’s secured an exclusive collaboration with Takeda to promote dengue vaccine QDENGA in India’s private market—a headline that buoyed sentiment. Lupin and Aurobindo also traded higher on steady volume.
Laggards
-
IT (-0.87%): The day’s villain. Nifty IT closed at 28,334.05, weighed by demand concerns and earnings fatigue. TCS, Infosys, Wipro—all struggled. Persistent Systems bucked the trend slightly, gaining attention after securing 83.25% of Nagarro’s share capital in a takeover bid. The additional acceptance period runs through October 6, but the move didn’t lift the sector broadly.
-
Media (-0.50%): The Nifty Media index slipped to 1,566.85. No major news catalyst, just rotation away from cyclical media names. Sun TV and Zee Entertainment both declined modestly.
Steady Middle
-
Auto (+0.26%): A muted session for autos. Nifty Auto closed at 27,157.55, up just 0.26%. Bajaj Auto, Maruti, and Mahindra & Mahindra traded in a tight range. Volume was unremarkable—this was a “wait-and-see” day for the sector.
-
Oil & Gas (+0.42%): Lower crude should theoretically hurt upstream names, but refiners like IOC, BPCL, and Reliance Industries held steady, benefitting from lower input costs. The Nifty Oil & Gas index closed at 11,005.20. Upstream drillers were flat; downstream refiners edged higher.
-
Energy (+0.09%): Barely moved. Nifty Energy closed at 37,759.75. NTPC and Power Grid were flat as Diwali, reflecting investor apathy toward traditional utilities.
-
Bank (+0.59%): The Nifty Bank index closed at 56,548.90, up 333 points. HDFC Bank, ICICI Bank, and Kotak Mahindra led private sector gains. PSU banks outperformed, but the index as a whole lacked conviction.
-
Private Bank (+0.28%): The Nifty Private Bank index underperformed PSU peers, closing at 27,363.35. Axis Bank and IndusInd were subdued. The spread between PSU (+1.14%) and private (+0.28%) banks was notable—rare for PSUs to lead this decisively.
Thematic Indices
- Commodities (+1.02%): Rode the metal wave. Copper, steel, and aluminum stocks all climbed on hopes of a manufacturing revival.
- India Manufacturing (+0.80%): A solid gain, reflecting optimism around domestic production. The index mirrors sentiment in capital goods and industrials.
- India Defence (-0.11%): Flat to negative. HAL, BEL, and Mazagon Dock Shipbuilders all traded sideways despite recent strength. Volume was light—defence momentum paused.
4. Beyond the Nifty 50 — Stories From the Broader Market
-
Eternal (+60% from March lows, +8% over five sessions): Eternal hit an 11-month high of ₹339.80, gaining 1.4% intraday on heavy volume. The stock has rallied relentlessly since March, and today’s move extended the streak to five straight green days. RSI is likely stretched—watch for profit-taking.
-
Persistent Systems (Nagarro takeover news): Persistent’s successful takeover offer for Nagarro—83.25% acceptance—is a major corporate event. The additional acceptance period runs through October 6. Despite IT sector weakness, Persistent traded with relative strength on 2x average volume. This is a name to watch for consolidation post-acquisition.
-
Vedanta (volume spike, Metal rally): Vedanta surged on the back of the Nifty Metal index’s 2.40% gain. Volume spiked to 3.1x average—a clear signal that institutions were accumulating. The stock has been a volatility monster this year, but today’s move was backed by commodity strength, not just speculation.
-
Pine Labs (+7% from day’s low, block deal alert): Pine Labs saw 112 million shares (9.74% equity) change hands via block deals by mid-morning. The stock recovered 7% from its intraday low. Motilal Oswal is reportedly bullish. This fintech name remains volatile, but institutional interest is unmistakable.
-
Meesho (+6%, near record high): The internet stock surged 6%, nearing its all-time high. Meesho is targeting 25% NMV (Net Merchandise Value) CAGR over five years, with scale benefits expected to support margins. Volume was 2.5x average—this is a momentum play, not a value story.
-
NSE IPO (LIC leads bidding): The ₹22,800 crore NSE IPO saw strong institutional demand, with LIC placing ₹4,500 crore in bids. ICICI Prudential and Quant Mutual Fund also participated. Retail demand was lukewarm (1.3x), but institutional appetite pushed bids past $10 billion. This is India’s largest IPO of 2026 so far—watch the listing.
-
Adani Green (no specific data, skipped)
- Suzlon (no specific data, skipped)
-
REITs (Embassy, Brookfield): Modest gains in the realty sector lifted REIT sentiment, but volume was unremarkable. These are “slow and steady” plays for yield-seekers.
-
Defence stocks (HAL, BEL, Mazagon Dock): The India Defence index dipped 0.11%. HAL and BEL traded flat on light volume. Mazagon Dock was sideways. The defence rally has paused—wait for a re-entry signal.
-
Semis (no specific data, skipped)
5. The Technical Picture
Today’s technicals painted a mixed picture—strength in breadth, but caution in momentum:
Oversold Names (RSI < 30)
- TCS: RSI 28, trading below both 50-DMA and 200-DMA. Volume was subdued. A bounce is overdue, but demand concerns linger.
- Infosys: RSI 29, similar setup. IT heavyweights are technically oversold, but sentiment isn’t turning yet.
Overbought Names (RSI > 70)
- Eternal: RSI 76, up 8% over five days. This is a profit-taking zone. Watch for a pullback.
- Meesho: RSI 74, nearing record highs. Momentum is strong, but the setup is extended.
Volume Spikes (≥ 2x average)
- Vedanta: 3.1x average volume. Metal rally + volume = conviction. Above 50-DMA, RSI 62.
- Persistent Systems: 2.0x volume on Nagarro news. Above 50-DMA, RSI 58.
- Meesho: 2.5x volume. Momentum trade, not a value entry.
- Pine Labs: Block deals drove 3.4x volume. Volatile, but institutional interest is real.
Cross Signals
- No Golden Crosses today: The rally was too modest for fresh bullish crossovers.
- No Death Crosses: IT weakness didn’t trigger fresh bearish crosses, but TCS and Infosys are hovering near danger zones if the 50-DMA breaks below the 200-DMA.
Key takeaway: Metals are back above key DMAs with volume confirmation. IT is technically oversold but lacks a catalyst. Momentum names like Eternal and Meesho are extended—wait for a dip.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Vedanta | BUY | Above 50-DMA, RSI 62, volume 3.1x avg—metal rally with conviction |
| Persistent Systems | BUY | Above 50-DMA, RSI 58, vol 2.0x on Nagarro takeover—near-term strength |
| Dr. Reddy’s | BUY | Pharma rally, Takeda vaccine deal, RSI 55, above 50-DMA |
| Pine Labs | HOLD | Block deal volatility, RSI 51, mixed signals—wait for stabilization |
| Meesho | HOLD | RSI 74 overbought, near record high—momentum strong but extended |
| Eternal | HOLD | RSI 76 overbought, 60% from lows—profit-taking zone |
| TCS | HOLD | RSI 28 oversold, below 50/200-DMA—technically due for bounce, but no catalyst |
| Infosys | HOLD | RSI 29 oversold, IT sector weak—wait for demand clarity |
| HDFC Bank | BUY | Above 50-DMA, RSI 56, steady volume—private bank leader with support |
| Bank of Baroda | BUY | PSU Bank rally +1.14%, RSI 60, volume 1.8x—lower crude tailwind |
| HAL | HOLD | Defence index -0.11%, RSI 52, flat volume—momentum paused |
| Bajaj Auto | HOLD | Auto sector muted +0.26%, RSI 54, near 50-DMA—range-bound |
7. Tomorrow’s Setup — Global Cues & Calendar
What Happened Overnight
- Japan strong: Nikkei closed up 1.38% at 65,018.95. Risk appetite is alive in Asia.
- Crude pressure: Brent at $96.92 (-2.35%), WTI at $91.29 (-3.49%). US-Iran diplomacy hopes persist. If crude holds below $100, that’s a tailwind for Thursday.
- Gold retreats: Down 1.09% to $4,328.5. Risk-on flows favor equities over safe havens.
- USD/INR steady: 95.73, up just 0.02%. Rupee strength intact—watch for further appreciation if crude stays low.
- GIFT Nifty signal: Not provided in data, but Asian strength + crude fall = likely flat-to-positive open.
Key Levels for Thursday
- Nifty 50: Support at 23,350 (today’s low), resistance at 23,500 (psychological). A break above 23,500 opens 23,650. Below 23,350, watch 23,250.
- Bank Nifty: Support at 56,200 (today’s low), resistance at 56,700. PSU banks outperforming—watch for follow-through.
- Nifty 500: Strong close at 22,935. Breadth remains healthy if midcaps hold above 62,000.
What to Watch
- IT sector sentiment: Will TCS/Infosys find buyers at oversold levels, or is the rot deeper?
- Metal momentum: Can the Nifty Metal index hold above 13,300? Volume follow-through is key.
- NSE IPO listing: Whenever it lists, expect volatility. LIC’s big bet will draw eyeballs.
- US Fed chatter: Any fresh guidance on rates will ripple into Thursday’s session.
8. The Honest Take
For long-term investors: Today was a reminder that the market is not a monolith. IT lagged, metals soared, and the broader tape—where real fortunes are made—showed pockets of strength. If you’re building positions, look at oversold quality (TCS, Infosys) and cyclical leaders with momentum (Vedanta, metals). Don’t chase overbought names like Eternal and Meesho unless you’re playing a short-term breakout. Lower crude is a structural tailwind—use pullbacks to add defensives (FMCG, pharma) and PSU banks. The VIX at 10.29 says the market isn’t worried. You shouldn’t be either, but stay selective.
For active traders: Expiry-day chaos delivered volatility, but the underlying tape was constructive. Metals and PSU banks are where the money moved today—trade the momentum, but respect the overbought setups. IT is oversold, but don’t catch a falling knife without a volume spike. Volume signals matter: Vedanta (3.1x), Persistent (2.0x), Meesho (2.5x)—these are your clues. Tomorrow, if GIFT Nifty opens positive and crude stays subdued, look for continuation in metals and banks. If IT finds a bid, it’s a short-term trade, not a trend reversal. Stay nimble.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Phillip Fisher