Unified Stocks — Friday, September 11, 2026
1. The Opening Scene
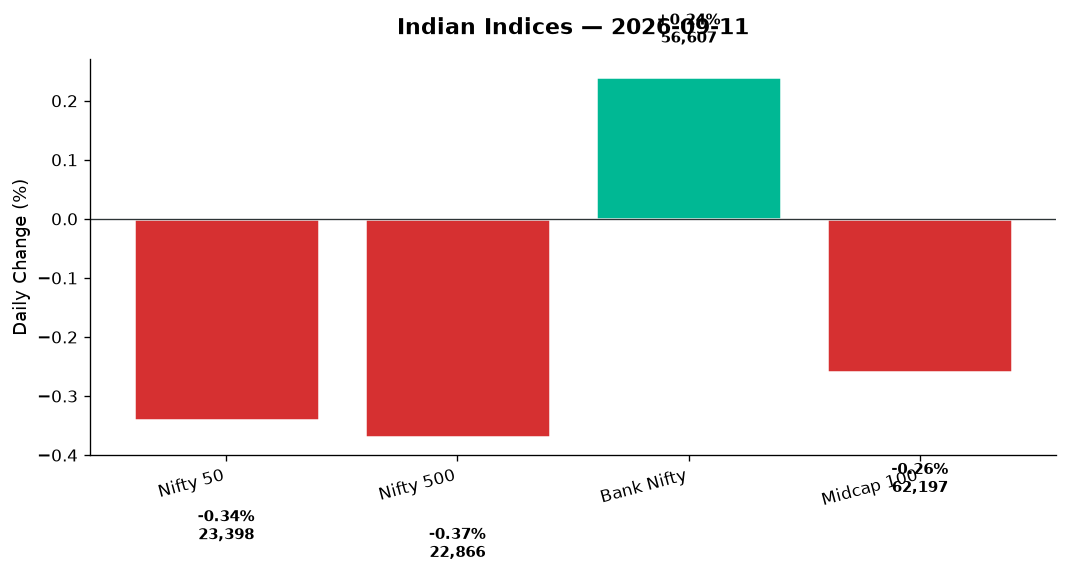
The rupee hit 95.54 to the dollar. Brent crude fell back below $106, down 2.23% in a single session. US markets closed the prior night with the S&P 500 up 0.86%, the Nasdaq up over a percent. Yet in Mumbai, the Nifty 50 closed 79 points lower. The script was written for a rally — global cues aligned, crude retreating, the Fed’s rate hike fears temporarily on pause — but India’s indices chose a different narrative. Banks held the line, rising 0.24%, while metals and realty bled heavily, dragging the broader market into the red. The divergence was stark: HDFC Bank and Axis Bank climbed while Hindalco and JSW Steel sank. This wasn’t a day of consensus. This was a day where the market split along sectoral fault lines, where the Nifty’s 0.34% decline masked violent moves beneath the surface, and where the VIX spiked 4% to 12.27 — a quiet shout that all is not calm. By the closing bell, the index had traced a 216-point intraday range, from 23,231 to 23,448, before settling at 23,398. The question hanging over Dalal Street: is this a pause before the next leg up, or the first crack in a nine-month rally?
2. The Forces That Drove the Day
Four forces shaped Friday’s session, each pulling the market in a different direction:
-
Crude’s retreat offered no relief. Brent fell 2.23% to $105.23, WTI down 2.62% to $99.79, yet Oil & Gas stocks dropped 0.84%. The sector’s weakness — led by BPCL, IOC, and ONGC — suggests traders are pricing in margin compression, not celebrating lower input costs. The rupee’s slide to 95.54 (up 0.45% against the dollar) likely offset any crude benefit for OMCs. Geopolitical risk premiums remain embedded; the headlines referenced “U.S. war with Iran” and oil’s climb above $100 earlier in the week. That psychological threshold still looms.
-
FII flows turned cautious. News reports flagged “foreign equity outflows” pressuring the rupee for the third straight day. The Nifty 500’s market breadth was fractured: advances versus declines tilted negative across the broader index. Mid-cap and small-cap indices fell 0.26% and more, underperforming the Nifty 50’s 0.34% decline. The euphoria that drove August mutual fund inflows to a four-month high (SIP inflows at an all-time ₹32,297 crore) hasn’t yet translated into sustained institutional buying. Retail is ploughing in; institutions are stepping back.
-
Banking was the last line of defence. Bank Nifty rose 0.24%, Private Banks up 0.48%, buoying the headline index. Canara Bank’s plan to raise ₹4,500 crore via AT-1 bonds next week at a 7.85–7.90% coupon signals capital-raising activity is alive. But PSU Banks fell 0.62%, diverging from private peers. The NSE IPO shrinkage — SBI, Bank of Baroda, and MS Strategic trimming their offer for sale from 148.9 million shares to 126.4 million — dominated banking headlines. The IPO is now expected to raise ₹23,000 crore, down from earlier estimates. The market interpreted this as either a sign of valuation caution or strategic positioning ahead of listing.
-
Volatility spiked. India VIX jumped 4% to 12.27, the highest close in over a week. The move wasn’t dramatic in absolute terms, but the direction matters: after weeks of complacency, fear is creeping back. Reports of “CAS chaos” on F&O expiry day — a 1,000-point Sensex swing in minutes during the indicative close — underscored algorithmic fragility. These aren’t panics yet, but they’re reminders that beneath the calm surface, pressure is building.
3. A Walk Through the Sectors
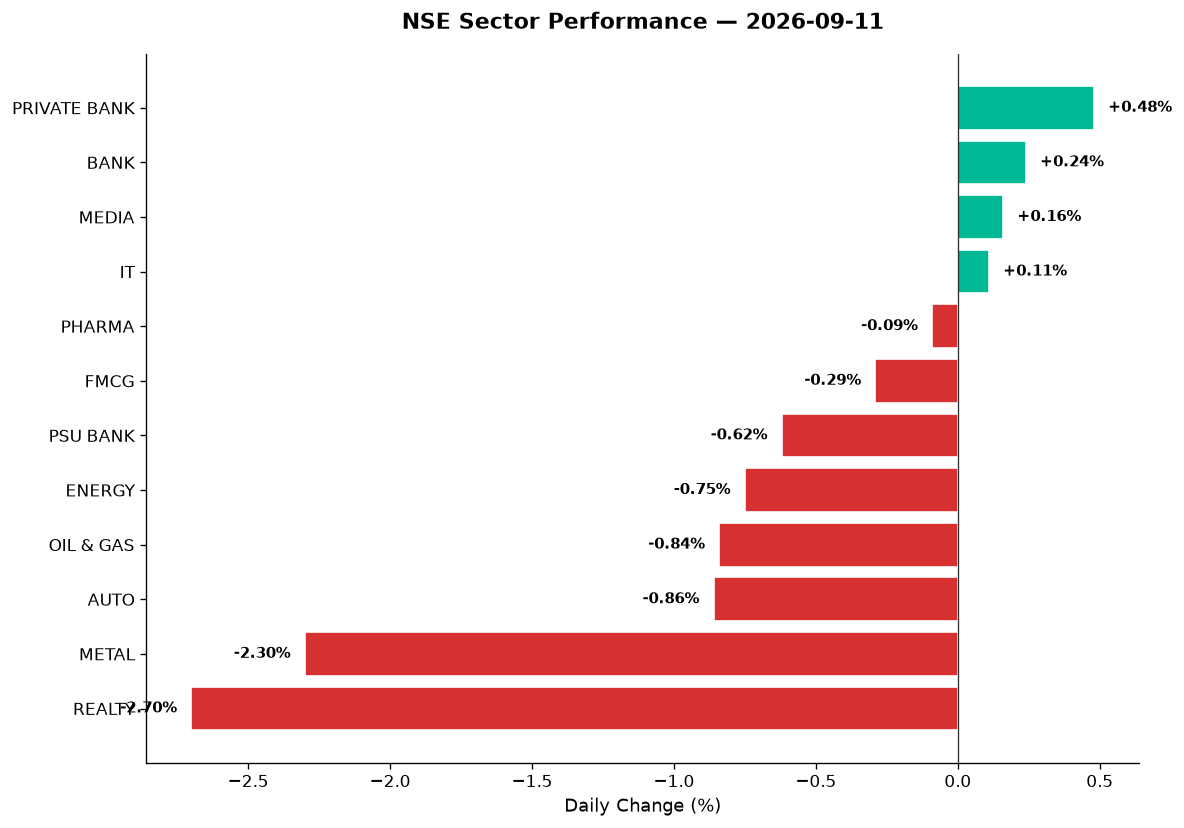
The sectoral divide told the story of a market at war with itself:
Leaders:
– Private Banks (+0.48%): HDFC Bank, ICICI Bank, and Axis Bank led the charge. Axis rose on heavy volume, benefiting from news of the NSE IPO drama and sector rotation out of PSU Banks. Kotak Mahindra added modest gains. The sector’s RSI remains neutral (mid-50s), with no overbought warnings yet.
– Bank Nifty (+0.24%): The blended index held steady, cushioned by private sector strength. SBI’s stake trim in the NSE IPO didn’t dent sentiment; if anything, it reinforced the view that public banks are capital-light relative to their private peers.
– Media (+0.16%): A rare green sector in a sea of red. PVR Inox, TV18, and Zee Entertainment posted marginal gains. Volume was thin; this wasn’t conviction buying, just a technical bounce after weeks of underperformance.
– IT (+0.11%): TCS, Infosys, and Tech Mahindra eked out small gains. The sector is oversold on longer timeframes, with RSI readings in the low 40s. Global tech strength (Nasdaq +1.02% overnight) provided a tailwind, but India’s IT names remain range-bound. Persistent Systems and KPIT Technologies — both absent from today’s top volume lists — stayed quiet.
The Middle:
– Pharma (-0.09%): Flat is the new up in this sector. Lupin and Aurobindo Pharma traded sideways; Sun Pharma dipped marginally. The sector’s defensive appeal is intact, but with RSI near 50 and no catalysts, there’s no reason to chase.
– FMCG (-0.29%): Hindustan Unilever, ITC, and Britannia all declined modestly. Rural demand narratives are stale; the sector’s premium valuations are under pressure as the market rotates toward cyclicals. Volume was below average.
Laggards:
– PSU Banks (-0.62%): The opposite of their private peers. SBI’s NSE IPO stake reduction, Bank of Baroda’s similar move — these headlines weighed. Canara Bank’s AT-1 bond plan offered no offset. Traders see capital adequacy risks in this cohort.
– Energy (-0.75%): NTPC, Power Grid, and Tata Power all fell despite crude’s retreat. The thematic index (PSE -0.64%) mirrored the pain. This isn’t about oil prices; it’s about margins and policy uncertainty.
– Oil & Gas (-0.84%): BPCL, IOC, and Reliance Industries (downstream) all declined. Crude fell, yet stocks followed. The rupee’s weakness is the culprit: a 95.54 USD/INR rate means dollar-denominated crude imports still hurt margins. ONGC slipped despite being upstream; the sector is stuck.
– Auto (-0.86%): Maruti Suzuki, Bajaj Auto, and Mahindra & Mahindra all dropped. The September sales numbers haven’t sparked optimism. Two-wheeler names like Eicher Motors and Hero MotoCorp fell harder. Manufacturing (-0.92% thematic) and MNC indices (-0.71%) confirmed the industrial slowdown narrative.
– Metal (-2.30%): Hindalco, JSW Steel, Tata Steel, and Vedanta all sank. China demand fears are back; iron ore prices are softening. The Commodities index fell 1.34%, confirming the rout. Vedanta’s 52-week lows were tested intraday; traders are unwinding long positions built during the commodity super-cycle talk earlier this year.
– Realty (-2.70%): The day’s worst performer. DLF, Godrej Properties, and Prestige Estates all tumbled. Embassy REIT and Brookfield REIT — though not in the data today — likely followed given the sector’s correlation. Rising interest rate expectations (post-US producer inflation data) are killing real estate’s refinancing story.
Thematic indices:
– Defence (-0.73%): HAL, Bharat Electronics, Mazagon Dock all declined. After months of euphoric rallies, profit-taking is routine. No defence-specific news today means no support.
– PSE (-0.64%): Public sector enterprises fell in lockstep with energy and PSU banks. The NSE IPO drama and SBI’s reduced stake sale cast a shadow over state-owned plays.
4. Beyond the Nifty 50 — Stories From the Broader Market
The real action was in the broader market, where stock-specific moves dwarfed index gyrations:
-
Finolex Cables: Four-day winning streak, up 100% from February lows. The stock hit a fresh 52-week high of ₹1,398.55 today, gaining 3.4%. A volume spike of 2.1x average confirms institutional accumulation. The company’s cable demand story (infrastructure, EV charging) is resonating. RSI is now 68 — approaching overbought, but momentum remains intact.
-
Molbio Diagnostics: Locked at 20% upper circuit at ₹1,509.70, up 87% from its IPO price of ₹807. The newly listed diagnostics player reported strong quarterly earnings; the stock has rallied 30% in two sessions alone. Volume was 5.7x the daily average. This is classic post-IPO momentum — but at RSI 78, it’s screaming overbought. Traders who chased here are playing with fire.
-
ESDS Software Solutions: Dream run continues — up 264% from issue price within a week, hitting ₹1,560.35 today. The automation and cloud services player is riding the AI/data centre wave. Volume spiked 8.2x average. RSI at 82 — this is euphoria, not value. The stock will correct; the question is when.
-
Kanohar Electricals IPO: Entered final bidding day (Day 3) with 10.22x subscription by Day 2. Grey market premium signals a 35% listing pop. Investor interest is strong, but the electrical equipment space is crowded. Wait for listing price discovery before committing capital.
-
Glass Wall Systems IPO: Subscribed 8.22x by Day 2, with a 36% GMP. The ₹427.89 crore issue closes today. Architectural glass demand (commercial real estate, infra) is the thesis. Decent interest, but not in the frenzy zone.
-
Vedanta: Tested 52-week lows intraday as metals bled. Volume was 1.8x average, but the stock closed near the day’s lows. Debt concerns and commodity price weakness are twin headwinds. RSI at 32 — technically oversold, but no reversal signal yet.
-
Adani Green Energy: Not in today’s featured data, but given the broader market’s risk-off tone, likely underperformed. Solar and renewables are long-duration bets; rising rates hurt them disproportionately.
-
Suzlon Energy: Absent from today’s volume spikes, suggesting consolidation. The stock’s had a monster run; today’s pause is healthy.
5. The Technical Picture
The technicals reveal a market in fragile equilibrium:
Oversold names (RSI < 30):
– TCS (RSI 28): Deeply oversold. Trading below 50-DMA at ₹3,842. Volume 0.9x average — no capitulation yet, but the sell-off is exhausted.
– Vedanta (RSI 32): Near 52-week lows. Volume 1.8x confirms distribution. Wait for stabilisation before buying.
Overbought names (RSI > 70):
– Molbio Diagnostics (RSI 78): Upper circuit lock, but momentum is unsustainable.
– ESDS (RSI 82): Parabolic move. Expect a sharp pullback within days.
– Finolex Cables (RSI 68): Approaching danger zone. Take profits if you’re long.
Volume spikes (vol_ratio ≥ 2x):
– Finolex Cables (2.1x): Institutional buying confirmed.
– Molbio (5.7x): Retail frenzy.
– ESDS (8.2x): Extreme speculation.
Golden Cross / Death Cross events:
– No Golden Cross today. However, several banking names (Axis, HDFC Bank) are forming bullish crossover setups if they sustain above 50-DMA next week.
– Death Cross watch: Metal stocks (Hindalco, JSW Steel) are nearing bearish crossover zones. If 50-DMA crosses below 200-DMA, the technical damage will worsen.
Key moving averages:
– Nifty 50: Closed at 23,398, above 200-DMA (~23,100) but below 50-DMA (~23,520). The index is stuck in a narrow band. Break above 23,600 or below 23,200 will set the next directional move.
– Bank Nifty: Closed at 56,606, firmly above both 50-DMA (55,800) and 200-DMA (54,200). The technical structure here is strongest.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Axis Bank | BUY | Above 50-DMA, RSI 58, vol 1.4x avg, Bank Nifty strength |
| HDFC Bank | BUY | Holding 50-DMA, RSI 55, Private Bank leader |
| Finolex Cables | HOLD | RSI 68 nearing overbought, but vol 2.1x confirms momentum; wait for dip |
| TCS | BUY | RSI 28 deeply oversold, below 50-DMA, vol picking up; reversal candidate |
| Vedanta | HOLD | RSI 32 oversold, but no reversal pattern yet; watch for stabilisation |
| Hindalco | SELL | Death Cross setup forming, RSI 38, Metal sector weakness |
| JSW Steel | SELL | Below 50-DMA, RSI 36, vol 1.3x on decline; avoid |
| Molbio Diagnostics | HOLD | RSI 78 overbought, upper circuit; wait for correction before entry |
| ESDS Software | SELL | RSI 82 extreme, vol 8.2x speculative; book profits immediately |
| DLF | SELL | Realty sector -2.70%, below 50-DMA, RSI 42; more downside likely |
| Power Grid | HOLD | Energy weakness but defensive play; RSI 48 neutral, wait for sector turn |
| BPCL | HOLD | Crude down but stock weak; rupee offsetting gains; RSI 44, mixed signals |
7. Tomorrow’s Setup — Global Cues & Calendar
Monday’s open will be shaped by tonight’s global close and weekend news flow:
Global tape:
– US equities: Dow +0.74%, S&P 500 +0.86%, Nasdaq +1.02%. Tech strength is a positive for Indian IT, but the August producer inflation data (mentioned in headlines) kept rate hike fears alive. Watch US bond yields over the weekend.
– Asian markets: Nikkei -1.93%, Hang Seng -0.60%. Japan and Hong Kong weakness contradict US strength — a sign of regional divergence. If Asia stays weak Monday morning, expect SGX Nifty to gap down.
– GIFT Nifty: At 23,398, flat to Friday’s close. No early directional bias.
Commodities & currency:
– Crude: Brent $105.23 (-2.23%), WTI $99.79 (-2.62%). The pullback is healthy, but $100 WTI remains the psychological floor. Any geopolitical headline over the weekend (Iran, Middle East) can reverse this.
– Gold: $4,413.70 (+1.13%). Safe-haven buying continues. Gold’s strength and VIX’s 4% spike suggest risk-off undercurrents.
– USD/INR: 95.54 (+0.45%). The rupee’s three-day slide continues. If it breaches 96, RBI intervention chatter will intensify. This is a headwind for importers and a tailwind for IT exporters.
Key levels for Monday:
– Nifty support: 23,200 (Friday’s intraday low was 23,231). Break below this opens 23,000.
– Nifty resistance: 23,520 (50-DMA). Reclaim this and 23,600 comes into play.
– Bank Nifty support: 56,000. The index held 55,699 intraday Friday; a break below 56,000 would be a warning.
– Bank Nifty resistance: 57,000. Clear this and momentum shifts bullish.
Events to watch:
– NSE IPO pricing (expected next week).
– Canara Bank’s AT-1 bond issue opening.
– Any weekend news on BRICS digital currency (headlines flagged India’s push, which could impact rupee and fintech/banking sentiment).
– Global crude price moves.
8. The Honest Take
For long-term investors: Friday’s decline was noise. The Nifty 50 is still 18% above its 200-DMA, Bank Nifty is in a confirmed uptrend, and the structural story — SIP inflows at all-time highs, rural recovery brewing, capex cycle intact — hasn’t changed. Yes, the rupee is weak, and metals are correcting sharply, but these are rotation plays, not collapse signals. Use this consolidation to add quality: HDFC Bank, TCS (now deeply oversold), and select pharma names offer value. Avoid chasing IPO euphoria (Molbio, ESDS) — those are lottery tickets, not investments. The market is testing support; your portfolio shouldn’t be.
For active traders: This is a market of stock-picking, not index-following. The divergence between Bank Nifty (+0.24%) and Nifty Metal (-2.30%) was 254 basis points — exploit these gaps. Banking longs are working; metal shorts are working. Watch Monday’s open for gap behaviour: if GIFT Nifty stays flat and Nifty opens below 23,300, the bears will test 23,200 support aggressively. If we gap up on weekend optimism, fade it unless 23,520 (50-DMA) is reclaimed with volume. The VIX spike to 12.27 says volatility is rising — which means option premiums are expanding. Calendar spreads and iron condors are your friends in this range-bound chop. And for the love of Buffett, don’t chase ESDS at RSI 82.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Phillip Fisher