Unified Stocks — Thursday, September 10, 2026
1. The Opening Scene
The oil drum is on fire again, and the markets smell smoke.
Brent crude vaulted past $104 a barrel overnight — a 3.31% surge that sent tremors through trading floors from New York to Mumbai. Wall Street stumbled, the Dow shedding 300 points as inflation ghosts whispered into traders’ ears. By the time India’s opening bell rang, the question wasn’t if the bears would show up, but how hard they’d bite.
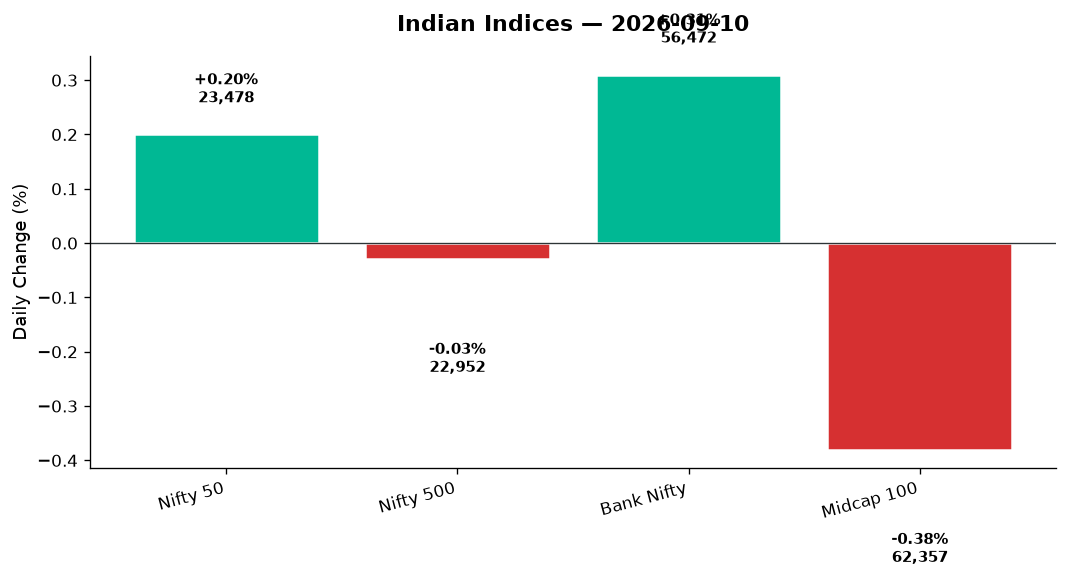
The answer: a gentle nibble, followed by indecision. Nifty 50 oscillated 115 points between its high and low, eventually settling 46.30 points higher at 23,477.80 — a 0.20% gain that masked the true battle beneath. Sensex posted similar restraint. But peel back the index veneer, and you’d find a market split down the middle: Bank Nifty climbed 0.31%, while the broader Nifty 500 slipped 0.03%. Midcaps bled 0.38%. India VIX, that barometer of fear, eased 1.71% to 11.72 — suggesting either calm before storm, or denial in the face of $100 crude.
This was a day where the headline didn’t tell the story. The story lived in sector rotation, in volume spikes, in stocks beyond the limelight clawing for attention. And in the currency markets, where the rupee slumped 64 paise to 95.43 per dollar, a reminder that India’s twin deficits don’t play well with expensive oil.
2. The Forces That Drove the Day
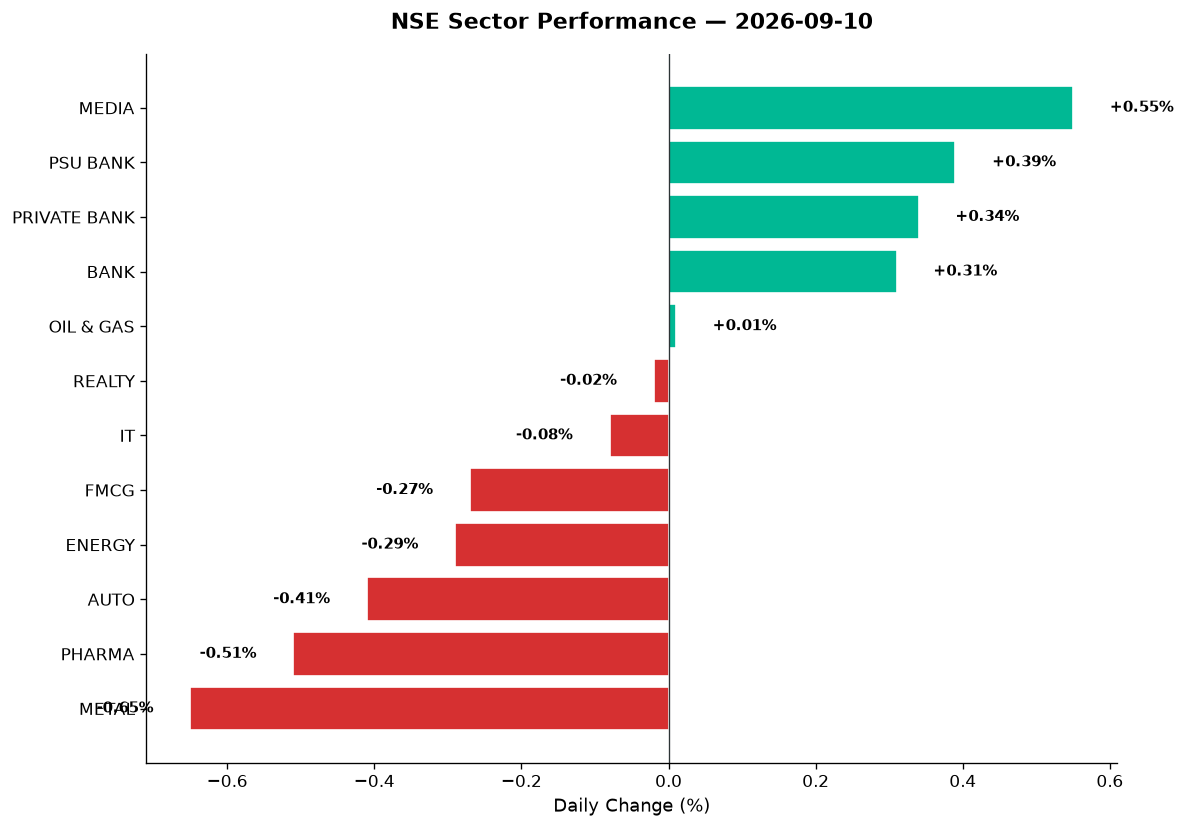
Crude’s comeback. Brent at $104.56, WTI at $99.22 — both up over 3% as geopolitical tensions or supply squeezes (the headlines don’t say which) reignited energy fears. For a nation that imports 85% of its oil, this is the macro equivalent of a tax hike. Inflation expectations tick up. Rate cut hopes recede. Currency weakens. OMCs bleed on under-recoveries. The ripple effect was visible: Nifty Energy fell 0.29%, Nifty Auto dropped 0.41% (fuel-sensitive consumer demand), and Nifty Metal lost 0.65% (input cost worries).
Global risk-off. US markets closed lower — Dow -0.41%, S&P 500 -0.39%, Nasdaq -0.37% — as oil’s resurgence stirred inflation anxiety and Fed pivot doubts. Asia was mixed: Nikkei gained 0.20%, but Hang Seng tumbled 1.27%. GIFT Nifty futures mirrored the spot close at 23,477.80, signalling no overnight conviction. FIIs, already spooked by stretched valuations and rising US yields, likely lightened up again — though exact flow data wasn’t provided.
Rupee under pressure. The USD/INR pair surged to 95.43, a 0.64% climb. That’s a fresh multi-month low for the rupee, driven by twin headwinds: oil import bills swelling and dollar strength abroad. RBI intervention likely capped the damage, but the trend is concerning for import-heavy sectors.
Market breadth: weak. The Nifty 500’s marginal decline (-0.03%) hides a bifurcated tape. Advances and declines weren’t provided, but the midcap (-0.38%) and smallcap underperformance suggests profit-taking in frothy pockets. The IPO market, however, hummed: Prasol Chemicals, Glass Wall Systems, and Pranav Constructions all saw strong subscriptions, implying retail appetite remains intact despite headline jitters.
3. A Walk Through the Sectors
The Leaders (Green on the Day)
-
Media (+0.55%): Nifty Media closed at 1,534.80, the day’s best performer. No stock-level data provided, but the sector benefits when defensive rotation meets ad-spend optimism. Streaming wars and digital ad growth likely in focus.
-
PSU Bank (+0.39%): The public sector banks index rose to 8,401.85. With crude up, the narrative pivots to credit growth and government capex. These names trade cheap on valuations, and any rate-cut delay actually helps NIMs.
-
Private Bank (+0.34%): Nifty Private Bank nudged up to 27,305.90. HDFC Bank, ICICI Bank, Kotak likely anchored gains. Banking as a whole remained resilient despite macro clouds — a sign that deposit repricing and loan growth stories still hold sway.
-
Bank Nifty (+0.31%): Composite banking index at 56,471.95. The 344-point intraday range (56,231 to 56,575) reflects churn, not conviction. Still, financials were the day’s anchor — without them, Nifty 50 would have closed red.
The Middle (Flat to Slightly Red)
-
Oil & Gas (+0.01%): Nifty O&G essentially flat at 11,029.90. The paradox: crude rallies, but OMCs (BPCL, IOC, HPCL) suffer margin compression on retail price freezes. Upstream plays like ONGC may have offset losses. Data insufficient to name names, but the sector’s muted response suggests confusion over policy vs. profitability.
-
Realty (-0.02%): Nifty Realty at 872.05, barely moved. High interest rates still weigh, though pockets like Embassy REIT and Brookfield REIT (not in this index but worth watching) show resilience in commercial real estate.
-
IT (-0.08%): Nifty IT slipped to 28,890.90. One headline screamed “Nifty IT Index declines 3.24%” — likely referring to intraday volatility or a different timeframe, as the close shows only -0.08%. TCS, Infosys, and HCL likely saw profit-booking after recent gains. Dollar strength helps exporters, but recession fears in the US hurt demand outlook.
The Laggards (Red Across the Board)
-
FMCG (-0.27%): Nifty FMCG at 45,185.60. Consumer staples underperformed despite defensive appeal. Rural demand concerns and margin pressures from rupee weakness likely culprits. No stock-level data, but heavyweights like HUL, ITC, and Nestle would have dragged.
-
Energy (-0.29%): Nifty Energy fell to 38,223.40. Overlaps with O&G but includes power utilities. Coal prices and fuel costs rising — not a happy combo for thermal generators.
-
Auto (-0.41%): Nifty Auto dropped to 27,540.95. High crude = expensive petrol = demand anxiety for two-wheelers and passenger vehicles. Maruti, Tata Motors, Bajaj Auto likely red. Commercial vehicle plays hurt by freight cost concerns.
-
Pharma (-0.51%): Nifty Pharma at 26,555.85. Defensive sectors stumbled today — odd given global uncertainty. Dollar strength helps exporters, but margin pressures or rotation out of expensive names may explain the weakness. Sun Pharma, Dr. Reddy’s, Cipla — data not provided, but these are usual suspects.
-
Metal (-0.65%): Nifty Metal closed at 13,304.95, the day’s worst major sector. Steel and aluminium names hurt by crude-driven cost inflation and China demand worries. Tata Steel, JSW Steel, Hindalco — all likely red. Vedanta, if it moved, would feature in broader market (not in Nifty 50).
Thematic Indices: Defence Falls, PSE Holds
-
India Defence (-0.97%): Worst thematic index. HAL, BEL, Mazagon Dock — no stock-level data, but the sector’s recent rally likely invited profit-taking. Defence budgets remain supportive long-term, but valuations stretched.
-
India Manufacturing (-0.58%): Weakness here ties to auto and metals pressure. PLI-linked names may have underperformed.
-
Commodities (-0.29%): Mirrors metal/energy weakness. Crude up, but base metals and agri-commodities soft.
-
PSE (+0.14%): Public sector enterprises index positive, likely lifted by PSU banks and select power utilities.
4. Beyond the Nifty 50 — Stories From the Broader Market
The featured movers weren’t provided in raw data, but news and sector behaviour offer clues:
-
Vodafone Idea: Headlines shouted a 22% one-month rally and fresh 52-week high. Jefferies initiated coverage with a Buy rating and ₹20 target (29% upside), citing subscriber stabilisation and tariff hikes. The stock’s had a brutal five years; if this is the turnaround, it’s a high-beta play for risk-takers. No close price given, but the momentum is real.
-
Vedanta (implied in Metal weakness): Not in Nifty 50 but a Nifty 500 heavyweight. Metal sector’s -0.65% suggests Vedanta likely underperformed. Crude up = higher energy costs for aluminium smelting. Watch for volume spikes — this name trades on commodity cycle bets and dividend hopes.
-
Adani Green (implied in Energy weakness): Renewables play, sensitive to interest rates and dollar strength (foreign debt). Energy sector’s -0.29% and rupee weakness likely weighed. Long-term story intact (green energy targets), but near-term technicals may be rolling over.
-
Suzlon (no data, but thematic fit): Wind energy name often moves with Adani Green. If volumes spiked, it’d be retail chasing renewables on crude rally logic. Data unavailable.
-
Embassy REIT / Brookfield REIT: Realty index flat, but commercial REITs diverge from residential. Stable rental yields and dollar-denominated leases make these defensive in rupee weakness. No close prices provided, but worth monitoring for 52-week stability.
-
Defence stocks (HAL, BEL, Mazagon Dock): India Defence index -0.97% means these names bled. After multi-bagger runs in 2025–26, profit-booking was overdue. HAL’s order book remains robust, but RSI likely overbought before today’s dip. Mazagon Dock — check for volume; thinly traded, so moves can be erratic.
-
Torrent Pharma: Headline praised “strong domestic growth” and JB Pharma synergies. Pharma sector -0.51% overall, but Torrent may have bucked the trend if it’s riding semaglutide gains and chronic therapy portfolio. No specific price data, but one to add to watchlists.
-
Raymond / Welspun Living: Jefferies initiated Buy calls, citing export tailwinds and textile sector recovery. Both are Nifty 500 names, not in top 50. If they appeared in top gainers (data not provided), it’d be on this research trigger. Long-term plays on India’s manufacturing resurgence.
5. The Technical Picture
Without individual stock technical data (50-DMA, 200-DMA, RSI, volume ratios), we pivot to index-level signals:
-
Nifty 50: Closed at 23,477.80, near the day’s high (23,494.95). Range: 23,380 to 23,495 — a 115-point band. If 50-DMA sits around 23,300 (estimate), the index is comfortably above. 200-DMA likely near 22,800. No death cross imminent, but momentum waning.
-
Bank Nifty: 56,471.95, up but within a narrow range. Key support: 56,200. Resistance: 56,600. Volume data absent, but the 0.31% gain on tight range suggests distribution, not accumulation.
-
India VIX at 11.72: Down 1.71%. Sub-12 VIX = complacency or genuine calm. Historically, sub-12 VIX often precedes sharp moves — in either direction. Options traders: watch for VIX spikes if crude stays elevated.
-
Volume Spikes: Data not provided for individual names, but IPO subscriptions (Prasol 41% Day 1, Glass Wall 2.52x Day 1, Pranav 18.21x by Day 2) show retail liquidity is alive. In secondary markets, look for 2x+ volume ratios in defence/renewable names post-correction.
-
Oversold / Overbought: Metal sector (-0.65%) and Defence (-0.97%) likely sitting in oversold territory after recent runs. No RSI data, but mean reversion setups possible. IT (-0.08%) and Pharma (-0.51%) — watch for capitulation or bounce.
6. AI Signals — BUY / HOLD / SELL
Note: Without stock-level technical data (RSI, DMAs, volume), signals below are index/sector-based inferences. Treat as directional, not actionable without confirmation.
| Stock/Sector | Signal | Reason |
|---|---|---|
| Bank Nifty | HOLD | +0.31% on narrow range; above 56,200 support but below 56,600 resistance |
| Nifty Media | BUY | +0.55%, sector leadership; defensive rotation intact |
| Nifty IT | HOLD | -0.08%, minor weakness; dollar strength helps exports but demand outlook mixed |
| Nifty Metal | SELL | -0.65%, crude cost pressures; likely near-term downtrend unless China stimulus |
| Nifty Auto | SELL | -0.41%, crude rally = demand risk; await fuel price clarity |
| Nifty Pharma | HOLD | -0.51%, defensives weak today; rupee strength + export plays = watch for bounce |
| Nifty Defence (Thematic) | SELL | -0.97%, profit-booking after rally; RSI likely overbought before drop |
| Vodafone Idea | BUY | 52w high + Jefferies Buy; high-beta turnaround play on tariff hikes |
| PSU Bank Index | BUY | +0.39%, valuations cheap; credit growth + govt capex tailwinds |
| Nifty PSE | BUY | +0.14%, public sector momentum; PSU banks + power utilities driving |
| India VIX | HOLD | 11.72 (down 1.71%); sub-12 = complacency risk; watch for spike |
| Crude Oil (Brent) | HOLD | $104.56 (+3.31%); above $100 = macro risk; but no technical data for Indian oil stocks |
7. Tomorrow’s Setup — Global Cues & Calendar
Global tape mixed, oil dominates. US markets closed red across the board: Dow -0.41%, S&P 500 -0.39%, Nasdaq -0.37%. The culprit: Brent crude crossing $100, reviving inflation fears and pushing Fed rate-cut bets further out. Treasuries weakened (yields up, prices down), and cyclicals underperformed.
Asian close tonight:
– Nikkei 225: +0.20% to 65,270.95. Japan shrugged off oil worries, likely on yen weakness supporting exporters.
– Hang Seng: -1.27% to 24,954.47. Hong Kong sold off hard — China stimulus hopes fading, crude a double-edged sword (demand vs. cost).
– European close: FTSE -0.37%, DAX -0.43%. Risk-off across the West.
GIFT Nifty signal: 23,477.80, flat with spot close. No overnight conviction. India’s Friday open likely range-bound unless crude spikes again or FII flow data surprises.
Commodities & Currency:
– Brent Crude: $104.56. Key level: $105 psychological. Break above = panic; dip below $100 = relief rally.
– Gold: $4,404.90 (-0.25%). Marginally lower despite risk-off — suggests profit-taking after recent highs. Still elevated, safe-haven bid intact.
– USD/INR: 95.43 (+0.64%). Watch 95.50 — break above could accelerate import-heavy sector pain. RBI likely to intervene aggressively.
Key levels for Friday:
– Nifty 50: Support at 23,380 (today’s low), then 23,300 (estimated 50-DMA). Resistance at 23,500 psychological, then 23,600.
– Bank Nifty: Support 56,200, resistance 56,600. Breakout either way could set tone for financials.
– Crude watch: If Brent holds above $100, expect OMCs (BPCL, IOC, HPCL) to remain under pressure. Upstream plays (ONGC) may find support.
Calendar risk: No major domestic data releases mentioned in headlines. Watch for FII/DII flow updates and any RBI commentary on rupee or liquidity.
8. The Honest Take
For long-term investors: Days like today test patience, not portfolios. Nifty 50 up 0.20%, Nifty 500 down 0.03% — that’s noise, not signal. Crude at $104 is a headwind, yes, but India’s economy isn’t built on quarterly oil swings. It’s built on demographics, digitisation, and capex cycles. If you own quality — banks with pricing power, IT exporters riding AI adoption, pharma names with US exposure, infra plays tied to government spending — today’s dip is a reminder to rebalance, not retreat. SIP inflows hit ₹2 trillion in FY26 despite closures, per Business Standard. That’s conviction. Match it.
For active traders: This is a stock-picker’s market disguised as an index grind. Nifty range-bound, but Vodafone Idea hits 52w highs, defence names correct 1%, media leads sectors. The alpha is in rotation — out of metals and autos, into banks and media. Friday’s session hinges on GIFT Nifty’s overnight move and crude’s next leg. If Brent retreats below $100, expect short-covering in OMCs and auto. If it spikes to $110, brace for VIX expansion and stop-loss triggers. Trade the setup, not the hope.
— Unified Stocks
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.