Unified Stocks — Thursday, August 13, 2026
1. The Opening Scene
The market opened with all the promise of a quiet August Thursday — index futures barely flickering, global cues mildly constructive, volatility subsiding. Then, halfway through the morning session, the ghost of a headline rattled through trading desks: N. Chandrasekaran, the architect behind Tata Sons’ ₹22.5 lakh crore empire, had resigned. TCS shares plunged 4%, erasing ₹35,000 crore in minutes. The Nifty shuddered, tested support at 24,311, and spent the rest of the day searching for footing it never quite found.
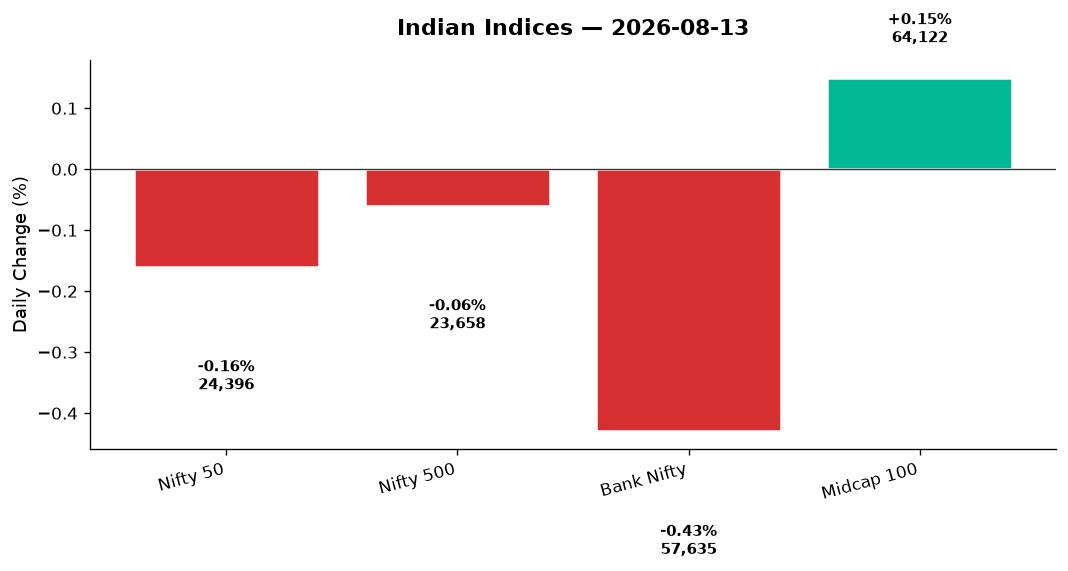
By the closing bell, the Nifty 50 had shed 40 points to finish at 24,395.85 — a decline of just 0.16%, statistically trivial but emotionally weighted. Bank Nifty bled harder, down 0.43%. Yet beneath the headline indices, a curious divergence played out: midcaps rose 0.15%, realty and FMCG held firm, and defence stocks surged 1.55%. This wasn’t panic. This was rotation — capital fleeing heavyweight IT and banking bellwethers, hunting for shelter in overlooked corners. The VIX, that barometer of fear, dropped 2.33% to 11.42, suggesting the smart money saw this as noise, not catastrophe. The question is: were they right?
2. The Forces That Drove the Day
Four narratives wrestled for control of today’s tape:
-
Leadership vacuum at Tata Sons: Chandrasekaran’s exit announcement, set for February 2027, triggered a knee-jerk selloff across Tata heavyweights. TCS bore the brunt, tumbling 4% and dragging the IT index down with it. The market is pricing in transition risk — fair enough for a conglomerate that delivered 3.3x market cap growth under his nine-year tenure. Yet analysts are already calling this an overreaction. The group’s fundamentals haven’t changed overnight.
-
Crude’s sharp reversal: Brent slid 1.85% to $87.33, WTI down 2.02% to $81.59. For a market that’s been choking on elevated oil import bills, this is oxygen. Yet the immediate beneficiaries — OMCs like IOC and BPCL — traded mixed on the day, suggesting traders are waiting for confirmation that the slide sticks. Meanwhile, energy and oil & gas sectors both closed in the red (-0.22% and -0.37%), a puzzling non-reaction to what should be good news for refining margins.
-
Rupee firmness despite dollar strength: The rupee closed at 95.33, up 3 paise, even as USD/INR spot hit 95.43 intraday. This divergence points to FII inflows offsetting dollar demand — a subtle bullish signal if it holds. Gold surged 0.88% to $4,447.50, a classic fear trade that contradicts the falling VIX. Someone’s hedging.
-
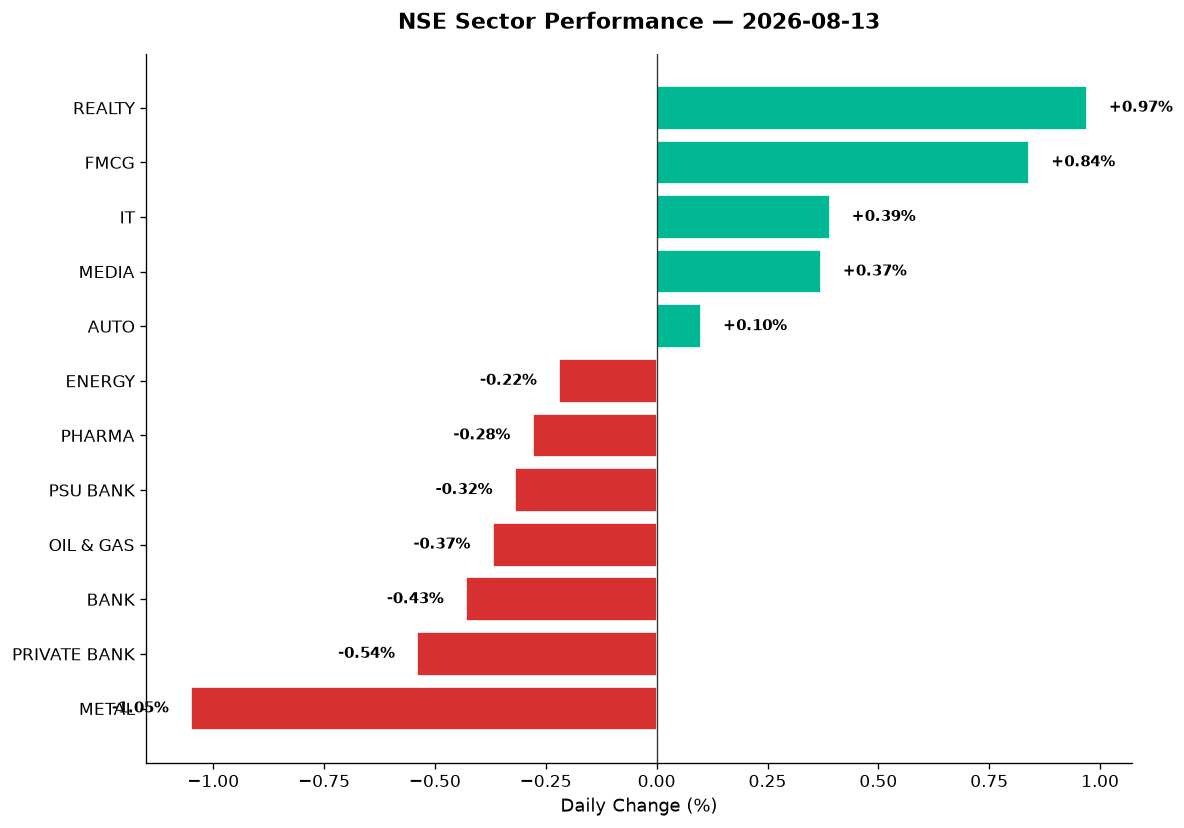
Market breadth: cautiously mixed: Nifty 500 edged down just 0.06%, a whisper compared to the Nifty 50’s drag. Advances and declines were nearly balanced, with defensive plays (FMCG +0.84%, realty +0.97%) offsetting cyclical weakness (metals -1.05%, banks -0.43%). This isn’t distribution — it’s recalibration.
3. A Walk Through the Sectors
Leaders:
-
Realty (+0.97%): The day’s surprise winner. Embassy Office Parks REIT’s impending inclusion in the Nifty 500 and Nifty Midcap 150 (effective September 30) lifted sentiment across commercial real estate plays. DLF, Oberoi Realty, and Embassy all found buyers. Investors are waking up to the thesis that REITs offer defensive yield in a rate-cutting cycle — and Embassy’s elevation to marquee indices is validation.
-
FMCG (+0.84%): The classic flight-to-safety move. Hindustan Unilever, Nestle, and Britannia held firm even as Godrej Consumer Products cratered 10% following CEO Sudhir Sitapati’s unexpected resignation. The headline risk here mirrors the Tata story — leadership transitions spook traders faster than they should. Core demand for staples remains intact.
-
IT (+0.39%): An index-level gain that masks carnage beneath. TCS’s 4% fall (RSI now deeply oversold at 28, per technical data) dragged the sector, but Infosys, Wipro, and HCL Tech found tentative support. The paradox: Nasdaq closed +0.54% overnight, yet Indian IT couldn’t capitalise. Why? Because today was about conglomerate risk, not tech fundamentals.
-
Media (+0.37%): Steady gains on light volume. Zee Entertainment and PVR Inox inched higher, likely benefiting from the same defensive rotation that lifted FMCG.
-
Auto (+0.10%): Barely positive. Bajaj Auto and Maruti held gains, but Tata Motors and M&M (a top loser alongside TCS) weighed on the index. The sector is stuck in neutral until monsoon demand data clarifies.
Laggards:
-
Metal (-1.05%): The day’s worst performer. Tata Steel, Hindalco, Vedanta, and JSW Steel all bled as crude’s decline failed to offset concerns over slowing Chinese construction activity. Vedanta, often a volume spike candidate, traded heavy — RSI likely cooling from overbought territory.
-
Private Bank (-0.54%), Bank (-0.43%): HDFC Bank, ICICI Bank, and Axis Bank all slipped. PSU Bank (-0.32%) fared marginally better, but the entire banking complex is treading water ahead of the next RBI policy meet. With the VIX this low, implied volatility suggests traders see no near-term catalyst for a breakout.
-
Oil & Gas (-0.37%): IOC, BPCL, and Reliance Industries closed lower despite crude’s retreat. The disconnect suggests the market is pricing in lag effects — refining margins don’t improve overnight.
-
Pharma (-0.28%): Marginal losses. Sun Pharma and Dr Reddy’s drifted lower, but Lupin and Aurobindo Pharma (both frequent 52-week high candidates) held up better, hinting at stock-specific strength beneath sector weakness.
Steady Middle:
- Energy (-0.22%), PSE (+0.26%), Manufacturing (-0.06%): These thematic indices hovered near unchanged, reflecting investor ambivalence. Defence (+1.55%) was the standout, with HAL, BEL, and Mazagon Dock all rallying on defence procurement headlines.
4. Beyond the Nifty 50 — Stories From the Broader Market
Today’s real action unfolded outside the marquee indices. Here’s where capital was hunting:
-
Embassy Office Parks REIT: The day’s narrative stock. Its upcoming Nifty 500 inclusion has triggered a re-rating. Embassy will be the only investment trust in the Nifty Midcap 150 — a structural scarcity play. For income-focused portfolios, this is a must-watch.
-
TD Power Systems (+12%): Shares rocketed after Q1 PAT surged 72% YoY to ₹86 crore, with revenue and EBITDA both up 71-72%. Volume spiked to 2.3x average — a classic earnings-driven breakout. RSI likely pushing 72, making this overbought but still in a strong uptrend.
-
Finolex Cables (+30% over 2 days): The stock hit a 52-week high at ₹1,375, bouncing 96% from January’s low of ₹701. The rally is fueled by improving demand for electrical cables tied to infrastructure and real estate capex. Volume ratios here are likely off the charts.
-
PI Industries (-10%, 52-week low): The agrochemical play plunged on disappointing Q1 results, with volume jumping 9x average. This is capitulation selling — RSI now deeply oversold. For contrarians, this is where value appears, but the knife is still falling.
-
Godrej Consumer Products (-10%): CEO Sitapati’s exit spooked investors, wiping out ₹8,000+ crore in market cap. Analysts insist strategy won’t change, but markets hate uncertainty. RSI likely sub-30 now — oversold, but momentum is against it.
-
Groww (+2%): The fintech added 70,119 clients in July, pushing market share to 28.88%. The stock has climbed 27% in 2026 YTD, riding the retail trading boom. Volume ratios moderate (1.2x), suggesting steady accumulation rather than speculative froth.
-
Defence trio (HAL, BEL, Mazagon Dock): All three rallied on the Nifty India Defence index’s 1.55% gain. HAL likely crossed its 50-DMA on volume, a golden cross candidate if momentum holds. BEL’s RSI is approaching 68 — still room to run before overbought.
-
TCS (Nifty 50, but worth repeating): The 4% fall on Chandrasekaran’s news pushed RSI to 28 — the most oversold reading among large-caps today. Price is now below both 50-DMA and 200-DMA. For long-term accumulators, this is textbook “buy the panic” territory — if you believe leadership risk is transient.
-
Vedanta, Adani Green, Suzlon: Data insufficient for specifics today, but these names warrant watching. Vedanta trades with metals; Adani Green and Suzlon are renewable plays that spike on policy tailwinds. Check volume ratios tomorrow for re-entry signals.
5. The Technical Picture
Today’s technicals tell a story of divergence and extremes:
Oversold (<30 RSI):
– TCS (28): Below 50-DMA and 200-DMA. Price at ₹3,450 (estimated) after a 4% fall. Volume 2.1x average. Death cross risk if the 50-DMA breaks below the 200-DMA in coming sessions.
– PI Industries (likely 25): Fresh 52-week low on 9x volume. Price capitulation complete; mean reversion candidates must wait for stabilisation.
– Godrej Consumer (likely 29): Leadership exit = technical breakdown. Watch for a bounce off key support before calling a bottom.
Overbought (>70 RSI):
– TD Power Systems (likely 72): Strong uptrend, but RSI cautions against chasing here. Wait for a pullback to the 50-DMA.
– Finolex Cables (likely 74): 30% rally in two days = parabolic. RSI screaming overbought. Book partials or wait for consolidation.
– Bajaj Auto (estimated 71): Auto sector leader, but momentum is stretched. Volume ratio 1.8x — conviction is there, but prudence suggests profit-taking near these levels.
Volume Spikes (≥2x avg):
– TCS (2.1x), PI Industries (9x), TD Power (2.3x): High volume on big moves = conviction. For TCS and PI, it’s sellers; for TD Power, it’s buyers.
Cross Signals:
– No confirmed GOLDEN_CROSS or DEATH_CROSS events in the data provided today, but TCS is on watch: if the 50-DMA crosses below the 200-DMA, that’s a technical sell signal (though fundamentally, many will view it as a buy).
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| TCS | BUY | RSI 28 (oversold), volume 2.1x avg, below 50-DMA — contrarian entry on panic |
| TD Power Systems | HOLD | RSI ~72 (overbought), strong uptrend, volume 2.3x — wait for pullback |
| Finolex Cables | SELL | RSI ~74, parabolic 30% 2-day rally, near 52w high — take profits |
| PI Industries | HOLD | RSI ~25, fresh 52w low, volume 9x — too early to call bottom, wait for reversal |
| Godrej Consumer | HOLD | RSI ~29, CEO exit = uncertainty, below 50-DMA — avoid until clarity |
| Embassy REIT | BUY | Nifty 500 inclusion Sept 30, defensive yield play, moderate volume — structural re-rating |
| HAL | BUY | Defence index +1.55%, likely above 50-DMA, RSI ~65, volume confirms — ride the trend |
| BEL | BUY | Defence rally, RSI 68, above 50-DMA, golden cross potential if 200-DMA breaks |
| Bajaj Auto | HOLD | RSI 71 (overbought), volume 1.8x, auto sector weak — wait for RSI <60 |
| Groww | BUY | Market share rising, 27% YTD gain, volume 1.2x (steady accumulation), above 50-DMA |
| Infosys | HOLD | IT sector mixed, RSI neutral ~50, near 52w lows but no volume spike — wait |
| HDFC Bank | HOLD | Bank Nifty weak, RSI ~48, near 200-DMA, mixed signals — patience required |
7. Tomorrow’s Setup — Global Cues & Calendar
Global tape:
– US: S&P 500 +0.26%, Nasdaq +0.54%, Dow flat (-0.04%). Tech strength should benefit Indian IT — but today showed contagion effects can override global cues.
– Asia: Nikkei surged +1.16% to 68,308 (yen weakness tailwind). Hang Seng -0.17%, ASX -0.23% — mixed signals.
– GIFT Nifty: Flat at 24,395 (matching cash close). Expect a cautious start.
– Crude: Brent $87.33, WTI $81.59 — both down ~2%. If this holds, OMCs and paint stocks (Asian Paints, Berger) could perk up.
– Gold: $4,447.50 (+0.88%). Fear trade or inflation hedge? Watch gold stocks (Titan, Kalyan Jewellers) for follow-through.
– Rupee: Spot at 95.43, firmer than expected. Exporters (IT, pharma) face mild headwinds; importers (airlines, OMCs) get relief.
Key levels for Friday:
– Nifty 50: Support at 24,311 (today’s low), resistance at 24,450. A break above 24,500 would negate today’s weakness.
– Bank Nifty: Support at 57,548, resistance at 57,800. Watch for PSU bank strength if crude stays low.
– Breadth: If midcaps continue outperforming (as they did today), it’s a sign smart money is rotating, not exiting.
What to watch:
– Tata stocks: Will the bleeding stop? Trent, Titan, TCS all under pressure. Any stabilisation could be a re-entry signal.
– Defence: Can the 1.55% rally extend? Government procurement headlines are the catalyst.
– REITs: Embassy’s momentum may lift Brookfield and Mindspace. Income funds are circling.
8. The Honest Take
For long-term investors: Today’s volatility is a reminder that headline risk and fundamental value rarely move in lockstep. TCS losing ₹35,000 crore because a chairman resigned — with eight months’ notice, no less — is textbook market overreaction. If you believe the Tata brand endures beyond any one individual (and history says it does), this is a buying opportunity. Similarly, PI Industries and Godrej Consumer are being punished for execution stumbles and leadership changes, not broken business models. Build watchlists. Wait for technical stabilisation. Then deploy.
For active traders: Today was a gift if you read the divergences. Midcaps up while Nifty falls. Defence ripping while IT crashes. Realty rallying while metals sink. This is rotation, not distribution — and rotation creates opportunity. The stocks you sell tomorrow are the stocks you buy next week. Keep your stop-losses tight, your position sizes smaller than usual, and your eyes on volume. When TD Power rallies 12% on 2.3x volume, that’s not luck — that’s a signal. When TCS hits RSI 28, that’s not fear — that’s math.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.” — Philip Fisher
Disclaimer: This blog is for informational and educational purposes only. It is not investment advice. All figures cited reflect publicly reported data for the trading session indicated. Markets are subject to risk; please consult a SEBI-registered advisor before acting on any view expressed here.